



Category: market research
The Solid State Drive Market: Strategic Shifts and Commercial Opportunities in an Era of Scarcity
The solid state drive market has evolved from a performance upgrade story into a foundational infrastructure play. Over the 2020–2025 historical window, global SSD revenue expanded from approximately 10.0 billion USD to 21.41 billion USD, reflecting a steep acceleration driven by data center expansion, AI workload migration, and the declining relevance of mechanical storage in performance-sensitive deployments. Forward projections estimate the market will reach 76.27 billion USD by 2032, translating to a compound annual growth rate of 19.9 percent across the 2026–2032 forecast period. This trajectory is not merely a function of unit volume growth; it reflects a structural re-pricing of storage as compute-intensive workloads demand higher throughput, larger capacities, and more efficient data movement. The market is large, growing fast, and increasingly constrained by supply-side dynamics that will define competitive outcomes over the next several years.
Yet rapid expansion does not guarantee smooth sailing. The SSD industry is entering a phase where demand signals, technology roadmaps, and supply chain realities are pulling in different directions. Enterprise and cloud customers are locking in capacity for AI and high-performance computing projects, while component availability and pricing power are shifting toward upstream manufacturers. For strategic planners and investors, the central question is no longer whether the SSD market will grow, but how value will be captured amid tightening supply, evolving interfaces, and a concentrated competitive field.
Market Snapshot: Scale, Structure, and Concentration
The revenue trajectory outlined above reflects a market that has already crossed an inflection point. In the historical period, SSD revenue grew from 13.97 billion USD in 2021 to 18.19 billion USD in 2023, then continued to 18.42 billion USD in 2024 before reaching 21.41 billion USD in 2025. The forecast period extends this climb steadily upward, with revenue projected at 25.96 billion USD in 2026, 37.02 billion USD in 2028, 54.23 billion USD in 2030, and 76.27 billion USD in 2032. These figures are presented in USD billions and reflect a market that is scaling at a pace rarely seen in mature semiconductor storage categories.
Beneath the headline growth, the revenue mix reveals where value is concentrating. NVMe has emerged as the dominant interface category, reflecting its alignment with low-latency, high-throughput enterprise and data center workloads. SATA and SAS retain meaningful positions, but their relative share reflects legacy deployment patterns and specific enterprise compatibility requirements rather than performance leadership. On the capacity dimension, the market is increasingly balanced across mid-range and high-capacity segments, with above-2TB and 1TB–2TB categories representing substantial revenue pools. This distribution signals that buyers are no longer purchasing SSDs primarily as capacity replacements for hard drives; they are investing in storage tiers that support faster data pipelines, larger model training datasets, and more aggressive inference workloads.
Market concentration further underscores the strategic stakes. The top three players account for approximately 68 percent of revenue, while the top five extend that share to roughly 76 percent. Such concentration matters because it shapes pricing dynamics, supply negotiation leverage, and the pace at which new technology transitions are adopted. In a market where high-density NAND capacity is increasingly scarce, concentrated leadership can translate into stronger control over allocation, roadmaps, and customer commitments.
Key Challenges and Inflection Points
The SSD market faces a set of interlocking challenges that will separate resilient strategies from reactive ones.
- Supply tightness and capacity allocation. High-density NAND availability is becoming a strategic bottleneck. Many downstream manufacturers and module producers are operating with limited inventory buffers, and major cloud providers are securing capacity for AI-related projects well in advance. This creates a market where lead times, prepayment structures, and long-term agreements increasingly determine who can fulfill large enterprise orders.
- Interface and form factor transition friction. As workloads migrate toward higher performance tiers, customers must navigate transitions from legacy interfaces to NVMe-centric designs and from traditional form factors to more space-efficient enterprise footprints. The transition is not purely technical; it affects system design, thermal management, compatibility, and total cost of ownership calculations.
- Regulatory and geopolitical pressure on advanced production. Export controls and related restrictions on advanced semiconductor manufacturing equipment and related items continue to shape where and how leading-edge NAND production can expand. For global supply chains, this introduces uncertainty around capacity addition timing, regional diversification, and the cost of maintaining access to advanced process technologies.
These challenges are not isolated. Tight supply amplifies the strategic importance of interface choices, while regulatory constraints complicate efforts to add capacity quickly. The result is a market where planning horizons are lengthening and competitive advantage is increasingly tied to supply security, technology readiness, and customer relationships rather than short-term pricing maneuvers.
Core Drivers Reshaping the SSD Landscape
Technology Innovation and the Push to Higher Density
Technology leadership is now expressed less in incremental speed gains and more in capacity density, interface efficiency, and workload-specific optimization. Recent product activity illustrates this shift clearly. In mid-2025, Kioxia announced the industry's first 245.76 TB NVMe SSD in 2.5-inch and E3.L form factors, designed for generative AI applications and moved into sampling with select customers. That same year, Micron entered the customer sample stage for its 6550 ION PCIe Gen5 NVMe SSD up to 61 TB in an E3.S form factor targeting high-capacity NVMe workloads. Earlier in the year, Solidigm extended a multi-year agreement with Broadcom for high-capacity SSD controllers supporting AI and data-intensive workloads.
These developments point to a clear pattern: the frontier is moving toward very large-capacity NVMe devices built for data center and AI environments, supported by controller and NAND technology advances that make high-density storage viable at scale. For enterprises, this means the conversation is shifting from "how much storage do we need?" to "how do we architect storage to keep pace with model training, inference, and massive dataset movement?" Higher-capacity SSDs can reduce the number of drives required for a given footprint, simplify rack-scale design, and improve data locality, but they also demand careful validation around endurance, thermal behavior, and controller reliability.
Policy and Regulatory Environment as a Strategic Variable
Regulatory dynamics are increasingly embedded in SSD supply planning. Export controls on advanced semiconductor manufacturing equipment and related items have been implemented in a way that restricts access for certain entities, affecting the trajectory of advanced NAND production expansion. While these measures are not specific to SSDs alone, they influence how quickly leading-edge capacity can be added and where it can be located.
For business planners, the implication is that regional sourcing strategies and supplier diversification are no longer optional risk mitigations; they are core to capacity assurance. Organizations that rely on a single geography or a narrow supplier base may face greater exposure to policy-driven disruptions and allocation decisions. The broader effect is a market in which long-term supply commitments, contractual flexibility, and multi-region sourcing become differentiators in securing critical storage capacity.
PW Consulting
Demand-Side Change: AI, Cloud, and Workload Re-Architecting
Demand is being reshaped by the growth of AI infrastructure and the associated re-architecture of data pipelines. Generative AI and large-scale analytics workloads place unusual stress on storage subsystems because they require high throughput for checkpointing, dataset loading, and rapid access to large volumes of training and inference data. This is encouraging cloud and enterprise buyers to prioritize NVMe-based solutions and larger individual drive capacities, especially where reducing the number of devices per rack or improving data movement efficiency can translate into meaningful operational gains.
At the same time, demand is not uniform across all segments. Consumer and gaming markets continue to value speed and form factor convenience, while enterprise environments prioritize reliability, capacity, and predictable performance under sustained loads. This divergence is pushing vendors to tailor product lines more carefully, with enterprise-focused SSDs emphasizing density and endurance while consumer and prosumer offerings emphasize latency, reliability, and platform compatibility.
Supply Chain and Cost Structure Pressures
The supply side story is becoming as important as the demand side. NAND flash availability is increasingly constrained, with much of the 2026 capacity already committed and high-density NAND effectively allocated to major projects. Inventory at several module manufacturers is expected to last only through early 2026, with stockouts beginning in March and more widespread shortages anticipated after the second quarter. In response, some major NAND foundries have sought three-year cash prepayments from certain customers, a signal that supply leverage has shifted materially upstream.
These conditions change the economics of SSD procurement and production. Buyers face longer commitment horizons and less flexibility to delay purchases without risking allocation. Manufacturers face pressure to secure raw material access, manage pricing carefully, and maintain credibility with enterprise customers who need predictable delivery. In such an environment, the ability to negotiate multi-year supply agreements becomes a competitive advantage. Western Digital and SanDisk, for example, signed multi-year supply agreements lasting up to five years for SSDs and HDDs to align with AI and data center demand. This type of arrangement reflects a broader strategic turn toward supply certainty in a market where capacity is not easily created on demand.
Competitive Landscape and Leadership Strategies
The competitive field in SSDs is concentrated and technically demanding. Samsung Electronics continues to lead in high-capacity data center and enterprise SSDs, with products such as the PM9D3a achieving read speeds up to 12,000 MB/s. SK hynix provides enterprise and high-performance SSDs powered by 321-layer QLC NAND, emphasizing advanced process technology as a differentiator. Micron Technology supplies high-capacity PCIe Gen5 NVMe SSDs, including the 6550 ION and 6600 ION families with capacities reaching up to 61 TB and 245.76 TB respectively, targeting large-scale data center deployments. Kioxia Corporation has pushed the capacity frontier with the LC9 Series and BiCS5 NAND-based drives, including what it describes as the industry's first 245.76 TB NVMe SSD.
Western Digital Corporation and its SanDisk brand continue to play a broad role across enterprise and high-performance SSDs, including the WD Black SN series and SanDisk-branded enterprise and portable products. Seagate Technology serves enterprise NVMe SSD needs for data centers and hyperscale applications. Solidigm focuses on high-capacity QLC PCIe SSDs for AI and data center workloads, exemplified by the D5-P5336 at 122 TB. In adjacent segments, Corsair produces high-performance gaming and M.2 NVMe SSDs such as the MP700 Pro XT; Kingston Technology emphasizes reliable consumer and enterprise offerings with a focus on speed and dependability; Crucial offers value-oriented NVMe and SATA SSDs with PCIe Gen5 options; Apacer Technology targets industrial and embedded applications; ADATA Technology produces gaming and portable SSDs across USB and NVMe form factors; ATP Electronics manufactures compact NVMe PCIe Gen4 SSDs with broad supply chain control; and Phison Electronics supplies enterprise SSD controllers and reference designs that enable other manufacturers to build competitive products.
Strategic Positioning and Differentiation
These companies are not competing on identical terms. Some differentiate through leading NAND process technology and capacity scaling; others through controller ecosystems, form factor specialization, or vertical integration across the supply chain. A few have built strong positions in enterprise density and AI-oriented workloads, while others concentrate on gaming, industrial, or value-oriented consumer markets. The most strategically resilient players tend to combine several of the following advantages:
- Capacity and technology leadership. Early moves into very large-capacity NVMe SSDs and advanced NAND layers can create credibility with data center customers who need to plan for multi-year workload growth.
- Supply assurance and contractual commitment. Long-term agreements and prepayment arrangements can secure allocation in a tight market, which is increasingly valuable when shortages are expected to persist into the second half of 2026 and beyond.
- Controller and ecosystem influence. Companies that shape controller designs or provide reference platforms can influence performance, reliability, and time-to-market across a broader manufacturing base.
- Segment focus. Clear positioning in enterprise, industrial, gaming, or consumer markets helps avoid direct head-to-head competition across every product tier and allows tailored validation and support.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market is likely to evolve along two parallel tracks. On one hand, concentration among top players supports scale advantages in capacity procurement, R&D investment, and enterprise customer relationships. On the other hand, specialized niches remain open for companies that serve industrial, embedded, gaming, or regional market needs with distinct form factors, durability profiles, or price-performance trade-offs. New entrants and smaller specialists can still win by addressing workload-specific requirements or by providing critical components such as controllers and reference designs that broader manufacturers integrate into their own products.
At the same time, the supply environment may accelerate consolidation behavior. When high-density NAND is scarce and prepaid commitments are required, smaller players with weaker balance sheets or limited supply access may find it harder to sustain large enterprise programs. Conversely, well-positioned specialists can benefit if larger customers seek additional sourcing options to reduce dependency risk.
Future Outlook: Three Strategic Trends for the Next 3–5 Years
Trend 1: Capacity Density Becomes the Central Battleground
Over the next several years, the most consequential competition will center on high-capacity NVMe SSDs designed for data center and AI environments. As model sizes, dataset scales, and inference demands grow, organizations will seek storage that minimizes the number of devices, simplifies rack design, and supports sustained throughput. This favors products that combine advanced NAND, efficient controllers, and validated enterprise reliability. The commercial opportunity lies in architecting storage solutions that reduce operational complexity while meeting performance and endurance requirements. The risk is that capacity claims outpace real-world reliability or thermal management, especially in dense deployments.
Trend 2: Supply Security Becomes a Strategic Procurement Priority
Given the current NAND shortage dynamics and the expectation that shortages may persist through the third quarter of 2026, procurement strategies will increasingly emphasize multi-year commitments, diversified sourcing, and early alignment with manufacturers. Organizations that wait for spot availability may face both price and allocation disadvantages. The commercial opportunity here is not simply buying earlier; it is building procurement relationships and contract structures that balance flexibility with security. The risk is over-committing to a single supplier or technology path before workload requirements are fully validated.
Worldwide SSD Memory Card Market
Trend 3: Interface and Platform Standardization Will Shape System Design
As NVMe continues to dominate new enterprise and data center deployments, system architects will place greater emphasis on form factor choices, thermal design, and integration with broader platform roadmaps. The transition toward compact enterprise form factors and higher-throughput interfaces will reward vendors that can demonstrate dependable performance in real deployment conditions, not just benchmark highlights. The commercial opportunity lies in helping customers navigate migration paths from legacy interfaces and larger device counts to fewer, higher-capacity NVMe devices. The risk is that migration introduces unforeseen compatibility or validation costs, particularly in mixed environments where older systems coexist with newer deployments.
Strategic Recommendations for Decision-Makers
For Manufacturers and Component Suppliers
Prioritize supply resilience and technology credibility. In a market where high-density NAND is heavily committed and prepayments are becoming more common, securing capacity through partnerships, long-term agreements, and disciplined inventory planning is essential. Equally important is validation: large-capacity enterprise SSDs must demonstrate endurance, thermal stability, and consistent performance under sustained workloads. Companies that can pair capacity leadership with reliable customer sampling, clear roadmap communication, and flexible sourcing options will be better positioned to retain enterprise trust.
For Investors
Focus on companies with defensible positions in capacity scaling, controller ecosystems, or specialized segments where technical barriers and customer relationships create durable advantages. The concentration of revenue among a small group of leaders suggests that scale and supply access matter, but specialized players can still outperform if they serve underserved workloads or provide critical enabling technologies. Monitor signals such as multi-year supply agreements, sampling progress for very large-capacity NVMe devices, and any shifts in prepayment or allocation practices, as these often precede changes in competitive leverage.
For Enterprise Buyers and Procurement Leaders
Treat storage capacity as a strategic input rather than a commoditized purchase. Where AI, analytics, or high-throughput data pipelines are central to operations, plan for multi-year supply alignment and evaluate vendors on the basis of capacity roadmaps, validation rigor, and ability to support migration from legacy interfaces. Diversify sourcing where feasible, and avoid relying on short-term availability assumptions in a market where NAND inventory buffers are thin and shortages are expected to extend through much of 2026. Balance commitment with flexibility by structuring agreements that protect against allocation risk without locking in unfavorable technology choices.
Closing Perspective
The SSD market is entering a phase where growth, scarcity, and technology transition intersect. Revenue is expanding rapidly, but the practical challenge for most organizations is not accessing a market that is obviously growing; it is securing the right capacity, at the right performance level, with enough supply certainty to support multi-year infrastructure plans. The companies and buyers that succeed will be those who treat SSDs as part of a broader data architecture strategy, align procurement with technology roadmaps, and prepare for a supply environment in which allocation and relationships matter as much as specifications.
Radiation-Hardened SSD Market
Detailed segmentation data, company-level assessments, and scenario-based guidance can help translate these strategic themes into operational decisions. PW Consulting's full research report provides deeper breakdowns across regions, interfaces, capacities, and competitive profiles, along with tailored recommendations for manufacturers, investors, and enterprise procurement teams seeking to navigate a market defined by both rapid growth and persistent supply constraints.
For detailed analysis of this topic, please visit the official page: Solid State Drive (SSD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
MOF Market 2026: Beyond the 20.6% CAGR—Shifting Demand & Regional Dynamics
By PW Consulting, 2026-09-21
The Metal-Organic Frameworks Market: Strategic Trajectories and Commercial Opportunities
The metal-organic frameworks (MOFs) market has transitioned from laboratory curiosity to industrial relevance at a pace that few materials markets have matched. Over the past half-decade, commercial activity has shifted decisively from gram-scale research supply toward multi-ton production runs, signaling that the inflection point between pilot validation and commercial deployment has arrived. Market revenue expanded from $0.65 billion in 2020 to $1.25 billion in 2025, and forward projections track sustained momentum through 2032, with expected revenue reaching $4.68 billion. The compound annual growth rate of 20.6 percent across the 2026 to 2032 forecast window reflects not merely incremental adoption but a structural reordering of how separation, storage, and purification functions are engineered across industrial value chains.
This growth trajectory helps explain why executives and investors are paying closer attention to MOFs. The materials class offers tunable pore architectures, high surface-area-to-volume ratios, and chemical specificity that conventional adsorbents struggle to replicate. Yet scale-up has historically been the binding constraint. The market is now demonstrating that manufacturing pathways are maturing quickly enough to support industrial demand, particularly in carbon capture, gas purification, and selective catalysis. Understanding where the market stands, what is driving it, and how competitive positioning is evolving provides a practical basis for strategic planning.
PW Consulting
Market Landscape: Growth Context and Core Challenges
The MOF market's expansion over 2020 to 2025 reflects a compound effect of technology readiness, commercialization activity, and rising demand from applications where selectivity and energy efficiency carry direct economic value. Revenue grew from $0.65 billion to $1.25 billion across that period, with the 2025 base year setting up a forecast period in which demand scales rapidly. The forward path suggests that by 2032, annual market revenue could approach $4.68 billion, implying that the later years of the forecast period will be defined by broader commercial adoption rather than early-stage experimentation.
This trajectory is meaningful because it points to a market that is no longer constrained primarily by scientific promise, but by manufacturing economics, application validation, and integration into existing industrial processes. That shift changes the strategic question for decision-makers. The issue is no longer whether MOFs can perform; it is whether companies can produce them consistently, cost-effectively, and at volumes that match operational requirements.
Scaling Production Without Compromising Performance
One of the most important challenges in the market has been moving from batch synthesis to continuous or semi-continuous manufacturing while preserving material consistency. MOF performance depends heavily on crystallinity, pore uniformity, and functionalization quality. In research environments, these attributes can be controlled with precision, but industrial-scale production introduces variability that can affect adsorption capacity, cycle stability, and downstream integration. The challenge is not simply producing more material; it is producing more material that behaves predictably under real operating conditions.
This matters because industrial buyers are unlikely to adopt materials that require extensive re-validation for every batch. For market participants, the strategic implication is clear: process control, quality assurance, and reproducible synthesis are becoming as important as the chemistry itself. Companies that can demonstrate repeatable performance at scale are positioned to capture commercial demand more effectively than those that rely on promising lab results alone.
Application-Specific Validation and Integration Risk
MOFs are not a single product category; they are a materials platform that must be matched to specific separation, storage, or catalytic requirements. That flexibility is an advantage, but it also creates a validation burden. End users need evidence that a particular MOF formulation will perform in their operating environment, often under cyclic conditions, exposure to impurities, and long-term thermal or pressure stress. For gas storage and purification, for example, performance expectations extend beyond capacity to include regeneration energy, lifetime durability, and compatibility with existing process equipment.
The commercial consequence is that adoption cycles can lengthen even when the materials are technically capable. Buyers may require pilot testing, on-site verification, or multi-phase qualification before committing to larger volumes. This dynamic favors suppliers that can support application engineering, not just material supply. It also means that early adoption is likely to remain concentrated in use cases where performance advantages are easiest to quantify and where integration risk can be managed through modular or retrofitted systems.
Cost Structure and Competitive Positioning Against Established Adsorbents
A third challenge is cost competitiveness relative to incumbent materials. Conventional adsorbents and separation technologies benefit from mature supply chains, well-understood manufacturing costs, and extensive operational history. MOFs must demonstrate that their performance advantages translate into total-cost advantages, whether through lower energy consumption, higher selectivity, reduced footprint, or longer service life. If the value case depends only on technical superiority without a clear economic pathway, adoption will remain limited to premium applications or highly regulated environments.
This cost dynamic is shaping the competitive landscape. Suppliers are increasingly focused on process efficiency, raw material selection, and manufacturing methods that can lower unit costs without sacrificing performance. The market is therefore evolving in a direction where production methodology, not just material design, determines commercial viability.
Key Drivers Shaping the MOF Market
Technical Innovation and Manufacturing Process Maturation
The most consequential driver in the MOF market is the convergence of material innovation and manufacturing readiness. Recent activity shows that scale-up is no longer theoretical. BASF achieved a milestone by becoming the first company to produce MOFs on a multi-ton production scale for carbon capture, a development that signals a shift from limited batch output to industrially meaningful volumes. That kind of production achievement matters because it reduces the perception risk that MOFs cannot be manufactured at relevant scale.
In parallel, other companies are advancing cost-oriented production pathways. Decarbontek launched commercial production and sale of its DCF-1 MOF, a low-cost, high-performance material available at kilogram scale for carbon capture. The emphasis on lower cost and commercial availability reflects a broader trend: suppliers are moving beyond performance demonstrations to pricing and availability strategies that can support real procurement decisions. Meanwhile, Promethean Particles fulfilled its largest-ever order of four tonnes of MOF for commercial applications, and later demonstrated MOF carbon capture technology in a high-profile showcase, reinforcing the growing visibility of MOFs in practical deployment contexts.
These developments point to a market in which process innovation is becoming a competitive differentiator. Continuous-flow synthesis, scale-up expertise, and the ability to deliver consistent material at commercial volumes are increasingly central to winning demand. For buyers, this means that supplier selection is shifting from pure material specifications to manufacturing reliability and supply assurance.
Policy, Regulatory Pressure, and Decarbonization Mandates
Policy and regulatory pressures are reinforcing demand for high-performance separation and capture materials. Carbon capture, gas purification, and emissions-related applications are increasingly influenced by compliance requirements, corporate decarbonization targets, and operational standards that make lower-energy, higher-selectivity technologies attractive. MOFs are well suited to applications where selectivity and regeneration efficiency can reduce operating cost or enable capture pathways that are otherwise impractical.
The strategic importance of this driver is that policy momentum can accelerate adoption timelines, especially in sectors where emissions performance or gas purity carries direct financial or regulatory consequences. In such environments, MOFs can gain traction faster because the value case includes compliance and risk reduction, not just process efficiency. This does not remove the need for cost competitiveness, but it widens the set of conditions under which MOFs can be commercially justified.
Demand-Side Shifts Toward Higher-Selectivity, Lower-Energy Solutions
Demand is also being shaped by operational priorities across end-use sectors. Companies managing gas streams, industrial emissions, or purification processes are increasingly focused on energy intensity, footprint constraints, and separation precision. In many cases, conventional methods involve trade-offs among capacity, energy use, and operational complexity. MOFs offer a different value proposition: materials that can be engineered for targeted molecular interactions, which can translate into more efficient separation or storage performance.
This demand-side shift favors suppliers that can communicate application-specific value rather than generic material properties. Key commercial questions now include how a MOF performs in a particular stream composition, how often it must be regenerated, what downstream effects it has on process design, and whether it can reduce total operating expense. As a result, the market is moving toward solution-oriented selling, where material performance is tied directly to operational outcomes.
Supply Chain Evolution and the Push Toward Cost-Effective Production
Supply chain dynamics are changing as well. The market is seeing greater attention to reproducible manufacturing, sourcing strategies, and the economics of moving from specialized chemical synthesis to more scalable production modes. Leadership and organizational changes in commercial-stage companies reflect this shift. For example, Promethean Particles appointed its first Chief Financial Officer to support the scale-up of MOF manufacturing, a signal that financing, cost management, and operational scaling are becoming central concerns as companies transition from development to growth.
This evolution is important because the cost of MOFs is not determined solely by chemistry. It is influenced by production throughput, yield consistency, quality control, and the ability to serve customers without excessive customization costs. As suppliers improve these dimensions, the market becomes more accessible to broader industrial adoption. For decision-makers, the implication is that the supply base is becoming more commercially structured, which can improve availability but also increase the importance of supplier differentiation.
Competitive Landscape and Leading Strategies
The competitive environment in the MOF market is shaped by a mix of established chemical manufacturers, specialized material developers, and application-focused suppliers. The market remains moderately concentrated, with a limited set of players holding substantial share, but it also includes a range of firms pursuing differentiated positions across production scale, application focus, and geographic reach.
BASF occupies a distinctive position through its commercial MOF offering for industrial-scale CO2 capture and sustainability applications. Its recent multi-ton production achievement reinforces a strategy centered on scaling proven chemistry into industrial supply. This positions BASF as a supplier capable of supporting large-volume demand where consistency and manufacturing credibility are critical. For buyers in carbon capture and related applications, that scale-up capability can be a decisive factor in procurement decisions.
Promethean Particles has built a position around cost-effective MOF production using a patented continuous-flow process, with applications spanning carbon capture, biogas upgrading, and atmospheric water harvesting. Its recent order fulfillment and executive scaling investments indicate a deliberate move toward commercial growth and operational maturity. The company's strategy illustrates how process technology can differentiate a supplier in a market where cost and repeatability are increasingly central.
Framergy emphasizes coordination polymer MOFs for oil and gas purification and selective adsorption, suggesting a more application-specific focus on industrial gas handling. NuMat Technologies provides custom MOF adsorbents for gas separation, catalysis, and energy applications, highlighting a flexible, customer-tailored approach. MOFapps and NovoMOF similarly concentrate on gas purification, separation, and industrial carbon capture, each with its own angle on performance, cost, or optimization.
On the research and specialty side, Strem Chemicals supplies high-purity MOF powders and research-grade materials, supporting academic and industrial development work. ACSYNAM manufactures custom MOFs for separation, purification, and specialty applications, reinforcing the role of bespoke synthesis in the market. Mosaic Materials and Decarbontek focus on proprietary or low-cost MOF adsorbents for carbon dioxide capture and gas separations, reflecting the growing emphasis on carbon-related applications and cost-sensitive commercialization.
Differentiation Strategies Among Leading Players
Across these companies, several strategic approaches stand out. One is scale-oriented commercialization, where the priority is demonstrating multi-ton production, reliable supply, and compatibility with industrial procurement. Another is cost and process differentiation, where continuous manufacturing or proprietary synthesis methods are used to lower unit costs and improve competitiveness against established adsorbents. A third is application specialization, where suppliers concentrate on particular use cases such as carbon capture, gas purification, biogas upgrading, or selective adsorption, building expertise and customer relationships in targeted segments.
A fourth strategy is customization and service depth, where suppliers position themselves as partners in application engineering rather than straightforward material vendors. This approach can be especially valuable in a market where performance depends heavily on operating conditions and integration requirements. Companies pursuing this model often compete on technical support, testing, and the ability to adapt material properties to customer needs.
How the Competitive Landscape Is Evolving
The market is likely to continue evolving along several lines. First, there is room for consolidation as successful scale-up creates advantages in supply credibility, cost management, and customer confidence. Larger or better-capitalized players may seek to strengthen their positions through partnerships, acquisitions, or expanded production capacity. Second, differentiation is expected to sharpen, because the market is moving from early technology validation toward commercial competition on price, reliability, and application outcomes. Third, new entrants may continue to appear, particularly where novel synthesis methods, lower-cost formulations, or unique application fit create an opening.
For decision-makers, this evolving landscape means that supplier selection should account for both current capability and trajectory. A company with strong research pedigree may not be the best fit if it lacks production scale, while a company with impressive scale-up progress may still be narrowing its application focus. The most relevant evaluation criteria will increasingly include manufacturing maturity, quality consistency, commercial availability, and the supplier's ability to support the buyer's specific operational environment.
Forward Outlook: Trends and Commercial Opportunities
From Pilot Adoption to Broader Industrial Deployment
Over the next three to five years, one of the most important trends is likely to be the shift from pilot and early commercial use toward broader industrial deployment in selected applications. The recent scale-up events and large-order fulfillment activity suggest that the supply side is becoming more capable of supporting commercial demand. As production becomes more routine, adoption can expand beyond niche or demonstration settings into operational environments where MOFs are evaluated on long-term economics and reliability.
This trend creates opportunity for suppliers that can provide not only material but also integration support, regeneration strategy, and performance assurance. It also creates opportunity for end users that can identify high-value separation or capture problems where MOFs offer measurable advantages. The commercial winners are likely to be those who can link material performance to measurable operational improvement in a way that justifies procurement and integration.
Cost Reduction as a Determinant of Market Breadth
A second trend is the growing centrality of cost reduction. As more companies pursue scalable production, competition around price and manufacturing efficiency will intensify. This is likely to widen the addressable market by making MOFs viable in a broader set of applications where cost thresholds previously limited adoption. Low-cost, high-performance materials are especially relevant in carbon capture and gas separation, where operating scale can make even modest efficiency gains economically significant.
The commercial implication is that cost leadership may become as important as performance leadership. Suppliers that can deliver acceptable performance at lower manufacturing cost, or that can tailor cost-performance trade-offs to specific applications, will have a stronger position in commercial negotiations. Buyers, in turn, should expect a wider range of pricing and performance options, which can improve procurement flexibility but also increase the need for careful technical evaluation.
Application Clustering Around Carbon Capture, Gas Purification, and Selectivity-Driven Use Cases
A third trend is likely to be application clustering around use cases where MOFs provide the clearest value. Carbon capture, gas purification, and related separation applications are already prominent in commercial activity, and these areas are well aligned with both performance advantages and external pressures for efficiency and decarbonization. Drug delivery and other specialized applications also remain part of the broader market picture, but industrial gas handling and capture appear particularly well positioned for near-term commercial expansion.
This clustering matters because it suggests that growth may be uneven across application areas. Some segments may scale faster due to stronger demand signals, clearer economic justification, or more favorable integration pathways. For investors and manufacturers, this points to the value of focusing on application environments where the path from material performance to commercial adoption is shortest and most measurable.
Zeolite Molecular Sieves Market
Risks and Uncertainties to Monitor
Despite the positive trajectory, several uncertainties remain. Production consistency and long-term material durability under real operating conditions will continue to be critical validation points. Supply chain constraints, raw material availability, and manufacturing bottlenecks could affect the pace of commercialization if demand grows faster than production capacity. In addition, the market's expansion will depend on whether MOFs can maintain a compelling economic case against established technologies, especially if incumbent solutions also improve or if regulatory and cost conditions shift.
There is also the risk of overconcentration in a small number of application narratives. If carbon capture or related areas dominate attention, other viable uses may receive less investment and slower adoption, even if they offer strong long-term potential. Decision-makers should therefore monitor both the momentum in leading applications and the emergence of differentiated use cases that could broaden the market over time.
Multifunctional Polyhedral Oligomeric Silsesquioxane Poss Market
Strategic Implications for Decision-Makers
For Manufacturers and Material Suppliers
Manufacturers should prioritize reproducible scale-up, quality consistency, and application-specific validation. The market is increasingly rewarding suppliers that can combine material performance with manufacturing reliability. Investing in process control, continuous or semi-continuous production methods, and customer-facing application support can strengthen competitive positioning. It is also important to define a clear value proposition by application rather than relying on broad claims about MOF performance. Suppliers that can demonstrate measurable benefits in target use cases are more likely to convert interest into commercial contracts.
For Investors
Investors should assess companies on manufacturing readiness, cost trajectory, and application fit, not just technical promise. The market is advancing quickly, but differentiation will increasingly come from execution: production scale, supply reliability, and the ability to serve commercial buyers with consistent material and usable solutions. When evaluating opportunities, it is useful to consider which companies are best positioned for the next phase of commercialization, where demand is likely to scale first, and how sustainable a supplier's cost advantage may be. Portfolio decisions should account for the possibility that market leadership will consolidate around players that can deliver both performance and commercial scalability.
For Procurement and End-User Organizations
Procurement teams should evaluate MOF suppliers with a strong focus on operational fit and total cost impact. Key questions include how the material performs in the specific gas stream or process environment, what regeneration and lifetime requirements look like, and whether the supplier can support pilot testing or phased deployment. It is also wise to compare options not only on material specifications but on supply assurance, quality consistency, and the supplier's ability to adapt to changing operational needs. In markets where performance advantages can translate into energy savings, footprint reduction, or compliance benefits, a structured evaluation can reveal value that is not apparent from product claims alone.
Getting the Full Picture
The MOF market is entering a phase in which commercial decisions matter as much as technical potential. Revenue growth, scale-up milestones, and expanding application activity all point to a market that is becoming more operationally significant, but also more complex to evaluate. Differences in manufacturing approach, application focus, cost structure, and supplier maturity are now central to understanding who is likely to capture demand and where adoption will scale fastest.
For organizations making decisions in this space, the most useful next step is to move from general market awareness to a detailed view of segment dynamics, application economics, regional variation, and supplier-specific positioning. A comprehensive report can provide that level of detail, including deeper segmentation data, competitive profiling, and tailored guidance aligned to specific strategic objectives. For executives, planners, and investors who need to act on the market rather than simply observe it, that granularity is where the real strategic value lies.
For detailed analysis of this topic, please visit the official page: Metal-organic Frameworks (MOF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Crude Heparin Market: How 7.47% CAGR and Surgical Demand Reshape Industry Profits
By PW Consulting, 2026-09-21
Navigating the Crude Heparin Market: Strategic Trends and Commercial Opportunities (2026–2032)
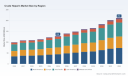
The global crude heparin market has entered a period of measured but steady expansion, with revenue projected to climb from 128.0 million USD in 2025 to 212.0 million USD by 2032, sustained by a compound annual growth rate of 7.47 percent. This trajectory reflects a market that is simultaneously maturing and reconfiguring. Demand anchored in cardiovascular applications and surgical procedures continues to provide a reliable base, while supply-side dynamics, regulatory scrutiny, and geographic rebalancing introduce new layers of complexity. For executives, investors, and procurement leaders, the central question is no longer whether the market will grow, but how participants can position themselves to capture value amid shifting competitive and compliance landscapes.
Market Snapshot and Structural Realities
The current market size of 128.0 million USD in 2025 represents more than incremental growth; it signals a market that has absorbed years of consolidation, quality standardization, and regional capacity adjustments. Over the historical window from 2020 through 2025, revenue moved from 100.0 million USD to its present level, reflecting resilience despite periodic supply interruptions and evolving regulatory expectations. Looking ahead, the forecast window from 2026 through 2032 points toward a consistent upward path, with annual figures crossing 140.32 million USD in 2026 and reaching 212.0 million USD in 2032.
A defining structural feature of this market is its fragmentation. The top three players account for roughly 24.5 percent of revenue, and the top five capture approximately 29.8 percent. Such concentration levels indicate that no single entity dominates the value chain outright, leaving room for regional specialists, vertically integrated producers, and downstream consumers to exert meaningful influence. This fragmented structure also means that differentiation tends to emerge through operational reliability, traceability credentials, and the ability to meet stringent quality requirements rather than through sheer scale alone.
Beyond the headline numbers, the market is navigating a series of inflection points. First, geographic demand is increasingly dispersed, with multiple regions contributing materially to overall volume and revenue. This dispersion complicates supply planning but also creates opportunities for producers with flexible sourcing and multi-region distribution capabilities. Second, the raw material base remains heavily tied to porcine intestinal mucosa, which continues to dominate global crude heparin output because of its high yield and comparatively lower disease transmission risk. That dependence creates efficiency advantages but also exposes the market to animal health disruptions that can ripple through supply availability. Third, the interplay between volume growth and regulatory stringency is tightening. Compliance is no longer a back-office function; it has become a commercial differentiator that influences procurement decisions, partnership formation, and market access.
For decision-makers, these structural realities translate into a simple imperative: growth will accrue to participants who can align capacity, quality assurance, and geographic agility while maintaining cost discipline. Operators and buyers alike need to treat crude heparin not as a commodity input but as a strategically managed resource with compliance, continuity, and traceability as core value drivers.
Key Drivers Shaping the Market
Several interlocking forces are propelling the crude heparin market forward while simultaneously reshaping how participants compete.
- Technological innovation and manufacturing precision are raising the bar for quality and consistency. Advances in extraction, purification, and analytical verification are helping producers standardize output across batches, reduce variability, and support downstream conversion into active pharmaceutical ingredients and low molecular weight heparin. These improvements matter because reproducibility directly affects supplier qualification, regulatory confidence, and ultimately commercial reliability.
- Regulatory and policy dynamics are redefining acceptable sourcing and documentation practices. Recent updates to heparin importation rules require specific analytical data, including species origin and contaminant testing for every shipment of crude heparin. Alongside this, active guidance on monitoring crude heparin for oversulfated chondroitin sulfate and ruminant material contaminants has reinforced the need for mandatory supplier qualification and lot testing. The practical effect is clear: documentation, traceability, and analytical rigor now function as market entry requirements rather than supplementary best practices.
- Demand-side behavior is becoming more risk-aware and procurement-disciplined. Cardiovascular applications remain a substantial and steady anchor for consumption, while surgical procedures provide additional procedural demand. At the same time, procurement teams are increasingly prioritizing supply continuity, validated quality records, and multi-source resilience over spot pricing alone. This shift is encouraging longer-term supplier relationships and more rigorous qualification processes.
- Supply chain and cost structures are being tested by animal health dynamics and regional capacity conditions. Industry reporting has highlighted ongoing outbreaks affecting a significant share of the global crude heparin supply associated with Chinese production, underscoring how animal disease can create bottlenecks and prompt buyers to diversify sourcing. At the same time, producers with vertically coordinated operations and established traceability are better positioned to absorb volatility and maintain reliable delivery.
These drivers are not operating in isolation. Innovation improves the ability to meet regulatory expectations; regulation raises the value of traceable sourcing; demand-side caution rewards continuity; and supply-side risks make diversification and integrated operations more commercially attractive. The net result is a market in which reliability and transparency are becoming as important as volume and price.
Competitive Landscape and Leading Strategies
The competitive field is defined by players with distinct strategic stances, each aligning capabilities to different parts of the value chain. Understanding these positions makes it easier to anticipate where partnerships, capacity investments, and procurement decisions are likely to flow.
Strategic Positioning of Key Players
Bioiberica has built a reputation around heparin molecule production, commercialization, and research, with an international footprint spanning multiple production sites. Its emphasis on pharmaceutical-grade crude porcine heparin for active pharmaceutical ingredients and low molecular weight heparin reflects a strategy oriented toward quality consistency and lifecycle engagement with the molecule. Participation in major industry events to mark corporate milestones and unveil refreshed branding suggests an ongoing effort to reinforce visibility and credibility within the pharmaceutical supply community.
Darling Ingredients, through its heparin operations, has focused on fully traceable crude porcine heparin extracted from hydrolyzed mucosa for pharmaceutical use as starting material for active pharmaceutical ingredients and low molecular weight heparin. Traceability is not merely a compliance checkbox here; it functions as a strategic asset that supports qualification, risk management, and buyer confidence. The company’s emphasis on profitable growth through strategic planning, including discussions of its heparin operations at investor events, signals an intent to treat heparin as a value-creating segment within a broader ingredients portfolio rather than a standalone volume play.
Shenzhen Hepalink operates as a multinational pharmaceutical company with a clear focus on heparin sodium active pharmaceutical ingredient and enoxaparin sodium active pharmaceutical ingredient production from crude sources. Its continued emphasis on these product lines through interim reporting indicates a strategy anchored in downstream conversion and product-level execution. By concentrating on active pharmaceutical ingredients, the company aligns itself with the value-added stages of the chain, where differentiation often depends on process control, regulatory standing, and consistent supply to formulation and finished-product markets.
Heparin Market
Hebei Changshan Biochemical Pharmaceutical specializes in research, development, production, and sales of heparin sodium active pharmaceutical ingredient and low molecular weight heparin, with a complete industrial chain extending from crude heparin products. Vertical integration across the chain can provide advantages in cost management, quality oversight, and responsiveness to demand fluctuations. Inclusion in recognized stock exchange indices has also drawn attention to the company, illustrating how market recognition and financial visibility can complement operational strategy in a fragmented competitive field.
Sanofi represents a different role in the landscape as a major consumer of crude heparin for low molecular weight heparin production, notably within its Clexane franchise and broader anticoagulant portfolio. For large downstream users, the crude heparin market is less about producing the molecule and more about securing dependable inputs that support branded and portfolio-level commercial commitments. This consumer-side perspective matters because major buyers can influence supplier qualification standards, specification expectations, and long-term supply commitments.
How the Landscape Is Evolving
The market is undergoing a nuanced evolution rather than a simple consolidation wave. On one hand, traceability, documentation maturity, and quality assurance are raising barriers for suppliers that cannot meet increasingly rigorous expectations. On the other hand, the relatively modest concentration levels leave space for regional specialists and integrated players to compete on operational excellence rather than market dominance alone. This environment favors strategies that combine reliable capacity, regulatory readiness, and transparent sourcing. It also creates openings for partnership models in which producers and downstream users align on qualification, continuity, and product-specific requirements.
PW Consulting
For investors and executives, the practical takeaway is that competitive advantage in this market is increasingly multidimensional. Scale matters, but so do traceability systems, animal-health risk management, analytical compliance, and the ability to serve downstream conversion with consistency. Companies that can demonstrate these attributes are better positioned to secure long-term relationships and withstand disruption.
Forward-Looking Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to shape how value is created and captured in the crude heparin market.
- Regulatory and quality requirements will continue to deepen as standard practice. Importation rules requiring species-origin and contaminant data, together with ongoing guidance on oversulfated chondroitin sulfate and ruminant contaminant monitoring, point toward a future in which analytical documentation is integrated into commercial workflows rather than treated as a periodic checkpoint. Producers and suppliers that can deliver standardized, verifiable data with each shipment will strengthen their qualification standing and reduce friction in procurement cycles.
- Geographic diversification and supply resilience will become more prominent in sourcing strategies. Animal health disruptions affecting a large share of supply associated with Chinese production have reinforced the importance of not concentrating sourcing too narrowly. Over the forecast period, buyers and producers alike are likely to place greater value on multi-region capability, flexible logistics, and contingency planning. This trend favors operators with diversified sourcing, transparent traceability, and the ability to maintain continuity when regional conditions shift.
- Downstream alignment and product-focused value creation will gain importance. Because cardiovascular applications and surgical procedures provide a durable demand base, participants that connect crude heparin supply more tightly to downstream active pharmaceutical ingredient and low molecular weight heparin production can capture more stable demand relationships. Vertical integration, long-term supply agreements, and product-specific quality alignment are likely to be rewarded as buyers seek to reduce variability and protect continuity for essential anticoagulants.
These trends create commercial opportunities for operators that can combine reliable production with compliance maturity and geographic flexibility. There is also opportunity in supplier qualification services, documentation systems, and analytical capabilities that help market participants demonstrate species origin, contaminant controls, and lot-level consistency. For downstream consumers, the opportunity lies in building qualified multi-source networks that reduce concentration risk without sacrificing quality or cost efficiency.
Risks and Uncertainties to Monitor
Despite the constructive growth path, several uncertainties warrant attention. Animal health events remain a persistent risk factor because of the market’s reliance on porcine intestinal mucosa. Regulatory expectations can evolve further, increasing documentation and testing burdens or adjusting qualification requirements. Concentration risk persists where sourcing is overly narrow, while over-diversification without strong quality assurance can introduce new variability. Currency and cost dynamics, regional capacity adjustments, and the pace of downstream demand growth can also influence margins and availability. Participants should treat these factors as variables to manage actively rather than external conditions to simply accept.
Strategic Actions for Decision-Makers
The current market environment rewards deliberate, differentiated action rather than passive participation. The right moves depend on a company’s position in the value chain, but several priorities apply broadly.
- For manufacturers and producers, investment in traceability, analytical documentation, and multi-region sourcing flexibility should be treated as core commercial capabilities. Aligning production with verifiable species-origin data, contaminant testing, and lot-level quality records can strengthen supplier qualification outcomes and improve resilience during regulatory or supply disruptions. Where feasible, vertical coordination or strategic partnerships that link crude heparin output to downstream active pharmaceutical ingredient and low molecular weight heparin needs can create more stable demand relationships and reduce exposure to spot-market volatility.
- For investors, the market’s fragmented structure and moderately concentrated leadership field suggest that value can be created through operational differentiation, compliance maturity, and disciplined growth planning rather than through scale alone. Emphasis on companies with transparent traceability, validated quality systems, and credible strategies for managing animal-health and supply continuity risks may align with the market’s evolving requirements. At the same time, monitoring how major downstream consumers structure sourcing and qualification can provide early signals about where supply relationships are heading.
- For procurement and supply chain leaders, the priority is to balance cost, continuity, and compliance in a way that reflects the market’s risk profile. Qualifying multiple suppliers, verifying documentation standards, and building contingency plans around animal-health and regulatory developments can reduce exposure to disruption. It is also important to treat supplier qualification as an ongoing process, given that importation rules and guidance on contaminants continue to shape acceptable sourcing practices. Long-term partnerships with suppliers that can demonstrate consistent analytical data and reliable delivery may offer more commercial stability than short-term price optimization alone.
Across these roles, the common thread is that crude heparin is increasingly evaluated through a lens that combines quality assurance, traceability, and continuity with traditional commercial considerations. Companies that internalize this lens are better positioned to navigate the forecast growth path from 128.0 million USD in 2025 toward 212.0 million USD by 2032 while managing the operational and regulatory risks that accompany it.
For decision-makers seeking a more detailed view of regional and application-level dynamics, sourcing patterns, and company-specific strategic paths, the full PW Consulting research report provides deeper segment data and tailored recommendations. It is designed to support scenario planning, supplier evaluation, and investment prioritization with the granularity required for operational and strategic decisions.
Heparin Sodium Market
For detailed analysis of this topic, please visit the official page: Crude Heparin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Steam Turbine Market: Asia Pacific’s Growth Drivers and the 2.8% CAGR Trajectory to 2032
By PW Consulting, 2026-09-21
The Steam Turbine Market at an Inflection Point: Strategy, Scale, and the Next Decade of Power Generation
The global steam turbine market is entering a phase of measured but decisive evolution. Valued at approximately 26.2 billion USD in 2025, the market has grown steadily from 22.82 billion USD in 2020, reflecting an average trajectory of 2.8% compound annual growth through 2032. While the headline numbers point to gradual expansion rather than explosive disruption, the underlying dynamics tell a more strategic story. Revenue concentration remains notable, with the top three firms capturing 48% of the market and the top five holding 50%, signaling that scale, technology access, and long-cycle project execution still reward incumbency. Yet the operational context is shifting fast: policy frameworks are tightening efficiency thresholds, data center demand is reshaping project pipelines, and material costs are pressuring margins across the value chain. For executives, investors, and procurement teams, the central question is no longer whether the market will grow, but where the growth will concentrate and how to position for it.
Market Snapshot: Steady Growth, Concentrated Structure, and a Changing Demand Base
Over the 2020 to 2025 period, the market expanded from the low 20-billion range to the mid-20s, with forward estimates reaching 31.79 billion USD by 2032. The compound annual growth rate of 2.8% captures a market that is expanding in line with infrastructure cycles rather than speculative demand. This baseline matters because it frames the strategic logic of the industry: steam turbines remain embedded in long-lived power assets, where efficiency, reliability, and compliance determine asset economics over decades.
Regionally, the market reflects a global but uneven footprint. Asia Pacific accounts for the largest share of revenue, followed by Europe and North America, with Latin America and the Middle East and Africa forming smaller but strategically important segments tied to utility expansion and industrial cogeneration. By application, power generation dominates the demand base, with oil and gas and other industrial uses representing smaller but commercially relevant niches. By type, both impulse and reaction turbines continue to serve distinct operating envelopes, with selection driven by pressure regimes, thermal profiles, and plant architecture rather than a single universal design.
What matters for strategy is not the spreadsheet of splits but the direction of travel. Demand is increasingly shaped by large-scale power projects that couple high-efficiency turbines with grid reliability mandates and, in several regions, by new load centers that require dedicated generation capacity. At the same time, the market’s concentration suggests that competitive wins are often won through differentiated technology packages, service relationships, and the ability to move quickly on project bookings in a capital-intensive environment.
Key Challenges and Inflection Points
Three challenges define the current turn in the market. First, efficiency and emissions regulations are rewriting the economics of existing assets. Updated performance standards for stationary combustion turbines now impose efficiency subcategorization thresholds, with large low-utilization units facing design efficiency expectations around 38%. For operators and OEMs, this creates a compliance calculus that affects turbine selection, cycle design, and retrofit strategies.
Second, the material and cost environment is becoming more volatile. Trade dynamics have elevated prices for nickel and chromium-based alloys that are central to turbine component performance. In a market where uptime and thermal resilience are valued, input cost pressure can compress margins and alter the attractiveness of certain design choices, particularly for long-lead components and high-stress rotor and blade assemblies.
Third, demand is bifurcating. Traditional thermal and cogeneration applications continue to matter, but a new demand vector is emerging from power-intensive digital infrastructure. AI data center power demand is accelerating combined-cycle projects that incorporate steam turbines, with several projects targeting online operation around 2028. This creates a fast-moving opportunity set, but also raises execution risk around timeline compression, site readiness, and the coordination of turbine supply with broader generation and grid integration plans.
Key Drivers Reshaping the Steam Turbine Market
Technology Innovation and the Efficiency Mandate
Efficiency remains the central technical battleground. Steam turbine value is increasingly derived from design refinements that extract more work from the same thermal input, reduce losses in moisture and staging, and improve part-load performance for plants that cycle more frequently. The push is not only about peak efficiency but about flexibility: operators want turbines that can respond to variable load profiles, integrate with different heat sources, and maintain reliability under changing operating regimes.
Recent commercial activity underscores this direction. Siemens Energy has booked significant steam turbine orders that contributed to a record backlog of 138 billion EUR, indicating strong demand for large-scale turbine-generator sets in complex power projects. The company’s selection to supply steam turbine generator sets for a 1 GW AI data center power project illustrates how turbine technology is being embedded into new demand centers where reliability and scale matter. Equally telling is the binding contract signed for a condensing steam turbine destined for an advanced reactor power plant, signaling that turbine applications are expanding beyond conventional thermal cycles into next-generation nuclear infrastructure.
These developments matter because they show how innovation is being validated through orders, not just laboratory benchmarks. For manufacturers, the strategic prize is to align efficiency gains with real project economics: fuel savings, emissions compliance, maintenance intervals, and the ability to operate across a wider load range. For buyers, the question is whether a turbine package can support both today’s operational needs and tomorrow’s regulatory and demand scenarios.
Policy and Regulatory Pressure as a Market Organizer
Policy is no longer a background condition; it is shaping project pipelines and asset decisions. The U.S. Department of Energy allocated 475 million USD in mid-2025 to enhance steam turbine efficiency in clean energy infrastructure, a signal that public funding is being directed toward performance improvements that can bridge conventional and low-carbon generation pathways. This kind of targeted support can accelerate adoption of higher-efficiency designs, especially where operators seek to extend asset life or improve economics before a wider transition.
On the compliance side, updated standards for coal-fired steam generating units require conversion to natural gas or carbon capture retrofit across a 2030 to 2039 window. Combined with efficiency thresholds for stationary combustion turbines, these rules create a structured timeline of decision points. Some plants will retrofit, some will repower, and some will be replaced entirely. For the steam turbine sector, this means demand will be redistributed across retrofit packages, new combined-cycle builds, and specialized configurations tied to evolving fuel and emissions pathways.
The practical implication is that policy is acting as an organizer of demand. Projects are being sequenced around compliance deadlines, and turbine selection is increasingly tied to the chosen compliance route. This favors suppliers that can offer flexible, documentation-ready solutions and that can support operators through the engineering and approval processes that accompany regulatory change.
Demand-Side Shifts: Data Centers, Grid Reliability, and New Load Centers
The most visible demand-side disruption is coming from power-intensive digital infrastructure. AI data center power demand is accelerating combined-cycle projects that incorporate steam turbines, with several initiatives targeting online operation around 2028. For turbine suppliers, this represents a shift from traditional utility-led procurement to a more diversified set of developers and offtakers that may prioritize speed, reliability, and dedicated supply for critical facilities.
This trend is not simply about adding load. It is about how that load is served. Data center power projects often require firm capacity, predictable availability, and tight integration with balance-of-plant systems. Steam turbines in combined-cycle configurations can offer the efficiency and scale needed to serve large continuous loads, while also supporting grid reliability when deployed in regions where new generation must come online quickly. The strategic opportunity lies in the convergence of industrial-scale turbine capability with fast-track project execution and service readiness.
A second demand shift is the continued relevance of industrial cogeneration and oil and gas applications. While smaller in revenue terms than power generation, these uses depend on turbines that can operate efficiently in tailored thermal environments and support process heat as well as electricity. Demand here is less about headline growth and more about reliability, lifecycle support, and the ability to adapt to site-specific constraints.
Supply Chain and Cost Structure: Materials, Lead Times, and Margin Discipline
Cost structure is becoming a strategic variable rather than a static input. Tariff-driven increases in nickel and chromium-based alloy prices are affecting components that are both performance-critical and long-lead. For manufacturers, this creates a balancing act between design integrity, sourcing strategies, and pricing discipline. For buyers, it can translate into more variable procurement costs and longer planning horizons as supply chains adjust.
The response is likely to differentiate winners. Suppliers that secure resilient sourcing, standardize high-value components where possible, and integrate service and lifecycle support can protect margins and reduce exposure to spot volatility. Buyers that engage early on specification, long-lead item planning, and service agreements can reduce execution risk and avoid late-stage cost surprises. In this environment, the steam turbine market behaves less like a commodity transaction and more like a structured engineering partnership, where risk allocation and planning horizon matter as much as unit pricing.
PW Consulting
Competitive Landscape and Leading Strategies
Incumbents with Scale, Technology, and Backlog Advantage
The market is led by large, globally integrated OEMs with strong positions in utility and industrial steam turbines. Siemens Energy brings a broad portfolio spanning conventional, combined-cycle, and nuclear applications, with an emphasis on efficiency and sector integration. Its recent order activity, including the record backlog and assignments tied to large data center and advanced reactor projects, highlights a strategy centered on winning complex, high-value projects where turbine performance is closely tied to overall plant economics.
GE Vernova remains a dominant force in installed capacity, with a long track record in steam turbine families for power plant solutions and advanced combined-cycle reheat designs. Its scale in global installed base creates a durable service and upgrade opportunity, while continued product development in high-efficiency configurations supports new project competitiveness. For the market, GE’s position illustrates how installed-base breadth can complement new-equipment leadership through lifecycle revenue and retrofit potential.
Mitsubishi Heavy Industries is notable for high-efficiency steam turbines in gas turbine combined-cycle plants, including components with hydrogen co-firing capabilities. This positions the firm at the intersection of efficiency and fuel flexibility, an increasingly relevant pairing as operators evaluate lower-carbon pathways without sacrificing thermal performance. The strategic value is in offering turbines that can operate across evolving fuel mixes while maintaining plant output and reliability.
Regional Players and Specialized Strengths
Alongside the global incumbents, several regional and specialized players hold meaningful positions. Dongfang Electric and Shanghai Electric are leading Chinese suppliers of large-scale turbines for power generation and utility-scale combined-cycle systems, with strong domestic demand and growing export activity. Harbin Electric similarly manufactures steam turbines with substantial domestic and export capability, reinforcing the importance of China’s manufacturing base in the global supply picture.
Doosan Enerbility has built a profile around combined-cycle and data center power projects, including recent North American orders, showing how a mid-tier global player can win by aligning turbine supply with fast-growing demand segments and executing on international project pipelines. Bharat Heavy Electricals Limited continues to serve Indian power generation and cogeneration applications, where domestic utility demand and cogeneration needs support a steady commercial base. Toshiba Energy Systems & Solutions and Ansaldo Energia add further depth in combined-cycle, cogeneration, and industrial power applications, reflecting the value of specialized engineering capabilities and regional project relationships.
Strategic Positioning and Differentiation
Across these firms, differentiation is emerging along several axes. Technology leadership in efficiency and cycle design remains foundational, but it is increasingly paired with fuel flexibility, service integration, and the ability to support complex compliance requirements. Backlog strength and project execution capacity are becoming competitive assets, especially where demand is concentrated in large, long-cycle projects that reward organizational reliability.
Another axis is application breadth. Players that can move across conventional thermal, combined-cycle, cogeneration, and emerging nuclear or advanced reactor applications are better positioned to capture demand that shifts as policies and load centers evolve. This breadth is not merely a portfolio feature; it is a hedge against demand volatility and a way to maintain utilization across different project types and geographies.
Service and lifecycle capability also matter. In a market where installed assets operate for decades, the ability to provide upgrades, maintenance, and performance restoration can stabilize revenue and deepen customer relationships. The competitive logic is straightforward: the turbine sale is often the entry point, but the long-term value is shaped by how well the supplier supports availability, efficiency retention, and compliance over the asset life.
Worldwide Steam Turbine for Power Station Market
Market Structure Trends: Integration, Differentiation, and New Entry Points
The market’s concentration suggests a tendency toward consolidation of advantage among scaled players, but it does not imply stagnation. Instead, the structure appears to be evolving through differentiation rather than pure consolidation. Global incumbents compete on technology, installed base, and complex project delivery, while regional players compete on cost, domestic relationships, and export execution. At the same time, new demand centers such as data center generation and advanced nuclear create entry points for specialized partnerships and project-driven wins, even if the core manufacturing barrier remains high.
This means the landscape is likely to remain layered. Leaders will continue to defend their positions through efficiency, scale, and service, while challengers and specialists will seek niches where project timeliness, regional proximity, or application-specific engineering provides an edge. For buyers, this layered structure creates options but also requires careful evaluation of technology fit, delivery risk, and long-term support.
Forward Outlook: Three Trends to Watch Over the Next 3 to 5 Years
Trend 1: Efficiency as the Default Purchase Criterion
Efficiency is likely to become an even more explicit purchase criterion as compliance windows tighten and fuel and emissions costs remain relevant. Projects will increasingly be evaluated on how turbine selection supports both immediate economics and future regulatory readiness. This favors designs that offer strong part-load performance, integration with higher-efficiency cycles, and clear documentation for compliance and permitting processes.
The commercial opportunity is in packages that link turbine performance to plant-level outcomes: reduced fuel intensity, lower exposure to emissions-related retrofit costs, and improved flexibility for cycling or dedicated load service. The risk is that efficiency gains can be undermined if material costs or lead times disrupt execution, or if operators underinvest in balance-of-plant and service planning that protects performance over time.
Trend 2: Demand Reallocation Toward Large Combined-Cycle and Dedicated Generation
The next few years are likely to see continued reallocation of demand toward large combined-cycle projects and dedicated generation for new load centers. AI data center power demand is already accelerating combined-cycle projects that incorporate steam turbines, and this pipeline is expected to shape order flow as projects move toward commissioning around 2028 and beyond. At the same time, retrofit and repower activity tied to coal-to-gas conversion and emissions compliance will redistribute demand across different project types.
For suppliers, the opportunity lies in aligning turbine offerings with the pacing of these projects and in demonstrating the ability to deliver under compressed timelines without compromising reliability. For developers and operators, the opportunity is in securing firm capacity with efficient, scalable generation assets that can support continuous loads and contribute to grid stability. The uncertainty is execution: timeline compression can stress supply chains, site readiness, and integration planning, especially when multiple large projects compete for the same materials and engineering resources.
Trend 3: Fuel Flexibility and Lifecycle Value as Competitive Differentiators
As operators evaluate lower-carbon pathways, fuel flexibility and lifecycle support will likely become more prominent differentiators. Hydrogen co-firing readiness, compatibility with changing fuel mixes, and upgrade paths that preserve efficiency and availability will matter for assets expected to operate through transition periods. Equally important will be service models that help operators manage performance, compliance, and maintenance across the asset life.
The strategic opportunity is in offering turbines and support structures that reduce the risk of stranded assets and extend useful life under evolving operating conditions. The risk is that fuel-flexibility claims must be matched by operational reality and that service promises must be delivered consistently, especially in markets where skilled labor and parts availability are constrained.
Actionable Guidance for Decision Makers
For Manufacturers and Suppliers
Position around efficiency, fuel flexibility, and delivery credibility. The market rewards technology that can be demonstrated in real projects, not only in specifications. Prioritize long-lead planning, resilient sourcing for critical alloys, and service integration that protects margins against input cost volatility. Where possible, build project-ready packages that simplify compliance documentation and reduce engineering friction for operators facing regulatory deadlines. Differentiate through application breadth where it can be supported by genuine engineering depth, especially in combined-cycle, cogeneration, and emerging nuclear-related applications.
For Investors
Evaluate exposure by project pipeline quality, backlog durability, and the ability to serve high-growth demand vectors without overconcentrating on any single cycle. The market’s 2.8% growth trajectory is steady, but the returns are likely to be uneven across players depending on their execution, technology positioning, and service mix. Watch for signs of margin resilience in the face of alloy cost pressure, and assess whether firms have credible pathways to capture data center-linked generation and retrofit-driven demand without compromising delivery reliability. Concentration in the market means scale matters, but differentiation in efficiency, fuel flexibility, and lifecycle support can determine who captures the higher-value segments of demand.
For Procurement and Operators
Treat turbine selection as a multi-decade decision shaped by compliance timelines, load profiles, and service realities. Engage early on specifications, long-lead items, and balance-of-plant coordination to reduce execution risk, especially for large combined-cycle or dedicated generation projects with ambitious commissioning targets. Evaluate suppliers not only on unit economics but on documentation support, upgrade paths, and the ability to sustain performance through regulatory transitions. In a market where material costs and lead times can shift, early planning and clear risk allocation are often as valuable as negotiating price.
Closing Perspective
The steam turbine market is not defined by rapid disruption but by a set of converging pressures that reward disciplined strategy. Efficiency, compliance, new demand centers, and cost discipline are reshaping where growth concentrates and how value is captured. The firms that navigate this environment well will be those that combine technical credibility with project execution, fuel flexibility with lifecycle support, and global scale with the ability to serve emerging demand channels. For executives and investors, the practical task is to map these trends to specific pipelines, asset strategies, and sourcing decisions before the next wave of project awards and compliance deadlines settles the market’s direction.
For a detailed breakdown of market size by region, type, and application, along with company-level profiles, recent order and contract developments, and regulatory and material cost dynamics, the full research report provides the segmented data and customized recommendations needed to support planning at the project and portfolio level.
Gas Turbine Market
For detailed analysis of this topic, please visit the official page: Steam Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Binders for Lithium Ion Batteries: Why the 15.8% CAGR Changes Everything
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Lithium Ion Battery Binders Market
The lithium-ion battery binders market has evolved from a supporting materials segment into a critical enabler of next-generation energy storage performance. As electrode architectures grow more demanding and manufacturing processes shift toward sustainability and localization, binder formulations now influence battery cycle life, production economics, and regulatory compliance. Over the historical period from 2020 to 2025, the market expanded steadily, reaching an estimated global revenue of USD 5.63 billion in 2025. Forward projections indicate continued momentum through the 2026-2032 forecast horizon, with the market expected to reach USD 15.72 billion by 2032. This trajectory reflects a compound annual growth rate of 15.8 percent, signaling that demand for specialized binder solutions is accelerating rather than plateauing.
Such expansion is not merely a byproduct of broader battery production growth. It reflects a structural shift in how binders are engineered, sourced, and validated. The market concentration remains relatively fragmented at the top, with the top three participants accounting for approximately 29.4 percent of revenue and the top five reaching 36.2 percent. This distribution suggests room for both specialized challengers and integrated suppliers, while also indicating that scale advantages in formulation consistency and supply reliability are becoming increasingly decisive in securing long-term contracts.
Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market
Structural Challenges and Inflection Points
Despite the favorable growth backdrop, the industry is navigating several interconnected challenges that will shape competitive outcomes over the coming years. Raw material volatility stands out as a persistent pressure point. PVDF binder feedstock pricing has exhibited fluctuations in the 15-25 percent range, directly affecting cathode binder production costs. At the same time, CMC and SBR feedstock inputs, tied to cellulose and styrene pricing, have driven material cost increases of 10-20 percent in 2025. These swings are not isolated margin issues; they force formulators to rethink co-binder ratios, adjust supply strategies, and invest in formulation flexibility to maintain performance without overreliance on any single input stream.
A second inflection point lies in the regulatory and environmental transition away from solvent-based electrode processing. Water-based binder processes are being actively promoted under environmental mandates, with the potential to reduce NMP usage by up to 90 percent in electrode manufacturing. This shift is not simply a compliance exercise. It changes drying profiles, slurry rheology requirements, and equipment specifications, which means binder suppliers must deliver formulations that perform reliably in water-based systems without sacrificing adhesion, conductivity, or cycle stability. Companies that can support manufacturers through this transition are gaining structural relevance beyond traditional product specifications.
Foundry Binder Market
A third challenge is the tightening of qualification standards for automotive and high-reliability applications. New ISO certifications for lithium-ion binder formulations have become required for EV OEM qualification, and 2025 updates mandate enhanced electrolyte compatibility testing. These requirements raise the barrier to entry for new suppliers and reward incumbents with established testing infrastructure, long-term validation data, and close engagement with cell makers during the development cycle. The practical effect is that binder selection is increasingly tied to risk management and certification readiness, not just price or basic performance metrics.
Key Drivers Reshaping the Market
Technology Innovation and Formulation Breakthroughs
The pace of binder innovation is closely tied to changes in anode and cathode design. For graphite-based anodes, SBR and CMC combinations continue to serve as the performance baseline, but the emergence of higher-silicon anodes is pushing formulators toward PAA and advanced co-binder architectures. Silicon-rich designs promise higher capacity, yet they introduce volume expansion challenges that require binders with stronger mechanical resilience and better interfacial stability. On the cathode side, binder selection increasingly intersects with cathode chemistry and cell architecture. PVDF remains widely used for its electrochemical stability and adhesive strength, but modified formulations are being optimized for longevity, energy density, and tolerance to high-voltage operation. The broader trend is toward tailored binder portfolios, where a single product line is no longer sufficient across multiple cell chemistries and manufacturing routes.
Policy, Regulation, and Supply Chain Nationalization
Policy dynamics are reinforcing the push toward localized and more sustainable binder supply chains. Government-backed supply chain initiatives have supported domestic PVDF and SBR binder production expansions, including substantial capacity additions in North America. These efforts reflect a broader strategic priority: reducing dependence on concentrated foreign supply for critical battery materials and improving resilience against logistics disruptions. At the same time, regulatory mandates favoring water-based processes are reshaping procurement priorities. Manufacturers are increasingly evaluating binders not only on technical performance, but also on how well they enable lower-solvent processing, reduce environmental footprint, and align with plant-level sustainability targets. The outcome is a dual incentive structure: cost and reliability remain important, but environmental process compatibility is becoming a procurement gate.
Demand-Side Shifts Across Applications
Demand is shifting in ways that reward binders designed for different performance and durability profiles. Electric vehicles remain the largest application driver, reflecting their scale, performance requirements, and the need for long calendar and cycle life. Energy storage systems represent a second major growth path, with applications that often prioritize cost efficiency, safety, and extended service life under stationary cycling conditions. Consumer electronics continue to demand binder solutions that balance thin-electrode processing, space constraints, and consistency at high volume. Industrial and marine devices, while smaller in current market share, create specialized requirements around temperature tolerance, mechanical robustness, and safety margins. As demand disperses across these segments, binder suppliers are increasingly evaluated on application-specific fit rather than generic capability.
Cost, Scale, and Manufacturing Localization
Cost structure and manufacturing geography are interacting in ways that influence both supplier strategy and buyer behavior. Expanding local production capacity reduces exposure to freight costs, import delays, and regional supply shocks, but it also requires disciplined scale-up and consistent quality control. Water-based SBR and CMC-compatible grades, for example, are being scaled to meet broader demand from graphite and silicon anodes while maintaining cycle stability and enhanced capacity performance. For buyers, localized supply can improve lead-time predictability and technical support responsiveness. For suppliers, the challenge is to balance capital deployment against uncertain demand timing while preserving formulation integrity across multiple production sites.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established polymer specialists, chemical majors, and regional-focused material suppliers. Japanese firms continue to hold strong positions in advanced binder technologies, with several companies emphasizing water-based anode binders, cathode-grade PVDF, and application-specific formulations aimed at tensile strength, cycle performance, and electrochemical stability. These companies often benefit from long development histories, close relationships with battery manufacturers, and the ability to offer formulation guidance beyond the product itself. At the same time, European and North American players are expanding capacity and broadening portfolios to serve cathode and anode requirements across multiple binder chemistries, including suspension and emulsion types, water-based SBR/CMC systems, and functional PVDF grades.
Differentiation Through Formulation Depth and Application Fit
Leaders are increasingly differentiating on formulation depth rather than volume alone. In cathode binder markets, differentiation often centers on adhesive strength, electrolyte resistance, and compatibility with high-energy or high-voltage designs. In anode markets, the emphasis shifts to slurry handling, adhesion under water-based processing, cycle stability with silicon-containing formulations, and the ability to support higher capacity without sacrificing electrode integrity. Suppliers that can present validated performance across these variables create stronger switching costs for buyers, because changing binders often requires requalification, slurry re-optimization, and cell-level testing. This dynamic favors companies that combine product breadth with application-specific engineering support and reliable qualification data.
Capacity Expansion and Localization as Strategic Moves
Recent activity shows that capacity and geographic positioning are becoming central strategic levers. In March 2025, one major supplier expanded U.S. manufacturing for water-based anode binders in Pennsylvania and Tennessee, targeting global lithium-ion battery demand with SBR and CMC-compatible grades. Around the same time, another firm began preparations for a new battery binder production line in Texas, expected to become operational in 2026 for localized supply. These moves are not merely capacity additions; they signal a deliberate alignment with regional demand, OEM localization expectations, and supply chain resilience goals. Local presence can improve technical engagement with cell manufacturers, reduce logistics risk, and support faster response to formulation tweaks required during pilot and ramp phases.
Market Structure Evolution and the Role of Specialized Entrants
The market is likely to continue evolving along two parallel tracks. On one hand, larger suppliers will seek to consolidate advantage through portfolio breadth, multi-region manufacturing, and qualification readiness across major application areas. On the other hand, specialized producers will remain relevant where niche formulations, localized feedstock advantage, or deep experience in a particular binder type create defensible positions. In practice, this creates a landscape where buyers may source standard grades from scale suppliers while relying on specialists for specific high-performance or application-tailored needs. The presence of companies focused on CMC, SBR, PAA for high-silicon anodes, and functionalized PVDF illustrates how segmentation is reinforcing itself. Over time, the most resilient players will be those that can move fluidly between commodity-scale supply and specialized formulation value.
Future Trends and Commercial Implications
Trend 1: Water-Based Processing as the Default Design Basis
The shift toward water-based binder processes is expected to deepen over the next three to five years. As environmental mandates and manufacturing sustainability goals gain traction, electrode production is likely to lean further into systems that reduce solvent dependence and the associated handling and recovery burden. The commercial implication is clear: binder portfolios built primarily around solvent-based compatibility may face growing marginalization in new production lines. Suppliers that have already adapted formulations for water-based slurry stability, drying behavior, and adhesion performance will be better positioned to participate in next-generation cell manufacturing. For buyers, this trend increases the importance of assessing supplier readiness for water-based qualification, not just current price-performance ratios.
Trend 2: Higher-Silicon and Chemically Diverse Anodes Driving Binder Complexity
Anode formulation is moving toward higher-silicon content and more diverse material blends, which places greater stress on binder performance. Binders will need to handle expansion, maintain contact integrity, and support stable cycling without compromising electrode processing. This trend creates an opportunity for suppliers offering advanced co-binder systems, PAA-based formulations, and engineered ratios that balance capacity with mechanical durability. It also raises the stakes for formulation transparency and testing support, because anode behavior is highly dependent on the interaction between active material, conductive additives, and binder architecture. Companies that can help customers optimize these interactions will capture value beyond the resin itself.
Trend 3: Qualification, Certification, and Supplier Reliability as Competitive Moats
As EV OEM qualification standards tighten and ISO-aligned testing requirements become more demanding, certification readiness will increasingly function as a competitive moat. The trend is toward more rigorous electrolyte compatibility testing, consistency verification, and documentation that supports multi-year validation cycles. This favors suppliers with established quality systems, predictable batch-to-batch performance, and the ability to support long qualification timelines. It also raises the importance of regional supply continuity, because qualification programs often prefer or require stable access to the same material source over extended periods. The practical commercial outcome is that supplier selection will place greater weight on reliability, documentation, and applied engineering support, especially in automotive and energy storage projects where downstream cost of failure is high.
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of market evolution. Raw material volatility may persist, particularly if feedstock pricing for PVDF, styrene, or cellulose-related inputs remains sensitive to macroeconomic and supply disruptions. A second risk is the possibility of uneven adoption of water-based processes, where some manufacturing lines or regions transition more slowly due to equipment constraints or formulation challenges. A third uncertainty lies in the speed and coordination of qualification cycles across automotive OEMs and cell makers, which can delay demand realization even when technical readiness exists. Finally, shifts in cathode and anode chemistry roadmaps could change the relative importance of specific binder types, making portfolio flexibility essential for suppliers and careful tracking essential for buyers.
Strategic Actions for Decision Makers
For Battery and Materials Manufacturers
Evaluate binder strategy as a system-level choice rather than a discrete procurement item. Map current and planned electrode chemistries against binder requirements, especially where water-based processing, silicon blending, or higher-energy cathode designs are involved. Prioritize suppliers that can demonstrate consistent performance across multiple production sites and provide formulation guidance during slurry optimization and cell qualification. Build dual-source or regional-supply options where qualification timelines and production continuity make it feasible, and align internal testing protocols with emerging certification expectations so that supplier changes do not create unnecessary delays.
For Investors and Strategic Planners
Focus on differentiation that translates into switching costs and recurring demand. In this market, sustainable advantage often comes from formulation depth, validation infrastructure, and regional manufacturing presence rather than brand alone. Track capacity expansions that align with localized demand and assess whether new entrants have the technical support capability to participate in qualification-heavy segments. Monitor feedstock sensitivity and formulation flexibility as indicators of resilience, and pay attention to how quickly suppliers can adapt to water-based processing requirements and higher-silicon anode trends. Portfolio exposure should favor companies that can serve both scale applications and specialized needs without sacrificing consistency.
For Procurement and Supply Chain Leaders
Treat binder sourcing as a risk and performance decision that should be coordinated with cell design roadmaps. Assess supplier readiness for water-based processing, electrolyte compatibility testing, and regional supply continuity, especially where OEM qualification and localization expectations are becoming more stringent. Use multi-year qualification and testing data as part of supplier evaluation, and ensure that cost negotiations do not obscure the potential downstream impact of inconsistent material performance. Where possible, align sourcing decisions with planned shifts in anode and cathode chemistry so that binder transitions are proactive rather than reactive.
The lithium-ion battery binders market is moving into a phase where technical complexity, regulatory direction, and supply chain geography jointly determine competitive outcomes. Growth is robust, but the real commercial value lies in understanding how formulation needs, processing shifts, and qualification requirements will reshape demand across EV, energy storage, consumer electronics, and specialized applications. Decision makers who track these dynamics closely will be better positioned to select suppliers, time capacity investments, and build resilient material strategies. For teams that need more granular segmentation data, regional demand patterns, and company-level benchmarking to support internal planning, the full research report provides a deeper evidence base and tailored analytical pathways.
For detailed analysis of this topic, please visit the official page: Binders for Lithium Ion Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Microducts Market: Why 11.3% CAGR Through 2032 Reshapes Fiber Expansion
By PW Consulting, 2026-09-21
Microducts Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The microducts market has entered a period of sustained expansion, driven by the global push toward higher-bandwidth fiber networks and the increasing density of connectivity infrastructure. Over the 2020 to 2025 evaluation window, revenue grew from approximately 2.82 billion USD to 4.84 billion USD, reflecting consistent year-over-year gains. The forward trajectory points to a compound annual growth rate of 11.3 percent across the 2026 to 2032 forecast period, with projected revenue reaching 10.17 billion USD by the end of the decade. This growth arc is not merely a function of volume expansion; it signals a structural shift in how fiber pathways are designed, installed, and maintained.
At the same time, the industry is navigating several inflection points that will determine which participants capture disproportionate value. First, the shift toward higher-fiber-count deployments and micro-trenching techniques is compressing installation windows and demanding tighter tolerances in duct geometry, connector compatibility, and cable blowability. Second, margin pressures are emerging from raw material volatility, particularly around high-density polyethylene feedstock, compounded by upstream logistics and geopolitical supply dynamics. Third, regulatory and standards frameworks are becoming more prescriptive, with fire-rated requirements, diameter specifications, and installation certifications increasingly shaping procurement decisions across indoor, outdoor, and multi-dwelling environments.
For executives and investors, these dynamics create a clear strategic question: how to align product roadmaps, capacity planning, and partnership structures with a market that is expanding rapidly but becoming more technically and commercially complex. The next phase of growth will reward participants who treat microducts not as commodity conduits but as engineered components within broader fiber architecture.
Key Drivers of Market Evolution
Several interconnected forces are reshaping demand, supply, and competitive positioning in the microducts sector. Understanding these drivers is essential for anticipating where capacity, innovation, and partnership opportunities will concentrate.
Pre-Wired Conduits Market
Technological Innovation and Installation Method Advances
The industry is moving decisively toward installation methods that reduce civil works footprint while increasing fiber density. Air-blown micro-cable deployment, multi-duct bundling, and micro-trenching are gaining traction as operators seek to accelerate fiber-to-the-home and broadband expansion without proportional increases in excavation or service disruption. These methods place higher demands on microduct dimensional consistency, inner wall smoothness, and mechanical resilience under tensile and pneumatic stress. Manufacturers that can standardize repeatable blowability performance, optimize connector and cassette integration, and deliver reliable multi-way architectures are positioned to capture premium segments of the market.
Recent operational moves illustrate this direction. Capacity expansions and facility upgrades have been announced to support additional microduct and bundle production lines, while product showcases emphasize multi-layer and multi-way systems designed for broadband scale-out. Partnerships are also increasingly focused on hardened connectivity solutions that combine blowable fiber optic micro-cables with compatible duct pathways, reflecting a shift from standalone component sales toward solution-level integration.
Policy and Regulatory Environment
Regulation continues to act as both a gatekeeper and an accelerator. Certification standards for microduct materials govern installation approvals for fire-rated and outdoor applications, while association standards specify microduct diameter ranges and microcable blowability requirements for fiber-to-the-home deployments. In parallel, building codes in the European Union and North America are increasingly mandating flame-retardant variants for indoor and multi-dwelling installations. These requirements raise the bar for material formulation, testing, and documentation, but they also create clearer specifications for procurement teams and reduce ambiguity in project compliance.
For suppliers, the practical implication is that certification readiness and specification alignment are becoming competitive differentiators. Manufacturers that can provide validated fire-rated options, diameter-consistent product families, and installation-friendly designs will face fewer friction points in bid evaluations and project approvals.
Demand-Side Shifts in Connectivity Infrastructure
Demand is being pulled by multiple deployment vectors. Fiber-to-the-x networks remain the dominant application driver, reflecting the ongoing densification of last-mile connectivity. Access networks and backbone networks continue to require scalable pathway solutions as traffic volumes grow and redundancy expectations increase. Data center buildouts are also contributing to demand for structured, fire-compliant microduct pathways that support high-density fiber management. The common thread is a need for pathways that can accommodate future fiber additions without repeated civil works, which favors modular, multi-duct, and low-friction designs.
Supply Chain and Cost Structure Dynamics
On the supply side, high-density polyethylene remains the primary feedstock for many microduct grades, and price volatility in this material is translating into margin pressure for manufacturers. Upstream resin logistics and geopolitical factors have contributed to effective cost increases for HDPE microduct grades, prompting operators to reassess sourcing strategies, inventory buffers, and long-term contract structures. This environment favors suppliers with stable resin access, efficient extrusion and compounding capabilities, and the ability to offer specification-optimized products that reduce installation waste and rework.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized microduct manufacturers, broader telecom infrastructure players, and regional suppliers with strong local distribution. Market concentration measures indicate that the top three participants hold roughly 32.8 percent of revenue, while the top five account for about 43.7 percent, suggesting a landscape that is neither highly fragmented nor dominated by a single incumbent. This structure leaves room for differentiation through technology, service, and regional execution.
Leading firms are pursuing distinct strategic positions. Some are emphasizing blown-fibre tubing and direct-install microducts tailored for telecom and broadband networks, leveraging deep expertise in air-blown deployment and connector ecosystems. Others are focusing on multi-microduct systems and customized solutions that simplify pathway planning for fiber rollouts. A further group is building out multi-layer and flame-retardant product lines to address data center, indoor, and regulated outdoor requirements. Several manufacturers are also expanding into HDPE-based microduct bundles and accessories, reinforcing their ability to supply complete conduit pathways rather than isolated components.
Recent activity underscores a trend toward scale, certification, and partnership. Capacity expansions are being used to add microduct and bundle production lines, supporting regional broadband acceleration. Certification recognition is being highlighted as evidence of installation performance in micro-trenching and communications applications. Facility upgrades are showcasing multi-production capabilities aligned with European broadband expansion. Strategic partnerships are being formed around hardened connectivity solutions that pair blowable fiber optic micro-cables with compatible duct systems. In parallel, broader network agreements between major fiber producers and operators are extending fiber network reach, indirectly supporting demand for structured pathway solutions.
The market is likely to evolve through a combination of consolidation among regional players seeking scale, continued specialization by firms with strong technical credentials, and selective entry by larger infrastructure groups looking to integrate microduct offerings into broader fiber portfolios. Differentiation will increasingly depend on installation reliability, certification breadth, material stability, and the ability to support multi-vendor fiber management.
Forward Outlook: Three Trends Shaping 2026 to 2032
Looking ahead, three trends are particularly relevant for strategic planning.
- Installation efficiency will become a primary value metric. As operators prioritize speed and reduced civil works, microduct systems that support air-blown cable deployment, micro-trenching, and easy future fiber addition will command preference. Suppliers that can demonstrate consistent blowability, low friction, and compatible cassette or connector interfaces will benefit from procurement bias in projects where installation risk is a key evaluation factor.
- Regulatory and specification alignment will shape procurement cycles. Fire-rated requirements, diameter standards, and certification expectations are becoming more explicit across regions. This creates a dual dynamic: higher compliance costs for underperformers, and clearer competitive moats for suppliers with validated, specification-ready portfolios. Projects in indoor, multi-dwelling, and outdoor environments will increasingly require documented compliance, making certification and technical documentation part of the commercial proposition.
- Material cost volatility will drive sourcing and product strategy. Feedstock price swings and logistics pressures will continue to influence margins and pricing. Participants with diversified resin access, efficient manufacturing, and design choices that reduce waste or installation rework will be better positioned to protect profitability. Long-term supply agreements, regional capacity alignment, and specification optimization will become more important as risk-mitigation tools.
These trends point to commercial opportunities in engineered product families, regional capacity scaling, and solution-oriented partnerships. At the same time, uncertainty remains around the pace of build-out in different geographies, the trajectory of raw material costs, and the extent to which standards will converge or diverge across markets. Companies should model multiple demand scenarios and stress-test supply assumptions against resin price and logistics variability.
Microgrid Market
Strategic Recommendations for Decision-Makers
The market's growth trajectory and increasing technical complexity call for focused action across the value chain. The following recommendations are intended to help manufacturers, investors, and procurement teams align with the most consequential shifts.
For Manufacturers and Suppliers
- Prioritize installation-centric product development. Invest in dimensional consistency, inner-wall finish, and compatibility with blowable micro-cables, cassettes, and connectors. Products that reduce installation risk and support future fiber additions will stand out in competitive bids.
- Strengthen certification and specification readiness. Ensure fire-rated, outdoor, and indoor variants are aligned with relevant standards and building code expectations. Clear documentation and test evidence can shorten evaluation cycles and reduce project friction.
- Hedge material and logistics exposure. Diversify resin sourcing where possible, secure long-term supply arrangements, and optimize product design to minimize waste and rework. Cost discipline will be as important as volume growth in protecting margins.
For Investors and Strategic Allocators
- Evaluate players on installation reliability and solution breadth, not just capacity. Firms that combine validated performance with partnership ecosystems and regional execution are more likely to sustain pricing power and repeat business.
- Watch for consolidation and capability aggregation. Regional specialists with strong local relationships may become attractive acquisition targets for larger groups seeking scale, while larger incumbents may pursue tuck-in acquisitions to expand technical portfolios.
- Model demand across multiple deployment vectors. Fiber-to-the-home, access and backbone expansion, and data center buildouts do not move in lockstep. Scenario-based forecasting will help avoid overcommitment in any single application stream.
For Procurement and Network Planners
- Specify for future density, not just current need. Choose microduct systems that support additional fiber pulls or blown cables without repeated civil works. Modular multi-duct and low-friction designs can reduce long-term lifecycle cost.
- Demand documented compliance and installation performance. Require evidence of certification, fire-rated suitability where applicable, and compatibility with planned deployment methods. This reduces risk and improves bid comparability.
- Engage suppliers early on installation methodology. Align duct specifications with micro-trenching, air-blown, or direct-bury approaches before tendering. Early coordination can lower installation cost and avoid rework.
The microducts market is expanding against a backdrop of technical refinement, regulatory clarification, and supply-chain complexity. Participants that act early on installation efficiency, compliance readiness, and material risk management are best positioned to convert growth into durable advantage. For teams seeking deeper segmentation, regional demand splits, and tailored scenario planning, the full research report provides the detailed data and customization needed to translate these macro trends into precise commercial decisions.
For detailed analysis of this topic, please visit the official page: Microducts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Slewing Bearings Market: Why 5.95% CAGR and Asia Pacific Demand Reshape Growth
By PW Consulting, 2026-09-21
The Slewing Bearings Market: Strategic Trends and Commercial Opportunities Through 2032
The slewing bearing market has evolved from a niche mechanical component sector into a critical enabler of industrial mobility, renewable energy infrastructure, and precision machinery. With global revenue climbing from approximately 331.45 million in 2020 to 438.27 million in 2025, the trajectory signals sustained expansion driven by capital-intensive infrastructure projects and technological maturation in heavy equipment. The forecast period through 2032 projects continued growth, approaching 652.66 million by the end of the decade, representing a compound annual growth rate of 5.95 percent. This expansion trajectory is not merely a function of population growth or broad industrial output; it reflects deliberate capital allocation toward higher-precision rotational systems that can withstand increasingly demanding operational environments.
Despite the positive momentum, the market is navigating a series of structural inflection points that will separate resilient operators from those reliant on legacy cost models. Fluctuating costs of specialty steel and rare earth elements have emerged as a persistent margin compression factor, forcing manufacturers to reconsider material sourcing strategies and engineering tolerances. At the same time, the competitive landscape remains moderately fragmented, with the top three manufacturers accounting for 24.6 percent of revenue and the top five reaching 32.1 percent. This concentration leaves ample room for both consolidation and niche specialization, depending on how companies position themselves along the value chain. Below, the structural dynamics shaping the slewing bearings market are examined through the lens of strategic decision-making.
Market Landscape and Core Challenges
The slewing bearing market has demonstrated consistent revenue growth over the historical period, with the pace accelerating notably as capital expenditures in renewable energy and heavy construction equipment gained traction. The 2025 base of 438.27 million serves as a foundation for the projected climb toward 652.66 million by 2032, a trajectory that implies steady year-over-year expansion rather than sudden spikes. This pattern reflects the capital-intensive nature of end-use sectors, where procurement cycles are long, specification requirements are rigorous, and replacement cycles are extended. The market's resilience during periods of broader industrial volatility underscores the relatively inelastic demand for high-load rotational components that are integral to project continuity.
One of the most significant challenges confronting manufacturers and end users alike is the volatility of raw material inputs. Slewing bearings are steel-intensive components, and fluctuations in alloy steel such as 42CrMo directly influence manufacturing costs and the fatigue life of the raceway. When specialty steel pricing shifts unpredictably, manufacturers face a difficult trade-off between absorbing costs to preserve customer relationships and passing increases through to a market that may already be sensitive to project budgets. This dynamic is particularly acute for producers serving multiple regions with varying procurement standards, as material substitution options are often limited by certification requirements and performance guarantees.
A second challenge lies in the regulatory environment, which is becoming more prescriptive across multiple jurisdictions. Standards such as ISO 16123:2025 now specify design, manufacture, and acceptance requirements for slewing bearings in marine cranes operating at ambient temperatures not lower than −40 °C. While such standards enhance safety and interoperability, they also raise the compliance burden for suppliers who must document design parameters, material traceability, and testing protocols with greater rigor. Simultaneously, the European Union has introduced new guidelines emphasizing reduced carbon footprints and enhanced recycling practices within bearing manufacturing processes. These requirements are reshaping procurement criteria, particularly for projects funded through public institutions or multinational operators with explicit sustainability mandates.
PW Consulting
A third structural challenge is the widening divergence between standardized commodity-grade products and highly customized engineered solutions. As end-use applications grow more specialized, the value proposition increasingly shifts toward tailored geometries, surface treatments, and integrated drive systems. Manufacturers that rely heavily on high-volume standard production may find margin erosion as customers migrate toward suppliers capable of delivering application-specific performance. Conversely, those that over-index on customization without disciplined cost control risk becoming uncompetitive for broader market segments.
Key Drivers Shaping Market Dynamics
Technology Innovation and Engineering Breakthroughs
The shift toward higher precision and greater load capacity continues to redefine product expectations. Manufacturers are investing in design methodologies that balance material efficiency with fatigue resistance, recognizing that even marginal improvements in raceway geometry or heat treatment can extend service life in demanding applications. Thin-section and slewing ring bearings have gained particular traction in sectors such as aerospace, robotics, and medical equipment, where spatial constraints and stringent performance criteria demand compact yet robust solutions.
Silverthin Bearing Group's release of a comprehensive catalog for thin section and slewing ring bearings in July 2025 illustrates this trend in practice. Targeting applications across space, aerospace, defense, robotics, medical, oil and gas, and semiconductor industries, the catalog reflects a deliberate move toward cross-industrial diversification. Rather than relying solely on traditional heavy machinery demand, the company is positioning precision slewing solutions as enablement components for high-value, technology-intensive sectors. This type of portfolio expansion signals a broader industry shift: slewing bearings are increasingly viewed not merely as mechanical parts but as engineered subsystems that influence the performance envelope of the equipment they support.
Policy and Regulatory Environments
Regulatory developments are reshaping both product specifications and procurement practices. The introduction of ISO 16123:2025 establishes clearer design and acceptance parameters for slewing bearings used in marine crane applications under extreme temperature conditions. This standard is likely to influence procurement requirements beyond marine environments, as operators in adjacent heavy-lift and offshore sectors adopt similar performance benchmarks to reduce risk across their equipment fleets.
At the same time, sustainability-oriented regulations are introducing new considerations into the manufacturing process. The European Union's emphasis on reduced carbon footprints and enhanced recycling practices is altering supplier evaluation criteria, particularly for OEMs and project developers with public sustainability commitments. For manufacturers, compliance is no longer a peripheral concern; it is becoming a competitive differentiator that can determine eligibility for certain contracts. Companies that proactively integrate material traceability, energy-efficient production methods, and end-of-life recycling pathways into their operations are better positioned to meet evolving procurement requirements.
Demand-Side Shifts in End-Use Sectors
Renewable energy remains a central driver of slewing bearing demand, as wind turbine installations and related infrastructure continue to expand globally. The rotational precision and durability required for turbine yaw and pitch systems make slewing bearings integral to long-term operational reliability. Construction and transit equipment also continues to contribute substantial demand, as excavators, cranes, and material handling systems rely on slewing components for controlled multi-directional movement. Mining operations, particularly in regions undergoing expanded extraction and processing investments, further reinforce demand for heavy-duty slewing solutions capable of withstanding abrasive environments and high-cyclic loading.
Beyond these established sectors, a gradual broadening of application scope is becoming evident. Precision slewing rings are increasingly integrated into automation systems, robotics platforms, and specialized industrial machinery where smooth torque transmission and compact form factors are critical. This diversification reduces dependence on any single end-use cycle and creates opportunities for suppliers who can adapt their engineering capabilities to smaller-volume, higher-specification orders.
Bearings Market
Supply Chain and Cost Structure Evolution
Material cost volatility remains a defining feature of the supply chain environment. The reliance on alloy steel and specialty materials means that manufacturing costs are closely tied to commodity markets that can shift rapidly in response to trade dynamics, production disruptions, and demand fluctuations across unrelated sectors. For slewing bearing producers, this translates into ongoing pressure to optimize material utilization, negotiate long-term supply agreements, or explore alternative formulations that maintain performance while mitigating price exposure.
External Tooth Slewing Bearing Market
The operational footprint of manufacturers is also evolving. thyssenkrupp rothe erde USA's announcement in May 2026 to consolidate operations in Aurora, relocating from Kentucky, illustrates a broader pattern of operational rationalization aimed at improving efficiency and reducing logistical complexity. Such moves are not purely cost-driven; they also reflect strategic decisions to align production capacity with key customer clusters and streamline engineering and service support. As supply chains continue to adjust, proximity to end markets and the ability to deliver integrated solutions, including drives and gears, will increasingly influence supplier selection.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of globally recognized engineering firms and specialized manufacturers with strong regional or application-specific positioning. SKF operates as a broad-line manufacturer of standard and customized slewing bearings with outside diameters ranging from 0.1 to 18 meters, giving it the capability to serve a wide spectrum of industrial applications. Kaydon Bearings has established a notable presence in wind energy applications, supplying slewing ring bearings and thin section bearings that align with the precision and reliability requirements of renewable energy infrastructure.
Thyssenkrupp Rothe Erde maintains a leadership position in large-diameter slewing bearings up to 25,000 millimeters, supported by facilities across Asia, Europe, and the Americas. This global footprint and specialization in very large components create a strong competitive moat in sectors such as heavy construction, mining, and industrial machinery where extreme load capacity is non-negotiable. Scheerer Bearing Corporation and SlewPro focus more intensively on high-quality slewing ring bearings, drives, and custom-engineered rings for OEM and U.S. industrial customers, emphasizing precision manufacturing and direct engineering collaboration.
In Europe, TGB Group and QCB provide slewing rings, drives, and thin section bearings across a broad diameter range, with QCB covering sizes from 100 millimeters to over 10,000 millimeters. Silverthin Bearing Group has carved out a distinct position in precision thin section and slewing ring bearings for aerospace, robotics, and industrial uses, reflecting a strategy oriented toward high-value niche applications rather than volume-driven heavy machinery.
In Asia, LDB Bearing and Fenghe Slewing Bearing represent the growing capability of Chinese manufacturers to serve heavy machinery, cranes, and OEM/ODM markets. Fenghe's positioning as a custom manufacturer capable of replacing SKF and Kaydon equivalents highlights the ongoing shift in cost-competitive sourcing options, particularly for applications where performance equivalence can be demonstrated and certification pathways are accessible. Xuzhou Wanda Slewing Bearing Co., Ltd.'s participation at CONEXPO-CON-AGG 2026 and LDB Bearing's exhibition at bauma CONEXPO INDIA 2026 further illustrate how manufacturers are using major trade events to strengthen visibility and build relationships within key end-use markets.
The strategic positioning within this landscape tends to fall into several distinct patterns. Large-diameter specialists leverage engineering depth and global service networks to defend high-load segments. Precision and thin-section players pursue diversification into high-technology sectors where specification rigor and customization create barriers to entry. Cost-competitive manufacturers expand their OEM and ODM footprint by offering functional equivalents to established Western brands, often backed by flexible production and growing certification capabilities.
Looking ahead, the market is likely to experience both consolidation and continued fragmentation, depending on segment and geography. In heavy-duty and large-diameter segments, scale advantages and integrated service offerings may encourage consolidation as customers seek reliable single-source partners for complex projects. In precision and specialized segments, fragmentation may persist as new applications emerge and smaller, agile suppliers develop domain expertise. The presence of multiple manufacturers investing in trade shows, catalogs, and operational consolidation suggests an industry in transition rather than one approaching maturity-driven stagnation.
Future Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape the slewing bearings market in ways that directly influence commercial strategy. The first is the deepening integration of slewing bearings with drive systems and precision control components. As equipment designs become more compact and performance expectations rise, suppliers that can deliver coordinated bearing-plus-drive solutions will be better positioned to capture value at the subsystem level rather than competing solely on component pricing. This trend favors manufacturers with engineering capabilities that extend beyond the raceway and rolling elements into gearbox integration, lubrication management, and application-specific mounting configurations.
A second trend is the growing importance of compliance-driven differentiation. As standards become more detailed and sustainability requirements more explicit, suppliers that can provide documented traceability, validated operating envelopes, and environmentally aligned manufacturing practices will gain an advantage in procurement processes where risk mitigation and regulatory conformance carry significant weight. This does not mean every contract will hinge on sustainability credentials, but in sectors with public funding, multinational operators, or offshore and marine applications, the compliance profile of a supplier is increasingly part of the evaluation framework.
A third trend is geographic rebalancing of demand and production capacity. Asia Pacific remains a substantial revenue contributor, reflecting both industrial expansion and a growing base of regional OEMs and project developers. At the same time, trade show participation by Asian manufacturers in North American and Indian markets indicates a deliberate effort to build direct relationships and expand export-oriented sales channels. For established Western manufacturers, this creates opportunities to differentiate through advanced engineering, certified compliance, and integrated service, while also requiring vigilance regarding cost-competitive substitution in price-sensitive applications.
These trends translate into commercial opportunities for companies that align their product strategies with where value is shifting. Manufacturers that invest in precision-grade portfolios, integrated drive offerings, and documentation-ready compliance processes can access higher-margin segments. Procurement leaders that engage suppliers early in the specification process can optimize total cost of ownership by balancing upfront pricing against fatigue life, maintenance intervals, and regulatory alignment. Investors evaluating the sector should pay attention to manufacturers demonstrating both application diversification and operational efficiency, as these characteristics are likely to support resilience across procurement cycles.
Potential risks remain, particularly around raw material cost volatility and the pace at which regulatory requirements propagate across regions. If alloy steel and specialty material pricing remain unstable, margin management will continue to test operational discipline. If sustainability and performance standards diverge between regions, manufacturers serving multiple markets may face added complexity in maintaining compliant product lines without excessive cost overhead. These uncertainties do not negate the growth trajectory, but they do underscore the need for strategic flexibility and a clear view of where cost and compliance exposures are concentrated.
Strategic Actions for Decision Makers
For manufacturers and product leaders, the priority is to determine where to compete along the precision-versus-volume spectrum. A balanced approach may involve maintaining standardized offerings for high-volume industrial applications while building dedicated engineering capacity for thin-section, aerospace-adjacent, or integration-heavy applications. Supplier development should also account for material cost exposure, whether through long-term alloy sourcing agreements, design-for-manufacturability initiatives that reduce material waste, or alternative process investments that preserve fatigue performance under cost constraints. Participation in major industry events and proactive catalog or specification updates can strengthen visibility and shorten the sales cycle in markets where equipment builders are actively evaluating suppliers.
For investors and strategic planners, the focus should be on identifying operators with durable competitive advantages in the segments most likely to sustain margin integrity. Large-diameter specialists with global service networks, precision players with diversified high-technology exposure, and cost-competitive manufacturers with credible OEM/ODM relationships each represent distinct risk-return profiles. Evaluating these profiles requires attention to revenue mix, engineering capability, compliance readiness, and operational footprint decisions such as capacity consolidation or regional expansion. Companies that can demonstrate the ability to serve demanding specifications while managing material and regulatory exposure are better positioned to capture value as the market progresses toward the 2032 horizon.
For procurement and engineering leaders in end-use industries, the strategic imperative is to treat slewing bearing selection as a total-cost and risk-management decision rather than a transactional purchase. Engaging suppliers during the design phase can reveal trade-offs between standard catalog options and custom configurations, allowing project teams to weigh initial cost against service life, maintenance requirements, and compliance alignment. As standards such as ISO 16123:2025 and evolving sustainability guidelines become embedded in procurement expectations, supplier documentation and process transparency will become increasingly valuable in reducing downstream operational risk. Building a supplier base that includes both broad-capability and specialized partners can provide flexibility across different equipment classes and project constraints.
The slewing bearings market is moving along a growth path shaped by engineering sophistication, regulatory maturation, and broadening application scope. For decision makers who need detailed segmentation data, regional breakdowns, competitor benchmarking, and customized scenario analysis, a comprehensive research report can provide the granular evidence required to translate these strategic themes into operational plans. Access to that level of detail supports more precise capital allocation, supplier selection, and product roadmap decisions as the market continues its trajectory toward 2032.
For detailed analysis of this topic, please visit the official page: Slewing Bearings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sterile Medical Packaging Market: Why 7.65% CAGR Reshapes Strategy Through 2032
By PW Consulting, 2026-09-21
Strategic Shifts in the Sterile Medical Packaging Market: Navigating Growth, Regulation, and Material Evolution
The sterile medical packaging market is approaching a defining period of structural transformation. Valued at approximately $501 million in 2025, the sector is projected to expand to $834 million by 2032, reflecting a compound annual growth rate of 7.65 percent. This trajectory is not merely a function of volume growth; it signals a deeper recalibration of how healthcare products are protected, delivered, and compliant with evolving regulatory and environmental mandates. Over the historical window from 2020 through 2025, the market demonstrated steady resilience, with revenue climbing from $350 million to its current level despite periodic supply chain volatility and shifting procurement patterns. The forward-looking period from 2026 to 2032 will test players' ability to align technological capability, regulatory readiness, and sustainable material strategies.
For executives, strategists, and investors, the implication is clear: sterile packaging is no longer a commoditized containment layer. It has become a critical enabler of product integrity, regulatory compliance, and brand positioning. The industry's expansion is unevenly distributed across material types, applications, and regions, but the underlying forces shaping these segments share common denominators. Understanding those drivers—and the competitive responses they are triggering—provides a roadmap for capital allocation, product development, and supply chain decisions.
Market Snapshot and Core Challenges
The market's baseline reflects a mature yet still expanding ecosystem. Revenue growth from 2020 to 2025 moved from $350 million to $501 million, a path marked by incremental acceleration rather than explosive jumps. The forecast period anticipates continued upward movement, with figures progressing from $550 million in 2026 to $834 million in 2032. The 7.65 percent CAGR sits in a range that suggests durable demand anchored in healthcare volume growth, but also indicates that market share dynamics will increasingly reward players who can navigate regulatory complexity, material constraints, and differentiation pressures. Market concentration remains modest, with the top three firms accounting for roughly 24.6 percent of revenue and the top five representing 28.3 percent. This fragmentation leaves room for both consolidation and targeted disruption.
Several structural challenges are reshaping how companies approach product design, sourcing, and go-to-market strategy. First, the regulatory environment is tightening across multiple jurisdictions simultaneously, raising the compliance floor and increasing the cost of market entry. Second, material cost pressures are compressing margins in categories that rely heavily on conventional resins and films, pushing manufacturers to reconsider substrate choices and lightweighting strategies. Third, the sustainability agenda is moving from aspirational messaging to enforceable requirements, with recyclability mandates, recycled content thresholds, and extended producer responsibility frameworks altering the economics of packaging design. Each of these forces interacts with the others, creating a landscape where technical performance, compliance, and environmental profile must be balanced rather than treated as separate workstreams.
Key Drivers Shaping Market Direction
Technological Innovation and Material Breakthroughs
Advancements in barrier performance, lightweighting, and form-factor flexibility are redefining what sterile packaging can achieve. Thermoformed trays with improved barrier properties are reducing weight while maintaining sterility assurance, an approach that directly addresses both material cost and transportation efficiency. Flexible pouch architectures, header bags, and lid systems continue to gain relevance for medical device and pharmaceutical applications where space, handling, and aseptic presentation matter. At the same time, glass and plastic primary packaging options are being refined to meet stringent cleanliness and compatibility requirements for injectable and implantable products. Innovation is increasingly oriented around dual objectives: preserve sterility and usability while reducing material intensity and improving end-of-life pathways.
Recent product introductions illustrate this direction. Lightweight thermoformed tray designs with enhanced barrier characteristics have been launched to serve sterile medical device applications, signaling a shift toward higher performance per unit of material. In parallel, sustainable glass packaging solutions for medical and nutraceutical use have been showcased at industry platforms, highlighting the role of glass as a reusable and recyclable substrate in contexts where clarity, protection, and formulation compatibility are paramount. These developments suggest that differentiation will increasingly stem from engineering efficiency and substrate selection rather than from packaging as a static barrier alone.
Regulatory and Policy Environment
Regulatory shifts are among the most consequential drivers of near-term strategy. In the United States, updated recognition of ISO 11607-1 for packaging of terminally sterilized medical devices is moving toward a compliance deadline that requires full adherence by December 2026. This standard influences testing protocols, material qualification, and validation practices across the device packaging lifecycle. Simultaneously, the U.S. Quality Management System Regulation, which aligns with ISO 13485:2016, requires full compliance by February 2026 for sterile medical packaging manufacturers. The convergence of these requirements raises the bar for documentation, process control, and supply chain traceability.
On the other side of the Atlantic, the EU Packaging and Packaging Waste Regulation has entered into force with a mandate that all packaging be recyclable by 2030, while recycled content requirements begin in 2026 and eco-modulated extended producer responsibility fees apply to producers. These provisions change the cost calculus for material choices and incentivize designs that perform well in recycling streams. In the United States, a growing patchwork of state-level packaging EPR programs across several states ties producer fees to recyclability and recycled content, adding a regional compliance layer for firms that serve national or multi-regional markets. Together, these regulatory currents are turning sustainability from a brand narrative into an operating requirement with measurable cost implications.
Demand-Side Evolution
Demand patterns are being reshaped by the broader trajectory of healthcare delivery and product complexity. Pharmaceutical and biological applications remain the largest demand pool, followed by surgical and medical instruments, with in vitro diagnostic products, medical implants, and other categories contributing additional volume. The common thread across these segments is a rising expectation that packaging must support aseptic handling, reduce contamination risk, and integrate smoothly with automated processing and sterilization workflows. As care settings expand beyond traditional hospital environments and device miniaturization continues, packaging is expected to be lighter, more adaptable, and more compatible with varied sterilization modalities.
Procurement behavior is also changing. Buyers are increasingly attentive to supply reliability, regulatory documentation, and environmental performance in addition to unit cost. This creates an opening for suppliers that can present validated, compliant, and materially efficient solutions with clear end-of-life profiles. It also places pressure on manufacturers to demonstrate consistent quality across batches and geographies, particularly where materials and components cross borders. The result is a demand environment that rewards transparency, technical support, and demonstrated compliance as much as it rewards price competitiveness.
Aseptic Packaging Market
Supply Chain and Cost Structure Dynamics
Cost structures are under pressure from multiple directions. Resin and film inputs remain a central variable for plastic-based sterile packaging, with producer price indices for plastics packaging film and sheet manufacturing indicating continued cost intensity. Volatility in feedstock pricing, energy costs, and logistics can quickly alter margin assumptions, especially for high-volume flexible and thermoformed products. At the same time, tighter regulatory requirements increase the cost of validation, testing, and documentation, while recycled content mandates can reshape the available supply of qualified substrates.
PW Consulting
These dynamics are prompting companies to revisit material mix, product geometry, and sourcing strategies. Lightweighting, consolidation of SKUs, and improved yield in conversion processes are becoming levers for margin protection. Suppliers that can offer stable input pipelines, qualified alternative materials, and efficient conversion technologies are gaining negotiating leverage. The broader lesson is that cost competitiveness in sterile packaging is less about chasing the lowest input price and more about engineering resilience into material selection, process design, and supplier relationships.
Competitive Landscape and Leading Strategies
The competitive field is diverse and moderately fragmented, with players occupying distinct positions based on material expertise, application focus, and regional reach. Several companies illustrate how strategy diverges across the market.
Amcor is positioned around thermoformed trays and flexible sterile medical packaging with an emphasis on responsible healthcare solutions, tying performance to sustainability-oriented positioning. DuPont de Nemours brings recognized material science to sterile pouches, header bags, and lids for medical device packaging, leveraging Tyvek-based substrates as a differentiated barrier platform. West Pharmaceutical Services focuses on injectable pharmaceutical packaging components and delivery systems for sterile applications, aligning packaging with dosage form and administration requirements. Sonoco Products Company draws on paper-based and composite solutions for rigid and flexible sterile medical packaging, offering a route to fiber-inclusive designs. Gerresheimer AG operates in glass and plastic primary packaging for sterile pharmaceuticals and medical devices, a segment where clarity, compatibility, and recyclability carry strategic weight. BillerudKorsnäs AB supplies medical-grade paper and paperboard for sterile packaging applications, reinforcing the role of fiber-based substrates in segments where structural integrity and recyclability can be engineered together. Placon Corporation specializes in thermoformed medical trays and sterile packaging solutions, with an emphasis on device-oriented applications. Nelipak Healthcare Packaging addresses high-volume healthcare applications with flexible and rigid sterile packaging, while Steripack Ltd and Constantia Flexibles round out the landscape with custom sterile solutions and flexible pharmaceutical and medical packaging, respectively.
These positions reveal several strategic themes. One is material expertise as a moat: companies that command recognized substrates, validated conversion processes, and specialized barrier properties can command premium positioning and longer qualification cycles. Another is application alignment: firms that connect packaging form factors to specific device, pharmaceutical, or diagnostic workflows are better equipped to provide value-added engineering support and regulatory documentation. A third is sustainability integration: with regulatory and buyer expectations moving toward recyclability and recycled content, players that can offer compliant, recyclable, and lower-material-intensity designs are building a differentiation edge that goes beyond price.
The market structure suggests room for both consolidation and continued fragmentation. Larger, diversified players may pursue bolt-on acquisitions to broaden material capabilities or geographic coverage, while niche specialists may deepen their focus on high-value applications, custom formats, or regional compliance expertise. New entry is possible where technology, qualification speed, or sustainability credentials offer a clear advantage, but the regulatory and validation burden in sterile packaging tends to favor incumbents with established documentation systems and customer relationships. The net effect is a landscape where growth will be captured by companies that can combine material performance, compliance readiness, and efficient cost structures rather than by scale alone.
Looking Ahead: Three Trends to Watch
Regulatory-Driven Material Redesign
Over the next three to five years, the most consequential trend will be the redesign of sterile packaging around recyclability, recycled content, and regional compliance requirements. As EU mandates tighten and U.S. state-level extended producer responsibility programs expand, packaging architectures that perform well in recycling streams and reduce reliance on hard-to-recycle layers will gain preference. This does not mean a uniform shift to a single substrate; rather, it points to a more segmented material strategy in which plastic, glass, metal, paper and paperboard, and composite options are selected based on application needs and end-of-life feasibility. Companies that build modular design capabilities and maintain a qualified portfolio of substrates will be better positioned to adapt to divergent regional rules without sacrificing sterility or usability. The commercial opportunity lies in offering compliant designs that also reduce total material use and improve handling efficiency, creating value for both the manufacturer and the customer.
Engineering-Efficiency as a Margin Defense
A second trend is the growing importance of engineering efficiency as a safeguard against input cost volatility and compliance-related overhead. Lightweighting, improved barrier performance per unit of material, and optimized thermoformed or flexible formats can lower transport costs, reduce resin consumption, and support sustainability targets simultaneously. Product launches that emphasize enhanced barrier properties in lighter formats point in this direction. The businesses likely to benefit are those that can translate material science into repeatable conversion processes, maintain tight quality control, and provide customers with validated, application-specific designs. For investors, the signal is to look beyond headline volume growth and assess which companies are building durable cost resilience through engineering rather than relying on price pass-through alone.
Compliance Infrastructure as a Competitive Barrier
A third trend is the elevation of compliance infrastructure into a strategic asset. With the updated ISO 11607-1 recognition, the Quality Management System Regulation alignment, and multiple recycling and recycled content mandates, the documentation, validation, and process control requirements are becoming more demanding and more interconnected. Suppliers that can provide clear qualification records, stable quality systems, and transparent traceability will reduce risk for device and pharmaceutical customers navigating their own compliance obligations. Over time, this can translate into longer customer relationships, fewer re-qualification cycles, and stronger positioning in regulated segments. The risk is that firms without robust quality systems may face rising rejection costs, project delays, and erosion of trust, especially where multi-region compliance is required.
Plastic Medical Packaging Market
Actionable Insights for Decision-Makers
For Manufacturers and Suppliers
- Audit material portfolios against upcoming recyclability and recycled content requirements, prioritizing designs that maintain sterility and performance while improving end-of-life outcomes.
- Invest in lightweighting and barrier optimization to reduce material intensity and logistics costs, treating engineering efficiency as a core margin lever rather than a secondary improvement.
- Strengthen quality management and validation documentation to align with updated standards and QMS expectations, reducing re-qualification friction and supporting faster customer onboarding.
- Diversify substrate options and conversion capabilities to buffer against resin and film cost volatility, using flexible or paper-inclusive designs where application requirements permit.
For Investors and Capital Allocators
- Focus on companies that demonstrate a credible combination of material expertise, compliance readiness, and cost-resilient engineering, since these attributes are increasingly decisive in a tightening regulatory environment.
- Evaluate exposure to regional regulatory divergence, especially where EPR frameworks and recycling mandates can alter cost structures and demand preferences across markets.
- Track product launches and trade activity that signal shifts toward sustainable glass solutions, lightweight thermoformed formats, and higher-performance flexible architectures, as these often presage broader portfolio direction.
- Consider the fragmentation of the market as both a risk and an opportunity, weighing consolidation potential against the durability of niche advantages in specialized applications or substrates.
For Procurement and Supply Chain Leaders
- Prioritize suppliers that can provide validated, compliant packaging with clear sustainability attributes, since these reduce downstream qualification burden and align with internal ESG and compliance goals.
- Assess total cost of ownership rather than unit price alone, factoring in lightweighting benefits, logistics efficiency, compliance documentation, and the stability of the supplier's quality system.
- Build visibility into material sourcing and regulatory timelines, particularly where state-level EPR programs and international recyclability mandates may affect availability, cost, and specification changes.
- Request application-specific engineering support and barrier performance data to ensure packaging choices match sterilization modality, handling requirements, and device or pharmaceutical characteristics.
The sterile medical packaging market is moving into a phase where growth will be shaped as much by regulatory alignment, material efficiency, and compliance infrastructure as by volume expansion. The companies and investors that can read these signals clearly, adapt product and sourcing strategies accordingly, and build durable qualification and quality systems will be best positioned to capture the next wave of value creation. For decision-makers seeking deeper segmentation data, region-specific regulatory mapping, and tailored strategic recommendations, a comprehensive market research report can provide the granular detail and scenario analysis needed to translate these high-level trends into precise business actions.
For detailed analysis of this topic, please visit the official page: Sterile Medical Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fiber Laser Cutting Machines Market: Why 3D Precision + Asia Pacific Push Reshape Growth
By PW Consulting, 2026-09-21
Fiber Laser Cutting Machines Market: Strategic Trends and Commercial Opportunities Through 2032
Navigating a Market in Transition
The fiber laser cutting machines market has evolved from a specialized manufacturing niche into a foundational technology stack for industrial metal processing. Valued at approximately USD 1.74 billion in 2025, the market is projected to reach USD 2.51 billion by 2032, reflecting a compound annual growth rate of 5.3 percent over the 2026 to 2032 forecast period. This trajectory signals steady, structurally supported expansion rather than cyclical hype. The growth is underpinned by a broader industrial shift toward precision fabrication, automation, and energy-conscious production methods. However, steady headline growth masks underlying complexity. Manufacturers, investors, and procurement leaders must look beyond aggregate figures to understand where value is concentrating, which segments are decoupling from the average, and how competitive dynamics are reshaping pricing power and innovation cycles.
Core Challenges and Inflection Points
Three structural challenges define the current market landscape and will determine which players capture disproportionate share over the next several years.
First, the market exhibits moderate concentration, with the top three players commanding roughly 36 percent of revenue and the top five reaching approximately 48 percent. This concentration indicates a mature core of established suppliers with strong brand equity, service networks, and installed-base advantages. Yet it also suggests that meaningful disruption is unlikely to come from a single breakthrough entrant. Instead, competitive pressure will accumulate through incremental differentiation in beam quality, automation integration, software-enabled workflow optimization, and total cost of ownership. Companies that treat fiber laser cutting as a pure hardware play risk being undercut by competitors offering integrated solutions that reduce labor dependence and improve throughput.
Second, raw material dependency introduces strategic vulnerability. The performance of fiber laser cutting machines hinges on rare-earth-doped optical fiber gain media, typically ytterbium-doped, which generate the beam through solid-state excitation and focus it through precision optics. While this solid-state architecture eliminates many of the maintenance and alignment challenges associated with traditional mirror-based systems, it also ties machine performance and supply continuity to specialized fiber production and rare-earth supply chains. Price volatility, geopolitical trade dynamics, and manufacturing bottlenecks in optical fiber components can affect lead times, cost structures, and ultimately margin trajectories for both suppliers and end users.
Medical Fiber Laser Market
Third, regulatory and safety compliance is becoming a more prominent market filter rather than a background requirement. Occupational safety frameworks and international standards increasingly mandate Class 4 laser safety features, including automatic beam shutters and protective enclosures. Export and market access requirements in major regions also demand certifications such as CE and FDA/CDRH compliance for relevant applications. For manufacturers, compliance is no longer a checkbox; it shapes product architecture, time-to-market, and the ability to serve multi-region customer bases. For buyers, certification status and safety design influence deployment risk, insurance considerations, and integration complexity.
Key Demand Drivers Shaping the Market
Technology Innovation and Beam Quality as a Competitive Lever
Performance differentiation is increasingly defined by beam quality, power density, and the ability to maintain cut precision across thicker or more complex materials. Recent product milestones illustrate how suppliers are pushing these boundaries. In mid-2026, IPG Photonics received the SPIE Prism Award for a novel 8 kW compact single-mode fiber laser source with beam quality below an M2 of 1.1. This type of advancement matters because tighter beam quality supports finer feature cutting, improved edge quality, and more efficient material processing, which in turn reduces rework and downstream finishing costs. For end users, the practical implication is that laser source performance is becoming a deciding factor in machine selection, especially where precision and repeatability directly affect part economics.
Equally important is the integration of laser sources into broader machine architectures that support higher productivity and more flexible workflows. High-power platforms designed for industrial cutting and machine tool integration are expanding the range of feasible applications, from conventional sheet metal fabrication to more demanding components in automotive, aerospace, and energy-related production. As platforms mature, the value proposition shifts from raw cutting speed to consistent process reliability, reduced setup time, and easier integration with downstream automation.
Policy, Regulation, and Energy Efficiency as Adoption Accelerators
Policy and regulatory dynamics are acting as an underappreciated demand catalyst. Energy efficiency mandates and broader sustainability pressures are accelerating adoption of fiber laser cutting machines over legacy approaches, largely because solid-state designs require fewer mirrors and generally offer lower operating costs. In practical terms, this means total cost of ownership calculations are becoming more favorable for fiber-based solutions in many industrial settings, especially where electricity consumption, maintenance intervals, and consumables influence procurement decisions.
At the same time, safety and market-access regulation are shaping product design and deployment. Mandatory Class 4 laser safety features, automatic shutters, and enclosed systems are becoming standard expectations rather than premium options. In export-facing markets, compliance with CE and relevant U.S. certification requirements is essential for commercial viability. The strategic takeaway is that regulatory alignment is now part of the product’s competitive positioning. Suppliers that design compliance into their platforms from the outset can reduce integration friction for customers and move faster in multi-region sales cycles.
Demand-Side Shifts: Automation Gaps and Workforce Pressures
Demand is being reshaped by a structural labor challenge in metal fabrication. Automation labor shortages are driving demand for high-power fiber laser systems that enable faster, more precise processing with reduced manual intervention. This is not simply a preference for faster machines; it reflects a broader operational need to stabilize throughput, improve consistency, and reduce dependency on scarce skilled labor. In many shops, the decision to invest in advanced laser cutting technology is inseparable from the desire to reduce variability in production and free human workers for higher-value tasks such as programming, quality control, and process optimization.
The application landscape reflects these demand-side pressures. Fiber laser cutting is increasingly embedded in general machinery processing and automotive-related fabrication, where repeatability and throughput are critical. At the same time, use cases in home appliances, aerospace, and shipbuilding illustrate the technology’s expanding versatility across different material thicknesses, tolerances, and production volumes. The commercial opportunity lies not only in selling machines, but in aligning machine capabilities with the specific workflow constraints of each sector, including batch size, material mix, and integration with existing fabrication lines.
Supply Chain and Cost Structure Realignment
Cost structures are being reshaped by the intersection of automation demand, component specialization, and system-level integration. On the supply side, the specialized nature of fiber gain media and precision optics means that cost leadership is increasingly tied to vertical coordination, long-term supplier relationships, and scale in critical subsystems. On the customer side, procurement decisions are increasingly influenced by life-cycle economics rather than upfront price alone. Energy consumption, maintenance complexity, scrap reduction, and labor efficiency all contribute to the economic case for upgrading or expanding fiber laser capacity.
This environment favors suppliers that can articulate a clear total cost narrative and support it with service, training, and software-enabled process control. It also creates openings for regional and value-oriented competitors that can deliver reliable performance at a lower price point for specific applications, particularly where customers prioritize speed to deployment and manageable initial capital outlay. The market is therefore becoming more segmented in practice, even if headline growth appears uniform.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Leading Players
The competitive field blends global technology leaders with specialized system builders and regional players targeting distinct customer segments. Several patterns stand out.
IPG Photonics continues to emphasize its position as a leading source of fiber laser technology and integrated systems, with a focus on custom robotic and automated cutting cells as well as high-power industrial solutions for metal fabrication. Its competitive advantage is rooted in source performance and system-level flexibility, which allows it to serve applications where beam quality, power scaling, and automation readiness are central to the purchase decision.
TRUMPF has built a strong industrial footprint around fiber laser cutting platforms and associated laser technology, including bevel cutting and automation for sheet metal processing. Its recent high-productivity fiber laser series, launched in mid-2025, targets industrial welding and cutting applications, including EV battery components. That product direction signals a clear strategic intent: align laser capabilities with high-growth manufacturing priorities where precision, throughput, and component complexity are increasing.
Bystronic competes through integrated sheet metal solutions that combine laser cutting systems with advanced automation and software. Its product showcasing at major industry events in 2025 highlighted modular frame designs and upgraded cutting heads, reinforcing an emphasis on flexibility, productivity, and integration. By early 2026, the company finalized the acquisition of Coherent’s Tools for Materials Processing unit, expanding its fiber laser capabilities and strengthening its position across the broader materials processing value chain. This move illustrates a consolidation logic that prioritizes capability expansion, installed-base leverage, and cross-product integration.
Coherent has focused on high-power fiber laser platforms for industrial cutting and machine tool integration, with product announcements in late 2025 underscoring its emphasis on industrial-grade performance and integration readiness. Its positioning reflects the growing importance of source and platform reliability in demanding applications across automotive, aerospace, and energy-related sectors.
Beyond the largest global suppliers, a broader set of companies is competing on specific value propositions. Some emphasize speed, precision, and reduced labor requirements for metal fabrication. Others target commercial and industrial engraving and cutting with enclosed or open-bed designs suited to different shop environments. Heavy-duty industrial systems remain an important category for high-efficiency processing and cut quality in more demanding workloads. Meanwhile, certain international-oriented producers have built commercial appeal around multi-material capability and accessible pricing for specific commercial applications. The presence of CNC-focused manufacturers with fully enclosed fiber laser systems and autofocus sensors also reflects the broader trend toward ease of use, larger work areas, and reduced operator dependency.
How the Landscape Is Evolving
The market is not simply consolidating; it is simultaneously consolidating at the high end and fragmenting in adjacent segments. At the premium and industrial end, acquisitions and product integration are strengthening the ability of leading players to offer end-to-end solutions rather than isolated hardware. This matters because buyers increasingly want predictable performance, service continuity, and software-driven process control across the entire cutting workflow.
PW Consulting
At the same time, new entrants and regional specialists continue to find room by targeting specific buyer priorities: lower entry cost, faster deployment, specialized material ranges, or commercial-use flexibility. The result is a layered competitive environment where leadership in one segment does not automatically translate into leadership across all segments. For investors and executives, this means that market share narratives can be misleading unless they are tied to segment economics, application fit, and regional dynamics.
A further evolution is the growing importance of ecosystem value. Companies that can combine laser sources, machine design, automation interfaces, and process software into a coherent solution are better positioned to capture long-term value from installation, training, maintenance, and upgrades. In contrast, purely transactional hardware competition tends to compress margins and shift the battle to price, which is a less durable position in a market where integration and reliability matter increasingly.
Forward Trends and Commercial Implications
Trend 1: Productivity-Driven System Design Will Redefine Procurement Criteria
Over the next three to five years, procurement decisions are likely to place greater weight on productivity per shift, automation readiness, and process consistency than on nominal cutting speed alone. High-power platforms, improved beam quality, and more capable cutting heads will continue to raise the baseline for what buyers expect from a modern fiber laser workstation. The commercial opportunity for suppliers is to package these advances into demonstrable operational improvements: shorter setup times, fewer rejects, smoother integration with material handling, and reduced reliance on manual interventions. For buyers, the strategic task is to evaluate machines not as isolated tools but as nodes in a broader fabrication workflow.
Trend 2: Consolidation and Capability Expansion Will Reshape Supply Options
Continued consolidation among leading suppliers will likely expand the range of integrated offerings available to industrial customers, particularly where materials processing capabilities can be combined with cutting, automation, and service infrastructure. This trend may improve solution coherence and reduce vendor fragmentation for large buyers, while also raising the bar for smaller competitors that must clearly articulate a differentiated niche. A practical risk is that consolidation could narrow choice in certain specialized segments if mid-tier players are absorbed or squeezed out. Buyers should therefore monitor not just who wins share, but which application-specific capabilities remain independently available and competitively priced.
Trend 3: Regulatory Design and Safety Features Will Become Table Stakes
Safety architecture, enclosure design, beam control, and certification readiness will move from compliance costs to core product attributes. This shift will favor manufacturers that incorporate these requirements early in the design process and develop repeatable processes for multi-region market entry. For procurement teams, certification and safety design should be evaluated alongside performance claims, since non-compliance or incomplete safety integration can increase deployment risk, delay commissioning, and complicate operator training. Energy efficiency expectations will also continue to influence adoption, reinforcing the appeal of solid-state fiber platforms in settings where operating cost and regulatory alignment both matter.
Risks and Uncertainties to Monitor
Several factors could alter the pace or distribution of market gains. Supply continuity for specialized optical fiber components and rare-earth dependencies may create cost or availability pressure at irregular intervals. Macroeconomic volatility can affect capital equipment budgets, particularly in smaller fabrication shops and cyclical end markets. Regulatory changes could raise compliance costs or shift market access requirements, especially for exporters serving multiple jurisdictions. Finally, the pace of automation adoption may vary by region and sector, meaning that demand growth will not be evenly distributed across applications or customer sizes. Companies that depend on a single geography, a narrow application mix, or a single cost advantage are more exposed to these shifts than those with diversified customer bases and flexible product portfolios.
Actionable Implications for Decision Makers
For Manufacturers and Solution Providers
Position around integration and total cost of ownership rather than hardware specifications alone. The most durable value capture will come from combining reliable laser sources, automation-friendly machine design, and software-enabled process support into a solution that reduces labor dependency and improves consistency. Pay close attention to beam quality, cutting head upgrades, and modular architectures that allow customers to scale capability without replacing entire systems. Also treat compliance and safety design as part of the product narrative, since these attributes increasingly influence procurement confidence and regional market access.
For Investors
Look beyond aggregate growth rates and evaluate where margin resilience and differentiation are actually being built. Companies with strong positions in automation integration, high-power industrial platforms, and multi-region compliance readiness are better placed to defend pricing and capture upgrade cycles. Monitor consolidation activity carefully, since acquisitions can expand capability but also change competitive dynamics in adjacent segments. Be cautious of businesses whose growth depends primarily on price competition in commoditizing segments, as this positioning tends to weaken as installed bases mature and buyers become more sophisticated.
For Procurement and Operations Leaders
Evaluate fiber laser investments as a workflow decision. The strongest returns usually come from matching machine capabilities to specific production constraints: material mix, typical batch sizes, required edge quality, labor availability, and downstream automation. Ask how a system will perform across the full life cycle, including energy use, maintenance demands, operator training, and integration with existing material handling or software infrastructure. Certification status, enclosure design, and safety features should be reviewed as operational requirements, not just regulatory formalities. Where possible, prioritize suppliers that can demonstrate consistent process reliability and support upgrades as production needs evolve.
Laser Cutting Machines Market
Closing Perspective
The fiber laser cutting machines market is moving from a phase defined by technical adoption to one shaped by integration, productivity, and operational resilience. Growth is supported by broader industrial needs for precision, automation, and energy-efficient production, but the real strategic question is no longer whether fiber laser technology is gaining ground. It is which suppliers, investors, and buyers can best align product capability, compliance readiness, and workflow economics with the increasingly segmented demands of modern metal fabrication. Detailed segmentation data, regional breakdowns, and customized scenario analysis can help decision makers translate these market-wide dynamics into concrete capital and sourcing choices. For those evaluating next steps, a deeper dive into the full research landscape offers a more granular view of where growth is concentrating and how competitive positions are likely to evolve through 2032.
For detailed analysis of this topic, please visit the official page: Fiber Laser Cutting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Polyethylene Glycol Market: Strategic Trends and Commercial Opportunities Through 2032
The global landscape for polyethylene glycol (PEG) is undergoing a quiet but significant transformation. Valued at approximately 5,780 million USD in 2025, the market has expanded steadily from a base of roughly 4,400 million USD in 2020, reflecting a compound annual growth rate of about 6.0 percent through 2032. While the headline trajectory suggests steady expansion, the underlying dynamics tell a more nuanced story. Demand composition, regulatory pressure, regional production footprints, and raw material volatility are reshaping where growth will materialize and which players will capture it.
PW Consulting
For executives, strategists, and investors, PEG is no longer a commodity chemical with uniform margins and predictable demand. It is a differentiated specialty input where formulation requirements, compliance standards, and sourcing resilience increasingly determine competitive advantage. The next several years will reward companies that can align technical capabilities with shifting regulatory and demand-side expectations while managing cost exposure across a tightening supply chain.
Market Snapshot and Core Challenges
The PEG market's scale and growth rate mask important structural pressures. Historical revenue patterns from 2020 through 2025 show consistent year-over-year gains, with forward projections indicating continued expansion into the early 2030s. Growth, however, is no longer evenly distributed across applications or regions. Certain end-use segments are absorbing demand faster than others, and regional production centers are repositioning to serve localized compliance and logistics requirements.
Several interconnected challenges define the current inflection point.
Regulatory scrutiny of environmental persistence is reshaping formulation choices. Authorities in key markets have tightened restrictions on polymers that demonstrate persistence in aquatic ecosystems, including certain PEG derivatives. Because PEG is derived from petroleum-based ethylene oxide and is not inherently biodegradable, these regulatory shifts are prompting formulators and producers to reassess product specifications, documentation, and lifecycle profiles. For markets that depend on consumer-facing and pharmaceutical applications, compliance is becoming a gatekeeping function rather than a back-office consideration.
Raw material cost volatility is compressing margins and complicating planning. Ethylene glycol prices in Asia moved largely downward during the second half of 2025 under strong supply pressure, illustrating the kind of input fluctuation that can disrupt cost structures across the value chain. While lower feedstock costs can improve producer margins in the short term, the broader pattern is one of unpredictability. Manufacturers and buyers alike face challenges in forecasting landed costs, negotiating long-term contracts, and maintaining consistent pricing in end products that rely on PEG as a functional ingredient.
Concentration among leading producers creates both resilience and strategic risk. The market remains moderately concentrated, with a small group of major suppliers holding a substantial share of total revenue. This concentration can stabilize supply for large-scale buyers, but it also introduces dependency risk when regulatory changes, capacity constraints, or regional disruptions affect a handful of critical facilities. Companies that rely on narrow sourcing channels are increasingly exposed to price resets and qualification delays, especially when switching to alternative grades requires revalidation.
These challenges are not abstract. They directly affect product roadmaps, procurement strategies, and investment timing. The companies that navigate them best will treat regulatory alignment, cost controllability, and supply diversification as strategic design parameters rather than operational afterthoughts.
Key Drivers Reshaping the Market
Market momentum is being driven by a combination of technical, regulatory, demand-side, and supply chain forces. Understanding how these drivers interact is essential for anticipating where growth will concentrate.
Technical Innovation and Formulation Differentiation
One of the strongest catalysts for change is continued innovation in PEG grades and reactive derivatives. Producers are expanding portfolios that support more precise solubility, viscosity, and reactivity profiles for specialized formulations. For example, the introduction of reactive polyethylene glycol grades for industrial formulators in Europe reflects a broader push toward tailored performance rather than volume-only supply. Such developments matter because they expand the addressable use cases for PEG in complex formulations where standard grades are insufficient.
The strategic implication is clear. Differentiation is increasingly tied to grade specificity, purity profiles, and application support rather than price alone. Manufacturers that can offer documented quality, regulatory readiness, and technical assistance are better positioned to deepen relationships with formulation-intensive buyers. This shifts competition from a transactional model toward a value-added partnership model, particularly in pharmaceuticals and personal care, where compliance and consistency carry a premium.
Regulatory and Compliance Evolution
Regulatory dynamics are not merely constraints; they are also shaping demand for compliant supply and prompting regional capacity realignment. As authorities increase scrutiny of polymer persistence and environmental impact, buyers in regulated sectors are prioritizing suppliers with robust documentation, GMP-aligned production, and traceable quality systems. This environment elevates the importance of production sites that can demonstrate compliance with recognized pharmaceutical and excipient standards.
A notable example is the expansion of GMP-compliant manufacturing capacity in the United States for pharmaceutical-grade PEG excipients, creating a localized production node designed to serve pharma formulations and extend reach into adjacent markets such as Latin America. Moves like this illustrate how regulatory pressure and customer qualification requirements are driving regional production strategies. For buyers, access to compliant, regionally positioned supply reduces qualification risk and shortens response times. For producers, it strengthens positioning in high-value segments where compliance is a competitive moat.
The practical takeaway is that regulatory shifts are accelerating a structural preference for suppliers with verifiable quality credentials and diversified geographic footprints. Companies that proactively align product lines with evolving expectations will face fewer barriers to adoption and fewer interruptions to qualification cycles.
Demand-Side Shifts in Pharmaceuticals and Personal Care
Demand patterns continue to reflect the centrality of PEG in medical and personal care applications, where it functions as an excipient, solubilizer, and formulation aid. Medical applications remain a major demand anchor, supported by ongoing formulation needs in oral, topical, and other pharmaceutical dosage forms. Personal care demand is similarly sustained by the material's functional versatility in creams, lotions, and other consumer products.
At the same time, demand is becoming more selective. Formulators are increasingly balancing performance objectives with concerns about environmental profile, supply continuity, and regulatory acceptability. This does not necessarily reduce PEG usage, but it does elevate the importance of grade selection and supplier reliability. Buyers are more likely to favor established grades with clear documentation when formulation integrity and regulatory approval are at stake, while also seeking options that support evolving sustainability expectations.
This shift favors suppliers that can communicate application-specific benefits clearly and support customers through changes in formulation architecture. It also creates opportunities for companies that can bridge technical performance with compliance assurance, particularly in markets where personal care and pharma overlap in quality expectations.
Supply Chain Reconfiguration and Cost Structure pressures
The PEG value chain remains tied to ethylene oxide-based production, which links market economics to broader petrochemical dynamics. Feedstock movements, regional capacity additions, and logistics considerations all influence cost structures and availability. The recent downward price pressure on ethylene glycol in Asia is one indicator of how quickly supply conditions can change, but it also highlights the importance of flexible procurement strategies.
Supply chain reconfiguration is being driven by more than cost. Regionalization of production, qualification requirements, and the desire to reduce lead-time variability are encouraging buyers and producers to build more localized or near-localized supply relationships. This is especially relevant where compliance-sensitive applications require close oversight of manufacturing conditions. As a result, the market is gradually moving toward a multi-node supply model in which regional production serves regional demand, supported by specialized grades and documented quality systems.
For decision-makers, the strategic question is not simply where costs are lowest today, but where supply can be secured with acceptable risk over the next several years. Cost optimization still matters, but it is increasingly balanced against resilience, qualification speed, and regulatory alignment.
Competitive Landscape and Leadership Strategies
The PEG market features a mix of global chemical specialists and regional producers, each pursuing distinct strategic positions. Rather than competing solely on volume, leading companies are differentiating through portfolio breadth, compliance readiness, regional capacity, and technical support. This competitive diversity is creating a landscape in which customers encounter both broad-scale suppliers and niche specialists, depending on the application and grade requirements.
Strategic Positioning Among Leading Players
Several companies have established recognizable positions by aligning their offerings with the most demanding segments of the market.
- BASF SE emphasizes specialized ethoxylated polymer-solubilizers and reactive PEGs for oral and topical pharmaceutical formulations, along with USP-compliant grades for excipients. Its portfolio orientation reflects a focus on formulation support and regulatory-grade consistency, particularly in pharma-adjacent applications.
- Dow Inc. maintains a broad PEG series positioned across solvency, lubricity, and formulation use in personal care, pharmaceutical, and industrial applications. Its scale and multi-application coverage make it a reference point for buyers seeking functional versatility across categories.
- Clariant has concentrated on excipient-grade PEG under recognized compliance standards, with recent expansion into North American GMP-compliant production. This move strengthens its ability to serve pharmaceutical customers with regionally accessible, compliance-oriented supply.
- INEOS produces key grades through ethylene oxide polymerization for industrial and personal care applications, reinforcing a position tied to reliable large-scale output and established production pathways.
- Lotte Chemical and Sanyo Chemical Industries both serve industrial, personal care, and pharmaceutical segments, with product ranges that reflect regional strengths and specialty demand. Their presence underscores the importance of Asian manufacturing capability in meeting varied application requirements.
- India Glycols and Chinese producers such as Jiangsu Haian Petrochemical Plant and Liaoning Oxiranchem focus significantly on industrial and personal care markets, often with an emphasis on scale and cost-competitive supply. These players illustrate how regional production hubs serve high-volume application demand while increasingly navigating compliance expectations.
- Croda International contributes PEG excipients and additives for personal care and pharmaceutical uses, aligning with markets where quality documentation and application expertise carry strategic weight.
Differentiation and Competitive Advantages
The most effective differentiators in this market are not abstract. They are concrete capabilities that reduce risk and improve outcomes for buyers. These include:
- Grade specificity and reactive functionality that enable more tailored formulations
- Documented compliance with recognized excipient standards and production controls
- Regional manufacturing footprints that shorten supply routes and support qualification needs
- Application-level technical support that helps formulators integrate PEG into complex systems
- Portfolio breadth that allows customers to consolidate supply without sacrificing performance
Companies that combine several of these capabilities are better positioned to defend margin and deepen customer relationships. By contrast, suppliers competing primarily on price in undifferentiated segments face greater exposure to input volatility and substitution risk.
Polyethylene Oxide (PEO) Market
Landscape Evolution: Consolidation, Fragmentation, and New Entry
The competitive landscape is evolving along multiple axes. In compliance-intensive segments, there is a tendency toward consolidation of preferred suppliers as buyers reduce the number of qualified sources to simplify procurement and quality oversight. At the same time, specialized grades and application-specific solutions create room for fragmentation, with smaller or regional players capturing niche demand that larger incumbents may under-serve.
New entry is most likely where alignment between production capability, compliance readiness, and regional demand is strong. Rather than entering broadly, successful newcomers often establish a defensible position by focusing on a specific grade range, a targeted regional market, or a compliance-critical application. This pattern suggests that the market will continue to reward focused strategies over undifferentiated scale alone.
For buyers, this evolving landscape means that sourcing decisions increasingly involve balancing scale, specialization, compliance assurance, and geographic reliability. For producers, it means that long-term competitiveness depends on being able to demonstrate value beyond volume.
Outlook for the Next Three to Five Years
Looking ahead to the late 2020s and into the early 2030s, several trends are likely to shape PEG market outcomes. These trends are interconnected, and their combined effect will influence both growth distribution and the character of competition.
Trend One: Compliance-Integrated Supply Becomes a Baseline Expectation
As regulatory scrutiny around polymer persistence and environmental impact continues to mature, compliance-integrated supply will move from a differentiator to a baseline requirement in many applications. This does not imply a sudden contraction in demand; rather, it suggests that access to qualified grades and documented production standards will become more central to purchasing decisions. Producers that proactively strengthen compliance documentation, expand GMP-aligned capacity where relevant, and maintain transparent quality communication will face fewer barriers to adoption.
The commercial opportunity here lies in reducing friction for customers. Companies that can shorten qualification cycles, supply regionally appropriate grades, and provide reliable documentation will be better positioned to capture demand in pharmaceutical and personal care segments where approval and consistency are paramount. The risk is that producers with weaker compliance infrastructure may see slower adoption or limited access to higher-value applications, even if their base materials are cost-competitive.
Trend Two: Regionalization of Capacity and Procurement Accelerates
The combination of qualification requirements, logistics considerations, and the desire for supply resilience is likely to accelerate regional capacity strategies. Buyers in multiple markets will continue to favor supply arrangements that reduce lead-time variability and simplify oversight. Producers, in turn, will keep adjusting their footprints to serve regional demand more directly, particularly where regulated or formulation-sensitive applications are concerned.
Strategically, this trend favors companies that can offer localized production or near-localized supply without sacrificing grade consistency. It also creates opportunities for partnerships and capacity investments that align production location with end-market concentration. The uncertainty lies in how quickly regionalization will propagate across all segments. Industrial applications may remain more price-sensitive and globally traded, while pharma and personal care may shift faster toward regional compliance-linked supply.
Trend Three: Value Moves Toward Specialized Grades and Application Support
Growth is expected to increasingly tilt toward specialized grades that deliver specific performance outcomes, rather than toward undifferentiated bulk supply. Reactive PEG derivatives, carefully controlled molecular weight ranges, and grades optimized for particular formulation environments are likely to command greater attention as formulators seek more predictable functionality. Alongside this, application support will become more valuable, as customers look for assistance in integrating materials into complex products while maintaining compliance and consistency.
This trend creates opportunities for suppliers that can pair product specialization with technical credibility. It also opens space for new product launches and targeted portfolio expansions that address unmet formulation needs. The risk is that overinvestment in broad volume capacity without corresponding differentiation may lead to weaker positioning if buyers shift toward grades that provide clearer functional or compliance advantages.
Risk Considerations
Several uncertainties could alter the trajectory outlined above. Continued volatility in ethylene oxide-related feedstocks could disrupt cost planning and squeeze margins for producers with limited hedging flexibility. Regulatory developments could intensify or shift in unexpected ways, altering the compliance burden for certain grades or applications. Substitution pressure may grow in select segments if alternatives can match performance at lower regulatory or environmental cost. Finally, regional capacity expansion may not unfold uniformly, creating temporary imbalances between supply location and demand concentration.
These risks do not negate the growth outlook, but they underscore the importance of scenario planning. Companies that prepare for multiple regulatory, cost, and supply pathways will be better equipped to respond without disrupting product development or procurement continuity.
Strategic Actions for Decision-Makers
The PEG market's evolution offers distinct implications depending on a company's role in the value chain. The following actions are designed to align strategy with the most consequential trends.
For Manufacturers and Producers
- Prioritize grade differentiation and reactive functionality in product development. Expanding specialized offerings can create defensible positioning in formulation-intensive markets where performance and documentation matter more than volume alone.
- Strengthen compliance readiness and quality documentation. Investing in recognized production controls and transparent quality communication reduces barriers to entry in pharmaceutical and personal care applications, where qualification is a critical gate.
- Evaluate regional capacity opportunities against demand concentration and regulatory context. Targeted production investments can improve supply reliability and customer proximity, especially where buyers are increasingly favoring localized or near-localized supply.
- Balance cost leadership with resilience. In a market exposed to feedstock volatility and qualification-related switching costs, margin strategies should account for both price competitiveness and the value of dependable, compliant supply.
For Investors
- Focus on companies with clear alignment between portfolio, compliance capability, and end-market demand. The most durable value creation is likely to come from suppliers that can operate credibly in regulated segments while maintaining flexible production and technical support.
- Assess exposure to feedstock volatility and regional capacity shifts. Investment theses should incorporate how companies manage input cost variability and whether their supply footprints are aligned with emerging regional demand patterns.
- Watch for targeted capacity expansions and portfolio launches that signal positioning in higher-value segments. Moves into GMP-aligned production or reactive specialty grades can indicate where competitive advantage is being built, but they should be evaluated alongside customer qualification pathways and regional demand durability.
For Procurement and Sourcing Leaders
- Diversify qualified sources with an eye toward compliance and geographic reliability, not just unit cost. Reducing dependency on a narrow supplier base can mitigate disruption risk while improving responsiveness to regulatory and formulation changes.
- Engage suppliers early on grade selection and documentation requirements. Proactive alignment on specifications, quality systems, and regional availability can shorten qualification timelines and reduce reformulation risk.
- Build procurement scenarios that account for volatility in feedstock-linked costs. Flexible contracting, multi-grade options, and regional sourcing alternatives can help stabilize supply while preserving cost discipline.
The strategic significance of these actions lies in their ability to connect market dynamics with operational decisions. PEG is not simply a material purchase or a production output; it is a functional input whose value increasingly depends on grade suitability, compliance assurance, and supply reliability. Organizations that treat these attributes as strategic variables will be better positioned to capture growth and manage risk as the market matures.
Polypropylene Glycol Market
For a more detailed view of segmentation dynamics, regional supply patterns, and company-level positioning, the full research report provides additional depth and customized guidance. Readers seeking to translate these trends into specific procurement plans, investment theses, or product strategy decisions may benefit from the granular data and scenario breakdowns available in the complete analysis.
For detailed analysis of this topic, please visit the official page: Polyethylene Glycol (PEG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


