



Category: market research
PW Consulting: Hybrid Adhesive & Sealant Market to hit USD 12.67B by 2032 (6.5% CAGR)
By PW Consulting, 2026-07-12
Hybrid Adhesive & Sealant Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive snapshot
As PW Consulting’s senior industry analysts, we present an executive preview of our new Hybrid Adhesive & Sealant Market study (base year 2025, historical 2020–2025, forecast 2026–2032). The market demonstrates resilient expansion driven by material innovation, regulatory realignment and cross-industry demand for lightweight, durable joining solutions — supporting a compounded annual growth rate (CAGR) of 6.5% across the forecast window. From a $X billion footprint in 2025, the market is poised to develop materially through 2032, creating strategic opportunities and operational risks that corporate decision-makers must address in 2026.
Hybrid Adhesive & Sealant Market
Why this study matters for 2026 decision cycles
2026 is the year many industrial organizations will finalize three- to five-year R&D budgets, make capital investments in production footprint and decide on mid-cycle M&A targets. Our brief translates market growth trajectories, supplier positioning and technology shifts into actionable guidance for those choices. Key strategic levers informed by the study include:
Hybrid Adhesive & Sealant Market
- R&D prioritization: where to allocate formulation work for low-VOC and bio-based hybrids that meet tightening emissions rules
- Procurement and supply chain: which feedstock exposures to hedge, and how transportation surcharges and tariffs can reshape sourcing footprints
- Commercial go-to-market: which end‑use segments and performance claims unlock premium pricing and faster adoption
- M&A and partnership screening: how to interpret concentration metrics when sizing bolt-on targets or joint-venture partners
Market trajectory — the big-picture numbers (what we disclose)
Our topline analysis synthesizes historical performance (2020–2025) and forward-looking scenarios (2026–2032). The market demonstrates steady compound growth at an expected 6.5% CAGR through 2032, reflecting a combination of replacement demand, new-specification adoption and expansion into adjacent applications such as advanced battery assembly and hybrid vehicle platforms. These topline dynamics underpin revenue and margin planning across manufacturing, distribution and OEM channels.
Hybrid Adhesive & Sealant Market
What we do not reveal here — and why
In keeping with the “trailer” principle of this preview, we deliberately withhold granular subsegment tables and region/application revenue line items that are included in the full report. Those breakdowns are necessary for precision budgeting and supplier risk models; access to them is available through the full report. The summary below nevertheless conveys the directional drivers, structural constraints and competitive signals critical to boardroom decisions.
Key dynamics shaping 2026 strategies
- Raw-material volatility: Hybrid formulations depend on petrochemical-derived feedstocks. Price swings and input shortages during 2025–2026 have compressed margins and led manufacturers to re-evaluate long-term procurement contracts, supplier diversification and strategic inventory buffers.
- Regulatory push toward low-VOC and sustainability: Tightened VOC limits in Europe and North America are accelerating reformulation toward low-VOC and bio-based hybrid chemistries. This trend creates both a compliance imperative and a competitive advantage for early movers who can demonstrate performance parity.
- Transportation and tariff pressures: Transport surcharges and recent tariff adjustments have shifted the landed cost calculus for certain polymer feedstocks. Organizations must re-run total-cost-to-serve models and consider nearshoring or alternate raw-material strategies to preserve margins.
- Labor and capability constraints: Production of moisture‑curing hybrid sealants requires specialized skills. Rising labor costs and skill shortages are increasing the value of process automation, employee retention programs and regional center-of-excellence investments.
Competitive landscape — concentration and strategic positioning
The market exhibits moderate concentration: the top three players account for a meaningful minority share, with the top five firms consolidating less than half of total market revenues. This fragmented-to-consolidated profile creates distinct strategic opportunities: large incumbents can extract scale advantages via technical sales and distribution networks, while nimble specialists can capture premium pockets through targeted innovation and service models.
Company-level implications and observed behaviors
- Henkel AG & Co. KGaA (Düsseldorf, Germany) — With established brands focusing on MS‑polymer and silane‑terminated systems for automotive lightweighting and EV battery assembly, Henkel’s recent launch of a flame‑resistant, sustainability‑oriented hybrid product signals a two‑pronged strategy: defend core industrial customers while penetrating new safety‑sensitive niches. For competitors, Henkel’s move reinforces the premiumization path in performance claims.
- Sika AG (Baar, Switzerland) — Sika’s portfolio emphasis on construction and marine applications, and the 2025 introduction of a versatile silane‑terminated hybrid designed for above- and below‑waterline use, demonstrates segmentation-driven product architecture. Expect Sika to leverage application engineering and channel depth to grow share in infrastructure and specialty marine projects.
- 3M Company (St. Paul, MN) — 3M’s Scotch‑Weld hybrid lines reflect a system‑selling approach toward construction, automotive and industrial assembly. Their advantage lies in portfolio breadth and fast cross-sell into adjacent tape and adhesive systems; rivals must prioritize differentiated formulation claims to compete on technical merit rather than distribution alone.
- H.B. Fuller Company (St. Paul, MN) — Focusing on performance-driven structural bonding and battery assembly, H.B. Fuller is positioned to capture opportunities in EV and industrial OEM supply chains. Their emphasis on acoustic sealing and assembly performance highlights a go‑to‑market play that ties product specifications to end‑user performance metrics.
- Dow Inc. (Midland, MI) — Dow’s hybrid silicone-based offerings align with transport and construction segments that require long-term weathering and sealing performance. Dow’s integration into upstream chemistry development provides an R&D edge in tuning silicone-hybrid interfaces.
- Wacker Chemie AG (Munich, Germany) — Wacker’s hybrid lines illustrate a classical industrial manufacturer strategy: stable supply, formulation expertise and local production. Their technical depth is an asset where regulatory compliance and consistent quality are non-negotiable.
- Arkema Group (Bostik, Paris, France) — Bostik’s hybrid polymers target construction and automotive niches with a focus on installation efficiency and bond durability. Arkema’s playbook frequently emphasizes channel partnerships and installer education to accelerate specification adoption.
Recent developments as strategic signals
- Henkel’s March 2026 launch of a flame‑resistant, sustainable Teroson MS hybrid highlights the intersection of safety performance and environmental claims — a blueprint for premium product positioning in regulated applications.
- Sika’s October 2025 Sikaflex-591 silane‑terminated hybrid for marine use underscores product differentiation via application-specific formulation, enabling specification capture in high‑value projects.
Operational playbook for leadership teams
Executives should treat the hybrid adhesives and sealants category as both a performance materials market and a regulatory arena. Our study recommends a three-track operational response for 2026 planning:
- Risk mitigation: Reassess supplier concentration for key monomers and silane feedstocks; model transport and tariff contingencies; negotiate flexible contracts with volume and price collars.
- Capability investment: Accelerate formulation work on low‑VOC and bio‑based hybrids; invest in analytical labs to shorten product qualification cycles; upskill production teams in moisture‑curing process control.
- Commercial execution: Reframe value propositions around lifecycle cost and regulatory compliance rather than unit price; pilot specification programs with OEMs in battery assembly and lightweight structural bonding where adoption curves are steepest.
Where M&A and partnerships create asymmetric value
Given the market’s moderate concentration, strategic acquisitions remain a powerful means to acquire formulation IP, regional capacity and channel relationships at scale. Our deal-readiness assessment in the full report highlights target archetypes: formulation-centric SMEs with validated low‑VOC platforms, regional producers with strategic logistics footprint and specialty application houses with deep OEM relationships. For partnerships, co‑development agreements with OEMs and raw material suppliers allow de‑risking of feedstock exposure while accelerating time‑to‑market.
Scenario planning and sensitivity analysis (what we model)
Our full study provides deterministic and probabilistic scenarios that quantify the impacts of feedstock price shocks, regulatory tightening and accelerated EV adoption on revenue, gross margin and capital requirements. These tools enable CFOs and strategy teams to stress-test investment cases — a capability that will be particularly valuable as 2026 budgets are finalized under persistent macro uncertainty.
Closing guidance and next steps
For companies active in or adjacent to the hybrid adhesive and sealant market, 2026 will be a decisive year to shift from reactive to proactive strategy. Priorities include locking in raw-material resilience, embedding low‑VOC product roadmaps into R&D pipelines, and selecting M&A or partnership plays that accelerate access to high-value applications. PW Consulting’s full report equips leaders with the quantitative subsegment tables, supplier maps, risk heatmaps and scenario models needed to convert these imperatives into executable plans.
Accessing the full intelligence
This preview intentionally emphasizes strategic insight while withholding the granular subsegment metrics and region/application tables that many teams require for tactical execution. To obtain the complete dataset, including comprehensive segmentation, supplier shares, price curves and downloadable scenario models, consult the full Hybrid Adhesive & Sealant Market report on our website or contact PW Consulting’s market intelligence desk.
For detailed analysis of this topic, please visit the official page: Hybrid Adhesive & Sealant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Supermarket Lockers Market to Reach USD 239M by 2032 at 5.65% CAGR
By PW Consulting, 2026-07-12
Supermarket Lockers Market — Strategic Briefing for 2026 Decision Makers
Executive Summary
Between 2020 and 2025 the supermarket lockers market moved from a niche operational convenience to a strategic fulfillment asset. Our analysis shows total market value expanding from approximately USD 110 million in 2020 to USD 160 million in 2025. Under current demand drivers and technology adoption pathways the market is forecast to grow at a compound annual growth rate (CAGR) of 5.65% through a 2026–2032 forecast window, reaching roughly USD 239 million by 2032. Market concentration is moderate: the three largest players account for a significant share of revenue (CR3 ~45.6%), and the top five approach two-thirds of the market (CR5 ~62.3%).
Supermarket Lockers Market
For corporate leaders planning allocation of capital and operational redesigns in 2026, this report functions as both a map and a toolkit: it explains where demand is maturing, which technology and service strategies de-risk rollout, how regulatory and labor pressures alter ROI, and what execution options preserve optionality as the market matures.
Supermarket Lockers Market
Why this matters for 2026 planning
- Operational leverage: Self-service locker implementations materially reduce front-line labor requirements in supermarket pickup operations. Our sector analysis models indicate labor-savings lift that can meaningfully shorten payback periods on in-store automation investments.
- Network economics: As installations scale, per-unit economics and software/telemetry amortization change. The market’s steady CAGR through 2032 implies a clear runway for incremental deployments rather than one-time waves — an important factor for multi-year CAPEX planning.
- Competitive positioning: Locker networks are increasingly battlefield terrain for click-and-collect, third-party delivery integrations, and perishable-handling differentiation. Early adopters that align locker strategy with broader omnichannel fulfillment can convert a logistics cost center into a customer-acquisition and retention channel.
Market trajectory & implications
The historical trajectory (2020–2025) reflects both pragmatic deployments in high-traffic supermarkets and early rollouts of temperature-controlled and smart-locker variants. The projected expansion to 2032 at a mid-single-digit CAGR signals steady mainstreaming rather than explosive disruption — a profile that favors disciplined, staged investment strategies.
Supermarket Lockers Market
Key implications for 2026:
- Prioritize pilots that replicate the edge case economics of your core stores rather than chasing headline installations. The maturity curve rewards proof points that demonstrate consistent throughput and customer adoption.
- Design contracts and procurement windows to capture cost declines in modular electronics and standardized connectivity without locking into legacy, proprietary ecosystems.
- Factor regulatory compliance and data localization into vendor selection and IT integration plans.
Dynamics shaping demand and supply
- Labor and cost pressure — Automation reduces front-line pickup staffing needs; our sector workbench shows meaningful reductions in staffing expense for grocery pickup workflows, shortening TCO timelines where throughput is sufficient.
- CAPEX and unit economics — Initial capital outlay per locker varies by size and feature set. Procurement strategies focused on modularity, upgradeability, and energy-efficient electronics materially reduce lifecycle maintenance and replacement costs.
- Regulatory environment — Data sovereignty and e‑commerce last-mile regulations are active constraints. Operators should expect requirements for localized user-data storage and always-on, contactless access mechanisms when designing solution architecture.
- Sustainability and materials — Modular designs that incorporate recyclable components and low-energy electronics are becoming best practice for high-traffic environments, reducing both operating costs and ESG risk.
Competitive landscape — strategic takeaways
The market features a mix of specialized locker manufacturers, logistics platform players, and robotics-integrated providers. Five firms are noteworthy for their combination of product breadth, route-to-market, and recent momentum:
- Cleveron AS (Viljandi, Estonia) — Known for combining robotic automation with traditional locker designs. Strength: modular robotics that support higher throughput click-and-collect scenarios. Strategic fit: retailers aiming at high-volume, automated pickups and those testing robotics at scale.
- Luxer One (McClellan, California) — Focused on smart package locker systems optimized for BOPIS and third-party grocery delivery. Recent product rollouts and trade-show visibility underline a push for retail-market mindshare and seasonal/peak-delivery solutions.
- Parcel Pending by Quadient (Irvine, California) — Broad deployment footprint and depth in temperature-controlled solutions. Recent disclosures highlight a large global installation base and revenue targets tied to retail and grocery use cases, signaling mature delivery and service capabilities across regions.
- KEBA AG (Linz, Austria) — High-capacity locker solutions with strong integration into parcel networks and retail partners. Strategic alliances and exclusive supplier relationships emphasize KEBA’s role in infrastructure-led rollouts.
- TZ Limited (Singapore) — Regional specialist with click-and-collect smart lockers optimized for supermarket environments, often suited to quick deployments and multi-format store rollouts in dense urban markets.
Recent company developments point to two operational realities: (1) incumbent locker and parcel players are pushing aggressive installation and revenue targets tied to grocery deployments, and (2) suppliers are differentiating by temperature control, robotics, and software integrations that simplify partner logistics.
What the full PW Consulting report includes (operationally focused)
We designed the full study as a pragmatic decision-support package for procurement, operations, and strategy teams. Highlights include:
- Methodology and transparent market-sizing: historical series (2020–2025) and a 2026–2032 forecasting model with scenario toggles for adoption rates and pricing.
- Decision playbooks: site-selection criteria, pilot templates, and rollout sequencing optimized for different store footprints and customer demographics.
- Vendor diligence matrices: comparative frameworks for product features (temperature control, robotics, integration APIs), service-level expectations, and contract negotiation levers.
- Commercial tools: TCO and ROI calculators, maintenance schedules, and depreciation schedules aligned to common supermarket procurement cycles.
- Compliance and data strategy guidance: implementation checklists to satisfy data-localization and contactless-access regulations in major markets.
- Case studies and procurement templates: real-world examples and contracting language to accelerate commercial negotiations.
The report is intentionally practical: executives receive not only market sizing and trend analysis but also the templates and KPIs needed to move from pilot to scale without unnecessary rework.
Recommended 2026 playbook — actionable steps
- Run two parallel pilots: one focused on high-frequency urban stores with temperature-controlled units; the other on suburban pickup models using standard smart lockers. Use identical KPI sets (customer pickup time, locker utilization, incremental basket lift, labor delta) for apples-to-apples comparison.
- Score vendors against a weighted matrix that prioritizes API openness, data residency options, modular upgrade paths, and proven maintenance throughput.
- Embed regulatory checkpoints into procurement milestones: contract sign-off contingent on demonstrable data localization and contactless-access compliance tests.
- Stage capital allocation over a 36-month horizon tied to utilization milestones rather than a single upfront budget; this both mitigates risk and captures vendor-led cost declines in electronics and connectivity.
- Adopt a sustainability clause in procurement to secure recyclable materials and low-energy electronics as baseline requirements — a move that lowers operational energy spend and supports corporate ESG goals.
KPIs to monitor in 2026
- Locker utilization (pickups per locker per day)
- Average customer pickup time and rate of failed pickups
- Labor hours saved per pickup node and associated wage delta
- TCO per locker over a 5‑ to 7‑year lifecycle (including service contracts)
- Percentage of transactions routed via integrated API vs manual override
Concluding note — strategic framing
Supermarket lockers are not a binary decision: they are a configurable infrastructure layer that can reshape last-mile economics, customer convenience, and store operations when deployed with discipline. The mid-single-digit CAGR through 2032 suggests patient, stage-gated investment will generally outperform speculative scale-ups. The full PW Consulting Supermarket Lockers Market study supplies the granular segmentation, vendor scorecards, and financial models necessary to translate these strategic insights into executable programs.
To access the granular segmentation, vendor financials, and downloadable ROI tools that underpin these recommendations, visit our full report landing page. The executive briefing above is designed to orient 2026 planning — the detailed modules will accelerate procurement, piloting, and scaled deployment with confidence.
For detailed analysis of this topic, please visit the official page: Supermarket Lockers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Face Masks Market to Reach USD 5.32B by 2032 — 6.1% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Medical Face Masks Market: Strategic Imperatives for 2026 — PW Consulting
Executive summary
The medical face masks market is transitioning from pandemic-driven urgency to structurally reinforced demand driven by infection prevention protocols, regulatory tightening, and technology-led differentiation. Our PW Consulting market model shows that the industry expanded significantly across 2020–2025, reaching a 2025 base-year value of USD 3.49 Billion, and is projected to continue expanding through our 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 6.1%, to reach roughly USD 5.3 Billion by 2032. While headline growth is attractive, the real strategic questions for 2026 are about competitive advantage, regulatory compliance costs, channel optimization, and resilient sourcing — not simply topline expansion.
Medical Face Masks Market
Why this study matters for 2026 decision-makers
-
Actionable market timing: With the market moving from episodic surges to sustained growth, investments made in 2026 will determine capacity and capability through the next full business cycle. Our analysis isolates the windows where incremental capacity versus capability investments deliver the highest risk-adjusted returns.
Medical Face Masks Market -
Regulatory inflection: 2025–2026 introduced new requirements (e.g., ASTM F2100-26 updates and EN 14683:2025 performance definitions) that raise the bar for labeling, instructions, and performance validation. Firms that align product-roadmaps and quality systems to these standards in 2026 will avoid time-to-market friction and costly rework.
Medical Face Masks Market -
Consolidation and concentration: The market exhibits mid-level concentration (our CR3 is approximately 45% and CR5 about 55%), implying meaningful advantages for scale but also opportunities for focused specialists to capture premium niches. That concentration profile should inform M&A and partnership strategies crafted in 2026.
Market trajectory and what the numbers reveal
From 2020 through 2025 the sector transitioned from crisis-driven capacity mobilization to normalization and modest consolidation. Our base-year analysis (2025) reflects the post-crisis baseline from which strategic choices will be measured. The forecast path to 2032—implied by a 6.1% CAGR over 2026–2032—signals steady demand growth, but not runaway expansion. This trajectory favors projects that improve unit economics, regulatory resilience, and product differentiation (filtration efficiency, fit, breathability) over large greenfield plants predicated on episodic peaks.
Key dynamics shaping 2026 strategies
-
Regulatory tightening is raising compliance complexity. ASTM’s 2026 update and the EN 14683:2025 specification extend obligations beyond raw material performance to labeling, user instructions, and design documentation. Companies must upgrade quality management, clinical evidence packages, and regulatory affairs capabilities to avoid late-stage product holds.
-
Material and technology differentiation matter. Adoption of higher-performance media (e.g., submicron nanofiber layers) can materially improve breathability and filtration trade-offs. Alpha Pro Tech’s use of a 0.1 micron filter achieving >95% bacterial filtration efficiency is an example of technology that confers credible product differentiation — but it also raises sourcing and IP considerations.
-
Supply chain and labor realities persist. Manufacturing medical face masks remains labor-intensive at key assembly stages (pleating, nose-bridge integration, strap welding). Automated investments can reduce labor risk, but capital allocation decisions must be tested against forecasted demand stability and margin uplift.
-
Regulatory approval pathways remain nuanced. FDA’s continued enforcement discretion for certain respirators and masks creates pathway uncertainty; firms must design regulatory strategies that adapt to jurisdictional differences and shifts in enforcement posture.
Competitive landscape — where winners will emerge
The competitive field includes multinational industrials with established healthcare portfolios, specialized manufacturers with advanced filtration IP, and distributors that aggregate scale and channel access. Our issuer-by-issuer analysis highlights three strategic postures that leaders take in 2026:
-
Scale-integrators (e.g., major diversified manufacturers) leverage broad distribution and procurement scale to compete on price and availability while investing selectively in performance upgrades. These players prioritize supply assurance for large institutional buyers and maintain innovation pipelines focused on manufacturability and compliance.
-
Tech-specialists deploy material science and engineered media to create differentiated products with verifiable performance gains. Recent product launches using nanofiber technology illustrate how innovation can improve the breathability-filtration tradeoff — a key purchasing criterion for clinicians and procurement committees.
-
Channel specialists and distributors focus on value-added services — validated supply chains, inventory management, and hospital-grade sourcing — enabling them to capture higher margin from service bundling despite limited upstream manufacturing control.
Representative participants include legacy safety and healthcare brands that bring broad clinical credibility; specialty manufacturers with proprietary media and filter designs; and distribution players that consolidate hospital purchasing. Notable recent activity includes a late-2025 product launch by a major industrial player that integrated nanofiber filtration to improve breathability and filtration efficiency, a direct example of innovation that will shape procurement decisions in 2026.
Practical, decision-focused content included in the report
PW Consulting’s Medical Face Masks Market report is built for executives making investment, sourcing, and M&A decisions in 2026. It is intentionally operational and includes:
-
Top-down and bottom-up market sizing with scenario envelopes calibrated to regulatory and pandemic-risk scenarios (base, upside, downside).
-
Competitive positioning maps and CR analyses with company-level profiles and strategic benchmarking.
-
Regulatory risk matrix covering ASTM, EN, and major regulatory agency pathways, with mitigation playbooks for product labeling, clinical evidence, and documentation upgrades.
-
Supply chain heatmaps identifying concentration risks for meltblown and advanced media, logistics choke points, and recommended dual-sourcing approaches.
-
Manufacturing economics: labor intensity analysis, capex/opex trade-offs for automation, and a marginal-cost curve for capacity expansion decisions.
-
Go-to-market playbooks tailored to three buyer archetypes (health systems, procurement consortia, and retail/OTC channels) with suggested commercial models and contract terms.
-
M&A and partnership templates including valuation heuristics, integration risk checklists, and a shortlist of value-creation levers post-close.
-
Implementation roadmaps and KPI dashboards to track quality, compliance, and supply continuity during the first 18 months after any strategic move.
Strategic implications and recommended actions for 2026
-
Prioritize regulatory-first product upgrades: Allocate budget in 2026 to bridge gaps introduced by ASTM and EN updates. Even modest investments in labeling, clinical validation, and user instructions materially reduce time-to-revenue risk.
-
Invest selectively in differentiated media: Technology like nanofiber layers or submicron filters can command premium positioning. Conduct a supplier diligence focused on IP freedom-to-operate and supply resilience before committing to long-term contracts.
-
Rationalize capacity expansion: Given the mid-single-digit CAGR forecast, favor modular capacity builds and contract-manufacturing options over high-capex greenfield projects unless you can secure firm demand commitments.
-
Design channel-specific offerings: Health systems value guaranteed supply and compliance documentation, while retail channels respond to comfort and convenience. Tailored SKUs and packaging can increase share without significant R&D outlays.
-
Use M&A to close capability gaps: For firms lacking specialized media or regulatory expertise, bolt-on acquisitions of technology specialists or contract manufacturers can accelerate market entry while managing integration risk with clear milestone-based earnouts.
What we deliberately omit here — and why
To preserve strategic value for purchasers of the full study, this article intentionally omits granular regional and application-level breakdowns, and detailed company revenue splits. Those granular matrices — which include region-by-region sizing, type and application splits, and price-variable scenarios — are core deliverables of the full report and are indispensable for tactical procurement and investment decisions. The summary above provides the directional intelligence and strategic recommendations you need to determine whether to procure the full dataset and modeling toolkit.
Next steps — how to use this insight in 2026
-
Board-level briefing: Use the report’s executive dashboard to align capital allocation and regulatory compliance priorities for H1 2026.
-
Procurement playbook update: Reframe supplier contracts and dual-sourcing clauses based on the supply-chain heatmap and labor-cost sensitivity analyses.
-
M&A screening: Run target shortlists through our valuation heuristics and integration checklists to identify deals that accelerate capability rather than just capacity.
-
R&D and manufacturing planning: Adopt the capex/opex models to evaluate automation investments and technology licensing versus in-house development.
Conclusion
2026 is a pivot year: the market will continue to grow, but the levers that determine winners are increasingly qualitative — regulatory compliance, media technology, and supply-chain resilience — rather than pure scale. PW Consulting’s Medical Face Masks Market report converts those qualitative dynamics into quantitative choices and executable roadmaps. For executives allocating capital, reshaping supply networks, or pursuing capability-driven M&A, the report is a decision-ready tool that reduces execution risk and sharpens ROI expectations.
How to obtain the full study
For the complete dataset, granular segmentation, scenario models, and downloadable implementation templates, access PW Consulting’s full Medical Face Masks Market report. The full report includes proprietary spreadsheets, playbooks, and regulatory checklists you will need to operationalize the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Medical Face Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electronic Data Interchange (EDI) Software Market: Strategic Preview for 2026 Decision-Makers
As organizations finalize their 2026 technology budgets and supply‑chain modernization roadmaps, understanding the economics and competitive dynamics of the EDI software market is now a strategic imperative. PW Consulting’s latest market study — anchored to base year 2025 — synthesizes a decade of vendor behavior, deployment shifts, regulatory friction points, and adoption economics into a practical intelligence package intended to reduce vendor risk, accelerate integration outcomes, and improve negotiated total cost of ownership (TCO) for enterprise buyers.
Electronic Data Interchange (EDI) Software Market
Market Trajectory: What the numbers tell procurement and IT leaders
The EDI software market has moved from niche, on-premise integrations to a mainstream component of digital supply‑chain stacks. Our historical series shows clear expansion from the early 2020s into 2025, with the market accelerating as cloud and hybrid models became operationally mature. By the 2025 base year the market had reached approximately USD 1.62 billion (revenue unit: Million), and our forecast through 2032 projects continued expansion to roughly USD 3.11 billion, driven by cross‑industry automation, regulatory digitization, and greater interoperability demands. The forecast period (2026–2032) is modeled at a 9.8% compound annual growth rate (CAGR), which positions EDI software as one of the more resilient middleware categories in the enterprise integration layer.
Electronic Data Interchange (EDI) Software Market
Two practical implications flow from this trajectory. First, the market growth rate signals that vendor viability risk is lower than in earlier cycles, but it also invites consolidation activity by both strategic incumbents and private equity. Second, sustained growth will translate into rising expectations for automation, analytics, and API/EDI convergence — putting a premium on integration platforms that can both modernize legacy trading partner networks and instrument them for real‑time decisioning.
Electronic Data Interchange (EDI) Software Market
What this study delivers — a practical, actionable toolkit
This report is intentionally operational. Executive summaries and headline charts are accompanied by tactical assets that procurement, IT, and line‑of‑business leaders can deploy during vendor selection and contract negotiations:
- Vendor assessment framework: qualitative scoring across architecture, scalability, multi‑protocol support (EDI, APIs), partner network depth, and professional services.
- TCO model templates: scenario‑based calculators that quantify upfront migration costs, integration labor, per‑transaction economics, and multi‑year vendor price escalations.
- Integration playbooks: step‑by‑step paths for cloud migrations, hybrid coexistence strategies, and ERP‑centric deployments (including common pitfalls and mitigation controls).
- Regulatory compliance checklists: coverage of emerging e‑invoicing and public‑sector certification requirements, with practical evidence requirements for auditors and procurement panels.
- Implementation KPIs: recommended SLAs, monitoring metrics, and maturity checkpoints to measure EDI health across trading‑partner networks.
- Negotiation levers: contractual tactics to limit per‑transaction escalators, cap professional services billable rates, and secure upgrade pathways.
We deliberately stop short in this preview of publishing micro‑segmentation tables and line‑item pricing benchmarks — these are retained for subscribers who require the full dataset, vendor scorecards, and the interactive model that powers scenario testing.
Competitive landscape — who to watch and why
The market shows moderate concentration. Our analysis reports a top‑three concentration in the mid‑30s percentage range and a top‑five approaching the high‑40s, which signals a competitive field where leading players exert influence but meaningful space remains for specialized and regional challengers. Strategic buyers must evaluate both the market leaders for scale and resilience, and specialist providers for vertical fit and faster time‑to‑value.
- Cleo Communications (United States) — Cleo’s Integration Cloud positions EDI within an AI‑enabled orchestration layer that converges EDI and API flows. Their recent product extensions emphasize self‑service management and automation for complex trading networks, which reduces integration labor and accelerates time to onboard new partners.
- SPS Commerce (United States) — SPS focuses on cloud‑native connectivity for retail ecosystems, with strengths in supplier compliance and retail partner networks. Their go‑to‑market is optimized around marketplaces and large retail trading hubs, making them a frequent choice where retail compliance is the dominant procurement criterion.
- TrueCommerce (United States) — TrueCommerce’s cloud EDI suite is distinguished by rapid ERP and eCommerce marketplace integrations. Notably, in 2025 they launched an integration with SAP S/4HANA Cloud Public Edition, signaling intensified support for ERP‑first migration strategies and opening pathway architectures for SAP customers.
- OpenText (Canada) — OpenText combines classic trading‑grid capabilities with cloud Business Network offerings. Their 2025 introduction of a cloud EDI solution for healthcare demonstrates the vendor’s move to package industry‑specific compliance and security controls for regulated verticals.
- IBM (United States) — IBM’s Sterling B2B Integrator remains a go‑to for enterprise deployments that require advanced routing, B2B transaction governance, and deep ERP adjacency. Sterlings’ positioning caters to complex, high‑transaction environments that prioritize throughput and enterprise governance.
Recent vendor developments underline the strategic moves you should expect: product launches that simplify self‑service EDI, ERP integrations that shorten migration cycles, and targeted vertical solutions for sectors like healthcare that are navigating specific regulatory requirements. These shifts have material procurement implications — vendors now bid not only on core capabilities, but on the speed of adoption and the degree to which they reduce downstream operational costs.
Market dynamics and “noise” — factors that will shape 2026 decisions
Three themes require explicit attention when building RFPs and migration roadmaps for 2026:
- Integration labor and hidden costs: EDI programs can be deceptively expensive. Beyond license fees, buyers face integration labor, per‑transaction fees, and the potential for routine annual price increases in the 5–10% range from some enterprise vendors. Our TCO templates make these line items explicit and provide sensitivity analyses that should be run for every vendor under consideration.
- Regulatory acceleration: Evolving e‑invoicing mandates and public procurement certification regimes — especially in parts of Europe — are raising the bar for compliance. The practical outcome: vendors that can deliver certification artifacts and audit trails with minimal custom development will materially reduce the buyer’s time‑to‑compliance and risk exposure.
- Hybrid EDI + API modernization: The market’s innovation frontier is at the intersection of EDI and APIs. Hybrid architectures that enable legacy partner connectivity while exposing real‑time, API‑driven services for modern trading partners will define winners. Investment in orchestration platforms that normalize both EDI and API payloads is now a competitive necessity, not a nice‑to‑have.
How to use this intelligence in your 2026 planning cycle
PW Consulting’s study is structured to convert market intelligence into procurement action. For teams drafting 2026 initiatives we recommend three practical steps:
- Run parallel TCO scenarios: Use the report’s TCO model to compare at least three trajectories — “lift and shift” (cloud replacement), “phased hybrid co‑existence,” and “greenfield integration” with API‑first architectures. Each scenario surfaces different labor profiles, compliance milestones, and vendor lock‑in risks.
- Prioritize regulatory readiness: Require vendors to demonstrate evidence of compliance for applicable jurisdictional regimes and to commit to contractually defined upgrade paths as new certifications emerge.
- Demand integration accelerators: Shortlist vendors that provide ERP connectors, marketplace adapters, or pre‑built partner maps for your industry. These accelerators are the fastest way to reduce onboarding costs and to validate projected ROI within your fiscal planning window.
Closing — what this preview leaves for the full report
This preview outlines the strategic backdrop, vendor dynamics, and tactical checklists that will shape EDI procurement and integration choices in 2026. To preserve the value of our forensic analysis and interactive models, we have intentionally withheld the full segmentation tables, granular regional and industry splits, and the detailed vendor scorecards from this summary. The full report contains:
- Granular segment revenue models and interactive forecast inputs
- Complete vendor scorecards with capability heatmaps and reference client verifications
- Downloadable TCO workbooks and contract clause templates
For procurement teams, CIOs, and operational leaders preparing for 2026, the full dataset and playbooks accelerate decision cycles and materially reduce execution risk. Access to the complete report enables scenario testing across deployment archetypes (cloud, on‑premise, hybrid), industry demand curves, and vendor portfolios — the precise inputs you need to finalize budgets and enter negotiations with leverage.
Contact PW Consulting to obtain the full EDI Software Market report and the accompanying implementation toolkit. Use the decision window in Q1–Q2 2026 to convert this market momentum into measurable operational and financial outcomes for your organization.
For detailed analysis of this topic, please visit the official page: Electronic Data Interchange (EDI) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acoustic Vents Market Poised for 6.32% CAGR Through 2032
By PW Consulting, 2026-07-12
Acoustic Vents Market — 2026 Strategic Preview
As cities densify and building performance expectations rise, acoustic vents have shifted from a niche product to a strategic building component. This PW Consulting preview translates the latest market modelling, supplier dynamics and regulatory imperatives into a concise playbook for executives planning decisions in 2026. Our base-year modelling (2025) and a 2026–2032 forecast horizon indicate a steady expansion driven by retrofit programmes, urban noise mitigation and energy-conscious ventilation design. The market, which grew through the first half of the decade, is projected to expand at a compound annual growth rate of approximately 6.32% over the forecast period — a profile that rewards focused product innovation, specification-led commercial models and disciplined supply-chain management.
Acoustic Vents Market
Why this research matters for 2026 decision-making
-
Policy and compliance are converging with occupant expectations. In several mature markets, acoustic vents must now satisfy background ventilation needs without compromising sound insulation targets — a dynamic driven by building regulations and independent acoustic testing standards.
Acoustic Vents Market -
Retrofit activity and urban noise abatement are creating sustained, repeatable demand. Where once acoustic venting was a specialist topic for high-noise projects, it is increasingly being specified in mainstream residential and commercial refurbishment programmes.
Acoustic Vents Market -
Material and manufacturing stability create strategic windows. The primary materials in use — UV-stabilised ABS and aluminium — have shown relative pricing stability amid volatile raw-material markets, enabling manufacturers to plan product roadmaps and margin strategies with greater confidence.
What the full report delivers — practical, executable intelligence
-
Market sizing and topline forecast (2020–2032) with scenario modelling to stress-test demand under alternative policy and energy-price paths.
-
A regulatory and standards matrix covering typical compliance pathways (including background ventilation requirements and sound reduction testing requirements), plus a checklist for product specification and certification.
-
Competitive landscape and supplier profiles with capability maps, go-to-market models and a short-list of strategic partners and acquisition candidates.
-
Product benchmarking and performance specification templates — acoustic attenuation, throughput, weathering and aesthetic options — for use in procurement and tender evaluation.
-
Material-cost and sourcing analysis that identifies leverage points in procurement and manufacturing, including recommendations on hedging and supplier diversification.
-
Commercial playbooks for OEMs, distributors and installers, including channel segmentation, specification-targeting and pricing tactics tailored to retrofit and new-build routes.
-
Financial modelling tools and KPIs designed to support investment cases for R&D, capacity expansion, and M&A decisions.
Data-driven signals you can act on in 2026
-
Growth runway: The market has expanded consistently since 2020, with the 2025 base supporting near-term acceleration. Our forecast shows an upward trajectory through 2032, underpinned by policy-driven retrofits and product upgrades — a strategic environment in which early commercial investment can capture specification-led wins.
-
Specification over price in many tenders: In noise-sensitive projects, procurement increasingly prioritises demonstrated acoustic performance and independent testing over lowest-cost bids. Firms that invest in third-party verification and transparent labelling gain a clear competitive edge.
-
Design integration is a differentiator: Recent product updates by established suppliers highlight the value of aesthetic options — for example, colour-matching and slimline profiles — that allow acoustic vents to be specified without aesthetic compromise. Product families that combine acoustic attenuation with façade integration are winning broader project adoption.
-
Materials and testing standards matter: Independent testing to accepted ISO and EN standards is a gating factor for many public and institutional contracts. Ensuring compliance and publishing verified performance data reduces sales friction in specification processes.
Competitive landscape — what to watch among tier-one and specialist suppliers
The acoustic vents field remains characterised by a mixture of highly specialised manufacturers and a broader cohort of component suppliers. The market is not highly concentrated; leadership is earned through technical credibility, testing pedigree and close relationships with specifiers.
-
Titon (United Kingdom): A well-established manufacturer emphasising high sound attenuation and compliance. Recent moves to expand colour-matching across plastic and aluminium ranges signal a strategic push into projects where design integration and acoustic performance are jointly required. For competitors and partners, Titon represents a benchmark for combining certification, product breadth and spec-channel access.
-
R.W. Simon Ltd (United Kingdom): A specialist in slimline, aesthetic acoustic trickle vents designed to meet building-regulation needs. Their positioning is instructive for companies targeting heritage, retrofit and architect-specified projects where visual impact is a constraint.
-
Caice Acoustic Air Movement Ltd (United Kingdom): Focused on attenuators and louvres with a strong emphasis on independent performance testing. Their product-driven credibility makes them an attractive partner for ventilation system integrators who need verified acoustic components.
-
DUCO Ventilation & Sun Control (Belgium): Differentiates through combined acoustic and energy-efficiency claims; their recent launch of a quiet combined-ventilation system highlights the premium commanded by dual-benefit solutions in Europe. Such multi-functional systems are a leading-edge development to monitor for product roadmaps.
-
TEK Ltd, DGS Group, Greenwood Airvac, Brookvent: Each brings particular strengths — from wall-vent systems to acoustic airbricks and high-attenuation residential vents. Collectively, these specialists illustrate the breadth of routes to market: direct specification, distributor partnerships and installer-focused channels.
Strategic imperatives for executives in 2026
-
Prioritise certified acoustic performance: Invest in independent testing to internationally recognised standards. Include performance data in BIM objects and specification packs to reduce friction in design-team assessments.
-
Design for specification: Offer aesthetic options (colour-matching, slim profiles) and modular form-factors that meet both façade architects and retrofit contractors halfway. Small product features can materially increase spec-in rates.
-
Differentiate around combined benefits: Pair acoustic performance with energy efficiency or integrated ventilation control. Systems that demonstrably deliver multiple compliance outcomes have outsized value in tenders and are less exposed to commodity pricing pressure.
-
Hedge materials and stabilise costs: Lock flexible supply arrangements for UV-stabilised ABS and aluminium, and consider dual-sourcing to mitigate concentration risks. Use the relative material-price stability to plan three-year product roadmaps and margin targets.
-
Pursue spec-driven commercial models: Invest in technical sales capabilities and partnerships with window and façade OEMs. Specification wins drive volume and reduce customer acquisition cost in this market.
-
Evaluate targeted M&A and partnerships: Look for tuck-in specialists with strong testing pedigrees or distribution footprints in retrofit channels. Acquiring a recognised acoustic brand can accelerate spec penetration faster than organic development.
-
Operationalise rapid iterations: Short development cycles for colour ranges, installation kits and retrofit fixings can be the difference between winning and losing specification rounds in 2026.
Scenarios and near-term triggers to monitor
-
Regulatory shifts: Any tightening of ventilation or acoustic requirements in national building codes will quickly re-weight demand toward independently tested products. Maintain a regulatory watch and scenario overlay for procurement and R&D timelines.
-
Material price shocks: Aluminum or polymer supply disruptions would stress margins for producers without flexible sourcing. Early supplier engagement and strategic inventory policies are prudent.
-
Product innovations: New combined ventilation solutions or major product launches by established suppliers can alter specification dynamics. Recent product updates from leading vendors demonstrate how quickly specification preferences can evolve.
-
Consolidation moves: Watch for acquisitive behaviour among larger façade or HVAC players seeking to internalise acoustic vent capabilities — this could compress supplier choice in some channels and create partnership opportunities in others.
For executives planning capital allocation, product roadmaps or channel investments in 2026, the strategic imperative is clear: convert acoustic performance into a specification advantage while protecting margin through disciplined sourcing and value-added product features. The full PW Consulting Acoustic Vents Market study supplies the detailed regional and application splits, supplier benchmarking scores, pricing curves and financial models you will need to operationalise these recommendations. To access the granular data and interactive scenario tools that underpin this preview, please consult the full report.
For detailed analysis of this topic, please visit the official page: Acoustic Vents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cold-Brew Market to Reach USD 9,756 Million by 2032 (17.12% CAGR)
By PW Consulting, 2026-07-12
Cold‑Brew Coffee Market — 2026 Strategic Briefing
Executive snapshot
As companies plan investment, product and channel strategies for 2026, the cold‑brew coffee category presents a distinct growth corridor—driven by changing consumer rituals, faster adoption of ready‑to‑drink formats, and structural shifts across supply and packaging. Our latest industry model (base year 2025; forecast 2026–2032) places the global market firmly in the multi‑billion dollar band and projects a robust compound annual growth rate (CAGR) of 17.12% through the forecast horizon. This growth trajectory creates both runway and complexity: attractive topline expansion coexists with margin pressure from commodity swings, evolving regulation, and accelerated competitive entry.
Cold-Brew Coffee Market
Why this report matters for 2026 decision‑makers
-
Investment prioritization: Rapid category growth increases the opportunity cost of delayed market entry. Our research quantifies the commercial impact of timing on share capture, and translates those dynamics into specific scenarios for greenfield launches, SKU expansions, and private‑label contracts.
Cold-Brew Coffee Market -
Risk‑adjusted supply planning: The cold‑brew value chain remains exposed to coffee commodity cycles, logistics volatility and packaging inputs. The report provides scenario modelling that links raw material volatility and tariff changes to unit economics across formats, enabling hedging and supplier‑diversification strategies.
Cold-Brew Coffee Market -
Channel and format playbooks: Consumer behavior is fragmenting across grocery, food service and direct‑to‑consumer channels. We benchmark channel economics and identify which formats and pack sizes shorten break‑even horizons for manufacturers and retailers alike.
-
M&A and contract manufacturing guidance: With moderate industry concentration (three‑player and five‑player concentration metrics included), the sector is ripe for consolidation, vertical integration and scale play. The report includes a prioritized M&A target list and diligence scorecards tailored to strategic acquirers and private‑label partners.
Market trajectory and structural drivers
From a 2025 base that reflects the post‑pandemic recovery and a wave of RTD innovations, the cold‑brew market is modeled to expand materially by 2032 under our central case. That expansion is not uniform: growth is accelerated where convenience, premiumization and clean‑label attributes converge. Key structural drivers highlighted in our analysis include:
-
Consumer ritual evolution: Consumers continue to shift from on‑premise coffee towards ready‑to‑consume formats for daily consumption. Within that trend, premium‑positioned cold‑brew (single‑origin, low‑acid, organic) commands a price premium and loyalty benefits—especially among younger cohorts.
-
Format innovation and preservation: Advances in packaging and cold‑chain logistics have extended reach for multi‑serve and single‑serve formats, enabling broader retail placement and longer shelf life for RTD offerings.
-
Raw material and regulatory pressure: Commodity price cycles and selective tariff changes have altered sourcing economics and supplier selection criteria. Organizations that align hedging strategies with flexible sourcing will preserve margins during price swings.
-
Sustainability and labeling expectations: Sustainability commitments and demand for certified organic and recyclable packaging increasingly influence buyer choice and retailer listings—requiring product teams to integrate lifecycle and certification costs into pricing models.
What the full report contains — practical, actionable modules
We designed this study as a decision‑support tool for commercial leaders, product teams, and corporate development groups. Key components include:
-
Market sizing and growth scenarios: A transparent model with historical series (2020–2025) and granular forecast logic (2026–2032). The model supports sensitivity testing against key variables such as price per serving, pack size mix and channel shift.
-
Supply chain and cost mapping: Line‑item unit cost studies across concentrate, RTD and nitrogen formats—highlighting margin levers and break‑even points for different production scales.
-
Channel economics: Comparative analysis of retail, food service and direct channels that shows distribution costs, margin expectations and SKU rationalization recommendations to optimize shelf productivity.
-
Packaging & shelf‑life playbook: Evaluation of can, carton and multi‑serve packaging options with practical guidance on negotiation levers with co‑packers and capital trade‑offs for in‑house filling lines.
-
Competitive positioning and capability matrices: Profiling of incumbent and insurgent players, mapping their product portfolios, manufacturing footprints and route‑to‑market capabilities—useful for both partnership screening and defensive responses.
-
M&A and partnership diagnostics: Valuation frameworks and synergy calculators tailored to vertical integration (roaster → manufacturer → RTD) and private‑label acceleration strategies.
-
Scenario planning toolkit: Prebuilt scenarios that allow executives to stress test strategies against commodity spikes, tariff shifts and rapid channel disruption.
Competitive landscape — who matters and why
The competitive picture blends national specialty roasters, large plant‑based beverage players, private‑label entrants and contract manufacturers. Market concentration metrics indicate a market where a small set of players holds meaningful but non‑dominant share, leaving room for nimble challengers and private‑label growth.
-
La Colombe Coffee Roasters — A category pioneer with strong brand equity in boxed fridge packs and on‑the‑go cans. Their dual focus on original and flavored variants makes them a benchmark for premium RTD positioning.
-
STōK Cold Brew Coffee — A scale RTD player known for slow‑brew positioning and energy‑oriented variants. Their distribution muscle in mainstream channels illustrates the commercial benefits of a clear functional claim.
-
Stumptown Coffee Roasters — Specialty credentials and concentrated cold‑brew SKUs give them credibility among discerning consumers; a useful case for how premium roasters can monetize brand beyond cafes.
-
Bizzy Cold Brew Coffee and Chameleon Organic Coffee — Examples of organic and specialty‑grade positioning. Their certifications and ingredient stories underline the premium/health axis retailers increasingly prize.
-
Califia Farms and Blue Bottle Coffee — Demonstrate adjacent category play and brand leverage into cold‑brew; Califia’s plant‑based expertise and Blue Bottle’s retail presence show different scale approaches to premium RTD.
-
Hardtank and private label (Trader Joe’s etc.) — Contract manufacturing and private‑label supply are critical capacity levers for rapid scale and margin management. These players exemplify the outsourcing pathway for brands that want to accelerate shelf presence without heavy CAPEX.
-
Royal Cup Coffee and Tea — Recent SKU extensions and product launches highlight how regional roasters are scaling into national retail with flavored RTD options and competitive pack sizing.
Recent product activity—new RTD and nitro launches across small roasters and regional brands—confirms that incumbents and newcomers alike continue to iterate on format and caffeine profiles to capture incremental consumption occasions.
Strategic implications and recommended moves for 2026
-
Prioritize formats with the fastest payback for the company’s route to consumer. If you are a roaster with retail relationships, a targeted RTD test can yield rapid distribution. If you are a CPG or retailer, private‑label RTD offers a low‑CAPEX path to capture volume.
-
Lock in flexible supply agreements. Negotiate contracts that allow volume and origin flexibility to manage coffee price cycles and to capitalize on attractive origin crops when they occur.
-
Invest selectively in certifications and packaging upgrades that matter to your consumers—organic, low‑acid claims and recyclable materials—but do so using a margin‑first lens to avoid price erosion.
-
Use contract manufacturing as a scale accelerator. Co‑packer partnerships reduce CAPEX and shorten time to shelf; the right partner can also provide formulation and shelf‑life expertise that protects brand integrity.
-
Design M&A plays around distribution and manufacturing access. Acquisitions that add co‑packing capacity, regional distribution or owned brand portfolios accelerate scale and provide immediate synergies.
Closing: how to use this briefing
This briefing is a strategic entry point—designed to orient executive teams to the opportunity, the risks and the high‑probability plays for 2026. For teams ready to operationalize, the full PW Consulting Cold‑Brew Coffee Market report contains the detailed segment matrices, scenario models and competitor scorecards you will need to execute. We intentionally withhold specific sub‑segment allocations and granular regional splits in this preview to protect the competitive utility of the dataset; the complete dataset and downloadable forecasting model are available in the full report.
Next steps
-
For immediate consultation, request a model walk‑through with our strategy team to align the forecast scenarios to your P&L and investment timetable.
-
Access the full report to retrieve segment‑level forecasts, interactive scenario tools, and the complete competitive database used to generate the insights summarized here.
For detailed analysis of this topic, please visit the official page: Cold-Brew Coffee Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cast Resin Transformers Market to Reach USD 6.42 Billion by 2032 at 9.5% CAGR
By PW Consulting, 2026-07-12
Cast Resin Transformers Market — Strategic Preview for 2026 Decision-Making
As energy systems turn denser, more electrified and increasingly safety-conscious, cast resin dry‑type transformers have moved from niche application stacks into strategic procurement and product-innovation agendas. PW Consulting’s latest Cast Resin Transformers Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes validated market sizing, trend vectors and competitive playbooks designed to inform board-level and operational decisions in 2026. This preview highlights the strategic value of the study while deliberately reserving core segmented tables and granular company valuations for subscribers who access the full analysis.
Cast Resin Transformers Market
Macro trajectory and what it implies for 2026
We track the market from a 2020 baseline through a 2025 reconciliation and then through a seven‑year forecast horizon. The cast resin transformers market expanded notably in the early 2020s — reflecting accelerating electrification of buildings, industrial reconfiguration and heightened safety requirements — rising from approximately USD 2.5 billion in 2020 to a reconciled base‑year figure of USD 3.85 billion in 2025. Our forecast begins in 2026 with a modest near‑term adjustment, followed by an average compound annual growth rate (CAGR) of 9.5% across the forecast period, culminating in a market size of roughly USD 6.4 billion by 2032.
Cast Resin Transformers Market
For 2026 decision-makers this trajectory is meaningful for three reasons: (1) growth is robust but non‑linear — implying timing sensitivity to product launches and capacity expansion; (2) an elevated safety and retrofit market exists alongside new-build demand, creating distinct product‑market fits; and (3) rising unit values and serviceable lifecycle revenues make aftermarket and digital monitoring services increasingly attractive profit pools.
Cast Resin Transformers Market
Critical dynamics shaping 2026 choices
-
Regulatory and fire‑safety demands — Standards such as IEC 60076‑11 and high‑fire‑safety certifications (Trihal and equivalent schemes) are shifting procurement specifications for indoor and critical installations. Compliance is now a baseline requirement in many urban and mission‑critical projects, raising the technical bar for product certification and third‑party testing.
-
Technology differentiation — Expect product features to bifurcate along two axes: enhanced safety (fire‑retardant systems, improved potting and reduced flammability) and digitalization (IoT thermal monitoring, remote diagnostics). Vendors demonstrating both will capture premium project pipelines.
-
Supply‑chain volatility — Cast resin production relies on epoxy systems with feedstocks sensitive to global chemical markets (notably bisphenol A and epichlorohydrin). Price and availability of these inputs materially influence unit economics and inventory strategies; firms must move from reactive procurement to hedged or partnered sourcing models.
-
Manufacturing footprint and labour considerations — Specialist producers operate with compact, skilled workforces and concentrated capabilities. Manufacturing and staffing models (for example, mid‑sized facilities with 200–500 employees) affect scale, customization capability and cost basis — critical when evaluating near‑term capacity expansion or contract manufacturing options.
-
Market concentration — The market exhibits mid‑level concentration among incumbents (our competitive concentration metrics indicate a meaningful share for top players), leaving room for specialization, targeted consolidation and strategic partnerships rather than dominant market control.
Competitive positioning — strategic takeaways
Industry incumbents fall into two archetypes: global platform players with broad portfolios and international manufacturing footprints, and regional specialists focused on niche performance, bespoke engineering and local market penetration. Examples that exemplify these archetypes include established international suppliers investing in digital and sustainable product variants, and specialist manufacturers promoting engineered dry‑type solutions for demanding applications.
-
Global platforms (broad service, global footprint): These firms bundle system integration, certification and aftermarket service. Their playbook centers on cross‑sell into larger accounts and leveraging global delivery networks to underwrite large tenders.
-
Regional specialists (custom engineering, focused segments): These producers emphasize application‑specific solutions — for rail, marine, data centres and industrial clients — and often lead with fast customization, local support and tight supply‑chain control.
Recent market developments underline these positioning strategies: product launches that combine advanced fire‑safety and bio‑based resins; new on‑load tap‑changer configurations for dry‑type units; and consistent exhibition and marketing activity aimed at sectors such as renewables and data centres. These moves are early indicators of where margin expansion and order‑book growth will originate.
Strategic themes for executive agendas in 2026
-
Certification as go‑to‑market currency — Prioritize product certification (fire safety and environmental standards) as an entry and pricing lever for indoor and mission‑critical projects. Certification timelines must be integrated into product roadmaps and procurement cycles.
-
Digitalization and lifecycle revenue — Embed condition monitoring and thermal analytics into product offers to convert equipment sales into recurring service revenues and to differentiate on total cost of ownership (TCO).
-
Supply‑chain resilience — Lock in strategic feedstock agreements, explore resin substitution pathways and assess nearshoring or dual‑sourcing to mitigate epichlorohydrin and bisphenol A volatility.
-
Product modularity and retrofit pathways — Develop modular portfolios that enable staged upgrades (e.g., retrofits for fire containment, IoT sensing or OLTC integration) which appeal to utilities and urban operators constrained by CAPEX budgets.
-
Service and aftermarket scale‑up — Build service organisations capable of supporting predictive maintenance and safety audits; the aftermarket is a major lever for margin improvement as installed bases age.
-
Targeted M&A and alliance plays — Given mid‑market concentration, opportunistic acquisitions of regionally strong specialists can accelerate technology access and local market entry without replicating manufacturing investments.
What PW Consulting’s full study delivers (operationally focused)
The full report is structured to move quickly from insight to execution. Key components include:
-
Validated market sizing and reconciled historicals (2020–2025) and an editable forecast model (2026–2032) with scenario toggles for resin price shocks, regulatory acceleration and urban electrification trajectories.
-
Technology and product benchmark: comparative scorecards across electrical performance, fire safety, maintainability and digital readiness, including UX‑driven deployment notes for installers and OEMs.
-
Supply‑chain exposure mapping and procurement playbook: supplier heatmaps, single‑sourced component risks, and recommended contracting strategies to stabilise input costs.
-
Competitive intelligence module: strategic profiles, capability grids and M&A heatmaps for incumbent and challenger manufacturers (detailed scorecards and financial proxies available in the full report).
-
Regulatory impact matrix and compliance pathways to support product development timelines and market access planning.
-
Commercial playbooks and 90/180/365‑day action plans aligned to business objectives (growth, margin improvement, risk reduction) including KPI templates and investment threshold guidance.
90/180/365-day tactical checklist for executives
-
0–90 days: Initiate supplier risk audits for resin feedstocks; accelerate certification gap assessments for indoor and critical‑site offerings; pilot a telemetry retrofit on a controlled installed base.
-
90–180 days: Finalize strategic procurement contracts with hedging clauses; launch a certified product upgrade program targeted to large urban utilities; appoint a cross‑functional digital services lead.
-
180–365 days: Evaluate M&A targets or JV partners that offer either specialized engineering capability or regional manufacturing presence; scale aftermarket services with bundled SLAs and predictive maintenance contracts.
Why this intelligence will matter for your 2026 planning
Decisions taken in 2026 will lock in product roadmaps, sourcing arrangements and service models that define competitiveness over the next decade. The market’s combination of steady near‑term demand, mid‑to‑high forecast growth (9.5% CAGR through 2032), evolving safety standards and supply‑chain sensitivity creates both upside and execution risk. PW Consulting’s study converts these macro signals into actionable playbooks: prioritised investments, quantified supply contingencies and competitive strategies that protect margin while enabling share capture.
Next steps
This preview intentionally highlights the strategic contours while withholding detailed segmentation tables and company financial proxies to preserve the research’s commercial core. Subscribers to the full report receive the complete quantitative model, granular segment breakouts, vendor scorecards and executable templates for procurement, product and M&A teams. For access to the full dataset, model licence and bespoke advisory support aligned to your portfolio, contact PW Consulting through our research portal.
For detailed analysis of this topic, please visit the official page: Cast Resin Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SSPA Satcom Amplifiers to reach USD 624.6M by 2032 (5.2% CAGR)
By PW Consulting, 2026-07-12
SSPA Satcom Amplifiers Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As satellite networks proliferate — from GEO and MEO backbone systems to dense LEO constellations and emerging mmWave uplinks — the market for solid-state power amplifiers (SSPAs) is transitioning from component replacement to systems-level strategic investment. Our SSPA Satcom Amplifiers Market study, anchored on a 2025 base year and covering historical performance from 2020–2025 with forecasts through 2032, shows a sustained market expansion driven by GaN adoption, gateway modernisation, and defence-led procurement. The market is set to grow at a compound annual growth rate (CAGR) of 5.2% over the forecast horizon, reflecting steady demand for higher-efficiency uplink solutions and increasing deployment of small-footprint, high-frequency terminals.
SSPA Satcom Amplifiers Market
Why this study matters for 2026 strategic choices
- Timing matters: 2026 is the inflection point at which short-cycle procurement (transportables, gateways upgrades) and long-cycle investments (satellite payload co-design, ground infrastructure refresh) converge — creating windows for market entry, consolidation, or premium positioning.
- Technology arbitrage: The transition to GaN-on-SiC and GaN power modules has reduced operating cost and size metrics for ground stations. Buyers and system integrators making decisions in 2026 will lock in multi-year TCO profiles that favour specific amplifier architectures and supply chains.
- Regulatory and defence tailwinds: Military standards and reimbursement mechanisms in major markets (for example, recent US Space Force and Wideband program requirements) are accelerating procurement cycles for MIL-grade SSPAs — a dynamic that procurement teams must internalise when drafting RFQs in 2026.
Market trajectory in concise numbers
Our model traces the overall market from the early 2020s recovery into a stable growth pattern. By the 2025 base year the market had recovered and consolidated around high-efficiency solid-state designs; the forecast to 2032 anticipates continued expansion with compound growth at 5.2% annually. The trajectory is driven by a mix of capacity upgrades at gateways, replacement of legacy TWTAs in many ground segments, and new deployments for higher-frequency uplinks (including mmWave bands). These macro totals underpin scenario planning for CAPEX timelines, inventory strategies, and R&D roadmaps across suppliers and users.
SSPA Satcom Amplifiers Market
What the market means for strategic stakeholders
- OEMs and component suppliers: Prioritise GaN linearity and thermal management improvements. Modular, block-up-converter (BUC)-integrated offerings and power-combining approaches for V/ E/ Ka bands are high-leverage product paths.
- System integrators and service providers: Balance upfront premium on GaN SSPAs against lifecycle operational savings — energy reductions and smaller mechanical footprints materially affect gateway OPEX and siting decisions.
- Defence procurement offices: Embed MIL-STD compliance and long-term sustainment clauses into contracts now; reimbursement programs and LEO gateway modernisation funds can be structured to accelerate fielding while protecting industrial base capacity.
- Investors and M&A teams: Seek targets with differentiated module IP, demonstrated production scalability, and access to defence certifications; market concentration indicates several leaders capture a meaningful share but room persists for niche specialists.
Competitive landscape — where value is being created
The SSPA market exhibits a mid-level concentration (top-three and top-five combined shares demonstrate incumbent strength but not insurmountable barriers). Competitive advantage is clustering around a few capability axes: GaN expertise and module linearity, multi-band BUC/SSPA integration, ruggedisation for military use, mmWave power-combining, and system-level integrations for VSAT and gateway platforms.
SSPA Satcom Amplifiers Market
- Communications & Power Industries (CPI): Known for GaN-based SSPAs and high-power block-up-converters across C through Ka bands, CPI is positioned for fixed, transportable and airborne satcom use cases where power density and system integration matter.
- Comtech Telecommunications: The Puma series underlines a strategy around compact, high-efficiency GaN SSPAs with accessory features (redundancy, web control) that appeal to managed service providers and VSAT operators.
- L3Harris Narda-MITEQ: Leverages reliability and breadth across standard SATCOM bands, targeting commercial, military and scientific ground stations and payload support markets.
- Filtronic: Focused on mmWave and high-frequency uplinks with GaN Cerus products; recent UK Space Agency funding and a 100W V-band product demonstrate a bet on high-frequency ground segment growth.
- MACOM, Mission Microwave, Advantech, Teledyne Paradise, Kratos, Gilat and others: These firms differentiate across module IP, form-factor innovations (BUC-integrated lines), and tailored defense-grade offerings. MACOM’s 2026 Ka- and Q-band announcements underscore supplier emphasis on payload and direct-to-device experimentation.
Recent developments to put on your radar
- Filtronic secured public funding to advance a high-power Ka-band GaN SSPA project and released next-generation V-band SSPAs in 2025 — signalling commercial confidence in mmWave uplink demand and government support for commercial amplifier innovation.
- MACOM’s product launches and trade show presence in 2026 highlighted demonstrations for direct-to-device payloads and linearised Q-band modules — important if your roadmap assumes tighter payload-hooks with amplifier vendors.
- L3Harris Narda-MITEQ’s exhibition emphasis on LEO-optimised amplifier assemblies illustrates supplier response to constellation-era gateway requirements.
- Policy and procurement shifts: recent defence contracting language and reimbursement pathways are actively shaping procurement cycles and the opportunity window for MIL-qualified SSPAs.
Operational levers and go-to-market playbook (practical contents of the report)
The full study provides executable modules for different stakeholder types. Highlights include:
- Proprietary forecast model (2026–2032) with scenario toggles for technology adoption rates, gateway refresh timelines, and defence procurement accelerants.
- Supplier scorecards and risk matrices assessing manufacturing capacity, IP ownership, certification status, and product roadmaps — ideal for sourcing teams evaluating preferred vendors.
- Build vs. buy decision frameworks combining TCO, sustainment cost curves, and supply-chain lead-time sensitivity to guide in-house amplifier development versus contract procurement.
- Go-to-market playbooks covering channel strategies for OEMs, value propositions for systems integrators, and bundling options for VSAT service providers.
- Operational worksheets: CAPEX/OPEX calculators, energy and footprint savings estimators (reflecting observed GaN efficiency improvements), and procurement timing calendars aligned with major defence and civil program release windows.
Risks, regulatory considerations and mitigation
- Standards and certification risk: Military standards such as recent MIL-STD requirements for Ka-band systems create a barrier to entry but also an annuity stream for certified suppliers. Early certification investment is a strategic hedge.
- Supply chain concentration: GaN substrate access and module assembly capacity can be pinch points; dual-sourcing strategies and design-for-repairability reduce exposure.
- Market substitution: TWTA-to-SSPA replacement is ongoing; however, pockets of TWTA persistence remain where extreme power or specific linearity profiles are required. Positioning products for the right use cases avoids commoditisation.
- Policy and funding volatility: Grant programmes (for example, national space innovation funds) materially accelerate product development but can shift with political cycles — diversify route-to-market to include commercial anchor customers.
How to use this study in 2026 planning cycles
- Procurement: Use the report’s scenario model to set budget phasing for gateway refresh and transportable terminal upgrades across 2026–2028, aligning RFQs to supplier certification timelines.
- R&D prioritisation: Allocate development resources to GaN linearity, thermal management, and modular BUC integration — the areas with the highest expected near-term ROI.
- M&A and partnerships: Target suppliers with demonstrable production scalability and complementary system integration capabilities rather than solely component IP.
- Energy and footprint optimisation: Quantify OPEX benefits from GaN adoption to accelerate business cases for early replacements of legacy amplifiers.
What we intentionally withhold here (and why)
In keeping with the “trailer” approach of this preview, we present the strategic line-of-sight — market growth rate, concentration dynamics, competitive vectors and practical playbooks — while purposefully omitting core segment-level tables and the detailed region/application share matrices that sit at the heart of procurement decision analytics. Those granular splits, supplier-specific revenue breakdowns and pricing ladders are available in the full report and interactive datasets for subscribers and direct purchasers.
Final thought
For decision-makers planning capital allocation, supplier selection, or product roadmaps in 2026, SSPA strategy is now a cross-functional priority spanning engineering, procurement, and finance. The market’s steady CAGR and the technological momentum behind GaN create an environment where early, well-informed choices capture sustained advantage. Our full SSPA Satcom Amplifiers Market report provides the detailed levers, numbers, and vendor-level intelligence you need to move from strategic intent to executable plans — precisely the inputs that turn 2026 opportunities into multi-year value.
For detailed analysis of this topic, please visit the official page: SSPA Satcom Amplifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
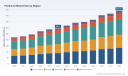
Panthenol Market 2026: Strategic Intelligence Briefing
As PW Consulting’s Lead Industry Analyst, I present this executive industry briefing to orient strategists, business development leaders, and C-suite executives on the strategic stakes as they approach 2026. Our Panthenol Market study synthesizes historical performance, competitive dynamics, supply-side drivers, regulatory inflection points and forward-looking scenarios to inform commercial decisions across product development, sourcing, manufacturing footprint and M&A activity.
Panthenol Market
Why Panthenol matters in 2026
Panthenol has evolved from a niche active into a multi-use functional ingredient embedded across personal care, pharmaceutical and nutrition value chains. Our research shows the global market expanded from approximately USD 220.8 Million in 2020 to about USD 295.5 Million in 2025, reflecting steady recovery and reinvestment after pandemic-era volatility. Looking forward, the market is projected to grow to roughly USD 439.9 Million by 2032, underpinned by a 6.0% compound annual growth rate across the 2026–2032 forecast window. These macro dynamics create an investment calculus that differs materially from other specialty chemistries: steady, mid-single-digit growth; concentration among a handful of global suppliers; and recurring demand from regulated downstream users that value reliability and provenance.
Panthenol Market
What this study delivers (practical outputs)
- Actionable supply-demand model calibrated to 2020–2025 history and stress-tested across three demand scenarios for 2026–2032.
- Price and margin sensitivity analysis that maps feedstock and energy shocks to manufacturer EBITDA under plausible near-term disruptions.
- Regulatory impact matrix that translates recent cosmetics and healthcare rules into reformulation risk, time-to-market changes and labeling costs for manufacturers and brand owners.
- Go-to-market playbooks for incumbents and new entrants covering route-to-market, distribution partnerships, and formulation support services.
- M&A and capacity investment decision framework, including valuation multipliers, integration risks and synergies based on asset type (API-grade vs cosmetic-grade manufacturing).
- Supplier risk heatmap and sourcing optimization toolkit to reduce single-source exposure while meeting quality, sustainability and regulatory specifications.
Market structure and competitive snapshot
The panthenol market exhibits moderate concentration, with the top three suppliers controlling a meaningful majority of global supply and the top five consolidating clear market power. This structure drives a competitive landscape where scale, regulatory credentials and formulation support capabilities determine commercial leverage.
Panthenol Market
- BASF SE: A global leader with deep capabilities in D-Panthenol USP for personal care and pharmaceutical applications. BASF’s recent product line emphasizing renewably sourced panthenol amplifies its sustainability positioning and offers margin and go-to-market advantages among premium personal care brands.
- Royal DSM (dsm-firmenich): A major integrated player across nutritional and health ingredients with pharmaceutical-grade offerings. Their strength lies in cross-category customer relationships and regulatory know-how in high-purity grades.
- Evonik Industries AG: Focused on care solutions and sustainability; the company expanded production capacity in Germany in late 2025 to meet rising demand—an operational response that tightens supply-side dynamics for competitors.
- Lonza Group Ltd and Croda International Plc: Specialty suppliers that blend high-purity production with formulation systems and co-development services, appealing to cosmeceutical and regulated pharmaceutical customers.
- TRI-K Industries, RITA Corporation and select Chinese producers (e.g., Brother Enterprises, Fengchen Group, Jing Jing Pharmaceutical): Providers that compete on high-purity grades, price competitiveness and local market access, particularly for regional formulators and distributors.
Recent corporate activity—capacity expansions by established majors and product launches focused on renewable feedstocks—signals a market where quality, provenance and sustainability claims are differentiating factors, not just price.
Key regulatory and market dynamics shaping 2026 decisions
- Regulatory resets in Europe: Amendments to the EU cosmetics regime that formalize concentration and labeling requirements for panthenol in leave-on formulations take effect in 2026. This will generate near-term reformulation demand and create compliance costs for brands, advantaging suppliers with certified documentation and regulatory support.
- Trade and customs friction: New import declaration requirements in markets such as Mexico introduce administrative complexity for medical and healthcare products. Supply chain teams must update import protocols and contingency plans to avoid delivery slippage for regulated customers.
- Feedstock and pricing noise: Regional feedstock and energy cost pressures produced moderate price volatility in Europe and an upward trend in Asia Pacific during 2025; North American markets experienced end-of-year restocking effects that tightened prompt availability. These episodic movements highlight the need for active price-risk management and flexible sourcing strategies.
Strategic implications for 2026 planning
Our study identifies several strategic imperatives for players across the value chain as they set priorities for 2026 budgets, capital allocation and commercial strategy.
- Sourcing resiliency and dual-sourcing: Given episodic feedstock-driven price moves and regional restocking dynamics, firms should adopt dual-sourcing where certification alignment is required and maintain strategic buffer inventory for critical SKUs serving pharmaceutical and baby-care customers.
- Regulatory-forward product development: Brands and ingredient suppliers must accelerate reformulation and labeling review cycles to align with 2026 EU rules. Suppliers that offer regulatory dossiers, stability data and co-development support will capture outsized share of reformulation spend.
- Segment-focused premiumization: With demand growth steady but not explosive, value capture will come from premiumization—sustainably sourced grades, documented supply chains and performance-backed claims. Multinationals with scale can bundle sustainability credentials with supply guarantees to win enterprise customers.
- Capacity timing and partnership models: The recent capacity expansion by major producers underscores that timing investments matter. New entrants should prioritize tolling, joint ventures or offtake agreements rather than greenfield build-outs unless they can secure advantaged feedstock or technology.
- M&A and bolt-on plays: Given a market where the top players command a substantial share, strategic acquisitions of specialty producers or formulation houses offer faster routes to capability and market access than organic growth—provided integration captures cost and regulatory synergies.
Operational playbook — concrete 90/180/360 day moves
- 0–90 days: Run a supply-chain exposure assessment; validate import documentation and local compliance (e.g., Mexico RFC requirements); renegotiate short-term contracts to include flexibility clauses for feedstock price swings.
- 90–180 days: Execute parallel development tracks for reformulation of impacted SKUs; secure conditional offtake agreements with multiple certified suppliers; begin customer communications on labeling and compliance timelines.
- 180–360 days: Finalize medium-term capacity or partnership decisions; deploy pricing mechanisms with indexation to key feedstock inputs; evaluate M&A targets and integration plans aligned to desired market segments (API-grade vs cosmetic-grade).
Implications by player archetype
- Global majors: Focus on consolidating premium positions through sustainability-credentialed products, global supply guarantees and regulatory services. Prioritize converting capacity into higher-margin, certified grades.
- Specialty formulators/ingredient houses: Differentiate via formulation support and bundled regulatory dossiers. These players benefit by deepening relationships with personal care and pharma customers who face reformulation demands.
- Regional manufacturers and distributors: Compete on responsiveness and cost but invest selectively in certification and quality systems to capture regulated demand. Partnering with global players for co-manufacturing can unlock higher-value customers.
- New entrants: De-risk entry with toll-manufacturing or licensing arrangements and target niche premium claims (e.g., bio-based feedstocks) rather than scale-driven commodity supply.
What we are watching into 2026
- Feedstock and energy price trajectories across major producing regions, and the degree to which costs pass through to formulators.
- Adoption pace of the EU regulatory changes and how quickly brands reformulate leave-on products to meet concentration and labeling requirements.
- Commercial impact of capacity additions by incumbents—whether they will relieve supply tightness broadly, or be absorbed by premium segments.
- Consolidation activity among specialty chemical players and whether strategic buyers target downstream formulation assets or upstream capacity for integration synergies.
Closing — the strategic value of this report for 2026 decisions
For executives planning 2026 investments, this Panthenol Market research is a decision-grade resource: it quantifies the size and trajectory of the market (historical and forecast), identifies the structural levers that determine margin capture, maps regulatory and trade disruption risks, and prescribes near-term operational moves. We intentionally surface directional segment insights and supplier power dynamics while reserving detailed sub-segment figures and granular regional/application splits for the full report—this approach ensures you receive a high-trust, evidence-based strategic preview while preserving the granular datasets that underpin investment and commercial execution.
To convert these insights into a tailored action plan—whether you are prioritizing sourcing resilience, evaluating an M&A target, or redesigning your product portfolio for regulatory compliance—our extended dataset and scenario models provide the necessary quantitative backing. Access to the full report will enable you to run custom scenarios using our demand, pricing and cost modules and to download the supplier matrix and M&A playbook that underlie the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Panthenol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Forged Alloy Aluminum Wheel Market - USD 3,050M in 2025 (6.11% CAGR)
By PW Consulting, 2026-07-12
Forged Alloy Aluminum Wheel Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, practice-oriented introduction to our full Forged Alloy Aluminum Wheel Market study. This briefing articulates the strategic imperatives that corporate leaders, OEM procurement teams, private equity investors, and operations heads must weigh as they set priorities in 2026. It is structured to demonstrate the analytical depth of our work while preserving the detailed proprietary segmentation that we reserve for the full report.
Forged Alloy Aluminum Wheel Market
Why this study matters for 2026
-
Macro momentum: After a recovery phase across 2020–2025, the forged alloy aluminum wheel market has reached an estimated USD 3,050 Million in the base year 2025, and our forecast models indicate continued expansion to roughly USD 4,605 Million by 2032 at a compound annual growth rate (CAGR) of approximately 6.11% (forecast period 2026–2032). These headline metrics frame a market that is sizable, investable, and structurally shifting.
Forged Alloy Aluminum Wheel Market -
Decision time horizon: 2026 will be the pivot year for many strategic moves—greenfield capacity choices, sourcing re-shoring, tariff mitigation strategies, and product roadmap shifts—because near-term supply and cost dynamics will materially affect medium-term margins and competitive positioning.
Forged Alloy Aluminum Wheel Market -
Consolidation and concentration: The topology of supplier concentration signals both opportunity and risk. The market shows a moderately concentrated supplier base (with the top-three and top-five players accounting for material shares of the market), which drives differentiated pricing power and creates both barriers and levers for newer entrants and tier-two suppliers.
Core drivers and structural dynamics
-
Premiumization and vehicle architecture: Weight reduction, fuel efficiency, and EV-range optimization continue to push OEMs toward lightweight forged solutions where acceptable on cost and certification grounds. Design-led differentiation—performance alloys, bespoke finishes, and integrated wheel systems—remains a competitive frontier.
-
Cost and supply volatility: Forged production carries materially higher unit costs versus cast or steel alternatives due to specialized machinery, premium aluminum blanks, and precision finishing. In early 2026, aluminum ingot prices spiked to multi-year highs following supply risks tied to geopolitical tensions in the Middle East, further compressing margins for manufacturers and downstream buyers alike.
-
Regulatory and market access considerations: Elevated trade policy risk reshapes sourcing strategies. Notably, recent tariff actions increased duties on aluminum derivatives in certain jurisdictions, and compliance regimes (ECE, DOT, and equivalent national standards) impose certification timelines that must be managed as part of product launches and cross-border supply strategies.
-
Application mix and OEM procurement cycles: Passenger vehicle premium segments and performance-focused light commercial use cases are the primary demand anchors for forged wheels. However, increasing productization tailored to heavier commercial vehicle applications is emerging as a strategic growth vector for suppliers seeking scale and diversified orderbooks.
Competitive landscape — what to watch in 2026
Our competitive analysis profiles incumbent global and regional leaders, assessing relative strengths across manufacturing footprint, technology, customer relationships, and product portfolios. Key firms covered include Superior Industries, CITIC Dicastal, Enkei Corporation, Maxion Wheels, Ronal Group, Alcoa Wheels, Borbet, and Topy Group.
-
Superior Industries (United States): Well entrenched with aluminum wheel portfolios targeted at passenger vehicle OEMs. Strengths include established OEM contracts and integration capabilities within aluminum system offerings.
-
CITIC Dicastal (China): A major cost-competitive producer with scale across passenger and commercial vehicle applications, leveraging vertical integration and proximity to key Asian supply chains.
-
Enkei Corporation (Japan): Technologically advanced in alloy design and performance-oriented wheel solutions, with a strong brand association in premium and motorsport-derived segments.
-
Maxion Wheels (Brazil): Noteworthy for expanding into forged commercial vehicle wheels. A near-term production launch at a new Manisa, Türkiye facility sets a strategic benchmark for capacity scaling and near-market manufacturing for regional demand.
-
Ronal Group (Switzerland): Specializes in high-end passenger and light commercial applications, with capabilities in customized finishes and engineering services.
-
Alcoa Wheels (United States): Positions forged products within broader aluminum wheel systems and leverages deep OEM relationships, especially where integrated weight-reduction solutions are pursued.
-
Borbet (Belgium): Focused on passenger and light truck markets with European manufacturing strengths and responsiveness to regional certification demands.
-
Topy Group (Japan): Entering 2026 with new commercial vehicle alloy lines and a branded product push, combining steel wheel expertise with a differentiated paint/process technology to address durability and aesthetics in heavier applications.
Recent tactical moves underscore two strategic themes: (1) capacity and capability expansion in commercial vehicle applications (e.g., greenfield launches targeting truck wheels), and (2) product platform differentiation via coatings, finishes, and alloy innovations. These moves are essential to monitor when assessing supplier selection, JV partners, or acquisition targets in 2026.
What the full PW Consulting report delivers (practical contents)
-
Robust market sizing: Year-by-year historicals (2020–2025) and a transparent forecast (2026–2032) with sensitivity bands tied to raw material and trade-policy scenarios.
-
Methodology appendix: Replicable approach combining bottom-up capacity build-ups, OEM vehicle production ramps, and demand elasticity models—valuable for corporate planning and board-level scenario stress tests.
-
Price and cost models: Unit-level cost build-ups for forging vs casting vs steel alternatives, including CAPEX profiles for new forging lines, tooling cycles, yield assumptions, and projected cost curves under different aluminum price scenarios.
-
Supply chain and localization playbook: Mapping of critical suppliers, logistics risk zones, recommended hedge strategies, and tariff mitigation options (contract structuring, tariff engineering, FTAs, nearshoring).
-
Competitive benchmarking: Capability matrices across technology, capacity, geographic reach, certification timelines, and R&D pipelines—enabling objective M&A screening and partnership scouting.
-
Commercial strategies: Go-to-market templates for OEM engagement, value-based pricing approaches, and aftermarket monetization frameworks that preserve margin while scaling volumes.
-
Operational readiness checklists: Site selection criteria, workforce skill requirements for precision forging, anticipated quality control regimes, and capital planning for 2026–2028 ramp phases.
-
Risk heatmap and mitigation: Prioritized risks—from commodity shocks and tariff shifts to certification bottlenecks—with tactical mitigation matrices and contingency triggers suitable for executive decision playbooks.
Actionable strategic recommendations for 2026
-
Prioritize flexible capacity over aggressive scale: Given raw material volatility and tariff unpredictability, staged capacity buildouts with modular forging lines and contract manufacturing options reduce downside risk while preserving optionality.
-
Pursue differentiated product routes: Invest in finish/process differentiation (coatings, paint systems, corrosion protection) and alloy innovations that create defendable margin pools outside pure price competition.
-
Re-evaluate sourcing strategies with tariff-aware models: The mid-2025 tariff adjustments materially change landed cost math. Closure of long-term contracts, nearshoring, or local JV structures can be decisive in preserving competitiveness.
-
Embed certification pathways into product development: ECE and DOT approvals can add months to time-to-market. Integrating compliance milestones into product and production plans is non-negotiable for 2026 launches.
-
Monitor consolidation windows: Market concentration suggests windows for bolt-on acquisitions or technology partnerships. Use CR3/CR5 concentration metrics and capability gaps to target M&A that accelerates entry into commercial vehicle forged segments.
How PW Consulting supports your 2026 planning
We translate this market intelligence into executable outputs: investment memos, supplier due-diligence templates, plant-location scorecards, and transaction-ready financial models. Our scenario frameworks allow clients to stress-test investments against aluminum price shocks, tariff escalations, and demand shifts across vehicle segments.
For stakeholders preparing capital allocation, supplier contracting, or market entry in 2026, the full PW Consulting Forged Alloy Aluminum Wheel Market report provides the data, diagnostics, and decision tools to act confidently. This introduction has showcased our analytical posture and the types of insights you will find in depth. To access the detailed, segment-specific tables, supplier scorecards, and our actionable playbooks, consult the full report and its appendices—where we disclose the granular intelligence that operational teams need to execute successfully in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Forged Alloy Aluminum Wheel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


