



Category: market research
PW Consulting: Serine Market to Reach USD 269.76 Million by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-09
Serine Market 2026: Strategic Imperatives from PW Consulting’s Forward Look
Executive summary
The PW Consulting Serine Market study is a decision-grade briefing for executives preparing strategic moves in 2026. Grounded in a five-year historical review (2020–2025) and a seven-year forecast horizon (2026–2032), the research quantifies market expansion, identifies concentration dynamics among producers, and translates technical trends into executable commercial playbooks. With an expected compound annual growth rate (CAGR) of 6.5% from the base year of 2025, the Serine market transitions from a niche biochemical commodity to a strategically relevant ingredient across health, pharma, and personal-care value chains.
Serine Market
Market outlook: scale, trajectory, and concentration
Key macro readings in the report give clear guidance for capital-allocation and corporate development choices in 2026. On an absolute basis, the global Serine market has grown from approximately USD 126.7 Million in 2020 to USD 173.6 Million in 2025, and is projected to reach roughly USD 269.8 Million by 2032. This scale and the steady mid-single-digit CAGR underpin growth narratives in R&D-led applications and scaled consumer adoption in supplements and cosmetics.
Serine Market
Equally important for strategy is the market’s structural profile. Our concentration analysis indicates that the top three suppliers control a dominant share (CR3 ~78.5%), with the top five capturing about 85.2% (CR5 ~85.2%). Such concentration creates both advantages and constraints: incumbents enjoy pricing and supply leverage, while new entrants face steep scale and certification barriers — yet there are targeted windows for specialist players and service providers to add differentiated value.
Serine Market
What this means for 2026 corporate decision-making
- Investment prioritization: Given an established growth trajectory and clear buyers in pharma, nutraceuticals, and personal care, prioritizing Serine-related assets (fermentation capacity, high-purity processing, or finished-product formulation) should be evidence-based and timed to avoid overcapacity exposure around peak investment waves.
- Supply security and dual sourcing: The concentrated supplier base raises exposure to single-point failures. Procurement strategies that layer strategic long-term contracts with flex toll-manufacturing arrangements are recommended.
- Value-capture via formulation: Margin expansion is most achievable downstream — in nutraceutical formulations, cosmeceuticals, and specialty pharma intermediates — where technical differentiation and branding command premium pricing.
- M&A and partnership playbook: Targets with adaptive fermentation IP, regulatory dossiers for pharmaceutical excipients, or direct-to-consumer channels for supplements present asymmetric returns when combined with a larger supplier’s scale.
Competitive landscape: strategic profiles and tactical signals
The study includes a deep-dive on leading players and supply-side archetypes. Below are distilled strategic profiles of core suppliers that will shape competitive dynamics in 2026 and near-term years.
- Ajinomoto Co., Inc. (Tokyo, Japan)
Positioned as a major fermentation-based producer, Ajinomoto’s strength lies in scale manufacturing for nutritional supplements, functional foods, and pharmaceutical supply chains. Its capability set — from strain engineering to commercial fermentation — makes it a baseline competitor for any volume-focused strategy. For partners or challengers, Ajinomoto’s cost and distribution economics must be a key counterfactual in commercial modeling.
- Kyowa Hakko Bio Co., Ltd. (Tokyo, Japan)
Kyowa Hakko’s strategic edge is in high-purity amino acids and nutraceutical-grade dossiers. Its platform is particularly relevant to firms seeking regulatory-compliant inputs or premium-branded supplements. Competitive moves from Kyowa Hakko tend to prioritize quality differentiation and channel partnerships in health-focused markets.
- Evonik Industries AG (Essen, Germany)
Evonik offers pharmaceutical- and industrial-grade Serine and operates at the intersection of specialty chemicals and pharma supply. Its positioning supports customers who require stringent quality systems and integrated supply solutions across related amino acids. A reasonable competitive conclusion is that Evonik is an attractive partner for firms seeking upstream quality assurance linked to regulated markets.
- BulkSupplements.com (USA)
As a high-volume retailer and supplier to end-market consumers and small formulators, BulkSupplements demonstrates the demand side’s appetite for cost-effective, off-the-shelf Serine powders. Its presence signals both consumerization opportunities and price-pressure at commodity levels — a reminder that brand- and formulation-led differentiation will defend margins.
Strategic risks and tailwinds
- Regulatory tightening: Pharmaceutical-grade adoption will be shaped by evolving excipient guidance and substantiation expectations for nutraceutical claims. Compliance-induced premiumization is likely for certified suppliers.
- Feedstock and fermentation economics: Improvements in fermentation yield and downstream purification materially alter unit economics; monitoring deployed bioprocess innovations is essential to scenario planning.
- Demand composition shifts: While healthcare and supplements are core demand engines, incremental uptake in cosmeceuticals and specialty industrial applications serves as a diversification hedge.
- Sustainability and ESG: Biobased production and lifecycle footprints will increasingly factor in procurement and brand positioning decisions.
What the full Serine Market report delivers (practical, actionable components)
PW Consulting’s full report is engineered for operators and strategists who must convert insight into action. Highlights include:
- Granular demand scenarios by application and region (note: this executive preview intentionally omits the granular breakdown to preserve the research’s commercial value).
- Detailed supplier scorecards covering capacity, quality certification, cost-positioning, and strategic intent.
- Price-sensitivity and margin models calibrated to varying purity grades and contract structures.
- Regulatory and compliance maps for pharmaceutical and nutraceutical pathways, including timelines and dossier requirements.
- Go-to-market frameworks for B2B and B2C launches, with channel economics and promotional playbooks.
- Transaction playbooks and valuation benchmarks tailored to M&A, joint ventures, and licensing options in the Serine ecosystem.
- Operationally-focused risk registers (supply disruption, feedstock volatility, quality failure), and recommended mitigating actions with expected costs and timelines.
Recommended 12–24 month roadmap for 2026 decision-makers
- Q1–Q2 2026: Market and supplier due diligence — Commission targeted supplier audits, validate fermentation yield improvements, and stress-test demand assumptions against the report’s scenarios.
- Q3 2026: Secure optionality — Negotiate flexible offtake agreements and identify toll-manufacturing partners to de-risk capacity commitments while preserving upside participation.
- Q4 2026–Q2 2027: Value-capture initiatives — Prioritize downstream formulation projects with higher unit economics, begin regulatory filings where pharmaceutical orientation is strategic, and pilot branded consumer SKUs if the company has D2C ambitions.
- Ongoing: Monitor supply concentration dynamics — Use rolling CR3/CR5 trackers and supplier health indices to flag acquisition or partnership opportunities that alter competitive balances.
Why PW Consulting’s approach matters
Many market briefs present forecasts without translating them into implementation pathways. Our Serine Market study blends quantitative forecasting with supplier intelligence, regulatory mapping, and executable commercial templates. The result is a tactical guide that helps corporate leaders ask the right questions in 2026: where to place capital, how to secure feedstock, which quality tiers to prioritize, and how to structure partnerships to capture margin without overextending balance sheets.
Next steps
This introduction is purposefully selective: it provides the strategic framing and key macro metrics (including the 6.5% CAGR and headline market sizes across the 2020–2032 window) while withholding the granular application and regional splits that underpin tailored commercial strategies. For teams preparing capital budgets, procurement renegotiations, or M&A targets in 2026, the full Serine Market report delivers the decomposed data, supplier matrices, and transaction templates required to act with conviction.
Access the full study to retrieve the detailed regional and application-level intelligence, scenario spreadsheets, and supplier dossiers that will convert strategy into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Serine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Trisenox Market to Hit USD 382 Million by 2032 at 8.5% CAGR — PW Consulting Insights
By PW Consulting, 2026-07-09
Trisenox Market 2026: Strategic Imperatives from PW Consulting’s Market Overview
As pharma and biotech leaders plan budgets and launches for 2026, a nuanced understanding of the Trisenox (arsenic trioxide) market is no longer optional — it is strategic. PW Consulting’s latest Trisenox Market study synthesizes historical performance, driver-level dynamics, competitive posture and forward-looking scenarios to convert macro signals into actionable choices. This preview outlines the report’s value to decision-makers, highlights the critical market dynamics through 2032, and signals where first-mover advantage will accrue — while intentionally withholding proprietary segment tables to encourage direct access to the full report.
Trisenox Market
Market trajectory: clarity where it counts
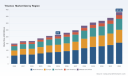
Fundamental market metrics show a resilient growth path. Using 2025 as the base year, the Trisenox market expanded from an estimated USD 150 million in 2020 to approximately USD 215 million by 2025, and our modeling projects continued expansion through the 2026–2032 forecast period at a compound annual growth rate (CAGR) of roughly 8.5%. By the end of the forecast horizon, the global market is projected to approach the high hundreds of millions (USD ~382 million in 2032 under the base scenario). Near-term momentum is visible in 2026 estimates that place the market north of USD 230 million, reflecting both durable clinical demand and ongoing shifts across pricing, manufacturing and therapeutic paradigms.
Trisenox Market
What these macro numbers mean for 2026 decision-making
- Revenue planning must account for divergent forces. Base growth is solid, but upside and downside scenarios diverge depending on competitive entry (generics and novel oral formulations), payer stance and manufacturing continuity. Financial plans that assume linear growth will misestimate both upside opportunity and downside risk.
- Margin compression is a credible near-term threat. The emergence and market penetration of lower-priced generics, which industry trackers indicate are materially discounted versus branded Trisenox, increases the probability of pricing-led share shifts and squeezes realized prices unless differentiated value is demonstrable to payers and providers.
- Lifecycle innovations can swing category economics. Oral arsenic formulations advancing through expedited regulatory pathways represent a classic disruption vector: easier administration plus improved patient convenience can re-reference standard-of-care economics and channel dynamics.
Competitive landscape: fragmented, competitive, and strategically active
The Trisenox market is characterized by a modest concentration profile — the leading firms do not dominate in the way seen in some specialty biologics. This fragmentation creates both opportunities and operational headaches:
Trisenox Market
- Incumbent brand holders retain label clarity and manufacturing provenance — Teva Pharmaceuticals remains the named manufacturer for the branded Trisenox product, which supports brand recognition and established formulary positions.
- Multiple generic manufacturers have active arsenic trioxide injection introductions, increasing pricing pressure and channel complexity. Large contract manufacturers and specialty injectables players supply clinically equivalent presentations, and some producers market multiple concentration formats, which matters for hospital procurement and dosing logistics.
- Low aggregate concentration (a CR3 in the low double digits and a CR5 only marginally higher) signals a marketplace where competitive tendering, volume-based contracting and localized sourcing decisions are routine. For commercial teams, that environment necessitates playbooks tailored to both national procurement and institutional formulary processes.
Regulatory, reimbursement and manufacturing dynamics to watch
- Regulatory acceleration for oral arsenic: An oral arsenic trioxide candidate received Fast Track designation in early 2026 and has advanced into late-stage testing. If approved, an oral option could reshape outpatient administration patterns and exert pricing pressure on intravenous presentations.
- Reimbursement backbone: Medicare-level coverage policies have been updated to include Trisenox and approved generics, reducing payer uncertainty in key markets. This coverage clarity is a double-edged sword: it supports baseline demand but also enables aggressive formulary competition among suppliers.
- Manufacturing and supply resilience: Leading suppliers produce multiple concentration formats, which influences hospital purchasing and cold-chain logistics. Continuity of API supply and validated manufacturing lines are immediate risk points for any player relying on tight inventory turns.
- Pricing delta between brand and generics: Market intelligence consistently shows generics priced substantially below the branded product. For branded owners and originators, this implies that commercial strategies must shift from price-based defense to outcomes and access-based differentiation.
Strategic playbook: five near-term priorities for 2026
PW Consulting’s scenario work and stakeholder interviews point to five imperatives that should inform boardroom decisions in 2026:
- Reframe value beyond price. Invest in real-world evidence (RWE) initiatives that demonstrate downstream cost offsets — e.g., shorter hospital stays, reduced infusion-related resource use, or improved adherence in specific regimens — to underpin higher net prices or preferred formulary placement.
- Hedge supply via dual-sourcing and fill-finish flexibility. Given the concentration of small manufacturers and the operational complexity of injectables, establish backup API agreements and secondary fill-finish relationships to minimize disruption risk.
- Prepare for oral competition with differentiated clinical narratives. Model adoption curves for a potential oral entrant and build contingency plans (e.g., bundled services, patient support programs) that can blunt outpatient migration.
- Segment go-to-market by decision-maker. Hospitals, oncology networks and national payers make different trade-offs. Tailored engagement — from tender tactics for procurement teams to outcomes contracts for payers — will outperform one-size-fits-all approaches.
- Pursue selective inorganic moves. M&A and licensing can be efficient ways to secure scale, API access or novel formulations. Target assets that fill delivery or cost gaps rather than chasing marginal volume additions.
Report deliverables: what’s inside the full PW Consulting study
This market briefing is a condensed window into the full study, which provides the granular deliverables executives need for decision-making in 2026:
- Comprehensive market sizing and a year-by-year forecast (2026–2032) with scenario-specific runways and sensitivity testing.
- Competitive intelligence dossiers on branded and generic manufacturers, including capability maps, commercial footprints and manufacturing capacity assessments.
- Payer and reimbursement mapping at national and institutional levels, with negotiation playbooks and modeled reimbursement outcomes under alternative contracting strategies.
- Supply chain and API risk-maps: single-point-of-failure identification, mitigation options and cost-to-implement estimates.
- Regulatory and pipeline tracker, integrating expedited pathways, trial milestones and potential market-access timing for oral and novel formulations.
- Commercial readiness checklists, launch playbooks and payer contracting templates designed for rapid operationalization.
- Appendices containing the underlying datasets, modeling assumptions, and detailed scenario outputs for internal stress-testing.
How competitors are likely to act — and how you should respond
Given the mix of branded incumbency and broad generics supply, the next 12–18 months are likely to see:
- broader tender activity and price-led contracting in hospitals;
- continued margin pressure on IV presentations as generics expand penetration; and
- early adopters evaluating oral arsenic options if phase outcomes validate non-inferiority plus convenience benefits.
For organisations with branded exposure, the recommended response package combines evidence-generation (to protect price), targeted contracting (to secure preferred access) and operational resiliency (to guarantee supply). For generics suppliers, scale and service differentiation — such as consistent multi-dose presentations and institutional logistics support — will be decisive.
Final strategic takeaway
The Trisenox category will not be static in 2026: it sits at the intersection of clinical innovation, pricing friction and manufacturing complexity. The market’s steady baseline growth (an 8.5% CAGR over the forecast window, with the global market growing from a mid-three-figure USD million base in 2025 to materially higher levels by 2032) hides important structural choices for companies. Firms that translate the macro trajectory into operational priorities — RWE investment, supply redundancy, payer-centered contracting and preparation for oral competition — will shape who captures disproportionate value.
This article is a concise executive preview. PW Consulting’s full Trisenox Market report contains the detailed breakdowns, scenario models, competitor scorecards and operational templates that boards and commercial teams require to convert insight into execution. Accessing the full dataset and confidential annexes will allow you to move from strategic intent to tactical commitment with confidence.
For detailed analysis of this topic, please visit the official page: Trisenox Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cyclodextrin Market 2026: Strategic Signals for Growth, Risk and Competitive Advantage
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an evidence-based preview of our new Cyclodextrin Market study — designed to inform executive decisions in 2026. This briefing synthesizes the market’s macro trajectory, structural dynamics, competitive posture and regulatory realities, and explains how the full report converts these insights into executable options for commercial, product and portfolio leaders. Consider this a high-fidelity trailer: you will find rigorous, decision-ready analysis here, while the full segmentation tables, proprietary demand matrices and granular supplier benchmarking remain reserved for the complete study.
Cyclodextrin Market
Why cyclodextrins matter to 2026 strategic choices
- Pharmaceutical reformulation and drug-delivery innovation continue to drive premium demand for pharmaceutical-grade cyclodextrins — an increasingly strategic excipient in late-stage development and lifecycle management.
- Food, cosmetics and specialty chemical applications are expanding the addressable market on distinct value propositions (stability, encapsulation, masking), creating cross-sector use cases for differentiated derivatives.
- Supply chain resilience and regulatory compliance, including compendial standards and drug master file (DMF/CEP) requirements, have become material factors in supplier selection and go-to-market timing.
Market trajectory — the macro view
The cyclodextrin market is on a multi-year expansion path. Using 2025 as our base year, the market demonstrates a steady compound annual growth rate (CAGR) in the mid-single digits — reflecting both sustained commercial adoption and incremental technical innovation. Historically, the market has grown from the low‑hundreds (USD, Million) range in 2020 to a larger base by 2025; projections through our 2026–2032 forecast window show continued expansion with occasional acceleration tied to pharmaceutical approvals and broader uptake in consumer-facing categories.
Cyclodextrin Market
Two practical takeaways for 2026 planning: first, assume a growth environment that supports incremental capacity investments or JV expansions where regulatory-qualified supply can be secured; second, expect price and margin dynamics to diverge by grade (pharma vs industrial/food) and by the availability of DMFs/CEPs for specific derivatives.
Cyclodextrin Market
Market structure and concentration — what it means for buyers and investors
The market exhibits moderate concentration. The top three and top five firms account for a meaningful share of supply, indicating scale advantages for established producers, but not an oligopoly impermeable to niche entrants. For corporates, this structure creates three strategic vectors:
- Secure supply: prioritize suppliers that offer pharmaceutical-grade documentation and cGMP-compliant manufacturing when your product roadmap depends on regulatory approvals.
- Differentiate via formulation: smaller, agile players and specialized derivative producers continue to win value through formulation services and co-development agreements.
- M&A and partnerships: the moderate concentration makes bolt-on acquisitions and strategic partnerships an efficient way to access new derivative capability or to vertically integrate feedstock-to-excipient value chains.
Regulatory and quality dynamics — the gating factors
Regulatory conformity is a gatekeeper in cyclodextrin commercialization. Pharmaceutical-quality supply hinges on adherence to compendial standards (USP, Ph.Eur., JP), cGMP manufacturing, and the availability of DMFs/CEPs for global supply chains. Several market participants already hold regulatory filings and approvals that materially shorten lead times for pharma customers.
Strategic implications:
- For drug developers: supplier DMF access and historical regulatory precedent can materially de‑risk timelines. Early supplier engagement should focus on documentation scope and international licensing arrangements.
- For producers: investment in compendial alignment and DMF filings is a high-return barrier to entry for premium segments; prioritize these investments if targeting pharma-focused growth.
- For investors: regulatory-capable assets command valuation premiums given the time and cost to replicate filings and GMP infrastructure.
Supply dynamics and raw materials
Cyclodextrin production remains rooted in enzymatic conversion of starch feedstocks (corn, potato, etc.). Feedstock availability, enzyme sourcing, and bioprocess optimization therefore influence cost curves and scaling timelines. This technical baseline makes feedstock security and process yield improvements attractive levers for cost leadership.
Competitive landscape — who brings what to the table
We evaluated the market through both capability and strategic lens. Below are high-level positioning notes on the core industry actors we analyze in the full study. Each profile contains implications for partnership, procurement and competitive response.
- Wacker Chemie AG (Munich, Germany) — Unique vertical breadth: Wacker is notable for producing all three native cyclodextrins plus derivatives and for supplying pharmaceutical-grade products across multiple purity tiers. Strategic implication: preferred partner for customers seeking a one-stop, compendial-aligned supplier with scale and global reach.
- Roquette Frères (Lestrem, France) — Pioneer in starch-based beta-cyclodextrin and active in both native and modified ranges. Roquette’s recent product launches demonstrate a focused R&D cadence aimed at formulation-ready excipients. Strategic implication: competitive in both pharma and food channels; watch for continued product-level innovation and expanded licensing agreements.
- CycloLab (Budapest, Hungary) — Specialized in pharmaceutical-grade derivatives and holds active DMF/filings for certain products. CycloLab’s R&D and GMP capabilities make it a frequent co-development partner for drug formulators. Strategic implication: attractive for programs requiring tailored derivative chemistry and rapid regulatory documentation.
- Ashland Global Holdings (Wilmington, Delaware, USA) — Major distributor and integrator of excipients, combining cyclodextrin supply with formulation services and go-to-market networks. Strategic implication: ideal channel partner for companies seeking market access and formulation support in consumer healthcare and personal care segments.
- Ensuiko Sugar Refining & Nihon Shokuhin Kako (Tokyo, Japan) — Regional leaders with strong footing in food and pharma-grade supply within Asia. Strategic implication: preferred suppliers for market entrants with Asia-centric commercial strategies or for global companies that require multi-regional sourcing redundancy.
- Shandong Binzhou Zhiyuan & Shandong Xinda (Binzhou, China) — Chinese manufacturers active across derivative grades, increasingly quality-focused and cost-competitive. Strategic implication: potential low-cost supply source for non-regulated or regionally regulated applications, with upward pressure toward pharma-grade capability.
Recent significant development
In October 2025, Roquette launched a methyl-beta-cyclodextrin product targeted at oral and parenteral formulations, underscoring how product innovation continues to unlock new routes to market and to influence supplier selection for downstream firms. Such launches can shift procurement discussions from price-only to capability-and-licensing negotiations.
What the full PW Consulting report delivers (practical, actionable content)
Our full study is designed for executives who need to act in 2026. Key deliverables include:
- Proprietary demand model and forecast through 2032, with scenario analysis on regulatory shocks and major pharmaceutical approvals.
- Supply-side capacity map and risk heatmap (supplier DMF/CEP status, cGMP certification, geographic concentration, feedstock exposure).
- Commercial playbooks by end-use (pharma, food & beverage, cosmetics, chemicals) that translate market dynamics into go-to-market moves and pricing strategies.
- Supplier decision matrix that balances technical fit, regulatory readiness and total landed cost for multi‑region sourcing.
- Opportunity map for R&D, M&A and manufacturing investments — identifying segments where margin expansion or defensible scale is attainable.
Actionable recommendations for 2026
- Embed supplier regulatory qualification into critical-path planning: make DMF/CEP access a gating decision for any program with regulatory timelines.
- Pursue dual-sourcing in pharma-grade segments: combine a Tier‑1 established supplier with a specialized partner for derivative work to balance cost, risk and innovation speed.
- Consider targeted capacity investments or JVs in enzymatic processing where feedstock volatility materially affects unit economics or time-to-market.
- Prioritize formulation partnerships over commodity procurement where differentiation (bioavailability, stability) creates premium pricing opportunities.
- Use M&A selectively to acquire DMFs, cGMP facilities or co-development teams rather than attempting greenfield builds that risk timeline slippage.
How to use this insight
If you are a C-suite leader in pharmaceuticals, consumer goods or specialty chemicals, this preview should shape your 2026 priorities: secure regulatory‑compliant supply, accelerate co-development conversations for derivative chemistry, and align procurement strategies with product roadmaps. For investors, the study identifies structural value drivers that separate commodity producers from high-margin, dossier‑enabled suppliers.
Next steps — where to get the granular intelligence
This briefing highlights the strategic contours and decision levers. The complete PW Consulting Cyclodextrin Market report contains the granular segmentation, supplier-by-supplier scorecards, and downloadable financial models required to execute procurement, technical and M&A strategies. Access to that detailed intelligence is available through our report page and bespoke advisory engagements — where we help translate the numbers into negotiated contracts, JV term sheets and prioritized R&D portfolios.
Contact PW Consulting to schedule a briefing of the full report and a tailored workshop that aligns these insights with your 2026 strategic plan.
For detailed analysis of this topic, please visit the official page: Cyclodextrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Albumin (as Excipient) Market Poised for 5.92% CAGR (2026–2032)
By PW Consulting, 2026-07-09
Albumin (as Excipient) Market — Strategic Briefing for 2026 Decision-Makers
As pharmaceutical and biopharmaceutical product portfolios expand in complexity, the role of albumin as an excipient has moved from a niche stabilizer to a strategic ingredient influencing formulation reliability, supply-chain resilience, and regulatory positioning. This PW Consulting briefing previews our full Albumin (as Excipient) Market study (base year 2025, historical 2020–2025, forecast 2026–2032) and explains why this analysis should sit on the desk of every executive making 2026 investment, sourcing, or M&A decisions.
Albumin (as Excipient) Market
Market snapshot — what the headline numbers tell you
-
Market trajectory: The albumin excipient market has expanded steadily, rising from approximately USD 747 million in 2020 to about USD 979 million in 2025. Our modelling projects a continuation of this expansion into 2026 and beyond, with the market passing the USD 1.04 billion mark in 2026 and reaching roughly USD 1.45 billion by 2032.
Albumin (as Excipient) Market -
Growth pace: A compound annual growth rate (CAGR) of ~5.9% across the 2026–2032 forecast window signals structural growth driven by biologics maturation, vaccine manufacturing scale-up, and increasing adoption of recombinant alternatives.
Albumin (as Excipient) Market -
Market structure: The sector is moderately concentrated — the top three suppliers account for roughly one third of the market, and the top five near half — creating a competitive environment where scale, regulatory credentials, and supply reliability materially affect pricing and access.
Why this report matters for 2026 strategic choices
-
Sourcing and procurement: Our analysis deciphers the trade-offs between plasma-derived and recombinant albumin in terms of availability, cost volatility, and supplier risk. This is essential for procurement teams designing multi-tier sourcing strategies or negotiating long-term offtakes.
-
Capacity and capex planning: For manufacturers and investors contemplating brownfield or greenfield builds, the report provides a decision framework that links expected product pipeline cadence with realistic lead times for albumin capacity expansion.
-
Formulation and product differentiation: R&D and CMC teams will find targeted guidance on when albumin inclusion delivers meaningful stability or delivery advantages versus alternative excipients — informing go/no-go formulation trade-offs ahead of pivotal trials.
-
Regulatory & market access: Policymakers and market-access teams get an evidence-backed roadmap for engaging regulators on sourcing constraints and substitution strategies, helping preserve launch timelines in jurisdictions sensitive to plasma supply disruptions.
-
M&A and partnership diligence: Our benchmarking, supplier scorecards, and scenario valuations sharpen acquirers’ ability to price targets that own plasma fractionation assets, recombinant platforms, or excipient-grade processing lines.
What you’ll find inside — practical, transaction-ready deliverables
-
Proprietary demand model (by therapeutic application and end-market scenarios) with sensitivity levers you can re-run under custom hypotheses.
-
Supply-side maps and capacity timelines highlighting chokepoints (plasma collection, fractionation throughput, recombinant bioprocess scale-up) and practical mitigation playbooks.
-
Supplier scorecards that synthesize GMP credentials, regulatory approvals, geographic resilience, and commercial readiness — arranged to support fast vendor selection without divulging confidential volumes.
-
Regulatory risk matrix and engagement templates designed to support dossiers and pre-submission interactions focused on excipient sourcing transparency.
-
Commercial scenarios and price-elasticity guidance calibrated to real-world procurement contracts, enabling sales and pricing teams to model margin impacts of supplier concentration and substitution.
-
Actionable playbooks for three archetypal buyers: (1) large integrated biopharma, (2) mid-sized biologics/contract developers, and (3) contract manufacturers / CDMOs — each with recommended near-term moves for 2026.
Competitive landscape — what the major players are doing and why it matters
-
Large plasma integrators (examples: CSL Behring, Grifols, Octapharma) retain advantage through integrated plasmapheresis networks and fractionation capacity. Recent public investments — including facility upgrades and capacity expansions — underscore the premium consumers place on supply assurance. For buyers, this translates into negotiating bandwidth: premium for guaranteed supply, or risk of exposure to substitution if premiums are declined.
-
Recombinant specialists and reagent suppliers (examples: InVitria/Ventria, Merck/Sigma-Aldrich, Sartorius, Albumedix) are accelerating adoption by providing animal- and blood-free alternatives with lower ethical and sourcing friction. These players have seen increasing acceptance in vaccines, gene therapies, and high-value biologic formulations — notably, recombinant albumin products have been dosed in the hundreds of millions of administrations and already support a substantial portion of the leading pharma cohort.
-
Regional producers and plasma product firms (examples: Baxter, Kedrion, Biotest, LFB, select Chinese producers) compete on cost, proximity, and regulatory alignment. Their role is pivotal in regional continuity plans, though they must continue investing in cGMP upgrades and traceability to win global contracts.
-
Market moves to watch (recent developments): Grifols’ announced production facility investment, Baxter’s digital supply-chain platform launch, and Octapharma’s strategic alliance to develop albumin-based therapies all highlight three near-term themes — capacity expansion, digitalization of logistics and traceability, and upstream product innovation via collaboration.
Industry dynamics and risk vectors — what keeps CFOs and CMC heads awake
-
Raw material & throughput constraints: Plasma availability and fractionation throughput materially constrain conventional Human Serum Albumin (HSA) manufacturing capacity. These constraints support resilient pricing and underline why buyers face a supply/price trade-off through the next decade.
-
Regulatory & geopolitical noise: Historical and ongoing plasma shortages in parts of Europe and elsewhere reinforce the need for contingency planning. Regulatory scrutiny focused on supply integrity and donor-sourced materials adds both cost and time to market for plasma-derived solutions.
-
Cost structure hurdles: High fixed and variable costs for both plasma-derived and recombinant manufacturing remain a headwind. This factor favors players with scale, vertical integration, or novel process economics that can compress costs without sacrificing compliance.
-
Recombinant adoption as a strategic lever: Recombinant albumin addresses ethical sourcing concerns and supply constraints, offering a credible substitution path in many use-cases. However, transition timelines, CMC comparability demands, and payer recognition vary by application, requiring bespoke migration plans.
Using this analysis to set 2026 priorities — recommended actions
-
Establish a dual-track sourcing policy: Combine long-term volumes under contract with plasma-integrated suppliers while qualifying recombinant alternatives as second-source or phased substitutes. Documentation and comparability studies should be initiated in 2026 if substitution is strategic.
-
Prioritize supply-chain digitization: Invest in visibility tools (lot-level traceability, predictive lead-time dashboards) to reduce contingency buffers without increasing stockholding costs. Early pilots with suppliers’ digital platforms can yield outsized resilience gains.
-
Targeted capex or M&A: If vertical integration into plasma collection or recombinant capacity aligns with your risk appetite, the next 12–24 months present acquisition windows where assets can be priced with clear upside from contracted demand assumptions.
-
Embed regulatory engagement early: Proactively align with regulators on substitution pathways for recombinant albumin and on excipient traceability standards — these dialogues shorten approval cycles and de-risk launches.
-
Advance formulation strategies: R&D and CMC should map which programs materially benefit from albumin inclusion and run accelerated stability comparability packages to lock excipient choices ahead of pivotal studies.
How PW Consulting’s study supports execution
-
Our full report supplies the granular datasets, scenario models, supplier scoring outputs, and commercial templates needed to operationalize the strategic moves above. The public brief you are reading intentionally omits confidential segmentation detail to protect client value — the full dataset unlocks the precise levers used in our client engagements.
-
For teams preparing procurement RFPs, M&A diligence, or CMC comparability plans in 2026, the study acts as a single-source-of-truth that combines macro forecasts with tactical playbooks, cutting due diligence timelines by weeks.
Concluding perspective — why act now
By 2026, albumin as an excipient will be more than a formulation choice — it will be a strategic axis for supply resiliency, regulatory positioning, and product differentiation. The moderate-growth trajectory (near 6% CAGR in our central forecast) masks meaningful asymmetries: capacity constraints, regulatory pressure, and recombinant adoption create pockets of acute risk and opportunity. Companies that define sourcing duality, invest selectively in traceable supply-chains, and engage regulators proactively will convert this structural change into competitive advantage.
PW Consulting’s full Albumin (as Excipient) Market report provides the data, scenarios, and executable playbooks required to make those 2026 decisions with confidence. For clients and shortlisted partners, we also offer bespoke workshops that translate the report’s insights into tailored procurement and R&D roadmaps. Contact the PW Consulting team to access the complete study and unlock the granular market segmentation, supplier analytics, and model-enabled scenarios underpinning these conclusions.
For detailed analysis of this topic, please visit the official page: Albumin (as Excipient) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Micro Electrode Array Market to Reach USD 1,981.35M by 2032 at 9.25% CAGR - PW Consulting
By PW Consulting, 2026-07-09
Micro Electrode Array (MEA) Market: Strategic Outlook and Action Roadmap for 2026
Executive snapshot
As organizations prepare capital and R&D allocations for 2026, the Micro Electrode Array (MEA) market has moved from a specialist niche into a mainstream platform technology for neuroscience, cardiotoxicity screening, and advanced drug-discovery workflows. Our PW Consulting market model shows sustained momentum: the global MEA market expanded from the mid-single-hundreds of millions in 2020 to a base-year size of approximately USD 1.07 billion in 2025, and is forecast to grow at a compound annual growth rate of roughly 9.25% through the 2026–2032 horizon, approaching nearly USD 2.0 billion by 2032. This growth profile creates distinct windows for investment, vertical integration, and technology differentiation — but it also sharpens operational and supply-chain risks that boards and strategy teams must address now.
Micro Electrode Array Market
Why this study matters for 2026 decision-makers
Executives face three simultaneous inflection points in 2026. First, adoption is broadening across pharma and academic labs, shifting procurement from project-based buys to platform-level purchases and service relationships. Second, technological variety is increasing — traditional planar arrays coexist with high-density CMOS-based systems, 3D assemblies and flexible substrates — raising product-roadmap and IP choices. Third, macro supply-chain and regulatory dynamics are tightening the production envelope: specialized microfabrication talent, critical electrode materials, and quality-system certification are now strategic inputs, not mere operational details.
Micro Electrode Array Market
For corporate leaders, this report converts those macro observations into actionable decisions: where to allocate R&D spend to maximize differentiated capability, how to structure supply contracts to insulate against export-control and critical-minerals shocks, and which commercial models best convert early-adopter research customers into recurring revenue streams in 2026 and beyond.
Micro Electrode Array Market
What the PW Consulting report delivers (practical contents)
- Proprietary market-sizing and a fully transparent topline model (2020–2025 historical, 2026–2032 forecast) built from supplier-level inputs and demand-side adoption curves.
- Segment-level frameworks (by geography, by device architecture, by application) with scenario toggles — note: segmented dollar detail is reserved for the full report to preserve client value.
- End-to-end value chain decomposition: material inputs (electrodes, substrates, interconnects), manufacturing process maps (cleanroom steps, lithography, plating), and time-to-market drivers.
- Commercial playbooks: validation study design, pricing heuristics for plate- and system-based licensing, channel partnership templates, and CRO/CMO partnership roadmaps for service expansion.
- Supply-chain and regulatory risk matrices: critical-minerals exposure analysis, ISO and quality-system requirements, export-control scenarios and mitigation playbooks.
- M&A and partnership scorecards: diligence checklists focused on IP defensibility, fabrication capability, customer stickiness, and TAM overlap.
- Scenario-driven strategic options: three investment paths (scale-manufacture; platform-differentiation; service-led monetization) with expected ROI profiles and break-even timelines under multiple demand curves.
Competitive landscape — who matters and why
The MEA supplier ecosystem mixes specialist device fabricators, modular platform vendors, and vertically integrated system providers. Market concentration metrics indicate a moderately consolidated market: the top three players account for roughly 42% of market activity, and the top five about 52% — enough concentration to create scale advantages, but with clear room for focused, technology-led challengers.
- MicroElectrodeDevices MED sàrl (Switzerland) — focused on custom MEA biochips using microfabricated platinum electrodes for in vitro recording and stimulation. Their strengths are bespoke design and tight manufacturing control across platinum-on-substrate constructs.
- Multi Channel Systems (Germany) — offers modular MEA systems spanning standard arrays to CMOS-enabled solutions. They bring broad product breadth and compliance depth (quality systems) that appeal to institutional procurement teams.
- MaxWell Biosystems (Switzerland) — positions around high-density CMOS HD-MEA platforms that deliver sub-cellular resolution; strong appeal in drug-discovery pipelines that require high-throughput, high-resolution electrophysiology data.
- 3Brain AG (Switzerland) — develops high-density multi-electrode well systems enabling simultaneous thousands-electrode recording per well, attractive for labs scaling parallel assays.
- Alpha MED Scientific, Inc. (Japan) — established MEA system supplier known for the MED64 platform and recent product-catalog updates that signal ongoing product lifecycle management.
- Axion BioSystems (United States) — commercializes plate-based MEA systems aimed at drug-discovery workflows and offers integrated software and analytics, strengthening the systems-plus-software value proposition.
- MicroProbes for Life Science (United States) — niche supplier of precision-tapered MEAs for acute and chronic in vivo/in vitro recordings, serving specialized research and translational applications.
Each supplier exhibits a different go-to-market logic — from instrument-centric sales to platform-plus-analytics or high-mix, low-volume custom fabrication. Our competitive benchmarking in the full report maps product roadmaps, price bands, installed-base strength, and customer satisfaction proxies to help buyers and partners choose optimal targets.
Operational, materials and regulatory dynamics that will shape 2026 outcomes
- Raw materials and manufacturing. MEA biochips typically use micro-fabricated platinum electrodes mounted on flexible polyimide or silicon substrates. Securing consistent electrode quality demands mature plating and passivation processes; any supply disruption in electrode materials or substrate wafers translates quickly into lead-time risk.
- Quality and certification. Consistent output requires ISO-grade quality systems; many industry manufacturers operate under ISO 9001:2015 frameworks, which function as procurement gatekeepers for institutional customers.
- Labor and capability. High-density MEA fabrication is effectively an adjacent semiconductor activity: cleanroom processes, lithography, and semiconductor expertise are required, meaning labor cost and talent scarcity drive margins and capital intensity.
- Geopolitics and export control. Recent frameworks aimed at securing critical minerals and semiconductor supply chains increase the strategic importance of supplier geography and contract structure; export-control scenarios should be modeled in procurement and sourcing strategies now.
Strategic imperatives for 2026 (action checklist)
Leaders should prioritize three categories of action to convert market growth into defensible advantage.
- Secure supply and modularize risk: Lock multi-year agreements for critical electrode materials and substrate wafers; qualify secondary suppliers and consider joint-investment in domestic fabrication capacity or consortia to mitigate export-control exposure.
- Differentiate at the platform level: Invest selectively in high-density CMOS or flexible-substrate capabilities if your target customers demand sub-cellular resolution or implantable-friendly designs. Alternatively, double down on system-level software and analytics for labs seeking turnkey assay throughput.
- Monetize beyond hardware: Build recurring revenue through validated assay kits, data-analysis subscriptions, and CRO-style waveform-analysis services that lock customers into multicampus deployments.
- Optimize manufacturing footprint: Map the cost-to-serve of in-house fabrication vs. contract microfabrication; emphasize quality-system compliance early in any insourcing decision to avoid time-to-market slippage.
- M&A and partnership criteria: Target acquisitions that provide immediate access to cleanroom capacity, key IP in CMOS readout, or established validation partnerships with pharma; use our diligence templates to stress-test integration risk and customer retention.
Use cases: how different buyers should interpret the findings
- Pharma R&D and CROs: Prioritize suppliers with validated plate-based systems and integrated analytics; negotiate for co-development rights and data-sharing agreements to accelerate assay standardization.
- Device OEMs and startups: Focus early R&D on manufacturable electrode chemistries and quality-compliant processes; consider partnerships with specialized fabricators to shorten capital expenditure cycles.
- Investors and corporate development: Evaluate targets through the lens of installed base and recurring revenue potential; fragmentation creates opportunities for platform consolidation and bolt-on acquisitions.
Conclusion — the strategic edge PW Consulting provides
For executives allocating capital and shaping product roadmaps in 2026, the MEA market offers attractive growth but requires disciplined decisions across technology, supply chain, and commercial model design. Our PW Consulting Micro Electrode Array Market study blends a transparent macro forecast with operationally prescriptive modules — from raw-material exposure maps and ISO compliance checklists to M&A scorecards and go-to-market playbooks — giving you the analytical rigor to move from option evaluation to executable plans.
Next step
This article is a strategic preview highlighting why the MEA market should be on your 2026 radar and how to convert growth opportunities into durable advantage. To access the full segment-level datasets, supplier scorecards, and downloadable scenario models that underpin these recommendations, request the complete PW Consulting Micro Electrode Array Market report through our client portal.
For detailed analysis of this topic, please visit the official page: Micro Electrode Array Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Isobornyl Acrylate Market to Reach USD 664.26M by 2032 at 7.52% CAGR | PW Consulting
By PW Consulting, 2026-07-09
Isobornyl Acrylate Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused preview of our new Isobornyl Acrylate market study — designed specifically to inform commercial, procurement, R&D, and M&A decisions in 2026. This briefing outlines the strategic value of the research, summarizes the operative insights contained in the full report, and highlights the competitive and structural dynamics that will determine winners and losers across the value chain. Per our “trailer” principle, the narrative below demonstrates analytical depth while intentionally omitting granular segment tables and proprietary figures — those are reserved for the full report.
Isobornyl Acrylate Market
Market trajectory at a glance
Isobornyl Acrylate (IBOA) has moved beyond niche specialty status to become a mid-sized, commercially significant monomer class. Between 2020 and 2025 the market expanded materially — from roughly USD 287 million to about USD 397 million — driven by accelerating adoption in UV/EB curing formulations, electronics encapsulants, and high-performance coatings. As of our base year (2025) the market momentum points into a multiyear growth phase: our modeled forecast projects the market to reach approximately USD 664 million by 2032, corresponding to a compound annual growth rate (CAGR) of 7.52% over the 2026–2032 horizon. The first actionable decision year — 2026 — therefore sits at an important inflection where short-term operational choices will determine strategic optionality for the remainder of the forecast.
Isobornyl Acrylate Market
Why this research matters for 2026 decisions
- Prioritize capital allocation with clarity: With mid-single-digit to high-single-digit CAGR and a clear pathway to near-doubling by 2032, investments in capacity, quality upgrades (high-purity grades), and downstream formulation support can generate differentiated returns. The report quantifies payback windows across alternative capex scenarios and provides sensitivity to raw-material price volatility.
- De-risk supply chains: The IBOA value chain sits downstream of acrylic acid and camphene feedstocks. Our analysis maps supplier concentration, feedstock exposure, and build versus buy trade-offs — enabling procurement teams to craft hedging, inventory, and dual-sourcing strategies for 2026 that preserve margin and continuity.
- Shape product strategy for sustainability demand: Regulatory and customer pressure is accelerating demand for lower-carbon and bio-derived monomers. We show how early adoption of bio-based variants and validated replacement pathways (including trade-offs in chemistry and cost) can open routes to premium pricing and preferred supplier status.
- Inform M&A and partnership bets: With a market that is moderately concentrated at the top, there is meaningful opportunity for scale-driven consolidation and bolt-on acquisitions. The report includes an M&A decision framework tailored to 2026 valuations and integration risks.
What the full report contains — practical, decision-ready assets
- Executive decision memo: concise action recommendations for CEOs, Heads of Supply Chain, and Head of R&D, clearly mapped to 6-, 12-, and 24-month time horizons.
- Market forecast model: interactive scenario outputs covering 2026–2032 with base, high-growth, and downside scenarios; sensitivities to feedstock cost, regulatory shifts, and substitution risks.
- Go-to-market playbooks: tailored templates for incumbent producers, new entrants, and downstream formulators — including pricing levers, quality positioning (high-purity vs. technical grades), and channel strategies.
- Supply-side diagnostics: supplier scorecards, capacity maps, and stress-test matrices for potential disruptions (feedstock shortages, regulatory changes, site outages).
- Competitive intelligence annex: comparative profiles and strategic positioning analysis of the leading suppliers, recent product launches, capacity investments, and likely next moves.
- Commercial tools: TCO calculators for sourcing decisions, sample contract clauses to protect against feedstock swings, and an integration checklist for acquisitions.
Competitive landscape — who matters and why
The market exhibits a moderate degree of top-end concentration, with the largest three suppliers accounting for nearly half of industry shipments and the top five capturing a substantial majority. That structure has three strategic implications: pricing power attached to specialty capabilities, room for regional players to defend niches, and transaction-driven consolidation possibilities.
Isobornyl Acrylate Market
- Evonik Industries (Essen, Germany) — Evonik’s VISIOMER® IBOA has been positioned as a high-performance monomer for emulsion and solution polymerization. Their recent capacity expansion in Europe (~18% increase in specialty acrylates in 2023) signals a readiness to serve higher-volume downstream partners and to defend premium segments where consistency and logistics matter.
- Sartomer (Arkema Group, USA) — A market leader in reactive diluents and UV-curable systems, Sartomer’s 2024 launch of a bio-based IBOA variant is a strategic hedge against regulatory and customer-driven sustainability demands. This move demonstrates how product-innovation can be both a risk mitigation and differentiation lever.
- IGM Resins (Belgium) — As a systems supplier integrating IBOA into UV-curing formulations, IGM’s advantage is verticalized know-how: selling a system rather than a monomer, which increases switching costs for customers and reduces price sensitivity.
- Japanese and Chinese producers (e.g., Osaka Organic, Mitsui Chemicals, Anhui Royal, Hubei Ipure) — These firms operate across a spectrum from high-purity specialty to industrial-scale supply. Their strategic playbooks differ: some compete on cost and scale for industrial downstreams, others on stringent quality certification for electronics and optics.
- Specialty distributors (e.g., Kowa American, Silver Fern Chemical, TCI) — Distribution and formulation support remain critical for market reach, especially in regions where manufacturers lack direct sales coverage. Distributors also provide valuable market feedback and speed-to-market for new variants.
Collectively, these players make for a market where technical differentiation (purity, regulatory compliance, low-odour, compatibility with photoinitiators) is as important as scale. Our competitive annex grades firms on technology, route-to-market, capacity flexibility, and sustainability roadmaps — allowing buyers and investors to prioritize shortlists for partnerships or M&A.
Key dynamics and risk vectors
- Feedstock exposure and cost volatility: IBOA synthesis relies on upstream petrochemical inputs (notably acrylic acid and camphene intermediates). Volatility in crude oil and refining intermediates therefore transmits directly into raw-material cost and margin pressure. Our stress scenarios model the impact of persistent high feedstock prices on supplier economics and downstream pass-through feasibility.
- Regulatory and sustainability drivers: Regulations limiting VOCs, or incentivizing bio-derived monomers, are reshaping formulation choices in coatings and adhesives. Sartomer’s bio-based IBOA launch exemplifies how regulatory pressure accelerates product innovation. The report maps potential regulatory timelines and compliance costs across major markets.
- Technology substitution and application evolution: Advances in photoinitiators, reactive diluents, and alternative acrylates could change demand composition among purity grades and application types. We model substitution elasticity and identify product features most resistant to displacement.
- Concentration and bargaining dynamics: With near half of the market in the hands of three firms and the top five controlling an even larger share, buyers that are overly dependent on a small set of suppliers face negotiation asymmetries. The report recommends contractual and operational tactics to restore balance.
How to use this research in 2026 — recommended next steps
- Procurement — Implement the supplier stress-test toolkit and renegotiate supply agreements with clearer pass-through clauses and defined escalation mechanisms for feedstock shocks.
- R&D and product teams — Prioritize piloting bio-based and hybrid formulations; use our compatibility matrices to shorten validation cycles for UV/EB curing customers.
- Corporate development — Use our M&A scorecards to evaluate targets that add either capacity, high-purity specialty chemistry, or route-to-market synergies; focus on targets that offer immediate cost synergies and near-term revenue uplift.
- Strategy and finance — Re-run the provided forecast model under your internal cost-of-capital assumptions to validate or adjust planned investment horizons and to stress-test ROI under alternative regulatory outcomes.
Final note — what you will find in the full report
The complete PW Consulting Isobornyl Acrylate market study provides the granular diagnostics and proprietary data tables that are essential for transaction diligence, procurement contracts, and technical product roadmaps. That includes the full regional and application split analyses, supplier-by-supplier market share details, detailed pricing curves, and all model inputs and sensitivities. We have deliberately kept those granular figures out of this preview to ensure your team engages with the full toolkit when making binding decisions.
For executives preparing 2026 budgets and strategic plans, this research converts market growth and structural dynamics into executable actions — from capex prioritization and supplier strategy to product innovation and deal-making. To access the full dataset, scenario model, and supplier dossiers, contact the PW Consulting Market Intelligence team or visit the report landing page for immediate download.
For detailed analysis of this topic, please visit the official page: Isobornyl Acrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Insulin API Market to Reach USD 344.8M by 2032 at 7.5% CAGR
By PW Consulting, 2026-07-09
Insulin API Market 2026: Strategic Imperatives for Corporates and Investors
As PW Consulting releases its latest Insulin API Market research, leaders across pharmaceuticals, biotech manufacturing, and strategic procurement face an inflection point. This briefing frames the report’s strategic value for decisions you must make in 2026 — from capacity investments and partnership models to regulatory playbooks and supply‑chain risk mitigation. We demonstrate the analytical depth that underpins our conclusions while preserving the granular tables and proprietary segment-level outputs that are available in the full report.
Insulin API Market
Why this study matters for 2026 planning
The insulin API market has moved from a stable, legacy segment to a dynamic arena shaped by biosimilar launches, large-scale incumbent investments, and changing geopolitics. Our base-year sizing (2025) and seven-year forecast highlight this evolution: the market has expanded from roughly USD 163.2 million in 2020 to about USD 215.0 million in 2025, and our model projects continued expansion to approximately USD 344.8 million by 2032 at a compound annual growth rate (CAGR) of 7.5% over the forecast horizon.
Insulin API Market
These topline figures matter because they change the calculus for capital allocation and commercial strategy. A mid-single-digit-to-high-single-digit CAGR in a regulated biologics input market invites different strategic moves than a stagnant market — namely, accelerating modernization of manufacturing, rethinking vertical integration, and reconfiguring global sourcing networks to balance cost, resilience, and regulatory pathway risk.
Insulin API Market
What the full report delivers (practical, actionable content)
- Independent market sizing and consensus scenario forecasts from 2020–2032, with sensitivity runs aligned to regulatory and geopolitical shocks.
- Supply-side intelligence: plant-by-plant capacity mapping, certification timelines, and realistic ramp curves for both recombinant human insulin and analogue APIs.
- Buyer playbooks: procurement strategies, contracting templates for API supply agreements, and price-pressure scenarios tied to biosimilar entry timing.
- Regulatory and quality checklists: stepwise requirements across major authorities, common audit findings, and remediation time/cost estimates for facility upgrades.
- Competitive intelligence: strategic profiles and capability matrices for the key API players, partner-fit assessments and counter-party risk scores.
- Investment guidance: CAPEX sizing heuristics for brownfield vs greenfield API projects, return-on-investment thresholds, and staged investment triggers.
- M&A and partnership diagnostics: value-creation levers for acquirers, integration risks, and term-sheet priorities when pursuing API targets.
Each module is designed so commercial, technical and finance leaders can translate insight into project plans, bid/no‑bid decisions, and board-ready investment cases.
Snapshot of competitive dynamics (how incumbents and challengers are shaping the market)
The competitive landscape is a blend of vertically integrated multinational producers and specialized API manufacturers that serve regional and branded biosimilar supply chains. Global leaders such as Novo Nordisk, Sanofi, and Eli Lilly maintain substantial in‑house API production capacity and leverage it for both finished-product security and strategic pricing/leverage. These incumbents are investing to protect their supply chains and to reinforce margins through integrated manufacturing footprints.
At the same time, major biosimilar-focused players — notably Biocon Biologics and selected Asian manufacturers — have been scaling capabilities, securing international approvals, and entering strategic partnerships to commercialize private‑label or public procurement offerings. Several mid‑tier API producers, including experienced GMP-certified firms in India and China, have expanded capacity and are increasingly competitive on cost, speed-to-market and localized certifications.
Strategic takeaways:
- Vertical integration remains a durable advantage for global formulators: control of API supply reduces interruption risk and supports premium product strategies where delivery and interchangeability are differentiators.
- Specialized API manufacturers can capture share by focusing on compliance stickiness (timely GMP approvals, regulatory dossiers) and regional supply contracts — particularly in public procurement and emerging‑market tenders.
- Partnerships are now more tactical: licensing arrangements, tolling agreements, and co‑manufacturing are tools to scale faster without incurring full greenfield CAPEX.
Recent industry events and what they imply
Several developments through 2025–2026 crystallize themes that will shape 2026 strategies:
- Large incumbents committing capital to manufacturing and R&D (e.g., a major multinational’s multi‑billion strategic investment) signals intensified competition for talent and local regulatory goodwill in high-value markets.
- Regulatory clearances and interchangeability approvals for biosimilar insulin APIs expand commercial optionality for biosimilar sponsors, accelerating price competition in mature markets while opening private‑label channels in the U.S.
- Geopolitical disruptions affecting cold‑chain hubs and re‑export pathways are real operational risks for insulin logistics, underscoring the need for diversified transit routes and localized buffer stocks.
- Partnerships between domestic manufacturers and international API suppliers demonstrate a trend toward onshore production for national health security imperatives.
For executives, the practical implication is clear: allocate resources to regulatory readiness and dual‑sourcing to protect supply while selectively investing in capabilities that create sustained differentiation (e.g., advanced formulations, integrated delivery systems).
Strategic framework for 2026 decision-making
We recommend a three‑layer framework to translate market dynamics into action.
- Horizon 1 — Protect: Operationalize resilience. Initiatives include contractual dual‑sourcing for critical APIs, inventory optimization for cold‑chain dependencies, and targeted quality audits. Prioritize short-term spend to mitigate supply interruptions.
- Horizon 2 — Adapt: Seize tactical commercial opportunities. Prepare dossiers for regulatory pathways in priority markets, form regional supply partnerships, and evaluate toll manufacturing to access capacity without full CAPEX exposure.
- Horizon 3 — Transform: Make confident, selective bets. Consider greenfield expansions where forecast demand and price dynamics justify long‑term CAPEX; evaluate M&A targets with clean compliance records and latent export capability; invest in formulation and delivery innovation that raises switching costs.
Each horizon is supported by specific decision triggers and KPIs in the full report — for example, time‑to‑approval thresholds, capacity utilization breakpoints, and acceptable counterparty risk scores for long-term contracts.
Scenario planning: anticipating 2026–2028 inflection points
We model three practical scenarios that should inform corporate contingency plans:
- Baseline: Continued steady growth consistent with the report’s central CAGR. Outcomes favor methodical capacity builds and negotiated long-term supply contracts.
- Acceleration: Faster biosimilar uptake and regulatory interchangeability approvals compress pricing and expand volumes; winners will be low-cost compliant manufacturers and firms with flexible production footprints.
- Disruption: Geopolitical shocks or major cold‑chain interruptions cause acute regional shortages. Rapid responses — local emergency production, emergency import waivers, and inventory reallocation — determine commercial continuity.
For each scenario, our full toolkit maps tactical playbooks, cost-to-implement estimates and timelines so leaders can pick responses aligned with risk appetite.
Practical next steps for executives and investors
- Procurement leads: Run a 30/60/90-day supplier stress test focusing on regulatory compliance, delivery lead times and logistics contingency plans.
- Manufacturing/operations: Benchmark capacity economics in the report’s CAPEX module to choose between brownfield upgrades and contract manufacturing partnerships.
- Commercial teams: Prioritize markets where interchangeability or regulatory clarity will unlock tenders; use the report’s go‑to‑market playbook to structure pricing and exclusivity clauses.
- Corporate development: Use our M&A risk matrix to screen acquisition targets and fast‑track diligence on regulatory liabilities and remediation cost estimates.
Why PW Consulting’s dataset is distinctive
Our analysis combines plant-level supply mapping, primary interviews with regulatory and procurement stakeholders, and a demand-side model calibrated to policy, epidemiology, and pricing trends. That synthesis produces not only a robust topline forecast — from the 2020 baseline through a 2025 calibration and an explicit 2026–2032 projection at a 7.5% CAGR — but also operationally focused insights that are immediately actionable.
To preserve the value of our proprietary modeling and to encourage consultative engagement, we present high-level strategic conclusions here while reserving the granular segmentation tables, contract-level price curves, and supplier scorecards for the full report downloadable from our website.
Closing: how to use this briefing in 2026
Use this briefing to align your executive agenda around three priorities: secure supply; accelerate regulatory readiness; and choose where to invest for competitive differentiation. The insulin API market is growing and remains strategically important to finished-product manufacturers, governments, and biosimilar innovators. Whether you lead procurement, manufacturing, commercial, or corporate development, the decisions you make in 2026 should be informed by the market growth trajectory, supplier capabilities, and the geopolitical and regulatory dynamics outlined here.
For the full dataset, market-by-market segmentation, supplier scorecards and downloadable decision templates, consult the PW Consulting Insulin API Market 2026 report on our website. The detailed intelligence will empower you to convert these strategic imperatives into concrete, measurable actions.
For detailed analysis of this topic, please visit the official page: Insulin API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hardening Machines Market to Reach USD 344.8M by 2032, 6.98% CAGR (2026–2032)
By PW Consulting, 2026-07-09
Hardening Machines Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s senior industry analyst presenting the Hardening Machines Market study, this briefing is designed as a strategic companion for executive teams planning capital allocation, supply-chain adjustments, product roadmaps, and M&A activity in 2026. We combine a multi‑year historical view (2020–2025) with a forward-looking forecast (2026–2032) to surface practical signals, vendor dynamics, and operational priorities — while reserving the full segment-level intelligence for the complete report.
Hardening Machines Market
Market snapshot: trajectory and scale
-
Base year and scope: The report uses 2025 as the base year and traces historical performance from 2020–2025, with a forecast window spanning 2026–2032.
Hardening Machines Market -
Absolute scale: The Hardening Machines Market recorded meaningful expansion over the historical window and stood at approximately USD 215.0 Million (revenue unit: Million) in 2025 according to our consolidated model.
Hardening Machines Market -
Growth outlook: The market is projected to grow at a compound annual growth rate (CAGR) of about 6.98% through the forecast period, driving the market to a mid‑to‑high‑hundreds million USD opportunity by 2032 under our central scenario.
-
Concentration: Competitive concentration is relatively low, with the top three and five players together accounting for single‑digit to low‑twenty percent ranges, reflecting a fragmented landscape that favors both specialized suppliers and regional champions.
Why the 2026 planning cycle matters
2026 will be a pivot year for organizations that depend on advanced hardening technologies — from automotive powertrain suppliers to precision component shops serving semiconductor and industrial OEMs. Several concurrent forces make this planning cycle distinct:
-
Capital intensity meets tightened energy economics. Buyers are re-evaluating CapEx payback horizons in light of rising energy scrutiny and decarbonization targets; energy-efficient induction systems are increasingly assessed not only for throughput and quality but as instruments of energy security and emissions reduction.
-
Standards and process assurance. Formal standards (for example, industry specs that govern induction hardening practices) are tightening qualification criteria for outsourced heat treatment and in‑house equipment procurement. Compliance risk now factors into supplier selection and capital approvals.
-
Modularization and automation. Vendors are accelerating modular and cell-based hardening architectures that integrate seamlessly with CNC machining and automated material handling — changing TCO and creating new retrofit opportunities.
-
Raw-material and input cost volatility. Steel feedstock and coil prices remain a direct input to the economics of component manufacture and, by extension, to demand for hardening services and equipment replacement cycles.
Strategic implications for enterprises
-
Investment timing: Locking in projects in 2026 should consider mid‑cycle availability of modular induction solutions that shorten installation and qualification time. For firms with aggressive decarbonization targets, prioritize units with clear energy-intensity and emissions reporting capabilities to accelerate regulatory and ESG approvals.
-
Technology choice: Induction hardening continues to displace older fuel‑based furnaces where cycle time, repeatability, and footprint matter. However, application-specific tradeoffs remain (penetration depth, part geometry, throughput), so product selection needs to be driven by a short list of in‑plant performance tests rather than vendor brochures alone.
-
Service and aftermarket as strategic lever: Given the fragmented vendor map, maintenance, sensorization, and digital service offerings are differentiators. Enterprises should procure with an eye toward lifecycle service contracts, remote diagnostics, and upgrade pathways that protect long-term productivity.
-
Supply-chain resilience: Component makers should hedge procurement by qualifying multiple vendors across geographies while ensuring compatibility of control systems and process recipes to avoid costly re‑qualification.
-
M&A and partnerships: Fragmentation creates opportunities for bolt‑on consolidation and strategic alliances — especially for companies seeking to combine induction expertise with automation and thermal-process controls.
Competitive landscape — profiles and positioning (select companies)
The vendor ecosystem is composed of specialized induction equipment suppliers, furnace manufacturers, machine-tool integrators, and turnkey system builders. Below are concise strategic profiles illustrating capability clusters and how incumbents are positioning themselves:
-
SECO/WARWICK (Poland) — Offers vacuum furnaces and induction technologies; positions around full-system heat treatment solutions for industrial customers seeking process integration. ( https://www.secowarwick.com)
-
Nabertherm (Germany) — Electric furnaces and heat-treatment platforms; appeals to customers needing standardised thermal-process equipment with proven reliability. ( https://www.nabertherm-furnaces.com)
-
EMA Indutec (Germany) — Focused on induction hardening for automotive and industrial components, emphasizing repeatability at scale. ( https://www.ema-indutec.de)
-
EMAG Machine Tools (Germany) — Integrates hardening into machine-tool platforms, targeting firms that need tight upstream-downstream process coupling. ( https://www.emag.com)
-
Aages SA (Switzerland) — Induction hardening specialists for precision applications. ( https://www.aages.com)
-
Interpower Induction (UK) — Known for induction heating systems tuned to hardening use cases. ( https://www.interpowerinduction.com)
-
Maschinenfabrik Alfing Kessler (Germany) — Offers grinding-plus-hardening systems—appeals to integrated finishing workflows. ( https://www.alfing-essler.de)
-
GH Induction Atmospheres (Spain) — Focus on flexible induction solutions across multiple part families. ( https://www.gh-ia.com)
-
EFD Induction (Norway) — Vertical hardening machine lines designed for high‑consistency production, including the HardLine series. ( https://www.enrx.com)
-
Inductotherm Group / Inductotherm (US) — Global presence in induction heating systems; strong in aftermarket and service networks. ( https://www.inductotherm.com)
-
Ajax Tocco Magnethermic (US) — Emphasizes energy-efficient induction solutions and custom hardening cells. ( https://www.ajaxtocco.com)
-
SMS Elotherm, eldec Induction, SAET EMMEDI, Electroheat Technologies, Canroon, ULTRAFLEX, Ambrell — These firms represent a mix of modular systems, high‑volume production equipment, and innovative induction power electronics; their product choices and geographic focus create pockets of competitive advantage.
Collectively, the landscape rewards vendors that combine deep process know‑how, local service capabilities, and modular automation. The relatively low CR3/CR5 concentration underscores both the opportunity for consolidation and the advantage of nimble niche players.
Recent signals and external drivers to monitor
-
Exhibitions and product launches: Market signals from industry trade shows remain reliable leading indicators of product trajectories — for example, recent demonstrations of high‑throughput induction lines and large‑part vertical hardening solutions at European and North American trade events.
- Regulatory and standards movement: Standards that formalize requirements for induction hardening processes are influencing OEM supplier qualification and should be monitored closely as they can extend supplier qualification timelines and affect procurement contracts.
- Raw-material and energy context: Input-cost dynamics — such as European hot‑rolled coil steel prices — and energy policies are materially relevant to end customers’ demand timing and to vendors’ cost-of-goods assumptions.
- Decarbonization and energy security: Industry initiatives toward lower CO2 footprints favor induction technologies over fossil‑fuel furnaces, creating an operational and procurement rationale to prioritize modern induction systems in 2026 investments.
What PW Consulting’s full report delivers (high‑level)
The complete study is operational in design and intended for corporate strategy, procurement, and engineering leaders. Key inclusions are:
- Validated market sizing and forward projections (2026–2032) with scenario analysis and sensitivity to energy and raw‑material price paths.
- Technology deep dives that decode induction vs. furnace tradeoffs, control architectures, and retrofit pathways.
- Vendor landscape with comparative capability matrices, total cost of ownership templates, and aftermarket/service scoring.
- Procurement playbooks and qualification checklists, plus CapEx/Opex modeling tools to align procurement decisions with ESG and payback constraints.
- M&A and partnership playbooks identifying consolidation targets, integration risks, and revenue‑synergy estimates.
- Practical case studies capturing implementation pitfalls and success factors across representative end‑markets.
To respect the “trailer” objective of this preview, we intentionally withhold the full segmentation tables, granular regional and application shares, and the transaction‑level vendor benchmarking data — all of which are available in the full research package on our web portal.
Action recommendations for 2026
-
Align procurement cycles with energy and standards roadmaps: Prioritize units that demonstrably lower energy intensity and support emissions reporting to ensure faster internal approvals.
-
Buy modularity: Where feasible, favor modular or cell‑based hardening solutions to reduce installation time and to retain flexibility for future capacity or process changes.
-
Lock service agreements early: Given the fragmented supply base, secure multi‑year service contracts and spare‑parts terms at the point of purchase to mitigate downtime risk.
-
Pursue partnership pilots: Manufacturers should run short, rigorously instrumented pilot programs with selected vendors to validate process recipes before full‑scale procurement.
For executives preparing 2026 capital plans and strategic roadmaps, this preview should help prioritize questions, scenarios, and procurement criteria. PW Consulting’s full Hardening Machines Market report contains the detailed segmental data, vendor scorecards, and executable templates that will convert these insights into procurement-ready decisions. Reach out via our research portal to access the complete dataset and customized advisory engagement options.
For detailed analysis of this topic, please visit the official page: Hardening Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cybersecurity Market Set for 13.8% CAGR, Strategic Insights Ahead
By PW Consulting, 2026-07-09
Cyber Security Market 2026: Strategic Imperatives for Enterprise Leadership
As organizations finalize their 2026 technology and security budgets, the Cyber Security market is no longer a defensive line-item — it is a strategic lever. PW Consulting’s latest market research, with a 2025 base year and a forecast horizon to 2032, documents a sustained, high-growth market driven by cloud transformation, AI adoption, regulatory pressure and a rising investment tide from public and private sectors. From an estimated market size of roughly USD 115 million in 2020, the sector expanded to approximately USD 219 million by 2025 and is forecast to surpass USD 540 million by 2032, growing at a compound annual growth rate of 13.8% over the forecast period. These headline dynamics frame a 2026 planning environment where choices about platform bets, talent investments, and procurement models will determine competitive position for the next decade.
Cyber Security Market
Why 2026 Is a Watershed Year
-
Policy acceleration: In early 2026, significant public sector moves — including the largest-ever Intelligence Community cybersecurity investment, a White House executive order establishing an AI cybersecurity clearinghouse, and multiple federal and state grant programs for schools, libraries and local governments — are reshaping funding flows and procurement priorities. These initiatives are unlocking near-term demand and creating new compliance baselines that enterprises must accommodate.
Cyber Security Market -
Technology inflection: AI-based detection and response, cloud-native access and Zero Trust architectures have shifted from experimental to mainstream. Vendors are rapidly integrating AI into detection, deception and automation layers, while buyers grapple with how to operationalize those capabilities safely and effectively.
Cyber Security Market -
Operational constraints: Chronic skill shortages, fragmented regulation, and limited visibility across IT/OT/IoT estates remain primary barriers to achieving cyber resilience. These constraints mean that capital alone will not buy security — the architecture and operational choices made in 2026 will be decisive.
Market Trajectory and Strategic Implications
The market’s historical trajectory and forward forecast illustrate two actionable realities for corporate leaders. First, growth is broad-based and accelerating: what was a mid-hundreds million marketplace in the early 2020s is entering an era of sustained expansion, driven by aggregated demand across enterprise IT modernization, cloud migration, supply-chain security and critical-infrastructure protection. Second, market concentration metrics indicate a balance between scale and specialization: a modest portion of demand is captured by leading global platforms, but nearly half the market remains accessible to focused specialists and regional players. Practically, this means enterprises will continue to see a dual landscape of large, integrated platform providers and best-of-breed specialists — and their procurement choices should reflect that mix.
Key Strategic Themes for 2026
-
AI-enabled defense, with human-in-the-loop governance: AI accelerates detection and automation but introduces new attack surfaces and governance complexity. For 2026, organizations should prioritize controlled pilots of AI-driven security functions, paired with clear model governance and incident-validation workflows.
-
Zero Trust as an operational program, not a project: Zero Trust investments must be sequenced against business-critical data flows and user populations. Adopt incremental, risk-prioritized implementations that produce measurable reduction in lateral-movement risk within 12–18 months.
-
Data resilience and ransomware preparedness: Backup and recovery — and the ability to validate data integrity quickly — have moved from insurance to strategic advantage. Investments in immutable storage, air-gapped verification, and tested recovery playbooks should be mandatory line items in 2026 CapEx planning.
-
Identity and privileged access as the new perimeter: Privileged Access Management and identity-centric controls are central to reducing attack surface. Prioritize identity risk quantification and integration of PAM into broader access governance.
-
Cloud-native security and developer-first tooling: As software supply chain attacks intensify, security needs to shift left — developer-integrated SCA, IaC scanning and runtime protections must be part of the CI/CD discipline.
-
Managed services and automation to overcome talent gaps: The industry-wide shortage of skilled cyber practitioners makes managed detection, response and co-managed models attractive. Combine managed services with automation to extend scarce senior analyst capacity.
Competitive Dynamics: How Leaders and Challengers Are Positioning
The competitive landscape is characterized by a mix of platform consolidation, targeted specialization, and rapid product evolution. Leading vendors have followed complementary strategies: some are integrating broad stacks to offer unified SASE, cloud and endpoint coverage; others double down on identity, data resilience or developer-first security.
-
Palo Alto Networks and Fortinet continue to emphasize platform integration, bundling network security, cloud controls and enforcement planes into cohesive stacks intended for enterprises seeking consolidation.
-
CrowdStrike and similar endpoint-native players position AI-driven prevention and detection as core differentiators for stopping modern attacks at initial entry points.
-
Zscaler and Cloudflare are illustrating the cloud-native path to secure access, endorsing a Zero Trust exchange model that minimizes on-premise appliances.
-
CyberArk emphasizes privileged access and identity controls, a category that remains essential for protecting critical systems and meeting stringent compliance mandates.
-
Specialists like Snyk and Rubrik target developer and data resilience vectors respectively — illustrating the continued role of best-of-breed tools within enterprise stacks.
-
Defense and systems integrators are also active; companies with national-security pedigrees are focusing on critical-infrastructure and government workflows where regulatory and assurance requirements drive vendor selection.
Market concentration indicators show that while the largest three firms capture a meaningful share of demand, the top five do not dominate the market to the exclusion of specialists. This distribution creates opportunities for targeted consolidation, alliance strategies, and differentiated product plays.
What the PW Consulting Report Delivers (Practical, Not Theoretical)
Our research translates market observation into operational decision tools for 2026 planning. The full report includes:
- An executive playbook that maps risks to prioritized investment levers over 12–36 months.
- Vendor scorecards and positioning matrices that evaluate platform fit by enterprise archetype.
- A procurement and integration checklist for composable security stacks, with recommended SLA and telemetry minimums.
- CapEx vs Opex modelling templates tailored to cloud-first, hybrid and regulated-industry scenarios.
- M&A and partnership heat maps identifying attractive targets by capability and commercial fit.
- Scenario analyses that quantify exposure under common adversary playbooks and regulatory shock events.
- Regulatory alignment guidance that synthesizes multiple federal and state requirements into practical control priorities for compliance teams.
Note: This article intentionally summarizes themes and outcomes. Core segment-level tables, regional and application splits, and vendor revenue shares are omitted here to encourage direct access to the primary research package where those granular data and model files can be downloaded.
How to Use This Research for 2026 Decision-Making
-
Translate growth expectations into capability roadmaps: Use the market growth trajectory to justify investments in automation, testing and recovery capabilities that will scale with your organization’s footprint over the next three budget cycles.
-
Prioritize outcomes over products: Define measurable resilience outcomes (e.g., mean time to detect/respond, recovery time objectives for critical datasets) and use them to score procurement options rather than feature checklists.
-
Leverage public funding windows: Align grant and procurement teams with program timelines emerging from federal and state announcements in 2026; these windows can subsidize modernization for education, local government and critical infrastructure operators.
-
Adopt hybrid delivery models: Combine managed services with internal rotations and automation to address the workforce shortage while retaining strategic oversight of key controls.
-
Build secure-by-design developer practices: Integrate SCA, IaC scanning and runtime protection into CI/CD pipelines as non-negotiable gates to production deployment.
Closing: What Leaders Must Decide Now
2026 presents both opportunity and obligation: public investment and regulatory attention will create demand and compliance complexity in equal measure. The market’s robust growth, underpinned by a mid-teens CAGR and rising public-sector spend, rewards decisive architecture and operating-model choices. Leaders who treat cybersecurity as an enterprise-level strategic program — aligning investment, talent and procurement to measurable resilience outcomes — will convert today’s defensive spend into tomorrow’s business enabler.
PW Consulting’s full Cyber Security Market report provides the granular data, vendor benchmarking, and executable templates necessary to operationalize these insights. This briefing outlines the strategic contours; the report contains the calibrated inputs and segment intelligence you will need to finalize your 2026 security roadmap.
For detailed analysis of this topic, please visit the official page: Cyber Security Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Health Products Market to Reach USD 7,153M by 2032, Growing at 6.8% CAGR
By PW Consulting, 2026-07-09
Health Products Market 2026: Strategic Outlook and Why This Report Is Mission-Critical for Executive Decision-Making
As PW Consulting’s Chief Industry Analyst, I present a focused briefing on the Health Products Market that synthesizes our quantitative modeling, primary research, and executable strategic guidance. The market we track — spanning consumer health formulations, personal care devices, wound care innovations and complementary medical products — has demonstrated steady expansion through 2020–2025 and is positioned for sustained growth across 2026–2032. Specifically, our base-year assessment pegs the global market at approximately USD 4,541 million in 2025, and our forecast model projects growth to about USD 7,153 million by 2032 at a compound annual growth rate (CAGR) of 6.8%.
Health Products Market
Why this report matters for 2026 strategic planning
-
Timing for investment and clinical development: 2026 is a transition year for regulatory strategy and capital allocation. With regulators signaling streamlined evidence pathways and an evolving reimbursement environment, companies must re-sequence clinical and commercial investments to capture accelerated routes to market while preserving payer access.
Health Products Market -
Portfolio prioritization under constrained budgets: The market’s mid-single-digit CAGR means incumbents and new entrants will compete for share growth through product differentiation, supply resilience, and channel optimization rather than pure market expansion. Our study translates market momentum into explicit investment levers — where to double down and where to de-risk.
Health Products Market -
M&A and partnership prioritization: Moderate market concentration (our concentration analysis shows that the top-three and top-five players together command a meaningful but not monopolistic share) creates opportunities for bolt-on acquisitions, specialty carve-outs, and strategic alliances. The report maps realistic acquisition corridors by capability, geography, and regulatory maturity.
What the report delivers — practical, transaction-ready intelligence
This is not a high-level brochure. The deliverable is built for corporate strategists, business development teams, and investment committees that need to execute in 2026. Highlights include:
-
Top-down market sizing and bottom-up forecast models spanning 2020–2032, with sensitivity cases reflecting alternative adoption curves and regulatory scenarios.
-
A validated competitive framework that benchmarks product portfolios, clinical status, manufacturing footprint, and go-to-market channels for the leading and emergent players.
-
Go-to-market playbooks for three archetypal entrants — incumbent CPG-extension, clinical-device innovator, and digitally enabled direct-to-consumer brand — including revenue ramp profiles and channel economics.
-
Transaction support materials: valuation multiples, precedent transactions, and an M&A scorecard that aligns target selection with integration risk and near-term revenue synergies.
-
Regulatory and reimbursement roadmaps that translate evolving policy drivers into milestone-based decision trees for clinical development, approvals, and coverage negotiations.
-
Supply chain stress-test scenarios that quantify cost, time-to-market, and margin impact from tariffs, supplier disruption, and reshoring initiatives.
-
A prioritized 18-month action plan for commercial teams and R&D leadership that converts market opportunity into KPI-linked initiatives and budget allocations.
How to use these findings in 2026 corporate decisions
-
Align clinical development to regulatory inflection points. The FDA’s movement toward allowing a single, rigorous pivotal study for many innovative health products shortens timelines but increases the importance of study design. Our report provides trial design guardrails that optimize statistical power while minimizing time and cash burn.
-
Reconfigure go-to-market cadence to capture early-adopter channels. With the market growing steadily, differentiated products win by converting premium early adopters and specialist channels before broader commercialization; the report identifies which channels offer the fastest payback for each product archetype.
-
Incorporate payer-impact scenarios into launch economics. Recent national-level agreements and Medicaid pricing dynamics are changing formulary and reimbursement negotiations. We translate these macro moves into concrete pricing and contracting strategies for 2026.
-
Hedge supply-chain and cost exposure proactively. Tariff escalations on certain imports have tangible effects on device components and packaging; our scenario modeling quantifies margin exposure and suggests low-cost, high-impact mitigation tactics, including dual-sourcing and near-shoring prioritization.
-
Prioritize M&A targets with integration playbooks. Given the market’s structure and concentration dynamics, targeted acquisitions can accelerate capability buildouts — our M&A templates rank targets by dilution risk, revenue accretion timing, and logistical complexity.
Competitive landscape — what to watch and what it implies
The competitive map is nuanced: established healthcare players, specialized device makers, and nimble personal health brands co-exist and compete on adjacent vectors — clinical evidence, supply chain reliability, regulatory agility, and channel relationships.
-
United Health Products, Inc. (United States): Focused on a novel hemostatic gauze product currently navigating a complex regulatory pathway. Recent regulatory developments — including a warning letter and an IDE decline in 2025 — highlighted compliance risk and study-design gaps, but a subsequent collaborative approval for a clinical program in 2026 signals a path forward. For competitors and investors, United Health’s trajectory is a reminder that clinical and regulatory execution materially changes commercial timing and valuation.
-
Solventum Corporation (United States): Positioned with personal health care and wound-care device offerings, Solventum exemplifies firms that bridge consumer and clinical markets. Their product set and channel approach illustrate how clinical credibility and consumer branding can be combined to capture higher-margin segments.
-
Bausch Health Companies Inc. (Canada): A diversified incumbent with pharmaceuticals, devices, and consumer health products. Its scale and portfolio breadth provide resilience but impose different strategic trade-offs compared with focused innovators. For smaller firms, Bausch is an archetypal strategic acquirer and distribution partner.
Our competitive benchmarking in the full report provides deeper profiles (capabilities heatmaps, regulatory maturity scores, IP posture) and a near-term horizon scan of likely strategic moves by these and other players.
Regulatory, supply chain and reimbursement forces shaping outcomes
-
Regulatory evolution: Agencies are experimenting with shorter evidence pathways that emphasize robust single pivotal studies for many devices and innovative health products. This reduces time-to-market but raises the stakes for trial design and post-market surveillance. Companies that align development plans to these expectations will shorten time to revenue and reduce capital risk.
-
Supply chain friction: Tariff actions and component bottlenecks are increasing variable costs and elongating lead times for certain device components. Our modeling quantifies the profit sensitivity to these inputs and provides a prioritized set of mitigation options that can be implemented within 6–12 months.
-
Reimbursement pressure and opportunity: High-level national payer negotiations and policy shifts are compressing prices in some channels while opening new contracting opportunities in others. The practical implication: launch plans must include early payer engagement and flexible contracting prototypes to protect ASPs and market access.
What we intentionally withhold — and why
In line with the “trailer” principle of this briefing, we demonstrate analytical rigor and strategic insight while deliberately withholding tabulated subsegment numbers, granular regional share tables, and proprietary unit economics that are included only in the full report. Those datasets — which combine primary interviews, invoice-level trade data, and PW’s proprietary market model — are required to run bespoke scenario analyses and to validate transaction assumptions. Access to the full dataset and downloadable models is available through our report portal.
Next steps and recommended executive actions for 2026
-
Initiate a 90-day clinical-regulatory sprint to stress-test trial designs against the single-study pathway and define go/no-go milestones tied to investor and board approvals.
-
Run a tariff and supplier concentration audit to identify components representing >X% (confidential benchmarking available in the report) of BOM risk, and implement dual-sourcing or near-shore pilots for the top two risk nodes.
-
Engage PW Consulting for a tailored M&A target short-list and integration roadmaps if inorganic growth is under consideration; our live models will convert valuation assumptions into accretion/dilution scenarios.
-
Adopt an early-payer engagement protocol for any product with clinical claims beyond general wellness; we provide contracting templates and KPI-driven pilots in the full report.
Final thought
The Health Products Market in 2026 is neither a wide-open frontier nor a mature, slow-growth sector. It is a selectively expanding ecosystem where regulatory inflection, supply-chain reconfiguration, and payer dynamics will determine winners. Our study equips leadership teams with the forecasts, scenario tools, and tactical playbooks needed to make high-conviction decisions this year. For the granular segmentation data, downloadable financial models, and company-level benchmarking that underpin these conclusions, please consult the full PW Consulting Health Products Market report.
For detailed analysis of this topic, please visit the official page: Health Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


