



Category: market research
Worldwide Toluic Acid Market: Asia Pacific $117.79B Leads 4.19% CAGR Shift
By PW Consulting, 2026-09-18
Navigating the Worldwide Toluic Acid Market: Strategic Trends and Commercial Opportunities Through 2032
Global Market Trajectory and Core Challenges
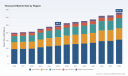
The worldwide toluic acid market has demonstrated steady, measured expansion over the past half-decade, evolving from a niche aromatic intermediate segment into a strategically positioned value chain within specialty chemicals. Starting from approximately USD 201.2 million in 2020, the market has grown to reach USD 248.5 million in 2025, reflecting an incremental yet resilient trajectory. Forward projections indicate continued upward momentum, with the market anticipated to surpass USD 263 million by 2026 and approach USD 331 million by 2032. This expansion translates to a compound annual growth rate of 4.19 percent across the forecast horizon, a figure that underscores moderate but dependable growth rather than speculative volatility. For executives and investors evaluating cyclic commodity exposure versus specialty chemical positioning, this trajectory signals a market characterized by steady demand absorption, moderate pricing power, and relatively predictable capacity utilization patterns.
Such growth characteristics are neither explosive nor stagnant; they reflect an industry operating in a mature but structurally evolving phase. The expansion is underpinned by sustained utilization in downstream manufacturing ecosystems, where toluic acid functions as a critical building block rather than a terminal consumer product. This intermediate positioning means that demand elasticity is closely tied to capital expenditure cycles, formulation shifts, and regulatory timelines in end-use sectors. While the aggregate revenue trajectory appears linear, the underlying dynamics are increasingly shaped by geographic redistribution of production capacity, isomer-specific demand divergence, and shifting cost传递 mechanisms from upstream petrochemical streams.
Three structural challenges currently define the market's inflection point. First, feedstock sensitivity remains a persistent volatility driver. Toluene, the primary oxidation feedstock for toluic acid synthesis, has experienced pronounced regional price fluctuations, with Northeast Asian benchmarks climbing toward USD 1,058 per metric ton FOB in early 2026 and broader global pricing averaging around USD 1.08 per kilogram in the same period. These movements reflect tightening supply conditions and crude-linked cost pressures that compress margins for producers operating without long-term feedstock alignment or integrated supply agreements. Second, regulatory complexity continues to reshape compliance frameworks across major trading jurisdictions. Aromatic monocarboxylic acid derivatives, including toluic acid isomers, navigate evolving chemical safety inventories, substance registration requirements, and tariff classifications that differ significantly between North American, European, and Asian customs regimes. These regulatory layers introduce administrative overhead, testing requirements, and documentation burdens that disproportionately affect mid-tier producers and emerging market exporters. Third, the industry faces a structural transition in capacity geography and competitive positioning. Production concentration has remained relatively fragmented, with no single entity commanding dominant market share, yet capital deployment patterns suggest a gradual shift toward integrated regional hubs that prioritize pharmaceutical-grade intermediate output and specialized purity standards. This dynamic creates both entry barriers for commoditized players and differentiation pathways for manufacturers that can secure certification, quality consistency, and supply reliability at scale.
Critical Drivers Shaping Market Dynamics
The expansion trajectory of the toluic acid market is not the result of isolated demand spikes but rather the convergence of technological, regulatory, demand-side, and supply chain forces that collectively redefine competitive benchmarks. Understanding these drivers provides decision-makers with a clearer view of where margin opportunities, capacity allocation decisions, and partnership strategies will yield the most durable returns.
Muconic Acid Market
Technological innovation in oxidation catalysis and process intensification has emerged as a primary efficiency driver. Traditional toluene oxidation pathways have historically balanced yield optimization against byproduct management, particularly acid recovery and isomer separation. Recent process refinements have focused on catalyst selectivity improvements, temperature control precision, and downstream purification sequences that reduce energy intensity while maintaining high-purity output standards. These advancements are particularly relevant for producers targeting pharmaceutical and fine chemical intermediate markets, where purity thresholds and batch consistency directly influence customer qualification timelines. Companies that invest in continuous processing upgrades, advanced monitoring systems, and closed-loop solvent recovery are better positioned to absorb feedstock cost fluctuations while preserving gross margin stability. The technology dimension also intersects with product differentiation, as enhanced purification capabilities enable producers to serve analytical, laboratory, and specialty-grade segments that command premium pricing relative to bulk industrial grades.
Regulatory and policy environments continue to exert structural influence across multiple dimensions. In the United States, toluic acid isomers are classified under specific harmonized tariff subheadings that shape import logistics, customs clearance timelines, and trade compliance workflows. In parallel, environmental and chemical safety frameworks in Europe require manufacturers and downstream users to adhere to substance registration protocols, safety data documentation, and workplace exposure guidelines. These regulatory layers are not uniformly restrictive; rather, they create compliance asymmetry that rewards organizations with established quality management systems, audit-ready documentation, and proactive regulatory monitoring. For market participants, the operational implication is clear: regulatory readiness has transitioned from a baseline requirement to a competitive differentiator. Firms that integrate compliance infrastructure into their production and export workflows reduce lead-time variability, minimize shipment friction, and strengthen buyer confidence in long-term supply agreements.
Demand-side behavior is undergoing a measurable shift driven by formulation requirements and intermediate utilization patterns. Agrochemical and pharmaceutical intermediate applications represent two of the most significant demand anchors in the market, each with distinct procurement cycles, purity specifications, and qualification processes. Pharmaceutical-grade intermediate consumption is particularly sensitive to manufacturing scale-up decisions, active pharmaceutical ingredient pipeline progression, and contract manufacturing organization sourcing strategies. As drug development and generic formulation activity expand in select regions, demand for consistent, high-purity toluic acid intermediates has become more structured and less susceptible to spot-market volatility. Meanwhile, specialty chemical applications, including pigment and dye synthesis as well as polymer initiator utilization, contribute steady baseline demand while offering flexibility for grade-specific sourcing. The broader implication for procurement and production strategy is that demand is increasingly segmented by quality tier, with premium applications incentivizing supply reliability and traceability over lowest-cost acquisition.
Supply chain restructuring and cost structure evolution represent the fourth critical driver. Regional feedstock pricing divergence has intensified as crude-linked cost movements, transportation constraints, and local supply-demand imbalances create uneven input cost environments. Producers operating in feedstock-advantaged locations or securing fixed-price supply arrangements are gaining relative cost competitiveness, while others are forced to pass through price adjustments or accept margin compression. This dynamic is accelerating a broader reevaluation of sourcing geography, inventory positioning, and long-term contract structures. Buyers are increasingly prioritizing multi-source qualification, regional buffer inventory, and supplier performance metrics that extend beyond price to include delivery reliability, batch consistency, and technical support capability. Simultaneously, capacity expansion decisions are being evaluated against not only capital expenditure but also logistics accessibility, export market proximity, and alignment with downstream customer clusters. A notable example of this strategic realignment occurred in early 2025, when Hanwha Chemical acquired a regional toluic acid production facility to expand capacity and strengthen its supply chain for pharmaceutical-grade intermediates, signaling that inorganic capacity deployment is being used to secure grade-specific output and supply chain resilience rather than merely increase volume.
Competitive Landscape and Strategic Positioning
The competitive architecture of the toluic acid market reflects a diverse participant base spanning regional manufacturers, export-oriented producers, and global specialty chemical suppliers. Market concentration remains moderate, with the top three participants collectively representing just over thirty percent of total revenue and the top five accounting for less than half of overall market value. This fragmentation indicates that no single entity currently exerts overwhelming pricing influence, while simultaneous underscoring that competitive advantage is derived from operational execution, grade specialization, and supply reliability rather than scale alone. The landscape is shaped by producers operating across China, India, Europe, and Japan, each pursuing distinct positioning strategies aligned with regional feedstock conditions, certification portfolios, and end-market focus.
Chinese manufacturers have established a prominent presence in the market by emphasizing production scale, isomer breadth, and cost-efficient intermediate output. Companies such as Evergreensino Chemical and Hefei TNJ Chemical Industry operate with a focus on p-toluic acid, o-toluic acid, and m-toluic acid, catering to industrial and pharmaceutical intermediate applications with an emphasis on bulk availability and consistent purity levels. Their strategic positioning typically leverages regional feedstock access, established export channels, and the ability to supply multiple isomer grades from centralized or coordinated production sites. For downstream buyers, this translates into accessible supply options and competitive pricing, though qualification and quality assurance processes remain essential when sourcing for regulated or high-specification applications.
PW Consulting
Indian producers have carved a differentiated position by emphasizing pharmaceutical and specialty chemical alignment, often supported by GMP frameworks, export-oriented quality controls, and multi-location manufacturing footprints. Kaival Chemicals, Muby Chemicals, Ottokemi, and Triveni Chemicals illustrate this approach, with product portfolios spanning para toluic acid, o-toluic acid, and m-toluic acid across purity grades suited for pharmaceutical, fragrance, laboratory, and industrial applications. Their competitive edge frequently derives from the combination of certification readiness, flexible batch sizing, and the ability to serve both bulk and precision-grade requirements. This positioning resonates with buyers who require validated quality documentation, reliable lead times, and the option to scale volumes as downstream production schedules evolve. The Indian segment's growth within the global market reflects broader trends in specialty chemical manufacturing, where regulatory compliance, export logistics, and technical grade differentiation increasingly determine supplier selection.
Global specialty suppliers, including Merck KGaA through its Sigma-Aldrich portfolio and Tokyo Chemical Industry, occupy a distinct niche focused on high-purity grades, analytical applications, and research-grade supply chains. Their strategic value lies in consistency, documentation rigor, and the ability to serve customers with stringent specification requirements. While these suppliers typically operate at lower volume scales relative to industrial manufacturers, they command pricing premiums and maintain strong customer retention in segments where specification fidelity and supply traceability outweigh cost sensitivity. Their presence in the market reinforces the multi-tier nature of toluic acid demand, where bulk industrial consumption and high-purity specialty usage coexist but follow different procurement logic.
The competitive landscape is evolving along several observable trends. Consolidation activity is emerging selectively, as demonstrated by inorganic capacity acquisitions that target pharmaceutical-grade intermediate supply chain strengthening. Such moves suggest that companies are prioritizing grade-specific capability expansion and regional supply security rather than pursuing undifferentiated volume aggregation. At the same time, market fragmentation persists, allowing nimble regional producers to compete on responsiveness, technical support, and customized grade offerings. New entrants and expanding producers face a higher bar for differentiation, as buyers increasingly evaluate suppliers on quality consistency, compliance readiness, and supply continuity rather than price alone. The resulting environment favors participants that can align production capabilities with clearly defined end-market requirements, maintain transparent documentation practices, and build supplier relationships that extend beyond transactional exchanges.
Forward Outlook: Strategic Trends for the Next Three to Five Years
Looking ahead, the toluic acid market is likely to be shaped by three interrelated trends that will influence sourcing strategies, capacity planning, and competitive differentiation. The first trend is the continued bifurcation of demand by quality tier. As pharmaceutical and specialty chemical applications expand their share of total utilization, procurement behavior will increasingly separate bulk industrial purchases from precision-grade requirements. This divergence will reward producers capable of maintaining dual-track capabilities, where standard industrial grades coexist with validated high-purity output and robust quality documentation. Buyers in regulated segments will place greater value on qualification speed, batch-to-batch consistency, and traceability, while price-sensitive industrial consumers will continue to optimize around feedstock-linked cost movements and regional availability.
The second trend is the ongoing realignment of supply chain geography around cost stability and regulatory alignment. Feedstock pricing volatility, coupled with transport and trade compliance complexity, will encourage longer-term contract structures, regional inventory buffering, and selective nearshoring or friend-shoring of intermediate supply. Capacity investments are likely to remain selective, with capital directed toward facilities that can serve specific grade profiles and downstream customer clusters rather than pursuing generalized volume expansion. This realignment will create opportunities for suppliers that can demonstrate predictable delivery performance and flexible volume scaling, particularly in markets where buyers are reducing single-source dependency.
The third trend involves incremental regulatory and compliance maturation as a competitive filter rather than a barrier. As chemical safety documentation, customs classification accuracy, and substance registration requirements become more embedded in procurement workflows, suppliers with established compliance infrastructure will experience fewer friction points and faster qualification cycles. Organizations that treat regulatory readiness as a strategic capability—integrated into production planning, export documentation, and customer communication—will be better positioned to sustain relationships in regulated downstream markets. The primary risk accompanying these trends is feedstock cost unpredictability, which can disrupt margin assumptions and alter relative competitiveness if not managed through contract design, inventory strategy, or process efficiency improvements. A secondary risk lies in qualification and documentation gaps that can delay supplier adoption, particularly for buyers operating under stringent quality and traceability expectations.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority should be aligning capacity and process investments with grade-specific demand rather than pursuing undifferentiated volume growth. Building capability across multiple purity tiers, strengthening quality documentation systems, and securing feedstock supply arrangements that reduce exposure to spot-market volatility will improve margin resilience and customer retention. Producers that can demonstrate consistent batch performance, transparent compliance practices, and responsive technical support will be better positioned to expand share in pharmaceutical and specialty chemical segments where qualification and reliability carry disproportionate weight.
Malonic Acid Market
For investors evaluating exposure to the toluic acid value chain, the most durable opportunities lie in participants with clear grade differentiation, disciplined capacity deployment, and supply chain positioning that aligns with downstream regulatory and quality requirements. Capital allocation should favor operational models that integrate feedstock risk management, compliance infrastructure, and customer qualification support rather than relying solely on scale-driven cost advantages. Monitoring regional feedstock pricing trends, capacity acquisition activity, and regulatory developments will provide early signals of competitive repositioning and margin trajectory shifts.
For procurement and sourcing leaders, the most effective strategy involves multi-source qualification, grade-specific supplier mapping, and contract structures that balance price competitiveness with delivery reliability and specification consistency. Evaluating suppliers on documentation readiness, batch traceability, and technical responsiveness will reduce qualification friction and improve supply continuity. Building buffer inventory strategies and maintaining alternative sourcing pathways will also help mitigate feedstock-linked price volatility and logistics disruption. For organizations seeking detailed segment data, regional supply analysis, and customized sourcing or investment scenarios, comprehensive market research provides the granular intelligence needed to translate these strategic directions into executable plans.
For detailed analysis of this topic, please visit the official page: Worldwide Toluicacid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Bread Production Line Market: How the 5.4% CAGR Signals a Quiet Shift
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Bread Production Line Market
Market Overview: State of Play and Core Pressures
A Resilient Market at an Inflection Point
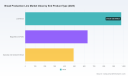
The global bread production line market has demonstrated steady expansion over the past five years, with total revenue climbing from approximately $1.6 billion in 2020 to an estimated $2.1 billion in 2025. The trajectory reflects a compound annual growth rate of 5.4 percent across the historical period, and forward projections suggest the market will surpass $3 billion by 2032. This growth is not merely a function of population increase; it is being driven by capacity upgrades, automation adoption, and shifting production economics across both mature and emerging markets. While the overall market remains broadly distributed among equipment manufacturers, regional food processors, and system integrators, concentration metrics indicate that the top three players command roughly 31 percent of revenue, with the top five capturing closer to 43 percent. This moderate concentration leaves meaningful room for specialized entrants and regional champions, but it also signals that scale, service networks, and technological differentiation are increasingly decisive in securing long-term contracts.
Despite the positive growth outlook, the industry is navigating a set of structural pressures that will define investment decisions over the next several years. The first is the tension between automation ambition and capital efficiency. Fully automatic production lines now account for the majority of equipment value, yet many mid-sized bakeries face constrained capex environments and uncertain demand forecasts. Upgrading to high-throughput, fully automated systems can improve consistency, reduce labor exposure, and increase throughput, but the payback period becomes longer when raw material volatility and energy costs erode margin assumptions. The second challenge is the widening gap between high-volume commodity bread production and the premium, texture-sensitive segment that includes artisan-style, specialty, and sandwich formats. Lines that excel at pan bread throughput may struggle to accommodate highly hydrated doughs or delicate shaping requirements without significant retooling, creating a strategic fork in product portfolio planning. The third challenge is geographic unevenness. Demand growth is not uniform across regions, and the economic case for new capacity depends heavily on local consumption patterns, import substitution dynamics, and the cost of building or retrofitting facilities. Producers expanding into newer markets must contend with differences in labor availability, utility infrastructure, and regulatory expectations around food safety and traceability.
Bakery Machine Market
Why This Moment Matters for Decision Makers
For executives planning capacity investments or evaluating supplier partnerships, the current environment is less about whether the market is growing and more about where value is being created and captured. The operators who will outperform are likely to be those who treat production lines not as static asset purchases but as configurable platforms that can adapt to product mix changes, labor constraints, and input cost variability. The broader trajectory favors automation and standardization, but the commercial winners will be those who align line flexibility with the realities of regional demand, raw material sourcing, and service responsiveness. Understanding these pressures is essential because they influence everything from equipment configuration choices to negotiation leverage with manufacturers and the timing of phased rollouts.
Key Drivers Shaping Market Momentum
Technology Innovation and Line Configurability
Technological progress remains the most visible driver of market evolution, particularly in the integration of dough handling, proofing, forming, and baking into coordinated systems that can be tuned for different product types. Leading manufacturers are increasingly differentiating on precision and adaptability rather than throughput alone. High-precision forming and dough processing equipment reduces waste and improves repeatability, while advanced proofing and tunnel oven systems support more consistent crumb structure and crust development across larger batches. For industrial bakeries, this matters because product consistency is no longer a secondary concern; it is tied directly to brand trust, retail slotting, and the ability to standardize across multiple plants. At the same time, equipment is becoming more configurable, allowing producers to switch between loaf bread, rolls, baguettes, and specialty formats with fewer changeover losses. This flexibility is especially valuable for bakeries that must serve both retail and food service channels or that are expanding across categories without building separate lines for each product type.
Policy, Regulatory, and Food Safety Dynamics
Regulatory expectations continue to influence equipment design and plant architecture. Food safety standards, traceability requirements, and hygiene protocols are pushing manufacturers toward equipment that is easier to clean, inspect, and validate. In many markets, this translates into more enclosed dough handling, improved surface materials, and control systems that log operating parameters for audit readiness. The regulatory environment also interacts with energy and sustainability policies. As utilities and local authorities tighten scrutiny on emissions, heat recovery, and energy intensity, production lines that incorporate more efficient baking systems or better thermal management gain a compliance and cost advantage. Producers evaluating new lines are increasingly weighing not only processing speed but also whether the equipment will support long-term regulatory alignment and reduce the risk of future retrofits. This is particularly relevant in regions where food manufacturing modernization programs are reshaping incentive structures and where larger customers expect suppliers to meet higher operational standards.
Demand-Side Shifts in Bread Consumption and Channel Mix
Consumer and customer behavior is reshaping the product profile that production lines must support. Bread consumption patterns are diversifying, with stronger interest in specialty formats, sandwich-ready products, and region-specific styles that demand more nuanced processing. At the same time, retail and food service buyers are asking for consistent availability, tighter specification control, and greater flexibility in pack sizes and formats. This combination favors lines that can produce multiple end-product types with controlled variation rather than lines optimized for a single high-volume output. Commercial bakeries are also responding to the need for faster responsiveness, especially where demand is fragmented across local preferences or where private-label growth is intensifying specification requirements. In effect, the demand side is rewarding producers who can maintain scale without sacrificing format diversity. That creates a strategic premium for production lines that balance automation with product versatility, especially in markets where bread is both a staple and a format-driven category.
Supply Chain Pressure and Input Cost Volatility
Raw material economics are a persistent source of uncertainty, and recent wheat price movements have underscored the sensitivity of bread production to upstream costs. With wheat prices rising sharply year over year in early 2026 and farm-level price forecasts signaling continued pressure, bakeries and equipment buyers are factoring input volatility more heavily into capacity planning. This environment encourages investment in lines that reduce dough waste, improve yield consistency, and allow better control over formulation changes. It also increases the importance of supplier relationships that can support faster reconfiguration when recipes or ingredient availability shift. For equipment purchasers, the cost backdrop makes it less attractive to over-specify for a single product niche if that choice limits future adaptability. Instead, there is greater interest in systems that can preserve throughput while accommodating changes in dough moisture, ingredient mix, or product dimensions. In a volatile cost environment, flexibility is not just a product feature; it is a margin management tool.
Competitive Landscape and Leading Strategies
How the Incumbents Are Positioning
The competitive field includes established European and North American system builders, precision-focused Asian manufacturers, and a growing set of specialists serving flatbread and regional product categories. AMF Bakery Systems stands out for its emphasis on complete system solutions for high-volume industrial bakeries, positioning itself as a partner for producers that need integrated lines rather than isolated unit equipment. Rademaker has built a strong reputation across the medium-to-large scale segment, with line capacities that span pan breads and highly hydrated artisanal formats, an attractive combination for producers seeking one platform for multiple bread types. Sveba Dahlen, often in cooperation with Glimek, has carved out a niche through advanced dough make-up lines, belt proofers, and tunnel ovens, with an emphasis on tailoring equipment to different bread types and production capacities. Mecatherm differentiates through automated bread production systems aimed at baguette and specialty bread processes, including proprietary offerings such as MECACRUSTY and MECAAUTHENTIK, signaling a strategy centered on format-specific precision. König Maschinen and Baker Perkins continue to play important roles in the industrial equipment space, with Baker Perkins particularly recognized for integrated mixing, dough handling, and baking systems that support complete line design. Rheon Automatic Machinery brings a strong focus on high-precision dough processing, which appeals to buyers where dough consistency and gentle handling are critical.
European Bread Market
Regional Dynamics and Emerging Entrants
The competitive map also reflects meaningful regional divergence. Turkey’s Sarmaşık represents a long-standing equipment manufacturer with a multi-decade track record, while Chinese suppliers such as Mysun and QinLi Machinery have built positions around industrial lines for toast, baguettes, buns, and customized bread formats. Their growth underscores a broader shift in which buyers increasingly evaluate credible alternatives to traditional Western equipment sources, especially when total cost of ownership, lead time, and customization matter as much as premium branding. Farhat Bakery Equipment adds another strategic angle by focusing on automated lines for pita, lavash, naan, and other flatbreads at industrial scale, illustrating how category specialization can become a competitive advantage when regional demand creates repeatable volume. MF Italy rounds out the picture with automatic lines that support variable shapes, weights, and sizes while aligning with Industry 4.0 standards, which is relevant for producers aiming to combine flexibility with data-driven process control.
Strategic Differentiation and Consolidation Signals
Across these players, differentiation is increasingly defined by three dimensions: product adaptability, integration depth, and service responsiveness. The most compelling strategic positions are emerging where manufacturers can prove that a line can handle a broader product envelope without sacrificing throughput or consistency. That requires coordination across forming, proofing, baking, and line control, not just excellence in one unit operation. Integration depth matters because bakeries are less interested in standalone equipment performance in isolation and more interested in how well the entire system reduces downtime, simplifies changeovers, and supports consistent quality. Service responsiveness is also becoming a competitive battleground, as newer automation increases the cost of unplanned stoppages and raises expectations for maintenance planning, remote diagnostics, and spare parts availability. At the same time, the market shows signs of both consolidation and fragmentation. Consolidated players benefit from broader portfolios and stronger global support networks, but fragmentation persists because regional bakeries, local bread traditions, and specialized product categories create demand for tailored solutions. New entrants are most likely to succeed where they bring a clear specialty, a credible cost position, or a differentiated approach to flexibility and automation.
Forward Outlook: Trends to Watch in the Next Three to Five Years
Broader Automation with Format-Level Flexibility
Over the next several years, the most consequential trend will be the continued spread of higher automation levels, but with an important twist: the winning lines will be those that combine scale with format-level flexibility. Purest throughput gains will still matter in high-volume segments, but demand diversification and product proliferation will push producers to invest in lines that can switch between loaves, rolls, baguettes, and specialty products with reduced changeover time and minimal quality drift. The commercial opportunity lies in equipment and service offerings that make flexible automation economically viable for mid-sized processors, not just the largest global bakeries. The risk is that some buyers overextend into automation blueprints that are optimized for narrow product assumptions, leaving them exposed if product mix shifts or if energy and labor costs alter the economics of complex changeovers.
PW Consulting
Cost Resilience Becomes a Core Equipment Selection Criterion
Input cost volatility is likely to remain a defining theme, making yield control, waste reduction, and formulation adaptability more valuable than they were in a lower-inflation environment. Equipment that supports consistent dough processing, tighter tolerance control, and faster response to recipe or ingredient changes will be prioritized because it gives producers more control over margin outcomes. The strategic opportunity for suppliers is to frame line value not only in terms of speed and capacity but also in terms of cost resilience and process stability. The downside risk is that cost pressure may delay capital spending among smaller producers, concentrating new investment among larger players and those with the strongest balance sheets or the most urgent capacity needs.
Regional Capacity Realignment and Category Specialization
A third trend is the ongoing realignment of where new capacity is added and what kinds of production lines are favored in different markets. Some regions will see investment driven by import substitution, local modernization programs, and growing domestic demand for standardized industrial bread. Others will focus on category specialization, particularly where flatbread, artisan-style products, or sandwich formats represent stronger growth than traditional loaf bread. For investors and manufacturers, the opportunity is to match equipment strategies to these divergent paths rather than assume a single global template. The uncertainty lies in the pace of regional execution: supply chain bottlenecks, utility constraints, and shifting regulatory requirements can all delay or reshape planned capacity additions.
Strategic Implications for Decision Makers
For Equipment Manufacturers and Line Integrators
Prioritize demonstrable flexibility and integration depth over headline throughput claims. The buyers who are most likely to commit to larger projects are those who see a clear path to product mix expansion, lower changeover costs, and stronger process control. Service capability, spare parts availability, and uptime support should be treated as core product attributes because they increasingly determine whether a line is viewed as a long-term asset or a risky capital outlay. Manufacturers that can align their offerings with cost resilience, hygiene compliance, and data-enabled process control will be better positioned as procurement teams evaluate total cost of ownership rather than upfront price alone.
For Investors and Strategic Buyers
The market’s moderate concentration and continuing regional fragmentation create opportunities in specialized equipment niches, service-led expansion, and category-focused production solutions. The more durable value is likely to come from businesses that can serve high-growth formats, support flexible automation for mid-market buyers, or provide reliable after-sales performance that reduces operating risk. Before committing capital, it is important to understand which product segments are expanding, which geographies are seeing genuine capacity demand versus speculative investment, and how raw material volatility is affecting buyer confidence. Detailed segment-level intelligence is essential here, because the headline market growth can obscure uneven performance across bread types, automation levels, and regions.
For Commercial Bakeries and Procurement Teams
Treat production line selection as a multi-year operating decision, not a one-time equipment purchase. Evaluate platforms based on how well they support likely future product mixes, how they perform under input cost variability, and whether the supplier can deliver localized service and faster response when disruptions occur. Where capex is constrained, phased upgrades and modular retrofitting may offer a better risk-adjusted path than large-scale replacement projects that assume stable demand and stable input costs. In parallel, procurement teams should pressure-test supplier claims against real changeover scenarios, maintenance obligations, and the operational burden of switching formulations or bread types. For organizations that need a more precise view of segment economics, regional demand patterns, and supplier positioning before finalizing investment plans, the full PW Consulting market research report provides the deeper breakdown and customized context required for high-stakes decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Bread Production Line Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Projection Vein Finders Market: Strategic Trends & Commercial Opportunities (2026–2032)
Market Landscape and Core Challenges
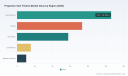
The global projection vein finders market has evolved from a niche clinical accessory into a mainstream capital equipment category, driven by steady demand for vascular access accuracy and procedural efficiency. Valued at approximately 263.2 million USD in 2025, the market is projected to expand to 563.91 million USD by 2032, reflecting a compound annual growth rate of 11.51 percent. This trajectory underscores a structural shift in how healthcare providers approach venipuncture, infusion, and diagnostic sampling—moving from anatomical palpation toward technology-assisted visualization that reduces failed attempts, patient discomfort, and clinician cognitive load.
The market's growth has not been linear. The period from 2020 through 2025 demonstrated a meaningful acceleration, with revenue climbing from 151.2 million USD to 263.2 million USD as procurement cycles normalized post-pandemic, hospital capital budgets reopened, and awareness of vascular access complications gained traction across clinical leadership. The forward-looking period from 2026 through 2032 points toward sustained expansion, with annual revenue expected to cross 400 million USD by the end of the decade. Such growth rates indicate that projection-based vein visualization is transitioning from early adopter enthusiasm to operational standard in many care settings.
Despite the favorable trajectory, several structural challenges are shaping the market's next phase. First, reimbursement fragmentation remains a persistent constraint. In many healthcare systems, there are no dedicated reimbursement codes for vein finder utilization, meaning acquisition and operating costs are typically absorbed as general capital or consumable expenditures rather than generating direct revenue streams. This dynamic forces procurement decisions to be justified primarily through workflow efficiency, complication reduction, and staff retention metrics rather than billable returns—a reality that compresses adoption timelines in price-sensitive environments and elevates the importance of total cost of ownership framing.
Second, the competitive and regulatory landscape is rewarding clinically differentiated engineering while pressuring undifferentiated hardware. Non-contact projection vein visualization systems are generally classified as Class 1 510(k) exempt devices in the United States and Class 1 devices in Europe, subject to general controls rather than premarket notification in many cases. In the European Union, however, compliance with the Medical Device Regulation (MDR 2017/745), including clinical evaluation, ISO 13485 quality management, and CE marking, remains a meaningful market access gate. The regulatory profile is comparatively accessible, but it also lowers barriers for new entrants, intensifying pressure on incumbents to demonstrate real-world differentiation beyond core near-infrared projection.
Third, end-user expectations are shifting from device presence to workflow integration. Hospitals increasingly include vein finders in tenders that specify rechargeable batteries, mounting stands, disposable sterile covers, and medical-grade components designed for seamless integration into vascular access procedures. Buyers are no longer evaluating standalone imaging performance alone; they are assessing bedside integration, infection prevention compatibility, staff training burden, and device ruggedness across diverse patient populations, including pediatric, dark-skinned, and scarred patients. This evolution is transforming procurement from a product purchase into a procedural enablement decision.
For executives and investors, the implication is clear: the market is large enough to reward scale, yet nuanced enough that value capture depends on execution quality, clinical relevance, and go-to-market discipline. Broad headline growth masks significant variation in segment attractiveness, procurement cycle intensity, and competitive intensity across geographies and application settings.
Key Drivers Powering Market Evolution
Several interconnected forces are shaping the direction of the projection vein finders market. Understanding which drivers are structural versus cyclical is essential for strategic planning, capital allocation, and capability building.
Technological innovation and imaging differentiation remain the most visible growth engine. The category is moving beyond basic near-infrared projection toward higher-resolution imaging engines, multi-color mapping, hands-free operation, and image fusion features that adapt to varying skin tones and vein conditions. Recent product activity illustrates this trajectory: AccuVein's launch of the AV600 next-generation near-infrared vein visualization device to U.S. customers in March 2026 introduced a 4x pixel count imaging engine and a sealed housing designed for infection prevention. This type of advancement matters because it simultaneously addresses two long-standing user pain points—image clarity for difficult access cases and device maintainability in infection-conscious environments. As imaging performance improves, the clinical value proposition expands from routine venipuncture assistance to more complex vascular access scenarios, broadening the addressable use cases within the same facility.
Policy, regulatory, and procurement frameworks are another critical driver, though they operate more as enablers and filters than as direct demand catalysts. The relatively accessible regulatory classification of most non-contact projection systems reduces time-to-market friction, but the burden of proof in procurement has increased. In the European Union, alignment with MDR 2017/745, clinical evaluation expectations, ISO 13485 quality management, and CE marking continues to shape which manufacturers can scale across regulated markets. In practice, this means that regulatory readiness is becoming a strategic moat: companies with mature quality systems and documented clinical evaluation pathways can expand faster and with lower compliance risk than those relying on reactive certification efforts. Meanwhile, procurement specifications are increasingly detailed. Tender documents such as those issued for medical vein visualization systems now commonly reference rechargeable batteries, stands or mounts, disposable sterile covers, and medical-grade components. These requirements elevate the importance of product ecosystem design and supplier reliability, not just device-level performance.
Demand-side behavioral shifts are reshaping where and how vein finders are deployed. Clinician and patient expectations around vascular access quality have risen, particularly in settings where repeated failed attempts carry operational and reputational costs. Hospitals and clinics are prioritizing tools that reduce puncture attempts, improve first-pass success, and support staff who manage high-volume vascular access workloads. At the same time, there is growing interest in point-of-care and decentralized settings, including emergency services and home care, where portability and ease of use can be decisive. This demand evolution is expanding the conversation beyond large inpatient departments into ambulatory, diagnostic, and field-adjacent care environments, each with distinct usability thresholds and procurement dynamics.
Supply-side and cost structure dynamics are also influencing competitive positioning. Manufacturers spanning the United States, China, and other production hubs are competing on multiple fronts: imaging quality, ergonomic design, multi-color projection modes, hands-free conversion, and pricing accessibility. Companies such as NextVein, Shenzhen Vivolight Medical Device & Technology Co., Ltd., ZD Medical Inc., HelloVein, and AimVein illustrate how product breadth is expanding across handheld and fixed-mount formats, with feature sets targeting affordability, customization across skin tones, and workflow flexibility. At the same time, established players like Christie Medical Holdings and Venoscope LLC continue to emphasize clinical heritage, patented near-infrared technology, and integration into provider networks. The resulting supply landscape is more pluralistic than in prior years, which benefits buyers through choice but also forces manufacturers to clarify defensible positioning rather than compete solely on specification sheets.
A notable demand-side catalyst is the role of procurement consortia and supplier agreements in widening access. Christie Medical Holdings' selection to exhibit VeinViewer at the Vizient Innovative Technology Exchange in August 2025, alongside expanded access through a Vizient provider agreement for vascular imaging solutions, highlights how distribution and group purchasing pathways can accelerate visibility and adoption among member hospitals. In healthcare markets where procurement is consolidated or influenced by shared sourcing networks, such relationships can materially affect competitive reach.
Taken together, these drivers suggest that the market's next growth wave will be won by organizations that align imaging innovation with procurement realities, regulatory readiness, and workflow integration. Technology alone is necessary but not sufficient; commercial execution around specification alignment, infection-prevention compatibility, and procurement narrative is increasingly decisive.
Worldwide LED Vein Finders Market
Competitive Landscape and Leading Strategies
The projection vein finders market features a mix of established clinical imaging specialists, regional manufacturing players, and increasingly agile entrants offering feature-rich handheld and fixed-mount solutions. Market concentration reflects meaningful but not insurmountable consolidation, with the top three players accounting for approximately 45.5 percent of revenue and the top five reaching roughly 62.3 percent. This concentration pattern indicates that scale and brand recognition matter, while still leaving substantial room for differentiated mid-tier and emerging competitors to capture specific use cases, geographies, or procurement segments.
Established U.S. players are leaning into imaging leadership, clinical heritage, and network-aligned distribution. AccuVein, Inc., operating from Medford, New York, has positioned itself around near-infrared projection vein visualization systems, most notably the AV600 and AV500, which project real-time superficial vasculature to improve venipuncture success. Its March 2026 introduction of the AV600 with a 4x pixel count imaging engine and sealed housing reflects a strategy centered on next-generation imaging fidelity and infection-prevention compatibility—two factors that resonate with procurement teams under pressure to reduce complications and support hygiene protocols. Christie Medical Holdings, Inc., based in Lake Mary, Florida, continues to emphasize its VeinViewer line, including the Vision2 advanced model with MaxReach and the portable Flex handheld, built on patented near-infrared technology for direct projection of vascular images onto skin. Christie's August 2025 participation in the Vizient Innovative Technology Exchange and associated provider agreement expansion points to a distribution and access strategy that leverages group purchasing visibility to broaden reach among member hospitals.
Mid-tier and emerging manufacturers are competing through affordability, feature breadth, and workflow flexibility. NextVein LLC offers the V800NV, a lightweight handheld digital system with multi-color projection modes that can convert to hands-free operation, positioned as an affordable high-performance alternative for vein visualization. This approach targets buyers who want advanced projection capability without premium pricing, particularly in settings where portability and multi-mode contrast are operationally valuable. Shenzhen Vivolight Medical Device & Technology Co., Ltd. manufactures the V800 series, including V800P and V800F, which project real-time vascular maps onto skin using near-infrared technology for clinical vein location. ZD Medical Inc., based in Hangzhou, produces portable medical projection infrared vein finders designed for real-time visualization, with support for difficult access cases such as pediatric, dark-skinned, or scarred patients—an explicit focus on clinically challenging populations that can differentiate a device in procurement evaluations.
Chinese and Asia-based entrants are expanding feature diversity and customization options. HelloVein develops AR and projection vein finders, including the Lite 2.0 and Max 3.0 models, with multi-color options, size adjustments, and image fusion features for venipuncture assistance. AimVein supplies projection vein finders such as the Pro 3.0, offering multi-color mapping with 10+ modes for customized contrast across skin tones and vein conditions. These product strategies reflect a broader trend: differentiation is increasingly defined by adaptive visualization, ergonomics, and user-configurable contrast rather than by projection capability alone. Meanwhile, Venoscope LLC and TransLite LLC / Veinlite continue to serve the market with devices using transillumination and projection technology for vascular access assistance, maintaining presence in segments where combined illumination approaches remain relevant.
PW Consulting
Strategically, the market is exhibiting both consolidation pressure and fragmentation potential. On one hand, larger players benefit from clinical credibility, established distribution relationships, and the ability to invest in next-generation imaging engines and sealed, infection-conscious housing designs. On the other hand, the relatively accessible regulatory classification of many non-contact projection systems lowers entry barriers, enabling new and regional manufacturers to introduce competitive hardware at varied price points. This dynamic creates a market where incumbents must continually raise the bar on image quality, workflow integration, and procurement-aligned feature sets, while newer entrants must prove durability, support infrastructure, and real-world reliability to progress from initial trials to repeatable purchasing.
A key evolution to watch is the shift from product competition to solution competition. Procurement is increasingly contextual: buyers evaluate devices alongside rechargeable batteries, stands or mounts, disposable sterile covers, and compatibility with vascular access workflows. Manufacturers that design for this broader ecosystem—and can articulate the operational benefits in procurement language—are better positioned to move beyond specification-based comparisons. Distribution relationships and group purchasing visibility, as illustrated by recent exhibition and agreement activity in the sector, are becoming important amplifiers of product merit, especially in concentrated procurement environments.
For market participants, the strategic question is not simply whether to compete, but where to position. Options include leading on imaging performance and infection-prevention design, competing on portability and affordability with strong feature sets, targeting difficult-access patient populations with specialized visualization, or building distribution alliances that expand access through institutional procurement channels. Each path carries different capital, operational, and competitive implications.
Vein Finder Market
Forward Outlook: Trends Shaping 2026–2032
Looking ahead, three interconnected trends are likely to define the projection vein finders market over the next three to five years.
First, imaging performance and adaptive visualization will become baseline expectations rather than differentiators. As higher-resolution imaging engines and multi-color projection modes become more common, the competitive center of gravity will shift toward application-specific usability, skin-tone adaptability, and workflow integration. Devices that can maintain clear projection across diverse patient populations and clinical settings will earn stronger repeat-use adoption, while those that perform well only in idealized conditions will face growing scrutiny. The commercial opportunity lies in pairing imaging advances with practical usability features—hands-free conversion, ergonomic form factors, and configuration flexibility—that make the technology easier to embed into daily practice.
Second, procurement-driven ecosystem requirements will increasingly shape product roadmaps. Buyers are specifying rechargeable batteries, mounting options, disposable sterile covers, and medical-grade components as part of the purchasing decision. This trend pushes manufacturers to think beyond the device unit and design for bedside integration, infection-prevention compatibility, and supply chain reliability. Companies that anticipate these requirements and align their offerings with tender language will gain an advantage in institutional procurement cycles. The risk is that manufacturers focused narrowly on hardware specifications may find themselves outpaced by competitors who offer a more complete procedural solution.
Third, distribution alliances and group purchasing pathways will play a larger role in market access. As procurement becomes more consolidated in certain regions and health systems, visibility through innovation exchanges and provider agreements can accelerate adoption independently of headline price competition. This does not eliminate the importance of product merit, but it does mean that go-to-market strategy—partner selection, clinical demonstration, and procurement narrative—will be as consequential as engineering quality. The opportunity for manufacturers is to build repeatable access channels; the risk is overreliance on a narrow set of relationships or underinvestment in clinical evidence and support infrastructure.
These trends carry inherent uncertainties. Reimbursement structures may evolve slowly, keeping acquisition decisions anchored in capital efficiency and operational outcomes rather than direct billing. Regulatory expectations in the European Union and other regulated markets will continue to require disciplined quality management and clinical documentation. Competitive entry remains relatively accessible, which could pressure margins unless differentiation is clearly established. Nonetheless, the underlying demand logic—better vascular access outcomes, reduced failed attempts, and improved clinician and patient experience—provides a durable foundation for continued growth.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to translate imaging and ergonomic strengths into procurement-ready value propositions. Product roadmaps should account for rechargeable power, mounting flexibility, sterile cover compatibility, and adaptive visualization across skin tones and difficult-access populations. Equally important is building clinical and quality-system credibility that supports expansion into regulated markets and institutional tenders. Differentiation will increasingly depend on workflow integration and supply reliability, not imaging claims alone.
For investors, the market's double-digit growth trajectory justifies attention, but value capture will be uneven. The most attractive opportunities lie with companies that combine defensible technology, repeatable procurement access, and disciplined cost structures, while also demonstrating readiness for regulatory and quality expectations in key regions. Due diligence should probe not only product features but also distribution alliances, tender adoption patterns, and post-sale support capability, since these factors often determine whether initial trials convert into sustained purchasing.
For procurement leaders and healthcare operators, the actionable focus is to evaluate vein finders as procedural enablement tools rather than standalone devices. Assessments should weigh first-pass success potential, compatibility with infection-prevention workflows, staff training burden, and total cost of ownership across battery replacement, sterile covers, mounts, and service. Where possible, procurement criteria should be aligned with the operational outcomes that matter most in the specific care setting, whether that is high-volume inpatient vascular access, ambulatory throughput, or point-of-care portability.
Detailed segment data, regional nuances, application-level dynamics, and customized scenario analysis can sharpen these decisions further. For decision-makers seeking a deeper, structured view of the market—including segmentation detail, competitive positioning, and procurement-aligned recommendations—the full PW Consulting report provides the supporting framework and granular intelligence needed to move from strategic direction to execution.
For detailed analysis of this topic, please visit the official page: Worldwide Projection Vein Finders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Small Molecule Liquid Chromatography Columns: Why 6.12% CAGR Redefines the Market
By PW Consulting, 2026-09-18
Strategic Horizons: Navigating Growth and Innovation in the Global Small Molecule Liquid Chromatography Columns Market
Market Overview and Core Challenges
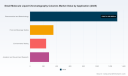
The global market for small molecule liquid chromatography columns is entering a phase of sustained, structured expansion. Valued at approximately $2,185.4 million in 2025, the sector is projected to surpass $3.3 billion by 2032, advancing at a compound annual growth rate of 6.12 percent. This trajectory reflects a mature yet evolving landscape where analytical precision, regulatory compliance, and operational efficiency converge. Historical performance from 2020 through 2025 demonstrates a consistent upward curve, driven by decades of method standardization and the entrenched role of chromatography in pharmaceutical development, quality control, and analytical research. The market remains heavily shaped by a concentrated competitive environment, where a handful of established manufacturers command significant share and benefit from deep technical portfolios, longstanding customer relationships, and integrated workflow solutions.
Despite the favorable growth trajectory, the industry faces structural challenges that will define competitive outcomes over the next several years. First, method validation and regulatory rigor are raising the performance threshold for column manufacturers. Analytical laboratories and pharmaceutical developers increasingly require columns that deliver reproducible retention times, minimal bleeding, and predictable lot-to-lot consistency, especially when methods must support regulatory filings or routine quality control. Columns that cannot meet these demands risk exclusion from validated workflows, regardless of price advantage. Second, the sector is contending with evolving cost and supply chain pressures. Material sourcing, manufacturing precision, and distribution logistics all influence margins, while end-users are placing greater emphasis on total cost of ownership rather than upfront purchase price. This shift rewards suppliers that can demonstrate longer column life, reduced re-equilibration time, and lower failure rates in high-throughput environments. Third, the market is experiencing a quiet but meaningful transformation around sustainability and environmental impact. Laboratories and procurement teams are increasingly scrutinizing the environmental footprint of consumables, from manufacturing processes to waste generation during method development and routine analysis. Suppliers that proactively address these expectations through certified practices or greener product design are gaining a subtle but growing credibility advantage.
Ion Chromatography Column Market
These dynamics create a market that is expanding but not undifferentiated. Growth is concentrated where technical reliability, regulatory alignment, and operational value intersect. Companies that treat columns as simple consumables risk being commoditized, while those that embed performance assurance, method support, and lifecycle value into their offerings are better positioned to capture share in an increasingly discerning buyer environment.
Chromatography Columns Market
Key Drivers Shaping Market Trajectory
Several interconnected forces are accelerating demand and reshaping competitive expectations across the small molecule liquid chromatography column market. The most prominent is continuous technical innovation in column chemistry and particle architecture. The shift toward highly efficient separations has reinforced demand for core-shell designs, inert surface treatments, and chemistries that tolerate challenging matrices without sacrificing resolution. Recent product activity underscores this direction. In September 2025, Agilent Technologies introduced the Altura Ultra Inert HPLC column series, aimed at improving performance with metal-sensitive small molecules and expanding applicability to peptide-related workflows. Earlier in the year, Waters Corporation expanded its MaxPeak Premier reversed-phase portfolio with preparative OBD columns designed for the purification of small molecules, peptides, and oligonucleotides. These launches illustrate how manufacturers are extending column capabilities beyond routine analytical use into purification and more demanding analyte profiles, effectively broadening the value proposition of a single product platform.
Regulatory and quality expectations are acting as a second powerful driver. The analytical procedure development guidance from the U.S. Food and Drug Administration emphasizes validated methods for small molecule pharmaceutical analysis, reinforcing the need for consistent column performance within HPLC workflows. In parallel, the United States Pharmacopeia maintains listings of chromatographic columns by brand for compendial methods, providing a framework for equivalence and reproducibility without endorsing specific suppliers. This environment rewards manufacturers that can document performance, support method transfer, and reduce variability across lots. It also increases the barrier to entry for undifferentiated products, since laboratories are less willing to risk method robustness on unproven hardware. A related signal of this trend is the growing attention to environmental accountability in manufacturing and use. Waters Corporation’s achievement of My Green Lab ACT Ecolabel certification for 42 LC columns reflects a broader movement toward transparency in the environmental impact of laboratory consumables. While sustainability alone does not drive purchasing decisions, it increasingly complements technical and compliance considerations in supplier evaluations.
Demand-side behavior is changing as well. Pharmaceutical and biotechnology organizations continue to represent the largest application segment, where small molecule analysis remains central to drug development, impurity profiling, stability testing, and quality control. At the same time, food and beverage testing, environmental monitoring, and academic or government research are sustaining steady demand for reliable separation tools. Across these sectors, users are seeking columns that reduce method development cycles, improve throughput, and minimize rework. This creates a preference for products that combine high efficiency with practical robustness, especially in settings where instrument time and analyst capacity are constrained. The result is a buyer mindset oriented toward performance assurance and workflow efficiency rather than price alone.
Supply chain and cost structure dynamics are reshaping how value is delivered and captured. Manufacturing precision, packing consistency, and quality control are critical differentiators because they directly affect column longevity and reproducibility. At the same time, regional demand patterns are encouraging suppliers to think more carefully about production footprint and distribution responsiveness. YMC Co., Ltd. broke ground on an expanded manufacturing facility in May 2025 to strengthen production of DAC columns and small molecule chromatography products for the Americas and Europe, a move that signals the importance of aligning capacity with regional demand and shortening supply pathways. GL Sciences followed a similar product-focused trajectory in November 2025 with the release of an Inertsil Hybrid-C18 HPLC column designed for enhanced alkali resistance in pharmaceutical applications. These developments suggest a market in which innovation is not limited to chemistry alone; it also encompasses manufacturing scale, material durability, and the ability to serve diverse application requirements without sacrificing consistency.
Taken together, these drivers point to a market where growth is earned through demonstrated reliability, regulatory readiness, and operational value. Suppliers that align product development with validation needs, support faster method workflows, and strengthen manufacturing and distribution resilience are best placed to convert market expansion into sustained share gains.
Competitive Landscape and Leading Strategies
The competitive structure of the small molecule liquid chromatography column market is defined by a concentrated group of technically advanced manufacturers, each pursuing differentiation through product architecture, application focus, and workflow integration. Waters Corporation, Agilent Technologies, and Thermo Fisher Scientific hold particularly prominent positions, supported by broad portfolios, established reputations, and deep ties to pharmaceutical and quality control environments. Their strategies tend to revolve around offering a wide range of separation modes, particle sizes, and formats while reinforcing performance claims through advanced surface technologies, inert designs, and preparative capabilities. Shimadzu Corporation contributes with column series built around specialized packing technologies that support small molecule workflows in pharmaceutical and quality control settings, while Phenomenex emphasizes high-efficiency core-shell and traditional chemistries tailored for pharmaceutical, clinical, and research use.
A second tier of highly focused competitors adds further differentiation through specialty chemistries and application-specific engineering. Restek Corporation provides Raptor and Ultra columns designed for reliable small molecule separations across pharmaceutical and environmental applications, emphasizing robustness across diverse matrices. YMC Co., Ltd. brings more than forty years of experience in analytical and preparative chromatography, with a strong emphasis on packing materials and columns for pharmaceutical purification and analysis. GL Sciences Inc. competes through Inertsil and InertSustain series that prioritize alkali resistance and inertness for pharmaceutical and chemical analysis. Tosoh Bioscience offers TSKgel columns suited to analytical and process applications, while Merck KGaA, through its MilliporeSigma and Supelco presence, supplies a diverse set of HPLC and UHPLC columns spanning monolithic, fused-core, and conventional designs. This layered competitive structure means that leadership is not defined solely by scale; it is also shaped by niche strength, chemical expertise, and the ability to support specialized workflows.
Recent company actions reveal how these players are translating strategy into market position. Agilent’s Altura Ultra Inert series targets metal-sensitive analytes and extends relevance into peptide-related applications, illustrating a move toward inertness as a performance differentiator. Waters’ expansion of MaxPeak Premier reversed-phase columns into preparative OBD formats reflects an effort to bridge analytical and purification workflows, increasing the strategic value of its column portfolio for biopharma and small molecule development. YMC’s manufacturing expansion indicates a capacity and regional responsiveness play, while GL Sciences’ alkali-resistant Hybrid-C18 column demonstrates a focus on durability and method flexibility in pharmaceutical use. Collectively, these moves suggest that leading companies are investing not just in incremental improvements but in extending the functional boundaries of their columns and reinforcing supply-side capability.
The market is likely to continue evolving along two parallel tracks. On one hand, consolidation pressure may persist among larger players seeking to broaden portfolios, streamline offerings, and capture cross-selling opportunities across analytical and purification workflows. On the other hand, specialization will remain valuable, particularly for companies that can address difficult analytes, harsh mobile phases, or highly regulated method environments with clearly documented performance. New entrants face a challenging environment because compendial listings, validation expectations, and established supplier relationships create meaningful inertia. However, opportunities exist for firms that bring genuinely distinct chemistry, demonstrable inertness, or superior lot-to-lot consistency to segments where current solutions still involve trade-offs. The competitive frontier is thus shifting from broad product availability toward proven performance, regulatory alignment, and the ability to reduce total analytical risk for the end user.
Future Trends and Commercial Opportunities
Over the next three to five years, the small molecule liquid chromatography column market is likely to be shaped by a few clear trends that carry direct commercial implications. The first is the continued premium on inertness and chemical resilience. As methods grow more demanding and analyte profiles become more varied, columns that resist metal interactions, tolerate wider pH ranges, and maintain stability across extensive use will gain preference. This creates an opportunity for suppliers to differentiate through surface engineering, packing consistency, and validation support that reduces uncertainty in method transfer and routine operation. Products positioned around durability and reproducibility can command stronger loyalty in settings where failed runs and re-analysis carry high operational costs.
A second trend is the tightening connection between column performance and regulatory and compendial expectations. As method validation becomes more central to pharmaceutical workflows, suppliers that provide robust documentation, lot consistency, and clear equivalence pathways will be better positioned to remain included in approved methods. This trend favors companies that invest in quality systems, technical support, and transparent performance data. It also opens the door for service-oriented value propositions, where column selection is paired with method development assistance, training, or workflow optimization. In effect, the commercial opportunity is shifting from selling a consumable to enabling a more predictable analytical process.
A third trend is the gradual realignment of manufacturing and supply strategies around regional demand and resilience. Expanding production capacity in key markets, improving distribution responsiveness, and stabilizing material supply can become competitive advantages, especially when paired with strong product performance. While sustainability and environmental certification are not yet primary purchasing drivers everywhere, they are increasingly part of supplier evaluation and may become more influential as laboratory sustainability programs mature. Companies that proactively address these expectations can strengthen their positioning with procurement teams and institutional customers that weigh environmental impact alongside technical merit.
PW Consulting
These trends are not without risk. Overinvestment in narrowly defined chemistries could leave suppliers exposed if application needs shift faster than anticipated. Pricing pressure may intensify in commoditizing segments, particularly where differentiation is weak. Regulatory expectations can also evolve, altering what qualifies as acceptable method support or documentation. Even so, the overall direction favors suppliers that combine technical excellence with operational reliability and clear alignment to end-user priorities. The commercial opportunity lies in turning performance into trust, and trust into recurring share in validated, high-value workflows.
Actionable Recommendations for Decision-Makers
For manufacturers and product leaders, the priority is to reinforce differentiation where it matters most to validated workflows and demanding applications. This means continuing to invest in inertness, chemical durability, and packing consistency while strengthening documentation, method support, and lot-to-lot assurance. Companies should also evaluate whether their portfolios adequately cover both analytical and preparative needs, since workflows that bridge separation and purification can increase the strategic value of a column line. Where capacity or regional responsiveness is constrained, targeted investment in production and distribution can become a meaningful competitive lever.
For investors, the most attractive exposure lies in suppliers that can demonstrate durable differentiation rather than broad but undifferentiated product lists. Focus on firms with clear technical moats, strong positions in pharmaceutical and quality control workflows, and evidence of alignment with validation and compliance expectations. Monitoring capacity expansion, product launches that extend into metal-sensitive or preparative applications, and sustainability-driven certifications can provide early signals of strategic intent. Caution is warranted in segments where price competition is eroding margins without corresponding performance gains.
For procurement and laboratory operations leaders, column selection should be evaluated through the lens of total analytical risk and workflow efficiency. Factors such as reproducibility, service and method support, column lifespan, and compatibility with validated methods can outweigh modest price differences. Building supplier relationships around performance transparency and documented reliability can reduce variability in day-to-day operations and simplify method transfer. As application requirements become more varied, maintaining flexibility in column selection while anchoring decisions in proven performance will help balance throughput goals with analytical integrity.
Sustained advantage in this market depends on staying ahead of technical, regulatory, and operational shifts before they become mainstream purchasing criteria. Detailed segment-level data, company-specific benchmarks, and tailored scenario analysis can help decision-makers translate these trends into precise strategy. Readers seeking a deeper dive into segmentation dynamics, regional demand patterns, and customized strategic recommendations are encouraged to explore the full PW Consulting report for a more comprehensive view of the opportunities and risks shaping the small molecule liquid chromatography columns market.
For detailed analysis of this topic, please visit the official page: Worldwide Small Molecule Liquid Chromatography Columns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Label Rolls Market: Why Asia Pacific & 4.65% CAGR Redefine Growth Strategy
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Label Rolls Market
Market Overview and Core Challenges
The worldwide label rolls market has established itself as a foundational component of the global packaging ecosystem. In 2025, the industry reached an estimated revenue valuation of 14.25 billion USD, reflecting consistent expansion over the preceding five years. Historical data indicates a trajectory from approximately 11.35 billion USD in 2020, driven by steady industrial activity and packaging demand across multiple sectors. Looking ahead, the market is projected to grow at a compound annual growth rate of 4.65 percent through 2032, with revenue expected to approach 19.59 billion USD by the end of the forecast period. This growth trajectory underscores the sector's resilience, yet it also highlights a market that is evolving faster than traditional supply chains can accommodate.
Despite the positive outlook, the industry faces several structural challenges that will define competitive positioning in the coming years. One of the most pressing issues is the tension between rising material costs and the demand for sustainable solutions. Producers of thermal paper and label substrates are navigating volatile input markets, with pricing pressures becoming particularly acute in early 2026. This cost environment forces manufacturers to make difficult trade-offs between margin preservation and competitive pricing, especially in price-sensitive segments.
A second critical challenge lies in the shifting regulatory landscape. Extended producer responsibility frameworks are gaining traction at regional levels, altering the incentive structures for packaging materials. As jurisdictions introduce new requirements for recyclable and responsibly sourced materials, label manufacturers must adapt their product portfolios and supply chain practices. These regulatory changes are not merely compliance exercises; they are reshaping procurement priorities and product design standards across end-use industries.
Finally, the market is experiencing a technological inflection point. Digital printing capabilities are maturing rapidly, enabling shorter runs, greater customization, and faster time-to-market for brands. However, integrating digital workflows into mainline production requires capital investment and operational rethinking. Companies that fail to align their manufacturing capabilities with these technological shifts risk losing relevance in segments where agility and personalization are becoming table stakes.
Key Drivers of Market Evolution
Several interconnected forces are propelling the label rolls market forward, each carrying distinct implications for strategic planning. Technology innovation stands out as a primary catalyst. The adoption of linerless label formats and perforated roll designs is reducing material waste while streamlining application processes. Recent product launches have demonstrated how removing backing paper can simplify handling and lower environmental footprints simultaneously. These innovations are not niche experiments; they represent a broader shift toward leaner material usage and more efficient downstream processing.
Regulatory and policy developments are equally influential. State-level extended producer responsibility initiatives are creating new demand signals for pulp-based and sustainably produced materials. As governments encourage packaging that aligns with circular economy principles, label manufacturers are being pushed to source materials that meet evolving standards. This dynamic is not uniform across regions, but the direction of travel is clear: compliance is increasingly tied to market access and customer preference.
On the demand side, brand owners are prioritizing labeling solutions that support sustainability claims and supply chain transparency. Consumers and retailers alike are scrutinizing packaging materials more closely, forcing manufacturers to provide documentation, certifications, and material traceability. This shift is particularly pronounced in food, beverage, and personal care segments, where labeling plays a critical role in communicating product attributes and regulatory compliance. The demand for labels that perform reliably while meeting sustainability criteria is reshaping procurement specifications and vendor selection criteria.
Labelling Market
Supply chain and cost dynamics complete the picture. Input cost pressures have been evident in recent months, with thermal paper producers implementing price increases and broader printing material indices reflecting elevated cost environments. At the same time, certain film substrates are experiencing demand-driven pricing adjustments linked to e-commerce growth and food packaging needs. Tariff considerations on raw materials add another layer of uncertainty, making supply chain diversification and hedging strategies more important than ever. Companies that can secure stable input sources or pass through cost changes transparently will be better positioned to maintain profitability.
Competitive Landscape and Leading Strategies
The competitive environment in the label rolls market is characterized by a mix of established multinational suppliers and specialized regional players. The top five companies collectively account for a significant share of market revenue, yet the concentration levels indicate room for competitive maneuvering. This structure suggests that while scale advantages matter, differentiation through material innovation, sustainability credentials, and service capabilities remains a viable path for both incumbents and challengers.
Leading manufacturers are pursuing distinct strategic positions. Some companies are leveraging their global production networks and broad material portfolios to serve diverse end-use industries, emphasizing reliability and volume capacity. Others are focusing on specialty substrates, such as thermal papers, self-adhesive films, and sustainable label stocks, targeting segments where performance and compliance requirements are particularly stringent. A recurring theme among top performers is the integration of sustainability into core product strategy, with initiatives spanning material sourcing, waste reduction, and recyclable label formats.
Label Release Paper Market
Recent developments illustrate how these strategies are playing out in practice. Innovations in linerless label rolls have garnered recognition for reducing backing paper waste and enabling single-step application, signaling a growing appreciation for efficiency and environmental benefits. Simultaneously, price adjustments in thermal paper grades highlight the reality of input cost pressures and the need for proactive pricing and procurement strategies. The broader maturation of digital printing for labels and packaging is also reshaping competitive dynamics, as manufacturers who can support digital workflows and short-run flexibility gain an edge in brand-driven applications.
PW Consulting
The market is likely to see continued evolution through both consolidation and specialization. Larger players may pursue acquisitions to expand geographic reach or deepen material expertise, while smaller firms may carve out niches in sustainable materials, thermal solutions, or regional service networks. New entrants with novel substrate technologies or digital integration capabilities could also disrupt established routines. For decision-makers, the key is to monitor not just market share movements but the underlying strategic bets companies are making around sustainability, technology, and supply chain resilience.
Future Trends and Strategic Implications
Looking ahead over the next three to five years, several trends are likely to shape the label rolls market. First, sustainability-driven material innovation will accelerate. Linerless formats, recyclable substrates, and responsibly sourced papers are expected to move from niche offerings to mainstream considerations, especially as regulatory frameworks and customer expectations tighten. Companies that invest early in sustainable label solutions will be better positioned to capture demand from brand owners seeking to align packaging with environmental commitments.
Second, digital integration will become a more central element of label production and application. As digital printing matures for mainline use, the ability to support variable data, shorter runs, and rapid design changes will become increasingly valuable. This trend creates opportunities for suppliers that can bridge material supply with digital workflow compatibility, enabling customers to respond faster to market shifts and consumer preferences.
Third, cost management and supply chain agility will remain critical success factors. Input price volatility, tariff uncertainties, and regional regulatory variation will continue to test margins and planning stability. Businesses that diversify sourcing, develop transparent pricing models, and build flexible production systems will be more resilient. At the same time, there is a risk that overinvestment in any single material pathway could leave companies exposed if demand patterns or regulatory requirements shift unexpectedly.
Actionable Guidance for Decision-Makers
For manufacturers, the priority should be aligning product portfolios with the dual demands of performance and sustainability. This means evaluating material choices, investing in linerless or recyclable options where feasible, and ensuring that production capabilities can support digital and short-run requirements. Building flexibility into manufacturing lines and supplier relationships will help navigate cost volatility while capturing emerging opportunities.
Investors should focus on companies demonstrating clear strategies around sustainable materials, digital readiness, and supply chain resilience. Market growth is positive, but the distribution of value will depend on execution. Monitoring pricing power, innovation pipelines, and regulatory adaptability will provide early signals of which players are likely to compound value over the forecast period.
Procurement and sourcing teams should prioritize transparency and diversification. With input costs fluctuating and regional regulations evolving, relying on single-source suppliers or rigid contracts increases exposure. Exploring alternative substrates, negotiating flexible pricing mechanisms, and aligning specifications with future regulatory expectations can reduce risk while supporting longer-term cost stability. In all cases, access to detailed, up-to-date market intelligence is essential for making informed choices. For those seeking deeper segmentation data, company-level profiling, and tailored strategic recommendations, the full research analysis provides a more granular view of the opportunities and trade-offs ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Label Rolls Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Protein Skimmers Market 2026: Why a 6.0% CAGR Redefines Growth Across Segments
By PW Consulting, 2026-09-18
Navigating the Worldwide Protein Skimmers Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global protein skimmers market has demonstrated steady expansion, with total revenue climbing from approximately $385 million in 2020 to $519 million by 2024, and reaching $520 million in the base year of 2025. Over the historical review period, the market experienced consistent upward momentum, reflecting broader growth in water treatment applications, aquarium hobbyism, and recirculating aquaculture systems. Looking forward, the sector is projected to continue its trajectory, with revenues expected to approach $560 million in 2026 and scale to roughly $782 million by 2032. This translates to a compound annual growth rate of approximately 6.0 percent across the 2026–2032 forecast window, a pace that underscores the market’s resilience and its positioning within the broader water quality management ecosystem.
Despite this constructive outlook, the industry is navigating several structural challenges that will shape how value is captured over the next decade. First, the market is moderately consolidated, with the top three participants accounting for roughly 38.5 percent of revenue and the top five collectively representing just over half of total sales. This concentration suggests that scale, brand recognition, and distribution reach confer meaningful advantages, while smaller or regionally focused players must compete on either cost efficiency, niche application specialization, or technological differentiation. Second, the market straddles two distinct demand environments: hobbyist and retail-oriented applications on one side, and commercial aquaculture, public aquariums, and agricultural water treatment on the other. These segments operate with different purchasing criteria, performance thresholds, and margin expectations, creating a tension between product standardization and application-specific customization.
A third challenge lies in material and manufacturing dynamics. Reaction chambers and contact columns commonly rely on cast acrylic or high-density polyethylene to balance durability, clarity, and chemical resistance. While these materials have proven effective, supply chain volatility, raw material cost fluctuations, and increasing emphasis on long-term lifecycle performance are pushing manufacturers to reconsider design trade-offs. Additionally, the shift toward in-house brushless DC pump integration is reshaping cost structures: companies that have brought pump design and production under their own control are gaining efficiency and reliability advantages, while those dependent on third-party pump suppliers face margin pressure and performance variability. Together, these dynamics are creating a market at a turning point, where incremental improvements will no longer be sufficient for sustained differentiation.
Key Drivers of Market Change
Several interconnected forces are propelling the protein skimmers market forward, and understanding their interaction is essential for positioning products, investments, and procurement strategies effectively.
Technological innovation remains the most direct catalyst for growth. Manufacturers have increasingly moved beyond legacy air-driven designs toward precision-controlled, low-noise systems that improve oxygenation, contact time, and foam collection efficiency. The introduction of in-house brushless DC skimmer pumps engineered specifically for protein skimmer applications is a notable example. These pumps reduce energy consumption, improve flow consistency, and enable quieter operation—attributes that matter increasingly in residential hobbyist settings and in noise-sensitive commercial installations. At the same time, advanced cone-shaped designs continue to refine water-air contact dynamics, supporting better organic waste removal in both aquarium and aquaculture contexts. On the commercial and RAS side, larger-scale fractionators and skimmers are being engineered to handle higher throughput while maintaining stable performance across varying load conditions.
PW Consulting
Regulatory and operational standards are reinforcing demand for reliable water quality management. In recirculating aquaculture systems, protein skimmers play a critical role in removing dissolved and suspended organic matter, helping operators maintain water parameters within accepted operational standards. Public aquariums and research facilities, which demand stable and predictable water quality for sensitive species and exhibition environments, are similarly driving interest in higher-performance units with robust construction and easier maintenance access. While the regulatory landscape varies by region, the underlying trend is clear: as aquaculture intensifies and public and institutional facilities expand, the expectation for integrated, dependable filtration solutions rises with it.
Demand-side behavior is evolving on both the hobbyist and commercial fronts. The marine aquarium hobby has continued to expand, supported by growing enthusiast communities, improved access to specialized livestock and equipment, and rising interest in reefkeeping as a long-term hobby investment. Hobbyists are increasingly seeking equipment that combines performance with user-friendly features such as app integration, automated control, and compact footprints that fit modern in-sump configurations. On the commercial side, the scaling of land-based aquaculture and the growth of large public aquarium and research installations are creating demand for durable, high-capacity skimmers that can operate continuously with minimal downtime. These divergent demand profiles are encouraging manufacturers to build broader portfolios that span nano and in-sump hobbyist models as well as heavier-duty commercial and RAS-oriented units.
Supply chain and cost structure shifts are reshaping competitive dynamics. The move toward vertically integrated pump and skimmer manufacturing is reducing reliance on external component suppliers and enabling tighter control over performance specifications, lead times, and warranty exposure. Companies that can design and produce key subsystems in-house are better positioned to manage cost volatility and iterate quickly on product improvements. At the same time, trade show activity and distributor networks remain important go-to-market channels, particularly for brands expanding across hobbyist and aquaculture markets simultaneously. Recent industry showcases have highlighted microbubble performance optimization, optional CO2 reactor air recirculation to support higher pH stability, and the ongoing rollout of refreshed product lines, all of which signal that innovation cycles are shortening and feature competition is intensifying.
Competitive Landscape and Leading Strategies
The protein skimmers market features a diverse set of participants spanning hobbyist specialists, premium European manufacturers, and companies oriented toward aquaculture, RAS, and agricultural applications. Rather than a single dominant model, the landscape is defined by several distinct strategic postures.
A first cluster of players competes on breadth and vertical integration. Reef Octopus, based in Shenzhen, offers one of the widest product ranges across hobbyist, professional, and commercial aquaculture and public aquarium use, with in-house designed and manufactured BLDC skimmer pumps and a fully in-house production model. This approach positions the company to control performance characteristics across its lineup while responding to demand across multiple end-use categories. Similarly, CoralVue Technology in the United States distributes and offers an extensive line spanning IceCap and Octopus skimmers from nano to large in-sump models, leveraging a broad distribution footprint to serve marine reef tank users at multiple scale points. Bubble Magus, operating out of China, also addresses both hobby and aquaculture markets, suggesting a strategy built on cross-segment reach rather than narrow specialization.
Pool Cleaners Market
A second cluster emphasizes premium construction, performance, and engineering heritage. Royal Exclusiv, known for Bubble King products in Cologne, specializes in high-quality German-made skimmers, filtration, and pumps for marine aquariums, with a reputation for premium build quality and performance. Deltec focuses on advanced cone-shaped skimmers that improve water contact time and performance, targeting applications where efficiency and precision matter. Nyos Aquatics develops ultra-quiet protein skimmers, including app-integrated series for reef aquariums, aligning quiet operation and digital control with the expectations of discerning hobbyist users. Ultra Reef in Italy produces high-end skimmers for reef aquariums and has continued to release refreshed models, while Sicce offers its Shark series for smaller aquarium volumes and showcases products at trade events. These players compete less on breadth and more on perceived quality, design refinement, and application-specific performance credibility.
A third cluster is oriented toward commercial, RAS, and agricultural applications. LASWIM in Zhongshan produces skimmers for aquaculture RAS water treatment and participates in industry trade shows, indicating a business-to-business orientation tied to system integrators and aquaculture operators. MAT Filtration Technologies in Greece develops large-scale skimmers and fractionators for public aquariums and recirculating aquaculture systems, addressing the higher-capacity, higher-reliability requirements of institutional and commercial environments. AquaOptima in Norway, Acquaeco in Italy, and AGK-Kronawitter in Germany each supply skimmers for agricultural applications, reinforcing the market’s reach beyond traditional aquarium channels. MRC in the United States manufactures Pro Series and commercial skimmers with heavy-duty cast acrylic construction, emphasizing durable, American-made quality for demanding use cases.
The competitive landscape is evolving along several axes. Integration is appearing in the form of vertically aligned product ecosystems, where manufacturers combine pumps, skimmers, and accessories into coordinated offerings that simplify procurement and improve compatibility. Differentiation is increasing through features such as brushless DC pump technology, app-based controls, CO2 interconnection options, and cone design refinements, which allow brands to stand out even in a moderately concentrated market. At the same time, new entrants and expanding regional players are pressing into niche segments, particularly where RAS growth, agricultural water treatment, and hobbyist demand create overlapping opportunities. The result is a market that rewards both broad portfolios and focused specialization, with success increasingly tied to the ability to match product capabilities to the performance, reliability, and user-experience expectations of each end-use environment.
Worldwide Pond Filters Market
Future Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape how the protein skimmers market develops and where commercial opportunities emerge.
First, the convergence of hobbyist and commercial feature sets will accelerate. App integration, automated dosing compatibility, quieter operation, and more compact footprints are no longer exclusive to premium hobbyist models. As these features prove their value in residential settings, commercial operators and system integrators are likely to adopt simplified, maintenance-friendly versions of the same control and performance concepts. Manufacturers that can adapt user-friendly technology to higher-duty cycles without sacrificing durability will be well positioned to capture cross-segment demand.
Second, RAS and land-based aquaculture expansion will continue to be a meaningful growth engine. As aquaculture operations scale and seek to improve water reuse efficiency, the demand for reliable organic waste removal and stable water quality management will rise. This creates opportunities for skimmer and fractionator designs that emphasize throughput, chemical resistance, ease of maintenance, and integration with broader RAS controller ecosystems. Companies that build credibility with aquaculture engineers and system integrators—through documentation, robust construction, and consistent field performance—are likely to gain share in this segment.
Third, product development cycles will shorten as feature competition intensifies. Trade show showcases, refreshed model releases, and incremental improvements in bubble performance, pump efficiency, and pH-supporting design options indicate that buyers increasingly expect regular innovation. This creates a dual implication: manufacturers must balance R&D investment with cost discipline, while distributors and procurement teams must stay current on product refreshes to avoid sourcing lagging-generation equipment. One uncertainty to monitor is the extent to which raw material and component cost pressures affect pricing flexibility, particularly for acrylic and HDPE-based construction and specialized pump components. Another is the degree to which regional demand patterns diverge, which could favor localized product configurations and distribution strategies over one-size-fits-all global offerings.
Strategic Guidance for Decision Makers
For manufacturers, the most immediate priority is to clarify which segments offer the strongest return on development effort. Companies with vertically integrated pump capabilities should leverage that advantage to improve efficiency claims, reliability, and warranty confidence, while those dependent on external pumps should evaluate supply partnerships and total-cost positioning carefully. Portfolios that bridge hobbyist and commercial applications can be powerful, but only if each product line is engineered and supported for the performance expectations of its target users.
For investors, the market’s steady growth trajectory and moderate concentration suggest opportunity in companies with clear differentiation, scale advantages, or specialized reach into RAS, aquaculture, or agricultural applications. Due diligence should focus on manufacturing control, feature roadmaps, distribution strength, and the ability to sustain innovation without eroding margins.
For procurement and end-user organizations, the emphasis should be on total cost of ownership rather than upfront price alone. Factors such as pump efficiency, maintenance access, material durability, compatibility with existing controller ecosystems, and supplier support quality can materially affect long-term operating costs. Engaging with detailed segment-level data and application-specific comparisons can help align equipment selection with operational priorities and reduce the risk of mismatched procurement.
For organizations seeking a more granular view of segment sizes, regional demand patterns, and company-level positioning, the full PW Consulting report provides expanded breakdowns and customized recommendations tailored to specific strategic questions.
For detailed analysis of this topic, please visit the official page: Worldwide Protein Skimmers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Tandem Rolling Mill Market: Why 3.7% CAGR and Asia Pacific Shift Strategy
By PW Consulting, 2026-09-18
Strategic Trends & Commercial Opportunities in the Worldwide Tandem Rolling Mill Market
Market Snapshot: Scale, Structure, and Core Challenges
The global tandem rolling mill market has entered a phase of steady, structurally supported expansion. Measured in USD millions, the sector has grown from a baseline of roughly 590 million in 2020 to just over 714 million in 2025, and forward indicators point to a consistent climb through 2032. The implied compound annual growth rate sits at approximately 3.7 percent, reflecting a market that is maturing rather than exploding. This trajectory is neither a cyclical surge nor a speculative boom; it is the result of long-lived capital investments in metal processing infrastructure, where replacement cycles, capacity modernization, and incremental efficiency upgrades compound over time.
The market structure carries a distinctly concentrated character. A small cluster of global technology providers commands a majority share of high-value equipment sales, service contracts, and retrofit business. This concentration is not a barrier to entry so much as a reflection of the engineering complexity, process know-how, and after-sales ecosystem required to deliver mills that meet today's metallurgical specs. Customers are no longer purchasing standalone machinery; they are acquiring integrated process lines with embedded automation, flatness control, and energy management capabilities. As a result, the commercial value has shifted from hardware volume to performance assurance, uptime guarantees, and lifecycle optimization.
Three interlocking challenges define the current inflection point for operators, equipment builders, and investors.
- Raw material price volatility and margin pressure. Recent pricing data shows hot-rolled coil benchmarks in the U.S. Midwest reaching multi-quarter highs, while Northeast Asia spot prices have climbed on the back of automotive, shipbuilding, and construction demand. Elevated input costs compress downstream margins and force rolling mill operators to extract more throughput per unit of energy and labor. Mills that cannot deliver consistent gauge control, reduced rework, and faster line speeds face deteriorating economics, making modernization decisions less optional and more urgent.
- The precision-at-thinner-gauges dilemma. Demand for advanced high-strength steels, electrical steels, and specialty non-ferrous alloys is pushing processors toward tighter tolerances, thinner gauges, and more uniform property distribution. Traditional rolling configurations struggle to maintain shape, flatness, and thermal stability at these specifications without significant upgrades to automation, work roll selection, and closed-loop control. The challenge is technical, but the commercial consequence is clear: capacity that cannot hold spec loses premium contracts.
- Energy, emissions, and regulatory exposure. Rolling operations are energy-intensive, and the operational cost of reheating, rolling, and auxiliary systems is increasingly tied to carbon intensity and local enforcement regimes. Mills that continue to rely on legacy furnace and drive configurations face rising operating costs and potential compliance friction. Conversely, energy-efficient upgrades are moving from "nice-to-have" engineering projects to core components of plant economics and financing eligibility.
These challenges converge on a single strategic question: how to justify and sequence capital investment in a market where utilization, specification compliance, and energy cost are all moving targets. The answer increasingly lies in targeted modernization, process digitization, and selective capacity additions rather than blanket expansion.
Key Drivers Reshaping the Tandem Rolling Mill Market
The market's upward arc is not accidental; it is being pulled by a set of reinforcing drivers that reshape where value is created and how competitive advantage is earned. Four forces stand out.
1. Technology innovation shifting from mechanical throughput to process intelligence
The most consequential technical shift is the migration from mechanical stand-alone capability to integrated, closed-loop process systems. Tandem configurations are increasingly paired with advanced shape and flatness control, automated gap and tension regulation, and real-time thermal modeling. In steel, this translates into the ability to hold tighter tolerances on high-strength and thin-gauge products without sacrificing line speed. In aluminum and non-ferrous processing, it means more uniform properties across wider strips and better control of surface quality for automotive and packaging grades.
PW Consulting
Recent contract activity illustrates this direction. One global equipment supplier secured an order for a two-stand tandem cold rolling mill oriented toward automotive and can sheet production at a new facility in China, signaling that end-market specification requirements are steering equipment selection. In a separate modernization project, a major Japanese heavy section mill adopted compact cartridge mill stands and a tandem rolling mill control system for automatic gap control, an upgrade pattern that prioritizes responsiveness and precision over raw capacity addition. These are not isolated events; they reflect a broader preference for upgrades that improve controllability, reduce variability, and extend the useful life of existing assets.
2. Policy and regulatory pressure reshaping cost structures and procurement priorities
Regulatory and industrial policy environments are acting as both constraint and catalyst. On the constraint side, energy pricing, emissions expectations, and local content or sourcing requirements in certain regions are altering the economics of plant operation and equipment selection. On the catalyst side, the same pressures are accelerating demand for more efficient reheating, reduced thermal losses, and automation that lowers labor intensity and variability.
Industry reference material indicates that modern tandem rolling lines incorporating energy-efficient technologies such as regenerative burners in reheating furnaces can achieve average energy savings above 30 percent while reducing CO2 and NOx emissions. That magnitude of operational improvement changes the payback calculus for upgrades and makes energy performance a relevant criterion in vendor evaluation. In practice, this means policy and cost pressures are aligning: the mills that can demonstrate lower specific energy consumption and cleaner operation are better positioned to secure internal capital approval, favorable financing, and in some cases preferential consideration in regulated or semi-regulated procurement environments.
Worldwide Tandem Piston Compressors Market
3. Demand-side shifts toward advanced materials and application-specific specifications
On the demand side, the story is one of specialization. Steel processors are increasingly asked to deliver advanced high-strength grades, more consistent electrical steels, and narrower tolerance windows for automotive lightweighting and electrical applications. Aluminum and non-ferrous processors face similar pressure from automotive can-sheet, packaging, and specialty alloy requirements. In electrical steel applications, for instance, tandem cold rolling configurations are being specified with emphasis on high-precision automation, temperature modeling, and edge control to meet extremely thin gauges and uniform property demands.
This demand shift matters commercially because it rewards capability over capacity. A mill that can reliably deliver a premium specification earns a different revenue profile than one that competes primarily on tonnage. It also changes the upgrade logic: companies are more willing to invest in precision control, surface quality, and automation when those investments unlock access to higher-margin product mixes rather than merely increasing throughput of commoditized grades.
4. Supply chain and cost structure reconfiguration favoring selective modernization
Supply chain dynamics are reinforcing a preference for targeted investment. Steel input prices have exhibited notable swings, with U.S. Midwest hot-rolled coil benchmarks reaching levels that represent a significant year-over-year increase, while Northeast Asia prices have moved higher on demand from automotive, shipbuilding, and construction. When input costs rise, the operating leverage of a rolling operation depends heavily on yield, downtime, and energy efficiency.
That reality is pushing many operators away from greenfield expansion toward modernization that improves existing asset productivity. Retrofit programs that restore reliability, replace wear components, and upgrade control systems can deliver meaningful reductions in unplanned downtime and improve throughput consistency without the cost and lead-time burden of new greenfield capacity. A recent turnkey-style rehabilitation project in Italy, for example, focused on restoring reliability and reducing downtime in a tandem cold rolling mill by replacing key mechanical components. Projects of this nature reflect a market where extending asset life and stabilizing operations can be more commercially attractive than building new capacity from scratch.
Competitive Landscape and Leading Strategies
The competitive field is defined by a relatively small group of globally capable equipment and technology providers, each competing on a different combination of metallurgical expertise, automation depth, regional reach, and aftermarket support. Concentration in the market means that procurement decisions are often shaped by the perceived risk reduction, technical support coverage, and integration capability a vendor can offer, not only by headline equipment price.
Several strategic positioning patterns are visible among leading players.
- Integrated precision and automation as a differentiator. Some suppliers have built their reputation around continuous tandem cold mill solutions with advanced shape control, thickness uniformity, and automation systems, especially for electrical steel and high-precision applications. Their value proposition is less about brute-force capacity and more about repeatability, thin-gauge capability, and process stability. This is particularly relevant for customers whose product roadmap depends on meeting tighter specifications and accessing premium end markets.
- Broad-spectrum capability across ferrous and non-ferrous metals. Other leaders compete by offering a wide range of cold and tandem rolling solutions covering multiple strip widths, alloys, and configurations, including modular designs that combine rolling and forming units. This breadth allows them to serve diverse processor portfolios and to propose flexible equipment architectures that can adapt to changing product mixes. For customers with multi-metal operations or uncertain product strategies, that flexibility can be a decisive commercial advantage.
- Regional execution and aftermarket intensity. A further dimension of competition comes from suppliers with strong regional execution capability and deep aftermarket presence. Modernization, component replacement, and reliability-focused rehabilitation projects create recurring touchpoints with customers and build long-term service relationships. In concentrated markets, the ability to respond quickly with localized engineering support and spare-part logistics can be as important as the original equipment sale.
- Specialty configurations for demanding alloys. Some participants specialize in high-capacity, automation-driven tandem solutions with particular strengths in magnetic materials, stainless steel, and special alloys, using design choices such as small work roll diameters and large-stroke shifting to handle difficult processing requirements. This kind of specialization allows them to command position in niches where generic solutions underdeliver on metallurgy or control.
The landscape is evolving along three overlapping trends. First, differentiation is increasingly tied to digital control, energy performance, and specification compliance rather than to mechanical configuration alone. Second, the boundary between "new equipment" and "modernization" is blurring, as many contracts effectively extend the life and capability of installed bases rather than adding entirely new lines. Third, regional demand centers, especially in Asia, are generating a steady cadence of new orders and upgrade projects that reward suppliers with both global technology and local project execution. Taken together, these trends suggest a market where winners are those who can pair process technology with dependable service, and where the most attractive commercial opportunities often emerge in selective upgrades rather than indiscriminate expansion.
Forward Outlook: Three Trends to Watch Over the Next 3–5 Years
Looking ahead, several trends are likely to shape where growth concentrates and which capabilities command premium positioning.
- Continued selective modernization over blanket capacity addition. Given the maturity of the market and the cost of new greenfield builds, a meaningful share of investment will continue to flow toward retrofits, control-system upgrades, and reliability improvements. Expect more contracts focused on gap control, flatness optimization, automation, and component renewal. The commercial opportunity here lies in sequencing upgrades that unlock higher-margin products and reduce operating cost, rather than pursuing capacity additions that do not improve specification performance.
- Energy efficiency and emissions performance becoming procurement criteria. As energy costs and regulatory scrutiny remain salient, mills that can quantify and deliver energy savings, lower specific consumption, and reduced emissions will have an advantage in both internal approval processes and external competitiveness. Equipment and service offerings that integrate energy-efficient furnace technologies, optimized drive configurations, and process control that reduces waste are likely to see stronger demand, particularly where financing or compliance considerations are tied to efficiency outcomes.
- Premium specification capability as the route to margin differentiation. Demand for advanced high-strength steels, electrical steels, and specialty non-ferrous products is expected to keep pressure on processors to deliver thinner gauges, tighter tolerances, and more uniform properties. Providers that can demonstrate repeatable thin-gauge performance, advanced automation, and metallurgical process control will be better positioned to support customers moving up the value chain. The strategic implication is that capability upgrading and product-mix upgrading are increasingly two sides of the same investment decision.
These trends carry meaningful but manageable risks. Raw material price volatility can shift the urgency of upgrades and the affordability of capital projects. Regional demand cycles in automotive, construction, and shipbuilding can speed up or slow down order books. And the concentration of capable suppliers means that procurement negotiations often hinge on ecosystem support and integration risk, which can raise barriers for newer entrants attempting to compete on price alone. Still, the underlying direction is clear: value is migrating toward precision, efficiency, and reliability.
Strategic Implications and Action Steps for Decision-Makers
For manufacturers and processors, the near-term priority is to align capital planning with specification and efficiency outcomes rather than with tonnage targets alone. Targeted modernization that improves gauge control, reduces downtime, and lowers specific energy consumption can improve both margin resilience and access to premium product segments. Where new capacity is justified, it should be evaluated against the ability to hold tighter specs and to integrate efficiently with existing automation and material-handling systems.
For investors and strategic planners, the most durable opportunities are likely to be found in providers and projects that combine process technology with strong aftermarket and service economics. In concentrated markets, recurring service relationships, retrofit pipelines, and energy-performance-driven upgrades can offer more predictable value than pure equipment volume. It is also worth monitoring regional demand centers where new orders and modernization projects are accumulating, since execution capability and local support often determine long-term share dynamics.
Worldwide Steel Rolling Oils Market
For procurement and sourcing leaders, vendor evaluation should expand beyond baseline equipment cost to include controllability, automation depth, energy performance, and the credibility of the support ecosystem. In a market where specification risk and operating cost are both high, the cheapest initial price can be misleading if it comes with higher variability, more downtime, or weaker efficiency.
Because the market is shifting across technology, regulation, and demand simultaneously, decision-makers benefit from having detailed segmentation data, regional dynamics, and customized scenario analysis at hand before committing to capital or partnership choices. A comprehensive research report can provide the granular breakdowns, competitive benchmarking, and forward scenarios needed to translate these directional trends into concrete project prioritization and sourcing strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Tandem Rolling Mill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Coffee Concentrate Juice Market: Why 6.12% CAGR Changes Everything
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Coffee Concentrate Market
Market Landscape and Core Challenges
The global coffee concentrate market has demonstrated consistent expansion, with revenue climbing from approximately USD 2,120.45 million in 2020 to an estimated USD 2,842.50 million in 2025. Projections indicate a compound annual growth rate of 6.12 percent through 2032, positioning the sector to reach roughly USD 4,303.18 million by the end of the forecast window. This trajectory reflects a broader reallocation of value within the beverage industry, where convenience, consistency, and scalability are increasingly dictating procurement decisions across both commercial and retail channels. The market's steady expansion suggests that concentrate formats are no longer functioning as a niche input but are becoming a structural component of modern beverage architecture.
Despite the favorable growth backdrop, the industry is navigating several structural friction points that will determine which participants capture disproportionate value in the coming years. First, raw material volatility continues to inject uncertainty into cost planning and margin management. The International Coffee Organization's Composite Indicator Price averaged 296.89 US cents per pound in January 2026, followed by a downward drift toward lows near 262 US cents per pound in February before partial stabilization in the 273–290 US cents per pound range during the spring months. This pattern underscores the sensitivity of concentrate economics to crop cycles, weather outcomes, and supply expectations. When input costs shift rapidly, manufacturers with limited hedging discipline or inflexible procurement structures face compressed profitability, while more adaptive firms can protect margins and even gain share during periods of price dislocation.
Second, regulatory architecture remains uneven and poorly synchronized across markets, creating compliance friction for global operators. Coffee and tea infusions derived from dried ingredients fall outside the scope of FDA Juice HACCP regulation, a distinction that differentiates coffee concentrates from fruit or vegetable juice concentrates intended for beverage use. At the same time, labeling rules for products purporting to contain juice require explicit juice content declarations and mandate that beverages made from concentrate include terms such as "from concentrate" or "reconstituted" where the product name appears. For coffee concentrate manufacturers operating in adjacent or hybrid categories, these overlapping and sometimes contradictory requirements increase formulation complexity, labeling costs, and the risk of misclassification. Firms that invest early in regulatory mapping and documentation discipline will face fewer costly disruptions as product portfolios expand across categories and geographies.
Third, the combination of market concentration and ongoing process innovation is raising the competitive bar. With the top three participants accounting for roughly 38.45 percent of revenue and the top five reaching approximately 52.3 percent, scale, brand equity, and distribution reach continue to confer meaningful advantages. Yet concentration also signals an opportunity for targeted differentiation. As major operators push proprietary processing technologies and customized concentrate variants, smaller or regionally focused players must avoid competing on commodity-like volumes alone. The market is bifurcating: scale players are leveraging volume and branding, while agile suppliers are carving positions through specialty origins, performance-focused processing, and tailored foodservice formats. Recognizing this divergence is essential for any operator planning capacity, partnership, or entry decisions.
Coffee Concentrates Market
Key Growth Drivers
Several interconnected forces are shaping the direction of the coffee concentrate market and creating differentiated opportunities for participants that align their capabilities with structural demand shifts.
Technological Innovation and Processing Differentiation
Process innovation remains one of the most consequential drivers of competitive advantage. Advances in cold-brew extraction, high-Brix concentration, and shelf-stable liquid formulation are enabling manufacturers to deliver concentrates with improved flavor consistency, reduced preparation complexity, and broader application compatibility. Recent product activity illustrates this trajectory clearly. In July 2025, Red Diamond Coffee & Tea introduced the Fitz Cold Brew Coffee Concentrate for foodservice operators, designed to simplify cold brew preparation by providing a ready-to-dilute format that reduces labor, variability, and equipment demands. A few months later, in April 2026, Nestlé and Starbucks unveiled the Starbucks Coffee Craft concentrate, expanding cold coffee availability through a concentrate format engineered for consistent taste and efficient deployment across foodservice and beverage manufacturing applications.
These launches are not isolated product additions; they reflect a broader shift toward concentrates that serve as operational tools rather than raw inputs. For beverage manufacturers and foodservice operators, the commercial appeal of concentrates increasingly rests on repeatability, speed of preparation, and compatibility with existing dispensing or blending infrastructure. Suppliers that can pair flavor integrity with formulation flexibility, such as customized Brix levels or origin-specific profiles, are well positioned to deepen customer relationships and move beyond transactional supply arrangements. The strategic implication is that processing capability is becoming a core differentiator, and investment in extraction, stabilization, and customization technologies is likely to separate market leaders from follow-on competitors.
Demand-Side Transformation and Channel Evolution
Consumer and enterprise behavior is reshaping where and how coffee concentrate is consumed. Cold coffee formats have moved from a seasonal novelty to a sustained category with year-round demand, and the concentrate segment is benefiting directly from this normalization. Foodservice operators are drawn to concentrate formats that reduce preparation variability and labor intensity, particularly in high-turnover environments where consistency and speed are essential. At the same time, retail and household channels are absorbing concentrates as consumers seek convenient, customizable home beverage experiences without the operational burden of brewing from scratch.
This channel divergence is producing distinct demand profiles. Foodservice demand tends to prioritize operational efficiency, portion control, and compatibility with existing equipment. Retail and household demand places greater weight on shelf stability, ease of use, and perceived premium quality. Manufacturers that design concentrate portfolios with these channel-specific requirements in mind can capture value across multiple touchpoints without forcing a single format to carry all use cases. The broader insight is that demand growth is being supported not only by total volume expansion but also by the migration of coffee consumption into formats that are inherently more concentrate-friendly.
Supply Chain Dynamics and Cost Structure Realignment
Coffee concentrate economics are being recalibrated by evolving raw material conditions and supply chain design choices. The recent softening of green coffee pricing, driven by expectations of record Brazilian harvests and broader global supply surpluses, has altered the near-term cost environment. While lower input prices can relieve margin pressure, they also introduce new considerations around procurement timing, inventory strategy, and supplier relationships. Firms that treat raw material volatility as a recurring design parameter rather than an episodic disruption are better equipped to maintain cost discipline. This includes diversifying origin exposure, structuring flexible offtake arrangements, and aligning concentrate specifications with cost-efficient processing routes where feasible.
PW Consulting
Supply chain resilience is increasingly tied to operational flexibility. Concentrate manufacturers are evaluating everything from batch sizing and packaging configurations to logistics networks and regional production footprints. In a market where foodservice and industrial processing customers demand reliable availability and predictable lead times, the ability to balance efficiency with responsiveness is becoming a differentiator. Cost structures that incorporate proactive inventory planning, multi-origin sourcing, and format optimization are more likely to sustain profitability through cycles of input price movement. The practical takeaway is that supply chain design is no longer a back-office concern; it is a strategic lever that shapes pricing power, service levels, and customer retention.
Regulatory Clarity as a Strategic Enabler
Regulatory dynamics are also functioning as a growth enabler by clarifying where concentrate products sit within existing compliance frameworks. The distinction between coffee and tea infusions from dried ingredients and juice-based concentrates under FDA Juice HACCP guidance helps reduce uncertainty for coffee-focused manufacturers, provided that labeling and category positioning are managed carefully. In parallel, customs marking exemptions for roasted and instant coffee and certain coffee preparations can simplify trade documentation and reduce administrative overhead for exporters and importers operating across jurisdictions. Where beverage products include juice claims, however, percentage declarations and from-concentrate labeling requirements still apply and must be integrated into product development and packaging processes.
These regulatory nuances are not merely compliance checkboxes; they influence product architecture, market entry sequencing, and labeling investment. Organizations that build regulatory literacy into their formulation and go-to-market planning can reduce time-to-market, avoid rework, and position products more cleanly within their intended categories. As the concentrate market expands across both coffee-centric and hybrid beverage applications, clarity on classification and labeling will increasingly separate operators that scale smoothly from those that encounter avoidable friction.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of global scale players, specialized concentrate suppliers, and foodservice-oriented manufacturers, each pursuing distinct value propositions. Nestlé and Starbucks exemplify a partnership-driven approach to category expansion, leveraging brand equity and distribution muscle to accelerate cold coffee availability through concentrate formats. Their focus on broad availability and recognizable branding targets mass consumption and beverage manufacturing channels where standardization and reach are paramount. This strategy underscores the continued relevance of scale, but it also highlights the importance of product relevance: even large incumbents must ensure that concentrate formats align with specific usage occasions and preparation expectations.
Finlays represents a more customization-oriented posture, supplying tailored coffee concentrates including cold brew and high-Brix variants for beverage manufacturing and ready-to-drink products. Its emphasis on multiple origins and certifications signals a strategy built on formulation flexibility and sourcing credibility. For industrial and beverage manufacturing customers, this profile can translate into stronger partnership potential, particularly where product differentiation depends on origin selection, processing nuance, or certification requirements. In a market where generic concentrate offerings are increasingly commoditized, the ability to adapt specifications to customer needs becomes a meaningful differentiator.
U.S.-based manufacturers such as Westrock Coffee Company, The J.M. Smucker Company, Keurig Dr Pepper, All American Coffee LLC, Red Diamond Coffee & Tea, Chameleon Cold-Brew, CoolBrew, and Jedwards International illustrate the breadth of domestic concentration activity across private label, retail, and foodservice applications. Some participants emphasize proprietary processing for customized formats, while others focus on convenience-driven foodservice concentrates or organic retail-oriented cold brew products. Red Diamond's Fitz Cold Brew launch, for example, reflects a practical service logic: enabling foodservice operators to deliver premium cold brew with simplified preparation. CoolBrew's proprietary cold-drip process and Chameleon's organic positioning point to differentiation through process identity and category authenticity. These approaches demonstrate that U.S. players are competing not only on volume but also on format design, brand narrative, and channel fit.
International and specialty-oriented operators add further texture to the landscape. Jake-Frut & Jake-Café provides custom branding solutions for concentrated juices and liquid coffee, targeting customers that value packaging and brand integration. Cafeahaus AG DEK specializes in soluble coffees and liquid coffee extracts for food industry and vending applications, an area where compatibility, dosing reliability, and machine-friendly formats matter. Batavia Cold Drip Coffee, with operations spanning the Netherlands and Indonesia, offers bulk liquid cold drip concentrates with customizable recipes and packaging options, an appealing profile for buyers seeking scale without sacrificing formulation input. Together, these companies show that the market is not a simple hierarchy of global giants versus niche suppliers; it is a layered ecosystem where competitive advantage can be built through provenance, customization, service model, or application expertise.
The competitive trajectory appears to be moving toward selective consolidation and simultaneous niche differentiation. Scale players will continue to consolidate advantageous distribution, brand recognition, and processing capacity, especially in broad consumer and foodservice segments. At the same time, new entrants and focused incumbents will likely find room by addressing underserved applications, origin narratives, organic or specialty certifications, and operational pain points such as preparation complexity or format incompatibility. The most durable strategies will be those that combine credible processing capability with clear customer value, whether that value is operational efficiency, flavor consistency, customization, or category positioning. A market with this level of strategic diversity rewards companies that define their positioning precisely rather than attempting to compete across every dimension at once.
Future Outlook: Three Signals to Watch
Looking ahead to the 2026–2032 window, several signals point to where strategic attention should be concentrated.
First, cold coffee adoption will continue to anchor concentrate demand, but the growth logic will increasingly shift from novelty to operational integration. As foodservice and beverage manufacturing customers mature in their use of concentrate formats, the value proposition will depend less on introducing cold coffee and more on improving preparation efficiency, consistency, and scalability. Manufacturers that align concentrate specifications with real-world workflow requirements, including dilution ratios, dispensing compatibility, and batch-to-batch stability, are likely to secure stickier customer relationships. The related opportunity is to design concentrate portfolios for repeatable deployment rather than one-off product launches.
Second, a period of lower input prices can reshape competitive behavior if it leads to complacency in cost management or procurement discipline. Lower green coffee pricing may temporarily ease margin pressure, but it can also obscure the need for robust hedging, origin diversification, and specification-to-cost alignment. Operators that use favorable pricing windows to strengthen supply chain resilience and lock in flexible sourcing arrangements will be better positioned when prices cycle back. The risk is that temporary cost relief encourages volume-driven competition without corresponding value or efficiency gains, which can erode profitability over time.
Third, category boundaries will continue to test labeling and regulatory clarity, especially as beverage concepts blur the line between coffee, juice-adjacent, and hybrid formats. Products that incorporate juice claims, from-concentrate language, or multi-ingredient formulations will face tighter scrutiny on declaration accuracy and consumer communication. This creates both a compliance challenge and an opportunity: companies that develop clean, category-appropriate labeling and transparent product narratives can reduce friction and build trust, while those that treat labeling as an afterthought risk rework, market delays, or consumer confusion. The strategic opportunity lies in treating regulatory and labeling design as part of product architecture rather than a downstream task.
Strategic Recommendations for Decision-Makers
For manufacturers, the immediate priority is to align concentrate development with application-specific value. This means prioritizing processing consistency, customization capability, and preparation simplicity where customer workflows demand it. Investment should be directed toward formats and specifications that reduce customer friction, whether that friction is operational, sensory, or regulatory. In parallel, supply chain strategy should incorporate flexible sourcing and inventory planning so that margin protection is not dependent on any single price environment.
Worldwide Citrus Concentrate Market
For investors, the most relevant question is not whether the market is expanding, but which business models are best configured to capture durable margin and share. Comparative evaluation should focus on processing differentiation, channel fit, customer retention logic, and exposure to raw material cycles. Companies that can demonstrate repeatable concentrate performance, clear application relevance, and disciplined cost management are more likely to translate market growth into sustained profitability. Due diligence should also assess regulatory readiness, especially for products operating near category boundaries or with multi-ingredient formulations.
For procurement and sourcing teams, concentrate selection should be evaluated on total operational impact rather than unit price alone. Dilution performance, shelf stability, equipment compatibility, lead-time reliability, and documentation clarity all influence total cost of ownership. Where feasible, buyers should seek suppliers with proven customization capacity and transparent compliance practices, particularly if product portfolios are expected to expand into hybrid or multi-format use cases. Strategic sourcing relationships, rather than transactional purchasing, will increasingly determine how smoothly concentrate programs scale.
Market-level growth is only one part of the story. The more consequential question is which participants will convert that growth into defensible advantage through better processing, smarter sourcing, and sharper category positioning. Detailed segmentation, regional dynamics, and application-level cost structures provide the granularity needed to make those judgments with confidence. Readers seeking a deeper view of segment performance, competitive benchmarking, and forward scenarios can consult the full PW Consulting report on the worldwide coffee concentrate market for more detailed data and tailored strategic guidance.
For detailed analysis of this topic, please visit the official page: Worldwide Coffee Concentrate Juice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Air Quality Sensor ICs Market to Hit $1.57B by 2032
By PW Consulting, 2026-09-17
A Strategic Imperative for Semiconductor Leaders: Navigating the Global Air Quality Sensor ICs Market (2026–2032)
The global trajectory of environmental monitoring is no longer defined solely by regulatory compliance; it is increasingly driven by a convergence of consumer health awareness, automotive cabin optimization, and industrial automation. For semiconductor strategists and product leaders, the air quality sensor integrated circuit (IC) market represents a high-growth vector where technological differentiation meets expanding application scope. Our latest research into the Worldwide Air Quality Sensor ICs Market provides a granular, forward-looking intelligence framework designed to support critical investment and portfolio decisions throughout the 2026–2032 forecast horizon.
In a landscape characterized by rapid technological iteration and shifting geopolitical supply chains, relying on historical analogs or fragmented public data is insufficient. This report distills complex market mechanics into actionable strategic insights, enabling stakeholders to identify high-value segments, anticipate competitive disruptions, and align R&D roadmaps with emerging demand patterns. The following analysis outlines the core value proposition of this study, highlighting the macro-economic currents, competitive dynamics, and operational frameworks that will define market leadership in the coming years.
Market Trajectory and Macro-Economic Foundations
The air quality sensor IC industry has demonstrated robust resilience and expansion over the past half-decade. Historical data from 2020 through 2025 reveals a market that has consistently grown its total addressable revenue, culminating in an estimated global valuation of approximately 780.0 million USD in the base year. This upward momentum is not merely cyclical; it is structural, fueled by the integration of sensing technologies into everyday electronic ecosystems and stringent indoor air quality (IAQ) mandates across major built environments.
Looking ahead, the forecast period from 2026 to 2032 projects sustained expansion. By 2026, the market is poised to cross the 868.92 million USD threshold, signaling a decisive acceleration in adoption rates across both mature and emerging application verticals. The compound annual growth rate (CAGR) for this forecast window stands at a compelling 10.51 percent, underscoring the sector's capacity to outperform broader semiconductor segments. As the timeline extends toward 2032, revenue projections escalate significantly, reflecting the maturation of next-generation sensor platforms and the deepening penetration of multi-parameter ICs in high-volume consumer and industrial deployments.
Air Quality Sensor Market
This growth trajectory is underpinned by a fundamental shift from single-function sensing to integrated, intelligent monitoring solutions. Manufacturers are increasingly prioritizing ICs that combine particulate matter detection, volatile organic compound (VOC) analysis, and environmental compensation within unified packages. Our research quantifies the revenue contribution of these converging technology stacks while isolating the specific drivers that will determine market share allocation among key geographies and end-use segments. While precise regional and application-level revenue breakdowns are detailed exclusively within the full report, the strategic narrative is clear: value is migrating toward ecosystems that demand higher accuracy, lower power consumption, and seamless system integration.
Technology Segmentation: From Discrete Sensing to Integrated Intelligence
The architecture of the modern air quality sensor IC market is defined by a multidimensional segmentation structure that spans technology type, application domain, and geographic deployment. At the core of the technology split, the market encompasses gas sensor ICs, particulate matter sensor ICs, and an emerging category of integrated multi-parameter ICs. Each of these technology tracks presents distinct value chains, manufacturing complexities, and performance benchmarks, requiring stakeholders to evaluate investment opportunities through a nuanced lens of risk and return.
Gas sensor ICs continue to anchor a substantial portion of overall revenue, driven by the persistent demand for VOC and NOx detection in both indoor and outdoor environments. Concurrently, particulate matter sensor ICs are witnessing accelerated adoption as public health initiatives and smart city infrastructure projects mandate real-time PM2.5 and PM10 monitoring. The integrated multi-parameter segment, though currently smaller in absolute scale, represents a critical frontier for differentiation, as system designers increasingly seek consolidated solutions that reduce bill-of-materials complexity and streamline embedded processing requirements.
On the application side, the market is diversified across consumer electronics, automotive cabin monitoring, industrial and smart city infrastructure, and medical and healthcare sectors. Each vertical carries unique performance tolerances, certification pathways, and procurement cycles. Consumer electronics leverage sensor ICs for personal health and home automation, while automotive cabin monitoring demands robust, humidity-tolerant solutions capable of operating in dynamic vehicular environments. Industrial and smart city deployments prioritize scalability, environmental ruggedness, and network interoperability, whereas medical and healthcare applications require exceptional accuracy and calibration stability to support diagnostic and therapeutic workflows.
The report provides a comprehensive mapping of these application segments, analyzing how revenue streams are distributed and where onboarding barriers remain highest. Rather than presenting isolated percentage splits, the study ties application dynamics to broader macro trends—such as the proliferation of energy-efficient HVAC systems in commercial buildings and the regulatory push toward healthier vehicle interiors—enabling readers to assess which verticals will generate the highest marginal returns over the forecast period.
Competitive Landscape: Key Players and Strategic Positioning
The global air quality sensor IC market is characterized by a moderately concentrated competitive environment, where a handful of established incumbents and technology specialists command a significant share of overall revenue. Our analysis indicates that the top three firms collectively account for approximately 42.5 percent of total market revenue, while the top five players extend their combined footprint to roughly 58.8 percent. This concentration level suggests a market where scale advantages and proprietary technology stacks play a decisive role, yet sufficient white space remains for agile entrants and specialized component suppliers to capture value in niche or rapidly evolving subsegments.
Among the recognized leaders shaping this competitive landscape is Sensirion AG, headquartered in Stäfa, Switzerland. Sensirion has built a strong reputation for its CMOSens®-based sensor ICs and modular platforms, including the SGP40 and SGP41 VOC/NOx sensor families and the integrated SEN6x platform that combines PM, CO2, and multi-gas sensing capabilities for indoor air quality monitoring. In December 2025, the company announced next-generation SEN65 and SEN63C indoor air quality sensor platforms, signaling a continued commitment to multi-parameter measurement enhancement and system-level optimization.
Worldwide Air Quality Sensor ICs Market
ScioSense B.V., based in Eindhoven, Netherlands, competes through its specialization in MOX-based air quality sensor ICs, notably the ENS16x, ENS160, and ENS170A series. These products are engineered for VOC, multi-gas, and indoor air quality detection, with certain variants offering integrated processing and automotive-grade qualifications. ScioSense's focus on configurable gas sensing solutions positions it as a flexible supplier for OEMs seeking customized environmental monitoring architectures.
Bosch Sensortec GmbH, operating from Reutlingen, Germany, leverages its MEMS expertise to deliver a diversified portfolio that includes the BME688 and BME690 4-in-1 gas, humidity, temperature, and pressure sensors augmented with AI-driven interpretation capabilities. The company also offers the BMV080, an ultra-compact PM2.5 particulate matter sensor. In June 2025, Bosch Sensortec unveiled the BME690 with up to 50 percent reduced power consumption, specifically optimized for high-condensation environments. Continuing this momentum, the company introduced the BMV080 in January 2026, describing it as the world's smallest fanless PM2.5 particulate matter air quality sensor for ultra-compact IoT devices.
Renesas Electronics Corporation, headquartered in Tokyo, Japan, supplies the ZMOD series of air quality sensor IC modules, including the ZMOD4410 for total VOC and indoor air quality applications and the ZMOD4510 for outdoor monitoring. Renesas differentiates its offerings through a firmware-configurable architecture that simplifies signal conditioning and accelerates time-to-market for end-product developers.
Infineon Technologies AG, based in Neubiberg, Germany, is recognized for its XENSIV™ PAS CO2 sensor ICs, which utilize photoacoustic spectroscopy to deliver accurate indoor air quality and CO2 monitoring within compact form factors. In September 2024, Infineon released the XENSIV PAS CO2 5V sensor for smart buildings, emphasizing real-time air quality data delivery and compliance with IAQ standards.
The competitive field also includes prominent contributors such as Amphenol Advanced Sensors (Telaire) in St. Marys, Pennsylvania, USA, which manufactures CO2, VOC, dust/PM, and humidity sensors leveraging NDIR and other technologies for HVAC, building automation, and automotive use cases. Amphenol SGX Sensortech, based in Corby, United Kingdom, develops MOX and other gas sensor technologies for indoor air quality, with recent introductions including the SGX4410 and SGX4510 series for versatile detection. Additionally, Cubic Sensor and Instrument Co., Ltd. in Wuhan, China, produces integrated air quality sensor modules that combine PM, CO2, VOC, and environmental parameters using NDIR, laser, and other sensing technologies.
Our report goes beyond corporate profiling to examine product portfolio overlaps, pricing strategies, and the strategic implications of recent product launches. By connecting launch timelines to broader market demand shifts, the analysis reveals which technology roadmaps are likely to capture disproportionate adoption and which legacy architectures may face margin compression.
Industry Dynamics: Supply Chain Pressures, Regulatory Shifts, and Environmental Realities
Market growth does not occur in a vacuum. The air quality sensor IC sector is navigating a complex matrix of macro-economic and regulatory forces that will profoundly influence sourcing strategies, cost structures, and regional competitiveness. In January 2026, U.S. Presidential Proclamations imposed a 25 percent tariff on certain advanced computing chips, while directing policy actions on critical minerals supply chains. Although this measure primarily targeted high-performance computing semiconductors, its ripple effects extend to the broader semiconductor ecosystem, potentially affecting the cost and availability of sensor IC components that depend on specialized fabrication processes and advanced packaging technologies.
Simultaneously, geopolitical tensions surrounding critical material access continue to shape the industry's operational calculus. China's restrictions on rare earth and critical mineral exports have raised expectations of supply shortages and increased input costs for materials integral to MEMS and gas sensor production. These constraints are particularly relevant for manufacturers that rely on specific element dependencies for sensor calibration, thermal management, or protective coatings. Strategic procurement and supply chain diversification are no longer optional; they are competitive necessities that will determine which firms can sustain margin stability through the forecast period.
Beyond geopolitical and trade dynamics, the environmental footprint of semiconductor manufacturing itself introduces additional cost and compliance pressures. Semiconductor fabrication processes generate air pollutants, including VOCs, NOx, SOx, and particulate matter, which influence upstream environmental compliance costs for sensor IC production. As regulators worldwide tighten emissions monitoring and enforce more rigorous sustainability standards, sensor manufacturers may face increased capital and operational expenditure requirements to maintain compliant production lines. Our report evaluates how these upstream dynamics intersect with downstream demand, identifying the segments that are best insulated from cost pass-through challenges and the geographies where regulatory alignment may facilitate faster adoption.
What This Research Delivers: An Operational Framework for 2026 Decision-Making
The Worldwide Air Quality Sensor ICs Market research is engineered to function as a strategic decision-support tool, not merely a descriptive data repository. Stakeholders across semiconductor manufacturing, component distribution, systems integration, and venture investment will find the report structured to answer the questions that directly impact capital allocation and product planning.
Key analytical deliverables include a comprehensive historical and forecast revenue assessment across the entire market and within defined segmentation parameters. The study traces the trajectory from 2020 through 2025 to establish baseline momentum, then projects forward through 2032 to map inflection points, growth accelerations, and potential saturation thresholds. By isolating the CAGR for the forecast period and contextualizing it within technology adoption curves, the report enables readers to differentiate between short-term demand spikes and durable secular growth.
The segmentation analysis provides a structured dissection of revenue by region, by type, and by application, allowing decision-makers to pinpoint where value creation is concentrated and where emerging pockets of demand are forming. Rather than exposing granular percentage splits in this preview, the full report delivers the precise regional revenue contributions and application-specific valuation profiles that procurement leaders, product managers, and investment analysts require to build robust market-entry or expansion strategies.
Competitive profiling within the study extends to a detailed examination of the top market participants, their strategic positioning, and the implications of recent innovations. The report evaluates how product launches from Sensirion, Bosch Sensortec, ScioSense, Renesas, Infineon, Amphenol, and Cubic Sensor and Instrument are reshaping performance expectations, power budgets, and form-factor constraints. By cross-referencing launch timelines with market demand signals, the analysis helps readers anticipate which corporate roadmaps will drive consolidation, which may open partnership opportunities, and where disruptor potential resides.
Additionally, the research integrates a critical assessment of industry dynamics, including tariff impacts, critical mineral supply risks, and environmental compliance cost trajectories. These factors are mapped against regional and segment-level demand profiles to identify the operating environments that will yield the most favorable risk-adjusted returns. The objective is to equip readers with a holistic view of the forces that will govern not only market size, but also profitability and long-term competitive resilience.
Positioning Your Organization for the Forecast Horizon
As the air quality sensor IC market advances toward the 2032 horizon, success will depend on the ability to interpret high-level growth signals with precision, align product roadmaps with evolving performance expectations, and navigate a supply environment that is increasingly sensitive to geopolitical and regulatory interventions. The structural expansion reflected in the forecast—a CAGR of 10.51 percent from 2026 through 2032—represents a meaningful opportunity, but it also intensifies competition for market share, talent, and preferred supply chain positioning.
This report is designed to convert that opportunity into executable strategy. By synthesizing historical performance, forward-looking projections, competitive intelligence, and macro-environmental analysis into a single cohesive narrative, it enables stakeholders to move beyond speculation and base their 2026 decisions on rigorously validated market intelligence. Whether the objective is to prioritize R&D investment, evaluate potential acquisition targets, optimize regional sales focus, or assess supply chain vulnerability, the study provides the structured insight necessary to act with confidence.
To access the complete segmentation data, full competitor profiles, detailed forecast tables, and region-specific strategic commentary, we invite you to consult the full Worldwide Air Quality Sensor ICs Market research report. The complete analysis delivers the granular revenue breakdowns, application-level valuation profiles, and competitive dynamics that will inform your most critical strategic choices throughout the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Air Quality Sensor ICs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Helical Spring Market Hits $3.12B in 2025, Projected to Reach $4.29B by 2032
By PW Consulting, 2026-09-17
Navigating the Automotive Helical Spring Market: Strategic Intelligence for 2026 Decision-Makers
Executive Overview
The automotive helical spring market stands at a critical inflection point as global original equipment manufacturers navigate simultaneous pressures from electrification, regulatory tightening, and supply chain realignment. Our latest Worldwide Automotive Helical Spring Market study provides a comprehensive, data-driven foundation for strategic planning through the end of the decade. Built on a rigorous historical baseline spanning 2020 through 2025 and extending forecast visibility to 2032, this intelligence asset translates complex market signals into actionable pathways for procurement leaders, product development teams, and competitive strategy executives. With the global market reaching approximately 3.12 billion USD in 2025 and projected to expand toward 4.29 billion USD by 2032, a compound annual growth rate of 4.65 percent shapes the trajectory that forward-looking organizations must navigate. The following analysis outlines the structural forces defining the sector, the competitive architecture shaping supplier relationships, and the operational dimensions that will separate resilient companies from those left behind. This is a trailer for a deeper intelligence asset. Complete segmentation breakdowns, regional revenue distributions, type-specific growth profiles, and company-by-company financial exposure metrics are available through the full report. Accessing the complete dataset ensures that your strategic planning rests on verified, granular intelligence rather than generalized industry narratives.
Macro Trajectory and Demand Architecture
Market expansion over the past half-decade reflects a sector recovering from post-pandemic supply disruptions while absorbing structural shifts in vehicle architecture. Revenue progression from 2.55 billion USD in 2020 through a brief contraction in 2021, followed by recovery and acceleration into 2025, illustrates the resilience of helical spring demand even amid semiconductor constraints, logistics bottlenecks, and raw material volatility. The forecast window extends steady growth across 2026 through 2032, with the market projected to nearly double its 2020 baseline by decade end. Several underlying demand vectors sustain this trajectory. Passenger vehicle production recovery in key Asian and European markets continues to anchor volume, while commercial fleet operators increasingly retrofit and maintain suspension systems to extend asset lifecycles. Light commercial vehicle deployments in urban logistics networks further stimulate replacement and OEM demand. Heavy commercial applications, though smaller in relative volume, contribute to baseline stability due to rigorous maintenance schedules and longer service intervals. The diversity of end-use demand across passenger cars, light commercial vehicles, and heavy commercial vehicles creates a portfolio effect that buffers individual segments against cyclical downturns. Understanding how these application streams interact with regional manufacturing footprints, cost structures, and supplier capabilities forms a central pillar of the full report. Readers seeking precise revenue allocations across application categories and regional markets will find detailed breakdowns in the complete study.
Competitive Architecture and Strategic Positioning
The competitive landscape reflects a concentrated yet fragmented structure where global specialists operate alongside regional cost-optimized manufacturers. Top-three concentration reaches approximately 38.45 percent, while the top five suppliers command roughly 52.6 percent of market revenue. This concentration level indicates meaningful scale advantages among leading players, yet leaves sufficient room for regional specialists to capture niche value through customization, localized service, and application-specific engineering. Japanese firms such as NHK Spring, Showa Corporation, and Chuo Spring maintain strong positions through advanced manufacturing, OEM relationships, and product integration expertise spanning passenger cars, trucks, and motorcycles. NHK Spring recently advanced its portfolio with a product launch in September 2025, introducing high-strength helical springs optimized for electric vehicle suspensions and lightweighting objectives. Showa Corporation completed durability testing validation in April 2025 for helical springs integrated into Honda hybrid vehicle lineups, reinforcing quality assurance narratives aligned with electrified powertrain requirements. Mubea Fahrwerke GmbH continues to strengthen its European OEM footprint, earning supplier nomination from BMW in June 2025 for helical torsion springs in next-generation chassis systems. Its affiliate Lesjöfors Springs extends spring manufacturing capabilities across Europe and Asia, supporting shock absorber and engine valve applications with broad geographic reach. Chinese manufacturers such as Zhejiang Changchun Spring and Huanyu Spring emphasize cost-effective high-volume production and custom helical compression solutions, leveraging steel alloy capabilities and export-oriented supply chains. Industrial Spring Inc. anchors North American heavy-duty truck suspension supply, serving a market segment where durability and load-bearing performance drive purchasing decisions. Competitive differentiation now extends beyond unit pricing. Lightweight design, fatigue resistance, corrosion mitigation, and supply chain responsiveness increasingly determine sourcing outcomes. The full report maps competitive positioning through revenue estimates, product scope, geographic coverage, and recent strategic moves, enabling procurement teams to benchmark supplier alternatives with precision.
Material, Regulatory, and Operational Dynamics Shaping Value Chains
Several interconnected external forces are reshaping how helical springs are specified, manufactured, and validated. Raw material conditions influence production economics and supplier margin structures. Automotive helical springs predominantly rely on SAE 5160 high-carbon spring steel, with prices experiencing fluctuations of 10 to 15 percent due to alloy scrap supply constraints. At the same time, silicon-manganese steel adoption has demonstrated significant corrosion reduction of approximately 30 percent in high-humidity regions, creating engineering incentives for material substitution where environmental exposure is elevated. Regulatory frameworks are also altering design priorities. Euro 7 emission standards mandate lighter suspension components, pushing development teams to redesign helical springs for around 20 percent weight reduction without compromising fatigue performance. These requirements directly impact geometry planning, material selection, and validation testing cycles. Safety standards add additional specification rigor, with FMVSS 209 requiring helical springs in seat belt retractors to withstand 5000 cycles at a 2000N load, reinforcing the importance of certified manufacturing controls and traceability. Labor economics further differentiate regional production strategies. Precision coiling operations require skilled labor, with US hourly rates near 28 USD compared with roughly 6 USD in China. This cost differential shapes make-versus-buy decisions, nearshoring evaluations, and automation investment pacing. Companies that integrate material strategy, compliance readiness, and labor optimization into a cohesive sourcing and design framework gain meaningful competitive advantage. The complete report translates these dynamics into scenario-based implications for procurement, product engineering, and regional capacity planning, with actionable guidance for managing volatility and capturing value from materials innovation.
What the Full Study Delivers
The Worldwide Automotive Helical Spring Market study is structured to support decision-making across multiple functional domains. It provides verified historical data, forward-looking forecasts, and multi-dimensional segmentation that connects market size with strategic interpretation. The analysis is organized to answer practical questions that leaders face when allocating capital, qualifying suppliers, and preparing for regulatory or technological transitions. Key deliverables include a complete market sizing framework covering the historical period and forecast horizon, with consistent methodology that supports trend analysis and benchmarking. Segmentation analysis examines market structure by region, type, and application, offering organizations the ability to align sourcing and product roadmaps with demand concentration patterns. Competitive profiling explores the strategies, geographic reach, product focus, and recent developments of leading suppliers, enabling structure-to-strategy comparisons for procurement and partnership evaluation. The study also integrates material and regulatory context so that engineering and compliance teams can assess how raw material trends and standard requirements influence cost, design, and validation timelines. Scenario interpretations translate data into operational guidance, highlighting where growth is likely to concentrate, where margin pressure may intensify, and where supplier diversification or vertical integration could improve resilience. This report is particularly valuable for organizations planning OEM negotiations, capacity investments, or entry into new application streams. It is designed for teams that need more than top-line estimates: they require structured intelligence that links market behavior to internal planning assumptions, risk registers, and strategic initiatives. Full access to the source data, including detailed regional and application breakdowns and type-level revenue distributions, ensures that decisions are grounded in a complete picture rather than partial indicators.
Worldwide Automotive Helical Spring Market
Strategic Takeaways for 2026 and Beyond
As organizations prepare for 2026 planning cycles, several strategic priorities emerge from the current market architecture. Supplier evaluation must extend beyond unit pricing to include lightweighting capability, fatigue and corrosion performance, compliance readiness, and geographic flexibility. Procurement strategies should assess how raw material volatility, particularly in high-carbon spring steel and alloy scrap availability, will affect cost forecasting and contract structuring. Engineering teams need to anticipate how regulatory pressure, especially around weight reduction and safety validation, will influence spring design, testing cycles, and qualification timelines. Competitive positioning will increasingly reward suppliers that can combine scale, precision manufacturing, and application-specific engineering with reliable delivery and regional responsiveness. Companies that treat the helical spring market as a static commodity segment risk underestimating the value of technical differentiation and supply resilience. Those that align sourcing, product development, and regulatory strategy with verified market intelligence will be better positioned to manage cost, performance, and risk through the forecast period. The full report converts these priorities into detailed benchmarks, regional demand maps, type-level growth outlines, and supplier profiles that support structured decision-making. Accessing the complete study provides the granularity necessary to validate assumptions, compare alternatives, and align cross-functional teams around a shared market view.
Automotive Leaf Spring Assembly Market
The Worldwide Automotive Helical Spring Market study is available now. Complete regional, type, and application breakdowns, supplier financial context, and scenario-based planning guidance are included in the full report. Download the complete intelligence package to equip your 2026 strategy with verified, presentation-ready market insights.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Helical Spring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


