



Category: market research
PW Consulting Forecasts IL-11 Market to Reach USD 848.2 Million by 2032 Amid Rising Biologic Demand
By PW Consulting, 2026-07-02
PW Consulting Releases Strategic Brief: Interleukin‑11 (IL‑11) Market Outlook — Actionable Intelligence for 2026 Decision‑Makers
PW Consulting today publishes an executive briefing accompanying our full Interleukin‑11 (IL‑11) Market Report (Base Year: 2025; Forecast Period: 2026–2032). The briefing distills the strategic imperatives that will define commercial and R&D choices in 2026, synthesizing macro market dynamics, competitive positioning, regulatory context, and practical playbooks that senior teams need as IL‑11 moves from a predominantly research reagent into a contested translational frontier.
Interleukin-11 (IL-11) Market
Headline Market Signals — Size, Trajectory, and Timing
Our firm’s updated market model shows the global IL‑11 market has expanded consistently through 2020–2025, rising from roughly USD 385 million in 2020 to an estimated USD 495 million in 2025 (USD, Million). Looking forward, we project continued growth through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 8.01%, reaching an estimated total market value in the high hundreds of millions by 2032.
Interleukin-11 (IL-11) Market
Two points matter for corporate planners in 2026: first, the market is at an inflection where clinical activity (notably IL‑11 pathway inhibitors) is increasing the demand for both high‑quality research reagents and transferrable translational assays; second, steady baseline growth in reagent and preclinical demand ensures commercial opportunity even before therapeutic approvals — making 2026 a pivotal year to lock supply chains, secure commercial partnerships, and shape regulatory strategy.
Interleukin-11 (IL-11) Market
Why IL‑11 Is Strategically Important Now
- Translational momentum: IL‑11 biology sits at the intersection of oncology supportive care (e.g., chemotherapy‑induced thrombocytopenia), fibrosis research, and cardiometabolic/renal pathophysiology. Ongoing clinical trials of IL‑11 inhibitors escalate the strategic value of upstream reagent and biomarker platforms.
- Supply‑side differentiation: Manufacturers compete on purity, bioactivity validation, expression systems (E. coli, mammalian, animal‑free), and formats (carrier‑free, lyophilized). These technical attributes drive buyer preference among research institutions and early translational units.
- Regulatory boundary conditions: Native IL‑11 remains a research‑only product in major jurisdictions; it is not approved by FDA or EMA for therapeutic use, and commercial products are sold explicitly for research use only. This regulatory reality shapes go‑to‑market options and claims architecture for suppliers and partners.
What the PW Consulting Report Delivers — Practical, Transaction‑Ready Content
The full IL‑11 Market Report is designed as a working tool for corporate strategy, BD, and product teams. Key deliverables include:
- Robust market sizing and forecasting (historical 2020–2025; forecast 2026–2032), with scenario sensitivity to clinical readouts and reagent adoption curves.
- Pipeline and clinical trial tracker for IL‑11 pathway inhibitors, mapped to anticipated data readouts and likely commercialization windows.
- Supply‑chain and manufacturing audit: formats, expression platforms, lot consistency practices, and supplier risk heat maps.
- Competitive benchmarking with product‑level feature comparisons, validated bioactivity claims, and recommended supplier selection criteria for translational programs.
- Regulatory and compliance playbook: positioning research products while preserving freedom to operate as therapeutic programs mature.
- Commercial go‑to‑market playbooks: licensing, co‑development, and channel strategies tailored to reagent suppliers, CROs, and clinical‑stage biotechs.
- Commercial diligence appendices for M&A and partnership teams, including due‑diligence templates and premium/discount levers tied to technical differentiation.
Competitive Landscape — Who Matters Today
The IL‑11 reagent niche is served by a small set of established life‑science suppliers who together shape quality expectations and distribution norms. Our report contains vendor profiles and tactical guidance for engaging each supplier. Key names to watch include:
- Sino Biological (Beijing, China) — Recognized for high‑purity recombinant human IL‑11 supplied in multiple formats (carrier‑free and lyophilized) and widely used across translational labs.
- R&D Systems (Bio‑Techne) (Minneapolis, MN, USA) — Offers recombinant IL‑11 with emphasis on lot‑specific activity testing and bioactivity characterization used by assay developers.
- PeproTech (Thermo Fisher Scientific) (Cranbury, NJ, USA) — Markets animal‑free recombinant IL‑11 variants aimed at in‑vitro consistency across lots, attractive to certain regulatory‑sensitive customers.
- MedChemExpress (Monmouth Junction, NJ, USA) — Positions its IL‑11 products with detailed bioactivity data and user‑facing storage/handling guidance for laboratory adoption.
- ProSpec (Ness Ziona, Israel) — Produces recombinant IL‑11 expressed in E. coli, serving cytokine research workflows with a cost/throughput emphasis.
For buyers and potential partners, supplier selection is no longer a commodity decision — differentiation in bioactivity validation, format options, and documentation can materially affect translational reproducibility and downstream clinical assays.
Regulatory and Clinical Dynamics You Must Factor Into 2026 Plans
- Regulatory posture: IL‑11 reagents are marketed as research‑only and cannot be promoted for diagnostic or therapeutic use. This constraint affects labeling, claims, and commercial narratives; firms should have compliant marketing and QA processes in place.
- Clinical catalyst risk/reward: Several anti‑IL‑11 antibodies and inhibitors are in clinical trials for fibrotic diseases. Positive clinical readouts could accelerate translational reagent demand and create licensing opportunities for companion diagnostics; negative readouts would slow the premium market expansion but leave a resilient baseline of academic and preclinical demand.
- Quality and reproducibility: Buyers increasingly demand lot‑level activity data and stability testing; suppliers that invest in robust QC will command pricing premiums and preferred supplier status with translational programs.
Strategic Implications and Recommended 2026 Actions
For executives considering commercial entry, partnership, or investment in IL‑11 reagents or therapeutics, PW Consulting recommends a prioritized set of actions for 2026:
- Lock core supplies: Secure multi‑year supply agreements with at least two qualified vendors to protect against lot failures and geopolitical disruption.
- Differentiate on data: If you are a supplier, invest in lot‑specific bioactivity testing and documentation; if you are a buyer, insist on these data in contracts to protect translational validity.
- Map trial timelines to commercial plans: Align commercial launches and inventory strategies with projected clinical readouts from IL‑11 inhibitor programs; treat these readouts as demand inflection points.
- Pursue targeted partnerships: Biotechnology firms developing IL‑11 pathway therapeutics should fast‑track agreements with reagent suppliers for early access to translational materials and co‑development of biomarkers.
- Prepare regulatory transition pathways: For organizations contemplating movement from reagent supply to diagnostic or therapeutic claim, build cross‑functional regulatory plans now — including CMC scale‑up and documentation upgrades — while the product remains research‑only.
- Use M&A as an accelerant: For incumbents seeking rapid access to differentiated manufacturing capabilities (animal‑free expression, GMP‑capable lines), prioritize tuck‑ins that shorten time‑to‑clinic.
- Quantify pricing elasticity: Build pricing models that reflect willingness to pay for validated bioactivity and traceability; this will be critical in negotiating supply and service contracts.
How PW Consulting’s Report Supports 2026 Decision Cycles
The full PW Consulting IL‑11 Market Report is structured to be immediately actionable for quarterly and annual planning cycles. It combines a live‑data model with scenario modules so teams can stress‑test strategies against alternate clinical outcomes, supply shocks, and regulatory changes. Our deliverables are intentionally operational: procurement scorecards, BD outreach templates, and a dossier for technical due diligence — not just high‑level slides.
Critically, the report provides granular, proprietary segmentation and pricing matrices that convert the headline market trajectory into line‑item P&L impacts for business cases and M&A underwriting. To preserve the strategic value of that detail in this public briefing, core segment‑level breakdowns and supplier revenue shares are available exclusively in the full report and accompanying datasets.
Limitations, Risks, and the Path Forward
- Market sensitivity to clinical outcomes: The pace and direction of growth are contingent on clinical developments for IL‑11 pathway inhibitors; teams should treat forecasts as scenario‑driven rather than deterministic.
- Regulatory constraints on claims and use: Ongoing vigilance is required to ensure marketing and distribution remain compliant with research‑only designations until or unless regulatory status changes.
- Data quality and reproducibility: Variability across expression systems and lots is a real operational risk; institutional buyers must institutionalize QC gates to de‑risk translational projects.
Next Steps — Accessing the Full Intelligence
PW Consulting’s IL‑11 Market Report (Base Year 2025; Forecast 2026–2032; currency USD, revenue unit: Million) is available now for organizations planning investments, partnerships, or market entry in 2026. The full report contains the segment‑level forecasts, supplier revenue matrices, and model workbooks that underpin the strategic recommendations summarized here. To obtain the comprehensive report, datasets, and a tailored briefing for your executive team, please visit the PW Consulting website or contact our research desk to schedule a briefing.
As IL‑11 moves from bench biology toward clinical decision points, 2026 will separate teams that merely observe from those that shape the market. PW Consulting’s analysis is designed to make your 2026 choices deliberate, defensible, and timed to the market’s forthcoming inflection points.
For detailed analysis of this topic, please visit the official page: Interleukin-11 (IL-11) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ethyl Phenyl Acetate Market to Grow from USD 54.5 Million (Base Year 2025) to USD 76.43 Million by 2032 at a 4.95% CAGR — Asia Pacific Leads with USD 21.67M
By PW Consulting, 2026-07-02
Ethyl Phenyl Acetate Market — 2026 Strategic Brief
PW Consulting’s latest market research release on Ethyl Phenyl Acetate (EPA) frames a precise, execution-oriented perspective for corporate decision-makers planning for 2026 and beyond. Our base-year analysis shows a global market that reached approximately USD 54.5 Million in 2025 and, under our central scenario, will expand at a compound annual growth rate (CAGR) of 4.95% through the 2026–2032 forecast window. By 2032 the market is projected to approach the mid-to-high seventies in million-dollar scale—evidence of steady, structurally supported growth rather than a short-term spike.
Ethyl Phenyl Acetate Market
Why this report is strategically valuable for 2026 decisions
- Translates macro trends into board-level choices: capital allocation, M&A screening, and product roadmap prioritization for fragrance, flavor, cosmetics, and pharmaceutical-intermediate portfolios.
- Delivers executable supply‑chain playbooks that reconcile raw-material risk with quality and regulatory requirements important to global customers and retail brands.
- Provides a decision-support toolkit: scenario-ready financial models, plant economics, supplier scorecards, and a regulatory compliance checklist tailored to ethyl phenyl acetate value chains.
Market dynamics — what executives must internalize
Three structural forces define the EPA landscape in 2026:
Ethyl Phenyl Acetate Market
- Feedstock intensity. Production economics are steeply dependent on phenylacetic acid and ethanol. Our cost-model benchmarking shows raw materials account for the lion’s share of operating expense in EPA manufacture—typically a large majority of direct production cost—making feedstock procurement the primary lever for margin management.
- Regulatory overlay. Phenylacetic acid is regulated in several jurisdictions as a controlled precursor because of diversion risks. In the United States, for example, it is listed under regulatory frameworks that demand enhanced customer vetting, record-keeping and, in some cases, licensing for handling and shipment. That compliance burden raises both direct costs and operational friction for manufacturers and distributors.
- Market concentration and supplier footprints. The EPA supply base blends multinational aroma and flavor houses, regional producers in Asia and India, and specialty natural‑ingredient suppliers. Market concentration metrics indicate a mid‑level aggregation—enough to create strategic corridors for price and quality leadership, yet sufficiently fragmented to enable agile entrants and contract manufacturers to capture niches.
What the report contains — practical outputs, not just insight
This is intentionally a practitioner’s dossier. Highlights include:
Ethyl Phenyl Acetate Market
- A calibrated market model (2020–2032) with scenario toggles for faster/slower demand, feedstock shocks, and regulatory tightening—designed to be used directly in financial planning sessions.
- End-to-end cost build-ups and a plant economics module based on industry-grade outputs. The model supports sizing runs from small-scale tolling to multi-thousand-tonne annual facilities and includes sensitivity to phenylacetic acid pricing, yield variation, and utility cost assumptions.
- Supplier mapping and an actionable due-diligence checklist that captures technical capabilities, certification footprints (e.g., Kosher/Halal, FCC/Food Grade, GC purity), and logistics resiliency scores.
- A compliance & controls playbook for handling regulated feedstocks—covering customer screening, record retention, audit triggers and international transport considerations.
- A go-to-market and procurement playbook for both buyers and sellers: contract structures (pricing collars, indexation clauses), specification hedges, and co-development frameworks for natural vs. synthetic variants.
- An M&A screening matrix and a prioritized short-list of acquisition/joint-venture archetypes that deliver vertical capture, geographic access, or specialty-grade differentiation.
Competitive landscape — how to read supplier intent and capability
The supplier universe for EPA can be segmented by strategic position rather than by raw market share alone:
- Global aroma and flavors majors — firms with broad formulation portfolios and integrated regulatory/commercial teams. These players compete on specification breadth, global logistics, and integrated customer service for fragrance and flavor houses.
- Regional manufacturers and distributors — lower-cost producers and worldwide distributors that supply technical and industrial grades, often serving regional blends, contract manufacturing, and local flavor houses.
- Specialty natural and isolate suppliers — firms that offer natural-label variants, Kosher-certified natural isolates, and niche cosmetic-grade materials that command a price premium in premium personal-care and natural-food markets.
Representative vendors profiled in our study include a mixture of each archetype: global specialty-chemicals houses and aroma majors that provide high-purity and branded aroma molecules; regional and contract producers with scale in Asia and India; and small-to-midsize specialists focused on natural isolates and cosmetic-grade material supply. Our benchmarking assesses each firm on production capability, certification & compliance posture, quality control, and customer-service KPIs—enabling buyers to craft dual-source and strategic-supplier relationships aligned to their risk appetite.
Recent developments that alter the 2026 playing field
- Plant-scale feasibility content has become more operationally tangible: a recent plant project report (March 2026) provides a template for 1,000–3,000 MT/yr setups, with capex and opex reference models. That work is directly integrated into our plant economics module to help firms evaluate near-term backward integration versus long-term off-take agreements.
- Phenylacetic acid supply and pricing: global production and pricing dynamics in 2025 crystallize the feedstock base. Firms that misjudge feedstock sourcing risk sudden margin compression; those that lock-in diversified sources and hedging strategies preserve negotiating flexibility.
- Heightened control measures for precursor chemicals are driving demand for enhanced compliance automation—buyers are increasingly favoring suppliers that demonstrate institutionalized customer-vetting, traceability, and audited logistics partners.
Opportunities and principal risks to weigh in 2026
- Opportunities:
- Premiumization and naturalization trends in fragrances and flavors create demand for high-purity and natural-label EPA variants.
- Contract manufacturing and tolling models present attractive near-term routes to secure supply without full-capex exposure.
- Targeted backward integration can be accretive where feedstock access and regulatory compliance can be internalized at scale.
- Risks:
- Regulatory tightening around precursor chemicals increases compliance cost and can slow time-to-market for new contracts.
- Feedstock price volatility—given its dominant share of production cost—can swiftly erode realized margins absent indexation or hedging clauses in contracts.
- Geo‑logistical and trade disruptions in major producing regions can exacerbate short-term supply tightness.
90‑day executive action plan
- Run the report’s sensitivity module against your current procurement book to quantify EBITDA exposure to a range of phenylacetic acid price scenarios; decide whether to adopt collars, forwards, or strategic storage.
- Complete a supplier audit focused on compliance credentials for regulated feedstocks—prioritize counterparty upgrades where KYC or recordkeeping gaps exist.
- Initiate a cost‑to‑build quick scan using the embedded plant economics module if vertical integration is on the strategic table; use the 1,000–3,000 MT/yr template as a reference starting point.
- Establish dual-sourcing agreements split by grade and certification (industrial vs. food/fragrance/cosmetic) to mitigate single-point-of-failure risks without sacrificing quality alignment.
- Prioritize M&A or JV targets from the report’s screening matrix for near-term bolt-on acquisitions that deliver feedstock security, regional access, or specialty-grade capabilities.
PW Consulting’s Ethyl Phenyl Acetate Market report is designed as a strategic instrument—combining market sizing, regulatory intelligence, supplier benchmarking, and hands-on financial tools—to move teams from diagnosis to decisive action in 2026. For practitioners seeking the granular segmentation, proprietary scenario outputs, and downloadable models referenced here, the full dossier and interactive workbooks are available through our report portal. PW Consulting stands ready to support tailored workshops, integration due diligence, and bespoke cost-model customization to convert this intelligence into measurable commercial advantage.
For detailed analysis of this topic, please visit the official page: Ethyl Phenyl Acetate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Client Portal Software Market Tops USD 2.19 Billion in 2025, Poised to Expand at a 14.28% CAGR Through 2032
By PW Consulting, 2026-07-02
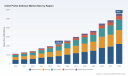
Client Portal Software Market 2026: Strategic Preview from PW Consulting
Executive summary
PW Consulting’s latest market research on Client Portal Software provides a focused, action-oriented roadmap for enterprise decision-makers preparing for 2026 procurement and transformation cycles. The market is maturing rapidly: after a period of accelerated adoption during 2020–2025, our base-year 2025 sizing indicates a market in excess of USD 2.18 billion (USD Million). Under our central forecast the sector continues to expand at a compound annual growth rate of 14.28% through 2032, approaching roughly USD 5.57 billion by the end of the forecast window.
Client Portal Software Market
This briefing highlights the strategic imperatives exposed by the study—where to invest, which vendor archetypes to prioritize, and how to structure TCO, compliance and deployment decisions for 2026—while reserving detailed subsegment metrics and vendor-level share tables for the full report available on our client portal.
Client Portal Software Market
Why this matters in 2026: the decision context
-
Strategic timing: 2026 is the year many enterprises codify post-pandemic service models. Client portals are no longer “nice-to-have” customer conveniences; they are operational backbones for secure collaboration, billing, case management and compliance. The forecast trajectory outlined above means procurement windows and capital plans made in 2026 will determine platform lock-in across the most favorable phase of market expansion.
Client Portal Software Market -
Build vs buy calculus: Rapid vendor feature innovation (AI-driven personalization, low-code page builders, integrated identity stacks) compresses differentiation among categories, changing the ROI math for in‑house builds. Our report provides a structured decision framework to test build-versus-buy hypotheses against TCO, time-to-value and compliance risk.
-
Negotiation leverage: Overall growth masks a fragmented supplier landscape. Leading vendors do not yet control an overwhelming share of the market, which preserves negotiating leverage for strategic buyers with clear procurement playbooks.
Key market dynamics and implications
-
Platform convergence and low-code acceleration: Major cloud and CRM providers are embedding portal capabilities into broader experience suites and low-code page builders. Expect purchasing decisions to be increasingly influenced by existing CRM or ERP footprints and by the vendor’s AI & automation roadmap.
-
Cost composition is shifting: Hosting discounts at scale (e.g., recent reductions in sustained-use instance pricing) and rising API/SSO licensing costs are creating divergent cost curves between platform-led and integration-led implementations. Our TCO models show that hosting savings alone do not offset API and identity licensing unless integration volumes are optimized.
-
Compliance as a primary driver: Privacy and audit requirements—GDPR pseudonymization expectations and SOC 2 Type II for financial data—are material design constraints. Compliance readiness influences vendor shortlists and time-to-production, especially for customer segments handling regulated data.
-
Talent & customization costs: High developer salary baselines and demand for specialist skills (security, API orchestration, identity management) increase the effective cost of bespoke portals. Buyers should quantify the premium for customization vs. adopting configurable vendor platforms.
Competitive landscape: what the major players are doing
The vendor universe ranges from CRM incumbents to vertical specialists and open‑source platforms. The market’s fragmentation persists: the combined share of the leading three suppliers is modest and the top five together capture well under one-third of total market revenue—conditions that favor a differentiated sourcing strategy rather than a single-vendor bet.
-
Salesforce — Experience and ecosystem strength: Salesforce’s Experience Cloud continues to evolve toward AI-driven personalization and deep CRM integration. Its recent enhancements position it as a default choice for enterprises prioritizing extensibility, single-vendor experience stacks, and ecosystem-driven accelerators.
-
Microsoft — Low-code and AI in the stack: Microsoft’s integration of Copilot into Power Pages and Dynamics portals lowers the bar for intelligent search and automation inside client portals, making it attractive to organizations with large Microsoft estates seeking rapid deployment and unified identity.
-
HubSpot, Zendesk, Freshworks — Mid-market and service specialization: These vendors compete on simplicity, integrated ticketing, and packaged workflows. Recent partnerships and product updates emphasize ease of use and ecosystem connectivity, appealing to mid-market service organizations.
-
Zoho & Odoo — Cost-effective integrated suites: Product updates that expand mobile support and e-signature, combined with an integrated ERP/CRM posture, make these suites compelling for organizations seeking predictable pricing and broad functional coverage with less heavy customization.
-
Vertical specialists (Clio, AppFolio, Practice Ignition) — Domain depth: Vendors focused on legal, property management, and accounting deliver deep, out-of-the-box workflows and compliance mapping, reducing integration effort for regulated use-cases.
-
Niche and open-source alternatives (Bitrix24, SugarCRM, Citrix ShareFile) — Flexibility and control: These providers are often chosen where data sovereignty, white-labeling, or bespoke automation is central; they require more integration effort but offer pricing and architectural flexibility.
Recent product moves that change vendor evaluation
-
Salesforce (Sept 2024): AI-driven personalization features expand the value of experience layers, shifting buyer focus to AI governance and data strategy.
-
Microsoft (June 2024): Copilot integration into Power Pages makes intelligent search and automation a checkbox in low-code scenarios.
-
HubSpot (Apr 2024): Workspace partnerships reduce friction for file sync; useful for document-heavy workflows.
-
Zoho (Mar 2024) and ServiceNow (Feb 2024): Mobile-first portal updates and enhanced analytics respectively lower go-live risk for client engagement and measurement.
What PW Consulting’s full report delivers (selected practical tools)
-
Decision frameworks to evaluate build vs buy, including sensitivity analysis on developer wages, identity licensing, and hosting costs.
-
Vendor archetype matrix and procurement playbooks tailored to enterprise, mid-market and regulated verticals (with anonymized scorecards and customization risk flags).
-
Implementation blueprints: phased migration roadmaps, RFP templates, acceptance test suites, and a vendor negotiation checklist that quantifies migration levers.
-
Compliance mapping: practical controls map for GDPR pseudonymization, SOC 2 alignment, and cross-border data flows—aligned to technical design patterns.
-
TCO and ROI models (interactive): hosting scenarios, API call cost sensitivity (including identity/SAML/SSO pricing assumptions), licensing comparators and break-even timelines for customization vs configuration.
-
Benchmarks and KPIs: standardized portal engagement metrics, SLA templates, and vendor performance baselines for security, uptime, and feature velocity.
Strategic recommendations for enterprise leaders in 2026
-
Start with compliance-first architecture. Map data flows and apply pseudonymization and encryption controls at design time—do not defer privacy controls to later sprints. For regulated lines of business, insist on audited SOC 2 Type II evidence before pilot sign-off.
-
Quantify identity costs early. SSO/API licensing can materially shift TCO; model Okta‑style per-user costs and realistic authentication volumes in procurement scenarios.
-
Use a vendor archetype approach to shortlisting. Separate vendors that win on ecosystem integration, low-code velocity, vertical depth, and cost flexibility, then match archetypes to your operational priorities.
-
Favor modular pilots with measurable KPIs. Validate automation, document workflows and AI search in a single line-of-business before full rollout to reduce rework and customization expense.
-
Lock in migration and exit terms. Given the market’s fast pace of feature change, contractually codify data exports, APIs, and portability clauses to protect against vendor lock-in.
-
Revisit resourcing assumptions. If customization is required, budget for specialist engineers and security resources; the current labor market materially increases the cost of bespoke builds.
How to use this preview
This release is intended as a strategic preview: it highlights the market trajectory, competitive behaviors and the practical levers procurement and product leaders should prioritize in 2026. The full PW Consulting Client Portal Software Market Report contains the granular subsegment breakdowns, regional and vertical splits, vendor scorecards, and the interactive TCO models and RFP templates referenced above. Those datasets are intentionally reserved for the full report and the client portal to preserve the actionable advantage for subscribers.
Next steps
If you are preparing a 2026 roadmap—whether deciding between upgrading an incumbent portal, adopting a packaged vendor solution, or building in-house—PW Consulting can provide a tailored briefing that applies our models to your estate and use-cases. Our diagnostics will map vendor fit, compliance gaps, and a 12–24 month implementation plan that aligns with your capital cycles and operational targets.
PW Consulting’s projections and playbooks aim to convert market-scale opportunity into executable decisions. The client portal market’s high growth and fragmented vendor base create windows for strategic buyers to secure favorable commercial terms, accelerate digital services, and reduce long-term TCO—if they act with a compliance-aware, identity-centered, and vendor-archetype driven strategy. For the full dataset, model access, and vendor scorecards, please consult the complete report on the PW Consulting client portal.
For detailed analysis of this topic, please visit the official page: Client Portal Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Cartridge Systems Market Poised to Grow at a 5.04% CAGR Through 2032
By PW Consulting, 2026-07-02
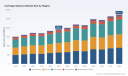
Cartridge Systems Market: Strategic Imperatives for 2026—A PW Consulting Preview
PW Consulting’s latest industry brief on the global Cartridge Systems Market synthesizes multi-year market dynamics, supplier positioning, commodity pressures, and technological inflection points to deliver actionable intelligence for executives planning 2026 strategies. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study combines rigorous quantitative modeling with playbook-style recommendations to help C-suite and business unit leaders prioritize investments, mitigate risks, and capture growth across pharmaceutical, industrial, and specialty applications.
Cartridge Systems Market
Market trajectory at a glance
The cartridge systems market has expanded steadily since 2020, recovering from pandemic-era distortions and evolving through incremental product and process innovation. PW Consulting’s modeling shows a market base just under USD 2.0 billion in 2025, and a continued expansion through the forecast window to exceed USD 2.7 billion by 2032. The implied compound annual growth rate for the 2026–2032 forecast period is 5.04%, reflecting a balance of demand drivers across injectable primary packaging, industrial dispensing, and specialty two‑component systems.
Cartridge Systems Market
Noteworthy in the historical series is a phase of volatility rather than secular decline—periods of modest contraction interspersed with renewed expansion—underscoring the sensitivity of cartridge demand to end‑market cycles (pharma launches, construction activity, electronics assembly) and to raw material and processing bottlenecks. That pattern both creates risk and opens tactical windows for incumbents and newcomers who can time capacity, pricing, and innovation correctly.
Cartridge Systems Market
Why this report matters for 2026 decision-making
- Precision under uncertainty: The report translates top-line projections into operational levers—capacity timing, fill/finish automation investment thresholds, and sourcing alternatives—so executives can convert market forecasts into capital and procurement decisions timed to 2026 budget cycles.
- Cost-to-competitiveness mapping: We quantify the seat‑of‑the‑pants impact of raw material swings on unit economics and provide hedging and specification-change scenarios that preserve margin even under sustained resin or elastomer price pressure.
- Regulatory and sustainability readiness: As sustainability requirements become procurement prerequisites—especially in pharma and large industrial OEMs—the report lays out compliance pathways and cost-to-benefit tradeoffs for recycled content, paper-based substrates, and RTU (ready-to-use) formats.
- Dealflow and partnership playbook: The intelligence package includes screens for M&A and JV targets, integration checklists, and commercial due-diligence templates tailored to cartridge-related assets and adjacent packaging capabilities.
Core strategic implications
- Portfolio calibration: Firms should prioritize modular product lines that allow flexible transitions between single-component dispensing and multi-component systems; the report helps identify break-even points where investments in 2K capability or RTU filling deliver disproportionate commercial returns.
- Supply-chain resilience: With plastics PPI and regional resin price differentials creating uneven cost pressure, the practical guidance recommends dual-sourcing strategies, regional inventory buffers, and selective onshoring of critical components to maintain service levels while controlling landed cost.
- Sustainability as a revenue lever: Early movers on PCR/PIR usage, paper-based formats, and low‑carbon supply chains are better positioned to win contracts from sustainability-driven procurement organizations; our scenarios quantify payback windows for such investments under realistic purchase timelines.
- Service and integration: Beyond the component sale, offering RTU filling, sterilization partnerships, or integrated dispensing systems materially increases customer stickiness—our commercial models show how service bundling lifts lifetime value.
Competitive landscape—what the leading players are signaling
The competitive geometry of the cartridge systems market includes legacy pharmaceutical glass specialists, industrial-dispensing innovators, and packaging incumbents expanding into adjacent niches. Market leadership is distributed: a small group of global manufacturers exert meaningful influence over standards and high‑value accounts, while a broader set of regional and specialty suppliers compete on price, customization, or service.
- Stevanato Group (Piombino Dese, Italy): A long-established leader in pharmaceutical glass cartridge systems and parenteral packaging. Stevanato’s decades of glass expertise and investments in drug-delivery formats (including pen and auto-injectors) position it as the primary reference for biologics and high-value drugs. For competitors, collaboration or differentiation will be required—either by targeting non‑sterile industrial applications or by offering superior RTU and secondary packaging solutions.
- SCHOTT AG (Mainz, Germany): A supplier with strong credentials in sterile containment and high-quality primary packaging. SCHOTT’s emphasis on containment and material science makes it a preferred partner for complex biologics; strategy for challengers should focus on niche differentiation (e.g., sustainability, rapid prototyping, or price performance for high-volume industrial uses).
- West Pharmaceutical Services (Exton, Pennsylvania, USA): Strong in containment systems, elastomers, and integrated delivery solutions. West’s systems-oriented approach highlights the commercial premium for end-to-end compatibility and validated supply chains; rivals can compete by offering lower TCO through onshore manufacturing and faster regulatory support.
- Gerresheimer AG (Düsseldorf, Germany): A hybrid player providing both glass and plastic cartridge options, enabling cross‑sell into existing pharma packaging relationships. Their strategy suggests consolidation benefits for players who own both primary packaging and dispensing technologies.
- Nordson EFD (East Providence, Rhode Island, USA): Focused on industrial fluid dispensing, Nordson competes on dispensing precision, ergonomics, and automation-friendly designs—principles that will increasingly matter for high-mix electronics and adhesives applications.
- Sulzer / medmix (Winterthur, Switzerland): Known for two-component Mixpac systems and sustainable greenLine offerings, medmix demonstrates how recycled plastics and circularity claims can be integrated without sacrificing performance—an instructive playbook for incumbents and new entrants alike.
- Fischbach GmbH, AptarGroup, Nipro Corporation, Syntegon and other specialists: These firms round out a landscape of capability—filling technologies, plungers/nozzles, dispensing components, and RTU production lines—creating an ecosystem where partnerships and co‑development accelerate route-to-market.
Dynamics shaping 2026 procurement and innovation choices
Three macro drivers will determine winners and losers next year:
- Raw material price volatility and regional differentials. Recent industry data show meaningful differences in polymer pricing across geographies and feedstocks, generating pressure on manufacturers with tightly integrated, single-source resin exposure. PW Consulting’s scenario analysis models the impact of resin price shifts on SKU profitability and recommends tactical contract structures and targeted conversion to lower-cost polymers where compatibility permits.
- Sustainability and circular-material initiatives. Product launches and pilot programs from OEMs and converters—including paper-based cartridge concepts and PCR/PIR resin platforms—are moving from proof-of-concept toward commercial trials. Manufacturers that can certify lower-carbon options while preserving functional performance will open procurement gates in regulated categories.
- Service and automation. Demand for RTU formats, validated filling, and integrated dispensing systems increases procurement preference for suppliers that minimize customer validation burden. Investments in filling automation or partnerships with RTU-specialists reduce time-to-market for pharma customers and provide defensible margins.
What PW Consulting’s full report delivers (practical, executable content)
- Top‑down and bottom‑up market sizing with sensitivity scenarios for commodity and regulatory shocks.
- Supply‑chain mapping and raw‑material exposure matrix with recommended hedging and specification pathways.
- Company profiles with strategic SWOTs, capability matrices, and potential alliance maps for the leading manufacturers and equipment suppliers.
- Go‑to‑market playbooks for incumbent manufacturers, private equity investors, and new entrants—covering product positioning, channel strategies, and pricing architecture.
- M&A screening tools and integration checklists tuned for cartridge-related assets (manufacturing, filling, and assembly operations).
- Regulatory and sustainability readiness checklist tying product choices to procurement thresholds in pharma and industrial sectors.
Recent industry signals—innovation and competitive moves
The market is already responding to sustainability and material innovation signals. Notable public moves include commercial introductions of paper-based cartridges aimed at adhesive and sealant use-cases, and trade events highlighting nitrocellulose‑free inks and printing technologies relevant to cartridge decoration and traceability. Separately, suppliers are commercializing recycled-plastic cartridge systems to lower lifecycle emissions while maintaining dispensing performance. These developments underscore two practical takeaways: (1) product innovation cycles are shortening; and (2) sustainability is shifting from “nice to have” to procurement criterion.
Recommendations for 2026 action
- Immediate (Q1–Q2 2026): Finalize sourcing contracts with polymer suppliers incorporating flexibility clauses; prioritize investments in validated RTU partnerships for regulated customers.
- Medium term (2026 planning horizon): Pilot low-carbon or recycled-content SKU lines with anchor customers to secure early revenue premiums and capture learnings ahead of tighter regulatory expectations.
- Strategic (18–36 months): Evaluate acquisitions or JVs that pair dispensing hardware with filling/sterilization capabilities to create integrated value propositions that raise switching costs for customers.
Conclusion and access to full intelligence
For executives charting 2026 priorities, the cartridge systems market presents a clear mix of steady growth and strategic inflection points. The market’s expansion trajectory is material—approaching a multi‑billion dollar opportunity over the next decade—yet the winners will be those who convert top‑line growth into defensible margin via materials strategy, service integration, and timely capability investments.
PW Consulting’s full Cartridge Systems Market report provides the granular segmentation, competitive scorecards, and financial models needed to operationalize the recommendations summarized here. To obtain the comprehensive dataset, company-by-company profiles, and the scenario toolset referenced in this preview, visit the official report page.
For detailed analysis of this topic, please visit the official page: Cartridge Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Smart Transmitter Market Poised to Expand at a 5.4% CAGR Through 2032
By PW Consulting, 2026-07-02
Smart Transmitter Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As industrial automation accelerates toward higher degrees of digitalization, the smart transmitter market emerges as a critical enabler of safer, more efficient, and more resilient operations. PW Consulting’s forthcoming Smart Transmitter Market report—anchored on a 2025 base year and a 2026–2032 forecast horizon—delivers an actionable intelligence package designed to shape capital allocation, vendor strategy, and product roadmaps for the 2026 decision cycle.
Smart Transmitter Market
Why 2026 is a Pivotal Year for Decision-Makers
After steady expansion through the early 2020s, the global smart transmitter market is positioned for continued, mid-single-digit growth. Our model, calibrated against historical performance through 2025, assesses the market’s structural drivers and projects the trajectory across the forecast period. With an enterprise-level compound annual growth rate (CAGR) of approximately 5.4% from 2026 onward, the market’s scale and momentum will materially influence procurement windows, R&D timing, and M&A windows in 2026. For C-level executives and portfolio managers, the report translates this macro trajectory into timelines for capital deployment and technology refresh cycles.
Smart Transmitter Market
What the Report Contains — Practical, Decision-Ready Content
This report goes beyond headline figures. It is organized to support strategic and operational decisions with granular tools and executable guidance while preserving commercial sensitivity where appropriate. Key practical deliverables include:
Smart Transmitter Market
- Market sizing and directional growth drivers at the market level (base year 2025), with a scenario suite that tests demand elasticity under alternate macro and regulatory outcomes for 2026–2032.
- Supply-chain heatmaps and a risk register that quantify lead-time exposure, critical component bottlenecks (including semiconductor availability), and mitigation options such as dual-sourcing, contract hedging, and onshore buffer strategies.
- Vendor performance scorecards that benchmark product portfolios on digital features, diagnostics, interoperability standards support, and service economics—designed for quick shortlisting in procurement RFx processes.
- Go-to-market playbooks for both incumbent manufacturers and new entrants, with tailored commercial models (capex vs. opex, subscription-based services, and lifecycle services) and channel strategies for 2026 rollout plans.
- Regulatory and standards impact analysis with compliance timelines and an implementation checklist—essential for engineering, QA, and procurement teams planning 2026 upgrades.
- Financial decision tools including TCO models, payback calculators for IIoT-enabled retrofits, and M&A screening matrices to prioritize targets by strategic fit and accretive potential.
Market Structure and Competitive Dynamics — What to Watch
The market shows a moderate degree of concentration: a cluster of established multinational instrument and automation suppliers holds a material share of global revenues. This concentration creates both stability in technology roadmaps and competitive windows for specialized players to capture differentiated segments through verticalization or regional service excellence.
Key competitive observations:
- Legacy automation and instrumentation leaders continue to consolidate value by integrating smart transmitters into broader digital-plant platforms. Their advantages include installed bases, aftermarket service networks, and integration expertise with process control systems.
- Product differentiation is increasingly driven by digital capabilities—advanced diagnostics, native support for fieldbus and industrial Ethernet standards, and secure IIoT connectivity—rather than by hardware precision alone.
- Regional and niche vendors remain important for customers seeking low-cost, high-precision solutions, or rapid local service; these vendors often win in retrofit or non-critical applications.
- Market entry opportunities exist for specialized providers offering lifecycle services (predictive maintenance as a service), retrofit conversion kits, and cybersecurity-hardened field devices tailored to regulated industries.
Company-Level Insights — Strengths and Strategic Postures
The report’s vendor analysis evaluates leading and emergent players across product breadth, digital roadmap, service reach, and operational resilience. Highlights include:
- Emerson Electric Co.: Deep portfolio breadth across pressure, temperature, and level transmitters, with strong support for HART, FOUNDATION Fieldbus, and wireless protocols. Emerson’s installed base and software integration capabilities make it a go-to partner for large-scale modernization programs.
- ABB Ltd.: Strong engineering focus on high-performance pressure measurement and an active product renewal cadence. Recent new-product previews signal continued investment in ultra-accurate transmitters optimized for process optimization and utility applications.
- Yokogawa Electric Corporation: Emphasis on advanced diagnostics and reliability in process industries; well-positioned where uptime and measurement integrity are priority selections.
- Honeywell International Inc. and Siemens AG: Both leverage extensive automation portfolios to drive transmitter adoption as part of broader IIoT and automation projects, with emphasis on predictive maintenance and systems integration.
- Endress+Hauser and WIKA: Pivotal players for customers insisting on instrument-level interoperability and modern fieldbus options such as Ethernet-APL; strong reputations in calibration and lifecycle services.
- Schneider Electric: Brings process-control integration via established brands and offers competitive aftermarket services.
- Specialists and regional vendors (e.g., Duon System, ASCON TECNOLOGIC, BD|SENSORS, GEORGIN): Often agile on customization and price, these firms remain strategic for retrofit programs, regional projects, and OEM partnerships.
For procurement and strategy teams, the competitive mapping in the report includes vendor heatmaps, innovation roadmaps, and supplier risk scores designed to accelerate shortlist formation and contract negotiations in 2026.
Standards, Regulation, and Supply-Chain Headwinds
Regulatory and standardization developments will materially influence certification timelines and integration choices. Among the developments we model and assess are:
- Updated test procedures and verification expectations affecting pressure transmitters, which increase validation workloads for manufacturers and could extend lead times for certified lines.
- Revisions to measurement management system standards impacting calibration regimes and QA practices—requiring suppliers and end-users to re-evaluate maintenance intervals and associated cost models in their 2026 budgets.
- Emerging transducer interface standards that enable richer device descriptions and mixed-mode communications, facilitating plug-and-play capabilities but also imposing new compliance tasks for legacy systems.
- Industry adoption of Ethernet-APL and similar digital fieldbus technologies, which accelerate digital integration but also demand changes in plant network architecture and cybersecurity posture.
- Geopolitical and trade-related pressures on semiconductor supply chains: export controls and constrained advanced-chip availability are modeled as a direct input to lead-time scenarios and inventory strategies.
Our scenario analysis quantifies how different regulatory and supply scenarios alter procurement lead times, TCO, and retrofit economics—critical inputs for 2026 capital planning.
Strategic Recommendations for 2026 (Executive Summary)
Based on our analysis, PW Consulting recommends the following strategic moves for organizations planning product, procurement, or investment decisions in 2026:
- Prioritize interoperability and standards compliance in procurement specs. Devices that natively support next-generation fieldbus standards will reduce integration costs and futureproof systems.
- Adopt a diversifying sourcing strategy for critical components—especially semiconductors—combining strategic stockpiles with dual-sourcing agreements to insulate production from geopolitical shocks.
- Shift commercial models toward lifecycle-oriented contracts that embed predictive-maintenance services; these lower total cost of ownership and create recurring revenue for suppliers.
- Accelerate pilot deployments of Ethernet-enabled field devices with clear ROI checkpoints to build internal capabilities for broader IIoT rollouts in 2027–2028.
- For investors and acquirers: prioritize targets that offer differentiated software services, strong service footprints, or niche product excellence—these are the most likely to unlock synergies with incumbent portfolios.
- Integrate standards and regulatory-update monitoring into procurement and QA functions to avoid certification-related delays and unplanned retrofit costs.
How PW Consulting’s Report Serves 2026 Decisions
This report is deliberately structured as a “strategy-to-execution” kit for 2026. It connects high-level market projections—anchored in a rigorous historical base and a 5.4% modeled CAGR—with practical levers: supplier selection frameworks, risk-mitigated sourcing plans, and operational playbooks for IIoT adoption. The deliverable package includes interactive models and decision-support tools that procurement, product, and corporate development teams can apply directly to their 2026 planning cycles.
To preserve the competitive value of our primary datasets and scenario outputs, the public summary intentionally omits granular segment-by-segment figures and certain proprietary vendor score details. These are available in full through the report’s subscription and licensing options, which include raw datasets, vendor-level scorecards, and customizable TCO calculators.
Next Steps and Access
For executives preparing 2026 capital plans, procurement cycles, or M&A pipelines, receiving the full report and model packages is the most effective way to convert these insights into operational decisions. PW Consulting’s advisory teams are available for bespoke briefings, supplier shortlists, and deep-dive workshops that translate the report’s findings into implementation roadmaps tailored to your organization.
Contact PW Consulting to schedule an executive briefing and obtain access to the full Smart Transmitter Market report, interactive models, and the complete vendor benchmarking dataset.
For detailed analysis of this topic, please visit the official page: Smart Transmitter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Membrane Filter Press Market to Reach USD 1.24 Billion by 2032
By PW Consulting, 2026-07-02
Membrane Filter Press Market — 2026 Strategic Outlook and Executive Briefing
Executive summary
As companies plan capital allocation and operational pivots in 2026, the membrane filter press market presents a reliable yet evolving opportunity. Our PW Consulting base-year analysis (2025) places the global market at approximately USD 845.5 million. Under the scenario set out in our forecast (2026–2032), the sector grows at a compound annual growth rate (CAGR) of 5.6%, reaching roughly USD 1,238 million by 2032. These macro dynamics create a clear rhythm for investment — steady growth driven by environmental regulation, automation, and demand for higher dewatering performance — but the competitive and technology landscapes will determine winners and losers.
Membrane Filter Press Market
Why this report matters for 2026 decision-makers
-
Capital prioritization: With mid-single-digit CAGR growth, executive teams must balance replacement cycles and new capacity investment to avoid over-committing in mature segments while capturing higher-margin retrofit and digital-service opportunities.
Membrane Filter Press Market -
Procurement strategy: Total cost of ownership (TCO) is shifting from simple equipment purchase to integrated solutions (equipment + automation + aftermarket services). Procurement teams must redesign RFQs and evaluation criteria accordingly.
Membrane Filter Press Market -
Technology roadmap alignment: The spread of IIoT-enabled presses and advanced membrane squeeze designs creates a differentiation axis that affects both OEM competitive positioning and end-user operational performance.
-
M&A and partnership timing: Strategic acquisitions of capacity, automation IP, or aftermarket service platforms can accelerate access to higher value pools; timing should reflect regional demand windows and regulatory enforcement schedules.
Key market dynamics shaping 2026 strategy
Three dynamics dominate near-term strategy formulation.
-
Regulatory and environmental pressure. Stricter sludge disposal and tailings management rules are prompting operators in municipal, mining, and industrial end-markets to prioritize solutions that maximize cake dryness and minimize disposal volumes. Membrane filter presses, due to their mechanical squeezing phase, consistently deliver higher cake dryness than standard chamber presses — a performance attribute that is now a regulatory de-risking lever for operators.
-
Digitalization and IIoT. The integration of intelligent automation and IIoT platforms is moving from optional to expected. Systems that combine process automation, predictive maintenance, and remote analytics reduce operating expenditure, shorten downtime, and enable service-based commercial models. The competitive moves by leading OEMs around advanced automation suites signal that digital capability will be a primary purchase differentiator.
-
Supply-chain and raw-material considerations. Polypropylene remains the dominant raw material for filter cloths and many plate components because of its chemical resistance and cost profile. Growth in demand for synthetic filter media has implications for supplier selection, contract duration, and contingency planning; procurement should stress raw-material traceability and dual-sourcing where practicable.
Competitive landscape — what to watch
The market exhibits a moderate level of concentration: a small group of global OEMs account for a significant portion of revenue, while specialized and regional manufacturers compete aggressively on price, lead time, and customization. Strategic implications differ by type of player:
-
Large global OEMs: Companies such as ANDRITZ Separation and Metso bring scale, established field service networks, and integrated automation platforms. ANDRITZ’s focus on IIoT-enabled systems and next-generation membranes, and Metso’s emphasis on high-throughput Larox FFP designs, exemplify the premium players’ playbook: sell integrated performance and service continuity rather than hardware alone.
-
High-volume manufacturers and exporters: Firms with large production footprints (notably some Chinese OEMs) are competing on capacity, modular designs, and aggressive export strategies — an important dynamic for buyers seeking shorter lead times or new greenfield projects.
-
Specialist and regional providers: A cohort of companies offers high-customization, heavy-duty configurations, or niche design features serving complex industrial or municipal projects. These vendors can provide compelling TCO for tailored applications.
Recent industry moves underscore these trends: major contract awards in mining and upgrades to automation suites signal expanding adoption in both greenfield and retrofit contexts. The vendor landscape rewards companies that combine mechanical performance with digital services and after-sales expertise.
Report coverage — practical, execution-focused content
PW Consulting’s full report is designed to be a practical playbook for commercial, technical, and strategy teams. Highlights include:
-
Market sizing and baseline trajectory (2020–2025 historicals; 2026–2032 forecast) with scenario analysis calibrated to regulatory and commodity cycles.
-
Vendor scorecards that evaluate product breadth, automation capability, aftermarket footprint, lead times, and geographic presence — enabling side-by-side procurement shortlists.
-
Commercial models: capex/opex TCO templates, payback calculators for retrofit vs. new builds, and service-contract economics to support build-vs-buy decisions.
-
Technology deep dives covering membrane squeeze mechanics, plate and cloth material choices, and automation architectures — including implications for maintenance regimes and spare-part strategies.
-
Regulatory mapping and adoption timelines by end-market, with actionable compliance pathways for operators facing tightening disposal standards.
-
Supply-chain risk maps focused on polypropylene and critical components, together with mitigation checklists and recommended contract clauses.
-
M&A and partnership playbook: valuation multiples observed, integration risks, and target screening criteria for buyers seeking scale or digital capabilities.
How leading vendors are positioning — brief profiles
-
ANDRITZ Separation (Austria): Emphasizes intelligent automation and IIoT integration; recent product introductions aim to compress cycle times and lower OPEX through predictive operations.
-
Metso (Finland): Focused on high-throughput membrane solutions for mining; recent contract wins demonstrate demand for high-capacity Larox FFP systems in large concentrator projects.
-
Major Chinese manufacturers: High production capacity and broad export reach make them price-competitive for large-scale and time-sensitive deployments.
-
Specialized providers (US, Germany, India, etc.): Offer customization, high cake-dryness designs, and heavy-duty configurations for demanding industrial applications.
Across vendor tiers, differentiation is converging on two attributes: the ability to demonstrate field-proven dewatering performance and to offer digital-enabled services that protect uptime and lifecycle economics.
Strategic recommendations for 2026
-
Adopt a TCO-first procurement framework. Move beyond purchase price: quantify energy, water, downtime, disposal, and service costs over a 7–10 year horizon.
-
Pilot automation upgrades. Implement IIoT-enabled trials on priority lines to validate predictive maintenance and process-optimization claims before enterprise roll-out.
-
Stress raw-material resilience. Insert contractual protections and secondary sourcing for polypropylene-based consumables to avoid production disruption and margin compression.
-
Prioritize aftermarket and service capabilities. Vendors with strong parts logistics and local service teams materially reduce lifecycle costs; factor this into supplier scorecards.
-
Use modular procurement and staged CAPEX. Where possible, procure scalable presses or modular expansions to align capital deployment with demand realization.
-
Evaluate M&A selectively to capture automation IP or regional service networks. Corporate development teams should focus on targets that close gaps in digital capability or aftermarket reach.
-
Embed regulatory scenario planning. Build compliance-triggered adoption pathways into engineering and procurement roadmaps to accelerate projects when enforcement tightens.
What we are intentionally not disclosing here (and why)
In keeping with the “trailer” principle of this briefing, we have presented the high-level market size, growth trajectory, competitive dynamics, and practical implications for 2026. However, this release does not publish granular subsegment allocations, regional/application-level percentages, or full vendor scorecards. Those datasets are part of the proprietary analytical models and detailed segment tables in the full PW Consulting report, which are designed to support transaction-level decisions and competitive benchmarking. Executives who require that level of precision will find it in the comprehensive dataset and model deliverables.
Next steps and how PW Consulting can support your 2026 agenda
For leadership teams shaping CAPEX, procurement, or M&A strategies in 2026, this market offers predictable growth but material differentiation by technology and service model. PW Consulting can help with custom scenario modeling, vendor due diligence, RFP redesigns, and integration planning. Our full report provides the quantitative granularity and executable templates needed to convert the market’s projected expansion into defensible returns.
To access the comprehensive dataset, vendor scorecards, and deployment-ready templates, please consult the PW Consulting publication page for the Membrane Filter Press Market report or reach out to our strategic advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Membrane Filter Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fleet Card Market to Grow at 6.5% CAGR from USD 28.5B in 2025 to ~USD 44.29B by 2032 — Fuel Cards Lead with USD 19.97B in 2025
By PW Consulting, 2026-07-02
Fleet Card Market 2026: Strategic Intelligence for Executive Decision‑Making
Executive summary
PW Consulting’s latest market research on the global fleet card market positions the sector as a resilient, transforming layer of commercial mobility finance. Anchored on a 2025 base year and a historical review from 2020–2025, the study forecasts the market through 2032 with an expected compound annual growth rate (CAGR) of 6.5% for the 2026–2032 period. Our topline series shows the market expanding from approximately USD 20,500 Million in 2020 to USD 28,500 Million in 2025, with a projection toward the mid‑40s (USD 44,289 Million) by 2032. For C‑suite leaders and procurement owners preparing 2026 strategies, this research translates those macro trends into executable choices—while deliberately reserving granular segmentation tables for readers of the full report.
Fleet Card Market
Why this matters for 2026 planning
Fleet cards have evolved from a narrow fuel payment mechanism into a multifunctional toolset—integrating telematics, expense controls, EV charging, and cross‑border payment services. The growth trajectory in our base analysis reflects not only volume recovery in commercial vehicle miles and freight activity over the historical window, but also product‑led adoption of richer data and control features. The net result is a market where scale and embedded platform capabilities increasingly determine margin and retention. For a 2026 playbook, executives must orient investments toward interoperability, vendor ecosystems, and governance that capture both cost savings and operational visibility.
Fleet Card Market
Market trajectory and core drivers
-
Demand recovery and sustained commercial activity: Our historical review ties market expansion to freight and commercial transport activity rebounds. Public transportation and logistics indices reported increases that correlate with stronger demand for fuel and related services, which underpins card transaction volumes.
Fleet Card Market -
Platformization and value‑added services: The transition from single‑purpose cards toward integrated expense, maintenance, toll, and EV charging payments is a primary growth vector. Providers that bundle payments with telematics and real‑time controls capture incremental wallet share and command differentiated pricing.
-
Regulation and transparency demands: Increasing regulatory emphasis on fuel transparency and real‑time monitoring is accelerating uptake of advanced reporting features—especially among large fleets, third‑party logistics providers, and regulated public operators.
-
Concentration and competitive intensity: The market exhibits a moderate concentration: leading incumbents control a substantial portion of transactional volume and acceptance networks. This dynamic creates both entry barriers for new providers and M&A opportunities for incumbents seeking capability fills.
Competitive landscape: positioning the major players
Our competitive analysis synthesizes vendor strategies across acceptance reach, platform integration, pricing structure, and product innovation. Key takeaways for 2026 vendor engagement and RFP design:
-
WEX Inc. — A leader in universal fleet cards with deep U.S. acceptance and broad service integration. WEX’s strengths lie in telematics integrations, real‑time spend controls, and an early move into EV charging support. For buyers, WEX represents a low‑integration risk partner for scale and network coverage.
-
Corpay, Inc. (formerly FleetCor) — Maintains a strong issuer footprint with a multi‑brand approach. Recent product launches emphasize blended rebate programs and mixed fleet servicing, signaling an offensive to capture multi‑fuel and mixed‑power fleets.
-
Shell / BP / ExxonMobil / Chevron — Branded fuel suppliers have leaned into hybrid product models pairing branded acceptance with universal access through partnerships. Their network leverage and loyalty programs remain decisive for fleets with predictable routing to branded networks.
-
U.S. Bancorp (Voyager) — Focuses on ubiquity across fuel, maintenance, and services with sophisticated reporting—attractive to government and enterprise fleets requiring detailed invoices and compliance documentation.
-
European specialists (TotalEnergies, DKV Mobility, UTA Edenred, Radius) — These providers emphasize cross‑border payments, toll integration, and pan‑European acceptance, serving international trucking and logistics operators with complex routing needs.
-
World Kinect — Differentiates via energy management services, which can be relevant to sectors (e.g., aviation ground support) where broader energy procurement strategies matter.
Recent vendor developments (e.g., product launches and partnerships during 2024–2025) confirm a clear trend: incumbents are layering analytics and EV capabilities atop acceptance networks. Procurement strategies that ignore these platform differences risk paying for network reach while missing value from analytics and controls.
Regulatory and technology tailwinds
-
Regulatory shifts toward transparency and monitoring increase the value of cards that capture granular transaction and telematics data. Expect compliance requirements to shape procurement specifications in 2026.
-
Net neutrality and open internet standards contribute to predictable performance for cloud‑based fleet platforms and telematics integrations—lowering the operational risk of cross‑vendor API ecosystems.
-
Electrification and public EV charging infrastructure are altering acceptance maps. Card issuers that proactively integrate charging networks and billing reconciliation for kWh usage will secure an early advantage with mixed‑power fleets.
What PW Consulting’s report delivers (practical contents)
Designed for decision makers who must balance cost, control, and transition risk, the PW Consulting report provides a practical toolkit—not just market narrative. Highlights include:
-
Proprietary market model and scenarios: Transparent methodology with baseline and alternative adoption curves to stress‑test procurement decisions under different fuel price and EV penetration assumptions.
-
Vendor assessment framework: A comparative matrix that evaluates network acceptance, data integration capabilities, rebate and pricing models, and service coverage—presented as decision levers rather than raw scores to fit bespoke RFPs.
-
Implementation playbooks: Stepwise roadmaps for enterprise pilots, rollout phasing (driver cohorts, regions, vehicle types), and KPI frameworks focused on cost‑to‑serve, exception rates, and reconciliation efficiency.
-
Procurement instruments: Template RFP clauses, vendor scorecard formats, and negotiation levers aligned to mitigate common pitfalls such as undisclosed network fees or inflexible rebate schedules.
-
Financial models: Total cost of ownership (TCO) calculators and scenario‑based payback analyses denominated in USD Million revenue units so finance teams can map card program economics directly to company reporting.
-
Regulatory and risk matrix: Assessment of compliance exposure across major markets and operational recommendations for maintaining audit trails and data sovereignty.
Strategic recommendations for 2026
-
Prioritize platform interoperability over incremental discounts. With the market maturing, analytics and integration capabilities deliver outsized value through reduced exception handling and better routing decisions.
-
Design pilots that test multi‑power fleets. Mixed diesel/EV deployments require reconciliation across energy sources and charging networks—run parallel pilots to surface operational gaps early.
-
Embed regulatory compliance into contractual KPIs. Specify reporting cadence, data retention, and audit access upfront to avoid retroactive retrofit costs.
-
Use procurement structures that reward innovation. Consider multi‑year agreements with built‑in innovation milestones rather than fixed‑term price plays alone.
-
Maintain competitive tension through dual‑sourcing where network risk exists—particularly in regions with fragmented acceptance or emerging EV infrastructure.
How to use the full PW Consulting dataset
Our “trailer” here highlights the strategic contours and operational imperatives shaping the fleet card market in 2026. The full PW Consulting report contains the underlying datasets, segmented forecasts, and per‑vendor deep dives that procurement, finance, and fleet operations teams will use to finalize budgets and RFPs. Subscribers receive downloadable models in USD Million units, granular regional and application breakdowns, and the vendor scorecards referenced above—information we intentionally omitted here to preserve the value of the complete deliverable.
Conclusion
The fleet card market stands at an inflection: a steady growth path supported by transport activity and an accelerating shift to platformized payments and energy management. With an expected 6.5% CAGR across the 2026–2032 forecast window and a market size that has expanded materially since 2020, 2026 is the year to align procurement, operations, and treasury around integrated card strategies. PW Consulting’s report is crafted to convert these macro dynamics into executable plans—equipping leaders to capture savings, reduce operational friction, and manage transition risks as fleets electrify and data becomes the currency of control.
Next steps
For the full dataset, vendor scorecards, scenario models, and actionable procurement templates, access the complete PW Consulting Fleet Card Market report. Contact PW Consulting to schedule a briefing where our senior analysts will walk your team through tailored scenarios and a prioritized action list for 2026.
For detailed analysis of this topic, please visit the official page: Fleet Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Skin Measurement Instruments Market Set to Surpass USD 1.02 Billion in 2025 — Global Outlook 2026–2032
By PW Consulting, 2026-07-02
Skin Measurement Instruments Market: Strategic Outlook for 2026 — PW Consulting Insight
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I am pleased to present a focused industry briefing that previews our new Skin Measurement Instruments Market report. This briefing is written as a “trailer”: it demonstrates the analytical depth and decision-ready orientation of the full study while intentionally withholding granular segment tables and proprietary scorecards to encourage direct engagement with the complete dataset on our website.
Skin Measurement Instruments Market
Executive snapshot
The skin measurement instruments market has transitioned from niche laboratory tools into a mainstream node connecting dermatology, aesthetic medicine, cosmetics R&D, and retail personalized beauty. Our model shows the market expanded materially across 2020–2025, moving from an early-stage base to more broadly commercial deployments by clinics and consumer-facing services. The market reached roughly USD 1.02 billion in the report base year (2025) and is projected to follow an 8.24% compound annual growth rate (CAGR) through our forecast window. By the terminal year of our projection horizon, the market is on track to approach the high‑single‑digit to low‑billion range, underscoring sustained investment and commercialisation opportunities across hardware, software analytics and service layers.
Skin Measurement Instruments Market
Why this report matters to 2026 decision-makers
- Translate growth signals into tactical moves: We convert headline CAGR and market sizing into timing recommendations for product launches, procurement cycles, and clinical validations.
- De-risk regulatory pathways: With recent regulatory shifts, our analysis maps how expected classification changes materially alter go-to-market sequencing for device manufacturers and integrators.
- Prioritise R&D and commercial focus: The report identifies which capability vectors—portable depth-specific hydration meters, multi-parameter imaging with AI analytics, optical lesion detection, or point-of-care spectroscopy—offer the best ROI under a range of adoption scenarios.
- Vendor and partner selection: For buyers and investors, our assessment ranks vendors across technology depth, clinical validation, software maturity and channel reach—key inputs for procurement and M&A screening.
What the report contains — practical, executable content
- Market model & scenarios: Transparent assumptions, sensitivity testing and three adoption scenarios (base, accelerated, conservative) for 2026–2032 planning.
- Decision playbooks: Checklists for clinical buyers, cosmetics R&D labs, aesthetic chains and retailers that translate product features into procurement criteria and validation protocols.
- Vendor benchmarking: Qualitative and semi-quantitative vendor profiles covering technology stack, clinical evidence depth, service capabilities and go-to-market motion—presented as a vendor matrix that supports shortlisting without exposing proprietary score weights.
- Regulatory & reimbursement map: Practical guidance on device classification routes, required clinical endpoints, and payer-facing documentation—structured to reduce submission risk and accelerate time-to-market.
- Technology roadmap & integration guidance: Recommendations for hardware/software modularity, interoperability standards, and AI model governance for imaging products and analytics platforms.
- Commercial templates: Sample procurement RFPs, P&L impact templates, and lifecycle TCO models for capital equipment vs. service-subscription choices.
- Case studies: Real-world implementations showing validation timelines, KPIs and lessons learned from clinics, cosmetics labs and retail rollouts.
Competitive landscape — interpretative analysis (not a roster dump)
The market exhibits moderate concentration. The top three vendors account for a meaningful share of revenue, and the top five enlarge that footprint further—creating an environment where established specialists coexist with fast-moving niche innovators. This structure produces three concurrent strategic dynamics:
Skin Measurement Instruments Market
- Specialist incumbents (diagnostic-grade instrumentation and validated measurement probes) continue to anchor clinical and research demand. Their value proposition rests on long-standing method validation, standards compliance and deep peer-reviewed evidence.
- Imaging and analytics vendors are converging hardware, 3D capture and AI-driven interpretation to create differentiated consultative products for aesthetic and dermatology practices. This segment’s recent launches illustrate a step-change in consultation capability—shifting many buyers from single-parameter metrics to whole-face intelligence.
- Portable, point-of-care and depth-specific devices are broadening adoption outside tertiary centers into everyday clinic workflows and field studies for cosmetics. These devices trade off some diagnostic depth for speed, cost and ease-of-use, unlocking large addressable pockets tied to retail and personalized beauty applications.
Key vendor strategic moves to watch (high-level):
- Companies with modular platforms that combine validated probes with extensible software ecosystems maintain the best defensive and offensive positions for 2026 — they can serve both rigorous R&D clients and high-volume clinical deployments.
- AI-enabled imaging entrants that also secure clinical validation partnerships create premium pricing power in aesthetic markets where visual evidence and consultative upsell matter most.
- Manufacturers focusing on miniaturisation and validated point-of-care metrics are expanding into non-traditional channels—retail consultations, decentralized clinical trials and home‑care monitoring—creating new recurring revenue vectors when paired with software services.
Regulatory and reimbursement dynamics shaping 2026 plays
Two regulatory and policy developments materially affect strategy in 2026:
- Regulatory reclassification in the U.S. has opened more predictable 510(k) pathways for certain optical diagnostic and impedance-based devices, lowering time and capital required for market entry. Manufacturers should re-evaluate their product roadmaps and clinical evidence strategies in light of a more certain regulatory trajectory.
- Reimbursement policy updates related to skin substitute product packaging and hospital outpatient payment classification can indirectly influence adoption economics for diagnostic and procedural equipment when devices are used as part of bundled therapeutic pathways. Procurement teams and business leads should model these shifts in revenue and cost recovery assumptions for hospital and ASC channels.
Strategic implications and recommendations — a 2026 playbook
- For device manufacturers: Re-orient product development to meet 510(k)-aligned evidence requirements where feasible; prioritize software‑first architectures that enable subscription services and post‑market data collection; consider modular probe ecosystems to capture cross-segment demand.
- For imaging and AI vendors: Lock clinical partnerships early to secure validation endpoints, publish peer-reviewed outcomes and design clinician-centric workflows that shorten consultation time while improving conversion and upsell.
- For cosmetics and R&D labs: Standardize measurement protocols and invest in interoperable data pipelines to accelerate claim support and reduce time-to-market for new formulations; prioritize instruments that deliver reproducible, depth-resolved endpoints.
- For dermatology and aesthetic clinic operators: Build mixed procurement strategies that balance capital equipment for high-value consultations with portable devices and cloud analytics for throughput and recurring revenue models.
- For investors and M&A teams: Target assets that combine hardware defensibility with software lock-in and recurring services. Pay particular attention to companies that can demonstrate regulatory readiness and published clinical evidence.
How to use the full PW Consulting report
This briefing outlines the strategic contours of the skin measurement instruments market but purposefully omits the granular regional and application split tables, vendor scorecards and price-point schedules that underpin procurement decisions. The full report provides those datasets, downloadable models, executable RFP templates, and an interactive vendor matrix to support vendor selection and transaction diligence.
For an enterprise-ready briefing (including an executive workshop, bespoke scenario runs, or a tailored procurement roadmap aligned to your clinical and commercial calendar), contact PW Consulting through our official channels to license the full report and arrange a strategy session.
In 2026, the opportunity is no longer simply to sell or buy a device: it is to architect an integrated measurement-to-insight capability that converges validated measurement, clinical evidence, and software-enabled commercialisation. The firms that assemble these building blocks first—and prove them in clinical and retail pilots—will define the market’s next chapter.
For detailed analysis of this topic, please visit the official page: Skin Measurement Instruments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Exhaled Nitric Oxide Detectors Market to Reach USD 351.6M by 2032 at a 7.42% CAGR — Handheld FeNO Devices Hold ~72% Share in 2025
By PW Consulting, 2026-07-02
Exhaled Nitric Oxide Detectors Market: Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market intelligence on Exhaled Nitric Oxide (FeNO) Detectors presents a forward-looking, actionable lens for healthcare executives, medtech strategists, and investors preparing plans for 2026 and beyond. The market has demonstrated robust momentum over the past half-decade and, under conservative modelling, is set to sustain mid-single-digit to high-single-digit growth through 2032—delivering a compound annual growth rate of 7.42% over the forecast period. This briefing summarizes the strategic value of the report for C-suite and business units while deliberately preserving segment-level detail to encourage direct engagement with the full study.
Exhaled Nitric Oxide Detectors Market
Why this market merits executive attention in 2026
-
Clinical validation is converging with policy momentum. The 2025 GINA update elevated FeNO testing’s role in diagnosing Type 2 asthma, reinforcing clinical adoption across primary, specialty, and ambulatory care pathways.
Exhaled Nitric Oxide Detectors Market -
Regulatory pathways are maturing. Recent 510(k) clearances and evolving device controls for flow-dependent accuracy make scalable product introductions and clinical integrations more predictable for entrants and incumbents alike.
Exhaled Nitric Oxide Detectors Market -
Commercial dynamics are supporting adoption. While reimbursement nuances remain (for example, CPT 95012 reimbursement dynamics in the U.S. create particular considerations around outpatient packaging and margin models), the combination of guideline support and improving device ergonomics is widening the buyer base.
Market trajectory: headline numbers and implications
Between 2020 and 2025 the installed market for FeNO detectors expanded materially, driven by a mix of guideline-driven clinical uptake, product innovations in portability and workflow, and targeted commercial activity. By our base year (2025) the market had reached a significant milestone and, at the modeled 7.42% CAGR, the market is forecast to grow materially by 2032. For strategic planners this trajectory implies that investment windows for device manufacturers, diagnostic service providers, and integrated care networks are extending: early investments in clinical evidence generation, reimbursement strategy, and channel partnerships will compound across the forecast horizon.
Competitive landscape — who matters and why
The market exhibits a concentrated competitive structure. The three largest firms together account for a substantial majority of reported revenues, and the top five firms exert even greater market control. This concentration has three immediate consequences for strategy:
-
Scale advantages in device distribution, service networks, and clinical trial partnerships confer durable leadership to incumbent suppliers.
-
New entrants must demonstrate differentiated value—either through cost, workflow advantages (e.g., shortened breath maneuvers), or platform integration—to penetrate established purchasing pathways.
-
M&A and alliance strategies remain viable routes for rapid capability buildup, particularly for companies aiming to add clinical-grade reference devices or to secure distribution footholds in hospital systems and outpatient chains.
Key players profiled in our report include global incumbents and emerging regional manufacturers. Highlights:
-
NIOX Group (Circassia) — long recognized for a clinically validated portable device regarded as a practitioner standard in many geographies. Strong alignment with ATS/ERS testing standards and guideline recognition cements its presence in specialist and primary-care adoption pathways.
-
Bedfont Scientific — notable for cost-efficient electrochemical sensor solutions and recent clinical publications that underscore FeNO’s role in care pathways; positions itself strongly where price-to-performance and local serviceability drive purchasing.
-
Bosch Healthcare Solutions — recent regulatory clearance broadened its market addressability and highlights the strategic importance of global regulatory playbooks for device manufacturers seeking to scale across regulated markets.
-
MGC Diagnostics (affiliated with CAIRE) — leveraging unique workflow differentiation (e.g., short-duration breath maneuvers) to address throughput and pediatric usability constraints common in busy clinical settings.
-
ECO MEDICS — retains leadership in reference-grade chemiluminescence analyzers favored in research and high-precision clinical environments.
-
Emerging manufacturers (e.g., Sunvou, Ysenmed) — expanding affordability and geographic reach, particularly in cost-sensitive outpatient and community settings.
The report’s company dossiers combine product-level strengths, regulatory status, go-to-market tactics, and partnership matrixes to help buyers and investors evaluate competitive moves and tactical options.
Regulatory, reimbursement and standards landscape
-
Device classification and compliance: FeNO systems are consistently reviewed under Class II device frameworks in primary regulated markets, with special controls addressing flow-dependent measurement accuracy. Regulatory strategy is therefore a non-trivial time and cost consideration for new product introductions.
-
Reimbursement realities: In major healthcare markets, procedural coding and outpatient packaging materially influence net revenue. For example, established U.S. coding creates specific payment benchmarks and bundling behavior in hospital outpatient settings—factors that affect pricing, contracting, and adoption incentives.
-
Standards and clinical guidance: Alignment with ATS/ERS testing procedures and inclusion in GINA guidance increases the clinical credibility of routine FeNO measurement and reduces the evidentiary friction for payers and health systems considering adoption.
What the PW Consulting report delivers — operational, purchase-ready insight
This market study is built for translation into commercial action. Key, operationally oriented deliverables include:
-
Integrated commercial models: unit economics and margin simulations tailored to device types and typical procurement channels (hospital vs ambulatory vs research).
-
Segmentation-driven go-to-market playbooks: positioning frameworks for handheld vs. stationary platforms, clinical adoption roadmaps, and channel partner scorecards.
-
Regulatory & reimbursement playbooks: timelines, evidence checklists, and coding-optimization strategies mapped to the major markets.
-
Clinical adoption accelerators: trial design templates, KOL engagement plans, and hospital implementation guides to shorten the sales cycle.
-
M&A and partnership screening: shortlist of inorganic targets and alliance candidates based on capability gaps, regional footprint, and technology complementarity.
-
Scenario-based financial forecasts: best-, base- and downside cases that stress-test pricing, reimbursement shifts, and competitive responses.
How purchasers, OEMs and investors should use the intelligence
-
Procurement leaders: use our hospital adoption playbooks and vendor scorecards to refine RFPs, optimize service agreements, and negotiate bundled purchasing arrangements.
-
OEM product teams: apply workflow analysis and regulatory roadmaps to prioritize feature roadmaps, reduce time-to-market, and build evidence packages aligned with payer expectations.
-
Private equity and corporate development teams: leverage M&A screens and scenario modeling to identify targets that can be scaled rapidly through channel consolidation or geographic platform plays.
Strategic takeaways for 2026 planning cycles
-
Invest in differentiated clinical evidence. Guideline recognition opens the door; robust prospective studies and health economic dossiers will determine payer coverage breadth.
-
Design for workflow: devices that materially reduce testing time or simplify operator training unlock adoption in high-throughput clinics and pediatric care.
-
Match go-to-market to profit pools: cost-effective devices can win in outpatient and primary care, while reference-grade analyzers retain a premium position in research and specialist centers.
-
Prepare for consolidation: the concentrated market structure favors strategic M&A and distribution alliances as routes to accelerate scale.
Report access and next steps
PW Consulting’s full market report contains the granular datasets, regional and application-level forecasts, vendor scorecards, and downloadable financial models that underpin the strategic conclusions above. To preserve the commercial value of those datasets for subscribers, this briefing omits the detailed segment tables and the full numeric breakdowns that inform procurement, valuation, and product strategy decisions. Decision-makers seeking the complete intelligence package—including interactive scenario models and supplier benchmarking matrices—are invited to access the report through PW Consulting’s market portal.
For leaders who are preparing product roadmaps, investment memos, or procurement strategies for 2026, this study provides the evidence-based scaffolding to act with precision. PW Consulting stands ready to support tailored workshops, due-diligence support, and implementation roadmaps derived from the research.
Contact PW Consulting to request the full Exhaled Nitric Oxide Detectors Market report and to arrange a briefing tailored to your organization’s strategic priorities.
For detailed analysis of this topic, please visit the official page: Exhaled Nitric Oxide Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automated Microplate Labeler Market to Expand at a 6.84% CAGR During the 2026–2032 Forecast Period
By PW Consulting, 2026-07-02
Automated Microplate Labeler Market: Strategic Intelligence for 2026 Decision-Making
As life sciences organizations accelerate laboratory automation and sample-management workflows, the automated microplate labeler market is entering a phase where timely, data-driven choices will determine competitive positioning. PW Consulting’s latest market research report provides the strategic line-of-sight needed by procurement leaders, automation architects, product strategists, and private equity teams as they plan for 2026. This executive briefing highlights the report’s most consequential takeaways—demonstrating methodological rigor and actionable insight—while preserving the granular segmentation and numeric models reserved for subscribers.
Automated Microplate Labeler Market
Market Snapshot: Growth Trajectory and What It Means
Our model benchmarks the automated microplate labeler market with a 2025 base year and a forecast horizon through 2032. In 2025 the market reached USD 284.5 Million (revenue, USD Million), and it is projected to expand at a compound annual growth rate (CAGR) of 6.84% over the forecast period. By 2026 the market is expected to surpass the USD 300 Million threshold. This growth reflects renewed capital investment in automated sample-management infrastructure, tighter regulatory and audit readiness requirements, and rising demand for integration-ready hardware in high-throughput environments.
Automated Microplate Labeler Market
For 2026 strategy cycles, these macro indicators accomplish two goals. First, the trajectory validates near-term capital allocation for automation projects rather than deferring purchase decisions. Second, the steady, mid-single-digit CAGR implies that differentiation will come less from rapid market expansion and more from share shifts achieved through integration capability, service economics, and regulatory-compliant software stacks.
Automated Microplate Labeler Market
Why This Report Matters for 2026 Decisions
- Timing of CapEx: Our scenario analysis maps total cost of ownership across acquisition models—standalone units, integrated systems, and refurbished equipment avenues—enabling CFOs and lab directors to select financing or leasing approaches that minimize disruption to 2026 budgets.
- Vendor Selection Framework: The report offers a decision matrix that weights technical fit (e.g., footprint compatibility, multi-side labeling, 1D/2D barcode support), throughput (stacker capacity and cycle time), software interoperability (LIMS, robotic controllers), and lifecycle service economics—enabling procurement teams to compare suppliers on business-relevant metrics, not just specs.
- Integration & Compliance Roadmap: For labs subject to clinical, diagnostic, or regulated research oversight, our guidance links hardware selection to compliance pathways (including device-quality standards and electronic-records expectations), reducing audit risk and accelerating validation timelines for 2026 go-lives.
- M&A and Partnership Targets: Private equity and corporate development teams gain a short-list of strategic acquisition archetypes—bolt-on automation OEMs, label consumable specialists, and middleware/software integrators—that can deliver rapid capability expansion without diluting core competencies.
Report Contents – Practical, Reproducible, and Audit-Ready
- Methodology appendix: transparent data sources, market sizing approach (historical window 2020–2025; forecast 2026–2032), and sensitivity testing.
- Commercial models: ROI and payback calculators tailored to common lab configurations and utilization profiles.
- Vendor assessment templates: scoring rubrics mapped to procurement objectives (speed-to-results, throughput, regulatory fit, and lifecycle cost).
- Integration playbooks: stepwise validation and commissioning checklists for LIMS and automation ecosystems, including electronic records considerations.
- Aftermarket playbook: service-level agreement (SLA) and spare-parts optimization strategies to improve uptime without inflating Opex.
- Strategic scenarios: three market evolution paths with corresponding tactical moves for incumbents, challengers, and ecosystem partners.
Competitive Landscape: Profiles and Strategic Implications
The automated microplate labeler space combines hardware precision, systems integration, and consumable performance. A set of established players and specialized suppliers compete on device robustness, stacker throughput, labeling flexibility, and software integration. Below we summarize the competitive positions and strategic options for leading providers.
-
Agilent Technologies (Santa Clara, CA)
Strengths: Offers compact benchtop devices engineered for seamless integration into automated liquid handling and plate-management workflows. Their devices emphasize ANSI/SLAS footprint compatibility and reliable multi-side barcode labeling, which simplifies robotic pick-and-place operations.
Strategic takeaway: Agilent’s reputation and systems approach make it a preferred partner for large labs and OEM integrations. For competitors, differentiation must target specialized throughput niches, software openness, or compelling service models to chip away at incumbent relationships.
-
Scinomix (Earth City, MO)
Strengths: Portfolio includes automated print-and-apply devices with stacker options and a focus on high-throughput pharmaceutical and life-science workflows. Recent activity—technical integration references and application guidance—signals ongoing product support and knowledge transfer to customers.
Strategic takeaway: Scinomix demonstrates how field documentation and application notes can accelerate adoption. Rivals and buyers should evaluate not only hardware specs but also the vendor’s commitment to operational best practices and service documentation.
-
Analytik Jena / CyBio (Jena, Germany)
Strengths: High-speed labelers with flexible, four-side labeling and stacker integration, delivered with consumables engineered for chemical resistance. Their models suit labs that require aggressive throughput without sacrificing label durability.
Strategic takeaway: Analytik Jena’s engineering of chemical-resistant labels and high-density stackers is a strong defense in environments with harsh solvents and continuous operations. Competitors need to match label longevity and integrate seamlessly into existing automation lines to compete.
-
Hudson Robotics / Hudson Lab Automation (Springfield, NJ)
Strengths: Solutions marketed for high-performance applications, supporting 1D/2D barcodes and multi-side data printing with scalable stacker capacities. Emphasis on scalability makes this vendor attractive for high-throughput and multi-shift labs.
Strategic takeaway: Scalability and robust throughput are Hudson’s core value propositions. Service partners and integrators should highlight their ability to maintain uptime at scale and provide efficient consumable replenishment to preserve run schedules.
-
Computype (St. Paul, MN – operational presence)
Strengths: Supplies advanced print-and-apply systems optimized for robotic handling and precision placement. The vendor is notable for catering to high-demand laboratory environments where reproducibility and alignment precision are critical.
Strategic takeaway: For buyers prioritizing exacting placement tolerances and robotic compatibility, Computype’s offerings merit close evaluation. Competitive responses should focus on integration toolkits and robotic interface support.
Recent Market Movements and Signals
- Secondary market activity and certified pre-owned equipment listings suggest growing demand for lower-cost entry points or interim capacity — a signal for OEMs to formalize refurbishment and trade-in programs.
- Product lifecycle evidence (manufacturing references and application notes) from leading vendors indicates continuing product refresh cycles and investment in end-user enablement resources—important context for service and consumable revenue planning.
- Regulatory and standards alignment is front-and-center: devices and integrations must map to medical-device QA frameworks and electronic records regulations when deployed in clinical or diagnostic settings.
Regulatory & Standards Considerations
Regulatory compliance is a persistent purchasing determinant. Vendors and buyers must account for medical-device quality systems (e.g., ISO 13485) when equipment is intended for clinical workflows. Where labeler data is captured or controlled by software, systems need to conform to electronic-records and auditability requirements consistent with relevant regulatory guidance. Finally, physical compatibility with laboratory workflows is governed by established plate footprint standards that the market widely supports, ensuring cross-vendor interoperability.
Innovation and Technology Trends to Watch
- Software-first integration: Vendors that deliver open APIs, LIMS adapters, and validated middleware will accelerate adoption in complex automation stacks.
- Consumable engineering: Advances in label adhesives and chemical-resistant materials are extending plate lifespans in solvent-rich workflows, reducing rework and misreads.
- Throughput modularity: Scalable stackers and modular labeling stations enable labs to grow capacity incrementally, protecting capital while matching throughput to demand.
- Aftermarket services: Predictive maintenance, remote diagnostics, and certified refurbishment programs are emerging as profitable, sticky revenue streams for vendors.
Actionable Recommendations for 2026 Planning
- Prioritize integration compatibility over lowest-quoted price; software and mechanical interoperability reduce validation time and hidden integration costs.
- Design procurement specs that include lifecycle service metrics (MTTR, spare-part availability, refurbishment options) and require demonstrable field references.
- Leverage refurbished equipment channels for near-term capacity needs but insist on certified refurbishment and warranty parity to manage operational risk.
- Build compliance into the procurement timeline—factor in validation and electronic-records acceptance testing to avoid program slippage.
- For OEMs and investors: invest in open software ecosystems and consumable differentiation to create recurring revenue and lock-in.
Conclusion & Next Steps
For organizations making automation and procurement choices in 2026, the automated microplate labeler market presents an environment of steady growth and meaningful competitive differentiation opportunities. PW Consulting’s full report equips decision-makers with the models, vendor assessments, and playbooks required to convert market signals into executable strategies. Core market segmentation tables, proprietary revenue models, and downloadable decision-support tools are available in the subscriber report—designed to move teams from evaluation to execution with confidence.
Access the full Automated Microplate Labeler Market report on our website to uncover the segment-level datasets, regional and end-user breakouts, and the financial models that underpin the strategic guidance summarized here.
For detailed analysis of this topic, please visit the official page: Automated Microplate Labeler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


