



Category: market research
PW Consulting: Targeted Multiple Myeloma Drugs Market to Reach USD 40,038.72M by 2032
By PW Consulting, 2026-07-13
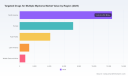
Targeted Drugs for Multiple Myeloma: Strategic Intelligence for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a concise but deep overview of the Targeted Drugs for Multiple Myeloma market designed to anchor executive decisions in 2026. This briefing synthesizes macro growth dynamics, competitive inflection points, regulatory and reimbursement shifts, and the practical implications for R&D, commercial strategy, M&A and manufacturing. It intentionally signals the analytical framework and decision levers you need while reserving the granular sub-segmentation tables and proprietary scenario outputs for the full report.
Targeted Drugs For Multiple Myeloma Market
Why this market matters in 2026
The multiple myeloma targeted therapies market has entered a phase of structural expansion and compositional change. After rising from roughly USD 18.5 billion in 2020 to about USD 25.85 billion in 2025, the market is forecast to grow at a compound annual growth rate (CAGR) of 6.45% through the 2026–2032 forecast window, reaching approximately USD 40.0 billion by 2032. That trajectory reflects not only continued demand for established modalities (antibodies, proteasome inhibitors, immunomodulatory agents) but also rapid adoption of next‑generation targeted constructs—bispecifics, antibody-drug conjugates (ADCs), and CAR-Ts—reshaping treatment algorithms and commercial models.
Targeted Drugs For Multiple Myeloma Market
Critically, market concentration is meaningful: the leading three companies account for a majority share of market revenues while the top five consolidate roughly three quarters of the market. This concentration creates both defensive moats and strategic openings: established players can leverage scale to accelerate combinations and label expansions, while challengers can capture niche, high-value positions via novel mechanisms or targeted partnerships.
Targeted Drugs For Multiple Myeloma Market
What’s changed in the regulatory and reimbursement landscape
- Regulatory pragmatism around surrogate endpoints: In early 2026 the FDA issued draft guidance clarifying the use of minimal residual disease (MRD) negativity and complete response as primary endpoints to support accelerated approvals in multiple myeloma trials. This aligns regulatory incentives with trial designs that are shorter and more efficient, increasing the value of candidates that can demonstrate deep, durable responses on MRD.
- Pathways to broader access: Building on analyses that link MRD to long-term outcomes, regulators and payers are more willing to accept MRD-based evidence for expedited access. Expect payer dossiers and HTA submissions in 2026–2027 to emphasize MRD-driven modeling and real‑world evidence plans up front.
- Operational de‑risking of cell therapies: Recent agency actions have streamlined monitoring requirements and removed REMS constraints for selected CAR‑T products, reflecting growing confidence in real‑world safety data. This materially reduces downstream commercialization friction and total cost of care considerations for CAR‑T providers and payers.
- Patent cliff and generic dynamics: The full generic entry of lenalidomide in the U.S. from January 31, 2026, materially alters backbone economics for many combination regimens and compels originators and competitors to accelerate lifecycle and differentiation strategies.
Key competitive inflection points (what to watch)
- Label and combination expansion: Johnson & Johnson (Janssen) continues to lead in execution—recent 2026 approvals expanded both combination and earlier-line indications for its monoclonal antibody franchises and bispecific pairings. These moves raise the benchmark for combination trials and for commercial access in earlier lines.
- Next‑generation oral agents: Bristol Myers Squibb’s positive Phase 3 readout for a next‑generation CELMoD signals that potent oral targeted agents can still shift the value equation—especially where they can be combined with proteasome inhibitors or antibodies to create all‑oral regimens with attractive clinic and payer appeal.
- Bispecifics and ADCs accelerating adoption: Players such as Regeneron, Pfizer, and GSK have secured regulatory footholds for BCMA-directed bispecifics and ADC combinations—fast adoption will depend on manufacturing scale, safety management protocols, and pricing models that reflect single‑agent vs. combination value.
- CAR‑T capacity and platform plays: CAR‑T portfolios (including collaborations and acquisitions among Gilead/Kite, Legend/Janssen and others) are shifting from proof‑point status to a commercial product class. Scale constraints and site-of-care logistics remain the gating factors; companies that secure manufacturing capacity and hub-and‑spoke care models will convert clinical wins into durable commercial returns.
Strategic implications for corporate leaders in 2026
- Portfolio prioritization: Recalibrate R&D and commercial resource allocation toward assets that can demonstrate MRD conversion and deep response durability within shorter trial timelines. For incumbents with mature franchises, prioritize label-expansion trials that pair established agents with high‑potential bispecifics or CELMoDs to defend share against biosimilars/generics.
- Launch sequencing and combination economics: Develop monetization strategies that account for evolving standard-of-care backbones post-generic entry. Pricing and contracting teams must model multiple reimbursement scenarios including indication‑based pricing, outcomes‑based agreements, and combination discounts to secure formulary placement.
- Manufacturing and supply chain: For CAR‑T and bispecific programmes, convert clinical supply investments into commercial readiness—invest in regionalized manufacturing capacity and cold‑chain logistics, and secure strategic partnerships for fill/finish to avoid launch bottlenecks.
- M&A and partnership playbook: Use targeted bolt-on acquisitions to fill technological gaps (cell therapy manufacturing, ADC conjugation expertise, bispecific platforms) while reserving larger transformational transactions for opportunities that create differentiated scale or first‑mover access to platform technologies.
- Real‑world evidence and HTA strategy: Build MRD-anchored real‑world evidence plans contemporaneous with registrational programs. Early engagement with payers to align on MRD‑based surrogate acceptance criteria will shorten the time from approval to reimbursement.
Commercial and go‑to‑market considerations
Distribution dynamics are shifting as care migrates across hospital systems, specialty clinics and, gradually, outpatient infusion/SC sites. Commercial teams should design multi-channel launch strategies that align with site-of-care economics and incorporate digital patient support models to accelerate uptake of complex regimens. For CAR‑T and other one‑time therapies, commercial value lies as much in hub network enablement and patient navigation as in list price. Payers are increasingly focused on total cost of care and durability; commercial evidence packages must quantify these dimensions.
What PW Consulting’s full report delivers (practical, actionable assets)
- Market model and scenarios: A detailed, auditable market model spanning 2020–2032 with base, upside and downside scenarios, plus sensitivity analyses on key inputs (MRD acceptance, generic entry timing, CAR‑T capacity utilization).
- Launch readiness playbooks: Step‑by‑step commercial and medical strategies for twelve launch archetypes (bispecific, ADC, oral CELMoD, CAR‑T, antibody combo), including pricing corridors, payer value dossiers, KOL maps, and phased market entry plans.
- Competitive profiles: Deep dossiers on leading companies, including pipeline maps, trial timelines, manufacturing capabilities, and partnership opportunities—scored for strategic fit and commercial impact.
- Regulatory & HTA navigation toolkit: Practical guidance for structuring MRD‑driven registrational programs, evidence generation roadmaps, and payer engagement templates tailored to regional HTA nuances.
- Commercial downside mitigation: Contract archetypes, patient support program blueprints, and manufacturing backup plans to reduce launch risk for high‑value assets.
How to use this intelligence in a 90‑ to 180‑day planning cycle
- 90 days: Re-align prioritization—identify 1–2 assets that should receive accelerated MRD‑focused registrational designs; initiate payer advisory boards to validate evidence needs; conduct a manufacturing capacity stress test for cell therapy candidates.
- 180 days: Implement commercialization frameworks—finalize launch sequencing, negotiate strategic manufacturing partnerships, and deploy early real‑world evidence pilots in high‑adoption centers of excellence.
Trailer: what’s contained but withheld here
In the interests of sparking immediate yet action-oriented decisions, this preview exposes the strategic contours and decision levers of the market but deliberately withholds detailed sub‑segment revenue tables, regional and drug‑class share breakouts, and proprietary scoring matrices that underpin our recommendations. Those granular outputs—core to investment, launch and M&A modeling—are included exclusively in the full PW Consulting Targeted Drugs for Multiple Myeloma Market report and interactive dashboards.
Final recommendation
Decision‑makers should treat 2026 as a pivot year: regulators and payers are aligning around MRD-driven approvals, generics are reshaping backbone economics, and new modalities are moving rapidly from niche to mainstream. Companies that act now—by integrating MRD into trial design, securing manufacturing and distribution capacity, and developing flexible pricing contracts tied to durability—will turn the sector’s structural growth (6.45% CAGR to ~USD 40 billion by 2032) into sustainable competitive advantage.
For the full data, granular segment tables, and the actionable playbooks referenced above, consult the complete PW Consulting report and our interactive modeling suite. Our team is available to walk executive teams through tailored scenario runs and launch readiness assessments that convert insight into near‑term action.
For detailed analysis of this topic, please visit the official page: Targeted Drugs For Multiple Myeloma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium-ion Consumer Electrolyte Market to Reach USD 3,559.9M by 2032 (5.2% CAGR)
By PW Consulting, 2026-07-13
Lithium‑Ion Consumer Battery Electrolyte Market — Strategic Outlook for 2026 Decision‑Making
Executive teaser
As PW Consulting’s lead industry analyst, I present a concise, actionable orientation to our full Lithium‑Ion Consumer Battery Electrolyte Market study — designed specifically to inform executive decisions in 2026. The global market reached USD 2,496.46 Million in our base year (2025) following steady growth across 2020–2025. Our bottom‑up forecast projects continued expansion through 2032, with a compound annual growth rate (CAGR) of 5.2% in the 2026–2032 period and a projected market size north of USD 3.5 billion by 2032. This briefing highlights the strategic implications and the kinds of operational intelligence contained in the complete report; detailed segment tables, supplier shares and proprietary model outputs are reserved for the full deliverable.
Lithium Ion Consumer Battery Electrolyte Market
What’s changing and why it matters in 2026
-
Demand intensity remains anchored by consumer electronics trends — higher charge‑rate requirements, incremental energy density improvements, and a growing installed base of portable devices and wearables drive steady electrolyte consumption growth.
Lithium Ion Consumer Battery Electrolyte Market -
Supply‑side pressures are amplifying margin and sourcing risk. Recent commodity dislocations and feedstock constraints have produced sharp spot price moves and contract volatility — a dynamic that materially affects unit economics for downstream cell and device makers.
Lithium Ion Consumer Battery Electrolyte Market -
Policy and trade actions enacted in late 2025 and early 2026 raise the bar for compliance and localization. New regulatory limits on certain fluorinated chemistries in Europe, tariff increases in major markets, and domestic content mandates in China alter the calculus for sourcing, R&D priorities and capacity siting.
-
The competitive structure is moderately concentrated: the top three suppliers account for a material majority of the market, and the top five command an even larger share. That concentration produces both supply stability from incumbent producers and opportunity for challengers with differentiated chemistries or localized capacity.
Key dynamics you must account for in 2026
-
Raw material volatility: Spot and contract prices for core carbonate solvents and lithium salts experienced meaningful spikes through 2025, driven by upstream feedstock shortages and regional supply tightness. These moves mean procurement strategies that worked historically will require re‑engineering for price risk transfer and continuity.
-
Regulatory disruption: Tightening chemical controls in major regulatory regimes and new rules limiting select fluorinated compounds necessitate product reformulation roadmaps and accelerated qualification cycles for non‑restricted alternatives.
-
Trade and localization: Elevated tariffs and subsidy‑tied domestic content rules force manufacturers to re‑evaluate global supply footprints and consider local manufacturing partnerships or greenfield investments in target markets.
-
Technology differentiation: Additives (stability, low‑temperature performance) and next‑generation salts (for high‑energy or fast‑charge chemistries) are rapidly moving from lab to pilot. Suppliers that pair formulation expertise with scale will capture premium contracts.
What our full study delivers — practical components for decision makers
The report is structured as an operational toolkit for procurement, product strategy, corporate development and regulatory teams. Highlights include:
-
Proprietary demand model (2020–2032) with bottom‑up unit flows and a price‑volume synthesis, enabling scenario runs for macro, commodity and technology shocks.
-
Supplier coverage and capability mapping, including production footprints, recent capex announcements, and readiness for alternate chemistries — designed to support dual‑sourcing and localization choices.
-
Price‑build and margin waterfall analyses for representative electrolyte formulations to quantify pass‑through potential and negotiation levers in long‑term contracts.
-
Regulatory impact maps and a compliance timeline that translate new limits and tariff changes into revenue and cost scenarios for 2026 planning cycles.
-
M&A and partnership playbooks: scoring templates, integration risk checklists, and quick filters to prioritize targets that accelerate market entry or secure critical raw materials.
-
Operational guidance for plant sizing, contract duration optimization, and inventory strategy aligned to the forecasted growth trajectory and volatility stress tests.
Competitive landscape — strategic takeaways
The market is shaped by a set of well‑established chemical producers and specialized electrolyte formulators. Our comparative review of principal players yields several clear implications for 2026 strategy:
-
Incumbent solvent and additive producers (major Japanese and European chemical houses) retain advantage in safety‑critical high‑purity materials and have R&D depth for next‑gen additives. Their strategic posture is often defensive — protecting long‑term OEM certifications.
-
Full‑stack electrolyte formulators and Chinese producers are aggressively expanding capacity to capture consumer battery demand at scale. Capacity additions announced in 2025–2026 will change availability patterns in Asia and export markets.
-
Specialist lithium salt suppliers and makers of high‑performance additives are differentiators for premium, fast‑charge and long‑life applications. Securing multi‑year supply agreements with these suppliers can be a meaningful product performance and margin lever.
-
Recent company moves worth noting: capacity expansions to meet consumer battery growth; product launches targeting low‑viscosity and high‑rate performance; and sustainability or certification achievements that ease market access with large OEMs. These actions accelerate consolidation pressures in select subsegments.
Strategic recommendations for 2026 (prioritized)
-
Immediate (0–6 months): Institute commodity hedging triggers and renegotiate contract terms to include flexible indexation and force‑majeure mitigants. Activate secondary sourcing pipelines for critical salts and carbonate solvents.
-
Near term (6–18 months): Localize key intermediate supply or form JVs in regions where tariffs and domestic content rules materially affect landed cost and market access. Align pilot production for PFAS‑free/formulation‑altered electrolytes to comply with emerging regulations.
-
Medium term (18–36 months): Invest selectively in formulation capability (or acquire a niche supplier) to own roadmap to advanced electrolytes such as LiFSI‑based systems or novel additives that reduce dependency on regulated chemistries.
-
Cross‑cutting: Build a regulatory and trade compliance function into commercial planning to translate rule changes into procurement and pricing actions rapidly. Use the report’s scenario outputs to stress‑test business cases at different commodity and policy states.
How to use this study in boardroom and commercial planning
-
Procurement — a tactical playbook and supplier scorecards to shorten sourcing cycles and quantify cost risk under alternative price paths.
-
R&D and product — prioritized chemistry roadmaps and trial‑scale costings to support qualification timelines with device OEMs.
-
M&A & Strategy — target filters and valuation adjustments that incorporate concentration, regulatory exposure and capacity timing.
-
Investor communications — an evidence‑based narrative to justify CAPEX or partnership investments against the market growth path and concentration dynamics.
Closing — why 2026 is a pivotal planning year
The combination of stable, mid‑single‑digit growth (5.2% CAGR through 2032), concentrated supply, raw‑material volatility and accelerating regulatory change means that 2026 will be a decisive year for positioning. Executives who proactively reconfigure sourcing, prioritize compliant formulations and time capacity investments using rigorous scenario analysis will convert near‑term turbulence into durable competitive advantage.
PW Consulting’s full report packages the quantitative models, supplier intelligence, and commercial playbooks necessary to execute those actions. For access to the detailed segment economics, company market shares, price decks and downloadable models that support boardroom decisions, please refer to the full study landing page.
For detailed analysis of this topic, please visit the official page: Lithium Ion Consumer Battery Electrolyte Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Anti-Fog Polycarbonate Film and Sheet Market: Strategic Outlook for 2026 Decisions
Executive preview
As companies prepare strategic plans for 2026, the anti-fog polycarbonate film and sheet market presents a mix of steady growth, concentration-driven competitive dynamics, and regulatory and feedstock-driven tailwinds that will materially affect sourcing, product development, and go-to-market choices. This introduction summarizes why a disciplined, scenario-driven approach to investments and partnerships in this segment is essential. It also explains how PW Consulting’s full study arms decision-makers with the operational frameworks, risk-mapped scenarios, and supplier-level intelligence required to act with confidence — while reserving the granular segment tables and proprietary model outputs for the full report.
Anti Fog Polycarbonate Film And Sheet Market
Where the market stands and where it’s headed
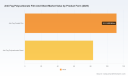
Between 2020 and 2025 the global market for anti-fog polycarbonate film and sheet expanded meaningfully, and our base-year analysis for 2025 captures a market that is now approaching the high hundreds of millions in USD revenue. Our forecast to 2032 embeds an expected multi-year expansion trajectory supported by a mid-single-digit compound annual growth rate (CAGR), reflecting persistent demand from safety/medical PPE, horticulture/greenhouse, displays, and industrial refrigeration applications. In short: growth is steady, predictable, and concentrated in a manageable set of end-markets — ideal conditions for disciplined capacity planning and targeted innovation.
Anti Fog Polycarbonate Film And Sheet Market
Market concentration is moderate: the top three global players do not yet dominate the majority of value, and the top five increase that share materially but still leave room for regional specialists and differentiated technology providers to capture pockets of premium margin. This structure creates both acquisition opportunities for scale and carve-out targets for capability-led entrants.
Anti Fog Polycarbonate Film And Sheet Market
Why 2026 is an inflection year for corporate decision-making
-
Operational cadence and timing. Several new production and fabrication capacities announced through 2025–2026 change lead times and regional supply balances. Firms that finalize partnerships or capacity commitments in early 2026 lock in advantaged service footprints for the next decade.
-
Regulatory and formulation thresholds. Recent additions to persistent organic pollutant lists and tightening chemical limits in major markets necessitate material requalification cycles. Product teams and procurement should treat 2026 as a window to validate formulations (including PFAS-free options) and secure compliant supply chains before stricter enforcement timelines take effect.
-
Input-cost signals. Volatility in polycarbonate feedstocks — driven by upstream shifts in phenol/acetone and bisphenol A pricing — will continue to pressure margins. Scenario-based procurement playbooks and hedging strategies developed now mitigate margin erosion during 2026–2028.
Practical, decision-oriented content included in the full report
PW Consulting’s full study is organized around practical outputs that executives and functional leaders can apply immediately:
-
Market sizing and demand-driver models with downloadable inputs to rerun forecasts under custom scenarios (supply disruptions, accelerated regulatory change, or demand shocks in medical PPE).
-
Supplier scorecards and capability matrices — covering technical performance of anti-fog chemistries, coating durability metrics, abrasion resistance, and long-term anti-fog lifetime claims — enabling rapid supplier shortlists for qualification pilots.
-
Commercial playbooks: pricing sensitivity maps, margin impact simulations by channel, and go-to-market templates for OEM partnerships and distribution agreements.
-
Capex decision framework: an investment checklist that translates demand forecasts into required capacity, OEE assumptions, and payback sensitivity to feedstock and regulatory scenarios.
-
Regulatory compliance checklist and reform-impact pathways, showing where reformulation will be necessary versus where supplier certifications can be fast-tracked.
These deliverables are intentionally operational: the study is more than trend commentary — it’s a toolkit to accelerate procurement, NPD, and M&A decisions in 2026.
Competitive landscape: who matters and how to engage them
The competitive map blends global commodity-scale polymers businesses, specialty sheet and coating specialists, and regional fabricators. Key players profiled in the report include leading global innovators and important regional suppliers. Each profile includes a capability assessment and transaction-ready negotiation levers — licensing, joint development, exclusive supply zones, tolling, and co-investment options.
-
POLYVANTIS (formerly SABIC Innovative Plastics) — A global technology leader with long-duration anti-fog films designed for high-humidity PPE and display environments. Their product positioning emphasizes long-term hydrophilic performance alongside impact resistance.
-
Covestro AG and Mitsubishi Gas Chemical — Two engineering-materials incumbents deploying broad polymer science and scale to serve automotive, electronics, and safety markets with anti-fog grades.
-
FSI Coating Technologies (SDC division) — Focused on durable, abrasion-resistant anti-fog coatings for visors and freezer display cases; recent innovation includes PFAS-free formulations that respond to evolving chemical restrictions.
-
Regional and specialty fabricators — Several China-based manufacturers and regional European/US sheet producers provide custom thicknesses, co-extruded multiwall panels, and localized service that remain critical to speed-to-market for OEMs and installers.
Engagement guidance: for OEM procurement teams, we recommend dual-track strategies — secure at least two qualified suppliers with different exposure to raw-material risk, and negotiate short-term exclusivity tied to volume commitments to protect product roadmaps without erecting long-term lock-ins.
Regulatory and input dynamics that will shape winners
-
Regulation: New listings and substance limits in major regulatory regimes force reformulation and new test regimens. Manufacturers with pre-validated, low-risk chemistries will accelerate into regulated segments (medical, automotive), while others will face multi-quarter relaunch costs.
-
Raw-materials: Upstream feedstock shifts materially influence cost curves. Price volatility is not a market abstraction — it is a determinative variable for margin modeling and should be simulated across stress scenarios when sizing capacity investments.
-
Trade environment: Expanded tariff and trade policy actions have added sourcing complexity. Companies with diversified procurement footprints and local conversion capability will avoid service interruptions and margin compression caused by geopolitical shocks.
Technology and sustainability: the dual front where differentiation is bought
Two concurrent themes will separate winners from laggards:
-
Performance innovation. Advances in coating durability, abrasion resistance, and hydrophilic longevity (products now claiming multi-decade performance in some settings) change warranty economics and total cost of ownership for end users.
-
Regulatory-aligned sustainability. The market is moving toward lower-impact chemistries and circular-material conversations. PFAS-free anti-fog alternatives and demonstrable recyclability are not only compliance responses but also commercial differentiators in procurement processes that increasingly weigh lifecycle metrics.
Actionable 90‑day plan for executives
-
Supply assurance: Run a supplier stress test using our baseline scenarios to identify single points of failure and secure contingency agreements that include conversion capacity or tolling clauses.
-
Product roadmaps: Prioritize reformulation or qualification of at least one PFAS‑free or low‑content chemistry for key SKUs where regulatory risk is highest.
-
Commercial pilots: Launch two co-development pilots with differentiated partners — one with a global materials innovator and one with a regional fabricator — to hedge technology and logistics risk.
-
M&A and partnerships: Use our valuation sensitives and acquisition scorecards to screen targets that offer either vertical integration (coating application) or market access (regional distribution).
Why PW Consulting’s full study matters for your 2026 planning
Executives need more than headline growth numbers; they need executable roadmaps. Our full report provides the quantitative models, supplier-level intelligence, and transaction-oriented playbooks that translate market dynamics into concrete decisions: where to build, what chemistry to adopt, who to partner with, and how to price through upstream volatility. The public snapshot you’re reading shows the strategic contours; the full study supplies the confidential tables, regional demand drivers, and segmentation economics that corporate teams will use to finalize 2026 budgets and contracts.
Next steps
For teams formulating 2026 investments, procurement strategies, or M&A pipelines in anti-fog polycarbonate film and sheet, PW Consulting’s comprehensive study is structured to be immediately operational. The final report includes the raw model files, supplier scorecards, and negotiation playbooks referenced here — essential inputs to convert market opportunity into defensible advantage. Contact our advisory desk to schedule a briefing and access the full dataset, proprietary scenarios, and supplier intelligence needed to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Anti Fog Polycarbonate Film And Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Walk-In Humidity Chambers Market Set to Expand at 6.3% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Walk In Humidity Chambers Market 2026: Strategic Preview for Executive Decision-Making
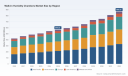
As organizations finalize capital and product development plans for 2026, the walk in humidity chambers market presents a predictable yet strategically nuanced growth corridor. At PW Consulting we frame this corridor not merely as an aggregate revenue trend — from USD 422.15 Million in 2020 to USD 566.52 Million in 2025 — but as a set of operational inflection points that will determine supplier selection, facility investments, and product roadmaps through the 2026–2032 forecast horizon. Our base-case outlook points to continued expansion (project-level CAGR of 6.3% across 2026–2032), culminating in a market that approaches USD 869 Million by 2032. This preview explains why that growth matters to senior leaders, what tactical choices it forces in 2026, and where the full research delivers the actionable detail your teams will need.
Walk In Humidity Chambers Market
Why this market matters to 2026 corporate plans
-
Testing and validation are moving from delegated lab hours to dedicated in-house facilities. Firms in electronics, aerospace, pharmaceuticals, automotive (including EV battery testing), and medical devices increasingly view controlled-environment capacity as a strategic asset rather than a commoditized service.
Walk In Humidity Chambers Market -
Regulatory and quality requirements continue to tighten — especially for pharmaceutical stability testing where ICH and FDA-aligned control regimes demand precise long-term humidity and temperature profiles. Compliance risk is now directly tied to chamber specification and ongoing calibration capability.
Walk In Humidity Chambers Market -
Operational priorities — energy efficiency, uptime, and digital monitoring — are reshaping procurement. Buyers are prioritizing total cost of ownership and service networks over first-cost alone.
Market trajectory and what it implies for 2026 decisions
The market’s steady expansion over 2020–2025 and the projected growth through 2032 reflect a combination of sustained demand from regulated industries and rising requirements in sectors such as battery testing and industrial electronics. For 2026 planning cycles, that translates into three immediate imperatives for executives:
-
Prioritize modularity and scalability in capital investments. Demand patterns are uneven across industries and product lifecycles; solutions that permit phased build-outs or reconfiguration will preserve optionality.
-
Factor in service and qualification capability as a negotiated deliverable. Long-term stability studies and high-value product testing are only as reliable as the maintenance, recalibration, and documentation chains that support them.
-
Accelerate energy-efficiency retrofit and specification standards. With operational runtime accounting for most lifetime cost, energy performance is a near-term differentiator.
Supply chain and component signals
-
Core construction relies on stainless-steel interiors and specialized insulation; procurement teams should expect periodic pressure on these inputs. High-performance compressors and precision humidity sensors are supply nodes with elevated risk profiles — a small number of specialized suppliers and rising demand for accurate control systems create potential bottlenecks.
-
Because humidity sensor availability and quality directly affect test validity, technical due diligence on sensor suppliers (including calibration traceability) needs to become a standard step in vendor qualification.
-
Manufacturers are responding with design choices that reduce exposure: modularized panels, standardization of control electronics, and options for local sourcing of common components. Buyers should insist on BOM transparency where long-term service is critical.
Regulatory and standards landscape
Regulatory frameworks are a major driver of product specification. Walk in humidity chambers intended for pharmaceutical stability testing must meet ICH conditions for long-term and accelerated studies, and many are engineered to comply with FDA, GMP, ISO 17025 and CE requirements. For 2026 procurement and validation plans that support regulated product launches, compliance pathways must be mapped into procurement timelines — including IQ/OQ/PQ sequences, software validation for monitoring systems, and documentation for audit readiness.
Competitive landscape — who matters and why
The market structure reflects a mix of specialized incumbents and regional manufacturers. The three- and five-firm concentration ratios (CR3 ~31.4%, CR5 ~42.8%) indicate a moderately fragmented market where specialist capabilities and service footprints offer meaningful differentiation.
-
BINDER GmbH (Tuttlingen, Germany) — Notable for ICH-focused walk-in solutions and advanced monitoring options. Recent strategic M&A has expanded its pharmaceutical stability reach and control-system capabilities.
-
Russells Technical Products (Holland, MI, USA) — Offers modular W-Series designs and altitude testing options, positioning it well for niche applications requiring custom thermal-humidity-altitude envelopes.
-
Weiss Technik North America (Grand Rapids, MI, USA, including CSZ) — Broad product range and brand depth across environmental simulation with recent manufacturing capacity expansion signaling stronger North American supply resilience.
-
Associated Environmental Systems (AES, North Chelmsford, MA) — Emphasizes custom and heavy-duty builds; recent facility relocation nearly doubled manufacturing space, a clear play for larger-volume and bespoke programs.
-
Darwin Chambers Company — Focused on pharmaceutical walk-in rooms and GMP storage; a preferred partner for organizations looking to outsource design-build-install projects with regulatory alignment.
-
Parameter Generation & Control (A BINDER Company) — Known for rapid-delivery lines and standard sizes tuned to stability testing; now integrated into a larger platform to extend reach and delivery capability.
-
Testron Group & Wewon (China-based providers with US support) — Competitive on lead times and customization, increasingly focused on sustainability (ISO14001) and regional aftersales networks.
Recent moves matter: BINDER’s acquisition of Parameter Generation & Control (July 2025) demonstrates consolidation aimed at vertical capability in pharmaceutical stability systems. AES’s and Weiss Technik North America’s manufacturing expansions (late 2025 and 2026 respectively) signal that suppliers are allocating capital to capacity and near-shore production — a response to demand growth and to customer preferences for shorter lead times and local service footprints.
Strategic questions for 2026 planning cycles
-
Do we treat controlled-environment capacity as a capital asset or an outsourced service? The answer will vary by industry and product lifecycle stage — but for regulated product portfolios, in-house control often mitigates supply and scheduling risk.
-
What level of supplier consolidation reduces risk without sacrificing innovation? The market shows room for specialists; however, consolidation trends indicate benefits from platform capabilities (software-enabled monitoring, rapid delivery, qualification services).
-
How will energy and lifecycle costs alter the ROI on replacement vs retrofit? Incorporating energy modeling and TCO runs during 2026 procurement cycles can change the preferred vendor, especially for high-utilization environments.
-
Which vendors demonstrate validated compliance workflows and documentation for IQ/OQ/PQ — and can they provide sustained local calibration support?
What PW Consulting’s full report provides (practical and operational deliverables)
-
Detailed market sizing and forecast models (2020–2032) with scenario variants reflecting demand shocks, regulatory tightening, and energy-cost sensitivity.
-
Vendor profiles and a decision-support matrix that evaluates suppliers on compliance, delivery lead time, TCO, and service network maturity.
-
Commercial negotiation playbook and contract clauses tailored to lifecycle support, spare parts availability, and performance SLAs.
-
Procurement-ready technical checklists, IQ/OQ/PQ templates, and a supplier due-diligence scorecard focused on humidity-control systems.
-
Capex planning tools including a TCO calculator and energy-performance benchmark suite to evaluate retrofit versus replacement decisions.
-
Scenario-based risk maps identifying supply-chain pinch points (critical raw materials, compressors, humidity sensors) and mitigation actions including dual-sourcing strategies and local stocking policies.
To honor the “trailer” principle: this article highlights the strategic contours and decision levers you need for 2026, but the granular segment breakdowns, regional and application-specific forecasts, and downloadable procurement templates are available only in the full Walk In Humidity Chambers Market report. Those datasets include the detailed splits, supplier scorecards, and financial models that procurement, facilities, and R&D teams will use as inputs into 2026 budgets and capital plans.
Immediate next steps for executives
-
Fast-track a multidisciplinary review (procurement, facilities, QA, and R&D) to convert strategic priorities into a 2026 capital and service plan.
-
Request vendor demonstrations that include live-data monitoring, energy consumption metrics, and maintenance logistics during bid evaluations.
-
Integrate sensor and control-system verification into supplier acceptance criteria; insist on documented calibration trails tied to ISO/ICH/FDA expectations.
-
Consider small-scale pilot purchases to validate supplier delivery, documentation, and service before committing to multi-site rollouts.
In the current cycle, the market’s steady growth masks a set of operationally critical differentiators: compliance assurance, uptime and service models, energy performance, and supply-chain resilience. Getting those elements right in 2026 will determine whether controlled-environment capabilities become a competitive advantage or a recurring risk. For a full, actionable briefing — including the segment-level forecasts, supplier rankings, and procurement tools you need to operationalize this strategy — access the complete PW Consulting Walk In Humidity Chambers Market report.
For detailed analysis of this topic, please visit the official page: Walk In Humidity Chambers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Telescopic Jack Market to reach USD 1,064.28 Million by 2032 (5.48% CAGR)
By PW Consulting, 2026-07-13
Telescopic Jack Market — 2026 Strategic Outlook: Why PW Consulting’s New Study Should Be on Every C‑Suite Agenda
As companies prepare budgets, product roadmaps, and M&A pipelines for 2026, the telescopic jack market is quietly reshaping the economics of lifting, maintenance and modular construction across multiple industrial value chains. PW Consulting’s new market study — grounded in a 2020–2025 historical base and a robust 2026–2032 forecasting framework — translates complex industry signals into decision-ready guidance. The analysis combines market sizing, competitive mapping, regulatory risk assessments and practical execution playbooks designed to inform capital allocation and commercial strategy in the coming 18–36 months.
Telescopic Jack Market
Market snapshot: scale, trajectory and what it means for 2026 planning
Our base-year view (2025) places the global telescopic jack market in the mid‑hundreds of millions (USD, revenue units in Millions), following steady growth through the 2020–2025 period. The market is projected to continue expanding at a compound annual growth rate (CAGR) of about 5.48% across the 2026–2032 forecast horizon, reflecting steady demand across elevator systems, heavy vehicle maintenance, tank erection, industrial lifting and specialty applications such as aerospace and mining.
Telescopic Jack Market
For executive teams, two practical takeaways emerge from the macro picture: first, steady rather than explosive growth means strategic moves should prioritize margin protection, operational efficiency and niche leadership. Second, predictable demand trajectories favor investments in platform scalability (manufacturing and service networks) and in product variants that unlock adjacent revenue streams (rental, maintenance contracts, electrified actuation).
Telescopic Jack Market
Strategic implications for 2026 decision cycles
- Capital spending and capacity planning: With stable CAGR-driven expansion, 2026 capital allocation should balance incremental capacity investments against flexible, contract-based capacity (e.g., rental fleets and OEM partnerships) to avoid overcommitment in cyclical pockets.
- Product roadmap prioritization: Multi-stage hydraulic designs remain core to many high-load applications, while electrified telescopic solutions and pneumatic variants are gaining traction for low-noise, precision and eco-regulatory use cases. Prioritize modularity and serviceability as differentiators.
- Supply chain resilience: High-strength carbon steel and welded assemblies dominate input requirements (per industry manufacturing standards). Secure long-term supply contracts and consider dual-sourcing for critical components to hedge raw material volatility and lead-time risk.
- Regulatory & certification readiness: Compliance is non-negotiable in elevator and tank erection segments (ASME A17.1/CSA B44, API 650 and welding codes such as AWS, with CWB certification expectations in some geographies). Factor certification timelines into product launches and tender responses.
- Service and rental economics: Rental and integrated service offerings can convert hardware sales into annuity streams — an especially attractive play given the market’s steady growth profile and rising demand for on-site lifting solutions in construction and industrial maintenance.
What the PW Consulting report delivers — operational, not academic
This study is designed for implementers. It moves beyond high-level forecasts to deliver tools you can put to work in 90–180 days:
- Granular market sizing and a repeatable forecast model (2026–2032) that powers portfolio stress-tests and “what-if” scenarios.
- Segment and channel diagnostics that identify profitable niches and demand elasticities (note: detailed split tables and model outputs are available in the full report).
- Value chain mapping and a supplier-cost index that highlights the levers to improve gross margins.
- Buyer decision frameworks for OEMs, rental houses and end-users to prioritize specs, compliance, and lifecycle costs.
- Competitive benchmarking (product, certification, channel reach) and a five-step M&A screening playbook for roll-up opportunities.
- Case studies that show how manufacturers moved from transactional sales to service-led revenue, including operating model charts and P&L impact estimates.
- Primary interview findings and a data appendix documenting sources, sampling and triangulation logic for reproducibility.
Competitive dynamics — what to watch among the established players
The market structure balances regional specialists and product-focused manufacturers. A few features define competitive advantage today:
- Product specialization vs. system integration: Some firms lead with purpose-built telescopic hydraulic elevator jacks optimized to ASME/CSA standards and compact, synchronized cylinders for holeless or inground installations. Others concentrate on heavy-duty jacks for tank erection, machinery lifting and rental fleets. The best performers marry product depth with integration into service and rental ecosystems.
- Manufacturing competence and certification: Companies with certified welding facilities and documented quality systems (ISO/CWB/AWS-aligned) command price premiums in regulated applications — particularly elevators and storage tank projects where safety codes are prescriptive.
- Operational models: A split exists between manufacturers that sell and those that combine sale-and-rent, or provide full lifting solutions for construction and industrial clients. Service capability and rapid field response increasingly determine contract wins.
Representative profiles (high-level):
- Elevator Equipment Corporation (EECO) — Notable for telescopic hydraulic elevator jacks built to elevator safety codes, strong materials-engineering orientation and compact multi-stage units suitable for passenger and freight elevator OEMs and refurbishments.
- ITI Hydraulik — Focuses on synchronized multi-section jacks that reduce civil work requirements and improve ride quality for hydraulic elevator installations; an example of engineering-driven differentiation aimed at cost reduction in installation.
- Bygging Infrastructure & Astha Infra Engg — Both firms exemplify the tank-erection specialists: product suites and rental models tailored to lifting thin-walled structures and bolted tanks, emphasizing safety systems and on-site services for global project work.
- Powerjac Systems & Taha International — Suppliers that cater largely to heavy machinery lifting and industrial customers, where stroke-in-constrained-space requirements and ruggedness are the key buying criteria.
- Compac GmbH (Hydraulik‑Vertrieb) — A European supplier focused on floor and transmission jacks for heavy vehicles, showcasing how niche product ergonomics and low minimum height designs drive value in automotive and heavy truck service markets.
Market structure, concentration and strategic consequences
The market demonstrates a moderate degree of concentration: the top three to five players together control a meaningful portion of revenue, but there remains ample room for specialized entrants and regional champions. For corporate strategists, this structure implies two clear paths: consolidate horizontally to capture scale and procurement leverage, or pursue vertical specialization (certified elevator systems, rental fleets, electrified actuation) to defend high-margin niches.
Regulatory and material dynamics that will shape 2026 outcomes
Materials and standards are not abstract constraints — they materially affect cost, time-to-market and contract eligibility. High-strength carbon steel is the prevalent material set for pistons, cylinders and structural members, and welding follows AWS and applicable parts of domain-specific codes. Elevator-centric products must align with ASME A17.1/CSA B44 provisions; tank-erection lifting practices adhere to API 650 guidance. These requirements translate into non-trivial lead times for certified manufacturing processes and create barriers to rapid, low-cost entry.
Recommended 2026 plays — a tactical checklist
- Prioritize investments in certification and testing infrastructure where you target elevator or API‑governed tank markets; being pre‑qualified shortens sales cycles.
- Expand service and rental capability as a lower-risk route to geographic expansion; align pricing models to lifecycle economics rather than one‑time hardware margins.
- Introduce modular product families that leverage shared components (cylinders, seals, valves) to reduce SKUs and simplify after-sales logistics.
- Pursue selective M&A to consolidate supply chain positions (critical steel components, machining capacity) in regions where logistics and lead times materially affect competitiveness.
- Embed digital monitoring and predictive maintenance features to differentiate on total cost of ownership and create recurring software-enabled revenue streams.
Using this study in boardroom decision-making
PW Consulting’s market model and playbooks are built for executives who need to translate market intelligence into capital allocation, product investments and go-to-market moves within the 2026 planning cycle. Use the report to: stress-test portfolio roadmaps, construct supplier scorecards, size M&A targets, model service revenue scenarios and set certification roadmaps aligned with tender calendars.
Next steps — where to find the full intelligence
This introduction surfaces the most consequential strategic signals and executable recommendations from our study while intentionally omitting the detailed segmentation tables and proprietary scenario matrices that underpin tactical actions. To access the full dataset, segmentation breakdowns, company scorecards and downloadable financial models that support transaction diligence and operational planning, please visit the report landing page listed in our distribution materials. PW Consulting’s advisory team is also available for tailored briefings that map the findings directly to your portfolio and address specific scenarios such as market entry, capability build vs. buy, and rental fleet economics.
In sum: the telescopic jack market offers steady growth and clear pockets of high return for players that combine certified manufacturing capability, service-led commercial models and disciplined supply chain control. For 2026 planners, the time to align strategy with certification, modular product design, and service monetization is now.
For detailed analysis of this topic, please visit the official page: Telescopic Jack Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fuel Vapor Canisters Market to grow at 3.42% CAGR through 2032
By PW Consulting, 2026-07-13
Automotive Fuel Vapor Canisters Market — Strategic Preview for 2026 Decisions
Executive trailer: what this preview delivers
As original equipment manufacturers (OEMs), Tier‑1 suppliers, aftermarket specialists and private‑equity investors plan for the critical 2026 decision window, the Automotive Fuel Vapor Canisters market presents a mix of steady growth, regulatory-driven technology demand and concentrated supplier economics. This preview synthesizes the macro trajectory (historical performance and base‑case forecast through 2032), the regulatory inflection points that will shape product specifications, and the supplier dynamics that matter when allocating R&D, procurement and M&A capital. The aim is to show the analytical depth that informs PW Consulting’s full study while intentionally withholding the granular segmentation tables and line‑item forecasts that are available in the full report.
Automotive Fuel Vapor Canisters Market
Market snapshot: scale, rhythm and near‑term outlook
Between 2020 and 2025 the market expanded modestly, reflecting the interaction of vehicle parc dynamics, tightening evaporative‑emission regulations, and the continued role of combustion powertrains in global mobility. In 2025 the global market reached approximately USD 2.95 billion. Under PW Consulting’s baseline modelling — which incorporates regulatory timelines, OEM cycle plans and material‑supply assumptions — the market is expected to grow at a compound annual growth rate of about 3.42% through the 2026–2032 forecast window, reaching an estimated market size north of USD 3.7 billion by 2032. This is a growth profile of steady, regulation‑anchored demand rather than explosive expansion, and it implies different strategic priorities than markets driven primarily by disruptive technology adoption.
Automotive Fuel Vapor Canisters Market
Why 2026 is a strategic inflection
- Regulatory alignment and product specifications: New evaporative emission test procedures and running‑loss standards adopted by major regulators have a phase‑in cadence that centers on 2026–2028. These standards do more than tighten acceptable emissions — they prescribe test protocols, working‑capacity criteria and size/pressure thresholds that materially affect canister designs, media formulations and system packaging.
- OEM program timing: Vehicle program development cycles mean that specification freezes and supplier selection decisions made in 2026 influence model years launching through the late 2020s. Suppliers that can demonstrate compliance at program sign‑off stand to win multi‑year content partnerships.
- Supply chain tightening for activated carbon: The adsorbent media at the heart of most canisters is subject to feedstock variability and capacity bottlenecks. Securing validated media—both in performance and in sustainable sourcing—becomes a procurement priority as OEMs push for validated high‑capacity media to meet new testing regimes.
What the PW Consulting report contains (practical, decision‑grade content)
The full study is built to support capital allocation, product roadmaps and commercial negotiation through:
Automotive Fuel Vapor Canisters Market
- Proprietary market sizing and a clear, auditable forecast model (2026–2032) that ties unit volumes to vehicle production scenarios, regulatory adoption curves and technical upgrades in canister design.
- Technology and test‑protocol gap analysis that maps regulatory requirements (e.g., running loss, butane working capacity and breakthrough criteria) to product attributes — media capacity, flow characteristics, purge strategies and canister sizing constraints.
- Procurement playbooks for activated carbon and composite housings: supplier scorecards, risk heatmaps and inventory/contract structures to mitigate feedstock and freight volatility.
- Go‑to‑market recommendations for OEMs and aftermarket players, including channel segmentation, warranty risk assessment and pricing sensitivity under different regulatory and fuel blend scenarios (gasoline, ethanol blends, LPG and methanol variants).
- Deal rationales for M&A and JV candidates, including financial thresholds, integration pitfalls and a framework for valuing proprietary media formulations or modular canister platforms.
Concrete tools include a scenario‑driven forecast workbook, supplier negotiation checklists and regulatory compliance matrices — all designed for immediate operational use by procurement, engineering and corporate development teams.
Competitive landscape: who matters and why
The market is commercially concentrated: a limited set of established suppliers dominate global content for activated carbon canister systems while a mix of aftermarket specialists and materials producers shape the complementary value chain. The players profiled in the study illustrate the strategic choices facing buyers and investors:
- PHINIA Inc. — A specialist with deep expertise in modular carbon canisters and integrated OBD/evaporative solutions. PHINIA’s long product lineage and modular approach make it a natural partner for OEMs that require flexible tank‑size support and fuel‑blend compatibility.
- A. Kayser Automotive Systems GmbH — A market leader in activated carbon canister systems, with full systems capability (valves, ventilation and purge lines). Kayser’s systems depth positions it to capture engineering content beyond the canister itself, which raises competitive barriers to smaller suppliers.
- MAHLE GmbH — An OEM‑grade supplier with integrated fuel management platforms. MAHLE’s scale and engineering resources allow it to drive system integration wins where thermal and packaging constraints must be solved across powertrain architectures.
- Standard Motor Products, Inc. (SMP) — A dominant aftermarket player with an expansive EVAP program and recent program and product expansions in 2025–2026. SMP’s aggressive coverage on late‑model applications underscores aftermarket growth opportunities and the importance of spares availability for in‑service fleets.
- MotoRad — Focused on EVAP canisters for replacement and service markets; a reminder that aftermarket channel strategies and warranty economics can support differentiated pricing and margin profiles versus OEM supply.
- Ingevity Corporation — A leading activated carbon producer whose hardwood‑based media is widely used in automotive EVAP systems. Media suppliers like Ingevity influence technical capability, validation timelines and, crucially, raw material availability.
Recent public moves — for example, SMP’s program expansions announced in mid‑2025 and early‑2026 — signal the aftermarket’s proactive response to fleet replacement needs and late‑model coverage. Regulatory updates (notably CARB’s 2022 adoption of new evaporative test procedures) functionally elevate the technical bar for all suppliers and accelerate qualification timelines for media and modules.
Regulatory & material dynamics that will shape supplier economics
- Test protocols become product drivers: Rules that define working‑capacity (for example, butane loading and 2‑gram breakthrough criteria), stabilization cycling and purge protocols create engineering targets. Suppliers that invest in test‑bench validation and can provide OEMs with documented compliance will command a premium in supplier selection.
- Feedstock and capacity risk for activated carbon: High‑capacity, durable adsorbent media is not a commoditized input in automotive EVAP contexts. Variability in feedstocks and converting capacity can create multi‑quarter qualification lead times; buyers should consider multi‑sourcing, inventory buffer strategies and strategic contracts with performance clauses.
- Design complexity and system integration: As evaporative regimes broaden to cover running loss, diurnal and hot‑soak emissions, canister solutions increasingly need multi‑layer media, high‑flow passages and integrated control valves. Suppliers with systems capability (canister + valves + lines + OBD integration) extract higher content per vehicle and create switching costs.
Practical strategic moves for executives in 2026
- For OEMs and Tier‑1s: Fast‑track canister validation projects tied to regulatory deadlines; prioritize suppliers that can demonstrate test‑bench data under the adopted protocols. Incorporate performance‑based contracting with media suppliers (e.g., warranty‑linked adsorption metrics) to de‑risk compliance.
- For suppliers and materials firms: Differentiate on validated media performance and systems integration capability. Consider modular platforms that allow tuning of media volumes and purge strategies across vehicle programs to increase addressable content without reinventing packaging.
- For aftermarket players: Leverage late‑model coverage expansions and warranty repair trends to build recurring revenue streams. Strengthen logistics and SKU rationalization to reduce time‑to‑repair for high‑utilization fleets.
- For investors and M&A teams: Target bolt‑on acquisitions that add validated media capacity, systems integration know‑how or regional manufacturing footprint in high‑volume OEM hubs. Avoid assets that are long on product but lack documented compliance to the latest test procedures.
Risk matrix — what could upset the base case
- Accelerated EV adoption in specific markets: Faster‑than‑expected electrification in key regions would reduce demand for ICE canisters and compress the market sooner than modelled.
- Feedstock shocks: Disruptions in activated‑carbon feedstock or conversion capacity could spike prices and materially affect supplier margins and qualification timelines.
- Regulatory variance: Divergent test interpretations or delayed implementation in major markets can create asymmetric adoption and inventory build cycles; this favors suppliers with geographic diversification.
Conclusion — the 2026 decision agenda
For organizations making strategic commitments in 2026, the fuel vapor canister market requires a focused, evidence‑based approach: prioritize validated technical compliance, secure media supply under performance guarantees, and evaluate partnerships that raise system‑level content rather than simply component supply. The market’s steady growth and regulatory anchoring create predictable opportunity — but converting that into durable commercial advantage hinges on execution across engineering validation, procurement design and channel strategy.
Next step
PW Consulting’s full Automotive Fuel Vapor Canisters Market report provides the detailed segmentation, supplier scorecards, scenario financials and downloadable forecast model needed to operationalize the recommendations above. To access the proprietary tables, regional and application splits, and the complete forecast workbook, please consult the report brief on our website or contact our industry team for a demonstration.
For detailed analysis of this topic, please visit the official page: Automotive Fuel Vapor Canisters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Grade Power Supplies to Reach USD 2,151.6M by 2032 at 5.8% CAGR
By PW Consulting, 2026-07-13
Medical Grade Power Supplies Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise but deep preview of our forthcoming Medical Grade Power Supplies Market study. This briefing is written as a strategic primer for executive teams preparing 2026 plans—highlighting the macro trajectory, structural dynamics, competitive moves, regulatory inflection points, and the practical intelligence our full report delivers. We intentionally show methodological depth and directional conclusions while withholding segment-level granularity to preserve the value of the full report.
Medical Grade Power Supplies Market
Market at a Glance — The Macro Trajectory
The global medical-grade power supplies market has moved from a post‑pandemic recovery phase into a structurally growing market characterized by steady demand from diagnostic imaging, patient monitoring, and an expanding at‑home medical device base. Our base-year calibration (2025) and historical series (2020–2025) underpin a forecast through 2032 that assumes moderate but resilient expansion: a mid-single-digit compound annual growth rate (CAGR) of approximately 5.8% from 2026 across the forecast horizon. Under our central scenario the total market expands meaningfully by 2032, reflecting both replacement cycles in hospital estates and an increasing share of power-intensive devices in ambulatory and home-care settings.
Medical Grade Power Supplies Market
Why This Matters for 2026 Strategic Planning
- Procurement & Sourcing Strategy: The market’s steady growth and supplier concentration dynamics imply that procurement teams should shift from transactional buying to supplier portfolio optimization—balancing reliability, compliance, and cost predictability across multi-year contracts.
- R&D and Product Roadmapping: Regulatory tightening and EMC requirements raise technical entry thresholds. Firms that front-load investment in isolation topologies, leakage-current minimization, and EMC shielding will shorten time-to-market for 2026 product launches.
- M&A and Partnership Playbooks: Market concentration and specialized capabilities create fertile ground for bolt-on acquisitions and strategic alliances focused on certification expertise and application‑specific designs.
- Go‑to‑Market Timing: Regulators and reimbursements influence adoption curves—understanding both is essential to time launches, especially for products that depend on hospital procurement cycles or durable medical equipment (DME) reimbursements.
Key Dynamics Shaping 2026 Decisions
- Regulatory Tightening: Medical power supplies must meet modern safety and risk management requirements—including updated IEC 60601-1 editions and mandatory risk management per ISO 14971. EMC standards have been tightened in the latest IEC 60601-1-2 4th edition, raising immunity thresholds and increasing test complexity for suppliers and OEMs alike.
- Supply‑chain Input Pressure: Component-level constraints remain a near-term cost and reliability issue. For example, high‑purity copper foil costs increased materially in 2024, stressing transformer margins and encouraging design optimization or dual-sourcing strategies.
- Reimbursement & End‑market Economics: Certain device classes continue to benefit from defined reimbursement pathways—an example is the HCPCS code covering power supplies for specific therapeutic devices. Where reimbursement exists, unit economics can support higher product development and certification costs.
- Quality & Safety Events: Recent Class II recalls tied to capacitor failures underscore the reputational and regulatory risks of component selection. Risk mitigation via supplier qualification, accelerated life testing, and traceable BOMs is now non‑negotiable.
Competitive Landscape — Who Matters and Why
The competitive field is a mix of long-established power specialists, diversified electronics conglomerates, and regional OEMs that serve vertical niches. Competitive intensity is moderate and characterized by technology-driven differentiation rather than pure price competition—though commoditization pressure exists at lower power bands.
Medical Grade Power Supplies Market
- Advanced Energy / Artesyn / SL Power (Advanced Energy group): These units combine high‑power capabilities and compliance breadth—supplying AC‑DC and DC‑DC platforms certified to contemporary IEC safety editions. Recent expansions include higher-wattage models and parallelable architectures that target imaging and surgical suites.
- XP Power: Focused on external/internal modular supplies, XP emphasizes margin‑accretive features such as 2xMOPP isolation and product families tailored for home healthcare and laboratory instruments. Their 2025 product introductions reflect a push into higher-density imaging applications.
- MEAN WELL & Delta Electronics: These manufacturers play a volume-to-value role—offering BF-class insulation and broad product portfolios for ventilators, infusion pumps, and bed systems. Certification updates and product refreshes in 2025 indicate active pursuit of clinical OEMs.
- TDK‑Lambda & Cosel: Japanese incumbents continue to compete on EMC performance, compact chassis solutions, and custom OEM designs—leveraging deep technical certifications and local market trust.
Collectively, top players account for a meaningful share of supply capacity, with the market exhibiting moderate concentration—enough that strategic decisions around partnerships, IP ownership, and factory footprint have material implications for access and margins.
Recent Industry Moves (Strategic Implications)
- Product introductions through 2025 show a clear trend: higher power density at certified isolation levels, and external modules tailored for imaging and ultrasound—indicating OEM demand for turnkey certified blocks that accelerate device certification.
- Certification updates and product expansions highlight the industry’s response to the newest IEC editions—firms that invested early in compliance are now converting that investment into commercial momentum.
- Supply‑side cost shocks (e.g., copper foil) and component reliability incidents place a premium on supply chain resilience—buyers should expect pass-throughs and periodic lead‑time volatility into 2026.
What the Full PW Consulting Report Contains (Practical Tools for 2026)
Our full market study is structured to be immediately operational for leadership teams. Key deliverables include:
- Top‑down market sizing and bottom‑up validation (base year 2025), with scenario-based forecasts through 2032 calibrated to regulatory and reimbursement pathways.
- Supply chain maps and a component risk heatmap that quantifies exposure to critical inputs, single‑source suppliers, and lead‑time sensitivities.
- Certification and compliance tracker (including IEC editions, EMC testing requirements, and emerging cybersecurity expectations) that links regulatory timelines to product release calendars.
- Commercial playbooks: go‑to‑market templates for new product introductions, distributor strategies, and OEM channel economics.
- Competitive intelligence dossiers for the leading suppliers, including capability matrices, recent product pipelines, and recommended counter‑moves.
- Acquisition target shortlist and valuation cushions (qualitative and quantitative) built from public filings, product breadth, and certification IP.
- Supplier scorecards and procurement KPIs designed to move procurement from tactical buying to strategic supplier relationship management.
Note: detailed segment‑level tables and regional/application splits are intentionally excluded from this preview; the full report contains the complete, attributable tables and interactive dashboards.
Actionable Strategic Recommendations for 2026
- Prioritize Certified Blocks for Faster Time‑to‑Market: For device OEMs targeting hospital tenders or regulated home-care markets, procure pre‑certified modules where feasible to reduce project risk and shorten approval timelines.
- Build Redundancy into Critical BOMs: Dual‑sourcing critical passive components and qualifying alternate transformer vendors will mitigate near‑term cost and supply shocks.
- Invest in EMC & Leakage Testing Early: Embedding EMC mitigation and leakage‑current control into early design reduces costly rework when testing to the latest IEC 60601‑1-2 benchmarks.
- Make Certification a Strategic Asset: Firms that own test suites, compliance documentation, and recognized test partners translate certification speed into commercial advantage—consider strategic partnerships or acquisitions to acquire these capabilities.
- Monitor Reimbursement Pathways: Where reimbursement is available, design trade-offs that increase device robustness and lengthen field life can be justified by improved unit economics.
How to Use This Preview
Consider this article a strategic framework: it identifies the market direction, the levers that matter for 2026, and the operational capabilities that separate leaders from followers. For teams preparing budgets, product roadmaps, or M&A lists, the full PW Consulting study provides the actionable tables, supplier-level data, and scenario models you will need to finalize plans.
Closing — The Strategic Edge for 2026
Medical power supplies sit at the intersection of safety, reliability, and regulatory complexity. Our market model—anchored on a 2025 base and a multi‑year forecast through 2032—shows a market expanding at roughly a mid‑single-digit CAGR. That growth masks important heterogeneity: some subsegments are seeing accelerated demand due to procedural digitization and home-care decentralization, while certification and component risk create barriers and opportunities in equal measure.
Executives who treat power supplies as a strategic component—rather than a commoditized box—will unlock faster product approvals, steadier margins, and lower regulatory risk. To access the full dataset, modeled scenarios, and our supplier scorecards that translate these insights into executable 2026 plans, request the complete PW Consulting Medical Grade Power Supplies Market report.
For detailed analysis of this topic, please visit the official page: Medical Grade Power Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Defense Asset Management Software to Reach USD 3,432.7M by 2032 (8.45% CAGR)
By PW Consulting, 2026-07-13
Defense Asset Management Software Market — Strategic Brief for 2026 Decision-Makers
As the world’s defense organizations accelerate platform sustainment, interoperability, and digitization, software that manages military assets is shifting from administrative tool to operational imperative. PW Consulting’s new market study — built on a 2020–2025 historical foundation and a 2026–2032 forecast horizon — quantifies that transition and translates it into actionable guidance for executives planning procurement, integration, and sustainment strategies in 2026.
Defense Asset Management Software Market
High-level market trajectory
Our base-year analysis (2025) and forward modeling show a market expanding at a compound annual growth rate of 8.45% across the forecast window. In practical terms, the market nearly doubles in scale from the mid-2020s into the early 2030s, driven by a convergence of programmatic modernization, regulatory pressure, and a wave of cloud- and AI-enabled product enhancements. This trajectory creates three categories of opportunity for defense stakeholders: immediate (risk reduction and compliance), medium-term (operational readiness and lifecycle cost reduction), and strategic (digital continuity and force transformation).
Defense Asset Management Software Market
Why this research matters for decisions in 2026
-
Procurement windows are compressing. The DoD’s Software Modernization Implementation Plan (FY25–26) creates new procurement dynamics—enterprise licensing, SaaS Authority to Operate (ATO) pathways, and FinOps disciplines—that materially change total cost of ownership and vendor selection criteria.
Defense Asset Management Software Market -
Operational requirements are evolving beyond maintenance schedules to include AI-enabled readiness forecasting, multi-domain asset visibility, and data fusion across logistics and operations. Programs such as the US Air Force’s Next-Generation AOC initiatives will demand asset management capabilities that integrate into mission-level decisioning.
-
Security and compliance are non-negotiable. CMMC 2.0 asset management practices, DLMS requirements for logistics data, and DCMA IT asset management directives mean implementation teams must treat software adoption as a combined technology-and-policy program.
Key strategic implications for 2026 planning
-
Favor composable architectures that can meet both operational and regulatory needs. Vendors that provide modular EAM/ALM (Enterprise Asset Management / Asset Lifecycle Management) components—capable of running securely on approved cloud enclaves or on-premise stacks—significantly reduce integration risk during contract execution.
-
Account for specialized labor as a material line item. Implementation, integration, and ongoing sustainment require personnel with security clearances and domain experience; these human costs frequently exceed basic software license spend and should be scoped early in procurement.
-
Design procurement around SaaS ATO and enterprise licensing opportunities. Where possible, leverage emerging DoD enterprise agreements and FinOps practices to accelerate deployment and reduce duplication of license management across programs.
-
Prioritize interoperability with logistics and standards frameworks. Compliance with logistics standards and the ability to transform non‑compliant legacy data are decisive capabilities for vendors competing for defense contracts.
-
Build AI and data integration into the business case, not as an afterthought. Recent vendor releases and pilot programs signal that asset health prediction, readiness scoring, and automated maintenance orchestration will be differentiating features during the next procurement cycle.
What’s in the full PW Consulting study (practical deliverables)
- Validated market-sizing using our 2020–2025 historical base and scenario-driven forecasts through 2032, including sensitivity models for technology adoption and regulatory shifts.
- A buyer’s playbook: procurement checklists, sample RFP language tailored for defense acquisition, SaaS ATO roadmaps, and a FinOps workbook for total-cost-of-ownership calculations.
- Implementation tooling: phased migration templates (on-premise to cloud, hybrid patterns), integration patterns for logistics standards, and security-control mappings aligned to CMMC/DLMS/DCMA guidance.
- Vendor evaluation materials: methodology and scorecards for capability, compliance, scalability, and sustainment; red-team considerations for supply chain and cybersecurity risk.
- Case studies and use cases demonstrating runway reductions in maintenance downtime, improvements in mission-availability metrics, and cost-to-service improvements under alternative deployment scenarios.
Competitive landscape — how to read the market
The competitive field is functionally segmented into three groups: large enterprise software vendors, defense primes and systems integrators, and specialized niche vendors. Our CR metrics identify a market with meaningful scale concentration at the top but substantial room for specialized players to win program-specific business. That structure produces predictable outcomes:
-
Enterprise incumbents (e.g., global ERP and EAM providers) bring broad lifecycle capabilities, deep integration stacks, and established enterprise licensing models conducive to large-scale, cross-domain deployments. Their value is strongest where defense organizations seek a single-source backbone for asset lifecycle, finance, and procurement integration.
-
Defense primes and systems integrators embed asset-management capability inside platform sustainment offers, often combining software with logistics engineering, depot modernization, and long-term sustainment contracts—an attractive model for platform-centric programs requiring tight lifecycle control.
-
Specialist vendors deliver rapid, feature-rich offerings focused on fleet management, MRO, or DoD contractor compliance and often provide faster time to capability for specific asset classes. These vendors are frequently the innovators in niche functional capability—AI-enabled diagnostics, complex parts tracking, or defense-grade inventory control.
For 2026, decision-makers should expect vendor competition to center on three axes: compliance-first readiness (ATO, CMMC), integration depth (ERP/PLM/logistics standards), and productized AI capabilities for predictive maintenance and readiness forecasting.
Recent programmatic and product developments that matter
-
Policy-level momentum from the DoD’s Software Modernization Plan is reshaping enterprise purchasing behavior—encouraging SaaS adoption under clearly defined security and licensing constructs.
-
Operational programs—such as next-generation command center initiatives—are creating new requirements for data fusion between asset management and mission systems, accelerating demand for interoperable solutions.
-
Vendors are responding: we have observed targeted releases and AI-enhancements aimed at defense asset management, signaling a near-term product cycle focused on predictive analytics and operational integration.
Risk factors and mitigations
-
Regulatory misalignment: procurement that does not account for SaaS ATO, CMMC, and DLMS interoperability risks project delays. Mitigation: pre-ATO discovery, inclusion of compliance milestones in contracts, and use of a regulatory mapping annex in Statements of Work.
-
Underestimated integration costs: legacy data and non‑standard inventory codes can balloon implementation efforts. Mitigation: early data health audits and budgeted transformation sprints.
-
Talent scarcity: cleared, domain-experienced staff are scarce and costly. Mitigation: hybrid staffing models, strategic use of specialist vendors, and investment in vendor‑provided managed services where appropriate.
A recommended decision framework for 2026
-
Define a succinct, measurable mission outcome (e.g., platform availability, depot throughput, fleet readiness) and map required functional capabilities to that outcome before engaging vendors.
-
Shortlist vendors using a layered evaluation: compliance gating, reference-based functional scoring, integration effort estimate, and sustainment economics over a 7–10 year horizon.
-
Run a focused pilot aligned to an operationally meaningful objective and scaled to expose integration, people, and regulatory risks within 6–12 months.
-
Institutionalize FinOps and license-governance within acquisition and sustainment teams to capture efficiency gains from enterprise agreements and shared services.
-
Lock in data stewardship and transformation standards to guarantee continuity as systems evolve and platforms are modernized.
Closing — how PW Consulting’s study supports your 2026 roadmap
Our research equips leaders with the market sizing and trend context necessary to prioritize investments, the procurement and technical playbooks required to execute quickly and compliantly, and vendor evaluation tools to make defensible vendor choices. We intentionally presented a high-resolution view of market direction, competitive positioning, policy tailwinds, and operational levers while reserving granular regional and application-level segment data, vendor scorecards, and the full set of financial tables for the full report. Those granular data sets are designed to plug directly into program-level business cases and procurement documentation.
For teams planning strategic acquisitions, upgrades, or large-scale sustainment programs in 2026, the study provides both the quantitative foundation and the practical, step-by-step guidance to convert market momentum into program success—while ensuring compliance, manageability, and measurable operational improvement.
For detailed analysis of this topic, please visit the official page: Defense Asset Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Built-In Electric Curtains Market at USD 3,248.5M in 2025; 10.51% CAGR (2026–2032)
By PW Consulting, 2026-07-13
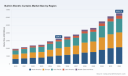
Built-In Electric Curtains Market — A 2026 Strategic Preview for Decision‑Makers
PW Consulting’s latest market research on Built‑In Electric Curtains frames the next investment cycle for product managers, procurement leads, real‑estate developers and systems integrators. Anchored on a 2025 base year and projecting through 2032, the study quantifies a high‑growth landscape: the market expands at a compound annual growth rate (CAGR) of 10.51% over the forecast window. Our topline sizing shows a multi‑year climb from the early 2020s into a substantially larger market by the end of the decade (figures in USD Million). This preview synthesizes the strategic implications you need to act in 2026 while intentionally holding back detailed sub‑segment tables — those are reserved for the full report.
Built In Electric Curtains Market
Why built‑in electric curtains matter now
-
Smart‑home and intelligent building adoption is shifting specification patterns. Stakeholders are moving away from add‑on retrofit motors toward fully integrated, recessed or track‑based systems that preserve interior design while delivering automation and energy‑management benefits.
Built In Electric Curtains Market -
Technology convergence (low‑power wireless standards, local bridging, cloud services and software ecosystems) is transforming curtain systems from discrete mechanical products into platform opportunities — unlocking recurring revenue through services, updates and integrated building control.
Built In Electric Curtains Market -
Cost dynamics and regulation are compressing time‑to‑market for new designs. Raw‑material duties and component import tariffs increase landed costs for motors and aluminum extrusions; safety standards (notably ANSI/WCMA A100.1‑2022) further influence product form factors and customer acceptance.
Market trajectory — what the numbers signal for strategy
The market’s 10.51% CAGR reflects a combination of accelerating demand in premium residential and commercial segments, growing retrofit activity in retrofit‑heavy regions, and stronger specification for integrated systems in new construction. From a strategic perspective, that growth rate creates three simultaneous imperatives for business leaders entering 2026:
-
Scale to capture volume while protecting margin — growth will reward players who can manage supply‑chain cost inflation and offer differentiated integration capabilities.
-
Differentiate through software and services — the hardware commodity risk rises unless firms bundle persistent value (control platforms, analytics, maintenance plans).
-
Manage regulatory and trade exposure — tariffs on motors, fabrics and aluminum extrusions, and safety standards eliminating free‑hanging cords, require product redesign and more agile sourcing.
What the full PW Consulting report delivers (practical, actionable)
This research is designed as a decision‑support toolkit for 2026 and beyond. Key deliverables include:
-
A validated market model with annual sizing (base 2025) and granular forecasts to 2032, including scenario analyses that stress tariffs, raw‑material cost swings and adoption curves for wireless platforms.
-
Go‑to‑market playbooks for three archetypes: OEM suppliers, branded system integrators, and channel/installer networks. Each playbook contains recommended product roadmaps, pricing levers, and channel incentive structures.
-
Supply‑chain diagnostics and mitigation templates: cost‑build models (motor, track, electronics, fabric), supplier concentration mapping, and contingency plans for duties and logistics disruptions.
-
Regulatory and standards tracker with practical compliance checklists (including ANSI/WCMA A100.1‑2022 implications) to accelerate safe‑to‑ship timelines.
-
Detailed competitive profiles and SWOTs for market participants, plus M&A and partner scouting lists for acquisition or alliance strategies.
-
Case studies on built‑in installations across residential, hospitality and institutional sites demonstrating OPEX impacts, installation workflows and specification language templates for architects and consulting engineers.
Note: this preview intentionally avoids publishing the detailed regional, power‑source and end‑use splits. Those core segmentation matrices and the revenue tables that many practitioners require are available exclusively in the full report.
Competitive landscape — practical takeaways
-
Market structure: The market displays a moderate concentration with top‑three players holding a substantial share and top‑five further extending reach. This dynamic creates a two‑tier opportunity: large platform players will continue to dominate high‑spec projects, while nimble challengers can win in retrofit, mid‑market and regional channels.
-
Player archetypes and strategic moves:
-
Platform integrators: Companies with deep system control capabilities focus on bundled lighting/shading ecosystems and premium residential/commercial specifications. Their competitive edge is integration with building automation platforms and channel relationships with designers.
-
Component specialists & OEMs: Providers of motors and tracks maintain margin by selling into both branded systems and white‑label channels; securing OEM contracts and scale manufacturing is core to their playbook.
-
B2B smart window suppliers: Newer entrants leveraging modern interoperability stacks (e.g., Matter/Thread) and rechargeable motor designs emphasize clean integrations and faster installer experiences.
-
-
Notable companies to watch: Established leaders bring scale and integration depth, while specialized track and motor manufacturers control critical component roadmaps. Recent product launches — for example, a 2025 introduction of a Matter bridge and showroom suite by a smart window covering B2B brand — illustrate how interoperability and customer experience are now front‑and‑center in product roadmaps.
Regulatory and cost headwinds — how they influence 2026 decisions
-
Tariffs and import duties: Motor components, fabrics and aluminum extrusions face import levies that can add materially to landed costs. Pricing strategies must account for potential 10–25% tariff exposures on specific components depending on origin and customs classification.
-
Standards and safety: ANSI/WCMA A100.1‑2022 and similar regional safety requirements accelerate the normalization of motorized solutions in place of hazardous free‑hanging cords; product development teams must embed compliance early to avoid late‑stage redesigns.
-
Raw‑material duties and supply risk: Additional duties on aluminum and tubular components increase production costs for integrated tracks, making near‑shoring and supplier diversification strategic priorities.
Priority actions for 2026 — a tactical roadmap
-
Secure your component supply chain: Lock multi‑year agreements with motor and extrusion suppliers, include tariff‑pass‑through clauses and evaluate local assembly to mitigate import duties.
-
Design for standards and retrofit: Revisit mechanical designs to meet ANSI/WCMA requirements and reduce installation time; create retrofit kits that minimize structural work in the field.
-
Invest in interoperability: Accelerate support for open ecosystems and bridges (Matter/Thread, Zigbee integrations) to be chosen by system integrators and smart‑building specifiers.
-
Develop a service monetization plan: Pilot subscription models for remote diagnostics, preventive maintenance and software feature tiers tied to installations.
-
Model scenario P&Ls: Run sensitivity analyses for tariff shocks, aluminum price spikes and slower adoption to inform pricing, inventory and new product launch timelines.
-
Plan selective partnerships and M&A: Where time to capability matters, pursue minority stakes or distribution deals with regional installers, or acquire niche track/motor specialists to internalize margin and IP.
Using this preview — next steps
This article is a curated preview designed to inform 2026 strategic planning. For commercial teams, the report is a playbook: it contains the full revenue matrices, regional and end‑use splits, channel economics and supplier lists that operationalize the recommendations above. For product leaders, the report includes design impact analyses and compliance roadmaps. For M&A and corporate development teams, it contains target scouting and valuation sensitivities tied to the sector’s growth profile.
PW Consulting’s full Built‑In Electric Curtains Market report is the source of the detailed segmentation, vendor scorecards and downloadable modeling assets referenced here. To access the full intelligence package and data tables required to convert the strategic priorities above into executable plans, please visit our report page or contact our industry team.
For detailed analysis of this topic, please visit the official page: Built In Electric Curtains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Charging Card Market to Reach USD 4,347.4M by 2032 at 18.24% CAGR
By PW Consulting, 2026-07-13
EV Charging Card Market: Strategic Briefing for 2026 Decision-Makers
As lead industry strategist at PW Consulting, I present a focused preview of our new Ev Charging Card Market research — an evidence-driven, decision-oriented intelligence product designed to inform executive strategy and capital allocation in 2026. This briefing highlights the study’s strategic value, major market dynamics, competitive positioning of key players, and the practical deliverables included in the full report. It intentionally surfaces high‑level metrics and qualitative insight to help you assess relevance, while withholding granular segment extracts to preserve the study’s commercial value and direct stakeholders to the full report for detailed modelling and tables.
Ev Charging Card Market
Market trajectory: scale, growth and what it means in 2026
The charging-card market moved from a nascent, fragmented opportunity in 2020 to a robust commercial market by 2025. Our base-year sizing shows the market at USD 1,345.5 Million (base year 2025), after accelerating through the 2020–2025 historical window. Looking forward, the market is forecast to expand at a compound annual growth rate of 18.24% over the 2026–2032 forecast period, reaching an estimated USD 4,347.38 Million by 2032.
Ev Charging Card Market
- Why this matters in 2026: an 18%+ CAGR implies rapidly expanding addressable revenue for charge-point operators (CPOs), network aggregators, energy retailers and card service providers; decisions made in 2026—on roaming, authentication standards, contract terms, and interoperability investments—will disproportionately determine market share through 2028–2030.
- Consolidation dynamics: market concentration indicators show a mid-level aggregation of share among leading firms (CR3 and CR5 metrics point to meaningful but not overwhelming dominance), signalling opportunity for scale players and differentiated niche specialists alike.
Strategic implications for corporate decision-making in 2026
Executives must treat charging-card strategy as a lever for customer control, roaming economics and data capture. The card is not merely a payment token — it is an authentication surface, a billing instrument, and a device for enforcing commercial policy (tariffs, priority access, charging limits). In 2026, the primary strategic trade-offs will be:
Ev Charging Card Market
- Control versus reach: owning a proprietary card ecosystem improves margins and user experience but demands investment in backend clearing and roaming partnerships. Many firms must decide whether to double down on proprietary stacks or accelerate roaming via neutral aggregators.
- Technology and UX choices: contactless RFID remains ubiquitous for tap-and-go convenience, while NFC and app-based flows are increasingly important for seamless authentication and dynamic pricing. Choose paths that balance device compatibility and futureproofing.
- Commercial model design: subscription vs. pay-as-you-go, role of aggregated invoicing for fleets, and incentives to lock user behavior (e.g., loyalty discounts, dynamic charging credits) will determine customer retention and revenue per user.
- Regulatory alignment and compliance: infrastructure mandates and public procurement programs are reshaping site selection and interoperability requirements—companies must bake regulatory scenarios into investment appraisals in 2026.
Competitive landscape: players to watch and their strategic postures
Our competitive landscaping canvasses manufacturers, network operators, energy incumbents and independent service providers. Notable participants include global OEMs and platform players that combine hardware, payment and network services with brand reach:
- Tesla: vertical integration with a proprietary access model, tightly coupled to its Supercharger estate and adjacent roaming partnerships. Their approach prioritizes seamless authentication for Tesla users, but evolving plug standards broaden competitive dynamics.
- ChargePoint, EVgo, Blink: network operators focused on scale, flexible payment options and enterprise fleets. Their positioning centers on open access and commercial partnerships with landlords, fleets and retail operators.
- Shell Recharge, Octopus Energy, Fortum Charge & Drive: energy incumbents and retailers using charging cards as an extension of customer energy relationships, leveraging brand and billing infrastructure to offer multi-network convenience.
- Infrastructure OEMs (ABB, Siemens): embed access control (RFID/NFC) into charging hardware, enabling CPOs to deploy turnkey authentication solutions while preserving the option for third-party back‑end integration.
- Regional integrators and aggregators (Radius, E-Flux, Tata Power): focus on multi-operator consolidation, simplified invoicing and localized roaming agreements—critical partners for fleet operators and corporate buyers.
Recent developments validate these strategic vectors. For example, EVgo’s early‑2026 expansion of NACS fast-connectors underscores the importance of connector and protocol support in enabling broader vehicle compatibility. Tata Power’s late‑2025 launch of an RFID-enabled tap-and-go card highlights the continued investment in physical authentication media, even as app-based solutions proliferate. Together, these moves reflect parallel races: one to expand physical reach and one to simplify user authentication and billing.
Regulatory and infrastructure tailwinds shaping card strategy
- Regulation: New and updated policies—such as EU AFIR directives demanding standardized access on major routes and U.S. federal guidance accelerating corridor deployments—are forcing standardization and interoperability, increasing the commercial value of cards that comply with roaming and access rules.
- Infrastructure scaling: Rapid growth in DC fast‑charging deployments and significant year‑over‑year increases in fast‑charging ports create a dense public network where card-based friction becomes a bottleneck if not addressed.
- Cost structures: Wide cost variance between Level 2 and high-power DC stations means firms must align auth/payment solutions with site economics — high-value sites justify premium, integrated user experience investments.
- Supply chain policy: Policies to onshore components under domestic preference provisions (e.g., Build America, Buy America) will influence procurement choices for hardware-integrated card readers and may favor regional OEM partners.
What PW Consulting’s report contains: practical, executable outputs
The full Ev Charging Card Market study goes beyond narrative to provide operational tools for 2026 decision cycles. Key deliverables include:
- Market sizing and high‑level historical trends (2020–2025) and forward scenarios (2026–2032) with base-case and stress-case assumptions that map to investment horizons.
- Vendor scorecards and capability matrices for hardware, network operators, energy retailers and card aggregators — enabling rapid shortlisting for RFPs.
- Commercial models and pricing benchmarks tailored for site types (public retail, corridor, fleet depot) including sensitivity analysis for tariff structures and roaming fees.
- Interoperability and standards playbooks — decision matrices for RFID, NFC, app-first and hybrid authentication strategies, with recommended transition paths for incumbent networks.
- Roaming and partnership negotiation templates — clauses and KPIs that matter in multi-lateral clearing and settlement agreements.
- Implementation checklists for pilot design, integration testing, PCI and data-protection alignment, and operational KPIs for scaling from pilot to multi-site rollouts.
- Strategic scenarios and go-to-market playbooks for OEMs, CPOs, energy retailers and fleet operators — each with decision triggers keyed to regulatory and infrastructure milestones.
- Data annex documenting primary and secondary sources, modelling assumptions, and a transparent replication pathway for in-house teams or third‑party auditors.
How to use the study in your 2026 planning cadence
The report is structured for practical use across corporate functions. Examples of immediate applications:
- CEO/CFO: Use scenario outputs to stress test capex and M&A plans, aligning near‑term capital allocation to the highest-margin card-enabled revenue streams.
- Commercial/Partnerships: Employ vendor scorecards and negotiation templates to accelerate roaming deals and consolidate invoicing for fleet customers.
- Product and Engineering: Adopt the authentication playbook to sequence reader upgrades, mobile token implementations, and back-end billing changes with minimal service disruption.
- Operations: Implement the pilot-to-scale checklists to reduce downtime and manage dispute resolution in multi-operator environments.
- Legal & Compliance: Map regulatory scenarios to contract clauses and data-protection workflows to avoid retroactive compliance cost shocks.
Why this is a must-read for 2026
Two forces make 2026 a pivot year: accelerating network deployment and rapid standard consolidation. Combined with an 18.24% forecast CAGR and market scale expanding from the 2025 base, the decisions organizations take this year—on roaming architecture, authentication technology, pricing frameworks and strategic partnerships—will determine competitive positioning for the next investment cycle.
Our analysis equips executives with the frameworks and operating artifacts needed to move from strategic intent to executable programs. It is intentionally crafted to be actionable for near-term procurement, product roadmap prioritization, and partnership negotiations while preserving the full financial and segment granularity for clients who require the detailed tables and models.
Next steps
This briefing is a trailer: it demonstrates the research’s depth and operational orientation while reserving comprehensive segment breakdowns, country-level splits and downloadable financial models for the full report. If your 2026 planning requires precise targeting—fleet propositions, roaming fee sensitivity, or capex justification for reader upgrades—request the full study to access the granular tables, model files and appendices that underpin these strategic recommendations.
PW Consulting stands ready to run bespoke workshops that apply the study’s scenarios to your portfolios, stress-test partnership frameworks and co-develop roll-out roadmaps aligned to your risk tolerance and regulatory roadmap. Contact our industry team to schedule a strategic briefing and receive the full dataset and modelling workbooks.
For detailed analysis of this topic, please visit the official page: Ev Charging Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


