



Why Waste-to-Energy Market Growth at 3.62% CAGR Shows Reshaping Forces in 2032
By PW Consulting, 2026-09-21
Navigating the Waste-to-Energy Market: Strategic Trends and Commercial Opportunities Through 2032
The waste-to-energy (WTE) sector stands at a critical inflection point. As municipal waste volumes continue to rise alongside growing pressure to decarbonize power generation, the industry is evolving from a niche waste management solution into a structured component of regional energy infrastructure. Market trajectories indicate steady expansion, with a compound annual growth rate of 3.62 percent projected through 2032. Revenue scales from an estimated 311.0 million USD in 2025 to approximately 399.58 million USD by 2032, reflecting a compound annual expansion of 3.62 percent. This growth trajectory is neither linear nor uniformly distributed. While baseline figures suggest consistent upward movement, the underlying dynamics reveal a market shaped by technological differentiation, regulatory recalibration, and shifting operational economics. For executives and investors, the challenge lies in distinguishing structural tailwinds from transitional noise and positioning accordingly.
Market Snapshot and Structural Challenges
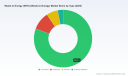
The current market environment reflects a mature but unevenly developed landscape. Thermal conversion routes continue to anchor the majority of installed capacity, with incineration accounting for the largest share of revenue. Complementary pathways such as gasification, pyrolysis, and anaerobic digestion represent a collective but growing portion of the market, signaling gradual diversification beyond conventional combustion. Application-wise, electricity generation dominates end-use deployment, while heat production captures a meaningful secondary segment. Regional distribution shows pronounced concentration, with Asia Pacific and Europe collectively representing the bulk of market value, North America maintaining a substantial position, and Latin America and the Middle East/Africa reflecting early-stage development potential.
This macro structure, however, masks several operational and strategic friction points that define the current cycle.
1. Conversion Efficiency and Emissions Compliance Under Scrutiny
Traditional grate-based incineration remains the operational backbone, yet it faces mounting pressure to improve net energy recovery while meeting tighter air emissions thresholds. Facilities that operate with older boiler configurations or suboptimal heat recovery systems struggle to maintain favorable levelized costs, particularly as grid parity expectations rise and carbon accounting becomes embedded in procurement and financing decisions. The industry is being pushed toward higher steam parameters, advanced flue gas treatment, and integrated heat utilization, which raises capital intensity but improves long-term contract economics.
2. Policy Fragmentation and Regulatory Transition Risk
WTE does not operate in a uniform regulatory vacuum. Jurisdictions are simultaneously incentivizing waste-to-energy as a clean generation pathway and imposing stricter monitoring, reporting, and offset obligations on incineration-based systems. This creates a dual dynamic: projects may qualify for clean electricity provisions in one market while encountering emissions compliance costs in another. Organizations with cross-border portfolios or multi-jurisdictional supply chains must navigate divergent definitions of eligibility, differing measurement methodologies, and staggered compliance timelines that can compress margins or delay commissioning.
3. Feedstock Reliability and Contract Structuring Complexity
The economics of WTE projects remain tightly linked to consistent waste supply, calorific value stability, and long-term offtake security. Diversion of recyclables, changes in municipal collection practices, and competition from alternative recovery pathways can alter feedstock composition mid-cycle. In markets where tariff structures, cost recovery mechanisms, or interconnection rules are still being formalized, developers face elevated negotiation risk. Securing bankable feedstock agreements and aligning them with energy revenue routes is increasingly a core strategic task rather than a secondary operational concern.
Key Drivers Reshaping the Sector
The market trajectory is being shaped by a set of mutually reinforcing forces that extend beyond simple waste volume growth or energy demand. Understanding the interaction between technology, policy, customer behavior, and cost dynamics is essential for identifying durable profit pools rather than short-term cycles.
Technology Innovation and System-Level Efficiency Gains
Innovation is moving beyond incremental boiler upgrades toward integrated plant design and alternative conversion routes. Gasification and pyrolysis continue to attract attention for their potential to produce secondary fuels and chemical precursors, while anaerobic digestion is carving out a distinct niche where organic-rich waste streams and heat-on-site applications align. On the thermal side, advanced combustion controls, improved refractory and boiler materials, and better heat recovery integration are helping facilities extract more usable energy per tonne of input. Equipment suppliers and EPC players are increasingly positioned as partners in lifecycle optimization, not just plant builders. The strategic implication is clear: technology choice now influences not only emissions performance but also revenue flexibility, grid qualification, and long-term contract structure.
Policy and Regulatory Reorientation
Recent regulatory developments illustrate how policy is both enabling and disciplining the market. Clean electricity tax credit guidance in the United States has clarified that WTE facilities can qualify when assessed through lifecycle analysis, giving eligible projects a clearer financing pathway and improving project economics for compliant operations. At the same time, emissions-related obligations are becoming more granular. In the United Kingdom, the extended carbon pricing and monitoring scope now captures energy-from-waste and incineration, with reporting obligations beginning and full surrender requirements phased in later in the decade. This creates a compliance dimension that must be modeled into cash flow forecasts rather than treated as a peripheral environmental cost.
In emerging and fast-scaling markets, regulatory clarity is directly shaping project pipelines. Indonesia's presidential regulation setting a fixed electricity purchase price for WTE under a state-backed program, with long-term contract structures and compensation mechanisms for grid connection costs, reduces revenue uncertainty for developers and equipment providers alike. Meanwhile, the Philippines has moved to incorporate WTE into national grid and distribution codes, with provisions for long-term cost recovery and subsidies to support interconnection. These frameworks do not guarantee uniform returns, but they do reduce a major class of financing friction and help convert conceptual pipelines into executable projects.
Demand-Side Shifts and Corporate Behavior
The demand environment is changing on two fronts. First, municipalities and industrial operators are increasingly treating WTE not merely as disposal but as part of integrated resource recovery strategies. Heat utilization, for example, is gaining relevance in contexts where district heating, industrial process heat, or adjacent thermal loads can absorb otherwise wasted energy. Second, corporate procurement of renewable and low-carbon energy is expanding the relevance of generation assets that can offer measurable lifecycle attributes. Facilities that can demonstrate credible emissions performance and stable energy output are better positioned to align with offtake relationships, public-private partnerships, and sustainability-linked financing structures. The commercial opportunity lies in packaging energy recovery with verifiable environmental performance rather than in volume alone.
Cost Structures and Supply Chain Realignment
Capital intensity remains a defining characteristic of the sector, but the composition of cost risk is shifting. Equipment supply, engineering procurement, and construction execution are increasingly influenced by regional project pipelines, localization requirements, and lead-time volatility for critical components. Recent project activity underscores this trend. In Taiwan, a major incinerator unit and equipment supply contract was awarded for a WTE plant under a build-operate-transfer model, highlighting the continuing relevance of proven thermal equipment in structured project delivery. At the same time, full EPC and operational partnerships are favored where developers seek integrated risk transfer rather than fragmented procurement. Cost competitiveness now depends on more than hardware pricing; it depends on execution certainty, emissions compliance readiness, and the ability to align plant design with local grid and feedstock conditions.
Waste-to-Energy Technologies Market
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of integrated waste and energy service providers, specialized plant equipment manufacturers, and regional project developers with strong deployment track records. Market concentration, with the top three firms holding approximately 42.5 percent of market value and the top five around 55.2 percent, indicates a sector where scale, operational expertise, and relationship depth matter, but where meaningful participation remains feasible for focused players.
Strategic Archetypes Among Leading Players
Several competitive patterns emerge from current positioning and recent activity:
- Integrated service and operations players combine waste management, plant operation, and energy production into end-to-end offerings. This model reduces coordination risk across collection, processing, and generation, and is particularly valuable where long-term municipal contracts and operational continuity are central to revenue stability.
- Equipment and technology specialists concentrate on core conversion hardware, boiler systems, or full plant delivery. Their differentiation often rests on moving grate and combustion technologies, high-efficiency boiler configurations, and the ability to supply standardized yet customizable solutions for BOT and EPC contexts. Strong delivery records and technology familiarity with grid-connected thermal plants remain central advantages.
- Regional developers and EPC-oriented operators focus on large-scale projects in geographies with active municipal build-outs, particularly in Asia and parts of the Middle East. Their value lies in local execution, permitting and stakeholder management, and the ability to structure projects that align with national energy and waste policy directions.
- Advanced conversion and fuel-oriented entrants emphasize alternative outputs such as renewable natural gas or engineered fuels. These players typically target niches where feedstock composition, product flexibility, and premium offtake structures can support differentiated economics.
How the Landscape Is Evolving
The market is not simply consolidating; it is stratifying. Traditional scale players continue to defend positions through operational breadth and integrated service models, but technology differentiation and policy-linked eligibility are creating new competitive axes. Companies that can combine reliable thermal performance with credible emissions management, grid compliance readiness, and flexible energy product offerings are gaining leverage in both tender processes and private financing discussions. At the same time, new entrants and specialized technology providers are carving out segments through alternative conversion routes or modular plant approaches, particularly where conventional capacity is constrained by regulation or community acceptance. The trend suggests a market in which the battleground is shifting from pure capacity addition toward lifecycle value, compliance resilience, and project structuring capability.
Forward Look: Three Trends to Watch
Looking across the current data and recent policy and project signals, three directional trends are likely to shape the next few years.
1. Policy-Linked Project Economics Will Become a Core Differentiator
As jurisdictions clarify eligibility for clean electricity incentives, define emissions monitoring obligations, and establish cost recovery or interconnection provisions, projects with stronger policy alignment will command better financing terms and more predictable revenue paths. The practical implication is that commercial success will increasingly depend on anticipating regulatory definitions, model lifecycle eligibility early, and structuring contracts to withstand compliance evolution rather than assuming static frameworks.
PW Consulting
2. Heat Integration and Multi-Output Designs Will Expand Value Capture
Electricity remains dominant, but the margin between successful and marginal projects may increasingly hinge on the ability to monetize thermal output. District heating linkages, industrial steam supply, and process heat utilization can improve overall plant economics and reduce sensitivity to electricity price volatility. Facilities and partners that design for heat export from the outset, rather than as an afterthought, can unlock incremental returns and strengthen long-term offtake narratives.
Waste Incinerators Market
3. Supply Chain Localization and Execution Discipline Will Matter More as Pipelines Scale
With several large-scale projects advancing in Europe, Asia, and emerging markets, the sector will test its ability to deliver on schedule, within budget, and with compliant emissions performance. Equipment suppliers and EPC organizations that can localize content where required, manage long-lead items effectively, and deliver standardized yet site-adaptive solutions will capture stronger positioning. Developers, meanwhile, will favor partners who can reduce integration risk across permitting, construction, commissioning, and operation.
These trends carry inherent uncertainty. Policy frameworks can shift as political priorities change, feedstock availability can be disrupted by diversion programs or municipal restructuring, and emissions compliance costs may rise if monitoring obligations tighten faster than anticipated. Additionally, community acceptance and landfill diversion trade-offs continue to influence siting decisions in multiple regions, adding a layer of execution risk that cannot be discounted.
Strategic Playbooks for Decision-Makers
For executives and investors evaluating near- to mid-term moves, the following considerations can help translate market signals into actionable positioning.
For Equipment Manufacturers and Technology Providers
- Prioritize designs that balance proven thermal reliability with flexibility for heat recovery and emissions control upgrades, since these features increasingly influence bid selection and lifecycle economics.
- Strengthen delivery and localization capabilities in regions with active WTE pipelines, where execution certainty and regulatory familiarity are becoming as important as hardware performance.
- Develop clear lifecycle and compliance narratives that align with evolving clean electricity and emissions frameworks, enabling customers to justify investment under changing policy conditions.
For Investors and Project Developers
- Focus underwriting on projects with credible feedstock security, aligned policy incentives, and offtake structures that account for both electricity and potential heat value streams.
- Stress-test returns against emissions compliance costs and monitoring obligations, particularly in markets where carbon pricing or MRV requirements are being phased in.
- Evaluate partners not only for capital and technology but also for permitting track record, grid interconnection experience, and ability to manage multi-year commissioning risk.
For Procurement and Municipal Decision-Makers
- Treat WTE as one element of an integrated waste and energy strategy, weighing siting, feedstock continuity, emissions performance, and heat utilization alongside disposal cost reduction.
- Structure contracts to balance long-term cost recovery with performance accountability, ensuring that operational and compliance responsibilities are clearly allocated.
- Request transparent lifecycle and emissions documentation to support public accountability and to future-proof assets against evolving regulatory definitions.
For deeper segmentation data, regional modeling, and tailored scenario analysis, the full PW Consulting research report provides expanded detail across technology pathways, application mixes, and policy-sensitive revenue drivers, along with customized recommendations aligned to specific operational and investment profiles.
For detailed analysis of this topic, please visit the official page: Waste to Energy (WTE) (Waste-to-Energy) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vacuum Evaporation Boat Market: How 6.98% CAGR and Asia Pacific Demand Reshape Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Vacuum Evaporation Boat Market
The global market for vacuum evaporation boats is entering a phase of predictable expansion grounded in steady industrial adoption. With a compound annual growth rate of approximately 6.98 percent over the forecast horizon extending to 2032, the sector is tracking from a baseline of roughly 215 million dollars in 2025 toward a projected valuation near 345 million dollars by the end of the period. The historical trajectory from 2020 through 2025 reflects consistent year over year gains, underscoring a market that has moved past initial volatility and settled into a rhythm driven by repeatable manufacturing demand rather than speculative cycles. This maturation matters for decision makers because it shifts the conversation from whether the market will grow to how growth will be distributed across technologies, applications, and supply chains.
At this stage, the industry faces a handful of structural turning points that will shape competitive outcomes. First, the transition from generic evaporation components to application specific geometries and thermal profiles is accelerating, forcing suppliers to align product development with downstream processing requirements rather than competing on commodity dimensions alone. Second, regulatory and certification pressures are reshaping procurement criteria, particularly around material traceability, energy intensity, and carbon accounting, which introduces new compliance costs but also creates differentiation for manufacturers that can demonstrate verified sustainability metrics. Third, capacity and qualification bottlenecks in high purity material sourcing are becoming more visible as demand scales, meaning that lead times and quality consistency will increasingly determine who wins recurring contracts. These dynamics are not isolated obstacles; they are signals of a market that rewards firms capable of linking engineering precision with supply chain resilience.
Key Drivers Shaping the Market Trajectory
Technology innovation continues to be the most direct lever for market expansion. Advances in boat design, including optimized filament arrangements, improved heat distribution, and tighter tolerances for thin film uniformity, are enabling manufacturers to run more stable evaporation processes at higher throughputs. The recent expansion of evaporation source catalogs by established component suppliers illustrates how product line breadth is being used to capture demand across thin film coating and metalizing workflows. When suppliers publish updated catalogs that broaden the range of boat configurations and material grades, they effectively lower the barrier for equipment integrators and end users to standardize on proven geometries, which in turn increases repeat purchasing and reduces qualification friction. In practice, this means that innovation in this segment is less about breakthrough physics and more about making reliable, repeatable deposition more accessible across a wider set of production environments.
Policy and regulatory developments are also shaping demand patterns, particularly where public funding and certification requirements intersect with industrial materials. Programs that support environmentally conscious extraction and processing of critical materials are indirectly influencing the upstream supply base for evaporation components, since graphite and metal based inputs must increasingly satisfy documented footprint and sourcing standards. At the same time, certification milestones at major production sites are becoming relevant procurement signals, especially for buyers in sectors where material consistency and environmental accountability are tied to downstream customer expectations. These are not merely compliance exercises; they alter the cost and risk profile of supplying high specification evaporation boats, and they reward manufacturers that integrate sustainability data into their commercial messaging and product documentation.
PW Consulting Automotive & Machinery Research Center
Demand side behavior is shifting as well, driven by the continued scaling of electronic component manufacturing and packaging materials that rely on controlled vacuum deposition. As device architectures become more compact and performance requirements more exacting, the need for stable evaporation sources that can deliver consistent film characteristics across production runs becomes more pronounced. This demand is not uniform across all end uses, but the concentration of activity in component and packaging applications indicates that the market is being pulled by process reliability rather than by one off experimental adoption. The practical implication is that commercial success increasingly depends on demonstrating how a given boat design reduces process variation, shortens ramp up time, or extends usable life under specific operating conditions.
On the supply and cost side, the market is absorbing pressures from raw material availability, production yields, and logistics for specialized components. Evaporation boats sit at the intersection of metallurgical precision and application engineering, so cost structures are influenced not only by base material prices but also by machining complexity, quality assurance, and the ability to scale qualified production without compromising tolerances. Suppliers that can stabilize input sourcing and maintain repeatable manufacturing outcomes are better positioned to manage pricing expectations while preserving margins. Conversely, volatility in high purity feedstock or unexpected qualification delays can quickly cascade into customer dissatisfaction, making supply chain transparency and production discipline strategic assets rather than operational details.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a modest level of concentration, where the leading players collectively account for a limited share of total market revenue. This fragmentation indicates that the market still leaves room for specialized positioning, regional service capability, and differentiated product portfolios rather than requiring scale alone to compete. Several established firms illustrate how different strategic orientations are being pursued. Plansee SE, headquartered in Reutte, Austria, emphasizes specialized high performance materials and precision components, aligning its offering with customers that value material consistency and engineered solutions for demanding deposition processes. H.C. Starck Solutions, based in Goslar, Germany, approaches the space through a combination of material expertise and process aligned product development, with increasing attention to sustainability credentials and publicly documented certification and research initiatives. 3M, operating from St. Paul, Minnesota, brings broader materials and coating experience to the ecosystem, allowing it to relate evaporation component needs to wider functional film and surface engineering contexts. The Kurt J. Lesker Company, in Clairton, Pennsylvania, has become widely recognized as a supplier of evaporation sources and related technical materials, reinforcing its position through catalog breadth and application support. R.D. Mathis Company, located in Long Beach, California, continues to strengthen its presence through expanded source lineups that address thin film coating and metalizing applications, signaling a strategy centered on product range and direct responsiveness to coating industry requirements.
The strategic differentiation among these players tends to fall into a few recognizable patterns. One is material and process expertise, where suppliers compete on the ability to specify and manufacture boats that behave predictably in specific vacuum environments and coating chemistries. Another is application coverage, where broader catalogs and cross referenced technical documentation help reduce customer evaluation time and support integration into existing workflows. A third is sustainability and compliance readiness, which is becoming a meaningful point of contrast for buyers who must justify material selection not only on performance but also on procurement policy and carbon accountability. These strategies are not mutually exclusive, and the most resilient suppliers typically combine technical credibility with clear documentation, reliable delivery, and responsive support.
Worldwide Ceramic Wafer Boat Market
Looking at how the landscape is evolving, there are signs of both consolidation pressure and continued niche specialization. Larger materials and components providers can leverage broader resource bases, cross selling opportunities, and established qualification networks, which makes them attractive partners for customers seeking stability across multiple product lines. At the same time, smaller or regionally focused suppliers can compete by offering faster customization, closer application support, and more agile responses to specialized coating requirements. New entry remains possible where a supplier can credibly claim an advantage in a narrow application segment, but entry barriers are reinforced by qualification cycles, documentation expectations, and the need to demonstrate repeatable performance over time. As a result, the market is likely to continue rewarding players that can balance product breadth with deep application relevance, rather than those that compete solely on price or generic specification sheets.
Forward Outlook and Emerging Commercial Opportunities
Over the next three to five years, the market is likely to be shaped by three interrelated trends. The first is a continued shift toward application tailored evaporation boats, where performance claims are tied to specific coating workflows, material systems, and desired film characteristics. This trend creates commercial opportunity for suppliers that invest in application engineering and can articulate how a particular boat geometry or material choice improves process stability, yield, or component consistency. It also raises the stakes for suppliers that rely on generic offerings without clear linkage to end user processing needs, because buyers increasingly expect evidence that a component has been considered within the context of a real production environment.
The second trend is the growing relevance of documented sustainability and traceability as procurement criteria. As certification and footprint tracking become more visible in industrial purchasing decisions, suppliers with verifiable data and transparent production practices will have an easier path to qualification in sensitive supply chains. This opens an opportunity for manufacturers to use compliance and environmental accountability as part of a broader value proposition, especially where downstream customers are under pressure to demonstrate responsible sourcing. The associated risk is that sustainability claims must be backed by credible documentation; vague messaging can erode trust quickly in a market where material integrity and process reliability are paramount.
The third trend involves supply chain stabilization and qualification speed as competitive differentiators. As demand expands, the ability to maintain consistent output, manage lead times, and support faster customer qualification will matter as much as the technical specifications of the boats themselves. Suppliers that can reduce friction in sourcing, testing, and repeat ordering will be better positioned to convert initial trials into long term supply agreements. The risk here is that any disruption in high purity material availability or quality control can quickly undermine reputation, so operational discipline will remain a central part of commercial strategy.
Actionable Guidance for Decision Makers
For manufacturers and suppliers, the priority is to align product development with application specific outcomes rather than treating evaporation boats as interchangeable hardware. This means investing in documentation that connects component design to process performance, expanding catalogs in ways that address recurring coating and metalizing needs, and ensuring that sustainability or certification credentials are integrated into commercial discussions where they influence procurement. Suppliers that can reduce customer qualification time while preserving technical credibility will find it easier to convert demand into stable recurring revenue.
For investors, the most relevant signals are not simply top line growth projections but evidence of differentiation that can withstand price competition and qualification cycles. Look for companies that combine material expertise with application focused product expansion, that maintain credible compliance or certification positioning, and that demonstrate control over production consistency and lead time management. The market’s moderate concentration suggests that value can be created through specialized positioning, but only when that positioning is supported by repeatable execution and clear customer relevance.
Worldwide Wafer Boat Market
For procurement and sourcing leaders, the practical implication is to evaluate evaporation boat suppliers on more than nominal specification matching. Qualifying partners that provide application context, consistent quality documentation, and transparent supply practices can reduce downstream process risk and improve production predictability. In a market where process stability is often the true cost driver, the cheapest component on paper is not always the lowest risk choice. Building supplier relationships around documented performance, responsiveness, and compliance readiness can improve long term operational reliability.
Detailed segment data, regional comparisons, and company level profiles can help translate these market level observations into procurement and investment decisions that fit a specific operational context. For decision makers who need to compare supply options, assess entry timing, or map competitive positioning in greater detail, the full research report provides the underlying segmentation and company breakdowns that support more precise planning.
For detailed analysis of this topic, please visit the official page: Vacuum Evaporation Boat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cleaning Robots Market: Strategic Trends and Commercial Opportunities in an AI-Driven Automation Era
The global cleaning robots market has transitioned from a niche convenience category into a foundational component of the broader automation and facility management landscape. Valued at approximately 5.98 billion USD in 2020 and scaling to 14.8 billion USD by 2025, the sector has demonstrated compounding momentum that reflects deeper structural shifts in how spaces are maintained, managed, and optimized. Forward projections through 2032 point to sustained expansion, with the market trajectory aligning to a 20.6 percent CAGR across the forecast horizon. This growth is not merely a function of hardware adoption; it is being reshaped by software-defined navigation, operational labor economics, and evolving regulatory frameworks that collectively redefine what cleaning automation can deliver and where value is captured.
At the same time, the market stands at a strategic inflection point. Early adoption cycles were driven by consumer curiosity and premium residential upgrades. Today, the commercial and industrial segments are accelerating deployment, but with higher expectations for uptime, safety validation, integration with facility management systems, and measurable return on investment. The companies that navigate this shift successfully will be those that can pair compelling hardware with ecosystem-ready software, proven compliance postures, and service models that reduce total cost of ownership rather than simply lowering sticker prices.
Market Landscape: Growth Trajectory and Strategic Inflection Points
The headline scale of the market masks a more nuanced reality beneath the surface. Growth has been broad-based across product types and end-use contexts, yet the composition of value is shifting as capabilities converge and buyer expectations mature. Floor cleaning robots represent the largest product concentration, underscoring the enduring importance of routine surface maintenance in both homes and commercial premises. At the same time, specialized segments such as pool, lawn, and window cleaning robots are carving out defensible niches by solving specific operational pain points that generalist platforms cannot address efficiently.
One of the defining characteristics of the current market is moderate concentration. The top three players account for roughly 32 percent of total revenue, while the top five capture approximately 37 percent. This dispersion signals a market that is large enough to support multiple viable strategies, but not so fragmented that scale advantages are irrelevant. It also means that positioning, distribution strength, and vertical integration decisions can materially alter competitive outcomes.
Key Challenges and Turning Points
The sector is not simply riding a technological wave; it is contending with several structural challenges that will separate durable players from transient ones.
- From feature parity to reliability economics. Early differentiation was heavily reliant on incremental features, yet buyers now reward consistent performance, simpler maintenance, and fewer service interruptions. As competition intensifies, the cost of warranty claims, spare parts logistics, and field support is becoming a decisive margin lever.
- Navigation and obstacle handling at scale. Real-world environments are cluttered, dynamic, and unpredictable. The market is moving past controlled demonstrations toward deployment in spaces with mixed flooring, moving obstacles, pets, cables, and high-traffic transitions. Robots that can maintain cleaning quality without frequent intervention will increasingly define category leadership.
- Data, privacy, and operational compliance. Cloud-connected robots generate continuous streams of environmental and usage data. This creates value for remote diagnostics and fleet optimization, but it also introduces governance obligations. As privacy expectations rise and safety standards evolve for mobile platforms, compliance is shifting from a back-office concern to a commercial prerequisite.
These challenges are not purely risks; they are also filters. They reward manufacturers that can operationalize reliability, integrate safety-by-design thinking, and build transparent data practices into product architecture.
Core Drivers Reshaping Demand and Competitive Advantage
The market’s momentum is being shaped by four interlocking forces. Understanding how they interact is essential for positioning products, allocating capital, and deciding where to compete.
Technology Innovation and the Software-Defined Cleaning Robot
The most consequential breakthroughs are less about mechanical cleaning and more about perception, planning, and adaptation. High-precision navigation, dynamic obstacle avoidance, and adaptive cleaning modes are transforming robots from pre-programmed floor machines into responsive environment-aware systems. In residential settings, this translates into better results around furniture, pet areas, and transitional spaces. In commercial environments, it enables repeatable cleanliness with reduced supervision.
Artificial intelligence is also expanding the functional envelope of cleaning robots. Stain detection, surface-type recognition, and task-specific mode switching allow a single platform to handle broader scope without sacrificing cleaning quality. This matters because it changes the value proposition from “automation for convenience” to “automation for consistency and coverage,” which is far more defensible in procurement decisions.
Policy and Regulatory Environment as a Competitive Variable
Regulatory and standards activity is increasingly shaping product design and go-to-market timelines. Recent updates to safety requirements for industrial mobile robots, alongside active specifications for commercial cleaning equipment, are reinforcing the importance of functional safety, risk assessment, and performance validation. At the same time, working-stage guidance on dynamically stable mobile platforms is pushing manufacturers to think more carefully about balance performance and safe operation zones.
Beyond hardware safety, data governance has become an integral part of market access. GDPR and CCPA compliance are now baseline expectations for cloud-connected deployments, and independent security certifications are increasingly used as trust signals in commercial procurement. These developments do not simply constrain the market; they raise the bar for entry and reward organizations that build compliance into their engineering and operational processes early.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the residential side, cleaning robots are increasingly evaluated as part of a broader smart-home or household management experience rather than as isolated appliances. Buyers are looking for seamless setup, low-friction maintenance, and cleaning outcomes that perform reliably across varied household conditions. This has raised the importance of user experience, dock intelligence, and maintenance automation, since these factors directly affect long-term satisfaction and retention.
In commercial and industrial contexts, the driver is different but equally powerful: the search for predictable service quality under constrained labor availability. Facility operators are not simply looking to replace labor; they are trying to stabilize outcomes, extend cleaning coverage across shifts, and reduce variability in hygiene standards. This is why commercial-grade platforms that can operate in demanding environments with minimal supervision are gaining traction, and why deployments are increasingly judged by uptime and service-level consistency.
Supply Chain and Cost Structure Evolution
Hardware economics are being reshaped by component availability, integration complexity, and the cost of differentiated software stacks. Commodities such as basic sensors and standard drive components have seen gradual normalization, but high-value differentiation is migrating toward navigation subsystems, AI processing, dock intelligence, and service ecosystems. As a result, manufacturers face a strategic choice: compete on volume and cost efficiency in more standardized segments, or invest in higher-margin platforms that combine superior perception, cleaner software integration, and stronger after-sales value.
This dynamic is also reshaping partnerships. Rather than building every capability internally, some companies are pursuing co-development arrangements and ecosystem alliances to accelerate time-to-market and broaden compatibility. Such moves can reduce development risk and improve product completeness, but they also require careful management of brand positioning, data handling, and long-term dependency.
Competitive Landscape: Positioning, Differentiation, and Evolution
The competitive field reflects the market’s breadth. Players range from consumer-focused leaders with strong brand equity and ecosystem reach to specialist manufacturers concentrated on professional and commercial cleaning, and to diversified electronics companies leveraging robotics as an extension of broader home portfolios.
Strategic Positioning Among Leading Companies
Several patterns are visible among the most influential participants.
Worldwide Toilet Cleaning Robot Market
- Residential AI leadership. Organizations such as iRobot have built strong recognition around home cleaning platforms that combine advanced navigation, self-emptying infrastructure, and multi-function cleaning modes. Their strategic advantage lies in brand trust, recurring attachment through docks and consumables, and a product architecture designed around residential usability.
- Navigation and mop-integration differentiation. Companies like Ecovacs Robotics and Roborock have emphasized high-precision navigation, self-washing mop systems, and AI-based obstacle handling. Their push has centered on improving cleaning completeness while reducing manual intervention, which is increasingly important in premium residential segments and larger indoor spaces.
- Commercial-grade specialization. Manufacturers such as Kärcher and SoftBank Robotics are oriented toward professional and facility-scale applications, where robustness, multi-surface capability, and operational endurance matter more than consumer-friendly packaging. Their value proposition is rooted in integration with facility workflows and the ability to deploy reliably in hotels, hospitals, and large public or industrial premises.
- Broad portfolio extension from consumer electronics. LG and Samsung have approached cleaning robots as part of wider appliance and smart-home ecosystems, using suction performance, self-cleaning infrastructure, and connectivity integration as differentiators. This approach can create cross-selling advantages and platform synergies, especially where consumers already trust the brand in adjacent categories.
- Niche autonomy in specialized environments. In pool cleaning, companies such as Maytronics have maintained relevance through purpose-built autonomy for a distinct use case, showing that specialized navigation and durability in water environments can sustain a strong position even as broader segments consolidate. SharkNinja has similarly leaned into brand-led AI vacuums and mops with features such as self-emptying systems and stain-detection technologies, illustrating how strong consumer branding can support robotics entry and expansion.
How the Landscape Is Evolving
The market is exhibiting a mix of consolidation pressure and deliberate differentiation. Some competitors are expanding into adjacent cleaning contexts, while others are narrowing focus to specific environments where they can command stronger pricing and service relationships. Alliances and co-development initiatives are becoming more common as companies seek to extend capabilities without stretching internal resources too thin. At the same time, new entrants are testing highly targeted solutions for overlooked tasks, particularly in commercial hygiene where labor constraints and cleanliness standards create persistent demand.
Recent developments highlight this direction. Strategic partnerships are being used to combine complementary expertise and accelerate next-generation solutions. Product launches are increasingly focused on autonomous restroom cleaning and expanded commercial fleets, reflecting a move toward higher-complexity environments that demand greater autonomy and task-specific engineering. Milestones such as major commercial scrubber sales thresholds also indicate that demand for professional automation is not theoretical; it is scaling in practice.
In this environment, competitive advantage is increasingly determined by the ability to deliver complete solutions rather than isolated hardware. That includes navigation reliability, maintenance design, safety and compliance documentation, integration with operational systems, and service economics. Companies that can prove they reduce operational friction for the buyer will have a stronger position than those competing primarily on feature lists or price alone.
Forward-Looking Trends and Where Value Will Concentrate
Looking ahead across the next three to five years, the market is likely to be shaped by a small number of durable trends. These trends create both opportunity and risk, depending on how organizations position themselves.
Trend 1: Commercial and Facility-Scale Automation as a Growth Anchor
The commercial segment is poised to become an increasingly important growth engine. Labor availability, consistency requirements, and the operational cost of manual cleaning are pushing facility managers toward autonomous solutions that can supplement or partially replace repetitive maintenance tasks. This trend favors robust platforms, clear service-level commitments, and proven performance in demanding environments. The commercial opportunity is not limited to large venues; it extends to offices, retail spaces, healthcare facilities, and educational environments where standardized cleanliness and coverage matter.
Commercial deployment also raises the stakes for total cost of ownership. Buyers will increasingly compare the combined cost of acquisition, maintenance, consumables, downtime, and supervision rather than focusing solely on unit price. Manufacturers that can document operational savings and reduce intervention requirements will have a stronger commercial narrative.
Trend 2: Convergence of Cleaning and Environmental Intelligence
Cleaning robots are becoming more embedded in broader environmental sensing and facility management workflows. Navigation and perception technologies that support cleaning can also support monitoring, mapping, and task coordination. This opens the door to broader value creation: robots that not only clean but also contribute to space utilization insight, maintenance scheduling, or workflow coordination.
This convergence creates opportunities for differentiated platforms, but it also introduces integration challenges. Data handling, interoperability, and system reliability become more important as robots participate in larger operational ecosystems. Privacy and security expectations will continue to shape what is commercially acceptable, especially in environments where cameras, sensors, or continuous connectivity are involved.
Trend 3: Safety, Compliance, and Trust as Commercial Entry Conditions
Safety standards, performance specifications, and data governance requirements are becoming more visible in procurement and deployment decisions. This is likely to accelerate product maturation, but it may also slow entry for players that lack engineering rigor or documentation discipline. Trust is becoming a competitive asset: operators want platforms that are not only effective, but also safe around people, dependable in varied environments, and transparent in how they handle operational data.
The implication is clear. Companies that treat safety and data governance as engineering and commercial priorities, rather than as legal afterthoughts, will find it easier to scale deployments and win enterprise confidence.
Logistics Robots Market
Risks and Uncertainties
Several uncertainties could shape the pace and shape of growth. Economic volatility may affect both consumer discretionary spending and enterprise capital allocation, influencing adoption timing across segments. Competition could compress margins in more standardized categories if differentiation fails to keep pace. Regulatory and standards developments may change product requirements faster than some organizations can adapt. Finally, the market may see segmentation intensify, where generalist platforms struggle to match the economics and performance of specialists in demanding niches.
Strategic Playbooks for Decision-Makers
The cleaning robots market rewards clarity of purpose. Whether the objective is manufacturing, investment, or procurement, the most useful question is not whether the market is growing, but where value is being created and how to capture it.
For Manufacturers and Product Leaders
- Decide where to win, not just what to build. The market supports both broad consumer platforms and specialized commercial solutions, but managing both without clear differentiation is difficult. Define the environments, tasks, and customer types where the company can credibly outperform, then align navigation, cleaning mechanism, maintenance design, and service model to that target.
- Prioritize reliability economics. Cleaning outcomes, uptime, and service simplicity increasingly determine long-term reputation and margin. Invest in perception robustness, obstacle handling, consumable and dock design, and field support processes that reduce repeat visits and warranty exposure.
- Make compliance and data trust part of the product story. Functional safety, performance validation, and responsible data handling are no longer optional polish. They are part of how commercial buyers evaluate risk and how consumers evaluate long-term trust.
For Investors
Capital allocation should be guided by durability of advantage rather than headline growth alone. The most attractive opportunities are likely to be found where there is a combination of clear demand drivers, defensible technology or niche focus, and economic models that scale through service, software, or specialized hardware rather than relying purely on unit volume. Assess whether a company can sustain differentiation as navigation and cleaning features become more common, and whether its go-to-market model can support commercial deployments where procurement cycles and reliability expectations are stricter. Also pay attention to partnerships and ecosystem moves, since they can accelerate capability but also change dependency structures and competitive positioning.
For Procurement and Operations Leaders
- Evaluate the full operational picture. Compare solutions on cleaning consistency, supervision requirements, maintenance burden, and integration with existing workflows. A lower upfront cost can be outweighed by higher intervention, downtime, or consumable complexity.
- Request evidence relevant to your environment. Demonstrations in idealized settings are useful, but procurement decisions should be informed by performance data, safety documentation, and deployment support that match the specific space type, traffic patterns, and cleanliness standards involved.
- Plan for service and lifecycle management. Autonomous cleaning is not a one-time purchase decision. It is an operational relationship. Assurance around support response, spare availability, software updates, and data handling practices can be as important as the hardware itself.
The Practical Payoff of Deeper Market Intelligence
The dynamics in this market are moving quickly enough that broad directional understanding is necessary but not sufficient. Segment-specific economics, company-level positioning, regional deployment patterns, and emerging product strategies can materially change the attractiveness of a particular opportunity or the risk profile of a given vendor choice. Decision-makers who need to compare options, size entry points, or evaluate competitive threats will benefit from more granular intelligence that connects market structure to actionable choices.
PW Consulting
For organizations looking to move from general awareness to confident execution, a detailed study of segment trends, company strategies, and commercial implications can provide the granularity needed to prioritize investments, shape product roadmaps, and negotiate procurement decisions with greater clarity. Access to more detailed research allows leaders to test assumptions, compare scenarios, and identify where to commit resources before the market shifts further.
For detailed analysis of this topic, please visit the official page: Cleaning Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Galvanized Steel Wire Market: 7.1% CAGR and $2.96B Outlook Shape Strategy
By PW Consulting, 2026-09-21
The Galvanized Steel Wire Market: Strategic Shifts, Competitive Dynamics, and Opportunities Through 2032
The galvanized steel wire market has entered a phase of measured but accelerating expansion, driven by a combination of structural demand, coating innovations, and evolving infrastructure priorities. From 2020 through 2025, total revenue climbed steadily, with the base year valuation reaching an estimated USD 1.83 billion. The forward trajectory points toward a compound annual growth rate of 7.1 percent across the 2026–2032 forecast window, tracking toward a market size that approaches USD 3 billion by the end of the period. This growth is not merely a continuation of historical patterns; it reflects a structural reorientation in how coated steel wire is specified, manufactured, and deployed across construction, agriculture, telecommunications, and infrastructure applications.
Beneath the headline growth trajectory lies a market that is consolidating around a handful of large producers while simultaneously fragmenting around application-specific performance requirements. The top three firms collectively control roughly 42 percent of global revenue, with the top five extending that share to just under half. Concentration of this magnitude suggests mature competitive dynamics, but it also masks meaningful divergence in technological positioning, geographic exposure, and product differentiation. For executives and investors, the operational implication is clear: scale alone no longer guarantees resilience. Competitive advantage is increasingly tied to coating chemistry, tensile performance, and the ability to align production capacity with localized demand signals.
Key Challenges and Inflection Points
Three structural challenges are reshaping how market participants plan capacity, pricing, and product roadmaps.
First, raw material volatility remains a persistent pressure on cost structures. Zinc price fluctuations continue to drive production cost variability for galvanized steel wire, forcing manufacturers to balance pass-through pricing with customer retention. This dynamic is particularly acute for producers reliant on conventional hot-dip galvanizing, where coating weight and zinc consumption are directly tied to input costs. Companies that cannot hedge exposure or transition toward more efficient coating architectures face margin compression during periods of commodity instability.
Second, the market is crossing an inflection point where traditional zinc coatings are no longer sufficient for demanding applications. Infrastructure projects, renewable energy installations, and high-stress structural uses are pushing beyond baseline corrosion protection thresholds. This creates a dual challenge: legacy product lines must be defended while next-generation coated wires require capital investment in new coating lines, quality control protocols, and technical sales capabilities. Firms that delay this transition risk ceding premium segments to competitors offering longer service life and higher strength-to-weight performance.
Third, the demand environment is becoming more application-diverse and regionally uneven. Construction remains a foundational demand pillar, but growth rates and specification requirements vary significantly across geographies and project types. Agricultural fencing, telecommunications infrastructure, and increasingly specialized industrial uses each impose distinct performance criteria. Navigating this fragmentation requires production flexibility, inventory strategies that align with project cycles, and commercial teams capable of translating technical specifications into procurement decisions.
Key Demand Drivers and Structural Forces
Technological Innovation in Coating and Wire Performance
Coating technology is moving from a commodity differentiator to a core value driver. The development of Zn-Al-Mg alloy coatings represents a meaningful departure from conventional hot-dip galvanizing, delivering corrosion protection that extends service life by roughly half again in demanding outdoor and marine-adjacent environments. This shift is not incremental; it changes the economics of infrastructure durability by reducing maintenance cycles and enabling wire specifications that withstand harsher exposure without thicker zinc layers. At the same time, high-tensile formulations are pushing mechanical performance upward, with newer products achieving yield strengths approaching 1,000 MPa alongside controlled zinc adhesion and uniform coating distribution.
The commercial significance of these advances lies in their ability to unlock premium pricing and application expansion. Offshore wind farm guy wires, highway safety barriers, seismic-resistant bridge cables, and solar panel frameworks are all environments where failure costs are high and replacement cycles are expensive. When a coated wire can deliver longer protection and higher structural performance, specifiers are more willing to accept elevated unit costs in exchange for lifecycle savings. Producers that have built technical demonstration capabilities, field validation data, and application-specific engineering support are gaining leverage in specification processes that historically defaulted to standard galvanized offerings.
Policy, Regulation, and Infrastructure Priorities
Regulatory and policy environments are shaping demand indirectly but powerfully by influencing project specifications, durability requirements, and public infrastructure spending priorities. Infrastructure programs that emphasize resilience, longer asset life, and reduced maintenance are creating a favorable backdrop for higher-performance coated wires. In parallel, safety standards for bridges, transportation corridors, and energy installations are tightening in ways that reward stronger materials with proven corrosion resistance. These dynamics are not uniform across regions, but they collectively reinforce a preference for coated steel wire that can meet more demanding engineering criteria.
The policy effect also intersects with renewable energy deployment and grid expansion. Solar frameworks, transmission conductors, and wind support infrastructure require materials that can operate reliably under outdoor exposure while maintaining structural integrity over decades. When procurement teams evaluate these applications, coating performance and tensile reliability increasingly enter the decision calculus alongside conventional considerations such as lead time and availability. This creates a tailwind for manufacturers that can document performance advantages and align product portfolios with infrastructure and energy-transition project requirements.
Demand-Side Shifts in End-Use Behavior
Demand patterns are being reshaped by how end users prioritize durability, total cost of ownership, and specification reliability. In construction and agricultural fencing, there is a growing tendency to specify wire based on anticipated service life and environmental exposure rather than lowest upfront price. This is especially visible where projects face corrosive soils, coastal conditions, or long maintenance cycles. In telecommunications and related infrastructure uses, reliability and consistency of supply are gaining weight as networks expand and installation schedules become more time-sensitive.
At the enterprise level, procurement behavior is shifting toward suppliers that can offer technical support, consistent coating quality, and predictable lead times. The commercial implication is that relationship-based selling and specification influence are becoming more valuable than price competition alone. Manufacturers that invest in application engineering, sample programs, and post-sale technical assistance are better positioned to capture and retain demand in segments where performance risk is high.
Supply Chain and Cost Structure Dynamics
Cost structures are being renegotiated by the interaction of raw material exposure, production efficiency, and capacity utilization. Zinc volatility remains a primary driver of production cost fluctuations, and producers are responding with a mix of procurement hedging, coating optimization, and selective pass-through strategies. The broader cost environment also reflects producer price trends in steel wire drawing and coated wire production, which have shown sustained elevation in recent readings. This reinforces the need for disciplined cost management and transparent pricing frameworks that preserve margin without alienating price-sensitive segments.
Supply chain resilience is also emerging as a differentiator. Industrial customers and infrastructure project teams increasingly value dependable availability and the ability to service large orders without disruption. Producers that maintain balanced capacity utilization, regional distribution reach, and responsive customer service can convert supply reliability into competitive advantage, particularly in applications where project timelines and installation schedules leave little room for delay.
Competitive Landscape and Leading Strategies
The market’s competitive architecture is defined by a mix of large integrated producers, specialized coated-wire specialists, and regional manufacturers with strong application footholds. The leading firms are not competing on a single dimension; rather, they are building differentiated positions around coating chemistry, tensile performance, geographic reach, and application-specific service models.
PW Consulting Chemical & Energy Research Center
ArcelorMittal has positioned itself around advanced coated wire solutions, including hot-dip galvanized steel wire and newer Zn-Al-Mg coated products designed for construction, infrastructure, and agricultural fencing. Its strategic emphasis on longer corrosion protection aligns with the broader shift toward durability-driven specifications. Nippon Steel Corporation has concentrated on high-strength galvanized and alloy-coated products, with particular relevance to offshore wind farm guy wires and highway safety barriers. This focus places the company in higher-performance segments where mechanical strength and coating resilience carry premium value.
Tata Steel has built a strong presence in low-carbon and high-tensile hot-dip galvanized wires for fencing, agriculture, and infrastructure, supported by capacity expansion that broadened output in its Jamshedpur facility. United States Steel Corporation has differentiated through specialized high-tensile galvanized offerings, including the ZincGuard® series developed for seismic-resistant bridge cables and solar panel frameworks. Its recent high-tensile product with 1,000 MPa yield strength and a 100 gsm zinc layer illustrates how targeted product engineering can serve demanding structural and energy-infrastructure applications.
Other notable participants include JFE Steel Corporation, which supplies galvanized and coated wire products for industrial and construction use; POSCO, with galvanized steel wire serving automotive components, infrastructure, and agricultural applications; Steel Authority of India Limited, active in hot-dip galvanized wire for fencing and construction; Bekaert, known for agricultural fencing, automotive components, and industrial cable applications; The Heico Companies, with wire mesh, fencing, and specialty industrial products; and Davis Wire Ltd., a producer focused on fencing and wire products.
The competitive landscape is evolving along two reinforcing trends. The first is consolidation of scale and technical capability among the largest producers, who are investing in advanced coatings, high-tensile processing, and application-focused commercial organizations. The second is continued differentiation in regional markets, where local producers maintain advantage through proximity, supply reliability, and familiarity with domestic specification practices. Strategic collaborations are also emerging as a way to commercialize advanced coating technologies more quickly, signaling that even well-resourced firms recognize the value of partnerships in accelerating technical deployment.
For companies evaluating competitive positioning, the strategic takeaway is that leadership is being redefined. It is no longer sufficient to be a low-cost galvanized wire supplier. The firms that are gaining strategic ground are those that can pair coating innovation with tensile performance, document lifecycle benefits, and align capacity with the most valuable end-use segments.
Strategic Implications of Recent Moves
Recent industry activity underscores how competitive advantage is being built. A major Indian producer expanded its galvanized steel wire production facility by 25 percent to increase output of low-carbon and high-tensile hot-dip galvanized wires, reinforcing a strategy centered on scale, cost efficiency, and expanded availability for fencing, agriculture, and infrastructure demand. A leading U.S. steelmaker launched a high-tensile galvanized wire with 1,000 MPa yield strength and a 100 gsm zinc layer aimed at seismic-resistant bridge cables, solar frameworks, and transmission conductors, illustrating a push into performance-oriented segments where specification influence matters. In parallel, a strategic collaboration between two major international producers focused on commercializing high-strength galvanized wires with advanced Zn-Al-Mg coatings, targeting 50 percent longer corrosion protection for offshore wind farm guy wires and highway safety barriers.
These developments collectively point to a market where capacity expansion, product premiumization, and technology partnerships are being used in combination. The pattern suggests that firms are preparing for a future in which demand growth is tied less to volume alone and more to value-added performance in applications where failure is costly and durability is prized.
Forward Outlook: Three Trends Shaping 2026–2032
Trend 1: Premium Coatings Gain Mainstream Relevance
Advanced alloy coatings and engineered zinc architectures are expected to move from niche applications into broader commercial use as infrastructure durability requirements intensify and maintenance costs become more visible in project economics. As specifiers compare total lifecycle cost rather than initial material price, coated wires offering longer corrosion protection and reliable adhesion will capture a growing share of high-value demand. The opportunity for manufacturers lies in building specification relationships early, providing field data, and aligning product lines with the environments where extended protection delivers measurable savings.
The associated risk is execution and adoption velocity. Premium coatings require new processing capabilities, quality assurance rigor, and customer education. If adoption is slower than anticipated, capacity investments in advanced lines may face underutilization, and price differentials may be difficult to sustain in price-sensitive segments.
Steel Wire Rope Market
Trend 2: High-Tensile Wire Expands Into Infrastructure and Energy Applications
High-tensile galvanized wire is poised to play a larger role in bridge cables, solar frameworks, transmission conductors, and safety barrier systems. The combination of higher strength and controlled coating performance allows engineers to reduce material mass while maintaining structural reliability, which is attractive in projects where span, load, and exposure conditions are demanding. Growth in this trajectory is likely to be reinforced by infrastructure modernization, renewable energy deployment, and transportation safety requirements.
The upside is meaningful, but it depends on consistent quality and proven performance in critical applications. Any quality inconsistency or field failure in high-stakes uses could slow specifier confidence and shift procurement toward more conservative choices, at least in the near term.
Trend 3: Regional Demand Divergence and Capacity Rebalancing
Demand growth will not be evenly distributed. Some regions will see stronger pull from construction activity, agricultural expansion, and infrastructure programs, while others will experience more modest growth or project cycle dependency. This divergence will encourage producers to rebalance capacity, adjust export strategies, and tailor product mixes to regional specification norms. Companies that can align regional capacity with local demand signals and maintain dependable supply chains are better positioned to capture disproportionate share in their served markets.
The uncertainty here lies in project timing, macroeconomic conditions, and policy implementation pace. If infrastructure spending or agricultural investment slows in key regions, near-term utilization may soften even as the longer-term growth trajectory remains intact. Producers with flexible capacity and diversified application exposure will be better equipped to manage that variability.
Strategic Actions for Decision Makers
For Manufacturers and Producers
Prioritize coating and tensile differentiation as the core of commercial strategy. The market is rewarding firms that can offer longer corrosion protection and higher mechanical performance in applications where lifecycle value justifies premium pricing. Invest in technical demonstration, field validation, and specification support so that sales teams can compete on performance rather than price alone. At the same time, manage zinc exposure and coating efficiency carefully, since raw material volatility will continue to pressure margins and require disciplined pricing and procurement practices.
Consider capacity decisions through the lens of application mix rather than aggregate volume. Expanding output is valuable only if it aligns with the segments where performance differentiation and reliable supply can be monetized. Where advanced coating or high-tensile lines are justified, ensure that quality control, customer technical support, and application engineering are scaled alongside production capacity.
For Investors
Evaluate exposure based on product positioning and end-use resilience rather than market-level growth alone. The most attractive risk-adjusted opportunities are likely to be found in firms with credible high-tensile and advanced coating portfolios, diversified application bases, and the ability to serve infrastructure, energy, and construction demand with differentiated specifications. Scale remains important, but it should be assessed alongside technological roadmap, margin defense against raw material volatility, and the strength of specification relationships in priority segments.
Watch for consolidation and partnership activity as signals of how the market is maturing. Collaborations around advanced coatings and capacity expansions in high-growth regions can reveal where value is being created and which technological pathways are gaining commercial traction.
Hot-dip Galvanized Steel Market
For Procurement and Supply Chain Leaders
Reassess specification criteria to reflect total cost of ownership, especially in applications exposed to corrosion, structural load, or long maintenance cycles. Where lifecycle performance matters, advanced coatings and high-tensile options may lower long-term risk even if unit costs are higher. Build procurement frameworks that allow for performance-based selection rather than defaulting to lowest initial price in every category.
Strengthen supplier relationships with an emphasis on quality consistency, coating reliability, and delivery dependability. In project-driven environments, supply assurance and technical support often matter as much as price. Diversifying sourcing where appropriate and maintaining visibility into supplier capacity and coating technology roadmaps can reduce risk during periods of raw material volatility or demand surges.
Navigating the Next Phase with Better Intelligence
The galvanized steel wire market is not simply expanding; it is restructuring around performance, durability, and application-specific value. Growth to nearly USD 3 billion by 2032 is plausible, but the distribution of that growth will favor firms and buyers who understand where premium coatings, high-tensile formulations, and regional demand patterns converge. For decision makers, the most valuable next step is to move from market-level awareness to segment-level clarity: which applications are shifting specifications fastest, where coating innovation is translating into commercial advantage, and how capacity and cost structures will evolve as raw material volatility and infrastructure priorities continue to interact.
A deeper dive into regional demand splits, type-level dynamics across hot-dip, electrogalvanized, and other coated wire categories, and application-level growth paths can sharpen strategic planning far beyond what headline figures reveal. Disaggregating the market by region, product type, and end use exposes where concentration risks lie, where premium segments are forming, and which capacity and procurement decisions are best timed now versus later. For executives and investors looking to translate market momentum into concrete action, that level of segmentation and forward scenario detail is where strategy becomes executable.
For detailed analysis of this topic, please visit the official page: Galvanized Steel Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Relay Market 2026: Why 6.2% CAGR and EV Demand Redefine Growth
By PW Consulting, 2026-09-21
Navigating the Automotive Relay Market: Strategic Trends and Commercial Opportunities
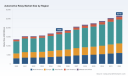
The automotive relay market is undergoing a structural transformation driven by vehicle electrification, evolving regulatory mandates, and shifting supply chain dynamics. Valued at approximately 17,850 million USD in 2025, the market has demonstrated consistent momentum over the past five years, expanding from roughly 13,600 million USD in 2020. This trajectory translates to a compound annual growth rate of 6.2 percent through 2032, positioning the segment as a steady contributor to broader automotive electrical components revenue. Rather than reflecting rapid disruption, the expansion pattern suggests incremental but persistent demand growth, underpinned by the increasing complexity of vehicle electrical architectures and the gradual replacement of mechanical switching components with more specialized relay solutions.
Regional and application distributions reveal a market that remains heavily anchored in established automotive manufacturing corridors, yet increasingly exposed to new demand vectors. Asia Pacific continues to command the largest share of overall volume, reflecting both legacy production capacity and accelerating domestic vehicle assembly. North America and Europe maintain substantial presence, though their growth profiles are increasingly shaped by regulatory timelines and platform-specific electrification strategies rather than pure volume expansion. From an application standpoint, powertrain and body/chassis systems remain the traditional volume anchors, while safety, HVAC, and battery management segments are gaining relative importance as vehicle electrical loads diversify. The market is also notably fragmented, with the top three participants capturing slightly under twenty percent of total revenue and the top five reaching roughly twenty-six percent, indicating that scale advantages exist but are not yet decisive enough to concentrate value exclusively among a handful of incumbents.
Key Challenges and Inflection Points
Despite the steady growth trajectory, the market faces several structural tensions that will define competitive outcomes over the next several years. The first challenge lies in reconciling traditional relay architectures with the electrical demands of modern vehicle platforms. As voltage levels rise and switching requirements become more bidirectional and high-frequency, conventional electromagnetic relays face performance and reliability constraints that necessitate redesigns, material substitutions, or migration toward alternative switching technologies in certain use cases. This creates a transitional period where suppliers must invest in new engineering capabilities without immediately retiring legacy product lines that still generate meaningful volume.
A second inflection point centers on cost structure volatility. Recent pricing actions across critical input materials, including contactors, relay accessories, glass epoxy multi-layer circuit board materials, and prepreg, signal a broader inflationary pressure on component production. These adjustments are not isolated procurement issues; they directly affect relay pricing feasibility, margin sustainability, and the ability of OEMs to absorb cost increases without altering component specifications or sourcing strategies. Suppliers that rely on rigid cost models or undifferentiated commodity positioning are especially exposed, while those with diversified material sourcing or integrated design capabilities are better positioned to manage fluctuations.
The third challenge involves the uneven pace of vehicle electrification across segments and geographies. While high-voltage and EV-related relay applications are expanding, the broader fleet transition remains staggered. Commercial vehicles, specialty platforms, and certain regional markets continue to rely on conventional electrical architectures, creating a hybrid demand environment where suppliers must simultaneously serve mature low-voltage applications and invest in higher-performance switching solutions. This dual demand profile complicates capacity planning, product roadmapping, and customer engagement strategies, particularly for manufacturers operating with limited flexibility across voltage classes and form factors.
Key Drivers Shaping Market Trajectory
Technological Innovation and High-Voltage Switching Evolution
Product development activity in the relay space increasingly reflects a shift from incremental refinement to targeted capability expansion. Recent launches illustrate how suppliers are responding to the need for compact, high-current, and gasless switching solutions tailored to next-generation electrification requirements. One notable example is the introduction of a high-voltage DC relay designed for 500 VDC and 120 A bidirectional operation, developed with a gasless plunger-type architecture that supports EV charging, battery systems, and power electronics applications while aligning with carbon-neutral design objectives. This type of product emphasizes two strategic priorities: enabling higher voltage and current handling within constrained packaging envelopes, and reducing reliance on gas-filled designs that carry environmental and regulatory complexity.
A parallel development is the launch of a high-current automotive relay built around magnetic arc blowout technology, engineered for industrial vehicle electrification and rated for substantial current and voltage ranges in a compact lightweight form factor. The design targets durability through defined operational lifecycles with integrated resistor and diode configurations, reflecting an emphasis on ruggedized performance for demanding vehicle platforms. Together, these examples underscore a broader trend: relay development is becoming more application-specific, with performance claims increasingly tied to real-world operating conditions, lifecycle expectations, and integration constraints rather than generic specification benchmarks.
Policy, Regulation, and Sustainability Alignment
Regulatory and sustainability expectations are shaping relay design choices in ways that extend beyond compliance. The move toward gasless relay architectures is not only a technical response to high-voltage switching needs but also a reflection of increasing attention to material use, emissions, and lifecycle considerations within component manufacturing. As vehicle manufacturers face broader decarbonization commitments and supply chain transparency requirements, relay suppliers that can offer designs reducing hazardous gas dependence or improving material efficiency gain a positional advantage in qualification processes and long-term sourcing discussions.
At the same time, regulatory pressure does not operate uniformly across regions or vehicle categories. Emissions standards, electrification incentives, and safety requirements influence the pace at which new relay specifications are adopted, creating a staggered demand environment. Suppliers that align product development with multiple regulatory trajectories, rather than optimizing for a single jurisdiction or platform, are better equipped to maintain relevance as qualification cycles lengthen and customer expectations broaden.
Demand-Side Shifts in Vehicle Electrification and Electrical Load Growth
Vehicle electrical architecture is becoming more decentralized and load-intensive, expanding the functional role of relays beyond traditional switching tasks. As platforms incorporate more electronic control units, higher-power comfort systems, advanced safety functions, and electrified powertrain components, the number and variety of switching points increase. This load growth supports continued demand for relays across multiple application areas, but it also raises performance expectations related to reliability, thermal management, and miniaturization.
In addition, the growing presence of electric and hybrid platforms is reshaping application priorities. High-voltage battery management, charging interfaces, and power distribution networks are creating new relay deployment contexts that differ materially from conventional low-voltage automotive use. These contexts require components that can handle higher stresses, support bidirectional power flow where relevant, and maintain consistent performance over extended service intervals. The demand shift is therefore not merely about volume growth; it is about a redefinition of the operating envelope in which relays must function.
Supply Chain Realignment and Cost Structure Pressures
Material and component pricing dynamics are reshaping the economics of relay production. Announcements of significant price increases for contactors, relay-related accessories, and printed circuit board materials indicate that supply chain costs are rising at a pace that cannot be ignored in product pricing strategies. These pressures affect both manufacturers and downstream customers, forcing a re-evaluation of specification thresholds, alternative material eligibility, and long-term contracting approaches.
For relay suppliers, the implication is clear: resilience increasingly depends on sourcing flexibility, design efficiency, and the ability to justify value beyond unit price. Suppliers that can integrate material optimization into product design, maintain multiple sourcing pathways, and communicate total cost of ownership benefits are more likely to preserve margins without sacrificing competitiveness. Conversely, those positioned as interchangeable commodity providers face greater vulnerability when input costs escalate and differentiation remains limited.
Competitive Landscape and Leading Strategies
The competitive field in the automotive relay market is broad and geographically diverse, featuring large multinational component suppliers, established electrical equipment manufacturers, and regional specialists with strong positions in specific voltage classes or application segments. This breadth matters because the market is not consolidating rapidly enough to eliminate differentiation opportunities, yet scale, engineering depth, and supply chain reach are becoming more valuable as product requirements intensify.
Leading participants tend to differentiate along several strategic axes. One is application-specific engineering, where suppliers build relay families optimized for high-voltage EV systems, industrial vehicle electrification, or compact PCB integration rather than offering generalized switching components. Another is integration and qualification support, which reduces customer adoption friction and strengthens long-term platform relationships. A third is material and manufacturing resilience, enabling suppliers to absorb cost volatility and sustain delivery reliability during periods of input-price instability. These dimensions are increasingly intertwined, as performance claims, sustainability attributes, and supply reliability all influence sourcing decisions.
Strategic Positioning Among Major Players
Global electronics and connectivity-focused suppliers often emphasize miniaturization, high-reliability contact systems, and broad automotive platform coverage. Their value proposition typically extends beyond the relay itself to include system-level integration support and a wide portfolio that can address multiple vehicle electrical functions. In the relay context, this approach helps capture demand across both conventional and electrified architectures, though it also requires sustained investment in product updates as voltage and current expectations rise.
Japanese manufacturers bring strong engineering discipline and a track record in component reliability, often targeting support for electrification, charging infrastructure, and precision switching applications. Their recent high-voltage relay introductions reflect a focus on compact designs, bidirectional capability, and environmental considerations such as gasless construction. This positions them as credible partners for customers seeking to align performance requirements with sustainability and packaging constraints.
European industrial and electrification-oriented players contribute depth in higher-power switching, robust contactor and relay ecosystems, and application support for demanding vehicle and industrial contexts. Their approach frequently combines electrical performance with broad accessory and system compatibility, which can be advantageous for customers prioritizing integration simplicity and lifecycle durability. At the same time, pricing sensitivity and material cost exposure remain important management considerations, particularly when input cost increases affect entire product families.
Chinese manufacturers have expanded their presence by combining volume production capability with growing engineering specialization across relay types and voltage ranges. Their strategic relevance lies in serving both domestic vehicle production growth and export-oriented supply chains, often with competitive cost structures and rapid capacity scaling. As application requirements become more demanding, however, sustained differentiation will depend on reliability validation, high-voltage capability, and the ability to meet international qualification expectations.
Market Evolution: Consolidation, Fragmentation, and New Entry Dynamics
The current market structure suggests that consolidation is occurring gradually rather than abruptly. The moderate concentration levels indicate that incumbents hold meaningful but not dominant shares, leaving room for specialized suppliers to compete on performance, region, or application fit. Over the next several years, differentiation is likely to sharpen as high-voltage and EV-related relay demand grows, rewarding suppliers that can reliably meet elevated electrical and environmental specifications.
PW Consulting Automotive & Machinery Research Center
At the same time, the market is not immune to fragmentation pressure. Regional manufacturing expansion, localized sourcing preferences, and platform-specific component requirements can sustain a diverse supplier base, especially where customers prioritize supply security or cost competitiveness. New entrants and niche specialists may find opportunities in targeted segments such as high-voltage DC switching, ruggedized industrial vehicle relays, or compact PCB-mounted solutions, particularly if they can demonstrate clear engineering advantages or sustainable design attributes. The strategic question for established players is whether to defend broadly across relay categories or concentrate resources on the highest-growth, highest-specification segments where performance and qualification barriers are rising.
Future Trends and Commercial Opportunities
High-Voltage and Bidirectional Switching Will Become a Core Differentiation Battleground
As vehicle electrical architectures continue to accommodate higher voltages and more complex power flow paths, relays designed for high-voltage DC applications and bidirectional switching are likely to capture disproportionate attention. This trend creates commercial opportunity for suppliers that can combine compact form factors, durable arc management, and gasless or environmentally optimized designs with validated performance claims. The opportunity is not limited to EV battery systems; it extends to charging interfaces, power distribution modules, and electrified commercial vehicle platforms where switching reliability and packaging efficiency are critical. Suppliers that establish early credibility in these specifications can strengthen platform qualifications and lock in long-term demand cycles.
Material Cost Volatility Will Redefine Value Propositions and Sourcing Strategies
The recent wave of input cost increases suggests that component pricing will remain a strategic concern rather than a temporary disruption. Over the next few years, the market is likely to see more active discussion of alternative materials, design-for-cost engineering, and long-term supply agreements that share or mitigate volatility. For relay manufacturers, this trend creates an opportunity to move up the value chain by offering solutions that reduce total system cost, simplify integration, or improve durability enough to justify premium positioning. For buyers, the opportunity lies in re-evaluating specification thresholds and supplier portfolios to balance performance requirements with cost resilience. Companies that treat material cost pressure as a design and sourcing challenge, rather than merely a procurement issue, will be better positioned to sustain margins and supply continuity.
Time Delay Relays Market
Application Diversification Will Drive Segment-Specific Relay Strategies
Relay demand is increasingly shaped by the functional needs of specific vehicle systems rather than by uniform fleet-wide replacement cycles. Powertrain, body and chassis, safety, comfort, and battery-related applications each impose distinct electrical, thermal, and lifecycle requirements. This diversification favors suppliers that can develop segment-specific relay families and support customers with application engineering rather than selling largely interchangeable products. It also creates opportunities for targeted growth in areas where electrical loads are expanding most rapidly and where reliability expectations are tightening. The commercial implication is that broad portfolio breadth alone will be less valuable than demonstrable fit to high-priority applications and the ability to validate performance under realistic operating conditions.
Worldwide Relay Output Module Market
Risks and Uncertainties to Monitor
Several uncertainties could alter the trajectory of these trends. If electrification adoption slows in certain regions or segments, high-voltage relay demand growth may not materialize as quickly as anticipated, leaving suppliers with elevated investment exposure in specialized product lines. If material cost pressures intensify further, margin compression could force price increases that test customer acceptance and accelerate the search for alternatives. If qualification cycles lengthen or sustainability requirements become more stringent, smaller or less-integrated suppliers may face disproportionate barriers to entry and retention. Finally, if alternative switching technologies gain traction in specific applications, traditional relay demand could face localized substitution risk, particularly where miniaturization, solid-state performance, or system-integration priorities dominate.
Strategic Recommendations for Decision-Makers
For Manufacturers and Component Suppliers
Focus product development on the intersection of high-voltage capability, compact packaging, and environmental optimization. Relay families that can demonstrate reliable performance under elevated voltage and current conditions, while reducing gas dependence or material intensity, are more likely to align with future platform requirements and qualification expectations. Equally important is supply chain resilience: diversify material sourcing, validate alternative input options where feasible, and build pricing strategies that can absorb volatility without eroding customer relationships. Where possible, invest in application engineering support that helps customers integrate relays into broader electrical architectures, since this deepens differentiation beyond unit specification comparisons.
For Investors and Strategic Capital Allocators
Evaluate relay-focused opportunities through the lens of specification upgrading and application alignment rather than volume growth alone. Companies with credible high-voltage DC relay capabilities, ruggedized industrial vehicle solutions, or differentiated sustainability attributes are better positioned to capture value as platform requirements intensify. Pay close attention to cost-structure resilience, sourcing flexibility, and the ability to sustain delivery reliability during periods of input-price instability. In addition, assess whether a target company’s portfolio is balanced across mature low-voltage demand and higher-growth electrification applications, since overconcentration in either direction can create vulnerability if adoption patterns shift.
For Procurement Teams and Vehicle Platform Buyers
Treat relay sourcing as a long-term performance and resilience decision, not a short-term price comparison. Specify requirements around voltage class, current handling, lifecycle durability, and environmental attributes where relevant, and validate supplier claims against realistic operating conditions. Diversify the supplier base where possible to reduce exposure to single-source cost shocks, while maintaining enough concentration to secure engineering support and qualification continuity. As input material costs remain volatile, consider multi-year agreements, alternative specification pathways, and total-cost frameworks that account for integration efficiency and service durability rather than initial unit price alone.
The automotive relay market is not defined by sudden disruption, but by a steady accumulation of technical, regulatory, and supply chain pressures that are reshaping how value is created and captured. Suppliers and buyers that anticipate these shifts, align product and sourcing strategies with emerging electrical architecture requirements, and build resilience into cost and qualification processes will be better positioned to convert market growth into durable commercial advantage. For organizations seeking a deeper breakdown of segment-level dynamics, regional demand patterns, and company-specific positioning across relay types and applications, a detailed research report can provide the granularity needed to translate these strategic themes into actionable planning.
For detailed analysis of this topic, please visit the official page: Automotive Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Traffic Signs Market Forecast 2026-2032: The 7.75% CAGR Reshaping Industry Growth
By PW Consulting, 2026-09-21
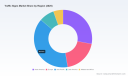
The Traffic Signs Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global traffic signs market is navigating a structural transition. Over the tracking period from 2020 through 2025, the sector expanded from approximately USD 44.59 million to a projected USD 64.76 million, and forward estimates point to continued growth toward nearly USD 110 million by 2032, supported by a compound annual growth rate of 7.75%. The trajectory signals more than routine infrastructure renewal. It reflects a convergence of regulatory tightening, material cost volatility, and the early stages of digital-physical integration in road safety infrastructure. For executives, planners, and investors, the question is no longer whether the market will grow, but which segments of the value chain will capture disproportionate value as standards evolve and procurement models reorganize.
Worldwide Traffic Signal Recognition Market
The numbers outline a market that has recovered from pandemic-era procurement pauses and is now anchored by sustained public investment in road safety, urbanization-driven signage demand, and incremental modernization of legacy traffic control systems. Historical data shows consistent year-over-year expansion, with the jump from 2023 to 2024 indicating a stabilization phase before the 2025 baseline accelerates. The forecast period through 2032 suggests that growth will not be linear; rather, it will be shaped by policy adoption cycles, regional infrastructure pacing, and manufacturers’ ability to navigate input cost pressure while maintaining compliance with evolving visibility and performance standards.
Market Reality and Core Challenges
The market’s expansion is real, but it is unfolding against a backdrop of operational friction. Three challenges stand out as particularly consequential for strategic planning.
Material Cost Volatility and Margin Compression
Aluminum remains the primary substrate for most traffic sign blanks, and its pricing dynamics have introduced a new layer of risk into production planning and bid economics. Through late 2025, Midwest Premium aluminum prices climbed approximately 190% year-over-year, a spike that compresses margins for manufacturers working under fixed-price municipal contracts or competing in price-sensitive procurement environments. This is not merely a cost issue; it reshapes sourcing strategies, inventory timing, and the economics of sign blank production versus finished sign assembly. Companies that rely heavily on coil stock and blank production are exposed to raw material volatility in ways that differentiate their cost structures from firms focused on value-added assemblies, illuminated solutions, or traffic calming systems.
PW Consulting
Regulatory Visibility Standards and Compliance Complexity
Visibility and retroreflectivity requirements are becoming more prescriptive, raising the bar for what qualifies as a compliant permanent traffic control sign. In Ohio, for example, guidance from the Department of Transportation has moved toward recommending Type III retroreflective sheeting for all permanent new traffic control signs on maintained highways, while also requiring Type IV, IX, or XI sheeting in specific contexts. These requirements are part of a broader standardization trend that ties sign performance to measurable visibility outcomes rather than legacy material norms. Compliance complexity is increasing because regulators are not only specifying sheeting grades but also linking them to placement, maintenance cycles, and nighttime performance expectations. For manufacturers and contractors, the operational implication is clear: product specifications that fall behind evolving standards risk disqualification in public tenders, while faster adoption can become a competitive differentiator.
At the same time, the broader framework governing traffic control devices continues to evolve. Recent updates to MUTCD standards are reinforcing visibility, placement, and performance requirements across a range of sign and traffic calming products. That means compliance is no longer a one-time certification exercise; it is an ongoing design constraint that affects product development cycles, testing protocols, and field deployments.
Procurement Fragmentation and the Pressure to Standardize
Traffic sign procurement remains fragmented across municipalities, state agencies, contractors, and cooperative purchasing vehicles. This fragmentation creates both opportunity and inefficiency. On one hand, it allows specialized providers to serve niche applications and regional preferences. On the other hand, it slows the adoption of higher-performance materials and limits scale economies for standardized solutions. The tension is visible in the market’s concentration profile, where a meaningful share of revenue is held by a relatively small group of firms, yet substantial demand still flows through dispersed buyers with varied specifications and purchasing timelines. As cooperative purchasing contracts and multi-agency frameworks expand, the market may tilt toward more standardized product families, but the transition will be uneven across regions and agency types.
Core Drivers Reshaping the Market
Technology Innovation: From Passive Signage to Active Visibility
One of the most significant shifts in the market is the move beyond static signage toward solutions that enhance driver awareness through illumination, flashing elements, and sensor-linked warnings. Solar-powered flashing warning signs, radar speed displays, and pedestrian crossing enhancements are expanding the definition of what a traffic sign can do. This is not a wholesale replacement of traditional signs, but an incremental layering of active visibility features where risk is higher or compliance requires stronger behavioral cues. The commercial relevance is that these products command different margin structures, different installation requirements, and different procurement justifications than passive blanks or reflective signs. Manufacturers that can combine compliance-grade base products with active visibility add-ons are positioned to capture value in applications where safety outcomes are measured and funded more explicitly.
The traffic calming segment illustrates this dynamic well. Products that integrate static signs with radar-based feedback, flashing warnings, and pedestrian-crossing enhancements are increasingly tied to public agency goals around speed management and intersection safety. As these solutions become more standardized and more visibly effective, they create a bridge between traditional sign manufacturing and the broader traffic safety equipment market.
Policy and Regulatory Momentum around Safety Outcomes
Policy is becoming a more direct driver of demand because road safety is increasingly framed around measurable outcomes rather than routine maintenance. Regulatory bodies and transportation departments are sharpening requirements for retroreflectivity, sheeting performance, and device visibility. This policy momentum benefits suppliers that can demonstrate compliance, provide documentation, and align product roadmaps with emerging standards. It also raises the importance of regulatory intelligence as a commercial capability. Companies that anticipate updates to visibility standards, understand regional interpretations, and design products with forward compliance in mind reduce the risk of specification obsolescence and improve their positioning in agency procurement.
A related policy driver is the increasing use of cooperative purchasing frameworks, which can broaden access to compliant products for public agencies while also creating more transparent price discovery. Recent contract awards that expand public agency access to MUTCD-compliant safety solutions show how procurement channels themselves are becoming a strategic lever. For manufacturers, inclusion in such frameworks can shorten sales cycles and increase volume predictability, but it also intensifies competition on specification, availability, and total cost of ownership.
Traffic Signal Controller Market
Demand-Side Shifts in Municipal and Regional Procurement
Demand is being shaped by a shift in how public agencies think about signage and safety infrastructure. Instead of treating signs purely as replacement items, agencies increasingly evaluate them within broader safety programs, work zone management plans, and traffic calming initiatives. That shift changes the sales narrative from unit price to functional outcome. It also expands the relevant buying center, bringing engineering, safety, and maintenance teams into the decision process alongside procurement. As a result, suppliers that can articulate performance benefits, maintenance implications, and compliance documentation are gaining an advantage over those competing primarily on material cost.
In addition, the demand mix is diversifying by application type. Guide and direction signs, warning signs, regulatory signs, and other specialized signage each serve different operational contexts, and the relative importance of each category varies by region and project type. The broader point is that demand is not monolithic. Growth is being distributed across categories with different replacement cycles, specification sensitivity, and installation complexity. Understanding which application categories are tied to higher-frequency renewal cycles versus longer-life installations is essential for revenue forecasting and capacity planning.
Supply Chain and Cost Structure Reconfiguration
The supply chain for traffic signs is being tested by material input volatility, logistics complexity, and the need to maintain consistent quality across reflective sheeting, metal substrates, and ancillary hardware. Cost structure is becoming a strategic differentiator rather than a back-office concern. Manufacturers that can manage blank production efficiently, secure stable sheeting supply, and reduce lead-time variability gain latitude in pricing and bidding. At the same time, regional manufacturing footprints matter more as agencies and contractors look for predictable delivery, localized support, and lower total installed cost. In this environment, the competitive edge often lies in combining material sourcing discipline with application-specific product configuration, rather than pursuing scale alone.
The rise of export-oriented manufacturers also adds a global dimension to supply dynamics. Some producers have built positions serving a wide range of countries with certifications that support cross-border distribution. That creates price and availability competition in certain segments while also giving buyers more options for specification-matched products. The strategic response for established players is not simply to compete on price, but to reinforce compliance assurance, service responsiveness, and product consistency that are harder to replicate through transactional importing.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of specialized U.S. manufacturers, export-oriented producers, and broader traffic systems providers. Several patterns define the current landscape.
A group of North American companies has built its positioning around MUTCD and DOT compliance for static signs, custom reflective aluminum signs, work zone products, and related control signage. These firms compete heavily on specification alignment, availability, and familiarity with public agency procurement requirements. Their differentiation often comes from product breadth within compliant signage categories, responsiveness to municipal and contractor demand, and the ability to supply both standardized and custom configurations. In a market where compliance documentation and material consistency matter, that positioning can be durable, especially when paired with cooperative purchasing access or strong regional distribution.
A second grouping emphasizes traffic calming and active visibility solutions. These providers extend beyond traditional sign blanks into radar speed displays, flashing warning signs, pedestrian crossing enhancements, and related systems. The strategic advantage here is category expansion: by offering products that address speed management and driver awareness directly, these companies can participate in projects where safety outcomes are prioritized and where funding is tied to measurable behavior change or risk reduction. This approach also diversifies revenue beyond replacement-driven signage demand, though it requires investment in product development, testing, and sometimes field support.
A third dimension is represented by broader traffic systems providers with portfolios spanning standard signs, variable message signs, dynamic signage, and illuminated solutions for highways and urban environments. These companies compete by offering integrated capability across static and dynamic categories, which can be attractive for larger projects or regions pursuing modernization programs. Their scale and portfolio breadth allow them to address multiple signage functions within a single engagement, but they must still navigate the same regulatory and material pressures as more specialized players.
Recent market activity shows how these strategies are playing out. One U.S. traffic calming provider expanded access to public agencies through a cooperative purchasing contract, strengthening the procurement channel for MUTCD-compliant safety solutions. Around the same time, the same provider introduced new solar flashing warning signs designed to improve visibility and driver awareness on critical roadways. These moves illustrate a combined strategy of channel expansion and product refresh aimed at active visibility applications. In parallel, an Austrian traffic systems provider previewed next-generation sign solutions at a major industry event, signaling continued investment in advanced signage portfolios for highways and urban deployments. Together, these developments suggest that competition is intensifying not only in price, but in channel access, product modernization, and the ability to meet evolving visibility expectations.
The market is also likely to see continued differentiation between firms that compete primarily as commodity-adjacent sign suppliers and those that position around performance, compliance assurance, and application-specific solutions. Consolidation may occur where scale, sourcing, and distribution advantages can be combined, while fragmentation may persist in specialized or region-specific segments where local service and specification knowledge matter. New entrants are most likely to appear in active visibility and traffic calming niches, where the link between product capability and safety outcome is more direct and where procurement narratives increasingly favor demonstrated performance.
Forward Trends and Commercial Opportunities
Active Visibility and Solar-Enabled Signage Will Move from Niche to Mainstream in Targeted Applications
Over the next three to five years, active visibility features are likely to become more common in high-risk corridors, school zones, pedestrian crossings, and work zone environments. Solar flashing warning signs and radar-linked displays will continue to gain traction where agencies need stronger behavioral cues and where wiring or grid access is impractical. The commercial opportunity lies in bundling these solutions with compliant base signage and installation support, creating offerings that are easier for agencies to adopt as part of broader safety programs. The risk is that active visibility products may face their own specification, maintenance, and durability scrutiny, so suppliers will need to invest in field reliability and documentation as well as initial performance claims.
Regulatory-Driven Material Upgrades Will Reset Product Standards and Replace Legacy Inventory
As visibility and sheeting requirements become more prescriptive, there will be a multi-year cycle of material upgrades and replacement demand. This creates a commercial window for manufacturers and distributors that can supply compliant retroreflective materials, upgrade existing product lines, and help agencies manage transition timelines. It also raises a strategic risk for suppliers whose product portfolios lag behind emerging standards. The opportunity is not just in selling new signs, but in helping buyers navigate the shift from older materials to higher-performance sheeting, including guidance on applicability, installation, and maintenance expectations. Firms that treat regulatory change as a product strategy input rather than a compliance afterthought will be better placed to capture this cycle.
Regional Demand Divergence Will Reward Segment-Specific Positioning
Demand growth will not unfold uniformly. Regions with faster urbanization, more active road safety programs, and stronger cooperative procurement frameworks are likely to show stronger momentum, while other markets may remain dependent on replacement cycles and budget pacing. For manufacturers and investors, this means that broad market averages can obscure where the most attractive opportunities actually sit. The more productive approach is to align product portfolios, distribution capacity, and pricing strategy with regional demand characteristics and procurement behavior. Companies that can tailor offerings to specific application mixes, agency types, and compliance expectations will be better positioned than those relying on a single standardized playbook.
For the materials and cost side, the forward risk is that aluminum and sheeting volatility may persist in cycles, making hedging, sourcing flexibility, and product mix optimization increasingly important. Suppliers that can shift emphasis toward higher-value assemblies, active visibility products, or service-linked offerings may be better insulated than those dependent on low-margin blank production alone.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
- Align product roadmaps explicitly with evolving visibility and sheeting standards so that compliance becomes a design input rather than a retrofit exercise.
- Expand into active visibility and traffic calming adjacencies where safety outcomes support stronger value propositions and differentiate pricing from commodity sign supply.
- Build sourcing and inventory strategies that reduce exposure to metal input volatility, including flexible blank procurement, regional supply options, and product mixes that balance material-intensive and value-added items.
For Investors and Strategic Capital
- Evaluate exposure to regulatory-driven replacement cycles and active visibility adoption, since these dynamics can shape both revenue durability and margin profiles across different business models.
- Distinguish between players that compete primarily on price and commodity-like supply and those that have defensible positions in compliance, product reliability, channel access, or application specialization.
- Watch for consolidation opportunities where regional distribution, cooperative purchasing access, and product breadth can be combined to improve scale and customer retention.
For Procurement Agencies and Contracting Entities
- Standardize specifications around current visibility and performance expectations to reduce specification lag and improve comparability across bids.
- Evaluate total cost and safety outcomes rather than unit price alone, especially when considering active visibility or higher-performance sheeting that may reduce long-term maintenance or improve driver response.
- Use cooperative purchasing and multi-agency frameworks strategically to expand access to compliant products while maintaining specification rigor and vendor accountability.
The traffic signs market is entering a phase where growth is increasingly tied to how well participants navigate regulatory change, material cost pressure, and the shift toward active visibility. The companies that will capture the most value are those that can combine compliance confidence with product modernization and efficient cost structures, while also understanding how demand differs by region, application, and procurement channel. For executives and investors looking to move from market awareness to detailed segmentation, competitive mapping, and tailored commercial strategy, a full research report can provide the deeper breakdown needed to support decisions with precision.
For detailed analysis of this topic, please visit the official page: Traffic Signs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Calcium Formate Market: The Real Drivers Behind 7.2% CAGR Growth Through 2032
By PW Consulting, 2026-09-21
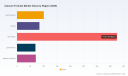
The Calcium Formate Market: Strategic Shifts and Commercial Opportunities Through 2032
The global calcium formate market has entered a period of steady expansion, characterized by consistent value growth and shifting demand patterns across construction, animal nutrition, and industrial applications. Valued at 495.16 million USD in 2020, the market climbed to 701.0 million USD by 2025, reflecting a compound annual growth rate of approximately 7.2 percent through the forecast horizon extending to 2032. By the close of the projection period, market value is positioned to surpass 1.14 billion USD, driven by structural demand in fast-setting construction chemistries, feed preservation formulations, and specialty industrial processes. The trajectory signals a transition from steady commodity positioning toward a more differentiated landscape where grade purity, regional supply reliability, and regulatory compliance increasingly dictate commercial outcomes.
A Market at an Inflection Point
While the headline growth figures suggest uninterrupted expansion, the underlying dynamics reveal a sector navigating several concurrent pressures. First, raw material cost volatility is reshaping margin structures across the value chain. Formic acid serves as the primary feedstock for calcium formate production, and recent pricing actions in European markets have directly altered production economics. A March 2026 price increase of 250 Euro per metric ton on formic acid immediately elevated input costs for downstream calcium formate manufacturers, compressing margins for producers operating without index-linked contracts or hedging mechanisms. This shift forces a reassessment of regional sourcing strategies and accelerates interest in vertically integrated or regionally balanced supply models.
Potassium Formate Market
Second, regulatory frameworks are redefining permissible use levels and creating new pathways for market entry. The formal approval of calcium formate as a feed acidifying agent for swine and poultry at up to 1.2 percent of complete feed marked a significant clarification for formulators and premix suppliers. Simultaneously, a 2026 consultation process in Canada regarding pre-market amendment of the Feeds Regulations, 2024 signals ongoing scrutiny and evolving approval timelines for new feed ingredient categories. For market participants, regulatory clarity expands addressable demand in animal nutrition, but inconsistent regional approval pathways introduce compliance complexity and extended time-to-market for cross-border product rollouts.
Third, demand-side shifts are altering grade prioritization and application mix. Construction chemical formulators continue to prioritize calcium formate for its performance in cold-weather concrete acceleration, tile adhesives, and dry-mix mortar systems, particularly in markets experiencing infrastructure renewal or seasonal construction constraints. At the same time, feed preservative demand is expanding where producers seek alternative acidifiers with favorable handling characteristics and compatibility with existing premix architectures. These parallel demand streams are pulling the market in different technical directions, requiring suppliers to maintain distinct product specifications rather than relying on a single commodity-grade offering.
PW Consulting
The competitive structure remains relatively fragmented, with the top three suppliers accounting for approximately one-quarter of total market value and the top five capturing just over one-quarter. This concentration pattern indicates meaningful room for regional differentiation and specialized positioning, but it also underscores the importance of scale efficiency, technical service capabilities, and supply continuity as competitive differentiators.
Core Drivers Reshaping the Market
Several interconnected forces are redefining how value is created and captured across the calcium formate landscape. Understanding these drivers provides the foundation for investment, sourcing, and product strategy decisions.
Feedstock dynamics and cost architecture. The relationship between formic acid pricing and calcium formate production economics is central to profitability. Recent European formic acid pricing adjustments have illustrated how quickly input costs can shift, particularly when supply is concentrated in specific regional hubs or affected by broader chemical market cycles. Producers with access to captive or long-term feedstock supply, or those positioned in regions with lower feedstock volatility, gain a structural cost advantage. Conversely, manufacturers relying on spot procurement face greater exposure to margin compression. This dynamic is encouraging a reevaluation of sourcing footprints, including regional substitution, dual-supplier strategies, and contractual structures that link cost pass-through to finished-grade pricing.
Regulatory evolution as a demand catalyst and barrier. Regulatory developments are simultaneously unlocking demand and adding compliance complexity. The formal recognition of safe use levels for calcium formate in swine and poultry feed creates a clearer formulation pathway for feed acidifiers, supporting demand in animal nutrition where gut health, preservation, and feed efficiency remain priorities. At the same time, ongoing consultation processes in markets such as Canada demonstrate that ingredient approval is not a one-time event but a continuous regulatory management requirement. Companies that treat regulatory alignment as a core commercial capability—rather than a backend compliance function—can accelerate market access and reduce the risk of reformulation delays.
Construction chemical performance requirements. Demand from construction applications continues to be shaped by performance needs that go beyond simple set acceleration. Formulators increasingly look for calcium formate grades that deliver reliable performance across varying temperature conditions, compatibility with diverse binder systems, and consistency in dry-mix and pre-blended mortar applications. Cold-weather concreting, tile adhesive performance, and corrosion-inhibition considerations in certain applications add technical nuance to procurement decisions. As infrastructure investment cycles and housing activity patterns shift regionally, suppliers that can provide application-specific grade optimization and technical support are better positioned to retain share even when price competition intensifies.
Animal nutrition and feed preservation trends. In the feed segment, demand is influenced by broader livestock production practices, biosecurity concerns, and the search for preservative solutions that integrate cleanly into existing feed formulations. Calcium formate's role as an acidifying and preserving agent aligns with formulator interest in ingredients that support feed stability and handling while meeting defined safety thresholds. The expansion of permitted inclusion levels in certain species has broadened the formulation envelope, allowing feed manufacturers to optimize dosage strategies without compromising compliance. This development is particularly relevant where producers aim to replace or supplement more traditional acidifiers with alternatives offering favorable handling, dust, or storage characteristics.
Competitive Positioning and the Evolution of the Landscape
The supplier landscape spans established multinational producers, specialized chemical manufacturers, and regional players concentrated in Asia Pacific, Europe, and North America. Rather than competing solely on price, leading participants are differentiating through grade specialization, application support, regional supply reliability, and selective expansion into higher-value industrial or feed-grade niches.
Multinational producers with broad chemical portfolios tend to emphasize high-purity calcium formate for construction, adhesives, and industrial uses, leveraging existing distribution networks and technical service capabilities. Their positioning often centers on specification consistency, regulatory documentation, and the ability to support large-formulation customers with product reliability across multiple markets. For these players, scale and portfolio breadth can translate into stronger relationships with specification-driven buyers who prioritize supply continuity and quality assurance.
Formic Acid Market
Specialized producers focused on green or application-specific calcium formate are carving out distinct positions in feed additives and construction chemicals. By aligning product development with sustainability narratives or regional performance requirements, these companies seek to reduce direct price comparison with commodity-grade alternatives. For feed-focused participants, the strategic emphasis is often on formulation compatibility, safe-use documentation, and regional regulatory readiness. For construction-focused participants, differentiation frequently comes through performance consistency in dry-mix mortars, tile adhesives, and cold-weather accelerators, alongside service responsiveness to formulator testing and customization needs.
Regional manufacturers, particularly in Asia Pacific, play an important role in meeting volume demand across feed and construction applications. Their growth trajectory is supported by proximity to feedstock supply, expanding domestic construction activity, and increasing integration into export-oriented supply chains. At the same time, these players face pressure to demonstrate grade consistency, regulatory compliance for destination markets, and reliable logistics performance as customers diversify their sourcing bases. The result is a landscape where regional scale and technical credibility increasingly coexist as prerequisites for broader market access.
Market structure appears to be evolving along several lines. Consolidation is plausible in segments where scale in feedstock procurement, production efficiency, and regional distribution provides durable advantages, particularly among suppliers targeting large construction-chemical or feed premix customers. At the same time, fragmentation is likely to persist where regional demand patterns, regulatory nuances, and application-specific requirements reward localized production and customized grade offerings. New entrants may find opportunities in niche industrial-grade supply, laboratory and research channels, or specialized feed-additive formulations, especially where incumbents are less focused on small-volume, high-specification segments. Recent feedstock pricing dynamics also suggest that competitive advantage will increasingly depend on cost management agility rather than volume alone, favoring companies that can adapt pricing, sourcing, and product mix quickly.
Forward Outlook: Three Trends to Watch Through 2032
Looking ahead, several trends are likely to shape commercial outcomes over the next three to five years. Each trend carries implications for strategy, risk management, and opportunity capture.
Trend 1: Feedstock-linked margin management becomes a core competitive capability. With formic acid pricing subject to regional volatility and periodic sharp adjustments, producers that institutionalize feedstock cost management—through long-term contracts, regional sourcing diversification, index-linked pricing mechanisms, or selective vertical integration—will be better positioned to protect margins. The commercial implication is clear: cost resilience will increasingly differentiate winners from laggards, especially in periods when raw material spikes cannot be immediately passed through to customers. Companies that fail to build flexible cost architectures risk margin erosion and reduced ability to invest in product development or regional expansion.
Trend 2: Regulatory alignment accelerates feed-grade demand in select markets while creating uneven global access. The formalization of safe use levels for calcium formate in swine and poultry feed expands the formulation toolkit for animal nutrition customers and supports demand growth where adoption is already underway. However, the staggered nature of regulatory consultations and approvals across jurisdictions means that market access will remain uneven. Feed-focused suppliers that invest early in regulatory documentation, regional approvals, and customer education are likely to capture first-mover advantages in markets where inclusion levels are clarified or expanded. Conversely, delays in approval pathways can constrain near-term commercialization even when underlying demand is strong.
Trend 3: Application-specific grade differentiation intensifies as construction and feed demand pull in different directions. Construction chemical requirements and feed preservation needs are not converging into a single commodity specification. Instead, they are reinforcing the need for distinct industrial-grade and feed-grade offerings, each with its own quality, handling, and compliance expectations. Suppliers that maintain clear grade separation, robust quality control, and transparent documentation will be better equipped to serve specification-sensitive buyers. This trend also creates opportunities for companies that can bridge multiple end-use segments, provided they avoid dilution of grade integrity or compliance positioning. At the same time, the growing emphasis on performance-specific grades may invite competitive pressure from alternative additives, requiring continuous demonstration of functional value rather than reliance on commodity positioning alone.
These trends are interconnected. Feedstock cost dynamics influence grade pricing and margin capacity for product development. Regulatory developments shape demand readiness in feed applications and affect the pace at which new formulations can be commercialized. Application-specific differentiation determines whether suppliers can sustain premium positioning or are forced into commodity price competition. Taken together, they point to a market where strategic agility, technical credibility, and regional execution matter more than simple volume scale.
Strategic Actions for Decision-Makers
The evolving calcium formate landscape presents distinct priorities depending on a decision-maker's position in the value chain.
For manufacturers and producers: Prioritize feedstock cost resilience and grade discipline. Evaluate sourcing contracts, regional supply options, and pricing mechanisms that reduce exposure to sharp feedstock swings. Maintain clear separation between feed-grade and industrial-grade offerings, supported by consistent quality control and documentation that meets destination-market requirements. Where feasible, build application-specific technical support capabilities to strengthen relationships with construction-chemical formulators and feed premix suppliers. Consider selective expansion into regions or segments where regulatory clarity is improving and where existing supply gaps create room for reliable, specification-driven participation.
For investors and corporate development teams: Assess exposure to feedstock volatility and regional regulatory pathways when evaluating opportunities. Companies with strong cost-management structures, clear grade positioning, and credible regulatory readiness are better placed to capture demand growth without sacrificing margin stability. Pay attention to market fragmentation as both a risk and an opportunity: fragmented markets can reward specialized, well-executed regional players, but they can also pressure undifferentiated suppliers into margin compression. Monitor consolidation signals in segments where feedstock procurement, production scale, or distribution density creates durable advantages, and evaluate whether potential targets have the technical and compliance capabilities to support broader commercial ambitions.
For procurement and supply chain leaders: Diversify sourcing strategies to reduce vulnerability to single-region feedstock disruptions and to improve responsiveness to grade-specific requirements. Establish specification frameworks that distinguish feed-grade and industrial-grade needs clearly, and align supplier selection with documentation, consistency, and delivery reliability rather than price alone. Where long-term supply relationships are in place, consider contractual structures that accommodate feedstock-driven cost movements while preserving budget predictability. Technical collaboration with suppliers can also help optimize dosage, handling, and formulation performance, turning procurement decisions into value-creating partnerships rather than transactional purchases.
Strategic decisions in this market benefit from detailed visibility into regional demand patterns, grade-level pricing dynamics, regulatory calendars, and competitive positioning. A comprehensive view of these variables supports more precise sourcing, investment, and product strategies, particularly as feedstock conditions and regulatory frameworks continue to evolve. For organizations seeking deeper segmentation data, region-level volume and value context, and customized scenario planning, PW Consulting's full market research report provides a structured foundation for next-step decision-making. The complete study extends beyond the trends summarized here, offering granular segmentation detail and tailored recommendations designed to support executive planning, investment evaluation, and supply strategy development.
For detailed analysis of this topic, please visit the official page: Calcium Formate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Feed Yeast Market: Why Live Yeast and Poultry Dominance Drive a 5.1% CAGR Through 2032
By PW Consulting, 2026-09-21
Navigating the Feed Yeast Market: Strategic Trends and Commercial Opportunities Through 2032
The global feed yeast market is entering a phase of measured but deliberate expansion. Over the past five years, the industry has evolved from a commodity-focused segment into a value-driven arena where strain specificity, functional efficacy, and supply chain reliability increasingly dictate purchasing decisions. By 2025, total market revenue reached approximately $150 million, reflecting a sustained upward trajectory from $115 million in 2020. The sector is projected to grow at a compound annual rate of 5.1 percent through 2032, when revenue is expected to approach $210 million. This growth profile signals more than incremental demand; it points to a structural shift in how livestock producers, aquaculture operators, and feed formulators view yeast-based inputs as functional nutrition tools rather than routine additives.
That said, the expansion is uneven, and the landscape carries notable friction. Market concentration remains pronounced, with the top three players accounting for roughly 65 percent of global revenue and the top five capturing over 82 percent. Such concentration reflects the capital intensity of modern fermentation infrastructure, the importance of technical service and veterinarian-level support, and the increasingly regionalized nature of regulatory requirements. For decision-makers, the implication is clear: scale alone no longer guarantees advantage. Differentiation, formulation expertise, and the ability to navigate shifting trade and compliance frameworks are becoming the decisive factors.
PW Consulting
Market Evolution and Structural Pressures
The feed yeast segment has matured along several axes simultaneously. Demand is being reshaped by tighter antibiotic restrictions, heightened scrutiny of gut health performance, and the broader movement toward preventive nutrition in monogastric and ruminant production. At the same time, the product portfolio has diversified beyond traditional live yeast into derivatives and spent yeast streams, each appealing to different technical and economic priorities. This evolution is not merely a story of more SKUs; it reflects a marketplace in which buyers are increasingly willing to trade a modest premium for measurable benefits in digestibility, pathogen binding, or stability during feed pelleting and storage.
Within this environment, a few structural pressures stand out as defining challenges for the next cycle. First, raw material economics create persistent volatility. The fermentation feedstock base that underpins Saccharomyces cerevisiae production remains sensitive to grain and energy inputs, and the average annual price for the core yeast input still ranges between $800 and $1,200 per metric ton as of 2025. This cost structure pressures margins and limits the ability of smaller players to compete on volume without sacrificing consistency or lead times. Second, trade policy is becoming a more material driver of regional pricing and sourcing decisions. In February 2026, a U.S. executive order introduced a 6.4 percent tariff on inactive yeasts under a specific tariff classification, excluding dried brewers’ yeast. While the measure does not apply uniformly across all feed yeast categories, it underscores how rapidly tariff exposure can alter the economics of cross-border supply and encourages buyers to reconsider sourcing portfolios. Third, regional production leadership is shifting the center of gravity in the market. China’s annual output now exceeds 200,000 tonnes and is primarily directed toward Asian and European markets, reinforcing a supply chain dynamic in which volume availability and export logistics play an outsized role in regional pricing behavior.
Core Drivers Reshaping the Market
Several interlocking forces are driving the current trajectory of the feed yeast market. Understanding these drivers is essential for evaluating where growth will materialize and which capabilities will translate into durable advantage.
Technological and Strain-Level Innovation
Innovation in this market is increasingly centered on strain selection, propagation efficiency, and functional reliability under real-world feeding conditions. The competitive edge is shifting from generic yeast inputs toward formulations designed for specific gastrointestinal targets, such as rumen stability, pathogen binding, or resilience during thermal processing. For producers, this means that manufacturing scale must be paired with application science: a large fermentation capacity is valuable, but the ability to document performance in target species and to provide technical guidance on inclusion rates and integration with other additives is what converts production capability into recurring demand. The industry context reinforces the point. Major producers operate fermentation infrastructure with annual capacity above 100,000 tonnes, yet the most differentiated offerings are increasingly defined by their functional claims and the evidence supporting them.
Regulatory and Compliance Environment
Regulatory dynamics are now a strategic variable rather than a background condition. Feed additives face varying approval pathways, renewal cycles, and labeling expectations across major markets. In Europe, for example, Alltech’s Yea-Sacc® yeast culture continues to be authorized for use in cattle feed under EFSA oversight, with renewals ongoing through 2025. Such continuity matters because it shapes buyer confidence in long-cycle procurement, especially for ruminant applications where health claims and compliance documentation carry significant weight. At the same time, the U.S. tariff action on certain inactive yeast categories illustrates the broader point that trade policy can alter the cost base of specific product types and incentivize formulation or sourcing shifts. Companies that actively monitor these regulatory and tariff signals, and that design portfolios with flexibility in mind, are better positioned to absorb shocks and preserve margin.
Yeast Market
Demand-Side Behavior and Animal Nutrition Priorities
The demand landscape is being reshaped by a combination of animal production economics and an evolving nutrition philosophy. Livestock operators are placing greater emphasis on gut health, feed conversion efficiency, and resilience to stress, especially in environments where preventive health strategies are replacing reactive treatments. Yeast-based inputs are increasingly evaluated through that lens: their value proposition is tied not only to nutrient contribution but also to functionality such as stabilization of the gastrointestinal environment, modulation of microbial balance, or binding of undesirable compounds. As a result, procurement decisions are becoming more evidence-driven, and buyers are more likely to seek technical support, trial data, and integration guidance alongside product specifications. This shift favors suppliers that can act as solution partners rather than simple vendors.
Supply Chain and Cost Structure Dynamics
Feed yeast production remains a scale-sensitive business. Fermentation, downstream processing, drying, and logistics all carry capital and operating requirements that reward continuity and keep smaller, underfunded entrants at a disadvantage. At the same time, the rise of integrated and cross-industry ownership is altering the supply base. A notable example is the acquisition of Leiber GmbH by Asahi Group Foods in March 2025, which consolidated brewers’ yeast production for both animal nutrition and food ingredient applications. Transactions of this type are not merely financial; they change operational priorities, improve access to certain raw material streams, and can create new avenues for cross-segment demand. For the feed yeast market, such moves hint at a broader trend in which ingredient producers seek to secure feedstock consistency, expand application portfolios, and reduce exposure to single-market volatility.
Competitive Landscape and Emerging Positioning
The competitive structure of the feed yeast market is dominated by a mix of global animal nutrition specialists, large ingredient companies, and regional producers with strong fermentation capabilities and technical service networks. The top players are not interchangeable; their strategic positioning reflects differences in geography, portfolio depth, application focus, and ownership structure. What unites the stronger performers is a tendency to build advantage around functional reliability and end-user support rather than price alone.
Among the firms shaping the current landscape, several patterns stand out. Angel Yeast has built a broad feed yeast portfolio spanning live yeast, inactive yeast, yeast extracts, and mycotoxin binders, and its scale-oriented production model is reinforced by participation in major trade forums such as SPACE 2025, where it showcased its full range of feed yeast solutions. This combination of volume capability and market-facing visibility helps the company maintain relevance across multiple buyer segments. Alltech continues to emphasize a more focused, science-backed approach through its Yea-Sacc® yeast culture for rumen health, leveraging regulatory continuity in Europe to support confidence in cattle feed applications. Lallemand and Lesaffre contribute from positions grounded in yeast strain expertise and broader animal health portfolios, often competing on the strength of application data and integrated nutrition messaging. Leiber’s position has evolved further following its acquisition, aligning brewers’ yeast capabilities with a larger group’s ingredient strategy and potentially expanding cross-market leverage. ADM, Novus, AB Agri, Chr. Hansen, Nutreco, and DSM-Firmenich each bring their own angles, whether through animal nutrition divisions, yeast cell wall components, or broader feed additive portfolios that incorporate yeast-derived inputs as part of a wider value proposition.
The market is not simply consolidating; it is also differentiating. Some players are moving toward integrated, multi-functional product systems, while others maintain a sharper focus on specific species or functional claims. The trend suggests a bifurcation in which scale and operational reliability protect share in commoditized segments, while application-specific formulation, documentation, and technical service drive growth in more demanding use cases. New entry is likely to remain difficult without access to fermentation capacity, regulatory fluency, and a credible technical narrative. At the same time, acquisition activity and cross-industry ownership may increase, especially where ingredient streams, regional distribution, or application expertise can be combined to create a stronger commercial position.
Worldwide Nutritional Yeast Market
Forward Outlook: Three Trends to Watch
Looking ahead to the 2026–2032 period, three developments are likely to define the commercial trajectory of the feed yeast market.
The first is a gradual shift from generic supplementation toward function-targeted formulations. As buyers increasingly evaluate yeast inputs for specific outcomes—such as rumen performance, gut stability, or resilience under stress—the market will reward products with clearer application narratives and stronger supporting evidence. Companies that invest in species-specific documentation, dosing guidance, and integration with other feed additives are more likely to secure repeat business and price resilience. The commercial opportunity here lies not just in product development but in the ability to translate technical claims into credible, practical recommendations for feed formulators and producers.
The second trend is regional recalibration of sourcing and pricing. Trade policy volatility, including tariff actions on certain inactive yeast categories, combined with concentrated production in key exporting countries, will encourage buyers to diversify supply sources and consider lead-time stability alongside unit cost. Suppliers with reliable export logistics, flexible packaging and specification options, and the ability to serve multiple regions will gain an edge. For manufacturers, regional demand growth will likely remain uneven, with some markets expanding faster as protein production intensifies and as nutrition programs become more preventive in design.
The third trend is continued portfolio and ownership consolidation, particularly where it enhances feedstock access, broadens application coverage, or strengthens technical service. Acquisitions that link yeast production with broader ingredient or food-grade operations can improve supply security and create cross-selling opportunities. At the same time, integration carries execution risk: differences in operating culture, quality systems, and customer expectations can complicate the anticipated benefits. The market will therefore reward operators that can combine scale with disciplined product stewardship and consistent technical support.
These trends carry both upside and uncertainty. Demand for functional nutrition is likely to remain supportive, but the pace of adoption will depend on economic conditions in animal production, the stringency of regulatory approvals, and the ability of suppliers to demonstrate consistent value. Cost pressures from feedstock inputs and the potential for additional trade measures also remain variables that can compress margins or shift competitive dynamics faster than expected. The companies best positioned to navigate this environment will be those that treat regulatory monitoring, supply resilience, and application documentation as core capabilities rather than peripheral concerns.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align fermentation scale with application credibility. Capacity provides optionality, but differentiation comes from strain performance, stability data, and the ability to guide customers through integration decisions. Building a portfolio that balances core volume products with more specialized, function-oriented offerings can help protect share while opening paths to higher-value engagements. Equally important is the discipline to track regulatory and tariff developments closely, because even narrow policy changes can reshape the economics of specific product types and influence sourcing preferences.
For investors, the market’s concentration pattern warrants attention. The dominance of a few large players suggests that scale, distribution, and technical service networks create meaningful barriers, but the presence of targeted acquisitions and cross-industry ownership also signals that value may be created through strategic combination rather than organic expansion alone. Due diligence should focus on the defensibility of functional claims, the stability of feedstock access, the exposure of each portfolio to trade and regulatory shifts, and the quality of customer support. In this market, durable growth is increasingly tied to reputation for reliability and efficacy, not simply to volume.
For procurement teams and feed formulators, the practical imperative is to evaluate yeast inputs as part of a broader nutrition strategy rather than as interchangeable commodities. Inclusion decisions should weigh functional performance, supply continuity, documentation quality, and the supplier’s ability to support integration with existing formulations. Diversifying sources where feasible can reduce exposure to regional disruptions and tariff fluctuations, while maintaining dialogue with suppliers that can provide species-specific guidance and consistent product quality. In an environment where pricing is influenced by both input costs and trade policy, proactive sourcing and evidence-based selection are likely to yield better outcomes than price-only comparisons.
The feed yeast market is moving toward a more demanding, more differentiated, and more regionally sensitive phase of its development. That shift creates opportunity for operators and buyers who treat functionality, compliance, and supply resilience as strategic assets. For decision-makers seeking a deeper view of segment trajectories, regional nuances, competitive positioning, and scenario-based implications, the full research report provides a more granular breakdown and tailored guidance to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Feed Yeast Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


