



High-intensity Focused Ultrasound Market: Why 7.25% CAGR and Oncology Demand Redefine Growth
By PW Consulting, 2026-09-21
Navigating the High-Intensity Focused Ultrasound System Market: Strategic Trends and Commercial Opportunities
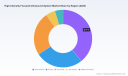
The global High-intensity Focused Ultrasound System Market has matured into a structurally sound growth sector, with total industry revenue surpassing $215 million in 2025 and projected Compound Annual Growth Rate of 7.25 percent through 2032. This trajectory reflects a transition from niche therapeutic adoption to broader clinical integration across oncology, urology, gynecology, and aesthetic procedures. Revenue projections indicate continued acceleration, with the market expected to approach $345 million by 2032, driven by expanding indication approvals, workflow optimization, and increasing acceptance of non-invasive tissue ablation. Rather than a uniform expansion, the growth pattern reveals concentrated value creation in specific therapeutic adjacencies and device configurations, requiring stakeholders to assess where technological differentiation, regulatory alignment, and reimbursement maturation intersect.
A defining characteristic of the current landscape is market concentration, with the top three companies accounting for roughly 68.5 percent of revenue and the top five capturing approximately 75.2 percent. This concentration reflects entrenched clinical reference points, long development cycles for focused ultrasound platforms, and the premium placed on regulatory clearances and reimbursement pathways. At the same time, the market remains dynamic enough to accommodate targeted innovations, particularly in compact form factors and specialized procedural applications. The interplay between established players defending core indications and newer entrants carving out differentiated niches creates a structured environment where strategic positioning matters more than generic market participation.
Navigating Structural Inflection Points
Three interconnected challenges currently shape operator and manufacturer decision-making. First, the reimbursement environment is actively recalibrating. Procedural coding frameworks are stabilizing in select geographies, with specific CPT code structures enabling outpatient coverage for prostate ablation and adjacent applications. However, reimbursement recognition is uneven, creating a patchwork where clinical adoption depends heavily on local payer policies, documentation requirements, and institutional procurement cycles. This fragmentation complicates volume scaling for manufacturers and introduces uncertainty in commercial forecasting.
Second, clinical validation and indication expansion remain uneven across therapeutic areas. While oncology and urology applications have accumulated substantial procedural evidence, other applications continue to move through evolving guideline development and health-economic evaluation. Stakeholders increasingly expect not only regulatory clearance but also comparative effectiveness data, workflow efficiency metrics, and total cost-of-care considerations. The burden of proof is rising, which favors organizations with robust clinical trial pipelines and disciplined real-world data generation.
Third, the operational complexity of focused ultrasound deployment introduces adoption friction in certain settings. Traditional platforms require specialized room configuration, multidisciplinary coordination, and operator training. Although portable and compact system designs are expanding accessibility, clinical centers still weigh capital outlay, maintenance requirements, procedure throughput, and integration with imaging guidance. These considerations are especially relevant as health systems prioritize capital efficiency and procedural standardization.
Key Drivers Shaping Market Trajectory
Several structural forces are reinforcing demand for focused ultrasound systems, but their impact differs across therapeutic categories and geographies. The most consequential drivers revolve around technological refinement, regulatory and reimbursement alignment, shifting clinical preferences, and evolving cost structures that influence purchasing behavior.
Engineering Precision and Workflow Efficiency
Technological progress is moving focused ultrasound from procedural feasibility toward operational efficiency. Imaging integration, robotic assistance, motion compensation, and lesion-targeting accuracy are steadily reducing procedural variability and expanding the range of treatable anatomies. Recent advancements in ultrasound imaging and workflow enhancements for robotic HIFU systems illustrate how manufacturers are prioritizing operator experience and procedural consistency, not just energy delivery. Similarly, platforms leveraging MR-guided focused ultrasound continue to support treatment of neurological and oncologic conditions by combining real-time visualization with precise ablation control. The strategic implication is clear: differentiation increasingly depends on end-to-end procedural value rather than hardware specifications alone.
High Intensity Focused Ultrasound (HIFU) Market
A second technological shift is the emergence of compact and portable configurations designed for broader clinical deployment. Smaller footprint systems lower some infrastructure barriers and support use in ambulatory settings, smaller hospitals, and outpatient clinics. This does not eliminate the need for imaging guidance or clinical expertise, but it expands the addressable deployment base and can improve utilization rates when matched to appropriate patient volumes. For manufacturers, the challenge is balancing portability with the performance standards required for complex ablation workflows.
High Intensity Focused Ultrasound (HIFU) Therapy Market
Regulatory Pathways and Reimbursement Maturation
Regulatory and reimbursement developments are becoming central market drivers, particularly where procedural coding and coverage policies reduce adoption friction. In the United States, long-standing CPT code structures have enabled outpatient reimbursement for specific HIFU prostate ablation procedures, creating a foundational reimbursement pathway. More recently, attention has turned to expanding procedural coverage for additional applications and clarifying documentation expectations for accurate billing. Health systems and providers are responding by investing in workflow documentation, coding alignment, and payer engagement, which strengthens the commercial environment for cleared devices.
At the same time, national reimbursement decisions influence adoption velocity in specific regions. Public health system coverage for certain focused ultrasound procedures can accelerate institutional purchasing decisions by reducing uncertainty around patient access and recurring revenue. Conversely, where reimbursement remains ambiguous, hospitals may delay procurement until clinical adoption curves and payer policies stabilize. The net effect is that reimbursement visibility is now as important as device performance in shaping commercial timelines.
Demand-Side Realignment Toward Non-Invasive Care
Clinical demand for less invasive procedural options continues to reshape treatment pathways across multiple specialties. Patients and providers are increasingly interested in modalities that can reduce recovery time, minimize procedural morbidity, and fit into outpatient care models. In oncology and urology, focal therapy approaches have gained attention for their potential to preserve function while targeting diseased tissue. In gynecology and breast health, focused ultrasound is being explored for targeted ablation of benign and malignant conditions where surgical alternatives carry meaningful trade-offs. In aesthetics and body contouring, demand is driven by consumer preference for non-surgical interventions and the broader shift toward minimally invasive enhancement procedures.
This demand-side evolution is not uniform, but it is persistent. Where clinical evidence supports safety and reproducible outcomes, focused ultrasound gains traction as an alternative or complement to existing interventions. Where evidence gaps remain, adoption proceeds more cautiously. That creates a strategic environment in which market leaders are those who can align device capabilities with the evidentiary standards required by specialty societies, institutional review processes, and payer evaluation.
Cost Structure Pressures and Procurement Behavior
Healthcare cost containment and capital allocation discipline are influencing how institutions evaluate focused ultrasound investments. Hospitals and ambulatory providers increasingly assess total cost of ownership, including service coverage, consumables, training, procedural throughput, and compatibility with existing imaging infrastructure. Supply chain considerations also matter, particularly for devices that rely on specialized components, software licensing, or integration with third-party imaging and navigation systems. As procurement teams compare capital-intensive platforms against workflow and reimbursement assumptions, manufacturers that can articulate value in operational terms gain an advantage.
At the same time, cost pressures can create openings for more compact, targeted, or application-specific solutions. Procurement decisions are not always driven by the most advanced platform; in many cases, the preferred solution is the one that matches institutional case mix, staff expertise, and reimbursement realities. This dynamic encourages manufacturers to develop tiered offerings and to tailor commercial models to specific clinical settings.
Competitive Landscape and Strategic Positioning
The competitive environment in focused ultrasound reflects a blend of specialized leaders, clinically anchored platforms, and targeted innovators. Several companies have established strong positions by concentrating on distinct procedural domains and investing in regulatory clearance, workflow refinement, and clinical evidence generation. Understanding how these firms differentiate reveals where value is being created and how the market is likely to evolve.
Differentiation Through Clinical Specialization
Several platform leaders have built competitive advantage by aligning their technology with specific clinical use cases and the operational requirements that accompany them. One robotic HIFU system for prostate cancer focal therapy has advanced by combining procedural precision with continuous imaging and workflow enhancements, supported by recent regulatory clearances for imaging and workflow improvements. The strategic value here is not only in the therapy itself, but in reducing procedural complexity and improving reproducibility for clinicians. Another developer has focused on non-invasive treatment of thyroid nodules, breast fibroadenomas, and varicose veins, emphasizing a diversified but focused portfolio across soft-tissue and vascular applications. This approach illustrates how specialized indication coverage can support commercial resilience when tied to appropriate reimbursement and referral patterns.
A different specialization path has emerged in MR-guided focused ultrasound, where platforms support neurological and oncologic applications by leveraging high-quality imaging for targeting and treatment control. These systems emphasize precision and safety in delicate indications, often appealing to specialized centers with the infrastructure and expertise required for complex procedures. Yet another platform has addressed prostate ablation, bone lesion treatment, and related oncologic applications through MR-HIFU integration, underscoring the importance of combining imaging modalities with ablation capability when targeting multidisciplinary oncology pathways.
Manufacturers outside the traditional Western medtech core have also played a significant role, particularly in non-invasive tumor ablation across liver, breast, and bone applications, supported by global distribution reach. These platforms demonstrate the international nature of focused ultrasound adoption and highlight how broad indication coverage and distribution networks can sustain growth even in competitive markets. Meanwhile, newer entrants have pursued highly targeted opportunities, including fluoroscopy-guided HIFU for chronic low back pain, reflecting the potential for focused ultrasound to expand into pain management when supported by appropriate regulatory clearance and procedural evidence.
PW Consulting
Strategic Moves and Recent Commercial Signals
Recent regulatory and reimbursement activity underscores how commercialization is being shaped at the procedural level. One company received FDA 510(k) clearance for ultrasound imaging and workflow enhancements to its robotic HIFU system for prostate cancer, reinforcing the strategic importance of software, navigation, and operator support in established therapeutic areas. Another company obtained De Novo clearance for a fluoroscopy-guided HIFU system aimed at chronic low back pain, signaling an expansion of focused ultrasound into pain intervention through nerve-targeted ablation. These events demonstrate how regulatory milestones can open new procedural categories while strengthening existing ones.
On the reimbursement and market access side, national coverage recognition in certain regions has improved procedural economics for prostate-focused HIFU, while ongoing payer policy updates continue to define which CPT codes apply to HIFU ablation procedures and how documentation should be structured. Provider-facing education around documentation and billing is increasingly part of commercialization, since procedural reimbursement depends not only on device availability but also on accurate coding and compliance. The launch of an international focused ultrasound society further reflects the sector's effort to standardize clinical practice, support adoption, and build a stronger professional foundation for the technology across indications.
Market Structure Evolution
The current concentration profile suggests that scale advantages, regulatory experience, and established clinical relationships will continue to matter. However, the market is unlikely to remain static. Several forces point toward selective consolidation and parallel differentiation. Larger or better-capitalized companies may pursue complementary technologies, indication expansion, or geographic expansion to strengthen installed base advantages. At the same time, smaller or more specialized companies can thrive by solving a narrow clinical problem exceptionally well, particularly in areas where workflow simplicity, portability, or unique guidance modalities provide a meaningful fit for a specific care setting.
This environment rewards strategic clarity. Companies that attempt to compete across every therapeutic area without a differentiated value proposition risk being outmatched by leaders with stronger procedural evidence, reimbursement alignment, or workflow integration. Conversely, organizations that define a focused commercial territory and build a defensible evidence and distribution strategy can capture meaningful share in specific segments, even within a concentrated overall market.
Future Trends and Commercial Implications
Looking ahead three to five years, the focused ultrasound market is likely to be defined by deeper therapeutic integration, broader procedural accessibility, and more structured market-access expectations. These trends create opportunity, but they also introduce execution requirements that will separate disciplined strategies from generic participation.
Deeper Integration into Multidisciplinary Care Pathways
One of the strongest forward-looking trends is the integration of focused ultrasound into broader care pathways rather than standalone procedures. In oncology and urology, this means closer alignment with imaging, navigation, biopsy, and follow-up workflows. In gynecology and breast health, it means coordination with specialty clinics and referral networks. In pain management and certain vascular applications, it means integration with interventional and rehabilitation services. When focused ultrasound becomes a recognized step within a care pathway, procurement decisions become less device-centric and more pathway-centric, which favors platforms that support clinical continuity, documentation, and cross-departmental adoption.
Commercially, this trend rewards companies that invest in multi-department usability, interoperable imaging integration, and clinical support services. It also reinforces the importance of real-world evidence, since pathway integration depends on demonstrated outcomes across heterogeneous patient populations and clinical settings.
Expanded Application Breadth with Targeted Indication Strategy
Application breadth is likely to continue expanding, but not indiscriminately. The clinical and commercial logic will favor targeted indication expansion where procedural feasibility, patient demand, and reimbursement alignment converge. Pain intervention, benign soft-tissue conditions, and specific oncology workflows are plausible areas of incremental growth, provided clinical evidence and regulatory clarity keep pace. The key strategic question for manufacturers is whether to extend existing platforms into adjacent indications or build dedicated solutions optimized for new procedural requirements. Both paths are viable, but each demands different investment profiles and clinical engagement strategies.
This trend creates opportunity for organizations that can identify indications with strong unmet need, manageable competitive overlap, and a realistic reimbursement trajectory. It also introduces risk for companies that overcommit to indication expansion before evidence and payer recognition are sufficiently mature.
More Institutional Procurement Discipline and Predictive Volume Planning
As reimbursement visibility improves in select areas, procurement behavior is likely to become more disciplined but also more predictable where coverage is clear. Health systems will increasingly evaluate focused ultrasound purchases based on case mix projections, reimbursement certainty, staff training requirements, and operational throughput. This suggests a shift from speculative adoption toward more evidence-based capital deployment. For manufacturers, the implication is that commercial success will depend on supporting customers with utilization modeling, workflow planning, and reimbursement documentation support, not simply offering device specifications.
The principal risk in this trend is that procurement discipline may slow adoption in settings where reimbursement remains uncertain or where the procedural case mix is insufficient to justify capital deployment. Strategic flexibility, including flexible financing, service models, and application-specific configurations, may become more important in bridging that gap.
Actionable Guidance for Decision-Makers
The current market dynamics suggest that strategic success depends less on broad exposure to focused ultrasound and more on aligning product, evidence, reimbursement, and commercial model with the most attractive procedural territories. The following considerations are relevant across different stakeholder roles.
For Manufacturers and Technology Developers
- Concentrate differentiation on end-to-end procedural value, including imaging integration, workflow efficiency, operator support, and documentation alignment, rather than emphasizing hardware features in isolation.
- Prioritize indication strategies where regulatory clearance, reimbursement recognition, and clinical demand reinforce one another, and avoid expansion that outpaces payer or guideline readiness.
- Build commercial support around utilization planning, clinical training, and reimbursement documentation, since these factors increasingly determine procurement timing and adoption velocity.
For Investors and Strategic Capital Allocators
- Assess commercial readiness by examining not only regulatory milestones but also reimbursement visibility, evidence-generation pipelines, and installed-base economics in priority indications.
- Look for companies with disciplined clinical and market-access strategies, especially where therapeutic specialization and workflow differentiation can support defensible positioning within a concentrated market.
- Monitor procedural reimbursement developments and clinical society activity closely, since these often provide earlier signals of adoption shifts than top-line revenue data alone.
For Procurement Leaders and Health System Decision-Makers
- Evaluate focused ultrasound investments based on total cost of ownership, case mix fit, staffing requirements, imaging compatibility, and expected reimbursement support rather than device capability alone.
- Align procurement timing with reimbursement clarity and workflow readiness, and require vendor support for documentation, coding alignment, and training to reduce adoption friction.
- Consider application-specific or compact configurations where patient volume and procedural mix justify them, while ensuring that performance standards remain appropriate for the intended clinical use.
The focused ultrasound market is advancing through a combination of technological maturation, procedural reimbursement development, and shifting clinical preferences. The commercial winners are likely to be those who translate these forces into focused strategies with clear indication priorities, credible evidence plans, and realistic models for institutional adoption. For decision-makers seeking detailed segmentation data, competitive benchmarking, and tailored guidance aligned to specific strategic objectives, deeper analysis can provide the granularity needed to convert these directional trends into operational choices.
For detailed analysis of this topic, please visit the official page: High-intensity Focused Ultrasound System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The DNA Sequencing Market: Strategic Trends and Commercial Opportunities for the Next Decade
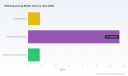
The global DNA sequencing market has entered a decisive phase of expansion, driven by converging advances in platform technology, regulatory momentum, and widening clinical adoption. From 2020 through 2025, the market grew from approximately $9.1 billion to $16.9 billion, reflecting a sustained upward trajectory that has extended into early forecast years. Projections point to continued acceleration through 2032, with the market anticipated to reach $44.6 billion and a compound annual growth rate of 14.9% across the forecast horizon. This growth is not merely incremental; it reflects a structural shift in how sequencing is positioned across research, clinical diagnostics, public health, and commercial genomics.
The current market base is anchored by next-generation sequencing, which commands the largest revenue share and underpins most high-throughput diagnostic and research workflows. Alongside this dominant modality, third-generation and single-molecule approaches are carving out specialized niches where read length, phasing, or real-time observation deliver distinct analytical advantages. The segment composition reveals a market that is simultaneously consolidating around platform standardization while preserving room for differentiated technologies that address specific biological or operational questions.
Beneath the headline growth figures, however, lie structural tensions that will shape competitive outcomes over the next several years. Three challenges stand out as particularly consequential. First, the industry faces mounting pressure to translate sequencing throughput into interpretable clinical action without inflating downstream bioinformatics costs. Second, supply chain and reagent economics remain sensitive to manufacturing scale, component availability, and the geographic concentration of platform suppliers. Third, the market is navigating a regulatory evolution that is becoming more prescriptive around validation, quality control, and data comparability, especially as sequencing moves deeper into diagnostic and therapeutic development pathways.
These dynamics matter because they determine who can convert technology leadership into durable commercial advantage. Companies that treat sequencing solely as an instrument business are increasingly exposed to commoditization risk, while those that integrate workflows, informatics, and evidence generation are building moats around recurring value.
Key Drivers Shaping the Market Trajectory
The expansion of sequencing adoption is being propelled by a set of reinforcing drivers rather than a single breakthrough. Understanding their interplay is essential for assessing where value will accumulate.
Technology Innovation and Platform Differentiation
Platform innovation continues to reshape what sequencing can deliver in terms of speed, cost, and biological resolution. Short-read next-generation systems remain the workhorse for high-volume applications, but long-read and single-molecule technologies are expanding the envelope for structural variant detection, haplotype resolution, and complex genome assembly. At the same time, a new wave of benchtop and high-throughput systems is targeting broader accessibility, with an emphasis on lowering total cost of ownership and simplifying operational complexity.
Recent product activity illustrates this direction. Illumina introduced a distributed whole-genome sequencing solution for highly sensitive minimal residual disease research, initially available to select partners with a broader commercial launch planned for 2027. This move signals a strategic push toward ultra-sensitive detection workflows that could bridge research and clinical oncology applications. In a different segment, Clear Labs launched an automated next-generation sequencing solution for Mycobacterium species identification and tuberculosis drug resistance mutation detection, underscoring how automation and targeted assay design are converging to reduce hands-on time and standardize results in pathogen testing.
The practical implication is that technology leadership is increasingly defined by workflow completeness rather than raw sequencing output alone. Systems that reduce sample preparation variability, streamline library construction, or pair sequencing with purpose-built analytics are gaining traction because they lower the barrier to reliable deployment across laboratories with varying levels of expertise.
Policy and Regulatory Environment
Regulatory and standardization activity is moving from passive oversight toward more active enablement, particularly where sequencing can improve safety assessment, outbreak response, and clinical trial initiation. In April 2026, the FDA distributed for comment a draft guidance on next-generation sequencing-based methods for safety assessment of genome editing in human gene therapy products, an indication that regulators are building frameworks to support more efficient evaluation of advanced therapies.
In parallel, public health mandates are creating structured demand for whole-genome sequencing in surveillance and outbreak investigation. The European Commission adopted regulation requiring member states to perform whole-genome sequencing on selected foodborne pathogen isolates for outbreak investigations, a policy shift that institutionalizes sequencing as a standard tool in epidemiological response. This kind of regulatory anchoring matters because it converts occasional demand into recurring, protocol-driven usage.
Standardization efforts are also advancing on the technical side. Development of ISO quality control metrics for DNA sequencing informatics has been progressing through enquiry phases, reflecting an industry-wide recognition that data quality, metadata consistency, and comparability across platforms will become increasingly important as sequencing data supports cross-institutional decision-making. Collectively, these regulatory and standards movements reduce ambiguity for adopters, but they also raise the bar for vendors that must demonstrate validation readiness and documentation rigor.
Demand-Side Shifts in Clinical and Commercial Settings
Demand is broadening beyond traditional research settings as sequencing becomes embedded in clinical workflows, precision medicine programs, and applied genomics. Oncology remains a central application arena, where sequencing supports biomarker discovery, therapy selection, residual disease monitoring, and translational research. At the same time, reproductive health, clinical investigation, and specialized typing applications continue to expand as laboratories seek higher-resolution insights from smaller sample volumes or more complex biological questions.
DNA Microarray Market
A notable demand-side shift is the growing expectation that sequencing output should be paired with interpretable, clinically relevant reporting. Laboratories and health systems are less interested in raw sequence generation in isolation; they want integrated solutions that connect assay performance with actionable interpretation, whether for oncology panels, infectious disease characterization, or transplant-related typing. This expectation is nudging the market toward solution-oriented commercialization, where value is created not just by selling instruments and reagents but by reducing the operational and cognitive burden on end users.
Sanger Sequencing Service Market
Cost Structure and Supply Chain Realities
Cost dynamics remain a fundamental driver of adoption, but the conversation has evolved beyond instrument price alone. Total cost of ownership now encompasses reagent economics, throughput utilization, labor intensity, failure rates, and informatics overhead. Manufacturers that can improve reagent efficiency, increase instrument uptime, or reduce consumable waste are able to offer compelling economics even when headline pricing appears similar across competitors.
Supply chain resilience has also become a strategic concern. The concentration of platform manufacturing and key consumable production creates dependencies that can affect availability, lead times, and regional pricing. As a result, some customers are evaluating multi-vendor strategies or prioritizing suppliers with stronger regional support and service networks. For vendors, this environment rewards operational reliability and transparent supply planning as much as it rewards technical specifications.
Competitive Landscape and Leading Strategies
The competitive structure of the DNA sequencing market is characterized by high concentration at the top, alongside active experimentation by emerging and specialized players. Roughly two-thirds of market revenue is associated with a small group of leading firms, and the top five together account for a substantial majority of revenue. This concentration does not imply stagnation; rather, it reflects the scale advantages involved in platform development, global service support, consumables ecosystems, and regulatory readiness.
Illumina remains a central force in next-generation sequencing, with a broad installed base and a portfolio spanning instruments, reagents, and applications-oriented research tools. Its recent emphasis on distributed whole-genome sequencing for minimal residual disease research suggests a strategy aimed at deepening relevance in high-value oncology workflows where sensitivity and reproducibility are paramount. Thermo Fisher Scientific offers a complementary breadth, combining next-generation sequencing, Sanger sequencing, and genomics instruments with a large consumables footprint. Its advantage lies in portfolio integration across multiple laboratory needs, which can simplify procurement and cross-platform support for institutions seeking operational consistency.
Oxford Nanopore Technologies and Pacific Biosciences represent long-read and single-molecule approaches with distinct technological identities. Oxford Nanopore’s nanopore-based platforms emphasize portable and real-time sequencing capabilities, which can be advantageous for field deployment, rapid pathogen characterization, and applications where flexibility matters. Pacific Biosciences focuses on high-fidelity long-read systems and single-molecule real-time technology, positioning around accuracy and read length for complex genomic analysis. Both companies illustrate how specialized technology narratives can sustain differentiated market positions even within a market dominated by short-read scale.
A second tier of challengers and specialists is expanding the boundaries of cost, automation, and application focus. Element Biosciences has introduced a benchtop next-generation sequencing platform designed for high-throughput, cost-effective sequencing, targeting laboratories that want strong performance without the footprint or economics of larger systems. Ultima Genomics has pursued high-throughput, cost-efficient sequencing for population-scale genomics, an approach that speaks directly to large cohort studies and initiatives where per-sample economics are critical. BGI Group, through its MGI technology offerings, continues to compete with whole-genome and targeted sequencing platforms, leveraging manufacturing scale and regional presence.
QIAGEN remains relevant through library preparation, sequencing panels, and hybrid capture technologies, areas where upstream sample and target enrichment can be as important as the sequencing run itself. Clear Labs is advancing fully automated next-generation sequencing for pathogen and oncology applications, with product activity such as its automated mycobacteria and tuberculosis resistance solution highlighting a focus on hands-off, clinically oriented workflows. Tempus AI illustrates a different model altogether, integrating whole-genome sequencing assays with an artificial intelligence-driven precision medicine platform, effectively linking sequencing data to decision support and clinical interpretation.
This landscape is evolving along several axes. One is consolidation around integrated solutions, where instrument, consumable, software, and support offerings are bundled to reduce fragmentation for customers. Another is fragmentation at the application layer, where specialists compete on speed, automation, or niche assay performance rather than on general-purpose throughput alone. A third is the continued entry of new platforms that challenge incumbent economics, particularly in benchtop and high-throughput cost-per-sample segments. The net effect is a market where incumbents must defend installed bases and recurring consumables revenue while newcomers and specialists attempt to open whitespace through operational simplicity, price advantage, or application specificity.
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to define the market's direction and shape commercial opportunities.
One major trend is the continued movement from sequencing as a data generation step toward sequencing as an integrated diagnostic and decision-support component. This will favor organizations that can align assay design, automation, bioinformatics, and reporting into cohesive workflows. The commercial opportunity lies in reducing turnaround time and interpretation burden, particularly in oncology and infectious disease settings where timely results influence clinical decisions. The risk is that integration expectations rise faster than standardization, creating interoperability challenges and increasing the cost of maintaining multiple workflow ecosystems.
A second trend is the growing institutionalization of whole-genome sequencing in public health, food safety, and surveillance contexts. Regulatory and policy anchors can create durable demand, but they also require consistent quality, traceability, and comparability across laboratories. Companies positioned to support standardized surveillance workflows, including validated panels, reference materials, and data reporting tools, may benefit from this shift. The uncertainty lies in how uniformly these mandates are implemented across regions and how quickly resource-constrained laboratories can adopt the required infrastructure.
A third trend is the intensifying competition around cost-efficient scale. As more platforms pursue lower per-sample economics, pressure will increase on incumbents to defend margins through workflow efficiency, service models, and differentiated applications rather than price alone. This environment can accelerate adoption among cost-sensitive users, but it also raises the stakes for suppliers that depend heavily on reagent and consumable revenue. The strategic opportunity is to pair economic competitiveness with value-added services such as bioinformatics, assay optimization, and laboratory workflow consulting, which can improve stickiness and reduce direct price sensitivity.
Across these trends, a shared risk is the possibility that technological promise outpaces evidentiary and regulatory readiness in certain clinical settings. Where claims outstrip validated utility, adoption may slow, reimbursement pathways may remain uncertain, and customers may become more cautious about platform commitments. Another risk is geopolitical and supply chain volatility, which can affect reagent availability, service continuity, and regional pricing stability. Companies planning long-cycle investments should therefore model not only technology adoption but also resilience and support capacity.
Strategic Actions for Decision-Makers
The current market environment rewards clarity of positioning and discipline in execution. Different stakeholder groups will need to prioritize differently, but several actions are broadly relevant.
For sequencing platform and consumable manufacturers, the priority is to strengthen total workflow value rather than competing solely on instrument specifications. That means investing in assay compatibility, library preparation efficiency, automation, and bioinformatics support that reduce customer friction. It also means preparing for a regulatory environment that increasingly expects validation documentation and quality control rigor. Companies that can demonstrate reliable performance across diverse laboratory settings, while maintaining clear service and supply commitments, will be better positioned to defend recurring revenue and expand into higher-value applications.
For investors, the most important question is where durable demand is being created versus where adoption depends primarily on technology enthusiasm. Workflow-integrated solutions, surveillance-driven public health demand, and oncology applications with clear clinical interpretation pathways offer stronger signals of sustained use than instrument launches alone. At the same time, concentration in the market means that competitive disruption can come from cost-efficient challengers, application specialists, or software-centric models that change how sequencing data is converted into decisions. Due diligence should therefore assess not only platform performance but also consumables economics, service networks, regulatory readiness, and the defensibility of any proprietary informatics or assay IP.
For procurement and laboratory decision-makers, the focus should be on total cost of ownership and operational fit. Instruments with attractive sticker prices can become expensive if they underutilize capacity, require specialized labor, or create informatics bottlenecks. Evaluating vendors on reliability, support responsiveness, assay breadth, and compatibility with existing workflows can yield better long-term outcomes than selecting solely on benchmark performance. It is also prudent to consider multi-platform strategies where applicable, especially in settings where application diversity or supply resilience matters more than single-vendor simplicity.
Across all of these roles, the pace of change in sequencing technology, regulation, and application design makes timely, detailed market intelligence valuable. Segment-level demand patterns, regional adoption differences, platform economics, and the regulatory calendar all influence where opportunities are emerging and where assumptions may be outdated. For organizations seeking deeper segmentation data, competitive benchmarking, and tailored scenario planning, a more detailed study of the DNA sequencing market can provide the granularity needed to support investment, product, and procurement decisions with greater confidence.
PW Consulting Health Care Research Center
For detailed analysis of this topic, please visit the official page: DNA Sequencing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Flexible Heating Element Market: Why 8.37% CAGR and EV Demand Reshape Strategy
By PW Consulting, 2026-09-21
Navigating the Flexible Heating Element Market: Strategic Trends and Commercial Opportunities
The flexible heating element market has evolved from a niche thermal management solution into a critical enabler of performance across high-growth industries. This analysis examines the market's trajectory, the structural forces reshaping competitive dynamics, and the strategic imperatives for manufacturers, investors, and procurement leaders navigating the next cycle of growth.
Market Overview and Current Challenges
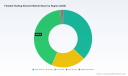
The global market for flexible heating elements has demonstrated consistent expansion over the past half-decade, driven by cross-sector demand for precision thermal control, compact form factors, and reliable performance in demanding environments. From 2020 through 2025, the market grew from approximately $0.95 billion to $1.42 billion, reflecting an accelerating adoption curve as end-use industries integrated flexible heating into increasingly complex product architectures. Forecasts indicate the market will continue its upward trajectory through 2032, surpassing the $2.4 billion mark by the end of the forecast window and maintaining a compound annual growth rate of 8.37 percent. This growth profile places flexible heating alongside other high-value thermal management sub-segments, but the underlying demand drivers are distinct in their technical specificity and regulatory sensitivity.
PW Consulting Automotive & Machinery Research Center
Several structural challenges are reshaping how companies approach product development, pricing, and market entry. First, the divergence in material performance requirements across application verticals has pressured manufacturers to specialize rather than pursue broad commoditization strategies. Flexible heaters deployed in semiconductor processing, medical instrumentation, or aerospace assemblies demand different thermal profiles, reliability thresholds, and certification pathways. Companies that attempt to serve all segments with generic portfolios are encountering margin compression and longer qualification cycles. Second, the cost structure of advanced flexible heating technologies remains elevated relative to traditional alternatives. Precision etching, lamination, and custom trace design for polyimide-based solutions introduce manufacturing complexity that raises unit costs significantly compared to rigid heating alternatives. Carbon-based and specialty conductive traces further compound material expenses, creating a cost differential that buyers must weigh against performance gains. Third, regulatory and certification requirements are tightening across target markets. Energy efficiency expectations, safety standards, and application-specific qualification frameworks are becoming non-negotiable market access conditions rather than optional differentiators. These dynamics are compressing the timeline from concept to volume production and rewarding organizations with established compliance capabilities and engineering partner ecosystems.
Worldwide Contact Heating Elements Market
Key Drivers Reshaping the Market
Technological Innovation and Material Performance
Material science advances are the most persistent driver of market evolution. Polyimide-based flexible heaters continue to gain traction in applications requiring high watt density, thermal stability, and compatibility with precision electronic assemblies. Recent industry demonstrations have highlighted pure-polyimide heater architectures achieving UL 94 V0 certification and progressing through ESA qualification pathways, signaling that high-reliability flexible heating is becoming viable for space-grade and mission-critical deployments. At the same time, silicone rubber solutions remain dominant where cost sensitivity, form-factor flexibility, and moderate thermal requirements intersect. The parallel development of both material tracks reflects a market that is simultaneously pushing performance boundaries and optimizing for volume economics. Innovations in integrated sensors, embedded thermocouples, and custom circuit design are also reducing the friction between heating element selection and system-level thermal management. Manufacturers offering combined heating and sensing solutions are shortening integration cycles for OEMs that previously managed these components separately.
Policy and Regulatory Environment
Regulatory expectations are acting as both a constraint and a catalyst. Stringent energy efficiency standards and safety requirements are pushing manufacturers toward designs that minimize thermal waste, improve temperature uniformity, and reduce failure modes. In medical and space applications, recognized construction standards and qualification frameworks have become baseline requirements rather than premium features. The emergence of clear certification milestones, such as UL recognition and ESCC qualification for specialized flexible heaters, is narrowing the field for suppliers serving regulated verticals. This regulatory intensification favors established players with documented qualification histories and penalizes new entrants lacking the testing infrastructure or compliance documentation to compete in high-stakes segments. Simultaneously, it creates an opportunity for suppliers that can package compliance readiness as a service, reducing the burden on OEMs navigating complex approval processes.
Demand-Side Shifts in End-Use Industries
Demand patterns are being reshaped by architectural changes in key end-use sectors. In automotive and transportation, the continued emphasis on battery thermal management and cabin comfort solutions is increasing the relevance of flexible heaters that can be integrated into tight mechanical envelopes without compromising durability. Electronics and semiconductor applications are driving demand for localized, precisely controlled heating in processing equipment, test fixtures, and advanced packaging workflows. Medical device manufacturers are seeking high-wattage flexible heating options that enable faster thermal response in compact instrumentation, while aerospace and defense programs are prioritizing lightweight, high-reliability heating solutions with documented qualification records. These demand shifts are not uniform; they create pockets of accelerated growth where performance requirements align with the technical advantages of flexible heating. Companies able to map application-specific requirements to material and design capabilities are seeing stronger conversion rates and shorter sales cycles in targeted verticals.
Supply Chain and Cost Structure Dynamics
Cost structures in flexible heating are being recalibrated by a combination of material pricing, processing complexity, and customer demand for lower minimum order quantities. Specialty conductive traces and carbon-based materials continue to elevate raw material costs relative to silicone rubber alternatives, while precision etching and lamination steps add manufacturing overhead for polyimide-based products. At the same time, new market entrants are introducing low-MOQ offerings and free design support to reduce barriers for prototyping and low-volume production. This shift is particularly relevant for electronics, EV, and medical applications where design iteration cycles are short and upfront cost risk must be minimized. The tension between premium material performance and accessible entry pricing is creating a more stratified market, with volume-driven cost optimization on one end and high-reliability, specification-driven solutions on the other. Suppliers that can navigate this spectrum without sacrificing quality or lead time are positioning themselves to capture demand across multiple tiers of the market.
Competitive Landscape and Leading Strategies
The competitive field in flexible heating is defined by a mix of established manufacturers with deep application expertise and newer entrants lowering barriers to adoption through accessible pricing and design support. Market concentration remains moderate, with a core group of leading suppliers accounting for a significant share of high-value contracts, while a broader tail of regional and specialty providers competes on customization, lead time, and niche qualification capabilities.
Electric Heating Elements (Electric Heater) Market
Several strategic positioning patterns are emerging among the most competitive players. One clear approach is engineering partnership and custom material specialization. Suppliers that emphasize custom polymer thick film, silicone rubber, polyimide, and etched foil technologies are building advantage through the ability to adapt heater geometry, watt density, and sensor integration to specific customer architectures. This model thrives in applications where standard off-the-shelf solutions cannot meet thermal or mechanical constraints, such as mission-critical medical assemblies or high-reliability aerospace systems. A second approach centers on accessibility and speed for prototyping and low-volume production. By removing minimum order quantity requirements, offering free circuit design assistance, and accelerating delivery timelines, some providers are capturing early-stage design wins in electronics, EV, and medical applications. This strategy is particularly effective in environments where engineers are evaluating multiple thermal options before committing to volume tooling. A third approach is qualification leadership in regulated verticals. Companies advancing ESA qualification, ESCC compliance, and UL certification for specialized polyimide heaters are differentiating through documented reliability and the ability to support space and high-performance applications with reduced qualification burden for the buyer.
Recent company-level developments illustrate these dynamics in action. In late 2025, one Italian manufacturer presented validation data on a pure-polyimide flexible heater architecture, including cross-sectional analysis, thermal aging results, cycled life testing, UL 94 V0 certification, and ongoing ESA qualification. Around the same period, the same group showcased flexible heating solutions at a major space commerce event and later presented thermal management systems incorporating flexible heater options at a mobility conference. These activities signal a deliberate push into high-reliability and transportation-adjacent applications where qualification and system-level integration are decisive. In early 2025, a provider of highly customized flexible heaters introduced a high-wattage polyimide heater aimed at medical applications, supporting elevated watt density and higher operating temperatures. Meanwhile, a China-based manufacturer expanded its offerings with a full flexible heater product line spanning polyimide and silicone rubber, removing MOQ constraints, including free design support, and emphasizing rapid delivery for prototyping. Together, these moves highlight a market where leaders are simultaneously advancing performance credentials and broadening access points for design-phase customers.
The competitive landscape is evolving through a combination of specialization and selective convergence. On one side, demand for application-specific qualification and advanced material configurations is encouraging divergence, as manufacturers deepen expertise in targeted verticals rather than competing on generic specifications. On the other side, the entry of lower-friction prototyping and low-MOQ providers is broadening the supplier base at the design stage, increasing pressure on incumbents to clarify their value proposition beyond legacy relationships. The likely outcome is a more layered competitive structure: premium, qualification-heavy suppliers anchoring high-reliability and regulated segments, agile custom manufacturers serving engineering-intensive applications, and accessible providers capturing early design exploration and shorter-run production. Integration activity may increase where scale advantages in materials, testing, and certification can be leveraged, but the market's technical diversity suggests that pure breadth plays will face persistent margin and service-level challenges.
Future Trends and Commercial Implications
Trend 1: Qualification-as-a-Service Becomes a Competitive Differentiator
As regulatory expectations and application-specific qualification requirements become more entrenched, suppliers that can package compliance readiness, testing documentation, and recognized construction standards as part of their offering will gain an advantage in medical, aerospace, and high-reliability industrial applications. Over the next three to five years, this trend will likely intensify as OEMs seek to reduce internal qualification burden and compress time-to-market. The commercial opportunity lies in positioning flexible heating not just as a component but as a qualified subsystem that lowers integration risk. The associated risk is that certification pathways remain fragmented across regions and application categories, creating uneven market access and raising the cost of maintaining multi-jurisdiction compliance.
Trend 2: High-Watt Density and Precision Thermal Control Expand into New Applications
Advances in polyimide and specialty heater architectures are enabling higher watt density and tighter temperature control in compact form factors. This is opening doors in medical instrumentation, advanced electronics processing, and selective automotive thermal management scenarios where rapid thermal response and spatial constraints are critical. The commercial implication is a gradual shift in addressable use cases beyond traditional heating roles, creating incremental growth in segments that previously relied on less flexible thermal solutions. The risk is that performance claims must be substantiated through consistent manufacturing quality and validated life testing, particularly in regulated applications where failure modes carry high consequences.
Trend 3: Lower- friction Entry Models Accelerate Design-Phase Competition
The availability of low-MOQ offerings, free design support, and rapid prototyping pathways is changing how flexible heating solutions are evaluated and selected. Engineering teams are increasingly able to test multiple material and geometry options early in the design cycle, which raises the importance of first-turn responsiveness and design collaboration. For suppliers, this trend expands the top of the funnel but also increases the volume of speculative design activity that must be managed efficiently. The commercial opportunity is to convert early-phase engagement into volume production through reliable execution, consistent quality, and clear scaling pathways. The risk is margin erosion if prototyping convenience is not paired with a credible plan for transitioning customers to higher-volume, cost-optimized production models.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the most effective path is to align product portfolios with application-specific qualification needs and material performance requirements rather than competing solely on breadth. Companies should prioritize documented certification status where regulated verticals are a strategic target, invest in engineering collaboration that reduces integration risk for customers, and maintain a credible low-volume entry point without compromising the economics of scale production. Differentiation will increasingly come from the ability to manage the full arc from prototype to qualified volume production, not from component specification alone.
For investors, the market presents selective opportunities where technical barriers, qualification depth, and application concentration combine to support durable positioning. Capital allocation should favor companies with clear vertical focus, demonstrated compliance capabilities, and operating models that can absorb the cost complexity of advanced materials without relying on undifferentiated volume. Monitoring the pace of certification progression, the emergence of integrated heating-and-sensing offerings, and the extent to which accessible prototyping models convert into recurring production demand will be important indicators of which players are building sustainable advantage.
For procurement and engineering leaders, the priority is to treat flexible heating selection as a system-level decision rather than a component sourcing exercise. Evaluating suppliers on qualification documentation, design support responsiveness, and the ability to scale from prototype to production will reduce downstream integration risk. Where performance requirements justify it, premium material architectures and recognized certifications should be weighed against total lifecycle cost and reliability exposure rather than unit price in isolation. Early engagement with suppliers that can provide both design flexibility and compliant production pathways will shorten qualification timelines and improve launch certainty.
The flexible heating element market is moving toward a more segmented, qualification-aware, and design-integrated future. Companies that understand where performance, regulation, and cost dynamics intersect will be best positioned to capture the next phase of growth. For decision-makers seeking detailed segmentation data, competitive benchmarking, and customized scenario planning across regions and applications, the full research report provides the deeper dataset and structured analysis required to translate these trends into specific organizational actions.
For detailed analysis of this topic, please visit the official page: Flexible Heating Element Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Turbo Expander Market: How 5.5% CAGR and US$530M Scale Redefine 2026-2032 Strategy
By PW Consulting, 2026-09-21
Turbo Expander Market: Strategic Trends and Commercial Opportunities Through 2032
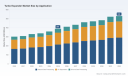
The global turbo expander market is entering a phase of disciplined growth, driven by the convergence of energy efficiency mandates, expanding cryogenic infrastructure, and the relentless push for industrial decarbonization. Estimated at roughly 390 million USD in 2025 and projected to reach approximately 530 million USD by 2032, the sector is on track for a compound annual growth rate of about 5.5 percent across the 2026 to 2032 horizon. This trajectory is not merely a reflection of capacity additions; it signals a structural shift in how industrial gas processing, liquefaction, and energy recovery systems are designed, procured, and operated. For executives and investors, the opportunity lies less in chasing headline volumes and more in understanding where capital is being directed, which technology archetypes are gaining share, and how regulatory and supply chain dynamics are reshaping competitive advantage.
Market Snapshot and Defining Challenges
The turbo expander market has sustained steady expansion over the past half-decade, with revenues climbing from around 302 million USD in 2020 to an estimated 390 million USD in 2025. The forward path points to continued upward momentum, supported by recurring demand in natural gas processing, air separation, and oil and gas processing applications, alongside growing deployment of radial, axial, and hybrid expander configurations across diverse industrial settings. Regional demand is broadly distributed, with meaningful activity concentrated in North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, each reflecting distinct project pipelines and regulatory pressures. Market concentration remains notable, with the top three players accounting for roughly 45 percent of revenue and the top five approaching nearly 70 percent, underscoring the importance of scale, technology credibility, and long-cycle project relationships in a sector where qualification and reliability carry heavy weight.
Beneath this orderly growth profile, several challenges and inflection points are reshaping the playing field.
Material Cost Volatility and Long-Cycle Engineering Constraints
Turboexpanders rely on specialized high-performance alloys and steels for turbine blades and casings, and their supply chains are exposed to global steel producers and commodity price fluctuations. In an environment where input costs can swing and lead times for qualified materials stretch, manufacturers face pressure on margins and project predictability. The challenge is not simply cost containment; it is the ability to maintain engineering consistency, manage qualification cycles, and protect delivery commitments without compromising metallurgical performance. Companies that treat material strategy as a core competency, through dual sourcing, strategic inventory, and design-for-manufacturability initiatives, are better positioned to absorb volatility while preserving margin integrity.
Efficiency-Driven Demand Is Real, but Cycles Remain Project-Dependent
Industrial energy efficiency improvements could account for nearly 40 percent of total emission reductions required to meet global climate goals by 2050, and efficiency mandates such as India’s Perform, Achieve and Trade scheme are accelerating turboexpander adoption in natural gas infrastructure. At the same time, demand for LNG continues to expand, with global LNG demand projected to grow approximately 3.5 percent annually through 2025, reinforcing expander use in liquefaction processes. Yet much of this demand is tied to large, multi-year project cycles and capital allocation decisions that can shift with commodity prices, financing conditions, and policy signals. The practical implication is that volume growth is durable but lumpy; operators and suppliers must plan around execution windows rather than assume smooth quarterly expansion.
Qualification Barriers and the Cost of New Entry
Stringent EU decarbonization plans and carbon cut targets are enforcing the use of energy-recovery technologies like turboexpanders in waste heat and low-carbon applications, which expands the addressable market but also raises the bar for performance verification and integration. In cryogenic and high-pressure gas service, operational reliability, safety certification, and site-specific engineering support are decisive. This creates a meaningful barrier for new entrants and rewards incumbents with proven reference lists, localized service capabilities, and the ability to co-engineer solutions with end users. The market is therefore likely to see selective expansion rather than broad fragmentation, with differentiation emerging through application-specific know-how and lifecycle service rather than price alone.
Core Drivers Shaping the Market
Several interlocking forces explain why the turbo expander market is expanding in this particular shape and where value is likely to concentrate.
Technology Innovation Focused on Efficiency and Integration
Innovation is increasingly oriented around maximizing energy recovery, reducing parasitic losses, and embedding expanders more seamlessly into existing process trains. Radial flow architectures continue to command significant share in high-efficiency recovery scenarios, while axial and hybrid designs are finding niches where flow profiles, space constraints, or multi-stage requirements call for tailored solutions. Advances in blade metallurgy, bearing and sealing systems, and digital monitoring are helping operators extract more value from pressure differential energy and improve uptime. For manufacturers, the strategic question is which technology platform can be adapted across multiple applications without sacrificing performance, and how quickly new configurations can be qualified for demanding service.
Policy and Regulatory Tailwinds Reshaping End-User Priorities
Regulatory pressure is moving turboexpanders from optional efficiency upgrades toward core infrastructure considerations in several regions. Energy efficiency mandates are accelerating adoption in natural gas networks and processing facilities, while EU decarbonization targets are reinforcing demand for energy-recovery technologies in waste heat and low-carbon applications. These policies do more than expand demand; they change the decision criteria for buyers, placing greater weight on verified efficiency gains, emissions reduction, and long-term operating cost savings. Suppliers that can articulate and document those outcomes, supported by reference projects and transparent performance data, are better positioned to win tenders and influence specification standards.
Demand-Side Shifts Toward Energy Recovery and Flexible Gas Infrastructure
End users are increasingly treating pressure-energy recovery as a source of incremental power and operational resilience rather than a one-off retrofit. The commissioning of a 500kW turboexpander at a natural gas regulating station, followed by operating agreements to deploy similar systems across additional sites, illustrates how energy recovery is being normalized within gas network operations. In cryogenic and industrial gas contexts, air separation and natural gas processing continue to anchor demand, while new use cases in LNG, hydrogen, and geothermal applications are broadening the technology’s footprint. The broader trend is toward modular, application-specific solutions that can be integrated with lower disruption and faster payback, especially where facilities seek to improve throughput and reduce emissions without full-scale plant rebuilds.
Supply Chain Realities and Cost Structure Dynamics
The cost structure of turboexpanders is influenced by specialized materials, precision machining, testing requirements, and the cost of qualification support. As commodity prices fluctuate and high-performance alloy supply chains remain globally distributed, manufacturers must manage both input costs and the indirect costs of engineering change, rework, and delivery risk. At the same time, consolidation among suppliers of components and services can create opportunities for more stable procurement and integrated design, provided companies negotiate from a position of technical clarity and volume predictability. The most resilient operators are those that align design choices with manufacturability, secure qualified material pathways, and treat supply chain resilience as a product attribute rather than a back-office concern.
Competitive Landscape and Leading Strategies
The competitive set is broad and geographically diverse, spanning established industrial groups, cryogenic specialists, and application-focused innovators. Atlas Copco, Cryostar, Air Products and Chemicals, Baker Hughes, Chart Industries, Siemens Energy, Elliott Group, Nikkiso ACD, R&D Dynamics Corporation, Turbogaz, L.A. Turbine, Turboden, Sapphire Technologies, MAN Energy Solutions, PBS Group, and Hangyang Group each bring distinct strengths to the market, from centrifugal and radial flow platforms to in-line energy recovery systems and cryogenic turboexpanders for industrial gases and LNG. What differentiates leaders is not merely product breadth, but the ability to pair technology credibility with project execution, service access, and increasingly, energy-recovery value propositions that align with customer efficiency goals.
Strategic Positioning Among Incumbents
Several incumbents are reinforcing their positions through portfolio expansion and targeted capability acquisitions. Atlas Copco, for example, expanded its gas compression and energy-efficiency portfolio through the acquisition of Haizea and MSS Nitrogen, a move that broadens its reach across compression and gas-related applications while strengthening its ability to offer integrated efficiency solutions. Baker Hughes and Chart Industries continue to leverage their presence in LNG, natural gas processing, and hydrocarbon processing to position turboexpanders as part of larger process and energy recovery systems. Siemens Energy and MAN Energy Solutions maintain a strong footing in industrial and LNG applications, where scale, engineering support, and long-cycle relationship depth matter. In cryogenic industrial gases, companies such as Nikkiso ACD and PBS Group emphasize specialized expander technology for air separation and gas processing, where metallurgical performance and reliability are central.
Turbocharger Market
Innovation and Financing as Growth Enablers
Beyond incumbents, a layer of innovators is shaping the market through application-specific designs and new financing pathways. Sapphire Technologies closed a Series C round with participation from Mitsubishi Heavy Industries, Equinor Ventures, Cooper and Company, and Energy Capital Ventures, signaling investor confidence in in-line radial turboexpanders for natural gas energy recovery and power generation. In parallel, Anax Power commissioned its inaugural 500kW turboexpander at a natural gas regulating station and subsequently signed operating agreements with Enbridge to deploy its turboexpander system in Pennsylvania and Ontario. These moves illustrate a broadening of the commercial model: technology providers are not only selling hardware, they are increasingly building deployment partnerships, financing alliances, and site-specific demonstration pathways that reduce buyer risk and accelerate adoption.
Evolution of the Competitive Map
Market concentration suggests a landscape that favors scale and track record, yet it is not static. Consolidation among larger players is likely to continue where it creates synergies in engineering, service, and geographic coverage, particularly in LNG and large-scale gas processing. At the same time, niche differentiation is expanding around energy recovery, modular deployment, and digital monitoring, where agile companies can win on performance and integration rather than on size alone. The emergence of new financing and partnership models also creates openings for companies that can combine proven hardware with credible project economics. Expect the competitive map to remain concentrated at the top while becoming more multi-dimensional in the middle, with value shifting toward those who can deliver measurable efficiency gains and lifecycle support across varied applications.
Outlook: Three Trends to Watch Over the Next Three to Five Years
Looking ahead, the most consequential developments will likely be found at the intersection of technology deployment, policy reinforcement, and commercial model evolution.
Worldwide Permanent Magnet Turbo Blower Market
Energy Recovery Moves from Niche to Standard Practice
As efficiency mandates strengthen and LNG and gas infrastructure continue to expand, in-line and integrated turboexpanders are poised to become more routine in natural gas networks, processing facilities, and selected cryogenic applications. The commercial logic is straightforward: pressure differential energy that was once wasted can be converted into useful power or process support, improving unit economics and reducing emissions intensity. The opportunity for suppliers is to standardize proven configurations while retaining enough application flexibility to fit diverse site conditions. The risk is execution: if deployment scales faster than qualification and service capacity, integration quality and reliability could become slippage points. Companies that invest early in field support, modular design, and performance verification will be better placed to capture this wave.
Integration With LNG, Hydrogen, and Industrial Decarbonization Pipelines
Turboexpanders are increasingly embedded in broader decarbonization and gas-infrastructure strategies, particularly where LNG, hydrogen, and industrial energy efficiency goals intersect. The International Energy Agency’s emphasis on industrial energy efficiency as a major contributor to emission reductions, combined with EU decarbonization pressure and national efficiency schemes, creates a policy backdrop that rewards technologies offering verifiable efficiency and recovery benefits. For executives, the implication is that turboexpander decisions are becoming part of larger capital and sustainability planning. Suppliers that can connect expander performance to plant-level efficiency targets, emissions reporting, and operational flexibility will have an advantage in specification discussions and long-term partnerships. The uncertainty lies in the pace and coherence of policy implementation across regions, which can affect project timing even when the technical case is strong.
Differentiation Through Service, Digitalization, and Lifecycle Value
As the market matures, competition is likely to shift further toward lifecycle performance, monitoring, and service responsiveness. Digital condition monitoring, predictive maintenance, and integration with plant control systems can improve uptime and help operators realize the efficiency gains that justified the investment in the first place. In a market with notable concentration among leading players, service quality and technology support can be as important as initial hardware specifications. The strategic opportunity is to design products and service offerings that reduce total cost of ownership and make efficiency outcomes measurable over time. The caveat is that digital and service promises must be matched by field-proven reliability and realistic performance baselines; overpromising on intelligence or savings can erode trust quickly in high-stakes industrial environments.
Actionable Guidance for Decision Makers
For manufacturers, investors, and procurement professionals, the current landscape rewards deliberate positioning over reactive participation. A few priorities stand out.
For Manufacturers and Technology Providers
Focus on application portfolios that combine recurring demand with measurable efficiency outcomes. Radial and hybrid platforms that can be adapted across natural gas processing, air separation, and energy recovery applications offer scale potential, but the differentiator will be how quickly and credibly a supplier can qualify new configurations, support site integration, and prove lifecycle value. Strengthening material supply resilience, investing in modular and application-specific designs, and building demonstrable reference projects will help protect margin and win specification influence. It is equally important to align product messaging with the outcomes that matter to buyers today: verified efficiency improvement, emissions reduction, uptime, and integration risk reduction.
For Investors
Prioritize business models that combine hardware credibility with scalable deployment and service economics. The market’s concentration and qualification barriers favor players with proven reference lists, but growth is also coming from energy-recovery innovators and partners that can de-risk adoption through financing, demonstration, and operating agreements. When evaluating opportunities, look for evidence of repeatable project economics, durable customer relationships, and a clear path to expanding within LNG, industrial gas, and efficiency-driven gas infrastructure applications. Be mindful of the cyclicality embedded in large project pipelines and the sensitivity of margins to specialized materials and lead times; businesses that manage those inputs with discipline are more likely to convert market growth into sustainable returns.
PW Consulting
Strategic positioning is also evolving through partnerships and targeted acquisitions, as seen in recent portfolio expansions and financing rounds across the sector. Investors should track not only revenue trajectories but also the pace of capability-building, regional deployment progress, and the credibility of efficiency claims in real operating environments. Companies that can turn technology into measurable operational value, while maintaining disciplined execution, are best placed to capture the upside from efficiency mandates and expanding cryogenic and gas-processing demand.
For Procurement and Operations Leaders
Treat turboexpander selection as a lifecycle decision rather than a component purchase. Define performance criteria around efficiency recovery, reliability in site-specific conditions, service responsiveness, and total cost of ownership, and validate those criteria with reference cases that resemble your operating environment. Where possible, favor modular, application-specific solutions that minimize integration disruption and shorten payback, and require clear documentation of efficiency outcomes and maintenance expectations. Given material cost volatility and project cycle lumpiness, building flexibility into specifications and qualification pathways can reduce execution risk while preserving performance standards. For organizations planning multiple deployments, exploring operating partnerships and standardized configurations can improve consistency and lower integration cost over time.
Closing Perspective
The turbo expander market is not expanding simply because more equipment is being ordered; it is evolving because efficiency, decarbonization, and gas infrastructure needs are converging around technologies that recover and reuse pressure energy with increasing reliability. The growth path to 2032 reflects that shift, and the companies that will capture the most value are those that can align technology, qualification, service, and commercial models with the outcomes buyers are now prioritizing. For executives and investors, the practical next step is to narrow the focus from broad market growth to the specific applications, regions, and commercial structures where that growth is most actionable. Detailed segmentation data, company-level benchmarks, and tailored strategic recommendations can sharpen that view further and support more confident capital and procurement decisions.
For detailed analysis of this topic, please visit the official page: Turbo Expander Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
IVC Filters Market to Reach $212M by 2032: Why 9.4% CAGR Signals a Strategic Shift
By PW Consulting, 2026-09-21
The Inferior Vena Cava Filter Market: Strategic Trends and Commercial Opportunities in a High-Growth Landscape
The Inferior Vena Cava (IVC) Filter Market has entered a phase of accelerated expansion, driven by a convergence of epidemiological shifts, technological maturity, and evolving clinical protocols. As of 2025, the global market valuation stands at approximately 113.0 million USD, reflecting a compound annual growth rate of 9.4 percent across the forecast horizon extending to 2032. Historical trajectories from 2020 through 2025 demonstrate consistent upward momentum, with revenues climbing from 72.0 million USD to the current baseline, signaling sustained adoption and procedural volume increases. Looking forward, the market is projected to surpass 212.0 million USD by the end of the forecast period in 2032. Such financial expansion underscores a structural shift in how venous thromboembolism and pulmonary embolism prevention are managed, particularly as minimally invasive vascular interventions continue to gain procedural preference over pharmacological monotherapy in high-risk cohorts. For executives and investors, this trajectory signals more than incremental revenue growth; it points toward a market undergoing redefinition through product innovation, regulatory scrutiny, and procurement evolution. Understanding the mechanics behind this expansion is essential for positioning portfolios, allocating capital, and shaping commercialization strategies in a space where clinical credibility and supply chain reliability are becoming decisive competitive moats.
Current Landscape and Core Challenges
Despite robust top-line growth, the industry is navigating a set of interconnected challenges that will shape competitive outcomes over the next several years. The first and most pressing is the intensifying regulatory and litigation environment surrounding retrievable filter safety and retrieval compliance. Decades of clinical use have produced a well-documented awareness of migration, fracture, and perforation risks, which has translated into heightened post-market surveillance expectations and a persistent volume of multidistrict litigation. As of mid-2026, more than 6,500 pending cases remain active against major manufacturers related to IVC filter complications, reinforcing the cost of quality, traceability, and post-market evidence generation. For companies operating in this space, risk management has moved from a compliance function to a strategic imperative that influences procurement decisions, hospital formulary inclusion, and insurance liability considerations.
The second challenge lies in balancing clinical adoption with appropriate retrieval practices. Regulatory bodies have repeatedly emphasized timely removal of retrievable filters once the acute risk of pulmonary embolism has subsided, yet real-world retrieval rates often lag behind clinical intent due to patient follow-up fragmentation, procedural scheduling constraints, and institutional workflow limitations. This gap between guideline expectations and bedside execution creates both a clinical liability and a commercial friction point: products that simplify retrieval, reduce procedural time, or offer convertible design features gain meaningful differentiation in an environment where retrieval compliance is increasingly measured and scrutinized.
PW Consulting Automotive & Machinery Research Center
The third challenge emerges from the supply chain and cost structure dynamics governing interventional vascular devices. While reimbursement frameworks provide baseline facility payment references, including facility Medicare payments for intravascular vena cava filter insertion, hospitals and health systems are under continuous margin pressure to optimize procedural efficiency and reduce total cost of care. Device complexity, introducer system reliability, and procedural duration directly influence operating room throughput and clinical satisfaction. Any resistance in device delivery, sheath navigation, or retrieval mechanics can translate into operational delays, resource reallocation, and downstream cost impacts. In this context, manufacturers must align engineering performance not only with clinical efficacy but also with the economic realities of high-volume procedural environments.
Blood Filter Market
Key Drivers of Market Change
Multiple interconnected forces are propelling the IVC filter market beyond its historical baseline. These drivers are reshaping product roadmaps, influencing procurement criteria, and clarifying where long-term value will accrue.
Technological Innovation and Design Breakthroughs
Product engineering continues to be a primary catalyst for market evolution. The dominance of retrievable filter architectures in current usage reflects a broader clinical preference for devices that can be deployed as temporary protective measures and removed once the risk window closes. At the same time, next-generation retrieval technologies are altering the risk-reward calculus for difficult removals. The regulatory classification of laser-powered IVC filter retrieval catheters into class II with special controls marks an important milestone, formalizing a category that was previously positioned for failure cases where conventional methods were insufficient. This classification is not merely an administrative event; it creates a regulated pathway for advanced retrieval tools, broadens the clinical toolkit for complex extractions, and opens commercial avenues for companies developing adjunctive systems that support safer, faster, and more controlled filter removal. For manufacturers, the opportunity lies in designing filter platforms that integrate smoothly with evolving retrieval accessories and in developing proprietary extraction or repositioning systems that reduce procedural friction and improve physician confidence.
Policy and Regulatory Environment
Regulatory communication and classification decisions have exerted a long-running influence on the market and continue to do so. Earlier safety communications encouraging timely retrieval of retrievable filters have reshaped expectations around device lifecycle management and institutional oversight. More recently, the formal classification of laser-based retrieval catheters reinforces the regulatory direction toward risk-based controls and evidence-supported special controls. Such actions signal that the market is moving toward more explicit post-market obligations, including device tracking, retrieval documentation, and real-world performance monitoring. This trajectory affects not only product design and labeling but also commercial operations, as manufacturers must demonstrate robust quality systems, adverse event responsiveness, and traceability across the device lifecycle. In parallel, reimbursement structures remain a structural enabler of procedural volume, but they also impose expectations for efficiency and predictable outcomes. The interplay between reimbursement clarity and regulatory stringency is shaping which product categories gain formulary preference and how hospitals balance clinical utility against liability and workflow considerations.
Demand-Side Shifts in Clinical Behavior
Clinician and institutional behavior is evolving in response to both clinical evidence and operational realities. The preference for retrievable filters underscores a strategy of temporary protection in patients who may not require permanent mechanical filtration, while also reflecting the need for adaptable solutions in patients with evolving anticoagulation status or uncertain duration of risk. At the same time, institutions are increasingly focused on procedural standardization and complication reduction. Devices that offer consistent deployment characteristics, predictable filtering performance, and retrieval-friendly configurations are gaining favor because they reduce procedural variability and support protocol-driven care. Another demand-side development is the growing attention to convertible and repositionable designs, which allow procedural adjustments during deployment and can ease the clinical burden associated with suboptimal initial placement. In hospital procurement, these attributes matter because they influence case time, physician training requirements, and post-procedure management load. As centers seek to streamline interventional workflows while maintaining patient safety standards, device simplicity, reliability, and retrieval compatibility are becoming central evaluation criteria.
Supply Chain and Cost Structure Considerations
Cost dynamics in the IVC filter market are increasingly influenced by total procedural economics rather than unit device price alone. Hospitals evaluate devices through the lens of operating room efficiency, ancillary consumable usage, complication-related costs, and retrieval logistics. A device that delivers reliable delivery system performance and minimizes introducer resistance, for example, supports smoother procedural flow and reduces the likelihood of delays or vein-related complications that can escalate care complexity. Conversely, product issues that introduce procedural resistance or increase the risk of vascular injury can have disproportionate cost consequences, undermining both clinical outcomes and institutional efficiency metrics. Supply chain resilience also matters as manufacturers must ensure consistent availability of both primary filters and retrieval accessories, particularly as advanced removal technologies become more embedded in standard practice. Companies that can integrate device and retrieval system offerings into a coherent procedural solution, while maintaining stable production and distribution capabilities, are better positioned to meet procurement expectations in cost-sensitive environments.
Competitive Landscape and Leading Strategies
The market structure is characterized by meaningful concentration among established players, yet competitive advantage is increasingly defined by product differentiation, procedural reliability, and lifecycle management rather than scale alone. Leading manufacturers have built portfolios around retrievable filter platforms, convertible designs, and retrieval-compatible systems, with individual companies emphasizing distinct clinical narratives and engineering strengths.
Strategic Positioning and Differentiation
Cook Medical remains a prominent reference point in the market, anchored by retrievable filter offerings such as the Celect Platinum and the Günther Tulip filter. Its commercial strength has been linked to broad procedural familiarity and a long track record in the space, though its market standing is simultaneously shaped by ongoing litigation associated with filter complications. For competitors, this environment underscores the strategic value of proactive retrieval compatibility, transparent post-market data, and design features that reduce long-term risk profiles. Becton, Dickinson and Company (BD) has emphasized its Denali filter platform, reflecting a strategy aligned with large-scale commercial infrastructure and integration within broader interventional portfolios. Argon Medical Devices, Inc. has focused on its Option Elite retrievable vena cava filter system, positioning itself around retrieval functionality and procedural versatility. Cordis Corporation, operating within Cardinal Health, has maintained presence through retrievable and permanent filter lines such as the OptEase and TrapEase platforms, emphasizing established product heritage in multiple filter categories. B. Braun Interventional Systems, Inc. offers convertible and lower-profile filter options through its VenaTech line, highlighting design flexibility and deployment adaptability. ALN Implants Chirurgicaux contributes a European-origin perspective with optional filter systems and associated extraction and repositioning capabilities, reinforcing a strategy centered on retrieval enablement and procedural control.
Central Venous Catheters Market
Across these players, differentiation is emerging around several axes: retrieval compatibility, delivery system performance, convertible or repositionable features, and the breadth of ancillary systems that support filter removal and repositioning. Companies that treat the filter as part of an end-to-end procedural workflow, rather than a standalone implant, are building more defensible positions in a market where retrieval compliance and procedural reliability are increasingly central to clinical and procurement evaluation.
Market Evolution and Consolidation Dynamics
The competitive landscape is likely to evolve through selective consolidation, portfolio rationalization, and targeted innovation rather than pure volume expansion. As regulatory expectations rise and retrieval-related technologies mature, smaller or narrowly focused players may face pressure to demonstrate differentiated clinical value, robust quality systems, and reliable supply. At the same time, established manufacturers may pursue complementary capabilities in retrieval, imaging support, or procedural accessories to strengthen integrated offerings. There is also room for new entrants that bring specialized retrieval technologies, advanced delivery mechanics, or novel materials that improve long-term compatibility and reduce complication risk. However, entry barriers remain meaningful because the market rewards regulatory experience, post-market surveillance infrastructure, and established clinician relationships. For incumbents, the strategic priority is to convert product familiarity into procedural value propositions that explicitly address retrieval, reliability, and total cost of procedural care. For challengers, the opportunity lies in solving specific pain points that broader portfolios have not fully addressed, particularly in difficult retrieval scenarios and delivery consistency.
Future Trends and Commercial Implications
Looking ahead over the next three to five years, several trends are likely to shape the direction of the market and define where commercial value will concentrate. These trends do not merely extend existing growth; they change the metrics by which success is measured.
Retrieval-Centric Product Architecture as a Baseline Expectation
As retrieval compliance becomes more closely monitored and retrieval technologies become more established, filter design will increasingly be judged through the lens of how easily and safely a device can be removed. Retrievable filters will continue to dominate usage, but the differentiating question will shift from whether a filter is retrievable to how predictable, efficient, and low-risk retrieval is in real-world settings. This will favor designs that support smoother sheath navigation, reduce mechanical resistance, and integrate with advanced retrieval tools when conventional removal is insufficient. For manufacturers, the commercial implication is clear: retrieval efficacy and procedural simplicity will become core value propositions rather than secondary features. For hospitals, this trend reinforces procurement criteria that prioritize devices capable of supporting standardized retrieval protocols and minimizing complication-related follow-up costs. The associated risk is that products with weaker delivery or retrieval performance may face growing clinical skepticism, formulary exclusion, or liability exposure if complications or procedural delays emerge.
Advanced Retrieval Technologies and Adjacent Market Expansion
The formalization of laser-based retrieval catheter classification points toward broader adoption of adjunctive removal technologies, particularly for cases where conventional techniques are challenged by endothelial incorporation or structural complexity. As these technologies become part of accepted clinical pathways, they create opportunities for companies offering complementary devices, training, procedural support, and bundled solutions. The commercial upside extends beyond the filter itself to the surrounding ecosystem of retrieval accessories, procedural optimization tools, and service models that support complex interventions. However, this trend introduces uncertainty around reimbursement allocation, clinical adoption variability, and the need for robust training and documentation. Companies that can demonstrate safety, efficiency, and procedural cost reduction in difficult retrieval scenarios are more likely to capture value, while those that enter without clear clinical differentiation or risk documentation may find adoption constrained by hospital procurement caution.
Evidence Generation, Post-Market Transparency, and Procurement Rigor
The combination of ongoing litigation, regulatory communication history, and class-based device controls is increasing the premium on evidence generation and post-market transparency. Institutions and procurement teams are likely to place greater weight on real-world performance data, retrieval documentation, adverse event responsiveness, and quality system credibility. This creates a strategic expectation for manufacturers to maintain comprehensive post-market programs, support clinical registries or real-world evidence initiatives, and communicate device lifecycle management clearly. For investors and executives, the trend implies that brand trust and data credibility will increasingly influence market share dynamics, especially in a concentrated market where a few players hold a large share of revenue. The risk side of this trend is that any reputational or compliance gap can have outsized effects in a market where clinical safety narratives are closely watched and where procedural liability concerns are already elevated.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align product development with retrieval compatibility, delivery reliability, and procedural transparency. Investment in filter platforms should be evaluated not only by implantation performance but also by removal ease, integration with retrieval accessories, and the robustness of post-market surveillance. Companies should also examine opportunities to bundle filters with repositioning or extraction systems where such integration reduces procedural friction and supports compliance with timely retrieval expectations. In parallel, supply chain discipline and consistent availability of both primary devices and retrieval components should be treated as competitive differentiators in settings where procedural efficiency directly impacts hospital economics.
For investors, the market offers growth potential, but valuation and risk assessment must account for regulatory, litigation, and execution dynamics. The strongest opportunities are likely to emerge from companies with differentiated retrieval capabilities, credible post-market data programs, and clear strategies for navigating class-based device controls and reimbursement realities. Due diligence should consider not only revenue momentum but also device lifecycle management, complication-related risk exposure, and the capacity to sustain reimbursement alignment while expanding into adjacent retrieval technologies. Diversification across filter categories and retrieval-supporting portfolios can reduce dependence on any single product narrative, particularly in a market where clinical reputation and procedural reliability are tightly linked to commercial outcomes.
For procurement teams and health system leaders, device evaluation should increasingly incorporate retrieval workflow, procedural reliability, and total cost implications rather than unit pricing alone. Questions to explore include how consistently a device delivers without excessive resistance, how retrieval complexity is managed, how the manufacturer supports post-market documentation and adverse event responsiveness, and how the device performs within institutional protocols for timely removal. Preference for products that reduce variability and support standardized retrieval pathways can help lower downstream complication costs and improve procedural predictability. At the same time, procurement strategies should account for supply continuity and the need for training support as advanced retrieval tools become more integrated into clinical practice.
For stakeholders seeking a deeper, segment-level view of market sizing, regional dynamics, product category splits, application patterns, competitive benchmarks, and customized scenario planning, the full PW Consulting research report provides a more granular analytical foundation. The complete study extends the discussion beyond the strategic overview presented here and offers detailed data structures, forecasting detail, and tailored recommendations designed to support operational planning and investment decisions in a market where clinical credibility and procedural efficiency are becoming the decisive dimensions of long-term competitive advantage.
For detailed analysis of this topic, please visit the official page: Inferior Vena Cava (IVC) Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vitamin A Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global Vitamin A market has demonstrated consistent growth over the past five years, expanding from approximately 520 million USD in 2020 to an estimated 665 million USD in 2025. This trajectory reflects a compound annual growth rate of roughly 5.5 percent through the 2026 to 2032 forecast period, positioning the market to approach nearly 970 million USD by the end of the decade. The steady expansion is underpinned by broad demand across nutrition, feed, and fortification applications, yet the industry is navigating a period of structural transition that demands strategic attention from market participants.
One of the most pressing challenges lies in the evolving regulatory and trade landscape. Recent policy shifts in major economies have introduced both protections and constraints for vitamin supply chains. The exemption of Vitamin A from new U.S. tariffs and reciprocal duties under Annex II of recent executive orders has insulated producers from cost volatility that has affected other commodity categories. At the same time, extended regulatory shutdowns at key production facilities, particularly the vitamin A precursor plant in Ludwigshafen, Germany, have constrained EU-origin supply and elevated prices among established suppliers. These dynamics create a fragmented operating environment where regional availability and pricing stability are no longer guaranteed.
A second challenge centers on the tension between natural and synthetic product segments. The market is split between natural Vitamin A sources and synthetic variants, with synthetic products accounting for a larger share of overall revenue. This division is not merely a matter of preference; it reflects deeper questions about sourcing sustainability, consumer perception, and formulation performance. Natural carotenoid-derived Vitamin A has gained traction in food, beverage, and dietary supplement applications, while synthetic forms continue to dominate in animal nutrition and industrial fortification. Companies must navigate the strategic implications of this bifurcation as downstream customers increasingly seek transparency and differentiation in their ingredient portfolios.
The third significant challenge is market concentration. A relatively small group of manufacturers commands a disproportionate share of the market, creating both stability and vulnerability. While concentrated supply ensures quality consistency and technical expertise, it also amplifies the impact of production disruptions, capacity constraints, or strategic decisions by a handful of firms. Buyers and investors alike must account for this concentration when evaluating supply resilience and long-term pricing dynamics.
PW Consulting
Key Growth Drivers
Several interconnected forces are shaping the direction of the Vitamin A market and creating distinct pathways for value creation.
Technological Innovation and Product Formulation
Advancements in microencapsulation and combined formulation technologies are redefining how Vitamin A is delivered across applications. Recent product launches illustrate this shift. A next-generation microencapsulated combined Vitamin A and D3 formulation has been introduced with an extended shelf life under standard storage conditions, addressing long-standing stability challenges in animal nutrition. Such innovations reduce waste, improve handling efficiency, and enable more precise dosing, which in turn supports adoption in cost-sensitive feed markets while also opening doors in human nutrition where stability and bioavailability are critical.
Beyond microencapsulation, the broader trend toward tailored vitamin formulations is gaining momentum. Manufacturers are increasingly moving from commoditized bulk vitamin supply toward value-added solutions that address specific application requirements, whether that means enhanced heat stability, improved mixing characteristics, or compatibility with complex feed matrices. This shift encourages differentiation and supports margin preservation in a market where basic vitamin ingredients face periodic pricing pressure.
Regulatory and Policy Environment
The regulatory backdrop is a decisive factor in market dynamics. The exemption of Vitamin A from recent U.S. tariff actions, including 20 percent duties under specific statutory provisions, has preserved cost stability for producers and downstream users. Most key vitamins, including Vitamin A and a broad range of B-complex and other essential nutrients, are fully exempt from these duties under relevant sections of recent trade policy directives. This exemption reduces the risk of supply chain disruption and supports uninterrupted production scheduling for feed, food, and pharmaceutical applications.
Vitamin D Market
However, regulatory divergence across regions introduces complexity. The extended regulatory shutdown at a major German production site has constrained EU-origin supply, pushing buyers to reconsider sourcing strategies and inventory planning. Such disruptions underscore the importance of regulatory monitoring and the need for flexible procurement models that can adapt to shifting compliance timelines and regional availability.
Demand-Side Shifts in Consumer and Corporate Behavior
Demand patterns are evolving as consumer awareness of nutrition and wellness continues to rise, particularly in food and beverage and dietary supplement categories. Fortification trends are expanding beyond traditional staples into functional foods, beverages, and specialized supplement formats, where Vitamin A plays a supporting role in product positioning and nutritional labeling. In animal feed, the drive for efficient livestock production and balanced nutrition sustains steady demand, while also pushing formulators toward combined vitamin solutions that streamline inclusion rates and improve overall feed performance.
Corporate behavior is also shifting toward greater supply chain resilience. Buyers are increasingly prioritizing suppliers who can offer consistent quality, transparent sourcing, and contingency options. This preference favors established manufacturers with diversified production footprints and technical service capabilities, while also creating openings for newer entrants that can address niche requirements or regional demand gaps.
Supply Chain and Cost Structure Dynamics
Cost structures in the Vitamin A market are influenced by raw material availability, energy inputs, and the geographic concentration of manufacturing capacity. The exemption of Vitamin A from recent tariff pressures has provided a degree of protection, but other cost factors remain in play. Energy costs, logistics constraints, and the operational status of key precursor plants all contribute to pricing variability. The continued shutdown at the Ludwigshafen facility, for example, has elevated prices among established suppliers and reinforced the strategic importance of alternative sourcing routes.
Supply chain resilience is increasingly tied to the ability to manage multi-regional production and distribution. Companies that can balance capacity across regions, maintain buffer inventory where appropriate, and align formulation strategies with regional regulatory realities are better positioned to navigate cost volatility and supply interruptions.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of large-scale synthetic vitamin producers, specialized natural ingredient suppliers, and regional manufacturers with growing international reach. The market is moderately concentrated, with a small group of firms accounting for a significant portion of total revenue. This structure rewards scale, technical capability, and the ability to serve multiple application segments.
Strategic Positioning of Key Players
BASF SE, headquartered in Ludwigshafen, Germany, maintains a leading position in synthetic Vitamin A production for animal nutrition and human fortification. Its recent focus on combined microencapsulated formulations, including a next-generation Vitamin A and D3 product with extended shelf life, reflects a strategy oriented toward formulation differentiation and application-specific performance. By investing in dedicated formulation capabilities within its Verbund site, BASF is reinforcing its role as a solutions provider rather than a commodity supplier.
DSM-Firmenich AG, based in Delft, Netherlands, operates as a major supplier of Vitamin A and derivatives across nutrition and feed applications. The company maintains active portfolio management and market updates, signaling a strategy that emphasizes responsiveness to market conditions and regulatory developments. Its presence across multiple downstream categories supports diversification and provides visibility into shifting demand patterns.
Vitamin Market
Bluestar Adisseo Company, headquartered in Shanghai, China, is a key manufacturer of synthetic Vitamin A products for global feed and food markets. Its strategic value lies in its ability to serve large-volume demand while navigating regional production dynamics. As Asian demand continues to grow, manufacturers with strong regional footprints and export capabilities play an increasingly important role in balancing global supply.
Fenchem Biotek Ltd., also based in China, is an active producer of Vitamin A and related ingredients for industrial and nutritional applications. Its positioning reflects the broader trend of regional manufacturers expanding their ingredient portfolios and seeking integration into global supply chains.
Lycored Ltd., headquartered in Israel, supplies natural carotenoid-derived Vitamin A for food, beverage, and dietary supplement markets. Its focus on natural sourcing aligns with growing consumer and brand preferences for clean-label and traceable ingredients, differentiating it from synthetic-focused competitors and creating niche opportunities in premium fortification and supplement applications.
Market Evolution and Emerging Dynamics
The competitive landscape is evolving along several axes. Integration among large-scale producers continues to reinforce scale advantages in synthetic vitamin production, while differentiation is increasingly driven by formulation technology, application expertise, and regional supply reliability. At the same time, natural ingredient suppliers are carving out distinct positions by addressing demand for transparency and plant-based or carotenoid-derived alternatives.
New entrants and regional manufacturers are gaining relevance where they can offer cost-competitive supply, localized service, or specialized product attributes. However, the concentrated nature of the market means that new entrants must navigate barriers related to production scale, regulatory compliance, and customer qualification processes. The result is a market that rewards both scale and specificity, with successful players often combining broad application coverage with targeted technical differentiation.
Future Trends and Commercial Opportunities
Looking ahead to the 2026 to 2032 period, several trends are likely to shape the Vitamin A market and its commercial opportunities.
Trend One: Formulation-Led Differentiation Will Intensify
As basic vitamin ingredients face periodic pricing pressure and supply variability, the value shift toward tailored formulations is expected to deepen. Microencapsulation, combined vitamin products, and application-specific stabilizers will become more central to competitive positioning. Manufacturers that can offer formulations with extended shelf life, improved stability under processing conditions, and easier integration into feed or food matrices will capture incremental value and strengthen customer loyalty. This trend creates opportunities for suppliers to move up the value chain and for buyers to reduce total cost of ownership through improved performance and reduced waste.
Trend Two: Regional Supply Rebalancing and Sourcing Flexibility
Regulatory disruptions and production constraints in key regions are likely to accelerate efforts to rebalance supply across geographies. Buyers will increasingly seek multi-source strategies, regional inventory buffers, and supplier partnerships that provide continuity during compliance or operational interruptions. This rebalancing favors manufacturers with diversified production footprints and transparent supply chain practices. It also creates opportunities for regional producers to strengthen their role in global supply networks, particularly where they can offer reliable quality and responsive service.
Trend Three: Natural and Synthetic Segments Will Continue to Coevolve
The coexistence of natural and synthetic Vitamin A segments will remain a defining feature of the market. Natural carotenoid-derived options will continue to find traction in consumer-facing applications where clean-label positioning and traceability matter. Synthetic forms will retain strength in high-volume feed and industrial fortification markets where cost efficiency and performance consistency are paramount. The commercial opportunity lies in understanding where each segment adds the most value and in building portfolios or sourcing strategies that align with downstream customer priorities.
Risks and Uncertainties
Several uncertainties warrant attention. Extended regulatory shutdowns or new compliance requirements at major production sites could further constrain supply and elevate pricing. Trade policy changes, while currently favorable for Vitamin A through tariff exemptions, remain subject to revision and could introduce new cost dynamics if exemptions are altered. Demand shifts in animal feed, driven by livestock market conditions or alternative nutrition strategies, could affect volume growth in key segments. Finally, the concentrated supplier base means that strategic decisions by a small number of firms can have outsized effects on availability and pricing, requiring buyers and investors to maintain contingency planning and diversified sourcing approaches.
Actionable Insights for Decision-Makers
For manufacturers and suppliers, the priority is to strengthen differentiation through formulation capability and application expertise. Investing in microencapsulation, combined vitamin products, and stability-enhancing technologies can support margin resilience and customer retention. Equally important is the development of flexible supply strategies that account for regional regulatory dynamics and production variability, ensuring continuity for downstream customers even when specific sites face constraints.
For investors, the market offers steady growth supported by broad demand across nutrition, feed, and fortification, but success will depend on selecting players with scalable production, regulatory agility, and the ability to serve multiple application segments. Concentration in the supplier base creates both reliability and vulnerability, making it essential to evaluate each company's production footprint, formulation pipeline, and exposure to regional disruptions. Long-term value creation is likely to accrue to firms that combine scale with differentiated product capabilities and resilient sourcing models.
For procurement and formulary decision-makers, the key is to balance cost efficiency with supply resilience. Diversifying across suppliers and regions, aligning specification requirements with realistic supply conditions, and engaging suppliers early on formulation and stability needs can reduce exposure to price spikes and availability gaps. Understanding the regulatory status of Vitamin A in key markets, including its exemption from recent tariff actions, helps inform sourcing decisions and inventory planning. Maintaining visibility into production status at major sites and monitoring regulatory developments will support more proactive procurement strategies.
For organizations seeking a deeper understanding of regional demand patterns, application-level dynamics, and customized sourcing or investment scenarios, detailed market intelligence can provide the granularity needed to translate these trends into executable plans. Comprehensive research encompassing segmentation data, competitive assessments, and scenario-based forecasting offers a practical foundation for strategic planning and risk management in a market defined by both steady growth and evolving structural complexity.
For detailed analysis of this topic, please visit the official page: Vitamin A Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Equipment Maintenance Market: Why 9.9% CAGR and Preventive Services Redefine Growth to $110.08B
By PW Consulting, 2026-09-21
The Medical Equipment Maintenance Market: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Snapshot and Core Challenges
The global medical equipment maintenance market has entered a period of pronounced expansion, with total revenue reaching approximately 57.0 billion in 2025 and projected to climb to 110.08 billion by 2032. This trajectory reflects a compound annual growth rate of 9.9 percent across the forecast horizon, signaling a structural shift rather than a short-term cyclical upturn. Over the past five years, the market has steadily moved from fragmented, reactive repair models toward integrated lifecycle management programs, driven by rising capital intensity in healthcare delivery and an accelerating push toward operational resilience.
Despite this momentum, the sector faces meaningful headwinds that will shape competitive positioning over the next several years. First, the boundary between servicing and remanufacturing continues to generate regulatory and commercial friction. Healthcare providers, OEMs, and third-party operators must navigate evolving guidance on what constitutes acceptable post-market maintenance versus material modification, a distinction that carries direct implications for liability, scope of work, and pricing models. Second, labor constraints and specialized skill shortages are compressing service capacity. The industry relies heavily on trained clinical engineers and field technicians, and the supply of qualified personnel has not kept pace with the volume of installed equipment across aging hospital fleets. Third, installed-base complexity is increasing faster than many organizations’ service capabilities. Devices are becoming more software-defined, interconnected, and modular, which raises the bar for diagnostic precision, parts logistics, and remote intervention.
These challenges are not merely operational footnotes; they define where value will be captured. Organizations that treat maintenance as a predictable, data-enabled discipline will be better positioned to protect uptime, manage total cost of ownership, and align service delivery with clinical and financial performance targets.
2. Key Drivers Shaping Market Direction
Technology Innovation and Intelligent Service Models
Predictive and condition-based maintenance is rapidly moving from pilot programs to mainstream adoption. AI-enabled monitoring, remote diagnostics, and connected device telemetry are allowing service teams to anticipate failures before they affect clinical workflows. Recent activity illustrates how quickly this capability is becoming table stakes. In 2025, GE HealthCare expanded its enterprise software and imaging service footprint through the acquisition of Intelerad Medical Systems Corporation for 2.3 billion, while also entering a seven-year Care Alliance with Sutter Health to deploy AI-powered imaging systems across more than 300 facilities. Separately, a collaboration with IBM Watson Health was announced to launch AI-powered predictive maintenance services for medical imaging equipment. Philips also moved to strengthen its informatics-driven service positioning after securing FDA approval for IntelliSpace Enterprise Edition 6.0, which includes predictive maintenance capabilities for imaging systems.
For commercial leaders, the implication is clear: maintenance is increasingly sold and evaluated as an outcomes-based capability rather than a labor-hours contract. Solutions that can reduce unplanned downtime, extend useful life, and integrate with clinical and operational data are gaining preference, especially in high-acuity environments where device availability directly affects throughput and care continuity.
Regulatory and Standards Evolution
The regulatory environment is tightening in ways that favor disciplined, well-documented service programs. The FDA Quality Management System Regulation became effective in early 2026, incorporating ISO 13485:2016 by reference and applying to manufacturers as well as facilities engaged in remanufacturing or servicing. This alignment raises the expectations for quality systems, traceability, and controlled processes across the service ecosystem. At the same time, the Joint Commission streamlined its accreditation standards effective January 1, 2026, consolidating previous requirements for inspecting, testing, and maintaining medical equipment into a single element of performance that hospitals must ensure essential equipment remains in safe operating condition.
These developments create a dual effect. On one hand, they increase compliance burden and can raise the cost of service delivery for organizations that depend on informal or poorly documented practices. On the other hand, they strengthen the commercial case for providers and OEMs that can demonstrate structured quality management, standardized procedures, and auditable maintenance records. In practical terms, regulatory momentum is rewarding service models that are transparent, repeatable, and integrated with device lifecycle governance.
Demand-Side Shifts in Healthcare Operations
Healthcare providers are under sustained pressure to optimize capital deployment, reduce total cost of ownership, and maintain service levels with constrained operational budgets. These pressures are pushing procurement teams to evaluate service contracts not as ancillary expenses but as strategic levers for equipment reliability and cost predictability. Hospitals and health systems are increasingly seeking bundled programs that combine preventive maintenance, corrective support, and operational oversight, rather than managing multiple fragmented vendor relationships.
This demand-side evolution is also visible in regional capacity expansion. Sodexo India opened a 6,700 square-foot Healthcare Technology Management facility in Kolkata, equipped with six specialized labs designed to support up to 500,000 devices. The move reflects broader interest in building localized service capacity that can respond faster, reduce logistics latency, and improve coverage density. For the market overall, it signals that service delivery is becoming more geographically distributed and more sensitive to response-time expectations.
Cost Structure and Supply Chain Dynamics
Parts availability, labor economics, and reverse logistics continue to shape service margins and contract design. As devices become more software-centric and modular, the economics of repair are shifting. In some categories, rapid diagnostics and component-level replacement can improve asset utilization and reduce total cost, while in others, specialized parts sourcing and calibration requirements tighten margins and extend resolution times. At the same time, remanufacturing and refurbishment pathways are gaining attention as organizations look for ways to extend asset life without compromising performance or compliance.
A recent FDA guidance finalized in 2024 clarified the distinction between remanufacturing and servicing of reusable medical devices, emphasizing that proper servicing is critical to continued performance and overall product lifecycle management. More recently, FDA finalized guidance on Predetermined Change Control Plans for AI/ML-enabled devices, enabling manufacturers to include post-market algorithm update plans in initial submissions. Together, these signals indicate that device lifecycles are being managed more actively, and service providers will need clearer frameworks for supporting evolving software and hardware configurations over time.
3. Competitive Landscape and Leading Strategies
The medical equipment maintenance market remains concentrated, with a small group of large players commanding a substantial share of high-value service contracts. GE HealthCare, Siemens Healthineers, Philips, and Medtronic each bring strong brand recognition, deep installed-base relationships, and the ability to bundle maintenance with device sales, informatics platforms, and clinical workflow solutions. This integration is a defining competitive advantage, because it links service delivery directly to equipment performance data, service history, and lifecycle planning.
Worldwide Heavy Equipment Maintenance Service Market
GE HealthCare has emphasized AI-driven predictive maintenance, imaging and cardiology service, and the expansion of enterprise software portfolios. Siemens Healthineers has focused on diagnostic imaging, laboratory, and therapeutic equipment maintenance with remote monitoring and service contracts tailored to healthcare facilities. Philips has leaned into informatics platforms with predictive capabilities, positioning maintenance as part of a broader clinical technology ecosystem. Medtronic’s service model is particularly relevant in implanted devices, cardiac rhythm management, and minimally invasive surgical equipment, where ongoing service and maintenance contracts intersect with clinical risk and long-term patient outcomes.
Outside the largest OEMs, a second tier of specialists is carving out differentiated positions. B. Braun has concentrated on infusion, dialysis, and related equipment maintenance across hospital settings. STERIS has built a strong identity around sterilization, infection prevention, and equipment maintenance and repair services. Agiliti and TriMedx have taken a more holistic approach to clinical engineering, equipment maintenance, and technology management, often targeting health systems that want to consolidate service oversight or improve asset utilization across diverse device fleets.
PW Consulting
Several strategic themes are shaping how these players compete. First, integration is becoming more important than isolated repair capability. Providers increasingly prefer partners that can combine maintenance with remote monitoring, data analytics, spare-parts logistics, and technology lifecycle planning. Second, AI-enabled service differentiation is accelerating. Predictive maintenance, automated fault diagnosis, and algorithm-driven scheduling are transitioning from innovative features to differentiators that affect contract selection and retention. Third, partnerships and acquisitions are being used to extend reach. The 2025 acquisition by GE HealthCare and collaborations with major health systems and technology partners highlight a pattern of strengthening software, informatics, and enterprise service capabilities rather than competing solely on field labor.
At the same time, the landscape is not static. Regional capacity investments, such as the Healthcare Technology Management facility in Kolkata, point to growing appetite for localized service delivery and specialized lab infrastructure. This suggests an ongoing tension between centralized, OEM-led service models and regional or third-party operators that can offer flexibility, coverage density, or niche device expertise. For buyers and investors, the relevant question is whether a provider’s model can scale while maintaining quality, compliance, and responsiveness across heterogeneous equipment portfolios.
4. Forward Outlook: Three Trends to Watch Through 2032
From Preventive Schedules to Predictive, Data-Connected Service
Preventive maintenance will remain foundational, but its role is likely to evolve from calendar-based tasks toward continuously informed service planning. Devices that generate operational telemetry, error logs, and performance trends will enable more precise intervention windows, which can reduce unnecessary visits while improving readiness. The commercial opportunity lies in contracts and service architectures that reward reliability, faster diagnosis, and deferred capital replacement. Organizations that can operationalize predictive insights across large installed bases will have a clearer path to differentiated pricing, stronger retention, and better asset utilization outcomes.
One risk is uneven data quality and interoperability. Predictive models are only as effective as the underlying device data, integration maturity, and process discipline supporting them. If telemetry coverage is incomplete or service workflows cannot act quickly on alerts, the theoretical gains from AI-driven maintenance may fail to materialize in practice.
Regulation-Driven Professionalization of Service Delivery
As quality management expectations rise and accreditation standards consolidate around safe operating condition requirements, service delivery is likely to become more formalized. Documentation, training, traceability, and controlled procedures will carry greater commercial weight, especially for organizations involved in remanufacturing or servicing activities that intersect with regulatory oversight. The trend favors providers that can standardize processes across sites and demonstrate compliance without imposing excessive administrative burden on clinical staff.
The uncertainty here is speed and consistency of adoption. Regulatory clarity is improving, but implementation varies by facility type, region, and device category. Market participants that assume uniform compliance behavior may misjudge the timeline for contract wins, service standardization, or partnership requirements.
Lifecycle Extension, Modularity, and Strategic Refurbishment
With device complexity rising and capital budgets under pressure, lifecycle management is gaining strategic importance. Maintenance programs are increasingly evaluated not only on uptime but also on whether they enable longer useful life, component-level optimization, and responsible refurbishment where appropriate. This creates opportunities for service providers that can combine repair expertise with parts logistics, calibration, software updates, and disposal or redeployment planning. It also raises the importance of clear boundaries between servicing and remanufacturing, since misclassification can create regulatory, quality, and commercial risk.
A key risk is that lifecycle extension strategies can be undermined by unavailable parts, obsolete software support, or changing clinical requirements. Without strong reverse logistics and lifecycle governance, maintenance programs may extend service duration without improving total cost outcomes.
5. Strategic Actions for Decision-Makers
For manufacturers and OEMs, the priority is to embed service intelligence into the product and contract architecture early. Predictive capabilities, remote diagnostics, and integrated informatics should be treated as core elements of the service offering rather than optional add-ons. Aligning service design with regulatory expectations for quality management and device lifecycle management can reduce downstream friction and strengthen contract positioning. Where possible, manufacturers should also consider how partnerships, acquisitions, and software expansion can broaden enterprise value beyond individual device repairs.
For investors, the market’s expansion is attractive, but differentiation will depend on execution quality. Due diligence should focus on whether a service provider has durable mechanisms for predictive maintenance, compliance readiness, geographic coverage, and parts logistics. Concentration in the market suggests that scale and brand matter, yet there is also room for specialists that address underserved device categories, regional demand, or integrated technology management. The most resilient business models will likely combine recurring service revenue with demonstrated improvements in uptime, total cost of ownership, and operational simplicity for customers.
Worldwide Pharmaceutical Equipment Maintenance Services Market
For healthcare procurement and clinical engineering teams, the decision framework should shift from lowest headline price to total value under real operating conditions. Contracts that provide transparent service levels, remote monitoring, rapid response, and well-documented quality processes can reduce hidden costs associated with downtime, repeated visits, and compliance gaps. Procurement teams should also evaluate whether the service provider can support mixed device portfolios, evolving software configurations, and future lifecycle needs rather than optimizing for a single equipment category in isolation.
Given the pace of regulatory change, technology adoption, and competitive consolidation, timely access to granular market intelligence is increasingly important for shaping contracts, portfolio strategy, and investment priorities. Readers seeking deeper segmentation data, regional expansion patterns, and customized recommendations aligned with specific device portfolios or service models may find value in PW Consulting’s comprehensive research report on the medical equipment maintenance market.
For detailed analysis of this topic, please visit the official page: Medical Equipment Maintenance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wind Lidar Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Landscape and Structural Shifts
The wind lidar market has evolved from a niche instrumentation segment into a critical enabler of modern wind energy development. Between 2020 and 2025, the market expanded steadily, reaching approximately $623 million in revenue. The trajectory accelerates into the forecast period, with projected growth to over $1.1 billion by 2032 and a compound annual growth rate of 9.3 percent. This expansion reflects a structural shift rather than a cyclical upswing. Wind lidar is no longer treated as an optional measurement tool; it is increasingly embedded in resource assessment, power performance validation, and operational optimization across onshore and offshore projects.
Three dynamics define the current market inflection point. First, standardization is maturing. The publication of IEC TS 61400-50-4:2025 for floating lidar systems, alongside continued validation of nacelle-mounted and ground-based systems under IEC 61400-50-2, is shifting lidar from demonstration-grade instrumentation to bankable measurement infrastructure. Second, deployment models are diversifying. Ground-based profiling, nacelle-mounted sensing, and scanning architectures are converging in project workflows, creating overlapping use cases that blur traditional product boundaries. Third, the value proposition is expanding beyond data acquisition. Lidar-derived wind profiles are increasingly integrated into analytics services, risk modeling, and turbine control optimization, turning hardware sales into recurring data and service relationships.
At the same time, fragmentation remains visible. The top three competitors account for roughly 28 percent of market revenue, and the top five reach about 36 percent. This concentration indicates a market where incumbents hold meaningful credibility and certification advantages, yet there is still ample room for specialized players, regional expanders, and service-led hybrids. The absence of a single dominant platform strategy means competitive advantage is increasingly determined by certification coverage, deployment reliability in harsh environments, integration with project development workflows, and the ability to translate measurements into financial confidence.
For decision makers, the implication is straightforward: wind lidar is transitioning from a procurement line item to a strategic data layer. Companies that treat it as a commodity risk underinvesting in validation, integration, and service continuity. Companies that treat it as a platform for bankable uncertainty reduction and operational insight are better positioned to capture the margin and loyalty that come with trusted measurement outcomes.
PW Consulting Information & Electronics Research Center
Core Growth Drivers
Technical Innovation and Measurement Confidence
Measurement confidence is the central technical driver. Continuous-wave and pulsed Doppler architectures are both advancing, but the commercial prize now sits in demonstrated classification, range, and uncertainty performance under independent testing. Recent product launches have emphasized wider effective range and reduced uncertainty at certified test sites, which directly addresses the financing and yield-risk questions that have historically constrained lidar adoption. Compact, low-maintenance designs are also widening applicability in boundary-layer meteorology, aviation safety, and harsh-environment offshore settings.
Equally important is the shift from single-point measurement to integrated profiling and scanning. Scanning lidar systems are enabling more detailed spatial characterization, while nacelle-mounted sensors are moving toward real-time performance monitoring and turbine control support. This dual expansion—higher accuracy for bankable assessment and faster feedback for operational optimization—creates a broader addressable market than either use case alone.
Policy, Regulation, and Certification as Adoption Accelerators
Standards and certification frameworks are becoming practical adoption triggers rather than abstract compliance requirements. The release of floating lidar guidance supports offshore measurement plans that were previously difficult to standardize, while ongoing alignment efforts across IEC and IEA Wind working groups are reducing ambiguity in scanning lidar methodologies. In parallel, recognized validation pathways from DNV and WindGuard continue to shape procurement decisions, particularly where lenders and developers require defensible uncertainty budgets for resource assessment and power curve measurements.
This regulatory maturation matters commercially because it lowers transaction risk. When measurement systems carry clear classification and independent validation, developers can use lidar earlier in project design, financiers can accept tighter uncertainty assumptions, and manufacturers can compete on demonstrated performance rather than narrative. In offshore wind especially, standardization is unlocking measurement approaches that were previously too uncertain to justify at scale.
Demand-Side Reorientation Toward Risk Reduction and Operations
On the demand side, the strongest pull comes from project developers and turbine operators seeking to reduce uncertainty at multiple stages. For new developments, lidar supports faster site characterization and more credible wind resource narratives, which can compress development timelines and improve financing conditions. For operating assets, nacelle-mounted lidar is increasingly used for performance monitoring, wake-aware optimization, and maintenance planning. The commercial logic is simple: better measurement data can reduce overdesign, improve availability, and support data-driven operational decisions.
A related shift is the growing use of lidar data as an input to analytics services. Rather than selling hardware as an isolated product, some players are bundling measurement with wind profile analytics, resource modeling support, and interpretive services. This reflects a demand-side preference for outcomes over instruments. Developers want defensible data packages and actionable insight, not just raw measurements. That preference is reshaping product roadmaps and go-to-market models across the segment.
Supply-Side and Cost-Structure Evolution
On the supply side, scale and manufacturing maturity are improving unit economics for certain product categories. High-volume production capability, combined with established certification portfolios, is helping some manufacturers serve global turbine OEM demand more efficiently. At the same time, the market is seeing differentiated cost structures: incumbents with strong certification and service networks command credibility premiums, while newer or region-focused players compete on specialization, lead time, and application fit.
This divergence matters because cost leadership alone is rarely decisive in bankable measurement applications. Buyers weigh total cost of assurance, not just instrument price. That includes calibration support, deployment robustness, data quality documentation, and the ability to meet lender or insurer expectations. Suppliers that optimize only for hardware cost may win tactical deals but lose strategic positions where measurement credibility determines procurement choice.
Competitive Positioning and Strategic Divergence
The competitive field is defined less by sheer vendor count than by differentiated positioning around measurement type, deployment context, and customer outcome. A clear split is emerging between specialist lidar manufacturers and broader instruments or analytics players, with the specialists generally competing on class-leading classification, application-specific hardware, and certification depth, while the broader players compete on integration, service reach, and multi-sector applicability.
Several strategic profiles stand out. Specialist continuous-wave and pulsed lidar providers with strong onshore, offshore, and nacelle-mounted portfolios compete on certified measurement range and deployment flexibility. Their advantage typically rests on recognizable classification performance, global deployment experience, and product lines that map directly to resource assessment and power performance testing. In this profile, credibility is built through demonstrable compliance and repeatable field results rather than brand breadth.
Worldwide 3D Scanning Wind Lidar Market
Another profile centers on Doppler lidar families used across wind energy, aviation, and meteorology, with nacelle-mounted and ground-based variants validated for bankable offshore data. This positioning leverages cross-sector engineering heritage and the ability to serve multiple institutional buyers, which can support scale and long-term service relationships. The commercial logic is to use broad validation and application coverage to become the default measurement option in projects where lenders and operators want familiar, defensible technology.
A third profile emphasizes compact, low-maintenance pulsed Doppler systems for boundary-layer meteorology, aviation safety, and wind energy, with an emphasis on harsh-environment operation. Here differentiation comes from robustness, ease of deployment, and suitability for demanding field conditions. That positioning can be especially valuable where maintenance access is costly or where measurement continuity is critical.
There is also a growing role for nacelle-focused sensing specialists that tie lidar directly to turbine performance monitoring and optimization. One notable pattern is deep integration with major turbine install bases, where nacelle-mounted sensors are used not only for measurement but also for ongoing performance management. In such cases, market position is reinforced by installed-base relationships and the ability to convert operational data into product and service stickiness.
Beyond hardware specialists, some players are moving toward lidar-enabled data services that combine measurement with resource analytics. This service-oriented approach reflects a broader industry preference for solution-level value, particularly where buyers want interpretable wind profiles and modeling support rather than a standalone instrument. The trend suggests that competitive advantage will increasingly depend on how well a vendor can connect hardware, validation, and analytics into a coherent customer outcome.
Looking at market evolution, three patterns are likely to shape the next phase. First, consolidation pressure will remain moderate rather than aggressive. The market is still fragmented enough that specialized leaders can grow through certification, geographic expansion, and application depth without immediate pressure to merge. Second, differentiation will tilt toward integration and validation. Vendors that can align hardware, certification, and service delivery with project finance and operations workflows will capture more value than those competing primarily on feature lists. Third, new entrants and regional players will continue to find niches, especially where local deployment support, specific environmental conditions, or OEM relationships create addressable pockets that global incumbents do not fully cover.
Forward Outlook: Three Strategic Trends for 2026–2032
Trend 1: Offshore Measurement Standardization as a Growth Catalyst
Offshore wind assessment is poised to become one of the strongest growth vectors for wind lidar, and standardization is the key enabler. Floating lidar guidance and improved nacelle and ground-based validation reduce the uncertainty that has historically made offshore measurement expensive and slow. As developers pursue larger offshore programs, the ability to deploy repeatable, certified measurement systems will support both early-stage resource assessment and later-stage performance validation. The commercial opportunity lies in turnkey offshore measurement packages that combine instrument selection, deployment logistics, validation documentation, and data interpretation into a single buyer-facing workflow. The principal risk is execution complexity: offshore deployments remain sensitive to logistics, weather windows, and integration with met mast or other complementary measurement strategies, so reliability and service readiness will separate winning offerings from marginal ones.
Trend 2: From Bankable Assessment to Operational Intelligence
The market is likely to shift further toward lidar as an operational data source, not just a project development tool. Nacelle-mounted sensors and scanning systems can feed performance monitoring, wake analysis, and turbine control support, creating value after construction as well as before it. This extends the revenue relationship beyond the measurement campaign and aligns lidar more closely with asset life-cycle economics. The opportunity for manufacturers and service providers is to design products and service contracts that support recurring use, data continuity, and integration with turbine control or asset management systems. The risk is that operational integration raises expectations for reliability, cybersecurity, and data governance, which can increase the cost of customer acceptance if not managed early.
Trend 3: Service-Adjacent Competition and Outcome-Based Buying
A third trend is the growing importance of analytics-enabled services and outcome-based buying. Customers increasingly evaluate lidar on the confidence it provides for financing, design, and operations, and they are more receptive to offerings that include data interpretation, uncertainty support, and workflow integration. This creates room for hybrid business models that combine hardware sales with service subscriptions, analytics partnerships, or interpretive support. The strategic challenge is that outcome-based competition rewards vendors with strong documentation, validation track records, and customer-facing expertise. Companies that compete only on instrument specifications may find themselves squeezed by suppliers who can better translate measurements into financial and operational assurance.
Strategic Actions for Decision Makers
For Manufacturers and Technology Providers
Invest in certification breadth and independent validation as core commercial assets, not just engineering milestones. In bankable measurement markets, demonstrable classification, documented uncertainty, and recognized validation pathways often matter more than incremental feature additions. Product roadmaps should prioritize the deployment contexts that financiers and developers most trust, including offshore measurement, nacelle-mounted performance use, and harsh-environment profiling. Equally important is designing for service continuity: calibration support, field robustness, and data-quality documentation can be as decisive as hardware performance in repeated procurement decisions.
Manufacturers should also evaluate business model expansion carefully. Where customers want outcomes rather than instruments, analytics partnerships, interpretive services, or structured data offerings can strengthen positioning and reduce direct hardware commoditization. The goal is to increase the measure of trust and usefulness in each deployment, which supports both pricing power and repeat business.
For Investors and Strategic Backers
Focus on vendors that can convert technical credibility into repeatable procurement. The most attractive opportunities are likely in companies with clear certification alignment, defensible deployment records, and strong fit with offshore and operational use cases. When evaluating candidates, look beyond top-line growth and assess whether the business can sustain validation leadership, service quality, and customer integration at scale. Supply-side scale can improve competitiveness, but in this market it is usually most valuable when paired with certification depth and customer-facing reliability.
Investors should also monitor the shift toward service-adjacent models. Companies that can package measurement with analytics or workflow integration may capture more durable value than those that remain purely hardware-focused, but the execution burden is higher. Due diligence should therefore weigh data handling, customer support, and the ability to satisfy lender or insurer expectations, not just product catalogs.
For Buyers, Developers, and Procurement Teams
Treat lidar selection as a risk-management and workflow decision, not just a procurement exercise. Specify measurement requirements around certification status, validated uncertainty, deployment environment, and data deliverables, and align those requirements with the stage of the project. For resource assessment, prioritize instruments and service packages that support bankable documentation and lender acceptance. For operational use, prioritize integration, reliability, and ongoing support over one-time instrument cost.
Procurement teams should also consider total assurance cost. That includes training, deployment logistics, maintenance, calibration, and the quality of interpretive support. A lower hardware price can be misleading if it increases uncertainty, delays project milestones, or weakens data defensibility. In practice, the strongest procurement outcomes usually come from vendors who can demonstrate consistent measurement quality and support the buyer's downstream decision process.
Conclusion
The wind lidar market is entering a phase where growth is increasingly tied to credibility, standardization, and integration rather than instrument novelty alone. Revenue expansion from the mid-six-hundred-million-dollar range toward more than a billion dollars by the early 2030s reflects a broader transformation in how wind projects are measured, financed, and operated. The companies and buyers that win in this environment will be those that understand lidar as part of a bankable data and service ecosystem, not as an isolated sensor.
For a detailed view of segment-level sizing, regional dynamics, application splits, and company-level positioning, the full market report provides deeper breakdown and tailored implications. The opportunity now is to align product strategy, investment thesis, or procurement planning with the standardized, outcome-focused direction the market is already taking.
Light Detection and Ranging (LIDAR) Market
For detailed analysis of this topic, please visit the official page: Wind Lidar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


