



Beyond the 9.24% CAGR Story: The Real Drivers Reshaping the Worldwide Intermediate Bus Converter Market
By PW Consulting, 2026-09-18
Strategic Shifts and Commercial Opportunities in the Worldwide Intermediate Bus Converter Market
Market Overview and Core Challenges
The global intermediate bus converter (IBC) market has established itself as a critical component within distributed power architectures, serving as the bridge between high-voltage input buses and low-voltage point-of-load regulators. Valued at approximately $640.0 million in 2025, the market has demonstrated consistent expansion over the past five years, recovering steadily from the volatility experienced during the early 2020s. Projections indicate that the sector will continue its upward trajectory, reaching an estimated $1.19 billion by 2032. This growth reflects a compound annual growth rate of 9.24 percent, signaling strong underlying demand drivers that extend beyond cyclical recovery.
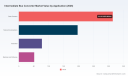
Geographically, the market spans a diverse footprint. Asia Pacific represents the largest revenue contributor, followed by North America and Europe. Latin America and the Middle East & Africa, while smaller in absolute terms, offer emerging opportunities as infrastructure modernization accelerates in these regions. In terms of technology segmentation, isolated IBC solutions currently command a larger share of revenue compared to non-isolated variants, reflecting the stringent safety and noise-immunity requirements in telecommunications and industrial infrastructure. However, non-isolated designs are gaining traction in applications where size, cost, and efficiency take precedence over galvanic isolation.
Interface Bridge ICs Market
Application-wise, data centers dominate consumption, fueled by the relentless expansion of cloud computing and hyperscale facilities. Telecommunications infrastructure remains a substantial consumer base, particularly as legacy networks transition to 5G and edge computing deployments. Industrial automation and medical/defense systems contribute to steady baseline demand, though these segments typically exhibit longer product lifecycles and more conservative adoption curves.
Despite the favorable growth trajectory, the IBC market faces several structural challenges that will shape competitive dynamics in the coming years.
- Architecture disruption from direct conversion trends. Emerging high-voltage DC distribution schemes and advanced wide-bandgap devices are enabling topologies that bypass or minimize the traditional intermediate bus stage. Some initiatives target 800V DC delivery directly to downstream converters, which could compress the addressable market for conventional IBC modules in certain AI server configurations.
- Thermal and power density limits. As rack densities climb, the ability to dissipate heat within standard form factors becomes a binding constraint. Manufacturers must balance efficiency gains against thermal management complexity, particularly in confined cabinet spaces where airflow is limited.
- Supply chain friction and component availability. High-performance IBC designs depend on specialized magnetics, high-voltage capacitors, and advanced semiconductor processes. Fluctuations in raw material costs, lead times for critical passive components, and geopolitical sourcing risks can create margin pressure and inventory volatility for both suppliers and end-users.
Key Drivers of Market Change
The expansion of the IBC market is being propelled by a convergence of technological, regulatory, and demand-side forces. Understanding these drivers is essential for assessing where value will accumulate and which product strategies will prove durable.
Technological Innovation and High-Voltage Architecture Shift
The most transformative driver is the push toward higher-voltage distribution and increased power density. Traditional 48V intermediate bus architectures have served the industry well, but the extreme power requirements of modern AI workloads are prompting a reevaluation of the power delivery chain. New reference designs are emerging that operate at ±400V or 800V DC levels, supported by wide-bandgap semiconductors such as gallium nitride. These developments enable higher efficiency and more compact conversion stages, but they also challenge the conventional role of the IBC. In parallel, non-isolated quarter-brick IBC modules are being optimized for hyperscale computing, with peak power capabilities reaching several kilowatts and efficiency levels approaching 98 percent in select designs. This dual path—higher voltage direct architectures on one hand, and ultra-high-performance intermediate bus modules on the other—creates a rich environment for engineering differentiation.
Regulatory and Safety Standards Shaping Design Choices
Safety and compliance requirements continue to influence product roadmaps and procurement decisions. Commercial IBC modules generally adhere to IEC/EN/UL 62368-1 safety standards applicable to information and communication technology equipment. As data centers and telecom operators consolidate infrastructure, the ability to demonstrate compliance with globally recognized safety frameworks becomes a competitive differentiator, especially in multi-vendor deployments where risk mitigation and interoperability matter. Additionally, trends toward centralized power distribution and higher voltage DC architectures are intersecting with evolving electrical codes and data center safety guidelines, creating a need for converters that can operate reliably in more electrically stressful environments.
PW Consulting
Demand-Side Shifts Driven by AI and Compute Intensity
The demand profile for power conversion hardware is being reshaped by the computational intensity of AI training and inference workloads. Hyperscale data centers are deploying denser racks with higher per-rack power budgets, and this directly increases the need for efficient intermediate conversion stages that can handle transient loads and deliver stable lower-voltage rails to downstream regulators. While some initiatives aim to eliminate the traditional IBC stage in specific AI server platforms, many deployments still rely on intermediate bus conversion to manage distribution losses, noise isolation, and modular scalability. Beyond data centers, telecommunications networks continue to expand edge and baseband processing units, and industrial automation systems are integrating more power-dense control electronics. These application trends sustain demand across a diversified end-use base.
Supply Chain and Cost Structure Dynamics
Cost structures in the IBC market are influenced by both material economics and engineering intensity. Designs that incorporate advanced magnetics, high-voltage isolation, and precision control circuitry tend to carry higher bill-of-material costs, which can pressure margins in price-sensitive segments. At the same time, the emergence of highly integrated modules and digital control architectures can reduce system-level complexity and improve overall total cost of ownership, even if the converter unit itself is more expensive. Supply chain resilience is increasingly a strategic consideration; companies that can secure reliable access to critical components and maintain design flexibility in the face of component shortages are better positioned to capture share when demand accelerates.
Competitive Landscape and Leading Strategies
The IBC market features a mix of specialist power semiconductor and converter manufacturers as well as broader industrial power electronics players. Concentration is moderately high, with the top three firms accounting for roughly 41.5 percent of revenue and the top five representing about 56.8 percent. This concentration suggests that scale, technology leadership, and established customer relationships matter, but there remains meaningful room for differentiated offerings in niche form factors, digital control, and high-voltage architectures.
Strategic Positioning Among Leading Players
Several incumbents have carved out distinct value propositions aligned with their technological strengths and target verticals:
Bus Validator Market
- Vicor Corporation has built a reputation around fixed-ratio isolated IBC products designed for distributed power architectures. Its focus on enterprise, telecom, and high-efficiency systems positions it well in applications where galvanic isolation and predictable conversion ratios simplify downstream design.
- Flex Power Modules has emphasized compact, high-performance IBC solutions optimized for AI and data center environments. Its product lines include non-isolated and digitally controllable designs with strong peak power capability, targeting hyperscale computing where density and efficiency are paramount.
- Infineon Technologies AG supplies high-density IBC modules and leverages wide-bandgap technology through CoolGaN-based reference designs. Its recent push into high-voltage architectures for 48V and 800V DC systems reflects a strategy aimed at leading the transition toward more electrically demanding power distribution topologies in AI server platforms.
- Analog Devices, Inc. focuses on discrete quarter-brick reference designs that prioritize efficiency and thermal performance, particularly for data center applications. By emphasizing detailed performance characterization and advanced control, it addresses engineering teams seeking proven building blocks with clear performance trade-offs.
- Delta Electronics, Murata Manufacturing, Bel Power Solutions, Artesyn Embedded Power, CUI Inc., and Reed Semiconductor collectively round out a competitive field that spans broad power conversion portfolios, embedded computing applications, telecom and networking use cases, and distributed power architectures for servers. Their strategies often emphasize portfolio breadth, compliance, cost positioning, and regional service capabilities.
Recent Developments and Strategic Signals
Recent product and reference design activity highlights where competitive attention is concentrating:
- In March 2026, Infineon Technologies AG introduced two new CoolGaN-based high-voltage IBC reference designs supporting ±400V and 800V DC architectures for AI server power systems. This move signals a strategic bet on high-voltage distribution becoming mainstream in next-generation AI infrastructure.
- Also in March 2026, Navitas Semiconductor demonstrated an 800V–6V DC-DC power delivery board using GaNFast technology designed to eliminate the traditional 48V intermediate bus converter stage for NVIDIA AI infrastructure. While this approach may reduce IBC unit demand in specific configurations, it underscores the broader competitive tension between modular intermediate conversion and direct high-voltage delivery.
- In September 2025, Flex Power Modules unveiled the BMR313 ultra-small, high-performance IBC engineered for AI and data center applications. The launch reinforces the push toward miniaturization and performance optimization in compute-heavy environments.
- In July 2025, Analog Devices, Inc. published detailed performance data on a discrete quarter-brick IBC reference design for data center power architectures, emphasizing efficiency and thermal management. This type of transparent engineering documentation helps establish credibility and accelerates adoption among design teams.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is likely to evolve along three axes. First, consolidation may continue as larger portfolios and broader service networks become valuable to large-scale data center and telecom buyers seeking supply chain simplicity. Second, differentiation will intensify around high-voltage capability, digital control features, thermal performance, and compliance assurance, particularly as AI workloads push the boundaries of power density. Third, new entrants and adjacent semiconductor players may introduce disruptive topologies that challenge conventional IBC architectures, especially where wide-bandgap devices enable more direct power delivery. Companies that combine strong reference design support, ecosystem compatibility, and the ability to adapt to evolving architecture preferences will be best positioned to retain and expand their footprint.
Future Trends and Outlook
Looking ahead across a three-to-five-year horizon, several trends are likely to define the IBC market’s trajectory and where commercial opportunities will emerge.
Coexistence of Intermediate Conversion and Direct High-Voltage Delivery
Rather than a clean replacement of IBCs by direct conversion, the market is more likely to see architectural bifurcation. In many hyperscale and edge deployments, intermediate bus conversion will remain valuable for isolation, noise reduction, modularity, and system-level flexibility. At the same time, certain AI server platforms will adopt high-voltage direct delivery to maximize efficiency and compute density. The commercial opportunity lies in delivering IBC solutions that are adaptable to multiple architectures, with clearly defined efficiency and thermal profiles, while also monitoring where direct-conversion adoption could reshape volume expectations in specific subsegments.
Higher Power Density and Digital Intelligence in Conversion Stages
Power density requirements will continue to rise, driven by rack-scale compute growth and the need to optimize footprint and cooling costs. Modules that combine high continuous and peak power capability with advanced thermal paths and digital control interfaces will gain preference in data center and telecom applications. Digitalization can enable better monitoring, adaptive control, and predictive maintenance, which aligns with operational priorities in large-scale infrastructure. Suppliers that integrate intelligence at the converter level, while maintaining safety and reliability, can create differentiated value beyond raw conversion performance.
Regional Diversification and Segment-Specific Demand Patterns
While data centers will remain the dominant demand pool, regional dynamics and segment-specific adoption cycles will influence growth patterns. Asia Pacific’s scale advantage may be complemented by incremental modernization in other regions as telecom, industrial, and defense programs refresh their power architectures. Segment-wise, telecommunications and industrial applications are likely to provide steadier, less cyclical demand, whereas data center volumes may be more sensitive to capex cycles and architectural changes. Companies that can balance a strong data center proposition with resilient demand from other verticals will enjoy more stable revenue streams.
Risks and Uncertainties
Several uncertainties could moderate the outlook. Architecture shifts that reduce reliance on intermediate bus stages in certain AI platforms may compress volume growth in specific form factors. Macroeconomic pressures on data center capex, changes in telecom investment timing, and component supply disruptions could create intermittent demand volatility. Additionally, safety and compliance requirements may evolve as high-voltage DC distribution becomes more prevalent, potentially influencing qualification timelines and design costs. Stakeholders should monitor these factors closely and adjust product roadmaps and inventory strategies accordingly.
Guidance for Decision Makers
Different stakeholder groups can extract actionable direction from the current market signals.
For Power Converter and Component Manufacturers
Prioritize engineering investments that address the two most consequential questions: how to maintain relevance in high-voltage and direct-conversion scenarios, and how to differentiate through power density, thermal performance, and digital control. Develop reference designs and application support that make it easy for customers to evaluate trade-offs between isolated and non-isolated IBC options, and between intermediate conversion and alternative architectures. Strengthen supply chain resilience for critical magnetics, capacitors, and semiconductor processes to reduce exposure to component shortages and cost swings.
For Investors and Corporate Development Teams
Focus due diligence on companies that demonstrate clear positioning around high-voltage readiness, AI and data center demand, and compliance assurance. Assess whether product portfolios are broad enough to benefit from steady demand in telecom and industrial segments while capturing upside from data center growth. Pay attention to firms that are actively shaping ecosystem compatibility and reference design quality, as these attributes often correlate with adoption velocity in complex power system designs.
For Procurement, Engineering, and Infrastructure Planning Teams
Evaluate IBC suppliers not only on unit cost but on total system impact, including efficiency, thermal behavior, qualification timelines, and compatibility with target architectures. Where possible, design for flexibility so that intermediate bus conversion can be retained or bypassed depending on final platform decisions. Maintain visibility into upcoming reference designs and architecture shifts, since these can materially affect qualification lead times and interoperability planning.
The intermediate bus converter market is at an inflection point where technology evolution, architecture debates, and demand concentration in AI-driven data centers are reshaping where value is created. Decision-makers who secure timely, granular intelligence on segment dynamics, competitive moves, and architecture transitions will be better equipped to align product strategies, investment priorities, and procurement plans with the market’s trajectory. For stakeholders seeking deeper segmentation details, regional breakdowns, and tailored guidance aligned to specific operational goals, accessing the full research report provides the granular evidence base needed to move from directional insight to precise execution.
For detailed analysis of this topic, please visit the official page: Worldwide Intermediate Bus Converter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Honeycomb Optical Breadboards Market: Why the 6.25% CAGR Reshapes Optics
By PW Consulting, 2026-09-18
Strategic Shifts and Commercial Opportunities in the Global Honeycomb Optical Breadboard Market
Market Overview and Critical Challenges
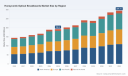
The global market for honeycomb optical breadboards has transitioned from a niche instrumentation sector to a strategically important component within precision photonics and laser systems. With a market valuation exceeding USD 190 million in 2025 and a projected compound annual growth rate of 6.25% through 2032, the segment reflects steady expansion driven by the proliferation of advanced optical assemblies. Historical revenue trajectories from 2020 through 2025 demonstrate consistent upward momentum, with particularly sharp acceleration observed in the 2023–2024 window. Forward projections indicate that the market will breach the 300 million threshold by the end of the forecast period, underscoring the growing integration of honeycomb structural components into high-value optical architectures.
Despite this encouraging trajectory, the industry faces several structural inflection points that demand strategic attention. First, the standardization-versus-customization tension continues to complicate product roadmaps. As optical setups grow more complex, end users increasingly request tailored damping profiles, mounting geometries, and surface finishes, yet manufacturers must balance these demands against the cost efficiencies of standardized production lines. Second, raw material volatility and supply chain fragmentation present persistent margin pressures. The structural performance of optical breadboards depends heavily on the quality and consistency of honeycomb cores and top-skin materials, making procurement strategies highly sensitive to global commodity fluctuations and regional manufacturing capacity constraints. Third, the competitive field is characterized by significant consolidation, with the top three players commanding over 58% of total revenue and the top five accounting for more than 72%. This concentration creates both advantages for established players with deep engineering resources and barriers for mid-sized manufacturers seeking to scale without differentiated capabilities.
These challenges are not insurmountable, but they reframe how executives should evaluate growth. The market is no longer expanding uniformly across all customer segments; instead, value creation is shifting toward firms that can align structural engineering expertise with application-specific performance requirements while navigating supply chain and pricing dynamics efficiently.
Key Demand Drivers Shaping Market Evolution
Several interconnected forces are accelerating demand and reshaping procurement priorities across the honeycomb optical breadboard ecosystem. Understanding these drivers provides a clearer lens for assessing where commercial value will concentrate over the next several years.
Honeycomb Sandwich Material Market
Technical performance requirements in precision optics remain the most direct catalyst. Modern photonics, laser interferometry, and quantum measurement systems demand exceptionally low vibration transmission, high flatness tolerances, and consistent modal damping across operational environments. Honeycomb architectures inherently deliver a favorable stiffness-to-weight ratio combined with structural damping characteristics that solid-plate alternatives struggle to match without substantial mass penalties. This engineering reality has made honeycomb breadboards the default structural foundation for optical tables, beam delivery assemblies, and calibration platforms where micro-vibration isolation directly impacts signal integrity. As laser wavelengths shorten and optical configurations become more densely packed, the tolerance for mechanical instability narrows, reinforcing the structural necessity of high-performance honeycomb cores.
Policy and research funding environments are indirectly but powerfully shaping procurement cycles. Government-backed initiatives in semiconductor equipment development, advanced manufacturing, and life sciences instrumentation continue to channel capital into laboratory infrastructure and pilot production lines. Public research institutions and private R&D centers depend on stable, vibration-isolated platforms for repeatable experimental outcomes, which sustains baseline demand from academic and scientific organizations. At the same time, regulatory emphasis on measurement traceability and environmental stability in testing laboratories encourages procurement of components with documented damping performance and dimensional consistency, elevating quality assurance from a compliance checkbox to a competitive differentiator.
Demand-side behavior in enterprise and industrial settings is shifting toward modular, reconfigurable optical infrastructure. Rather than committing to fixed installations, engineering teams increasingly favor breadboards and table extensions that can be rearranged, upgraded, or integrated into larger setups as project requirements evolve. This modular preference is particularly pronounced in aerospace testbeds and research facilities, where experimental configurations change frequently and downtime for reconfiguration must be minimized. The result is a preference for breadboard designs that support standardized mounting patterns, consistent skin thicknesses, and compatible interface hardware, reducing integration friction across multiple procurement cycles.
Worldwide Honeycomb Board Market
Supply chain and cost structure dynamics are exerting dual pressure on manufacturers and buyers. On the material side, core composition choices influence both performance and total cost of ownership. Aluminum honeycomb structures have secured a substantial share of broader honeycomb core material consumption due to their balance of weight efficiency, machinability, and cost, while certain polymer-based cores are gaining traction in adjacent applications where moisture resistance and recyclability offer lifecycle advantages. For optical breadboard producers, this means material strategy is no longer purely about structural specification; it also involves forecasting commodity availability, qualifying alternative suppliers, and designing product families that can absorb material substitution without compromising flatness or damping targets. On the manufacturing side, regional production footprints and lead-time variability are becoming more prominent in sourcing decisions, especially for customers running time-sensitive development programs or operating in locations where logistics delays could stall project milestones.
PW Consulting
Together, these drivers indicate that growth will be earned through application alignment, material strategy discipline, and the ability to deliver modular performance without sacrificing structural integrity.
Competitive Landscape and Strategic Positioning
The competitive environment for honeycomb optical breadboards is defined by a handful of established manufacturers with deep optical engineering heritage, alongside a broader set of regional and specialty producers that compete on cost, customization, or specific material configurations. The market's revenue concentration underscores the advantage held by firms that can combine consistent quality, recognized brand trust, and comprehensive application support.
Leading players are pursuing differentiation through several complementary strategies. Some emphasize monolithic or hybrid honeycomb construction paired with advanced damping features, positioning their breadboards as high-stiffness platforms for demanding photonics and laser applications. Others focus on series breadth, offering multiple core materials, skin finishes, and mounting hole patterns to cover a wide range of laboratory and industrial configurations. A third strategic vector involves ferromagnetic or magnetic top-skin options that simplify component alignment and extension, particularly for optical table ecosystems where breadboards serve as modular add-ons rather than standalone workstations. These approaches reflect a broader realization that winning in this market depends less on selling a commodity plate and more on delivering a predictable mechanical environment for sensitive optical assemblies.
Recent product and commercial activity reinforces the importance of portfolio discipline and market visibility. One manufacturer retired an industrial-grade breadboard model and directed customers toward a scientific-grade replacement, signaling a deliberate shift toward higher-performance, application-aligned offerings rather than maintaining broad but undifferentiated catalog depth. Another major participant used a premier photonics conference to showcase hybrid honeycomb breadboards alongside clean-top optical tables, reinforcing the message that breadboard selection should be evaluated within the context of complete optical infrastructure rather than as isolated hardware. These moves illustrate a maturing competitive dynamic in which product rationalization and ecosystem positioning are becoming as important as raw specification leadership.
The landscape is also showing signs of both consolidation and targeted expansion. Larger incumbents with global distribution and technical support networks are well placed to defend share in price-sensitive segments while competing on performance in high-margin applications. Smaller and regional manufacturers, meanwhile, are creating space by specializing in specific core material variants, offering faster custom quoting, or serving local markets where logistics and relationship-based selling matter more than global brand recognition. At the same time, new entrants face a steep credibility curve because optical engineers prioritize documented flatness, vibration behavior, and long-term supplier reliability. As a result, the most plausible contour of market evolution is continued leadership by established names, with incremental pressure from specialists that can demonstrate clear performance or service differentiation in defined application niches.
Forward Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2031 period, three trends are likely to shape how value is created and captured in this market.
- Performance-tiered portfolio segmentation will deepen. Buyers will increasingly separate procurement into two streams: standardized solutions for routine laboratory and educational setups, and engineered solutions for semiconductor equipment, advanced life sciences instrumentation, and aerospace testing. Manufacturers that can articulate distinct value propositions across these tiers, rather than stretching a single product line across all use cases, will be better positioned to protect margins and serve application-specific expectations.
- Modular and customized integration will become a baseline expectation. Demand for breadboards that interoperate cleanly with optical tables, damping legs, and mounting accessories will keep rising, especially where research infrastructure and aerospace prototyping require frequent reconfiguration. Suppliers that invest in compatible interface standards, clear extension roadmaps, and predictable lead times will reduce friction for buyers and build repeat procurement relationships.
- Material and sourcing strategy will move from background concern to strategic priority. As core material choices influence both cost and structural behavior, manufacturers and buyers will pay closer attention to supply continuity, substitution pathways, and qualification cycles. Firms that can demonstrate reliable material availability and consistent performance across core and skin combinations will gain negotiation leverage, while those exposed to single-source dependencies or abrupt material transitions may face margin and delivery risk.
These trends create opportunities for suppliers that can align product architecture with real-world integration needs, and for buyers that can structure sourcing around performance tiers rather than uniform specification comparisons. At the same time, uncertainty remains. Shifts in research funding cycles, changes in semiconductor equipment investment pacing, and potential disruptions in specialty material availability could alter demand velocity in specific regions or application verticals. Competitive intensity may also rise if larger players aggressively rationalize portfolios or if regional manufacturers successfully scale differentiated offerings. The market is therefore likely to reward organizations that monitor these signals continuously and adjust product, sourcing, and partnership decisions before shifts become obvious in aggregate revenue data.
Actionable Recommendations for Decision-Makers
For optical component manufacturers: Prioritize product portfolio clarity. Map offerings explicitly to performance tiers and application contexts, and retire or reposition catalog items that create confusion without contributing to differentiation. Invest in documentation that communicates damping behavior, flatness consistency, and compatibility with common mounting and extension hardware, since these attributes increasingly influence repeat procurement more than headline specifications alone.
For investors and strategic buyers: Evaluate targets and partners based on engineering credibility, material sourcing resilience, and the ability to serve high-value application segments rather than sheer catalog breadth. In a concentrated market, durable advantage tends to come from application adjacency, technical support quality, and integration-oriented product design. Scrutinize whether a company's roadmap emphasizes modular interoperability and performance-tiered segmentation, as these characteristics are more likely to support sustained relevance than undifferentiated volume plays.
For procurement and engineering leaders: Move evaluation beyond unit price and base specification sheets. Establish internal criteria for vibration isolation requirements, mounting compatibility, and expected reconfiguration frequency, then align supplier selection with those operational realities. Where project timelines are tight or application environments are demanding, prioritize suppliers with transparent performance documentation and consistent lead-time performance over those competing solely on initial cost. For organizations seeking detailed segmentation data and supplier-level comparisons to support these decisions, a comprehensive market study can provide the structured detail needed to refine sourcing strategy and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Honeycomb Optical Breadboards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Femtosecond OPA Market: Why 6.91% CAGR Reshapes Growth Beyond 2032
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Femtosecond OPA Market
Market Overview and Core Challenges
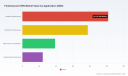
The global femtosecond optical parametric amplifier (OPA) market has established itself as a critical enabler for advanced photonic applications, bridging the gap between fixed-wavelength laser sources and the broad tunability required for cutting-edge research and industrial processes. Based on current valuation metrics, the market reached approximately 242.45 million USD in 2025, reflecting a compound annual growth rate of 6.91 percent projected through 2032. This trajectory suggests a steady expansion from the 172.85 million USD baseline observed in 2020, indicating sustained demand despite macroeconomic fluctuations. The forecast period extending to 2032 points toward a valuation approaching 386.78 million USD, signaling a mature yet growing ecosystem where technological capability increasingly dictates market share.
Despite this positive revenue outlook, the industry stands at a critical juncture defined by several structural challenges. One primary hurdle is the dependency on specific nonlinear crystal materials. The performance, tuning range, and efficiency of femtosecond OPA systems rely heavily on the availability and quality of crystals such as BBO, LBO, KTA, or emerging materials like BaGa4Se7. Supply chain volatility in these specialized components can directly impact production timelines and system performance specifications, creating vulnerabilities for manufacturers who lack diversified sourcing strategies.
Another significant challenge lies in the pump laser infrastructure. The primary hardware bottleneck for high-power femtosecond OPAs is the availability of stable, high-average-power Yb-based femtosecond pump lasers, often requiring power levels between 50 and 300 W with excellent beam quality and synchronization capabilities. As applications demand higher repetition rates and average powers, the integration complexity between the pump source and the OPA stage increases, requiring tighter engineering tolerances and more sophisticated thermal management solutions.
Worldwide Solid State Mode-Locked Picosecond Lasers Market
Furthermore, the regulatory landscape introduces an element of uncertainty. Export controls on advanced laser technologies, including certain high-power ultrafast systems, may apply under international frameworks for dual-use items. These controls affect global supply chains for research-grade femtosecond OPAs, potentially limiting market access in certain regions or complicating cross-border collaborations. While femtosecond OPA systems are primarily used in controlled laboratory and research environments under general laser safety standards such as IEC 60825-1, the lack of a specific industry-wide ISO standard unique to femtosecond OPAs means manufacturers must navigate a patchwork of regional safety and compliance requirements.
Key Drivers of Market Growth
The expansion of the femtosecond OPA market is propelled by a convergence of technological innovation, evolving application demands, and shifts in the supply chain dynamics. Understanding these drivers is essential for stakeholders looking to position themselves advantageously within the value chain.
Technological Innovation and Performance Frontiers
The quest for broader tunability and higher pulse energies continues to drive product development. Recent advancements demonstrate a clear trend toward compact, high-repetition-rate systems that maintain sub-50 fs pulse durations. For instance, the launch of the FemtoTune series femtosecond OPA in July 2025 highlighted the industry's push toward integrating high-repetition rates up to 100 kHz with broad tunability ranges extending from visible to gapless mid-IR. Similarly, updates to existing platforms in early 2026 have emphasized supporting high pump powers and automated operation, reflecting a maturity in design that prioritizes stability and ease of integration. These innovations are not merely incremental; they expand the accessible parameter space for users, enabling experiments and processes that were previously constrained by source limitations.
Demand-Side Shifts in Research and Industry
Demand is being reshaped by the specific needs of ultrafast spectroscopy, multiphoton microscopy, and high-harmonic generation. In spectroscopy, the ability to tune across wide spectral ranges allows researchers to probe specific molecular transitions with greater precision. In microscopy, particularly multiphoton and three-photon imaging, the spectral flexibility of OPAs enables deeper tissue penetration and reduced phototoxicity. The industrial micromachining sector also contributes to demand, albeit from a smaller base, as manufacturers seek precise ablation capabilities that rely on specific wavelengths achievable through OPA technology. The shift from purely academic research to applied industrial settings is broadening the customer base beyond traditional laser physics laboratories.
Supply Chain and Component Specialization
The supply side is characterized by a high degree of specialization, particularly regarding nonlinear optics and pump laser synchronization. The critical role of nonlinear crystals means that companies capable of securing high-quality materials or developing proprietary crystal solutions gain a competitive edge. Additionally, the reliance on stable Yb-based femtosecond pump lasers creates a symbiotic relationship between OPA manufacturers and pump laser vendors. This interdependency encourages integrated solutions where the OPA is designed to work seamlessly with specific laser platforms, reducing integration friction for the end user. However, it also means that bottlenecks in pump laser production can cascade through the OPA market.
Regulatory and Safety Environment
While not a direct growth driver in the traditional sense, the regulatory environment shapes market behavior. The absence of a unique ISO standard for femtosecond OPAs means manufacturers must adhere to general laser safety standards, which influences product design regarding enclosure, interlocks, and beam delivery. Moreover, export controls on dual-use items require companies to maintain rigorous compliance protocols. For global players, navigating these regulations without stifling innovation is a delicate balance that can affect market entry strategies and partnership formation.
Competitive Landscape and Leading Strategies
The market exhibits a moderate level of concentration, with a significant portion of revenue captured by a handful of established players. This concentration suggests that barriers to entry remain high, primarily due to the technical complexity of designing stable, tunable systems and the established relationships required to penetrate key customer segments.
PW Consulting
Leading companies have adopted distinct strategic positions to differentiate themselves. Light Conversion, based in Vilnius, Lithuania, has positioned itself as a dominant provider through its ORPHEUS series, offering tunable UV to MIR coverage with high repetition rates up to 2 MHz. Their strategy emphasizes high stability for Yb-pumped systems and the ability to attach compactly to CARBIDE/PHAROS lasers, targeting spectroscopy, microscopy, and micromachining applications. This integration-focused approach reduces system complexity for the user.
APE Angewandte Physik und Elektronik GmbH, located in Berlin, Germany, focuses on robustness and automation. Their AVUS femtosecond OPA supports up to 50 W pump power with versions for varying pulse durations, tunable across broad ranges such as 650 nm to 2.5 μm or 210 nm to 11 μm. The use of an air-cooled monolithic design targets thermal stability and automation, appealing to users who prioritize long-term reliability and minimal maintenance in high-power scenarios.
Coherent, headquartered in Santa Clara, California, leverages its extensive portfolio with integrated solutions like the OPerA Solo. This one-box, computer-controlled system tunes from 240 nm to 20 μm for kHz amplifiers, extending tuning for spectroscopy and microscopy. Their strategy involves integrating OPAs into broader ultrafast laser ecosystems, such as pairing with Monaco or Astrella systems, to offer a turnkey experience for high-end research facilities.
EKSPLA, also from Vilnius, competes through specialized series like FemtoTune, offering sub-50 fs pulses at up to 100 kHz. Their focus on tunable ranges including extensions to UV-VIS and gapless mid-IR up to 10,000 nm, pumped by industrial FemtoLux lasers, targets users needing specific spectral coverage for ultrafast spectroscopy and imaging.
Spectra-Physics (MKS Instruments) maintains a strong presence in the microscopy and optogenetics sectors with Spirit-NOPA tunable non-collinear optical parametric amplifiers. Optimized for Spirit HE/One ultrafast lasers, they deliver pulses from less than 30 fs to less than 100 fs tunable in VIS-IR, catering to applications like multiphoton microscopy where pulse duration and stability are critical.
Amplitude, based in Bordeaux, France, differentiates with the Mango optical parametric amplifier platform, offering tuning from 210 nm to 11,000 nm from a single port with consistent polarization. Supporting up to 2 MHz and featuring dispersion management, this platform targets complex imaging applications like 3P imaging and time-resolved spectroscopy, emphasizing versatility and polarization control.
Class 5 Photonics, headquartered in Hamburg, Germany, specializes in OPCPA systems incorporating OPA stages. Their White Dwarf series provides tunable femtosecond pulses, including high-power few-cycle options pumped by industrial Yb lasers. This positions them at the intersection of high-power physics and application-driven needs such as attosecond science and high-harmonic generation.
Ultrafast Lasers Market
The market landscape is evolving through both consolidation and specialization. While established players strengthen their positions by expanding spectral ranges and pulse repetition rates, there is room for new entrants who can solve specific bottlenecks, such as reducing size, weight, and power consumption for field-deployable systems or improving efficiency in specific mid-IR regions. The trend suggests a move toward more integrated, turnkey solutions where the distinction between the pump laser and the OPA blurs, offering customers greater ease of use.
Future Trends and Predictions
Looking ahead to the next three to five years, several key trends are likely to shape the trajectory of the femtosecond OPA market. These trends present both opportunities for growth and risks that require strategic mitigation.
Trend 1: Convergence of High Power and High Repetition Rates
As applications in microscopy and industrial processing demand more signal or faster processing, the pressure to increase both average power and repetition rates will intensify. Systems that can deliver high pulse energies at multi-kHz or MHz repetition rates without compromising beam quality or tunability will capture significant market share. This trend creates opportunities for manufacturers who can solve thermal management issues in nonlinear crystals and optimize pump laser synchronization. However, it also raises the risk of component failure or degradation if thermal loads are not adequately managed.
Trend 2: Expansion into New Spectral Regimes
While visible and near-IR tunability is well-established, there is growing interest in the mid-IR and deep-UV regions for specific molecular fingerprinting and high-harmonic generation applications. Technologies that enable gapless coverage or efficient conversion into these harder-to-reach spectral ranges will find niche but high-value markets. Emerging crystal materials like BaGa4Se7 may play a crucial role here. The risk lies in the cost and availability of exotic crystals, which could limit scalability if supply chains are not secured.
Trend 3: Automation and User Accessibility
The democratization of advanced laser techniques is driving demand for systems that require less specialized knowledge to operate. Future OPAs are likely to feature more automated alignment, tuning, and monitoring capabilities, reducing the barrier to entry for non-expert users. This shift expands the potential customer base to smaller laboratories or industrial quality control teams. The uncertainty involves balancing automation with the flexibility required by expert researchers who may need manual override or custom configurations.
Actionable Insights for Decision Makers
For manufacturers, the priority should be on securing supply chains for critical nonlinear crystals and developing partnerships with pump laser vendors to ensure compatibility. Investing in thermal management solutions and automation features will differentiate products in a crowded field. Companies should also monitor regulatory changes regarding dual-use items to ensure uninterrupted global distribution.
Investors should look for companies that demonstrate strong integration capabilities with existing laser platforms, as turn-key solutions are increasingly preferred over modular components. Firms that show innovation in high-repetition-rate, high-power regimes or those accessing underserved spectral regions may offer attractive growth potential. Due diligence should include an assessment of the company's ability to navigate export controls and supply chain vulnerabilities.
Procurement leaders and research heads should focus on specifying systems that offer flexibility for future applications rather than optimizing solely for current needs. Evaluating the vendor's support ecosystem, including software integration and automation features, is as important as the technical specifications of the OPA itself. Ensuring compatibility with existing infrastructure will reduce total cost of ownership and downtime.
For those requiring granular data on regional splits, specific application revenue breakdowns, and detailed competitor benchmarking, accessing the full market intelligence report is recommended. The complete research provides the necessary depth to support investment decisions, product roadmap planning, and strategic positioning in this evolving high-tech sector.
For detailed analysis of this topic, please visit the official page: Worldwide Femtosecond OPA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Formaldehyde Testing Instrument Market: The 5.85% CAGR Reality
By PW Consulting, 2026-09-18
Strategic Horizons: Navigating the Global Formaldehyde Testing Instrument Market
Market Landscape and Critical Challenges
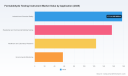
The global market for formaldehyde testing instruments has entered a phase of steady, structurally supported expansion. Valued at approximately USD 387.8 million in 2020, the market has consistently climbed, crossing the USD 500 million threshold by 2025 and positioning itself to reach roughly USD 767.0 million by 2032. This trajectory reflects a compound annual growth rate of 5.85% across the forecast horizon. The growth is not merely cyclical; it is anchored in tightening regulatory expectations, widespread industrial adoption of indoor air quality monitoring, and the gradual replacement of legacy detection methods with faster, more integrated analytical systems.
PW Consulting
Despite the favorable momentum, the industry faces several structural tensions. The first is the calibration-compliance paradox. As regulatory bodies across multiple jurisdictions update emission and exposure standards, testing protocols are becoming more prescriptive. Instruments that once met general workplace monitoring requirements now need to demonstrate alignment with specific chamber methods, micro-chamber protocols, and third-party certification frameworks. Manufacturers and end users alike must navigate a landscape where compliance is no longer a one-time validation but an ongoing operational requirement.
The second challenge lies in the convergence of detection sensitivity and deployment practicality. Many high-precision analytical systems deliver the accuracy required for laboratory and regulatory-grade testing, yet their size, cost, and operational complexity limit field adoption. Conversely, portable handheld devices offer flexibility and speed, but users in industrial and healthcare settings increasingly demand quantifiable assurance that low-level readings remain reliable over extended monitoring periods. Bridging this gap without sacrificing accuracy or ease of use remains a persistent engineering and commercial hurdle.
A third inflection point is the fragmentation of application requirements. Testing needs differ sharply between continuous emissions monitoring at manufacturing sites, spot-checking for indoor air quality in buildings, and controlled laboratory emissions testing for composite materials. Each segment carries distinct performance expectations, calibration rhythms, and reporting obligations. Companies that attempt to serve all segments with a single product architecture often find themselves stretched across competing engineering priorities and compliance demands.
Key Challenges at a Glance
- Aligning instrument performance with evolving, region-specific regulatory test methods
- Balancing laboratory-grade accuracy with the portability and cost constraints of field deployment
- Designing product strategies that address divergent requirements across industrial, building, healthcare, and environmental use cases
Key Drivers Shaping Market Evolution
Several interconnected forces are accelerating demand for formaldehyde testing instruments and reshaping how they are positioned in the market. Understanding these dynamics is essential for any organization evaluating product roadmaps, procurement strategies, or investment exposure.
Paraformaldehyde Market
Technology Innovation and Analytical Precision
The most visible driver is the continued refinement of detection technologies that reduce measurement latency while preserving analytical rigor. Traditional methods often relied on chemical sampling, extended chamber exposure, or laboratory transfer steps that delayed results and increased operational burden. Newer approaches are compressing that timeline. For example, infrared laser spectroscopy has enabled rapid micro-chamber testing that can deliver formaldehyde readings in roughly 15 minutes without chemical reagents, creating an attractive option for laboratories seeking faster throughput and lower consumable costs. At the same time, advancements in sensor modularity and multi-gas platform design are making it easier for safety teams to add formaldehyde monitoring to existing field instruments rather than managing entirely separate devices.
This technological shift matters because it expands the addressable use cases for testing instruments. Faster results support more frequent quality control cycles in materials manufacturing. Modular sensors simplify exposure monitoring in facilities where multiple gases must be tracked simultaneously. And improved low-level detection capabilities give building and environmental professionals greater confidence in indoor air assessments. The practical effect is a market in which performance is no longer measured solely by accuracy, but also by turnaround time, workflow integration, and total cost of ownership.
Regulatory and Standards Environment
Regulatory activity continues to be one of the strongest structural drivers. Updates to emission standards and testing protocols for composite wood products, along with broader occupational exposure requirements, are compelling manufacturers, testing laboratories, and compliance teams to revisit their measurement methods. Recent proposals illustrate this direction. In February 2026, a regulatory proposal sought to update voluntary consensus standards for formaldehyde emission standards in composite wood products, incorporating new test methods including an updated international standard as an alternative quality control test method. Alongside that, broader updates to formaldehyde standards for composite wood products referenced the incorporation of revised ASTM and ISO test methods and introduced a new small-scale quality control chamber test method.
These developments create demand on multiple fronts. Manufacturers of wood-based and composite materials must ensure their testing workflows align with the latest recognized methods. Independent testing laboratories need instruments and chambers that can satisfy updated protocols and third-party certification requirements. And workplace safety teams must continue to meet occupational exposure monitoring expectations, including established accuracy thresholds for time-weighted average sampling. As standards evolve, the instruments that can most easily adapt to new methods gain a meaningful commercial advantage.
Demand-Side Shifts in Indoor Air Quality and Industrial Safety
Beyond formal regulatory mandates, demand is being shaped by changing expectations around air quality, worker safety, and consumer awareness. Public and professional attention to indoor environmental conditions has increased across both residential and commercial settings. Building operators, facility managers, and property developers are placing greater emphasis on documented air quality performance as part of broader sustainability, health, and occupant wellbeing goals. That emphasis is translating into more routine formaldehyde monitoring, especially in spaces where composite materials, adhesives, furnishings, or finishes may contribute to volatile organic compound levels.
In parallel, industrial and chemical safety programs are becoming more proactive. Rather than treating gas detection as a reactive compliance exercise, many organizations are integrating formaldehyde monitoring into broader exposure management systems. Portable multi-gas monitors with interchangeable formaldehyde sensors have gained relevance in this context because they allow safety teams to maintain a common operational platform while still addressing substance-specific risks. The result is a growing preference for instruments that can support both immediate hazard detection and longer-term exposure documentation.
Supply Chain and Cost Structure Considerations
The cost and availability of materials, sensors, and calibration support are also influencing market behavior. While formaldehyde testing instruments do not require the same scale of raw material inputs as heavy industrial equipment, they do depend on precision components, specialized sensor elements, and reliable consumables or calibration services. Organizations that can stabilize supply, localize support, and reduce recurring operational costs are better positioned to compete, particularly when buyers are comparing instruments on lifecycle economics rather than initial purchase price alone.
This dynamic is especially relevant for buyers who operate across multiple sites or regions. An instrument that offers strong specification performance may still lose out if calibration turnaround, replacement part availability, or technical support introduces unacceptable downtime. As a result, suppliers that build dependable service networks and transparent cost structures around their instruments are increasingly differentiating themselves in a market where functional specifications alone no longer guarantee adoption.
Competitive Landscape and Leading Strategies
The competitive environment in the formaldehyde testing instrument market is defined by a mix of established industrial manufacturers, specialized instrument developers, and companies with strong compliance-aligned product portfolios. The market remains moderately concentrated, with the top three players accounting for roughly 32.4% of total revenue and the top five reaching approximately 46.85%. That level of concentration suggests enough fragmentation to allow differentiated entrants, but also enough leadership presence to shape buyer expectations around reliability, compliance, and service.
Distinct Strategic Positions
Participation in the market is not uniform; leading companies have adopted different positioning strategies based on their technical strengths and target applications.
- 3M has built a recognizable presence in passive diffusive formaldehyde monitoring for personal and area sampling. Its monitor designs are aligned with established workplace accuracy expectations, making them relevant for healthcare, laboratory, and industrial exposure monitoring where standardized sampling and compliance documentation matter.
- Aero-Laser GmbH focuses on high-precision continuous measurement, offering analyzers suited to emissions monitoring, indoor air quality assessment, and laboratory or research applications. This positions the company closer to users who prioritize measurement continuity and analytical control over field portability.
- Fagus-GreCon has emphasized laboratory and inline formaldehyde emission testing from wood-based and other materials, with systems that align to widely recognized emission standards. Its product updates illustrate a push toward faster, chemical-free testing methods, reinforcing a strategy centered on throughput, protocol alignment, and materials testing compatibility.
- GrayWolf Sensing Solutions targets indoor air quality and environmental monitoring with advanced meters and probes designed for low-level formaldehyde detection and data logging. This places the company in a segment where usability, portability, and long-duration monitoring are particularly important.
- Honeywell, through its RAE Systems brand , offers portable multi-gas monitors that support interchangeable formaldehyde sensors. Its strength lies in integrating formaldehyde detection into broader multi-substance safety platforms, appealing to industrial users who value operational consistency across different hazard scenarios.
- Markes International develops sampling equipment such as microchamber samplers for dynamic headspace collection, often used with thermal desorption workflows. Its relevance stems from materials and automotive-related emissions testing, where method compliance and sample integrity are central.
- PPM Technology Ltd produces both portable and fixed formaldehyde monitors, targeting indoor air quality and toxic gas detection across varied environments. Its product breadth supports customers who need flexible deployment options rather than a single instrument class.
- RKI Instruments, Inc. provides gas detection instruments that include formaldehyde-capable models for safety monitoring in industrial and laboratory settings, reinforcing a practical, safety-oriented value proposition.
How the Landscape Is Evolving
Several patterns are shaping the future shape of competition. One is differentiation by measurement format. Some companies are strengthening their position in continuous, high-precision analytical systems, while others are expanding portable, field-ready portfolios. This division is likely to persist because the underlying customer needs differ: laboratory and compliance testing demand repeatability and protocol alignment, whereas field safety and building assessments value mobility, speed, and ease of use.
Another trend is the growing importance of method compatibility as a competitive asset. Instruments that can accommodate recognized chamber methods, micro-chamber testing, and updated standards without requiring extensive workflow changes are better placed to retain and expand their customer base. In a regulatory environment where test methods are being revisited and refined, flexibility is becoming as valuable as raw performance.
Market convergence is also emerging in the multi-gas safety segment, where formaldehyde capability is increasingly treated as one function within a broader exposure monitoring strategy. At the same time, divergence remains strong among organizations that specialize in materials emission testing or indoor air quality diagnostics. New entrants are most likely to succeed if they address a clearly defined gap, such as faster laboratory screening, more robust low-level field detection, or better integration between portable measurement and compliance documentation.
Smart Formaldehyde Detector Market
Forward Outlook: Strategic Trends for the Next Three to Five Years
Looking ahead, the market is likely to be shaped by a combination of regulatory refinement, technology adoption, and shifting procurement priorities. Three trends stand out.
1. Faster, More Integrated Testing Workflows Will Become a Baseline Expectation
The move toward rapid micro-chamber methods and chemical-free analysis is not a passing upgrade cycle; it reflects a broader expectation that testing should support faster decision-making. Laboratories and quality control teams increasingly want instruments that reduce waiting time without compromising method recognition or data quality. Over the next few years, products that combine rapid screening with established compliance alignment will have a stronger competitive position, particularly in materials manufacturing and third-party testing environments.
2. Compliance Adaptability Will Separate Mature Suppliers from Narrow Product Players
As test methods are revised and new alternative protocols are incorporated into updated standards, instruments and workflows that can adapt with minimal disruption will gain advantage. Buyers are likely to favor solutions that can support both current requirements and anticipated method changes, rather than tools locked into a single legacy approach. This favors suppliers that invest in method flexibility, documentation support, and service capabilities alongside hardware performance.
3. Indoor Air Quality and Exposure Management Will Expand the Commercial Base
Formaldehyde testing is increasingly embedded in broader indoor environmental quality programs and industrial exposure management systems. That broader context creates opportunities for instruments that can support routine monitoring, recordkeeping, and multi-substance safety workflows. It also increases the importance of usability and data handling, since the business value of testing often depends on how easily results can be interpreted, shared, and acted upon across facilities or projects.
Risks and Uncertainties
These opportunities are accompanied by real uncertainties. Regulatory timing can shift as standards undergo review, and method updates may require revalidation of existing workflows. Economic pressure on facility budgets could slow discretionary testing purchases, especially in segments where compliance is not the primary driver. In addition, the market may see variability in how quickly new rapid-testing approaches are accepted across different regions and application areas. Organizations should therefore plan for a landscape where demand growth is strong but not uniform, and where method alignment remains more important than any single hardware feature.
Actionable Guidance for Decision Makers
For organizations operating in or adjacent to this market, the strategic question is less about whether demand will grow and more about where to position capabilities and resources. A few practical priorities emerge.
For Manufacturers and Product Developers
- Prioritize method flexibility in product design so instruments can adapt to updated chamber, micro-chamber, and consensus standards without forcing customers to redesign their workflows.
- Invest in recurring value elements such as calibration support, consumables availability, and service responsiveness; in a moderately concentrated market, these often determine repeat purchases and long-term loyalty.
- Decide clearly whether to compete in high-precision continuous analysis, portable safety monitoring, or materials emission testing, rather than diluting resources across all three without a distinct positioning advantage.
For Investors
- Focus on companies whose revenue logic is tied to compliance adoption, faster testing throughput, or multi-gas integration, since these themes are more likely to support sustained demand than single-feature differentiation alone.
- Watch for consolidation signals among specialized testing suppliers and laboratories, especially where method compatibility and service networks create barriers for smaller players.
- Assess geographic exposure carefully; demand drivers differ by region, and product competitiveness often depends on local standards, support infrastructure, and procurement practices.
For Procurement and Operations Leaders
- Evaluate instruments on lifecycle performance, including method alignment, calibration turnaround, and documentation support, rather than initial specification sheets alone.
- Align purchasing decisions with upcoming compliance updates to avoid premature deployment of tools that may need replacement or revalidation as standards evolve.
- Where multi-site monitoring is required, favor platforms that can standardize workflows across locations while still meeting the specific detection needs of each environment.
The formaldehyde testing instrument market is moving from a compliance-driven niche toward a more diversified, performance-sensitive commercial space. That shift rewards organizations that can connect technical capability with regulatory adaptability, operational practicality, and clear application focus. For decision makers who need detailed segmentation data, company-level benchmarking, or tailored scenario planning, the full research report provides a deeper set of figures and structured analysis to support those decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Formaldehyde Testing Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global 9% Nickel Steel Plate Market to Hit $3.6B by 2032: Why LNG Storage Shift Drives 7.5% CAGR
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide 9% Nickel Steel Plate Market
Market Context and Core Challenges
The global market for 9% nickel steel plate has evolved into a structurally critical segment within the broader cryogenic and energy infrastructure supply chain. Over the historical period from 2020 to 2025, the market expanded from approximately $1.51 billion to $2.15 billion, reflecting sustained investment in liquefied natural gas (LNG) infrastructure and industrial cold-chain applications. Projections extending through 2032 indicate a continuation of this trajectory, with revenue expected to surpass $3.5 billion by the end of the forecast window. This growth path corresponds to a compound annual growth rate of roughly 7.5%, signaling a market that is out pacing broader steel segments and embedding itself deeper into long-cycle energy and industrial projects.
Despite the clear upward trajectory, the sector faces several structural friction points that decision-makers must navigate carefully. First, the reliance on nickel as the primary alloying element ties plate pricing and availability directly to a volatile commodity market. Nickel supply cycles, geopolitical trade dynamics, and competing demand from battery and stainless steel industries create periodic cost uncertainty for mill operators and downstream engineers. Second, the market exhibits pronounced regional concentration, with a handful of established heavy-plate producers in Europe and Asia controlling a significant share of high-quality cryogenic-grade output. This concentration restricts supply flexibility during peak project execution phases and raises the stakes for qualification timelines in new build programs. Third, regulatory and trade policy shifts are reshaping cross-border procurement strategies. Recent tariff reintroductions in key import markets have altered cost calculations for engineering, procurement, and construction firms, forcing earlier sourcing decisions and regional supply chain redesign.
These challenges do not diminish the market's long-term relevance; rather, they define the operational rules for competitive positioning. Organizations that treat 9% nickel plate procurement as a strategic variable rather than a simple materials purchase will be better positioned to manage cost volatility, secure mill capacity during bottleneck periods, and align sourcing with evolving code requirements and project phasing.
Key Drivers of Market Change
Technological Innovation and Metallurgical Substitution
Metallurgical advancement continues to reshape how engineers specify and deploy cryogenic-grade materials. Extended solidification control, controlled rolling and accelerated cooling, and vacuum treatment have improved the consistency of 9% nickel plates across wider thickness ranges and larger panel dimensions. At the same time, a notable innovation thread involves lower-nickel alternatives that aim to deliver equivalent fracture toughness at reduced alloy cost. Recent technical disclosures from leading producers emphasize TMCP-based steel plates with adjusted nickel content that approach the cryogenic performance of traditional 9% nickel grades while lowering raw material exposure. This direction matters because it expands the design space for tank and vessel engineers, potentially altering procurement specifications for new LNG storage projects and pressure vessel programs. For procurement teams, the practical implication is that material selection is no longer a binary choice between standard 9% nickel and cost-saving substitutes; it is becoming a spectrum where mechanical property guarantees, weldability, and total delivered cost must be evaluated together.
Policy and Regulatory Environment
Regulatory frameworks governing LNG containment and cryogenic service provide the baseline justification for 9% nickel plate demand. International code recognition of austenitic microstructures that retain fracture toughness at cryogenic temperatures has cemented the material's role in tank walls, fuel containment systems, and processing infrastructure. At the same time, trade policy is becoming an equally important driver of market behavior. The reinstatement of broad steel import duties in major markets has introduced a new layer of cost and sourcing complexity. Import-dependent projects now face higher landed costs and longer lead-time risk if mill capacity must be rerouted to alternative regions or if quotas and derivative provisions constrain eligible supply. For developers and EPC contractors, this regulatory shift elevates the importance of early mill engagement, localized qualification packages, and contingency planning for feedstock availability.
PW Consulting
Demand-Side Shifts Across LNG and Industrial Cryogenics
Demand for 9% nickel plate is anchored by LNG storage and transport infrastructure, but the application mix is diversifying. Large onshore LNG storage tanks remain a dominant consumption pathway, driven by terminal expansions, peak-shaving facilities, and regional energy security programs. Beyond storage, carrier vessels, fuel tank systems, and cryogenic pipelines and processing equipment contribute a growing share of requirements as LNG is integrated into power generation, industrial fuel switching, and maritime bunkering networks. On the industrial side, applications that require reliable performance at extremely low temperatures continue to pull specialty plate into pressure vessels and processing modules. The common thread across these demand streams is a preference for materials with documented impact toughness, predictable weld behavior, and certification documentation that satisfies classification societies and engineering standards bodies. This demand profile favors suppliers that can offer not only the plate itself but also traceability, inspection support, and application-specific technical guidance.
Supply Chain and Cost Structure Dynamics
Nickel feedstock dynamics sit at the center of the cost structure for 9% nickel plate production. Global nickel output is projected to reach approximately 2.5 million metric tons in 2026, and while this level suggests adequate baseline supply, the distribution of refined product, ore availability, and competing downstream demand create localized scarcity risks. Mills that operate integrated refining routes or secure long-term alloy supply arrangements hold a structural advantage in stabilizing plate pricing and delivery reliability. At the same time, logistics and regional tariffs affect total cost of ownership. A plate that appears competitive on a per-ton basis may become less attractive once freight, qualification lead times, and tariff exposure are factored into the project budget. The result is a market where cost competitiveness is increasingly defined by supply chain resilience, not just raw unit price.
Competitive Landscape and Leading Strategies
The 9% nickel steel plate market is characterized by a concentrated group of established heavy-plate manufacturers alongside a growing cohort of regional producers focused on LNG and cryogenic applications. European and Asian incumbents have built their positions on metallurgical expertise, large-format production capability, and documented performance in major LNG projects. Several of these firms produce plates across the thickness ranges and widths required for large tank fabrication, and they reinforce their market position with technical documentation that guarantees cryogenic impact properties and supports code compliance. This combination of material capability and application support creates a defensible advantage, especially for projects where structural integrity at extreme temperatures is non-negotiable.
Asian producers have expanded their relevance by aligning plate production with domestic and regional LNG build-outs, securing project-specific supply roles, and demonstrating quality systems that satisfy stringent cryogenic requirements. Chinese mills, in particular, have become embedded in project supply networks for major storage and vessel programs, leveraging scale, localized cost structures, and accreditation pathways recognized by classification societies. For some of these producers, the strategy is less about global brand visibility and more about reliable execution in project-critical supply slots. This model can be successful when paired with consistent metallurgical quality and responsive technical service.
Differentiation within the competitive set increasingly rests on three dimensions. The first is grade and property assurance. Producers that publish guaranteed transverse impact performance, provide weldability guidance, and offer plate varieties tailored to specific fabrication requirements reduce uncertainty for engineers and fabricators. The second is format flexibility. The ability to supply plates in thicknesses up to and beyond 40 millimeters, with controlled width envelopes and specialized thin-gauge options for large-scale tanks, opens access to more demanding design configurations. The third is supply stability. In a market where qualification cycles and project execution timelines are long, mills that maintain documentation continuity, support material traceability, and avoid disruptive quality issues earn repeat participation in follow-on phases and sister projects.
The competitive landscape is also evolving through incremental substitution and selective entry. Lower-nickel, TMCP-based alternatives are creating pressure on traditional 9% nickel specifications in certain applications, prompting incumbents to defend their positions with enhanced property documentation and cost-optimized processing routes. At the same time, specialized mills that focus on cryogenic accreditation and narrow application niches are finding room to serve regional demand and project-specific requirements. The market is therefore not converging into a single dominant model; it is fragmenting by application expertise, service depth, and regional supply strategy. Organizations evaluating supplier relationships should assess not only production capacity but also the supplier's ability to navigate code expectations, deliver consistent property guarantees, and provide the technical partnership that complex cryogenic projects require.
Ship Plate Market
Forward Outlook: Trends That Will Shape the Next Three to Five Years
The most consequential trend over the next several years will be the continued negotiation between material performance and cost efficiency. As LNG infrastructure expands and industrial cryogenic applications grow, designers and procurement teams will increasingly weigh guaranteed toughness against alloy cost. This will accelerate the adoption of lower-nickel and thermomechanically processed alternatives in select applications, while sustained demand for proven 9% nickel grades will keep the core segment robust. The net effect is a more nuanced specification environment where material selection is project-specific and value-engineered rather than standardized across all cryogenic uses.
Ferronickel Market
A second trend is the reinforcement of regional supply strategies in response to trade policy and project timing risk. As import duties and logistical constraints alter cross-border cost equations, developers and fabricators are likely to place greater emphasis on regional mill partnerships, localized qualification packages, and staged procurement that aligns with project phasing. This shift benefits suppliers with credible regional capacity and documentation readiness, while challenging those that depend heavily on long-distance shipment without sufficient cost and timeline buffers.
A third trend concerns the growing importance of technical service and certification support as a competitive differentiator. In cryogenic applications, the plate is only one element of a broader system that must satisfy design codes, inspection protocols, and classification requirements. Suppliers that bundle material supply with engineering support, impact property guarantees, and project-specific documentation will capture more influence over specification decisions. The commercial opportunity here is clear: value in this market is increasingly created through reduced execution risk and faster qualification cycles, not merely through tonnage pricing.
These trends carry inherent uncertainty. Nickel price volatility, changes in trade policy scope, and the pace of lower-nickel substitution can all shift the balance of advantage in either direction. Organizations that monitor these variables continuously and maintain flexible specification and sourcing strategies will be better equipped to convert market change into competitive leverage rather than cost exposure.
Strategic Considerations for Decision-Makers
For mill operators and material producers, the priority is to strengthen differentiation through documented property assurance and format flexibility. Investing in technical documentation that supports code compliance, providing weldability and fabrication guidance, and maintaining consistent quality across thick and thin gauges will reinforce repeat participation in large LNG and cryogenic programs. Producers should also evaluate how lower-nickel or TMCP-based options fit into their portfolios, positioning them as targeted alternatives rather than blanket replacements, so that engineering teams can select the right grade for each application.
For investors and strategic planners, the value lies in assessing exposure to nickel cost cycles, regional supply concentration, and policy-driven sourcing shifts. Portfolio decisions should account for the growing importance of application-specific technical capability and the risk that trade policy can alter the economics of cross-border plate supply. Companies with credible cryogenic documentation, established project supply relationships, and regional footprint resilience offer a more stable path through the market's structural volatility.
For procurement and engineering teams, early engagement with qualified suppliers is essential. Specification decisions should integrate total cost of ownership, including tariff exposure, logistics, qualification lead time, and inspection support, rather than relying on base plate pricing alone. Building contingency plans for mill capacity constraints and maintaining awareness of evolving code expectations will reduce schedule risk in large storage and carrier projects. For organizations seeking detailed segmentation data, regional and thickness-level breakdowns, and tailored sourcing or investment recommendations, the full PW Consulting industry study provides the structured detail needed to support those decisions.
For detailed analysis of this topic, please visit the official page: Worldwide 9% Nickel Steel Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Bio-engineered Stent Market: Why 8.12% CAGR Changes Everything
By PW Consulting, 2026-09-18
Global Bio-engineered Stent Market: Strategic Trends and Commercial Opportunities
The global bio-engineered stent market has entered a phase of mature expansion, characterized by steady revenue growth and evolving clinical standards. In 2025, the market reached an estimated revenue baseline of approximately $1,420 million, building on a consistent upward trajectory from 2020 through 2025. Projections for the 2026-2032 period indicate a compound annual growth rate of 8.12%, which would lift total market value to roughly $2,452 million by the end of the forecast window. This growth reflects both the expanding adoption of advanced coronary and peripheral interventions and the steady replacement of legacy bare-metal and first-generation drug-eluting platforms with next-generation bio-engineered designs.
Behind these headline figures lies a market structure defined by notable concentration and rapid technological iteration. A small group of dominant players accounts for a majority of global revenue, while regional performance remains uneven. North America and Europe continue to anchor substantial portions of total demand, supported by established reimbursement frameworks and high procedural volumes. Asia Pacific represents a rapidly scaling region, driven by expanding healthcare infrastructure and growing procedural capacity. Latin America and the Middle East and Africa contribute smaller but increasingly strategic shares, often serving as early adoption zones for cost-optimized and regionally tailored solutions. The application landscape remains heavily weighted toward coronary artery disease, though peripheral artery disease interventions are gaining incremental momentum as operator experience with bio-engineered platforms extends beyond coronary territories.
Despite the favorable growth trajectory, the industry faces several structural challenges that will shape competitive outcomes over the next decade. The first is the tension between clinical performance expectations and the economic realities of device procurement. Health systems are increasingly scrutinizing cost-per-procedure metrics, pushing manufacturers to demonstrate not only superior restenosis and thrombosis profiles but also measurable reductions in repeat interventions and downstream care costs. The second challenge is regulatory and post-market complexity. As bio-engineered stents are classified as high-risk devices, manufacturers must navigate rigorous premarket approval pathways and sustain long-term post-market surveillance commitments, which raises the barrier to entry and compresses the window for rapid product cycles. The third challenge stems from raw material and manufacturing constraints. Medical-grade bioabsorbable polymers and specialized coating technologies remain costly, and supply chain volatility can disproportionately affect margins for smaller manufacturers or novel entrants attempting to scale production. These pressures are not merely operational; they are reshaping who can compete, where value is captured, and how quickly innovation reaches the bedside.
Key Drivers of Market Change
Technology innovation remains the central engine of market evolution. The shift from permanent metallic scaffolds to bioabsorbable polymer platforms and biologically active surface modifications has redefined performance benchmarks. Modern bio-engineered stents increasingly rely on controlled drug-release kinetics, biodegradable polymer matrices, and endothelial-friendly surface engineering to reduce late inflammation and support vessel healing. These design improvements are not cosmetic; they directly address the clinical vulnerabilities that have historically limited long-term stent outcomes. Recent product milestones illustrate the direction of travel. Regulatory clearances and approvals for advanced everolimus-eluting platforms, bioabsorbable polymer systems, and complementary drug-coated balloon technologies have expanded the procedural toolkit for interventional cardiologists. At the same time, published long-term clinical data from flagship platforms have reinforced confidence in sustained vessel patency and reduced target lesion revascularization, strengthening the value proposition for bio-engineered designs over legacy alternatives.
Regulatory and reimbursement environments are equally influential in shaping adoption patterns. Because bio-engineered stents are regulated as Class III devices, market access depends on robust evidence packages that demonstrate safety and efficacy in reducing restenosis. This requirement favors companies with mature clinical research infrastructure and the ability to generate multi-year outcomes data. Reimbursement policy further determines how quickly hospitals can adopt new platforms. Payment structures for percutaneous coronary interventions establish per-procedure reimbursement ranges that influence budget allocation and procurement decisions. When reimbursement frameworks align with the cost profile of advanced stents, adoption accelerates; when they lag, hospitals may delay transitions or negotiate aggressively on pricing. The interaction between regulatory evidentiary demands and reimbursement economics creates a dual filter: innovation must be clinically credible and financially integrable to achieve scale.
Stent Grafts Market
Demand-side behavior is also shifting, driven by changing patient profiles and provider priorities. Aging populations and rising prevalence of coronary and peripheral vascular disease are expanding the addressable procedural base. At the same time, clinicians are placing greater emphasis on long-term outcomes rather than short-term procedural success alone. The decline of late thrombotic events and the desire for faster endothelialization have made bio-engineered platforms increasingly attractive in complex lesion subsets. Hospital procurement teams, meanwhile, are moving from volume-driven purchasing toward value-based evaluation, weighing total cost of care, complication rates, and inventory predictability. This shift rewards manufacturers that can offer consistent performance across diverse anatomies and provide data that supports downstream cost avoidance.
Supply chain and cost structure dynamics add another layer of strategic importance. The cost of medical-grade bioabsorbable polymers and specialized coating materials remains elevated due to stringent biocompatibility requirements and manufacturing precision. These input costs can create pricing rigidity, especially for premium platforms. At the same time, geopolitical and logistics pressures have reinforced the need for resilient sourcing and regional manufacturing redundancy. Companies that secure stable polymer supply, invest in scalable production, and optimize component sourcing can protect margins while offering more predictable pricing to health systems. For new entrants, the cost barrier is significant, but it also creates an opportunity for differentiated designs that achieve clinical parity with lower material complexity or more efficient manufacturing footprints.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a concentrated group of established manufacturers, each pursuing differentiated clinical and commercial positioning. Medtronic has emphasized controlled drug-release technology through bioengineered platforms that combine durable delivery with polymer systems designed to support predictable healing. Its strategic emphasis on long-term clinical evidence, including sustained outcome data from global trials, reinforces confidence in durability and restenosis reduction. Boston Scientific has focused on bioabsorbable polymer engineering that aims to promote endothelialization while reducing long-term inflammation, complementing this approach with adjacent technologies such as drug-coated balloons that broaden the intervention portfolio. Abbott Laboratories has built a strong position around everolimus-eluting platforms designed for biocompatible healing and low thrombotic risk, with newer iterations aimed at improving deliverability and lesion coverage. Terumo Corporation has advanced bioengineered drug-eluting stents that pair sirolimus-based therapy with biodegradable polymer design, targeting a balance of efficacy and vascular compatibility.
These companies are not competing solely on device performance; they are competing on evidence ecosystems, procedural integration, and market access readiness. A clear differentiator among leaders is the ability to present a complete clinical narrative that spans premarket approval, post-market surveillance, and real-world adoption support. Regulatory milestones such as premarket approvals and international certifications serve as gating events that validate clinical claims and unlock procurement pathways. Equally important are commercial strategies that reduce friction for hospitals, including streamlined logistics, training support, and data-sharing models that help operators demonstrate outcomes within their own institutions. In a concentrated market, these operational capabilities can be as decisive as product specifications.
The broader market structure appears to be evolving along two parallel paths. On one hand, consolidation is likely to continue as larger manufacturers seek to expand portfolios, broaden geographic reach, and capture more of the total procedure value chain. On the other hand, there is room for targeted differentiation by companies that can address specific clinical niches or regional cost constraints without attempting to match premium platforms across every dimension. New entrants face steep barriers because of regulatory burden, reimbursement complexity, and the dominance of incumbents with established relationships and long-term data. However, specialized innovations in polymer design, surface engineering, or delivery systems can still create entry points if they solve a clearly defined clinical or economic problem. The market is therefore unlikely to become commoditized quickly; instead, it will reward platforms that can demonstrate credible long-term outcomes, cost predictability, and procedural versatility.
Future Trends and Commercial Implications
Over the next three to five years, one of the most significant trends will be the increasing emphasis on long-term vessel healing and late-event reduction as primary value metrics. As clinical data mature, purchasers and clinicians will likely evaluate bio-engineered stents less on immediate procedural success and more on durability, endothelial recovery, and the reduction of repeat interventions. Platforms that can document sustained outcomes across diverse patient populations and lesion types will gain preferential positioning in formulary decisions and procurement negotiations.
Cardiac Stent Market
A second trend will be the gradual expansion of bio-engineered stent use into broader peripheral vascular applications and more complex coronary anatomies. As operator confidence grows and delivery systems improve, the addressable market will extend beyond straightforward lesions into segments that historically relied on alternative interventions. This expansion creates opportunities for manufacturers that can adapt platform designs to greater flexibility, radial strength, and deliverability without compromising biocompatibility. It also opens the door for combination strategies, where stents and complementary devices are used in coordinated treatment pathways rather than as isolated product choices.
A third trend involves growing pressure to align innovation with healthcare cost containment. Hospitals will continue to demand transparent evidence of economic value, not just clinical superiority. This may drive more structured outcome reporting, health economics analyses, and risk-sharing procurement models. At the same time, reimbursement environments and regulatory expectations may evolve, creating uncertainty around timing and adoption pacing. Manufacturers that proactively integrate economic evidence with clinical data will be better positioned to navigate price negotiations and formulary inclusion. The principal risk is that cost pressure could slow the adoption of premium platforms if the perceived incremental benefit does not justify the price differential in specific market segments.
Strategic Actions for Decision-Makers
Manufacturers should prioritize evidence generation and market-access readiness as core strategic assets. Building multi-year clinical data, strengthening post-market surveillance capabilities, and aligning product roadmaps with reimbursement realities will be essential to preserving pricing power and competitive differentiation. Innovation should be focused on measurable clinical benefits and cost predictability, rather than incremental feature upgrades that do not translate into adoption advantage.
Investors should evaluate companies based on their ability to sustain long-term outcome credibility, manage material and supply chain costs, and expand into adjacent procedural categories without diluting execution focus. Platforms with strong regulatory momentum, clear reimbursement alignment, and supportive real-world evidence are better positioned to capture share through the forecast period. Portfolio breadth and procedural integration can also serve as indicators of resilience in a concentrated market.
Procurement leaders and hospital decision-makers should treat bio-engineered stent selection as a total-cost-of-care decision rather than a unit-price comparison. Evaluating platforms on long-term complication risk, inventory predictability, and operator support can yield better outcomes and reduce downstream spend. Ongoing access to detailed segmentation data, regional pricing dynamics, and competitive benchmarking can improve negotiation leverage and demand planning. For organizations seeking deeper visibility into submarket dynamics, detailed regional breakdowns, type- and application-level demand patterns, and customized strategic scenarios are available in the full PW Consulting market study.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Bio-engineered Stent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oral Tissue Adhesives: Why 8.12% CAGR and Dental Surgery Shift the Market
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Oral Tissue Adhesives Market
Market Overview and Core Challenges
The global oral tissue adhesives market has demonstrated consistent expansion over the past half-decade, evolving from a niche adjunct in surgical procedures to a recognized standard in various dental and oral healthcare applications. By 2025, the market reached a valuation of approximately USD 580.45 million, growing steadily from USD 390.12 million in 2020. This trajectory reflects a compound annual growth rate of 8.12%, with projections indicating the market will surpass the USD 1 billion threshold by 2032. This growth is not merely a reflection of increasing patient volumes but signifies a structural shift in how oral surgical wounds are managed, driven by the demand for faster recovery times and improved procedural efficiency.
Worldwide Bioadhesives Market
Despite the positive momentum, the industry stands at a critical juncture defined by several pressing challenges. One significant hurdle is the regulatory complexity surrounding medical device classification. As cyanoacrylate-based products are formulated specifically for intraoral biocompatibility, manufacturers must navigate stringent quality management systems and regional approval processes that vary considerably across jurisdictions. Maintaining compliance while scaling production adds operational overhead that can stifle agility for smaller players.
Worldwide Denture Adhesives Market
Another challenge lies in the balance between performance and safety. While high-viscosity formulations offer controlled application and effective wound stabilization, there is an ongoing industry-wide focus on ensuring these adhesives do not impede natural healing processes or cause adverse tissue reactions. The formulation chemistry itself presents a technical barrier; optimizing blended octyl and butyl cyanoacrylate compositions to maximize adhesion strength while minimizing inflammation requires continuous research and development investment.
Finally, market concentration remains a defining characteristic of the current landscape. With the top three companies controlling over 42% of the market share and the top five accounting for nearly 58%, the environment is moderately consolidated. This concentration creates high barriers to entry for new competitors but also pressures incumbent firms to innovate continuously to defend their positioning against potential disruptive technologies or specialized niche entrants.
Key Drivers of Market Change
Several interconnected factors are propelling the growth and evolution of the oral tissue adhesives sector. Understanding these drivers is essential for stakeholders aiming to capitalize on emerging opportunities.
Technological Innovation and Formulation Breakthroughs
Advancements in material science are central to the market's expansion. The development of high-viscosity variants, such as the 90HV formulations, allows for precise application in periodontal surgical procedures where controlling flow is critical. These innovations address specific clinical needs, such as securing sutures, stabilizing grafts, and protecting wound sites without the risk of runoff into unintended areas. Furthermore, the shift toward blended cyanoacrylate formulations optimizes performance for the unique environment of the oral cavity, balancing adhesion speed with flexibility. Recent clinical evaluations, such as ongoing trials assessing wound healing and patient-reported outcomes with high-viscosity bioadhesives for flap closure, underscore the industry's focus on evidence-based performance. This commitment to clinical validation enhances confidence among practitioners and accelerates adoption rates.
Regulatory Environment and Quality Standards
The regulatory landscape acts as both a gatekeeper and a quality signal. Compliance with standards such as ISO 13485 for quality management systems has become a baseline expectation for manufacturers supplying medical-grade adhesives. Products like PeriAcryl® Oral Tissue Adhesive maintain such certifications, signaling reliability to healthcare providers. As regulations tighten around biocompatibility and material safety for intraoral applications, manufacturers with robust quality systems gain a competitive advantage. This environment favors established players who have already invested in compliance infrastructure, while simultaneously raising the bar for new entrants who must demonstrate equivalent safety and efficacy profiles to gain market access.
Shifts in Demand and Clinical Preferences
On the demand side, there is a growing preference for minimally invasive procedures and faster postoperative recovery. Oral tissue adhesives support these goals by reducing bleeding, stabilizing tissues, and protecting surgical sites, which can lead to improved patient comfort and reduced healing times. Dental surgeons and periodontists are increasingly integrating these adhesives into standard workflows for procedures ranging from flap closure to graft stabilization. This behavioral shift among practitioners is reinforced by patient expectations for treatments that minimize downtime and discomfort. As the value proposition of adhesives becomes clearer through real-world outcomes, adoption expands across both complex surgical cases and routine orthodontic or periodontal interventions.
Supply Chain and Cost Structure Dynamics
Cost structures in the medical device sector are influenced by raw material availability and manufacturing efficiency. The production of cyanoacrylate adhesives relies on specific chemical precursors, and fluctuations in supply chains can impact margins. However, the trend toward standardized kits and multi-use options helps amortize costs and improve accessibility for clinics. Companies that optimize their supply chains to ensure consistent availability of high-quality formulations while managing production costs are better positioned to maintain competitive pricing without compromising on safety or performance. Additionally, as demand grows in diverse geographic regions, localization of distribution networks becomes a strategic lever to reduce logistics costs and improve service levels.
Competitive Landscape and Leading Strategies
The competitive environment in the oral tissue adhesives market is characterized by a mix of specialized manufacturers and distributors, with a notable concentration around key product lines. Understanding the strategic positioning of major players provides insight into how value is captured and defended in this space.
Strategic Positioning and Differentiation
GluStitch Inc., based in Delta, British Columbia, stands out as a primary innovator and manufacturer. Their focus on the PeriAcryl® Oral Tissue Adhesive line, including high-viscosity variants, demonstrates a strategy centered on product specialization for periodontal surgical procedures. By maintaining ISO 13485:2016 certification, GluStitch reinforces its commitment to quality management, which serves as a key differentiator in a market where safety and reliability are paramount. Their formulation approach, utilizing blended octyl and butyl cyanoacrylate optimized for oral cavity performance, highlights a deep technical understanding of the application environment.
Distribution partners and related entities such as DoWell Dental Products, Inc. and AD Surgical play a crucial role in expanding market reach. DoWell Dental Products distributes high-viscosity multi-use kits, catering to oral surgery applications like flap closure and wound protection. AD Surgical offers similar high-viscosity options for oral and implant surgery, focusing on securing sutures and stabilizing tissues. Blacklock Medical Products also contributes to the landscape by supplying PeriAcryl® products, noted for their status as top-selling dental cyanoacrylates worldwide. These companies often leverage established distribution networks and clinical relationships to drive adoption, complementing the manufacturing expertise of primary innovators.
Market Evolution and Entry Dynamics
The market structure suggests a trend toward consolidation among successful niche players, while also leaving room for specialized entrants who can address specific unmet needs. The presence of multiple entities distributing or offering variations of the same core technology indicates a fragmented downstream landscape even where upstream manufacturing may be concentrated. New entrants typically face the challenge of overcoming the reputation and compliance advantages held by incumbents. However, opportunities exist for companies that can introduce novel delivery mechanisms, improve ease of use, or provide compelling clinical data that differentiates their offerings. The recent clinical study activity, such as the evaluation of wound healing outcomes with new bioadhesive formulations, signals that innovation continues to be driven by a focus on patient outcomes, which can reshape competitive dynamics if new data supports superior performance.
Overall, the competitive landscape rewards those who combine technical formulation expertise with robust quality systems and effective distribution channels. Differentiation is increasingly achieved through clinical validation and specialized product variants that address specific procedural requirements, rather than solely on price competition.
Future Trends and Outlook
Looking ahead to the next three to five years, several key trends are likely to shape the trajectory of the oral tissue adhesives market. These trends present both opportunities for growth and risks that require strategic management.
1. Expansion of Clinical Evidence and Indications. As ongoing clinical trials continue to generate data on wound healing, patient-reported outcomes, and procedural efficiency, the body of evidence supporting the use of high-viscosity cyanoacrylate adhesives will expand. This trend is expected to broaden the range of accepted indications and reinforce confidence among clinicians. Commercial opportunities lie in leveraging this evidence to support educational initiatives, training programs, and marketing efforts that highlight specific clinical benefits. However, there is a risk that negative or inconclusive results from trials could slow adoption for specific formulations or applications, requiring manufacturers to manage expectations and communicate transparently.
2. Regional Growth Divergence. While North America and Europe currently hold significant market shares, the Asia Pacific region represents a substantial growth engine driven by increasing healthcare access and dental procedures. Over the forecast period, regional dynamics will diverge based on regulatory maturity, healthcare infrastructure, and local competitive activity. Companies that can tailor their go-to-market strategies to regional nuances, including adapting to local regulatory requirements and forming strategic partnerships, will capture disproportionate value. The risk here involves underestimating local competition or misjudging the pace of regulatory approval in emerging markets, which can delay market entry and revenue realization.
3. Technological Refinement and Material Science Advances. Continued investment in material science is likely to yield adhesives with improved biocompatibility, controlled degradation profiles, or enhanced handling characteristics. Innovations may focus on reducing postoperative sensitivity or improving adhesion durability in wet environments. This trend creates opportunities for product line extensions and premium positioning. However, the uncertainty lies in the translation of laboratory innovations to commercially viable products that meet cost and manufacturing scalability requirements. Balancing R&D investment with commercial pragmatism will be critical for sustaining long-term growth.
Actionable Insights for Decision Makers
For manufacturers, the priority should be strengthening clinical validation and quality certifications to differentiate in a concentrated market. Investing in high-viscosity formulations and specialized kits that address specific procedural pain points can reinforce market positioning. Additionally, exploring strategic partnerships with distributors in high-growth regions can accelerate expansion while mitigating local entry risks.
Investors should focus on companies with robust quality management systems and a pipeline of clinically supported innovations. The market's growth trajectory favors players who can demonstrate consistent product performance and navigate regulatory landscapes effectively. Monitoring clinical trial outcomes and regional adoption rates will provide early signals of shifting competitive dynamics and potential valuation drivers.
Procurement leaders and healthcare providers should evaluate adhesives based on total procedural value rather than unit cost alone. Factors such as ease of application, wound protection efficacy, and impact on patient recovery times contribute to overall outcomes and operational efficiency. Engaging with suppliers that offer comprehensive technical support and evidence-based product information can help optimize purchasing decisions and improve clinical results.
PW Consulting
As the market continues to evolve, accessing detailed segmentation data, competitor benchmarking, and customized strategic recommendations becomes increasingly valuable for making informed decisions. Comprehensive research reports provide the granular insights needed to navigate complexity, identify specific growth avenues, and refine execution strategies in this dynamic sector.
For detailed analysis of this topic, please visit the official page: Worldwide Oral Tissue Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
False Twist Texturing Machine Market: Why 6.45% CAGR Through 2032 Reshapes Fiber Strategy
By PW Consulting, 2026-09-18
Strategic Shifts in the False Twist Texturing Machine Market: Navigating Growth, Innovation, and Competitive Dynamics
Market Current State and Core Challenges
The global false twist texturing machine market has demonstrated consistent expansion over the past half-decade, with overall valuation crossing the USD 2.2 billion threshold in 2025 and maintaining a compound annual growth rate of approximately 6.45 percent through the 2032 forecast horizon. This trajectory reflects sustained capital expenditure in yarn processing infrastructure, driven by evolving textile demand, capacity modernization, and the continuous push toward higher-speed, more flexible production lines. The market's steady rise from roughly USD 1.42 billion in 2020 to the current level underscores how false twist texturing has transitioned from a mature, commoditized segment into a strategically vital node within synthetic yarn manufacturing.
Despite this favorable backdrop, the industry stands at a critical juncture shaped by several converging pressures. The first is the intensifying volatility in raw material economics. Polyester partially oriented yarn, the primary feedstock for false twist texturing, has experienced pronounced price swings tied to feedstock dynamics and regional oversupply cycles. These fluctuations directly compress margins for machinery operators and complicate ROI calculations for new equipment investments, forcing manufacturers to reassess payback timelines and financing structures.
The second challenge lies in the technological and operational expectations placed on modern lines. Buyers increasingly demand machines that balance high throughput with energy efficiency, precise temperature control, and rapid changeover capabilities. Legacy equipment configured for single-product runs struggles to meet these requirements, creating a structural divide between facilities that can accommodate agile, multi-count production and those locked into rigid, cost-heavy setups. The pressure to upgrade or retrofit is not merely a performance issue; it is becoming a competitive necessity as downstream textile mills prioritize consistency, elasticity control, and yarn hand feel.
PW Consulting Automotive & Machinery Research Center
The third challenge emerges from regulatory and safety standardization. Updated machinery safety frameworks, including the EN ISO 11111-4 specification for textile processing equipment, are reinforcing compliance expectations across design, operation, and maintenance. While these standards ultimately benefit operational safety and market credibility, they raise the technical bar for manufacturers and can slow deployment cycles for smaller producers lacking in-house engineering capacity to align with evolving certification requirements.
Air Jet Weaving Machines Market
Together, these dynamics are reshaping how market participants approach capacity planning, technology adoption, and risk management. The trajectory ahead will favor organizations that can translate these pressures into procurement discipline, modular equipment strategies, and proactive engagement with upstream and downstream partners.
Key Drivers of Market Transformation
The evolution of the false twist texturing machine market is being propelled by several interlocking forces that extend beyond simple capacity additions. Understanding these drivers is essential for anticipating where investment, innovation, and strategic positioning will concentrate over the next several years.
Tufting Machine Market
Technological Innovation and Equipment Differentiation
A defining feature of recent market development is the shift toward modular, individually driven, and thermally precise machine architectures. Leading designs now emphasize independent drive control per spindle or zone, enabling operators to adjust tension, speed, and heat profiles with greater granularity. This level of control is particularly valuable for fine to coarse count processing, where elasticity, crimp uniformity, and handling characteristics must be tuned to specific downstream applications. High-temperature capability, advanced PLC-based temperature regulation, and optional features such as interlacing nozzles further expand the functional range of a single machine platform. These innovations reduce the need for separate lines dedicated to different yarn specifications, lowering total footprint and improving asset utilization.
Complementing hardware evolution is the adoption of models tailored to smaller and specialized production environments. Compact false twist texturing systems designed for pilot runs, innovation centers, and master batch producers are gaining relevance as textile research, custom yarn development, and specialty applications require accessible, flexible processing capacity. The modular nature of these systems supports rapid reconfiguration and accelerates learning cycles for new yarn structures.
Policy, Standards, and Regional Regulatory Alignment
Regulatory clarity and international standards harmonization are exerting a quiet but influential pull on equipment design and market access. Machinery safety specifications that address textile processing equipment are encouraging consistent engineering practices around guarding, thermal management, and operator interfaces. For manufacturers, compliance is increasingly a baseline expectation rather than a differentiator, which means the competitive edge shifts toward reliability, serviceability, and integration with broader plant safety systems. Regions with strong export orientation are particularly sensitive to these standards, as they affect not only domestic acceptance but also the ability to supply equipment into markets that reference aligned safety frameworks.
Demand-Side Shifts in Synthetic Yarn Usage
The demand profile for false twist texturing remains anchored in polyester processing, but the underlying application mix is gaining complexity. Synthetic yarns are being specified for broader ranges of apparel, technical textiles, and performance garments, where elasticity, surface texture, and consistency directly affect end-product quality. As downstream mills seek to reduce lot variability and improve dye uptake uniformity, the precision of the texturing step becomes more consequential. This demand-side pressure incentivizes producers to invest in machines that deliver repeatable output across count ranges and elasticity settings, reinforcing interest in flexible, high-speed platforms.
Demand volatility in certain synthetic segments also shapes procurement behavior. When polyester POY pricing softens due to regional oversupply, some producers accelerate equipment upgrades to capture cost advantages and improve throughput efficiency while input prices are favorable. Conversely, when feedstock costs rebound, capital spending can tighten, shifting focus toward retrofits, efficiency improvements, and selective capacity additions rather than broad fleet expansion.
Supply Chain, Licensing, and Cost Structure Evolution
The market's cost structure is being influenced by how machinery rights, manufacturing capabilities, and regional production are organized. Patent-based licensing arrangements have emerged as a meaningful mechanism for expanding technology reach in key geographies. Exclusive manufacturing and commercialization rights for specific false twist texturing machine models allow local producers to offer advanced designs while leveraging established intellectual property. This model can accelerate regional adoption, shorten supply chains for spare parts and service, and adapt equipment to local operating conditions and labor profiles.
At the same time, raw material price trends remain a persistent variable in total cost of ownership calculations. Polyester POY pricing has shown downward movement in certain periods amid oversupply, while other intervals have seen upward pressure driven by feedstock costs such as PTA and MEG. These swings affect both machine utilization economics and the timing of capital deployment. Producers are increasingly factoring feedstock trajectory into equipment selection, favoring platforms that can maintain efficiency and quality across a wider input cost environment rather than optimizing solely for a single price regime.
Competitive Landscape and Leading Strategies
The competitive environment in false twist texturing machinery is characterized by a mix of established technology leaders, regional manufacturing specialists, and targeted licensing partnerships. Market concentration, with the top three and top five participants holding substantial share, indicates that scale, technology credentials, and service networks matter significantly. Yet the landscape is not static; differentiation is increasingly defined by how companies align product range, regional presence, and strategic partnerships with the needs of distinct buyer segments.
Technology-Led Positioning in Fine to Coarse Processing
A Swiss-based manufacturer offers a portfolio of false twist texturing machines built around individual drives and modular design, targeting premium DTY production across a broad count range. This approach signals a strategic emphasis on flexibility and high-speed output without sacrificing control precision. By enabling operators to manage multiple specifications on a single platform, such designs address the demand-side need for count agility and consistent yarn characteristics. Participation in major trade events further reinforces visibility and technical credibility, positioning the company as a reference point for buyers seeking proven, high-performance configurations.
High-Speed Regional Manufacturing and Feature-Forward Offerings
A Chinese machinery maker has focused on high-speed false twist texturing equipment designed to convert POY into DTY with both low and high elasticity options. Its product lineup includes features such as optional interlacing nozzles, biphenyl heating, and PLC temperature control, highlighting a strategy of delivering functionally rich platforms tailored to throughput and operational control. Exhibition launches and regional trade show presence have been used to intensify engagement with domestic and neighboring markets, where demand for cost-competitive, feature-dense machines continues to grow. This path reflects a broader trend in which regional manufacturers expand their competitive reach by combining speed, feature flexibility, and localized support.
Specialized and Compact Platforms for Niche Applications
Another Swiss producer has developed false twist texturing equipment optimized for small and medium scale production, with particular relevance for innovation centers, universities, and master batch producers. High-temperature capability and modular design support experimentation and specialized processing needs. This strategy demonstrates how false twist texturing is not solely a mass-production story; accessible, reconfigurable systems create value for R&D-intensive users and producers of specialty batches. By serving this segment, manufacturers can diversify their customer base while reinforcing technical leadership in application-specific solutions.
Licensing Strategies and Geographically Targeted Access
A German technology organization has advanced its market reach through patented false twist texturing machine designs, including models developed under its eAFK lineage, and has pursued licensing arrangements that enable manufacturing rights in specific regions. In parallel, an Indian engineering firm holds an exclusive license to manufacture and commercialize patented false twist texturing technology within its home market, offering high-productivity DTY configurations. This licensing dynamic illustrates how intellectual property can be deployed to localize advanced capacity, reduce lead times, and adapt equipment to regional operating contexts. It also suggests a competitive pattern in which global innovators and regional licensees coordinate to balance technology protection with market expansion.
Strategic Implications and Landscape Evolution
Taken together, these profiles reveal a market where differentiation is increasingly multidimensional. Leaders are not competing on throughput alone; they are aligning modular architecture, count flexibility, safety compliance, and regional support models to capture distinct segments. The trend points toward continued consolidation of technology credentials among established players, while regional manufacturers and licensees expand their footprint through feature-rich platforms and localized production. New entrants face a meaningful barrier in proprietary designs, safety certification, and service infrastructure, but opportunities remain for companies that can address underserved applications, offer strong retrofit and upgrade paths, or partner effectively to access protected technologies in specific geographies.
Future Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to shape the false twist texturing machine market and define where commercial value is created.
Trend One: Modular, Multi-Specification Platforms Will Become the Default Expectation
As downstream textile requirements grow more varied and changeover frequency increases, equipment that can seamlessly adapt across count ranges and elasticity settings will be increasingly preferred. Machines with individual drive control, precise thermal regulation, and modular components will enable producers to run diverse specifications without dedicating separate lines. The commercial opportunity here lies in equipment that reduces total installed footprint, improves asset utilization, and shortens setup time, thereby lowering operating costs while expanding product flexibility.
Trend Two: Licensing and Regional Manufacturing Will Deepen Market Access
Patent-based licensing arrangements are likely to continue as a practical route for expanding advanced technology availability in key regions. Local manufacturing of licensed models can shorten delivery cycles, improve after-sales support, and adapt equipment to regional feedstock and labor conditions. For investors and manufacturers, this trend creates opportunities in partnerships, localized production capabilities, and service networks that complement the equipment itself. The risk is that licensing terms, intellectual property boundaries, and regional compliance requirements must be managed carefully to avoid exposure to disputes or uneven market access.
Trend Three: Energy Efficiency, Safety Compliance, and Retrofit Economics Will Influence Purchase Decisions
With raw material pricing subject to cyclical swings and safety standards becoming more firmly embedded in procurement criteria, buyers will increasingly weigh total cost of ownership over initial price alone. Energy-conscious design, maintainability, and the ability to retrofit older lines for better control and throughput will shape purchasing behavior. The opportunity for suppliers is to offer upgrade paths and service-led value propositions that extend equipment life and improve performance without requiring full replacement. The risk lies in underestimating the operational burden of compliance and feedstock volatility; machines that are not designed with flexibility and serviceability in mind may face longer payback periods in fluctuating markets.
Strategic Recommendations for Decision-Makers
For machinery manufacturers and equipment suppliers , prioritize modular architectures that balance speed with count and elasticity flexibility. Align product roadmaps with safety and compliance expectations early in the design process, and develop clear retrofit and upgrade offerings that help existing users improve efficiency without full replacement. Where appropriate, explore licensing or partnership structures that can extend technology reach into high-potential regions while protecting core intellectual property.
For investors and strategic financiers , focus on segments where flexibility, service density, and regional manufacturing capabilities create defensible positions. Capital deployment should account for feedstock volatility by favoring assets and business models that can sustain performance across input cost cycles. Licensing-linked ventures can offer growth potential, but diligence must cover IP scope, exclusivity terms, and the operational capacity to deliver reliable service and spare parts locally.
For textile producers and procurement leaders , treat false twist texturing equipment as a strategic enabler of product flexibility and quality consistency rather than a purely cost-driven purchase. Evaluate platforms based on changeover speed, thermal precision, and the ability to handle a range of counts and elasticity profiles. Time major purchases with feedstock trends in mind, and consider phased upgrades or retrofits when capital conditions are constrained. Building a clear picture of technology options, compliance requirements, and regional supply capabilities will improve procurement outcomes.
Detailed segmentation data, competitive benchmarks, and region-specific procurement guidance are available in the full research report, which provides the granular breakdown needed to translate these strategic directions into actionable plans.
For detailed analysis of this topic, please visit the official page: False Twist Texturing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


