



Medical Computer Cart Market 2026: Why 6.98% CAGR and Mobility Trends Reshape Healthcare IT Infrastructure
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Medical Computer Cart Market
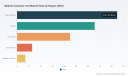
The medical computer cart market has moved from a niche peripheral category to a foundational component of point-of-care infrastructure. Between 2020 and 2025, the sector grew from approximately $163.15 million to $215.0 million in annual revenue, reflecting an accelerated adoption curve driven by digital Records, bedside workflows, and hybrid care models. Looking ahead through 2032, the market is projected to expand at a compound annual growth rate of 6.98%, reaching $344.8 million by the end of the forecast period. This trajectory reflects more than incremental device replacement; it captures a structural re-architecture of how clinical teams interact with technology at the bedside, in imaging suites, and during virtual encounters.
For executives and investors, the outline signals a maturing but still expanding category with concentrated leadership, clear compliance guardrails, and evolving clinical demands. The growth is not uniform across all use cases or geographies. Rather, it is being shaped by the convergence of workflow digitization, safety certification requirements, and the operational need for mobile, battery-enabled computing stations that can move seamlessly across care environments. The market is large enough to attract specialized entrants, yet concentrated enough that established players with strong certification footprints and integration-ready designs continue to set the pace.
Market Snapshot and Core Challenges
The revenue path through 2032 indicates steady expansion with a notable inflection in the mid-2020s, when the market crossed the $200 million threshold and sustained momentum into the late 2020s. By 2032, total revenue is expected to approach $345 million, a level that underscores the category’s transition from optional mobility accessories to integral clinical workflow platforms. This growth is underpinned by recurring institutional procurement cycles, the need to replace aging carts with smarter, safer alternatives, and the broader digitization of bedside documentation, medication administration, and tele-consultation workflows.
Several structural challenges and inflection points are shaping the market’s next phase.
- Regulatory and certification compliance as a market gatekeeper. Electrical safety standards such as UL/EN/IEC 60601-1 and quality management frameworks like ISO 13485:2016 have become baseline expectations for active manufacturers. Products that integrate powered systems or diagnostic accessories increasingly require 510(k) clearance, adding time and cost to development cycles. Compliance is no longer a differentiator; it is the price of entry, which elevates the importance of proven engineering and documentation capabilities.
- Reimbursement ambiguity and procurement cycles. While mobile carts are often covered under durable medical equipment and physician fee schedule categories, there are no specific new CPT or DRG updates that directly target the cart category beyond standard electronic health record infrastructure billing. This means purchase decisions are typically tied to broader hospital IT modernization budgets and workflow efficiency narratives, making adoption sensitive to capital planning cycles and internal ROI framing.
- Workflow integration versus device proliferation. As hospitals deploy more mobile computing stations, the challenge shifts from acquiring hardware to integrating it into clinical workflows without adding friction. Carts that are not optimized for battery management, ergonomic adjustment, antimicrobial protection, or seamless mounting of imaging and telehealth peripherals can become underutilized assets. Procurement teams increasingly evaluate carts as workflow platforms rather than standalone terminals, pressuring manufacturers to deliver systems that reduce cart replacement frequency and align with infection control protocols.
These dynamics create a market where technical readiness, compliance documentation, and real-world usability converge as decision criteria. The result is a category that rewards manufacturers with integrated power systems, proven safety certifications, and designs that adapt to varied clinical settings, while filtering out less differentiated offerings.
Key Drivers of Market Evolution
The market’s growth is being propelled by a combination of technological breakthroughs, regulatory shaping, demand-side behavior changes, and supply-side cost dynamics. Each driver reinforces the others, creating a compounding effect on adoption and product sophistication.
Technological Innovation and Workflow Enablement
The most visible driver is the shift from passive computer stands to intelligent mobile workstations that combine battery management, height adjustability, integrated power systems, and mounting flexibility for cameras, tablets, and imaging peripherals. Recent product movements illustrate this trajectory. In early 2024, a leading telehealth cart platform was updated with integrated camera positioning and device mounting capabilities designed for remote consultations, reflecting the broader expansion of virtual care into bedside and clinic workflows. Around the same time, upgraded workstation carts with integrated battery management systems were introduced to support bedside digital documentation, addressing a persistent pain point around uptime and mobility during long shifts. By early 2025, broader exhibitions of mobile mounts, power systems, and medical carts at major health IT conferences signaled that the category is increasingly presented alongside complementary infrastructure rather than as isolated hardware.
Metabolic Cart Market
These innovations matter because they reduce the operational burden on clinical teams. Battery systems that provide clear charge indicators and reliable runtime diminish downtime and cart swapping. Height-adjustable designs improve ergonomics for both clinicians and patients across varied tasks. Antimicrobial coatings and robust power architectures support infection control and safety requirements. In combination, these features turn the cart from a simple mount into a workflow enabler that can host electronic prescribing, medication administration, and point-of-care documentation without disrupting movement through rooms, bays, and imaging areas.
Policy, Regulation, and Certification as Market Architects
Regulatory and certification requirements are shaping product design and competitive entry. Electrical safety standards for powered systems, quality management expectations for healthcare manufacturing, and, where relevant, premarket notification for diagnostic accessories or powered patient-care configurations create a compliance environment that favors established engineering processes. This environment is reinforcing a market where manufacturers that maintain ISO 9001:2015 and ISO 13485:2016 certifications across design, manufacturing, and service are better positioned to win institutional trust and multi-year contracts.
At the same time, reimbursement structures remain tied to broader electronic health record infrastructure billing rather than to the cart category itself. This does not constrain demand, but it does influence procurement logic: purchasing decisions are more likely to be justified through operational efficiency, error reduction, and bedside documentation improvements than through direct device-level reimbursement. As a result, the policy environment rewards vendors that can articulate clear workflow benefits, demonstrate compliance readiness, and support standardized integration with existing clinical systems.
Demand-Side Shifts in Clinical and Care Delivery Models
Clinical demand is evolving as hospitals and ambulatory providers expand hybrid care, mobile documentation, and bedside digital workflows. Workstations on wheels are increasingly used for medication management, bedside documentation, and virtual consultations, while also supporting imaging workflows that require adjustable ergonomics and reliable power. The rise of remote consultations and point-of-care electronic records has made mobile computing stations more than convenience items; they are becoming essential for care teams that must move between rooms while maintaining continuous access to patient information and communication tools.
This demand shift is also visible in the prominence of hospital and clinic settings as primary application areas, alongside ambulatory surgical centers and other care environments. Facilities are looking for carts that can adapt to varied clinical contexts, from acute care and imaging to outpatient procedures and telehealth. The result is a demand profile that values versatility, durability, and integration potential over narrowly specialized form factors.
Medical Panel PC Market
Supply Chain and Cost Structure Dynamics
Supply-side conditions are influencing both product design and commercial strategy. Lead times, component availability, and the cost of certification and compliance activities affect development cycles and pricing. Manufacturers that can offer multi-year warranties, consistent power system performance, and clear service support are better equipped to manage total cost of ownership arguments with procurement teams. Meanwhile, the emphasis on antimicrobial coatings, integrated power, and ergonomic adjustments adds value but also requires disciplined manufacturing and quality processes, which tends to favor companies with established quality management systems and repeatable production practices.
Cost structures are also being shaped by the growing importance of interoperability and mounting ecosystems. As carts are deployed alongside mobile monitors, tablets, and peripherals, the ability to standardize mounting and power across devices reduces integration friction and can lower total deployment costs. This is pushing manufacturers toward modular designs and robust accessory ecosystems that support varied clinical configurations without sacrificing safety or compliance.
Competitive Landscape and Leading Strategies
The market’s competitive structure remains concentrated, with leading players capturing a significant share of revenue while a broader set of specialized manufacturers competes on workflow fit, certification readiness, and regional service capabilities. The strategic positioning of incumbents reflects a blend of product breadth, compliance documentation, ergonomic design, and integration-ready ecosystems.
Several companies illustrate the range of strategic approaches shaping the category:
- Capsa Healthcare emphasizes mobile computing workstations and telehealth platforms designed for point-of-care electronic records, medication management, and virtual consultations. Its recent updates to telehealth cart platforms with integrated camera positioning and device mounting reflect a focus on enabling remote patient consultations within bedside and clinic workflows.
- Ergotron focuses on medical carts with integrated power systems, height-adjustable designs, and full electrical safety certifications tailored to acute care and imaging contexts. This positioning underscores the importance of compliance-ready engineering and ergonomic flexibility in high-acuity environments.
- RDP Health Ltd offers custom workstations on wheels for electronic patient records, electronic prescribing and medicines administration, and phlebotomy, with features such as 360-degree battery indicators and extended warranties aimed at public health system procurement. This approach highlights regional workflow customization and long-term service reliability.
- Lund Industries (DataCart) provides custom powered and non-powered healthcare computer carts with antimicrobial coatings, sit/stand height adjustment, and multi-year warranties. Its emphasis on customization and durability reflects a strategy centered on adapting to varied clinical configurations while supporting infection control requirements.
- Advantech contributes computerized medical carts and tablets for mobile medication administration, point-of-care documentation, and telehealth in hospitals, positioning its offerings around mobility, documentation efficiency, and broad clinical deployment.
- Parity Medical supplies UK-designed and assembled workstations on wheels for electronic patient records, electronic prescribing and medicines administration, and bedside clinical applications, illustrating the role of regional design and assembly in meeting local procurement expectations and service requirements.
These players are competing on a combination of product features, certification readiness, regional customization, and ecosystem compatibility. The result is a landscape where differentiation is increasingly tied to workflow fit and compliance documentation rather than to hardware novelty alone. Companies that can deliver reliable battery management, clear safety certifications, ergonomic flexibility, and mounting ecosystems that support monitors, tablets, and telehealth peripherals are better positioned to win multi-year contracts and repeat procurement cycles.
Recent market activity reinforces these strategic directions. An advanced medical cart received FDA listing for hospital use in mid-2024, highlighting the regulatory pathway for products that integrate powered systems or diagnostic accessories. Upgraded workstation carts with integrated battery management systems entered the market around the same period, addressing bedside documentation needs with improved uptime and charge visibility. Updated telehealth cart platforms with camera positioning and device mounting expanded remote consultation capabilities, while broader exhibition of mobile mounts, power systems, and medical carts at major health IT events signaled growing integration between carts and surrounding infrastructure. Together, these developments suggest a category that is moving toward more standardized safety expectations, smarter power management, and tighter alignment with virtual care and point-of-care documentation workflows.
Looking ahead, the competitive landscape appears likely to evolve along three lines. First, consolidation pressure may build as larger technology and medical device ecosystems seek to offer more complete mobile computing solutions that combine carts, power, mounting, and software integration. Second, segmentation may continue between general-purpose mobile workstations and more specialized configurations for imaging, medication management, and telehealth, with differentiation driven by certification, ergonomics, and workflow integration. Third, new entrants may find opportunities in niche regions, custom configurations, and service-led models that emphasize long warranties, battery transparency, and local support, particularly where public-sector procurement values compliance documentation and predictable lifecycle costs.
Forward Outlook: Trends and Commercial Opportunities
Based on current growth dynamics and the trajectory of product and regulatory developments, several trends are likely to shape the market over the next three to five years.
Trend One: Workflow-Integrated Mobility Becomes the Baseline. Mobile computing stations will increasingly be evaluated as integrated workflow platforms rather than as standalone hardware. Buyers will expect reliable battery management, clear charge indicators, height adjustability, antimicrobial protection, and mounting options that support cameras, tablets, and monitors. Vendors that design for interoperability with existing clinical systems and accessory ecosystems will capture more procurement interest, while devices that create integration friction will face greater resistance. The commercial opportunity lies in bundling compatible power systems, mounting solutions, and service terms that reduce total cost of ownership and simplify deployment across departments.
PW Consulting
Trend Two: Compliance and Safety Readiness Move from Advantage to Requirement. As electrical safety standards and quality management expectations become more firmly embedded in purchasing criteria, certification readiness will function as a market requirement rather than a differentiator. This will favor manufacturers with disciplined design controls, documented safety testing, and consistent service processes. For buyers, this trend creates an opportunity to streamline procurement by prioritizing vendors with verifiable compliance footprints and multi-year support commitments, reducing the risk of integration delays and lifecycle service gaps.
Trend Three: Hybrid Care and Point-of-Care Digitalization Expand Use Cases. The continued expansion of remote consultations, bedside documentation, and mobile medication workflows will broaden the application profile of medical computer carts. Telehealth-ready configurations, integrated camera positioning, and flexible device mounting will become more important, while carts used in imaging and acute care will need robust power, ergonomic adjustment, and safety certifications. The commercial opportunity is in designing and positioning products that can serve multiple clinical contexts without sacrificing specialization, enabling facilities to standardize on fewer platforms while meeting varied workflow needs.
These trends are accompanied by risks and uncertainties. Reimbursement frameworks remain tied to broader electronic health record infrastructure billing rather than to the cart category, so procurement momentum can be sensitive to capital budget cycles and internal ROI framing. Regulatory pathways for powered systems and diagnostic accessories can add development time and cost, particularly for new entrants or highly specialized configurations. Supply chain variability, component availability, and certification timelines may affect product launches and pricing. Finally, if workflow integration is under-prioritized, organizations risk accumulating underutilized carts that do not deliver expected efficiency gains, undermining the business case for broader adoption.
Strategic Recommendations for Decision Makers
The market’s direction suggests practical priorities for different stakeholder groups. The following guidance translates current dynamics into actionable focus areas.
- For manufacturers: Prioritize workflow integration and compliance readiness as core product attributes. Build battery management systems with transparent charge indicators, support height adjustability and ergonomic flexibility, and maintain documented safety certifications that align with recognized electrical and quality standards. Develop mounting and power ecosystems that accommodate monitors, tablets, and telehealth peripherals, and structure service terms around multi-year warranties and clear lifecycle support. Differentiation will increasingly come from reliability, integration ease, and certification documentation rather than from hardware novelty alone.
- For investors: Evaluate companies on their ability to deliver compliant, integration-ready mobile workstations with defensible service and warranty models. Focus on manufacturers that demonstrate consistent quality management, clear safety certification status, and product lines that serve multiple clinical contexts without fragmenting the portfolio. Watch for consolidation opportunities among specialized players, and consider the commercial value of ecosystems that combine carts, power, mounting, and service support into repeatable deployment packages. Be mindful of regulatory pathway complexity and reimbursement framing, which can influence procurement timing and margin profiles.
- For procurement and clinical operations leaders: Treat medical computer carts as workflow infrastructure investments rather than commodity hardware. Standardize on configurations that meet electrical safety and quality management expectations, and prioritize battery transparency, ergonomic adjustability, and mounting compatibility with existing devices. Build procurement narratives around bedside documentation efficiency, medication management support, and virtual consultation enablement, and align purchasing cycles with broader IT modernization plans to strengthen justification. Evaluate total cost of ownership including service, warranty, and integration effort, and select vendors that can demonstrate consistent compliance documentation and reliable lifecycle support.
As the market approaches the late 2020s, the most successful commercial outcomes will belong to organizations that can connect product capabilities to real clinical workflows, maintain rigorous compliance readiness, and deliver predictable service over multi-year cycles. For executives and investors seeking detailed segmentation data, regional dynamics, application-level revenue splits, and custom scenario analysis, a comprehensive research report can provide the deeper breakdown needed to support procurement planning, portfolio strategy, and investment decisions. The broader market signals are clear; the next step is translating them into precise, actionable plans with the right level of detail.
For detailed analysis of this topic, please visit the official page: Medical Computer Cart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Composite Insulators Market: Why 6.98% CAGR Redefines 2032 Revenue Trajectory
By PW Consulting, 2026-09-21
Composite Insulators Market: Strategic Trends and Commercial Opportunities Through 2032
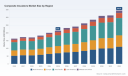
The composite insulators market has transitioned from a niche alternative to a mainstream component in high-voltage infrastructure, reflecting a structural shift in how utilities and OEMs approach reliability, weight, and maintenance economics. Valued at approximately 215.0 million USD in 2025 and projected to reach 344.8 million USD by 2032, the market follows a compound annual growth rate of 6.98 percent across the 2026–2032 forecast window. Growth from 163.15 million USD in 2020 to 215.0 million USD in 2025 illustrates a steady expansion trajectory, with momentum accelerating through the end of the decade. This trajectory is not simply volume-driven; it signals a maturing value proposition where polymer-based designs are increasingly selected for their durability in harsh environments, reduced creepage requirements, and compatibility with modular grid architectures.
Behind the headline numbers lies a market that is gaining confidence but not without friction. The sector is navigating raw material volatility, evolving certification expectations, and a competitive landscape that is consolidating around firms with differentiated manufacturing depth. For executives and investors, the question is no longer whether composite insulators will capture additional share, but where the highest-margin segments will form, which capabilities will separate winners from commoditized producers, and how supply chain and regulatory dynamics will shape returns over the next five years.
A Market at an Inflection Point
The current landscape is defined by three intersecting pressures that are reshaping strategy across the value chain. First, cost structures are increasingly sensitive to input price swings, particularly in resin and fiberglass, which directly influence pultrusion economics and margin stability. Second, international standards are tightening, raising the bar for sheath integrity, interface quality, and long-term performance validation. Third, the supplier base is undergoing selective consolidation, with larger multinational groups acquiring specialized production assets to secure technology, capacity, and certification portfolios. These forces are not isolated; together they are increasing the importance of process integration, quality assurance, and regional compliance readiness.
For market participants, the practical implication is that scale alone is no longer a sufficient advantage. Competitors that can control core manufacturing steps, align product designs with updated standards, and demonstrate consistent performance in demanding applications are better positioned to defend pricing and win long-term utility contracts. Firms that remain dependent on fragmented sourcing or minimal differentiation face greater exposure to price competition and specification-driven disqualification.
Core Drivers Reshaping Demand and Supply
Several structural drivers are underpinning the market’s expansion, and each carries distinct implications for product strategy and commercial positioning.
Technological innovation continues to broaden the applicability of composite insulators. Advances in silicone rubber formulations and hollow-core engineering are enabling lighter, more hydrophobic solutions that perform well in polluted or high-humidity environments. The release of new high-consistency silicone rubber for composite insulator production illustrates how material innovation is opening design space for manufacturers, especially where traditional porcelain or glass solutions carry weight, breakage, or maintenance penalties. At the same time, process technologies that improve interface quality and sheath uniformity are becoming more important as standards raise minimum performance thresholds.
Policy and regulatory evolution is sharpening the focus on compliance and interoperability. Updated frameworks such as IEC 61109 Edition 3.0 and EN IEC 62217:2025 are reinforcing expectations around sheath thickness, interface quality, and defined performance classes for polymeric high-voltage insulators. These revisions do more than set technical baselines; they reduce ambiguity for specifiers and create a more uniform path for manufacturers seeking to serve multiple regions. In practice, this is encouraging producers to invest in certification readiness and to design families of products that can be validated across transmission, substation, and distribution contexts.
Demand-side behavior is also changing. Utilities and industrial operators increasingly favor solutions that reduce footprint, simplify installation, and lower long-term maintenance burden. Composite insulators are gaining traction where their mechanical resilience and corrosion resistance translate into lower lifecycle risk, especially in remote corridors, coastal settings, or regions with aggressive atmospheric contamination. At the same time, the broader push toward grid modernization and expanded transmission capacity is lifting volumes across both overhead lines and substation equipment, broadening the addressable base beyond traditional replacement cycles.
PW Consulting Chemical & Energy Research Center
Supply chain and cost dynamics remain a critical variable. Pultruded fiberglass profiles for composite insulator cores generally cost between 5 and 15 USD per linear foot, or roughly 2 to 10 USD per pound depending on resin selection and customization. This range underscores how sensitive production economics are to glass fiber and resin pricing, and why manufacturers with integrated processes or disciplined procurement strategies can achieve more stable margins. When raw material prices fluctuate, the impact is not limited to input cost; it ripples through lead times, quotation reliability, and the ability to scale capacity without eroding unit economics.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of technologically specialized manufacturers, regionally concentrated producers, and multinational groups pursuing targeted expansion. Market concentration remains moderate, with the top three firms holding approximately 24.6 percent and the top five about 26.2 percent of the market. This fragmentation suggests room for both differentiation and consolidation, depending on the segment and geography.
Worldwide Low Voltage Insulators Market
Leading players are pursuing distinct strategic positions. Some manufacturers emphasize full vertical integration in hollow composite insulator production, building end-to-end control over core fabrication, housing, and final assembly. This model is particularly valuable where OEMs and utilities prioritize traceability, repeatability, and the ability to offer alternative gas or insulation options. Others compete on breadth of product families, covering suspension, line post, pin, tension, and bushing types across transmission, substation, and distribution networks. That breadth can be a strong commercial advantage when specifiers want a single source for multiple asset classes, especially in large-scale grid build-outs.
A third strategic theme is technology-led specialization. Certain producers focus on epoxy-resin glass fiber cylinders and high-temperature injection or advanced molding technologies that target substation and line applications requiring precise mechanical and electrical performance. These capabilities can support premium positioning when paired with rigorous qualification data and strong service networks. In parallel, manufacturers active in Asia and India continue to expand capacity and export reach, often competing on combination of cost, scale, and growing technical credibility. Their growth reflects both domestic demand and the broader international search for reliable supply alternatives.
Recent industry developments offer a clear window into how the landscape is evolving. The introduction of new silicone rubber materials for composite insulator production highlights the ongoing push to improve material consistency and processing efficiency. Meanwhile, corporate moves such as the acquisition of composite insulator production facilities by a larger group, including machinery and intellectual property, point to a strategy of securing specialized manufacturing assets and expanding capacity in established industrial regions. This kind of transaction suggests that controls over core processes, proprietary know-how, and certified production lines are becoming strategic assets rather than mere operational inputs.
Trade show participation and regional exhibition activity also indicate where companies are concentrating commercial effort. Exhibiting advanced high-voltage composite insulators at international grid equipment events and utility-focused conferences signals a continued emphasis on face-to-face specification engagement, particularly in markets where project pipelines are active and relationships with utilities, contractors, and system integrators matter.
Taken together, the competitive picture suggests three unfolding dynamics. First, differentiation is shifting toward process depth, materials expertise, and certification readiness rather than catalog breadth alone. Second, consolidation is likely to continue in pockets where complementary technologies, regional access, or specialized production assets create clear value. Third, new entrants and expanding regional manufacturers will keep pressure on pricing in commodity-adjacent segments, while more engineered applications remain open to firms with strong technical validation and application support.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by the intersection of materials progress, standards-driven specification clarity, and selective consolidation. The first trend is the continued migration of composite insulators into higher-value applications where performance under stress, weight reduction, and maintenance savings justify the choice over traditional alternatives. This shift will not be uniform; it will concentrate in environments where contamination, humidity, vibration, or access limitations make polymer-based designs especially advantageous.
Composite Insulated Panels Market
The second trend is the growing importance of compliance as a commercial differentiator. As updated standards raise expectations for sheath quality, interface integrity, and consistent high-voltage performance, manufacturers that can demonstrate robust qualification processes and repeatable production control will gain an advantage in tender evaluations and OEM supply agreements. Certification readiness is becoming less of a back-office function and more of a market-access requirement, particularly for suppliers targeting multiple regions or working with large multinational buyers.
The third trend is the continued realignment of manufacturing capacity and ownership. Strategic acquisitions and capacity expansions in established production hubs indicate that scale, technology control, and localized capability will matter more as customers seek reliable supply and shorter qualification cycles. At the same time, raw material sensitivity will keep cost discipline and formulation flexibility in focus, especially where resin and fiberglass pricing can compress margins or disrupt quoting.
These trends create concrete commercial opportunities. There is room for product strategies that pair material consistency with application-specific design, enabling suppliers to serve both transmission and substation segments without diluting manufacturing focus. There is also opportunity in regional expansion where grid investment is accelerating and where localized support, certification alignment, and service responsiveness can outweigh pure price competition. For buyers, the opportunity lies in reducing lifecycle risk through more predictable performance and in consolidating the supplier base where quality assurance and technical support can be managed more efficiently.
Risks and uncertainties remain. Raw material volatility can quickly alter cost assumptions and erode the economics of capacity expansions if not managed with hedging, formulation options, or process efficiencies. Regulatory updates, while beneficial in the long run, can impose rework, retesting, or redesign costs if product families are not aligned early. In addition, intensified competition in volume-oriented segments may pressure margins even as premium segments expand, creating a bifurcated market where profitability depends heavily on positioning and execution.
Strategic Implications for Decision Makers
Manufacturers should prioritize capabilities that convert technical advantage into commercial advantage. That means investing in process integration where it strengthens quality, consistency, and traceability; aligning product families with updated standards before specification cycles lock in; and building formulation and procurement flexibility to absorb raw material swings. Where possible, firms should also consider targeted expansion of engineered product lines rather than undifferentiated catalog growth, since higher-value applications are likely to reward proven performance and application support more than breadth alone.
Investors should evaluate exposure not just to market growth but to the underlying drivers of margin durability. Capacity expansions, technology acquisitions, and regional entry decisions all look more attractive when paired with certification readiness, material expertise, and a clear route to utility or OEM demand. The most resilient opportunities are likely to emerge where operators can demonstrate control over critical production steps and where the customer base values reliability and lifecycle performance enough to support disciplined pricing.
Procurement and specification teams should treat composite insulator selection as a lifecycle decision rather than a unit-price comparison. Evaluating sheath quality, interface design, material consistency, certification status, and supplier process control can reduce installation risk and long-term maintenance exposure. Consolidating suppliers where supported by strong technical documentation and consistent qualification data may also improve procurement efficiency, especially across transmission, substation, and distribution programs with overlapping performance requirements.
Closing Perspective
The composite insulators market is entering a phase where growth is increasingly tied to technical credibility, standards alignment, and strategic control of manufacturing depth. The pathway from 215.0 million USD in 2025 to 344.8 million USD by 2032 will not be evenly distributed across every supplier or segment. Instead, value will accrue to participants that can combine material innovation, compliance readiness, and operational discipline with a clear focus on the applications where composite designs deliver the strongest economic and technical case. For organizations operating in or adjacent to this market, the most valuable next step is to map these shifts against specific product portfolios, regional pipelines, and procurement strategies, and to update assumptions as standards, materials, and ownership structures continue to evolve.
For detailed analysis of this topic, please visit the official page: Composite Insulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pomegranate Market 2026-2032: Why 6.8% CAGR Growth Redefines Future Strategy
By PW Consulting, 2026-09-21
The Pomegranate Market: Strategic Trends and Commercial Opportunities Through 2032
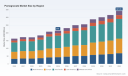
The global pomegranate market has transitioned from a niche seasonal offering to a mainstream, multi-segment commercial category. Total market revenue crossed the 215 million USD threshold in the base year, reflecting consistent expansion across production geographies and value-added formats. The sector has demonstrated a compound annual growth rate of 6.8 percent across the forecast horizon, a pace that positions pomegranates ahead of many legacy fruit categories but still requires deliberate portfolio strategy to capture. Revenue figures across the historical and projected periods illustrate a trajectory that moved from 163.15 million USD in 2020 to 341.83 million USD by 2032, with particularly pronounced expansions occurring after 2023. Such progression is not simply a function of acreage expansion; it reflects structural shifts in how fruit is processed, formulated, and positioned across food, wellness, and personal care applications.
For executives evaluating exposure to this category, the takeaway is that pomegranate is no longer a single-commodity story. The market now operates as an ecosystem where fresh fruit distribution, juice and concentrate processing, and ingredient-level applications for supplements and cosmetics interact with each other. This interconnected structure means that shifts in one segment can rapidly alter demand, pricing, and margin profiles across the broader chain. Understanding the interplay between volume growth, product-form diversification, and regional production patterns is essential before committing capital or reformulating supply strategies.
Key Structural Challenges and Inflection Points
Three pressures are reshaping how participants compete and where profitability is likely to concentrate. First, water intensity and irrigation discipline are becoming strategic variables rather than operational details. Recent scoping work in Western Cape orchards and commercial field trials have demonstrated that optimized irrigation scheduling can improve yield, fruit quality, and water use efficiency at the same time, which indicates that water management is a direct lever on quality consistency and cost structure rather than a compliance cost alone.
Second, labor exposure in high-touch orchard systems continues to pressure margins. Pruning and multi-stage harvesting can account for a substantial share of annual operational expenses in established European orchards, alongside significant upfront investment per hectare. This cost reality means that differentiation increasingly depends on agronomic efficiency, mechanization readiness, and yield consistency, not simply access to premium labeling or origin prestige.
Third, the category is being reshaped by the dominance of a few high-volume production centers alongside scattered but growing cultivation in newer regions. The structural imbalance between large-scale sourcing geographies and fragmented downstream processors creates both sourcing advantages and concentration risk, particularly for companies that rely on a narrow band of origin points or single processing formats. The practical implication is that resilience planning must account for agronomic variability, logistics continuity, and the ability to pivot across fresh and processed channels when weather, labor, or regulatory conditions shift.
Key Drivers Shaping the Pomegranate Market
The growth path is being generated by several reinforcing forces that operate across technology, regulation, consumer behavior, and cost structure. These drivers do not simply lift volume; they change which business models are likely to outperform.
Technological and Agronomic Innovation
Precision orchard management is becoming a core competitive advantage. Field evidence from commercial monitoring indicates that adjusting irrigation to a carefully managed fraction of evapotranspiration can improve fruit quality and yield while reducing cost and certain quality defects such as sun cracking. Equally important, the findings underline that evapotranspiration levels can vary widely across seasons and sites, so standardized irrigation assumptions are increasingly inadequate. For processors and brand owners, the strategic implication is that fruit quality consistency is becoming more dependent on upstream production discipline and traceability than on downstream blending or formulation alone.
Policy and Regulatory Context
Regulatory and environmental pressures are reinforcing the shift toward water-smart cultivation and documentation-intensive supply chains. In markets where water availability is tightening or where agricultural resource management is being scrutinized more closely, orchard-level efficiency is increasingly tied to license to operate. At the same time, cultivation expansion in newer regions is often supported by targeted investment in high-density systems and structured production programs. The broader lesson is that regulatory trends are not only creating constraints; they are also shaping where and how expansion is economically viable, particularly in regions where water productivity can be measured and improved.
Demand-Side Transformation
Consumer and corporate purchasing behavior is moving pomegranate further into wellness-oriented and convenience-driven use cases. Fresh fruit remains a foundation, but demand from food and beverage applications continues to be the largest consumption channel, reflecting both traditional culinary use and broader incorporation into beverages and formulated products. At the same time, nutraceutical and supplement use, along with cosmetics and pharmaceutical applications, adds a higher-value demand layer that rewards standardized extracts, stable concentrates, and ingredient-grade consistency. For commercial strategy, this means the same raw crop can support multiple value pathways, but each pathway requires different quality thresholds, formulation controls, and positioning.
Supply Chain and Cost Structure Evolution
Cost structure is being redefined by the interaction of labor intensity, capital investment per hectare, and the economics of processing form. Orchards that rely heavily on manual pruning and repeated harvesting face structurally higher operating costs, while growers adopting denser plantings and more controlled inputs can improve unit economics if they can sustain quality and yield. On the processing side, the economics of juice, concentrate, and other processed forms depend on fractionation efficiency, shelf-life management, and the ability to serve both bulk ingredient buyers and branded consumer channels. The combined effect is that margin leadership is increasingly determined by integrated efficiency from orchard to finished product, rather than by any single step in isolation.
Competitive Landscape and Leading Strategies
The competitive environment includes vertically integrated growers, branded fruit and juice operators, organic-focused processors, and international ingredient exporters. The market remains moderately fragmented at the top, with concentration levels indicating room for consolidation but also for differentiated niches. That combination matters because it means scale is not the only path to leadership; consistency, origin storytelling, certification, and format specialization can all support premium positioning.
Strategic Positioning of Key Players
Vertically integrated operators that control both growing and processing have a structural advantage in managing quality, timing, and channel mix. By managing cultivation alongside juice and value-added products, these companies can reduce dependency on third-party sourcing and create tighter feedback loops between orchard outcomes and finished product specifications. Their differentiation often rests on branded narrative, consistent supply, and the ability to offer multiple formats from a single origin. These are powerful advantages in consumer-facing channels, but they also require disciplined execution across agronomy, cold chain, and product development.
Organic and family-oriented processors compete through provenance, minimal-processing positioning, and consumer trust. In categories where label simplicity and clean formulation matter, these players can command attention even without the broadest distribution footprint. Their challenge is scaling while preserving the operational discipline and certification standards that support their positioning. For ingredient buyers, such producers can be attractive where traceability and organic integrity are procurement priorities.
PW Consulting Health Care Research Center
International ingredient exporters, particularly from major production geographies, play a different role: they supply bulk fruit products, pulps, concentrates, pastes, and fresh fruit for broader distribution networks. These companies are important to the market because they provide volume flexibility and geographic reach, especially for processors and formulators that need consistent input supply across seasons. Their competitive edge typically comes from sourcing scale, processing capability, export logistics, and the ability to match specifications for both food service and industrial buyers.
How the Landscape Is Evolving
The market is showing signs of both consolidation and fragmentation depending on the segment. In branded consumer channels, scale and marketing intensity favor players who can sustain shelf presence and brand recognition. In ingredient and processed forms, the trend is more fragmented, with regional and origin-specific suppliers competing on cost, quality consistency, and service reliability. At the same time, newer cultivation regions are expanding, which introduces additional sourcing diversity and can reduce dependence on a narrow set of origins over time.
Another important shift is the growing relevance of supply-side innovation as a competitive differentiator. Where water productivity, irrigation scheduling, and yield optimization are measurable and improved, suppliers can offer better quality and more predictable delivery. This is gradually turning agronomic performance into a commercial asset rather than a private operational matter. Companies that can document efficiency, quality stability, and responsible resource use are better positioned to enter higher-value contracts and withstand volatility in labor or weather conditions.
Future Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to define where value is created and where risk accumulates.
Trend One: Water-Smart Production as a Purchasing Criterion
Water productivity is moving from an operational concern to a procurement differentiator. Evidence from orchard monitoring and irrigation studies indicates that optimized water use can support both quality and cost performance, which suggests that buyers will increasingly favor suppliers who can demonstrate responsible irrigation management and consistent output under variable conditions. The commercial opportunity lies in tying sourcing decisions to measurable production efficiency, not only to price or origin. Suppliers able to provide verifiable efficiency data, stable quality, and documented yield improvement are likely to gain preference in higher-value contracts and long-term supply arrangements.
The uncertainty here is that water conditions, regulatory expectations, and climate variability differ significantly by region. Strategies that work where evapotranspiration is highly variable may need adjustment in other contexts, and over-reliance on a single improvement model could leave some operators exposed if local conditions change.
Trend Two: Format Diversification Will Outpace Single-Channel Growth
The market will continue to reward companies that can move fluidly across fresh fruit, juice and concentrate, and other processed forms. This diversification matters because different formats absorb seasonality and price volatility differently, and because downstream demand is spread across food and beverage, nutraceuticals, supplements, and cosmetics or pharmaceutical uses. Companies that can align product-form capability with the quality requirements of each channel are better positioned to capture multiple revenue streams from the same crop base.
The strategic opportunity is to treat product form as a portfolio decision rather than an operational afterthought. Where a company can efficiently fractionate fruit into fresh, juice, concentrate, or ingredient-grade outputs, it can better serve both consumer-facing and industrial buyers. The risk is that format expansion can dilute focus or strain quality control if processing lines, specification management, and customer support are not designed to handle varied applications.
Trend Three: Origin Expansion and Sourcing Reconfiguration
Cultivation is expanding in regions that have historically been smaller players, supported by investment in production systems and targeted development programs. This trajectory introduces new sourcing options and gradually broadens the geographic base of supply. For buyers, the opportunity is greater flexibility, potential cost arbitrage, and reduced concentration risk. For growers and processors, it is a chance to enter supply chains that value differentiated origin, consistent quality, and documented efficiency.
Garnet Market
The uncertainty is execution. Newer production regions often face startup costs, learning-curve effects, and logistics complexity. The most attractive opportunities will not automatically go to regions with expansion potential; they will go to those that can combine growth with quality reliability, export readiness, and credible performance data.
Actionable Guidance for Decision-Makers
For Manufacturers and Consumer-Facing Brands
Treat pomegranate as a multi-format portfolio rather than a single ingredient. Build flexibility into sourcing and processing so that fresh, juice, concentrate, and value-added forms can be balanced according to demand and margin. Where possible, align product development with applications that reward consistency and documentation, since those uses are likely to grow alongside wellness and personal care demand. Prioritize suppliers whose agronomic discipline and quality traceability are visible and verifiable, as those attributes are increasingly tied to commercial reliability.
For Investors
Evaluate exposure across the value chain rather than assuming that volume growth alone translates into returns. The most resilient opportunities are likely to be found where operational efficiency, format diversification, and measurable sustainability performance reinforce one another. Look closely at companies that can demonstrate water productivity improvements, controlled labor exposure, and the capability to serve more than one demand channel. Equally important, assess concentration risk in sourcing regions and the readiness of supply bases to adapt to weather, labor, and regulatory shifts.
Avocado Market
For Procurement and Supply Chain Leaders
Diversify origin exposure while maintaining specification rigor. Multi-origin strategies can reduce vulnerability to localized weather, labor, or logistics disruption, but they only work if quality standards and documentation are consistently applied across suppliers. Consider sourcing criteria that include irrigation efficiency, yield stability, and the ability to provide evidence of production discipline. Where possible, structure relationships that allow flexibility across processed forms so that supply continuity can be maintained when fresh-market conditions or processing availability shift.
Closing Perspective
The pomegranate market is entering a phase where commercial success depends less on simple category growth than on structural clarity: how fruit is produced, how it is processed into different forms, and how well participants can demonstrate value beyond price. The combination of water-smart production, format diversification, and broadening origin geography is expanding the strategic surface area of the category. That expansion rewards companies that can align quality, efficiency, and application fit across multiple channels. It also raises the cost of passive sourcing, since buyers and investors alike are increasingly exposed to agronomic variability, labor intensity, and concentration risk. In that environment, the most valuable next step is to move from broad category confidence to precise, segment-level intelligence that supports sourcing, product, and investment choices with greater certainty.
For detailed analysis of this topic, please visit the official page: Pomegranate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Particle Size Analyzers Market: Why 6.5% CAGR and Healthcare Demand Shift Strategy Through 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Particle Size Analyzers Market: A PW Consulting Outlook
Market Landscape and Core Challenges
The particle size analyzers market has entered a phase of accelerated expansion, driven by tightening quality control requirements across regulated industries and the growing demand for precise material characterization in pharmaceutical, chemical, and advanced manufacturing applications. Measured in millions of USD, the sector moved from approximately 350.0 in 2020 to an estimated 512.0 in 2025, with a projected compound annual growth rate of 6.5 percent through 2032, when revenue is expected to approach 800. The trajectory reflects a market that has transitioned from steady instrumentation replacement cycles to a broader adoption environment shaped by regulatory scrutiny, miniaturization of analytical workflows, and cross-industry quality standards.
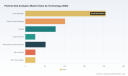
At the macro level, regional demand shows a clear concentration in established industrial and research hubs, with mature pharmaceutical and chemical markets driving consistent procurement volumes. Technology segments remain anchored by laser diffraction as the dominant measurement principle, while complementary methods such as dynamic light scattering, imaging, and nanoparticle tracking analysis continue to expand the addressable use cases in sub-micron and nano-range characterization. End-user demand is similarly structured around sectors where particle attributes directly influence product performance, stability, dissolution behavior, and process efficiency. Healthcare applications represent the largest share of demand, followed by academia, chemicals, and a diversified set of manufacturing sectors including food, cosmetics, and mining. The market remains moderately consolidated, with the top three players accounting for roughly 38 percent of revenue and the top five reaching about 42 percent, indicating that while scale and brand recognition matter, the competitive field still accommodates specialized and regional entrants.
Despite the favorable growth outlook, the market faces three structural challenges that are reshaping commercial strategies:
- Intense capital expenditure scrutiny in healthcare and public-sector laboratories: Particle size analyzers are treated as laboratory capital equipment rather than revenue-generating diagnostic tools. Hospitals and clinical laboratories operate under tight budget envelopes and reimbursement constraints, which prolong procurement cycles and increase competition for available CapEx. This dynamic places pressure on vendors to justify total cost of ownership, service reliability, and workflow integration rather than relying solely on technical performance.
- Standardization, compliance, and costly component requirements: Laser diffraction remains governed by established measurement standards that ensure traceable and repeatable results, but high-end instruments increasingly rely on precision optics and electronics that must meet certified, medical-grade component expectations in regulated pharma and clinical settings. Maintaining ISO certifications, CE marking, and audit-ready documentation adds operational complexity and restricts cost-down strategies, especially for manufacturers serving dual-use markets.
- Competition between performance differentiation and cost-efficient alternatives: The market is not homogeneous. While premium vendors compete on reproducibility, automation, and application-specific support, cost-effective alternatives have expanded reach in laboratory and industrial segments. Buyers in price-sensitive environments are increasingly weighing functional adequacy against brand prestige, forcing incumbents to demonstrate measurable advantages in throughput, operator ease, and integration with broader quality systems.
Key Drivers Shaping Market Dynamics
The growth of the particle size analyzers market is not simply a function of incremental instrument replacement. It is being reshaped by converging forces across technology, regulation, user behavior, and supply economics. Understanding these drivers is essential for assessing where demand will intensify and which commercial models will hold up under scrutiny.
Technology innovation and measurement versatility
Instrument development is moving beyond basic size distribution outputs toward integrated workflows that combine repeatability, automation, and easier interpretation for non-specialist operators. Laser diffraction systems continue to lead because they cover broad size ranges with fast measurement cycles, but the market is also expanding where sub-micron, nanoparticle, and morphological characterization matter. Dynamic light scattering and nanoparticle tracking analysis are gaining relevance for nanoformulations and dispersed systems, while imaging-based methods support morphology and shape factors that size-only outputs cannot capture. These capabilities matter because particle attributes increasingly affect formulation behavior, processing consistency, and downstream performance in complex materials.
PW Consulting
For vendors, the strategic implication is that performance leadership now depends on more than optical precision alone. Automation, sample handling flexibility, software usability, and seamless data traceability are becoming differentiators that influence purchasing decisions, especially where laboratory throughput and compliance documentation are critical. Instruments that reduce operator variability and simplify validation packages can command stronger adoption in regulated settings, even when upfront pricing is higher.
BET Surface Area Analyzer Market
Regulatory expectations and compliance-driven procurement
Regulatory and standardization dynamics play an outsized role in purchase timing, specification requirements, and vendor selection. Laser diffraction measurement practices are anchored by long-standing standards that support traceable and repeatable results, which makes them well suited to pharmaceutical and clinical applications where data integrity is essential. In parallel, major manufacturers maintain CE marking and relevant certifications for instruments used in regulated medical device and pharmaceutical particle characterization. This compliance posture is not a minor detail; it is a procurement prerequisite in many quality-sensitive environments.
At the same time, reimbursement and budgeting realities shape adoption. Particle size analyzers are capital equipment items without dedicated procedural billing codes, so purchasing decisions are strongly influenced by laboratory budget cycles and institutional cost control. The result is a dual dynamic: regulated applications can create durable demand because particle characterization supports quality and process validation, but procurement timing can be delayed or compressed depending on institutional CapEx availability. Vendors that can align their value proposition with audit readiness, documentation support, and predictable service coverage are better positioned to convert technical strength into commercial wins.
Demand-side shifts in formulation, manufacturing, and research
User demand is changing because the importance of particle attributes is rising across multiple end-use sectors. In healthcare and pharmaceutical environments, particle size and distribution can influence dissolution, bioavailability, and consistency of drug products, which reinforces the need for reliable characterization during development and quality control. Academic and research institutions continue to drive demand through fundamental material science, nanomaterial studies, and interdisciplinary programs that require precise sizing across different measurement ranges.
In industrial settings, the motivation is often operational rather than regulatory. Chemical, food, cosmetic, and mineral-processing operations use particle size data to optimize mixing, dispersion, reactivity, flow behavior, and end-product consistency. As manufacturers seek greater process control and reduced variability, the analyzer shifts from a periodic measurement device to a more integral quality assurance tool. This shift expands the value proposition beyond the instrument itself and toward workflow integration, repeat measurement confidence, and support for process decisions.
Supply-side and cost structure pressures
Cost structures in the high-end segment are increasingly shaped by component requirements. Precision optics and electronics in advanced laser diffraction systems often depend on certified, medical-grade components when instruments are deployed in pharma or clinical environments. These requirements constrain aggressive cost reduction and can affect lead times, sourcing flexibility, and service scalability. Meanwhile, in the broader market, regional manufacturers and cost-efficient models are expanding choice for laboratory and industrial users who prioritize functionality and price over premium brand positioning.
This divergence creates an important strategic tension. On one side, compliance and performance requirements support premium pricing and more defensible margins for vendors with strong documentation, service networks, and application support. On the other, price sensitivity in less regulated or more volume-driven segments pressures incumbents to compete on throughput, ease of use, and total cost of ownership. Supply-side strategy therefore matters as much as product performance: sourcing resilience, service coverage, and scalable calibration support can determine whether a product succeeds commercially across regions and customer segments.
Competitive Landscape and Leading Strategies
The market is led by a set of established multinational players with distinct technology portfolios, application focus areas, and geographic strengths. Their strategies reveal how vendors are navigating the tension between premium performance, compliance, and broader accessibility.
Amino Acid Analyzers Market
Malvern Panalytical remains a prominent force in laser diffraction, with a recognized presence in pharmaceutical applications where particle characterization supports drug dissolution and bioavailability studies. Its positioning reflects the broader value of strong brand recognition, application depth, and alignment with regulated workflows. Danaher, through its life sciences portfolio, combines Coulter Principle and laser diffraction systems that serve clinical laboratory and pharmaceutical particle characterization, giving it a strong fit in environments where clinical and quality control demands intersect. HORIBA Scientific offers laser diffraction systems covering sub-micron to larger particle ranges, emphasizing broad measurement versatility for laboratory and scientific use. Anton Paar focuses on laser diffraction analyzers with automation features designed to improve precision and repeatability, an approach that addresses the need for reduced operator variability in controlled environments.
A second layer of competitors illustrates the market's expanding accessibility. Bettersize Instruments, based in China, specializes in cost-effective laser diffraction and dynamic light scattering systems for laboratory and industrial applications, targeting users who require solid measurement capability without premium pricing. Microtrac provides laser diffraction, DLS, and image analysis options for fluid and dry materials, supporting customers who need multi-mode characterization flexibility. Sympatec develops laser diffraction systems oriented toward powders, granules, suspensions, and process monitoring, aligning closely with manufacturing and inline or process-adjacent use cases. Shimadzu supplies particle characterization instruments for laboratory powders and liquids, benefiting from broad scientific instrumentation credibility. Fritsch integrates particle sizing within a wider milling and sizing portfolio, which can be attractive for customers linking sample preparation and analysis. Mettler Toledo incorporates particle size analyzers into automated characterization offerings for laboratory and process use, reinforcing a workflow-oriented value proposition. Scitek Global, also from China, offers lab and medical equipment including particle size analyzers with ISO 13485 certification, a compliance signal that can matter in regulated procurement environments.
These profiles show a market where differentiation is no longer defined solely by measurement method. Leading positions are increasingly tied to application support, software usability, compliance documentation, service reach, and the ability to serve both development and quality control needs. Vendors that can bridge laboratory characterization and process-relevant insights gain an advantage in sectors where particle data must inform operational decisions, not just generate reports.
The competitive landscape is evolving along three trajectories:
- Consolidation pressure among mid-tier and regional players: As buyers demand broader support, calibration, and service coverage, smaller vendors face mounting pressure to scale service infrastructure or partner for distribution. This favors larger players with existing institutional relationships and multi-channel support, while creating opportunities for acquisitions that add geographic coverage or complementary technologies.
- Differentiation through workflow integration and software: Hardware performance remains essential, but commercial advantage is shifting toward automation, data handling, and traceability features that reduce burden in regulated environments. Systems that simplify validation, reporting, and multi-user operation are better positioned to withstand procurement scrutiny.
- New entry and niche expansion in specific measurement ranges and applications: Demand for nano-range characterization, dispersed systems, and specialized sample types continues to create openings for focused entrants. Rather than challenging leaders across the full instrument spectrum, new players often compete by targeting specific size ranges, sample formats, or regional price points with credible certification and application support.
Future Trends and Strategic Opportunities (2026–2032)
The next several years are likely to be shaped by how the market balances performance, compliance, cost, and workflow value. Three trends stand out as particularly consequential for commercial planning.
1. Wider adoption of automated, workflow-oriented analyzers in regulated environments
As laboratories face staffing constraints and greater documentation demands, instruments that reduce operator dependence and improve measurement repeatability will gain traction. Automation in sampling, cleaning, data export, and reporting can lower total cost of ownership by improving throughput and reducing error-related rework. This trend is especially relevant in pharmaceutical and clinical-adjacent settings, where compliance-ready documentation and consistent results support validation and audit processes. Commercial opportunity lies not only in instrument sales but in bundled offerings that include service, training, software updates, and compliance support. The risk is that automation claims must be backed by demonstrable reliability and service coverage; otherwise, perceived complexity can slow adoption.
2. Growing demand for multi-method and application-specific characterization solutions
Particle characterization needs are becoming more diverse as materials and formulations grow more complex. Some applications require broad dynamic range, others need nano-scale sensitivity, and still others benefit from shape or morphology information. This is likely to increase demand for vendors that can offer method flexibility or integrate complementary techniques within a coherent workflow. For end users, the appeal is faster method selection, fewer handoffs between instruments, and more interpretable results for specific applications. For vendors, the opportunity is to position instruments as part of an application solution rather than as standalone measurement boxes. The uncertainty is that cross-method integration can raise cost and support complexity, so success will depend on clear use-case targeting rather than broad but shallow capability claims.
3. Intensifying competition between premium performance and cost-efficient access
Market growth is likely to broaden access to particle characterization in emerging industrial and regional markets, where cost sensitivity and practical usability may outweigh premium brand value. At the same time, regulated and performance-critical applications will continue to reward vendors with strong compliance credentials, service depth, and demonstrated reproducibility. This bifurcation creates a strategic choice for companies: compete premium or compete broadly. The more profitable path may be a segmented strategy that protects high-margin regulated positions while using targeted cost-efficient models to capture volume in less regulated sectors. A key risk is brand erosion if premium positioning is diluted without clear differentiation, or if cost-focused models cannot sustain service and calibration quality over time.
Actionable Guidance for Decision-Makers
The commercial implications of these trends vary by role, but a common theme is that purchasing and competitive decisions increasingly hinge on total workflow value, compliance readiness, and service sustainability rather than on measurement capability alone.
For manufacturers and technology providers
- Prioritize differentiation through automation, software usability, and documentation support that reduces burden in regulated settings. Technical excellence matters, but repeatable workflows and audit-ready outputs often decide procurement outcomes.
- Segment the portfolio deliberately. Use premium, compliance-oriented offerings for pharmaceutical and clinical-adjacent demand, while developing credible cost-efficient options for broader laboratory and industrial segments without compromising support quality.
- Strengthen service, calibration, and regional coverage. In a market where CapEx approval is cyclical and compliance expectations are high, long-term customer value depends heavily on post-sale support and sourcing resilience for precision components.
For investors and strategic planners
- Focus on business models that combine instrument revenue with recurring service, software, and application support, since these elements can improve resilience through budget-constrained procurement cycles.
- Watch for consolidation signals among regional and mid-tier players, especially where scale in service distribution, certification coverage, or application breadth becomes a competitive requirement.
- Evaluate exposure to regulated end-use demand carefully. While pharmaceutical and healthcare applications can sustain premium positioning, purchasing timing may be sensitive to hospital and laboratory budget cycles, which can affect short-term revenue visibility even when long-term demand remains strong.
For procurement leaders and laboratory operators
- Evaluate total cost of ownership, not just purchase price. Consider measurement repeatability, operator training burden, service response time, and documentation support, especially where compliance and throughput matter.
- Define application requirements clearly before sourcing. The “best” instrument depends on sample type, size range, throughput needs, and regulatory context, and over-specifying or under-specifying can create unnecessary cost or performance gaps.
- Request evidence of workflow fit and support capability. References, validation support, and service coverage may be as important as performance specifications when procurement must justify capital allocation within institutional budget constraints.
The strategic picture is clear: the particle size analyzers market is expanding under the influence of regulatory expectations, workflow automation, and broader application demand, but it is also becoming more segmented and more service-dependent. Companies that understand where compliance, cost, and performance intersect will be best positioned to capture durable demand, while buyers who evaluate instruments as part of a broader quality workflow will make more resilient procurement decisions. For decision-makers seeking detailed segmentation data, regional demand patterns, and customized competitive scenarios across technologies and end users, a full research report can provide the deeper quantitative context needed to translate these trends into precise commercial planning.
For detailed analysis of this topic, please visit the official page: Particle Size Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Color Coated Steel Market: How 4.86% CAGR and Asia Pacific's Lead Redefine Revenue Paths
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Color Coated Steel Market
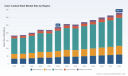
The color coated steel market is navigating a period of structural transition. Between 2020 and 2025, global revenue grew from $183.0 million to $238.0 million, reflecting steady demand across construction, manufacturing, and consumer applications. The trajectory points toward $330.71 million by 2032, implying a compound annual growth rate of 4.86 percent. This expansion is neither uniform nor frictionless. Regional imbalances, regulatory reconfiguration, and material cost volatility are reshaping how value is created and captured across the value chain. For executives and investors, the opportunity lies not in chasing aggregate growth, but in positioning operations and portfolios around the structural forces that will determine competitive advantage over the next five years.
The market remains moderately concentrated, with three firms accounting for roughly 55 percent of revenue and five firms controlling approximately 62 percent. This concentration masks significant fragmentation at the regional and application levels, particularly among processors and fabricators who serve localized construction and industrial demand. The operating environment is also being redefined by policy shifts and material economics that differ sharply across jurisdictions. The following analysis examines the core challenges, demand drivers, competitive dynamics, and emerging trends that will shape strategic decisions in the color coated steel sector.
Market Landscape and Critical Inflection Points
The period from 2020 through 2025 demonstrates resilient demand, but the growth path is uneven. Revenue crossed the $220 million threshold in 2023 before a slight contraction in 2024, followed by recovery in 2025. This pattern reflects the sensitivity of coated steel demand to construction cycles, import policy volatility, and the timing of large project pipelines. The forecast horizon through 2032 indicates that growth will increasingly be driven by application diversification, coating technology upgrades, and regional supply realignment rather than by uniform volume expansion.
Steel Roofing Market
Several structural challenges are converging at once.
- Policy and trade friction are compressing arbitrage opportunities. Tariff escalations and anti-dumping actions are narrowing the traditional cost advantages of cross-border sourcing. Import-dependent supply chains face higher landed costs and greater planning uncertainty, while domestic producers confront both protection and the pressure to justify scale investments.
- Material cost volatility is reshaping margin structures. The zinc galvanizing layer that provides the essential corrosion barrier accounts for approximately 8 to 12 percent of total production cost, with pricing influenced by global commodity exchanges. Fluctuations in zinc and substrate costs directly affect coating economics, especially for producers operating on thin service-center margins.
- Regulatory mandates are accelerating formulation change. Environmental requirements around chromate-free and ultra-low-VOC coating systems are moving from optional best practice to compliance baseline in key markets. This shifts the competitive conversation from price-per-ton to performance durability, compliance documentation, and downstream certification readiness.
These forces are not isolated. Trade policy influences where capacity is built, material costs determine which coating chemistries remain economically viable, and environmental regulations raise the bar for product qualification. The net effect is a market that rewards operators with flexible production systems, transparent compliance records, and the ability to serve application-specific performance requirements rather than generic commodity volumes.
Key Demand Drivers Reshaping the Market
Growth is being pulled by a combination of technology, policy, demand-side behavior, and supply chain economics. Each driver reinforces the others, creating a landscape where differentiation is increasingly tied to capability depth rather than scale alone.
Coating technology and performance differentiation. Advances in resin systems and surface engineering are expanding the addressable use cases for color coated steel. Polyester-based formulations continue to anchor high-volume construction and consumer applications due to cost efficiency and adequate durability. At the same time, higher-performance chemistries are gaining traction where exposure conditions, aesthetic requirements, and service life expectations justify premium pricing. The practical impact is a market that is segmenting by performance tier rather than by commodity classification. Producers who can demonstrate measurable improvements in weather resistance, color retention, and formability are capturing share in application segments where failure costs are high.
Policy and regulatory reconfiguration. Trade and environmental policy are becoming central to competitive positioning. The United States increased Section 232 tariffs on steel from 25 percent to 50 percent in mid-2025, a move intended to reduce import dependence and stimulate domestic capacity investment. In parallel, the European Union's carbon border adjustment mechanism for iron and steel became fully operational at the end of 2025, imposing carbon-related costs on imported products. Brazil's foreign trade authority also announced definitive anti-dumping tariffs in early 2026 on pre-painted steel from India and China, with rates spanning a wide per-tonne range. These measures alter the economics of inter-regional trade and push buyers and suppliers to reconsider sourcing geography, inventory strategy, and contract structures.
Demand-side behavior and application expansion. Construction remains the largest demand anchor, but the character of demand is evolving. Residential and commercial building activity, infrastructure renewal, and retrofit programs continue to support volume, while specification requirements increasingly emphasize durability, corrosion protection, and environmental compliance. Beyond construction, consumer goods and automotive applications provide additional demand layers that value consistent finish quality, weight efficiency, and formability. The presence of multiple application streams reduces dependence on any single cycle and creates opportunities for suppliers who can align coating systems with specific end-use performance criteria.
Supply chain structure and cost dynamics. The cost stack for color coated steel is sensitive to substrate availability, coating raw materials, and energy intensity. The zinc layer, which serves as the critical anti-corrosion component, introduces commodity-linked cost variability. At the same time, regional production footprints are being reassessed in response to tariff and carbon policy. Some operators are prioritizing closer-to-market coil processing and finishing to reduce exposure to trade friction, while others are investing in integrated capabilities to protect margin and improve qualification speed. Supply chain resilience is becoming a commercial differentiator, particularly for buyers who require consistent lead times and documented compliance across multiple SKUs.
Competitive Landscape and Strategic Positioning
The competitive field spans manufacturers, processors, and traders across North America, India, and South Korea, with distinct strategic postures emerging by region and business model. Companies are not competing solely on price; they are competing on qualification breadth, coating system versatility, compliance readiness, and the ability to support downstream fabrication and assembly requirements.
In North America, a group of active manufacturers and processors has built positions around pre-painted and color coated steel coils for construction, building panels, garage doors, and service canopy applications. Several of these firms emphasize specific resin platforms, including PVDF-based systems and weather-resistant polyester coatings, to align with architectural and industrial specification requirements. The regional focus reflects both the tariff environment and the importance of responsive service, short lead times, and localized technical support for fabricators and building product manufacturers.
India hosts a dense set of manufacturers and exporters with varying capacities and coating portfolios. Some operators focus on large-scale production and broad geographic reach, exporting across multiple continents. Others differentiate by offering a wide range of colors, embossed patterns, and coating systems such as RMP, SMP, PU, and PVDF to serve roofing, cladding, and industrial applications. The combination of domestic demand growth and export orientation creates a competitive environment where scale, standard compliance, and coating versatility are key advantages.
South Korean participants include integrated manufacturers and traders offering pre-painted coils and sheets across multiple coating types, including silicon polyester, PVDF, and high-polymer systems. Several firms maintain substantial annual production capacity and emphasize product standards compliance and appliance-grade finish quality. Their positioning reflects the region's strength in process precision and the importance of meeting specification requirements for downstream manufacturers in construction and consumer durable segments.
Across these regions, several strategic patterns are evident.
- Differentiation through coating systems and compliance. Leading participants are building reputations around specific resin platforms, color consistency, and adherence to international standards. This matters because downstream buyers increasingly require documented performance, VOC compliance, and corrosion resistance data as part of procurement decisions.
- Regionalization of supply as a risk management tool. Tariff and carbon policy are encouraging closer alignment between production, processing, and end markets. Operators with flexible regional footprints can reduce exposure to trade volatility and respond faster to specification changes.
- Capacity and qualification as barriers. In segments where reliability, certification, and throughput matter, capacity scale and process control create meaningful barriers. At the same time, niche processors can compete effectively by specializing in high-specification applications or by offering rapid customization for local fabricators.
The market structure suggests continued divergence. Large integrated players will continue to compete on scale, standard compliance, and export reach, while regional processors and specialists will compete on service speed, coating flexibility, and application-specific performance. Consolidation is possible where scale and compliance costs favor larger operators, but fragmentation can persist where localized service and specification support remain critical to winning business.
Forward Outlook: Three Trends to Watch
Looking ahead to the 2026 through 2032 horizon, three trends are likely to shape where value concentrates and where risk accumulates.
Coil Coatings Market
Trade and carbon economics will continue to rewire sourcing maps. The combination of higher steel tariffs in certain markets, operational carbon border mechanisms in others, and targeted anti-dumping actions will keep inter-regional arbitrage under pressure. Over the next few years, buyers and suppliers will likely place greater weight on nearby processing capacity, inventory buffering, and contract structures that can absorb policy variability. For producers, this environment rewards transparency around carbon intensity and the ability to offer compliance-ready documentation alongside product quality. The commercial opportunity lies in serving buyers who need predictable sourcing under changing policy conditions.
Performance-tier segmentation will intensify. As formulators advance chromate-free and ultra-low-VOC systems and as end markets raise durability expectations, the market will increasingly separate into performance tiers. Commodity-grade volumes will remain important, but growth and margin will be more concentrated in applications that demand long service life, high weather resistance, and strict environmental compliance. Suppliers with validated coating systems, clear test data, and application engineering support will have an advantage in specification-driven segments such as architectural cladding, infrastructure, and corrosion-sensitive industrial uses.
Material cost management will become a strategic capability rather than an operational detail. With zinc-linked costs representing a meaningful share of the production cost base, effective raw material procurement, coating formulation optimization, and waste reduction will directly influence profitability. Operators that can align coating selection with application requirements while controlling input costs will be better positioned to maintain margins through commodity cycles. This is particularly relevant for processors serving price-sensitive construction and consumer segments, where small cost advantages can translate into competitive share gains.
PW Consulting
These trends carry risk. Policy directions can shift faster than capacity decisions, and carbon compliance costs may rise as mechanisms mature. Formulation mandates can increase production complexity and require reformulation investment. Demand in construction-linked applications remains sensitive to interest rates, project finance conditions, and regional economic cycles. Participants who overestimate the stability of current trade and demand patterns risk building capacity or sourcing commitments that become suboptimal if conditions change.
Actionable Guidance for Decision Makers
Different roles in the value chain face different priorities, but several strategic moves are broadly relevant.
For manufacturers and processors. Prioritize coating flexibility and compliance documentation as core capabilities. The ability to offer multiple resin systems, demonstrate VOC and chromate compliance, and provide clear performance data will increasingly determine access to specification-driven demand. Where possible, align production and finishing capacity with the markets you serve most frequently to reduce exposure to trade and logistics volatility. In parallel, treat raw material cost management as a strategic lever, integrating supplier relationships, formulation optimization, and yield improvement into a single margin-protection plan.
For investors. Focus on operators with differentiated positioning rather than undifferentiated volume exposure. Companies with strong certification records, application-specific coating expertise, and regional supply alignment are better placed to navigate policy and cost volatility. Assess exposure to carbon-related costs, tariff sensitivity, and the proportion of revenue tied to performance-tier applications versus commodity-grade volume. In markets where consolidation is plausible, look for signs of scale advantage in compliance, process control, and export readiness; in more fragmented settings, look for specialists with durable local relationships and technical service depth.
For procurement and specification teams. Build sourcing strategies that assume continued policy and cost variability. Diversify between domestic and regional supply options where feasible, validate compliance documentation before award, and include coating performance and environmental requirements explicitly in specifications. Where lead time and availability matter, consider the trade-offs between lowest landed cost and supply resilience, especially for applications where re-specification or replacement carries high downstream cost.
The color coated steel market is moving from a phase where aggregate volume growth was the primary narrative to one where policy, performance, and cost structure determine who wins share and where margin is earned. Navigating this environment requires granular understanding of regional dynamics, coating system capabilities, and the evolving requirements of downstream applications. Detailed segmentation data, company-level benchmarks, and scenario-based sourcing analysis can sharpen these decisions significantly. For decision makers who need to move beyond high-level trends into market-specific sizing, competitive mapping, and tailored strategy options, the full research report provides the deeper dataset and structured analysis necessary to support investment, capacity, and procurement choices with greater confidence.
For detailed analysis of this topic, please visit the official page: Color Coated Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
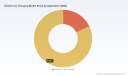
Electric Car Chargers Market: Strategic Trends and Commercial Opportunities
The electric vehicle charging infrastructure sector has shifted from a niche sustainability initiative to a core component of global transportation and energy systems. Over the past half-decade, the market has demonstrated consistent momentum, with revenue scaling from approximately 12.5 billion USD in 2020 to 34.8 billion USD by 2025. Projections through 2032 place the sector on a trajectory toward 143.1 billion USD, supported by a compound annual growth rate of roughly 22.5 percent. This expansion reflects more than incremental adoption; it signals a structural realignment in how electricity is distributed, consumed, and monetized across mobility networks.
USB Car Chargers Market
For executives and investors, the numbers themselves tell only part of the story. The real value lies in understanding what is accelerating deployment, what is constraining it, and where competitive advantages are being forged. The charging ecosystem no longer operates as a standalone hardware play. It intersects with grid capacity, fleet electrification timelines, consumer payment expectations, and increasingly stringent domestic sourcing rules. Companies that treat charging infrastructure as a systems integration challenge rather than a transactional equipment sale are beginning to capture disproportionate margins and market share.
Several inflection points are reshaping the landscape. First, the gap between residential and commercial deployment is widening in strategic importance. While home charging remains foundational for individual vehicle owners, commercial and public charging networks are becoming the primary battleground for scale, utilization rates, and recurring revenue models. Second, the technology mix is bifurcating between slower alternating current solutions and higher-power direct current systems, each serving distinct use cases and requiring different grid interconnections, permitting pathways, and maintenance frameworks. Third, market concentration remains moderate, with the top three players holding a combined share near 35 percent and the top five approaching 42 percent. This fragmentation suggests room for consolidation, but also indicates that regional specialization, software differentiation, and partnership ecosystems matter more than pure manufacturing volume.
Key Drivers Shaping Market Trajectory
Technology Innovation and Performance Thresholds
Charging hardware is evolving from a relatively static product category into a performance-optimized platform. Direct current fast charging continues to advance in power output and thermal management, enabling shorter dwell times for medium- and heavy-duty fleets, ride-hailing operations, and highway corridor deployments. At the same time, alternating current chargers are gaining intelligence through embedded load-balancing algorithms, energy monitoring, and integration with home energy management systems. The practical effect is a market where throughput, reliability, and software responsiveness increasingly determine utilization rather than mere charger availability.
Recent industry activity illustrates this shift. Tritium has been advancing its DC fast charging portfolio through modular platforms designed for ultra-fast public and fleet scenarios, emphasizing scalability and serviceability in high-traffic environments. ZEROVA has focused on high-power commercial and fleet applications, pushing hardware capable of delivering substantial charging capacity in constrained spaces. These developments reflect a broader industry realization that charger specifications must align with operational realities: fleet turnaround windows, peak demand pricing, and site electrical constraints. Companies that design for modular upgrades, remote diagnostics, and predictable uptime are reducing total cost of ownership for operators and improving session completion rates.
Policy and Regulatory Dynamics
Government procurement standards, utility make-ready programs, and domestic content rules are actively shaping where and how infrastructure gets deployed. In the United States, federal-aid projects face evolving Buy America requirements that have prompted discussions about raising domestic content thresholds for EV charger components. Proposed adjustments would increase the required share of domestic component costs, with comment periods and implementation guidance continuing to mature through early and mid-2026. For projects obligated after certain dates, charger compliance frameworks are aligning more closely with general manufactured products rules, which changes how suppliers structure supply chains and document sourcing.
At the state and utility level, interoperability and hardware conformance standards are gaining enforcement traction. Certain public service commission programs have begun requiring ISO 15118-3 hardware conformance for level 2 chargers, signaling a move toward standardized communication protocols that support smoother plug-and-charge experiences, billing transparency, and grid integration. These rules do more than set technical baselines; they influence which products can participate in subsidized programs, how quickly deployments can clear regulatory review, and which manufacturers have the compliance infrastructure to scale across jurisdictions.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are changing the economics of charging networks. Individual consumers increasingly prioritize ease of payment, session reliability, and predictable pricing over raw charger count. Fleet operators and commercial property managers, meanwhile, are evaluating charging infrastructure through the lens of operational continuity, energy cost management, and vehicle utilization schedules. This divergence is pushing vendors to offer more segmented solutions: residential and light commercial options that emphasize installation simplicity and smart energy features, versus high-throughput public and fleet systems built for repeated high-power cycles.
The commercial application segment has become particularly important in revenue terms, reflecting the growing role of workplace charging, retail destinations, logistics hubs, and fleet depots. As more organizations electrify portions of their vehicle assets, charging infrastructure is no longer a peripheral amenity; it is part of the operational backbone. That shift raises the stakes for uptime, remote monitoring, and service response times. It also encourages companies to bundle hardware with network services, energy management tools, and site-level load optimization, creating value beyond the initial equipment sale.
Supply Chain Structure and Cost Dynamics
Hardware manufacturing, component sourcing, and installation capacity remain central to market execution. Domestic content expectations, semiconductor and power electronics availability, and regional manufacturing footprints all influence lead times and pricing stability. Suppliers that can maintain consistent quality while navigating changing procurement rules are gaining an advantage in federally supported and utility-sponsored programs. At the same time, the cost structure of charging deployments is increasingly tied to electrical upgrades, civil works, and network connectivity rather than the charger unit alone. This reality rewards companies that offer streamlined installation pathways, interoperable components, and financing or turnkey models that reduce project friction.
Recent collaboration activity highlights how the industry is adapting to these supply-side realities. Nayax and Tritium announced a global partnership designed to simplify payment enablement for EV chargers. By connecting hardware providers with payment and transaction infrastructure, such arrangements aim to reduce one of the persistent operational pain points: fragmented payment experiences that complicate utilization and revenue reconciliation. In parallel, deployment partnerships are expanding physical networks in targeted corridors. Kempower and Blink Charging, for example, moved forward with a multi-site DC fast charging expansion along the U.S. East Coast, leveraging high-power hardware to strengthen coverage in high-traffic regions. These types of initiatives reflect a market that is increasingly comfortable combining hardware, software, and site development expertise rather than pursuing isolated product launches.
Competitive Landscape and Leading Strategies
The competitive field spans established network operators, hardware specialists, energy technology companies, and regional manufacturers. ChargePoint has built a presence around charging stations and network management solutions spanning home, commercial, and fleet applications, positioning itself around software-enabled session management and broader ecosystem connectivity. Enphase has moved into bidirectional charging, supporting vehicle-to-home and vehicle-to-grid integration that links electric vehicles more tightly with distributed energy resources. This direction points toward a future where chargers function not only as energy consumers but as controllable assets within broader home and grid energy flows.
Other manufacturers are differentiating through durability, compatibility, and targeted use cases. Grizzl-E has emphasized rugged level 2 chargers with multiple connector compatibilities and a domestic manufacturing footprint, participating actively in regional industry events to reinforce brand visibility and dealer relationships. Emporia Energy has focused on smart level 2 chargers with load-balancing and energy monitoring, appealing to users who want visibility into consumption and coordination with household electrical loads. EVOIQO and Apex Charger have concentrated on practical level 2 offerings with flexible installation options and connector-specific designs, addressing residential and light commercial buyers who value straightforward specifications and deployment simplicity.
In the higher-power segment, Tritium and ZEROVA illustrate distinct approaches to fast charging. Tritium’s platform orientation emphasizes modular DC fast charging for public and fleet contexts, while ZEROVA has targeted high-power commercial and fleet applications with substantial output capabilities. The strategic implication is that fast charging is not a single market but a set of segmented requirements: corridor hubs, fleet depots, retail fueling equivalents, and destination sites all place different demands on power delivery, canopy design, electrical service, and maintenance models.
The market structure is evolving through a mix of consolidation, partnership, and specialization. Moderate concentration at the top suggests that scale alone has not yet produced a dominant monopoly-style landscape. Instead, competitive advantage is being built through several overlapping strategies. One is ecosystem integration, where charging hardware is paired with network software, payment services, and energy management features. Another is regional proximity and supply chain resilience, which matters more as domestic content expectations and program eligibility rules tighten. A third is application-specific engineering, where winners design products for clearly defined operational profiles rather than attempting to serve every segment with a single platform.
Trade presence and targeted partnerships are also becoming more important as a signal of execution capability. Grizzl-E’s participation in major industry exhibitions, for instance, reflects the continued relevance of in-person demonstrations, dealer engagement, and hands-on product visibility in a market where installation partners and fleet buyers want to assess build quality, compatibility, and support structures directly. Meanwhile, payment enablement partnerships and multi-site deployment agreements indicate that the industry is moving toward integrated operating models, where hardware reliability, transactional smoothness, and geographic coverage are treated as interconnected commercial priorities.
Forward Outlook: Three Strategic Trends for the Next Three to Five Years
The next phase of market development will likely be defined by integration, standardization, and utilization economics rather than raw charger count alone.
The first trend is the rise of smarter, more interoperable charging networks. As hardware conformance expectations and communication protocols become more firmly embedded in program rules and consumer expectations, chargers that support smooth plug-and-charge interactions, reliable payment processing, and utility-readable data will gain preference. This creates opportunities for manufacturers and service providers that can deliver consistent interoperability across sites and reduce the operational friction that currently depresses utilization in some networks. The commercial opportunity lies in recurring software, maintenance, and energy-management revenue, not just hardware turnover.
The second trend is the continued divergence between residential and commercial deployment pathways. Home charging will remain essential for private vehicle owners, but commercial and public charging will drive a growing share of strategic investment, especially where fleets, high-traffic destinations, and corridor travel converge. Businesses that can optimize commercial sites for load management, peak demand avoidance, and high session throughput will be better positioned to convert infrastructure into dependable operating margins. For residential and light commercial players, the opportunity is in simplifying installation, expanding connector compatibility, and offering intelligent energy features that align with consumer interest in cost visibility and home energy coordination.
The third trend is supply chain and compliance reshaping procurement winners. As domestic content expectations evolve and manufactured product rules become more explicitly aligned with program requirements, suppliers with transparent sourcing, adaptable bill-of-materials strategies, and documentation readiness will face fewer deployment delays. This is especially relevant for federally supported and utility-sponsored programs, where eligibility can determine whether a project moves forward on schedule. Companies that treat compliance as a design and supply-chain function rather than a late-stage paperwork exercise will likely secure more consistent access to capital-intensive deployment pipelines.
PW Consulting
These trends carry risks that decision makers should monitor. Grid capacity and interconnection timelines can constrain site readiness, particularly in areas with rapid deployment interest. Utilization risk remains real in locations where traffic patterns, pricing structures, or payment friction limit session frequency. Regulatory timelines can shift as agencies refine content requirements and program guidance, altering project economics with limited lead time. Finally, hardware reliability and service response continue to influence customer experience and operator reputation; in a market where networks are compared session by session, uptime gaps can translate quickly into lost share.
Actionable Implications for Decision Makers
Different stakeholders face different priority sets, but several strategic moves are broadly relevant.
For hardware and network providers, the priority is to align product roadmaps with operational realities rather than aggregate specifications. That means designing for modular servicing, predictive diagnostics, connector compatibility, and payment interoperability, while also ensuring that supply chains can withstand evolving domestic content expectations. Companies should evaluate whether they compete primarily on hardware performance, network services, energy integration, or geographic coverage, and then build the partnerships necessary to reinforce that position. A clear application focus, supported by reliable installation and service pathways, tends to outperform broad but shallow product portfolios in a market where uptime and user experience drive repeat utilization.
Electric Vehicle Charging App Market
For investors, the opportunity lies in distinguishing between companies that are building durable operating models and those that are relying on short-term subsidy tailwinds or hardware-only economics. Favor businesses that demonstrate recurring revenue potential through software, maintenance, energy management, or transaction services, and that show evidence of compliance readiness and supply chain resilience. Pay attention to deployment partnerships and payment integrations, since these often signal a move toward integrated commercialization rather than standalone product sales. Also weigh regional exposure carefully; markets with strong utility programs, clear procurement rules, and established installation ecosystems will generally outpace fragmented environments where permitting and electrical upgrades slow project velocity.
For commercial buyers and fleet operators, the focus should be on total cost of ownership, session reliability, and site-level energy management rather than sticker price alone. Evaluate charger platforms based on expected utilization profiles, downtime history, remote monitoring capabilities, and the availability of service support in your operating region. Consider how load-balancing, scheduled charging, and potential bidirectional capabilities could reduce demand charges or improve energy flexibility. Engage early with electrical planners and installation partners, because site readiness and interconnection timelines often determine project success more than the choice of charger brand. Where possible, prefer solutions that simplify payment and reporting, since transaction friction frequently undermines utilization and complicates reconciliation across multiple sites.
Why Detailed Intelligence Matters Now
The charging market is moving from rapid qualitative expansion into a more demanding phase where execution quality, regulatory alignment, and utilization economics determine commercial outcomes. In that environment, broad headlines are helpful for orientation but insufficient for planning. Segment-level deployment patterns, regional program eligibility, compliance timelines, and competitor positioning all influence which strategies will hold up under scrutiny. Decision makers who need to prioritize regions, applications, technology paths, or partnership structures benefit from more granular data than a high-level market narrative can provide.
A deeper research resource can help translate these dynamics into specific choices: where to allocate capital, which product segments offer the strongest risk-adjusted opportunity, how regulatory shifts may alter project timelines, and which competitive moves are likely to reshape category leadership. For organizations already operating in the space, that level of detail supports pricing, capacity planning, and go-to-market execution. For those evaluating entry or expansion, it reduces the risk of committing to segments where utilization, compliance, or supply-chain friction is underpriced.
The market trajectory suggests continued scale, but scale alone does not guarantee profitable execution. The companies and investors that perform best over the next several years will be those that treat charging infrastructure as an integrated systems business, align their strategies with evolving rules and user expectations, and base their decisions on segment-level evidence rather than aggregate projections. Detailed research reports can provide the subcategory breakdowns, regional comparisons, and competitive tracking necessary to turn these strategic signals into concrete operational plans and investment committees’ decisions.
For detailed analysis of this topic, please visit the official page: Electric Car Chargers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Shot Blasting Machines Market: Why 6.32% CAGR and Automation Shift Commercial Dynamics
By PW Consulting, 2026-09-21
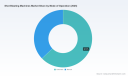
Shot Blasting Machines Market: Strategic Trends and Commercial Opportunities
The global shot blasting machines market is undergoing a structural transformation defined by automation, digital integration, and shifting end-use priorities. With a projected compound annual growth rate of 6.32 percent and an expanding revenue trajectory from approximately $1.5 billion in 2025 toward over $2.3 billion by 2032, the sector reflects sustained industrial demand for surface preparation, cleaning, and finishing solutions. Growth is not merely a function of volume; it is increasingly shaped by how manufacturers align equipment capabilities with stricter cleanliness standards, labor constraints, and operational efficiency targets. Understanding where momentum is building, and which forces are reshaping competitive positioning, is essential for executives evaluating capital deployment, product strategy, or procurement direction.
Market Landscape and Core Challenges
The market has moved through a period of steady expansion, recovering from earlier cyclical softness and reaccelerating as industrial throughput improved across multiple regions. Revenue figures have climbed consistently year over year, supported by replacement cycles, capacity additions in casting and forging, and broader investments in surface treatment infrastructure. This trajectory signals a market that is stabilizing around higher baseline demand, yet one that is also entering a more demanding operational environment where incremental efficiency gains matter as much as unit sales.
Several forces are creating friction and opportunity at the same time. First, the link between surface preparation quality and downstream performance is becoming more visible across metal-intensive industries. Cleanliness, profile consistency, and blast repeatability now carry direct implications for coating adhesion, corrosion resistance, and component life. That makes shot blasting less of a commodity service and more of a controlled process step, raising expectations for equipment precision and documentation.
PW Consulting
Second, labor availability and skill constraints are altering how plants use existing equipment. In several major markets, shortages of experienced metalworking technicians are limiting utilization rates and increasing the cost of manual interventions. This dynamic is pushing organizations to favor machines that reduce operator dependency, simplify changeovers, and maintain output even with thinner skilled-labor pools.
Third, material and consumable volatility is forcing a sharper focus on total cost of ownership. Abrasive media usage, dust handling, and wear-part replacement directly affect operating economics. When media prices fluctuate and alternative materials compete for adoption, manufacturers are increasingly evaluating blast systems not only by purchase price but by consumption control, recovery efficiency, and integration with broader material management practices. These challenges are not purely restrictive; they are also helping separate operators who treat blast cleaning as a cost center from those who treat it as a process capability that can be optimized.
Key Drivers Reshaping the Market
Market momentum is being driven by a combination of technology maturation, regulatory pressure, demand-side behavior, and supply-side cost dynamics. These drivers are interacting, not operating in isolation.
Technology Innovation and Process Control
The most visible shift is the move from standalone mechanical systems toward connected blast platforms that provide visibility into media consumption, wheel wear, and process consistency. Intelligent monitoring and data-linked controls are making it easier to balance output quality with consumable usage. For operators, that means fewer unplanned interruptions, more predictable cleaning results, and stronger alignment between surface preparation and downstream workflow. The practical value is not just automation itself, but the ability to standardize results across shifts, batches, and product mixes.
Alongside connectivity, equipment design continues to evolve around throughput, ergonomics, and serviceability. Machines are being configured to handle a wider range of part geometries and throughput requirements while reducing manual handling. That is especially relevant where mixed production schedules or shorter runs demand flexible equipment rather than rigid high-volume lines. The market is increasingly rewarding systems that combine repeatability with practical adaptability.
Regulatory and Standards Pressure
Regulatory expectations around worker exposure, dust control, and surface cleanliness are strengthening the case for more controlled blast environments. Filtrations, containment, and protective features are becoming central to equipment selection rather than peripheral add-ons. In parallel, widely referenced surface cleanliness standards are pushing structural fabricators and metal processors toward more consistent automated preparation methods.
Cast Steel Shot & Grit Market
The commercial consequence is twofold. Equipment that can demonstrate reliable compliance and cleaner outputs gains a qualitative advantage in bid-sensitive environments. At the same time, buyers are less willing to treat blast capacity as interchangeable, since cleanliness and handling requirements increasingly influence qualification decisions. This is expanding the premium on engineered systems that integrate dust management, media recovery, and controlled blast intensity into a cohesive process.
Demand-Side Shifts in End-Use Industries
End-use demand is becoming more segmented and performance-driven. Automotive and aerospace remain influential, but the nature of demand is shifting toward consistent surface quality, tighter throughput expectations, and components that must meet demanding service environments. Foundries and metal processors continue to rely on shot blasting for casting cleaning and scaling removal, but they are also weighing equipment against broader line efficiency and inspection readiness. Construction, rail, shipbuilding, and other industrial applications contribute to demand in their own ways, particularly where heavy components, infrastructure materials, or repaired assets require dependable surface treatment.
A notable change is that buyers increasingly view blast equipment as part of a broader quality and throughput system. That means machine selection is more closely tied to downstream finishing, coating, inspection, and rework reduction. The implication is that performance claims grounded in process control, media efficiency, and repeatable outcomes are becoming more persuasive than broad equipment descriptions alone.
Supply Chain and Cost Structure Dynamics
Cost pressures are reshaping purchasing logic. Raw material swings, regional production differences, freight variability, and service-part availability all influence the delivered economics of shot blasting equipment. As a result, buyers are paying more attention to system-level operating costs, including media life, wheel wear, filtration load, and maintenance downtime. This is particularly important in environments where machines run frequently and downtime carries disproportionate production penalties.
Shot Peening Machine Market
At the same time, regional manufacturing footprints are becoming strategically relevant. Localized support, faster parts availability, and proximity to end markets can reduce operating risk. In several cases, expanding production capacity in or near high-growth regions is being used to improve service response and strengthen competitive positioning. This points to a market where hardware capability still matters, but responsiveness and execution may differentiate suppliers as much as product specifications.
Competitive Landscape and Leading Strategies
The competitive field is diversified, with global players, regional specialists, and application-focused manufacturers coexisting across different machine types, technologies, and service models. Market concentration remains moderate, indicating that share is distributed across a broad set of participants rather than resting with a small group of dominant incumbents. That structure leaves room for differentiation through technology, application expertise, regional presence, and aftermarket support.
Strategic Positioning of Leading Players
Several companies illustrate distinct strategic arcs within the market. International manufacturers with broad portfolios are emphasizing integrated solutions that span wheel blast and air blast systems, batch and continuous processes, and industrial surface preparation across multiple end markets. Their positioning tends to rely on a wide application base, global service networks, and established product ranges that can be adapted to varied customer requirements.
Other players have leaned toward engineering depth and digital-enabled process control. Smart platform capabilities, real-time wear monitoring, and integration with plant systems are being used to position equipment as a productivity and quality enabler rather than a standalone cleaning device. This strategy is particularly relevant for customers seeking consistent output and lower consumable waste in demanding production environments.
Regional and specialized manufacturers continue to play an important role by focusing on specific machine configurations, material types, or local support expectations. Their advantage often lies in responsiveness, customization, and close alignment with regional fabrication or foundry practices. For buyers prioritizing shorter lead times, local service, or application-specific tuning, these suppliers can be highly competitive.
Recent Moves Shaping the Landscape
Recent activity highlights where competition is intensifying. The rollout of IoT-linked blast platforms with analytics for abrasive media consumption and wheel wear points to a market that is moving toward data-informed operation. Demonstrations combining live performance testing, augmented reality, and optimization sessions indicate growing interest in practical efficiency gains rather than product novelty alone. Participation in international trade events and facility expansion in high-growth regions further suggests that manufacturers are investing in visibility, capacity, and localized support to capture demand more effectively.
Taken together, these developments suggest a competitive environment in which differentiation is increasingly built on three layers: core machine reliability, process intelligence, and service responsiveness. Companies that can align those layers with customer operating priorities are better positioned to capture share in a market where specifications alone are no longer a sufficient advantage.
Consolidation, Fragmentation, and New Entry
The market is not trending toward rapid monopoly-style consolidation. Instead, it appears to be evolving through selective consolidation at the service and technology levels while remaining broad at the product level. Larger players may pursue complementary capabilities, regional reach, or application coverage, but fragmentation persists because blast cleaning requirements vary widely by part type, material, throughput, and labor context. New entrants can still find opportunity by serving niche applications, offering lower-cost configurations, or focusing on fast regional support. However, long-term credibility tends to depend on consistent performance, parts availability, and the ability to demonstrate measurable savings in media usage, downtime, and rework.
Future Trends to Watch
Over the next three to five years, several trends are likely to define how the market evolves and where commercial value accumulates.
- Process intelligence becomes standard rather than exceptional. Connected monitoring, consumables analytics, and integration with plant systems will increasingly be expected in higher-value installations. The commercial opportunity lies in reducing total operating cost, improving consistency, and making blast performance easier to manage across shifts and product variations.
- Automation and labor-efficient designs gain preference. As skilled-worker constraints persist in several regions, equipment that reduces manual intervention, simplifies setup, and supports steady utilization will be favored. This trend creates opportunities for manufacturers who can prove that their machines maintain output with fewer dependent labor inputs.
- Compliance and cleanliness become stronger purchase criteria. Regulatory expectations and surface quality requirements will continue to push buyers toward equipment with better containment, filtration, and repeatable surface preparation. Suppliers that can tie equipment capabilities to documentation, consistency, and risk reduction will have an advantage in qualified and bid-sensitive environments.
These trends are not risk-free. Technology integration can raise upfront complexity and require training, data management, and support infrastructure that smaller users may find difficult to absorb. Material price volatility can still disrupt operating budgets, especially when alternative media options shift demand patterns. And if regional economic conditions slow capital investment, demand may become more replacement-driven than expansion-driven, which would reward reliability and service more than new unit sales. Capital intensity, installation constraints, and the need for practical process adaptation also mean that the strongest opportunities will likely accrue to players who can pair advanced functionality with implementable, site-specific solutions.
Actionable Guidance for Decision Makers
For manufacturers, the strategic priority is to move beyond equipment selection as a purely mechanical decision. Investments should be evaluated against total operating cost, cleanliness consistency, service accessibility, and integration with existing production workflows. The most resilient product and capacity strategies are likely to emphasize flexible configurations, measurable consumable efficiency, and support models that help customers sustain utilization. Companies that can demonstrate how blast performance reduces downstream rework or improves coating readiness will find stronger commercial traction than those competing mainly on headline specifications.
For investors, the attractive question is not simply whether demand will continue to grow, but which business models can convert growth into durable margins. Preference should be given to organizations with clear aftermarket revenue streams, repeatable installation and service processes, and credible differentiation in efficiency or compliance-related capabilities. It is also worth watching how regional expansion, localized support, and digital-enabled offerings reshape competitive dynamics, since these factors can influence both market share and long-term return profiles.
For procurement and operations leaders, the practical focus should be on total cost of ownership and process reliability. Selection criteria should include media consumption behavior, wear-part accessibility, filtration and containment readiness, changeover simplicity, and the supplier’s ability to support consistent utilization. Where possible, buyers should seek performance evidence tied to their own part types and throughput conditions rather than relying on generic capability claims. Aligning blast equipment with downstream quality requirements and labor realities can materially reduce operating risk.
Strategic decisions in this market are best made with detailed segmentation, regional nuance, and application-specific benchmarks in view. A targeted view of machine types, technology preferences, operational modes, end-use demand, and regional dynamics can clarify where investment, procurement, or partnership opportunities are most likely to pay off. For decision makers seeking a deeper breakdown of market size by segment, regional trajectories, competitive positioning, and scenario-based demand outlooks, the full PW Consulting report provides the supporting detail needed to translate these trends into concrete next steps.
For detailed analysis of this topic, please visit the official page: Shot Blasting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Refrigeration Equipment Market: Why Asia Pacific and Ammonia Redefine the 4.9% CAGR Outlook
By PW Consulting, 2026-09-21
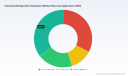
The Industrial Refrigeration Equipment Market: Navigating the Next Wave of Growth and Transformation
The industrial refrigeration equipment market is entering a structurally distinct phase. Over the 2020 to 2025 period, the market expanded from approximately $17.87 billion to $22.70 billion, reflecting a compound trajectory that has outpaced many adjacent industrial segments. The forecast period through 2032 points to continued expansion, with revenue projected to reach roughly $31.73 billion, translating to a compound annual growth rate of 4.9 percent. These figures represent more than incremental capacity additions; they signal a market transitioning from steady replacement cycles to a demand profile shaped by regulatory mandates, refrigerant transitions, and capital expenditure patterns that favor higher-efficiency, lower-emission architectures.
Beneath the headline growth lies a landscape that is simultaneously fragmented in execution and increasingly concentrated in strategic influence. The market continues to operate with a moderate concentration profile, where the top three participants command roughly 38 percent of total revenue and the top five approach 46 percent. This structure suggests that while regional specialists, engineering firms, and component suppliers retain meaningful share, scale players and technology-focused incumbents are widening their influence through integrated system offerings, expanding service footprints, and partnerships that reduce project risk for end users. For executives and investors, the implication is clear: the market is large enough to sustain multiple business models, yet selective enough that differentiation in technology, compliance readiness, and service economics will increasingly determine who captures disproportionate value.
Market Context and Strategic Challenges
The current market environment is defined by a collision of long-cycle infrastructure demand and fast-moving regulatory and technological change. Three challenges stand out as particularly consequential for companies operating across the industrial refrigeration value chain.
First, the refrigerant transition has moved from a compliance topic to a design constraint that influences equipment architecture, component selection, and total cost of ownership. Natural refrigerant platforms, especially carbon dioxide and ammonia, are increasingly central to new installations and major retrofits. However, the shift is not uniform. Different applications impose different safety, efficiency, and operating-pressure requirements, and the pace of adoption varies by region, sector, and capital budget. Equipment manufacturers and system integrators are therefore being asked to support a broader portfolio of solutions while maintaining engineered reliability across diverse operating conditions.
Second, cost pressure on inputs is reshaping project economics. Tariff actions affecting steel and aluminum imports have pushed up the cost of compressors, condensers, and structural frameworks. In industrial refrigeration, where systems often represent large capital projects with long payback expectations, material cost volatility can alter bid dynamics, compress margins, and delay commitment cycles. The challenge is not simply higher input prices, but managing the ripple effects through supply agreements, lead-time planning, and value engineering without compromising durability or energy performance.
Third, the market is navigating a complex and evolving standards environment. Regulatory provisions targeting high-global-warming-potential refrigerants, combined with energy efficiency priorities and updated safety standards, are raising the bar for system design and operation. For operators, this means more scrutiny on refrigerant choice, maintenance practices, and lifecycle performance. For suppliers, it means that product differentiation is increasingly tied to compliance readiness, documentation, training, and the ability to support customers through transitions rather than simply shipping hardware.
These challenges should not be read only as headwinds. They are also reshaping the basis of competition. Companies that can offer lower-risk transitions, stronger energy performance, and more predictable project execution are finding greater leverage with customers who must balance operational continuity with regulatory and sustainability obligations.
Core Drivers Shaping the Market
Several forces are working in Concert to reshape demand, pricing, and competitive positioning across industrial refrigeration. The most consequential can be grouped into technology, policy, demand-side behavior, and supply-side cost structures.
Technology Innovation and the Rise of Natural Refrigerant Systems
The most visible technical shift is the acceleration of carbon dioxide and ammonia-based solutions in commercial and industrial applications. Recent industry activity highlights how rapidly these platforms are moving from specialized niches into broader mainstream consideration. At AHR Expo 2026, for example, the exhibition floor featured a strong showing of CO2-based products, including condensing units, transcritical and subcritical compressor technologies, and specialized valves and fittings designed for natural refrigerant systems. This level of visibility matters because it signals that suppliers are not only advancing individual components but also building out integrated ecosystems around refrigerants that require distinct engineering approaches.
For the market, the practical implication is that equipment roadmaps are increasingly aligned with refrigerant performance curves, system controls, and safety architecture. Companies that can combine compressors, heat exchangers, valves, and controls into coherent, application-specific solutions are better positioned to reduce integration risk and improve system reliability. At the same time, component-level innovation remains essential. Specialized fittings, check valves, and ball valves for high-pressure CO2 environments illustrate how seemingly narrow product categories can become critical enablers of broader adoption.
Policy and Regulatory Pressure as a Market Catalyst
Policy is no longer a peripheral factor. In the United States, EPA Technology Transitions provisions under the AIM Act have established a schedule that bans HFC refrigerants with a GWP above 700 in new industrial process refrigeration chillers starting January 1, 2026, with additional phased limits tightening to a GWP of 300 for certain cold storage applications. Broader EPA rules effective at the same date prohibit high-GWP refrigerants across new commercial and industrial refrigeration systems. These timelines create a concrete forcing function for equipment selection and replacement planning.
In parallel, energy efficiency is becoming a more prominent policy target. Industrial refrigeration compressors have been identified by the U.S. Department of Energy as a priority category for energy efficiency standards, reflecting the scale of energy consumption in food and pharmaceutical manufacturing. This matters because it links refrigerant policy with operational cost policy. Customers are increasingly asked to optimize for both environmental compliance and energy consumption, which elevates the strategic importance of high-efficiency compressors, improved heat exchange design, and controls that adapt to load variability. Updated industry standards, such as revised industrial refrigeration guidelines incorporating the latest ISO and safety requirements, further reinforce the direction of travel toward more formalized design and operational practices.
Demand-Side Change Across Food, Pharmaceutical, and Industrial End Markets
Demand is being reshaped by more than regulatory compliance. Cold chain reliability, production quality, and operational resilience have become priority concerns across multiple end-use sectors. In food and beverage operations, temperature control remains foundational to product quality and safety, but customers also care about throughput, redundancy, and energy intensity. In pharmaceutical applications, precision and reliability are paramount, and refrigeration systems are increasingly viewed as part of a broader quality and compliance infrastructure rather than isolated mechanical assets. Chemical processing and other industrial uses add further complexity, where refrigeration may be tied to process conditions, batch consistency, and facility-level efficiency goals.
Road Transport Refrigeration Equipment Market
A notable demand-side dynamic is the shift toward lifecycle thinking. Buyers are increasingly looking beyond first cost and considering the broader economics of refrigerant choice, maintenance requirements, service availability, and expected energy consumption over the life of the system. This does not eliminate price sensitivity, but it does change the criteria by which solutions are evaluated. Suppliers that can articulate and deliver on total cost of ownership, including compliance and service considerations, are better positioned to compete in capex-heavy and mission-critical environments.
Supply Chain Dynamics and Cost Structure Sensitivity
The cost environment remains an important driver of market behavior. Tariff-related increases on steel and aluminum have affected key structural and mechanical components, adding uncertainty to project planning and procurement. In an industry where lead times, sourcing reliability, and build quality all affect customer confidence, input cost volatility can have outsized effects on quoting, scheduling, and margin management.
At the same time, supply chain dynamics are encouraging greater attention to sourcing strategy and design flexibility. Some manufacturers are revisiting material specifications, supplier diversification, and inventory buffers to reduce exposure. Others are using system architecture choices to optimize cost and performance simultaneously, for example by balancing component consolidation against redundancy and serviceability. These adjustments are not merely defensive; they can become sources of advantage when executed with discipline and transparency.
Competitive Landscape and Leading Strategies
The competitive field in industrial refrigeration equipment is diverse, spanning commercial and industrial unit manufacturers, compressor specialists, component suppliers, and project-oriented system integrators. Rather than a single dominant model, the market rewards different forms of differentiation depending on the customer segment and application.
Several companies illustrate the range of strategic positions now in play. Heatcraft Refrigeration Products focuses on unit coolers, condensers, and evaporators for commercial and industrial refrigeration applications, positioning around core components that are widely specified across multiple system architectures. Magna Industrial Refrigeration provides industrial refrigeration equipment, components, and solutions, including unit coolers for commercial and industrial use, reflecting a strategy centered on breadth of product availability and application coverage. NDL Industries emphasizes high-pressure CO2 fittings, valves, check valves, and three-way valves for industrial refrigeration and natural refrigerant systems, illustrating how a component-focused specialist can play a vital role in enabling refrigerant transitions.
PW Consulting
On the compressor and system side, Danfoss, Copeland, and Bock GmbH represent technology-driven positions that emphasize solutions for low-temperature and transcritical CO2 applications, along with compressor platforms tailored to industrial cold storage and process cooling. These players are competing not just on hardware, but on the ability to offer engineered solutions that simplify adoption of natural refrigerants and support specific performance targets. Frigo Mekanik represents a complementary model, specializing in project design, manufacturing, and turnkey installation of industrial refrigeration cooling systems. This approach highlights the continuing importance of integration capability, especially where site-specific constraints, local service requirements, and project execution risk are significant.
Recent industry activity reinforces the direction of these strategies. The IIAR Natural Refrigeration Conference and Heavy Equipment Expo featured exhibitors such as Magna Industrial Refrigeration by Heatcraft, underscoring continued engagement with industrial refrigeration and natural refrigerant safety and equipment. Meanwhile, Frigo Mekanik’s participation in the HVACR Egypt Expo 2026 points to the regional expansion of project-oriented players seeking exposure to international demand and project pipelines. On the event calendar, RETA’s national conference continues to provide a focused forum for industrial refrigeration systems and components, reinforcing the importance of concentrated industry gatherings in shaping technology diffusion, standards awareness, and supply chain relationships.
Worldwide Compression Refrigeration Machine Market
The competitive trends that emerge from this landscape are best described as selective integration paired with targeted specialization. Larger players are broadening their offerings to reduce customer friction across specification, installation, and service, while specialized suppliers are deepening their role in critical subsystems that become differentiators in natural refrigerant applications. The market is not necessarily moving toward a single consolidated model; instead, it is evolving toward ecosystems in which components, compressors, controls, and project capabilities are combined in ways that reduce total risk for the buyer. In that environment, companies that can demonstrate compliance readiness, reliable performance under changing refrigerant regimes, and strong service economics are likely to capture a disproportionate share of high-value projects.
Forward Outlook: Trends and Opportunities for 2026 to 2030
Looking ahead, the market is likely to be shaped by a small number of reinforcing trends that translate into defensible commercial opportunities for well-positioned players.
One major trend is the continued mainstreaming of natural refrigerant solutions in new builds and retrofits. As regulatory deadlines take effect and customer expectations around environmental performance rise, CO2 and ammonia platforms will see increasing specification in a wider range of applications. The commercial opportunity lies not just in selling equipment, but in helping customers manage the engineering, safety, and operational implications of these systems. Suppliers that can standardize design approaches, simplify commissioning, and provide robust field support will be better positioned to scale adoption without eroding reliability.
A second trend is the tightening link between refrigerant policy and energy efficiency. As efficiency standards and compliance requirements reinforce one another, end users will increasingly look for solutions that reduce both emissions exposure and operating cost. This creates opportunities around high-efficiency compressors, improved heat transfer designs, advanced controls, and integrated monitoring that supports optimization over time. The upside is especially significant in sectors with high utilization and sensitive temperature requirements, where even modest efficiency improvements can translate into meaningful operational savings.
A third trend is the growing importance of service, lifecycle support, and standards-based execution. As systems become more specialized and regulations more detailed, the value of post-sale support rises. Customers will increasingly favor partners that can help with maintenance planning, technician training, spare parts availability, and compliance documentation. This shift favors companies that treat service not as an afterthought, but as a core part of the commercial proposition. It also raises the stakes for component and equipment suppliers to design for maintainability and to align their offerings with updated industry standards and safety practices.
These trends are not without risk. The pace of adoption may vary by region and application, and customers may delay capital decisions if cost pressures, interest rates, or project timelines become unfavorable. Material cost volatility can continue to complicate bidding and margin planning. In addition, technological transitions can create temporary friction, especially where engineering expertise, trained labor, or supply availability lag behind product availability. Companies should therefore treat natural refrigerant leadership as a long-term play that requires disciplined execution, not simply a product-line expansion.
Strategic Implications for Decision Makers
The most useful way to approach this market is to align strategy with the forces that are most likely to determine purchasing decisions and competitive outcomes over the next several years. The following recommendations are intended to separate signal from noise and focus action where it matters most.
For equipment manufacturers and system integrators, the priority is to reduce the friction of transition. This means developing and communicating clear pathways for natural refrigerant adoption, strengthening integration across components and controls, and reinforcing service and training capabilities that lower customer risk. Where material cost pressure is persistent, value engineering and supply chain resilience should be treated as strategic capabilities rather than transactional tasks. Differentiation will increasingly come from how well a company helps customers navigate compliance, efficiency, and reliability together.
For investors and strategic partners, the opportunity is to identify businesses whose value is tied to durable shifts rather than short-cycle demand. Indicators of resilience include exposure to applications with high uptime requirements, strong positions in components or subsystems essential to natural refrigerant systems, and service models that generate recurring value beyond initial equipment sales. It is also worth watching how companies adapt to cost volatility and whether they can convert regulatory pressure into differentiated offerings rather than treating it as a compliance burden.
For procurement leaders and end-user organizations, the focus should be on total cost and transition risk. Specifying equipment with an eye toward lifecycle energy performance, refrigerant compliance, service availability, and ease of maintenance can reduce exposure to future regulatory changes and operating cost escalation. Where capital projects are planned, early engagement with suppliers on system architecture, standards alignment, and local support can improve execution certainty and reduce the likelihood of costly rework or delayed commissioning.
For all of these audiences, timely access to detailed market data can sharpen decision-making. Segment-level dynamics, regional demand patterns, competitive moves, and regulatory timelines all influence how opportunities should be prioritized. A focused view of these variables helps turn broad market growth into a more actionable plan, especially when decisions involve capital intensity, long service life, and compliance-sensitive technologies.
Closing Perspective
The industrial refrigeration equipment market is large, expanding, and increasingly governed by structural forces that reward clarity of strategy. Growth to the mid-2030s is expected to remain steady, but the more important story is how that growth is being shaped by refrigerant transitions, efficiency priorities, input cost pressures, and the rising importance of service and integration. Companies that can combine technical strength with compliance readiness, project reliability, and lifecycle value will be best positioned to convert market expansion into durable advantage. For executives, investors, and procurement leaders, the practical task is to use these signals to prioritize where to invest, where to differentiate, and where to reduce risk before the next wave of regulatory and demand-side change fully settles in.
For detailed analysis of this topic, please visit the official page: Industrial Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


