

Blogs
Kiosk Market 2026: Why 15.6% CAGR and Asia Pacific Expansion Change Everything
By PW Consulting, 2026-09-21
The Kiosk Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global kiosk market has evolved from a niche self-service experiment into a foundational layer of modern retail, financial services, hospitality, and public sector infrastructure. With a base-year market valuation of approximately USD 394.9 million in 2025 and a projected trajectory to USD 1,089.4 million by 2032, the sector is expanding at a compound annual growth rate of 15.6% across the 2026–2032 forecast window. Historical momentum reinforces this trajectory: the market moved from USD 191.3 million in 2020 to USD 343.89 million in 2024, reflecting a structural shift rather than a cyclical spike. This growth is not merely a function of unit proliferation. It represents a broader realignment in how organizations design customer touchpoints, manage labor allocation, and deploy connected hardware at scale. Understanding where the market stands today, what is driving its acceleration, and how incumbents are positioning themselves is essential for executives navigating procurement decisions, capital allocation, and product roadmap planning.
Despite the optimistic trajectory, the kiosk sector is confronting a set of structural tensions that will define competitive outcomes over the next several years. First, hardware reliability and total cost of ownership have emerged as critical pressure points. Deployments are increasingly expected to operate continuously in high-traffic environments, yet component cost volatility and supply chain friction are compressing margins for manufacturers and raising the bar for operational durability. Second, the regulatory and standards landscape is tightening around payment security, accessibility, and network modernization, forcing vendors to align hardware architecture with compliance requirements that vary across jurisdictions. Third, the market is experiencing a strategic fork in the road between standardized, high-volume deployments and highly customized, vertical-specific solutions. Companies that attempt to serve both models without clear architectural boundaries risk dilution, while those that commit to a distinct value proposition are capturing defensible share. These dynamics are not temporary headwinds; they are reshaping the basis of competition.
Key Drivers Reshaping the Kiosk Market
Technology Innovation and Hardware-Software Convergence
The most consequential driver of market expansion is the convergence of hardened hardware, embedded computing, and intelligent software layers. Kiosk deployments are no longer standalone terminals; they are becoming managed nodes within broader digital ecosystems. Recent product activity illustrates this shift clearly. In February 2026, KIOSK Information Systems launched ergonomic Windfall Series kiosks built with AOPEN hardened processing units, a move explicitly aimed at addressing reliability concerns in digital front-door deployments. That same company expanded its software ecosystem in March 2026 through a partnership with OpenTech Alliance to deploy INSOMNIAC self-storage software on the Windfall Series, signaling a broader trend toward bundling purpose-built applications with durable hardware platforms. The implication for the market is straightforward: competitive advantage is increasingly determined by how seamlessly hardware, operating software, and vertical applications integrate, rather than by hardware specifications alone.
Beyond core hardware, digital payment architecture is reshaping the design constraints of kiosk systems. PCI PIN on Glass rules now apply to kiosk hardware supporting contactless payments, requiring manufacturers to embed secure cryptographic handling directly into the display and input chain. This regulatory-technical intersection is pushing vendors to rethink bill-of-materials architecture, certification cycles, and long-term software support. Companies that treat compliance as an afterthought face retrofit costs and deployment delays, while those that design for secure payment workflows from the outset are shortening time-to-market and reducing integration risk for end customers.
Self-service Kiosk Market
Policy, Regulatory, and Infrastructure Dynamics
Regulatory and infrastructure developments are simultaneously easing some constraints while introducing new cost structures. On the connectivity side, the FCC’s March 5, 2026 Report and Order reduced regulatory burdens on network modernization for broadband infrastructure, a change that supports more reliable back-end connectivity for distributed kiosk fleets. Improved connectivity lowers the operational risk of cloud-managed kiosks and remote monitoring, which in turn makes large-scale deployments more viable for retail, hospitality, and public-sector operators. This is a meaningful enabler, particularly for organizations that depend on centralized fleet management and real-time software updates.
At the same time, hardware cost pressures are intensifying. Semiconductor tariffs on components raised build and operating costs for kiosk hardware in 2026, squeezing manufacturers that rely on imported processing units, displays, and peripheral controllers. Compounding this, regional infrastructure policies are reshaping the broader technology cost environment. In Alberta, a new policy effective December 31, 2026 requires data centers drawing 75 MW or higher to pay a 2% levy on computer hardware, and states advanced grid infrastructure accountability policies in 2026 are requiring data centers to offset upgrade costs. While these measures target large-scale data infrastructure, they reflect a broader policy environment in which compute and hardware expenditures are increasingly scrutinized. For kiosk vendors and enterprise buyers alike, this environment reinforces the importance of total-cost modeling, energy efficiency, and lifecycle planning rather than focusing solely on upfront unit pricing.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, the kiosk market is being pulled forward by two reinforcing behavioral shifts. Consumers and business customers increasingly expect fast, consistent, and contactless self-service options, particularly in QSR, retail, and financial services environments where queue reduction and transaction speed directly influence satisfaction and throughput. Enterprises, meanwhile, are reevaluating labor deployment models. Self-service kiosks are no longer viewed simply as cost-reduction tools; they are increasingly positioned as service-quality multipliers that free skilled staff for higher-value interactions while standardizing routine transactions. This reframing broadens the addressable use cases and supports adoption beyond traditional high-volume settings.
Accessibility is another demand-side force that is moving from compliance checkbox to competitive differentiator. In August 2025, LG Electronics USA unveiled Gen 2 accessible self-ordering kiosks developed with a Tech for All consultant, designed for users with vision, mobility, and hearing disabilities. This product direction signals a broader market expectation: inclusive design is becoming a baseline requirement rather than a niche feature. Organizations deploying kiosks in public-facing roles are increasingly evaluated on how well their self-service infrastructure serves a full spectrum of users, and vendors that embed accessibility into hardware ergonomics, software navigation, and payment workflows are gaining an advantage in regulated and high-visibility environments.
Supply Chain and Cost Structure Evolution
The cost structure of kiosk manufacturing and deployment is undergoing a measurable transition. Component tariffs, processing unit availability, and durable enclosure requirements are pushing manufacturers to reconsider sourcing strategies, standardization levels, and build-vs-integrate decisions. At the same time, the rise of hosted and software-driven add-ons is changing how value is captured across the stack. In November 2025, Datacap Systems launched a Virtual Gift Card program as a hosted digital gift card add-on for kiosk deployments, an example of how software services can layer onto hardware platforms to create recurring revenue and enhance the end-user experience without requiring a full hardware redesign. This hybrid model—durable hardware combined with modular software services—offers a path to offset hardware margin pressure while improving customer stickiness. For manufacturers, the strategic question is whether to build these software capabilities internally, partner for them, or integrate third-party hosted services into a managed offering.
Competitive Landscape and Leading Strategies
The kiosk market is characterized by a mix of specialized hardware manufacturers, vertically focused solution providers, and broader technology companies extending into self-service deployments. Market concentration reflects a moderately consolidated environment, with the top three players holding roughly 60% of market share and the top five approaching 65%. This concentration suggests that scale, brand trust, and deployment ecosystems matter, but it also leaves meaningful room for specialized players that serve distinct verticals or accessibility needs. The competitive dynamics are best understood by examining how leading companies differentiate rather than by treating the market as a single commodity battleground.
NIOSK Information Systems exemplifies a deployment-oriented strategy centered on design, manufacturing, monitoring, and support across retail, self-storage, healthcare, government, and hospitality. Its February 2026 Windfall Series launch and March 2026 OpenTech Alliance partnership reflect a clear emphasis on reliability and application-specific integration, particularly in self-storage and digital front-door use cases. This approach positions the company as an end-to-end partner for organizations that want a single point of accountability for hardware durability and software ecosystem compatibility. Elo Touch Solutions, by contrast, anchors its offering in self-service kiosks and touchscreens for retail, QSR, and healthcare, leaning on display and interface expertise that matters in high-interaction environments. Its competitive leverage lies in touch fidelity, ergonomic design, and application familiarity across sectors where user interaction quality directly affects throughput and satisfaction.
LG Electronics USA has carved out a distinctive position around accessibility with its Gen 2 self-ordering kiosks designed for vision, mobility, and hearing disabilities. This is not merely a product feature but a strategic positioning that aligns with regulatory expectations and inclusive service mandates. Diebold Nixdorf brings a different angle, providing intelligent kiosks for banking, retail, and the public sector with IoT and cloud management capabilities. Its strength is in managed infrastructure thinking: kiosks as connected, monitorable assets within a broader fleet, which appeals to organizations that prioritize remote oversight, predictive maintenance, and integration with existing enterprise systems. NCR Corporation complements this landscape with AI-powered self-service and contactless kiosks for retail and hospitality, leaning into intelligent transaction handling and contactless experience design. Together, these players illustrate a market where differentiation is increasingly defined by the combination of hardware durability, software intelligence, accessibility, and fleet management maturity.
The broader field further highlights the fragmentation of specialized use cases. Companies such as Redyref, Olea Kiosks, MetroClick, Advanced Kiosks, Pyramid Computer, Acrelec, Coates Group, Meridian, ZIVELO, Embross, Neumo, AOPEN, Posiflex, and HiStone each emphasize distinct value propositions, from interactive digital building directories and ADA-compliant self-service units to hardened processing units, Android-based kiosk computers, and QSR-focused self-ordering hardware. Acrelec’s position as a large global hardware and software supplier for self-ordering in QSR and retail underscores how vertical specialization can scale internationally, while Neumo’s focus on DMV and government self-service kiosks shows how public-sector requirements create durable, regulation-driven demand. HiStone’s expansion from a primarily domestic Chinese market into international channels points to the growing cross-border flow of kiosk hardware and the increasing relevance of cost-competitive manufacturing in the global supply picture.
The competitive evolution is moving along three observable paths. First, there is consolidation pressure among suppliers that can offer integrated hardware, software, and managed services at scale, particularly in retail, QSR, and banking. Second, there is continued differentiation among niche leaders serving accessibility, public-sector, and bespoke environments where customization and compliance outweigh volume economics. Third, new entrants and adjacent technology providers are exploring the space through modular computing, Android-based platforms, and hosted software add-ons, lowering barriers for organizations that want to assemble solutions rather than buy fully integrated units. The likely outcome is a layered market: a concentrated core of scaled providers competing on reliability, fleet management, and vertical breadth, surrounded by specialized manufacturers and software partners competing on accessibility, custom design, and application-specific functionality.
Kiosk Printer Market
Future Trends and Commercial Opportunities (2026–2032)
Trend 1: Managed, Cloud-Integrated Kiosk Fleets Become the Default Expectation
As deployments scale, the operational model is shifting from standalone installation to managed fleet infrastructure. Cloud-managed monitoring, remote updates, and IoT-enabled diagnostics are becoming baseline expectations rather than premium features. The practical effect is that buyers will increasingly evaluate kiosk investments through the lens of uptime, maintenance cost, and software lifecycle support, not just unit price. For manufacturers, this creates an opportunity to build managed service layers that improve stickiness and reduce support fragmentation. For enterprise buyers, it opens the door to predictable operating models and faster issue resolution across distributed locations. The risk is that vendors without robust backend management capabilities will face growing pressure as customers compare total operational performance rather than hardware specs at purchase time.
PW Consulting Information & Electronics Research Center
Trend 2: Accessibility and Inclusive Design Move from Compliance to Brand Value
Accessibility will increasingly function as both a regulatory requirement and a commercial differentiator. Product activity such as LG’s Gen 2 accessible self-ordering kiosks indicates where the market is heading: inclusive ergonomics, multimodal interaction, and payment workflows designed for a broader range of users. As public-facing deployments expand in retail, hospitality, transportation, and government settings, organizations that treat accessibility as a design standard rather than a retrofit will reduce compliance exposure and improve user experience quality. The commercial opportunity lies in developing modular accessibility features that can be integrated across product lines without fragmenting manufacturing scale. The uncertainty is in how quickly standards and customer expectations will converge across regions, which could create uneven compliance timelines and redesign pressure for vendors with global footprints.
Trend 3: Software-Layered Revenue Models Offset Hardware Cost Pressure
With semiconductor tariffs and broader hardware cost pressures reshaping build economics, the market is likely to see more hosted software add-ons, digital payment enhancements, and application-specific services layered onto kiosk platforms. Datacap’s hosted digital gift card add-on is a useful signal of this direction: value is increasingly created through software services that enhance the transaction experience and create recurring engagement without requiring a full hardware redesign. Over the next several years, this trend should encourage more partnerships between hardware manufacturers and software providers, as well as more packaged solutions that combine durable hardware with modular services. The strategic opportunity is to design hardware platforms that can accommodate third-party software integration cleanly, reducing customization cost while enabling faster feature deployment. The risk is fragmentation if integration standards remain inconsistent, which could raise implementation complexity and slow adoption in larger enterprise environments.
Strategic Recommendations for Decision Makers
For Kiosk Manufacturers and Solution Providers
Prioritize architectural clarity between standardized high-volume platforms and customized vertical solutions. The pressure on hardware costs and the rising importance of fleet management make it risky to blur the line between mass-deployable units and bespoke builds. Companies should define a core hardware roadmap that supports modular software integration, accessibility features, and secure payment workflows, then selectively layer vertical applications through partnerships or hosted services. Product activity such as the Windfall Series launch and the INSOMNIAC software partnership demonstrates the value of pairing durable hardware with a focused software ecosystem, and that model is likely to become more relevant as buyers compare total cost of ownership across multi-year deployments.
Equally important is designing for compliance and lifecycle support from the outset. PCI PIN on Glass requirements, accessibility expectations, and connectivity modernization all influence hardware and software choices. Manufacturers that internalize these constraints early can reduce retrofit risk, shorten certification cycles, and present a more dependable value proposition to enterprise buyers managing large, distributed fleets.
For Investors Evaluating the Kiosk Sector
Assess companies based on their ability to manage the hardware-software-service balance rather than on unit volume alone. The most durable growth stories are likely to come from players that can combine reliable hardware platforms with recurring software or managed-service elements, because that mix improves resilience against component cost volatility and creates stronger customer retention. Vertical specialization also deserves attention: accessibility-focused designs, government and public-sector deployments, and QSR self-ordering solutions each have distinct demand drivers and compliance profiles that can support steadier demand than undifferentiated self-service hardware. Investors should also monitor supply-side risk, particularly around component tariffs and regional hardware levies, since these factors can affect build costs, margin structure, and the timing of price adjustments across the value chain.
For Enterprise Buyers and Procurement Teams
Evaluate kiosk investments as multi-year operational commitments, not one-time hardware purchases. The relevant metrics should include uptime performance, remote management capability, accessibility compliance, secure payment architecture, and the supplier’s ability to support software updates and application integration over time. Buying decisions should weigh the trade-off between standardized platforms, which typically offer better scale economics and simpler support, and custom solutions, which may better fit specialized environments but can increase maintenance complexity and lifecycle cost. Procurement teams should also clarify which software services will be hosted, which will be managed internally, and how payment and accessibility requirements will be maintained as standards evolve.
Given the pace of change in hardware cost structures, regulatory expectations, and software-enabled feature sets, detailed segmentation data and customized deployment guidance can materially improve planning accuracy. PW Consulting’s complete research report provides deeper breakdowns across regions, application segments, and solution types, along with tailored recommendations for procurement strategy, vendor evaluation, and investment prioritization. For decision makers looking to translate these market-level trends into specific procurement choices or capital allocation plans, the full report offers the granular intelligence needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Kiosk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hemp Fiber Market: How 18.5% CAGR and Shifting Demand Redefine the 2032 Outlook
By PW Consulting, 2026-09-21
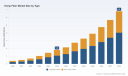
The Hemp Fiber Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview: A Sector in Rapid Transition
The global hemp fiber market has evolved from a niche agricultural byproduct into a strategically significant industrial commodity. Between 2020 and 2025, revenue expanded steadily, crossing the threshold from under half a billion USD to $1.8 billion. The trajectory suggests a compound annual growth rate of approximately 18.5 percent through 2032, with the market projected to reach $6.8 billion by the end of the forecast period. This expansion is not merely a continuation of historical growth patterns; it reflects structural shifts in material sourcing, regulatory clarity, and end-market demand that are reshaping the industry's fundamentals.
Several dynamics explain the acceleration. Production volumes have scaled meaningfully, as evidenced by U.S. fiber hemp open-field output reaching 67.3 million pounds in 2025, an 11 percent increase over the prior year, with an average value of $0.20 per pound. At the same time, regulatory frameworks are stabilizing after years of uncertainty. The USDA's decision to delay enforcement of the requirement that all hemp be tested by DEA-registered laboratories until December 31, 2026, provides a transitional window that reduces compliance pressure on producers in the near term. Furthermore, draft language in the 2026 Farm Bill clarifies the federal definition of industrial hemp as an agricultural commodity and signals a reduction in regulatory burdens for growers and processors. These developments collectively lower barriers to scale and encourage investment in processing infrastructure.
Despite the positive momentum, the sector faces three critical challenges that will determine which players capture value and which fall behind. First, consistent fiber quality remains elusive across supply chains. Variability in decortication methods, retting practices, and crop management leads to divergent grades of bast and core fibers, complicating downstream adoption in applications that require precise material specifications. Second, supply chain fragmentation persists. Many growers lack reliable off-take agreements, while processors struggle to secure steady volumes of consistent raw material. This mismatch creates price volatility and undermines long-term planning for manufacturers seeking to integrate hemp fiber into their product lines. Third, competition from established natural and synthetic alternatives continues to pressure cost parity. Hemp fiber must demonstrate not only environmental or performance advantages but also reliable economics that justify substitution in commercial settings.
Key Drivers: What Is Propelling the Market Forward
The market's trajectory is shaped by an intersection of technology, policy, consumer behavior, and supply chain restructuring. Each driver reinforces the others, creating a compound effect that favors companies able to align across multiple dimensions.
Technological Innovation in Fiber Extraction and Processing
Advancements in decortication and fiber refinement are among the most tangible drivers of market growth. Traditional mechanical separation methods often yield fibers with inconsistent length, strength, or surface characteristics, limiting their suitability for higher-value applications. Newer processing approaches, including low-impact mechanical and bio-assisted technologies, are improving the yield and quality of textile-grade bast fibers while reducing waste streams. Companies such as Canvaloop have introduced product lines that transform agricultural and bast waste into textile-grade hemp fibers and yarns, demonstrating that waste valorization can simultaneously address cost and sustainability objectives. Such innovations expand the addressable market by making hemp fiber viable for applications that previously required more expensive or less available alternatives.
Innovation is also evident in composite and construction material applications. Processors are developing material formulations that leverage hemp hurd and bast fiber for insulation, paneling, and lightweight automotive components. These formulations depend on consistent input quality, which incentivizes closer coordination between growers, decorticators, and end-product manufacturers. The trend toward integrated processing facilities reflects this reality, as vertical integration reduces the friction of coordinating multiple supply chain stages and allows for tighter quality control.
Policy and Regulatory Clarity as an Enabler
Regulatory uncertainty has historically constrained investment in hemp fiber infrastructure. The recent policy signals mark a shift toward greater predictability. The 2026 Farm Bill draft language that clarifies the federal definition of industrial hemp as an agricultural commodity reduces ambiguity for growers and accelerates onboarding of new production capacity. The USDA's enforcement delay on DEA-registered laboratory testing through the end of 2026 offers a practical relief window, giving processors and producers time to align compliance processes without immediate disruption. At the state level, requirements such as Virginia's retail hemp product registration, effective November 15, 2024, illustrate that subnational regulation remains a relevant consideration, particularly for companies distributing finished goods. Overall, the direction of policy is toward normalization, which supports more confident capital allocation and long-term planning.
Demand-Side Shifts Across Textiles, Automotive, and Construction
End-market demand is expanding beyond traditional niches. In textiles, brands and manufacturers are seeking regenerative and lower-impact fiber inputs to meet sustainability commitments and respond to consumer preferences. Hemp's attributes, including relatively low water intensity and the ability to grow with fewer chemical inputs, align with these priorities. In automotive composites, lightweighting and material strength drive interest in natural fiber reinforcements that can reduce vehicle weight and improve sustainability profiles. Construction materials represent another growth avenue, with hemp-based composites and hempcrete gaining traction for insulation, wall systems, and other building applications where thermal performance and carbon footprint are valued. Across these segments, the common thread is a preference for materials that can demonstrate both performance and credible sustainability credentials.
Supply Chain Reconfiguration and Cost Dynamics
Supply chains are being reconfigured to reduce dependence on fragmented, opportunistic sourcing. Vertically integrated operators are scaling decortication and processing capacity to secure more predictable input streams and to offer consistent product grades. This shift is significant because consistent supply is often more important to industrial buyers than marginal cost differences. At the same time, the cost structure is influenced by the economics of raw material production. With U.S. fiber hemp production valued at an average of $0.20 per pound in 2025, the sector continues to work toward cost levels that enable broader substitution. Improvements in yield, harvesting efficiency, and processing throughput will be central to closing any remaining gap with incumbent materials. Partnerships that link U.S. growers with international manufacturing hubs are also emerging as a strategic mechanism to access processing expertise and end-market demand simultaneously.
Competitive Landscape: Strategic Positioning and Evolution
The market remains relatively unconcentrated, with the top three firms accounting for approximately 25 percent of revenue and the top five for about 35 percent. This fragmentation indicates that scale advantages are still emerging and that positioning, rather than incumbency, will define winning strategies. Several distinct strategic archetypes are visible among leading participants.
Vertically integrated producers are building end-to-end control from cultivation through processing. Hemp Inc., with the largest U.S. decortication facility, exemplifies this approach, producing fiber for textiles, composites, and hempcrete. Vertical integration reduces dependency on third-party processors and enables tighter quality management, which is valuable for buyers requiring repeatable material specifications. Similarly, American Hemp, LLC has expanded decortication and processing capacity to serve textile, composite, and construction applications, signaling a focus on multi-application throughput rather than a single niche. This breadth can be advantageous when demand cycles differ across applications, as it allows capacity to be allocated where margins and orders are strongest.
Processors focused on technical fiber and export supply chains represent another strategic profile. IND HEMP, LLC decorticates U.S.-grown hemp straw to produce bales of technical bast fiber, premium refined or cottonized hemp fibers, and hurd in various particle sizes, serving both domestic and export markets. Its recent activities highlight the importance of partnership-driven expansion. In April 2026, the company signed a memorandum of understanding with Summit International Trading and Thien Phuoc Ramie Group to integrate U.S.-grown hemp fiber into Vietnam's textile manufacturing supply chain. A prior engagement at TechTextil North America 2025 in Atlanta, where the company showcased new hemp fiber solutions, indicates a deliberate effort to build visibility among textile industry buyers. These moves underscore a strategy that combines product differentiation with supply chain partnerships to access high-value textile markets.
Innovation-led processors are emerging around waste-to-fiber and low-impact technology. Canvaloop's November 2025 launch of a new line of textile-grade hemp fibers and yarns using low-impact waste-to-fiber technology illustrates how technology can redefine cost and sustainability profiles. By converting waste streams into marketable fiber, such companies can potentially lower input costs and improve margin resilience, while also appealing to buyers with strong sustainability mandates. This approach may also reduce competition for prime crop inputs, since it leverages material that might otherwise be discarded.
International players add geographic and application diversity. Ecofibre Ltd. produces and sells hemp-derived fibers and yarn for textiles and industrial applications, supplying both U.S. and Australian markets, which demonstrates cross-market operational capability. Dun Agro Hemp Group operates as a hemp fiber and grain processor and supplier for European and global markets, while Cavac Biomateriaux focuses on hemp fiber-based materials and composites for construction and industrial sectors in France. These firms highlight the global nature of demand and the importance of regional processing footprints to serve local construction, textile, and composite markets efficiently. Other U.S. processors such as BastCore, Inc., BaFa, and Konoplex LLC contribute to industrial and composite supply, reinforcing the breadth of the processing base and the ongoing specialization by application.
The competitive landscape is evolving along several axes. Integration is accelerating as processors acquire or build decortication capacity to secure inputs and ensure quality. At the same time, specialization is increasing, with firms differentiating by fiber type, application focus, or geographic market. New entrants are likely to continue arriving, particularly in regions where policy support and processing infrastructure align. The net effect is a market that is moving from fragmentation toward selective consolidation, but one in which multiple viable business models can coexist if they secure reliable supply, consistent quality, and clear customer value propositions.
Future Outlook: Trends That Will Shape the Next 3 to 5 Years
Three trends are likely to define the market's evolution through the early 2030s.
First, quality standardization and specification maturity will become increasingly important. As textile, automotive, and construction buyers integrate hemp fiber into regular procurement, they will require consistent grades, test data, and traceable supply. Processors that invest in quality systems, grading protocols, and documentation will be better positioned to secure long-term contracts, while those that supply inconsistent material will face marginalization. This trend favors operators with scale, integrated control, or strong technical partnerships, and it raises the bar for all participants.
PW Consulting
Second, geographic arbitrage and cross-border supply chain linkages will intensify. The integration of U.S.-grown fiber into manufacturing hubs in Asia, as illustrated by recent partnership activity, reflects a broader pattern of matching production regions with processing and fabrication expertise. Companies that can navigate logistics, customs, and qualityConsistency across borders will gain access to larger end markets and more diversified revenue streams. This trend also creates opportunities for regional processors that can serve as intermediaries, blending local feedstock with international demand.
Third, policy and compliance dynamics will continue to influence investment timing and operating costs. The current enforcement delay and the direction of the Farm Bill create a near-term environment that is more favorable for expansion, but state-level requirements and future federal rulemaking remain variables. Firms that build compliance flexibility into their operations, including adaptable testing and registration processes, will be less exposed to disruption if requirements tighten. The risk is that regulatory changes, while broadly constructive, could introduce new costs or administrative burdens that affect margins, particularly for smaller operators.
A related uncertainty is the persistence of cost gaps with incumbent materials. Even with strong demand, hemp fiber adoption will depend on achieving credible economics at scale. If processing yields, harvesting efficiency, or logistics costs do not improve sufficiently, adoption may remain selective rather than broad-based. This risk is particularly relevant in price-sensitive applications where sustainability benefits alone may not justify a premium.
Strategic Recommendations for Decision-Makers
For manufacturers evaluating hemp fiber integration, the priority is to secure reliable, specification-aligned supply before scaling product commitments. Engaging with processors that offer documented grades, consistent decortication output, and clear traceability will reduce the risk of quality variability disrupting production. Where possible, manufacturers should establish multi-source arrangements or partnership-based supply to mitigate dependence on a single chain, and they should validate performance in end-use conditions early to avoid late-stage rework or rejection.
For investors, the most compelling opportunities lie where processing capacity, quality control, and demand access converge. Vertically integrated operators with expanding decortication throughput, low-impact or waste-to-fiber technology, and established channels into textile, composite, or construction markets offer a combination of scale and differentiation. Investors should also monitor partnership activity that links feedstock origins to manufacturing hubs, since these arrangements can accelerate volume growth and reduce market risk. At the same time, due diligence should weigh regulatory exposure, state-level registration requirements for downstream products, and the pace of cost improvement relative to alternatives.
Hemp Market
For procurement and sourcing teams, the focus should be on total value rather than unit price alone. Hemp fiber's advantages in sustainability, weight reduction, and material performance can translate into downstream savings or brand value, but only if supply consistency and specification fit are confirmed. Procurement strategies should include technical trials, clear grading requirements, and contingency plans for supply variability, particularly during the transition from pilot to volume use. Building relationships with processors that demonstrate quality systems and transparent communication will reduce friction as volumes increase.
Across these audiences, the common imperative is to act with both urgency and discipline. The market is expanding quickly, and early positioning can secure access to supply, partnerships, and customer relationships that become harder to establish as the sector matures. At the same time, not all growth is equally valuable; the winners will be those who build defensible advantages in quality, supply reliability, and application fit rather than simply participating in volume expansion.
Hemp Seeds Market
For decision-makers seeking deeper segmentation data, company-level financials, regulatory timelines, and tailored scenario planning, a comprehensive research report can provide the granularity needed to translate these trends into concrete investment and sourcing decisions. The strategic direction is clear, but the details of segment economics, competitive capability, and regional readiness will determine execution success, making detailed intelligence a critical input for the next phase of planning.
For detailed analysis of this topic, please visit the official page: Hemp Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Strategic Shift in Smartphone Power Management ICs: Navigating Growth, Complexity, and Competitive Realignment
The smartphone power management IC (PMIC) market has entered a phase of steady, structurally driven expansion. Total revenue across the sector reached approximately 185.0 million in 2025, building on a consistent climb from 140.0 million in 2020. Over the 2026–2032 forecast horizon, the market is projected to grow at a compound annual growth rate of 5.5 percent, reaching 267.0 million by 2032. This trajectory reflects more than incremental handset volume growth. It signals a fundamental reallocation of value within mobile power architectures, where efficiency, integration, and thermal-aware design are quietly reshaping procurement priorities, product roadmaps, and competitive positioning.
Market Context and Structural Challenges
The revenue curve over the past five years shows a market that has absorbed supply chain volatility, component shortages, and shifting OEM priorities without losing momentum. Growth has been broad-based, but not uniform. The underlying dynamics point to a sector that is consolidating technical requirements while fragmenting competitive approaches. Several structural challenges define the current inflection point.
First, power density and thermal constraints are tightening faster than conventional discrete approaches can accommodate. As smartphone processors, display panels, and RF subsystems draw higher peak currents and operate across wider voltage ranges, PMICs must deliver more precise sequencing, faster transient response, and lower quiescent loss. The burden on system designers is rising, and the margin for error in battery life and thermal performance is shrinking.
Second, the competitive base is broad and increasingly layered. Market concentration remains moderate, with the top three participants holding roughly 22.5 percent of revenue and the top five reaching about 28.5 percent. This distribution indicates a market that is not dominated by a single architecture or vendor, but instead shaped by multiple design houses, foundry relationships, and region-specific OEM requirements. The result is a landscape where differentiation depends less on scale alone and more on the ability to integrate power management with application processors, charging protocols, and system-level firmware.
Third, procurement cycles and platform lifecycles are creating timing friction. Handset OEMs are extending platform validation windows, demanding longer availability commitments, and tightening qualification procedures for power components that sit close to the battery and core rails. Suppliers that cannot guarantee continuity, documentation consistency, and design-in support risk losing position even when their technical specifications are competitive.
Core Drivers Reshaping the Market
Several interlinked forces are accelerating change in smartphone power management. Understanding these drivers is essential for anyone making sourcing, investment, or product planning decisions.
Technology innovation is moving from incremental efficiency gains to architectural integration. Multi-channel PMICs, battery management blocks, and voltage regulation stages are increasingly combined into fewer packages with more programmable control. This integration reduces board space, simplifies power sequencing, and allows OEMs to tailor rail behavior to specific workload profiles. At the same time, fast-charge support, power-path management, and adaptive voltage delivery are becoming baseline expectations rather than premium features. The practical effect is that PMIC selection now influences not only battery endurance, but also user perception of charging speed, thermal comfort, and device reliability.
Power Management IC (PMIC) Market
Policy and regulatory pressure is reinforcing the efficiency trajectory. Energy consumption standards, battery safety expectations, and e-waste considerations are pushing manufacturers toward designs that minimize loss, extend usable battery life, and simplify end-of-life handling. While regulations vary by region, the directional signal is consistent: mobile devices must do more with less energy, and power management is a primary lever for compliance. This environment rewards suppliers that can provide documented efficiency curves, predictable thermal behavior, and evidence of robust fault protection.
Demand-side behavior is also changing the value equation. Consumers expect devices that hold charge longer under mixed usage, recharge quickly without excessive heat, and maintain consistent performance across battery states. Enterprise and premium consumer segments add further requirements, including longer product support windows, tighter supply continuity, and more transparent component provenance. These expectations increase the stakes for PMIC designers, because power management is increasingly visible to end users through charging behavior, thermal performance, and charge-cycle longevity.
Supply chain and cost structure dynamics continue to shape sourcing strategies. Component availability, packaging constraints, and the cost of qualifying alternative parts have made resilience a first-order concern. OEMs and contract manufacturers are diversifying supplier bases where possible, while also seeking partners that can provide stable lead times, clear revision control, and design flexibility. In this environment, cost competitiveness is still important, but it is increasingly weighed against risk mitigation, technical support, and the ability to sustain designs through multiple product generations.
Competitive Landscape and Strategic Positioning
The market features a diverse set of participants, each pursuing a distinct path to relevance. The strategic differences among them reveal where value is being created and how the competitive map is evolving.
Texas Instruments maintains a broad portfolio spanning multi-output PMICs for smartphone battery charging, voltage regulation, and power sequencing. Its positioning rests on depth of reference design, long-standing mobile phone PMIC heritage, and continued development of modern battery management solutions. For system architects, this breadth translates into optionality across charging topologies and rail configurations, supported by a documentation and design-in ecosystem that reduces integration risk.
Analog Devices emphasizes fast-charge support and power-path management, with PMICs integrated alongside battery chargers and low-dropout regulators in mobile platforms. Its differentiation lies in precision power delivery and a focus on charge behavior that aligns with user experience expectations. This approach appeals to designs where charge timing, battery health, and stable operation across load transients are prioritized.
NXP Semiconductors offers configurable power sequencing and fault protection optimized for smartphone CPUs, GPUs, and memory rails. Its value proposition centers on flexibility and protection in handheld environments, where rail ordering and fault handling can materially affect system stability. This makes NXP relevant for platforms that require tailored sequencing across heterogeneous processing blocks.
Renesas Electronics, including its Dialog Semiconductor capabilities, supplies multi-channel PMICs and sub-PMICs for smartphones, tablets, and RF modules, with advanced buck-boost and power distribution solutions. The strategic emphasis is on distribution efficiency and multi-rail control, which supports complex handheld architectures that must balance performance, leakage, and thermal headroom.
ON Semiconductor focuses on efficiency and integration in mobile power management for consumer electronics. Its approach targets loss reduction and functional consolidation, which matters in designs where board area and energy waste are tightly constrained. Richtek Technology contributes PMICs for portable and handheld devices, including buck-boost converters and battery charge controllers, with a practical focus on charging control and conversion efficiency in smartphone applications.
ROHM Semiconductor provides linear and switching regulators along with power management switch ICs tailored for mobile phones and displays. Its portfolio supports designs that need a mix of regulation styles and switching elements, particularly where display and handset rail requirements intersect. Skyworks Solutions is associated with PMICs in next-generation smartphones, including wireless networking and power delivery solutions, positioning power management closer to connectivity and RF subsystem needs.
Qualcomm Technologies integrates Snapdragon SoCs with Power Managers for optimized power delivery, fast charging, and efficiency. Its advantage comes from tight coupling between application processors and power management, enabling coordinated behavior across compute, charging, and delivery paths. MediaTek develops PMICs for smartphones and IoT, including multi-buck and LDO-based power distribution and charging solutions, with a focus on scalable integration across broad handheld and connected device portfolios.
These profiles illustrate a market where differentiation is multidimensional. Some players compete on integration breadth and reference design maturity. Others compete on precision charging, sequencing flexibility, or processor-coupled optimization. The practical implication for decision makers is that PMIC selection is no longer a single-specification purchase. It is a platform decision that affects charging experience, thermal behavior, validation effort, and long-term design continuity.
The competitive structure is evolving along three directions. Consolidation is occurring where suppliers can bundle power management with adjacent functions and reduce total integration cost. Differentiation is intensifying where charging speed, efficiency, and protection features become decisive in premium segments. New entry and regional specialization remain possible where local support, cost structures, and design-in relationships create niches that broader portfolios do not fully address. The moderate concentration levels suggest that the market will remain competitive, but that coordinated advantages in integration, support, and platform alignment will increasingly separate leaders from followers.
Forward Trends and Commercial Implications
Looking ahead across the 2026–2032 period, three trends are likely to shape commercial outcomes.
Integrated, programmable power architectures will become more central to smartphone design. As rail counts, workload variability, and charging expectations increase, PMICs that offer configurable sequencing, adaptive regulation, and tighter coordination with processors and charging protocols will gain preference. The commercial opportunity lies in reducing validation complexity, improving thermal performance, and enabling faster design cycles for OEMs that need to support multiple handset variants from a common power architecture. Suppliers and partner ecosystems that can provide flexible configuration options, clear firmware or control interfaces, and predictable behavior across operating conditions will be better positioned to capture design wins.
Efficiency and thermal-aware design will move from optimization goals to qualification gates. With battery life, charging comfort, and regulatory expectations all trending upward, PMICs that minimize loss, manage transients cleanly, and support stable operation under fast-charge conditions will become harder to substitute. This creates opportunity for vendors that can document efficiency across load profiles, provide robust protection features, and help OEMs meet both performance and compliance targets. The risk is that efficiency claims become commoditized unless supported by measurable system-level outcomes and reproducible validation data.
Supply resilience and lifecycle continuity will increasingly influence sourcing decisions. As platform cycles lengthen and qualification costs rise, procurement teams will favor suppliers that can demonstrate stable availability, disciplined revision control, and the ability to support designs over multiple generations. The commercial implication is that relationship depth, technical support, and continuity planning may become as important as unit pricing. This trend also raises the bar for smaller or less established participants, while rewarding suppliers that can commit to long-lived design support and transparent change management.
Worldwide Consumer Electronics Power Management IC Market
These trends are not guaranteed to unfold uniformly. Risks include component pricing volatility, shifting OEM platform strategies, and the possibility that integration advantages concentrate value among a smaller set of platform-aligned suppliers. There is also uncertainty around how quickly charging protocols, battery technologies, and regulatory expectations will evolve, which could alter the relative importance of specific PMIC features. Decision makers should therefore treat power management strategy as a living assessment rather than a fixed specification exercise.
PW Consulting
Actions for Executives, Investors, and Procurement Teams
For handset and component manufacturers, the priority is to align power management choices with platform strategy rather than treat PMICs as interchangeable commodities. That means evaluating integration depth, sequencing flexibility, fast-charge behavior, and supplier support alongside unit cost. Designs that can reuse a common PMIC architecture across multiple models, while retaining enough programmability to tune rail behavior, will typically reduce validation burden and improve lifecycle economics. Manufacturers should also weigh the value of tighter coordination between processor platforms and power delivery, especially where charging experience and thermal performance are differentiators.
For investors, the relevant question is where value is likely to accrue as integration and efficiency requirements intensify. Companies that can combine multi-channel control, battery management, and regulation in cohesive solutions, while maintaining strong design-in support and stable product lifecycles, are better placed to defend positioning in a moderately concentrated market. Attention should also be paid to suppliers whose roadmaps align with fast-charge adoption, thermal-aware design, and platform-level integration, since these are the areas where commercial differentiation is most likely to widen. Portfolio exposure should be assessed with an eye on continuity risk, qualification lead times, and the ability to sustain designs through multiple product generations.
For procurement and sourcing leaders, the practical focus should be on resilience and traceability without sacrificing technical fit. Qualifying multiple sources where feasible, verifying revision-control discipline, and requiring clear documentation for configuration and protection features can reduce downstream risk. Procurement teams should also evaluate supplier capacity to support long-lived platforms, because the cost of re-qualification and design changes often outweighs narrow unit-price advantages. In parallel, sourcing strategies should reflect the growing importance of charging behavior and thermal performance in end-user satisfaction, since these attributes are increasingly tied to PMIC selection.
Across these roles, the common theme is that smartphone power management is becoming more strategic, less commodity-like, and more tightly linked to platform outcomes. The market’s growth trajectory is steady, but the real value is shifting toward architectures and suppliers that can reduce integration risk, improve efficiency and charging behavior, and sustain designs through changing requirements. Detailed segmentation data, region- and type-level revenue splits, application breakdowns, and supplier-level assessments can sharpen these decisions significantly. For teams that need granular sizing, competitive mapping, and tailored sourcing or investment implications, the full research report provides the deeper quantitative and strategic detail needed to move from market-level direction to actionable plans.
For detailed analysis of this topic, please visit the official page: Smartphone Power Management Ics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Global Shea Butter Market
The global shea butter market has evolved from a niche ingredient in specialty cosmetics into a strategically significant commodity spanning personal care, food, and pharmaceutical applications. Valued at approximately USD 970.0 million in 2025, the market has demonstrated consistent expansion over the past five years, accelerating from USD 655.2 million in 2020. Forward projections indicate continued growth, with the market expected to surpass USD 1.6 billion by 2032, reflecting a compound annual growth rate of 8.2 percent through the forecast period ending in 2032.
This trajectory reflects more than incremental demand growth. It signals a structural shift in how shea butter is sourced, processed, regulated, and positioned across end-use markets. For executives and investors evaluating exposure to natural ingredients, the shea butter sector offers compelling upside, but it also presents a complex landscape shaped by regional policy interventions, supply chain reconfiguration, and evolving consumer expectations.
PW Consulting's market intelligence on this sector highlights that the opportunities ahead will not accrue uniformly. Companies that understand the interplay between production geography, processing capability, regulatory compliance, and application-specific demand will be best positioned to capture value. This analysis examines the current market structure, the forces reshaping competitive dynamics, and the strategic moves required to navigate the next phase of growth.
Market Landscape and Core Challenges
The shea butter market operates at the intersection of agricultural commodity trading and value-added specialty ingredients. Over the historical period from 2020 to 2025, the market expanded steadily, driven by rising demand for plant-based and naturally derived ingredients across cosmetics, food formulations, and pharmaceutical applications. The forecast period through 2032 projects continued expansion, with the market reaching an estimated USD 1.69 billion by the end of the forecast horizon.
While the top-line growth narrative is clear, the operational reality for market participants is more nuanced. Three structural challenges define the current inflection point.
Supply Chain Concentration and Raw Material Volatility
Shea butter production remains heavily concentrated in specific West and Central African regions, creating geographic dependency that introduces both price volatility and supply continuity risk. The crop's seasonal nature, combined with variable yields and the predominance of smallholder farming, means that raw material availability can fluctuate significantly between harvest cycles. This structural characteristic has historically forced downstream buyers to balance cost efficiency against supply security, often through long-term contracting or geographic diversification of sourcing portfolios.
Compounding this challenge, the gap between raw kernel availability and processed butter output creates bottlenecks. Entities that control refining and fractionation capacity can extract disproportionate value, while those dependent on spot-market purchases face margin compression during periods of tight supply. The market's medium concentration levels, with the top three firms holding a notable share and the top five firms controlling a larger portion of traded volume, indicate that scale and vertical integration confer meaningful advantages.
Regulatory and Policy Fragmentation
The regulatory environment for shea butter varies substantially by destination market and by application. Food-grade shea butter entering the European Union, for example, must comply with mandatory labeling requirements, hygiene standards, and hazard analysis and critical control points systems. Cosmetic and pharmaceutical applications impose their own quality and traceability expectations. This fragmentation increases compliance costs and creates barriers for smaller producers or exporters who lack the institutional capacity to navigate multiple regulatory regimes simultaneously.
More significantly, recent policy actions in key producing countries are reshaping the value-capture dynamics within the supply chain. Governments in the region are increasingly focused on capturing more domestic value by restricting raw nut exports and encouraging local processing. These interventions introduce both opportunity and disruption: they can stimulate investment in local refining infrastructure, but they also create short-term market dislocation, pricing uncertainty, and the need for buyers to renegotiate supply arrangements.
Quality Consistency and Standardization Gaps
Despite growing demand, the shea butter market continues to contend with variability in quality, purity, and processing standards across the supply base. Unrefined and raw variants, which represent a substantial portion of traded volume, differ widely in terms of moisture content, free fatty acid levels, and impurity profiles. For manufacturers in cosmetics and personal care, where consistency and stability are paramount, this variability complicates formulation and can increase quality control overhead. For food and pharmaceutical applications, the bar is even higher, requiring documented traceability and adherence to precise specifications.
Standardization is improving, but the pace is uneven. The presence of minimum price mechanisms tied to quality specifications in some producing markets reflects an effort to align incentives, but widespread adoption of uniform grading and certification remains a work in progress. Companies that invest in supplier qualification, incoming inspection protocols, and collaborative quality improvement with upstream partners can differentiate themselves, but this requires sustained commitment rather than transactional sourcing.
Key Drivers Reshaping the Market
Policy Interventions and the Shift Toward Domestic Value Addition
One of the most consequential developments in the shea butter market is the emergence of policy measures designed to retain more value within producing countries. In July 2025, a minimum price for raw shea kernels was established, set at GH₵9.01 per kilogram, with specific quality parameters covering moisture content, free fatty acids, and impurity levels. This mechanism creates a pricing floor linked to quality, aiming to provide more predictable returns for producers while incentivizing better grading practices.
Shortly thereafter, Nigeria implemented a ban on exports of raw shea nuts, with the stated objective of shifting from raw nut exports toward domestic production of refined shea butter, oil, and derivatives. The ban, initially set for a six-month review period, was reported to have triggered an immediate drop in domestic prices, reflecting the sudden redirection of supply within the local market. Analysts noted that Nigeria accounts for a significant share of global raw shea nut production, and that a substantial portion of that output had historically been exported in unprocessed form.
These policy moves are not isolated. They represent a broader trend among producing nations seeking to capture more value along the supply chain. For downstream buyers and processors, this means that sourcing strategies can no longer assume seamless access to raw materials at historical price levels. Instead, companies must evaluate opportunities to engage with local processing capacity, invest in partnership structures that align incentives, or factor in the cost of compliance with new trade and quality regimes.
Technological and Processing Advancements
Processing technology is a critical lever in the shea butter value chain. The distinction between raw, unrefined butter and refined, fractionated products is not merely a matter of purity; it reflects differences in application suitability, shelf stability, odor and color profile, and cost structure. Refinement and fractionation enable producers to tailor shea butter for specific end uses, including high-stability cosmetic formulations and food applications that require consistent functional properties.
Companies that have invested in refining infrastructure and value-added fractionation are better positioned to serve demanding customers in the food and cosmetic sectors. By converting raw kernels into standardized butter and derivative products, these entities can command higher margins and build longer-term supply relationships. Conversely, reliance on manual or low-scale processing limits the ability to meet the consistency and volume requirements of large industrial buyers.
The technological trajectory also includes improvements in quality testing, traceability systems, and process control. As destination markets impose more stringent requirements, the ability to document and verify product attributes becomes a competitive differentiator. Investments in laboratory capacity, certification, and digital traceability are increasingly relevant for suppliers aiming to access premium segments.
Consumer and Formulation Trends Driving Demand
On the demand side, the shift toward naturally derived, plant-based, and sustainably sourced ingredients continues to reshape formulations across cosmetics, personal care, food, and pharmaceutical products. Shea butter's profile as a multifunctional, naturally occurring lipid aligns with consumer preferences for clean-label and botanical ingredients. In cosmetics and personal care, it is valued for its emollient properties and is used across a range of products, from moisturizers and balms to hair care formulations.
In food and beverage applications, shea butter and its derivatives serve functional roles where stable, plant-based fats are required. The pharmaceutical segment utilizes shea butter in topical formulations and other applications where biocompatibility and consistency are important. Across these segments, the trend is not simply toward natural ingredients in general, but toward ingredients with documented provenance, consistent quality, and the ability to meet application-specific performance criteria.
This demand evolution has implications for how shea butter is positioned and priced. Buyers in premium segments are increasingly willing to pay for verified quality, traceability, and compliance documentation. At the same time, cost-sensitive applications continue to drive volume demand for more commodity-oriented grades. The coexistence of these demand tiers means that the market is not monolithic; success depends on matching product attributes to the right customer segments and application requirements.
Supply Chain Restructuring and Cost Dynamics
The cost structure of shea butter is influenced by multiple factors, including raw kernel pricing, labor and processing costs, logistics, and the cost of meeting regulatory and quality requirements. Recent policy changes in producing countries have introduced new variables into this equation. Minimum price mechanisms can stabilize producer income but may also affect the economics of export-oriented supply chains. Export restrictions on raw nuts redirect supply domestically, which can lower local raw material prices in the short term but also create uncertainty about future availability for international buyers.
For processors and converters, these dynamics create both pressure and opportunity. On one hand, sourcing disruptions and policy uncertainty can increase the cost of securing consistent supply. On the other hand, the push toward domestic processing creates openings for entities that can invest in refining capacity, enter into structured offtake arrangements, or provide technical and commercial support to local producers. The companies that navigate this environment effectively will be those that treat supply chain strategy as a dynamic capability rather than a static procurement function.
Cost dynamics also vary by region and application. Markets with strong local processing ecosystems may offer more predictable input costs for domestic manufacturers, while international buyers may face higher logistical and compliance costs. Understanding these regional and application-specific differences is essential for accurate margin planning and competitive positioning.
Competitive Landscape and Leading Strategies
The shea butter market features a diverse set of participants, from large multinational processors with established supply chains to regional specialists and origin-country producers focused on organic and manually processed products. The competitive landscape reflects different strategic choices regarding scale, vertical integration, product focus, and geographic reach.
Differentiated Strategic Positions
AAK operates with a clear focus on processing and exporting shea kernels and butter derivatives from West Africa, maintaining major supply chains that serve manufacturers in Europe and North America. This position emphasizes scale, supply chain reliability, and the ability to serve demanding downstream customers with consistent product flow. By controlling significant portions of the sourcing and export process, AAK can offer volume stability and quality assurance that are critical for large industrial buyers.
Loders Croklaan has built its positioning around refining shea kernels into crude butter and value-added fractions tailored for food and cosmetic applications. This strategy focuses on the midstream of the value chain, where processing expertise and fractionation capability create differentiation. By offering products that meet specific functional requirements, Loders Croklaan addresses customers who need more than commodity-grade butter, including those in food formulations and high-performance cosmetics.
Almond Oil Market
The Savannah Fruits Company represents a different model, emphasizing organic shea nut sourcing and manual processing at the village level. This approach is oriented around organic certification, rural livelihoods, and export of unrefined butter. The strategic value of this model lies in its alignment with sustainability and social impact expectations, as well as its ability to serve niche markets that prioritize origin authenticity and organic status. The trade-off is scale and consistency relative to larger industrial processors.
VedaOils operates in the wholesale and bulk export segment, focusing on organic and unrefined shea butter for cosmetic and personal care markets. This positioning targets cost-conscious buyers who still require organic or natural credentials, bridging the gap between premium certification and volume supply. The emphasis on wholesale and manufacturing allows VedaOils to serve a broad customer base while maintaining a focus on natural and organic attributes.
Market Structure Evolution
The competitive landscape is evolving along several dimensions. Consolidation pressure exists in segments where scale, refining capacity, and export infrastructure confer advantages. Larger processors with integrated supply chains and compliance capabilities are well placed to capture share from smaller, less capitalized players, particularly in food and pharmaceutical applications where regulatory requirements raise the bar for entry.
At the same time, differentiation and fragmentation persist in niches such as organic, fair-trade, and village-processed products. These segments reward brand story, certification, and direct relationships with producer communities. New entrants that can combine authenticity with reliable quality and documentation may find opportunities, especially as consumer and corporate procurement teams place greater weight on sustainability and provenance.
A third dynamic is the potential for vertical coordination between origin-country processors and downstream buyers. As producing countries encourage domestic refining, opportunities arise for partnerships that align local processing investment with long-term offtake commitments. Such arrangements can reduce supply risk for buyers while providing the capital and offtake certainty that local processors need to expand capacity. The extent to which this model scales will depend on policy stability, investment climate, and the willingness of both sides to commit over multi-year horizons.
Forward Trends and Strategic Implications
Trend 1: Deepening of Domestic Processing and Value Capture in Origin Countries
The policy direction evident in recent interventions points toward a sustained push for domestic processing in key producing countries. If export restrictions on raw nuts become more entrenched or are replicated in other markets, the supply chain will gradually shift toward more refined and fractionated products originating in the region. This creates opportunities for investors and companies that can support or participate in local refining capacity, quality infrastructure, and certification systems.
For downstream buyers, this trend implies that sourcing strategies will need to incorporate more engagement with origin-country processing ecosystems. Long-term contracts, joint ventures, or technical assistance arrangements may become more common as a way to secure supply and influence quality. The commercial opportunity lies in building resilient, multi-year relationships that align incentives across the value chain, rather than relying on spot-market transactions that are vulnerable to policy shocks.
Trend 2: Increasing Importance of Quality, Traceability, and Compliance Documentation
As destination market requirements tighten and application segments demand more consistent attributes, the value of quality assurance and traceability will continue to rise. Companies that can provide documented evidence of product characteristics, processing conditions, and supply chain integrity will be better positioned to access premium segments and command price premiums. This is particularly relevant for food and pharmaceutical applications, where regulatory expectations are highest.
The strategic implication is that investments in quality systems, certification, and traceability are not merely compliance costs; they are enablers of market access and differentiation. For suppliers, this means building the institutional capacity to meet varied requirements across customers and markets. For buyers, it means incorporating quality and documentation capabilities into supplier evaluation and development programs.
Mango Butter Market
Trend 3: Segmentation Between Commodity and Premium Value Chains
The shea butter market is likely to continue diverging into distinct value chains: one oriented toward volume, cost efficiency, and commodity-grade supply, and another oriented toward premium quality, certification, and application-specific performance. This segmentation mirrors broader trends in natural ingredients markets, where buyers increasingly differentiate between baseline commodity supply and value-added, verified products.
PW Consulting
For market participants, the strategic question is where to compete. Companies that operate primarily in the commodity tier will face pressure on margins and will need to compete on cost, reliability, and scale. Those that position in the premium tier will need to demonstrate consistent quality, relevant certifications, and the ability to meet specific formulation or regulatory needs. Hybrid strategies that span both tiers are possible but require operational sophistication to manage the different cost structures and customer expectations involved.
Risk Considerations
Several risks warrant attention. Policy uncertainty in producing countries could lead to further trade restrictions, price volatility, or shifts in export patterns that disrupt established supply chains. Quality and standardization gaps could persist, creating friction in premium segments and increasing the cost of quality assurance. Competition for supply could intensify as more players seek to secure processing capacity or long-term sourcing arrangements, potentially driving up input costs. Finally, demand-side preferences could shift if alternative natural ingredients gain traction or if formulation trends evolve in ways that reduce reliance on shea butter in certain applications.
These risks do not negate the growth outlook, but they underscore the importance of proactive strategy. Companies that monitor policy developments, diversify sourcing where feasible, invest in quality and traceability, and align product offerings with the right application segments will be better equipped to manage uncertainty while capturing growth.
Strategic Recommendations for Decision Makers
The shea butter market's growth trajectory and evolving structure create distinct imperatives for different types of stakeholders. The following recommendations are intended to guide strategic planning and resource allocation.
For Manufacturers and Processors
- Evaluate supply chain resilience in light of recent policy interventions. Companies dependent on raw kernel imports should assess the risk of export restrictions and consider diversifying sourcing geographies, developing alternative supply routes, or engaging with origin-country processors to secure refined supply.
- Invest in product positioning that matches application requirements. Align product grades, quality documentation, and processing attributes with the specific needs of cosmetics, food, or pharmaceutical customers. Where relevant, build capability in refinement and fractionation to access higher-value segments.
- Strengthen quality systems and traceability. Documented quality consistency and supply chain transparency will increasingly determine access to premium customers and compliance with destination-market requirements. Treat these capabilities as strategic assets rather than overhead.
For Investors
- Assess opportunities in origin-country processing and quality infrastructure. The policy push toward domestic value addition creates potential for investments in refining capacity, testing laboratories, certification support, and logistics that enable local processors to meet export-grade standards.
- Differentiate between commodity-scale plays and premium-segment opportunities. Investment theses should account for the distinct economics of volume-driven commodity supply versus certification-intensive, traceability-rich premium products. The risk-return profiles differ materially.
- Monitor policy trajectories and their second-order effects. Export restrictions, minimum price mechanisms, and quality-linked pricing can alter competitive dynamics quickly. Investors should factor policy risk into valuation assumptions and consider scenarios that reflect a range of possible regulatory outcomes.
For Procurement and Sourcing Leaders
- Move beyond transactional sourcing where supply security matters. For critical applications, structured relationships with suppliers, multi-year agreements, or collaborative quality development can reduce exposure to price shocks and supply interruptions.
- Incorporate policy and regulatory monitoring into sourcing strategy. Changes in origin-country policy, destination-market regulations, and quality requirements should be tracked systematically and integrated into supplier selection and contract design.
- Balance cost objectives with quality and compliance needs. In applications where consistency, documentation, and certification are essential, the total cost of ownership may favor suppliers with stronger quality systems, even if unit prices are higher. Procurement decisions should reflect this broader calculus.
Navigating the Next Phase
The shea butter market is entering a period in which growth potential and structural complexity are both increasing. The macro trajectory points to continued expansion, with the market progressing toward the USD 1.6 billion range by the early 2030s. Yet the path to capturing this growth is shaped by policy interventions in producing countries, the maturation of processing and quality infrastructure, and the evolving expectations of customers across cosmetics, food, and pharmaceutical applications.
Success in this environment requires more than awareness of top-line trends. It demands granular understanding of regional supply dynamics, the implications of policy changes for sourcing and pricing, the competitive positioning of key players, and the specific requirements of each application segment. The companies that thrive will be those that combine market-level insight with operational execution: securing resilient supply, delivering consistent quality, and aligning product offerings with the right customer tiers.
For decision makers seeking deeper segmentation data, regional supply analysis, competitor benchmarking, and customized strategic scenarios, a comprehensive research companion is available that extends the analysis presented here with detailed quantitative and qualitative coverage. Access to that level of granularity can materially improve the quality of sourcing decisions, investment theses, and competitive positioning in a market where the difference between generic exposure and targeted advantage is increasingly significant.
For detailed analysis of this topic, please visit the official page: Shea Butter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Digital LOTO Improves Safety, Compliance, and Maintenance
Machines do not always show obvious signs before they start moving or regain power. Equipment may appear fully separated from its energy source, a valve may seem firmly shut, and the surrounding work area may look completely safe. Yet a single missed precaution can change that situation quickly. A lock may not have been installed, a required tag may be absent, or critical documentation may be unavailable at the moment it is needed. When these gaps exist, hazardous energy can return without warning and expose employees to severe injury. Digital Lockout/Tagout (LOTO) software helps close these gaps by replacing paper records, disconnected spreadsheets, and uneven manual practices with a defined, repeatable workflow. Supervisors can see more of what is happening, technicians can receive step by step direction, and the entire isolation activity can be documented from start to finish, giving everyone involved a clearer picture of what has been completed, what remains outstanding, and where additional attention may be required before the equipment is returned to normal operation. This also makes responsibilities easier to understand during complex maintenance activities on site.
Digital LOTO software creates a centralized environment for planning, managing, and documenting hazardous energy isolation. Different energy types, including electrical, hydraulic, pneumatic, mechanical, and thermal sources, can be handled through one coordinated process. Authorized employees can work through equipment specific shutdown and isolation instructions, helping teams follow the same approach across departments and locations. As individual actions are completed, the system can capture each step and its time, creating an audit trail that indicates whether required locks and tags were in place before maintenance started. The purpose remains simple and essential: identify the correct equipment, complete the required isolation sequence, and retain clear evidence that the critical safeguards were performed.
Moving away from memory based practices and relying on guided digital workflows can reinforce safer isolation behavior. Employees are less dependent on outdated instructions, informal knowledge, or personal interpretation when completing high risk shutdown activities. Returning equipment to service after maintenance can also be more orderly because teams can see which locks remain active and follow the designated removal sequence. Audit preparation becomes less burdensome because records are created during the job rather than reconstructed afterward. When standardized procedures are combined with verification and approval points, organizations can better manage compliance concerns, unnecessary downtime, and preventable incidents. The result is a more controlled process that helps reduce the possibility of unintended energy release while preserving information that remains useful after the maintenance task ends.
Another important benefit of digital LOTO is improved operational visibility for supervisors. Active isolations can be monitored as work occurs, with information showing responsible personnel, the duration of an isolation, and the location of the activity. Records can be filtered according to facility, production zone, contractor, shift, or other relevant factors, making it easier for management to spot conditions that may need attention. Workers in the field can likewise access current instructions associated with the equipment in front of them. QR codes placed on assets can provide a quick route to the appropriate isolation procedure. Visual aids, including photographs showing where locks should be positioned, can make instructions easier to understand and help prevent execution errors.
During maintenance, required documentation can be created and retained automatically. The system can capture timestamps, electronic approvals, and lock or tag information without asking workers to maintain paper records or enter details manually after the work has finished. If a hazardous condition develops, such as a lock being removed prematurely or power being restored unexpectedly, the platform can generate an alert. Supervisors can then investigate the situation, understand the sequence of events, and respond before the issue becomes a larger incident.
Digital approval processes can also be adapted to an organization's operating requirements without removing necessary supervisory oversight. Requests may be directed to assigned approvers, while additional checks can be introduced when circumstances change. Authorized personnel can complete approvals from computers or mobile devices, giving teams more flexibility while work is underway. This approach can reduce administrative delays without weakening the controls that support safe energy isolation.
A typical digital LOTO workflow moves through defined stages, beginning with preparation and ending with documented completion. Teams can create isolation plans using reusable templates informed by equipment information and previous maintenance records. Employees receive notice of planned work before isolation begins. Technicians then use guided instructions to address each identified energy source, supported by visual references when helpful. Before repair or maintenance starts, supervisors confirm that the equipment has reached a verified zero energy condition. Once the work is finished, locks and tags are removed according to the required sequence after the appropriate digital authorization has been secured. Work notes and relevant history are then retained automatically, giving teams information that can assist with later maintenance planning, future isolation activities, and audits.
The value of digital LOTO is not limited to satisfying regulatory requirements. Reusable templates can reduce the amount of planning that must be repeated for similar jobs, making preparation more efficient. Field work can become more consistent because technicians have structured instructions available at the point of activity. Administrative workload can also decline when records are captured as tasks occur instead of being recreated later. Together, these improvements can reduce preparation effort, limit unnecessary operational interruptions, and help organizations gain practical value from their technology investment more quickly.
Current digital LOTO platforms can also support mobile operations and connections with other workplace systems. Linking LOTO activities with maintenance management, reporting, and training platforms can create a more connected process across operational functions. Field personnel may continue recording information even when connectivity is temporarily unavailable, with data synchronized once the connection returns. This capability helps maintain continuity between remote work locations and centralized teams. The system can also provide channels for escalating hazards, conflicts, and near miss events for additional review. Earlier visibility gives organizations an opportunity to investigate concerns sooner, pursue corrective measures, and strengthen safety practices over time.
Organizations that still depend on paper files, shared folders, or individual knowledge to manage hazardous energy isolation may face avoidable weaknesses in both safety and efficiency. Digital LOTO provides a structured alternative by standardizing procedures, recording individual actions, and making compliance part of routine work. Instead of viewing Lockout/Tagout only as a regulatory requirement, organizations can establish it as a consistent and repeatable safety practice that supports employee protection while helping operations become more controlled, efficient, and dependable.
Book a free demo @ https://toolkitx.com/campaign/loto/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=near-miss-reporting-systems
https://toolkitx.com/blogsdetails.aspx?title=how-to-prevent-accidents-on-a-construction-site
https://toolkitx.com/blogsdetails.aspx?title=5-steps-to-risk-assessment-guide
The PVB Film Market at a Strategic Inflection Point: Growth, Innovation, and Competitive Realignment
The poly vinyl butyral (PVB) film market has entered a phase of sustained expansion, with global revenue projected to climb from approximately 215.0 million USD in 2025 to 344.8 million USD by 2032, reflecting a compound annual growth rate of 6.98% across the 2026–2032 forecast window. This trajectory builds on a recovery and acceleration pattern observed from 2020 through 2025, during which the market moved from 163.15 million USD to its current scale despite intermittent supply chain disruptions and macroeconomic volatility. The underlying growth is not merely a bounce-back from pandemic-era constraints; it signals a structural shift driven by performance requirements, regulatory pressures, and evolving end-use expectations. For executives and investors, the PVB film sector presents a concentrated yet dynamically evolving landscape where technological differentiation, sustainability credentialing, and supply chain resilience are becoming the primary axes of competition.
At the same time, the market is not sailing into calm waters. Three interlocking challenges define the current operating environment. First, raw material volatility and input cost pressure continue to test margin structures. Key precursors for PVB film production, including butyraldehyde and polyvinyl alcohol, remain exposed to petrochemical price cycles, logistics friction, and currency translation effects. Recent disclosures indicate that exchange rate fluctuations and fuel cost movements have imposed material headwinds on operating profit for major producers, with one leading manufacturer reporting a negative impact quantified in the billions of its local currency during its most recent fiscal reporting period. Second, the industry is navigating a tightening sustainability and transparency mandate. Customers and regulators are increasingly scrutinizing the carbon footprint of interlayers, pushing producers to adopt certified bio-based or recycled content, renewable energy usage, and third-party verification frameworks. Third, demand is bifurcating across application segments, with some verticals demanding higher structural performance and others prioritizing aesthetic customization or cost efficiency. This divergence forces manufacturers to manage multiple product architectures simultaneously, complicating capacity planning and R&D allocation.
Navigating the Core Challenges
The margin challenge is not simply a cost-pass-through exercise. Producers that rely on undifferentiated standard PVB film face intensifying price sensitivity, especially in applications where interlayer performance requirements are modest. At the same time, the shift toward high-performance variants, which command premium positioning, requires incremental investments in formulation science, processing control, and application-specific validation. These investments are non-trivial, and the return profile depends on the ability to secure design wins in automotive programs, specification adoption in architectural projects, and qualification in photovoltaic laminates. The sustainability mandate adds another layer of complexity. Certification achievements and the integration of recycled resin content are becoming table stakes in certain customer conversations, particularly in Europe and North America, where procurement teams are embedding environmental criteria into supplier qualification processes. Producers that treat sustainability as a compliance checkbox rather than a product and process strategy risk losing specification relevance over time.
Demand bifurcation is equally consequential. Automotive applications continue to drive a substantial share of volume, propelled by evolving vehicle architectures, safety expectations, and the gradual redesign of interiors and glazing systems. Architectural usage remains a steady and growing contributor, supported by building codes, renovation activity, and a growing appetite for specialized visual effects in premium and commercial projects. The photovoltaic segment, while smaller in relative terms, is gaining attention as solar module makers explore improved encapsulation and durability characteristics. The strategic implication is clear: growth is available, but it is unevenly distributed, and capturing it requires targeted product roadmaps rather than broad-based volume plays.
Key Drivers Reshaping the PVB Film Market
Three to four core drivers are interacting to reshape the competitive and commercial dynamics of the PVB film market. These drivers do not operate in isolation; they reinforce one another and collectively raise the bar for what constitutes a viable market position.
Technological Innovation and Performance Breakthroughs
Performance differentiation is moving from a nice-to-have to a decisive purchase criterion. In laminated safety glass, the interlayer's role is expanding beyond basic structural bonding and optical clarity.Automotive OEMs and Tier suppliers are seeking interlayers that contribute to acoustic comfort, impact resistance, and shape retention under stress, while architectural specifiers are looking for films that enable thinner glass packages, improved load-bearing characteristics, and distinctive visual finishes. Recent product introductions illustrate this direction. In the spring of 2024, a major producer launched a next-generation interlayer engineered for improved structural capacity, resistance, toughness, and elasticity, signaling a push toward higher-performance standards in safety glass applications. Later in the year, another incumbent introduced a low-carbon film variant that incorporated recycled resin content and leveraged renewable energy in its production process. By the following year, a European-focused manufacturer unveiled a specialized interlayer designed to deliver a refined visual effect suited to minimalistic architectural designs. These launches collectively demonstrate that innovation is branching into both performance engineering and aesthetic customization, broadening the value proposition beyond traditional transparency and adhesion.
The strategic takeaway is that R&D is becoming a direct revenue lever. Manufacturers that can shorten qualification cycles, align product attributes with end-use validation protocols, and communicate performance benefits in customer-relevant terms are better positioned to secure long-term specification loyalty. Conversely, firms that stagnate on product architecture risk being squeezed between premium innovators and cost-oriented competitors.
Policy, Regulation, and Sustainability Credentials
Regulatory and sustainability dynamics are increasingly shaping procurement decisions and competitive access. Certification frameworks that verify the bio-based or recycled content of materials, as well as the sustainability of manufacturing operations, are gaining traction in customer qualification checklists. Recent certification milestones have covered PVB film products and major production sites across Europe, the United States, and Asia, reflecting a deliberate effort by leading players to institutionalize sustainability credentials across their global footprint. This is not merely a public relations exercise; it is becoming a gateway to certain projects and programs where environmental criteria are embedded in sourcing policy. At the same time, producers are deploying financial and operational instruments to manage input volatility, including derivative tools to hedge exposure on strategic raw materials. The combination of sustainability certification and cost-risk management is creating a more resilient operating model, but it also raises the investment threshold for staying competitive.
For decision-makers, the implication is that sustainability is converging with commercial risk management. Procurement teams are weighing not only price and performance but also the compliance and reputational risk associated with material sourcing. Manufacturers that can provide traceable, verified content and energy sourcing data are gaining an advantage in specification discussions, particularly in regions where regulatory and customer expectations are advancing most quickly.
Demand-Side Shifts in Automotive, Architecture, and Energy Applications
Demand-side behavior is evolving across the three primary application areas, each with distinct drivers. In automotive, glazing strategies are being influenced by vehicle electrification, interior redesign, noise and vibration refinement, and the ongoing push for lighter, safer, and more aesthetically cohesive cabin environments. These trends support continued demand for interlayers that can meet stricter performance profiles while enabling designers to achieve new visual and tactile outcomes. In architecture, the drivers are more varied: building energy codes, renovation and retrofit activity, security and safety requirements, and a growing interest in bespoke finishes for commercial and premium residential projects. The photovoltaic application, while representing a smaller share of current demand, is attracting attention as module manufacturers and integrators evaluate encapsulation options that can contribute to longevity, optical consistency, and processing compatibility. The common thread is that customers are becoming more application-literate and are expecting film suppliers to speak to specific use-case requirements rather than offering generic interlayer solutions.
This specificity changes the commercial dynamic. Winning in automotive often requires long lead times, rigorous testing, and program-aligned supply commitments. Winning in architecture frequently depends on specification relationships, visual and performance differentiation, and the ability to support architects and fabricators with consistent quality and aesthetic options. Winning in photovoltaic contexts depends on validation against module-level durability and processing requirements. Each path requires a tailored go-to-market model, and the firms that can orchestrate these models coherently are better positioned to convert demand into durable revenue.
Supply Chain and Cost Structure Evolution
The supply side is being reshaped by the interplay of input volatility, capacity decisions, and regional localization pressures. Key raw materials remain sensitive to petrochemical cycles and logistics costs, and currency movements can materially affect operating results for globally exposed producers. In response, leading manufacturers are pursuing a combination of hedging strategies, production optimization, and selective capacity expansion or rationalization. The objective is to protect margins without sacrificing service levels or quality consistency. There is also a growing emphasis on reducing the carbon intensity of production, which can involve energy sourcing changes, process efficiency improvements, and the integration of recycled or bio-based feedstocks where technically and commercially viable. These efforts are not isolated initiatives; they are increasingly woven into product positioning and customer discussions, blurring the line between operational efficiency and market-facing value creation.
The practical consequence is that cost leadership alone is becoming harder to sustain as a differentiator. While efficiency remains essential, the more durable advantages are emerging from the combination of performance innovation, verified sustainability attributes, and reliable supply assurance. Producers that can deliver this combination are able to command more favorable commercial terms and build deeper relationships with specifiers and procurement organizations.
Competitive Landscape and Leading Strategies
The PVB film market is characterized by a high degree of concentration, with the top three producers accounting for approximately 79% of market value and the top five representing around 85%. This concentration reflects the scale, technical know-how, and qualification infrastructure required to compete effectively across automotive and architectural applications. It also means that competitive dynamics are shaped by a relatively small number of players whose product portfolios, geographic reach, and sustainability commitments directly influence market direction.
Strategic Positioning of Leading Players
Several incumbent companies illustrate the divergent yet overlapping strategies now unfolding. One U.S.-based producer has built a strong association with laminated safety glass interlayers for both automotive and architectural markets, leveraging established brand recognition and a broad application footprint. Recent moves have combined product innovation with sustainability positioning, including the introduction of a low-carbon film variant that incorporates recycled resin content and uses renewable energy in production. The same company has also relied on derivative instruments to manage volatility in the cost of strategic raw materials, highlighting a dual focus on product differentiation and cost-risk control. Another major player, headquartered in Japan, maintains a globally recognized interlayer portfolio and has pursued a parallel path of performance and sustainability advancement. This includes the launch of a next-generation stiff interlayer designed for improved structural capacity and the achievement of sustainability certification covering products and major plants in Europe, the United States, and Asia. A Taiwanese producer contributes a distinct angle through its focus on polyvinyl butyral resins and film for safety glass interlayers, adhesives, and printing inks, reflecting a broader materials orientation that can support integrated supply advantages. A Belgium-based manufacturer has carved out a specialized position in high-quality PVB film for architectural laminated safety glass, with recent attention to refined visual effects tailored for minimalistic design contexts.
These profiles reveal a market in which leaders are not merely competing on volume but are differentiating along multiple axes: performance engineering, aesthetic customization, sustainability verification, and supply chain resilience. The strategic implication is that competitive advantage is becoming multidimensional. A single strength, such as cost efficiency or brand recognition, is less sufficient on its own than it once was. Instead, the most defensible positions combine at least two of the following: application-specific performance leadership, credible sustainability credentials, and reliable, localized supply capability.
Market Structure Evolution: Consolidation, Differentiation, and Entry Dynamics
Given the high concentration and the technical barriers associated with qualification, scale, and application validation, the market is likely to see continued consolidation pressure among smaller or less differentiated participants. At the same time, the bifurcation of demand and the emergence of specialized product attributes are creating space for targeted differentiation, even within a concentrated landscape. New entry remains challenging because of the need to secure design wins, pass validation protocols, and establish supply reliability across demanding customer segments. However, niche opportunities may arise in specialized architectural finishes, high-performance interlayers for specific automotive programs, or application-tailored solutions for photovoltaic encapsulation, where focused innovation and strong specification relationships can offset scale disadvantages. The broader trend is one of strategic segmentation: the market is not becoming uniformly consolidated into a single winners-take-all structure, but rather into a set of performance and application niches where distinct value propositions can command premium positioning.
VCI Film Market
For observers of competitive dynamics, the key question is not whether concentration will persist, but how value will be distributed within that concentrated structure. Leaders that can translate product innovation into specification wins and sustainability credentials into procurement preference will likely capture a disproportionate share of the incremental growth projected through the end of the decade and into the early 2030s.
Forward Outlook: Three Trends to Watch Over the Next Three to Five Years
Looking ahead, the PVB film market is likely to be shaped by trends that connect technological ambition, sustainability expectations, and application-specific demand. These trends carry both opportunity and risk, and they should inform near-term strategic planning.
Performance-Led Premiumization Accelerates
The push toward higher-performance interlayers is expected to intensify as automotive and architectural customers raise their expectations for structural capacity, acoustic behavior, durability, and design flexibility. This trend favors producers that can validate advanced attributes in relevant applications and secure design or specification wins early in program or project cycles. The commercial opportunity lies in building a portfolio of differentiated variants that address specific performance gaps, supported by technical service and application engineering. The risk is that premiumization outpaces the ability to scale qualified production or that customers resist premium pricing in cost-sensitive segments, forcing difficult trade-offs between margin and volume.
Sustainability Becomes a Specification Factor, Not a Differentiator
Sustainability credentials are on a trajectory from optional advantage to expected attribute in several regions and customer segments. Certification coverage across major production sites, the use of recycled or bio-based content, and renewable energy integration are increasingly part of supplier evaluations. The opportunity is to embed sustainability into product identity and process design in ways that are verifiable and customer-relevant, thereby reducing friction in qualification and strengthening preference in competitive bids. The uncertainty lies in the pace and uniformity of adoption. If expectations diverge significantly by region or application, producers may face complex portfolio and compliance decisions. If standards tighten faster than anticipated, firms that have not invested early may find themselves excluded from certain opportunities or forced into catch-up investments at higher cost.
Supply Chain Localization and Cost Discipline Reshape Competitive Resilience
Input volatility, currency exposure, and logistics complexity are likely to keep cost and supply resilience in focus. Producers will continue to pursue a mix of hedging, process efficiency, energy sourcing changes, and selective capacity adjustments. The opportunity for resilient operators is to combine cost discipline with reliable service and consistent quality, building trust with customers who are themselves managing procurement risk. The risk is that overinvestment in capacity in a softening segment or underinvestment in qualifying new variants can distort the portfolio and weaken competitive positioning. Additionally, regional cost structures and regulatory environments may create uneven profitability across geographies, requiring disciplined portfolio management rather than blanket expansion.
PW Consulting Chemical & Energy Research Center
Actionable Implications for Decision-Makers
For manufacturers, the priority is to align product roadmaps with the specific performance and aesthetic requirements of high-value applications while institutionalizing sustainability credentials across production sites. This means treating R&D as a commercial engine, not a back-office function, and ensuring that new variants are supported by validation data, technical service, and clear positioning. It also means building cost-risk management into the operating model, using hedging and process optimization to protect margins without compromising quality or service. Companies that can demonstrate measurable performance benefits and credible sustainability attributes are more likely to secure specification loyalty and defend premium positioning.
For investors, the strategic signal is that growth is real but unevenly distributed across applications and product tiers. The most attractive exposure is likely to be found in producers that combine application-relevant innovation with verified sustainability and disciplined cost management, rather than in undifferentiated volume plays. Due diligence should focus on qualification pipelines, certification coverage, raw material exposure, and the ability to convert product launches into specification wins. Portfolio valuation should account for the possibility that premiumization and sustainability adoption will accelerate in some regions and segments faster than others, creating divergence in growth and margin profiles across the competitive set.
For procurement and sourcing leaders, the practical guidance is to evaluate suppliers on a broader set of criteria that includes performance validation, sustainability verification, and supply assurance, not just unit price. The most resilient sourcing relationships will be those in which the supplier can demonstrate traceability, consistent quality, and the ability to support application-specific requirements over the life of a program or project. Engaging early in design and specification cycles, and aligning on sustainability and performance expectations upfront, can reduce downstream risk and improve total value.
For all of these audiences, the pace of change in the PVB film market argues for timely, granular intelligence. High-level growth figures and concentration ratios provide context, but the commercial decisions that matter most—program qualification, specification strategy, capacity allocation, sustainability investment, and sourcing commitments—depend on detailed segmentation data, regional demand patterns, and company-level trajectories. Accessing deeper, structured analysis can shorten the distance between market awareness and actionable strategy, enabling more precise prioritization of investments, partnerships, and risk mitigation.
PV Ribbon Market
For detailed analysis of this topic, please visit the official page: PVB Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sodium Permanganate Market: Why 4.6% CAGR and Water Treatment Demand Change Everything
By PW Consulting, 2026-09-21
Sodium Permanganate Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global sodium permanganate market is navigating a period of structural transformation, defined by steady expansion against a backdrop of regulatory tightening, raw material volatility, and evolving end-use requirements. Over the historical period spanning 2020 through 2025, market revenue demonstrated consistent upward movement, reflecting both post-pandemic industrial recovery and sustained investment in critical infrastructure. The base year of 2025 marks an inflection point where demand growth has begun to outpace earlier cyclical patterns, driven by capital expenditure programs in water infrastructure and electronics manufacturing. The forecast window through 2032 projects a compound annual growth rate of 4.6 percent, suggesting that the market will continue to expand at a moderate but resilient pace, supported by long-cycle investments rather than short-term discretionary spending.
Scale alone, however, does not define the strategic landscape. The market exhibits a pronounced concentration profile, with the top three firms controlling approximately seventy percent of revenue and the top five firms capturing roughly three-quarters of total share. This structure implies limited competitive fragmentation, high barriers to entry around certification and distribution networks, and a pricing environment where incumbents can exert meaningful influence over contract terms. At the same time, concentrated markets are vulnerable to supply shocks and regulatory adjustments that can cascade quickly through the value chain. The current environment presents several interrelated challenges that decision-makers must address.
First, raw material cost volatility has become a persistent pressure point. Manganese-based inputs underpin sodium permanganate production, and recent pricing movements in related chemical streams have introduced margin uncertainty. Quarter-over-quarter increases in manganese sulfate pricing, linked in part to higher sulfuric acid costs, illustrate how upstream inputs can compress profitability even when end-market demand remains robust. Second, supply disruptions tied to mining operations have reinforced the fragility of raw material availability. Weather-related interruptions at manganese-producing sites have periodically tightened supply, pushing ore prices higher and creating timing mismatches between procurement cycles and production schedules. These dynamics elevate the strategic importance of supplier diversification, inventory planning, and long-term contracting.
Third, regulatory frameworks are reshaping competitiveness in ways that go beyond simple compliance. Designations that elevate high-purity manganese to a strategic material status introduce new considerations around supply security, traceability, and alignment with broader policy priorities. In practice, this means procurement decisions increasingly factor in resilience and continuity alongside price and quality. Organizations that can demonstrate certified supply chains, documented compliance, and stable sourcing arrangements gain an advantage in bidding environments where reliability carries tangible commercial weight. Taken together, these challenges do not threaten the market’s trajectory, but they do reward firms that treat supply chain resilience and regulatory readiness as core capabilities rather than operational afterthoughts.
Key Drivers of Market Change
Technological Innovation and Product Differentiation
Innovation in sodium permanganate markets is less about radical chemistry shifts and more about precision, purity, and application fit. High-purity grades have gained traction in end-use segments where contamination sensitivity is critical, particularly in electronics manufacturing and specialized industrial processes. The availability of purity levels approaching ultra-high specifications reflects a broader trend toward customization: buyers are increasingly unwilling to accept commodity-grade solutions when performance margins and process reliability are at stake. This shift favors suppliers capable of delivering consistent quality with rigorous documentation and testing regimes.
Sodium Percarbonate Market
In parallel, liquid-formulation expertise continues to differentiate incumbents in water treatment applications. NSF-certified grades and compliance with AWWA standards have become baseline expectations in municipal and government procurement, not optional enhancements. Suppliers that can provide certified products, clear safety data documentation, and application support are better positioned to secure long-term contracts. The strategic implication is clear: technical credibility and certification infrastructure now function as competitive moats. In a concentrated market, the firms that invest early in quality systems and application-specific grade development are more likely to preserve pricing power and customer loyalty over time.
Policy and Regulatory Environment
Policy developments are increasingly influencing where capital flows and how supply chains are evaluated. The elevation of high-purity manganese within critical raw materials frameworks has made supply security a strategic priority for downstream industries and public-sector buyers alike. When manganese is explicitly recognized as a material important to supply security, procurement teams and project developers pay closer attention to sourcing origins, price stability, and the continuity of available grades. This does not simply add a compliance layer; it changes the decision calculus for large-volume contracts and infrastructure programs.
Simultaneously, government support for domestic production capacity in battery-grade and industrial manganese streams signals a longer-term shift toward supply localization in key geographies. Grant programs and policy incentives aimed at building production facilities reflect a broader emphasis on reducing dependence on imported inputs for strategic applications. For sodium permanganate markets, this creates a dual effect. On one hand, policy-driven investment in manganese production capacity could improve long-term availability and moderate input cost volatility. On the other hand, transitional periods may still be marked by tightness, regional disparities, and competition for intermediate materials. Companies that maintain visibility into these policy dynamics can better time procurement commitments, capacity planning, and partnership structures.
Manganese Sulphate Market
Demand-Side Shifts in Water Treatment and Electronics
Demand growth continues to be anchored by water treatment applications, where sodium permanganate remains a valued oxidizing agent for odor control, iron and manganese removal, and broader oxidation processes. Infrastructure budgets, public health priorities, and tightening water quality standards all contribute to sustained procurement needs in this segment. Importantly, large municipal and government contracts often follow multi-year planning cycles, meaning demand in this area is relatively stable but highly dependent on certification compliance, specification alignment, and trust in supplier reliability. Contract awards that reference NSF and AWWA standards exemplify how procurement processes reward documented conformity and supply consistency.
In the electronics segment, demand is shaped by process sensitivity and purity requirements rather than volume alone. High-specification applications reward suppliers capable of delivering tightly controlled grades with comprehensive quality documentation. As electronics manufacturing continues to emphasize reliability and contamination control, the value proposition of specialty-grade sodium permanganate strengthens. The broader demand picture includes additional application areas that add incremental growth and diversify end-use exposure, reducing reliance on any single vertical. For commercial strategy, the key insight is that demand-side strength varies by segment quality thresholds, procurement structures, and certification dependencies. Success depends on matching product architecture to the specific requirements of each major application rather than treating the market as a homogeneous whole.
Supply Chain and Cost Structure Dynamics
Cost structures in this market are heavily influenced by manganese availability, chemical input pricing, and the logistics of specialized distribution. Recent quarter-over-quarter increases in manganese sulfate pricing illustrate how quickly input economics can shift, especially when driven by higher costs for essential precursor chemicals such as sulfuric acid. These movements affect not only production costs but also the timing of contract negotiations and the structure of pricing terms. In concentrated markets, suppliers with established sourcing relationships and inventory buffers may be better positioned to manage short-term volatility without passing all costs downstream.
Supply disruptions from manganese mining operations further complicate cost planning. When production interruptions occur due to environmental incidents or operational constraints, ore prices can rise and availability can tighten, forcing downstream producers and distributors to adjust procurement strategies. Events such as mine suspensions linked to cyclone damage have shown how quickly physical supply conditions can change. The result is a market where resilience is increasingly priced into sourcing decisions. Buyers are willing to pay for assurance, and suppliers that can offer dependable continuity, transparent documentation, and proactive risk management gain leverage. Over time, this dynamic rewards organizations that treat supply chain design as a strategic function, integrating supplier diversification, contractual flexibility, and scenario planning into everyday operations.
Competitive Landscape and Leading Strategies
The competitive structure of the sodium permanganate market is defined by a small group of established U.S.-based producers and distributors with strong positioning in water treatment, government procurement, specialty-grade supply, and bulk distribution. This concentration reflects the importance of certification, application expertise, and supply reliability. Rather than competing primarily on price, leading firms differentiate through product grades, compliance documentation, distribution reach, and customer relationships built around recurring contract cycles.
Carus Corporation stands out as a major producer and supplier of liquid sodium permanganate for water treatment applications, including NSF-certified grades. Its strategic positioning centers on alignment with municipal and industrial water treatment requirements, where certification and product consistency are decisive. By maintaining a focus on certified grades and application-oriented supply, the company reinforces its role in high-value public-sector and industrial procurement environments. In a market where contract awards increasingly reference NSF and AWWA standards, that certification-oriented posture is a meaningful competitive asset.
Hawkins, Inc. operates as a domestic manufacturer, blender, and distributor with a B2B-only sales model focused on municipal and government water treatment. Its strategy emphasizes local production and distribution reliability, targeting customers that prioritize continuity of supply and direct commercial relationships. The B2B-only orientation allows the firm to concentrate on specification-driven buyers rather than broader retail-style channels. This model supports stable demand attachment to public-sector and institutional customers where procurement processes favor established distribution partners with documented compliance capabilities.
Valudor Products, LLC supplies 40 percent sodium permanganate solution certified for water treatment with full safety data documentation. Its differentiation is rooted in product specification clarity and documentation completeness, which matter in procurement settings where compliance and transparency are non-negotiable. Suppliers that make safety data sheets and certification information readily accessible reduce friction in the purchasing process and strengthen trust with buyers who must satisfy internal and external audit requirements. In concentrated markets, even incremental improvements in documentation and specification clarity can influence supplier selection.
American Elements positions itself around high-purity offerings, providing sodium permanganate at purity levels up to 99.999 percent for commercial, research, and industrial uses. This strategy targets segments where purity thresholds drive value rather than cost minimization alone. High-purity specialization creates a different competitive logic: customers in electronics and advanced industrial applications often prioritize grade integrity and documentation over bulk commodity pricing. By focusing on ultra-high purity capability, the company serves demand that is less sensitive to commodity price fluctuations and more sensitive to performance assurance.
Rock Chemicals, Inc. operates as a trusted bulk supplier with emphasis on reliable sourcing and compliance documentation. Its positioning reflects a practical, reliability-first value proposition: customers in bulk procurement environments value consistency, sourcing transparency, and the ability to meet compliance requirements without administrative delay. In a market where raw material volatility and supply interruptions are real risks, that emphasis on dependable sourcing and documentation provides a practical competitive edge, especially for procurement teams seeking to reduce uncertainty in recurring supply contracts.
Recent procurement activity highlights how these competitive dynamics play out in practice. Contract awards such as the 2025 supply agreement for sodium permanganate under NSF and AWWA standards demonstrate that public-sector buyers continue to prioritize certified compliance and specification alignment. Such contracts reinforce the value of firms that can meet documented standards and sustain reliable delivery. In a concentrated market, these wins are not merely transactional; they signal a broader pattern where certification readiness and procurement compatibility shape share dynamics over multi-year horizons. The competitive landscape is likely to evolve through selective integration, deeper specialization by purity or application, and the continued importance of distribution and documentation capabilities. New entrants will face steep barriers unless they can credibly replicate certification infrastructure, supply reliability, and customer trust.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several interconnected trends are likely to shape commercial strategy in sodium permanganate markets. The first is a reinforcement of certification and compliance as competitive drivers. As water infrastructure procurement remains anchored in public-sector standards and industrial buyers demand documented traceability, firms with robust certification portfolios and clear application-specific grades will be better positioned to win and retain contracts. The opportunity here lies in strengthening application alignment, expanding certified grade availability where feasible, and reducing friction in the buyer’s compliance review process. Organizations that can provide clearly documented, specification-matched products will find it easier to command premium positioning in procurement cycles where risk avoidance matters.
A second trend is the continued tension between demand resilience and raw material volatility. Infrastructure spending and electronics-related demand are expected to provide underlying support, but input cost fluctuations tied to manganese sulfate pricing and mining disruptions will likely remain a recurring theme. This creates commercial opportunities for firms that can secure longer-term sourcing arrangements, build inventory buffers where appropriate, and design pricing structures that balance stability with flexibility. For buyers, the opportunity is to reduce exposure through diversification, strategic contracting, and clearer visibility into upstream pricing signals. For suppliers, the opportunity is to differentiate through reliability, documentation, and service quality in a market where continuity can be as valuable as unit price.
The third trend is the growing influence of strategic raw material policy on supply chain behavior. As manganese gains recognition within critical materials frameworks and public investment supports domestic production development, procurement and production strategies may gradually shift toward greater supply security, regional diversification, and alignment with policy priorities. This creates opportunities for firms that can articulate supply resilience, traceability, and continuity as part of their commercial value proposition. At the same time, transitional uncertainty may persist, particularly during periods when new capacity is being developed but has not yet stabilized availability. Decision-makers should therefore plan for a market environment where policy, sourcing, and pricing interact more closely than in the past.
These trends carry potential risks and uncertainties. Raw material price swings can compress margins or trigger renegotiation pressure if contracts lack flexibility. Regulatory changes can alter compliance expectations faster than product or documentation systems can adapt. Supply disruptions may expose overreliance on limited sourcing channels. In addition, market concentration means that shifts in the strategy or capacity of a small number of incumbents can affect overall availability and pricing dynamics. The commercial opportunity is not simply to forecast growth, but to build operational and commercial buffers that allow firms to respond decisively when conditions change.
Actionable Guidance for Decision-Makers
For manufacturers and producers, the priority is to reinforce differentiation through grade specialization, certification readiness, and supply reliability. Investment in high-purity capability, certified water treatment grades, and rigorous documentation can support premium positioning in application-sensitive segments. Equally important is proactive management of input costs and sourcing risk. Diversifying supplier relationships, maintaining visibility into manganese-related pricing trends, and structuring contracts with appropriate flexibility can protect margins without sacrificing customer trust. Manufacturers should also consider how application-specific support, technical documentation, and compliance clarity can reduce friction in customer qualification processes, especially where procurement cycles are long and specification-driven.
For investors, the market presents a profile of steady growth with concentrated leadership and strategic sensitivity to raw material and regulatory dynamics. Due diligence should focus on supply chain resilience, certification positioning, and exposure to input cost volatility rather than on top-line growth alone. Companies with strong compliance documentation, recurring government or municipal contracts, and credible sourcing strategies are better equipped to withstand disruptions and defend pricing. At the same time, investors should monitor the pace of policy-driven capacity development and any shifts in manganese availability that could affect cost structures or regional supply patterns. In concentrated markets, competitive advantage often depends on reliability and credibility as much as scale, so qualitative assessments of operational maturity can be as important as financial metrics.
For procurement teams and buyers, the strategic priority is to reduce exposure to volatility while preserving quality and compliance. Diversifying approved suppliers, aligning purchasing cycles with upstream cost signals, and prioritizing vendors with robust certification and documentation can improve contract stability. Where possible, long-term agreements should incorporate mechanisms that address raw material price movements without sacrificing service quality or specification integrity. Procurement strategies should also account for the increasing importance of supply security and continuity in public-sector and industrial environments, where auditability and reliability can outweigh marginal price differences. In this context, detailed segment-level intelligence on grade demand, certification dependencies, and sourcing risk can materially improve sourcing decisions.
For organizations seeking a more granular view of segment dynamics, regional demand patterns, and contracting trends, deeper analysis can clarify where value is created and where risk concentrates. A detailed research report can provide the segmented data, competitive mapping, and scenario context needed to support pricing, capacity, and sourcing decisions with greater precision. Given the pace of regulatory and raw material developments, timely access to structured market intelligence is not merely an analytical exercise; it is a practical input to strategy execution. For decision-makers who need to translate market signals into procurement, investment, or product strategy, a fuller examination of the data and competitive dynamics can help ensure that action plans are grounded in current conditions rather than assumptions.
PW Consulting Chemical & Energy Research Center
For detailed analysis of this topic, please visit the official page: Sodium Permanganate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Natural Astaxanthin Market: Why 9.1% CAGR & Shifting Demand Dynamics Redefine Growth
By PW Consulting, 2026-09-21
The Natural Astaxanthin Market: Strategic Trends and Commercial Opportunities
The natural astaxanthin sector has evolved from a niche antioxidant into a strategically significant ingredient market, driven by converging forces in health and wellness, aquaculture growth, and formulation innovation. Between 2020 and 2025, global revenue expanded from approximately 248.56 million to 372.0 million, reflecting a compound annual growth rate of 9.1 percent. Looking ahead to 2032, the trajectory points toward 686.45 million, with the forecast period (2026-2032) expected to sustain momentum as applications diversify and production systems mature. This growth is not uniform across sources, formats, or end-use categories, and the strategic value for decision-makers lies in understanding where scale, differentiation, and regulatory clarity intersect.
For executives, investors, and procurement teams, the market’s appeal rests on three characteristics: a rich antioxidant profile that commands premium positioning in human nutrition, a biologically active pigment that serves functional roles in animal health, and a supply base that is transitioning from fragmented cultivation to increasingly engineered production environments. Yet the sector is also navigating structural tensions around feedstock economics, regional regulatory divergence, and the balance between batch consistency and cost efficiency. The following analysis maps the current landscape, the forces reshaping it, the competitive postures defining it, and the strategic moves that will separate winners from followers over the next three to five years.
Market Snapshot and Core Tensions
The macro picture is straightforward: demand is expanding, and the revenue curve is steepening as downstream applications broaden. What makes this market strategically interesting is not the headline growth alone, but the way value is distributed across production methods and form factors. Microalgae-derived astaxanthin represents the dominant share of the market, reflecting years of cultivation refinement and the ingredient’s positioning as a clean, plant-based antioxidant. Yeast-based routes account for a meaningful secondary share, offering distinct scalability and cost profiles. Smaller contributions come from krill and shrimp-derived sources, along with other niche inputs. The split matters because each source carries different cost structures, purity expectations, and application fit, which in turn shape pricing power and customer acquisition strategies.
On the formulation side, powder continues to lead in market share, underscoring its versatility across nutraceutical blends, feed premixes, and cosmetic bases. Oil-based formats remain important where bioavailability and sensory performance are priorities, while softgel and other consumer-ready forms occupy a smaller but growing niche as finished-product manufacturers seek convenience and perceived premium quality. Regionally, the market is balanced rather than concentrated in a single hub, with North America, Europe, and Asia Pacific each representing substantial demand centers, and Latin America plus the Middle East and Africa contributing more specialized but increasingly active demand. This geographic spread creates both diversification benefits and complexity in regulatory navigation.
Several structural tensions define the current inflection point. First, feedstock economics remain a persistent pressure point. Natural astaxanthin from Haematococcus pluvialis powder is the primary upstream feedstock for commercial production, with global output estimated at around 800 metric tons annually. This concentration creates sensitivity to cultivation yield, harvest timing, contamination risk, and energy inputs. Companies that can stabilize biomass supply and reduce per-unit production cost gain a durable advantage, but the pathway is capital-intensive and technically demanding.
Second, regulatory divergence is shaping where and how ingredients can be positioned. In the European Union, EFSA concluded in December 2025 that proposed uses of algal meal and oleoresin from Haematococcus pluvialis at levels exceeding the FEEDAP ADI of 0.034 mg/kg body weight per day cannot be established for non-food-supplement applications. At the same time, the powder with 5.0%–5.6% w/w ATX and oleoresin with 10%–12% w/w ATX has been restricted in the EU to food supplements since 1995 under novel food rules. These boundaries create a clear ceiling for certain feed and food uses in Europe, while simultaneously reinforcing the strategic importance of food supplement channels and premium nutraceutical positioning. AstaReal AB also submitted an application in December 2025 for novel food authorization covering algal meal, red viscous oleoresin, and water-dispersible formulations, signaling that the regulatory map is still being redrawn and that clarity, once achieved, can unlock new commercial pathways.
Third, the market is balancing scale against differentiation. With a CR3 of 42.5 percent and CR5 of 56.8 percent, the sector is moderately consolidated, but the room for regional specialists, formulation innovators, and application-specific suppliers remains meaningful. The tension lies in whether growth will be captured by producers who compete primarily on volume and cost, or by those who build defensible positioning through purity claims, traceability, application expertise, and regulatory readiness.
Key Drivers Reshaping the Market
Technology Innovation and Process Maturation
Production technology is moving from artisanal cultivation toward engineered control. Closed-system photobioreactors, improved strain performance, and tighter contamination management are reducing variability in biomass quality and astaxanthin yield. These advances matter because astaxanthin’s value proposition depends heavily on purity, isomer profile, and oxidative stability. Manufacturers that can deliver consistent specifications across batches gain credibility with formulators and finished-product brands, especially in nutraceuticals and cosmetics where claims and consumer trust are tightly linked to ingredient quality. At the same time, open-pond systems continue to play a role where cost efficiency and scale are paramount, particularly for feed-oriented volumes. The strategic question is not which system wins outright, but how each producer aligns technology choice with target applications and margin expectations.
Formulation technology is also advancing the commercial narrative. Water-dispersible and stabilized variants, beadlet integration, and oleoresin refinement expand the ingredient’s usability across matrices that historically posed dispersion or stability challenges. These improvements reduce formulation friction for customers and create opportunities for higher-value, application-tailored offerings rather than commodity-style transactions.
Policy and Regulatory Environment
Regulation is both a constraint and a catalyst. In Europe, the boundaries around feed and broader food uses are being clarified through EFSA opinions, which compresses certain expansion pathways while reinforcing the value of compliance-ready supply. In parallel, novel food authorization efforts signal potential future openings, especially if data packages support broader usage levels or new formulation types. For market participants, the strategic implication is that regulatory readiness is becoming a differentiator. Companies that proactively build dossiers, maintain documentation for traceability and safety, and align labeling and claims with regional requirements can move faster when opportunities open, and avoid disruption when restrictions tighten.
Beyond Europe, regulatory and certification dynamics in destination markets influence purchasing decisions in nutraceuticals, food and beverages, and aquaculture. Organic certification, GRAS status for food use, and contamination control documentation increasingly serve as gatekeeping criteria for buyers who need to defend ingredient choices to regulators, retailers, and end consumers. Regulatory alignment is therefore not simply a compliance exercise; it is a commercial enabler.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, three shifts are particularly relevant. First, the nutraceutical segment continues to anchor demand for natural astaxanthin, supported by consumer interest in antioxidant support, eye health, skin health, and sports recovery formulations. This segment rewards clarity of benefit, clean-label positioning, and brand trust, which in turn favors suppliers that can provide documentation, consistency, and application support. Second, aquaculture and animal feed represent a large and growing demand pool, where astaxanthin’s functional role in pigmentation and health supports adoption in shrimp, salmon, and other species. Here, cost-per-unit performance, batch reliability, and regulatory compliance for feed applications are central, and pricing sensitivity is higher than in premium human nutrition. Third, cosmetics and food and beverage applications, while smaller in share, create high-visibility branding opportunities and can command premium positioning when combined with compelling sensory and stability attributes.
The broader behavioral trend is a move toward ingredients with documented origin, sustainable production stories, and transparency. Buyers are increasingly hesitant to treat natural astaxanthin as a interchangeable input; they want assurance that sourcing, extraction, and final specifications meet the requirements of their specific market and claim structure.
Fucoxanthin (CAS 3351-86-8) Market
Supply Chain and Cost Structure Evolution
Cost structure dynamics are shifting as production volumes scale and operational efficiency improves. Recent developments illustrate this clearly. In June 2025, Cyanotech Corporation reported meaningful improvement in gross margin for fiscal 2025, with increasing production volumes of BioAstin Hawaiian Astaxanthin driving lower per-unit costs. This is a useful signal that scale, when combined with process maturity, can translate into margin expansion rather than merely top-line growth. In May 2025, Beijing Gingko Group announced expansion of astaxanthin manufacturing facilities in Yunnan Province, including a new research laboratory to support its AstaZine natural astaxanthin line. Capacity expansion of this kind indicates confidence in demand durability and a push to strengthen both volume and technical capabilities. Meanwhile, in July 2024, Algatechnologies introduced AstaPure 5% natural astaxanthin for softgels, extending its product line with all-natural extracts. Moves like this show how suppliers are layering formulation-specific offerings onto core production capabilities to capture more value.
The broader supply chain implication is that advantage is increasingly determined by integrated control over cultivation, extraction, and finishing, or by strong partnerships that achieve the same effect. Fragmented, transactional supply chains create exposure to quality variation and price volatility, while integrated or closely coordinated models support specification reliability, margin retention, and faster response to customer needs. Energy costs, water management, and contamination control remain critical cost drivers, especially for microalgae-based systems, and will continue to separate efficient operators from less optimized ones.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The market’s competitive core includes a mix of established producers with proprietary cultivation and extraction systems, regional specialists with strong application focus, and larger nutrition and ingredient groups leveraging astaxanthin as part of broader portfolios. The strategic distinction lies less in participation alone and more in how each company constructs defensibility.
AstaReal Inc. operates with a clear brand-centered strategy around natural astaxanthin from Haematococcus pluvialis microalgae, supported by patented cultivation systems and contributions to standards development. Its emphasis on branded extracts, oleoresin, and powder across nutraceutical, cosmetic, and food applications reflects a premium, documentation-rich approach that targets customers seeking reliability and claim support.
Cyanotech Corporation has built a long-standing position around integrated Haematococcus pluvialis cultivation and extraction, with patented open-pond technology and GRAS certification for food use. Its BioAstin Hawaiian Astaxanthin line illustrates how regional identity, certification, and production scale can combine into a recognizable offering. Recent margin improvement tied to higher production volumes reinforces the value of scaling mature processes efficiently.
Algatechnologies Ltd. focuses on high-purity natural astaxanthin from closed-system cultivation, supplying premium extracts and oleoresin with strict contamination control for nutraceuticals, cosmetics, and aquaculture. Its emphasis on purity and controlled environments aligns with buyers who prioritize specification consistency and risk reduction, particularly in sensitive applications.
Beijing Gingko Group stands out as a large-scale producer of natural astaxanthin from Haematococcus pluvialis, offering certified organic biomass, powder, and extracts for global nutraceutical and feed markets. Its scale, ongoing facility expansion, and research investment position it to compete on volume, cost, and broad application coverage, while also building technical depth.
Algalif Iceland operates a large-scale photobioreactor facility and supplies sustainable Haematococcus-derived extracts under its own brand for premium nutraceutical applications. Its strategy highlights how geographic identity, controlled production, and sustainability narratives can support premium positioning in targeted downstream markets.
Fuji Chemical Industry contributes through natural astaxanthin manufacturing via its AstaReal subsidiary, providing high-purity extracts, beadlets, and formulations for human consumption and related applications. This reflects a formulation-oriented model that adds value through finished or semi-finished formats tailored to end-use requirements.
Divis Laboratories Limited participates as a supplier of natural astaxanthin extracts and derivatives, with focus on nutraceutical and cosmetic grades and sustainable sourcing. Its role illustrates the importance of specialty extraction and derivative capabilities in markets where customization and grade differentiation matter.
Astaxanthin (CAS 472-61-7) Market
Differentiation, Consolidation, and New Entry Dynamics
Differentiation is coalescing around several axes: purity and specification control, application-specific formulation support, regulatory readiness, sustainability and traceability claims, and the ability to scale without sacrificing consistency. The most resilient players tend to combine at least two of these strengths rather than competing on a single dimension. For example, a producer may pair controlled cultivation with strong documentation, or combine scale with brand and certification advantages that help customers justify ingredient choices to their own stakeholders.
The market is not moving toward extreme concentration in the near term, but selective integration is likely. Expect more partnerships between cultivation specialists and formulation or distribution networks, more regional capacity investments aligned with local demand and regulatory conditions, and more vertical coordination where producers seek to control feedstock, extraction, and finishing to protect margin and quality. At the same time, new entrants will continue to appear where they can offer a credible technology edge, a defensible sustainability story, or access to an underserved application. The barrier is not simply capital; it is the ability to deliver consistent quality, navigate regulatory complexity, and build buyer trust in a market where claims and contamination risk carry real consequences.
Future Trends and Commercial Opportunities
Over the next three to five years, several trends are likely to define the market’s evolution.
-
Application diversification with a premium core. Nutraceuticals will remain the anchor, but growth will increasingly come from better-matched formulations, stabilized variants, and application-specific grades that reduce customer friction and support stronger positioning. Cosmetics and food and beverage uses will remain smaller in share but can deliver outsized brand value when paired with sensory quality and regulatory compliance.
-
Regulatory clarity as a competitive filter. As novel food and feed-related assessments progress, the regulatory map will become clearer in some regions and more constrained in others. Companies that have already invested in documentation, safety data, and compliant positioning will be better placed to expand into newly authorized uses or defend existing channels when restrictions crystallize.
PW Consulting -
Margin improvement through scale and process control. The recent margin improvement reported by established producers suggests that scale, when combined with mature cultivation and extraction processes, can convert volume growth into profitability. Capacity expansions and research investments indicate that leading players are preparing for sustained demand rather than treating growth as a short-cycle opportunity.
-
Sustainability and traceability as purchase criteria. Buyers are increasingly weighing origin, energy and water intensity, and supply transparency. Producers that can substantiate sustainability claims and provide traceable batches will gain advantage in premium segments and in procurement environments where reputational risk matters.
These trends translate into concrete commercial opportunities. For producers, the opportunity lies in aligning capacity and technology with the applications that offer the best combination of margin, growth, and defensibility, rather than chasing all segments equally. For ingredient buyers and formulators, there is an opportunity to secure reliable supply of specification-consistent astaxanthin that supports stronger claims, cleaner labels, and more stable procurement costs. For investors, the appealing thesis centers on operators that combine process maturity, regulatory readiness, and application focus with a credible path to margin expansion as volumes scale.
Potential risks and uncertainties should not be understated. Feedstock availability and cultivation risk can affect supply consistency and pricing, particularly if contamination events or yield variability intensify. Regulatory outcomes may narrow certain applications in key regions, especially where feed and broader food uses face tighter limits. Competitive intensity could compress margins if supply expands faster than demand in specific formats or regions. And claim substantiation expectations may rise, increasing the cost of doing business for suppliers that cannot provide robust documentation and traceability. These risks do not negate the growth outlook, but they do mean that execution quality will determine who captures value.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to match technology and capacity strategy to the applications where differentiation is most defensible. If the target is premium nutraceuticals and cosmetics, investment in controlled cultivation, purity assurance, and documentation is likely to pay off more than pure volume expansion. If the target includes aquaculture and feed, the focus should be on cost efficiency, batch reliability, and compliance with regional feed rules, while preserving enough quality consistency to maintain customer trust. In both cases, formulation-specific offerings and finished or semi-finished formats can help capture more value than commodity supply alone.
For investors, the most compelling opportunities are likely to be found in operators that demonstrate a combination of process maturity, credible regulatory readiness, and a clear application focus. Capacity expansion is meaningful only when paired with the ability to convert volume into margin, and regulatory navigation is increasingly part of the valuation story. Due diligence should examine not just scale and geography, but also contamination control, documentation quality, formulation capability, and the durability of customer relationships in segments where specification consistency matters.
For procurement teams and formulators, the strategic move is to treat natural astaxanthin as a specification-driven ingredient rather than a interchangeable input. Locking in supply partnerships with suppliers that can provide consistent batches, transparent origin, and application support will reduce reformulation risk and strengthen claim confidence. Diversifying across sources and formats where appropriate can also mitigate exposure to regional regulatory shifts or feedstock constraints, especially when planning for longer-term product roadmaps.
The market’s next phase will reward participants who combine technical discipline with commercial clarity. As regulatory boundaries become sharper, production systems become more engineered, and buyers demand stronger documentation and sustainability assurance, the winners will be those who can deliver consistent quality at scale while aligning their offerings to the applications that matter most. For decision-makers seeking to move from broad market awareness to actionable planning, deeper segmentation, supplier benchmarking, and region-specific regulatory mapping will be essential. PW Consulting’s full research report on the natural astaxanthin market provides that level of detail, including segmented demand dynamics, competitive benchmarking, and tailored recommendations designed to support investment, sourcing, and product strategy decisions.
For detailed analysis of this topic, please visit the official page: Natural Astaxanthin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Machine Stretch Film Market: Why 5.5% CAGR from 2026 to 2032 Redefines Packaging Strategy
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Machine Stretch Film Market
The machine stretch film market has entered a period of structural transformation, moving beyond incremental volume growth to a phase where material science, regulatory pressure, and supply chain resilience redefine competitive advantage. Valued at approximately $360 million in 2025, the market has expanded from roughly $280 million in 2020, reflecting a compound annual growth rate of 5.5 percent through the 2026-2032 forecast horizon. This trajectory is not merely a function of increased pallet wrapping activity; it signals a deeper shift in how logistics operators, manufacturers, and retailers approach load containment, material efficiency, and end-of-life accountability. The market's composition reveals a clear hierarchy in product architecture and application demand, with cast extrusion technologies and logistics-driven use cases commanding the largest revenue shares. Yet the headline figures only scratch the surface. Beneath the growth curve lies a landscape where raw material volatility, extended producer responsibility mandates, and performance differentiation are forcing incumbents and new entrants alike to recalibrate their operating models.
Rebuilding Margins in a Volatile Input Environment
One of the most persistent challenges shaping strategic decision-making is the pricing instability of primary and recycled polyethylene feedstocks. In May 2026, linear low-density polyethylene prices in North America hovered between $1.13 and $1.16 per kilogram, while regional increases of 8.7 to 12.6 percent were reported across Asia and Europe. This input pressure compounds with tighter availability of recycled LLDPE pellets, which traded between 55 and 60 cents per kilogram in 2025 and faced continued upward pressure into 2026 due to supply constraints. For film producers, this environment erodes the traditional cost-pass-through mechanism, particularly in commoditized blown film segments where differentiation is limited. Companies that rely on volume-based pricing without performance or sustainability premiums are seeing margin compression, while those with integrated resin strategies or advanced extrusion capabilities are better positioned to absorb fluctuations without sacrificing competitiveness.
Regulatory Compliance as a Design Constraint, Not an Afterthought
The regulatory landscape has shifted from voluntary sustainability commitments to mandatory material sourcing and reporting requirements. As of August 2025, five U.S. states mandate post-consumer recycled content in plastic packaging, with stretch film falling under flexible packaging targets within extended producer responsibility frameworks. Minnesota's Packaging Waste and Cost Reduction Act, implemented in phases through 2025 and 2026, requires producers to comply with EPR plans that explicitly cover stretch film. Simultaneously, EU and U.S. EPR schemes active in 2026 include mandatory recycled content goals that directly influence production formulations and material procurement. These regulations are no longer peripheral compliance exercises; they are redesigning the economics of film production. Manufacturers must balance recycled content integration with tensile strength, cling, and puncture resistance requirements, while avoiding penalties or market access restrictions in jurisdictions with tightening standards. The operational implication is clear: compliance is becoming a product development parameter, not a post-production adjustment.
Performance Expectations Outpacing Traditional Formulations
A third inflection point lies in the growing disconnect between standardized film specifications and the operational realities of automated wrapping lines. High-throughput distribution centers, robotic palletizers, and precision load containment requirements demand films that maintain stability at high pre-stretch ratios, resist punctures during high-stack storage, and deliver consistent cling without excessive material usage. Traditional blown films often struggle to meet these combined performance thresholds, creating sustained demand for cast and pre-stretched alternatives that offer tighter gauge control, higher elongation, and reduced consumption per pallet. The challenge for producers is to engineer formulations that satisfy these operational demands while navigating recycled content mandates and input cost volatility. Companies that treat performance and sustainability as competing priorities are losing ground to those that integrate both into a single product architecture.
Key Drivers Reshaping Market Dynamics
The market's trajectory is being pulled by four interconnected forces that are redefining how machine stretch films are engineered, sourced, and deployed. Understanding these drivers is essential for executives evaluating capacity investments, procurement strategies, or portfolio positioning.
Advanced Extrusion and Multi-Layer Architecture
Technological progress in nano-layer extrusion and precision gauge control is fundamentally altering the performance ceiling of machine-applied stretch films. Multi-layer coextrusion enables manufacturers to distribute material properties across functional layers, achieving higher stretch ratios and improved load containment without increasing total film weight. Recent product launches demonstrate this shift in action. A major producer commissioned a new 55-layer nano-layer extrusion line in Ohio, delivering machine stretch films with up to 350 percent stretch and approximately 25 percent material reduction. Another specialist introduced pre-stretched film lines incorporating 35 percent post-consumer recycled content while maintaining tensile strength at 22 MPa for machine applications. These developments illustrate a broader industry movement: performance and material efficiency are no longer trade-offs but co-engineered outcomes. For downstream users, this translates into fewer film changes, lower consumption per wrap cycle, and more predictable load stability on automated lines.
Extended Producer Responsibility and Recycled Content Mandates
Policy frameworks are accelerating the integration of recycled polyethylene into machine-grade films, transforming what was once a niche sustainability offering into a compliance-driven baseline. With multiple U.S. states and EU jurisdictions enforcing recycled content targets within EPR schemes, producers are reformulating products to meet minimum thresholds without compromising machine performance. One integrated packaging group launched pre-stretched lines with 35 percent PCR content, while two other major producers introduced stretch film lines featuring 30 percent post-consumer recycled content for high load stability. These milestones reflect a structural shift: recycled content is becoming a spec requirement, not a marketing differentiator. The operational impact extends beyond formulation. Procurement teams must secure consistent recycled resin supply, quality control protocols must adapt to variable feedstock characteristics, and sales teams must articulate performance equivalence to customers transitioning from virgin-only films.
Demand-Side Pressure for Load Containment and Throughput Optimization
End-users are increasingly prioritizing films that reduce waste, minimize changeover downtime, and maintain integrity under high-stack or long-transit conditions. Logistics and distribution operations, which represent the largest application share, are operating with thinner margin buffers and higher throughput expectations, making film consumption a visible cost lever. Food and beverage applications add further complexity, requiring films that balance cling, clarity, and regulatory compliance for perishable or branded goods. Agriculture and industrial packaging sectors demand puncture resistance and weather tolerance, while still seeking material efficiency gains. The common thread across these segments is a preference for films that deliver predictable performance at lower total usage, rather than simply lower price per kilogram. This behavior is reshaping purchasing criteria: total cost per wrapped pallet, line efficiency, and load rejection rates are gaining weight over raw material price alone.
Feedstock Sourcing and Supply Chain Recalibration
The combination of virgin resin price increases and recycled pellet supply constraints is forcing companies to rethink sourcing strategies. Regional price divergence means that producers with geographically diversified resin procurement or localized recycling partnerships can mitigate cost shocks more effectively than those dependent on single-region supply chains. Some manufacturers are integrating recycled polyethylene directly into machine-grade products through new resin blending protocols, while others are investing in closed-loop recovery programs with large logistics customers. The broader implication is that supply chain resilience is becoming a competitive differentiator. Companies that secure predictable access to qualified recycled and virgin feedstocks, while maintaining formulation flexibility, are better equipped to sustain pricing stability and service reliability amid market turbulence.
Worldwide Puncture Resistance Stretch Film Market
Competitive Landscape and Strategic Positioning
The machine stretch film market is characterized by a concentrated core of established producers alongside specialized manufacturers and regional suppliers navigating distinct competitive niches. The top three players collectively account for approximately 55 percent of market revenue, while the top five extend their share to around 70 percent. This concentration reflects the technical barriers to high-performance extrusion, the importance of integrated resin and film production capabilities, and the value of long-term relationships with large logistics and industrial customers. Yet the landscape is not static. Product launches, formulation innovation, and regulatory-driven reformulation are creating pockets of differentiation that allow smaller or regional players to compete on performance specificity rather than sheer scale.
Performance Engineering as the Primary Differentiator
Leading manufacturers are competing on measurable performance attributes rather than generic film availability. One producer emphasizes nano-layer extrusion lines that deliver up to 350 percent stretch with material reduction, targeting automated pallet wrapping operations where film consumption and load stability are critical. Another manufacturer highlights Rite-Gauging technology for consistent pre-stretch and reduced usage, alongside high-cling and high-load containment variants designed for demanding distribution environments. A specialist producer focuses on clarity, stretch performance, and high-strength applications tailored to automated wrapping systems, while a separate player offers series films engineered for pre-stretch levels exceeding 300 percent, high load containment, and puncture resistance. These positioning strategies reflect a shared insight: customers are willing to pay for reliability, reduced consumption, and line compatibility, provided the performance claims are verifiable and consistent.
PLA Biodegradable Stretch Film Market
Sustainability Integration as a Operational Imperative
Sustainability is increasingly embedded into product portfolios rather than marketed as a separate line. Producers are launching films with 30 percent post-consumer recycled content, integrating recycled polyethylene into machine-grade products through new resin protocols, and aligning formulations with EPR and recycled content mandates. One European supplier emphasizes sustainability and performance in its machine-applied stretch films, while a global packaging group positions its machine stretch films within an integrated portfolio focused on performance and cost efficiency. This convergence of sustainability and performance is reshaping competitive dynamics. Companies that treat recycled content integration as a core engineering challenge, supported by consistent feedstock access and robust quality assurance, are building defensible positions. Those that rely on superficial sustainability claims without performance validation risk losing credibility with procurement teams that must meet both cost and compliance targets.
Market Evolution: Consolidation Pressure and Niche Differentiation
The market is experiencing simultaneous forces of consolidation and fragmentation. Scale advantages in resin procurement, extrusion capacity, and distribution networks favor larger producers, particularly in mature regions where automated wrapping infrastructure is widespread. At the same time, regional suppliers and specialists are carving out positions by focusing on specific performance needs, localized service, or regulatory-aligned formulations. New entrants face high technical and compliance barriers, but opportunities exist for companies that can address underserved application requirements, offer verifiable performance improvements, or provide flexible supply arrangements in regions with growing logistics infrastructure. The likely trajectory is a market where a concentrated core sets baseline performance and pricing expectations, while specialized players compete on formulation precision, application-specific engineering, and regional responsiveness.
Forward Outlook: Three Critical Trends for 2026-2032
The next several years will be defined by how quickly producers, investors, and procurement leaders adapt to the intersection of performance demands, regulatory constraints, and input cost dynamics. Three trends are likely to shape strategic outcomes.
Recycled Content as a Baseline, Not a Premium
Mandatory recycled content targets will continue to normalize PCR integration across machine stretch film portfolios. As more jurisdictions enforce minimum thresholds and EPR frameworks tighten, films without qualified recycled content will face procurement disadvantages or market access limitations. This trend creates opportunities for producers with proven formulation stability, consistent recycled resin supply, and transparent compliance documentation. It also introduces risk for companies that overpromise on recycled content without ensuring tensile strength, cling, and puncture resistance remain within specification. The commercial opportunity lies in offering films that meet or exceed regulatory requirements while delivering measurable performance parity or improvement, thereby converting compliance from a cost center into a competitive asset.
PW Consulting
Material Efficiency and Automated Line Optimization
The push toward higher stretch ratios, tighter gauge control, and reduced consumption per pallet will intensify as distribution centers seek to lower total wrapping costs and improve line throughput. Films that enable consistent pre-stretch, minimize changeover variability, and maintain load stability under automated operation will see sustained demand. Producers investing in multi-layer extrusion, precision dispensing compatibility, and application-specific formulations are well positioned to capture this shift. The risk lies in over-engineering films for narrow use cases without ensuring broad compatibility across wrapping equipment and load types. Success will depend on balancing performance specificity with practical deployability across diverse operational environments.
Regional Divergence in Regulatory and Supply Dynamics
Regulatory mandates, recycled resin availability, and virgin resin pricing will continue to diverge across regions, creating uneven competitive conditions. North America and Europe are likely to see faster adoption of EPR-aligned formulations and recycled content integration, while Asia Pacific and emerging markets may experience more gradual regulatory rollout but stronger volume growth driven by expanding logistics infrastructure. LLDPE price increases of 8.7 to 12.6 percent in Asia and Europe, alongside North American price levels around $1.13 to $1.16 per kilogram, illustrate the regional cost landscape that producers must navigate. Companies with flexible sourcing strategies, localized production, or regionally tailored product lines will be better equipped to manage these divergences. The uncertainty centers on the pace and uniformity of regulatory enforcement, the stability of recycled resin supply, and the potential for trade or tariff shifts that could disrupt feedstock flows.
Strategic Actions for Decision Makers
Translating these trends into actionable strategy requires different priorities depending on a company's role in the value chain. The following recommendations highlight where focused effort can yield the strongest returns.
For film manufacturers and producers: Prioritize formulation engineering that treats recycled content and performance as integrated design parameters. Invest in extrusion capabilities that enable higher stretch ratios, consistent gauge control, and material reduction without sacrificing load containment or puncture resistance. Secure diversified resin sourcing to mitigate regional price volatility, and develop transparent compliance documentation that supports procurement teams navigating EPR and recycled content mandates. Differentiate through verifiable performance claims and application-specific solutions rather than volume-based pricing alone.
For investors and portfolio strategists: Evaluate exposure to producers with demonstrated capabilities in advanced extrusion, recycled content integration, and regional supply resilience. Favor companies that can articulate clear performance advantages, maintain formulation flexibility amid input cost fluctuations, and align product portfolios with regulatory trajectories. Monitor consolidation dynamics and niche differentiation opportunities, particularly in regions where logistics infrastructure is expanding and automated wrapping adoption is accelerating. Assess risk around recycled resin supply constraints, virgin resin price divergence, and regulatory enforcement variability.
For procurement leaders and logistics operators: Shift evaluation criteria from price per kilogram to total cost per wrapped pallet, incorporating film consumption, line efficiency, load rejection rates, and compliance readiness. Prioritize suppliers that provide consistent performance at high pre-stretch levels, maintain quality across recycled and virgin blends, and offer documentation that supports EPR and recycled content reporting. Engage early with formulation changes to ensure compatibility with existing wrapping equipment and load profiles, and consider supplier partnerships that provide feedstock transparency and supply stability amid market volatility.
The machine stretch film market is moving into a phase where technical precision, regulatory alignment, and supply chain resilience determine competitive outcomes. The companies that succeed will be those that treat performance, sustainability, and cost efficiency as interconnected objectives rather than competing priorities. For executives seeking granular segmentation data, regional pricing dynamics, competitor benchmarking, and customized strategic scenarios, the full research report provides the detailed framework needed to translate these market-wide insights into precise operational and investment decisions.
For detailed analysis of this topic, please visit the official page: Machine Stretch Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cold Milling Machine Market: 6.26% CAGR and the Strategic Shifts Reshaping 2026–2032 Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Cold Milling Machine Market
The global cold milling machine market has entered a phase of sustained expansion, driven by aging infrastructure, tightening environmental mandates, and a strategic shift toward high-efficiency pavement rehabilitation. Valued at approximately $215 million in 2025, the market has grown at a compound annual growth rate of 6.26 percent over the 2020 to 2025 period and is projected to reach $345 million by 2032. This trajectory reflects more than cyclical road maintenance spending; it signals a structural transformation in how contractors approach surface rehabilitation, material recycling, and emissions compliance. The next seven years will be defined by technological differentiation, regulatory alignment, and regional demand rebalancing.
Reconciliation of Physical Infrastructure Reality and Environmental Mandates
The market's underlying growth is rooted in a pragmatic reality: governments and private developers cannot afford to rebuild entire pavement networks from scratch. Instead, they rely on cold milling as a targeted, cost-effective method to remove deteriorated layers, prepare binding surfaces, and recover reusable aggregates. This operational logic has remained consistent, but the execution environment has changed dramatically. Contractors now face overlapping pressures: tighter municipal budgets, stricter noise and emission limits at urban job sites, and client expectations for project completion times that align with modern logistics windows. Machinery that simply removes asphalt or concrete is no longer sufficient. The winning equipment must integrate precise depth control, consistent output, and verifiable sustainability metrics while maintaining operational flexibility across multiple pavement types.
At the same time, the market confronts fragmentation in adoption readiness. Developed regions with mature road networks are prioritizing fine milling, surface rehabilitation, and emissions-reduced operations. Emerging markets are still scaling basic rehabilitation capacity, often balancing imported high-performance equipment against domestically manufactured alternatives. Navigating this divide requires a clear view of where regulatory pressure converts into procurement behavior, and where cost sensitivity still dictates purchasing decisions.
Key Drivers Shaping Market Dynamics
Technological Innovation and the Automation of Precision Milling
The most consequential shift in the market is the transition from mechanical power to controlled, data-enabled precision. Modern cold milling machines increasingly embed intelligent drum speed regulation, grade and slope tracking, and operator-assist systems that reduce variability in cut depth and material consistency. These capabilities directly affect downstream paving quality and the efficiency of material recycling. When a milling pass produces predictable particle size and uniform surface preparation, contractors spend less time on corrective work and more time maintaining throughput.
Recent product introductions illustrate this trajectory. Wirtgen Group's W 210 XF and W 250 XF models, unveiled in early 2025, emphasize high-output milling combined with advanced automation. The W 250 XF was presented as a high-capacity platform with dual-engine architecture and refined milling technology, targeting large-scale rehabilitation where output and consistency determine project economics. Alongside larger platforms, the same manufacturer introduced the W 50 Re battery-electric small milling machine and an updated generation of recyclers designed for lower specific emissions. This pairing of large-scale high-power machines with compact electrified alternatives reflects a broader industry recognition: different job profiles require different power and control architectures, and electrification is entering the market not as a single solution but as a modular option.
From a commercial standpoint, automation is not merely a feature upgrade. It is becoming a procurement criterion. Contractors evaluating bids increasingly weigh whether a machine can reduce operator fatigue, improve cut consistency across long runs, and provide feedback loops that support maintenance planning. Equipment that integrates these functions into a coherent workflow offers a practical advantage in labor-constrained environments and in projects where site access limits the margin for error.
Worldwide Milling Machine Market
Regulatory Pressure and Emissions Compliance as Procurement Catalysts
Environmental regulation has moved from a compliance backdrop to an active determinant of machine selection. European and global frameworks continue to tighten carbon emission expectations for construction equipment, with enforcement and reporting requirements making real-time emissions visibility more valuable. In this environment, cold milling machines that generate transparent performance data and meet advanced emission standards are better positioned for public tenders and large contractor fleets.
Recent regulatory-aligned developments demonstrate how manufacturers are responding. Wirtgen's latest large milling machines incorporate EU Stage 5 and US EPA Tier 4f emission standards alongside real-time CO2 tracking through performance monitoring systems. Caterpillar's PM Series cold planers are designed around Tier 4 Final and Stage V compliant engines to support sustainable construction and reduce operating cost exposure tied to emissions compliance. Rather than treating emissions as an abstract requirement, leading manufacturers are connecting compliance to operating economics: fuel efficiency, maintenance intervals, and fewer regulatory disruptions on urban or sensitive job sites.
This dynamic matters for strategic planning because it introduces a second layer of value beyond raw capacity. Machines that document emissions performance, reduce specific fuel consumption, and support fleet reporting are easier to justify in tender processes where environmental scoring is part of the evaluation. Over the forecast period, this trend is likely to widen the gap between equipment that meets minimum compliance and equipment that actively supports sustainability reporting and cost control.
Demand-Side Shifts Toward Rehabilitation, Recycling, and Lifecycle Thinking
Demand is increasingly shaped by a lifecycle view of pavement assets rather than a replacement mindset. Municipalities, roadway authorities, and large contractors are focusing on rehabilitation strategies that extend service life, recover aggregates, and reduce the need for virgin material inputs. Cold milling sits at the center of this shift because it enables precise removal of distressed layers and produces milled material that can be reintroduced into recycling streams or base layers.
This demand evolution changes how buyers evaluate machines. Output capacity remains important, but it must be balanced against the ability to handle different materials, switch between coarse and fine milling tasks, and support downstream recycling workflows. Contractors operating in regions with high volumes of asphalt rehabilitation are prioritizing consistent milling quality and rapid setup changes, while concrete rehabilitation users need equipment that manages more abrasive surfaces and maintains drum performance over extended usage. The practical implication is that demand is fragmenting by application logic even as overall market volume rises.
A second demand-side pressure is job-site logistics. Urban rehabilitation projects increasingly require equipment that can operate within constrained access windows, minimize noise impact, and adapt to tighter footprints. This favors machines that combine maneuverability with reliable output and that can integrate into coordinated paving and recycling operations without becoming a bottleneck. In practical terms, the strongest commercial opportunities are emerging where cold milling equipment is sold not as a standalone tool but as part of an integrated rehabilitation process.
Supply Chain Realities and Cost Structure Reframing
Equipment economics are also being reshaped by supply chain considerations and operating cost structures. Engine availability, component sourcing, and the cost of maintaining compliance with evolving emission systems all influence total cost of ownership. High-horsepower platforms, in particular, depend on reliable engine supply and service networks that can support advanced exhaust aftertreatment and diagnostic systems. Any disruption in these areas affects uptime and can alter the attractiveness of certain machine architectures.
At the same time, fuel efficiency has become a direct commercial lever rather than a secondary benefit. Advanced drum speed control and optimized transmission systems can deliver measurable fuel savings, which matters in markets where operating costs are under scrutiny and where contractors run machines for long shifts. Fuel consumption is no longer just an engineering metric; it is a tender differentiator and a fleet budgeting variable. In that sense, cost structure is moving from a static procurement concern to a dynamic performance target.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players holding approximately 24.6 percent of the market and the top five reaching around 26.2 percent. This level of concentration suggests that scale, brand recognition, and technology leadership are rewarded, but it also leaves meaningful room for differentiated regional participants, application specialists, and new entrants targeting specific job profiles or price-performance segments. Competition is increasingly defined less by raw size and more by the ability to deliver compliant, efficient, and operationally intelligent machines that match local demand patterns.
Wirtgen Group stands out for portfolio breadth and technology integration. Its lineup spans compact models to large platforms, with recent additions emphasizing automation, mill assist controls, and performance tracking for milling operations. The company's 2025 introductions, including the W 210 XF and W 250 XF, reinforce a high-performance large-machine strategy while its battery-electric small milling machine and updated recycler generation indicate a parallel push toward lower specific emissions and electrified compact equipment. The strategic signal is clear: the company is positioning across multiple power and scale points, using automation and emissions visibility as differentiators.
Caterpillar contributes a different kind of strength: large-engine reliability, emissions compliance, and telematics integration. Its PM Series half-lane cold planers, including models such as PM825 and PM620, are built around high-horsepower engines and Tier 4 Final compliance, with telematics support aimed at fleet management and operational efficiency. Caterpillar's positioning benefits from its broader construction equipment ecosystem, where service networks, parts logistics, and machine data integration can extend value beyond the cold planer itself. For contractors managing multiple asset types, that ecosystem appeal can be decisive.
Regional and application-focused players continue to shape competitive dynamics in specialized ways. Bomag, Dynapac, Volvo Construction Equipment, Sakai, Roadtec, and CMI Roadbuilding each maintain cold milling offerings aligned with particular operating profiles or regional expectations. Roadtec's RX Series cold planers, for example, were updated in early 2025 with higher-horsepower Caterpillar Tier 4 Final engines to target higher production and reliability. These participants often compete on feature-fit, service responsiveness, and application alignment rather than attempting to lead on sheer portfolio scale.
In Asia, SANY Group, XCMG Group, LiuGong, and Shantui represent a distinct competitive dynamic. Their SCM, XM, 5100-2/SM, and SM series machines demonstrate strong capability in road construction and infrastructure applications, with a focus on cost-effective high-performance equipment for local and export markets. The strategic implication is that competition is not only about premium features; it is also about whether manufacturers can balance compliance, durability, and price in ways that match the procurement realities of fast-growing infrastructure regions.
Several competitive trends are emerging. First, there is a clear convergence around compliance-driven engineering, with manufacturers treating emission standards and fuel efficiency as baseline expectations rather than optional enhancements. Second, product launches are increasingly paired with digital value propositions, whether through performance tracking, telematics, or operator-assist features. Third, the market is not consolidating into a single winner-takes-most pattern; instead, it is fragmenting by application, power architecture, and region. That means competitive advantage will depend on matching machine characteristics to specific procurement priorities, not simply on offering the largest or most expensive platform.
Future Trends and Commercial Implications
Electrification and Alternative Powertrains Will Expand by Job Profile
Electric and low-emission configurations are entering the market in targeted forms rather than as blanket replacements. Compact milling tasks, urban rehabilitation, and environments with strict site emissions limits are likely to be the earliest adoption zones. Over the next three to five years, expect battery-electric and hybrid-enabled machines to broaden where site constraints, noise restrictions, or localized sustainability requirements make conventional diesel operation less attractive. Commercial opportunity lies not just in selling an alternative powertrain but in defining the applications where it delivers a credible cost and operational case. Manufacturers and distributors that understand which job profiles justify electrified equipment, and how to support charging, deployment, and maintenance, will be better positioned to shape demand rather than react to it.
Cold Planers Market
Automation and Data Feedback Will Become Table Stakes for High-Value Tenders
Real-time milling control, grade support, and performance data capture are moving from premium differentiators to expected features in competitive procurement. As tender evaluation increasingly includes operating efficiency, emissions documentation, and process consistency, machines without meaningful data capabilities risk losing relevance in higher-value contracts. The commercial implication is that equipment value may shift from purchase price toward lifecycle performance and reporting utility. This favors manufacturers and service providers that can package machine performance with fleet diagnostics, maintenance insight, and verifiable operating metrics. It also creates an opening for service-led revenue models, where monitoring, diagnostics, and process optimization become part of the customer relationship.
Regional Demand Divergence Will Deepen Selection Logic
Market growth will not unfold uniformly. Regions with strict emission environments, mature rehabilitation practices, and dense urban projects will favor automated, compliant, and often electrified solutions. Regions focused on capacity expansion and cost efficiency will still reward durable, high-output machines that deliver reliable performance at a competitive total cost of ownership. This divergence means that successful commercial strategies will require regional calibration: product mix, service coverage, financing support, and application messaging all need to align with local procurement priorities. Companies that attempt a single global narrative across all markets will likely leave value on the table.
These trends carry uncertainty. Emissions frameworks may accelerate or shift implementation timelines. Electrification may progress faster in some geographies while remaining limited in others due to infrastructure and cost constraints. Fuel price volatility, component supply conditions, and changes in public infrastructure spending can all reshape the pace of adoption. Commercial planning should therefore treat these trends as directional indicators rather than fixed predictions, and build flexibility into product, service, and market-entry decisions.
Strategic Actions for Decision Makers
For manufacturers and equipment suppliers, the priority is to align product architecture with the real purchasing drivers of the next cycle. That means maintaining a credible path on emissions compliance, treating automation and data capture as core value elements instead of accessories, and explicitly mapping which machine sizes, power options, and features fit which applications and regions. Pricing and service strategies should reflect total cost of ownership, not only upfront specifications. Where feasible, offering bundled diagnostics, maintenance planning support, and emissions reporting capabilities can strengthen customer retention and differentiate offers in competitive bids.
PW Consulting Automotive & Machinery Research Center
For investors and strategic partners, the opportunity is to focus on the segments where regulatory pressure, rehabilitation demand, and technology adoption intersect most strongly. Equipment that combines compliance, fuel efficiency, and operational data is likely to command stronger positioning in tenders and fleet renewals. Vertical relevance matters as much as product specifications: distribution strength, service coverage, parts logistics, and the ability to support electrified or digitally integrated machines are becoming part of the investment thesis. Monitoring the pace of electrification adoption, the stability of emission compliance requirements, and regional procurement behavior will help identify where demand is real and where it is still aspirational.
For procurement leaders and contractors, the practical goal is to evaluate cold milling equipment against operational context rather than headline capacity alone. Project selection should consider cut precision, material recovery needs, site-access constraints, emissions documentation requirements, and the cost implications of fuel efficiency and maintenance intervals. When renewing fleets or entering multi-year rehabilitation programs, buyers benefit from specifying performance expectations that include consistency, reporting, and service support, not just milling width or engine power. Choosing equipment that fits the workflow reduces rework, improves scheduling predictability, and strengthens the business case for rehabilitation-focused projects.
In a market where specifications, compliance, and application fit increasingly determine winning offers, broad market awareness is useful but not enough. Detailed segmentation data, regional procurement patterns, competitive benchmarking, and product-level performance comparisons are what translate strategic direction into practical decisions. For that level of segmentation and actionable recommendation, interested parties can review the complete report.
For detailed analysis of this topic, please visit the official page: Cold Milling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com