

Blogs
LIDAR Market 2026: The 20.32% CAGR Surge and Strategic Shifts Redefining Global Competition
By PW Consulting, 2026-09-21
The Lidar Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
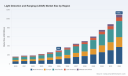
The Light Detection and Ranging market has moved well beyond its experimental phase. From a base of 299.0 million USD in 2025, the sector is projected to reach 1088.2 million USD by 2032, expanding at a compound annual growth rate of 20.32 percent. The trajectory from 2020 through 2025 tells a story of accelerating adoption rather than linear growth. Revenue climbed from 162.3 million USD in 2020 to 219.56 million USD in 2023, then accelerated sharply to 257.35 million USD in 2024 before crossing the 300 million threshold in 2025. That step-change in velocity matters. It signals that lidar is graduating from niche deployments into mainstream integration across mobility, infrastructure, and environmental monitoring.
What makes this growth cycle different from prior technology adoption curves is the breadth of pull. Automotive programs are scaling from prototype fleets to production intent. Mapping and smart infrastructure initiatives are institutionalizing three-dimensional elevation data as a public utility. Defense and industrial applications are demanding higher reliability under constrained form factors. Yet the market is not simply riding a single wave. It is navigating a set of structural tensions that will separate durable operators from those chasing short-term hype.
Wind Lidar Market
For executives evaluating their posture in this space, the question is no longer whether lidar matters. It is how to position for a market that is simultaneously fragmenting by application, consolidating by capability, and being reshaped by policy and supply constraints. The following analysis maps the forces at work, the competitive logics emerging among leading firms, and the strategic moves that will determine who captures value over the next three to five years.
Market Reality and the Core Tensions Defining the Next Phase
From Proof-of-Concept to Production Pressure
The market has cleared the proof-of-concept hurdle. The rapid expansion between 2023 and 2025 reflects programs moving from validation to pilot and early production. That transition is unforgiving. Sensors that work in controlled demonstrations must now survive automotive-grade thermal cycles, vibration profiles, and cost targets that leave little margin for optical complexity or software rework. The same pressure applies to smart infrastructure and environmental monitoring, where instruments must operate continuously across seasons and integrate with legacy data pipelines. The market’s growth is therefore not a simple function of demand; it is a function of how quickly suppliers can convert capability into manufacturable, serviceable, and cost-defensible products.
Operationalizing production at scale introduces a different set of constraints than developing a working sensor. Yield consistency, thermal management, calibration throughput, and software validation all become revenue gates. Companies that treat these as engineering afterthoughts find their growth throttled by quality escapes and program delays. Those that design manufacturability into the architecture early can convert market momentum into booked revenue and, eventually, operating leverage.
The Supply Chain Bottleneck as a Strategic Variable
Hardware scarcity is not a transient procurement issue; it is a structural filter. Shortages of semiconductors, optical lenses, and high-precision MEMS chips have emerged as the primary bottleneck limiting lidar production scale-up. This constraint reshapes commercial logic in several ways. First, it elevates the value of vertical integration and supplier relationships that can guarantee allocation. Second, it forces design teams to make trade-offs between performance, bill-of-materials cost, and component availability that no single engineering discipline can resolve in isolation. Third, it rewards firms that can offer modular architectures, allowing customers to adapt to component substitutions without redesigning entire perception stacks.
The implication for operators is that supply resilience is a competitive capability, not a back-office function. Companies that treat component strategy as a first-class design input can maintain program continuity when others face allocation risk. They can also shape customer conversations around total cost of deployment rather than headline sensor price, which is where durable differentiation often lives.
Regulatory and Standards Divergence as a Market Shape
Policy and standardization activity is no longer a peripheral concern. In December 2025, the SAFE LiDAR Act was introduced in the 119th Congress to restrict the use of foreign adversary lidar in the United States. That legislative direction introduces a geopolitical filter into procurement decisions that previously focused on performance and cost alone. At the same time, regulatory clarity is uneven. A Federal Register notice issued on January 16, 2025 reaffirmed that lidar hardware is excluded from supply-chain review under the Connected Vehicles framework. The coexistence of targeted restrictions and carve-outs creates a compliance environment where buyers must navigate sector-specific rules, origin requirements, and validation expectations that vary by application and geography.
Standards work is compounding this complexity. Hesai is co-leading the Automotive LiDAR Working Group at the International Standards Organization, developing test methods for lidar performance and safety. The latest Lidar Base Specification, LBS 2025 rev. A, was released by the U.S. Geological Survey in June 2025 for the 3D Elevation Program. These developments point to a market where interoperability, testability, and data formatting are becoming gateways to adoption, particularly in government and infrastructure programs. Suppliers that help their customers satisfy these expectations gain a defensible path to recurring engagement.
PW Consulting Information & Electronics Research Center
Key Drivers Shaping the Lidar Market Trajectory
Technology Innovation as a Rewriting of the Form-Factor Equation
The most consequential engineering shift in the market is the re-architecture of lidar around smaller, more integrated, and software-defined systems. Solid-state approaches are gaining share relative to mechanical designs because they reduce moving parts, improve robustness, and simplify packaging. The split between mechanical and solid-state revenue in 2025 reflects this migration, with solid-state reaching meaningful scale while mechanical platforms maintain a substantial base in applications that still value mature scanning patterns and high dynamic range. The strategic point is not that one architecture wins universally. It is that customers are increasingly selecting platforms based on fit-for-purpose trade-offs among range, resolution, module thickness, and serviceability.
Product introductions in early 2026 illustrate how these trade-offs are being translated into commercial solutions. Hesai introduced the ET25 ultra-thin sensor at 25 millimeters thickness for behind-windshield mounting, alongside the PandarXT 32-channel mid-range lidar with zero minimum range and self-developed ASICs. The behind-windshield form factor matters because it lowers integration friction for automotive programs that want lidar without external housings or prominent bump placements. The zero minimum range and custom silicon point to a broader industry move toward tailored silicon that can optimize power, latency, and cost for specific use cases rather than relying on general-purpose components.
For manufacturers and integrators, the opportunity is to align platform selection with deployment realities rather than laboratory benchmarks. A sensor that excels in open-road long-range detection may be structurally awkward for compact urban vehicles, robotics, or retrofit infrastructure. A sensor optimized for short-to-mid range perception may unlock new placement options and cost envelopes. The winners will be those who can articulate where each architecture adds the most value and how to scale the corresponding supply chain.
Policy, Procurement, and the Rise of Institutional Demand
Government and institutional procurement is becoming a powerful demand engine, and it operates under rules that differ from consumer or commercial automotive buying. The U.S. Geological Survey’s FY25 3DEP Data Collaboration Announcement selected projects including newly acquired QL1 lidar for Palm Beach County to support a new 3DHP pilot project. The relevance extends beyond one county. It reflects a broader institutional embrace of high-quality elevation data as a foundation for planning, resilience, and digital twin infrastructure. When public agencies standardize on lidar-based data collection and release specifications such as LBS 2025 rev. A, they create repeatable procurement patterns that suppliers can design for.
Standards and conferences are reinforcing this institutional pull. The 5th edition of the European Lidar Conference was held in September 2025 in Warsaw, Poland, bringing together research, application, and supplier communities in a forum that accelerates the transfer of methods and expectations across sectors. Conferences of this kind matter commercially because they influence procurement norms, test expectations, and cross-industry best practices. They also create pathways for suppliers to demonstrate capability to informed buyers who increasingly compare offerings across domains.
For firms targeting public-sector and infrastructure work, the strategic task is to treat compliance and data interoperability as product attributes, not paperwork. Certification traceability, metadata discipline, and alignment with agency specifications can shorten sales cycles and reduce integration risk. In markets where procurement rules and data standards are hardening, the suppliers who build for those requirements first gain a structural advantage.
Demand-Side Behavior and the Shift to Scalable Perception
Demand is changing not only in volume but in shape. Automotive and ADAS applications remain the largest application segment in 2025, and the growth trend indicates that perception is moving from safety augmentation toward higher levels of automation where lidar complements camera and radar stacks. At the same time, demand is broadening across robotics, smart cities, industrial automation, and defense. This diversification matters because it changes what customers care about. An automotive program may prioritize long-range performance, safety validation, and cost per unit at volume. A robotics or smart-infrastructure program may prioritize compact volume, continuous operation, digital integration, and total cost of ownership across a deployed network.
MicroVision’s launch of its Global Partner and Reseller Program in April 2026 is a practical example of how suppliers are responding to distributed demand. Rather than relying solely on direct sales, the company is building channels to accelerate adoption of scalable lidar and perception technologies across industrial, defense, and real-world applications. This model reflects a market where reach and application expertise matter as much as sensor capability. Customers often buy through ecosystems that understand their specific operating conditions, and suppliers that enable those ecosystems can expand faster than those that try to cover every segment directly.
The commercial lesson is that lidar value is increasingly realized at the system and deployment level, not just at the component level. Suppliers that can package sensors with perception software, integration support, and channel expertise are better positioned to capture the economics of scale than those selling hardware in isolation.
Cost Structure and the Logic of Targeted Integration
Cost reduction is happening, but not through brute-force commoditization. Lidar pricing is being reshaped by a combination of architectural simplification, custom silicon, and selective integration. Self-developed ASICs, for example, can reduce dependency on generic components and improve performance-per-watt, but they also concentrate design risk and require volume commitment to justify the investment. Behind-windshield mounting and thin form factors reduce vehicle integration cost and design complexity, which can make lidar more palatable for mid-tier programs that would otherwise defer adoption.
The deeper strategic insight is that cost advantage in lidar is increasingly a function of integration intelligence. Customers do not just buy a sensor; they buy a path to a working perception system. The less friction there is in mounting, calibration, software integration, and supply continuity, the lower the effective cost of adoption. Suppliers that reduce these frictions can command more stable demand and better lifecycle economics, even if their headline hardware price is not the lowest in the market.
Competitive Landscape and the Emerging Strategies of Leaders
Positioning Through Form Factor, Range, and Application Fit
The competitive field is characterized by differentiated bets rather than a single race to the top. Hesai Technology, based in Shanghai, is emphasizing solid-state automotive lidar sensors with high-volume production and 3D perception solutions for autonomous mobility and robotics. Its recent manufacturing expansion in Thailand, expected to come online later in 2026 to supply sensors to non-Chinese companies, signals an intent to broaden geographic reach and serve customers outside China directly. This move reflects a strategic logic of diversifying supply footprint while maintaining scale economics in production.
Luminar Technologies, headquartered in Orlando, is focused on long-range pulsed lidar sensors and perception systems for Level 3+ autonomous vehicles and ADAS. Its differentiation is anchored in range and perception depth for higher automation levels, where detecting objects at distance and characterizing them reliably are central value propositions. The strategic implication is that Luminar is playing in a segment where performance credibility and validation rigor matter more than module thickness or price alone. Its customers are likely to be programs where safety case and long-range perception are non-negotiable.
Ouster, based in San Francisco, is building around digital lidar sensors optimized for scalability in autonomous vehicles, robotics, and smart infrastructure. Its emphasis on scalability suggests a platform mindset: design a digital architecture that can be adapted across form factors and applications with minimal rework. That approach is attractive in markets where demand is fragmented and customers want a common technology base that can be configured rather than entirely custom-built.
Worldwide 3D Scanning Wind Lidar Market
Innoviz Technologies, in Rosh Ha’ayin, is concentrating on automotive-grade lidar platforms with high-resolution 3D perception for consumer vehicles and commercial applications. Its positioning targets the intersection of consumer-facing vehicle programs and commercial deployments, where resolution and automotive qualification must coexist with cost discipline. LeddarTech, in Québec, is pursuing a complementary path through solid-state lidar sensors and LeddarVision software for ADAS and autonomous driving perception, emphasizing the software layer that turns raw detections into usable driving decisions. The strategic point is that competition is not only about the hardware envelope; it is also about who can deliver a usable perception pipeline that customers can integrate with confidence.
MicroVision, in Redmond, is advancing MEMS-based lidar 2.0 sensors and perception solutions for industrial, defense, and autonomous applications. Its MEMS foundation positions it for scenarios that demand compact volume, durability, and tailored performance across non-automotive domains. Cepton Technologies, in San Jose, is leaning into lidar-based solutions for automotive ADAS, smart cities, and industrial automation, which suggests a multi-domain strategy that leverages common optical and processing building blocks across sectors.
How the Market Is Evolving: Consolidation Pressure Meets Application Fragmentation
The market structure is best understood as simultaneous consolidation and fragmentation. On the consolidation side, three-firm concentration stands at 35.0 percent and five-firm concentration at 52.0 percent, indicating that a meaningful share of revenue is already concentrated among a set of scaled players. As programs move to production and compliance requirements tighten, there is natural pressure toward fewer, more capable suppliers that can meet automotive-grade, government, or infrastructure expectations. Consolidation is also driven by the cost of maintaining multiple qualified architectures, test suites, and supply relationships.
At the same time, application fragmentation is intensifying. Automotive and ADAS demand is distinct from aerospace and defense, which is distinct from smart infrastructure and mapping, which is distinct from environment and forestry. Each segment has its own performance priorities, procurement rhythms, and validation regimes. This fragmentation creates room for specialized players and channel models, but it also raises the bar for suppliers that must support multiple domains without diluting focus. The most resilient strategies are those that combine a coherent core technology with the ability to configure it for different application requirements.
New entrants will continue to appear, particularly around niche form factors, custom silicon, and vertical software. However, the practical hurdle is not just technical differentiation. It is the ability to survive the transition from excellent prototype to repeatable production while managing component scarcity, qualification cycles, and geography-specific policy constraints. Entrants that underestimate the operational weight of scaling tend to stall after initial interest. Entrants that plan for manufacturability, compliance, and channel reach from the start have a realistic path to carve out defensible positions.
Forward Trends and the Commercial Opportunities They Create
Trend One: Standardization and Compliance Will Become Purchase Criteria
Over the next three to five years, lidar purchasing will increasingly be shaped by testability, safety validation, data formatting, and geopolitical compliance. The SAFE LiDAR Act trajectory, ongoing ISO working group activity, and USGS data specifications all point toward an environment where buyers compare offerings not only on performance but on traceability and conformity. Suppliers that can document test methods, align with recognized specifications, and simplify compliance for customers will reduce friction in the sales process and gain preference in regulated programs.
The commercial opportunity here is to treat standards readiness as a product capability. Firms that publish clear performance methodologies, support agency data specifications, and offer origin and sourcing clarity can differentiate in segments where procurement teams are under pressure to demonstrate due diligence. This is especially relevant for infrastructure, mapping, and government-adjacent applications, where data quality and program continuity are valued alongside sensor specifications.
Trend Two: Scale Will Favor Modular, Software-Enabled Architectures
The next growth phase will reward architectures that scale across applications without requiring full redesign. Modular sensor platforms, configurable channel counts, and perception software that can be tuned to different operating conditions will be more valuable than highly specialized one-off designs. This is because demand is spreading across automotive, robotics, smart infrastructure, and defense, and customers in each segment want a credible base platform that can be adapted efficiently.
For suppliers, the opportunity is to build a technology core that can be reused while differentiating through integration, software, and channel support. For customers, the opportunity is to select platforms that reduce long-term integration risk and enable incremental expansion. The strategic risk is over-customization: tailoring too narrowly to a single program or geography can leave suppliers exposed if that program slips, the policy environment changes, or component allocations shift.
Trend Three: Geographic Realignment and Supply Footprint Strategy
Lidar is likely to become more geographically deliberate. Buyers will increasingly weigh origin, local supply continuity, and regulatory exposure when selecting sources. Hesai’s Thailand manufacturing expansion to serve non-Chinese companies is an early signal that suppliers are building regionally balanced footprints to meet customer demands for proximity, allocation security, and compliance comfort. This does not mean every supplier must build everywhere. It does mean that footprint strategy will matter more explicitly in winning programs that span multiple markets.
The opportunity is for suppliers to design supply footprints that match the geography of their strongest demand and the expectations of their most demanding customers. The risk is to assume a single manufacturing base can satisfy all customers indefinitely, especially as policy and procurement preferences become more varied. Firms that can demonstrate credible regional options without fracturing their engineering core will have an advantage in multi-market deployments.
Strategic Moves for Decision-Makers
For Lidar and Component Manufacturers
Design for manufacturability and supply resilience as core capabilities, not secondary concerns. Treat custom silicon, modular architecture, and thermal and calibration throughput as revenue enablers. Build compliance and standards alignment into the product narrative early, especially if you intend to serve automotive, government, or infrastructure programs. Consider geographic supply options that reflect where your customers face the most procurement and continuity pressure, and ensure that any expansion does not dilute engineering focus.
For Investors
Evaluate companies on the basis of production readiness, channel strategy, and standards posture in addition to sensor performance. The market is moving toward repeatable deployment, which means yield, allocation, software integration, and compliance capability will increasingly determine who scales. Assess whether a company’s differentiation is durable across multiple applications or dependent on a single program narrative. Pay attention to the interplay between architectural bets and supply-chain exposure, because component scarcity and regulatory filters can change the economics of a strategy quickly.
For Procurement and Integration Leaders
Choose lidar platforms based on total deployment fit rather than peak performance in a narrow test. Prioritize architectures that match your mounting constraints, data formatting needs, and validation expectations, and that can be supported by credible channels or integration partners. For public-sector and infrastructure work, confirm alignment with current data specifications and procurement expectations before committing to a supplier relationship. For automotive and ADAS programs, weigh long-range perception requirements against integration complexity and cost trajectory, recognizing that the best sensor on a bench is not always the best sensor in a production vehicle.
A market growing at this pace will not leave much room for passive positioning. The firms and buyers that succeed will be those who treat lidar as a systems challenge, plan for manufacturability and compliance as first-class concerns, and select architectures that can adapt as applications and policies evolve. For decision-makers who need granular segmentation, supplier-by-supplier capability mapping, and scenario-based guidance tailored to a specific product plan or investment thesis, the full PW Consulting report provides the detailed breakdown and customized recommendations that underpin these strategic conclusions.
For detailed analysis of this topic, please visit the official page: Light Detection and Ranging (LIDAR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Diesel Particulate Filter Market: Navigating Growth, Regulation, and Technological Shifts Through 2032
Market Evolution: Scale, Trajectory, and Structural Pressures
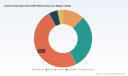
The global Diesel Particulate Filter market has undergone a period of measured expansion followed by a noticeable acceleration in recent years. From 2020 through 2025, revenue growth reflected the gradual integration of stricter emission standards, sustained commercial vehicle production, and steady aftermarket demand. The market crossed the twenty-billion-dollar threshold in 2025, establishing a new baseline for subsequent growth. Looking ahead through 2032, the sector is projected to expand at a compound annual growth rate of approximately 6.98 percent, with values climbing steadily each year as original equipment adoption and fleet compliance programs compound.
This trajectory is not merely a function of vehicle population growth. It represents a market responding to structural regulatory pressure, technological maturation, and shifting commercial operating models. Growth is increasingly distributed across mature compliance markets and emerging regions where emission control adoption is still catching up to established standards. The overall expansion reflects both incremental volume gains and unit price movements driven by more advanced substrate configurations, integrated thermal management systems, and software-enabled regeneration strategies.
Despite the positive outlook, the market faces several structural challenges that will shape competitive outcomes over the next several years. The first challenge lies in balancing emission performance with operational efficiency. Operators increasingly demand filters that maintain high particulate reduction without imposing excessive backpressure or fuel penalties during regeneration cycles. The second challenge stems from regulatory fragmentation. While certain jurisdictions have standardized verification and certification pathways, others maintain divergent testing protocols, sulfur limits, and retrofit approval processes. This creates uneven deployment timelines and complicates cross-regional supply strategies. The third challenge is material and manufacturing cost stability. Substrate selection, coating formulation, and thermal durability requirements continue to place pressure on production economics, particularly for smaller OEMs and aftermarket suppliers operating on tighter margins.
Engine Filter Market
Core Drivers Reshaping the Market Landscape
Several interconnected forces are accelerating change in the diesel emission control sector. Understanding how these drivers interact is essential for positioning products, sourcing strategies, and investment decisions.
Technological Innovation and Material Performance
Material science remains one of the most decisive differentiators in filter performance. Silicon carbide substrates, for example, provide higher filtration efficiency and superior thermal stability at elevated operating temperatures compared with traditional cordierite alternatives. This advantage translates into more consistent particle number reduction at lower backpressure, which is increasingly valued in applications where engine efficiency and regeneration reliability matter most. At the same time, catalyst formulations and coating technologies continue to evolve, enabling better soot oxidation, reduced dosing requirements, and more robust performance under varied duty cycles.
The significance of this innovation layer extends beyond peak performance metrics. Better substrate and catalyst combinations reduce the frequency of active regeneration events, improve cold-start behavior, and help systems remain within compliance thresholds across a wider range of operating conditions. As a result, OEMs and fleet operators are increasingly willing to pay a premium for solutions that lower total cost of ownership rather than focusing solely on upfront hardware cost.
Policy and Regulatory Momentum
Regulatory frameworks continue to act as the primary catalyst for market demand. Verified diesel particulate filter systems are being updated and reaffirmed in multiple jurisdictions, with certification programs regularly incorporating new retrofit and OEM configurations. In the United States, verification guidelines have reinforced requirements for ultra-low-sulfur diesel use and confirmed particulate reduction thresholds that systems must meet to remain approved for non-road and heavy-duty applications. These standards do more than constrain emissions; they shape procurement eligibility, fleet compliance roadmaps, and aftermarket replacement cycles.
In parallel, regional certification processes continue to govern which systems can be legally deployed in specific environments. California's verification and executive order processes, for instance, illustrate how marine and off-road applications must meet distinct certification expectations even within the same broader regulatory ecosystem. This layered approval landscape encourages manufacturers to design products that can satisfy multiple verification pathways while still providing application-specific tuning for thermal load, exhaust flow, and particulate loading profiles.
Demand-Side Shifts in Commercial and Off-Highway Segments
Demand patterns are shifting not only by geography but also by usage profile. Passenger vehicles and light commercial vehicles remain significant contributors to volume, but heavy-duty trucks and off-highway equipment are increasingly central to compliance-driven demand. Operators in logistics, construction, mining, and municipal services face mounting pressure to maintain older assets while meeting evolving emission expectations. That dynamic sustains retrofit and replacement demand even in markets where new vehicle sales fluctuate.
Fleet managers are also becoming more sophisticated buyers. Rather than treating emission control hardware as a standalone compliance purchase, they are evaluating how filters interact with engine calibration, fuel quality, maintenance intervals, and downtime risk. This shift benefits suppliers that can offer integrated system advice, service support, and performance guarantees rather than purely transactional hardware sales.
Supply Chain and Cost Structure Dynamics
The production economics of diesel particulate filters are influenced by raw material availability, substrate pricing, coating complexity, and manufacturing scale. As performance expectations rise, the cost gap between lower-efficiency and higher-efficiency substrate options becomes more consequential. Manufacturers must balance the performance advantages of advanced materials with the need to remain competitive in price-sensitive segments.
Supply chain resilience has also become a strategic consideration. Filters depend on specialized ceramic materials, precious metal components, and precision manufacturing processes. Disruptions in any of these layers can affect lead times and unit costs. Companies that diversify sourcing, secure long-term material agreements, and invest in process optimization are better positioned to protect margins during periods of volatility.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The diesel particulate filter market features a broad set of global and regional players, each anchored in different strengths across materials, catalytic chemistry, system integration, and application expertise. While no single company dominates the field outright, competitive advantage increasingly stems from how well manufacturers combine substrate performance, catalyst formulation, thermal management, and service capability.
Industrial and chemical specialists have strengthened their position by investing in catalyst research infrastructure and process technology. Recent moves such as the inauguration of a catalyst development and solids processing center reflect a continued focus on R&D capacity for emission control systems. These investments matter because they shorten the cycle from material experimentation to production-ready formulations, enabling faster response to evolving regulatory specifications and customer performance requests.
Materials and components leaders bring deep expertise in ceramic substrates and advanced filtration media. Their advantage lies in balancing filtration efficiency, thermal durability, and mechanical strength, particularly in demanding heavy-duty and off-highway environments. Companies with strong substrate capability can offer more consistent performance across a wider temperature and duty-cycle range, which supports both OEM integration and aftermarket replacement strategies.
System integrators and emission control specialists occupy another critical niche. Their value proposition often centers on combining filtration hardware with regeneration strategies, monitoring approaches, and application-specific tuning. By offering complete system perspectives, these players can address fleet compliance goals more comprehensively, particularly where retrofit certification and operational reliability must be proven simultaneously.
Automotive and thermal management suppliers contribute expertise in packaging, airflow control, and integration with broader vehicle or engine architectures. Their ability to fit emission systems into constrained spaces while maintaining heat management and regeneration reliability is especially important for light commercial and passenger vehicle applications. In parallel, catalyst and chemical suppliers play a supporting but vital role by enabling lower dosing, improved oxidation behavior, and longer service life through advanced additive and coating technologies.
The competitive landscape is evolving along several directions. Consolidation remains relevant where scale advantages in R&D, manufacturing, and certification create barriers for smaller players. At the same time, differentiation is intensifying through application specialization, with suppliers tailoring offerings for marine, off-road, heavy-duty, and urban fleet environments. New entrants and niche specialists continue to appear where they can address regional certification needs, retrofit compatibility, or specialized duty cycles that broader portfolios may not serve optimally. The result is a market that rewards both scale and specificity, depending on the segment and geography in question.
PW Consulting
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next phase of market development will likely be defined by the interaction between regulatory enforcement, material performance, and commercial operating priorities. Three trends stand out as particularly influential.
Higher Performance Baselines Become the Norm
As verification standards remain stringent and operators become more familiar with emission control performance expectations, the acceptable baseline for filtration efficiency and thermal durability will continue to rise. Systems that merely meet minimum compliance thresholds will face growing pressure from solutions that reduce backpressure, improve regeneration stability, and extend service intervals. This trend creates opportunities for suppliers that can consistently deliver advanced substrate and catalyst combinations without sacrificing manufacturability or cost control.
The commercial opportunity here lies in moving the conversation from compliance to performance optimization. Suppliers that can quantify fuel impact, downtime reduction, and maintenance savings will be better positioned to capture premium demand in heavy-duty and off-highway applications where operational continuity is critical.
Retrofit and Aftermarket Demand Stays Resilient
Even as new vehicle emissions technologies advance, large installed bases of older diesel equipment will continue to require compliant retrofits and component replacements. Verification updates for active DPF retrofit systems in non-road and heavy-duty applications confirm that retrofit pathways remain relevant, particularly where fleets aim to extend asset life while maintaining operational eligibility. This creates a durable aftermarket demand stream that is less dependent on new vehicle production cycles.
For manufacturers and service providers, this trend suggests value in building retrofit-ready designs, clear verification alignment, and support models that simplify installation and compliance documentation. The opportunity is not only in selling filters but in helping operators navigate certification requirements and maintain performance over time.
Worldwide DPF (Digital Photo Frame) Market
Regional Divergence Creates Both Complexity and Opportunity
Different regions will continue to move at different speeds in terms of enforcement, certification, and adoption maturity. Mature markets may see more incremental growth driven by replacement demand and higher-performance upgrades, while developing markets may experience stronger volume expansion as emission control adoption broadens. At the same time, cross-border fleet operations and globally sourced equipment create pressure for products that can satisfy multiple regulatory expectations without excessive customization.
This divergence opens the door for regionally tailored strategies. Suppliers that can combine global technology platforms with local certification knowledge, application tuning, and service support will gain an advantage in navigating the gap between global scale and local compliance. The risk, however, is that companies without sufficient regional coordination may face delays, rework, or limited market access when verification requirements diverge more sharply than anticipated.
Actionable Priorities for Decision Makers
Strategic choices in this market should be guided by the intersection of performance expectations, compliance pathways, and total cost of ownership. Different stakeholders will benefit from emphasizing different priorities.
For Manufacturers and System Suppliers
- Prioritize substrate and catalyst development that improves filtration efficiency and thermal stability while managing backpressure and regeneration frequency.
- Align product roadmaps with verification criteria across key jurisdictions to reduce rework and accelerate time to market for new applications.
- Strengthen aftermarket and retrofit support, including documentation, service training, and compatibility guidance, to capture demand from existing fleets.
- Evaluate manufacturing and sourcing strategies for resilience, especially around specialized materials and coating processes that can affect lead times and cost consistency.
For Investors
- Look for companies with credible R&D infrastructure and the ability to move material and catalyst innovations into production efficiently.
- Assess exposure to retrofit and aftermarket demand, which can provide revenue stability independent of new vehicle cycles.
- Consider suppliers that demonstrate application-specific expertise in heavy-duty, off-highway, or marine segments where performance requirements and certification complexity create stronger competitive moats.
- Monitor material cost dynamics and regional regulatory fragmentation as key variables that can influence margins and market access.
For Procurement and Fleet Decision Makers
- Evaluate DPF solutions based on total operating impact rather than sticker price, including regeneration behavior, backpressure, maintenance frequency, and downtime risk.
- Confirm verification status and fuel requirements early in the procurement process to avoid compliance gaps or unexpected operating constraints.
- Consider service and support capability as part of the purchasing decision, especially for fleets operating in demanding duty cycles or across multiple regulatory environments.
- Plan for lifecycle management, including regeneration strategy, filter replacement timing, and compatibility with existing engine calibration and fuel quality.
Closing Perspective
The diesel particulate filter market is entering a period where compliance, performance, and commercial reliability increasingly converge. Growth is expected to continue at a steady pace, but the more important question for decision makers is not simply how large the market will become. It is which suppliers, technologies, and operating strategies will capture the most valuable segments as performance expectations rise and regulatory pathways remain complex. Companies that invest in material and catalyst capability, align closely with verification requirements, and address the practical needs of fleets and operators will be best positioned to turn market expansion into durable competitive advantage. For organizations seeking deeper segmentation data, regional deployment patterns, company-level positioning, and customized go-to-market guidance, the full PW Consulting research report provides the detailed breakdown needed to support more precise strategic planning.
For detailed analysis of this topic, please visit the official page: Diesel Particulate Filter (DPF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Panel Meter Market: How 5.9% CAGR and $2.87B Growth Reshape Competition
By PW Consulting, 2026-09-21
Digital Panel Meter Market: Strategic Trends and Commercial Opportunities in an Era of Intelligent Instrumentation
The digital panel meter market has entered a phase of steady, value-driven expansion, transitioning from a commoditized component category into a strategic node within broader industrial automation and energy management ecosystems. Valued at approximately USD 1,550.0 million in 2020, the market grew to roughly USD 1,925.0 million by 2025, reflecting a compound annual growth rate of 5.9 percent across the 2020 to 2025 period. Forward projections indicate that revenue will reach USD 2,040.7 million in 2026, USD 2,189.85 million in 2027, and continue climbing to USD 2,865.0 million by 2032. This trajectory underscores a market that is no longer defined solely by incremental replacement cycles but by structural shifts in how industrial operators visualize, interpret, and act upon real-time process data.
Beneath these macro figures lies a competitive landscape characterized by moderate concentration. The top three players command roughly 31.5 percent of global revenue, while the top five account for approximately 42.6 percent. This distribution signals a fragmented middle tier where regional specialists, OEM-focused manufacturers, and emerging connectivity-driven entrants continue to compete on precision, integration ease, and total cost of ownership. The market is simultaneously consolidating around platform-oriented players while fragmenting in application-specific niches, creating a dynamic environment where strategic positioning matters as much as scale.
Several structural challenges and inflection points are reshaping how companies approach product roadmaps, pricing strategies, and channel partnerships. First, the convergence of panel metering with broader industrial control and cloud analytics is compressing the window for standalone hardware differentiation. Devices that once competed purely on accuracy or display clarity now must demonstrate seamless interoperability with supervisory systems, edge gateways, and data historians. Second, supply chain volatility and component cost fluctuations are forcing manufacturers to balance domestic production resilience with offshore cost efficiency, particularly as demand for calibrated, certified meters remains sensitive to lead times and quality consistency. Third, procurement cycles in process industries are increasingly tied to capital planning horizons that favor integrated solutions over discrete instrument purchases, shifting commercial competition from unit pricing to lifecycle value and deployment speed.
PW Consulting
Key Demand Drivers and Structural Shifts
The expansion of the digital panel meter market is being propelled by a combination of technological maturation, regulatory tightening, evolving operational expectations, and supply chain realignment. Each factor reinforces the others, creating compounding demand rather than isolated spikes.
Technology Innovation and the Connectivity Inflection
Instrumentation is shifting from localized readout devices to networked data endpoints. Recent product announcements illustrate this transition clearly. In August 2025, Fluke Corporation introduced a new series of digital panel meters emphasizing advanced connectivity features designed to improve user experience and data accessibility. Shortly afterward, in September 2025, Yokogawa Electric Corporation unveiled a cloud-based platform for real-time monitoring and data analysis of industrial applications, signaling a move toward continuous visibility rather than point-in-time measurement. By January 2026, Ditel expanded its portfolio with a Junior-D model featuring a six-digit display alongside an updated Micra M MAX line incorporating web server, Bluetooth, and MQTT capabilities. These developments are not isolated product refreshes; they reflect a broader industry pivot toward meters that can communicate natively with modern control architectures, support remote diagnostics, and reduce the friction of manual data collection.
For manufacturers, the implication is clear: accuracy and durability remain table stakes, but differentiation now hinges on protocol support, configuration flexibility, and integration with existing automation stacks. For end users, connected meters reduce downtime, simplify troubleshooting, and enable condition-based maintenance routines that were previously impractical with isolated displays.
Digital Pressure Gauges Market
Policy, Regulatory Pressure, and Energy Visibility
Regulatory and sustainability mandates are accelerating demand for precise, auditable measurement at the panel level. Energy efficiency reporting, emissions tracking, and operational compliance increasingly require granular visibility into voltage, current, temperature, and process variables. Digital panel meters that support standardized data output and reliable calibration are becoming essential components in facilities that must demonstrate continuous compliance rather than periodic snapshots.
At the same time, the push toward decarbonization and smart energy management is reshaping procurement priorities. Schneider Electric’s July 2025 strategic partnership with a leading renewable energy firm to develop smart energy management solutions incorporating digital panel meters illustrates how instrumentation is being embedded into broader energy optimization strategies. In this context, panel meters are no longer just monitoring devices; they are contributing elements in systems designed to balance load, improve efficiency, and support renewable integration.
Demand-Side Evolution in Industrial Operations
Operational expectations across manufacturing, process industries, and infrastructure are shifting toward real-time decision-making and reduced manual intervention. Plant operators increasingly expect instrumentation that can feed directly into control loops, alarm management, and analytics dashboards without extensive engineering overhead. This demand-side change favors meters that are easy to configure, support multiple input types, and can be maintained with minimal service disruption.
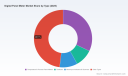
The application landscape reflects this broadening mandate. Voltage display remains the largest application segment, driven by electrical monitoring and power quality requirements. Current display continues to hold significant share, particularly in energy monitoring and motor control contexts. Temperature display maintains a dedicated role in process environments where thermal management directly affects quality and safety. A remaining portion of demand spans specialized monitoring scenarios that require multi-input handling, totalization, or custom indicator configurations. The overall pattern suggests that customers are not simply replacing legacy meters; they are upgrading measurement points to support data-driven operations and tighter process control.
Supply Chain and Cost Structure Realignment
Cost dynamics in the digital panel meter market are being reshaped by component availability, calibration requirements, and the economics of integrating communication modules. Manufacturers that rely on highly standardized internal architectures are better positioned to absorb fluctuations in sensor components, display elements, and connectivity chips. Conversely, designs that require extensive customization or proprietary interconnects face greater exposure to lead-time variability and cost escalation.
This environment is encouraging a dual strategy. Larger players are investing in modular platforms that can scale across multiple input types and communication options without redesigning core hardware. Smaller and regional manufacturers are focusing on compact, cost-effective OEM models that serve high-volume embedding scenarios where panel builders prioritize price consistency, form factor compatibility, and reliable delivery. The result is a market where scale advantages matter, but targeted application expertise and dependable supply can still secure strong positioning.
Competitive Landscape and Strategic Positioning
The competitive field spans established automation multinationals, specialized instrumentation suppliers, and regional manufacturers with strong OEM relationships. Several companies stand out for how they frame their value propositions and where they commit resources.
Established Automation and Process Players
Siemens continues to position digital panel meters within broader industrial automation and smart manufacturing platforms, emphasizing integration into control environments rather than standalone performance alone. ABB similarly focuses on high-precision meters for process and energy automation, aligning its instrumentation with industrial settings where reliability and compliance matter. Phoenix Contact reinforces a modular control systems narrative, supporting process automation through meters that fit naturally into flexible control architectures. Yokogawa ties its panel meter offerings to process instrumentation and cloud-based monitoring, extending the value proposition from measurement to analysis.
These players benefit from existing relationships with engineering teams, system integrators, and large industrial customers. Their strategic advantage lies in ecosystem compatibility, global service reach, and the ability to bundle meters into broader automation or energy management engagements. The trade-off is that their broader portfolios can sometimes prioritize platform coherence over niche cost optimization.
Specialized Instrumentation and Connectivity Leaders
Schneider Electric’s Harmony series and smart energy management orientation reflect a strategy centered on harmonizing instrumentation with energy efficiency goals and process control. Red Lion Controls emphasizes high-precision industrial panel meters for display and process instrumentation in automation and control applications, targeting users who need dependable measurement with straightforward integration. Precision Digital serves industrial and laboratory measurement contexts where accuracy and stable performance are paramount. Murata Power Solutions has focused on versatile digital panel meters for over forty years, offering DC and AC line-voltage monitoring models built around quartz crystal accuracy and self-powered operation, an approach that appeals to designers seeking reliability and simplified power requirements.
This group often competes by sharpening application specificity, reducing integration friction, and demonstrating measurable performance advantages in targeted environments. Their momentum depends on staying ahead of connectivity expectations while maintaining the precision and durability that industrial buyers require.
Digital Multimeter (DMM) Market
Regional, OEM, and Emerging Players
Autonics concentrates on compact, cost-effective OEM digital panel meters designed for industrial monitoring and measurement, an approach that aligns well with panel builders and equipment manufacturers seeking predictable pricing and standardized footprints. Guangzhou EcoNewlink Technology Co., Ltd. focuses on high-precision digital panel meters with global certification and automated OEM/ODM production for electrical panel builders, positioning itself as a scalable partner for customized volume supply. Omron Corporation maintains a steady presence in digital panel meters for industrial control and measurement applications, leveraging its broader automation and sensing ecosystem. Carlo Gavazzi targets energy and power monitoring digital panel meters with advanced connectivity, appealing to users who view measurement as part of energy management rather than isolated instrumentation.
These companies illustrate how regional strengths, certification capabilities, and OEM service models can create durable positions even in a moderately concentrated market. Their growth often depends on responsiveness, consistent quality, and the ability to support customers who need reliable meter supply without the complexity of large-platform procurement.
Recent Moves That Signal Strategic Direction
Recent activity underscores how companies are trying to shape the next phase of competition. Fluke’s August 2025 product launch emphasized connectivity and data accessibility, reinforcing a user-centric approach to measurement. Yokogawa’s September 2025 cloud platform release pointed toward continuous monitoring and remote analysis as a commercial differentiator. Schneider Electric’s July 2025 partnership with a renewable energy firm highlighted the growing link between panel instrumentation and smart energy strategies. Ditel’s January 2026 catalog expansion introduced both a compact six-digit model and an updated line with web server, Bluetooth, and MQTT support, showing how even focused manufacturers are adding communication and configuration flexibility to remain relevant.
Together, these moves suggest a market where product leadership is increasingly defined by data usability, integration readiness, and the ability to support both local display and remote insight.
Future Outlook: Three Trends Shaping the Next Three to Five Years
Looking ahead, the digital panel meter market is likely to be shaped by a small number of reinforcing trends. These trends will not only influence product development but also reshape commercial models, channel strategies, and purchasing criteria.
Trend One: From Display Devices to Data-Ready Measurement Nodes
Panel meters will increasingly be evaluated on how effectively they feed data into control, monitoring, and analytics workflows. Devices that support standard communication pathways, remote configuration, and consistent data formatting will gain preference in environments where engineering teams want to minimize integration effort. This trend creates opportunities for manufacturers that can offer modular connectivity, clear documentation, and predictable behavior across multiple input types. It also raises the stakes for suppliers whose devices require custom bridging or extensive manual setup to fit into modern automation environments.
The commercial opportunity lies in enabling faster deployment and lower total cost of ownership. Customers will reward solutions that reduce commissioning time, simplify troubleshooting, and support continuous visibility without demanding a full system overhaul. Companies that can package meters with practical integration guidance, compatible protocol support, and reliable firmware management will be better positioned to capture repeat business and expansion within existing accounts.
Trend Two: Energy Management and Compliance as Growth Multipliers
Energy visibility, efficiency reporting, and operational compliance will continue to expand the role of panel meters beyond traditional process display. As facilities invest in smarter energy management and more rigorous reporting, measurement points that support accurate voltage, current, and temperature monitoring become foundational. Partnerships and product strategies that link panel instrumentation to broader energy optimization initiatives are likely to gain traction, particularly in sectors where energy cost and sustainability performance directly affect operating margins.
This trend favors players that can articulate how panel meters contribute to energy outcomes, not just measurement accuracy. It also opens doors for integrated offerings that combine instrumentation with management software, analytics, or service models. The risk is that buyers may begin to expect these capabilities as standard, compressing margins for suppliers that treat connectivity and energy alignment as optional add-ons.
Trend Three: Modular Platforms and Targeted Nichches Co-Evolve
The market will likely continue along two parallel paths. Large platform players will extend modular architectures that can serve multiple applications with shared core designs, reducing time to market and improving consistency. At the same time, regional and OEM-focused manufacturers will deepen their positions in high-volume embedding scenarios and niche applications where cost predictability, form factor consistency, and certification support are decisive. This co-evolution creates a market where scale and specialization both matter, and where competitive advantage can come from either broad platform relevance or deep application fit.
For entrants and incumbents alike, the implication is that product strategy should be deliberately aligned with a chosen lane. Attempting to compete broadly without clear differentiation in integration, cost, or application expertise will become harder as buyers grow more sophisticated and comparison easier. The more sustainable path is to define a specific customer problem, deliver measurable advantage against that problem, and build repeatable channels around it.
Strategic Implications and Decision-Maker Priorities
The next phase of growth in the digital panel meter market will be captured by organizations that treat instrumentation as part of a broader data and operational strategy rather than as a discrete hardware purchase. The following priorities are especially relevant across different roles.
For Manufacturers and Product Leaders
- Prioritize connectivity and configuration flexibility as core design objectives, not afterthoughts. Protocols, remote diagnostics, and user-friendly setup are increasingly part of the purchase decision.
- Reduce integration friction by aligning product behavior with common control and data environments. Clear documentation, stable firmware practices, and predictable input handling can be as important as headline accuracy.
- Clarify the target lane. Decide whether the strategy emphasizes platform breadth, OEM volume supply, application-specific precision, or energy-focused monitoring, and shape pricing, certification, and channel support accordingly.
For Investors and Corporate Development Teams
- Evaluate exposure to data-ready instrumentation and energy management alignment as indicators of durable demand. Companies that can link panel meters to broader monitoring, analytics, or service models may command stronger retention and expansion potential.
- Assess supply chain resilience and certification readiness as part of due diligence. Stable quality, predictable lead times, and global certification capability increasingly influence large-scale selection decisions.
- Watch for consolidation in the middle tier, where regional and OEM-focused players may become attractive acquisition targets for firms seeking faster access to specific applications, geographies, or cost-efficient production.
For Procurement and Engineering Decision-Makers
- Evaluate total cost of ownership rather than unit price alone. Consider commissioning effort, maintenance burden, integration compatibility, and the ability to support future monitoring or analytics needs.
- Verify that chosen meters can fit into existing automation and data workflows without excessive custom bridging. Compatibility with current control architectures and standard data pathways reduces long-term operational risk.
- Require consistent calibration, certification, and documentation support. Reliable measurement integrity matters not only for operations but also for compliance and reporting obligations that are becoming more stringent.
Getting Ahead with Detailed Market Intelligence
The strategic picture is clear enough to guide near-term decisions, but execution depends on segment-level detail that sits beyond the scope of a market overview. Revenue splits by region and application, type-level growth dynamics, competitive benchmarking, pricing patterns, channel behavior, and segmentation-specific forecasts all shape the practical choices manufacturers, investors, and procurement teams face. Several additional layers of intelligence can materially improve positioning and timing.
- Segment-level sizing and growth rates that clarify where demand is accelerating, plateauing, or shifting toward higher-specification requirements.
- Regional procurement patterns and certification expectations that influence market entry timing, partner selection, and compliance investment.
- Competitive profiling that goes beyond public positioning to examine product architectures, integration strengths, channel reach, and likely response to connectivity and energy-management trends.
- Scenario-based outlooks that link supply chain conditions, regulatory developments, and automation adoption rates to demand trajectories across key segments.
For organizations that need to move from strategic direction to implementation, a detailed research baseline can shorten evaluation cycles and reduce uncertainty around segment choice, product roadmap priorities, and partnership opportunities. The most actionable insights typically emerge when high-level trends are combined with granular segmentations, company-level comparisons, and application-specific demand drivers. Readers seeking that depth can access the complete PW Consulting research report for full segmentation data, competitive assessments, and tailored guidance aligned to specific operating contexts and investment horizons.
For detailed analysis of this topic, please visit the official page: Digital Panel Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Liquid Malt Extracts Market: Why the 3.8% CAGR Story Is Just the Beginning
By PW Consulting, 2026-09-21
Strategic Horizons: Navigating the Liquid Malt Extracts Market Amidst Transition and Growth
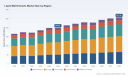
The liquid malt extracts market is at an inflection point where steady growth intersects with complex operational and strategic shifts. Based on 2025 as the base year, the market has demonstrated resilience over the historical period from 2020 to 2025, and current trajectories suggest a compound annual growth rate of 3.8% throughout the forecast period extending to 2032. The total revenue is projected to evolve from approximately 200.65 million in 2025 to nearly 257.92 million by 2032. This expansion is not merely a reflection of population growth but indicates a deepening integration of malt extracts into diverse value chains, driven by shifting consumer preferences and industrial efficiencies. However, the path forward is not uniform; it is characterized by specific challenges that require strategic navigation to capitalize on the projected upside.
Market Overview and Structural Dynamics
The broader market landscape suggests a moderate but consistent expansion, with the revenue trajectory indicating a cumulative increase over the forecast horizon. The top three players hold a combined share of 28.4%, while the top five account for 39.5%, indicating a moderately concentrated market structure that leaves room for both established dominance and targeted disruption by niche players. This fragmentation across the competitive spectrum suggests that while scale advantages exist, specialization and regional agility remain viable pathways for growth.
Key Challenges and Inflection Points
Despite the positive growth outlook, the industry faces distinct headwinds that could alter competitive dynamics. First, raw material volatility presents a persistent operational risk. Barley, the dominant upstream feedstock, is subject to regional price fluctuations. Recent data points to a 5% month-to-month increase in US malting barley prices in early 2026, signaling that cost pressures can escalate rapidly, squeezing margins for manufacturers who lack hedging strategies or diversified sourcing networks. Second, regulatory frameworks are reshaping cost structures and sourcing requirements. The European Union's Common Agricultural Policy includes provisions that affect barley supply and malt production costs, with forecasts for 2025/26 indicating modest year-over-year production changes in certain regions. These policy-driven variables can create unpredictable shifts in availability and pricing, necessitating proactive supply chain alignment. Third, the market is navigating a divergence in demand quality. While traditional applications remain strong, there is increasing pressure to provide extracts that meet specific functional, flavor, or sustainability criteria, pushing manufacturers to move beyond commodity-grade offerings toward differentiated solutions.
Worldwide Wheat Malt Market
Key Drivers of Market Evolution
Innovation in Product Formulation and Sustainability
Technological and process innovations are becoming central to competitive differentiation. Leading companies are increasingly focusing on the sustainability profile of their products as a value proposition. For instance, Muntons introduced Climate Positive Malt, which offers up to 30% lower carbon emissions per tonne compared to the UK malt average, leveraging regenerative agriculture practices. This type of innovation addresses the growing demand for transparency and reduced environmental impact, allowing suppliers to command premium positioning and align with the sustainability goals of downstream buyers. Such advancements demonstrate that product development is no longer solely about functional performance but also about embedding environmental credentials into the core offering.
Chocolate Liquid Extract Market
Regulatory and Policy Shifts Influencing Supply Chains
The regulatory environment acts as a double-edged sword, influencing both costs and opportunities. Policy adjustments, such as those within the EU's agricultural framework, can alter the economics of barley production, affecting the baseline costs for malt extract manufacturers. Simultaneously, global cereal market dynamics show that barley prices are influenced by spillover effects from tighter maize and wheat markets, with overall cereal indices rising in recent months. These interconnected commodity markets mean that malt extract producers must monitor broader agricultural trends, not just barley-specific metrics. Regulatory compliance and the ability to adapt to shifting subsidy or production incentives can become a source of competitive advantage for firms that integrate policy analysis into their strategic planning.
Demand-Side Shifts in Brewing and Food Applications
Consumer and industrial behavior continues to reshape application landscapes. In brewing, the pursuit of consistent flavor profiles and efficient production processes sustains the reliance on liquid malt extracts. However, there is a growing emphasis on specialty and clean-label ingredients that cater to niche beer styles and health-conscious consumers. In the food sector, the use of malt extracts in bakery and confectionery applications is being driven by the desire for natural sweeteners and flavor enhancers that align with clean-label trends. This demand-side evolution encourages manufacturers to expand their portfolios beyond standard extracts, offering tailored solutions that address specific texture, taste, or nutritional requirements. The shift toward premiumization in certain segments creates opportunities for suppliers that can demonstrate technical expertise and flexibility.
Supply Chain Adaptation and Cost Management
The structure of the supply chain is undergoing recalibration in response to volatility and demand complexity. With US barley production forecasted at 154 million bushels for 2025/26, a slight decrease from the prior year, feedstock availability remains stable but requires vigilant monitoring. Manufacturers are increasingly focusing on supply chain resilience, exploring long-term contracts, geographic diversification, and vertical integration where feasible. Cost management strategies are evolving to mitigate the impact of input price swings, with some players investing in process efficiencies to reduce yield losses and energy consumption. The ability to balance cost control with reliable supply is becoming a critical competency, distinguishing operators that can maintain margin stability in a fluctuating environment.
Competitive Landscape and Leading Strategies
Profiles of Market Leaders and Strategic Positioning
The competitive arena features a mix of large-scale manufacturers and specialized producers, each pursuing distinct strategic angles. Muntons, headquartered in Suffolk, UK, stands as Europe's largest manufacturer of malt extracts and malted ingredients, producing a range of liquid malt extracts for brewing, baking, and food applications. Its scale allows for broad market coverage, while its recent initiatives in sustainability, such as retaining a Gold EcoVadis Sustainability Rating for the sixth consecutive year, position it as a leader in corporate responsibility, appealing to buyers prioritizing ethical sourcing. The Malt Company, based in the United States, specializes in liquid malt extract products for homebrew and commercial brewing, offering premium LME variants. Its focus on the brewing segment enables deep technical specialization and brand loyalty among brewers seeking high-quality, consistent inputs. Ireks, located in Kulmbach, Germany, produces malt extracts including liquid malt extracts and related cereal ingredients for baking and brewing, leveraging its European base to serve regional demand with strong technical support. Doehler, from Darmstadt, Germany, provides malt-based ingredients and extracts for beverage and food industries, benefiting from a diversified ingredient portfolio that can cross-sell and integrate solutions across multiple applications. Briess Malt & Ingredients, based in Stevens Point, Wisconsin, USA, offers organic liquid malt extracts and concentrated brewers wort from 100% pure malted barley, targeting the premium and organic segments where certification and purity are key differentiators. Maltexco, in Belgium, manufactures liquid malt extracts and malted ingredients, serving the European market with a focus on quality and reliability. Barmalt, operating in Europe, produces liquid malt extracts for brewing and food sectors, maintaining a presence in the regional supply network. Malt Products, in the United States, specializes in malt-based ingredients including liquid malt extracts, catering to domestic demand with a focused product range. PureMalt Products, also in the United States, supplies liquid malt extracts for brewing and food applications, competing on service and product consistency. These companies illustrate the breadth of strategies, from scale and sustainability to specialization and organic focus.
Differentiation and Competitive Advantage
Leading players are carving out advantage through multiple levers. Scale players like Muntons leverage production capacity and geographic reach to serve large-volume customers while using sustainability credentials to enhance brand equity and meet the ESG criteria of global buyers. Specialty firms like The Malt Company and Briess Malt & Ingredients target specific niches, such as premium brewing or organic ingredients, where technical knowledge and product purity justify price premiums. Cross-industry players like Doehler utilize diversified portfolios to capture value across beverage and food segments, offering integrated solutions that reduce the procurement complexity for customers. The differentiation is increasingly multidimensional, combining product quality, certification, sustainability performance, and technical service. Companies that can articulate a clear value proposition across these dimensions are better positioned to defend margins and secure long-term contracts.
Evolution of Market Structure
The market structure is likely to evolve through a combination of consolidation and fragmentation. On one hand, the moderate concentration among top players suggests potential for further integration, as larger firms seek to expand their footprint through acquisitions or capacity expansions to capture economies of scale. On the other hand, the presence of numerous specialized players indicates that fragmentation will persist in niches where customization, regional focus, or specific certifications create barriers to entry for generalist competitors. New entrants may emerge in segments aligned with emerging trends, such as organic or climate-positive extracts, challenging incumbents to continuously innovate. The net effect is a dynamic landscape where strategic positioning must be continually reassessed to respond to both competitive moves and shifting demand patterns.
Future Trends and Commercial Opportunities
Sustainability as a Commercial Imperative
Sustainability is transitioning from a compliance requirement to a core commercial driver. With initiatives like Climate Positive Malt and sustained high sustainability ratings, the market is moving toward greater scrutiny of carbon footprints and agricultural practices. Over the next three to five years, extracts with verified lower emissions, regenerative sourcing, or organic credentials are expected to gain share in segments where buyers face pressure to reduce Scope 3 emissions or meet consumer expectations. This trend opens opportunities for manufacturers to develop certified sustainable product lines and for buyers to integrate these options into their procurement strategies to enhance their own sustainability narratives. The risk lies in the potential for greenwashing accusations or the cost of certification, which requires genuine process changes and transparent reporting.
Regional Divergence and Localization
Demand patterns are likely to exhibit regional divergence, influenced by local brewing traditions, food preferences, and regulatory environments. Europe continues to represent a significant portion of market value, with strong industrial brewing and bakery sectors, while North America maintains a robust demand base supported by both commercial and craft brewing. Asia Pacific shows potential for growth as brewing and processed food industries expand, though infrastructure and taste preferences may shape the pace of adoption. Latin America and the Middle East and Africa represent smaller but potentially emerging markets where urbanization and changing consumption habits could drive incremental demand. Manufacturers that can localize products, adapt to regional application requirements, and navigate local regulatory nuances will be better equipped to capture growth in diverse geographies. The risk includes overgeneralization, where a one-size-fits-all approach fails to resonate with regional buyers.
Premiumization and Specialty Extracts
The push toward premiumization is expected to accelerate, with buyers seeking extracts that offer specific functional benefits, distinct flavor profiles, or certification advantages. Specialty malt extracts, encompassing niche varieties tailored for particular applications or consumer segments, represent a growth avenue that aligns with this trend. As the market matures, the share of standard commodity extracts may stabilize or grow more slowly, while specialty segments capture higher margins and foster loyalty through performance and differentiation. This shift encourages investment in R&D, process control, and application testing to meet the precise needs of brewers and food manufacturers. The uncertainty is that premiumization may be sensitive to economic cycles, and in downturns, buyers might trade down, pressuring premium positions unless the value proposition is robust and demonstrable.
Strategic Recommendations for Decision Makers
For Manufacturers and Producers
Manufacturers should prioritize building resilience and differentiation simultaneously. Diversifying barley sourcing and establishing hedging mechanisms can mitigate raw material volatility, protecting margins against sudden price swings. Investing in sustainability certifications and process innovations, such as reducing carbon intensity or adopting regenerative practices, can create a defensible competitive edge and open access to premium customer segments. Expanding technical service capabilities and application support can deepen customer relationships, particularly in brewing and food sectors where performance and consistency are paramount. Additionally, exploring strategic partnerships or selective acquisitions can strengthen market position, especially in regions or segments where scale or local presence offers advantages.
For Investors and Capital Allocators
Investors should focus on companies with clear strategic positioning and the ability to execute in a changing environment. Evaluate players that demonstrate strong sustainability credentials, as these are increasingly tied to customer selection and long-term contract viability. Assess the balance between scale and specialization; large, diversified firms may offer stability, while niche leaders with premium products can deliver margin resilience if they maintain technical leadership. Monitor regulatory developments and commodity trends that could impact cost structures, as these factors can alter profitability trajectories. Opportunities may exist in segments aligned with organic growth, specialty extracts, or regions with expanding brewing and food processing industries, provided the competitive dynamics and entry barriers are well understood.
For Procurement and Supply Chain Leaders
Procurement professionals should approach sourcing with a focus on risk mitigation and value creation. Diversifying the supplier base can reduce exposure to regional volatility and supply disruptions, ensuring continuity for critical applications. Engaging with suppliers that offer transparency on sustainability metrics and certifications can support internal ESG goals and enhance brand positioning downstream. Prioritizing long-term relationships with suppliers that demonstrate technical support and consistent quality can reduce total cost of ownership by minimizing variability and production issues. Evaluating specialty extract options for specific applications may yield functional benefits that justify cost premiums, particularly where product differentiation or clean-label attributes are strategic priorities. Staying informed about market trends and regulatory shifts enables proactive adjustments to sourcing strategies, ensuring alignment with evolving business needs.
The liquid malt extracts market offers a landscape of moderate growth underpinned by structural demand and evolving value drivers. Success in this environment requires a clear understanding of cost dynamics, sustainability imperatives, and the shifting priorities of brewing and food manufacturers. The depth of segmentation, regional nuances, and competitive benchmarks warrants continuous monitoring and detailed analysis to inform precise strategic moves. For decision makers seeking to navigate these complexities with confidence, comprehensive research that unpacks granular data, competitive profiling, and scenario-based insights can provide the foundation for informed action.
PW Consulting
For detailed analysis of this topic, please visit the official page: Liquid Malt Extracts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
High-intensity Focused Ultrasound Market: Why 7.25% CAGR and Oncology Demand Redefine Growth
By PW Consulting, 2026-09-21
Navigating the High-Intensity Focused Ultrasound System Market: Strategic Trends and Commercial Opportunities
The global High-intensity Focused Ultrasound System Market has matured into a structurally sound growth sector, with total industry revenue surpassing $215 million in 2025 and projected Compound Annual Growth Rate of 7.25 percent through 2032. This trajectory reflects a transition from niche therapeutic adoption to broader clinical integration across oncology, urology, gynecology, and aesthetic procedures. Revenue projections indicate continued acceleration, with the market expected to approach $345 million by 2032, driven by expanding indication approvals, workflow optimization, and increasing acceptance of non-invasive tissue ablation. Rather than a uniform expansion, the growth pattern reveals concentrated value creation in specific therapeutic adjacencies and device configurations, requiring stakeholders to assess where technological differentiation, regulatory alignment, and reimbursement maturation intersect.
A defining characteristic of the current landscape is market concentration, with the top three companies accounting for roughly 68.5 percent of revenue and the top five capturing approximately 75.2 percent. This concentration reflects entrenched clinical reference points, long development cycles for focused ultrasound platforms, and the premium placed on regulatory clearances and reimbursement pathways. At the same time, the market remains dynamic enough to accommodate targeted innovations, particularly in compact form factors and specialized procedural applications. The interplay between established players defending core indications and newer entrants carving out differentiated niches creates a structured environment where strategic positioning matters more than generic market participation.
Navigating Structural Inflection Points
Three interconnected challenges currently shape operator and manufacturer decision-making. First, the reimbursement environment is actively recalibrating. Procedural coding frameworks are stabilizing in select geographies, with specific CPT code structures enabling outpatient coverage for prostate ablation and adjacent applications. However, reimbursement recognition is uneven, creating a patchwork where clinical adoption depends heavily on local payer policies, documentation requirements, and institutional procurement cycles. This fragmentation complicates volume scaling for manufacturers and introduces uncertainty in commercial forecasting.
Second, clinical validation and indication expansion remain uneven across therapeutic areas. While oncology and urology applications have accumulated substantial procedural evidence, other applications continue to move through evolving guideline development and health-economic evaluation. Stakeholders increasingly expect not only regulatory clearance but also comparative effectiveness data, workflow efficiency metrics, and total cost-of-care considerations. The burden of proof is rising, which favors organizations with robust clinical trial pipelines and disciplined real-world data generation.
Third, the operational complexity of focused ultrasound deployment introduces adoption friction in certain settings. Traditional platforms require specialized room configuration, multidisciplinary coordination, and operator training. Although portable and compact system designs are expanding accessibility, clinical centers still weigh capital outlay, maintenance requirements, procedure throughput, and integration with imaging guidance. These considerations are especially relevant as health systems prioritize capital efficiency and procedural standardization.
Key Drivers Shaping Market Trajectory
Several structural forces are reinforcing demand for focused ultrasound systems, but their impact differs across therapeutic categories and geographies. The most consequential drivers revolve around technological refinement, regulatory and reimbursement alignment, shifting clinical preferences, and evolving cost structures that influence purchasing behavior.
Engineering Precision and Workflow Efficiency
Technological progress is moving focused ultrasound from procedural feasibility toward operational efficiency. Imaging integration, robotic assistance, motion compensation, and lesion-targeting accuracy are steadily reducing procedural variability and expanding the range of treatable anatomies. Recent advancements in ultrasound imaging and workflow enhancements for robotic HIFU systems illustrate how manufacturers are prioritizing operator experience and procedural consistency, not just energy delivery. Similarly, platforms leveraging MR-guided focused ultrasound continue to support treatment of neurological and oncologic conditions by combining real-time visualization with precise ablation control. The strategic implication is clear: differentiation increasingly depends on end-to-end procedural value rather than hardware specifications alone.
High Intensity Focused Ultrasound (HIFU) Market
A second technological shift is the emergence of compact and portable configurations designed for broader clinical deployment. Smaller footprint systems lower some infrastructure barriers and support use in ambulatory settings, smaller hospitals, and outpatient clinics. This does not eliminate the need for imaging guidance or clinical expertise, but it expands the addressable deployment base and can improve utilization rates when matched to appropriate patient volumes. For manufacturers, the challenge is balancing portability with the performance standards required for complex ablation workflows.
High Intensity Focused Ultrasound (HIFU) Therapy Market
Regulatory Pathways and Reimbursement Maturation
Regulatory and reimbursement developments are becoming central market drivers, particularly where procedural coding and coverage policies reduce adoption friction. In the United States, long-standing CPT code structures have enabled outpatient reimbursement for specific HIFU prostate ablation procedures, creating a foundational reimbursement pathway. More recently, attention has turned to expanding procedural coverage for additional applications and clarifying documentation expectations for accurate billing. Health systems and providers are responding by investing in workflow documentation, coding alignment, and payer engagement, which strengthens the commercial environment for cleared devices.
At the same time, national reimbursement decisions influence adoption velocity in specific regions. Public health system coverage for certain focused ultrasound procedures can accelerate institutional purchasing decisions by reducing uncertainty around patient access and recurring revenue. Conversely, where reimbursement remains ambiguous, hospitals may delay procurement until clinical adoption curves and payer policies stabilize. The net effect is that reimbursement visibility is now as important as device performance in shaping commercial timelines.
Demand-Side Realignment Toward Non-Invasive Care
Clinical demand for less invasive procedural options continues to reshape treatment pathways across multiple specialties. Patients and providers are increasingly interested in modalities that can reduce recovery time, minimize procedural morbidity, and fit into outpatient care models. In oncology and urology, focal therapy approaches have gained attention for their potential to preserve function while targeting diseased tissue. In gynecology and breast health, focused ultrasound is being explored for targeted ablation of benign and malignant conditions where surgical alternatives carry meaningful trade-offs. In aesthetics and body contouring, demand is driven by consumer preference for non-surgical interventions and the broader shift toward minimally invasive enhancement procedures.
This demand-side evolution is not uniform, but it is persistent. Where clinical evidence supports safety and reproducible outcomes, focused ultrasound gains traction as an alternative or complement to existing interventions. Where evidence gaps remain, adoption proceeds more cautiously. That creates a strategic environment in which market leaders are those who can align device capabilities with the evidentiary standards required by specialty societies, institutional review processes, and payer evaluation.
Cost Structure Pressures and Procurement Behavior
Healthcare cost containment and capital allocation discipline are influencing how institutions evaluate focused ultrasound investments. Hospitals and ambulatory providers increasingly assess total cost of ownership, including service coverage, consumables, training, procedural throughput, and compatibility with existing imaging infrastructure. Supply chain considerations also matter, particularly for devices that rely on specialized components, software licensing, or integration with third-party imaging and navigation systems. As procurement teams compare capital-intensive platforms against workflow and reimbursement assumptions, manufacturers that can articulate value in operational terms gain an advantage.
At the same time, cost pressures can create openings for more compact, targeted, or application-specific solutions. Procurement decisions are not always driven by the most advanced platform; in many cases, the preferred solution is the one that matches institutional case mix, staff expertise, and reimbursement realities. This dynamic encourages manufacturers to develop tiered offerings and to tailor commercial models to specific clinical settings.
Competitive Landscape and Strategic Positioning
The competitive environment in focused ultrasound reflects a blend of specialized leaders, clinically anchored platforms, and targeted innovators. Several companies have established strong positions by concentrating on distinct procedural domains and investing in regulatory clearance, workflow refinement, and clinical evidence generation. Understanding how these firms differentiate reveals where value is being created and how the market is likely to evolve.
Differentiation Through Clinical Specialization
Several platform leaders have built competitive advantage by aligning their technology with specific clinical use cases and the operational requirements that accompany them. One robotic HIFU system for prostate cancer focal therapy has advanced by combining procedural precision with continuous imaging and workflow enhancements, supported by recent regulatory clearances for imaging and workflow improvements. The strategic value here is not only in the therapy itself, but in reducing procedural complexity and improving reproducibility for clinicians. Another developer has focused on non-invasive treatment of thyroid nodules, breast fibroadenomas, and varicose veins, emphasizing a diversified but focused portfolio across soft-tissue and vascular applications. This approach illustrates how specialized indication coverage can support commercial resilience when tied to appropriate reimbursement and referral patterns.
A different specialization path has emerged in MR-guided focused ultrasound, where platforms support neurological and oncologic applications by leveraging high-quality imaging for targeting and treatment control. These systems emphasize precision and safety in delicate indications, often appealing to specialized centers with the infrastructure and expertise required for complex procedures. Yet another platform has addressed prostate ablation, bone lesion treatment, and related oncologic applications through MR-HIFU integration, underscoring the importance of combining imaging modalities with ablation capability when targeting multidisciplinary oncology pathways.
Manufacturers outside the traditional Western medtech core have also played a significant role, particularly in non-invasive tumor ablation across liver, breast, and bone applications, supported by global distribution reach. These platforms demonstrate the international nature of focused ultrasound adoption and highlight how broad indication coverage and distribution networks can sustain growth even in competitive markets. Meanwhile, newer entrants have pursued highly targeted opportunities, including fluoroscopy-guided HIFU for chronic low back pain, reflecting the potential for focused ultrasound to expand into pain management when supported by appropriate regulatory clearance and procedural evidence.
PW Consulting
Strategic Moves and Recent Commercial Signals
Recent regulatory and reimbursement activity underscores how commercialization is being shaped at the procedural level. One company received FDA 510(k) clearance for ultrasound imaging and workflow enhancements to its robotic HIFU system for prostate cancer, reinforcing the strategic importance of software, navigation, and operator support in established therapeutic areas. Another company obtained De Novo clearance for a fluoroscopy-guided HIFU system aimed at chronic low back pain, signaling an expansion of focused ultrasound into pain intervention through nerve-targeted ablation. These events demonstrate how regulatory milestones can open new procedural categories while strengthening existing ones.
On the reimbursement and market access side, national coverage recognition in certain regions has improved procedural economics for prostate-focused HIFU, while ongoing payer policy updates continue to define which CPT codes apply to HIFU ablation procedures and how documentation should be structured. Provider-facing education around documentation and billing is increasingly part of commercialization, since procedural reimbursement depends not only on device availability but also on accurate coding and compliance. The launch of an international focused ultrasound society further reflects the sector's effort to standardize clinical practice, support adoption, and build a stronger professional foundation for the technology across indications.
Market Structure Evolution
The current concentration profile suggests that scale advantages, regulatory experience, and established clinical relationships will continue to matter. However, the market is unlikely to remain static. Several forces point toward selective consolidation and parallel differentiation. Larger or better-capitalized companies may pursue complementary technologies, indication expansion, or geographic expansion to strengthen installed base advantages. At the same time, smaller or more specialized companies can thrive by solving a narrow clinical problem exceptionally well, particularly in areas where workflow simplicity, portability, or unique guidance modalities provide a meaningful fit for a specific care setting.
This environment rewards strategic clarity. Companies that attempt to compete across every therapeutic area without a differentiated value proposition risk being outmatched by leaders with stronger procedural evidence, reimbursement alignment, or workflow integration. Conversely, organizations that define a focused commercial territory and build a defensible evidence and distribution strategy can capture meaningful share in specific segments, even within a concentrated overall market.
Future Trends and Commercial Implications
Looking ahead three to five years, the focused ultrasound market is likely to be defined by deeper therapeutic integration, broader procedural accessibility, and more structured market-access expectations. These trends create opportunity, but they also introduce execution requirements that will separate disciplined strategies from generic participation.
Deeper Integration into Multidisciplinary Care Pathways
One of the strongest forward-looking trends is the integration of focused ultrasound into broader care pathways rather than standalone procedures. In oncology and urology, this means closer alignment with imaging, navigation, biopsy, and follow-up workflows. In gynecology and breast health, it means coordination with specialty clinics and referral networks. In pain management and certain vascular applications, it means integration with interventional and rehabilitation services. When focused ultrasound becomes a recognized step within a care pathway, procurement decisions become less device-centric and more pathway-centric, which favors platforms that support clinical continuity, documentation, and cross-departmental adoption.
Commercially, this trend rewards companies that invest in multi-department usability, interoperable imaging integration, and clinical support services. It also reinforces the importance of real-world evidence, since pathway integration depends on demonstrated outcomes across heterogeneous patient populations and clinical settings.
Expanded Application Breadth with Targeted Indication Strategy
Application breadth is likely to continue expanding, but not indiscriminately. The clinical and commercial logic will favor targeted indication expansion where procedural feasibility, patient demand, and reimbursement alignment converge. Pain intervention, benign soft-tissue conditions, and specific oncology workflows are plausible areas of incremental growth, provided clinical evidence and regulatory clarity keep pace. The key strategic question for manufacturers is whether to extend existing platforms into adjacent indications or build dedicated solutions optimized for new procedural requirements. Both paths are viable, but each demands different investment profiles and clinical engagement strategies.
This trend creates opportunity for organizations that can identify indications with strong unmet need, manageable competitive overlap, and a realistic reimbursement trajectory. It also introduces risk for companies that overcommit to indication expansion before evidence and payer recognition are sufficiently mature.
More Institutional Procurement Discipline and Predictive Volume Planning
As reimbursement visibility improves in select areas, procurement behavior is likely to become more disciplined but also more predictable where coverage is clear. Health systems will increasingly evaluate focused ultrasound purchases based on case mix projections, reimbursement certainty, staff training requirements, and operational throughput. This suggests a shift from speculative adoption toward more evidence-based capital deployment. For manufacturers, the implication is that commercial success will depend on supporting customers with utilization modeling, workflow planning, and reimbursement documentation support, not simply offering device specifications.
The principal risk in this trend is that procurement discipline may slow adoption in settings where reimbursement remains uncertain or where the procedural case mix is insufficient to justify capital deployment. Strategic flexibility, including flexible financing, service models, and application-specific configurations, may become more important in bridging that gap.
Actionable Guidance for Decision-Makers
The current market dynamics suggest that strategic success depends less on broad exposure to focused ultrasound and more on aligning product, evidence, reimbursement, and commercial model with the most attractive procedural territories. The following considerations are relevant across different stakeholder roles.
For Manufacturers and Technology Developers
- Concentrate differentiation on end-to-end procedural value, including imaging integration, workflow efficiency, operator support, and documentation alignment, rather than emphasizing hardware features in isolation.
- Prioritize indication strategies where regulatory clearance, reimbursement recognition, and clinical demand reinforce one another, and avoid expansion that outpaces payer or guideline readiness.
- Build commercial support around utilization planning, clinical training, and reimbursement documentation, since these factors increasingly determine procurement timing and adoption velocity.
For Investors and Strategic Capital Allocators
- Assess commercial readiness by examining not only regulatory milestones but also reimbursement visibility, evidence-generation pipelines, and installed-base economics in priority indications.
- Look for companies with disciplined clinical and market-access strategies, especially where therapeutic specialization and workflow differentiation can support defensible positioning within a concentrated market.
- Monitor procedural reimbursement developments and clinical society activity closely, since these often provide earlier signals of adoption shifts than top-line revenue data alone.
For Procurement Leaders and Health System Decision-Makers
- Evaluate focused ultrasound investments based on total cost of ownership, case mix fit, staffing requirements, imaging compatibility, and expected reimbursement support rather than device capability alone.
- Align procurement timing with reimbursement clarity and workflow readiness, and require vendor support for documentation, coding alignment, and training to reduce adoption friction.
- Consider application-specific or compact configurations where patient volume and procedural mix justify them, while ensuring that performance standards remain appropriate for the intended clinical use.
The focused ultrasound market is advancing through a combination of technological maturation, procedural reimbursement development, and shifting clinical preferences. The commercial winners are likely to be those who translate these forces into focused strategies with clear indication priorities, credible evidence plans, and realistic models for institutional adoption. For decision-makers seeking detailed segmentation data, competitive benchmarking, and tailored guidance aligned to specific strategic objectives, deeper analysis can provide the granularity needed to convert these directional trends into operational choices.
For detailed analysis of this topic, please visit the official page: High-intensity Focused Ultrasound System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The DNA Sequencing Market: Strategic Trends and Commercial Opportunities for the Next Decade
The global DNA sequencing market has entered a decisive phase of expansion, driven by converging advances in platform technology, regulatory momentum, and widening clinical adoption. From 2020 through 2025, the market grew from approximately $9.1 billion to $16.9 billion, reflecting a sustained upward trajectory that has extended into early forecast years. Projections point to continued acceleration through 2032, with the market anticipated to reach $44.6 billion and a compound annual growth rate of 14.9% across the forecast horizon. This growth is not merely incremental; it reflects a structural shift in how sequencing is positioned across research, clinical diagnostics, public health, and commercial genomics.
The current market base is anchored by next-generation sequencing, which commands the largest revenue share and underpins most high-throughput diagnostic and research workflows. Alongside this dominant modality, third-generation and single-molecule approaches are carving out specialized niches where read length, phasing, or real-time observation deliver distinct analytical advantages. The segment composition reveals a market that is simultaneously consolidating around platform standardization while preserving room for differentiated technologies that address specific biological or operational questions.
Beneath the headline growth figures, however, lie structural tensions that will shape competitive outcomes over the next several years. Three challenges stand out as particularly consequential. First, the industry faces mounting pressure to translate sequencing throughput into interpretable clinical action without inflating downstream bioinformatics costs. Second, supply chain and reagent economics remain sensitive to manufacturing scale, component availability, and the geographic concentration of platform suppliers. Third, the market is navigating a regulatory evolution that is becoming more prescriptive around validation, quality control, and data comparability, especially as sequencing moves deeper into diagnostic and therapeutic development pathways.
These dynamics matter because they determine who can convert technology leadership into durable commercial advantage. Companies that treat sequencing solely as an instrument business are increasingly exposed to commoditization risk, while those that integrate workflows, informatics, and evidence generation are building moats around recurring value.
Key Drivers Shaping the Market Trajectory
The expansion of sequencing adoption is being propelled by a set of reinforcing drivers rather than a single breakthrough. Understanding their interplay is essential for assessing where value will accumulate.
Technology Innovation and Platform Differentiation
Platform innovation continues to reshape what sequencing can deliver in terms of speed, cost, and biological resolution. Short-read next-generation systems remain the workhorse for high-volume applications, but long-read and single-molecule technologies are expanding the envelope for structural variant detection, haplotype resolution, and complex genome assembly. At the same time, a new wave of benchtop and high-throughput systems is targeting broader accessibility, with an emphasis on lowering total cost of ownership and simplifying operational complexity.
Recent product activity illustrates this direction. Illumina introduced a distributed whole-genome sequencing solution for highly sensitive minimal residual disease research, initially available to select partners with a broader commercial launch planned for 2027. This move signals a strategic push toward ultra-sensitive detection workflows that could bridge research and clinical oncology applications. In a different segment, Clear Labs launched an automated next-generation sequencing solution for Mycobacterium species identification and tuberculosis drug resistance mutation detection, underscoring how automation and targeted assay design are converging to reduce hands-on time and standardize results in pathogen testing.
The practical implication is that technology leadership is increasingly defined by workflow completeness rather than raw sequencing output alone. Systems that reduce sample preparation variability, streamline library construction, or pair sequencing with purpose-built analytics are gaining traction because they lower the barrier to reliable deployment across laboratories with varying levels of expertise.
Policy and Regulatory Environment
Regulatory and standardization activity is moving from passive oversight toward more active enablement, particularly where sequencing can improve safety assessment, outbreak response, and clinical trial initiation. In April 2026, the FDA distributed for comment a draft guidance on next-generation sequencing-based methods for safety assessment of genome editing in human gene therapy products, an indication that regulators are building frameworks to support more efficient evaluation of advanced therapies.
In parallel, public health mandates are creating structured demand for whole-genome sequencing in surveillance and outbreak investigation. The European Commission adopted regulation requiring member states to perform whole-genome sequencing on selected foodborne pathogen isolates for outbreak investigations, a policy shift that institutionalizes sequencing as a standard tool in epidemiological response. This kind of regulatory anchoring matters because it converts occasional demand into recurring, protocol-driven usage.
Standardization efforts are also advancing on the technical side. Development of ISO quality control metrics for DNA sequencing informatics has been progressing through enquiry phases, reflecting an industry-wide recognition that data quality, metadata consistency, and comparability across platforms will become increasingly important as sequencing data supports cross-institutional decision-making. Collectively, these regulatory and standards movements reduce ambiguity for adopters, but they also raise the bar for vendors that must demonstrate validation readiness and documentation rigor.
Demand-Side Shifts in Clinical and Commercial Settings
Demand is broadening beyond traditional research settings as sequencing becomes embedded in clinical workflows, precision medicine programs, and applied genomics. Oncology remains a central application arena, where sequencing supports biomarker discovery, therapy selection, residual disease monitoring, and translational research. At the same time, reproductive health, clinical investigation, and specialized typing applications continue to expand as laboratories seek higher-resolution insights from smaller sample volumes or more complex biological questions.
DNA Microarray Market
A notable demand-side shift is the growing expectation that sequencing output should be paired with interpretable, clinically relevant reporting. Laboratories and health systems are less interested in raw sequence generation in isolation; they want integrated solutions that connect assay performance with actionable interpretation, whether for oncology panels, infectious disease characterization, or transplant-related typing. This expectation is nudging the market toward solution-oriented commercialization, where value is created not just by selling instruments and reagents but by reducing the operational and cognitive burden on end users.
Sanger Sequencing Service Market
Cost Structure and Supply Chain Realities
Cost dynamics remain a fundamental driver of adoption, but the conversation has evolved beyond instrument price alone. Total cost of ownership now encompasses reagent economics, throughput utilization, labor intensity, failure rates, and informatics overhead. Manufacturers that can improve reagent efficiency, increase instrument uptime, or reduce consumable waste are able to offer compelling economics even when headline pricing appears similar across competitors.
Supply chain resilience has also become a strategic concern. The concentration of platform manufacturing and key consumable production creates dependencies that can affect availability, lead times, and regional pricing. As a result, some customers are evaluating multi-vendor strategies or prioritizing suppliers with stronger regional support and service networks. For vendors, this environment rewards operational reliability and transparent supply planning as much as it rewards technical specifications.
Competitive Landscape and Leading Strategies
The competitive structure of the DNA sequencing market is characterized by high concentration at the top, alongside active experimentation by emerging and specialized players. Roughly two-thirds of market revenue is associated with a small group of leading firms, and the top five together account for a substantial majority of revenue. This concentration does not imply stagnation; rather, it reflects the scale advantages involved in platform development, global service support, consumables ecosystems, and regulatory readiness.
Illumina remains a central force in next-generation sequencing, with a broad installed base and a portfolio spanning instruments, reagents, and applications-oriented research tools. Its recent emphasis on distributed whole-genome sequencing for minimal residual disease research suggests a strategy aimed at deepening relevance in high-value oncology workflows where sensitivity and reproducibility are paramount. Thermo Fisher Scientific offers a complementary breadth, combining next-generation sequencing, Sanger sequencing, and genomics instruments with a large consumables footprint. Its advantage lies in portfolio integration across multiple laboratory needs, which can simplify procurement and cross-platform support for institutions seeking operational consistency.
Oxford Nanopore Technologies and Pacific Biosciences represent long-read and single-molecule approaches with distinct technological identities. Oxford Nanopore’s nanopore-based platforms emphasize portable and real-time sequencing capabilities, which can be advantageous for field deployment, rapid pathogen characterization, and applications where flexibility matters. Pacific Biosciences focuses on high-fidelity long-read systems and single-molecule real-time technology, positioning around accuracy and read length for complex genomic analysis. Both companies illustrate how specialized technology narratives can sustain differentiated market positions even within a market dominated by short-read scale.
A second tier of challengers and specialists is expanding the boundaries of cost, automation, and application focus. Element Biosciences has introduced a benchtop next-generation sequencing platform designed for high-throughput, cost-effective sequencing, targeting laboratories that want strong performance without the footprint or economics of larger systems. Ultima Genomics has pursued high-throughput, cost-efficient sequencing for population-scale genomics, an approach that speaks directly to large cohort studies and initiatives where per-sample economics are critical. BGI Group, through its MGI technology offerings, continues to compete with whole-genome and targeted sequencing platforms, leveraging manufacturing scale and regional presence.
QIAGEN remains relevant through library preparation, sequencing panels, and hybrid capture technologies, areas where upstream sample and target enrichment can be as important as the sequencing run itself. Clear Labs is advancing fully automated next-generation sequencing for pathogen and oncology applications, with product activity such as its automated mycobacteria and tuberculosis resistance solution highlighting a focus on hands-off, clinically oriented workflows. Tempus AI illustrates a different model altogether, integrating whole-genome sequencing assays with an artificial intelligence-driven precision medicine platform, effectively linking sequencing data to decision support and clinical interpretation.
This landscape is evolving along several axes. One is consolidation around integrated solutions, where instrument, consumable, software, and support offerings are bundled to reduce fragmentation for customers. Another is fragmentation at the application layer, where specialists compete on speed, automation, or niche assay performance rather than on general-purpose throughput alone. A third is the continued entry of new platforms that challenge incumbent economics, particularly in benchtop and high-throughput cost-per-sample segments. The net effect is a market where incumbents must defend installed bases and recurring consumables revenue while newcomers and specialists attempt to open whitespace through operational simplicity, price advantage, or application specificity.
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to define the market's direction and shape commercial opportunities.
One major trend is the continued movement from sequencing as a data generation step toward sequencing as an integrated diagnostic and decision-support component. This will favor organizations that can align assay design, automation, bioinformatics, and reporting into cohesive workflows. The commercial opportunity lies in reducing turnaround time and interpretation burden, particularly in oncology and infectious disease settings where timely results influence clinical decisions. The risk is that integration expectations rise faster than standardization, creating interoperability challenges and increasing the cost of maintaining multiple workflow ecosystems.
A second trend is the growing institutionalization of whole-genome sequencing in public health, food safety, and surveillance contexts. Regulatory and policy anchors can create durable demand, but they also require consistent quality, traceability, and comparability across laboratories. Companies positioned to support standardized surveillance workflows, including validated panels, reference materials, and data reporting tools, may benefit from this shift. The uncertainty lies in how uniformly these mandates are implemented across regions and how quickly resource-constrained laboratories can adopt the required infrastructure.
A third trend is the intensifying competition around cost-efficient scale. As more platforms pursue lower per-sample economics, pressure will increase on incumbents to defend margins through workflow efficiency, service models, and differentiated applications rather than price alone. This environment can accelerate adoption among cost-sensitive users, but it also raises the stakes for suppliers that depend heavily on reagent and consumable revenue. The strategic opportunity is to pair economic competitiveness with value-added services such as bioinformatics, assay optimization, and laboratory workflow consulting, which can improve stickiness and reduce direct price sensitivity.
Across these trends, a shared risk is the possibility that technological promise outpaces evidentiary and regulatory readiness in certain clinical settings. Where claims outstrip validated utility, adoption may slow, reimbursement pathways may remain uncertain, and customers may become more cautious about platform commitments. Another risk is geopolitical and supply chain volatility, which can affect reagent availability, service continuity, and regional pricing stability. Companies planning long-cycle investments should therefore model not only technology adoption but also resilience and support capacity.
Strategic Actions for Decision-Makers
The current market environment rewards clarity of positioning and discipline in execution. Different stakeholder groups will need to prioritize differently, but several actions are broadly relevant.
For sequencing platform and consumable manufacturers, the priority is to strengthen total workflow value rather than competing solely on instrument specifications. That means investing in assay compatibility, library preparation efficiency, automation, and bioinformatics support that reduce customer friction. It also means preparing for a regulatory environment that increasingly expects validation documentation and quality control rigor. Companies that can demonstrate reliable performance across diverse laboratory settings, while maintaining clear service and supply commitments, will be better positioned to defend recurring revenue and expand into higher-value applications.
For investors, the most important question is where durable demand is being created versus where adoption depends primarily on technology enthusiasm. Workflow-integrated solutions, surveillance-driven public health demand, and oncology applications with clear clinical interpretation pathways offer stronger signals of sustained use than instrument launches alone. At the same time, concentration in the market means that competitive disruption can come from cost-efficient challengers, application specialists, or software-centric models that change how sequencing data is converted into decisions. Due diligence should therefore assess not only platform performance but also consumables economics, service networks, regulatory readiness, and the defensibility of any proprietary informatics or assay IP.
For procurement and laboratory decision-makers, the focus should be on total cost of ownership and operational fit. Instruments with attractive sticker prices can become expensive if they underutilize capacity, require specialized labor, or create informatics bottlenecks. Evaluating vendors on reliability, support responsiveness, assay breadth, and compatibility with existing workflows can yield better long-term outcomes than selecting solely on benchmark performance. It is also prudent to consider multi-platform strategies where applicable, especially in settings where application diversity or supply resilience matters more than single-vendor simplicity.
Across all of these roles, the pace of change in sequencing technology, regulation, and application design makes timely, detailed market intelligence valuable. Segment-level demand patterns, regional adoption differences, platform economics, and the regulatory calendar all influence where opportunities are emerging and where assumptions may be outdated. For organizations seeking deeper segmentation data, competitive benchmarking, and tailored scenario planning, a more detailed study of the DNA sequencing market can provide the granularity needed to support investment, product, and procurement decisions with greater confidence.
PW Consulting Health Care Research Center
For detailed analysis of this topic, please visit the official page: DNA Sequencing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Flexible Heating Element Market: Why 8.37% CAGR and EV Demand Reshape Strategy
By PW Consulting, 2026-09-21
Navigating the Flexible Heating Element Market: Strategic Trends and Commercial Opportunities
The flexible heating element market has evolved from a niche thermal management solution into a critical enabler of performance across high-growth industries. This analysis examines the market's trajectory, the structural forces reshaping competitive dynamics, and the strategic imperatives for manufacturers, investors, and procurement leaders navigating the next cycle of growth.
Market Overview and Current Challenges
The global market for flexible heating elements has demonstrated consistent expansion over the past half-decade, driven by cross-sector demand for precision thermal control, compact form factors, and reliable performance in demanding environments. From 2020 through 2025, the market grew from approximately $0.95 billion to $1.42 billion, reflecting an accelerating adoption curve as end-use industries integrated flexible heating into increasingly complex product architectures. Forecasts indicate the market will continue its upward trajectory through 2032, surpassing the $2.4 billion mark by the end of the forecast window and maintaining a compound annual growth rate of 8.37 percent. This growth profile places flexible heating alongside other high-value thermal management sub-segments, but the underlying demand drivers are distinct in their technical specificity and regulatory sensitivity.
PW Consulting Automotive & Machinery Research Center
Several structural challenges are reshaping how companies approach product development, pricing, and market entry. First, the divergence in material performance requirements across application verticals has pressured manufacturers to specialize rather than pursue broad commoditization strategies. Flexible heaters deployed in semiconductor processing, medical instrumentation, or aerospace assemblies demand different thermal profiles, reliability thresholds, and certification pathways. Companies that attempt to serve all segments with generic portfolios are encountering margin compression and longer qualification cycles. Second, the cost structure of advanced flexible heating technologies remains elevated relative to traditional alternatives. Precision etching, lamination, and custom trace design for polyimide-based solutions introduce manufacturing complexity that raises unit costs significantly compared to rigid heating alternatives. Carbon-based and specialty conductive traces further compound material expenses, creating a cost differential that buyers must weigh against performance gains. Third, regulatory and certification requirements are tightening across target markets. Energy efficiency expectations, safety standards, and application-specific qualification frameworks are becoming non-negotiable market access conditions rather than optional differentiators. These dynamics are compressing the timeline from concept to volume production and rewarding organizations with established compliance capabilities and engineering partner ecosystems.
Worldwide Contact Heating Elements Market
Key Drivers Reshaping the Market
Technological Innovation and Material Performance
Material science advances are the most persistent driver of market evolution. Polyimide-based flexible heaters continue to gain traction in applications requiring high watt density, thermal stability, and compatibility with precision electronic assemblies. Recent industry demonstrations have highlighted pure-polyimide heater architectures achieving UL 94 V0 certification and progressing through ESA qualification pathways, signaling that high-reliability flexible heating is becoming viable for space-grade and mission-critical deployments. At the same time, silicone rubber solutions remain dominant where cost sensitivity, form-factor flexibility, and moderate thermal requirements intersect. The parallel development of both material tracks reflects a market that is simultaneously pushing performance boundaries and optimizing for volume economics. Innovations in integrated sensors, embedded thermocouples, and custom circuit design are also reducing the friction between heating element selection and system-level thermal management. Manufacturers offering combined heating and sensing solutions are shortening integration cycles for OEMs that previously managed these components separately.
Policy and Regulatory Environment
Regulatory expectations are acting as both a constraint and a catalyst. Stringent energy efficiency standards and safety requirements are pushing manufacturers toward designs that minimize thermal waste, improve temperature uniformity, and reduce failure modes. In medical and space applications, recognized construction standards and qualification frameworks have become baseline requirements rather than premium features. The emergence of clear certification milestones, such as UL recognition and ESCC qualification for specialized flexible heaters, is narrowing the field for suppliers serving regulated verticals. This regulatory intensification favors established players with documented qualification histories and penalizes new entrants lacking the testing infrastructure or compliance documentation to compete in high-stakes segments. Simultaneously, it creates an opportunity for suppliers that can package compliance readiness as a service, reducing the burden on OEMs navigating complex approval processes.
Demand-Side Shifts in End-Use Industries
Demand patterns are being reshaped by architectural changes in key end-use sectors. In automotive and transportation, the continued emphasis on battery thermal management and cabin comfort solutions is increasing the relevance of flexible heaters that can be integrated into tight mechanical envelopes without compromising durability. Electronics and semiconductor applications are driving demand for localized, precisely controlled heating in processing equipment, test fixtures, and advanced packaging workflows. Medical device manufacturers are seeking high-wattage flexible heating options that enable faster thermal response in compact instrumentation, while aerospace and defense programs are prioritizing lightweight, high-reliability heating solutions with documented qualification records. These demand shifts are not uniform; they create pockets of accelerated growth where performance requirements align with the technical advantages of flexible heating. Companies able to map application-specific requirements to material and design capabilities are seeing stronger conversion rates and shorter sales cycles in targeted verticals.
Supply Chain and Cost Structure Dynamics
Cost structures in flexible heating are being recalibrated by a combination of material pricing, processing complexity, and customer demand for lower minimum order quantities. Specialty conductive traces and carbon-based materials continue to elevate raw material costs relative to silicone rubber alternatives, while precision etching and lamination steps add manufacturing overhead for polyimide-based products. At the same time, new market entrants are introducing low-MOQ offerings and free design support to reduce barriers for prototyping and low-volume production. This shift is particularly relevant for electronics, EV, and medical applications where design iteration cycles are short and upfront cost risk must be minimized. The tension between premium material performance and accessible entry pricing is creating a more stratified market, with volume-driven cost optimization on one end and high-reliability, specification-driven solutions on the other. Suppliers that can navigate this spectrum without sacrificing quality or lead time are positioning themselves to capture demand across multiple tiers of the market.
Competitive Landscape and Leading Strategies
The competitive field in flexible heating is defined by a mix of established manufacturers with deep application expertise and newer entrants lowering barriers to adoption through accessible pricing and design support. Market concentration remains moderate, with a core group of leading suppliers accounting for a significant share of high-value contracts, while a broader tail of regional and specialty providers competes on customization, lead time, and niche qualification capabilities.
Electric Heating Elements (Electric Heater) Market
Several strategic positioning patterns are emerging among the most competitive players. One clear approach is engineering partnership and custom material specialization. Suppliers that emphasize custom polymer thick film, silicone rubber, polyimide, and etched foil technologies are building advantage through the ability to adapt heater geometry, watt density, and sensor integration to specific customer architectures. This model thrives in applications where standard off-the-shelf solutions cannot meet thermal or mechanical constraints, such as mission-critical medical assemblies or high-reliability aerospace systems. A second approach centers on accessibility and speed for prototyping and low-volume production. By removing minimum order quantity requirements, offering free circuit design assistance, and accelerating delivery timelines, some providers are capturing early-stage design wins in electronics, EV, and medical applications. This strategy is particularly effective in environments where engineers are evaluating multiple thermal options before committing to volume tooling. A third approach is qualification leadership in regulated verticals. Companies advancing ESA qualification, ESCC compliance, and UL certification for specialized polyimide heaters are differentiating through documented reliability and the ability to support space and high-performance applications with reduced qualification burden for the buyer.
Recent company-level developments illustrate these dynamics in action. In late 2025, one Italian manufacturer presented validation data on a pure-polyimide flexible heater architecture, including cross-sectional analysis, thermal aging results, cycled life testing, UL 94 V0 certification, and ongoing ESA qualification. Around the same period, the same group showcased flexible heating solutions at a major space commerce event and later presented thermal management systems incorporating flexible heater options at a mobility conference. These activities signal a deliberate push into high-reliability and transportation-adjacent applications where qualification and system-level integration are decisive. In early 2025, a provider of highly customized flexible heaters introduced a high-wattage polyimide heater aimed at medical applications, supporting elevated watt density and higher operating temperatures. Meanwhile, a China-based manufacturer expanded its offerings with a full flexible heater product line spanning polyimide and silicone rubber, removing MOQ constraints, including free design support, and emphasizing rapid delivery for prototyping. Together, these moves highlight a market where leaders are simultaneously advancing performance credentials and broadening access points for design-phase customers.
The competitive landscape is evolving through a combination of specialization and selective convergence. On one side, demand for application-specific qualification and advanced material configurations is encouraging divergence, as manufacturers deepen expertise in targeted verticals rather than competing on generic specifications. On the other side, the entry of lower-friction prototyping and low-MOQ providers is broadening the supplier base at the design stage, increasing pressure on incumbents to clarify their value proposition beyond legacy relationships. The likely outcome is a more layered competitive structure: premium, qualification-heavy suppliers anchoring high-reliability and regulated segments, agile custom manufacturers serving engineering-intensive applications, and accessible providers capturing early design exploration and shorter-run production. Integration activity may increase where scale advantages in materials, testing, and certification can be leveraged, but the market's technical diversity suggests that pure breadth plays will face persistent margin and service-level challenges.
Future Trends and Commercial Implications
Trend 1: Qualification-as-a-Service Becomes a Competitive Differentiator
As regulatory expectations and application-specific qualification requirements become more entrenched, suppliers that can package compliance readiness, testing documentation, and recognized construction standards as part of their offering will gain an advantage in medical, aerospace, and high-reliability industrial applications. Over the next three to five years, this trend will likely intensify as OEMs seek to reduce internal qualification burden and compress time-to-market. The commercial opportunity lies in positioning flexible heating not just as a component but as a qualified subsystem that lowers integration risk. The associated risk is that certification pathways remain fragmented across regions and application categories, creating uneven market access and raising the cost of maintaining multi-jurisdiction compliance.
Trend 2: High-Watt Density and Precision Thermal Control Expand into New Applications
Advances in polyimide and specialty heater architectures are enabling higher watt density and tighter temperature control in compact form factors. This is opening doors in medical instrumentation, advanced electronics processing, and selective automotive thermal management scenarios where rapid thermal response and spatial constraints are critical. The commercial implication is a gradual shift in addressable use cases beyond traditional heating roles, creating incremental growth in segments that previously relied on less flexible thermal solutions. The risk is that performance claims must be substantiated through consistent manufacturing quality and validated life testing, particularly in regulated applications where failure modes carry high consequences.
Trend 3: Lower- friction Entry Models Accelerate Design-Phase Competition
The availability of low-MOQ offerings, free design support, and rapid prototyping pathways is changing how flexible heating solutions are evaluated and selected. Engineering teams are increasingly able to test multiple material and geometry options early in the design cycle, which raises the importance of first-turn responsiveness and design collaboration. For suppliers, this trend expands the top of the funnel but also increases the volume of speculative design activity that must be managed efficiently. The commercial opportunity is to convert early-phase engagement into volume production through reliable execution, consistent quality, and clear scaling pathways. The risk is margin erosion if prototyping convenience is not paired with a credible plan for transitioning customers to higher-volume, cost-optimized production models.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the most effective path is to align product portfolios with application-specific qualification needs and material performance requirements rather than competing solely on breadth. Companies should prioritize documented certification status where regulated verticals are a strategic target, invest in engineering collaboration that reduces integration risk for customers, and maintain a credible low-volume entry point without compromising the economics of scale production. Differentiation will increasingly come from the ability to manage the full arc from prototype to qualified volume production, not from component specification alone.
For investors, the market presents selective opportunities where technical barriers, qualification depth, and application concentration combine to support durable positioning. Capital allocation should favor companies with clear vertical focus, demonstrated compliance capabilities, and operating models that can absorb the cost complexity of advanced materials without relying on undifferentiated volume. Monitoring the pace of certification progression, the emergence of integrated heating-and-sensing offerings, and the extent to which accessible prototyping models convert into recurring production demand will be important indicators of which players are building sustainable advantage.
For procurement and engineering leaders, the priority is to treat flexible heating selection as a system-level decision rather than a component sourcing exercise. Evaluating suppliers on qualification documentation, design support responsiveness, and the ability to scale from prototype to production will reduce downstream integration risk. Where performance requirements justify it, premium material architectures and recognized certifications should be weighed against total lifecycle cost and reliability exposure rather than unit price in isolation. Early engagement with suppliers that can provide both design flexibility and compliant production pathways will shorten qualification timelines and improve launch certainty.
The flexible heating element market is moving toward a more segmented, qualification-aware, and design-integrated future. Companies that understand where performance, regulation, and cost dynamics intersect will be best positioned to capture the next phase of growth. For decision-makers seeking detailed segmentation data, competitive benchmarking, and customized scenario planning across regions and applications, the full research report provides the deeper dataset and structured analysis required to translate these trends into specific organizational actions.
For detailed analysis of this topic, please visit the official page: Flexible Heating Element Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Turbo Expander Market: How 5.5% CAGR and US$530M Scale Redefine 2026-2032 Strategy
By PW Consulting, 2026-09-21
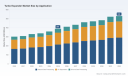
Turbo Expander Market: Strategic Trends and Commercial Opportunities Through 2032
The global turbo expander market is entering a phase of disciplined growth, driven by the convergence of energy efficiency mandates, expanding cryogenic infrastructure, and the relentless push for industrial decarbonization. Estimated at roughly 390 million USD in 2025 and projected to reach approximately 530 million USD by 2032, the sector is on track for a compound annual growth rate of about 5.5 percent across the 2026 to 2032 horizon. This trajectory is not merely a reflection of capacity additions; it signals a structural shift in how industrial gas processing, liquefaction, and energy recovery systems are designed, procured, and operated. For executives and investors, the opportunity lies less in chasing headline volumes and more in understanding where capital is being directed, which technology archetypes are gaining share, and how regulatory and supply chain dynamics are reshaping competitive advantage.
Market Snapshot and Defining Challenges
The turbo expander market has sustained steady expansion over the past half-decade, with revenues climbing from around 302 million USD in 2020 to an estimated 390 million USD in 2025. The forward path points to continued upward momentum, supported by recurring demand in natural gas processing, air separation, and oil and gas processing applications, alongside growing deployment of radial, axial, and hybrid expander configurations across diverse industrial settings. Regional demand is broadly distributed, with meaningful activity concentrated in North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, each reflecting distinct project pipelines and regulatory pressures. Market concentration remains notable, with the top three players accounting for roughly 45 percent of revenue and the top five approaching nearly 70 percent, underscoring the importance of scale, technology credibility, and long-cycle project relationships in a sector where qualification and reliability carry heavy weight.
Beneath this orderly growth profile, several challenges and inflection points are reshaping the playing field.
Material Cost Volatility and Long-Cycle Engineering Constraints
Turboexpanders rely on specialized high-performance alloys and steels for turbine blades and casings, and their supply chains are exposed to global steel producers and commodity price fluctuations. In an environment where input costs can swing and lead times for qualified materials stretch, manufacturers face pressure on margins and project predictability. The challenge is not simply cost containment; it is the ability to maintain engineering consistency, manage qualification cycles, and protect delivery commitments without compromising metallurgical performance. Companies that treat material strategy as a core competency, through dual sourcing, strategic inventory, and design-for-manufacturability initiatives, are better positioned to absorb volatility while preserving margin integrity.
Efficiency-Driven Demand Is Real, but Cycles Remain Project-Dependent
Industrial energy efficiency improvements could account for nearly 40 percent of total emission reductions required to meet global climate goals by 2050, and efficiency mandates such as India’s Perform, Achieve and Trade scheme are accelerating turboexpander adoption in natural gas infrastructure. At the same time, demand for LNG continues to expand, with global LNG demand projected to grow approximately 3.5 percent annually through 2025, reinforcing expander use in liquefaction processes. Yet much of this demand is tied to large, multi-year project cycles and capital allocation decisions that can shift with commodity prices, financing conditions, and policy signals. The practical implication is that volume growth is durable but lumpy; operators and suppliers must plan around execution windows rather than assume smooth quarterly expansion.
Qualification Barriers and the Cost of New Entry
Stringent EU decarbonization plans and carbon cut targets are enforcing the use of energy-recovery technologies like turboexpanders in waste heat and low-carbon applications, which expands the addressable market but also raises the bar for performance verification and integration. In cryogenic and high-pressure gas service, operational reliability, safety certification, and site-specific engineering support are decisive. This creates a meaningful barrier for new entrants and rewards incumbents with proven reference lists, localized service capabilities, and the ability to co-engineer solutions with end users. The market is therefore likely to see selective expansion rather than broad fragmentation, with differentiation emerging through application-specific know-how and lifecycle service rather than price alone.
Core Drivers Shaping the Market
Several interlocking forces explain why the turbo expander market is expanding in this particular shape and where value is likely to concentrate.
Technology Innovation Focused on Efficiency and Integration
Innovation is increasingly oriented around maximizing energy recovery, reducing parasitic losses, and embedding expanders more seamlessly into existing process trains. Radial flow architectures continue to command significant share in high-efficiency recovery scenarios, while axial and hybrid designs are finding niches where flow profiles, space constraints, or multi-stage requirements call for tailored solutions. Advances in blade metallurgy, bearing and sealing systems, and digital monitoring are helping operators extract more value from pressure differential energy and improve uptime. For manufacturers, the strategic question is which technology platform can be adapted across multiple applications without sacrificing performance, and how quickly new configurations can be qualified for demanding service.
Policy and Regulatory Tailwinds Reshaping End-User Priorities
Regulatory pressure is moving turboexpanders from optional efficiency upgrades toward core infrastructure considerations in several regions. Energy efficiency mandates are accelerating adoption in natural gas networks and processing facilities, while EU decarbonization targets are reinforcing demand for energy-recovery technologies in waste heat and low-carbon applications. These policies do more than expand demand; they change the decision criteria for buyers, placing greater weight on verified efficiency gains, emissions reduction, and long-term operating cost savings. Suppliers that can articulate and document those outcomes, supported by reference projects and transparent performance data, are better positioned to win tenders and influence specification standards.
Demand-Side Shifts Toward Energy Recovery and Flexible Gas Infrastructure
End users are increasingly treating pressure-energy recovery as a source of incremental power and operational resilience rather than a one-off retrofit. The commissioning of a 500kW turboexpander at a natural gas regulating station, followed by operating agreements to deploy similar systems across additional sites, illustrates how energy recovery is being normalized within gas network operations. In cryogenic and industrial gas contexts, air separation and natural gas processing continue to anchor demand, while new use cases in LNG, hydrogen, and geothermal applications are broadening the technology’s footprint. The broader trend is toward modular, application-specific solutions that can be integrated with lower disruption and faster payback, especially where facilities seek to improve throughput and reduce emissions without full-scale plant rebuilds.
Supply Chain Realities and Cost Structure Dynamics
The cost structure of turboexpanders is influenced by specialized materials, precision machining, testing requirements, and the cost of qualification support. As commodity prices fluctuate and high-performance alloy supply chains remain globally distributed, manufacturers must manage both input costs and the indirect costs of engineering change, rework, and delivery risk. At the same time, consolidation among suppliers of components and services can create opportunities for more stable procurement and integrated design, provided companies negotiate from a position of technical clarity and volume predictability. The most resilient operators are those that align design choices with manufacturability, secure qualified material pathways, and treat supply chain resilience as a product attribute rather than a back-office concern.
Competitive Landscape and Leading Strategies
The competitive set is broad and geographically diverse, spanning established industrial groups, cryogenic specialists, and application-focused innovators. Atlas Copco, Cryostar, Air Products and Chemicals, Baker Hughes, Chart Industries, Siemens Energy, Elliott Group, Nikkiso ACD, R&D Dynamics Corporation, Turbogaz, L.A. Turbine, Turboden, Sapphire Technologies, MAN Energy Solutions, PBS Group, and Hangyang Group each bring distinct strengths to the market, from centrifugal and radial flow platforms to in-line energy recovery systems and cryogenic turboexpanders for industrial gases and LNG. What differentiates leaders is not merely product breadth, but the ability to pair technology credibility with project execution, service access, and increasingly, energy-recovery value propositions that align with customer efficiency goals.
Strategic Positioning Among Incumbents
Several incumbents are reinforcing their positions through portfolio expansion and targeted capability acquisitions. Atlas Copco, for example, expanded its gas compression and energy-efficiency portfolio through the acquisition of Haizea and MSS Nitrogen, a move that broadens its reach across compression and gas-related applications while strengthening its ability to offer integrated efficiency solutions. Baker Hughes and Chart Industries continue to leverage their presence in LNG, natural gas processing, and hydrocarbon processing to position turboexpanders as part of larger process and energy recovery systems. Siemens Energy and MAN Energy Solutions maintain a strong footing in industrial and LNG applications, where scale, engineering support, and long-cycle relationship depth matter. In cryogenic industrial gases, companies such as Nikkiso ACD and PBS Group emphasize specialized expander technology for air separation and gas processing, where metallurgical performance and reliability are central.
Turbocharger Market
Innovation and Financing as Growth Enablers
Beyond incumbents, a layer of innovators is shaping the market through application-specific designs and new financing pathways. Sapphire Technologies closed a Series C round with participation from Mitsubishi Heavy Industries, Equinor Ventures, Cooper and Company, and Energy Capital Ventures, signaling investor confidence in in-line radial turboexpanders for natural gas energy recovery and power generation. In parallel, Anax Power commissioned its inaugural 500kW turboexpander at a natural gas regulating station and subsequently signed operating agreements with Enbridge to deploy its turboexpander system in Pennsylvania and Ontario. These moves illustrate a broadening of the commercial model: technology providers are not only selling hardware, they are increasingly building deployment partnerships, financing alliances, and site-specific demonstration pathways that reduce buyer risk and accelerate adoption.
Evolution of the Competitive Map
Market concentration suggests a landscape that favors scale and track record, yet it is not static. Consolidation among larger players is likely to continue where it creates synergies in engineering, service, and geographic coverage, particularly in LNG and large-scale gas processing. At the same time, niche differentiation is expanding around energy recovery, modular deployment, and digital monitoring, where agile companies can win on performance and integration rather than on size alone. The emergence of new financing and partnership models also creates openings for companies that can combine proven hardware with credible project economics. Expect the competitive map to remain concentrated at the top while becoming more multi-dimensional in the middle, with value shifting toward those who can deliver measurable efficiency gains and lifecycle support across varied applications.
Outlook: Three Trends to Watch Over the Next Three to Five Years
Looking ahead, the most consequential developments will likely be found at the intersection of technology deployment, policy reinforcement, and commercial model evolution.
Worldwide Permanent Magnet Turbo Blower Market
Energy Recovery Moves from Niche to Standard Practice
As efficiency mandates strengthen and LNG and gas infrastructure continue to expand, in-line and integrated turboexpanders are poised to become more routine in natural gas networks, processing facilities, and selected cryogenic applications. The commercial logic is straightforward: pressure differential energy that was once wasted can be converted into useful power or process support, improving unit economics and reducing emissions intensity. The opportunity for suppliers is to standardize proven configurations while retaining enough application flexibility to fit diverse site conditions. The risk is execution: if deployment scales faster than qualification and service capacity, integration quality and reliability could become slippage points. Companies that invest early in field support, modular design, and performance verification will be better placed to capture this wave.
Integration With LNG, Hydrogen, and Industrial Decarbonization Pipelines
Turboexpanders are increasingly embedded in broader decarbonization and gas-infrastructure strategies, particularly where LNG, hydrogen, and industrial energy efficiency goals intersect. The International Energy Agency’s emphasis on industrial energy efficiency as a major contributor to emission reductions, combined with EU decarbonization pressure and national efficiency schemes, creates a policy backdrop that rewards technologies offering verifiable efficiency and recovery benefits. For executives, the implication is that turboexpander decisions are becoming part of larger capital and sustainability planning. Suppliers that can connect expander performance to plant-level efficiency targets, emissions reporting, and operational flexibility will have an advantage in specification discussions and long-term partnerships. The uncertainty lies in the pace and coherence of policy implementation across regions, which can affect project timing even when the technical case is strong.
Differentiation Through Service, Digitalization, and Lifecycle Value
As the market matures, competition is likely to shift further toward lifecycle performance, monitoring, and service responsiveness. Digital condition monitoring, predictive maintenance, and integration with plant control systems can improve uptime and help operators realize the efficiency gains that justified the investment in the first place. In a market with notable concentration among leading players, service quality and technology support can be as important as initial hardware specifications. The strategic opportunity is to design products and service offerings that reduce total cost of ownership and make efficiency outcomes measurable over time. The caveat is that digital and service promises must be matched by field-proven reliability and realistic performance baselines; overpromising on intelligence or savings can erode trust quickly in high-stakes industrial environments.
Actionable Guidance for Decision Makers
For manufacturers, investors, and procurement professionals, the current landscape rewards deliberate positioning over reactive participation. A few priorities stand out.
For Manufacturers and Technology Providers
Focus on application portfolios that combine recurring demand with measurable efficiency outcomes. Radial and hybrid platforms that can be adapted across natural gas processing, air separation, and energy recovery applications offer scale potential, but the differentiator will be how quickly and credibly a supplier can qualify new configurations, support site integration, and prove lifecycle value. Strengthening material supply resilience, investing in modular and application-specific designs, and building demonstrable reference projects will help protect margin and win specification influence. It is equally important to align product messaging with the outcomes that matter to buyers today: verified efficiency improvement, emissions reduction, uptime, and integration risk reduction.
For Investors
Prioritize business models that combine hardware credibility with scalable deployment and service economics. The market’s concentration and qualification barriers favor players with proven reference lists, but growth is also coming from energy-recovery innovators and partners that can de-risk adoption through financing, demonstration, and operating agreements. When evaluating opportunities, look for evidence of repeatable project economics, durable customer relationships, and a clear path to expanding within LNG, industrial gas, and efficiency-driven gas infrastructure applications. Be mindful of the cyclicality embedded in large project pipelines and the sensitivity of margins to specialized materials and lead times; businesses that manage those inputs with discipline are more likely to convert market growth into sustainable returns.
PW Consulting
Strategic positioning is also evolving through partnerships and targeted acquisitions, as seen in recent portfolio expansions and financing rounds across the sector. Investors should track not only revenue trajectories but also the pace of capability-building, regional deployment progress, and the credibility of efficiency claims in real operating environments. Companies that can turn technology into measurable operational value, while maintaining disciplined execution, are best placed to capture the upside from efficiency mandates and expanding cryogenic and gas-processing demand.
For Procurement and Operations Leaders
Treat turboexpander selection as a lifecycle decision rather than a component purchase. Define performance criteria around efficiency recovery, reliability in site-specific conditions, service responsiveness, and total cost of ownership, and validate those criteria with reference cases that resemble your operating environment. Where possible, favor modular, application-specific solutions that minimize integration disruption and shorten payback, and require clear documentation of efficiency outcomes and maintenance expectations. Given material cost volatility and project cycle lumpiness, building flexibility into specifications and qualification pathways can reduce execution risk while preserving performance standards. For organizations planning multiple deployments, exploring operating partnerships and standardized configurations can improve consistency and lower integration cost over time.
Closing Perspective
The turbo expander market is not expanding simply because more equipment is being ordered; it is evolving because efficiency, decarbonization, and gas infrastructure needs are converging around technologies that recover and reuse pressure energy with increasing reliability. The growth path to 2032 reflects that shift, and the companies that will capture the most value are those that can align technology, qualification, service, and commercial models with the outcomes buyers are now prioritizing. For executives and investors, the practical next step is to narrow the focus from broad market growth to the specific applications, regions, and commercial structures where that growth is most actionable. Detailed segmentation data, company-level benchmarks, and tailored strategic recommendations can sharpen that view further and support more confident capital and procurement decisions.
For detailed analysis of this topic, please visit the official page: Turbo Expander Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
IVC Filters Market to Reach $212M by 2032: Why 9.4% CAGR Signals a Strategic Shift
By PW Consulting, 2026-09-21
The Inferior Vena Cava Filter Market: Strategic Trends and Commercial Opportunities in a High-Growth Landscape
The Inferior Vena Cava (IVC) Filter Market has entered a phase of accelerated expansion, driven by a convergence of epidemiological shifts, technological maturity, and evolving clinical protocols. As of 2025, the global market valuation stands at approximately 113.0 million USD, reflecting a compound annual growth rate of 9.4 percent across the forecast horizon extending to 2032. Historical trajectories from 2020 through 2025 demonstrate consistent upward momentum, with revenues climbing from 72.0 million USD to the current baseline, signaling sustained adoption and procedural volume increases. Looking forward, the market is projected to surpass 212.0 million USD by the end of the forecast period in 2032. Such financial expansion underscores a structural shift in how venous thromboembolism and pulmonary embolism prevention are managed, particularly as minimally invasive vascular interventions continue to gain procedural preference over pharmacological monotherapy in high-risk cohorts. For executives and investors, this trajectory signals more than incremental revenue growth; it points toward a market undergoing redefinition through product innovation, regulatory scrutiny, and procurement evolution. Understanding the mechanics behind this expansion is essential for positioning portfolios, allocating capital, and shaping commercialization strategies in a space where clinical credibility and supply chain reliability are becoming decisive competitive moats.
Current Landscape and Core Challenges
Despite robust top-line growth, the industry is navigating a set of interconnected challenges that will shape competitive outcomes over the next several years. The first and most pressing is the intensifying regulatory and litigation environment surrounding retrievable filter safety and retrieval compliance. Decades of clinical use have produced a well-documented awareness of migration, fracture, and perforation risks, which has translated into heightened post-market surveillance expectations and a persistent volume of multidistrict litigation. As of mid-2026, more than 6,500 pending cases remain active against major manufacturers related to IVC filter complications, reinforcing the cost of quality, traceability, and post-market evidence generation. For companies operating in this space, risk management has moved from a compliance function to a strategic imperative that influences procurement decisions, hospital formulary inclusion, and insurance liability considerations.
The second challenge lies in balancing clinical adoption with appropriate retrieval practices. Regulatory bodies have repeatedly emphasized timely removal of retrievable filters once the acute risk of pulmonary embolism has subsided, yet real-world retrieval rates often lag behind clinical intent due to patient follow-up fragmentation, procedural scheduling constraints, and institutional workflow limitations. This gap between guideline expectations and bedside execution creates both a clinical liability and a commercial friction point: products that simplify retrieval, reduce procedural time, or offer convertible design features gain meaningful differentiation in an environment where retrieval compliance is increasingly measured and scrutinized.
PW Consulting Automotive & Machinery Research Center
The third challenge emerges from the supply chain and cost structure dynamics governing interventional vascular devices. While reimbursement frameworks provide baseline facility payment references, including facility Medicare payments for intravascular vena cava filter insertion, hospitals and health systems are under continuous margin pressure to optimize procedural efficiency and reduce total cost of care. Device complexity, introducer system reliability, and procedural duration directly influence operating room throughput and clinical satisfaction. Any resistance in device delivery, sheath navigation, or retrieval mechanics can translate into operational delays, resource reallocation, and downstream cost impacts. In this context, manufacturers must align engineering performance not only with clinical efficacy but also with the economic realities of high-volume procedural environments.
Blood Filter Market
Key Drivers of Market Change
Multiple interconnected forces are propelling the IVC filter market beyond its historical baseline. These drivers are reshaping product roadmaps, influencing procurement criteria, and clarifying where long-term value will accrue.
Technological Innovation and Design Breakthroughs
Product engineering continues to be a primary catalyst for market evolution. The dominance of retrievable filter architectures in current usage reflects a broader clinical preference for devices that can be deployed as temporary protective measures and removed once the risk window closes. At the same time, next-generation retrieval technologies are altering the risk-reward calculus for difficult removals. The regulatory classification of laser-powered IVC filter retrieval catheters into class II with special controls marks an important milestone, formalizing a category that was previously positioned for failure cases where conventional methods were insufficient. This classification is not merely an administrative event; it creates a regulated pathway for advanced retrieval tools, broadens the clinical toolkit for complex extractions, and opens commercial avenues for companies developing adjunctive systems that support safer, faster, and more controlled filter removal. For manufacturers, the opportunity lies in designing filter platforms that integrate smoothly with evolving retrieval accessories and in developing proprietary extraction or repositioning systems that reduce procedural friction and improve physician confidence.
Policy and Regulatory Environment
Regulatory communication and classification decisions have exerted a long-running influence on the market and continue to do so. Earlier safety communications encouraging timely retrieval of retrievable filters have reshaped expectations around device lifecycle management and institutional oversight. More recently, the formal classification of laser-based retrieval catheters reinforces the regulatory direction toward risk-based controls and evidence-supported special controls. Such actions signal that the market is moving toward more explicit post-market obligations, including device tracking, retrieval documentation, and real-world performance monitoring. This trajectory affects not only product design and labeling but also commercial operations, as manufacturers must demonstrate robust quality systems, adverse event responsiveness, and traceability across the device lifecycle. In parallel, reimbursement structures remain a structural enabler of procedural volume, but they also impose expectations for efficiency and predictable outcomes. The interplay between reimbursement clarity and regulatory stringency is shaping which product categories gain formulary preference and how hospitals balance clinical utility against liability and workflow considerations.
Demand-Side Shifts in Clinical Behavior
Clinician and institutional behavior is evolving in response to both clinical evidence and operational realities. The preference for retrievable filters underscores a strategy of temporary protection in patients who may not require permanent mechanical filtration, while also reflecting the need for adaptable solutions in patients with evolving anticoagulation status or uncertain duration of risk. At the same time, institutions are increasingly focused on procedural standardization and complication reduction. Devices that offer consistent deployment characteristics, predictable filtering performance, and retrieval-friendly configurations are gaining favor because they reduce procedural variability and support protocol-driven care. Another demand-side development is the growing attention to convertible and repositionable designs, which allow procedural adjustments during deployment and can ease the clinical burden associated with suboptimal initial placement. In hospital procurement, these attributes matter because they influence case time, physician training requirements, and post-procedure management load. As centers seek to streamline interventional workflows while maintaining patient safety standards, device simplicity, reliability, and retrieval compatibility are becoming central evaluation criteria.
Supply Chain and Cost Structure Considerations
Cost dynamics in the IVC filter market are increasingly influenced by total procedural economics rather than unit device price alone. Hospitals evaluate devices through the lens of operating room efficiency, ancillary consumable usage, complication-related costs, and retrieval logistics. A device that delivers reliable delivery system performance and minimizes introducer resistance, for example, supports smoother procedural flow and reduces the likelihood of delays or vein-related complications that can escalate care complexity. Conversely, product issues that introduce procedural resistance or increase the risk of vascular injury can have disproportionate cost consequences, undermining both clinical outcomes and institutional efficiency metrics. Supply chain resilience also matters as manufacturers must ensure consistent availability of both primary filters and retrieval accessories, particularly as advanced removal technologies become more embedded in standard practice. Companies that can integrate device and retrieval system offerings into a coherent procedural solution, while maintaining stable production and distribution capabilities, are better positioned to meet procurement expectations in cost-sensitive environments.
Competitive Landscape and Leading Strategies
The market structure is characterized by meaningful concentration among established players, yet competitive advantage is increasingly defined by product differentiation, procedural reliability, and lifecycle management rather than scale alone. Leading manufacturers have built portfolios around retrievable filter platforms, convertible designs, and retrieval-compatible systems, with individual companies emphasizing distinct clinical narratives and engineering strengths.
Strategic Positioning and Differentiation
Cook Medical remains a prominent reference point in the market, anchored by retrievable filter offerings such as the Celect Platinum and the Günther Tulip filter. Its commercial strength has been linked to broad procedural familiarity and a long track record in the space, though its market standing is simultaneously shaped by ongoing litigation associated with filter complications. For competitors, this environment underscores the strategic value of proactive retrieval compatibility, transparent post-market data, and design features that reduce long-term risk profiles. Becton, Dickinson and Company (BD) has emphasized its Denali filter platform, reflecting a strategy aligned with large-scale commercial infrastructure and integration within broader interventional portfolios. Argon Medical Devices, Inc. has focused on its Option Elite retrievable vena cava filter system, positioning itself around retrieval functionality and procedural versatility. Cordis Corporation, operating within Cardinal Health, has maintained presence through retrievable and permanent filter lines such as the OptEase and TrapEase platforms, emphasizing established product heritage in multiple filter categories. B. Braun Interventional Systems, Inc. offers convertible and lower-profile filter options through its VenaTech line, highlighting design flexibility and deployment adaptability. ALN Implants Chirurgicaux contributes a European-origin perspective with optional filter systems and associated extraction and repositioning capabilities, reinforcing a strategy centered on retrieval enablement and procedural control.
Central Venous Catheters Market
Across these players, differentiation is emerging around several axes: retrieval compatibility, delivery system performance, convertible or repositionable features, and the breadth of ancillary systems that support filter removal and repositioning. Companies that treat the filter as part of an end-to-end procedural workflow, rather than a standalone implant, are building more defensible positions in a market where retrieval compliance and procedural reliability are increasingly central to clinical and procurement evaluation.
Market Evolution and Consolidation Dynamics
The competitive landscape is likely to evolve through selective consolidation, portfolio rationalization, and targeted innovation rather than pure volume expansion. As regulatory expectations rise and retrieval-related technologies mature, smaller or narrowly focused players may face pressure to demonstrate differentiated clinical value, robust quality systems, and reliable supply. At the same time, established manufacturers may pursue complementary capabilities in retrieval, imaging support, or procedural accessories to strengthen integrated offerings. There is also room for new entrants that bring specialized retrieval technologies, advanced delivery mechanics, or novel materials that improve long-term compatibility and reduce complication risk. However, entry barriers remain meaningful because the market rewards regulatory experience, post-market surveillance infrastructure, and established clinician relationships. For incumbents, the strategic priority is to convert product familiarity into procedural value propositions that explicitly address retrieval, reliability, and total cost of procedural care. For challengers, the opportunity lies in solving specific pain points that broader portfolios have not fully addressed, particularly in difficult retrieval scenarios and delivery consistency.
Future Trends and Commercial Implications
Looking ahead over the next three to five years, several trends are likely to shape the direction of the market and define where commercial value will concentrate. These trends do not merely extend existing growth; they change the metrics by which success is measured.
Retrieval-Centric Product Architecture as a Baseline Expectation
As retrieval compliance becomes more closely monitored and retrieval technologies become more established, filter design will increasingly be judged through the lens of how easily and safely a device can be removed. Retrievable filters will continue to dominate usage, but the differentiating question will shift from whether a filter is retrievable to how predictable, efficient, and low-risk retrieval is in real-world settings. This will favor designs that support smoother sheath navigation, reduce mechanical resistance, and integrate with advanced retrieval tools when conventional removal is insufficient. For manufacturers, the commercial implication is clear: retrieval efficacy and procedural simplicity will become core value propositions rather than secondary features. For hospitals, this trend reinforces procurement criteria that prioritize devices capable of supporting standardized retrieval protocols and minimizing complication-related follow-up costs. The associated risk is that products with weaker delivery or retrieval performance may face growing clinical skepticism, formulary exclusion, or liability exposure if complications or procedural delays emerge.
Advanced Retrieval Technologies and Adjacent Market Expansion
The formalization of laser-based retrieval catheter classification points toward broader adoption of adjunctive removal technologies, particularly for cases where conventional techniques are challenged by endothelial incorporation or structural complexity. As these technologies become part of accepted clinical pathways, they create opportunities for companies offering complementary devices, training, procedural support, and bundled solutions. The commercial upside extends beyond the filter itself to the surrounding ecosystem of retrieval accessories, procedural optimization tools, and service models that support complex interventions. However, this trend introduces uncertainty around reimbursement allocation, clinical adoption variability, and the need for robust training and documentation. Companies that can demonstrate safety, efficiency, and procedural cost reduction in difficult retrieval scenarios are more likely to capture value, while those that enter without clear clinical differentiation or risk documentation may find adoption constrained by hospital procurement caution.
Evidence Generation, Post-Market Transparency, and Procurement Rigor
The combination of ongoing litigation, regulatory communication history, and class-based device controls is increasing the premium on evidence generation and post-market transparency. Institutions and procurement teams are likely to place greater weight on real-world performance data, retrieval documentation, adverse event responsiveness, and quality system credibility. This creates a strategic expectation for manufacturers to maintain comprehensive post-market programs, support clinical registries or real-world evidence initiatives, and communicate device lifecycle management clearly. For investors and executives, the trend implies that brand trust and data credibility will increasingly influence market share dynamics, especially in a concentrated market where a few players hold a large share of revenue. The risk side of this trend is that any reputational or compliance gap can have outsized effects in a market where clinical safety narratives are closely watched and where procedural liability concerns are already elevated.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align product development with retrieval compatibility, delivery reliability, and procedural transparency. Investment in filter platforms should be evaluated not only by implantation performance but also by removal ease, integration with retrieval accessories, and the robustness of post-market surveillance. Companies should also examine opportunities to bundle filters with repositioning or extraction systems where such integration reduces procedural friction and supports compliance with timely retrieval expectations. In parallel, supply chain discipline and consistent availability of both primary devices and retrieval components should be treated as competitive differentiators in settings where procedural efficiency directly impacts hospital economics.
For investors, the market offers growth potential, but valuation and risk assessment must account for regulatory, litigation, and execution dynamics. The strongest opportunities are likely to emerge from companies with differentiated retrieval capabilities, credible post-market data programs, and clear strategies for navigating class-based device controls and reimbursement realities. Due diligence should consider not only revenue momentum but also device lifecycle management, complication-related risk exposure, and the capacity to sustain reimbursement alignment while expanding into adjacent retrieval technologies. Diversification across filter categories and retrieval-supporting portfolios can reduce dependence on any single product narrative, particularly in a market where clinical reputation and procedural reliability are tightly linked to commercial outcomes.
For procurement teams and health system leaders, device evaluation should increasingly incorporate retrieval workflow, procedural reliability, and total cost implications rather than unit pricing alone. Questions to explore include how consistently a device delivers without excessive resistance, how retrieval complexity is managed, how the manufacturer supports post-market documentation and adverse event responsiveness, and how the device performs within institutional protocols for timely removal. Preference for products that reduce variability and support standardized retrieval pathways can help lower downstream complication costs and improve procedural predictability. At the same time, procurement strategies should account for supply continuity and the need for training support as advanced retrieval tools become more integrated into clinical practice.
For stakeholders seeking a deeper, segment-level view of market sizing, regional dynamics, product category splits, application patterns, competitive benchmarks, and customized scenario planning, the full PW Consulting research report provides a more granular analytical foundation. The complete study extends the discussion beyond the strategic overview presented here and offers detailed data structures, forecasting detail, and tailored recommendations designed to support operational planning and investment decisions in a market where clinical credibility and procedural efficiency are becoming the decisive dimensions of long-term competitive advantage.
For detailed analysis of this topic, please visit the official page: Inferior Vena Cava (IVC) Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vitamin A Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global Vitamin A market has demonstrated consistent growth over the past five years, expanding from approximately 520 million USD in 2020 to an estimated 665 million USD in 2025. This trajectory reflects a compound annual growth rate of roughly 5.5 percent through the 2026 to 2032 forecast period, positioning the market to approach nearly 970 million USD by the end of the decade. The steady expansion is underpinned by broad demand across nutrition, feed, and fortification applications, yet the industry is navigating a period of structural transition that demands strategic attention from market participants.
One of the most pressing challenges lies in the evolving regulatory and trade landscape. Recent policy shifts in major economies have introduced both protections and constraints for vitamin supply chains. The exemption of Vitamin A from new U.S. tariffs and reciprocal duties under Annex II of recent executive orders has insulated producers from cost volatility that has affected other commodity categories. At the same time, extended regulatory shutdowns at key production facilities, particularly the vitamin A precursor plant in Ludwigshafen, Germany, have constrained EU-origin supply and elevated prices among established suppliers. These dynamics create a fragmented operating environment where regional availability and pricing stability are no longer guaranteed.
A second challenge centers on the tension between natural and synthetic product segments. The market is split between natural Vitamin A sources and synthetic variants, with synthetic products accounting for a larger share of overall revenue. This division is not merely a matter of preference; it reflects deeper questions about sourcing sustainability, consumer perception, and formulation performance. Natural carotenoid-derived Vitamin A has gained traction in food, beverage, and dietary supplement applications, while synthetic forms continue to dominate in animal nutrition and industrial fortification. Companies must navigate the strategic implications of this bifurcation as downstream customers increasingly seek transparency and differentiation in their ingredient portfolios.
The third significant challenge is market concentration. A relatively small group of manufacturers commands a disproportionate share of the market, creating both stability and vulnerability. While concentrated supply ensures quality consistency and technical expertise, it also amplifies the impact of production disruptions, capacity constraints, or strategic decisions by a handful of firms. Buyers and investors alike must account for this concentration when evaluating supply resilience and long-term pricing dynamics.
PW Consulting
Key Growth Drivers
Several interconnected forces are shaping the direction of the Vitamin A market and creating distinct pathways for value creation.
Technological Innovation and Product Formulation
Advancements in microencapsulation and combined formulation technologies are redefining how Vitamin A is delivered across applications. Recent product launches illustrate this shift. A next-generation microencapsulated combined Vitamin A and D3 formulation has been introduced with an extended shelf life under standard storage conditions, addressing long-standing stability challenges in animal nutrition. Such innovations reduce waste, improve handling efficiency, and enable more precise dosing, which in turn supports adoption in cost-sensitive feed markets while also opening doors in human nutrition where stability and bioavailability are critical.
Beyond microencapsulation, the broader trend toward tailored vitamin formulations is gaining momentum. Manufacturers are increasingly moving from commoditized bulk vitamin supply toward value-added solutions that address specific application requirements, whether that means enhanced heat stability, improved mixing characteristics, or compatibility with complex feed matrices. This shift encourages differentiation and supports margin preservation in a market where basic vitamin ingredients face periodic pricing pressure.
Regulatory and Policy Environment
The regulatory backdrop is a decisive factor in market dynamics. The exemption of Vitamin A from recent U.S. tariff actions, including 20 percent duties under specific statutory provisions, has preserved cost stability for producers and downstream users. Most key vitamins, including Vitamin A and a broad range of B-complex and other essential nutrients, are fully exempt from these duties under relevant sections of recent trade policy directives. This exemption reduces the risk of supply chain disruption and supports uninterrupted production scheduling for feed, food, and pharmaceutical applications.
Vitamin D Market
However, regulatory divergence across regions introduces complexity. The extended regulatory shutdown at a major German production site has constrained EU-origin supply, pushing buyers to reconsider sourcing strategies and inventory planning. Such disruptions underscore the importance of regulatory monitoring and the need for flexible procurement models that can adapt to shifting compliance timelines and regional availability.
Demand-Side Shifts in Consumer and Corporate Behavior
Demand patterns are evolving as consumer awareness of nutrition and wellness continues to rise, particularly in food and beverage and dietary supplement categories. Fortification trends are expanding beyond traditional staples into functional foods, beverages, and specialized supplement formats, where Vitamin A plays a supporting role in product positioning and nutritional labeling. In animal feed, the drive for efficient livestock production and balanced nutrition sustains steady demand, while also pushing formulators toward combined vitamin solutions that streamline inclusion rates and improve overall feed performance.
Corporate behavior is also shifting toward greater supply chain resilience. Buyers are increasingly prioritizing suppliers who can offer consistent quality, transparent sourcing, and contingency options. This preference favors established manufacturers with diversified production footprints and technical service capabilities, while also creating openings for newer entrants that can address niche requirements or regional demand gaps.
Supply Chain and Cost Structure Dynamics
Cost structures in the Vitamin A market are influenced by raw material availability, energy inputs, and the geographic concentration of manufacturing capacity. The exemption of Vitamin A from recent tariff pressures has provided a degree of protection, but other cost factors remain in play. Energy costs, logistics constraints, and the operational status of key precursor plants all contribute to pricing variability. The continued shutdown at the Ludwigshafen facility, for example, has elevated prices among established suppliers and reinforced the strategic importance of alternative sourcing routes.
Supply chain resilience is increasingly tied to the ability to manage multi-regional production and distribution. Companies that can balance capacity across regions, maintain buffer inventory where appropriate, and align formulation strategies with regional regulatory realities are better positioned to navigate cost volatility and supply interruptions.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of large-scale synthetic vitamin producers, specialized natural ingredient suppliers, and regional manufacturers with growing international reach. The market is moderately concentrated, with a small group of firms accounting for a significant portion of total revenue. This structure rewards scale, technical capability, and the ability to serve multiple application segments.
Strategic Positioning of Key Players
BASF SE, headquartered in Ludwigshafen, Germany, maintains a leading position in synthetic Vitamin A production for animal nutrition and human fortification. Its recent focus on combined microencapsulated formulations, including a next-generation Vitamin A and D3 product with extended shelf life, reflects a strategy oriented toward formulation differentiation and application-specific performance. By investing in dedicated formulation capabilities within its Verbund site, BASF is reinforcing its role as a solutions provider rather than a commodity supplier.
DSM-Firmenich AG, based in Delft, Netherlands, operates as a major supplier of Vitamin A and derivatives across nutrition and feed applications. The company maintains active portfolio management and market updates, signaling a strategy that emphasizes responsiveness to market conditions and regulatory developments. Its presence across multiple downstream categories supports diversification and provides visibility into shifting demand patterns.
Vitamin Market
Bluestar Adisseo Company, headquartered in Shanghai, China, is a key manufacturer of synthetic Vitamin A products for global feed and food markets. Its strategic value lies in its ability to serve large-volume demand while navigating regional production dynamics. As Asian demand continues to grow, manufacturers with strong regional footprints and export capabilities play an increasingly important role in balancing global supply.
Fenchem Biotek Ltd., also based in China, is an active producer of Vitamin A and related ingredients for industrial and nutritional applications. Its positioning reflects the broader trend of regional manufacturers expanding their ingredient portfolios and seeking integration into global supply chains.
Lycored Ltd., headquartered in Israel, supplies natural carotenoid-derived Vitamin A for food, beverage, and dietary supplement markets. Its focus on natural sourcing aligns with growing consumer and brand preferences for clean-label and traceable ingredients, differentiating it from synthetic-focused competitors and creating niche opportunities in premium fortification and supplement applications.
Market Evolution and Emerging Dynamics
The competitive landscape is evolving along several axes. Integration among large-scale producers continues to reinforce scale advantages in synthetic vitamin production, while differentiation is increasingly driven by formulation technology, application expertise, and regional supply reliability. At the same time, natural ingredient suppliers are carving out distinct positions by addressing demand for transparency and plant-based or carotenoid-derived alternatives.
New entrants and regional manufacturers are gaining relevance where they can offer cost-competitive supply, localized service, or specialized product attributes. However, the concentrated nature of the market means that new entrants must navigate barriers related to production scale, regulatory compliance, and customer qualification processes. The result is a market that rewards both scale and specificity, with successful players often combining broad application coverage with targeted technical differentiation.
Future Trends and Commercial Opportunities
Looking ahead to the 2026 to 2032 period, several trends are likely to shape the Vitamin A market and its commercial opportunities.
Trend One: Formulation-Led Differentiation Will Intensify
As basic vitamin ingredients face periodic pricing pressure and supply variability, the value shift toward tailored formulations is expected to deepen. Microencapsulation, combined vitamin products, and application-specific stabilizers will become more central to competitive positioning. Manufacturers that can offer formulations with extended shelf life, improved stability under processing conditions, and easier integration into feed or food matrices will capture incremental value and strengthen customer loyalty. This trend creates opportunities for suppliers to move up the value chain and for buyers to reduce total cost of ownership through improved performance and reduced waste.
Trend Two: Regional Supply Rebalancing and Sourcing Flexibility
Regulatory disruptions and production constraints in key regions are likely to accelerate efforts to rebalance supply across geographies. Buyers will increasingly seek multi-source strategies, regional inventory buffers, and supplier partnerships that provide continuity during compliance or operational interruptions. This rebalancing favors manufacturers with diversified production footprints and transparent supply chain practices. It also creates opportunities for regional producers to strengthen their role in global supply networks, particularly where they can offer reliable quality and responsive service.
Trend Three: Natural and Synthetic Segments Will Continue to Coevolve
The coexistence of natural and synthetic Vitamin A segments will remain a defining feature of the market. Natural carotenoid-derived options will continue to find traction in consumer-facing applications where clean-label positioning and traceability matter. Synthetic forms will retain strength in high-volume feed and industrial fortification markets where cost efficiency and performance consistency are paramount. The commercial opportunity lies in understanding where each segment adds the most value and in building portfolios or sourcing strategies that align with downstream customer priorities.
Risks and Uncertainties
Several uncertainties warrant attention. Extended regulatory shutdowns or new compliance requirements at major production sites could further constrain supply and elevate pricing. Trade policy changes, while currently favorable for Vitamin A through tariff exemptions, remain subject to revision and could introduce new cost dynamics if exemptions are altered. Demand shifts in animal feed, driven by livestock market conditions or alternative nutrition strategies, could affect volume growth in key segments. Finally, the concentrated supplier base means that strategic decisions by a small number of firms can have outsized effects on availability and pricing, requiring buyers and investors to maintain contingency planning and diversified sourcing approaches.
Actionable Insights for Decision-Makers
For manufacturers and suppliers, the priority is to strengthen differentiation through formulation capability and application expertise. Investing in microencapsulation, combined vitamin products, and stability-enhancing technologies can support margin resilience and customer retention. Equally important is the development of flexible supply strategies that account for regional regulatory dynamics and production variability, ensuring continuity for downstream customers even when specific sites face constraints.
For investors, the market offers steady growth supported by broad demand across nutrition, feed, and fortification, but success will depend on selecting players with scalable production, regulatory agility, and the ability to serve multiple application segments. Concentration in the supplier base creates both reliability and vulnerability, making it essential to evaluate each company's production footprint, formulation pipeline, and exposure to regional disruptions. Long-term value creation is likely to accrue to firms that combine scale with differentiated product capabilities and resilient sourcing models.
For procurement and formulary decision-makers, the key is to balance cost efficiency with supply resilience. Diversifying across suppliers and regions, aligning specification requirements with realistic supply conditions, and engaging suppliers early on formulation and stability needs can reduce exposure to price spikes and availability gaps. Understanding the regulatory status of Vitamin A in key markets, including its exemption from recent tariff actions, helps inform sourcing decisions and inventory planning. Maintaining visibility into production status at major sites and monitoring regulatory developments will support more proactive procurement strategies.
For organizations seeking a deeper understanding of regional demand patterns, application-level dynamics, and customized sourcing or investment scenarios, detailed market intelligence can provide the granularity needed to translate these trends into executable plans. Comprehensive research encompassing segmentation data, competitive assessments, and scenario-based forecasting offers a practical foundation for strategic planning and risk management in a market defined by both steady growth and evolving structural complexity.
For detailed analysis of this topic, please visit the official page: Vitamin A Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com