



Category: market research
Barbituric Acid Market to Hit USD 25.5M by 2032 at 4.6% CAGR — PW Consulting
By PW Consulting, 2026-07-12
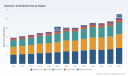
Barbituric Acid Market 2026: Strategic Preview for Decision-Makers
As companies prepare strategic roadmaps for 2026, the Barbituric Acid market represents a compact but strategically significant niche within specialty chemicals. Our latest PW Consulting briefing synthesizes multi-year historical trends (2020–2025), an anchored base year (2025), and a forward-looking forecast window (2026–2032) to convert market intelligence into operational choices. This preview outlines the value of the full study for 2026 decision cycles: how to prioritize sourcing, de-risk supply chains, and position product- and channel-strategies in a market growing at a mid-single-digit CAGR.
Barbituric Acid Market
Market Snapshot: Growth Profile and Structural Traits
At the macro level, the Barbituric Acid market has expanded steadily over the past half-decade and enters the 2026 planning horizon with momentum. Historical figures show a consistent uptrend from 2020 through 2025, and our forecast projects continued growth through 2032 under a baseline compound annual growth rate of 4.6%. The trajectory is neither hypercyclical nor stagnant: it is characterized by measured expansion driven by demand in pharmaceutical intermediates, specialty organic synthesis, and niche applications where high-purity grades are required.
Barbituric Acid Market
Importantly, the market’s structure is concentrated. The leading suppliers together account for a substantial majority of value, creating a marketplace where a small set of incumbents exert outsized influence on pricing, quality norms, and contract terms. For 2026 planning, that concentration translates into both bargaining leverage for established suppliers and strategic risk for buyers who lack diversification in their sourcing strategy.
Barbituric Acid Market
Why this report matters for 2026 decisions
- Translating growth into supply strategy: With a reliable growth baseline, procurement and operations leaders can calibrate inventory, contract lengths, and capacity commitments to avoid costly over- or under-investment.
- De-risking in a concentrated market: High concentration magnifies supplier risk. The study equips buyers to evaluate counterparty exposure and to design multi-tier sourcing that balances quality, lead time, and cost.
- Regulatory and quality lenses: For pharmaceutical intermediates and certified reference uses, regulatory compliance and traceability are non-negotiable. The full report provides decision frameworks to align supplier selection, QA sampling, and documentation practices to current standards.
- Strategic M&A and partnership playbook: For corporates exploring vertical integration or bolt-on acquisitions, the briefing provides scenario-based valuations and negotiation levers appropriate for a market where incumbents hold scale advantages.
Key market drivers and short-term dynamics to watch in 2026
- Pharmaceutical R&D and API synthesis demand: End-market activity in drug discovery and small-molecule synthesis is the primary growth engine—particularly where barbituric acid serves as an intermediate or scaffold. Companies with close ties to contract development and manufacturing organizations (CDMOs) will see demand signals earlier.
- Purity segmentation shaping value capture: There is a persistent premium for analytical and certified-reference grades versus bulk industrial grades. This margin differential affects supplier economics and buyer sourcing strategies.
- Supply-side modularity: A mix of legacy western laboratory suppliers and nimble manufacturers from Asia provides a spectrum of offerings—from certified reference materials and small-pack high-purity reagents to bulk commodity shipments. Buyers must trade off lead time, certification, and total landed cost.
- Regulatory and quality compliance: For regulated use-cases, traceability and certified standards create stickiness—suppliers that can provide certified reference materials and rigorous QA controls maintain privileged positions in regulated supply chains.
- Concentration-driven volatility: Because top players control a large share of the market, any operational disruption, regulatory action, or capacity reallocation can rapidly impact availability and lead times.
Competitive landscape: how incumbents shape opportunity and risk
The market architecture spans distinct supplier archetypes. Understanding these archetypes helps procurement and business leaders match supplier capabilities to their technical and commercial requirements.
- Laboratory and scientific distributors: Established names in laboratory supply channels provide high-purity, small-quantity offerings suitable for research and analytical use. Their value proposition centers on consistent quality, granular packaging, and rapid fulfillment for R&D customers.
- Certified-reference and standards providers: Firms that supply certified reference materials play a pivotal role for analytical labs and regulated manufacturers. Their offerings are critical for method validation, regulatory submissions, and quality assurance programs.
- Specialty OEMs and bulk manufacturers: A cohort of manufacturers—operating primarily out of Asia—serves industrial and synthesis markets with bulk quantities and export capabilities. These players compete on price and scale, and many have international shipping and distribution networks.
- ISO-certified and export-focused producers: Several producers combine certifications with export focus, enabling them to serve both domestic industry and global buyers with varying compliance needs.
The full report contains granular supplier profiles and sourcing checklists. In this preview, we highlight representative supplier roles without disclosing proprietary market shares to preserve the strategic value of the complete intelligence package.
What the full PW Consulting report delivers (operationally focused)
- Validated market sizing and forecasting model (2020–2032) with scenario variants and sensitivity analysis for demand shocks, regulatory changes, and raw-material price swings.
- Supply-chain map and capacity overlay: facility footprints, product-grade capabilities, typical lead times, and a risk matrix for single-sourced nodes.
- Buyer’s playbook: sourcing templates, qualification matrices for high-purity versus industrial supply, recommended contract structures (including safety-stock formulae tied to lead-time distributions), and sample RFP language.
- Pricing architecture and cost-driver analysis: input-cost pass-through dynamics, margin bands by grade, and indicators to identify opportunistic procurement windows.
- Regulatory and compliance compendium: key standards for analytical and pharmaceutical intermediate uses, guidance on certificate of analysis (CoA) expectations, and audit checklists.
- Competitive profiles: capability maps for leading distributors, reference-material providers, and bulk manufacturers—highlighting differentiators such as certified material offerings, packaging options, and export readiness.
- M&A and partnership scenarios: valuation frameworks for target screening, integration checklists, and post-acquisition value-capture blueprints tailored to this market’s concentration dynamics.
- Actionable dashboards and templates: supplier scorecards, risk-heat maps, and an executive one-page decision memo for 2026 strategic choices.
Strategic recommendations for 2026 (concise playbook)
- Diversify tier-1 suppliers across archetypes: combine a certified-reference supplier for regulated uses with a reliable bulk manufacturer to balance quality and cost. Formalize second-source agreements with clear qualification milestones.
- Lock in quality, not just price: for pharmaceutical intermediates, prioritize suppliers able to deliver robust documentation and traceability; the regulatory cost of switching or remediation exceeds near-term procurement savings.
- Introduce flexible contracting: use staggered purchase commitments and option volumes to capture upside from demand variability while limiting stranded inventory.
- Build a lead-time hedging strategy: maintain a short-term strategic stock of certified-grade materials and a rolling cushion for bulk intermediates keyed to forecast variability and supplier concentration indices.
- Monitor consolidation signals: given the high market concentration, anticipate and model the implications of supplier M&A on availability and pricing; develop contingency plans for rapid requalification if necessary.
- Invest in supplier development: for players with strategic potential, co-invest in QC upgrades or smaller packaging lines to secure preferential allocation and improve resilience.
Final note: how to use this intelligence in 2026 planning
For executives and functional leaders mapping commitments in 2026, this market requires practical, defensible decisions: secure quality-critical inputs through certified suppliers, hedge bulk exposure through alternate manufacturers, and structure agreements to preserve flexibility as demand evolves. Our complete PW Consulting report converts the market’s macro growth baseline—anchored by the historical time series and mid-single-digit CAGR—into detailed, executable steps: supplier scorecards, contractual language, and scenario-based inventory models that teams can operationalize immediately.
This preview frames the strategic choices; the full report supplies the actionable tables, supplier diagnostics, and the confidential segment-level intelligence you need to convert strategy into measurable outcomes. For teams aligning 2026 budgets, capital plans, and procurement playbooks, the richer dataset and templates in the complete study are designed to shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Barbituric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sawmill Market to Grow at 3.23% CAGR (2026–2032), North America Holds 35.3%
By PW Consulting, 2026-07-12
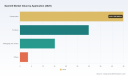
Sawmill Market 2026: Strategic Preview for Executive Decision-Makers
Executive snapshot
As PW Consulting releases its latest Sawmill Market study, this preview frames the strategic value the full report delivers to executives making investment, operational, and policy decisions in 2026. The global sawmill market—measured on a revenue basis in USD Million and anchored to a 2025 base year—has moved from the high‑70s in 2020 to just under 94 in 2025, and is projected to continue expanding through 2032. Our modeled baseline scenario embeds a compound annual growth rate of 3.23% across the 2026–2032 forecast window, creating a stable expansion narrative for capital allocation and capacity planning.
Sawmill Market
Why this report matters for 2026 decision-making
- Macro visibility: Supply chains, stumpage and delivered-log cost dynamics, and trade policy shocks have materially changed industry margins. The report translates these macro factors into actionable revenue and margin scenarios for 2026 planning cycles.
- Time-sensitive policy and financing implications: Recent government programs and legislative proposals are altering the capital landscape for sawmill modernization and restart projects. Our work quantifies the economic impact of these interventions on project IRRs and payback timelines.
- Competitive advantage through selective transparency: This preview demonstrates analytical depth while withholding detailed segment and regional breakdowns—designed to show how strategic insight is grounded in data, and to direct readers to the full study for the granular inputs required for transaction diligence.
Market dynamics and structural drivers
The sawmill sector in 2020–2025 exhibited modest growth punctuated by episodic shocks: price volatility in logs and finished lumber, weather- and fire-driven supply interruptions, and tariff adjustments affecting cross-border flows. These dynamics have pushed operators to re-evaluate operating models along three fault lines:
Sawmill Market
- Input cost pressure: Rising stumpage, trucking, and labor costs—paired with compressed residual-value recovery—have tightened operating margins for many mills. Our cost‑curve analysis highlights the elasticity of margins to delivered-log price moves and labor cost changes, and identifies breakpoints where cash cost increases force curtailments or capacity rationalization.
- Policy & capital availability: Public financing programs and proposed legislation are shifting the economics of capital projects. For example, targeted guaranteed loan programs announced to accelerate reopening or modernization of mills processing ecosystem-restoration byproducts materially lower financing costs for eligible projects and shorten payback periods for facilities focused on restoration-sourced wood.
- Market concentration and supply chain resilience: The market shows a moderate level of concentration among leading producers, with the top three and five firms accounting for a material share of global capacity. That concentration creates both systemic resilience in standards and potential vulnerabilities where regional curtailments or incidents—such as mill fires—can create supply and price ripples.
Recent shocks and policy signals every executive should monitor
- Targeted capital programs: Public loan guarantees and grants are now a realistic part of the project finance toolkit for sawmill owners pursuing modernization, restart, or wildfire-recovery processing capacity. These instruments can change project selection criteria and creditor terms.
- Trade policy volatility: Elevated import duties on certain softwood lumber flows are imposing cost penalties and reshaping regional sourcing strategies. Procurement and hedging strategies must be updated to reflect tariff-induced price floors and altered competitive dynamics.
- Operational disruptions: Physical risks—such as fire damage and localized curtailments due to raw-material constraints—remain a recurring source of capacity churn. The full report includes probabilistic disruption scenarios and contingency planning tools for supply continuity.
Competitive landscape — who shapes the market and how
The competitive map combines large integrated forest-products conglomerates, regional sawmill groups, and specialized equipment and portable-mill manufacturers. Market concentration metrics indicate that a relatively small group of established producers account for a sizable portion of global capacity, but the ecosystem includes agile entrants and equipment suppliers pushing modular and on‑site production models.
Sawmill Market
- Large integrated producers: Firms with extensive sawmill footprints and downstream engineered‑wood businesses retain scale advantages in procurement, product diversification, and financing access. Their strategic priorities include low‑carbon product lines, mill modernization, and integration of engineered wood into broader building-product portfolios.
- Regional leaders and specialists: Several North American and European regional champions focus on operational excellence and niche hardwood or softwood product lines. Consolidation activity and selective asset sales have been material in the last 18 months, shifting capacity pools and creating localized M&A opportunities.
- Equipment & portable-mill innovators: Manufacturers of portable and mobile sawmills are enabling new on‑site production economics—particularly in agricultural, wildfire salvage, and remote-logging contexts—opening new value chains and shortening transport-heavy logistics.
Key companies profiled in our coverage include long-standing North American operators with integrated manufacturing, Nordic and Central European mill groups specializing in industrial timber products, and specialized portable-mill equipment suppliers. The profile set covers strategic moves such as asset sales, operational curtailments, product demonstrations of new portable models, and capital redeployment—each analyzed for competitive and supply-chain impact.
What the full PW Consulting report contains (practical, transaction-ready deliverables)
- Top-line forecast and risk-adjusted scenarios: Multi-scenario projections for 2026–2032 with sensitivity analyses by cost, tariff, and demand shocks.
- Operational financial models: Plant-level cash cost curves, utilization breakeven tables, and CAPEX spend schedules for typical retrofit and greenfield projects.
- Project bankability assessments: Financing structures, public program overlays, and covenant stress tests for modernization and restart initiatives.
- Commercial go‑to‑market playbooks: Product mix optimization, channel strategies for construction and furniture end-markets, and margin-maximizing pricing levers under different competitive environments.
- M&A and asset-level intelligence: Pipeline maps, valuation comparables, and post-merger integration risk checklists focused on capacity consolidation, technology adoption, and regional supply balance.
- Supply-chain and sustainability roadmaps: Risk matrices for log sourcing, transport logistics, and carbon/ESG compliance paths for buyers and producers looking to capture premium low-carbon premiums.
- Executive dashboards: Ready-to-use KPIs for operational monitoring, procurement alerts, and capital allocation prioritization.
Strategic implications and recommended moves for 2026
Based on our integrated analysis, PW Consulting recommends a tiered set of actions depending on an organisation’s starting position.
- For incumbent integrated producers: Accelerate mill modernization projects that unlock yield gains and lower unit energy consumption; prioritize facilities positioned to process restoration- and salvage-sourced timber to capture both public financing and improving margin structures.
- For mid-size regional operators: Consider selective bolt-on acquisitions and capacity swaps to increase scale in strategic corridors; use available loan guarantees to lower the cost of capital for efficiency upgrades that hedge against tariff and input-cost volatility.
- For investors and private-equity sponsors: Focus diligence on asset-level operating leverage to delivered-log price swings and on capex pathways that reduce operating risk. The market’s moderate concentration creates opportunities for roll-up strategies in fragmented regional markets.
- For equipment and service providers: Emphasize modular, mobile, and low-emissions solutions that enable on-site production and rapid redeployment in salvage/forest-restoration contexts—areas where demand and public support are growing.
Methodology and data integrity
The study synthesizes historical revenue series from 2020–2025, primary interviews with operators and equipment manufacturers, proprietary cost-models, and scenario-based macroeconomic inputs to produce the 2026–2032 forecast. We apply a multi-layered validation approach that combines top‑down market balancing with bottom‑up plant-level modeling and third‑party cross-checks to ensure robust directional guidance for strategic decisions.
Read this if you need to...
- Decide on 2026 capital commitments for mill modernization or restart projects;
- Structure financing that leverages new public loan guarantees and legislative programs;
- Evaluate M&A opportunities in a market with meaningful but not extreme concentration;
- Design sourcing and hedging strategies in a tariff-volatile environment; or
- Assess product and technology investments that will drive margin expansion over the next planning cycle.
Next steps — discover the full intelligence
This preview demonstrates the strategic framing and analytical rigor we apply to the full Sawmill Market study. Detailed segment-level splits, regional demand overlays, plant-level cost curves, and downloadable financial models are intentionally reserved for the complete report and client portals to support transaction-level decision-making. PW Consulting invites executives to access the full dataset and scenario tools to translate these insights into executable 2026 strategies.
For detailed analysis of this topic, please visit the official page: Sawmill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Law Enforcement Software Market to Reach USD 30.02B by 2032 (10% CAGR)
By PW Consulting, 2026-07-12
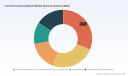
Law Enforcement Software Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s senior industry analyst, I present an executive preview of our new Law Enforcement Software Market study — a practical intelligence product designed to shape procurement, investment and operational decisions in 2026. The market is in the middle of a multi‑year expansion driven by cloud migration, evidence digitization, and mandate‑driven compliance. Our analysis shows the sector growing from a mid‑teens billion USD base in 2025 toward a substantially larger market by the end of the decade, underpinned by a forecast compound annual growth rate (CAGR) of 10.0% during the planning window. This preview highlights strategic implications, competitive dynamics and the core levers public‑safety leaders and solution providers must prioritize; detailed segment data and model outputs are reserved for the full report to preserve the “trailer” effect and drive direct engagement with the research portal.
Law Enforcement Software Market
Why this study matters for 2026 decisions
-
Timing: 2026 is the year many agencies finalize cloud‑first roadmaps, consolidate evidence and records platforms, and trade tactical fixes for longer‑term IT architectures. Procurement cycles, grant calendars and staffing constraints create a narrow window where roadmap choices can lock an agency’s operating model for a decade.
Law Enforcement Software Market -
Scale and momentum: The market is expanding rapidly off a 2025 base (our study uses 2025 as the primary reference year), with forecasts showing the sector continuing to accelerate through 2032. The growth is broad‑based across dispatch, records, case/evidence management and digital policing modules — producing recurring revenue opportunities for suppliers and recurring cost obligations for agencies.
Law Enforcement Software Market -
Decision gravity: Choices made in 2026 around deployment model (cloud vs. on‑premises), data residency, vendor lock‑in and integration approach will determine operational resilience, compliance posture and total cost of ownership for years to come.
Market dynamics that will determine winners and losers
-
Cloud and sovereign‑data constraints: Cloud adoption is accelerating, but CJIS and regional data localization rules make “one‑size‑fits‑all” public clouds impractical. Vendors that offer flexible regional hosting and CJIS‑attested architectures will command a premium in procurements.
-
Staffing shortfalls and automation imperatives: Persistent shortages in sworn and civilian staff are forcing agencies to pursue automation-driven efficiencies. Grants and federal funding programs (for example, Byrne‑style assistance) are materially accelerating modernizations — but they also shorten procurement windows, favoring vendors with ready‑to‑deploy modules and clearly demonstrable ROI.
-
Regulatory and audit risk: Compliance is increasingly structural, not transactional. Platforms must bake in evidence integrity, chain‑of‑custody workflows and audit trails to meet CJIS and other jurisdictional standards. Narrow technical non‑compliance can create outsized legal and operational liabilities.
-
Consolidation and concentration: Market concentration is substantial; a relatively small group of incumbents control a majority of institutional deployments, creating high switching costs. At the same time, specialists and point‑solution disruptors are winning pockets of demand by delivering focused functionality or superior integration into camera/LPR and body‑worn systems.
-
Feature velocity and productization: Continuous product updates — from CAD/RMS integrations to AI‑assisted incident triage — are reshaping buyer expectations. Recent vendor activity (for example, feature updates in leading RMS offerings in early 2026) underscores how the competitive battle is now about platform extensibility and upgrade experience as much as feature lists.
Strategic questions for 2026 stakeholders
-
For agency executives: Should you prioritize rapid cloud adoption to get immediate efficiencies, or adopt a hybrid approach to minimize regulatory and legal risk? What is the optimal cadence for consolidating legacy records and evidence silos while preserving case integrity?
-
For procurement and IT teams: How do you design RFPs and SLAs that capture long‑term costs (including migration and sunset of legacy systems) and guard against inadvertent vendor lock‑in?
-
For vendors: Do you double down on platform breadth (end‑to‑end suites) or pursue best‑of‑breed integrations? How do you price multi‑year support and cloud hosting to reflect compliance overheads?
-
For investors and M&A strategists: Which capability gaps (analytics, LPR/AI, evidence lifecycle) justify tuck‑in acquisitions to accelerate time‑to‑value for public‑safety customers?
Competitive landscape — who to watch and why
The vendor field includes large enterprise suites, specialized point vendors, and regional players. Our full report contains a vendor matrix and scoring model; here we summarize strategic positions of core firms that are materially shaping procurement dynamics in 2026:
-
Caliber Public Safety — Known for comprehensive CAD, RMS and CJIS‑secure cloud hosting. Competitive where agencies demand integrated records with strong compliance guarantees.
-
Vector Solutions — Strong in agency readiness and personnel management; competitive advantage when buyers prioritize workforce optimization alongside records modernization.
-
Motorola Solutions — A key incumbent with deep capabilities in CAD/RMS and multi‑agency dispatch coordination; benefits from integration into critical communications ecosystems.
-
Tyler Technologies — Enterprise public‑safety suite vendor with analytics and mobile access strengths; often wins on breadth and existing municipal relationships.
-
Flock Safety — Point‑solution innovator integrating LPR video, AI and investigational workflows. Attractive to agencies seeking rapid intelligence uplift.
-
Axon Enterprise — Differentiates through evidence management and direct integrations to body‑cam ecosystems; strong chain‑of‑custody story.
-
Versaterm — Cloud CAD/RMS player with community engagement modules; competitive in regions looking for modern dispatch and citizen interfaces.
-
CODY Systems — Emphasizes NIBRS native support and mobile RMS, appealing to agencies focused on reporting compliance and cross‑platform data sharing.
-
EIS — Supplier of core CAD, RMS and jail solutions with depth in traditional public‑safety capabilities.
-
PsPortal — Specialist in CJIS‑compliant cloud access for NCIC/NLETS; offers secure gateway capabilities that are essential for compliant cloud deployments.
-
Verint — Focused on emergency call handling and recording; wins where operational efficiency in dispatch centers is mission‑critical.
-
Oracle — Enterprise public‑safety suite with strong system integration, appealing to large jurisdictions and federal customers.
Each vendor’s near‑term performance will depend on the clarity of their compliance posture, hosting footprint, integration APIs, and a field service footprint capable of driving migrations with minimal operational disruption.
What the PW Consulting report delivers (practical contents)
-
Proven market sizing and base‑case forecasts (base year 2025; multi‑scenario projections through 2032) — enabling budgetary planning and revenue modeling for vendors and agencies.
-
Decision frameworks and procurement checklists — RFP language templates, SLA guardrails for CJIS and data residency, and migration risk matrices.
-
Vendor diagnostic scorecards — coverage of architecture, compliance posture, upgrade experience, and third‑party ecosystem strength (non‑public scoring reserved for subscribers).
-
Implementation playbooks — phased migration plans for records and evidence consolidation, rollback triggers and costed staffing models for transition periods.
-
Integration and API maturity assessment — practitioner guidance for integrating CAD, RMS, body‑worn camera systems, LPR feeds and analytics pipelines while preserving chain‑of‑custody.
-
Funding and procurement safeguard guidance — alignment of Byrne‑style grants, capital planning and multi‑year procurement to accelerate adoption with compliance safeguards.
-
M&A and partnership signals — capability gaps likely to attract consolidation and the functional areas where tuck‑ins will create the most immediate customer value.
How to use this intelligence in 2026
-
Procurement teams should treat the report as a short‑list tool: use the scorecards and RFP language to materially lower bid evaluation time and to surface hidden TCO risks that commonly appear during implementation.
-
Agency executives must align funding cycles with migration roadmaps: choose phased technical approaches that prioritize continuity of operations for dispatch and evidence systems.
-
Vendors should use the market sizing and scenario outputs to prioritize product investments — specifically, regional hosting, CJIS attestation, and integration bundles that accelerate agency adoption.
-
Investors and M&A teams can use our triggers list and capability gaps section to identify high‑leverage targets that shorten sales cycles or unlock cross‑sell opportunity for incumbent suites.
Final note and next steps
2026 will be a defining year for law enforcement IT modernization. The market’s trajectory is clear: sustained double‑digit expansion backed by funding flows, pressing operational needs and an accelerating requirements set for compliance and integration. This preview is a tactical orientation; the complete PW Consulting report contains the detailed segmentation, vendor scoring, and downloadable models you need to operationalize decisions. To access the full datasets, scenario models and procurement artifacts referenced here, please obtain the full report through PW Consulting’s research portal — the granular numbers, regional breakdowns and downloadable tools are available to subscribers and purchasing clients.
For immediate advisory engagements — vendor selection workshops, procurement document reviews, or integration assurance — PW Consulting is available to support short‑term deliverables calibrated to 2026 timelines.
For detailed analysis of this topic, please visit the official page: Law Enforcement Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
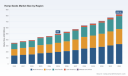
Hemp Seeds Market — Strategic Preview for 2026 Decisionmakers
As companies plan resource allocation, channel prioritization, and M&A activity for 2026, the hemp seeds market is moving from a niche speciality category into a structurally growing ingredient ecosystem. Our PW Consulting market model (base year 2025, historical 2020–2025, forecast 2026–2032) shows the overall market expanding from roughly USD 350 Million in 2020 to USD 500 Million in 2025, and our central scenario projects growth to about USD 826.5 Million by 2032 at a compound annual growth rate of 7.5%. The 2026 near-term inflection — with an expected market value in the mid-500s (USD Million) — creates a limited window for firms to set up advantaged supply chains, build branded formats, and secure processing capacity before competition intensifies.
Hemp Seeds Market
Why this preview matters for 2026
-
Timing pressure: A mid-single-digit CAGR hides concentrated pockets of faster growth and localized capacity constraints. Companies that make targeted investments in processing, quality assurance, or channel development in 2026 will disproportionately capture market share over the next three years.
Hemp Seeds Market -
Operational levers matter more than product marketing alone: With certain product forms already evaluated as GRAS for food use, the differentiator shifts to cost-to-serve, ingredient traceability, and formulation know-how.
Hemp Seeds Market -
Regulatory tailwinds and tightening definitions will alter supplier risk profiles. Firms that integrate regulatory scenario planning into procurement and product roadmaps will avoid last-minute supply shocks.
-
Market concentration is meaningful: our concentration analysis shows the three largest players control a substantial share of the market, and the top five command more than half — a structural reality that shapes pricing dynamics, partnership opportunities, and consolidation economics.
Market trajectory and implications for investment timing
The trajectory from USD 350 Million in 2020 to USD 500 Million in 2025 demonstrates early commercial traction underpinned by health-oriented consumer trends, plant-based protein demand, and ingredient adoption in food and personal care. The 7.5% CAGR we model for 2026–2032 represents a mature growth profile: steady, investable, and sensitive to capacity, regulation, and ingredient substitution trends.
For 2026 planning this implies three practical imperatives:
-
Prioritize conversion of strategic intent into operating capability within 6–12 months. Processing lines, certified supply contracts, and co-manufacturing agreements take time to stand up; lead times matter.
-
Use scenario-based unit economics. At the aggregate level growth is robust, but margin sensitivity is high if a firm underestimates processing costs or quality loss in upstream grain supplies.
-
Design an end-to-end traceability and compliance playbook. Regulatory changes and import pathways will influence sourcing decisions, especially for companies exporting into the U.S. market.
What the PW Consulting report delivers — operational content
This study is designed as a boardroom-to-shop-floor toolkit. It combines market-level forecasting with executable workstreams that translate strategic options into 12–36 month operational plans. Key deliverables include:
-
A transparent, model-driven market forecast (base year 2025; forecast 2026–2032) with configurable levers so internal teams can run bespoke scenarios for pricing, penetration, and innovation velocity.
-
Supply-chain maps and supplier scorecards: mapped sourcing corridors, processing node capabilities, and risk matrices that quantify exposure to regulatory, climatic, and quality shocks.
-
Go-to-market playbooks for B2B and consumer-facing formats: channel economics, private label vs. branded strategies, and commercialization timelines by product form.
-
Processing and capex blueprints: sizing guides for fractionation, hulled product lines, oil extraction, and protein isolation — including throughput, yield assumptions, and payback profiles.
-
Regulatory tracker and compliance playbook: implications of federal definitions, import pathways, and GRAS status for product approval timelines and labeling requirements.
-
Competitive due diligence pack: assessed capabilities, strategic positioning, and likely near-term moves for the leading firms — designed to support M&A, JV, or supply partnership decisions.
-
Commercial risk heatmap and mitigation strategies: hedging approaches, alternative sourcing plans, and contract structures to stabilize input costs and ensure continuity of supply.
Competitive landscape — who matters and what they signal
The market shows a clear stratification between large ingredient-specialist players and regional processors. The largest established manufacturers have built scale across processing, branded product lines, and retail distribution; mid-size innovators are focused on proprietary extraction or certification differentials. Notable players profiled in our report (representative, not exhaustive) include:
-
Manitoba Harvest Hemp Foods (Canada): a vertically integrated, large-scale hemp foods manufacturer with notable control over North American grain-to-shelf flows — strength in branded retail and ingredient supply.
-
Victory Hemp Foods (Carrollton, KY, USA): an example of a firm that has invested in processing innovation — patented solvent-free fractionation that enables allergen-free protein and oil streams, and which recently expanded processing capacity in North America to serve higher-volume customers.
-
Navitas Organics and Nutiva (USA): consumer-facing brands that have leaned into organic, non-GMO, and premium positioning — important benchmarks for pricing and certification premiums in retail channels.
-
Specialist processors and bulk suppliers (several North American and European players): these firms provide scale in B2B bulk supply and possess flexible packaging and certification capabilities required by food manufacturers and co-packers.
Strategic takeaways:
-
Processing capability is a gateway to margin capture. Firms that control fractionation and isolation technology can supply higher-value protein and oil fractions rather than commoditized raw seed.
-
Certification portfolios (organic, non-GMO, allergen-free) are differentiators in premium channels. However, certification increases working capital and traceability costs — make those investments against a validated route-to-market.
-
Partnerships with established ingredient players accelerate distribution and credibility. For firms lacking scale, secure co-manufacturing or supply agreements with top-5 incumbents to anchor growth.
Regulatory and structural dynamics shaping near-term opportunity
Three regulatory developments are particularly material for 2026 strategic planning:
-
Updated federal definitions affecting THC thresholds and treatment of viable seeds (public law changes in late 2025). These alter the legal treatment of certain seed flows and change compliance monitoring obligations for suppliers and buyers.
-
USDA’s alternative import pathway for hemp seeds after DEA authority changes provides a practical route to diversify sourcing — but it comes with new documentation and testing expectations that increase upfront compliance costs.
-
Existing GRAS evaluations for hulled seed, protein powder, and oil mean many product formats can be used as food ingredients today without new ingredient petitions — translating regulatory clarity into a commercialization advantage if firms can meet quality and labeling standards.
The combined effect of these dynamics is to shrink windows for late movers and raise the value of compliance-ready suppliers. Firms that build regulatory intelligence into sourcing decisions will reduce time-to-market for new SKUs and minimize costly reformulation or relabeling down the line.
Priority actions for 2026 — a tactical playbook
-
Lock capacity early: secure processing slots or add modular fractionation capacity to avoid being priced out as demand ramps.
-
Segment customers by margin-to-complexity: prioritize high-margin food and supplement customers where certification and traceability command premiums; use co-pack arrangements for lower-margin, high-volume channels.
-
Hybrid sourcing strategy: combine long-term contracts with spot-market agility to manage price volatility and quality variation across growing regions.
-
Invest selectively in quality and certification where the P&L supports a price premium; otherwise, compete on logistics and consistency.
-
Build an M&A screening funnel: prioritize targets that add processing IP, scale in strategic geographies, or complement product portfolios — our report includes financial and operational checklists to evaluate targets rapidly.
-
Operationalize regulatory monitoring: embed a compliance dashboard into commercial planning so procurement, R&D, and legal share a unified view of risk triggers.
Why PW Consulting’s full report is strategic for 2026 decisionmakers
This preview outlines the structural growth case, the competitive dynamics, and the immediate tactical decisions that matter for companies seeking to lead or defend positions in the hemp seeds market as we enter 2026. The full PW Consulting study goes deeper: it provides the modeled market-size pathways, a configurable scenario engine, supplier scorecards, capex templates, and a competitive intelligence pack that includes the operational metrics and investment profiles necessary to run diligence or board-level scenario planning.
We intentionally withhold some segment-level figures and granular regional splits in this preview to protect the analytic core of our model and to encourage direct engagement for tailored forecasts. If your 2026 strategy depends on precise product-form sizing, region-by-region demand modeling, or validated supplier economics, our complete report and the accompanying Excel model will provide the inputs and assumptions you need to make confident capital and commercial decisions.
Contact PW Consulting to review the full report and arrange a strategy session where we translate these insights into a concrete 12–24 month action plan aligned to your organization’s risk tolerance and growth ambitions.
For detailed analysis of this topic, please visit the official page: Hemp Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: FM market USD 2,145B in 2025, set to grow at 6.8% CAGR to 2032
By PW Consulting, 2026-07-12
Facility Management Services Market 2026: Strategic Preview for C-Suite and Procurement Leaders
As organizations enter 2026, facility management (FM) is no longer an operational backwater—it is a strategic fulcrum for resilience, cost control, and sustainability. PW Consulting’s forthcoming Facility Management Services Market study (base year 2025; historical review 2020–2025; forecast 2026–2032) synthesizes macro trajectories, competitive moves, regulatory pressures, workforce dynamics, and technology inflection points to give leaders the intelligence required to make high-stakes decisions this year. This introduction outlines the study’s strategic value for 2026 decision cycles while intentionally withholding the granular segment tables and contract-level benchmarks to encourage direct access to the full report for procurement- and portfolio-level action plans.
Facility Management (FM) Services Market
Top-line market context you need to internalize
The FM market has demonstrated both resilience and acceleration through recent cycles. From a global market size in 2020 through 2025, the sector has expanded materially—reaching an estimated USD 2,145.0 billion in 2025—and is forecast to continue growing robustly. Over the study’s forecast window (2026–2032) PW Consulting projects a compound annual growth rate (CAGR) of approximately 6.8%, taking the market to an estimated USD 3,380.32 billion by 2032. The implication for enterprise leaders is straightforward: FM will capture increasing operational and strategic spend, and decisions made in 2026 about suppliers, technology investments, and operating models will shape cost, risk, and sustainability profiles for the rest of the decade.
Facility Management (FM) Services Market
Why this study matters for 2026 decisions
- Timing matters: 2026 is a pivot year where investments in decarbonization and digitalization begin to compound in impact. Early movers capture outsized operational efficiencies and regulatory compliance advantages. The report furnishes tactical roadmaps and ROI timeframes suitable for board-level business cases.
- Risk mitigation & continuity: Labor scarcity, wage inflation, and regulatory acceleration increase service delivery risk. The study quantifies delivery exposure and provides mitigation playbooks—helpful to buyers deciding between insourcing, co-sourcing, or outsourcing models.
- Vendor strategy under pressure: With market concentration remaining relatively low (the top three and top five vendors account for modest shares of global revenue), the sector presents both partnership opportunities and supplier risk. The research helps procurement teams build diversification, partner-tiering, and performance-guarantee strategies.
- CapEx vs OpEx trade-offs: Capital-intensive decarbonization projects and tech modernization require new financing and commercial models. The report includes templates for structuring blended finance and performance-linked contracts aligned to sustainability KPIs.
Key dynamics shaping FM through 2026
- Labor & skills crunch: The labor market pressures are acute. Forecasts point to a shrinking active workforce participation into the early 2030s, exacerbating shortages in HVAC, electrical, and plumbing technicians—skills crucial to FM operations. Higher wages and longer time-to-service are already pressuring margins and delaying maintenance programs in some portfolios.
- Regulation and sustainability: Government building codes, corporate net-zero targets, and frameworks such as ISO 41001 are raising the bar for how FM is procured and delivered. Decision-makers must integrate energy management, emissions reporting, and compliance workflows into vendor KPIs.
- Technology convergence: Digital twins, IoT-enabled predictive maintenance, integrated workplace management systems (IWMS), and AI-driven scheduling are moving from pilots to scale. Software vendors and systems integrators are now critical partners in FM transformation programs.
- Service integration & buyer expectations: Buyers increasingly demand outcome-based contracts that bundle hard and soft services with energy and workplace experience deliverables. This forces providers to orchestrate cross-disciplinary capabilities and creates new procurement complexity.
Competitive landscape — what we observed in market activity
The provider ecosystem is diverse—global outsourcing specialists, integrated services firms, niche technical contractors, and software/platform vendors all compete for slices of the expanding market. Notable competitive themes surfaced from recent corporate actions and deal flow:
Facility Management (FM) Services Market
- Consolidation with capability expansion: Major players continue to pursue acquisitions that either expand service breadth (workplace experience, catering, security) or deepen technical capability (decarbonization, energy management). These moves are often accompanied by new dedicated business units focused on building operations and experience.
- Tech partnerships and platform plays: Several providers are forming partnerships with spatial-data, digital-twin and IWMS vendors to deliver integrated asset and workspace management. This trend elevates software and analytics as a competitive differentiator, not just an operational tool.
- Contract wins centered on integrated offerings: Outsourcing contracts awarded in recent quarters favored providers that could demonstrate global delivery scale plus local technical depth for specialized maintenance and energy services.
- Emergence of outcome-oriented services: Decarbonization and energy optimization services are being packaged as discrete commercial offerings—often with performance guarantees and measurement frameworks—reflecting buyer demand for measurable sustainability outcomes.
PW Consulting’s full report contains benchmarked company profiles, competitive scorecards, and M&A trend maps covering leading providers across the FM ecosystem—including global facilities managers, specialist contractors, and software/platform firms. These profiles analyze strategy, gaps, and fit for different buyer archetypes. (Note: detailed vendor revenue splits and contract-level pricing models are reserved for the full report.)
What the full study delivers — practical content for immediate 2026 action
This research is intentionally operational. Beyond market sizing and high-level forecasting, the report delivers tools that procurement and operations teams can use today:
- Actionable go-to-market and supplier-selection frameworks tailored to buyer size, asset mix, and sustainability ambitions.
- Contract design templates that align incentives, allocate risk, and embed sustainability and digital KPIs.
- ROI and payback models for common technology investments—predictive maintenance, energy management platforms, and space optimization tools—customizable for portfolio-level sensitivity analyses.
- Decarbonization playbooks and measurement frameworks map to regulatory milestones and corporate net-zero pathways.
- Workforce strategies for 2026—recruitment, upskilling, blended labor models, subcontractor ecosystems and wage stress mitigation.
- Scenario-based stress tests and readiness checklists for continuity planning under labor shortages or regulatory shifts.
For executives seeking to accelerate pilot-to-scale timelines, the report includes a phased adoption roadmap and procurement timelines that reflect vendor readiness and market capacity constraints. To maintain the “trailer” principle, granular tables (including regional splits, service-type revenue breakdowns, and contract-level benchmarks) are accessible in the full report data packs.
Strategic recommendations for 2026
- Prioritize decarbonization as a buyer differentiator: Embed energy and emissions KPIs into core FM contracts now. Align payment milestones to verified energy savings and emissions reductions to accelerate provider investment in retrofit and O&M optimization.
- Adopt hybrid delivery models: Where technical labor is scarce, combine provider delivery with certified sub-contractors and upskilled in-house teams. Require providers to submit resourcing contingency plans and apprenticeship commitments as part of RFP responses.
- Invest in interoperability and data governance: Make platform interoperability a contractual pre-condition. Define a single source of truth for asset and energy data to enable portfolio-level optimization and benchmarking.
- Shift to outcome-based commercial models selectively: Use outcome contracts for assets with predictable baselines (e.g., HVAC efficiency, energy use intensity), while retaining traditional models for episodic repair and highly variable services.
- Plan for supplier consolidation and diversity simultaneously: Given the market’s relatively low top-end concentration, pursue strategic partnerships with tier-one providers for scale, while maintaining a diverse network of specialists to ensure technical depth and local responsiveness.
- Embed workforce resilience into vendor SLAs: Include requirements for cross-training, certification targets, and advanced hiring pipelines to reduce service disruption risk from labor shortages.
How PW Consulting’s study supports board and procurement briefings
Boards and procurement committees require succinct, defensible options. This research equips leaders with executive-ready materials—decision trees, investment cases, contract comparators, and a phased implementation calendar tied to supplier capability maps. For buyers evaluating digital twin pilots, the report provides vendor shortlists and expected time-to-value estimates. For organizations facing new government mandates or ISO 41001 considerations, the study supplies compliance pathways and auditing checklists that speed certification and reduce legal exposure.
Next steps — where to get the full intelligence
This introduction provides the strategic contours you need to prioritize FM decisions in 2026. For procurement teams, real estate executives, and sustainability leaders who must translate strategy into contracts and CAPEX/OPEX plans, PW Consulting’s full Facility Management Services Market study delivers the granular models, regional and service-level splits, vendor scorecards, and downloadable templates needed to act. Access to the complete dataset and playbooks is available via PW Consulting’s research portal; the full report includes the proprietary segmentation detail intentionally omitted here to preserve the value of the primary data pack.
In a market growing into the trillions of dollars globally and evolving under the twin pressures of labor disruption and regulation, the decisions you make this year will shape operational risk, sustainability performance, and total cost of occupancy for the next decade. PW Consulting’s study is designed to convert uncertainty into a defensible plan.
For detailed analysis of this topic, please visit the official page: Facility Management (FM) Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Deburring Machine Market to Reach USD 691.27M by 2032 at 3.85% CAGR
By PW Consulting, 2026-07-12
Automatic Deburring Machine Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As the manufacturing sector moves deeper into higher-mix, higher-precision production paradigms, automatic deburring machines have migrated from an efficiency play to a strategic production lever. PW Consulting’s latest market study (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies that maturation: the global market has expanded steadily over the past half decade and is projected to grow at a compound annual growth rate (CAGR) of 3.85% through 2032 (all values in USD Million). For corporate strategists planning capital allocation, capacity expansion, or M&A in 2026, this research is designed as an operationally focused intelligence pack — showing where to act and why, while preserving the granular datasets behind a gated analysis for subscribers and clients.
Automatic Deburring Machine Market
Market trajectory and what it means for 2026 planning
- Between 2020 and 2025 the reported market exhibited steady recovery and growth in line with broader capital equipment investment cycles, reflecting renewed spending in metal fabrication, automotive components, aerospace, and electronics supply chains.
- With a 2025 base established, our forecast through 2032 assumes steady technology substitution and selective capacity additions. The market’s moderate CAGR of 3.85% signals a mature growth profile: not explosive, but predictable — a profile that favors disciplined, ROI-driven investments rather than speculative expansion.
- For CFOs and heads of operations, that predictability enables multi-year capital planning tied to measurable productivity and quality KPIs (scrap reduction, first-pass yield, cycle-time improvements) rather than exposure to volatile demand swings.
Why automatic deburring matters now — strategic drivers
- Labor economics: Ongoing skilled-labor shortages and escalating wage pressure are pushing manufacturers to eliminate manual deburring from critical workstreams where tolerance and repeatability are determinative of downstream process yield.
- Quality & throughput: Automated systems bring reproducibility that manual operations struggle to match across mixed-batch runs, making them attractive as OEMs shorten lead times and tighten specifications.
- Regulatory and sustainability pressure: New energy-efficiency targets and waste-reduction regulations are accelerating demand for machines that minimize consumables, enable closed-loop fluid management, and reduce secondary finishing steps.
- Materials and abrasives: Advances in engineered abrasives and polymer components are expanding the addressable part geometries for automatic systems, unlocking retrofit and greenfield opportunities in precision metal finishing.
Market structure and competitive dynamics — a pragmatic read
The market is characterized by fragmentation: numerous specialized OEMs and systems integrators provide solutions across vibratory, tumbling, centrifuge, water-jet, and robotized deburring technologies. No single supplier dominates; top vendors account for less than a third of total revenue, which creates a competitive landscape composed of niche specialists and regional champions.
Automatic Deburring Machine Market
For 2026 strategic programs, this structure creates two evergreen plays:
Automatic Deburring Machine Market
- Acquire or partner for capability: Large fabricators and automation players can accelerate time-to-market through bolt-on acquisitions of niche deburring technology providers or by partnering with best-of-breed OEMs for co-developed systems.
- Differentiate on integration and services: Vendors that combine machine capability with robust material handling, part tracking, and consumable management will capture higher-margin aftermarket revenue and longer customer lifecycles.
Competitive snapshot — vendors to watch
The market’s vendor universe includes equipment specialists, systems integrators, and global machine builders. Our study profiles the competitive strategies of leading names and what their moves imply for buyers and competitors:
- Timesavers LLC — Known for a comprehensive line of automated deburring and metal finishing systems leveraging advanced abrasives. Their strength lies in end-to-end finishing lines suited to mid- and high-volume metal shops.
- ARKU GmbH — German engineering focused on coil- and sheet-level edge processing with strong automation concepts and material handling for stamped and cut-part workflows.
- Sugino Corp. — Japanese specialist in high-pressure water-jet CNC deburring and washing systems, particularly for complex geometries common in precision industries.
- United Surface Solutions LLC — U.S.-based centrifugal deburring and water recycling systems provider, with offerings aimed at sustainability-conscious operations.
- Valgro India Limited — A regional player leveraging brush and belt grinding technologies for sheet metal processing, with expanding international trade-show visibility.
- Autopulit S.A. — Spanish firm delivering CNC and robotized solutions tailored to sheet metal and precision manufacturing, emphasizing flexibility for small- to medium-batch production.
- Fladder Danmark A/S — Danish supplier of programmable deburring and surface finishing machines covering multiple substrates including metal and plastics.
- Murata Machinery, Ltd. — Integrates deburring machines into larger automated lines, targeting customers seeking turnkey high- and low-volume solutions.
- Kramer Industries Inc. — Offers finishing equipment serving metal fabrication, automotive, and aerospace segments, positioned for retrofit and replacement demand.
Recent product and commercial activity underscores shifting competitive priorities: notable trade-show reveals in 2025 included demonstrations by Timesavers and ARKU at major fabricator exhibitions and Valgro’s showcase of finishing systems in North America — evidence that OEMs are using live events to accelerate product validation and customer acquisition.
What PW Consulting’s report delivers — operationally actionable insight
We built this research to be a tool that drives decisions in 2026. The deliverables are organized around executable outcomes rather than raw charts:
- Market sizing and validated historical series (2020–2025) plus forward projections (2026–2032) by technology class and application — enabling capital budgeting and addressable-market calculations.
- Adoption-roadmaps mapping technology fit to part families and production models, helping engineering leaders select the right architecture (vibratory, tumbling, centrifugal, water-jet, robotic) for their SKU mix.
- Buyer’s playbook — procurement scorecards, expected TCO ranges, lead-time sensitivities, and negotiation levers tied to consumables and service agreements.
- Vendor impact matrices — comparative positioning of the key OEMs, integration capabilities, aftermarket economics, and go-to-market tendencies (direct vs. distributor, retrofit focus, industry specialization).
- Regulatory and sustainability checklists — energy and waste-reduction benchmarks, compliance pathways, and supplier audit templates to accelerate procurement approvals.
- Supply-chain stress tests — scenario-based analysis on abrasives and polymer components, highlighting single-supplier risks and substitution pathways.
- M&A and partnership screening — tactical criteria and shortlists for acquirers and corporate development teams to fast-track diligence on strategic targets.
- Case studies and ROI models — real-world deployment examples quantifying cycle-time gains, labor-content reduction, and quality improvements with modeled payback periods.
How executives should use this intelligence in 2026
- Capital planners: Use the report’s segmented demand outlook to phase investments in deburring assets against product ramps, testing alternate CAPEX sizing tied to productivity KPIs.
- Operations leaders: Apply the adoption-roadmaps and case-study templates to pilot machine classes in selected lines, measuring throughput, rework, and consumable cost impacts over a 12–24 month horizon.
- Procurement & supply chain: Leverage vendor impact matrices and supply-chain stress tests to re-shape supplier contracts and secure redundancy for critical consumables.
- M&A and corporate development: Prioritize targets that deliver either technological differentiation (robotized, water-jet) or service-led aftermarket growth — then use our screening criteria to speed diligence.
Risks, unknowns, and what we conceal here (intentional)
True to the “trailer” principle of this preview, we surface strategic direction and high-level metrics but intentionally withhold the detailed segmentation matrices, regional shares, and line-item market splits that buyers and competitors find most actionable. Those guarded datasets — including discrete regional, application, and technology share tables and our ranked supplier revenue estimates — are included in the full report and in our client-ready data feeds.
Key uncertainties we model explicitly in the full analysis (but do not publish in this preview) include: sensitivity of demand to macro-construction cycles in target geographies, pricing elasticity for aftermarket consumables, and the pace at which OEMs adopt closed-loop waste systems under tightening regulation.
Final recommendation — what to do before Q3 2026
- Adopt a staged investment approach: prioritize pilot deployments in lines where manual deburring is a measurable bottleneck and financial payback is under three years.
- Lock consumable and parts supply terms: secure multi-year agreements with alternate suppliers to mitigate potential abrasives and polymer constraints.
- Explore partnerships with best-of-breed OEMs: co-development agreements for machine integration can shorten deployment timelines and create differentiated finishing capabilities.
- Subscribe to the full PW Consulting dataset: obtain the granular regional, type, and application splits necessary for precise addressable-market and ROI modelling.
Next steps
PW Consulting’s full Automatic Deburring Machine Market report provides the data tables, vendor models, and decision frameworks required to translate this strategic preview into a 90–180 day executable plan. For procurement teams, operations leads, and corporate development groups planning actions in 2026, the detailed datasets and scenario tools in the full study are the logical next step to de-risk investments and accelerate time-to-benefit.
For detailed analysis of this topic, please visit the official page: Automatic Deburring Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Chargeable Flexible Battery Market to hit USD 932.34 Million by 2032 — CAGR 22.4% | PW Consulting
By PW Consulting, 2026-07-12
Chargeable Flexible Battery Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
As organisations plan investments and product roadmaps for 2026 and beyond, the chargeable flexible battery sector is transitioning from niche innovation into a commercially material market. PW Consulting’s latest study—anchored on a 2025 base year and projecting through 2032—quantifies that trajectory in commercial terms while linking it directly to the regulatory, manufacturing and go‑to‑market decisions firms must make now.
Chargeable Flexible Battery Market
In headline terms, the global market (USD, revenue in Million) expanded from approximately 93.15 in 2020 to 226.52 in 2025 and PW Consulting forecasts a continuation of rapid expansion to roughly 932.34 by 2032. This expansion reflects a compounded annual growth rate of 22.4% across our 2026–2032 forecast window. Market concentration today is moderate: the top three firms account for about 25% of revenue and the top five roughly 32%, leaving substantial addressable opportunity for new entrants and adjacent incumbent players.
Chargeable Flexible Battery Market
Why 2026 is a strategic inflection point
- Regulatory timing: New EU battery rules and labelling requirements that took effect around 2026 dramatically change compliance costs and supplier selection criteria for manufacturers and OEMs targeting European markets.
- Commercial scale-up: 2024–2026 was the period when pilot deployments matured into first commercial programs—creating the need for robust supply chain contracting, qualification procedures and lifecycle cost modelling.
- Technology maturation: Multiple cell chemistries and form factors (thin film, printed, solid‑state variants) have reached sufficient TRL to be considered for volume programs; choosing the right technical partner is now a commercial, not just an R&D decision.
Market trajectory and interpretation
Understanding the market trajectory is foundational for capital allocation. Our historical series (2020–2025) shows an early, steady rise followed by a pronounced acceleration as flexible batteries were integrated into new classes of wearables, medical sensors and industrial IoT. The forecast to 2032 anticipates continued high‑teens to low‑twenties CAGR (22.4% in our baseline), driven by unit adoption, new form factor applications, and higher average revenue per device as functionality (fast‑charging, embedded management, certification) is bundled into battery subsystems.
Chargeable Flexible Battery Market
For executives this means: revenue pools will expand quickly, but they will do so unevenly across use cases and geographies. The result is a high‑value window in which early strategic moves—technology licensing, exclusive supply arrangements, or differentiated compliance capabilities—can secure disproportionate commercial returns.
Dynamics reshaping supplier selection and product strategy
- Regulatory and standards pressure: The EU Battery Regulation introduced mandatory carbon footprint verification for larger rechargeable batteries and new labelling and removability guidance. These rules are translating into customer procurement requirements and new vendor pre‑qualification checkpoints.
- Certification and conformity: Accredited notified bodies and testing partners are becoming gating factors. Recent accreditations of major test houses signal faster routes to market for manufacturers that engage early with conformity processes.
- Sustainability economics: Recycling efficiency targets and lifecycle reporting are shifting the cost curve. Buyers increasingly value suppliers with verifiable recycling pathways and lower cradle‑to‑gate footprints.
- IP and technology differentiation: New patents for flexible high‑cycle lithium and scalable flexible battery systems indicate continued innovation around energy density, cycle life and manufacturability—each of which will determine where value pools consolidate.
Competitive landscape: what to watch
The sector combines large, vertically integrated incumbents with specialised innovators. The competitive set we examine includes global battery majors (e.g., Samsung SDI, LG Chem, Panasonic) alongside flexible/patterned battery specialists and printed‑battery pioneers (e.g., Blue Spark Technologies, Enfucell, BrightVolt, Imprint Energy, Cymbet, Jenax, FlexEl).
- Large incumbents (Samsung SDI, LG Chem, Panasonic): Their strengths are scale manufacturing, deep OEM relationships, and materials development capability. They are best positioned to supply tier‑one wearable customers and industrial integrators that require stringent supply continuity, warranty frameworks and technical integration support.
- Specialist innovators (Blue Spark, Enfucell, BrightVolt, Imprint Energy, Cymbet, Jenax): These firms govern important niches: printed batteries optimized for conformal sensors, ultrathin solid‑state solutions for ultra‑low profile devices, and zinc‑based chemistry for specific cost/perf tradeoffs. Their value is speed‑to‑market in new product categories and the ability to adapt form factor and integration approaches quickly.
- Custom converters (FlexEl and others): These players serve medical device and industrial wearable customers where bespoke mechanical and regulatory requirements defeat off‑the‑shelf solutions. They are high touch, high margin partners for regulated end markets.
Strategically, incumbents will compete on reliability, certification and global footprint; specialists will compete on differentiation of form factor, integration ease, and aggressive cost curves. Partnerships and M&A in 2026 will likely follow two patterns: (1) incumbents acquiring or partnering with printed/solid‑state innovators to round out portfolios; (2) strategic alliances between OEMs and flexible battery specialists for co‑developed modules with embedded sensing, firmware and verification.
Recent developments and implications
- Patent activity around high‑cycle lithium and scalable flexible systems indicates that next‑generation chemistries will be selectively proprietary. Licencing strategies and freedom‑to‑operate checks should be pursued early in product development.
- Regulatory actions—specifically EU rules taking effect in early 2026 and due diligence phases in 2027—create a compliance timeline that product and procurement teams must map into their launch schedules.
- Accreditation of conformity assessment bodies accelerates time‑to‑market for compliant products, but firms must engage these bodies early to avoid qualification bottlenecks.
What PW Consulting’s full study provides (practical deliverables)
Our full report is engineered as a decision‑support toolkit for corporate leaders, product managers and procurement teams. Key deliverables include:
- Market sizing and scenario modelling (historical 2020–2025, baseline and two alternative adoption scenarios for 2026–2032 with sensitivity to unit economics and regulatory cost impacts).
- Technology roadmaps that align chemistry, form factor and manufacturing maturity to specific use‑case economics.
- Regulatory compliance playbook—step‑by‑step actions and timelines for EU conformity, labelling and carbon reporting obligations, plus vendor contract clauses to allocate compliance risk.
- Supplier scorecards and sourcing decision matrices tailored by OEM use case: wearables, medical devices, consumer devices and industrial sensors.
- Commercial due diligence templates and valuation heuristics for M&A and licensing transactions in this space.
- Go‑to‑market playbooks for new entrants: channel strategy, pilot program design, and enterprise customer qualification frameworks.
To preserve the report’s role as a strategic asset, we intentionally present headline macro flows publicly while withholding detailed breakouts for regions, types and applications in this introduction—these granular allocations are included in the client report and underpin the revenue forecasts and scenario outputs.
Action framework for executives in 2026
- Map compliance to product roadmaps: Integrate EU labelling and carbon footprint timelines into product launch gates. Non‑compliant products risk market exclusion or costly rework.
- Prioritise platform partners: Choose technology partners based on a mix of technical fit, certification readiness and IP posture—not just on price per cell.
- Design for circularity: Make recyclability and removability upstream design criteria; this reduces total cost of ownership as recycling targets and reporting requirements tighten.
- Stage investments: Use the 2026–2028 window to pilot, standardise and modularise battery subsystems before scaling manufacturing investments that are harder to reverse.
- Hedge with multiple chemistries: Given rapid innovation and patenting activity, maintain optionality across solid‑state, thin‑film and printed approaches for key product lines.
Final thoughts — the opportunity and the trade‑offs
The chargeable flexible battery market presents a classic growth‑with‑complexity opportunity: fast expanding revenue pools (our baseline projects near fourfold growth from 2025 to 2032), meaningful differentiation on technical and regulatory axes, and a supplier base split between scale and specialist capability. The winners will not be those who merely move fastest, but those who align technical choice, regulatory readiness and commercial partnerships into a coherent, executable plan.
PW Consulting’s full study provides the actionable intelligence and tools to do exactly that: quantified scenarios, supplier assessments, compliance playbooks and deal templates that translate market potential into executable strategies. For teams making 2026 decisions—whether to partner, acquire, enter new segments or re‑engineer products—the difference between a pilot and a profitable, repeatable program will be the quality of the market and risk insights that guide those choices.
Learn more
This introduction is a synopsis of the study’s strategic findings. For the full dataset, segmented forecasts, supplier benchmarking and our actionable 90‑day implementation playbook, please consult the full PW Consulting report and client portal.
For detailed analysis of this topic, please visit the official page: Chargeable Flexible Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Soundbars Market to Hit USD 4,650.9M in 2025; 7.08% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Soundbars Market 2026: A Strategic Preview for Decision‑Makers
As consumer audio moves from a commodity TV accessory to a strategic living‑room platform, executives and investors need a clear, actionable line of sight into where value will concentrate over the next seven years. PW Consulting’s Soundbars Market study—anchored on a 2025 base year—provides that line of sight. The global market reached approximately USD 4,650.9 Million in 2025 and, with a compound annual growth rate of 7.08% projected across the forecast horizon, is on track to exceed USD 7.4 Billion by 2032. This preview highlights the report’s strategic value for 2026 decision‑making, outlines the competitive dynamics you must plan around, and signals the operational and supply‑chain levers that separate winners from laggards.
Soundbars Market
Market Snapshot: Macro Trajectory and Competitive Concentration
-
Historical momentum: The category has expanded steadily through 2020–2025 as TV replacement cycles, streamer adoption, and at‑home entertainment demand converged to upgrade baseline audio experiences.
Soundbars Market -
Near‑term projection: Our base‑case forecasts illustrate sustained demand growth into the late 2020s, driven by premiumization (immersive formats such as Dolby Atmos), modularity, and multi‑device ecosystems that extend soundbar relevance beyond traditional TV listening.
Soundbars Market -
Market structure: The competitive intensity is moderate—three leading firms control a meaningful share of revenue while the top five firms approach an even higher combined share (CR3 ≈ 53.9%; CR5 ≈ 59.2%). That concentration underpins premium pricing where incumbents defend margin with software features, ecosystem lock‑in, and premium component sourcing.
What This Report Delivers (Practical, Executable Content)
-
Actionable strategies for 2026: product roadmaps, pricing bands, channel sequencing (direct vs. retail vs. e‑commerce), and promotional calendar optimization tied to major content windows.
-
Commercial playbooks: tailored guidance for OEMs, distributors, retail chains, and private‑label manufacturers—covering assortments, margin engineering, and bundling with TVs and sound services.
-
Supply‑chain risk matrix: granular supplier dependency scoring, critical component tightness, and contingency options for magnet and semiconductor exposure.
-
Competitive benchmarking: feature‑level comparisons, go‑to‑market case studies, and M&A/partnership candidate shortlists based on capability gaps and valuation ranges.
-
Scenario modelling: demand sensitivity to economic cycles, content platform investments, and regulatory shocks—each with quantified P&L impacts and suggested tactical responses.
-
Note on disclosure: the study’s core segmentation tables (region, product type, connectivity, application) and the revenue‑level breakdowns that inform our tactics are intentionally withheld in this preview to preserve the integrity of the proprietary analysis. Full segmented intelligence and interactive dashboards are available in the complete report.
Competitive Landscape — Who’s Shaping 2026?
The market’s leading incumbents continue to push two complementary plays: richer immersive experiences and tighter integration with TV and smart‑home ecosystems.
-
Samsung Electronics: Expanding its Q‑Series portfolio with higher‑channel Atmos configurations and ecosystem features such as synchronized audio with Q‑Symphony. These moves reinforce Samsung’s strategy of TV‑led soundbar adoption.
-
LG Electronics: Focusing on modular systems that allow customers to scale performance (soundbar + wireless sub + surrounds) with AI tuning—an approach that increases attach rates and lifetime revenue per household.
-
Sony: Leveraging high‑fidelity tuning and spatial audio to position soundbars as a true home‑cinema upgrade, funneling premium seekers into higher ASP brackets.
-
Bose, Sonos: Competing on refined sound signature and ecosystem stickiness—Sonos’s multi‑room and wireless credentials remain a strong retention mechanism, while Bose emphasizes refined, space‑adaptive presentation.
-
Newer/adjacent entrants (SVS, KEF): Emerging with audiophile‑grade engineering—room correction, Uni‑Q coaxial drivers, and scalable architectures—threatening to pull premium buyers away from traditional consumer‑electronics brands.
-
Tiered competitive dynamic: OEMs with TV platforms hold advantage in mainstream channels; specialist audio brands continue to erode premium margins by emphasizing acoustics and build quality.
Recent Product and Market Moves (Jan 2026 signals)
-
LG introduced a modular Atmos system that blends wireless sub/surround scalability with AI tuning—designed to increase customer upgrade paths and aftermarket accessory sales.
-
Samsung expanded its Q‑Series, emphasizing multi‑device audio alignment and dialogue‑centric features to improve perceived clarity in mixed content—an important differentiator for mainstream buyers.
-
SVS and KEF launched first‑in‑category products that prioritize room correction and coaxial driver architectures respectively—clear signals that audio‑first engineering is migrating into the soundbar format.
Supply Chain, Regulation, and Material Risks — What to Watch in 2026
-
Critical minerals: Geopolitical shifts in rare‑earth policy create asymmetric price and availability risks for high‑performance driver magnets. A key policy milestone to monitor is the scheduled expiration of a temporary suspension of expanded export controls later in 2026—behaviour around that date will materially affect sourcing strategies.
-
Battery and electronics: While soundbars are not battery‑centric products, the broader trend toward wireless subwoofers and portable audio means lithium availability and recycling will progressively influence accessory designs and supplier selection.
-
Manufacturing concentration: Component bottlenecks (drivers, DSP chips, Wi‑Fi/Bluetooth modules) can disproportionately affect new entrants lacking multi‑sourced supply. Our report maps supplier capacity and escalation timelines to quantify lead‑time and cost shocks under stress scenarios.
Strategic Imperatives for 2026 (Recommended Priorities)
-
Embed software and tuning as a product differentiator: Invest in AI‑based room calibration and OTA update capability to maintain feature parity without frequent hardware refreshes.
-
Design for modularity: Offer upgradeable configurations (add wireless sub, surrounds) to increase lifetime value and reduce churn—particularly effective when paired with financing or trade‑in programs.
-
Lock in TV partnerships and content bundles: Joint promotions with TV OEMs and streaming platforms accelerate adoption—negotiate revenue shares and co‑marketing commitments up front.
-
Hedge critical‑material exposure: Secure multi‑year supply contracts for magnets and key semiconductors, explore recycled inputs, and qualify alternate suppliers outside concentrated geographies.
-
Pursue selective premiumization: Use acoustic engineering (coaxial drivers, advanced DSP) to defend higher ASPs—balance engineering spend with realistic TAM expectations per channel.
-
Prepare for consolidation: Use 2026 to build M&A optionality—bolt‑on acoustics specialists and calibration software providers deliver rapid capability upgrades with defensible IP.
Go‑to‑Market Playbook (Tactical Checklist)
-
Prioritize SKUs for online discovery and in‑store demo: allocate inventory to high‑visibility bundles during key content windows.
-
Implement dynamic pricing algorithms aligned to promotional elasticity and competitor moves in real time.
-
Mandate interoperability tests with leading TV platforms and voice assistants prior to product launch.
-
Set up an early‑warning supplier dashboard that flags lead‑time drift and cost escalation by component.
-
Pilot subscription‑style service offers (calibration, extended warranties, content bundles) to smooth revenue recognition and increase retention.
Why PW Consulting’s Study Matters for Your 2026 Decisions
The full study combines bottom‑up product‑level modeling with primary interviews across OEMs, distributors, and retail buyers, and overlays these insights with a probabilistic scenario engine. That combination yields three practical advantages for executives:
-
It translates market growth into revenue and margin outcomes under alternative strategies (e.g., modular premiumization vs. cost leadership).
-
It surfaces near‑term tactical moves that materially affect 2026 P&L (channel allocation, promotional cadence, component contracts).
-
It preserves commercial confidentiality while enabling negotiable playbooks—our deliverables include downloadable M&A candidate lists, supplier risk heatmaps, and an executive‑ready one‑page strategy matrix.
Note: This preview deliberately omits the granular segment tables and the revenue breakdowns by region, type, connectivity, and application that underpin our tactical recommendations. Those assets—along with interactive dashboards and downloadable models—are available in the full report.
For teams planning capital allocation, product roadmaps, or partner strategies in 2026, the value of timely, scenario‑based intelligence cannot be overstated. PW Consulting’s Soundbars Market study equips decision‑makers with the context, the contingencies, and the prioritized actions required to capture disproportionate value as the category evolves. Access the full intelligence package to see the segment‑level analytics, supplier schedules, and executable playbooks that will drive winning positions through 2032.
For detailed analysis of this topic, please visit the official page: Soundbars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pool Cleaners Market to Reach USD 197.09 Million by 2032 (6.23% CAGR)
By PW Consulting, 2026-07-12
Pool Cleaners Market 2026 — Strategic Outlook & Actionable Intelligence
Executive teaser
By 2025 the global pool cleaners market reached a significant inflection point with an estimated market size of USD 115.0 Million (base year 2025). Our forecast through 2032 projects continued healthy expansion at a compound annual growth rate (CAGR) of 6.23%, taking the market to roughly USD 197.1 Million by 2032. For executives making resource allocation and go-to-market decisions in 2026, these headline numbers are more than a growth story — they frame a time-limited window to capture share as product innovation, channel evolution, and supply-side disruption converge.
Pool Cleaners Market
Why this research matters for 2026 decision cycles
-
Prioritization: With mid-single-digit CAGR and accelerating product innovation, companies must choose where to invest R&D and capex to convert macro growth into profitable share gains.
Pool Cleaners Market -
Risk mitigation: New tariff regimes and raw-material pressures introduced in 2025 meaningfully affect cost structures. The research translates these macro shocks into scenario-ready mitigation plans.
Pool Cleaners Market -
M&A and partnering: Consolidation opportunities are concentrated in specific technology niches and manufacturing capabilities. Our work shows where bolt-on acquisitions or JVs create immediate strategic leverage.
-
Commercialization timing: Rapid new-product introductions — notably at CES 2026 — have compressed the product cycle. The report gives timing guidance to accelerate commercialization while protecting margins.
Market dynamics — what is changing and why it matters
The market expansion we model is not uniform. It is being driven by three interlocking forces: (1) product-level innovation (AI navigation, hybrid power systems, cordless autonomy), (2) shifting buyer expectations (smart-home integration, lower energy footprints, improved user UX), and (3) supply-chain and regulatory disruption that is raising the floor on manufacturing costs. Each force creates both opportunity and constraint for incumbent manufacturers and new entrants.
-
Product innovation: 2026 has already shown strong momentum. Several leading players launched next-generation robotic cleaners featuring AI-powered navigation, multi-modal suction and jet systems, and hybrid/cordless power configurations. These advances materially raise buyer willingness to pay and shift competitive parity toward firms that can scale software-enabled features.
-
Channel transformation: E-commerce, subscription service models (maintenance-as-a-service), and value-added installer networks are changing distribution economics. The research maps viable channel mixes by business model archetype and quantifies the sales productivity delta between legacy and new-channel approaches.
-
Supply-side pressure: New tariffs imposed as of March 2025 (including elevated duties on key metals and selective tariffs on imports from specific origins) are increasing input cost volatility and creating incentives to rethink localization, dual-sourcing, and component redesign to avoid tariff buckets.
Competitive landscape — profiles and strategic implications
The market is populated by a mix of long-established incumbents and fast-moving specialty players. Our competitive framework assesses each major player across product breadth, channel reach, innovation capability, manufacturing footprint, and financial flexibility. Key takeaways for 2026 planning:
-
Maytronics Ltd. (Kibbutz Yizre'el, Israel): A clear leader in AI-enabled robotic platforms and strong brand equity in both residential and commercial segments. Their latest generation devices emphasize advanced navigation and hybrid power, reinforcing a product-led premium strategy. Strategic implication: rivals seeking to neutralize Maytronics’ differentiation must invest in comparable software and service ecosystems, not just hardware.
-
Hayward Industries, Inc. (Charlotte, NC, USA): A broad-based player with multi-technology offerings across robotic, suction, and pressure-side solutions. Their scale in distribution and aftermarket parts gives them resilience on price competition. Strategic implication: Hayward can play a defensive role on volume while selectively targeting margin accretion through services and aftermarket subscriptions.
-
Pentair plc (Eden Prairie, MN, USA): Offers a full range of cleaner modalities and benefits from integrated product portfolios across pool systems. Their strength is cross-selling and channel partnerships with installers. Strategic implication: companies competing on product must account for Pentair’s advantage in bundled offers that increase customer switching costs.
-
Fluidra S.A. (Barcelona, Spain): A portfolio player with strong brand lines and global reach. Fluidra’s strategy balances premium robotic products with distribution efficiency. Strategic implication: potential inorganic moves to shore up technology gaps or capacity shortfalls are realistic near-term plays.
-
Aiper Intelligent LLC (USA): A fast innovator in cordless, AI-driven robotic cleaners. Recent launches have signaled an aggressive push into smart, consumer-friendly price points. Strategic implication: nimble entrants can reshape market expectations on features, forcing incumbents into faster innovation cycles.
-
NingBo Poolstar Pool Products Co., Ltd. (Ningbo, China): A major OEM/ODM with scale manufacturing capability. Their value proposition is low-cost production and customization, enabling both own-brand and private-label strategies. Strategic implication: companies requiring cost flexibility or private-label capabilities will continue to engage with large OEMs, but should stress-test quality and IP protections.
Recent developments that reset strategic timelines
-
January 2026 — Aiper unveiled next‑gen Scuba V3 models emphasizing advanced AI navigation at CES 2026, signaling the speed of feature adoption in the cordless segment.
-
January 2026 — Maytronics launched the Dolphin EON with JetIQ and SmartMap navigation; a hybrid power approach that targets both energy-sensitive buyers and commercial operators seeking uptime improvements.
-
February 2026 — iGarden / Fairland Group released an award-honored bionic dual‑vision cleaner, highlighting how new sensor-fusion approaches are moving from concept to consumer-ready products.
Report contents — what you will get and how it is practical
This study combines quantitative forecasting with operational toolkits designed for immediate executive use. Highlights include:
-
Macro sizing & trend analysis from 2020 through 2025, with a forward build and scenario modeling across 2026–2032 (anchored to our base-year estimate and CAGR).
-
Technology and product roadmap mapping that shows adoption curves for robotic, suction, and pressure-side cleaners — and the conditional triggers that accelerate migration to higher-margin robotic platforms.
-
Competitive intelligence dossiers for leading vendors, including strategic positioning, go-to-market playbooks, recent product launches, and an assessment of who benefits most from current shifts.
-
Supply-chain stress tests and tariff-impact scenarios (post-March 2025 regulatory changes), plus actionable sourcing strategies — from nearshoring to design-for-cost initiatives.
-
Commercial frameworks: pricing-sensitivity models, channel economics, installer incentive designs, and pilot templates for subscription or service-based business models.
-
M&A and partnership heatmaps that identify capability gaps (e.g., AI navigation, battery systems, localized manufacturing) and suggest match candidates by strategic fit and execution complexity.
How to use these insights in the next 90 days
-
Week 1–2: Run a rapid impact assessment against the tariff scenarios included in the report. Identify the three product lines most exposed to input-cost inflation and quantify margin vulnerability.
-
Week 3–6: Undertake a product feature prioritization workshop using our feature-economics matrix. Decide which AI, power, and connectivity features to fast-track into production for 2026 launches.
-
Month 2–3: Execute a channel pilots plan — test a direct-to-consumer subscription bundle and an installer partnership in two contrasting markets to evaluate CAC and lifetime value assumptions.
-
Quarter 1: Formalize a 12-month M&A screening process using our heatmap to pick the right inorganic targets for capability or capacity extension.
Strategic options to consider
-
Invest in software and service: Convert hardware buyers into recurring revenue relationships by embedding diagnostics, predictive maintenance, and subscription maintenance plans.
-
Redesign for tariff resilience: Accelerate design-for-manufacture programs that minimize duty exposure and enable easier local assembly.
-
Differentiate through energy efficiency: Prioritize hybrid and low-energy platforms to capture environmentally conscious buyers and reduce total cost of ownership.
-
Pursue selective consolidation: Use M&A to acquire specialized AI navigation or battery IP rather than building internally on a long timeline.
Concluding note — the strategic value for 2026
With the market on a steady growth trajectory and product innovation accelerating, 2026 is a pivotal operational year. Executives who combine disciplined scenario planning (to offset tariff and supply risk) with rapid commercialization of software-enabled features will capture outsized returns. Our report is designed to be the playbook that translates the broad market trajectory — anchored in our base-year sizing and 6.23% CAGR forecast — into executable moves for the next twelve months.
Next steps
For the full suite of models, segment-level forecasts, company scorecards, and downloadable scenario tools that underpin these conclusions, please consult our detailed market report. The executive summary above intentionally highlights the strategic direction while preserving the granular segment data for the full study to ensure you have the complete intelligence required to act with conviction.
For detailed analysis of this topic, please visit the official page: Pool Cleaners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: FeSi Powder Market to Reach USD 2,193.6 Million by 2032 at 5.2% CAGR
By PW Consulting, 2026-07-12
Fesi Powder Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Lead Industry Analyst, I present a forward‑looking primer on the Fesi (ferrosilicon) powder market that is tailored for executive teams preparing decisions in 2026. This piece synthesizes the high‑level market trajectory, regulatory inflection points, competitive dynamics and practical actions you should be taking now — while deliberately withholding the transaction‑level segmentation tables and granular region/application shares that are contained in our full Fesi Powder Market study. Consider this a strategic trailer: enough context to shape boardroom debate, not the full ledger required for final contracting.
Fesi Powder Market
Market snapshot: the macro trajectory
The Fesi powder market is on a steady expansion path. Using 2025 as our base year and a historical window of 2020–2025, our market systematics project the sector through a 2026–2032 forecast horizon. The market exhibits a mid‑single digit compound annual growth rate (CAGR) of 5.2% over the forecast period. Put simply, the market that was measured in the low‑to‑mid billions (USD, Million unit reporting) in the early 2020s continues to expand, with the 2025 base providing a launch point for 2026 planning and a clear ramp across the late 2020s into 2032.
Fesi Powder Market
Why emphasize the macro numbers? Because procurement cadence, capex timing and contract tenors should be set against an expectation of sustained demand growth rather than a short‑lived cycle. The growth profile creates windows for capacity investments, premium product positioning (high‑purity powders, narrow particle size distributions) and consolidation plays — but those moves must be timed against regulatory signals and supply reactions detailed below.
Fesi Powder Market
Why 2026 is a decisive window
- Regulatory shockwaves are compressing lead times. From late‑2025 onward multiple jurisdictions introduced import and export controls that change trade math and create near‑term price and availability volatility. These changes materially affect sourcing from large exporting hubs and alter the calculus for local versus imported supply.
- Supply adjustments are already visible. Major producers have responded to uncertainty by moderating production in certain assets. At the same time, new greenfield and brownfield capacity investments in exporter regions are being brought online. This simultaneous contraction and expansion creates localized tightness even as aggregated capacity increases — a classic environment favoring agile buyers and position‑taking sellers.
- Application demand is evolving. Traditional metallurgical demand remains foundational, but specialty uses (dense media separation for mining, high‑purity deoxidation grades for advanced steels, powder for electrode and additive applications) are consuming improving shares of the value chain. Product specification matters increasingly as customers seek narrow particle size distributions and trace element control.
Key strategic questions for 2026
- How much price and availability risk do you want to carry through 2026–2027, and which contract structures (term versus spot, indexed pricing, minimum take) best balance cost and continuity?
- What portion of your demand should be shifted to accredited, traceable suppliers versus opportunistic spot purchases from low‑cost exporters?
- Do you have in‑house capabilities to adjust product specification (particle milling, blending) to capture value from higher‑margin grades?
- Which regulatory scenarios (tightening export controls, import duties/tariff rate quotas) have the largest downside for your supply chain, and which early indicators will you monitor?
- Is there an M&A or JV opportunity (e.g., minority stakes in regional producers or toll‑processing arrangements) that can secure preferential allocation for your off‑take?
What our Fesi Powder Market report delivers — practical, execution‑oriented content
The full PW Consulting study is designed as an operational playbook for 2026 action. Highlights include:
- Forward demand model and scenario engine (2026–2032) that lets you stress test demand under alternative macro, regulatory and technology pathways.
- Supplier capacity and utilization database with plant‑level intelligence, commissioning schedules and a risk scorecard for each production asset.
- Price and cost curve analytics, inclusive of energy, alloying inputs and logistics sensitivity — with scenario outputs for contracted vs spot exposure.
- Regulatory impact maps and a playbook that translates new export/import controls into actionable procurement steps (compliance checkpoints, certification requirements, documentation and sample testing protocols).
- Supplier benchmarking and procurement templates — RFP language, specification checklists (particle size, chemical tolerances), contract clauses for allocation and force majeure tailored to the recent trade shifts.
- M&A and partnership shortlists with high‑level financial proxies and integration considerations; an annex with negotiation levers for securing throughput or priority allocations.
- Excel‑based models and slide packs for boardroom briefings so you can convert market insight into procurement and capex decisions within weeks, not months.
Note: the report contains detailed segmentation by region, type (atomized, milled, other) and application with a full breakdown of shares and values. We omit those granular splits here to preserve the “trailer” purpose of this article and to invite you to access the full dataset and interactive tools on our website.
Competitive landscape — who matters and why
The Fesi powder market shows moderate concentration: the top three producers account for a material share of global sales, and the top five increase that footprint further — a structure that enables coordinated supply responses when market signals shift. Against that backdrop, several firms warrant strategic attention:
- DMS Powders (South Africa) — A focused supplier of milled and atomized grades engineered for dense media separation. Their product suite and quality control for slurry applications make them a preferred partner for mining customers that require narrow density control. If your exposure to mining is material, DMS‑specialized suppliers are an allocation play.
- Elkem ASA (Norway) — An integrated global manufacturer with upstream capabilities and well‑developed metallurgical powders. Recent production curtailments in response to market and regulatory developments signal the strategic balancing act large producers are making between price discipline and market share protection.
- Ferroglobe PLC & Finnfjord AS — European producers with strong footholds in alloy and powder supply. Their positioning matters most where regional safeguards or logistics create a premium on local supply.
- OM Holdings Ltd (Singapore) — A diversified supplier with reach across Asia and downstream relationships that can be leveraged for strategic stocks or preferred pricing agreements.
- Stanford Advanced Materials (United States) — A niche, high‑purity supplier focused on ≥99% FeSi grades for demanding deoxidation and specialty steelmaking applications.
- Anyang Lishi & Zhenan Metallurgy (China) — High‑volume producers and exporters that historically supplied large volumes into global markets. New export licensing regimes and batch testing requirements will reprice and reallocate flows; buyers that previously leaned on low‑cost Chinese origins should revalidate qualification pathways and contingency plans.
For each competitor we map strategic levers in the full report: volume flexibility, quality differentiation, geographic exposure, and willingness to trade long‑term vs opportunistic contracts. URLs and company profiles are included in the annex for procurement teams validating counterparty credentials.
Immediate recommendations for procurement and strategy teams (next 90–180 days)
- Initiate a scenario planning sprint that models three regulatory outcomes (status quo, targeted restrictions, broad export controls) and their impact on price and availability for your specific product specs.
- Secure 6–12 month cover on critical grades where supply‑chain frictions are plausible; favor contracts with allocation guarantees and tiered pricing that align supplier incentives with your reliability needs.
- Qualify at least two alternate suppliers for each critical specification and document accelerated qualification steps (testing labs, sample flows, acceptance criteria).
- Task a commercial analytics cell with monitoring leading indicators: expiring quotas, export licence issuance cadence, vessel/charter rates to key hubs and energy price movements at major production sites.
- Map inventory triggers and working capital tradeoffs — use our downloadable threshold model to define reorder points tied to real market signals rather than calendar rules.
Medium‑term moves (2026–2028)
- Evaluate strategic equity or tolling arrangements in regions where long‑term allocations can be secured at a predictable margin.
- Invest selectively in in‑house powder processing capabilities (milling, classification) if premium differentials for tailored particle sizes justify capital.
- Develop an ESG‑aligned supplier program that incorporates traceability, emissions intensity and compliance auditing — buyers who can credibly claim low‑risk supply will capture a valuation premium in specialty segments.
Using the report in your 2026 boardroom
Boards and procurement committees will be asking for three things: a quantified risk exposure, a set of implementable mitigation steps, and a recommended capital allocation that balances upside capture with downside protection. The PW Consulting Fesi Powder Market report is organized to deliver exactly that: an executive summary with three scenarios, a tactical 90‑day playbook, and the financial sensitivities to support an approval package. We also provide a ready‑to‑use slide deck and a customizable Excel model so teams can present alternatives backed by our data.
Final note and call to action
The global Fesi powder landscape in 2026 is best described as growth with guarded fragility: structural demand drivers support a mid‑single digit CAGR, yet trade measures, export licensing reforms and localized capacity decisions create episodic tightness and price dispersion. Smart market participants will convert visibility into selective, contractual advantage rather than blanket hedging or speculative accumulation.
For access to the full data tables, plant‑level capacity database, segmentation breakdowns and supplier scorecards that underpin this executive preview, visit the PW Consulting Fesi Powder Market report page or contact our team for a tailored briefing. The full study contains the granular intelligence you need to convert the strategic implications outlined here into executed decisions in 2026.
For detailed analysis of this topic, please visit the official page: Fesi Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


