



Category: market research
The Acoustic Edge: Strategic Trends and Commercial Opportunities in the Gunshot Detection Systems Market
Urban safety architecture is undergoing a fundamental reassessment. As municipal authorities, critical infrastructure operators, and defense contractors confront escalating security threats, the market for gunshot detection systems has transitioned from a niche public safety tool to a core component of integrated security ecosystems. Valued at approximately USD 1.04 billion in 2025, the sector is projected to expand to USD 2.25 billion by 2032, reflecting a compound annual growth rate of 11.8 percent over the forecast period. This trajectory is not merely a function of rising threat perception; it represents a structural shift in how organizations approach real-time threat identification, response automation, and cross-platform interoperability. For executives navigating capital allocation, technology roadmaps, or procurement strategies, understanding the underlying dynamics of this market is no longer optional.
The growth pattern reveals a market maturing beyond initial adoption cycles. Historical data from 2020 through 2025 shows consistent year-over-year expansion, with the 2025 valuation marking a notable inflection point where commercial and institutional deployments began scaling in parallel with military and homeland security applications. Looking ahead to 2032, the revenue curve suggests sustained momentum rather than a temporary surge. This outlook is underpinned by converging technological advancements, evolving regulatory frameworks, and a clear demand-side pivot toward systems that deliver actionable intelligence rather than passive alerting. Yet growth alone does not guarantee strategic advantage. The market carries structural complexities, technological trade-offs, and competitive pressures that demand careful navigation.
Market Landscape and Core Challenges
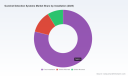
The gunshot detection sector operates at the intersection of acoustic engineering, sensor fusion, and emergency response logistics. Revenue distribution across installation types reflects a clear preference for permanent, infrastructure-integrated deployments, which continue to dominate commercial and municipal contracts. Vehicle-mounted and soldier-mounted configurations maintain a strong presence in defense and tactical mobility applications, while the split between indoor and outdoor use cases highlights a persistent operational reality: outdoor environments account for the majority of deployment volume due to their coverage requirements and public safety mandates, yet indoor installations carry disproportionately high value in critical facilities where response time precision is non-negotiable.
Worldwide Automatic Noise Monitoring System Market
Challenge 1: False Positive Management and Environmental Interference
No metric captures the operational friction of this market more accurately than false positive rates. Acoustic sensors operating in dense urban environments, industrial zones, or high-traffic transit hubs must continuously differentiate between genuine ballistic events and environmental noise—construction equipment, vehicle backfires, fireworks, and even structural resonance. The consequence of misclassification extends beyond alert fatigue; it erodes trust in automated response protocols and can trigger costly emergency mobilization. Recent product iterations have leaned heavily on multi-sensor fusion and machine learning refinement to address this gap, but environmental variability remains a persistent engineering constraint.
Challenge 2: Certification Bottlenecks and Procurement Complexity
Deployment at scale increasingly hinges on regulatory alignment rather than raw sensor performance. In the United States, DHS SAFETY Act certification has become a functional prerequisite for suppliers targeting government agencies and critical infrastructure operators. Without this designation, manufacturers face restricted access to federal contracts and limited eligibility for institutional procurement channels. In the United Kingdom, the National Police Chiefs' Council has reinforced similar expectations through the NPSA Technical Guidance, requiring all deployed systems to appear in the Catalogue of Security Equipment with documented performance metrics. These frameworks elevate accountability but also compress time-to-market for vendors lacking established compliance pathways.
PW Consulting
Challenge 3: Integration Friction Across Legacy Security Stacks
A standalone detection sensor offers limited strategic value if it cannot communicate seamlessly with access control systems, video management platforms, and automated lockdown protocols. Many organizations still operate fragmented security architectures where alert data arrives too late or in incompatible formats to trigger coordinated responses. The market's next growth frontier lies less in improving standalone detection accuracy and more in reducing integration complexity, standardizing data exchange, and ensuring that detection outputs translate directly into executable emergency procedures.
Key Drivers Accelerating Market Evolution
Technological Innovation and Sensor Fusion
The most consequential shift in this market is the move from single-modality acoustic detection to multi-sensor architectures that combine acoustic, infrared, and energy-based inputs. By cross-validating signals across modalities, systems can isolate ballistic signatures with greater confidence and reduce reliance on post-event manual verification. Machine learning layers are now being embedded directly into sensor firmware, enabling continuous adaptation to localized acoustic profiles rather than depending on static threshold settings. This evolution is particularly visible in recent outdoor detection releases, where multi-mode configurations have demonstrated improved discrimination in open environments with higher ambient noise variability.
Military-grade sensing technology is also migrating into civilian and commercial applications at an accelerating pace. Acoustic and energy-based detection platforms originally designed for battlefield situational awareness are being re-engineered for schools, transit hubs, corporate campuses, and industrial sites. This transfer of capability lowers the performance barrier for high-confidence detection while expanding the addressable use-case portfolio. Vendors that can adapt military-proven architectures to civilian installation constraints—without sacrificing durability, calibration stability, or maintenance efficiency—are capturing disproportionate attention from procurement teams.
Policy and Funding Mechanisms as Growth Accelerators
Regulatory and fiscal environments are actively shaping deployment velocity. Federal funding channels, particularly grants administered through the Bureau of Justice Assistance, have made implementation and evaluation resources available for high-crime areas, reducing the financial friction that historically slowed municipal adoption. These programs do not merely subsidize hardware purchases; they incentivize evidence-based deployment models that require measurable outcomes, thereby rewarding vendors that can supply performance data, audit trails, and post-deployment evaluation frameworks.
At the same time, certification regimes are functioning as market filters. DHS SAFETY Act approval and comparable international standards are effectively separating suppliers that can integrate into government and critical infrastructure procurement pipelines from those confined to ad-hoc or private-sector deals. For manufacturers, compliance is no longer a bureaucratic afterthought; it is a strategic capability that determines contract eligibility, pricing leverage, and long-term contract durability.
Worldwide Audio Sensors Market
Demand-Side Shifts Toward Automated Response and Situational Awareness
End-user expectations have evolved beyond immediate alert generation. Security operators now demand systems that classify threat location, estimate trajectory context, and feed structured data into broader emergency management workflows. This shift is driven by the recognition that detection without coordinated response creates operational gaps. Educational institutions, for example, have prioritized indoor detection solutions engineered specifically to minimize false positives in environments where routine noise—sports events, maintenance work, or student activity—can overwhelm conventional acoustic thresholds. The emphasis has moved toward systems that support institutional response plans rather than simply notifying security personnel after an event has occurred.
Supply Chain and Cost Structure Dynamics
Sensor manufacturing, edge processing hardware, and calibration services are experiencing incremental cost optimization as production scales and component standardization improves. At the same time, the cost of deployment is increasingly tied to integration effort, ongoing maintenance, and data management rather than raw hardware expense. Vendors that bundle detection hardware with integration support, remote calibration tools, and performance monitoring dashboards are positioning themselves to capture recurring revenue streams while reducing the total cost of ownership for buyers. This structural change is nudging the market toward service-oriented commercial models rather than one-time equipment transactions.
Competitive Landscape and Strategic Positioning
The market exhibits moderate to high concentration, with a limited group of established players commanding the majority of revenue share. This concentration reflects the capital intensity of sensor development, the importance of certification track records, and the long validation cycles required to earn trust in public safety and defense procurement environments. Yet the competitive field is not static. Differentiation is increasingly defined by architectural approach, integration readiness, and the ability to demonstrate measurable performance in specific deployment contexts.
Company Positioning and Differentiation
- ACOEM Group has anchored its strategy around acoustic threat detection engineered for critical infrastructure and public safety use cases. Its recent system iterations emphasize high-attribute acoustic intelligence engines capable of single-sensor gunshot identification while improving situational awareness. The company's positioning reflects a focus on precision detection with reduced dependency on multi-node sensor arrays, which can lower installation complexity in certain environments.
- EAGL Technology, Inc. differentiates through energy-based detection combined with adaptive response protocols. Its integration capabilities span access control, video systems, and automated emergency workflows, creating a more closed-loop security architecture. DHS SAFETY Act approval further strengthens its eligibility for U.S. government and critical infrastructure contracts, giving it a clear procurement advantage in regulated channels.
- Hyperion Technology Group, Inc. has built its reputation on infrasound-based detection sensors designed for military, homeland security, and industrial applications. Its field-proven deployments and continued R&D emphasis position it as a specialist in environments where conventional acoustic sensing faces physical or operational limitations.
- QinetiQ has extended its EARS family of gunshot localization systems into both soldier-mounted and military police applications. With thousands of portable units shipped and combat-tested validation, the company leans on operational credibility and scalability in tactical mobility contexts. Its SWATS model illustrates how portable localization can complement fixed infrastructure in layered defense strategies.
- Raytheon Company maintains a strong footprint in vehicle-mounted detection, with continued model upgrades targeting faster threat response and improved battlefield situational awareness. Its positioning reflects the broader trend of adapting mobile detection platforms for both defense operations and high-security mobile units.
- Shooter Detection Systems (SDS) has expanded its portfolio across indoor and outdoor environments, combining acoustic and infrared modalities with machine learning refinement. Its recent outdoor system commercialization and institutional indoor deployments highlight a strategy centered on multi-mode accuracy, false-positive reduction, and recognized performance validation through industry awards and safety certifications.
- SoundThinking, Inc. remains a prominent name in acoustic detection for law enforcement, with wide city-level deployments and an expanded AI engine that emphasizes real-time alert processing. Its scale in municipal deployments provides a strong reference base, though the company continues to navigate the broader market shift toward integrated response ecosystems rather than standalone alerting.
- Safety Dynamics, Inc. maintains a focused presence in public safety and law enforcement applications, reinforcing the market's continued reliance on specialized vendors that understand operational policing and emergency response requirements.
Competitive Evolution: Consolidation, Specialization, and New Entrants
The market is exhibiting a dual trajectory. On one side, established players are deepening integration capabilities, expanding certification coverage, and broadening product lines across indoor, outdoor, fixed, and mobile installation types. On the other, specialization is intensifying as vendors carve out defensible positions in infrasound sensing, energy-based detection, portable military localization, or institution-specific false-positive mitigation. New entrants face a high barrier to credibility, particularly when procurement decisions rely on certification status, deployment track records, and interoperability with existing security stacks. Nevertheless, the ongoing migration of military sensing technology into civilian contexts creates openings for companies that can translate advanced sensing capabilities into practical, compliance-ready commercial solutions. Integration partnerships are also reshaping competitive dynamics, as detection suppliers align with video management, access control, and emergency communications providers to offer more complete response architectures.
Future Trends and Commercial Implications
Trend 1: Multi-Modal Detection as the Baseline Standard
The market is moving toward multi-sensor fusion as a default expectation rather than a premium feature. Systems that rely on a single detection modality will increasingly face scrutiny in environments where environmental noise, structural echo, or weather conditions complicate acoustic-only identification. Commercial opportunity lies in architectures that combine acoustic, infrared, and energy-based inputs with on-device machine learning capable of continuous calibration. Vendors that can demonstrate measurable false-positive reduction across varied deployment settings will command pricing leverage and longer contract tenure.
Trend 2: Response Automation and Cross-Platform Interoperability
Detection is becoming only one layer of a broader automated response chain. The next phase of value creation will come from systems that not only identify and locate threats but also trigger access control lockdowns, redirect camera coverage, notify first responders with structured data packets, and log event timelines for post-incident analysis. Procurement teams are likely to prioritize solutions that minimize integration effort and support open data exchange with existing security infrastructure. This creates commercial upside for vendors that invest in API compatibility, standardized alert formats, and pre-built integration modules for common security platforms.
Trend 3: Funding-Linked Deployment Models and Evidence-Based Procurement
Federal and institutional funding mechanisms will continue to influence deployment patterns, particularly in municipal and high-crime area initiatives. Buyers will increasingly require vendors to support grant-aligned implementation models, including performance evaluation, auditability, and documented outcomes. This trend favors suppliers that can provide deployment analytics, maintenance transparency, and post-installation assessment frameworks. At the same time, certification requirements will remain a gating factor for government and critical infrastructure contracts, reinforcing the strategic importance of compliance readiness.
Risks and Uncertainties
Despite the favorable growth trajectory, several uncertainties warrant attention. Environmental and operational variability will continue to challenge detection accuracy in edge cases, particularly in dense urban or industrial settings where ambient noise profiles shift unpredictably. Regulatory frameworks may tighten or diverge across regions, increasing compliance costs and complicating international expansion. Procurement cycles in public safety and defense can be prolonged, with budget approvals and certification timelines creating revenue timing risk. Additionally, as integration becomes more central to system value, vendors that fail to align with prevailing security architectures may face margin pressure or displacement by bundled solution providers.
Strategic Recommendations for Decision-Makers
For Technology Manufacturers and Solution Providers
- Prioritize multi-modal architectures and on-device machine learning that reduce false positives without requiring excessive sensor density. Calibration stability and environmental adaptability should be treated as core product attributes, not secondary engineering tasks.
- Treat certification and compliance as strategic capabilities. Align product development with DHS SAFETY Act requirements and equivalent international standards early in the design cycle to avoid late-stage procurement disqualification.
- Expand integration readiness. Invest in open data interfaces, pre-built connectors for common video and access control platforms, and clear documentation that reduces deployment friction for procurement teams and system integrators.
For Investors and Strategic Capital Allocators
- Evaluate companies based on recurring revenue potential, integration capability, and certification coverage rather than hardware unit sales alone. The market's value migration is tilting toward solutions that support ongoing performance monitoring, maintenance, and automated response workflows.
- Watch for consolidation signals in the integration layer. Vendors that can bundle detection with emergency protocol automation, data analytics, and compliance reporting are positioned to capture higher contract value and longer customer retention.
- Assess exposure to funding-dependent deployment channels. Municipal and grant-aligned contracts can accelerate volume, but they also introduce procurement timing risk and evaluation requirements that may affect cash flow predictability.
For Procurement Leaders and End-User Organizations
- Define operational requirements around response integration before evaluating detection accuracy in isolation. A system that delivers fast, precise alerts but cannot feed structured data into lockdown, video redirection, or first-responder notification workflows will underdeliver relative to total cost.
- Weight certification status and documented performance metrics heavily in vendor selection. Compliance readiness directly affects contract eligibility, especially for government and critical infrastructure deployments.
- Request deployment-specific false-positive data and environmental profiling support. Vendors that can tailor calibration to site conditions and provide ongoing performance transparency will reduce operational risk over the system lifecycle.
The gunshot detection systems market is expanding on the back of technological convergence, regulatory alignment, and a clear demand shift toward actionable response rather than passive alerting. Yet the winners in this environment will be determined less by headline growth figures and more by the ability to deliver accurate detection, seamless integration, and compliance-ready deployment in real-world conditions. Organizations that need granular segment data, regional deployment patterns, pricing architecture breakdowns, or tailored competitive benchmarking will benefit from access to the full research report, which provides the detailed segmentation, company-level financials, and customized strategic recommendations required to convert market awareness into executable decision-making.
For detailed analysis of this topic, please visit the official page: Gunshot Detection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
DSL Chipset Market 2026: Understanding the [5.94%] CAGR Beyond Reported Figures
By PW Consulting, 2026-09-21
DSL Chipsets Market: Strategic Trends and Commercial Opportunities
The DSL chipsets market has entered a period of measured but steady expansion, driven by the continuing need for high-speed broadband access in regions where fiber deployment remains incomplete or economically challenging. Valued at approximately USD 215.0 million in 2025, the market is projected to reach USD 322.0 million by 2032, reflecting a compound annual growth rate of 5.94 percent. This trajectory indicates a mature segment that is not experiencing explosive growth, but rather a sustained, technology-driven evolution shaped by infrastructure realities, competitive dynamics, and shifting demand patterns. For executives and investors operating in broadband hardware, semiconductor supply chains, or telecommunications infrastructure, understanding the forces shaping this market is essential to positioning for the next cycle of investment and product development.
The historical trajectory from 2020 through 2025 reveals a market that has recovered from pandemic-era supply disruptions and stabilized around a baseline of consistent demand. Growth has been supported by incremental upgrades to existing copper-based access networks, particularly in residential and commercial environments where last-mile connectivity continues to rely on xDSL technologies. The forecast period through 2032 suggests that DSL chipsets will maintain relevance, though the pace of expansion will be moderated by the gradual migration toward fiber and wireless alternatives in certain geographies. The market's resilience lies not in volume breakthroughs, but in the ability of chipset vendors to deliver higher throughput, improved power efficiency, and more flexible architectures that extend the useful life of copper infrastructure while accommodating next-generation access requirements.
Market Overview: Positioning in a Mature but Evolving Segment
The DSL chipsets market operates at the intersection of legacy infrastructure and modern broadband expectations. Copper-based networks remain deployed across large portions of the global access landscape, particularly in areas where fiber rollout has been delayed by terrain, cost, or regulatory hurdles. In these environments, DSL chipsets continue to serve as the enabling technology for delivering broadband services that meet contemporary speed and reliability standards. The market's size and growth profile reflect a balance between ongoing replacement cycles, incremental upgrades, and the introduction of higher-performance variants such as VDSL2 and G.fast, which have gained traction in dense urban and suburban deployments where copper vectoring can deliver meaningful throughput improvements.
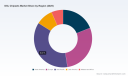
Several structural features define the current market environment. Demand is distributed across residential, commercial, and industrial applications, with residential connectivity representing the largest share of end-use volume. Regional demand patterns vary considerably, with Asia Pacific representing the largest market by value, followed by Europe and North America. Latin America and the Middle East and Africa contribute smaller but growing shares, often driven by infrastructure expansion programs and emerging broadband adoption. The market is characterized by moderate concentration, with the top three players accounting for roughly a quarter of total revenue and the top five holding approximately a third. This fragmentation indicates that no single vendor dominates the landscape, creating room for specialized players, regional competitors, and technology-focused entrants to compete on performance, cost, and support capabilities.
The competitive environment is further shaped by the coexistence of established semiconductor manufacturers and specialized DSL technology providers. Broadcom, MaxLinear, Texas Instruments, Intel's Lantiq division, Qualcomm's Ikanos portfolio, STMicroelectronics, Marvell, Realtek, Sckipio, and Hitron Technologies each occupy distinct positions in the value chain, with product portfolios spanning ADSL, VDSL, and G.fast solutions. The presence of multiple well-resourced incumbents alongside niche specialists suggests a market where differentiation is driven by architecture, power management, signal processing capability, and the ability to support high-density deployment scenarios. This diversity also implies that pricing pressure and technology migration risks are distributed unevenly across vendors, depending on their product focus and geographic exposure.
Key Challenges and Inflection Points
Despite the market's steady growth profile, several challenges and transition points warrant attention. The first is the ongoing tension between copper-based access and fiber migration. While DSL chipsets continue to serve a meaningful role in existing networks, the long-term trajectory of broadband infrastructure favors fiber in many developed markets. This does not eliminate demand for DSL solutions, but it does require vendors and buyers to assess where copper upgrades remain economically viable and where fiber investment will eventually render DSL chipsets obsolete in specific service areas. The inflection point lies in determining the pace of fiber rollout and the extent to which G.fast and VDSL2 can sustain service quality in the interim.
PW Consulting
A second challenge is supply chain concentration risk. Advanced G.fast and VDSL2 chipsets are increasingly manufactured on leading-edge CMOS nodes at a limited set of foundries, including TSMC and Samsung. This concentration creates potential production vulnerability, particularly in the event of geopolitical disruptions or capacity constraints. For manufacturers and buyers who rely on these advanced nodes, the risk is not merely theoretical; it affects lead times, cost stability, and the ability to scale production in response to demand fluctuations. The implication is that supply chain resilience is becoming a strategic consideration, not just an operational one.
A third challenge comes from pricing dynamics in volume-sensitive segments. In ADSL customer premises equipment markets, particularly in Asia and emerging economies, Chinese semiconductor vendors have developed competitive domestic alternatives that exert downward pressure on average selling prices. This pricing pressure complicates margin expectations for incumbents and raises the bar for differentiation. At the same time, geopolitical restrictions have limited the penetration of certain Chinese DSL chipsets in Western markets, creating a bifurcated competitive landscape where regional accessibility and trade policy influence market share as much as product performance.
Together, these challenges point to a market that is not standing still. Vendors and buyers must navigate the intersection of technology lifecycle, supply chain exposure, and regional competitive dynamics. The companies that succeed will be those that can align product roadmaps with realistic infrastructure timelines, manage sourcing risk, and maintain differentiation in the face of pricing pressure.
Key Growth Drivers
Technology Innovation and Signal Processing Advances
Technology development remains a central driver of market activity. Chipset vendors have increasingly focused on improving throughput, reducing noise, and enhancing power efficiency within the constraints of copper-based transmission. Intel's Lantiq division, for example, has emphasized AI-enhanced DSP algorithms for DSL applications, targeting throughput improvements in the 20 to 30 percent range. Such advances are significant because they extend the capability of existing copper infrastructure without requiring immediate fiber replacement, allowing service providers to improve customer experience while managing capital expenditure. Similarly, Broadcom's BCM65x00 family and BCM65550 G.fast vector processor chipsets support high-density multi-DSL and vectoring applications across ADSL2+, VDSL2, and G.fast standards, reflecting a focus on central office and access equipment that can handle multiple line types in a single platform.
MaxLinear's recent product activity illustrates another dimension of technological progress. The company's announcement of an intelligent modular power management solution for next-generation broadband SoCs, supporting DSL, fiber, cable, and fixed wireless access gateways, highlights a shift toward integrated architectures that address power, thermal, and modularity requirements across multiple access technologies. This kind of cross-platform competence is valuable because it allows equipment manufacturers to streamline design cycles and reduce component complexity, even as they support diverse access standards.
Policy and Regulatory Environment
Policy and regulatory developments also shape market dynamics. In the United States, the CHIPS Act incentives have enhanced domestic semiconductor processing capacity, with new facilities expected to create approximately 2,000 jobs by 2029. While the CHIPS Act is broader than DSL chipsets, its impact on domestic manufacturing capacity and supply chain diversification is relevant to any semiconductor segment that depends on advanced nodes and stable production environments. Improved domestic capacity can reduce exposure to geopolitical risk and support more predictable sourcing for vendors and buyers who prioritize supply assurance.
At the same time, regulatory and trade dynamics continue to influence regional market access. Geopolitical restrictions have limited the penetration of certain Chinese DSL chipsets in Western markets, even as those vendors maintain strong deployments in China and other regions. This divergence creates a fragmented competitive landscape where product availability is shaped not only by technical merit, but also by trade policy and national security considerations. For multinational equipment manufacturers, this means that chipset selection cannot be evaluated in isolation from sourcing geography and regulatory risk.
Demand-Side Shifts and Infrastructure Realities
Demand-side behavior continues to support DSL chipset relevance in specific contexts. Residential broadband remains a primary application, with consumers and households expecting reliable connectivity for streaming, remote work, education, and smart home services. In areas where fiber is not yet available, copper-based solutions continue to meet these needs, and upgrades to VDSL2 or G.fast can deliver meaningful improvements in speed and stability. Commercial and industrial applications also contribute to demand, though at lower volume shares, as businesses and facilities rely on broadband access for operations, monitoring, and connectivity in environments where fiber deployment may be delayed or impractical.
The broader demand picture is influenced by the pace of infrastructure investment and the economic calculus of upgrading versus replacing. In many markets, extending the life of copper networks through higher-performance chipsets is a cost-effective strategy, particularly when paired with vectoring and other throughput-enhancing techniques. This demand dynamic supports continued chipset sales, but it also requires vendors to justify the value of DSL solutions against the backdrop of fiber migration plans and wireless alternatives.
Supply Chain and Cost Structure Considerations
Cost structure and supply chain strategy are increasingly important drivers of competitive outcomes. The concentration of advanced node manufacturing among a limited number of foundries means that cost volatility and supply risk are not evenly distributed. Vendors that can secure reliable access to leading-edge production, or that can architect chipsets to operate effectively on more accessible process nodes, may gain an advantage in cost predictability and delivery assurance. At the same time, pricing pressure in ADSL CPE segments from competitive domestic alternatives in China underscores the importance of managing bill-of-materials costs and offering value that goes beyond raw chipset performance.
The cost dynamic also intersects with product architecture. Integrated power management, modular designs, and support for multiple access standards can reduce system-level costs for equipment manufacturers, creating value that is not captured by chipset pricing alone. In this sense, the commercial opportunity is not only in selling chipsets, but in enabling lower total cost of ownership and simpler integration for the broader access ecosystem.
Competitive Landscape and Leading Strategies
The competitive landscape is defined by a mix of broad-line semiconductor companies and DSL-focused specialists. Broadcom and Intel's Lantiq division occupy positions that emphasize vector processing, high-density support, and algorithm-driven throughput improvements. Broadcom's BCM65x00 family and BCM65550 G.fast vector processor address central office and multi-DSL scenarios, while Intel's Lantiq division leverages AI-enhanced DSP to target measurable throughput gains. These strategies reflect a focus on performance and integration in environments where dense line handling and advanced signal processing are critical.
MaxLinear differentiates through broadband SoC power management and modular architectures that span DSL, fiber, cable, and FWA gateways. This approach positions the company as a supplier capable of supporting next-generation access equipment with integrated power and control solutions, rather than offering DSL chipsets in isolation. Texas Instruments contributes analog components and integrated circuits optimized for DSL applications, including low-noise pre-amps and ADC-capable components, supporting the signal chain requirements of DSL systems. Qualcomm's Ikanos Communications portfolio provides ADSL, VDSL, and G.fast chipset options for broadband applications, while STMicroelectronics supplies semiconductor solutions and components for xDSL standards in access network equipment. Marvell offers DSL chipset solutions for broadband access and CPE applications, with support for VDSL and G.fast technologies.
Realtek focuses on cost-effective DSL chipsets primarily for ADSL CPE segments in Asia and emerging markets, reflecting a strategy centered on volume and affordability. Sckipio specializes in G.fast chipset solutions for high-density DSL deployments, targeting environments where advanced copper vectoring is a priority. Hitron Technologies develops DSL chipsets and gateways for CPE and broadband access platforms, combining chipset and endpoint capabilities in certain segments. This diversity of focus illustrates a market where differentiation is achieved through product scope, regional emphasis, technology specialization, and system-level integration.
The market is evolving through a combination of consolidation pressure and niche specialization. Larger players with broad portfolios can leverage cross-platform competence and supply chain scale, while specialized vendors can compete on G.fast performance, power efficiency, or regional cost leadership. At the same time, the influence of Chinese domestic alternatives in volume-sensitive ADSL segments and the constrained access of certain vendors in Western markets suggest that competitive outcomes will increasingly depend on geographic strategy, regulatory alignment, and the ability to deliver differentiated value beyond price alone. The trend is not toward a single dominant architecture, but toward a multi-vector landscape where incumbents, specialists, and regional competitors each pursue distinct advantages.
Power Over Ethernet Poe Chipset Market
Future Trends and Commercial Opportunities
Looking ahead, three trends are likely to shape the market over the next three to five years. The first is the continued optimization of copper-based access through higher-performance chipsets and vectoring techniques. G.fast and VDSL2 will remain relevant in dense urban and suburban environments where fiber rollout is gradual, and chipset improvements that deliver higher throughput and better noise resilience will sustain demand. The commercial opportunity lies in enabling service providers to extract more value from existing copper assets while planning for eventual fiber migration, creating a bridge technology that supports revenue and customer retention.
The second trend is the increasing importance of power management and modular architectures. As access equipment becomes more integrated and energy-aware, chipsets that contribute to lower power consumption, simpler thermal management, and flexible platform design will be more attractive to equipment manufacturers. MaxLinear's modular power management approach for broadband SoCs is one example of this direction. The opportunity here is not limited to chipset performance; it extends to system-level cost reduction and design simplification, which can be decisive in competitive CPE and access equipment markets.
Wi-Fi Chipsets Market
The third trend is supply chain resilience and regional diversification. Given the concentration of advanced node production and the influence of geopolitical and trade dynamics, vendors and buyers will place greater weight on sourcing security, domestic capacity, and supplier diversification. The CHIPS Act-driven expansion of U.S. semiconductor processing capacity is one indicator of this shift. For companies that can demonstrate reliable supply, flexible architecture, and alignment with regional regulatory expectations, this trend creates an opportunity to build trust and secure long-term design wins, particularly in markets where supply assurance is a priority.
These trends are not without risk. Fiber migration could accelerate in certain regions, reducing the addressable market for DSL chipsets faster than anticipated. Supply chain concentration may continue to expose advanced node-dependent products to disruption. Pricing pressure could intensify in volume segments, compressing margins for vendors that cannot differentiate effectively. And regulatory or trade shifts could alter the competitive balance in specific geographies. The commercial opportunity is real, but it requires a clear-eyed assessment of where copper-based DSL solutions remain viable, how supply risk is managed, and what value proposition justifies adoption in a changing infrastructure landscape.
Strategic Recommendations for Decision Makers
For manufacturers and chipset vendors, the priority is to align product roadmaps with realistic infrastructure timelines and to invest in differentiation that goes beyond raw speed. Power management, modular architectures, and support for high-density deployments can create value that resonates with equipment makers seeking lower system cost and simpler integration. Securing reliable access to advanced nodes, or designing for process flexibility where possible, should be treated as a strategic capability rather than a sourcing detail. In volume-sensitive segments, cost leadership must be paired with defensible differentiation to avoid margin erosion from competitive domestic alternatives.
For investors, the market offers exposure to a mature but resilient segment with steady growth and clear technology-driven demand drivers. The key is to evaluate vendors based on their ability to manage supply chain concentration, navigate regional competitive dynamics, and deliver differentiated architectures that support multi-standard access equipment. Companies with strong positions in G.fast and VDSL2, effective power management solutions, and diversified sourcing strategies are better positioned to sustain value as the market evolves. Investors should also monitor the pace of fiber migration and the impact of trade policy on regional market access, as these factors can influence demand trajectories and competitive outcomes.
For procurement and network planning teams, chipset selection should be evaluated in the context of total cost of ownership, supply assurance, and alignment with infrastructure roadmaps. Where copper-based solutions are part of a longer-term access strategy, prioritizing chipsets that support higher throughput, efficient power use, and flexible integration can reduce lifecycle cost and improve service quality. Where supply risk is a concern, diversifying sourcing and considering vendors with stronger regional manufacturing alignment may provide additional assurance. Procurement decisions should also account for the competitive and regulatory environment in each geography, as market access and pricing dynamics can vary significantly across regions.
For executives and planners seeking a deeper understanding of segmentation dynamics, regional demand patterns, pricing structures, and vendor-specific positioning, a more detailed research report can provide the granular data and tailored analysis needed to support precise decisions. Comprehensive segmentation breakdowns, competitive benchmarking, and scenario-based forecasts can help translate the strategic themes discussed here into actionable plans for product development, investment, and procurement.
For detailed analysis of this topic, please visit the official page: DSL Chipsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Computer Cart Market 2026: Why 6.98% CAGR and Mobility Trends Reshape Healthcare IT Infrastructure
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Medical Computer Cart Market
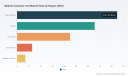
The medical computer cart market has moved from a niche peripheral category to a foundational component of point-of-care infrastructure. Between 2020 and 2025, the sector grew from approximately $163.15 million to $215.0 million in annual revenue, reflecting an accelerated adoption curve driven by digital Records, bedside workflows, and hybrid care models. Looking ahead through 2032, the market is projected to expand at a compound annual growth rate of 6.98%, reaching $344.8 million by the end of the forecast period. This trajectory reflects more than incremental device replacement; it captures a structural re-architecture of how clinical teams interact with technology at the bedside, in imaging suites, and during virtual encounters.
For executives and investors, the outline signals a maturing but still expanding category with concentrated leadership, clear compliance guardrails, and evolving clinical demands. The growth is not uniform across all use cases or geographies. Rather, it is being shaped by the convergence of workflow digitization, safety certification requirements, and the operational need for mobile, battery-enabled computing stations that can move seamlessly across care environments. The market is large enough to attract specialized entrants, yet concentrated enough that established players with strong certification footprints and integration-ready designs continue to set the pace.
Market Snapshot and Core Challenges
The revenue path through 2032 indicates steady expansion with a notable inflection in the mid-2020s, when the market crossed the $200 million threshold and sustained momentum into the late 2020s. By 2032, total revenue is expected to approach $345 million, a level that underscores the category’s transition from optional mobility accessories to integral clinical workflow platforms. This growth is underpinned by recurring institutional procurement cycles, the need to replace aging carts with smarter, safer alternatives, and the broader digitization of bedside documentation, medication administration, and tele-consultation workflows.
Several structural challenges and inflection points are shaping the market’s next phase.
- Regulatory and certification compliance as a market gatekeeper. Electrical safety standards such as UL/EN/IEC 60601-1 and quality management frameworks like ISO 13485:2016 have become baseline expectations for active manufacturers. Products that integrate powered systems or diagnostic accessories increasingly require 510(k) clearance, adding time and cost to development cycles. Compliance is no longer a differentiator; it is the price of entry, which elevates the importance of proven engineering and documentation capabilities.
- Reimbursement ambiguity and procurement cycles. While mobile carts are often covered under durable medical equipment and physician fee schedule categories, there are no specific new CPT or DRG updates that directly target the cart category beyond standard electronic health record infrastructure billing. This means purchase decisions are typically tied to broader hospital IT modernization budgets and workflow efficiency narratives, making adoption sensitive to capital planning cycles and internal ROI framing.
- Workflow integration versus device proliferation. As hospitals deploy more mobile computing stations, the challenge shifts from acquiring hardware to integrating it into clinical workflows without adding friction. Carts that are not optimized for battery management, ergonomic adjustment, antimicrobial protection, or seamless mounting of imaging and telehealth peripherals can become underutilized assets. Procurement teams increasingly evaluate carts as workflow platforms rather than standalone terminals, pressuring manufacturers to deliver systems that reduce cart replacement frequency and align with infection control protocols.
These dynamics create a market where technical readiness, compliance documentation, and real-world usability converge as decision criteria. The result is a category that rewards manufacturers with integrated power systems, proven safety certifications, and designs that adapt to varied clinical settings, while filtering out less differentiated offerings.
Key Drivers of Market Evolution
The market’s growth is being propelled by a combination of technological breakthroughs, regulatory shaping, demand-side behavior changes, and supply-side cost dynamics. Each driver reinforces the others, creating a compounding effect on adoption and product sophistication.
Technological Innovation and Workflow Enablement
The most visible driver is the shift from passive computer stands to intelligent mobile workstations that combine battery management, height adjustability, integrated power systems, and mounting flexibility for cameras, tablets, and imaging peripherals. Recent product movements illustrate this trajectory. In early 2024, a leading telehealth cart platform was updated with integrated camera positioning and device mounting capabilities designed for remote consultations, reflecting the broader expansion of virtual care into bedside and clinic workflows. Around the same time, upgraded workstation carts with integrated battery management systems were introduced to support bedside digital documentation, addressing a persistent pain point around uptime and mobility during long shifts. By early 2025, broader exhibitions of mobile mounts, power systems, and medical carts at major health IT conferences signaled that the category is increasingly presented alongside complementary infrastructure rather than as isolated hardware.
Metabolic Cart Market
These innovations matter because they reduce the operational burden on clinical teams. Battery systems that provide clear charge indicators and reliable runtime diminish downtime and cart swapping. Height-adjustable designs improve ergonomics for both clinicians and patients across varied tasks. Antimicrobial coatings and robust power architectures support infection control and safety requirements. In combination, these features turn the cart from a simple mount into a workflow enabler that can host electronic prescribing, medication administration, and point-of-care documentation without disrupting movement through rooms, bays, and imaging areas.
Policy, Regulation, and Certification as Market Architects
Regulatory and certification requirements are shaping product design and competitive entry. Electrical safety standards for powered systems, quality management expectations for healthcare manufacturing, and, where relevant, premarket notification for diagnostic accessories or powered patient-care configurations create a compliance environment that favors established engineering processes. This environment is reinforcing a market where manufacturers that maintain ISO 9001:2015 and ISO 13485:2016 certifications across design, manufacturing, and service are better positioned to win institutional trust and multi-year contracts.
At the same time, reimbursement structures remain tied to broader electronic health record infrastructure billing rather than to the cart category itself. This does not constrain demand, but it does influence procurement logic: purchasing decisions are more likely to be justified through operational efficiency, error reduction, and bedside documentation improvements than through direct device-level reimbursement. As a result, the policy environment rewards vendors that can articulate clear workflow benefits, demonstrate compliance readiness, and support standardized integration with existing clinical systems.
Demand-Side Shifts in Clinical and Care Delivery Models
Clinical demand is evolving as hospitals and ambulatory providers expand hybrid care, mobile documentation, and bedside digital workflows. Workstations on wheels are increasingly used for medication management, bedside documentation, and virtual consultations, while also supporting imaging workflows that require adjustable ergonomics and reliable power. The rise of remote consultations and point-of-care electronic records has made mobile computing stations more than convenience items; they are becoming essential for care teams that must move between rooms while maintaining continuous access to patient information and communication tools.
This demand shift is also visible in the prominence of hospital and clinic settings as primary application areas, alongside ambulatory surgical centers and other care environments. Facilities are looking for carts that can adapt to varied clinical contexts, from acute care and imaging to outpatient procedures and telehealth. The result is a demand profile that values versatility, durability, and integration potential over narrowly specialized form factors.
Medical Panel PC Market
Supply Chain and Cost Structure Dynamics
Supply-side conditions are influencing both product design and commercial strategy. Lead times, component availability, and the cost of certification and compliance activities affect development cycles and pricing. Manufacturers that can offer multi-year warranties, consistent power system performance, and clear service support are better equipped to manage total cost of ownership arguments with procurement teams. Meanwhile, the emphasis on antimicrobial coatings, integrated power, and ergonomic adjustments adds value but also requires disciplined manufacturing and quality processes, which tends to favor companies with established quality management systems and repeatable production practices.
Cost structures are also being shaped by the growing importance of interoperability and mounting ecosystems. As carts are deployed alongside mobile monitors, tablets, and peripherals, the ability to standardize mounting and power across devices reduces integration friction and can lower total deployment costs. This is pushing manufacturers toward modular designs and robust accessory ecosystems that support varied clinical configurations without sacrificing safety or compliance.
Competitive Landscape and Leading Strategies
The market’s competitive structure remains concentrated, with leading players capturing a significant share of revenue while a broader set of specialized manufacturers competes on workflow fit, certification readiness, and regional service capabilities. The strategic positioning of incumbents reflects a blend of product breadth, compliance documentation, ergonomic design, and integration-ready ecosystems.
Several companies illustrate the range of strategic approaches shaping the category:
- Capsa Healthcare emphasizes mobile computing workstations and telehealth platforms designed for point-of-care electronic records, medication management, and virtual consultations. Its recent updates to telehealth cart platforms with integrated camera positioning and device mounting reflect a focus on enabling remote patient consultations within bedside and clinic workflows.
- Ergotron focuses on medical carts with integrated power systems, height-adjustable designs, and full electrical safety certifications tailored to acute care and imaging contexts. This positioning underscores the importance of compliance-ready engineering and ergonomic flexibility in high-acuity environments.
- RDP Health Ltd offers custom workstations on wheels for electronic patient records, electronic prescribing and medicines administration, and phlebotomy, with features such as 360-degree battery indicators and extended warranties aimed at public health system procurement. This approach highlights regional workflow customization and long-term service reliability.
- Lund Industries (DataCart) provides custom powered and non-powered healthcare computer carts with antimicrobial coatings, sit/stand height adjustment, and multi-year warranties. Its emphasis on customization and durability reflects a strategy centered on adapting to varied clinical configurations while supporting infection control requirements.
- Advantech contributes computerized medical carts and tablets for mobile medication administration, point-of-care documentation, and telehealth in hospitals, positioning its offerings around mobility, documentation efficiency, and broad clinical deployment.
- Parity Medical supplies UK-designed and assembled workstations on wheels for electronic patient records, electronic prescribing and medicines administration, and bedside clinical applications, illustrating the role of regional design and assembly in meeting local procurement expectations and service requirements.
These players are competing on a combination of product features, certification readiness, regional customization, and ecosystem compatibility. The result is a landscape where differentiation is increasingly tied to workflow fit and compliance documentation rather than to hardware novelty alone. Companies that can deliver reliable battery management, clear safety certifications, ergonomic flexibility, and mounting ecosystems that support monitors, tablets, and telehealth peripherals are better positioned to win multi-year contracts and repeat procurement cycles.
Recent market activity reinforces these strategic directions. An advanced medical cart received FDA listing for hospital use in mid-2024, highlighting the regulatory pathway for products that integrate powered systems or diagnostic accessories. Upgraded workstation carts with integrated battery management systems entered the market around the same period, addressing bedside documentation needs with improved uptime and charge visibility. Updated telehealth cart platforms with camera positioning and device mounting expanded remote consultation capabilities, while broader exhibition of mobile mounts, power systems, and medical carts at major health IT events signaled growing integration between carts and surrounding infrastructure. Together, these developments suggest a category that is moving toward more standardized safety expectations, smarter power management, and tighter alignment with virtual care and point-of-care documentation workflows.
Looking ahead, the competitive landscape appears likely to evolve along three lines. First, consolidation pressure may build as larger technology and medical device ecosystems seek to offer more complete mobile computing solutions that combine carts, power, mounting, and software integration. Second, segmentation may continue between general-purpose mobile workstations and more specialized configurations for imaging, medication management, and telehealth, with differentiation driven by certification, ergonomics, and workflow integration. Third, new entrants may find opportunities in niche regions, custom configurations, and service-led models that emphasize long warranties, battery transparency, and local support, particularly where public-sector procurement values compliance documentation and predictable lifecycle costs.
Forward Outlook: Trends and Commercial Opportunities
Based on current growth dynamics and the trajectory of product and regulatory developments, several trends are likely to shape the market over the next three to five years.
Trend One: Workflow-Integrated Mobility Becomes the Baseline. Mobile computing stations will increasingly be evaluated as integrated workflow platforms rather than as standalone hardware. Buyers will expect reliable battery management, clear charge indicators, height adjustability, antimicrobial protection, and mounting options that support cameras, tablets, and monitors. Vendors that design for interoperability with existing clinical systems and accessory ecosystems will capture more procurement interest, while devices that create integration friction will face greater resistance. The commercial opportunity lies in bundling compatible power systems, mounting solutions, and service terms that reduce total cost of ownership and simplify deployment across departments.
PW Consulting
Trend Two: Compliance and Safety Readiness Move from Advantage to Requirement. As electrical safety standards and quality management expectations become more firmly embedded in purchasing criteria, certification readiness will function as a market requirement rather than a differentiator. This will favor manufacturers with disciplined design controls, documented safety testing, and consistent service processes. For buyers, this trend creates an opportunity to streamline procurement by prioritizing vendors with verifiable compliance footprints and multi-year support commitments, reducing the risk of integration delays and lifecycle service gaps.
Trend Three: Hybrid Care and Point-of-Care Digitalization Expand Use Cases. The continued expansion of remote consultations, bedside documentation, and mobile medication workflows will broaden the application profile of medical computer carts. Telehealth-ready configurations, integrated camera positioning, and flexible device mounting will become more important, while carts used in imaging and acute care will need robust power, ergonomic adjustment, and safety certifications. The commercial opportunity is in designing and positioning products that can serve multiple clinical contexts without sacrificing specialization, enabling facilities to standardize on fewer platforms while meeting varied workflow needs.
These trends are accompanied by risks and uncertainties. Reimbursement frameworks remain tied to broader electronic health record infrastructure billing rather than to the cart category, so procurement momentum can be sensitive to capital budget cycles and internal ROI framing. Regulatory pathways for powered systems and diagnostic accessories can add development time and cost, particularly for new entrants or highly specialized configurations. Supply chain variability, component availability, and certification timelines may affect product launches and pricing. Finally, if workflow integration is under-prioritized, organizations risk accumulating underutilized carts that do not deliver expected efficiency gains, undermining the business case for broader adoption.
Strategic Recommendations for Decision Makers
The market’s direction suggests practical priorities for different stakeholder groups. The following guidance translates current dynamics into actionable focus areas.
- For manufacturers: Prioritize workflow integration and compliance readiness as core product attributes. Build battery management systems with transparent charge indicators, support height adjustability and ergonomic flexibility, and maintain documented safety certifications that align with recognized electrical and quality standards. Develop mounting and power ecosystems that accommodate monitors, tablets, and telehealth peripherals, and structure service terms around multi-year warranties and clear lifecycle support. Differentiation will increasingly come from reliability, integration ease, and certification documentation rather than from hardware novelty alone.
- For investors: Evaluate companies on their ability to deliver compliant, integration-ready mobile workstations with defensible service and warranty models. Focus on manufacturers that demonstrate consistent quality management, clear safety certification status, and product lines that serve multiple clinical contexts without fragmenting the portfolio. Watch for consolidation opportunities among specialized players, and consider the commercial value of ecosystems that combine carts, power, mounting, and service support into repeatable deployment packages. Be mindful of regulatory pathway complexity and reimbursement framing, which can influence procurement timing and margin profiles.
- For procurement and clinical operations leaders: Treat medical computer carts as workflow infrastructure investments rather than commodity hardware. Standardize on configurations that meet electrical safety and quality management expectations, and prioritize battery transparency, ergonomic adjustability, and mounting compatibility with existing devices. Build procurement narratives around bedside documentation efficiency, medication management support, and virtual consultation enablement, and align purchasing cycles with broader IT modernization plans to strengthen justification. Evaluate total cost of ownership including service, warranty, and integration effort, and select vendors that can demonstrate consistent compliance documentation and reliable lifecycle support.
As the market approaches the late 2020s, the most successful commercial outcomes will belong to organizations that can connect product capabilities to real clinical workflows, maintain rigorous compliance readiness, and deliver predictable service over multi-year cycles. For executives and investors seeking detailed segmentation data, regional dynamics, application-level revenue splits, and custom scenario analysis, a comprehensive research report can provide the deeper breakdown needed to support procurement planning, portfolio strategy, and investment decisions. The broader market signals are clear; the next step is translating them into precise, actionable plans with the right level of detail.
For detailed analysis of this topic, please visit the official page: Medical Computer Cart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Particle Size Analyzers Market: Why 6.5% CAGR and Healthcare Demand Shift Strategy Through 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Particle Size Analyzers Market: A PW Consulting Outlook
Market Landscape and Core Challenges
The particle size analyzers market has entered a phase of accelerated expansion, driven by tightening quality control requirements across regulated industries and the growing demand for precise material characterization in pharmaceutical, chemical, and advanced manufacturing applications. Measured in millions of USD, the sector moved from approximately 350.0 in 2020 to an estimated 512.0 in 2025, with a projected compound annual growth rate of 6.5 percent through 2032, when revenue is expected to approach 800. The trajectory reflects a market that has transitioned from steady instrumentation replacement cycles to a broader adoption environment shaped by regulatory scrutiny, miniaturization of analytical workflows, and cross-industry quality standards.
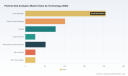
At the macro level, regional demand shows a clear concentration in established industrial and research hubs, with mature pharmaceutical and chemical markets driving consistent procurement volumes. Technology segments remain anchored by laser diffraction as the dominant measurement principle, while complementary methods such as dynamic light scattering, imaging, and nanoparticle tracking analysis continue to expand the addressable use cases in sub-micron and nano-range characterization. End-user demand is similarly structured around sectors where particle attributes directly influence product performance, stability, dissolution behavior, and process efficiency. Healthcare applications represent the largest share of demand, followed by academia, chemicals, and a diversified set of manufacturing sectors including food, cosmetics, and mining. The market remains moderately consolidated, with the top three players accounting for roughly 38 percent of revenue and the top five reaching about 42 percent, indicating that while scale and brand recognition matter, the competitive field still accommodates specialized and regional entrants.
Despite the favorable growth outlook, the market faces three structural challenges that are reshaping commercial strategies:
- Intense capital expenditure scrutiny in healthcare and public-sector laboratories: Particle size analyzers are treated as laboratory capital equipment rather than revenue-generating diagnostic tools. Hospitals and clinical laboratories operate under tight budget envelopes and reimbursement constraints, which prolong procurement cycles and increase competition for available CapEx. This dynamic places pressure on vendors to justify total cost of ownership, service reliability, and workflow integration rather than relying solely on technical performance.
- Standardization, compliance, and costly component requirements: Laser diffraction remains governed by established measurement standards that ensure traceable and repeatable results, but high-end instruments increasingly rely on precision optics and electronics that must meet certified, medical-grade component expectations in regulated pharma and clinical settings. Maintaining ISO certifications, CE marking, and audit-ready documentation adds operational complexity and restricts cost-down strategies, especially for manufacturers serving dual-use markets.
- Competition between performance differentiation and cost-efficient alternatives: The market is not homogeneous. While premium vendors compete on reproducibility, automation, and application-specific support, cost-effective alternatives have expanded reach in laboratory and industrial segments. Buyers in price-sensitive environments are increasingly weighing functional adequacy against brand prestige, forcing incumbents to demonstrate measurable advantages in throughput, operator ease, and integration with broader quality systems.
Key Drivers Shaping Market Dynamics
The growth of the particle size analyzers market is not simply a function of incremental instrument replacement. It is being reshaped by converging forces across technology, regulation, user behavior, and supply economics. Understanding these drivers is essential for assessing where demand will intensify and which commercial models will hold up under scrutiny.
Technology innovation and measurement versatility
Instrument development is moving beyond basic size distribution outputs toward integrated workflows that combine repeatability, automation, and easier interpretation for non-specialist operators. Laser diffraction systems continue to lead because they cover broad size ranges with fast measurement cycles, but the market is also expanding where sub-micron, nanoparticle, and morphological characterization matter. Dynamic light scattering and nanoparticle tracking analysis are gaining relevance for nanoformulations and dispersed systems, while imaging-based methods support morphology and shape factors that size-only outputs cannot capture. These capabilities matter because particle attributes increasingly affect formulation behavior, processing consistency, and downstream performance in complex materials.
PW Consulting
For vendors, the strategic implication is that performance leadership now depends on more than optical precision alone. Automation, sample handling flexibility, software usability, and seamless data traceability are becoming differentiators that influence purchasing decisions, especially where laboratory throughput and compliance documentation are critical. Instruments that reduce operator variability and simplify validation packages can command stronger adoption in regulated settings, even when upfront pricing is higher.
BET Surface Area Analyzer Market
Regulatory expectations and compliance-driven procurement
Regulatory and standardization dynamics play an outsized role in purchase timing, specification requirements, and vendor selection. Laser diffraction measurement practices are anchored by long-standing standards that support traceable and repeatable results, which makes them well suited to pharmaceutical and clinical applications where data integrity is essential. In parallel, major manufacturers maintain CE marking and relevant certifications for instruments used in regulated medical device and pharmaceutical particle characterization. This compliance posture is not a minor detail; it is a procurement prerequisite in many quality-sensitive environments.
At the same time, reimbursement and budgeting realities shape adoption. Particle size analyzers are capital equipment items without dedicated procedural billing codes, so purchasing decisions are strongly influenced by laboratory budget cycles and institutional cost control. The result is a dual dynamic: regulated applications can create durable demand because particle characterization supports quality and process validation, but procurement timing can be delayed or compressed depending on institutional CapEx availability. Vendors that can align their value proposition with audit readiness, documentation support, and predictable service coverage are better positioned to convert technical strength into commercial wins.
Demand-side shifts in formulation, manufacturing, and research
User demand is changing because the importance of particle attributes is rising across multiple end-use sectors. In healthcare and pharmaceutical environments, particle size and distribution can influence dissolution, bioavailability, and consistency of drug products, which reinforces the need for reliable characterization during development and quality control. Academic and research institutions continue to drive demand through fundamental material science, nanomaterial studies, and interdisciplinary programs that require precise sizing across different measurement ranges.
In industrial settings, the motivation is often operational rather than regulatory. Chemical, food, cosmetic, and mineral-processing operations use particle size data to optimize mixing, dispersion, reactivity, flow behavior, and end-product consistency. As manufacturers seek greater process control and reduced variability, the analyzer shifts from a periodic measurement device to a more integral quality assurance tool. This shift expands the value proposition beyond the instrument itself and toward workflow integration, repeat measurement confidence, and support for process decisions.
Supply-side and cost structure pressures
Cost structures in the high-end segment are increasingly shaped by component requirements. Precision optics and electronics in advanced laser diffraction systems often depend on certified, medical-grade components when instruments are deployed in pharma or clinical environments. These requirements constrain aggressive cost reduction and can affect lead times, sourcing flexibility, and service scalability. Meanwhile, in the broader market, regional manufacturers and cost-efficient models are expanding choice for laboratory and industrial users who prioritize functionality and price over premium brand positioning.
This divergence creates an important strategic tension. On one side, compliance and performance requirements support premium pricing and more defensible margins for vendors with strong documentation, service networks, and application support. On the other, price sensitivity in less regulated or more volume-driven segments pressures incumbents to compete on throughput, ease of use, and total cost of ownership. Supply-side strategy therefore matters as much as product performance: sourcing resilience, service coverage, and scalable calibration support can determine whether a product succeeds commercially across regions and customer segments.
Competitive Landscape and Leading Strategies
The market is led by a set of established multinational players with distinct technology portfolios, application focus areas, and geographic strengths. Their strategies reveal how vendors are navigating the tension between premium performance, compliance, and broader accessibility.
Amino Acid Analyzers Market
Malvern Panalytical remains a prominent force in laser diffraction, with a recognized presence in pharmaceutical applications where particle characterization supports drug dissolution and bioavailability studies. Its positioning reflects the broader value of strong brand recognition, application depth, and alignment with regulated workflows. Danaher, through its life sciences portfolio, combines Coulter Principle and laser diffraction systems that serve clinical laboratory and pharmaceutical particle characterization, giving it a strong fit in environments where clinical and quality control demands intersect. HORIBA Scientific offers laser diffraction systems covering sub-micron to larger particle ranges, emphasizing broad measurement versatility for laboratory and scientific use. Anton Paar focuses on laser diffraction analyzers with automation features designed to improve precision and repeatability, an approach that addresses the need for reduced operator variability in controlled environments.
A second layer of competitors illustrates the market's expanding accessibility. Bettersize Instruments, based in China, specializes in cost-effective laser diffraction and dynamic light scattering systems for laboratory and industrial applications, targeting users who require solid measurement capability without premium pricing. Microtrac provides laser diffraction, DLS, and image analysis options for fluid and dry materials, supporting customers who need multi-mode characterization flexibility. Sympatec develops laser diffraction systems oriented toward powders, granules, suspensions, and process monitoring, aligning closely with manufacturing and inline or process-adjacent use cases. Shimadzu supplies particle characterization instruments for laboratory powders and liquids, benefiting from broad scientific instrumentation credibility. Fritsch integrates particle sizing within a wider milling and sizing portfolio, which can be attractive for customers linking sample preparation and analysis. Mettler Toledo incorporates particle size analyzers into automated characterization offerings for laboratory and process use, reinforcing a workflow-oriented value proposition. Scitek Global, also from China, offers lab and medical equipment including particle size analyzers with ISO 13485 certification, a compliance signal that can matter in regulated procurement environments.
These profiles show a market where differentiation is no longer defined solely by measurement method. Leading positions are increasingly tied to application support, software usability, compliance documentation, service reach, and the ability to serve both development and quality control needs. Vendors that can bridge laboratory characterization and process-relevant insights gain an advantage in sectors where particle data must inform operational decisions, not just generate reports.
The competitive landscape is evolving along three trajectories:
- Consolidation pressure among mid-tier and regional players: As buyers demand broader support, calibration, and service coverage, smaller vendors face mounting pressure to scale service infrastructure or partner for distribution. This favors larger players with existing institutional relationships and multi-channel support, while creating opportunities for acquisitions that add geographic coverage or complementary technologies.
- Differentiation through workflow integration and software: Hardware performance remains essential, but commercial advantage is shifting toward automation, data handling, and traceability features that reduce burden in regulated environments. Systems that simplify validation, reporting, and multi-user operation are better positioned to withstand procurement scrutiny.
- New entry and niche expansion in specific measurement ranges and applications: Demand for nano-range characterization, dispersed systems, and specialized sample types continues to create openings for focused entrants. Rather than challenging leaders across the full instrument spectrum, new players often compete by targeting specific size ranges, sample formats, or regional price points with credible certification and application support.
Future Trends and Strategic Opportunities (2026–2032)
The next several years are likely to be shaped by how the market balances performance, compliance, cost, and workflow value. Three trends stand out as particularly consequential for commercial planning.
1. Wider adoption of automated, workflow-oriented analyzers in regulated environments
As laboratories face staffing constraints and greater documentation demands, instruments that reduce operator dependence and improve measurement repeatability will gain traction. Automation in sampling, cleaning, data export, and reporting can lower total cost of ownership by improving throughput and reducing error-related rework. This trend is especially relevant in pharmaceutical and clinical-adjacent settings, where compliance-ready documentation and consistent results support validation and audit processes. Commercial opportunity lies not only in instrument sales but in bundled offerings that include service, training, software updates, and compliance support. The risk is that automation claims must be backed by demonstrable reliability and service coverage; otherwise, perceived complexity can slow adoption.
2. Growing demand for multi-method and application-specific characterization solutions
Particle characterization needs are becoming more diverse as materials and formulations grow more complex. Some applications require broad dynamic range, others need nano-scale sensitivity, and still others benefit from shape or morphology information. This is likely to increase demand for vendors that can offer method flexibility or integrate complementary techniques within a coherent workflow. For end users, the appeal is faster method selection, fewer handoffs between instruments, and more interpretable results for specific applications. For vendors, the opportunity is to position instruments as part of an application solution rather than as standalone measurement boxes. The uncertainty is that cross-method integration can raise cost and support complexity, so success will depend on clear use-case targeting rather than broad but shallow capability claims.
3. Intensifying competition between premium performance and cost-efficient access
Market growth is likely to broaden access to particle characterization in emerging industrial and regional markets, where cost sensitivity and practical usability may outweigh premium brand value. At the same time, regulated and performance-critical applications will continue to reward vendors with strong compliance credentials, service depth, and demonstrated reproducibility. This bifurcation creates a strategic choice for companies: compete premium or compete broadly. The more profitable path may be a segmented strategy that protects high-margin regulated positions while using targeted cost-efficient models to capture volume in less regulated sectors. A key risk is brand erosion if premium positioning is diluted without clear differentiation, or if cost-focused models cannot sustain service and calibration quality over time.
Actionable Guidance for Decision-Makers
The commercial implications of these trends vary by role, but a common theme is that purchasing and competitive decisions increasingly hinge on total workflow value, compliance readiness, and service sustainability rather than on measurement capability alone.
For manufacturers and technology providers
- Prioritize differentiation through automation, software usability, and documentation support that reduces burden in regulated settings. Technical excellence matters, but repeatable workflows and audit-ready outputs often decide procurement outcomes.
- Segment the portfolio deliberately. Use premium, compliance-oriented offerings for pharmaceutical and clinical-adjacent demand, while developing credible cost-efficient options for broader laboratory and industrial segments without compromising support quality.
- Strengthen service, calibration, and regional coverage. In a market where CapEx approval is cyclical and compliance expectations are high, long-term customer value depends heavily on post-sale support and sourcing resilience for precision components.
For investors and strategic planners
- Focus on business models that combine instrument revenue with recurring service, software, and application support, since these elements can improve resilience through budget-constrained procurement cycles.
- Watch for consolidation signals among regional and mid-tier players, especially where scale in service distribution, certification coverage, or application breadth becomes a competitive requirement.
- Evaluate exposure to regulated end-use demand carefully. While pharmaceutical and healthcare applications can sustain premium positioning, purchasing timing may be sensitive to hospital and laboratory budget cycles, which can affect short-term revenue visibility even when long-term demand remains strong.
For procurement leaders and laboratory operators
- Evaluate total cost of ownership, not just purchase price. Consider measurement repeatability, operator training burden, service response time, and documentation support, especially where compliance and throughput matter.
- Define application requirements clearly before sourcing. The “best” instrument depends on sample type, size range, throughput needs, and regulatory context, and over-specifying or under-specifying can create unnecessary cost or performance gaps.
- Request evidence of workflow fit and support capability. References, validation support, and service coverage may be as important as performance specifications when procurement must justify capital allocation within institutional budget constraints.
The strategic picture is clear: the particle size analyzers market is expanding under the influence of regulatory expectations, workflow automation, and broader application demand, but it is also becoming more segmented and more service-dependent. Companies that understand where compliance, cost, and performance intersect will be best positioned to capture durable demand, while buyers who evaluate instruments as part of a broader quality workflow will make more resilient procurement decisions. For decision-makers seeking detailed segmentation data, regional demand patterns, and customized competitive scenarios across technologies and end users, a full research report can provide the deeper quantitative context needed to translate these trends into precise commercial planning.
For detailed analysis of this topic, please visit the official page: Particle Size Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Color Coated Steel Market: How 4.86% CAGR and Asia Pacific's Lead Redefine Revenue Paths
By PW Consulting, 2026-09-21
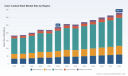
Strategic Shifts and Commercial Opportunities in the Color Coated Steel Market
The color coated steel market is navigating a period of structural transition. Between 2020 and 2025, global revenue grew from $183.0 million to $238.0 million, reflecting steady demand across construction, manufacturing, and consumer applications. The trajectory points toward $330.71 million by 2032, implying a compound annual growth rate of 4.86 percent. This expansion is neither uniform nor frictionless. Regional imbalances, regulatory reconfiguration, and material cost volatility are reshaping how value is created and captured across the value chain. For executives and investors, the opportunity lies not in chasing aggregate growth, but in positioning operations and portfolios around the structural forces that will determine competitive advantage over the next five years.
The market remains moderately concentrated, with three firms accounting for roughly 55 percent of revenue and five firms controlling approximately 62 percent. This concentration masks significant fragmentation at the regional and application levels, particularly among processors and fabricators who serve localized construction and industrial demand. The operating environment is also being redefined by policy shifts and material economics that differ sharply across jurisdictions. The following analysis examines the core challenges, demand drivers, competitive dynamics, and emerging trends that will shape strategic decisions in the color coated steel sector.
Market Landscape and Critical Inflection Points
The period from 2020 through 2025 demonstrates resilient demand, but the growth path is uneven. Revenue crossed the $220 million threshold in 2023 before a slight contraction in 2024, followed by recovery in 2025. This pattern reflects the sensitivity of coated steel demand to construction cycles, import policy volatility, and the timing of large project pipelines. The forecast horizon through 2032 indicates that growth will increasingly be driven by application diversification, coating technology upgrades, and regional supply realignment rather than by uniform volume expansion.
Steel Roofing Market
Several structural challenges are converging at once.
- Policy and trade friction are compressing arbitrage opportunities. Tariff escalations and anti-dumping actions are narrowing the traditional cost advantages of cross-border sourcing. Import-dependent supply chains face higher landed costs and greater planning uncertainty, while domestic producers confront both protection and the pressure to justify scale investments.
- Material cost volatility is reshaping margin structures. The zinc galvanizing layer that provides the essential corrosion barrier accounts for approximately 8 to 12 percent of total production cost, with pricing influenced by global commodity exchanges. Fluctuations in zinc and substrate costs directly affect coating economics, especially for producers operating on thin service-center margins.
- Regulatory mandates are accelerating formulation change. Environmental requirements around chromate-free and ultra-low-VOC coating systems are moving from optional best practice to compliance baseline in key markets. This shifts the competitive conversation from price-per-ton to performance durability, compliance documentation, and downstream certification readiness.
These forces are not isolated. Trade policy influences where capacity is built, material costs determine which coating chemistries remain economically viable, and environmental regulations raise the bar for product qualification. The net effect is a market that rewards operators with flexible production systems, transparent compliance records, and the ability to serve application-specific performance requirements rather than generic commodity volumes.
Key Demand Drivers Reshaping the Market
Growth is being pulled by a combination of technology, policy, demand-side behavior, and supply chain economics. Each driver reinforces the others, creating a landscape where differentiation is increasingly tied to capability depth rather than scale alone.
Coating technology and performance differentiation. Advances in resin systems and surface engineering are expanding the addressable use cases for color coated steel. Polyester-based formulations continue to anchor high-volume construction and consumer applications due to cost efficiency and adequate durability. At the same time, higher-performance chemistries are gaining traction where exposure conditions, aesthetic requirements, and service life expectations justify premium pricing. The practical impact is a market that is segmenting by performance tier rather than by commodity classification. Producers who can demonstrate measurable improvements in weather resistance, color retention, and formability are capturing share in application segments where failure costs are high.
Policy and regulatory reconfiguration. Trade and environmental policy are becoming central to competitive positioning. The United States increased Section 232 tariffs on steel from 25 percent to 50 percent in mid-2025, a move intended to reduce import dependence and stimulate domestic capacity investment. In parallel, the European Union's carbon border adjustment mechanism for iron and steel became fully operational at the end of 2025, imposing carbon-related costs on imported products. Brazil's foreign trade authority also announced definitive anti-dumping tariffs in early 2026 on pre-painted steel from India and China, with rates spanning a wide per-tonne range. These measures alter the economics of inter-regional trade and push buyers and suppliers to reconsider sourcing geography, inventory strategy, and contract structures.
Demand-side behavior and application expansion. Construction remains the largest demand anchor, but the character of demand is evolving. Residential and commercial building activity, infrastructure renewal, and retrofit programs continue to support volume, while specification requirements increasingly emphasize durability, corrosion protection, and environmental compliance. Beyond construction, consumer goods and automotive applications provide additional demand layers that value consistent finish quality, weight efficiency, and formability. The presence of multiple application streams reduces dependence on any single cycle and creates opportunities for suppliers who can align coating systems with specific end-use performance criteria.
Supply chain structure and cost dynamics. The cost stack for color coated steel is sensitive to substrate availability, coating raw materials, and energy intensity. The zinc layer, which serves as the critical anti-corrosion component, introduces commodity-linked cost variability. At the same time, regional production footprints are being reassessed in response to tariff and carbon policy. Some operators are prioritizing closer-to-market coil processing and finishing to reduce exposure to trade friction, while others are investing in integrated capabilities to protect margin and improve qualification speed. Supply chain resilience is becoming a commercial differentiator, particularly for buyers who require consistent lead times and documented compliance across multiple SKUs.
Competitive Landscape and Strategic Positioning
The competitive field spans manufacturers, processors, and traders across North America, India, and South Korea, with distinct strategic postures emerging by region and business model. Companies are not competing solely on price; they are competing on qualification breadth, coating system versatility, compliance readiness, and the ability to support downstream fabrication and assembly requirements.
In North America, a group of active manufacturers and processors has built positions around pre-painted and color coated steel coils for construction, building panels, garage doors, and service canopy applications. Several of these firms emphasize specific resin platforms, including PVDF-based systems and weather-resistant polyester coatings, to align with architectural and industrial specification requirements. The regional focus reflects both the tariff environment and the importance of responsive service, short lead times, and localized technical support for fabricators and building product manufacturers.
India hosts a dense set of manufacturers and exporters with varying capacities and coating portfolios. Some operators focus on large-scale production and broad geographic reach, exporting across multiple continents. Others differentiate by offering a wide range of colors, embossed patterns, and coating systems such as RMP, SMP, PU, and PVDF to serve roofing, cladding, and industrial applications. The combination of domestic demand growth and export orientation creates a competitive environment where scale, standard compliance, and coating versatility are key advantages.
South Korean participants include integrated manufacturers and traders offering pre-painted coils and sheets across multiple coating types, including silicon polyester, PVDF, and high-polymer systems. Several firms maintain substantial annual production capacity and emphasize product standards compliance and appliance-grade finish quality. Their positioning reflects the region's strength in process precision and the importance of meeting specification requirements for downstream manufacturers in construction and consumer durable segments.
Across these regions, several strategic patterns are evident.
- Differentiation through coating systems and compliance. Leading participants are building reputations around specific resin platforms, color consistency, and adherence to international standards. This matters because downstream buyers increasingly require documented performance, VOC compliance, and corrosion resistance data as part of procurement decisions.
- Regionalization of supply as a risk management tool. Tariff and carbon policy are encouraging closer alignment between production, processing, and end markets. Operators with flexible regional footprints can reduce exposure to trade volatility and respond faster to specification changes.
- Capacity and qualification as barriers. In segments where reliability, certification, and throughput matter, capacity scale and process control create meaningful barriers. At the same time, niche processors can compete effectively by specializing in high-specification applications or by offering rapid customization for local fabricators.
The market structure suggests continued divergence. Large integrated players will continue to compete on scale, standard compliance, and export reach, while regional processors and specialists will compete on service speed, coating flexibility, and application-specific performance. Consolidation is possible where scale and compliance costs favor larger operators, but fragmentation can persist where localized service and specification support remain critical to winning business.
Forward Outlook: Three Trends to Watch
Looking ahead to the 2026 through 2032 horizon, three trends are likely to shape where value concentrates and where risk accumulates.
Coil Coatings Market
Trade and carbon economics will continue to rewire sourcing maps. The combination of higher steel tariffs in certain markets, operational carbon border mechanisms in others, and targeted anti-dumping actions will keep inter-regional arbitrage under pressure. Over the next few years, buyers and suppliers will likely place greater weight on nearby processing capacity, inventory buffering, and contract structures that can absorb policy variability. For producers, this environment rewards transparency around carbon intensity and the ability to offer compliance-ready documentation alongside product quality. The commercial opportunity lies in serving buyers who need predictable sourcing under changing policy conditions.
Performance-tier segmentation will intensify. As formulators advance chromate-free and ultra-low-VOC systems and as end markets raise durability expectations, the market will increasingly separate into performance tiers. Commodity-grade volumes will remain important, but growth and margin will be more concentrated in applications that demand long service life, high weather resistance, and strict environmental compliance. Suppliers with validated coating systems, clear test data, and application engineering support will have an advantage in specification-driven segments such as architectural cladding, infrastructure, and corrosion-sensitive industrial uses.
Material cost management will become a strategic capability rather than an operational detail. With zinc-linked costs representing a meaningful share of the production cost base, effective raw material procurement, coating formulation optimization, and waste reduction will directly influence profitability. Operators that can align coating selection with application requirements while controlling input costs will be better positioned to maintain margins through commodity cycles. This is particularly relevant for processors serving price-sensitive construction and consumer segments, where small cost advantages can translate into competitive share gains.
PW Consulting
These trends carry risk. Policy directions can shift faster than capacity decisions, and carbon compliance costs may rise as mechanisms mature. Formulation mandates can increase production complexity and require reformulation investment. Demand in construction-linked applications remains sensitive to interest rates, project finance conditions, and regional economic cycles. Participants who overestimate the stability of current trade and demand patterns risk building capacity or sourcing commitments that become suboptimal if conditions change.
Actionable Guidance for Decision Makers
Different roles in the value chain face different priorities, but several strategic moves are broadly relevant.
For manufacturers and processors. Prioritize coating flexibility and compliance documentation as core capabilities. The ability to offer multiple resin systems, demonstrate VOC and chromate compliance, and provide clear performance data will increasingly determine access to specification-driven demand. Where possible, align production and finishing capacity with the markets you serve most frequently to reduce exposure to trade and logistics volatility. In parallel, treat raw material cost management as a strategic lever, integrating supplier relationships, formulation optimization, and yield improvement into a single margin-protection plan.
For investors. Focus on operators with differentiated positioning rather than undifferentiated volume exposure. Companies with strong certification records, application-specific coating expertise, and regional supply alignment are better placed to navigate policy and cost volatility. Assess exposure to carbon-related costs, tariff sensitivity, and the proportion of revenue tied to performance-tier applications versus commodity-grade volume. In markets where consolidation is plausible, look for signs of scale advantage in compliance, process control, and export readiness; in more fragmented settings, look for specialists with durable local relationships and technical service depth.
For procurement and specification teams. Build sourcing strategies that assume continued policy and cost variability. Diversify between domestic and regional supply options where feasible, validate compliance documentation before award, and include coating performance and environmental requirements explicitly in specifications. Where lead time and availability matter, consider the trade-offs between lowest landed cost and supply resilience, especially for applications where re-specification or replacement carries high downstream cost.
The color coated steel market is moving from a phase where aggregate volume growth was the primary narrative to one where policy, performance, and cost structure determine who wins share and where margin is earned. Navigating this environment requires granular understanding of regional dynamics, coating system capabilities, and the evolving requirements of downstream applications. Detailed segmentation data, company-level benchmarks, and scenario-based sourcing analysis can sharpen these decisions significantly. For decision makers who need to move beyond high-level trends into market-specific sizing, competitive mapping, and tailored strategy options, the full research report provides the deeper dataset and structured analysis necessary to support investment, capacity, and procurement choices with greater confidence.
For detailed analysis of this topic, please visit the official page: Color Coated Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
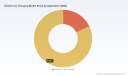
Electric Car Chargers Market: Strategic Trends and Commercial Opportunities
The electric vehicle charging infrastructure sector has shifted from a niche sustainability initiative to a core component of global transportation and energy systems. Over the past half-decade, the market has demonstrated consistent momentum, with revenue scaling from approximately 12.5 billion USD in 2020 to 34.8 billion USD by 2025. Projections through 2032 place the sector on a trajectory toward 143.1 billion USD, supported by a compound annual growth rate of roughly 22.5 percent. This expansion reflects more than incremental adoption; it signals a structural realignment in how electricity is distributed, consumed, and monetized across mobility networks.
USB Car Chargers Market
For executives and investors, the numbers themselves tell only part of the story. The real value lies in understanding what is accelerating deployment, what is constraining it, and where competitive advantages are being forged. The charging ecosystem no longer operates as a standalone hardware play. It intersects with grid capacity, fleet electrification timelines, consumer payment expectations, and increasingly stringent domestic sourcing rules. Companies that treat charging infrastructure as a systems integration challenge rather than a transactional equipment sale are beginning to capture disproportionate margins and market share.
Several inflection points are reshaping the landscape. First, the gap between residential and commercial deployment is widening in strategic importance. While home charging remains foundational for individual vehicle owners, commercial and public charging networks are becoming the primary battleground for scale, utilization rates, and recurring revenue models. Second, the technology mix is bifurcating between slower alternating current solutions and higher-power direct current systems, each serving distinct use cases and requiring different grid interconnections, permitting pathways, and maintenance frameworks. Third, market concentration remains moderate, with the top three players holding a combined share near 35 percent and the top five approaching 42 percent. This fragmentation suggests room for consolidation, but also indicates that regional specialization, software differentiation, and partnership ecosystems matter more than pure manufacturing volume.
Key Drivers Shaping Market Trajectory
Technology Innovation and Performance Thresholds
Charging hardware is evolving from a relatively static product category into a performance-optimized platform. Direct current fast charging continues to advance in power output and thermal management, enabling shorter dwell times for medium- and heavy-duty fleets, ride-hailing operations, and highway corridor deployments. At the same time, alternating current chargers are gaining intelligence through embedded load-balancing algorithms, energy monitoring, and integration with home energy management systems. The practical effect is a market where throughput, reliability, and software responsiveness increasingly determine utilization rather than mere charger availability.
Recent industry activity illustrates this shift. Tritium has been advancing its DC fast charging portfolio through modular platforms designed for ultra-fast public and fleet scenarios, emphasizing scalability and serviceability in high-traffic environments. ZEROVA has focused on high-power commercial and fleet applications, pushing hardware capable of delivering substantial charging capacity in constrained spaces. These developments reflect a broader industry realization that charger specifications must align with operational realities: fleet turnaround windows, peak demand pricing, and site electrical constraints. Companies that design for modular upgrades, remote diagnostics, and predictable uptime are reducing total cost of ownership for operators and improving session completion rates.
Policy and Regulatory Dynamics
Government procurement standards, utility make-ready programs, and domestic content rules are actively shaping where and how infrastructure gets deployed. In the United States, federal-aid projects face evolving Buy America requirements that have prompted discussions about raising domestic content thresholds for EV charger components. Proposed adjustments would increase the required share of domestic component costs, with comment periods and implementation guidance continuing to mature through early and mid-2026. For projects obligated after certain dates, charger compliance frameworks are aligning more closely with general manufactured products rules, which changes how suppliers structure supply chains and document sourcing.
At the state and utility level, interoperability and hardware conformance standards are gaining enforcement traction. Certain public service commission programs have begun requiring ISO 15118-3 hardware conformance for level 2 chargers, signaling a move toward standardized communication protocols that support smoother plug-and-charge experiences, billing transparency, and grid integration. These rules do more than set technical baselines; they influence which products can participate in subsidized programs, how quickly deployments can clear regulatory review, and which manufacturers have the compliance infrastructure to scale across jurisdictions.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are changing the economics of charging networks. Individual consumers increasingly prioritize ease of payment, session reliability, and predictable pricing over raw charger count. Fleet operators and commercial property managers, meanwhile, are evaluating charging infrastructure through the lens of operational continuity, energy cost management, and vehicle utilization schedules. This divergence is pushing vendors to offer more segmented solutions: residential and light commercial options that emphasize installation simplicity and smart energy features, versus high-throughput public and fleet systems built for repeated high-power cycles.
The commercial application segment has become particularly important in revenue terms, reflecting the growing role of workplace charging, retail destinations, logistics hubs, and fleet depots. As more organizations electrify portions of their vehicle assets, charging infrastructure is no longer a peripheral amenity; it is part of the operational backbone. That shift raises the stakes for uptime, remote monitoring, and service response times. It also encourages companies to bundle hardware with network services, energy management tools, and site-level load optimization, creating value beyond the initial equipment sale.
Supply Chain Structure and Cost Dynamics
Hardware manufacturing, component sourcing, and installation capacity remain central to market execution. Domestic content expectations, semiconductor and power electronics availability, and regional manufacturing footprints all influence lead times and pricing stability. Suppliers that can maintain consistent quality while navigating changing procurement rules are gaining an advantage in federally supported and utility-sponsored programs. At the same time, the cost structure of charging deployments is increasingly tied to electrical upgrades, civil works, and network connectivity rather than the charger unit alone. This reality rewards companies that offer streamlined installation pathways, interoperable components, and financing or turnkey models that reduce project friction.
Recent collaboration activity highlights how the industry is adapting to these supply-side realities. Nayax and Tritium announced a global partnership designed to simplify payment enablement for EV chargers. By connecting hardware providers with payment and transaction infrastructure, such arrangements aim to reduce one of the persistent operational pain points: fragmented payment experiences that complicate utilization and revenue reconciliation. In parallel, deployment partnerships are expanding physical networks in targeted corridors. Kempower and Blink Charging, for example, moved forward with a multi-site DC fast charging expansion along the U.S. East Coast, leveraging high-power hardware to strengthen coverage in high-traffic regions. These types of initiatives reflect a market that is increasingly comfortable combining hardware, software, and site development expertise rather than pursuing isolated product launches.
Competitive Landscape and Leading Strategies
The competitive field spans established network operators, hardware specialists, energy technology companies, and regional manufacturers. ChargePoint has built a presence around charging stations and network management solutions spanning home, commercial, and fleet applications, positioning itself around software-enabled session management and broader ecosystem connectivity. Enphase has moved into bidirectional charging, supporting vehicle-to-home and vehicle-to-grid integration that links electric vehicles more tightly with distributed energy resources. This direction points toward a future where chargers function not only as energy consumers but as controllable assets within broader home and grid energy flows.
Other manufacturers are differentiating through durability, compatibility, and targeted use cases. Grizzl-E has emphasized rugged level 2 chargers with multiple connector compatibilities and a domestic manufacturing footprint, participating actively in regional industry events to reinforce brand visibility and dealer relationships. Emporia Energy has focused on smart level 2 chargers with load-balancing and energy monitoring, appealing to users who want visibility into consumption and coordination with household electrical loads. EVOIQO and Apex Charger have concentrated on practical level 2 offerings with flexible installation options and connector-specific designs, addressing residential and light commercial buyers who value straightforward specifications and deployment simplicity.
In the higher-power segment, Tritium and ZEROVA illustrate distinct approaches to fast charging. Tritium’s platform orientation emphasizes modular DC fast charging for public and fleet contexts, while ZEROVA has targeted high-power commercial and fleet applications with substantial output capabilities. The strategic implication is that fast charging is not a single market but a set of segmented requirements: corridor hubs, fleet depots, retail fueling equivalents, and destination sites all place different demands on power delivery, canopy design, electrical service, and maintenance models.
The market structure is evolving through a mix of consolidation, partnership, and specialization. Moderate concentration at the top suggests that scale alone has not yet produced a dominant monopoly-style landscape. Instead, competitive advantage is being built through several overlapping strategies. One is ecosystem integration, where charging hardware is paired with network software, payment services, and energy management features. Another is regional proximity and supply chain resilience, which matters more as domestic content expectations and program eligibility rules tighten. A third is application-specific engineering, where winners design products for clearly defined operational profiles rather than attempting to serve every segment with a single platform.
Trade presence and targeted partnerships are also becoming more important as a signal of execution capability. Grizzl-E’s participation in major industry exhibitions, for instance, reflects the continued relevance of in-person demonstrations, dealer engagement, and hands-on product visibility in a market where installation partners and fleet buyers want to assess build quality, compatibility, and support structures directly. Meanwhile, payment enablement partnerships and multi-site deployment agreements indicate that the industry is moving toward integrated operating models, where hardware reliability, transactional smoothness, and geographic coverage are treated as interconnected commercial priorities.
Forward Outlook: Three Strategic Trends for the Next Three to Five Years
The next phase of market development will likely be defined by integration, standardization, and utilization economics rather than raw charger count alone.
The first trend is the rise of smarter, more interoperable charging networks. As hardware conformance expectations and communication protocols become more firmly embedded in program rules and consumer expectations, chargers that support smooth plug-and-charge interactions, reliable payment processing, and utility-readable data will gain preference. This creates opportunities for manufacturers and service providers that can deliver consistent interoperability across sites and reduce the operational friction that currently depresses utilization in some networks. The commercial opportunity lies in recurring software, maintenance, and energy-management revenue, not just hardware turnover.
The second trend is the continued divergence between residential and commercial deployment pathways. Home charging will remain essential for private vehicle owners, but commercial and public charging will drive a growing share of strategic investment, especially where fleets, high-traffic destinations, and corridor travel converge. Businesses that can optimize commercial sites for load management, peak demand avoidance, and high session throughput will be better positioned to convert infrastructure into dependable operating margins. For residential and light commercial players, the opportunity is in simplifying installation, expanding connector compatibility, and offering intelligent energy features that align with consumer interest in cost visibility and home energy coordination.
The third trend is supply chain and compliance reshaping procurement winners. As domestic content expectations evolve and manufactured product rules become more explicitly aligned with program requirements, suppliers with transparent sourcing, adaptable bill-of-materials strategies, and documentation readiness will face fewer deployment delays. This is especially relevant for federally supported and utility-sponsored programs, where eligibility can determine whether a project moves forward on schedule. Companies that treat compliance as a design and supply-chain function rather than a late-stage paperwork exercise will likely secure more consistent access to capital-intensive deployment pipelines.
PW Consulting
These trends carry risks that decision makers should monitor. Grid capacity and interconnection timelines can constrain site readiness, particularly in areas with rapid deployment interest. Utilization risk remains real in locations where traffic patterns, pricing structures, or payment friction limit session frequency. Regulatory timelines can shift as agencies refine content requirements and program guidance, altering project economics with limited lead time. Finally, hardware reliability and service response continue to influence customer experience and operator reputation; in a market where networks are compared session by session, uptime gaps can translate quickly into lost share.
Actionable Implications for Decision Makers
Different stakeholders face different priority sets, but several strategic moves are broadly relevant.
For hardware and network providers, the priority is to align product roadmaps with operational realities rather than aggregate specifications. That means designing for modular servicing, predictive diagnostics, connector compatibility, and payment interoperability, while also ensuring that supply chains can withstand evolving domestic content expectations. Companies should evaluate whether they compete primarily on hardware performance, network services, energy integration, or geographic coverage, and then build the partnerships necessary to reinforce that position. A clear application focus, supported by reliable installation and service pathways, tends to outperform broad but shallow product portfolios in a market where uptime and user experience drive repeat utilization.
Electric Vehicle Charging App Market
For investors, the opportunity lies in distinguishing between companies that are building durable operating models and those that are relying on short-term subsidy tailwinds or hardware-only economics. Favor businesses that demonstrate recurring revenue potential through software, maintenance, energy management, or transaction services, and that show evidence of compliance readiness and supply chain resilience. Pay attention to deployment partnerships and payment integrations, since these often signal a move toward integrated commercialization rather than standalone product sales. Also weigh regional exposure carefully; markets with strong utility programs, clear procurement rules, and established installation ecosystems will generally outpace fragmented environments where permitting and electrical upgrades slow project velocity.
For commercial buyers and fleet operators, the focus should be on total cost of ownership, session reliability, and site-level energy management rather than sticker price alone. Evaluate charger platforms based on expected utilization profiles, downtime history, remote monitoring capabilities, and the availability of service support in your operating region. Consider how load-balancing, scheduled charging, and potential bidirectional capabilities could reduce demand charges or improve energy flexibility. Engage early with electrical planners and installation partners, because site readiness and interconnection timelines often determine project success more than the choice of charger brand. Where possible, prefer solutions that simplify payment and reporting, since transaction friction frequently undermines utilization and complicates reconciliation across multiple sites.
Why Detailed Intelligence Matters Now
The charging market is moving from rapid qualitative expansion into a more demanding phase where execution quality, regulatory alignment, and utilization economics determine commercial outcomes. In that environment, broad headlines are helpful for orientation but insufficient for planning. Segment-level deployment patterns, regional program eligibility, compliance timelines, and competitor positioning all influence which strategies will hold up under scrutiny. Decision makers who need to prioritize regions, applications, technology paths, or partnership structures benefit from more granular data than a high-level market narrative can provide.
A deeper research resource can help translate these dynamics into specific choices: where to allocate capital, which product segments offer the strongest risk-adjusted opportunity, how regulatory shifts may alter project timelines, and which competitive moves are likely to reshape category leadership. For organizations already operating in the space, that level of detail supports pricing, capacity planning, and go-to-market execution. For those evaluating entry or expansion, it reduces the risk of committing to segments where utilization, compliance, or supply-chain friction is underpriced.
The market trajectory suggests continued scale, but scale alone does not guarantee profitable execution. The companies and investors that perform best over the next several years will be those that treat charging infrastructure as an integrated systems business, align their strategies with evolving rules and user expectations, and base their decisions on segment-level evidence rather than aggregate projections. Detailed research reports can provide the subcategory breakdowns, regional comparisons, and competitive tracking necessary to turn these strategic signals into concrete operational plans and investment committees’ decisions.
For detailed analysis of this topic, please visit the official page: Electric Car Chargers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Shot Blasting Machines Market: Why 6.32% CAGR and Automation Shift Commercial Dynamics
By PW Consulting, 2026-09-21
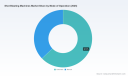
Shot Blasting Machines Market: Strategic Trends and Commercial Opportunities
The global shot blasting machines market is undergoing a structural transformation defined by automation, digital integration, and shifting end-use priorities. With a projected compound annual growth rate of 6.32 percent and an expanding revenue trajectory from approximately $1.5 billion in 2025 toward over $2.3 billion by 2032, the sector reflects sustained industrial demand for surface preparation, cleaning, and finishing solutions. Growth is not merely a function of volume; it is increasingly shaped by how manufacturers align equipment capabilities with stricter cleanliness standards, labor constraints, and operational efficiency targets. Understanding where momentum is building, and which forces are reshaping competitive positioning, is essential for executives evaluating capital deployment, product strategy, or procurement direction.
Market Landscape and Core Challenges
The market has moved through a period of steady expansion, recovering from earlier cyclical softness and reaccelerating as industrial throughput improved across multiple regions. Revenue figures have climbed consistently year over year, supported by replacement cycles, capacity additions in casting and forging, and broader investments in surface treatment infrastructure. This trajectory signals a market that is stabilizing around higher baseline demand, yet one that is also entering a more demanding operational environment where incremental efficiency gains matter as much as unit sales.
Several forces are creating friction and opportunity at the same time. First, the link between surface preparation quality and downstream performance is becoming more visible across metal-intensive industries. Cleanliness, profile consistency, and blast repeatability now carry direct implications for coating adhesion, corrosion resistance, and component life. That makes shot blasting less of a commodity service and more of a controlled process step, raising expectations for equipment precision and documentation.
PW Consulting
Second, labor availability and skill constraints are altering how plants use existing equipment. In several major markets, shortages of experienced metalworking technicians are limiting utilization rates and increasing the cost of manual interventions. This dynamic is pushing organizations to favor machines that reduce operator dependency, simplify changeovers, and maintain output even with thinner skilled-labor pools.
Third, material and consumable volatility is forcing a sharper focus on total cost of ownership. Abrasive media usage, dust handling, and wear-part replacement directly affect operating economics. When media prices fluctuate and alternative materials compete for adoption, manufacturers are increasingly evaluating blast systems not only by purchase price but by consumption control, recovery efficiency, and integration with broader material management practices. These challenges are not purely restrictive; they are also helping separate operators who treat blast cleaning as a cost center from those who treat it as a process capability that can be optimized.
Key Drivers Reshaping the Market
Market momentum is being driven by a combination of technology maturation, regulatory pressure, demand-side behavior, and supply-side cost dynamics. These drivers are interacting, not operating in isolation.
Technology Innovation and Process Control
The most visible shift is the move from standalone mechanical systems toward connected blast platforms that provide visibility into media consumption, wheel wear, and process consistency. Intelligent monitoring and data-linked controls are making it easier to balance output quality with consumable usage. For operators, that means fewer unplanned interruptions, more predictable cleaning results, and stronger alignment between surface preparation and downstream workflow. The practical value is not just automation itself, but the ability to standardize results across shifts, batches, and product mixes.
Alongside connectivity, equipment design continues to evolve around throughput, ergonomics, and serviceability. Machines are being configured to handle a wider range of part geometries and throughput requirements while reducing manual handling. That is especially relevant where mixed production schedules or shorter runs demand flexible equipment rather than rigid high-volume lines. The market is increasingly rewarding systems that combine repeatability with practical adaptability.
Regulatory and Standards Pressure
Regulatory expectations around worker exposure, dust control, and surface cleanliness are strengthening the case for more controlled blast environments. Filtrations, containment, and protective features are becoming central to equipment selection rather than peripheral add-ons. In parallel, widely referenced surface cleanliness standards are pushing structural fabricators and metal processors toward more consistent automated preparation methods.
Cast Steel Shot & Grit Market
The commercial consequence is twofold. Equipment that can demonstrate reliable compliance and cleaner outputs gains a qualitative advantage in bid-sensitive environments. At the same time, buyers are less willing to treat blast capacity as interchangeable, since cleanliness and handling requirements increasingly influence qualification decisions. This is expanding the premium on engineered systems that integrate dust management, media recovery, and controlled blast intensity into a cohesive process.
Demand-Side Shifts in End-Use Industries
End-use demand is becoming more segmented and performance-driven. Automotive and aerospace remain influential, but the nature of demand is shifting toward consistent surface quality, tighter throughput expectations, and components that must meet demanding service environments. Foundries and metal processors continue to rely on shot blasting for casting cleaning and scaling removal, but they are also weighing equipment against broader line efficiency and inspection readiness. Construction, rail, shipbuilding, and other industrial applications contribute to demand in their own ways, particularly where heavy components, infrastructure materials, or repaired assets require dependable surface treatment.
A notable change is that buyers increasingly view blast equipment as part of a broader quality and throughput system. That means machine selection is more closely tied to downstream finishing, coating, inspection, and rework reduction. The implication is that performance claims grounded in process control, media efficiency, and repeatable outcomes are becoming more persuasive than broad equipment descriptions alone.
Supply Chain and Cost Structure Dynamics
Cost pressures are reshaping purchasing logic. Raw material swings, regional production differences, freight variability, and service-part availability all influence the delivered economics of shot blasting equipment. As a result, buyers are paying more attention to system-level operating costs, including media life, wheel wear, filtration load, and maintenance downtime. This is particularly important in environments where machines run frequently and downtime carries disproportionate production penalties.
Shot Peening Machine Market
At the same time, regional manufacturing footprints are becoming strategically relevant. Localized support, faster parts availability, and proximity to end markets can reduce operating risk. In several cases, expanding production capacity in or near high-growth regions is being used to improve service response and strengthen competitive positioning. This points to a market where hardware capability still matters, but responsiveness and execution may differentiate suppliers as much as product specifications.
Competitive Landscape and Leading Strategies
The competitive field is diversified, with global players, regional specialists, and application-focused manufacturers coexisting across different machine types, technologies, and service models. Market concentration remains moderate, indicating that share is distributed across a broad set of participants rather than resting with a small group of dominant incumbents. That structure leaves room for differentiation through technology, application expertise, regional presence, and aftermarket support.
Strategic Positioning of Leading Players
Several companies illustrate distinct strategic arcs within the market. International manufacturers with broad portfolios are emphasizing integrated solutions that span wheel blast and air blast systems, batch and continuous processes, and industrial surface preparation across multiple end markets. Their positioning tends to rely on a wide application base, global service networks, and established product ranges that can be adapted to varied customer requirements.
Other players have leaned toward engineering depth and digital-enabled process control. Smart platform capabilities, real-time wear monitoring, and integration with plant systems are being used to position equipment as a productivity and quality enabler rather than a standalone cleaning device. This strategy is particularly relevant for customers seeking consistent output and lower consumable waste in demanding production environments.
Regional and specialized manufacturers continue to play an important role by focusing on specific machine configurations, material types, or local support expectations. Their advantage often lies in responsiveness, customization, and close alignment with regional fabrication or foundry practices. For buyers prioritizing shorter lead times, local service, or application-specific tuning, these suppliers can be highly competitive.
Recent Moves Shaping the Landscape
Recent activity highlights where competition is intensifying. The rollout of IoT-linked blast platforms with analytics for abrasive media consumption and wheel wear points to a market that is moving toward data-informed operation. Demonstrations combining live performance testing, augmented reality, and optimization sessions indicate growing interest in practical efficiency gains rather than product novelty alone. Participation in international trade events and facility expansion in high-growth regions further suggests that manufacturers are investing in visibility, capacity, and localized support to capture demand more effectively.
Taken together, these developments suggest a competitive environment in which differentiation is increasingly built on three layers: core machine reliability, process intelligence, and service responsiveness. Companies that can align those layers with customer operating priorities are better positioned to capture share in a market where specifications alone are no longer a sufficient advantage.
Consolidation, Fragmentation, and New Entry
The market is not trending toward rapid monopoly-style consolidation. Instead, it appears to be evolving through selective consolidation at the service and technology levels while remaining broad at the product level. Larger players may pursue complementary capabilities, regional reach, or application coverage, but fragmentation persists because blast cleaning requirements vary widely by part type, material, throughput, and labor context. New entrants can still find opportunity by serving niche applications, offering lower-cost configurations, or focusing on fast regional support. However, long-term credibility tends to depend on consistent performance, parts availability, and the ability to demonstrate measurable savings in media usage, downtime, and rework.
Future Trends to Watch
Over the next three to five years, several trends are likely to define how the market evolves and where commercial value accumulates.
- Process intelligence becomes standard rather than exceptional. Connected monitoring, consumables analytics, and integration with plant systems will increasingly be expected in higher-value installations. The commercial opportunity lies in reducing total operating cost, improving consistency, and making blast performance easier to manage across shifts and product variations.
- Automation and labor-efficient designs gain preference. As skilled-worker constraints persist in several regions, equipment that reduces manual intervention, simplifies setup, and supports steady utilization will be favored. This trend creates opportunities for manufacturers who can prove that their machines maintain output with fewer dependent labor inputs.
- Compliance and cleanliness become stronger purchase criteria. Regulatory expectations and surface quality requirements will continue to push buyers toward equipment with better containment, filtration, and repeatable surface preparation. Suppliers that can tie equipment capabilities to documentation, consistency, and risk reduction will have an advantage in qualified and bid-sensitive environments.
These trends are not risk-free. Technology integration can raise upfront complexity and require training, data management, and support infrastructure that smaller users may find difficult to absorb. Material price volatility can still disrupt operating budgets, especially when alternative media options shift demand patterns. And if regional economic conditions slow capital investment, demand may become more replacement-driven than expansion-driven, which would reward reliability and service more than new unit sales. Capital intensity, installation constraints, and the need for practical process adaptation also mean that the strongest opportunities will likely accrue to players who can pair advanced functionality with implementable, site-specific solutions.
Actionable Guidance for Decision Makers
For manufacturers, the strategic priority is to move beyond equipment selection as a purely mechanical decision. Investments should be evaluated against total operating cost, cleanliness consistency, service accessibility, and integration with existing production workflows. The most resilient product and capacity strategies are likely to emphasize flexible configurations, measurable consumable efficiency, and support models that help customers sustain utilization. Companies that can demonstrate how blast performance reduces downstream rework or improves coating readiness will find stronger commercial traction than those competing mainly on headline specifications.
For investors, the attractive question is not simply whether demand will continue to grow, but which business models can convert growth into durable margins. Preference should be given to organizations with clear aftermarket revenue streams, repeatable installation and service processes, and credible differentiation in efficiency or compliance-related capabilities. It is also worth watching how regional expansion, localized support, and digital-enabled offerings reshape competitive dynamics, since these factors can influence both market share and long-term return profiles.
For procurement and operations leaders, the practical focus should be on total cost of ownership and process reliability. Selection criteria should include media consumption behavior, wear-part accessibility, filtration and containment readiness, changeover simplicity, and the supplier’s ability to support consistent utilization. Where possible, buyers should seek performance evidence tied to their own part types and throughput conditions rather than relying on generic capability claims. Aligning blast equipment with downstream quality requirements and labor realities can materially reduce operating risk.
Strategic decisions in this market are best made with detailed segmentation, regional nuance, and application-specific benchmarks in view. A targeted view of machine types, technology preferences, operational modes, end-use demand, and regional dynamics can clarify where investment, procurement, or partnership opportunities are most likely to pay off. For decision makers seeking a deeper breakdown of market size by segment, regional trajectories, competitive positioning, and scenario-based demand outlooks, the full PW Consulting report provides the supporting detail needed to translate these trends into concrete next steps.
For detailed analysis of this topic, please visit the official page: Shot Blasting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Refrigeration Equipment Market: Why Asia Pacific and Ammonia Redefine the 4.9% CAGR Outlook
By PW Consulting, 2026-09-21
The Industrial Refrigeration Equipment Market: Navigating the Next Wave of Growth and Transformation
The industrial refrigeration equipment market is entering a structurally distinct phase. Over the 2020 to 2025 period, the market expanded from approximately $17.87 billion to $22.70 billion, reflecting a compound trajectory that has outpaced many adjacent industrial segments. The forecast period through 2032 points to continued expansion, with revenue projected to reach roughly $31.73 billion, translating to a compound annual growth rate of 4.9 percent. These figures represent more than incremental capacity additions; they signal a market transitioning from steady replacement cycles to a demand profile shaped by regulatory mandates, refrigerant transitions, and capital expenditure patterns that favor higher-efficiency, lower-emission architectures.
Beneath the headline growth lies a landscape that is simultaneously fragmented in execution and increasingly concentrated in strategic influence. The market continues to operate with a moderate concentration profile, where the top three participants command roughly 38 percent of total revenue and the top five approach 46 percent. This structure suggests that while regional specialists, engineering firms, and component suppliers retain meaningful share, scale players and technology-focused incumbents are widening their influence through integrated system offerings, expanding service footprints, and partnerships that reduce project risk for end users. For executives and investors, the implication is clear: the market is large enough to sustain multiple business models, yet selective enough that differentiation in technology, compliance readiness, and service economics will increasingly determine who captures disproportionate value.
Market Context and Strategic Challenges
The current market environment is defined by a collision of long-cycle infrastructure demand and fast-moving regulatory and technological change. Three challenges stand out as particularly consequential for companies operating across the industrial refrigeration value chain.
First, the refrigerant transition has moved from a compliance topic to a design constraint that influences equipment architecture, component selection, and total cost of ownership. Natural refrigerant platforms, especially carbon dioxide and ammonia, are increasingly central to new installations and major retrofits. However, the shift is not uniform. Different applications impose different safety, efficiency, and operating-pressure requirements, and the pace of adoption varies by region, sector, and capital budget. Equipment manufacturers and system integrators are therefore being asked to support a broader portfolio of solutions while maintaining engineered reliability across diverse operating conditions.
Second, cost pressure on inputs is reshaping project economics. Tariff actions affecting steel and aluminum imports have pushed up the cost of compressors, condensers, and structural frameworks. In industrial refrigeration, where systems often represent large capital projects with long payback expectations, material cost volatility can alter bid dynamics, compress margins, and delay commitment cycles. The challenge is not simply higher input prices, but managing the ripple effects through supply agreements, lead-time planning, and value engineering without compromising durability or energy performance.
Third, the market is navigating a complex and evolving standards environment. Regulatory provisions targeting high-global-warming-potential refrigerants, combined with energy efficiency priorities and updated safety standards, are raising the bar for system design and operation. For operators, this means more scrutiny on refrigerant choice, maintenance practices, and lifecycle performance. For suppliers, it means that product differentiation is increasingly tied to compliance readiness, documentation, training, and the ability to support customers through transitions rather than simply shipping hardware.
These challenges should not be read only as headwinds. They are also reshaping the basis of competition. Companies that can offer lower-risk transitions, stronger energy performance, and more predictable project execution are finding greater leverage with customers who must balance operational continuity with regulatory and sustainability obligations.
Core Drivers Shaping the Market
Several forces are working in Concert to reshape demand, pricing, and competitive positioning across industrial refrigeration. The most consequential can be grouped into technology, policy, demand-side behavior, and supply-side cost structures.
Technology Innovation and the Rise of Natural Refrigerant Systems
The most visible technical shift is the acceleration of carbon dioxide and ammonia-based solutions in commercial and industrial applications. Recent industry activity highlights how rapidly these platforms are moving from specialized niches into broader mainstream consideration. At AHR Expo 2026, for example, the exhibition floor featured a strong showing of CO2-based products, including condensing units, transcritical and subcritical compressor technologies, and specialized valves and fittings designed for natural refrigerant systems. This level of visibility matters because it signals that suppliers are not only advancing individual components but also building out integrated ecosystems around refrigerants that require distinct engineering approaches.
For the market, the practical implication is that equipment roadmaps are increasingly aligned with refrigerant performance curves, system controls, and safety architecture. Companies that can combine compressors, heat exchangers, valves, and controls into coherent, application-specific solutions are better positioned to reduce integration risk and improve system reliability. At the same time, component-level innovation remains essential. Specialized fittings, check valves, and ball valves for high-pressure CO2 environments illustrate how seemingly narrow product categories can become critical enablers of broader adoption.
Policy and Regulatory Pressure as a Market Catalyst
Policy is no longer a peripheral factor. In the United States, EPA Technology Transitions provisions under the AIM Act have established a schedule that bans HFC refrigerants with a GWP above 700 in new industrial process refrigeration chillers starting January 1, 2026, with additional phased limits tightening to a GWP of 300 for certain cold storage applications. Broader EPA rules effective at the same date prohibit high-GWP refrigerants across new commercial and industrial refrigeration systems. These timelines create a concrete forcing function for equipment selection and replacement planning.
In parallel, energy efficiency is becoming a more prominent policy target. Industrial refrigeration compressors have been identified by the U.S. Department of Energy as a priority category for energy efficiency standards, reflecting the scale of energy consumption in food and pharmaceutical manufacturing. This matters because it links refrigerant policy with operational cost policy. Customers are increasingly asked to optimize for both environmental compliance and energy consumption, which elevates the strategic importance of high-efficiency compressors, improved heat exchange design, and controls that adapt to load variability. Updated industry standards, such as revised industrial refrigeration guidelines incorporating the latest ISO and safety requirements, further reinforce the direction of travel toward more formalized design and operational practices.
Demand-Side Change Across Food, Pharmaceutical, and Industrial End Markets
Demand is being reshaped by more than regulatory compliance. Cold chain reliability, production quality, and operational resilience have become priority concerns across multiple end-use sectors. In food and beverage operations, temperature control remains foundational to product quality and safety, but customers also care about throughput, redundancy, and energy intensity. In pharmaceutical applications, precision and reliability are paramount, and refrigeration systems are increasingly viewed as part of a broader quality and compliance infrastructure rather than isolated mechanical assets. Chemical processing and other industrial uses add further complexity, where refrigeration may be tied to process conditions, batch consistency, and facility-level efficiency goals.
Road Transport Refrigeration Equipment Market
A notable demand-side dynamic is the shift toward lifecycle thinking. Buyers are increasingly looking beyond first cost and considering the broader economics of refrigerant choice, maintenance requirements, service availability, and expected energy consumption over the life of the system. This does not eliminate price sensitivity, but it does change the criteria by which solutions are evaluated. Suppliers that can articulate and deliver on total cost of ownership, including compliance and service considerations, are better positioned to compete in capex-heavy and mission-critical environments.
Supply Chain Dynamics and Cost Structure Sensitivity
The cost environment remains an important driver of market behavior. Tariff-related increases on steel and aluminum have affected key structural and mechanical components, adding uncertainty to project planning and procurement. In an industry where lead times, sourcing reliability, and build quality all affect customer confidence, input cost volatility can have outsized effects on quoting, scheduling, and margin management.
At the same time, supply chain dynamics are encouraging greater attention to sourcing strategy and design flexibility. Some manufacturers are revisiting material specifications, supplier diversification, and inventory buffers to reduce exposure. Others are using system architecture choices to optimize cost and performance simultaneously, for example by balancing component consolidation against redundancy and serviceability. These adjustments are not merely defensive; they can become sources of advantage when executed with discipline and transparency.
Competitive Landscape and Leading Strategies
The competitive field in industrial refrigeration equipment is diverse, spanning commercial and industrial unit manufacturers, compressor specialists, component suppliers, and project-oriented system integrators. Rather than a single dominant model, the market rewards different forms of differentiation depending on the customer segment and application.
Several companies illustrate the range of strategic positions now in play. Heatcraft Refrigeration Products focuses on unit coolers, condensers, and evaporators for commercial and industrial refrigeration applications, positioning around core components that are widely specified across multiple system architectures. Magna Industrial Refrigeration provides industrial refrigeration equipment, components, and solutions, including unit coolers for commercial and industrial use, reflecting a strategy centered on breadth of product availability and application coverage. NDL Industries emphasizes high-pressure CO2 fittings, valves, check valves, and three-way valves for industrial refrigeration and natural refrigerant systems, illustrating how a component-focused specialist can play a vital role in enabling refrigerant transitions.
PW Consulting
On the compressor and system side, Danfoss, Copeland, and Bock GmbH represent technology-driven positions that emphasize solutions for low-temperature and transcritical CO2 applications, along with compressor platforms tailored to industrial cold storage and process cooling. These players are competing not just on hardware, but on the ability to offer engineered solutions that simplify adoption of natural refrigerants and support specific performance targets. Frigo Mekanik represents a complementary model, specializing in project design, manufacturing, and turnkey installation of industrial refrigeration cooling systems. This approach highlights the continuing importance of integration capability, especially where site-specific constraints, local service requirements, and project execution risk are significant.
Recent industry activity reinforces the direction of these strategies. The IIAR Natural Refrigeration Conference and Heavy Equipment Expo featured exhibitors such as Magna Industrial Refrigeration by Heatcraft, underscoring continued engagement with industrial refrigeration and natural refrigerant safety and equipment. Meanwhile, Frigo Mekanik’s participation in the HVACR Egypt Expo 2026 points to the regional expansion of project-oriented players seeking exposure to international demand and project pipelines. On the event calendar, RETA’s national conference continues to provide a focused forum for industrial refrigeration systems and components, reinforcing the importance of concentrated industry gatherings in shaping technology diffusion, standards awareness, and supply chain relationships.
Worldwide Compression Refrigeration Machine Market
The competitive trends that emerge from this landscape are best described as selective integration paired with targeted specialization. Larger players are broadening their offerings to reduce customer friction across specification, installation, and service, while specialized suppliers are deepening their role in critical subsystems that become differentiators in natural refrigerant applications. The market is not necessarily moving toward a single consolidated model; instead, it is evolving toward ecosystems in which components, compressors, controls, and project capabilities are combined in ways that reduce total risk for the buyer. In that environment, companies that can demonstrate compliance readiness, reliable performance under changing refrigerant regimes, and strong service economics are likely to capture a disproportionate share of high-value projects.
Forward Outlook: Trends and Opportunities for 2026 to 2030
Looking ahead, the market is likely to be shaped by a small number of reinforcing trends that translate into defensible commercial opportunities for well-positioned players.
One major trend is the continued mainstreaming of natural refrigerant solutions in new builds and retrofits. As regulatory deadlines take effect and customer expectations around environmental performance rise, CO2 and ammonia platforms will see increasing specification in a wider range of applications. The commercial opportunity lies not just in selling equipment, but in helping customers manage the engineering, safety, and operational implications of these systems. Suppliers that can standardize design approaches, simplify commissioning, and provide robust field support will be better positioned to scale adoption without eroding reliability.
A second trend is the tightening link between refrigerant policy and energy efficiency. As efficiency standards and compliance requirements reinforce one another, end users will increasingly look for solutions that reduce both emissions exposure and operating cost. This creates opportunities around high-efficiency compressors, improved heat transfer designs, advanced controls, and integrated monitoring that supports optimization over time. The upside is especially significant in sectors with high utilization and sensitive temperature requirements, where even modest efficiency improvements can translate into meaningful operational savings.
A third trend is the growing importance of service, lifecycle support, and standards-based execution. As systems become more specialized and regulations more detailed, the value of post-sale support rises. Customers will increasingly favor partners that can help with maintenance planning, technician training, spare parts availability, and compliance documentation. This shift favors companies that treat service not as an afterthought, but as a core part of the commercial proposition. It also raises the stakes for component and equipment suppliers to design for maintainability and to align their offerings with updated industry standards and safety practices.
These trends are not without risk. The pace of adoption may vary by region and application, and customers may delay capital decisions if cost pressures, interest rates, or project timelines become unfavorable. Material cost volatility can continue to complicate bidding and margin planning. In addition, technological transitions can create temporary friction, especially where engineering expertise, trained labor, or supply availability lag behind product availability. Companies should therefore treat natural refrigerant leadership as a long-term play that requires disciplined execution, not simply a product-line expansion.
Strategic Implications for Decision Makers
The most useful way to approach this market is to align strategy with the forces that are most likely to determine purchasing decisions and competitive outcomes over the next several years. The following recommendations are intended to separate signal from noise and focus action where it matters most.
For equipment manufacturers and system integrators, the priority is to reduce the friction of transition. This means developing and communicating clear pathways for natural refrigerant adoption, strengthening integration across components and controls, and reinforcing service and training capabilities that lower customer risk. Where material cost pressure is persistent, value engineering and supply chain resilience should be treated as strategic capabilities rather than transactional tasks. Differentiation will increasingly come from how well a company helps customers navigate compliance, efficiency, and reliability together.
For investors and strategic partners, the opportunity is to identify businesses whose value is tied to durable shifts rather than short-cycle demand. Indicators of resilience include exposure to applications with high uptime requirements, strong positions in components or subsystems essential to natural refrigerant systems, and service models that generate recurring value beyond initial equipment sales. It is also worth watching how companies adapt to cost volatility and whether they can convert regulatory pressure into differentiated offerings rather than treating it as a compliance burden.
For procurement leaders and end-user organizations, the focus should be on total cost and transition risk. Specifying equipment with an eye toward lifecycle energy performance, refrigerant compliance, service availability, and ease of maintenance can reduce exposure to future regulatory changes and operating cost escalation. Where capital projects are planned, early engagement with suppliers on system architecture, standards alignment, and local support can improve execution certainty and reduce the likelihood of costly rework or delayed commissioning.
For all of these audiences, timely access to detailed market data can sharpen decision-making. Segment-level dynamics, regional demand patterns, competitive moves, and regulatory timelines all influence how opportunities should be prioritized. A focused view of these variables helps turn broad market growth into a more actionable plan, especially when decisions involve capital intensity, long service life, and compliance-sensitive technologies.
Closing Perspective
The industrial refrigeration equipment market is large, expanding, and increasingly governed by structural forces that reward clarity of strategy. Growth to the mid-2030s is expected to remain steady, but the more important story is how that growth is being shaped by refrigerant transitions, efficiency priorities, input cost pressures, and the rising importance of service and integration. Companies that can combine technical strength with compliance readiness, project reliability, and lifecycle value will be best positioned to convert market expansion into durable advantage. For executives, investors, and procurement leaders, the practical task is to use these signals to prioritize where to invest, where to differentiate, and where to reduce risk before the next wave of regulatory and demand-side change fully settles in.
For detailed analysis of this topic, please visit the official page: Industrial Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Jet Engines Market: Why 6.5% CAGR and Civil Aviation’s 53% Share Redefine Growth
By PW Consulting, 2026-09-21
Strategic Fronts in the Jet Engines Market: Navigating Growth, Technology, and Geopolitical Complexity
The global jet engines market is entering a phase defined by the intersection of sustained demand recovery, accelerating technological evolution, and heightened geopolitical friction. Revenue for the segment reached USD 78.9 billion in 2025 and is projected to expand to USD 122.34 billion by 2032, translating to a compound annual growth rate of approximately 6.5% across the 2026–2032 forecast window. These figures reflect a market that has moved past the immediate disruptions of the early 2020s and is now being shaped by long-cycle fleet investment, regulatory pressure on emissions, and shifting supply-chain configurations. For executives and capital allocators, understanding where value will concentrate requires looking beyond headline growth and examining the structural forces that are redefining competitive advantage in propulsion.
Trajectory and Structural Dynamics
The market’s expansion over the 2020–2025 period was uneven but steadily positive, moving from roughly USD 64.78 billion in 2020 to the current 2025 baseline. Growth is now supported by a broad backlog of commercial aircraft deliveries, renewed military modernization programs, and the gradual replacement of aging powerplants with higher-thrust, more fuel-efficient configurations. The market remains moderately fragmented at the top, with the top three firms accounting for about 24.6% of revenue and the top five reaching approximately 26.2%. This concentration level indicates that durable pricing power and aftermarket control are still influenced by a small set of incumbents, even as specialized suppliers and regional players gain relevance in components, accessories, and dedicated platform programs.
Key Challenges and Inflection Points
Three structural challenges are redefining how value is captured across the jet engines market. First, the tension between near-term cost pressures and long-cycle innovation is intensifying. Engine development requires multi-year investment with uncertain returns, while operators and airlines are simultaneously sensitive to fuel costs and total operating expense. This creates a delicate balance where manufacturers must deliver measurable efficiency gains without destabilizing unit economics or delivery timelines. Second, the regulatory and trade environment is becoming more fragmented. Export-control measures now extend to certain civil aircraft parts when there is a risk of military end-use, and tariff frameworks have introduced new complexity for engine and aircraft trade flows. Supply commitments increasingly need to account for jurisdictional restrictions, license requirements, and sourcing adjustments. Third, the aftermarket is becoming a strategic battleground. As new engine families enter service, the long-term service, repair, and overhaul ecosystem will determine a meaningful share of lifecycle profitability, particularly for narrow-body and regional platforms that operate in high-cycle environments.
Core Drivers Reshaping Demand and Value Creation
The market’s direction is being shaped by forces that cut across technology, regulation, demand behavior, and cost architecture. Each driver interacts with the others, creating opportunities for firms that can align product strategy with changing operating realities.
Technology Innovation as a Competitive Lever
Efficiency and emissions performance are no longer secondary attributes; they are central to platform selection and long-term fleet economics. Next-generation engine programs are increasingly built around higher bypass ratios, advanced materials, and architectures that reduce fuel burn and carbon intensity. CFM International’s RISE program, for example, has matured technologies aimed at reducing net carbon emissions by up to 20% for the next-generation CFM engine targeted for mid-2030s entry. This kind of forward-looking development matters because it signals a shift from incremental upgrades to platform-level architectural change. For manufacturers, the implication is clear: differentiation will depend on the ability to demonstrate credible performance improvements that reduce operating costs while meeting evolving environmental expectations. For buyers, the practical question is whether near-term configuration choices will hold up under future regulatory and fuel-price scenarios.
Policy, Regulatory and Trade Dynamics
Policy is becoming a more direct factor in engine market economics. In early 2026, U.S. export-control measures under the EAR began requiring licenses for certain civil aircraft parts and components destined for China when there is a risk of military end-use. Earlier, U.S. authorities paused certain exports of aircraft and semiconductor technology, including jet-engine components, to China in response to Beijing’s restrictions on critical minerals. At the same time, the Trump administration imposed new tariffs on aircraft and engines in 2025, with exemptions for USMCA-compliant aerospace components from Canada and targeted measures against selected Chinese end-users. These developments do not simply change trade flows; they reshape sourcing strategies, after service coverage, and the relative attractiveness of different manufacturing locations. Companies that can design flexible supply chains and maintain compliance assurance will have an advantage in preserving program continuity and customer confidence.
Demand-Side Shifts in Civil and Military Aviation
Demand is being driven by two reinforcing trends. In civil aviation, airline fleets are moving toward more efficient narrow-body and regional platforms, supported by sustained travel demand and a desire to reduce operating costs. In military aviation, modernization programs continue to require propulsion solutions that balance performance, survivability, and long-term sustainment. The market structure reflects this dual demand: civil aviation represents the majority of revenue, while military aviation remains a substantial and technologically demanding segment. For suppliers, this split suggests that growth is unlikely to come from a single path. Commercial programs reward scale, reliability, and low total cost of ownership, while defense and specialized platforms reward capability, customization, and secure production relationships. Firms that can manage both worlds without diluting execution quality are likely to maintain stronger strategic positioning.
Supply Chain and Cost Architecture
Cost dynamics remain a defining constraint. Global average jet fuel price fell 11.4% week-on-week to $141.64 per barrel, with U.S. Gulf Coast prices at $3.30 per gallon as of early June 2026. Even with this near-term relief, fuel continues to be a major operating expense, and volatility keeps efficiency on the agenda. At the same time, engine-makers are investing in site expansion and new manufacturing capacity to support output and complex part production. Safran, for example, expanded operations in Le Creusot to manufacture complex parts for Rafale engines, and Williams International began building a new $1 billion turbine engine factory in Florida. These investments suggest that capacity, precision manufacturing, and localized production are becoming as important as design leadership. For procurement teams and investors, the relevant insight is that the cost structure of propulsion is increasingly tied to manufacturing footprint, supply resilience, and the ability to manage long-lead inputs without sacrificing quality.
Competitive Landscape and Strategic Positioning
The market’s competitive structure is shaped by a small number of engine families, collaborative ventures, and a layered supplier base. Differences in platform focus, aftermarket control, and geopolitical exposure create distinct strategic positions rather than a single race to the bottom on price.
Leading Companies and Differentiated Advantages
GE Aerospace remains a central force in commercial turbofans, designing, manufacturing, and servicing a broad portfolio that includes CF34, CF6, the CFM LEAP family, CFM56, GEnx, and GE9X, alongside military engines for narrow-body, wide-body, and business aviation. Its breadth across multiple aircraft categories gives it scale and the ability to serve both high-volume and premium long-haul segments. Pratt & Whitney focuses on large commercial turbofans such as the GTF family, PW1000G, PW4000, and PW6000, powering platforms including the Airbus A320neo family, A220, and Embraer E-Jets. Its strategy is closely tied to narrow- and regional-jet adoption, making reliability and engine-family support important differentiators. Rolls-Royce positions itself strongly in wide-body propulsion through the Trent family, including Trent XWB, Trent 7000, Trent 900, Trent 500, and Trent 800 for aircraft such as the Boeing 787 and A350. This wide-body emphasis gives it a distinct role in long-haul operations where thrust requirements and mission profiles differ from single-aisle work.
Safran Aircraft Engines and CFM International illustrate the strategic value of joint-venture structures and platform concentration. CFM International, a 50/50 GE Aerospace–Safran JV, produces the LEAP and CFM56 narrow-body turbofans for the Airbus A320neo family and Boeing 737 MAX. Safran contributes the LEAP-1A/B/C single-aisle turbofans and brings additional reach into military programs. The JV model supports scale and resource sharing while concentrating risk and reward on dominant narrow-body platforms. MTU Aero Engines adds a complementary layer by focusing on component manufacturing and support for Pratt & Whitney GTF family engines and PW4000 engines, while also participating in next-generation fighter engine development. This positions MTU as a critical supplier and technology partner rather than a single-brand original equipment manufacturer. Tusaş Engine Industries supports indigenous jet engines and engine parts or modules for UAVs, commercial, and military aircraft, alongside assembly and component production for international programs. Its profile reflects a growing regional capability set that is especially relevant where sovereignty, defense readiness, and local content requirements shape procurement. Williams International rounds out the landscape with the FJ33/FJ44 business jet turbofan family, serving general aviation and business aircraft platforms. This specialization in business aviation creates a focused niche where product range, service responsiveness, and platform fit matter more than mass-market volume.
Recent Developments and Strategic Implications
Recent company actions show how the competitive field is shifting in practice. In May 2026, SSAMC became the first CFM LEAP Premier MRO Provider in China, and in April 2026, IAG and CFM signed a new LEAP Premier MRO license agreement. These moves underscore the importance of controlled aftermarket expansion and the strategic value of service authorizations in key geographies. In January 2026, Safran expanded operations in Le Creusot to manufacture complex parts for Rafale engines, reinforcing defense-oriented capacity. In February 2026, Safran launched the European Clean Aviation TAKE OFF project with partners, pointing toward collaborative decarbonization efforts that may influence future engine architectures and supporting ecosystems. Tusaş Engine Industries showcased national aviation engines at SAHA 2026 in May 2026, aligning with regional demand for sovereign propulsion capabilities. Williams International’s new $1 billion turbine engine factory in Florida, announced in April 2026, reflects continued investment in business aviation manufacturing capacity. Together, these developments highlight three recurring themes: the expanding importance of MRO ecosystems, the continued layering of defense and commercial production needs, and the strategic use of facility investment to support both volume and specialized output.
Emerging Structural Trends in Competition
The competitive landscape is not simply consolidating or fragmenting; it is becoming more layered. On one hand, integrated engine families and JV structures continue to concentrate value in capable incumbents with strong platform positions and aftermarket capability. On the other hand, specialized suppliers, regional manufacturers, and platform-specific entrants are gaining relevance in components, modules, UAVs, and defense programs. For the market as a whole, this means competition is increasingly multidimensional. Some firms will compete on scale, fuel efficiency, and global support networks. Others will compete on customization, regional access, and secure production relationships. New entrants are unlikely to displace the largest engine franchises quickly, but they can create meaningful influence in niches where local content, sovereign requirements, or specialized missions shape purchasing decisions. The strategic question for incumbents is whether they can preserve platform leadership while accommodating new suppliers and navigating trade-sensitive sourcing. For smaller players, the opportunity lies in demonstrating differentiated technical value and reliable execution in selected programs.
Diesel Engines Market
Forward Outlook: Where Value Is Likely to Concentrate
Looking across the 2026–2032 horizon, three trends are likely to shape commercial outcomes and define where strategic advantage can be built.
Efficiency as a Default Requirement, Not an Optional Upgrade
As next-generation engine technologies mature and environmental expectations tighten, efficiency will move from a competitive differentiator to a baseline requirement. CFM International’s RISE program is one example of how propulsion roadmaps are being structured around materially lower carbon emissions for mid-2030s entry. This matters commercially because efficiency improvements affect fuel costs, maintenance profiles, and fleet planning over long asset lives. For manufacturers, the opportunity is to turn technology roadmaps into credible product narratives and delivery commitments. For operators and financiers, the opportunity is to align platform selection with future operating conditions rather than only current economics. The uncertainty is timing: technology maturation, certification pathways, and airline fleet cycles do not always move in sync, and early positioning can carry commitment risk if deployment schedules shift.
Geopolitically Aware Supply Chains and Aftermarket Coverage
Trade policy, export controls, and tariff structures are now part of the market’s operating environment. License requirements for certain civil parts destined for China when military end-use risk exists, combined with broader export pauses and targeted tariffs, mean that engine supply and service coverage need to be mapped against jurisdictional rules. This creates a strategic premium for firms that can maintain resilient sourcing, qualify alternative supply paths, and offer customers predictable service continuity. Over the next few years, we can expect more attention to regional MRO capacity, localized production for sensitive platforms, and structured compliance management as part of customer value propositions. The risk is that overly rigid supply designs reduce flexibility, while overly simplified assumptions about trade rules create disruption when regulations change. The balance will favor companies that treat geopolitical exposure as a managed variable rather than a background condition.
Aftermarket Control as a Profitability Anchor
As new engine families accumulate service hours, the aftermarket will increasingly determine lifecycle economics. Service agreements, MRO provider designations, and license relationships are becoming more visible strategic tools. Recent MRO agreements involving CFM and regional providers show how engine-makers are building service presence in important markets. This trend is likely to continue because aftermarket revenue can be more stable and recurring than new-engine delivery cycles, especially for high-utilization narrow-body fleets and long-serving military platforms. For competitive positioning, the ability to provide reliable, authorized support can reinforce customer lock-in and improve total-value perception. The risk is that aftermarket expansion can become uneven if service capacity, parts availability, or regulatory access does not keep pace with engine placement, especially in complex or trade-sensitive regions.
Rocket Engine Market
Actionable Guidance for Decision-Makers
The jet engines market offers strong long-cycle growth, but capturing value requires decisions that reflect technology timing, trade complexity, and aftermarket strategy rather than relying on demand growth alone.
For Manufacturers, Program Leaders, and Suppliers
Align product roadmaps with the efficiency expectations that are now reshaping platform selection. This means investing not only in performance claims, but in certification progress, serviceability, and demonstrable operating-cost reduction. Build supply strategies that can tolerate export-control and tariff friction without disrupting core programs. Where possible, diversify critical component sources and maintain clear compliance pathways for cross-border movement of parts and technical data. For component suppliers and specialized manufacturers, identify niches where sovereign content, defense readiness, or dedicated platform support create structural demand, and focus on execution reliability and qualification speed.
For Investors and Corporate Strategy Teams
Evaluate propulsion exposure with a focus on lifecycle economics, not only unit sales. Engine programs with strong aftermarket potential, durable platform adoption, and manageable trade exposure are likely to offer more predictable value than those dependent on narrow delivery windows. Pay attention to where capacity investments are being made and how service coverage is expanding, because these signals often precede shifts in competitive strength. Be attentive to concentration risk and to the fact that market leadership may be unevenly distributed across civil and military segments, regions, and engine types. A portfolio view that distinguishes between high-volume narrow-body exposure, wide-body specialization, and defense-linked production can provide better clarity on where returns are most likely to materialize.
For Procurement, Fleet Planners, and Operating Companies
Treat propulsion selection as a multi-period decision. Engine efficiency, fuel-price exposure, support availability, and compliance complexity should all be weighed together, because a lower acquisition cost can be offset by higher operating expense or service constraints over time. When evaluating options, prioritize vendors that can demonstrate reliable local or regional support, clear licensing and trade readiness, and stable parts and MRO pathways. In trade-sensitive contexts, structure sourcing and service plans to reduce disruption risk, including contingency arrangements for spare parts, repair capacity, and technical support. Where specialized platforms or UAVs are involved, consider whether indigenous or regional capability offers strategic value beyond pure cost comparison.
PW Consulting
Why Deeper Intelligence Matters Now
The market is moving on several axes at once: technology roadmaps are advancing, trade and export conditions are shifting, and aftermarket relationships are becoming more strategically important. These changes alter which combinations of platform, geography, and supplier capability will generate the strongest returns. Broad market sizing and high-level segmentation can identify direction, but they do not show where specific opportunities are likely to open or where exposure may be concentrated. Detailed forecasts by engine family, application, region, pricing trajectory, and program-level service dynamics are needed to turn strategic themes into operational decisions. For that reason, teams evaluating investments, production plans, or procurement strategies should pair this high-level view with a more granular research asset that maps the segments, company developments, and regional dynamics in greater depth. A full research report can provide the decomposed data and customized assumptions required to test scenarios, prioritize initiatives, and compare competitive positioning across the most relevant segments.
For detailed analysis of this topic, please visit the official page: Jet Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ear Wash Station Market: Beyond the 4.65% CAGR Story—Key Shifts Explained
By PW Consulting, 2026-09-21
The Eye Wash Station Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for emergency eye wash stations has entered a phase of measured, steady expansion. From 2020 through 2025, total market revenue climbed from approximately USD 300.0 million to USD 435.0 million, reflecting a compound trajectory that underscores the essential nature of workplace safety infrastructure. Looking ahead to the 2026–2032 forecast horizon, the market is projected to grow at a CAGR of 4.65 percent, reaching an estimated USD 596.0 million by 2032. This growth profile is not explosive, but it is structurally resilient. Emergency first-aid equipment sits at the intersection of regulatory compliance, industrial activity levels, and organizational risk management priorities. As long as those foundational drivers remain intact, the market maintains a predictable revenue floor alongside pockets of incremental upside.
Behind the headline numbers, however, lie structural shifts that demand attention from manufacturers, distributors, procurement leaders, and investors. The market is no longer moving purely on compliance-driven replacement cycles. It is being reshaped by evolving technical expectations, tightening performance standards, supply chain recalibration, and shifting application profiles across high-exposure industries. Understanding these dynamics is essential for anyone positioning themselves in the safety equipment space.
Current Market Landscape and Critical Challenges
The eye wash station market operates as a mature but still evolving segment within the broader workplace safety equipment ecosystem. Revenue growth over the past half-decade has been supported by steady industrial output, ongoing laboratory expansion, and consistent investment in occupational health infrastructure. Rather than experiencing abrupt cyclical swings, the market reflects the incremental nature of compliance upgrades, facility build-outs, and periodic modernization programs. The forecast period through 2032 suggests continued expansion, but at a pace that rewards companies with disciplined product planning, strong service networks, and clear differentiation rather than those relying solely on volume-driven commoditization.
Three core challenges and inflection points are shaping how participants navigate the market today.
Compliance complexity and specification drift. Emergency eyewash requirements are not static checklists. Regulatory frameworks and recognized standards continue to refine expectations around water temperature, flow consistency, activation speed, and maintenance protocols. For manufacturers and specifiers alike, this creates a moving target: products must satisfy baseline compliance while also aligning with installation practices, testing routines, and user training expectations that vary by facility type, region, and internal safety policies. The challenge is not simply meeting a standard once; it is designing systems that remain compliant over their service life under real operating conditions.
Total cost of ownership versus upfront purchase price. Many procurement decisions still default to initial cost, even though the operational footprint of an eyewash station can be substantial. Plumbed systems involve plumbing integration, water quality management, and ongoing testing programs. Self-contained units reduce infrastructure dependence but require cartridge or solution replacement, inventory management, and scheduled service. Combination units and higher-performance configurations add complexity and cost. Organizations increasingly need to evaluate installed cost, maintenance burden, downtime risk, and compliance documentation rather than treating eyewash stations as discrete commodity purchases.
Uneven adoption across facility types and geographies. While large industrial operators and accredited laboratories tend to have mature safety programs, smaller facilities, newer industrial zones, and certain emerging market environments may lag in standardization. This creates a bifurcated market where some segments demand advanced features and frequent replacement cycles, while others remain price-sensitive or delay investment until regulatory inspection or incident-driven reassessment forces action. Participants must therefore balance portfolio scope: offering accessible entry-level solutions while preserving higher-margin options for performance-conscious buyers.
These challenges also represent the market's pressure points for innovation. Companies that reduce compliance uncertainty, simplify maintenance, or make total cost easier to quantify are better positioned to capture specification wins and retain end users over time.
Key Drivers Shaping the Market
The market's trajectory is being pulled by several interconnected forces. Individually, each matters; together, they define where growth is likely to concentrate and where competitive advantage will be earned.
Eye Anatomical Model Market
Technical innovation and performance differentiation
One of the most significant drivers is the ongoing push toward better flushing performance, faster activation, and more predictable user experience. Innovative rinsing technologies, improved flow distribution, and ergonomic actuation mechanisms are becoming meaningful differentiators, especially in environments where seconds matter and the margin for error is small. Products designed to deliver consistent dual-eye coverage, tepid water delivery, and intuitive activation address both compliance goals and practical usability concerns. In laboratory and healthcare-adjacent settings, compact footprints, easy integration with existing wall or bench configurations, and reduced risk of cross-contamination during use are also shaping purchasing preferences.
For manufacturers, the strategic implication is clear: technical features are increasingly tied to specification decisions. Product leadership now extends beyond build quality into performance reliability, ease of testing, and the ability to document compliance over time. This elevates the importance of engineering discipline, validation data, and post-sale support in competitive positioning.
Regulatory expectations and standards enforcement
Regulatory frameworks continue to anchor demand for emergency eyewash infrastructure. Occupational safety requirements mandate suitable facilities for immediate flushing where eyes or body may be exposed to harmful corrosive materials. In practice, this creates a baseline obligation for employers operating in at-risk environments and pushes safety equipment from optional courtesy infrastructure into essential compliance assets.
At the same time, recognized performance and installation guidance continues to sharpen expectations around continuous flow, tepid water delivery, minimum flush duration, and simultaneous eye coverage. Manufacturers and facility managers must therefore consider not only whether a unit exists, but whether it performs correctly under required conditions and can be maintained accordingly. This dynamic reinforces demand for compliant products and services, while also raising the stakes for installation, testing, and recordkeeping practices. In effect, regulation is not only stimulating purchase volume; it is also increasing the cost of non-compliance and rewarding organizations that treat eyewash readiness as an integrated program rather than a point purchase.
Demand-side behavior and organizational risk culture
Buyer behavior is shifting from reactive compliance toward proactive risk management. In chemical-intensive industries, pharmaceutical operations, electronics manufacturing, and oil and gas facilities, the consequences of inadequate first-aid readiness are visible and potentially severe. As a result, safety equipment is increasingly evaluated through the lens of incident mitigation, employee protection, and operational continuity rather than solely regulatory checking.
This cultural shift influences purchasing in several ways. Facilities are more likely to standardize across sites, prefer combination units in high-risk zones, and invest in products that simplify inspection and maintenance workflows. Laboratory environments, in particular, often prioritize immediate accessibility and space-efficient designs that support rapid deployment without disrupting sensitive workflows. In parallel, growing awareness of worker welfare and safety branding can make higher-specification units more attractive, especially where organizations are trying to signal a strong safety culture to staff, auditors, or partners.
Supply chain structure and regional manufacturing dynamics
Cost structure and supply resilience are becoming more prominent in purchasing and product strategy. Manufacturers must navigate raw material pricing, component availability, shipping volatility, and the operational requirements of maintaining consistent quality across different production locations. At the same time, regional sourcing options are shaping buyer considerations around lead times, customization, and support responsiveness.
This environment favors companies that can balance scale with flexibility. For some buyers, domestically produced or well-supported regional products offer perceived advantages in documentation, service proximity, and specification familiarity. For others, competitive pricing and broader portfolio availability from international manufacturers create attractive alternatives, especially in price-sensitive segments or fast-growing industrial markets. The result is a more varied competitive field in which differentiation often comes from a combination of product reliability, service access, and the credibility of compliance support rather than price alone.
Competitive Landscape and Leading Strategies
The market features a diverse set of participants spanning established manufacturers, safety-focused brands, laboratory specialists, distributors, and international producers. This diversity reflects the broad application base of emergency eyewash equipment and the different ways customers evaluate solutions. The presence of multiple competent suppliers also means that competitive advantage depends heavily on execution: product design, compliance alignment, service coverage, and go-to-market clarity.
Parts Washer Market
Strategic positioning among leading participants
Several companies illustrate the range of successful strategic approaches in the market.
Haws Corporation has built a strong identity around flushing performance and application-specific engineering. Its emphasis on advanced rinsing technology for industrial, laboratory, and healthcare settings positions it as a solution provider for buyers who prioritize performance consistency and specialized use cases. This approach helps the company compete on specification quality rather than solely on price, particularly in environments where superior flushing performance is directly tied to safety outcomes.
Guardian Equipment Company is widely recognized for emergency eyewash and shower equipment that covers wall-mounted, pedestal-mounted, and combination configurations. Its alignment with ANSI/ISEA Z358.1 and OSHA expectations gives buyers a straightforward compliance narrative, which is valuable in procurement environments where standardization and audit readiness matter. The breadth of mounting options and unit types also supports flexibility across facility layouts and risk zones.
Bradley Corporation focuses on industrial emergency eyewash stations, safety showers, and combination units with customizable features for high-risk chemical exposure areas. This positions the company well in environments where exposure risk is significant and where specifiers want solutions that can be adapted to specific operational conditions. Customization capability can be a decisive factor when standard off-the-shelf configurations do not fully match site requirements or when facilities seek to consolidate safety equipment specs across complex installations.
Speakman Company offers plumbed and portable eyewash stations along with replacement parts and safety showers. This combination of product supply and parts availability supports longer-term customer relationships by addressing the maintenance and replacement cycle. For many end users, ongoing service access and parts availability are as important as the initial purchase, especially when compliance testing and operational readiness must be sustained over time.
Haws Safety Products under Honeywell brings the recognizable Fendall® brand into industrial and laboratory settings with eye wash stations and cartridges designed for immediate flushing. The brand and cartridge-based approach can resonate with buyers looking for predictable performance, simplified resupply, and familiarity across multiple sites. In laboratory contexts especially, compact cartridge-based solutions may offer a practical balance between readiness and infrastructure demands.
Hughes Safety Company designs ANSI-compliant eyewash stations, self-contained units, and emergency showers for global industrial and workplace use. Its international orientation and compliance-focused portfolio make it relevant for organizations operating across multiple jurisdictions or seeking a consistent safety equipment standard across global facilities. For multi-site enterprises, that consistency can reduce specification fragmentation and simplify training and maintenance programs.
LOC Scientific targets laboratory eye wash station units designed for immediate emergency rinsing and compliance in research and industrial labs. By concentrating on laboratory-specific needs, it addresses a segment where accessibility, space constraints, and rapid response expectations are particularly acute. Niche focus can be a strong competitive lever when the end user environment has distinct operational requirements and when general-purpose products do not fit as cleanly.
Unicare stands out as a pioneer manufacturer based in India, producing eye/face wash stations and safety showers with in-house engineering for industrial and laboratory applications. This reflects the growing relevance of regional manufacturing capability and self-contained engineering resources. For buyers in emerging industrial markets or those seeking localized supply and support, such providers can offer attractive combinations of price, responsiveness, and application understanding.
EyewashDirect.com operates as a distributor and provider of eyewash stations, safety showers, and repair parts from leading manufacturers. Its role highlights the continued importance of distribution channels in this market. Many buyers prefer consolidated sourcing, technical guidance, and access to multiple brands when specifying safety equipment. Distributors that can combine product breadth with compliance-oriented support often serve as important intermediaries between manufacturers and end users.
Sysbel Manufacturing, based in China, supplies laboratory and industrial eye wash systems, including emergency eyewash solutions for chemical splash protection. Its presence underscores the growing influence of international manufacturers in both laboratory and industrial segments, particularly where cost competitiveness, export capability, and expanding portfolio range align with buyer needs.
How the competitive structure is evolving
The market is neither highly concentrated nor fragile. The competitive share distribution suggests room for multiple winners, with leadership determined by product relevance, service quality, and specification influence rather than by scale alone. Over time, three evolutionary patterns are likely to persist.
Consolidation through capability, not just acquisition. Some tightening may occur as larger platforms strengthen their safety portfolios or as distributors integrate broader product lines. However, meaningful consolidation will likely be driven by the desire to offer more complete compliance, service, and specification support rather than by eliminating competition purely for market share.
Segmentation by application and performance tier. As buyers become more sophisticated, the market will continue to differentiate between baseline compliance units and higher-performance or specialized solutions. Manufacturers that can clearly articulate why a given design is better suited to a specific environment—chemical processing areas, laboratory benches, outdoor sites, or multi-hazard work zones—will have stronger positioning.
Entry and expansion from regional and international suppliers. New and expanding suppliers can gain traction by offering competitive alternatives in specific geographies or application niches. This creates both opportunity and pressure for incumbents to defend specification relationships, demonstrate reliable performance, and maintain strong service networks.
Future Trends and What They Mean for Opportunities
Over the next three to five years, the eye wash station market is likely to be shaped by trends that blend compliance, technology, and operational practicality. These trends are not speculative shifts; they are extensions of current pressures and buyer priorities.
Trend 1: Compliance-as-program instead of compliance-as-equipment
Emergency eyewash readiness will increasingly be treated as an ongoing operational program rather than a one-time installation decision. That means greater emphasis on testing routines, documentation, activation reliability, solution or cartridge management, and user training. For suppliers, this opens opportunities in service, replacement parts, inspection support, and products designed to make compliance easier to sustain. For buyers, it argues for selecting equipment and partners that reduce administrative and maintenance friction over the asset lifecycle.
Trend 2: Performance features become default purchasing criteria
As the market matures, features that improve flushing effectiveness, speed of access, temperature control, and ease of use are likely to move from differentiators to expected attributes in many segments. This will reward manufacturers with clear engineering advantages and penalize those competing only on price in specification-driven environments. The commercial opportunity lies in translating technical performance into practical outcome language that resonates with safety managers, facility engineers, and procurement teams.
Trend 3: Broader application diversification and regional growth paths
Demand will continue to spread across chemical, pharmaceutical, electronics, oil and gas, and other industrial or laboratory environments, but the pace and mix will vary. In some regions, expanding industrial activity and laboratory build-outs will support stronger volume growth. In others, replacement cycles and compliance upgrades will be the main driver. This unevenness creates targeted opportunities: companies that align product portfolios with high-exposure segments and regional demand patterns can capture disproportionate relevance in the markets that matter most to them.
PW Consulting
Potential risks and uncertainties
Several uncertainties deserve attention. Regulatory expectations or interpretation can shift, affecting specification requirements and maintenance burdens. Economic cycles may pressure capital spending, particularly among smaller operators or in segments where safety equipment competes with more immediate operational priorities. Supply chain disruptions or input cost volatility can affect margins and delivery reliability. In addition, if buyers over-emphasize lowest initial cost, the market may experience pressure on quality differentiation and service investment. Companies that depend on a narrow product range or on a single geography may also face greater exposure if demand patterns shift unexpectedly.
Strategic Actions for Decision Makers
Different participants should approach the market with different priorities, but several actionable themes apply across roles.
For manufacturers and product developers, clarity of application focus is essential. Rather than competing broadly on volume alone, define where your design advantages actually matter—whether that is flushing performance, laboratory compactness, combination-unit flexibility, cartridge-based resupply, or serviceability. Invest in the documentation, validation, and support materials that help specifiers justify selection during procurement reviews. In parallel, treat maintenance and parts availability as part of the product story, because long-term compliance depends on them.
For investors and strategic planners, the market offers steadier demand characteristics than many discretionary industrial categories, but the best opportunities are likely to come from companies with defensible positioning in specification-driven segments. Look for participants that can demonstrate consistent compliance alignment, meaningful product distinction, and reliable routes to end users through distribution, service, or direct enterprise relationships. Capital allocation should favor structures that can withstand pricing pressure while still investing in performance and support.
For procurement teams and facility operators, the strongest buying decisions will come from evaluating total ownership impact rather than unit price alone. That includes installation requirements, testing burden, water quality considerations, cartridge or solution replacement logistics, replacement part availability, and the consistency of the solution across multiple sites. Where possible, standardize specifications to reduce training and maintenance complexity, and ensure that selected units genuinely match the exposure profile of each zone rather than defaulting to a single model across all areas.
Across all of these roles, timely and detailed market intelligence matters because the eye wash station market is not driven by a single force. It is shaped by overlapping regulation, technical expectations, application needs, and regional dynamics. Decisions made without a clear view of those layers can lead to over-investment in the wrong product tier, missed specification opportunities, or insufficient attention to service and compliance sustainability. The broader market trajectory is constructive, but the real value lies in understanding where growth is concentrated, which product attributes are becoming non-negotiable, and how competitive advantage is being earned on the ground.
Conclusion
The eye wash station market is expanding along a stable, compliance-anchored path, with growth reinforced by industrial activity, laboratory demand, and the continued institutionalization of workplace safety programs. Yet the most important developments are not simply the headline revenue figures. They are the shifts in how products are specified, maintained, and justified; the increasing importance of performance and usability; and the growing influence of service, distribution, and regional manufacturing in shaping buyer choices. Participants that treat eyewash readiness as a long-term operational commitment—and build products, bundles, and relationships accordingly—are best positioned to benefit from the market's next phase of growth.
For detailed analysis of this topic, please visit the official page: Eye Wash Station Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


