



Category: market research
PW Consulting: FeSi Powder Market Hits $1,554.12M in 2025, Projects 5.2% CAGR to $2,193.59M
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Ferrosilicon Powder Market in 2026 and Beyond
The global ferrosilicon powder market stands at a critical inflection point. As industries ranging from steelmaking to mineral processing demand higher precision and regulatory compliance, understanding the trajectory of this specialized materials sector is no longer optional—it is a strategic imperative. PW Consulting's latest comprehensive market research offers a definitive guide for stakeholders preparing to navigate the complexities of the 2026-2032 forecast period.
Iron Powder Market
This analysis serves as a strategic primer, outlining the macroeconomic currents, competitive tensions, and regulatory shifts that will define the landscape. For decision-makers seeking granular data to inform capacity planning, supply chain optimization, or market entry strategies, this research provides the foundational intelligence required to act with confidence.
Market Trajectory and Growth Dynamics
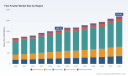
The historical performance of the ferrosilicon powder market demonstrates a consistent upward trajectory, reflecting the material's entrenched role in modern industrial applications. Between 2020 and 2025, the market expanded from approximately 1,190.55 million USD to 1,554.12 million USD, showcasing resilience even during periods of global economic volatility. This growth stabilization sets a robust baseline for the forecast period.
Looking ahead to 2032, the market is projected to reach a valuation of 2,193.59 million USD. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 5.2% over the forecast period. Such growth indicates a healthy demand environment, though it also suggests that early movers who secure supply chain advantages will capture disproportionate value. The acceleration is not uniform; it is being reshaped by geographical production shifts and evolving technical requirements in downstream sectors.
For corporate strategists, the key takeaway lies beyond the headline numbers. The growth trajectory signals sustained demand but also highlights the necessity of efficiency. As volumes increase, margins depend heavily on navigating input cost fluctuations and regulatory hurdles, which were notably intense in late 2025.
Segmentation and Application Nuances
While the aggregate market size provides a macro view, the real strategic opportunities lie in understanding the differential growth rates across product types and application verticals. The market is broadly categorized by production technology and end-use industry, each facing distinct demand drivers and technical barriers.
In terms of product type, the market is dominated by atomized ferrosilicon powder, which continues to hold the largest revenue share due to its widespread application in dense media separation and high-precision metallurgical processes. Milled ferrosilicon powder and other specialized types constitute significant but smaller segments, often catering to niche requirements where particle size distribution and purity are critical differentiators. The choice between atomized and milled forms often depends on the specific density and flow characteristics required by the downstream application, making technical specification intelligence vital for procurement teams.
Application-wise, the metallurgy sector remains the primary consumption engine. This includes deoxidation and inoculation processes in steelmaking, where consistent powder quality directly impacts final product integrity. The machinery industry and other specialized sectors follow, utilizing ferrosilicon powder for alloy production and specific industrial manufacturing processes. The interdependence between steel production cycles and ferrosilicon powder demand means that stakeholders must monitor broader industrial metal cycles closely.
PW Consulting's report delves deep into these segmentation splits, offering detailed revenue analysis and volume estimates that are essential for identifying high-growth niches. However, understanding the specific value contributions of each region or application segment requires access to the full dataset, as these figures fluctuate based on real-time supply chain adjustments and regional policy interventions.
Competitive Landscape and Strategic Positioning
The ferrosilicon powder market is characterized by a moderately concentrated competitive structure. With the top three players holding approximately 32.5% of the market share and the top five controlling around 38.7%, the landscape offers room for both established giants and agile regional specialists to compete. This concentration level suggests that while scale provides advantages in distribution and cost management, specialized technical capability and regional proximity remain significant differentiators.
Several key companies define the current competitive boundaries. DMS Powders, based in South Africa, stands out as a leading producer specifically focused on milled and atomized ferrosilicon powders for dense media separation applications in mining. Their product grades, ranging from coarse to fine cyclone specifications, highlight the technical granularity required in the mining sector. Meanwhile, European industrial giants like Elkem ASA and Finnfjord AS maintain strong footholds in metallurgical applications, producing ferrosilicon powders for deoxidation and inoculants. Elkem's recent operational decisions reflect the broader industry caution; in October 2025, the company partially curtailed production at its Rana plant in Norway and its Iceland facility, citing market conditions and the impact of EU safeguard measures.
Ferroglobe PLC and OM Holdings Ltd represent significant cross-regional capabilities. Ferroglobe, headquartered in the United Kingdom, supplies powders for steelmaking deoxidation and foundry uses, leveraging integrated production networks. OM Holdings, based in Singapore, serves as a key supplier for steel and alloy production, bridging Asian demand with global supply. On the high-purity flank, Stanford Advanced Materials in the United States supplies high-purity Ferro Silicon Powder with purity levels reaching 99% for specialized deoxidation needs, targeting segments where impurity control is paramount.
In Asia, particularly China, manufacturers like Anyang Lishi Industrial Co., Ltd. and Zhenan Metallurgy Co., Ltd. play crucial roles. Anyang Lishi is a notable manufacturer and exporter of both atomized and milled ferrosilicon powders for metallurgical and electrode applications. Zhenan Metallurgy focuses on low-aluminum ferrosilicon powder, catering to specific steelmaking requirements where aluminum content must be strictly controlled. The strategic positioning of these Asian players is critical, given the region's volume dominance in global supply.
Understanding the specific capacity, export capabilities, and proprietary grade portfolios of these competitors is essential for any market entry or expansion strategy. Our full report provides detailed competitor profiling, including SWOT analyses and strategic moves that are not publicly aggregated in general market summaries.
Regulatory Shifts and Industry Dynamics
The operating environment for ferrosilicon powder is undergoing significant transformation due to regulatory interventions and raw material dynamics. These factors introduce both risks and opportunities that must be modeled into any forward-looking strategy.
One of the most impactful recent developments occurred in November 2025, when the European Commission imposed safeguard measures on ferro-silicon imports, including powder forms. The EU established three-year tariff-rate quotas and implemented out-of-quota variable duties based on a price threshold of 2,408 USD per ton. This move is designed to protect local producers but introduces immediate complexity for importers and downstream users in Europe. The ramifications were felt quickly; Elkem ASA's production curtailment in late 2025 was partially attributed to the uncertainty generated by these safeguard measures.
Simultaneously, regulatory scrutiny is increasing in the supply source regions. Starting January 2026, China introduced new export license rules for ferrosilicon. These regulations require detailed specifications for exports, including particle size for FeSi products. Furthermore, batch-specific checks are now mandated for aluminum, calcium, phosphorus, and particle size for grades with 75% Si or higher. For global buyers, this means supply chain verification processes must be tightened, and lead times may be affected by administrative compliance. Anyang Lishi Industrial Co., Ltd. highlighted these changes in December 2025, signaling a shift toward stricter trade governance.
Infrastructure developments also signal shifting supply centers. In November 2025, Kazakhstan launched a new ferroalloys plant in Pavlodar. This facility, representing a 177 million USD investment, is designed to produce high-grade FeSi75 at an annual capacity of 240,000 tons for export. This expansion adds new volume to the global market and potentially alters trade flows, particularly for buyers seeking alternatives to traditional supply hubs.
On the technical application side, the fundamental utility of the material continues to drive demand stability. For instance, in dense media separation (DMS) applications within mining, powdered ferrosilicon is mixed with water to form a slurry used for density adjustment and mineral separation. This specific application requirement ensures that demand from the mining sector remains correlated with mineral processing activity, which varies by commodity cycles.
Strategic Implications for 2026 Decision Making
For corporate leaders, the convergence of these factors creates a complex operational environment. The 5.2% CAGR suggests that the market is growing faster than general industrial inflation, implying real demand expansion. However, the regulatory barriers in key markets like Europe and the stricter export controls from China mean that supply security is becoming as important as price competitiveness.
Companies must now evaluate their sourcing strategies with a multi-regional lens. Relying on a single supply corridor introduces vulnerability to tariff shocks and export licensing delays. The entry of new capacity in Central Asia offers diversification potential, but requires thorough due diligence on quality consistency and logistics reliability. Furthermore, the distinction between atomized and milled powders is not merely technical; it affects compatibility with existing processing equipment and compliance with specific metallurgical standards.
Procurement teams need to factor in the cost implications of the EU safeguard measures. For European manufacturers, the tariff structure may influence decisions on whether to source domestically or import from outside quota allocations. For exporters, understanding the price threshold mechanisms is critical to maintaining margin integrity. Meanwhile, the focus on purity and particle size specifications, driven by both regulatory checks and end-user performance requirements, elevates the importance of supplier technical audits.
PW Consulting's full market research report goes beyond these high-level dynamics to provide the specific quantitative forecasting and segmentation data necessary to model these scenarios. We analyze historical consumption patterns from 2020 to 2025, benchmark them against the forecast period through 2032, and isolate the growth contributions of each segment. This level of detail allows stakeholders to stress-test their strategies against various regulatory and demand outcomes.
Conclusion: The Value of Granular Intelligence
The ferrosilicon powder market offers compelling growth opportunities, but realizing them requires more than a top-line growth rate. It demands a nuanced understanding of who is producing what, where trade barriers are being erected, and how technical specifications are evolving to meet downstream needs. The competitive landscape is stable yet reactive, with major players adjusting production and trade strategies in response to the new regulatory normal.
Fesi Powder Market
As 2026 unfolds, the ability to access precise market intelligence will differentiate between organizations that merely react to market shifts and those that proactively shape their position within them. PW Consulting's in-depth analysis provides the roadmap for this navigation, offering the data density and strategic context required for high-stakes decision making.
To access the complete dataset, including detailed regional revenue breakdowns, specific application volume estimates, and comprehensive competitor strategic profiles, please refer to the full PW Consulting Fesi Powder Market Research Report. The insights contained within are designed to empower your next strategic move with precision and confidence.
For detailed analysis of this topic, please visit the official page: Fesi Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Manual Motor Starters Market Hits $630M in 2025, Projected 4.5% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Next Decade: Strategic Insights into the Global Manual Motor Starters Market (2026-2032)
The industrial landscape is undergoing a profound transformation, driven by the dual engines of automation and electrification. At the heart of this shift lies the fundamental infrastructure of motor control. For enterprise decision-makers, understanding the trajectory of the Manual Motor Starters Market is not merely an exercise in supply chain management; it is a strategic imperative that influences capital expenditure planning, safety compliance, and operational resilience. PW Consulting is proud to introduce our latest comprehensive market research study, designed to equip leadership teams with the actionable intelligence needed to thrive in the forecast period of 2026 through 2032.
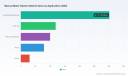
This report serves as a critical navigational tool for stakeholders ranging from procurement directors to strategic planners. By analyzing historical performance from 2020 to 2025 and projecting forward, we uncover the underlying currents shaping the industry. The market, valued at approximately 630.0 Million USD in the base year of 2025, is poised for steady expansion. Our forecast models indicate a trajectory moving toward 857.0 Million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.5 percent, signaling a mature yet consistently evolving sector where reliability and compliance drive demand rather than volatile speculation.
For organizations operating within or alongside the industrial manufacturing, oil and gas, water management, and mining sectors, these figures represent more than just top-line revenue. They reflect the ongoing replacement cycles of aging infrastructure, the integration of new safety standards, and the increasing complexity of motor protection requirements. This introduction provides a high-level overview of the strategic landscape, but the full depth of this intelligence is contained within the full report. The following analysis highlights the key themes our research unpacks in detail.
Macroeconomic Trajectory and Market Stability
The Manual Motor Starters Market has demonstrated remarkable resilience over the past five years. From 2020 to 2025, the market navigated global supply chain disruptions and economic fluctuations while maintaining a positive growth curve. The jump from 582.19 Million USD in 2024 to 630.0 Million USD in 2025 highlights a period of recovery and accelerated adoption. As we look toward 2026, the market is expected to reach 659.77 Million USD, setting the stage for a decade of incremental but significant growth.
This stability is crucial for long-term planning. Unlike high-volatility technology sectors, the demand for manual motor starters is tied to fundamental industrial output. The forecast period suggests that while the percentage growth may not be explosive, the absolute value addition is substantial. Companies that align their inventory and product development strategies with this steady 4.5 percent CAGR can optimize cash flow and reduce the risk of overstocking or undercapacity. However, realizing these benefits requires a nuanced understanding of where the growth is originating, which varies significantly by technology type and application vertical.
Manual Motor Starters Market
Segmentation Dynamics: Type and Application
A superficial view of the market hides the complex interplay between different product types and end-use applications. Our research dives deep into these segmentation splits to reveal where the highest value opportunities lie. The market is broadly categorized by technology, with AC Manual Motor Starters continuing to dominate the revenue share due to their widespread use in standard industrial power systems. However, the nuances within DC and other types offer specific niches for specialized engineering firms.
Similarly, the application landscape is diverse. Industrial manufacturing remains a primary driver, reflecting the need for cost-effective motor control in high-volume environments. Yet, sectors such as Oil and Gas and Water and Wastewater are critical growth engines due to stringent safety regulations and the harsh operating conditions that require robust starter solutions. Mining operations also contribute a significant portion of demand, particularly in regions undergoing infrastructure development.
Understanding the revenue contribution of each segment is vital for targeting. For instance, knowing which application vertical is expanding fastest can help manufacturers tailor their sales strategies and technical support teams. However, the specific percentage allocations and exact valuation figures for each region and application are proprietary data points that require the full report to access. This level of granularity allows competitors to benchmark their performance against the market average and identify untapped potential in specific verticals.
Regional Landscape and Distribution Channels
Geography plays a pivotal role in market dynamics. The global footprint of manual motor starters is uneven, reflecting the varying stages of industrialization and infrastructure investment across continents. Our analysis covers key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique set of challenges and opportunities, from regulatory compliance in Europe to cost-sensitive competition in Asia Pacific.
Motor Control Centers Mcc Market
Europe, for example, often leads in terms of advanced safety standards and premium product adoption, while other regions may prioritize volume and affordability. The distribution of market revenue across these geographies influences where companies should focus their marketing spend and logistical hubs. Supply chain localization is becoming increasingly important as trade policies shift and customers demand faster delivery times.
Our report provides a detailed breakdown of regional market sizes and growth rates. This information is essential for multinational corporations deciding on regional expansion strategies or local distributors looking to partner with global brands. The specific revenue values and growth contributions for each geographic zone are detailed within the full study, enabling precise market entry planning without the guesswork.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderate level of concentration, with the top three players holding approximately 35.5 percent of the market share, while the top five control around 48.2 percent. This structure indicates a competitive environment where dominant players coexist with agile regional specialists. Understanding the strategies of these key competitors is essential for maintaining market position.
Leading global entities such as ABB, headquartered in Zurich, continue to strengthen their portfolio with specific series like MS116 and MS132, focusing on compact units that integrate protection and control. Schneider Electric, based in France, maintains a strong presence with the TeSys Deca GV2 and GV3 series, recently updating their catalog with TeSys Deca Advanced solutions in late 2025. Eaton, from Dublin, offers robust options like the PKZM and Cutler-Hammer B100 series, catering to diverse machinery control needs.
Siemens remains a key player with their 3RV2 series, serving the high-standard European and global markets. Meanwhile, specialized players are carving out niches. NOARK Electric, based in California, recently expanded their offering with the Ex9S80 Manual Motor Starter in mid-2025, emphasizing built-in fault indication. Fuji Electric in Tokyo continues to innovate with their Duo Series, while Appleton Electric, part of Emerson in Illinois, focuses on factory-sealed starters for hazardous locations. LS Electric in South Korea contributes with their Metasol MMS series, highlighting the global nature of this supply chain.
Competitive strategy in this market is not just about price. It is about compliance, reliability, and product features. Companies must navigate specifications such as short-circuit breaking capacity up to 100 kA at 400 VAC. Failure to meet these technical benchmarks can disqualify a product from key tenders. Our analysis examines the recent developments and product launches of these key companies to identify trends in innovation and market share shifts. The full report details the specific strategic moves and product portfolios that are defining the competitive edge in 2026.
Regulatory Environment and Technical Standards
Compliance is a non-negotiable aspect of the manual motor starter business. These electromechanical devices serve as the first line of defense for manual isolation, control, and overcurrent protection. They must adhere to rigorous international standards, including IEC and UL certifications. The regulatory landscape is tightening, particularly in hazardous environments.
For instance, starters designed for use in hazardous locations, such as Class I, Division 1 and 2 areas, require specific factory-sealed designs to prevent ignition sources. This creates a barrier to entry for lower-quality manufacturers and rewards established brands with proven certification histories. Furthermore, the average selling price of industrial-grade manual motor starters typically ranges from 150 to 450 USD, depending on current ratings between 10A and 100A and the complexity of protection features.
This pricing structure reflects the cost of compliance and engineering quality. Procurement teams must balance budget constraints with the inherent risks of non-compliance. Our research evaluates how regulatory changes are impacting product design and pricing strategies across the industry. We analyze the compliance requirements that are becoming key differentiators in procurement bids. Detailed regulatory impact assessments for specific regions and application types are included in the comprehensive study.
Investment and Procurement Outlook for 2026
As organizations move into the 2026 fiscal year, capital allocation decisions must be informed by data. The forecast growth to 768.22 Million USD by 2030 suggests a sustained demand environment. For procurement leaders, this means securing supply chains early to mitigate potential shortages or lead time extensions. For manufacturers, it means scaling production capabilities in line with the 4.3 percent to 4.5 percent growth corridors identified in our models.
The period from 2026 to 2032 will likely see consolidation among smaller players and increased investment in product features that enhance safety and diagnostics. Companies that adapt to these trends will capture greater market share. Those that rely on legacy designs without adapting to newer safety standards risk obsolescence.
Strategic planning also involves understanding the cyclical nature of the industries served. While manufacturing may fluctuate with economic cycles, utilities and water management often provide stable, recurring revenue. A diversified portfolio approach is recommended for market players. Our report provides the scenario planning tools necessary to model revenue under different economic conditions.
Why This Report is Essential for Decision Makers
In an era of information overload, clarity is the most valuable commodity. This report cuts through the noise to provide verified data, expert analysis, and forward-looking insights. It is not just a collection of numbers; it is a strategic framework for understanding the Manual Motor Starters Market.
By utilizing this research, your organization can:
- Benchmark your internal forecasts against independent market projections for the 2026-2032 period.
- Identify high-growth segments and regions before competitors do.
- Understand the competitive moves of key players like ABB, Schneider Electric, and Eaton to anticipate market shifts.
- Navigate regulatory complexities with confidence, ensuring product compliance and market access.
- Optimize supply chain strategies based on regional demand nuances and historical performance data from 2020 to 2025.
The market size data provided in the introduction offers a glimpse into the potential, but the actionable intelligence lies in the segmentation, competitive analysis, and regional breakdowns that are fully detailed in our complete study. The specific revenue splits by type, application, and region, along with the in-depth company profiles and recent development timelines, are critical for forming a precise strategy.
Access to the full report unlocks the detailed segmentation splits, such as the specific contributions of AC versus DC starters and the exact market valuation for industrial manufacturing versus other applications. It also provides the granular regional data necessary for local market planning. In a market projected to reach 857.0 Million USD by 2032, knowing exactly where to focus resources is the difference between average performance and market leadership.
Conclusion
The Manual Motor Starters Market offers a landscape of steady opportunity for those equipped with the right intelligence. As the industry moves past the base year of 2025 and into the forecast horizon, the convergence of regulatory pressure, technological refinement, and industrial demand will define the winners. PW Consulting's latest research provides the lens through which to view this future. We invite stakeholders to leverage this comprehensive analysis to drive informed decision-making and secure a competitive advantage in the years to come.
For those ready to transform data into strategy, the full market intelligence report is available for review. Engage with our detailed findings to align your organizational roadmap with the definitive market trajectory.
For detailed analysis of this topic, please visit the official page: Manual Motor Starters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cigarette Rolling Paper Market to Hit $328M by 2032, 3.5% CAGR
By PW Consulting, 2026-09-16
Cigarette Rolling Paper Market Strategic Outlook 2026: Navigating Volatility and Growth
Executive Summary: The 2026 Decision Point
The global cigarette rolling paper market stands at a critical juncture as we move through 2026. For stakeholders in the tobacco supply chain, packaging sector, and investment community, understanding the nuanced shifts in this industry is no longer optional—it is a strategic imperative. Our latest comprehensive market research report offers a detailed examination of the forces shaping the landscape from 2026 through 2032. This document serves as an introduction to the depth of intelligence available, designed to equip leadership teams with the foresight needed to navigate regulatory changes, material shifts, and competitive pressures.
Cigarette Rolling Paper Market
While the market has experienced a period of contraction in the immediate past, the forecast period suggests a stabilization and eventual recovery driven by innovation and regulatory mandates. This article outlines the strategic value of our research, highlighting key dynamics, competitive structures, and growth vectors without disclosing the granular data required for precise modeling. To access the specific valuations and segment breakdowns necessary for financial planning, stakeholders are encouraged to utilize the full report.
Market Trajectory and Valuation Overview
Understanding the historical context is vital for projecting future performance. The market has undergone a notable correction over the last five years, reflecting broader shifts in smoking habits, regulatory tightening, and economic pressures on disposable income. Our analysis covers historical data from 2020 through the base year of 2025, establishing a robust baseline for forecasting.
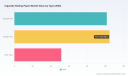
In 2025, the market revenue was recorded at approximately USD 258.0 Million. This figure represents a culmination of downward pressure seen in previous years, where valuations dipped from higher levels observed in the early 2020s. However, the forecast period from 2026 to 2032 indicates a shift in momentum. The market is expected to grow at a Compound Annual Growth Rate (CAGR) of 3.5% over this forecast window.
This growth trajectory is not linear. It suggests a market that is finding its footing through premiumization and regulatory compliance rather than volume expansion alone. By 2032, the market valuation is projected to reach new highs, driven by specific catalysts that our report dissects in detail. For business leaders, relying on historical decline rates without accounting for these upcoming inflection points could lead to suboptimal capital allocation. The transition from the 2025 baseline to the 2032 endpoint underscores the importance of timing investments in product portfolios and regional expansions.
Segmentation Dynamics and Material Shifts
The composition of the market is changing faster than the top-line revenue figures suggest. Traditionally, the industry has been categorized by material types and production methods. However, 2026 introduces new complexities in how these segments are valued and prioritized. Our report segments the market by type, application, and region, providing a multi-dimensional view of where value is being created.
Material and Type Evolution
The market is primarily divided into polyolefin films, polyester films, and other types. While traditional synthetic materials maintain a significant presence, the share of value attributed to these segments is under scrutiny due to environmental concerns and regulatory shifts. The report analyzes how manufacturers are balancing cost-efficiency with the demand for newer material specifications. It is no longer just about functionality; it is about compliance and brand perception.
Application Splits
Demand is driven largely by machine-made cigarettes, which continue to represent the bulk of volume. However, the handmade and other application segments offer unique insights into consumer behavior shifts, particularly among roll-your-own (RYO) demographics. Understanding the revenue contribution of each application type is crucial for suppliers targeting specific manufacturing clients or retail consumers. Our analysis details the dependency ratios between these applications and how vulnerabilities in one segment can be offset by strength in another.
Regional Performance
Geographically, the market is dispersed across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Each region presents a distinct risk-return profile. Europe and Asia Pacific hold significant portions of the market value, but growth rates vary considerably. Latin America and Africa, while smaller in current valuation, are identified as regions with high potential for incremental value addition due to specific regulatory changes. The report provides a comparative analysis of these regions, highlighting where infrastructure, demand stability, and regulatory environments favor investment.
Regulatory Dynamics and Premiumization Trends
One of the most potent drivers of market value in 2026 is regulation. Specifically, Low Intensity Paper (LIP) mandates are reshaping the cost structure and revenue potential of the industry. LIP papers are designed to reduce smoke intensity, and their adoption is becoming a requirement in several key markets.
- Price Premiums: Industry data indicates that LIP papers command a price premium of 15-25% over standard papers. This margin expansion is critical for manufacturers able to adapt their production lines to the specialized banding technology required.
- Natural Fiber Alternatives: Consumer preference for sustainability is translating into price tolerance. Natural fiber alternatives, such as hemp, bamboo, and rice-fiber variants, command retail price premiums of 30-50% over standard wood pulp papers. This creates a high-margin niche that is increasingly attractive despite lower volumes.
- Market Value Impact: New LIP mandates in Latin America, Southeast Asia, and Sub-Saharan Africa are expected to add significant incremental market value by 2030. This regulatory-driven demand provides a clear growth vector that is less sensitive to consumer volume fluctuations than traditional smoking rates.
Furthermore, product launches are reflecting this shift. In 2024, a substantial portion of new product launches were eco-friendly and organic rolling papers. This trend is accelerating into 2026, signaling that R&D departments must prioritize sustainability to remain competitive. Our report evaluates which companies are leading this transition and what the barrier to entry looks like for new players.
Competitive Landscape and Strategic Positioning
The market structure is moderately concentrated, with the top three players holding a combined share of approximately 38.4% and the top five reaching 45.6%. This concentration suggests that while there is room for niche players, the bulk of market power resides with established specialty paper producers and tobacco product portfolio owners. Success in this environment requires more than just capacity; it requires brand equity, technical capability, and supply chain resilience.
Key Market Participants
Our report provides detailed profiles of the leading companies shaping the industry. These profiles include headquarters, product portfolios, and strategic focus areas.
Cigarette Market
- SWM International (Switzerland): A specialty paper producer offering conventional and LIP cigarette papers. They provide light/ultra-light weight rolling papers in various finishes, positioning themselves as a technical partner for high-specification requirements.
- Julius Glatz GmbH (Germany): A fine paper manufacturer producing Cigla cigarette paper, including LIP versions optimized for high-speed tobacco applications. Their focus is on efficiency and compliance for industrial manufacturing.
- Miquel y Costas & Miquel (Spain): A leading cellulose paper supplier providing cigarette paper and textile pulps. Their vertical integration into pulp supply offers a competitive advantage in cost and quality control.
- OCB (France): A historic manufacturer of premium rolling papers and cones. They have diversified into hemp, bamboo, and rice-fiber variants, catering strongly to the roll-your-own premium segment.
- PDL Papeteries du Léman (France): Produces lightweight rolling papers and cones using certified wood pulp and sustainable fibers. They target the RYO/MYO markets with a strong emphasis on certified materials.
- Republic Brands (United States): A portfolio owner producing and representing brands including OCB, e-z Wider, JOB, DRUM, and PREMIER. Their strategy leverages brand diversity across cigarette and rolling paper categories.
- Moondust Paper Pvt. Ltd. (India): A manufacturer and exporter of premium unbleached brown rolling papers. They serve brands in North America, Europe, and Mexico, highlighting the global nature of niche supply chains.
- Delfort Group (Czech Republic): Offers a complete portfolio of cigarette papers, plug wrap, tipping base, and rolling papers. Their breadth of product allows them to serve multiple segments of the tobacco packaging value chain.
Understanding the specific strengths of these competitors is vital for benchmarking. Our report analyzes their recent developments, production capacities, and strategic moves to help clients identify white space opportunities or potential partnership avenues.
Actionable Intelligence Within the Report
To move from general awareness to specific strategy, stakeholders need granular data. Our full report is structured to provide actionable intelligence across several dimensions:
- Demand Forecasting: Detailed volume and value forecasts broken down by segment and region, allowing for precise revenue modeling.
- Supply Chain Analysis: Examination of raw material availability, cost structures, and logistics challenges affecting production margins.
- Regulatory Impact Assessment: A country-by-country breakdown of upcoming mandates and their estimated financial impact on production costs and pricing strategies.
- Competitive Benchmarking: Deep-dive profiles that go beyond public information, offering insights into market positioning, product development pipelines, and strategic alliances.
- Investment Risks: Identification of key risk factors, including regulatory volatility, raw material price fluctuation, and shifting consumer preferences, with mitigation strategies.
This comprehensive approach ensures that whether you are a manufacturer looking to expand capacity, a supplier seeking to enter new regions, or an investor evaluating portfolio performance, you have the data required to make informed decisions.
Conclusion: The Path Forward
The cigarette rolling paper market in 2026 is defined by a tension between contractionary pressures and value-accretive innovations. While the headline revenue figures show a market stabilizing after a period of decline, the underlying dynamics tell a story of premiumization, regulatory compliance, and material innovation. Companies that fail to adapt to LIP mandates or ignore the premium potential of natural fibers risk being left behind in a market that rewards differentiation.
Our research provides the clarity needed to navigate this complexity. By combining historical analysis with forward-looking forecasts, we offer a roadmap for the 2026-2032 period. The data contained within the full report will enable you to quantify these opportunities, assess competitive threats, and align your strategic roadmap with market realities. We invite you to access the complete market study to unlock the detailed segment data, regional valuations, and company-specific intelligence necessary to secure your position in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Cigarette Rolling Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reverse Transcriptase Market Hits $1,530M in 2025, Projects 6.69% CAGR to $2.4B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Reverse Transcriptase Market: Navigating Growth and Consolidation Through 2032
The global reverse transcriptase market stands at a critical inflection point. As molecular biology techniques become increasingly central to pharmaceutical development, clinical diagnostics, and academic research, the enzymes that enable RNA-to-DNA conversion are no longer commodities but strategic assets. For executives, procurement leaders, and R&D directors operating in 2026, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for informed capital allocation, partnership formation, and competitive positioning. PW Consulting's latest comprehensive study of the reverse transcriptase sector delivers precisely the analytical rigor required to navigate this evolving landscape.
Reverse Transcriptase Market
Macro Trajectory and Investment Context
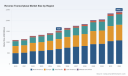
Historical revenue patterns indicate a sector that has consistently expanded, with global market size rising from approximately 1.1 billion USD in 2020 to an estimated 1.53 billion USD by 2025. This sustained momentum reflects broader shifts in life sciences funding, accelerated adoption of next-generation diagnostic platforms, and the persistent demand for high-fidelity enzymatic solutions across both developed and emerging markets. The forecast horizon through 2032 projects continued appreciation, with the market expected to surpass the 2.4 billion USD threshold by the end of the period. The compound annual growth rate of 6.69 percent underscores a mid-single-digit expansion profile that balances steady demand with selective premiumization in specialized applications.
For strategic planners, these figures translate into more than aggregate growth. They signal a market where volume expansion is increasingly coupled with value migration toward differentiated product lines, integrated workflow solutions, and regions experiencing rapid infrastructure modernization. The base year of 2025 and the forward-looking window through 2032 provide decision-makers with a sufficiently granular temporal framework to model capital deployment, capacity planning, and technology roadmap alignment.
Structural Segmentation and Demand Drivers
Type-Based Demand Dynamics
Reverse transcriptase demand is structured around distinct enzyme categories that serve different therapeutic, diagnostic, and research endpoints. A substantial portion of revenue continues to originate from HIV reverse transcriptase applications, driven by enduring needs in antiretroviral development, resistance profiling, and global public health initiatives. Hepatitis C virus reverse transcriptase and Hepatitis B reverse transcriptase segments contribute meaningful additional volume, reflecting sustained investment in viral characterization, vaccine research, and diagnostic assay standardization. A smaller but strategically important share is allocated to other reverse transcriptase variants that serve specialized laboratory workflows and emerging biotechnology pipelines.
The relative weighting of these categories is not static. Shifts in funding priorities, regulatory approvals, and the emergence of novel therapeutic modalities continuously reshape which enzyme applications command the greatest commercial attention. Understanding the interplay between these segments requires more than headline figures; it demands an appreciation of how procurement cycles, clinical trial pipelines, and academic grant structures influence long-term demand elasticity.
Application Channels and Workflow Integration
The application landscape reveals how reverse transcriptase enzymes are embedded into downstream workflows. Molecular diagnostics remains a dominant channel, underpinned by the expansion of point-of-care testing, centralized laboratory automation, and the growing reliance on nucleic acid amplification techniques. Viral load analysis constitutes a significant secondary pathway, essential for monitoring treatment efficacy and disease progression in chronic viral conditions. Gene expression analysis and DNA sequencing applications, while representing smaller revenue shares, are critical to high-value research programs, transcriptomics, and advanced genomic characterization. RNA analysis, though currently a niche application, carries strategic significance as laboratories increasingly focus on transcriptome profiling and non-coding RNA discovery.
The strategic implication for 2026 and beyond is clear: procurement decisions are no longer driven solely by unit pricing. Laboratories and diagnostic providers evaluate enzyme performance in the context of workflow compatibility, batch-to-batch consistency, scalability, and total cost of ownership across integrated platforms. Suppliers that align their reverse transcriptase offerings with these broader workflow priorities are positioned to capture premium positioning and longer-term contract commitments.
Competitive Landscape and Strategic Positioning
The reverse transcriptase market exhibits a moderately concentrated structure, with a small group of established life sciences and diagnostics companies commanding the majority of revenue. The top three players collectively represent a significant share of overall market activity, while the top five extend that concentration further, reflecting the high barriers associated with quality certification, global distribution networks, regulatory compliance, and sustained R&D investment. In such an environment, competitive differentiation depends less on broad categorization and more on the precision of product offerings, the strength of technical support, and the ability to integrate enzymatic solutions into larger instrument and assay ecosystems.
Several core companies anchor this competitive landscape. New England Biolabs, headquartered in Ipswich, Massachusetts, maintains a strong reputation for specialized enzyme portfolios and is recognized for its focus on tailored reverse transcriptase offerings that serve both research and applied molecular biology workflows. Thermo Fisher Scientific, based in Waltham, Massachusetts, leverages its expansive instrumentation and consumables ecosystem to position reverse transcriptase products within integrated diagnostic and laboratory automation platforms, appealing to large-scale clinical and industrial laboratories. QIAGEN, located in Hilden, Germany, brings deep expertise in sample preparation and molecular testing, aligning its reverse transcriptase capabilities with standardized diagnostic workflows and global laboratory operations. Merck KGaA, with its headquarters in Darmstadt, Germany, operates across life science research and industrial segments, deploying reverse transcriptase solutions within broader reagent and bioprocessing portfolios. Promega Corporation, in Madison, Wisconsin, is known for its emphasis on reliable enzymatic reagents and focused product development, catering to both academic and commercial research environments. Takarabio, based in Otsu, Japan, delivers specialized reverse transcriptase products that serve Asian and global research markets, with particular attention to performance characteristics relevant to high-precision applications.
The competitive calculus among these firms is increasingly shaped by their ability to offer not just an enzyme, but a validated solution. Product performance, supply chain resilience, regional regulatory alignment, and the depth of customer technical engagement all influence purchasing decisions at the organizational level. In a market where concentration is significant but innovation remains continuous, companies that can demonstrate measurable workflow advantages and maintain consistent quality standards are better positioned to defend and expand their share.
Market Dynamics and Industry Context
Several macro-level dynamics inform the reverse transcriptase market's trajectory. The broader life sciences sector continues to benefit from sustained investment in molecular diagnostics, infectious disease research, and precision medicine initiatives. Public health priorities, particularly those related to chronic viral conditions, have reinforced the importance of reliable enzymatic tools in both clinical and surveillance contexts. Simultaneously, the research community's expanding focus on transcriptomics, viral evolution, and therapeutic discovery sustains demand for high-quality reverse transcriptase enzymes across academic, governmental, and commercial laboratories.
Supply chain considerations also play an increasingly prominent role. As laboratories seek to reduce operational risk and ensure uninterrupted access to critical reagents, vendor reliability, regional sourcing options, and logistical stability have become important evaluation criteria. This trend favors suppliers that can combine technical performance with dependable fulfillment and localized support structures. In addition, the growing standardization of diagnostic workflows and the push toward regulatory conformity in certain application areas create both opportunities and compliance considerations for manufacturers and distributors alike.
For enterprises operating in 2026, these dynamics necessitate a strategic posture that balances cost efficiency with resilience. Short-term procurement optimization must be weighed against the long-term implications of supplier dependence, workflow integration, and the pace of technological change. The most effective strategies will be those that incorporate market intelligence at the level of product trends, regional demand shifts, and competitive capability mapping rather than relying solely on historical purchasing patterns.
Inside the Report: Analytical Depth and Decision-Ready Frameworks
PW Consulting's reverse transcriptase market study is structured to deliver actionable intelligence rather than static observation. The report provides a detailed mapping of revenue trends across the forecast period, contextualized within historical performance to highlight growth inflection points and structural shifts. Segmentation analysis examines how demand is distributed across enzyme types and application channels, enabling readers to identify where commercial emphasis is strengthening and which workflows are driving sustained procurement activity.
The competitive assessment component profiles the strategic posture of leading suppliers, with attention to their market positioning, product focus, and the operational advantages that support their standing. By analyzing the concentration structure and the capabilities of incumbent players, the report provides a framework for evaluating partnership opportunities, competitive threats, and potential whitespace for differentiated offerings.
Real-Time PCR Machines Market
Geographic analysis within the report examines regional market dynamics without reducing the picture to superficial aggregates. It explores the factors that influence demand intensity, including laboratory infrastructure development, diagnostic program expansion, and the maturity of local life sciences ecosystems. This regional lens helps organizations understand where growth is likely to be volume-driven versus value-driven, and where market entry or expansion may require tailored technical or commercial approaches.
Operational and strategic readers will also benefit from the report's synthesis of demand-side considerations, including the influence of workflow integration, quality expectations, and supply chain reliability on purchasing behavior. The study connects these operational realities to broader market trends, offering a coherent basis for scenario planning, capacity forecasting, and investment prioritization. Throughout, the analysis is designed to support executive discussion, cross-functional alignment, and evidence-based decision-making rather than to function as a disconnected data repository.
Why This Study Matters for 2026 Decision-Making
As organizations plan their initiatives for 2026 and look beyond to the remainder of the decade, the reverse transcriptase market presents both opportunity and complexity. A mid-single-digit growth trajectory suggests that the sector will continue to expand, but the distribution of that growth across enzyme categories, application workflows, and regions is uneven and subject to shifting priorities. Market concentration among established players raises the importance of understanding competitive moves, while evolving laboratory expectations around reliability, integration, and total cost of ownership reshape the criteria by which suppliers are judged.
PW Consulting's study is built to address these realities with precision. It translates macro-level market data into strategic context, connects segmentation patterns to operational decision-making, and frames the competitive landscape in terms of capability, positioning, and long-term relevance. For executives evaluating product portfolio direction, procurement strategy, partnership options, or regional expansion, the report supplies a foundation of structured insight that can be applied directly to planning processes.
The full depth of the analysis, including detailed segmentation interpretations, competitive positioning assessments, and forward-looking scenario considerations, is available in the complete report. Readers seeking to translate market intelligence into actionable strategy will find that the study goes beyond headline figures to provide the analytical clarity required for confident decision-making throughout the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Reverse Transcriptase Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LSA Market Hits $606M in 2025, Forecast to Reach $845M by 2032 at 4.85% CAGR
By PW Consulting, 2026-09-16
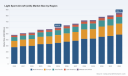
The Light Sport Aircraft Market: Strategic Horizons for 2026 and Beyond
The Light Sport Aircraft (LSA) sector is currently navigating a transformative period defined by regulatory evolution, shifting consumer preferences, and a steady expansion of market boundaries. For stakeholders operating within general aviation, aviation manufacturing, or flight training ecosystems, understanding the trajectory of this market is no longer optional—it is a strategic imperative. Our latest market research publication, the Light Sport Aircraft (LSA) Market report, offers a comprehensive examination of the industry’s past performance and future potential, designed specifically to inform high-stakes decision-making in 2026 and onwards.
This article serves as a strategic preview of the research, outlining the broader economic narrative, the regulatory forces reshaping the competitive landscape, and the practical intelligence contained within the full study. By exploring the structural dynamics of the LSA market, we aim to highlight why precise, data-backed intelligence is critical for capital allocation, product development, and market entry strategies in the coming years.
Market Trajectory: Steady Growth Amid Evolving Demand
The LSA market has demonstrated consistent resilience over the past half-decade. Between 2020 and 2025, the market navigated the complexities of a post-pandemic aviation landscape while maintaining a clear upward revenue trajectory. Historical data indicates that the market size in 2020 stood at approximately 482.35 million, gradually climbing through the subsequent years to reach an estimated 606.25 million by 2025. This growth pattern reflects a steady, compounding expansion rather than volatile spikes, suggesting a maturing market base with sustained demand drivers.
Our forecast analysis projects this positive momentum to continue through the end of the decade and into the early 2030s. We anticipate the market to reach roughly 640.4 million in 2026 and continue its ascent, with projected figures exceeding 844.73 million by 2032. This growth is underpinned by a compound annual growth rate (CAGR) of 4.85 percent. Such a trajectory signals a healthy, long-term expansion phase. However, for strategic planners, the aggregate numbers only tell part of the story. The true value lies in understanding the underlying velocity, the regional drivers, and the application segments that are contributing most significantly to this aggregate growth. The full report dissects these components with granular precision, offering a level of detail essential for targeted strategic planning.
The MOSAIC Rule and the Regulatory Paradigm Shift
No discussion of the LSA market in 2026 can proceed without addressing the profound regulatory changes introduced by the Federal Aviation Administration (FAA). In July 2025, the FAA finalized the MOSAIC rule, a landmark decision that fundamentally alters the definition and eligibility criteria for Light Sport Aircraft. Historically, LSA classifications were heavily constrained by fixed weight and performance metrics. The MOSAIC rule shifts this framework to performance-based criteria, such as stall speed, effectively expanding the scope of eligible aircraft. This includes allowances for higher maximum weights and configurations accommodating up to four seats, provided they meet specific performance thresholds.
The effective dates of this rule create a phased implementation environment. Pilot privileges associated with the new criteria began on October 22, 2025, while the full certification requirements for new make and model combinations will come into force on July 24, 2026. This staggered timeline is of critical importance to manufacturers and operators. It creates a window of adaptation for existing manufacturers while setting a new compliance bar for future entrants. The market impact of MOSAIC is multifaceted: it could stimulate demand by offering aircraft with greater utility and capacity, potentially attracting new demographics of pilots and recreational users. Conversely, it imposes new certification burdens and compliance costs on Special Light Sport Aircraft (SLSA) manufacturers, who must now demonstrate adherence to accepted industry consensus standards for design, production, and airworthiness under 14 CFR §22.100.
Light Sport Aircraft (LSA) Market
Our research provides a detailed analysis of how this regulatory shift is anticipated to redistribute market share, influence type certification strategies, and alter the risk profiles of various aircraft categories. We examine the operational implications of these changes, including the requirement for new make/model combinations to notify the FAA AIR-842 before special airworthiness certificates can be issued. The interplay between expanded market opportunity and heightened regulatory compliance is a central theme of our analysis, offering decision-makers a clear view of the landscape they will operate in.
Competitive Landscape: A Diverse and Fragmented Ecosystem
The LSA market is characterized by a broad and geographically diverse competitive landscape. The industry features a multitude of manufacturers ranging from established aerospace entities to specialized niche producers. This fragmentation contributes to a dynamic environment where innovation and differentiation are key competitive advantages. Our report includes a comprehensive roster of key companies that are actively shaping the market, detailing their operational bases, manufacturing specializations, and compliance profiles.
Prominent participants include entities such as Aero Adventure, based in Deland, Florida, which offers the Aventura II model under FAA 14 CFR 21.190 compliance. AERO AT Sp. z o.o., located in Mielec, Poland, produces the AT-4 LSA series, often utilizing Rotax engine options. Similarly, AeroJones Aviation USA LLC in Zephyrhills, Florida, specializes in the AJ Sport model with Rotax 912 iS engine compliance. The landscape also encompasses manufacturers like Aeropilot SRO in Čáslav, Czech Republic, offering the Legend 600 Amphib series with multiple engine configurations, and Aeroprakt Manufacturing Sp. z o.o. in Zakliczyn, Poland, known for the A-22LS and A32 Vixxen models.
Other significant players include Aeropro CZ in Hluk, Czech Republic, producing Aerotrek and Eurofox models; Aerospool SRO in Prievidza, Slovakia, with the Dynamic WT9; and Aerosport Ltd in Hohentengen, Germany, manufacturing Ikarus C42 series models. The list extends to Air Creation in Aubenas, France, with Tanarg models; Air Elite Aviation in Three Rivers, Michigan, offering the Storm Rally LSA; and Airborne Windsports PTY LTD in Redhead, Australia, producing weight-shift-control EDGE series models.
Manufacturers such as Aircraft Mfg & Development Co in Eastman, Georgia, offer CH series models licensed from Zenair. AirMax Construcoes Aeronauticas in São Paulo, Brazil, produces the SeaMax M-22, while Airtime Aircraft Inc. in Fort Walton Beach, Florida, offers the Cygnet model. The market also includes the American Legend Aircraft Company in Sulphur Springs, Texas, known for AL series models with Continental and Lycoming engines, and Apollo Aircraft Inc in Zephyrhills, Florida, with the Apollo LSA Fox and Delta Jet series.
Further diversity is seen with Arion Aircraft LLC in Shelbyville, Tennessee, offering the Lightning LS-1 with Jabiru engines; Atec VOS in Libice nad Cidlinou, Czech Republic, with the Atec 321 Faeta; and Aveko SRO in Brno, Czech Republic, producing the VL-3C-1. Other notable entities include Bilsam Aviation in Poznań, Poland, with the Sky Cruiser; Breezer Aircraft GmbH in Bredstedt, Germany; and BRM Aero in Kunovice, Czech Republic, offering Bristell series models. Bushcaddy International Inc. in Summerstown, Ontario, produces the BushCaddy Explorer. The list continues with Cessna Aircraft Co in Wichita, Kansas, historically associated with the 162 Skycatcher; CGS Aviation in Mulberry, Florida, with the Hawk Arrow II; Colyaer SL in Spain, offering the Freedom S100; and Composite Aeronautic Group SL in Zaragoza, Spain, with the Toxo SLSA.
Costruzioni Aeronautiche Tecnam S.p.A. in Capua, Italy, offers a wide range of models including the Astore and P92/Echo series, P2002 Sierra, P2004 Bravo, and P2008. Criquet Aviation in DeLand, Florida, produces the Storch FI-156. CubCrafters Inc. in Yakima, Washington, offers the Sport Cub and Carbon Cub models with various engine options. Czech Aircraft Works in Kunovice, Czech Republic, produces models like the CH 601 XL RTF and SportCruiser. Czech Sport Aircraft and Czech Sportplanes SRO also operate in Kunovice, offering SportCruiser and Dynamic WT9 models. Finally, Delta Trikes Aviation SARL in Montélimar, France, offers Voyageur II and other weight-shift-control models.
This diverse roster reflects the global nature of LSA manufacturing and the variety of product offerings available. Our research goes beyond mere enumeration. We analyze the competitive positioning of these firms, their strategic responses to regulatory changes, and their potential for market share expansion or consolidation. The report examines how companies are adapting their product lines, engine selections, and compliance strategies to maintain relevance and competitiveness in a market that is becoming increasingly performance-oriented.
Segmentation Dynamics and Value Creation Opportunities
While the aggregate market size and growth rate provide a macro-level view, strategic success often depends on a nuanced understanding of market segmentation. The LSA market is segmented across multiple dimensions, including geographic regions, aircraft types, and application areas. Each segment exhibits distinct growth characteristics, demand drivers, and competitive intensities.
For instance, certain regions demonstrate significantly higher concentration and revenue generation, reflecting established general aviation infrastructures, regulatory maturity, and higher disposable income levels. Other regions show emerging potential, driven by increasing aviation awareness, infrastructure development, and regulatory harmonization efforts. The full report provides a rigorous breakdown of these regional dynamics, identifying where opportunities for market penetration or partnership may be most viable.
Similarly, segmentation by aircraft type reveals preferences for different configurations, ranging from two-seat to four-seat models. The distribution of revenue across these types is not uniform and is subject to change as the MOSAIC rule potentially shifts demand toward higher-capacity aircraft. Understanding the current revenue contributions and growth trajectories of each type category allows manufacturers and investors to assess product portfolio alignment and future development priorities.
Application-based segmentation further illuminates how LSAs are being utilized. Personal recreation remains a dominant application, driven by the appeal of accessible flying and leisure travel. Flight training represents another critical segment, where LSAs are valued for their lower operating costs and suitability for initial pilot instruction. Commercial transport applications, while smaller in relative terms, offer specialized opportunities for niche operations such as aerial survey, patrol, or cargo delivery in remote areas. The interplay between these applications and the evolving regulatory environment creates distinct value propositions for different stakeholders. Our research delineates these application-specific trends, helping clients identify the most promising use cases and tailor their strategies accordingly.
Operational Safety and Regulatory Compliance as Strategic Assets
In the current LSA market environment, operational safety and regulatory compliance are not merely administrative requirements; they are strategic assets that influence customer confidence, insurance costs, and market reputation. The FAA's continued focus on safety monitoring is evident in reports such as the 2024 SLSA Continued Operational Safety (COS) Report, which documents trends in fatal and non-fatal accidents and incidents across SLSA classes. This report includes analysis by manufacturer fleet size and occurrence categories, providing valuable feedback loops for manufacturers and operators.
Furthermore, SLSA manufacturers are required to maintain a Partnership for Safety Plan (PSP) with the FAA to demonstrate continued compliance. This ongoing engagement with regulatory bodies ensures that safety remains a central pillar of the LSA ecosystem. The April 2026 SLSA Make/Model Directory highlights these requirements and specifies that only assigned Aviation Safety Inspectors (ASI) may issue special airworthiness certificates for new make/model combinations not appearing in the directory. These procedural details underscore the importance of maintaining rigorous compliance standards and building robust relationships with regulatory authorities.
Our market research integrates these safety and compliance dynamics into the broader market analysis. We evaluate how safety records and compliance reputations impact competitive positioning and market access. For potential entrants or existing manufacturers seeking to expand their fleet, understanding the nuances of the COS reporting framework, PSP requirements, and the certification process for new models is essential. The report provides actionable insights into navigating this regulatory landscape, mitigating risk, and leveraging safety performance as a differentiator.
Strategic Imperatives for 2026 Decision-Makers
As the market moves forward, several strategic imperatives emerge for stakeholders operating in the LSA sector. First, agility in response to regulatory change is paramount. The MOSAIC rule presents both opportunities and challenges, and companies must be prepared to adapt their product development cycles, certification strategies, and marketing messages to align with the new performance-based criteria. Early movers who can effectively navigate the transition to the July 2026 certification deadline may gain a competitive advantage.
Second, the fragmented nature of the competitive landscape suggests that differentiation through innovation, quality, and service will remain key success factors. With a wide array of manufacturers offering diverse models and engine configurations, customers have numerous choices. Companies must clearly articulate their value proposition, whether through advanced avionics integration, superior performance characteristics, lower total cost of ownership, or specialized support networks. The full report includes a competitor benchmarking analysis that helps identify white spaces and areas where differentiation can be most effective.
Third, understanding the demand drivers across different segments is critical for resource allocation. Investing in product lines or market expansion initiatives that align with high-growth segments or underserved applications can yield higher returns. The detailed segmentation analysis in our report enables clients to prioritize initiatives based on empirical data rather than assumptions.
Low Speed Vehicle Market
Finally, the importance of safety and compliance cannot be overstated. In an industry where trust is built on reliability and adherence to standards, a strong safety culture and transparent compliance practices are indispensable. The report highlights how leading companies are integrating safety into their operational DNA and how this contributes to long-term sustainability and brand equity.
Unlocking the Full Intelligence: Access the Complete Report
This article has provided a high-level overview of the key themes, market dynamics, and strategic considerations shaping the Light Sport Aircraft market in 2026. We have explored the steady growth trajectory, the transformative impact of the MOSAIC rule, the diverse competitive landscape, and the critical role of segmentation and compliance. However, this preview only scratches the surface of the actionable intelligence contained within our comprehensive market research study.
The full Light Sport Aircraft (LSA) Market report offers a depth of analysis that is essential for making informed, high-stakes decisions. It provides precise market size estimates for specific regions, detailed revenue breakdowns by aircraft type and application, and nuanced forecasts that account for the interplay of regulatory, economic, and technological factors. The report also includes in-depth profiles of key companies, an assessment of competitive strategies, and a thorough examination of the regulatory environment, including the latest FAA directives and their implications.
For executives, investors, and strategic planners, access to this level of detail is invaluable. It enables the formulation of data-driven strategies, the identification of high-potential opportunities, and the mitigation of risks associated with market volatility and regulatory complexity. We invite you to explore the complete findings of our research. Visit our website to download the full report and gain the comprehensive market intelligence needed to navigate the future of the LSA sector with confidence.
For detailed analysis of this topic, please visit the official page: Light Sport Aircraft (LSA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mercury Adsorbents Market Hits $1.55B in 2025, 6.2% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Mercury Removal Adsorbents Market: Strategic Imperatives for 2026 and Beyond
The global industrial landscape is undergoing a profound transformation driven by increasingly stringent environmental regulations and a heightened focus on operational safety. Within this shifting paradigm, the mercury removal adsorbents market stands as a critical enabler for energy infrastructure, chemical processing, and emissions control. As we move into 2026, stakeholders across the value chain face a complex matrix of growth opportunities, technological shifts, and cost pressures that demand precise strategic navigation. This article serves as an executive preview of our latest comprehensive market study, designed to equip decision-makers with the actionable intelligence required to capitalize on emerging trends while mitigating inherent risks.
Our analysis indicates that the global market for mercury removal adsorbents is poised for steady expansion. Valued at approximately 1,553.81 million USD in the base year of 2025, the sector is projected to reach 2,370.91 million USD by the end of the forecast period in 2032. This trajectory reflects a compound annual growth rate of 6.2 percent, signaling a robust demand environment fueled by regulatory compliance and infrastructure modernization. However, raw numerical growth tells only part of the story. The true strategic value lies in understanding the underlying dynamics that will dictate competitive positioning, supply chain resilience, and product portfolio optimization over the coming years.
Worldwide Zeolite Adsorbents Market
Market Scale and Growth Trajectory
The historical data from 2020 through 2025 reveals a consistent upward trend, with revenue climbing from 1,160.65 million USD to the current 1,553.81 million USD benchmark. This five-year growth phase was characterized by gradual adoption rates and incremental regulatory tightening. Looking forward, the forecast period from 2026 to 2032 suggests an acceleration in market valuation, with significant jumps anticipated as global industries align with stricter emissions standards. The projection of 1,594.41 million USD for 2026 alone underscores the immediate commercial relevance of this sector for investors and operational leaders alike.
While the aggregate figures provide a macro view, the strategic nuance lies in the segmentation of demand. The market is diversified across several key types, applications, and regions, each presenting distinct growth profiles. Activated carbon continues to represent a substantial portion of the product mix, reflecting its established role in flue gas and process stream treatment. However, specialized solutions such as sulfur-impregnated carbon and other advanced material types are gaining traction due to their superior sequestration capabilities in challenging operating conditions. Understanding the relative performance and adoption rates of these product categories is essential for companies aiming to align their R&D investments with market demand.
Application-wise, the petroleum refining sector remains a dominant driver of consumption, leveraging adsorbents to protect catalysts and meet environmental discharge limits. Natural gas processing follows as another critical demand center, where mercury removal is vital for preventing equipment corrosion and ensuring product purity for LNG and pipeline transport. Other applications, spanning industrial exhaust and water treatment, contribute to the broader ecosystem but often require tailored solutions that differ significantly from bulk industrial uses. The geographic distribution of demand further complicates the landscape, with mature markets in North America and Europe facing different regulatory and cost structures compared to the rapidly industrializing regions in Asia Pacific and Latin America.
Competitive Landscape and Key Players
The market structure is moderately fragmented, with a consolidated top tier of established multinational corporations holding significant market share. Our analysis highlights a CR3 of 24.6 percent and a CR5 of 26.2 percent, indicating that while a few major players dominate, there remains substantial room for specialized niche providers and regional specialists. The competitive arena is defined by continuous innovation in adsorbent chemistry, regeneration capabilities, and integration with downstream processing systems.
Calgon Carbon Corporation, headquartered in Pittsburgh, maintains a strong presence through its HGR, Fluepac, and HGR-P product lines. These sulfur-impregnated granular and powdered activated carbon solutions are specifically engineered for mercury removal from natural gas, flue gas, and various process streams. Their focus on granular and powdered formats allows for flexible deployment in both fixed-bed and injection systems, catering to diverse operational requirements.
UOP, a Honeywell company based in Des Plaines, offers a differentiated portfolio with its UOP GB series of non-regenerative metal sulfide adsorbents and HgSIV regenerable molecular sieve adsorbents. These products are designed for total mercury sequestration from natural gas, LPG, and light hydrocarbon streams, providing operators with options between single-use and regenerable technologies depending on throughput and economic considerations.
Johnson Matthey, operating from London, contributes the PURASPEC range of mixed metal sulfide absorbents. This product family is recognized for effective and complete mercury removal in both gas and liquid phase duties, making it particularly relevant for complex processing streams where phase versatility is required. The emphasis on mixed metal formulations highlights the industry's shift toward high-capacity chemistries that can handle variable feed compositions.
Cabot Corporation, based in Boston, focuses on the DARCO Hg family of powdered activated carbon products. These are primarily targeted at flue gas mercury removal, addressing emissions control requirements in power generation and industrial boilers. The powdered format is optimized for injection systems that require rapid kinetics and fine particle distribution to maximize capture efficiency.
Pall Corporation, located in Port Washington, provides integrated systems and solutions for mercury removal from natural gas. Their approach combines adsorption technology with engineered systems, offering both non-regenerative and regenerative adsorbents. This system-integration perspective allows customers to optimize lifecycle costs and operational simplicity, particularly in remote or offshore gas processing environments.
Nucon International Inc., operating out of Columbus, offers the MERSORB series of impregnated activated carbons. These products are designed for mercury removal across a broad spectrum of media, including air, natural gas, process exhaust gases, water, and petroleum liquids. The versatility of the MERSORB line positions it as a multi-application solution for facilities managing multiple emission and effluent streams simultaneously.
Axens, headquartered in Rueil-Malmaison, France, brings the AxTrap 200 series to the market. This includes non-regenerative and ready-to-use adsorbents such as AxTrap 273 and AxTrap 277, specifically formulated for mercury removal from hydrocarbons. A notable feature is the safe air-loading capability, which addresses operational safety concerns during adsorbent change-out and startup procedures in hydrocarbon processing facilities.
BASF SE, based in Ludwigshafen, Germany, offers the Durasorb HG mixed metal oxide adsorbent. This product is engineered for high-capacity mercury removal from natural gas under wet conditions, addressing a specific operational challenge where moisture can degrade the performance of conventional adsorbents. The focus on wet-condition performance reflects the industry's need for robust solutions in humid or subsea processing environments.
SLB, formerly Schlumberger, headquartered in Houston, provides the SELECT Hg mixed metal sulfide-based adsorbents. These are designed for effective mercury removal from a wide range of hydrocarbon streams, including natural gas, crude oil, condensates, and LNG. The breadth of stream compatibility positions SLB's offering as a comprehensive solution for upstream and midstream operators managing diverse production fluids.
Market Dynamics and Strategic Challenges
Despite the favorable growth outlook, the market is not without significant headwinds that require strategic attention. One of the most pressing challenges is the cost structure associated with advanced mercury removal technologies. Industry data indicates that costs for advanced mercury removal solutions remain 20 to 30 percent higher than conventional activated carbon. This premium reflects the specialized impregnation chemistries, manufacturing complexity, and performance guarantees required for high-efficiency removal. For operators, this cost differential translates into a careful balancing act between compliance assurance and operational expenditure, particularly in margin-sensitive segments of the petroleum and gas industries.
Furthermore, the high cost of mercury removal adsorbents is expected to hamper market growth over the forecast period to some extent. While demand is inelastic in highly regulated applications, price sensitivity remains a factor in less stringent environments or in regions where compliance enforcement is still evolving. Companies entering this space must carefully evaluate total cost of ownership, including not just the purchase price of the adsorbent but also regeneration cycles, disposal logistics, and system downtime.
A critical and often underestimated dynamic is the disposal cost of spent adsorbents. Spent media disposal costs can reach between 500 and 2,000 USD per ton, depending on regional regulations, waste classification, and transportation logistics. This disposal burden can significantly impact the lifecycle economics of adsorbent-based removal systems. Operators in regions with stringent hazardous waste regulations face particularly acute cost pressures, which may drive demand for regenerable adsorbents or alternative treatment technologies that reduce waste volume. The financial magnitude of disposal costs also creates an incentive for innovation in adsorbent lifetime extension and saturation monitoring, as maximizing the usable capacity of each adsorbent batch directly reduces disposal frequency and associated fees.
Sustainability considerations are increasingly shaping product development and procurement strategies. There is a noticeable movement toward selenium- and sulfur-based solutions for sustainability in mercury removal adsorbents. These chemistries are being explored not only for their removal efficiency but also for their potential to reduce environmental footprint during production and disposal. As regulatory frameworks evolve to incorporate broader sustainability criteria, adsorbents that align with green chemistry principles may gain a competitive advantage in procurement evaluations, particularly among multinational operators with explicit ESG commitments.
Mercury Removal Adsorbents Market
Report Scope and Strategic Utility for 2026 Decision-Making
Our comprehensive market research report is designed to move beyond high-level trends and deliver the granular intelligence required for operational and strategic planning. The study covers the historical period from 2020 to 2025 and provides a detailed forecast extending through 2032, allowing stakeholders to model long-term investment returns and capacity planning scenarios. All revenue figures are presented in USD million, ensuring consistency for international benchmarking and cross-regional comparison.
The report delves deeply into market segmentation, offering detailed breakdowns by type, application, and region. This segmentation analysis is critical for companies seeking to identify high-growth pockets within the broader market or to assess the competitive intensity in specific product categories. For instance, understanding the relative adoption rates of sulfur-impregnated carbon versus other advanced types can inform product development roadmaps and marketing positioning. Similarly, application-level insights help operators and suppliers align their technical offerings with the most economically viable demand centers, whether in petroleum refining, natural gas processing, or niche industrial applications.
Regional analysis is another cornerstone of the study. While aggregate regional values provide a snapshot of demand distribution, the report goes further to analyze the underlying drivers, regulatory timelines, and infrastructural factors that shape regional growth trajectories. This includes an examination of how mature markets are transitioning toward more advanced, regenerable solutions, while emerging markets are scaling up their baseline adsorption capacity to meet new compliance mandates. Such regional granularity is essential for supply chain optimization, localization strategies, and market entry planning.
The competitive landscape section of the report provides detailed profiles of the key players shaping the market. Each profile examines the company's specific product offerings, technological focus, and strategic positioning within the mercury removal adsorbents ecosystem. This analysis enables stakeholders to benchmark their own portfolios against industry leaders, identify potential partnership or acquisition targets, and anticipate competitive responses to market shifts. The inclusion of recent developments and strategic moves by these companies further illuminates the dynamic nature of the competitive arena.
In addition to quantitative data and company profiles, the report synthesizes critical market dynamics that influence strategic decision-making. The analysis of cost pressures, disposal economics, and sustainability trends provides a framework for evaluating the robustness of different business models and operational strategies. Decision-makers can use these insights to stress-test their pricing strategies, evaluate the viability of regenerable versus non-regenerative product lines, and assess the potential impact of evolving waste regulations on their customer base.
For 2026 and the years ahead, the ability to navigate the intersection of regulatory compliance, cost efficiency, and technological innovation will define market success. Companies that can offer high-capacity, cost-effective, and environmentally sustainable adsorbent solutions will be best positioned to capture growth. Likewise, operators that proactively manage adsorbent lifecycle costs, including disposal and regeneration, will gain a competitive edge in operational efficiency. This report serves as a strategic compass, providing the data, analysis, and contextual understanding necessary to make informed decisions in a market that is both lucrative and complex.
The detailed segmentation data, regional breakdowns, and competitive intelligence contained within the full study are essential for translating macro trends into actionable tactics. Readers interested in accessing the complete dataset, including specific regional revenue figures, application split percentages, and in-depth company benchmarking, are encouraged to explore the full report through our official channels. The comprehensive intelligence housed in the study is designed to support strategic planning, investment analysis, and operational optimization for years to come.
For detailed analysis of this topic, please visit the official page: Mercury Removal Adsorbents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TCB Bonder Market Hits $203.25M in 2025, Poised for 18.31% CAGR Growth Through 2032
By PW Consulting, 2026-09-16
The TCB Bonder Market at an Inflection Point: Why 2026 Demands Precision Intelligence
The thermal compression bonder market is no longer operating in a phase of incremental growth. Between 2020 and 2025, the sector expanded from 85.7 million USD to 203.25 million USD, reflecting an acceleration that mirrors the semiconductor industry's structural pivot toward advanced packaging, heterogeneous integration, and high-density interconnects. Our latest TCB Bonder Market report maps this trajectory across a forecast horizon extending to 2032, projecting sustained expansion at a CAGR of 18.31 percent. For executives navigating capital allocation, technology roadmaps, and supply chain resilience in 2026, this is not a market that rewards superficial observation. It demands a granular, forward-looking intelligence framework.
The Growth Architecture: What the Numbers Signal for 2026 Planning
The revenue curve tells a clear story of compounding momentum. From 124.78 million USD in 2022, the market climbed to 144.75 million USD in 2023, then 171.85 million USD in 2024, before reaching 203.25 million USD in 2025. The forecast places 2026 at 237.34 million USD, with successive years projecting 285.27 million USD in 2027, 338.79 million USD in 2028, and 419.37 million USD by 2029. By 2032, the market is positioned to approach 679.93 million USD. These figures are not merely historical bookkeeping; they define the strategic bandwidth companies must allocate to bonding equipment, process validation, and capacity planning.
For 2026 specifically, the transition from 203.25 million USD to 237.34 million USD represents a critical inflection. This is the year when procurement cycles, technology qualification timelines, and capacity expansion decisions converge. Organizations that rely on fragmented supplier data or outdated equipment catalogs will face compounding friction as lead times tighten and process specifications become more exacting. Our report is structured to remove that uncertainty by delivering a comprehensive view of the market's size, trajectory, and the operational variables that will determine execution success.
What the Report Delivers: Operational Intelligence Beyond Macro Trends
A market research document earns its place on an executive's desk when it converts aggregate data into actionable decision architecture. This TCB Bonder Market report is built around that principle. Rather than stopping at headline figures, the analysis decomposes the landscape into dimensions that directly shape sourcing, deployment, and competitive positioning.
TCB Bonder Market
The report examines the market through three structural lenses. First, it analyzes the equipment classification landscape, differentiating between automated and manual bonding platforms and mapping how each category aligns with production volume, precision requirements, and capital intensity. Second, it evaluates application-driven demand drivers, focusing on the segments that are pulling bonding capacity into new configurations, including integrated device manufacturing systems and outsourced semiconductor assembly and testing operations. Third, it traces regional demand distribution, identifying where capacity expansion, technology adoption, and procurement concentration are converging, and where latent growth pockets remain under-monitored.
Beyond segmentation, the report provides a detailed competitive landscape assessment. Market concentration is a defining feature of this sector, with the top three players accounting for 52.5 percent of total market revenue and the top five reaching 68.0 percent. That concentration has direct implications for pricing leverage, technology access, and partnership strategy. The analysis profiles the incumbents that are shaping equipment standards, process norms, and qualification expectations, giving buyers and investors a clear view of where differentiation is being created and where competitive pressure is intensifying.
The report also incorporates regulatory and operational context that frequently determines whether a bonding investment succeeds or stalls. Medical device applications, for example, represent a meaningful revenue share within the thermal compression bonder market, and they carry qualification requirements that extend well beyond standard production tolerances. Class II and Class III medical device manufacturing environments demand full material lot traceability, process documentation, and yield assurance protocols that drive premium pricing for medical-grade bonding systems. These requirements are not peripheral details; they are decision-critical variables that shape total cost of ownership, supplier selection, and deployment timelines. The report integrates these operational realities so that 2026 planning accounts for both technical performance and compliance architecture.
Competitive Landscape: Where Capability Is Being Concentrated
The TCB bonder market is shaped by a handful of firms that have invested heavily in precision control, throughput optimization, and application-specific process architectures. Understanding their distinct positioning is essential for companies evaluating equipment partnerships, capacity expansion, or technology migration in 2026.
Kulicke & Soffa Industries, headquartered in Willow Grove, Pennsylvania, has built its TCB bonder offering around the APAMA PLUS series and advanced thermo-compression bonding platforms. These systems are engineered for ultra-fine pitch interconnects, with precise heat-and-pressure control optimized for high-density semiconductor assembly. For organizations pursuing advanced packaging roadmaps where interconnect density and thermal management are primary constraints, K&S represents a benchmark for process precision and platform scalability.
ASMPT Amicra, based in Singapore, has focused its TCB bonder portfolio on high-volume production efficiency. Its NOVA Pro die attach systems support die placement accuracies down to ±1.5 μm at 3σ, with cycle times reaching as low as 3 seconds per bond. This combination of sub-micron placement precision and rapid throughput positions the company strongly in environments where volume, repeatability, and equipment utilization are decisive competitive factors.
BE Semiconductor Industries N.V., operating from Duiven in the Netherlands, has established a strong presence through thermocompression bonding systems deployed at volume for advanced flip chip and die bonding applications. Its equipment footprint extends into some of the most technologically demanding integration architectures, including CoWoS and HBM-related packaging flows. For firms tracking the equipment supply chain behind advanced logic and memory packaging, BESI's capabilities are directly relevant to process continuity and yield performance.
Toray Engineering, headquartered in Japan, has developed flip chip bonders that support TCB, DAF, and hybrid bonding across wafer and large panel sizes up to 600 mm by 600 mm. This dimensional flexibility is increasingly significant as packaging formats expand beyond traditional die-scale processing and as panel-level integration gains traction. Toray's platform breadth makes it a notable reference point for organizations evaluating multi-mode bonding strategies and larger-format handling capabilities.
CTBN Market
Palomar Technologies, based in Carlsbad, California, anchors part of its TCB bonder strategy in the 3880-II Die Bonder series, which applies thermocompression bonding processes for ultra-precise applications in medical devices and photonics. This positioning reflects a broader market reality: precision bonding is no longer confined to mainstream semiconductor assembly. It is expanding into niche but high-value domains where process stability, repeatability, and documentation rigor carry substantial commercial weight.
These profiles are not isolated product summaries. Together, they reveal how capability is being distributed across precision, throughput, format flexibility, and application specialization. The report examines these dynamics in greater depth, mapping how each player's strengths intersect with buyer requirements and where competitive differentiation is likely to sharpen through 2032.
Market Dynamics and the 2026 Decision Environment
The TCB bonder market does not evolve in isolation. It is shaped by the intersection of packaging complexity, capacity constraints, qualification demands, and the operational discipline required to scale precision manufacturing. In 2026, several forces converge to make equipment strategy a board-level concern rather than a departmental procurement exercise.
First, advanced packaging demand continues to pull bonding requirements toward finer pitch, tighter thermal control, and more demanding alignment tolerances. As interconnect architectures become denser and package formats more heterogeneous, bonding equipment must deliver repeatable process windows that hold across high-mix and high-volume conditions alike. This raises the stakes for equipment selection, because process migration later in a product lifecycle is far more costly than upfront qualification discipline.
Second, concentration in the competitive landscape means that procurement leverage, technology access, and supply continuity are intertwined. With the top five firms controlling more than two-thirds of market revenue, buyers must navigate a landscape where supplier relationships, process compatibility, and long-term support capacity can matter as much as unit pricing. The report's competitive analysis is designed to clarify where dependency risk exists and where alternative pathways remain viable.
Third, application-specific requirements are reshaping total cost calculations. Medical device bonding applications illustrate this clearly. They represent a distinct revenue share within the thermal compression bonder market and impose documentation, traceability, and qualification obligations that elevate system cost but also create defensible pricing structures for suppliers that can meet the standard. For 2026 planning, this means that market participation cannot be assessed purely on volume potential; process qualification burden, compliance readiness, and yield assurance must be factored into investment decisions.
Why the Full Report Matters for 2026 Strategy
Executive decisions in this market are won or lost on the quality of the underlying intelligence. Headline market size and CAGR provide direction, but they do not answer the operational questions that determine execution: which equipment category aligns with a given production profile, where regional demand is intensifying, how concentration affects sourcing strategy, and what qualification pathways are required for application-specific deployment. The full TCB Bonder Market report is built to answer those questions with structure and specificity.
The document is designed as a decision-support asset rather than a static market summary. It connects the macro trajectory to the operational layers that determine whether a 2026 investment scales efficiently or encounters friction later. For capital planning, it provides the framework needed to evaluate equipment type, application alignment, and regional demand distribution without relying on fragmented data. For competitive strategy, it offers a structured view of the incumbents that are defining process norms, throughput benchmarks, and precision standards. For risk management, it incorporates the compliance and qualification realities that can influence supplier selection and deployment timing.
The report also preserves forward visibility. By extending the forecast horizon to 2032, it allows organizations to test 2026 commitments against longer-term market evolution, rather than optimizing for a single annual cycle. That continuity is critical in a market growing at a CAGR of 18.31 percent, where early positioning can compound into structural advantage or entrenched disadvantage.
Moving from Market Awareness to Strategic Advantage
The TCB bonder market is entering a phase where scale, precision, and application complexity reinforce one another. The revenue expansion from 85.7 million USD in 2020 to a projected 679.93 million USD by 2032 reflects more than demand growth; it reflects a structural reorientation of semiconductor packaging toward bonding-intensive architectures and high-value precision manufacturing. In that environment, 2026 is not a routine planning year. It is a decisive window for aligning equipment strategy, supplier relationships, and process qualification with the market's trajectory.
The full TCB Bonder Market report provides the depth required to navigate that window with confidence. It translates the headline growth narrative into segmented analysis, competitive profiling, compliance-aware application context, and forward-looking market structure. For organizations that need to move beyond aggregate trends and into execution-ready intelligence, the complete study is the necessary next step.
Access the full report to capture the complete segmentation detail, the regional and application-level market architecture, the competitive concentration analysis, and the operational variables that will shape 2026 investment decisions. The macro direction is clear; the strategic advantage lies in the specifics.
For detailed analysis of this topic, please visit the official page: TCB Bonder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: FLIM Market Hits $332.3M in 2025, Poised for 5.91% CAGR Growth to 2032
By PW Consulting, 2026-09-16
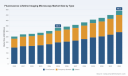
Fluorescence Lifetime Imaging Microscopy (FLIM) Market: Strategic Intelligence for 2026 and Beyond
Unlocking Temporal Contrast: The Strategic Imperative for Enterprise Leaders
In an era where spatial resolution alone no longer suffices, fluorescence lifetime imaging microscopy (FLIM) has emerged as a transformative modality that decodes molecular environments through temporal contrast. For life science enterprises, medical device developers, academic commercializers, and industrial imaging innovators, FLIM represents more than a laboratory technique; it is a rapidly maturing platform ripe for strategic positioning, partnership, and market capture. Our latest Fluorescence Lifetime Imaging Microscopy Market research is designed to give decision-makers the exact intelligence needed to navigate this inflection point with precision.
Between 2020 and 2025, the global FLIM market demonstrated resilient expansion, with annual revenue climbing from approximately 252.5 million USD to 332.3 million USD. The forward trajectory is similarly compelling: the 2026 baseline is projected at 344.01 million USD, advancing to an estimated 490.2 million USD by 2032. This growth unfolds at a compound annual growth rate of 5.91 percent across the forecast window from 2026 through 2032. These headline figures signal more than incremental progress; they map a structural shift in how biophotonics, translational research, and industrial imaging converge around lifetime-based contrast.
Yet aggregate numbers only scratch the surface. For enterprise strategists, the real value lies in understanding how adoption drivers are redistributing across technology architectures, end-use domains, and geographies; how regulatory, reimbursement, and clinical validation pathways are reshaping commercialization timelines; and where competitive pressure is intensifying. This report delivers a tightly integrated intelligence framework that turns macro momentum into actionable strategy for 2026 and the years that follow.
Why 2026 Is a Decisive Inflection Point for FLIM Strategy
FLIM is no longer confined to specialized photonics laboratories. The technique is rapidly becoming a transformative tool in neurology, enabling the visualization of molecular and metabolic information that supports surgical tumor margin detection and personalized medicine approaches. This clinical promise intersects with renewed commercial interest from imaging system manufacturers, reagent developers, and workflow integrators seeking to embed lifetime imaging into routine workflows. However, the path from scientific promise to commercial scale is mediated by technical, economic, and institutional factors that executives must model explicitly.
Our research frames 2026 as a year in which several structural forces begin to align. First, platform-level designs are increasingly supporting modular FLIM capabilities, allowing existing confocal and multiphoton systems to be retrofitted or expanded rather than replaced outright. Second, end-user requirements are diverging: biomedical applications demand rigorous validation trajectories, academic institutions prioritize flexibility and grant-aligned instrumentation, while chemical and materials applications focus on throughput and reproducibility. Third, market concentration remains moderate yet influential, underscoring the need for strategies that balance scale with differentiation.
For executive teams, the strategic question is no longer whether FLIM will grow, but where competitive advantage will accrue. Will advantage come from integrated systems, upgrade-and-accessorize business models, specialized consumables, application-specific data workflows, or regional channel partnerships? The answer depends on granular patterns that aggregate forecasts cannot reveal on their own.
What the 2026–2032 Outlook Means for Enterprise Planning
A market advancing from 344.01 million USD in 2026 to 490.2 million USD in 2032 at a 5.91 percent CAGR suggests sustained, not speculative, demand. Importantly, the growth path is not linear across all segments. Revenue is shaped by how practitioners balance instrumentation purchases against reagent and consumables economics, how retrofit kits influence upgrade cycles, and how regional purchasing power interacts with local research funding and clinical trial activity.
The 2025 baseline of 332.3 million USD anchors our forward model, but strategy requires more than the top line. Our analysis examines how revenue distribution across categories evolves as adoption matures. For example, temporal-domain and frequency-domain architectures compete on distinct performance profiles and use-case fit. Certain applications demonstrate stronger pull from translational and clinical momentum, while others reflect steady research-driven procurement. Regions present different growth rates and adoption prerequisites, shaped by ecosystem density, funding availability, and regulatory maturity.
Rather than treating these patterns as isolated variables, our report integrates them into a strategic lens: how should product roadmaps be prioritized, which customer segments offer the fastest payback, which geographies justify channel investment now versus later, and how should pricing and bundling reflect unit economics and upgrade potential. This is the kind of intelligence that converts a forecast into a plan.
Report Contents: Practical Intelligence for Real-World Decisions
This study is built for strategists, product leaders, commercial directors, and investor teams who need to translate FLIM market dynamics into executable actions. It combines macro foresight with operational detail in a way that supports multiple use cases: market entry evaluation, product portfolio design, regional prioritization, competitive response planning, and investment thesis refinement.
The report includes:
Fluorescence Lifetime Imaging Microscopy Market
- A comprehensive market size and forecast framework spanning historical baselines through the 2026–2032 outlook, with scenario-aware interpretation rather than single-point assumptions.
- Technology architecture analysis comparing time-domain, frequency-domain, and alternative approaches, with practical implications for integration, performance trade-offs, and upgrade economics.
- End-use application assessments covering biology and medical, academic institutes, chemical industry, and other segments, emphasizing adoption drivers, procurement behavior, and commercial friction points.
- Regional market intelligence that evaluates demand characteristics, channel dynamics, and localized barriers across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Competitive landscape profiling that maps positioning, product strategies, and recent developments among leading FLIM and imaging innovators.
- Market concentration analysis that helps assess competitive intensity, differentiation opportunities, and the strategic relevance of scale versus specialization.
- Market dynamics coverage that integrates regulation, reimbursement, clinical validation expectations, material cost considerations, and emerging application frontiers such as intraoperative and surgical use cases.
- Actionable strategic takeaways for market entry timing, partnership selection, segmentation focus, and risk mitigation in a market shaped by both scientific opportunity and institutional requirements.
We deliberately focus on structuring insight for decisions, not just describing trends. Each section is intended to feed directly into go-to-market planning, investment allocation, and competitive positioning discussions.
Competitive Landscape: Leaders, Positioning, and Emerging Innovation Vectors
The FLIM market reflects a diverse set of players spanning integrated microscope platforms, scientific camera and detector specialists, upgrade-kit providers, and application-focused consumables developers. This multi-form competitiveness creates both challenge and opportunity: it raises the bar for differentiation, but it also allows entrants to choose between full-system leadership, modular add-on pathways, and niche application dominance.
Leica Microsystems, headquartered in Wetzlar, Germany, has reinforced the system-integration pathway with the STELLARIS 8 FALCON confocal microscope system, which embeds FLIM for medical device and life science applications. This reflects a strategy centered on premium platforms with integrated lifetime imaging as a core capability. Teledyne Princeton Instruments, based in Acton, Massachusetts, United States, contributes a complementary angle through FLIM-compatible scientific imaging systems and cameras for research and medical device development, emphasizing detector and imaging subsystem strength. Renishaw plc, headquartered in Gloucestershire, United Kingdom, integrates FLIM solutions with advanced microscopy platforms for industrial and medical applications, positioning lifetime imaging within broader analytical and materials ecosystems.
PicoQuant, based in Berlin, Germany, leans into upgrade and accessibility with compact FLIM and FCS upgrade kits and an LSM Upgrade Kit for existing laser scanning microscopes. Becker & Hickl GmbH, also in Berlin, addresses high-resolution imaging needs with DCS-120 confocal and multiphoton FLIM systems, TCSPC/FLIM cards, and upgrade kits, reinforcing a strong technical footprint in detector and electronics ecosystems. HORIBA, headquartered in Kyoto, Japan, expanded its platform narrative with the July 2024 launch of the InverTau platform for confocal FLIM, an example of ongoing investment in integrated FLIM offerings. Bruker, located in Billerica, Massachusetts, United States, supports life science and medical applications with the ULTIMA multiphoton microscope equipped with FLIM and PLIM modules, extending lifetime imaging across multiple contrast modes. ibidi GmbH, based in Gräfelfing, Germany, takes a different but strategically important angle by offering μ-Slide and polymer/glass coverslips optimized for FLIM imaging applications, highlighting the role of sample preparation and consumables in imaging workflows.
Taken together, the competitive field indicates that advantage will likely accrue to players who can balance system completeness with upgrade flexibility, application-specific workflow support, and credible validation pathways where clinical or regulated use is involved. The presence of both full-platform leaders and modular specialists also suggests that partnerships, bundling strategies, and channel alignment can be as important as hardware specifications.
Market Dynamics: Regulation, Reimbursement, and Clinical Translation
Commercial success in FLIM is increasingly shaped by institutional dynamics rather than technical capability alone. The widespread clinical integration of fluorescence lifetime imaging microscopy hinges heavily on regulatory and reimbursement structures. That means enterprise strategies must account for validation requirements, evidence generation, and the reality that clinical adoption timelines depend on more than instrumentation performance.
Regulatory approval will also depend on the validation of FLIM-based biomarkers and demonstration of clinical benefit in large, multicenter trials. This elevates the importance of strategic planning around evidence generation, clinical partnerships, and product roadmaps that anticipate regulated-use requirements. For medical device and diagnostics-adjacent players, the ability to align development cycles with regulatory expectations can determine not only time-to-market but also the commercial credibility needed to secure reimbursement traction.
Beyond regulatory pathways, practical implementation details matter. Modifications have been made for intraoperative use, including portability, remote fiber optic access to patients, fiber-probe sterilization, and medical safety. These realities underscore that clinical adoption is not just about imaging quality; it is also about workflow compatibility, sterility, safety, and ergonomics in high-stakes environments. Enterprise teams evaluating FLIM opportunities should therefore consider device usability, integration complexity, and operational constraints as core commercial variables rather than secondary engineering concerns.
From Insight to Action: How to Use This Research for 2026 Decision-Making
Strategic value comes from connecting market structure to your specific context. For product leaders, the report helps identify which architecture and application combinations offer the strongest alignment with your capabilities and customer base. For commercial and channel teams, it clarifies where demand is most accessible and where longer validation or funding cycles may influence pacing. For investors and corporate development teams, it supports sharper distinction between near-term revenue pull and longer-cycle transformation plays.
The research is also built to support scenario thinking. Because the market spans different technology forms, application priorities, and regional maturity levels, the same headline growth rate can translate into very different implications depending on your segment focus. Our analysis surfaces those divergences so that planning reflects reality rather than averaging effects.
To make confident decisions, executives need more than directional signals. They need the detailed breakdowns, comparative positioning data, and segment-specific dynamics that this study assembles in one place. The full report translates the 2026–2032 trajectory into an operational intelligence package, enabling teams to prioritize investments, refine go-to-market plans, and anticipate competitive moves with greater confidence.
Conclusion: Positioning for a Market in Motion
The fluorescence lifetime imaging microscopy market is entering a phase where scientific promise, platform evolution, and institutional adoption pressure converge. With a 2026 baseline near 344.01 million USD and a projected path to 490.2 million USD by 2032 at a 5.91 percent CAGR, the opportunity is substantial, but the shape of the opportunity is what determines success. Technology architecture, application fit, regional readiness, regulatory and reimbursement realities, and competitive differentiation will each influence where value is created and captured.
PW Consulting’s Fluorescence Lifetime Imaging Microscopy Market research is engineered to give your team the clarity and precision needed to navigate that environment strategically. The complete study provides the detailed segmentation analysis, competitive intelligence, and market dynamics assessment required for decisive 2026 planning. To access the full intelligence framework and secure the deeper insights behind this preview, visit our report page for the complete analysis.
Light Sheet Microscopy Market
For detailed analysis of this topic, please visit the official page: Fluorescence Lifetime Imaging Microscopy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for a Critical Materials Landscape: Navigating the Germanium Market 2026-2032
In the rapidly evolving landscape of critical minerals, germanium occupies a unique and increasingly precarious position. Once viewed primarily as a niche byproduct of zinc mining, this element has become a linchpin for advanced optics, semiconductor infrastructure, and defense technologies. As supply chains fragment along geopolitical lines and demand curves shift toward high-tech applications, understanding the trajectory of the germanium market is no longer optional for strategic planners—it is imperative.
PW Consulting is pleased to introduce our latest comprehensive market study, designed to equip stakeholders with the actionable intelligence needed to navigate the period from 2026 through 2032. This report goes beyond surface-level statistics to provide a granular analysis of market drivers, regulatory headwinds, and competitive dynamics that will define the industry in the coming years.
Market Trajectory and Structural Resilience
The global germanium market has demonstrated remarkable resilience and growth over the past half-decade. Our analysis traces historical performance from 2020 through 2025, where the market valuation climbed from 260.0 USD Million to 320.0 USD Million. This upward trend reflects sustained demand from fiber optic networks and infrared imaging systems, coupled with tightening supply constraints.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion, albeit with nuanced fluctuations driven by external shocks. The compound annual growth rate is estimated at 3.5 percent, signaling a steady but calculated growth environment. By the end of the forecast horizon in 2032, the market is anticipated to reach a significant valuation, underscoring the long-term viability of germanium-dependent technologies.
However, growth is not uniform. The period between 2027 and 2029 shows notable variance, highlighting how sensitive the market is to geopolitical interventions and supply chain reconfigurations. Stakeholders must understand that while the long-term trajectory is positive, volatility remains a key feature of this landscape. The report dissecting these fluctuations provides the context needed to model risk scenarios accurately.
Geopolitical Dynamics and Supply Chain Realignment
The most profound shift in the germanium market over the last few years has been the weaponization of supply chains. Regulatory frameworks have moved from background concerns to primary market drivers. China, historically the dominant supplier, imposed export licensing controls on germanium in July 2023 and escalated restrictions by banning direct exports to the United States in December 2024. These actions, documented by the U.S. Department of Commerce, have fundamentally altered trade flows and forced a rapid search for alternative sourcing.
In response, the United States has accelerated efforts to domesticate production. U.S. Executive Order 14241 of March 2025 directs the Secretary of Defense to facilitate private investment in domestic mineral production projects, including germanium refining. This policy shift is not merely symbolic; it is backed by tangible financing and strategic intent to reduce reliance on foreign supply. Furthermore, U.S. tariffs on Chinese imports of critical minerals including germanium were imposed in September 2025 to further insulate domestic markets.
These regulatory maneuvers have had immediate price implications. Germanium metal price data from the U.S. Geological Survey Mineral Commodity Summaries 2026 notes a rise from 3,150 USD per kilogram in January 2025 to 5,380 USD per kilogram by October 2025 in Europe. By early 2026, global prices reached 8,597.50 USD per kilogram, representing a dramatic increase from early 2025 levels. Such volatility necessitates robust hedging strategies and long-term supply agreements, details of which are covered extensively in our supply chain risk assessment section.
Competitive Landscape and Strategic Consolidation
The market structure is moderately concentrated, with the top three players holding a significant portion of market share and the top five commanding nearly half of the total revenue. This concentration suggests that pricing power and supply security are heavily influenced by a select group of integrated producers and refiners.
Key companies shaping the landscape include major integrated producers such as Yunnan Chihong Zinc & Germanium Co., Ltd. and Yunnan Lincang Xinyuan Germanium Industry Co., Ltd., both based in China. These entities control extensive operations from mining and purification to refining, offering germanium metal, ingots, and related forms for infrared, fiber optics, and semiconductor applications. Their strategic positioning allows them to react quickly to demand shifts, though regulatory constraints now complicate their access to Western markets.
In the West, Umicore of Belgium stands out as a leading refiner and recycler, specializing in high-purity metal and ingots from secondary sources. This focus on recycling offers a degree of supply insulation against primary mining disruptions. Similarly, Teck Resources Limited in Canada supplies germanium as a byproduct of integrated zinc production, providing metal and oxides for industrial and high-tech uses. In Russia, JSC Germanium remains a primary producer from zinc and coal sources, manufacturing compounds and tetrachloride for electronics and optics.
Specialized refiners and manufacturers also play critical roles. PPM Pure Metals GmbH in Germany and Indium Corporation in the United States refine and recycle germanium for high-purity applications in semiconductors and advanced electronics. AXT, Inc. and 5N Plus Inc. focus on compound semiconductor manufacturing and specialty chemicals, sourcing germanium for wafer production and defense-related optical applications. China Germanium Co., Ltd. rounds out the key players as an integrated producer offering high-purity metal and refined products for electronics and fiber optic sectors.
Recent developments highlight the intensity of strategic maneuvering. In January 2026, the Department of Defense invested 18.1 million USD in Defense Production Act funds to expand zone refining capacity for germanium metal sevenfold at the St. George, Utah facility operated by 5N Plus Inc., targeting optics and satellite solar crystals. In March 2026, Indium Corporation received a New Product Introduction Award for their halogen-free solder paste, signaling innovation in assembly applications. Metallium Limited signed a 10-year offtake agreement with Indium Corporation to supply recovered gallium and germanium from U.S. recycling operations, emphasizing the growing importance of circular supply chains. Additionally, Blue Moon Metals Inc. closed the purchase of Teck's Apex germanium and gallium mine in March 2026, securing a domestic primary supply source.
Segmentation Insights and Application Drivers
Understanding where demand originates is crucial for targeted investment. The market is segmented by type, application, and region, with each segment exhibiting distinct growth characteristics. Product forms such as germanium ingots, tetrachloride, and high-purity dioxide serve different industrial needs, from semiconductor substrates to optical lens manufacturing.
On the application side, fiber optics remains a dominant consumption channel, driven by global bandwidth expansion and telecommunications infrastructure upgrades. Infrared optics continues to be a critical segment, fueled by defense, thermal imaging, and night vision technologies. Electronics and solar applications represent a growing frontier, particularly as compound semiconductors gain traction in high-efficiency photovoltaic cells and specialized electronic components.
Regional consumption patterns reveal a complex tapestry of demand. While Asia Pacific remains a central hub for manufacturing and consumption, North America and Europe are prioritizing supply chain security and domestic processing capabilities. Latin America and the Middle East and Africa represent emerging opportunities, though their current share reflects developing infrastructure and limited localized refining capacity. The report provides a deep dive into how these regional dynamics interact with trade policies and logistics costs.
Report Content and Operational Utility
This market research is designed as a decision-support tool for executives, procurement managers, and investors. It contains detailed profiles of key companies, analyzing their capacities, strategic focus, and recent operational moves. The competitive landscape section evaluates market share distribution and identifies potential partnerships or M&A opportunities that could reshape the industry.
Readers will find comprehensive segmentation analysis that breaks down revenue contributions by product type and application without exposing sensitive proprietary data until the full report is accessed. The regulatory impact analysis quantifies how export controls and tariffs affect supply chain costs and lead times. Furthermore, the price trend analysis correlates historical data with policy events to forecast potential future scenarios.
Our methodology ensures that all data is cross-verified with industry sources and government publications. The forecast model incorporates multiple variables, including production capacity expansions, recycling rates, and demand elasticity for downstream technologies. This rigorous approach ensures that the insights provided are robust enough to support CAPEX planning, inventory strategy, and market entry decisions.
Germanium Market
Conclusion: The Imperative for Intelligence
As the germanium market navigates a period of historic transformation, information asymmetry will be the primary differentiator between success and stagnation. The convergence of geopolitical tension, technological demand, and supply chain restructuring creates a complex environment where intuition is insufficient. Access to verified, forward-looking data is essential.
PW Consulting's Germanium Market report offers the depth and clarity required to make informed strategic choices in 2026 and beyond. We invite you to explore the full findings, including detailed segmentation data, comprehensive company profiles, and scenario-based forecasts, by visiting our research portal. Secure the intelligence needed to lead in a critical materials market.
Indium Market
For detailed analysis of this topic, please visit the official page: Germanium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Road Transport Refrigeration Equipment Market Hits $4.48 Billion in 2025, Growing at 5.8% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Cold Chain: Navigating the Road Transport Refrigeration Equipment Market from 2026 Onward
The global logistics infrastructure underpinning perishable goods, pharmaceuticals, and temperature-sensitive industrial products relies fundamentally on the reliability of road transport refrigeration equipment. As supply chains grow more complex and regulatory frameworks tighten, the market for transport refrigeration units has evolved from a commodity hardware sector into a strategic battleground defined by electrification, emissions compliance, and operational efficiency. Our recently published market research offers a definitive lens through which organizations can assess the structural shifts reshaping this industry. The findings provide a critical framework for decision-makers who must allocate capital, plan fleet transitions, and position themselves competitively through 2032.
The Trajectory of Growth and Capital Allocation
The sector has demonstrated consistent resilience through the early twenty-first decade, reflecting the indispensable nature of temperature-controlled logistics. Historical revenue data from 2020 through 2025 reveals a steady expansion trajectory, with the global market climbing from approximately 3.38 billion USD to 4.48 billion USD over that five-year window. This upward momentum is not merely a recovery from prior disruptions but a structural expansion driven by increased cold chain outsourcing, cross-border perishable trade, and stricter food safety mandates worldwide.
Looking forward, the forecast period spanning 2026 to 2032 projects the market to approach 6.65 billion USD by the end of the decade. This growth is underpinned by a compound annual growth rate of 5.8 percent, signaling a sustained, moderate expansion rather than a speculative boom. For strategic planners, this CAGR represents a reliable baseline for capacity planning, sales pipeline modeling, and investment horizon alignment. The forecast accounts for both organic demand growth and the technological substitution effects expected as legacy diesel fleets face increasing pressure from zero-emission mandates. The revenue curve suggests that while volume will increase, the margin dynamics will diverge significantly between traditional mechanical units and next-generation electric platforms, making operational cost modeling an essential component of any go-to-market strategy.
Regulatory Dynamics and the Electrification Imperative
The regulatory environment has emerged as the single most disruptive force shaping procurement strategies and product roadmaps. The California Air Resources Board has taken a pioneering role, implementing amendments that effectively dictate the pace of technological transition across the United States and influencing global standards through trade and manufacturing alignment. Under the TRU ATCM amendments, newly manufactured truck and trailer refrigeration units must now utilize refrigerants with a global warming potential of 2,200 or lower, or operate without refrigerant entirely. Furthermore, model-year 2023 and newer units must meet stricter particulate standards, raising the bar for emissions compliance across the board.
These mandates carry hard deadlines that require immediate fleet planning. As of December 31, 2025, truck TRU fleets operating in California must achieve a 45 percent zero-emission composition, with the threshold rising to 60 percent by December 31, 2026. The U.S. Environmental Protection Agency granted a partial waiver of federal preemption for these zero-emission requirements in January 2025, simultaneously authorizing the state to enforce the remainder of the rule. This creates a de facto compliance cascade: manufacturers and operators who fail to prepare for the 2026 threshold will face mounting operational fees, registration restrictions, and mandatory reporting burdens. The economic calculus of compliance is shifting from a peripheral concern to a core component of total cost of ownership analysis.
Energy cost differentials further accelerate the incentive to transition. Electric transport refrigeration units consume approximately 8.1 kW per hour, whereas traditional diesel units burn roughly 0.8 gallons of diesel per hour. The resulting average hourly savings of 1.36 USD may appear modest on a per-unit basis, but when scaled across large fleets and factoring in maintenance reductions, the cumulative impact on operating margins becomes substantial. These operational economics must be weighed against the higher upfront capital expenditure of electric platforms and the infrastructure requirements for charging depots, making a phased transition strategy essential for fleet managers.
Competitive Arena and Strategic Positioning
The market exhibits moderate concentration, with the top three players commanding approximately 45 percent of global revenue and the top five consolidating around 65 percent. This structure indicates a competitive landscape where dominant incumbents hold significant sway over pricing, technology standards, and dealer networks, while leaving meaningful room for regional specialists and innovation-driven challengers to capture niche segments. The presence of established multinational manufacturers alongside agile regional players creates a dynamic environment where partnerships, aftermarket service quality, and local regulatory expertise often determine winning positions as much as hardware specifications do.
Road Transport Refrigeration Equipment Market
Thermo King, headquartered in Wood Dale, Illinois, continues to broaden its portfolio across diesel, hybrid, and all-electric transport refrigeration units for trucks, trailers, and vans. Its July 2025 introduction of the V-520 nose-mount unit for small to medium box trucks demonstrates a focused push into segments requiring precise temperature control with compact footprint constraints. Carrier Transicold, based in Minneapolis, maintains a strong position with diesel-powered and electric refrigeration units and integrated cooling systems for road transport. Its Vector 8811MT refrigeration unit for center-divide trailers, also launched in mid-2025, emphasizes reduced maintenance intervals and lower operating costs, directly addressing the total cost of ownership concerns that fleet operators increasingly prioritize.
In Asia, Guchen Thermo has established a strong manufacturing footprint in China, producing diesel, electric, and battery-powered transport refrigeration units tailored for medium and heavy trucks. Its growth trajectory reflects the broader expansion of cold chain logistics in developing economies and the increasing domestic demand for temperature-controlled freight. Zanotti, an Italy-based specialist now operating as a Daikin Industries subsidiary, focuses on refrigerated van and truck refrigeration systems and conversions, leveraging its integration with a global refrigerant and HVAC technology leader to advance low-GWP and zero-emission solutions. Kingtec Group, with headquarters in the United States and global operations, manufactures transport refrigeration and cold storage solutions for trailers, trucks, and recreational vehicles, expanding its addressable market beyond traditional freight into adjacent mobile cooling segments. Hubbard Products Ltd, based in the United Kingdom, serves as a supplier and innovator of commercial and transport refrigeration equipment, bringing specialized engineering capabilities and a strong service network to the European and export markets.
Segment Structure and Demand Drivers
The product landscape bifurcates primarily around temperature control complexity. Single temperature units continue to represent the dominant share of revenue, driven by the extensive volume of dedicated cold-chain and frozen logistics applications where simplicity, lower cost, and proven reliability are paramount. Multi-temperature units, while representing a smaller overall share, deliver disproportionate value in mixed-load operations where a single trailer must simultaneously serve compartments at different thermal setpoints. The flexibility of multi-temperature configurations supports consolidated shipping, reduces empty miles, and appeals to operators managing diverse SKU portfolios, particularly in regional distribution and food service supply chains.
Trailer Refrigeration System Market
Application-wise, the food and beverage sector remains the overwhelming anchor of demand, reflecting the relentless global consumption of perishable goods and the regulatory and consumer-driven requirements for unbroken cold chains from farm to fork. Pharmaceutical and healthcare applications, while commanding a smaller revenue share, represent a high-value niche where temperature excursions carry severe regulatory and patient safety consequences. This segment demands stricter validation protocols, more sophisticated monitoring integration, and higher willingness to pay for reliability. Floral products constitute a specialized application where short transit windows, seasonal volatility, and precise humidity and temperature control combine to create a demanding operational environment that tests the precision and durability of transport refrigeration systems.
Material Volatility and Operational Realities
Beyond regulatory and competitive pressures, the industry faces ongoing supply chain friction. Steel components used in TRU housings and structural elements have experienced persistent volatility due to fluctuations in global metal markets. These input cost swings directly affect manufacturing margins and delivery lead times, requiring procurement teams to adopt hedging strategies, long-term supplier agreements, or design-for-manufacturing adjustments that reduce material intensity without compromising durability. As the market expands toward 2032, manufacturers that can stabilize their supply base while maintaining quality standards will hold a distinct advantage in a price-sensitive but compliance-driven environment.
The release of the first-ever report on transport refrigeration by the North American Council for Freight Efficiency in late 2024 marked a significant step toward establishing industry-wide benchmarks on efficiency and performance. This kind of third-party benchmarking creates transparency that benefits operators evaluating competing units and pushes manufacturers to demonstrate verifiable performance rather than relying solely on specifications. It also gives fleet managers the data needed to build internal business cases for fleet renewal programs and to compare total cost of ownership across diesel, electric, and hybrid platforms under real-world operating conditions.
Inside the Road Transport Refrigeration Equipment Market Research
Our newly released study goes far beyond top-line market sizing. It delivers a granular examination of the forces that will shape procurement, manufacturing, and sales strategies through the end of the decade. The research unpacks the compliance timeline implications of California's TRU ATCM and evaluates how the partial EPA waiver alters the enforcement landscape for facilities and operators. It maps the competitive positioning of incumbent manufacturers, analyzing product launch cadence, technology roadmaps, and the strategic significance of recent introductions such as the V-520 and Vector 8811MT within their respective target segments.
The report also dissects the structural balance between single temperature and multi-temperature units, identifying where design simplification converges with cost pressures and where multi-zone flexibility drives premium pricing in mixed-load logistics. It examines application-level demand patterns across food and beverage, pharmaceutical and healthcare, and floral products, revealing how risk tolerance, validation requirements, and operational tempo differ across these verticals and how those differences translate into pricing power and service expectations. Supply-side dynamics are explored in detail, including the impact of steel price volatility on manufacturing economics and the infrastructure and charging considerations that determine the pace at which electric TRUs can realistically scale.
Finally, the study integrates the latest regulatory events, including the June 2025 CARB implementation update and FAQ that detail compliance requirements for facilities and operators, the enforcement guidance authorizing operating fees, registration requirements, and reporting for all TRUs, and the broader efficiency benchmarking that is reshaping procurement evaluation criteria. These elements are woven into scenario-based frameworks that allow decision-makers to test their strategies against alternative compliance timelines, energy price trajectories, and fleet renewal cadences.
Strategic Imperative for 2026 Decision-Makers
For executives, procurement leaders, and strategic planners, the window between now and 2026 represents a critical inflection point. The 5.8 percent CAGR provides a reliable backdrop for growth planning, but it is the intersection of regulation, electrification economics, and competitive intensity that will separate leaders from laggards. Organizations that treat zero-emission compliance as a distant checkbox risk abrupt cost shocks and operational disruptions. Those that integrate the 2025 and 2026 California thresholds into multi-year fleet planning, evaluate total cost of ownership across electric and diesel platforms using real hourly savings data, and align product sourcing with the capabilities of manufacturers who have demonstrated recent innovation velocity will secure a durable competitive advantage.
The full report provides the detailed segmentation analysis, regional revenue breakdowns, competitive financial proxies, scenario modeling, and actionable recommendations necessary to convert these macro insights into executable strategy. Readers seeking to validate internal assumptions, benchmark procurement options, or build investment cases for fleet modernization should access the complete market intelligence to inform their 2026 and beyond planning with precision.
For detailed analysis of this topic, please visit the official page: Road Transport Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


