



PW Consulting: Flavor Enhancer Market Hits $6.8B in 2025, 6% CAGR to $10.06B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence in the Food Flavor Enhancer Market: Navigating Growth and Complexity Through 2032
The global food flavor enhancer industry is entering a decisive phase of transformation. As consumer preferences shift toward cleaner labels, functional nutrition, and reduced sodium profiles, manufacturers across the value chain face a critical window to align product portfolios with emerging demand signals. PW Consulting's latest Food Flavor Enhancer Market research provides a rigorous, data-grounded framework to support executive decision-making through the 2026-2032 forecast horizon. This report is structured not as a static snapshot, but as a living strategic asset designed to inform capital allocation, competitive positioning, and supply chain resilience in a market that continues to evolve at a measured yet unmistakable pace.
Food Flavor Enhancer Market
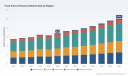
Drawing on verified historical data and forward-looking modeling, the analysis traces a market that expanded from approximately 5.5 billion USD in 2020 to an estimated 6.8 billion USD in 2025, with a projected trajectory toward roughly 10.1 billion USD by 2032. The forecast points to a compound annual growth rate of 6.0 percent over the forecast period, reflecting steady volume expansion supported by industrial food processing, retail convenience formats, and ongoing reformulation efforts in mature and emerging economies alike. Base-year calibration for 2025 anchors the modeling to current operating conditions, while the projection window captures the intersection of consumer behavior shifts, regulatory recalibration, and technological optimization within the flavor ingredients ecosystem.
Market Structure and the Strategic Signal Within the Data
Understanding the architecture of this market requires looking beyond headline revenue figures. Historical movement between 2020 and 2025 reveals how external pressures, commodity dynamics, and product mix adjustments shaped year-over-year performance, including periods of compression and recovery that tested supply chain discipline. The forecast period from 2026 through 2032 maps a sequence of incremental gains, with year-by-year estimates calibrated to reflect realistic adoption curves, capacity announcements, and pricing sensitivity across major end-use channels.
The analytical depth within the full report decomposes these trajectories across the core dimensions that matter to strategy teams: product type, application category, and geographic footprint. Rather than offering generic statements, the study isolates where momentum is concentrating, which segments exhibit structural durability versus cyclical vulnerability, and how category leadership is likely to shift as ingredient platforms mature. Critically, the segmentation analysis is designed to inform product roadmap decisions, pricing strategy, and regional Go-to-Market prioritization without exposing sensitive competitive signals prematurely. Executives seeking the complete set of segment-level estimates, share distributions, and growth attribution breakdowns will find them within the full publication, where each figure is cross-referenced with demand drivers and supply-side constraints.
Competitive Landscape: Consolidation, Differentiation, and the Playbook of Leading Players
The flavor enhancer space is characterized by a concentrated core of globally active ingredient and flavor companies, complemented by regional specialists that compete on formulation expertise, sourcing proximity, or application-specific performance. Concentration metrics within the study indicate that a small group of established players commands a substantial share of total market revenue, underscoring the importance of differentiation through innovation, sourcing reliability, and regulatory readiness. At the same time, the presence of multiple competitors across glutamate-based systems, yeast-derived ingredients, hydrolyzed vegetable proteins, and specialty taste modulation solutions signals a market where technical capability and customer intimacy remain decisive.
Several companies stand out for their scale, technological breadth, and geographic reach. Ajinomoto Co., Inc. remains closely associated with monosodium glutamate production rooted in fermentation-based processes using plant-derived feedstocks, while also expanding its operational footprint in key producing markets. Givaudan SA continues to advance plant-derived and natural alternative platforms, increasingly emphasizing speed-to-market through digital and consumer-insight tools. Kerry Group plc has built a strong position around natural umami and yeast-derived systems suited to processed and savory applications. International Flavors & Fragrances Inc. offers a broad portfolio spanning synthetic and natural enhancement solutions for food processing environments, and Sensient Technologies Corporation supplies integrated flavor systems that support multiple beverage and food categories. Mane SA and Takasago International Corporation contribute specialized ingredient capabilities, while Biospringer by Lesaffre, Ohly, and Angel Yeast Co., Ltd. represent a strong yeast-based value chain that spans both traditional umami enhancement and clean-label positioning. Firmenich SA and Symrise AG round out a competitive set that blends taste modulation science with application-focused formulation support.
Beyond these anchor names, the landscape includes additional suppliers such as American International Foods, Inc., which maintains a strong MSG supply orientation, and Actus Nutrition, whose whey protein-based ingredient portfolio adds another functional dimension to flavor enhancement discussions. Rather than treating this roster as a static directory, the report evaluates each company's strategic posture in terms of capacity decisions, platform launches, geographic expansion, and response to regulatory change. This company-level intelligence is essential for benchmarking, partnership assessment, and competitive threat mapping.
Recent Developments Shaping the 2026 Decision Calendar
Recent operational moves and innovation announcements signal where the industry is placing its bets. In late 2025, Ohly opened a new spray drying tower in Hamburg, Germany, expanding production capacity for yeast-based flavor enhancer products and reinforcing the strategic importance of yeast extract platforms in natural enhancement strategies. Around the same period, Ajinomoto expanded its MSG production footprint across Brazil, Vietnam, and Thailand, a move that strengthens global supply resilience and positions the company closer to demand centers in multiple regions. In the spring of 2025, Fufeng Group introduced a new plant-based MSG product line at a major food additives expo, targeting clean-label and vegan applications and reflecting the broader industry push toward label-friendly presentation without abandoning performance expectations.
Flavor and Fragrance Market
Innovation cadence also accelerated through platform launches and trade show activity. Givaudan showcased Myromi and Consumer Foresight platforms at VivaTech 2025, designed to compress innovation cycles and connect sensory science with consumer trend intelligence. Ajinomoto Health & Nutrition introduced Salt Answer and Palate Perfect platforms aimed at sodium reduction and taste optimization, directly addressing one of the most persistent reformulation challenges in savory and processed food categories. These developments illustrate a market in which competitive advantage is increasingly tied to formulation agility, messaging precision, and the ability to translate scientific advances into commercial-ready solutions.
The full report situates each of these events within a broader strategic context, assessing their implications for capacity utilization, regional supply balance, and the pace of substitution between traditional and alternative enhancer systems.
Regulatory and Supply-Side Dynamics That Cannot Be Ignored
No forward-looking strategy in this sector is complete without accounting for the regulatory environment and feedstock realities that influence cost structures and market access. In early 2026, the U.S. Department of Commerce conducted antidumping duty administrative reviews and released preliminary results concerning imports of monosodium glutamate from China, while the U.S. International Trade Commission subsequently determined that revoking existing antidumping orders on MSG from China and Indonesia would likely lead to continuation or recurrence of material injury. These actions create a complex trade environment with direct implications for pricing, sourcing decisions, and the cost competitiveness of imported versus domestically sourced or regionally produced material.
On the regulatory front, the U.S. Department of Health and Human Services directed the FDA in 2025 to explore rulemaking that could affect the self-affirmed GRAS pathway for food ingredients, including flavor enhancers. Although MSG continues to maintain GRAS status and remains subject to standard ingredient-panel labeling requirements, any tightening or clarification of the pathway for ingredient recognition would have ripple effects across product development timelines, documentation burdens, and the speed at which new enhancer systems can reach market. The report analyzes these dynamics not as isolated headlines, but as structural variables that shape portfolio risk, compliance strategy, and market entry sequencing.
Supply-side considerations are equally important. Corn starch remains the primary feedstock for monosodium glutamate production in China, accounting for a substantial majority of usage in 2025, which ties producer economics to agricultural commodity trends, regional availability, and input cost volatility. For companies dependent on glutamate-based systems, feedstock exposure is a strategic variable that influences both margin stability and geographic sourcing strategy. The study integrates these raw material dynamics into its segment discussion, highlighting where input sensitivity is most acute and where alternative feedstock routes or ingredient platforms may offer greater resilience.
What the Report Delivers: An Action-Oriented Blueprint
PW Consulting's Food Flavor Enhancer Market research is designed to convert complex market information into executable strategy. The publication provides a full historical and forecast series anchored to 2025 base-year conditions and extended through 2032, enabling scenario modeling for revenue planning, capacity planning, and long-cycle investment decisions. The segmentation framework covers the primary type categories, major application domains, and regional markets, with discussion of the demand logic, competitive intensity, and development patterns that differentiate each segment. Rather than offering undifferentiated growth numbers, the analysis connects each segment to the operating conditions that drive performance, giving readers a practical basis for prioritizing resources.
The competitive section combines company profiles, recent development tracking, and strategic interpretation to help readers assess relative positioning, risks, and opportunities across the market. Regional and application-level insights are paired with regulatory and supply-side context so that strategy teams can evaluate not only where growth is happening, but also what conditions must be managed to capture it. This integrated approach is especially valuable for organizations evaluating new formulation platforms, considering geographic expansion, or weighing exposure to trade policy and ingredient recognition changes.
Importantly, the report functions as a decision-support system rather than a standalone dataset. It enables users to test assumptions about category substitution, sodium-reduction reformulation, clean-label positioning, and supply chain localization. By linking market size evolution to underlying drivers, the study helps executives distinguish between temporary fluctuations and durable structural shifts, reducing the risk of overreacting to short-term noise or underestimating longer-term transitions.
Why This Research Matters for 2026 Decision-Making
The 2026-2032 window is shaping up to be a period in which disciplined strategy will separate durable performers from reactive followers. A 6.0 percent CAGR may appear moderate at the headline level, but the composition of that growth matters immensely. Different product types, applications, and regions are advancing at different speeds, and the companies that succeed will be those able to combine technical credibility with supply resilience, regulatory readiness, and sharp customer insight. Recent capacity investments, platform launches, and trade-policy developments already demonstrate that the boardroom agenda in this market extends well beyond volume growth alone.
Executives using this report will be better positioned to answer several critical questions: where to concentrate innovation resources, how to anticipate regulatory and trade-related disruptions, which ingredient platforms offer the strongest long-term alignment with label and health trends, and how to interpret competitor activity without losing sight of proprietary positioning. The complete segmentation data, regional breakdowns, application-level estimates, and company-level intelligence are essential to turning these questions into concrete plans.
For decision-makers who require the full granularity necessary to set budget priorities, define market-entry strategies, and evaluate competitive threats, the complete Food Flavor Enhancer Market research provides the depth and structure needed to act with confidence. The teaser figures and directional insights presented here establish the strategic frame; the full report delivers the operational intelligence required to execute within it.
For detailed analysis of this topic, please visit the official page: Food Flavor Enhancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Loyalty Management Market to Hit $10.25 Billion in 2025, Surging to $23.21 Billion by 2032
By PW Consulting, 2026-09-16
Global Loyalty Management Market Intelligence: Strategic Imperatives for 2026 and Beyond
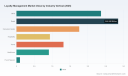
As organizations navigate an increasingly complex customer retention landscape, the global loyalty management market stands at a critical inflection point. Having been carefully tracked from 2020 through 2025 and projected forward across a 2026-2032 forecast horizon, this sector demonstrates a sustained growth trajectory that underscores shifting consumer expectations, technological maturation, and intensifying competitive dynamics. The most recent comprehensive analysis from PW Consulting reveals a market that expanded from approximately 5.4 billion U.S. dollars in 2020 to an estimated 10.25 billion in 2025, with forward calculations projecting continued acceleration toward 11.47 billion in 2026 and extending to a projected 23.21 billion by 2032. This represents a compound annual growth rate of 12.4 percent across the forecast window, positioning loyalty management as one of the more resilient and strategically vital technology domains in the broader customer experience ecosystem.
The Convergence of Scale and Strategic Necessity
What makes these aggregate figures particularly instructive for enterprise decision-makers is not merely the magnitude of expansion but the structural forces driving it. Historical data from 2020 through 2025 reflects a market that weathered macroeconomic volatility while maintaining steady adoption curves across industries. The transition from isolated point solutions to integrated loyalty ecosystems has fundamentally altered how organizations allocate budget, design program architecture, and measure return on customer retention investments. As we look toward 2026, the compounding effect of AI-enabled personalization, omnichannel orchestration, and heightened regulatory scrutiny on data practices creates a decision environment where tactical program adjustments are insufficient. Leadership teams require structural intelligence that maps technology pathways against consumer behavior shifts, competitive benchmarks, and compliance calendars.
Regulatory Realignment and Consumer Value Expectations
The 2026 operating environment introduces regulatory and behavioral pressures that directly reshape loyalty program design. Effective January 1, 2026, California Consumer Privacy Act regulations classify loyalty programs offering points, rewards, or other financial incentives as triggers for mandatory consumer disclosures. Businesses must now provide clear notices detailing material program terms, categories of implicated personal information, and the perceived data value exchanged before consumers opt into data collection. This regulatory layer compounds existing GDPR obligations around transparency in data processing and mandates Data Protection Impact Assessments for higher-risk loyalty activities.
Simultaneously, consumer motivation patterns are recalibrating around immediate economic benefit. Industry studies published in early 2026 indicate that approximately 85 percent of Quick-Service Restaurant loyalty participants prioritize cost-saving benefits as their primary engagement driver in an inflationary environment. This behavior signals a broader market shift where value-focused program structures, transparent reward economics, and frictionless redemption paths are becoming baseline expectations rather than competitive differentiators. Organizations that fail to align program architecture with these dual forces of regulatory clarity and consumer value sensitivity risk elevated opt-out rates, diminished lifetime value capture, and reputational exposure around data practices.
Competitive Landscape Architecture
The loyalty management vendor ecosystem now spans established enterprise platforms, cloud-native engagement suites, and specialized retail or sector-focused solutions, each occupying distinct positioning along orchestration depth, integration complexity, and deployment modality. Salesforce delivers cloud-based loyalty management capabilities that emphasize real-time insights and integrated customer profile analytics within broader marketing technology workflows. Oracle embeds loyalty functions within CRM and ERP architectures to support personalized retention strategies at enterprise scale, while SAP focuses on large-scale customer engagement programs driven by structured data and enterprise-grade reward management. Adobe contributes creative and data-driven platform capabilities with emphasis on journey orchestration and personalization for retention outcomes.
Loyalty Management Market
In the specialized and mid-market segments, several vendors have carved differentiated positions. Capillary Technologies concentrates on enterprise-focused, AI-powered omnichannel programs spanning retail, travel, and automotive verticals with an increasingly explicit posture toward privacy-first loyalty design. LoyaltyLion targets e-commerce and retail organizations with streamlined program setup and analytics-focused tooling. Yotpo integrates loyalty mechanics with reviews, referrals, and user-generated content to deepen engagement loops. Annex Cloud and Ignite Retail Technology both emphasize omnichannel engagement and scalable analytics, with Ignite notably extending its unified platform footprint through recent retail and convenience-channel deployments. Zinrelo and Open Loyalty differentiate through multi-channel program flexibility, gamification mechanics, and API-first or headless design philosophies that support bespoke program construction. TrueLoyal positions around combined rewards and fan club mechanisms to drive retention and brand advocacy across channels. GROWERS applies AI-enhanced loyalty architecture to agriculture retail, enabling customized rewards and predictive insights for retailers and producers.
This competitive spread reflects a market in which no single solution archetype dominates all use cases. Rather, enterprises face a segmentation challenge in matching organizational maturity, data infrastructure readiness, channel complexity, and compliance posture to appropriate platform classes. PW Consulting's market study maps these vendor archetypes against deployment patterns, solution types, and organizational sizing to support more defensible selection and investment reasoning. The analysis also highlights market concentration dynamics that indicate meaningful share distribution among leading providers while leaving substantial openness for specialized and emerging entrants in targeted verticals.
Operational Intelligence Within the Full Research Scope
The complete PW Consulting loyalty management market research extends well beyond headline sizing and growth rates. Executive and strategy readers can expect a structured examination of solution architecture classifications, deployment preference evolution, organization-size adoption curves, and industry vertical demand patterns that together reveal where investment momentum is concentrating and where white-space opportunities are forming. By solution orientation, the study distinguishes platform-based, API-based, and services-led delivery models and examines how each maps to enterprise integration requirements, speed-to-program timelines, and ongoing management burdens. Deployment analysis compares on-premise and cloud-anchored adoption trajectories, including the operational and governance implications of each path under evolving data-handling expectations.
Retail Bank Loyalty Program Market
The research also breaks down organization-size dynamics to differentiate large enterprise program strategies from small and mid-sized enterprise adoption constraints and acceleration paths. Vertical-level viewing captures demand intensity across BFSI, retail, consumer goods, hospitality, travel, healthcare, IT and telecom, and adjacent sectors, illustrating where loyalty programs are evolving from promotional vehicles into core retention and data-strategy assets. Importantly, the study intentionally withholds granular percentage splits and dollar-level breakdowns of these segments within this preview to preserve analytical exclusivity; full segment matrices, cross-tabulations, and forward demand allocations are reserved for the complete report and accompanying data appendices.
Recent Market Movements and Their Strategic Signals
Several recent developments provide early indicators of how vendor capabilities and enterprise adoption are co-evolving. In late 2025, Ignite Retail Technology announced a platform partnership through which a major convenience retailer transitioned loyalty operations to its unified platform for enhanced analytics and multi-channel engagement, signaling growing enterprise appetite for consolidated loyalty-and-analytics architectures rather than fragmented point tools. Earlier in the year, GROWERS launched AI-driven enhancements to its agriculture-focused loyalty offering, enabling predictive insights for retailers and farmers and demonstrating how sector-specific loyalty technology is moving toward forward-looking decision support rather than retrospective reward tracking. Mid-2025 saw Capillary Technologies publicly emphasize privacy-first loyalty strategies amid evolving regulations, reinforcing the market-wide recognition that compliance-aware design is now a core capability rather than a peripheral legal consideration. In early 2026, Alchemer released a Quick-Service Restaurant study reinforcing the consumer cost-sensitivity trend, further validating the strategic importance of value-aligned loyalty economics.
Strategic Decision Framework for 2026 Planning
For leadership teams constructing 2026 technology roadmaps, loyalty management now demands evaluation across three interlocking lenses. First, architecture and integration readiness determine whether loyalty data can feed broader customer profiles, personalization engines, and enterprise analytics with sufficient latency and fidelity. Second, compliance and data-value transparency must be designed into program mechanics from inception, particularly as incentive-linked data collection triggers expanded disclosure duties in key jurisdictions and as cross-border privacy expectations continue to harden. Third, program economics and consumer motivation alignment require explicit testing of reward structures, redemption friction, and perceived value against current inflationary behavior patterns, especially in high-frequency verticals where immediate savings increasingly outweigh abstract points accumulation.
The most effective 2026 strategies will treat loyalty platforms not as standalone promotional utilities but as structural components of customer data infrastructure, lifetime value optimization, and regulatory resilience planning. That shift requires decision-makers to evaluate vendors and deployment pathways against operational outcomes rather than feature checklists, and to incorporate segment-specific demand signals rather than relying on generic adoption narratives.
Accessing Complete Market Intelligence
A disciplined approach to loyalty investment in 2026 begins with access to the full dataset, competitive benchmarking, vertical demand mapping, and solution-deployment cross analysis that only the complete PW Consulting research provides. The detailed report delivers precise segment allocations, forward demand projections by organization size and industry vertical, solution-type growth reasoning, deployment trajectory commentary, and vendor positioning frameworks that together support procurement, product strategy, and board-level investment rationale.
The full study, accompanying executive summaries, and segment-level intelligence are available through the source research portal. Readers seeking complete quantitative matrices, competitive profiles, regulatory-impact scenario mapping, and actionable planning templates are encouraged to access the full report directly to obtain the granular intelligence necessary for high-stakes strategic decisions.
Conclusion: From Tactical Loyalty to Structural Retention Advantage
The loyalty management market's sustained double-digit growth trajectory through 2032 reflects a durable transition in how enterprises conceive retention: from transactional reward distribution toward integrated, data-rich, compliance-aware engagement infrastructure. For 2026 decision-makers, the strategic opportunity lies in selecting platforms, program architectures, and governance practices that convert regulatory complexity and consumer value sensitivity into differentiated retention advantage. PW Consulting's market research provides the foundational intelligence needed to make those choices with confidence, while the complete report preserves the segment-level detail and competitive depth that executive planning demands.
For detailed analysis of this topic, please visit the official page: Loyalty Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Running Watches Market Hits $7.4B in 2025, 9.4% CAGR to $13.9B by 2032
By PW Consulting, 2026-09-16
Navigating the Next Horizon: Strategic Intelligence for the Global Running Watches Market (2026–2032)
The athletic wearables sector has matured rapidly over the past five years, transforming from a niche enthusiast category into a core component of the broader performance technology ecosystem. As we approach the mid-decade inflection point, organizations operating across manufacturing, retail, investment, and strategic planning require a disciplined lens into the structural forces shaping the Running Watches Market. PW Consulting’s latest industry analysis provides a comprehensive, boardroom-ready examination of the landscape from a 2025 base year through a 2032 forecast horizon, translating historical momentum into actionable intelligence. The study maps a clear trajectory from a 4.74 billion USD valuation in 2020 to a projected 13.95 billion USD by 2032, anchored by a compound annual growth rate of 9.4 percent. This document outlines the strategic architecture of the report and demonstrates how decision-makers can leverage its frameworks to navigate competitive intensity, supply chain volatility, and accelerating consumer demands.
A Decade of Acceleration: Mapping the Revenue Trajectory
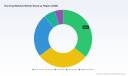
Historical performance across the 2020 through 2025 window reveals an unbroken expansion curve, with annual valuations climbing from 4.74 billion to 7.43 billion USD. The progression from 5.28 billion in 2021, 5.85 billion in 2022, and 6.11 billion in 2023 demonstrates sustained demand absorption, while the subsequent jump to 6.90 billion in 2024 and 7.43 billion in 2025 confirms that growth has decoupled from post-pandemic recovery dynamics. Looking forward, the forecast model positions 2026 at 8.33 billion USD and extends steadily upward, reaching 9.06 billion in 2027, 9.82 billion in 2028, 10.73 billion in 2029, 11.65 billion in 2030, 12.86 billion in 2031, and ultimately 13.95 billion by 2032. These figures are not isolated projections; they reflect modeled demand elasticity, product cycle cadence, and the structural migration of mainstream fitness consumers toward performance-grade instrumentation. Crucially, the research isolates the primary velocity drivers without oversimplifying the underlying complexity. Readers will find explicit analysis of how GPS-enabled precision, physiological monitoring integration, and multi-sport versatility are reshaping purchase criteria across different user cohorts. The narrative deliberately avoids fragmenting the outlook by slicing the market into isolated regional or application-level percentage shares, because executive strategy demands a first-principles understanding of interaction effects, capacity allocation, and portfolio prioritization rather than static tabular breakdowns.
Portfolio Architecture and Product-Level Innovation
The report dissects the product ecosystem along a structured type framework that captures the full spectrum of running-centric instrumentation. This segmentation spans GPS-native devices, standalone pedometer-focused instruments, dedicated heart-rate monitoring watches, and hybrid GPS plus heart-rate models optimized for continuous athletic tracking. The analysis demonstrates how each architecture serves distinct positioning tiers and how manufacturers are engineering feature convergence to capture overlapping demand pools. Parallel to this, the application landscape is mapped across running, biking, cardio training, climbing, and adjacent use cases, revealing how cross-training behavior, outdoor endurance pursuits, and structured fitness programming are influencing SKU rationalization and platform investment. Rather than presenting these dimensions as disconnected columns, the study examines how product architecture, sensor suites, and software ecosystems must be aligned with consumer use patterns to protect margin profiles and reduce inventory risk. Strategic readers will gain clarity on where engineering investment yields the strongest competitive differentiation, which feature combinations are becoming table-stakes, and how platform modularity is enabling faster iteration cycles without compromising cost discipline.
Running Watches Market
Competitive Architecture and Strategic Positioning
Market concentration remains pronounced, with the top three participants commanding roughly 72.4 percent of aggregate revenue and the top five consolidating approximately 88.0 percent. This concentration underscores the importance of understanding not merely who leads the category, but how incumbents defend share while emerging and adjacent players pursue differentiated value propositions. Garmin continues to anchor the premier performance tier through a disciplined lineup built around the Forerunner 970 and Forerunner 570, alongside the Fenix 8 and Enduro 3 series. Their strategy emphasizes precise training metrics, advanced navigation, and athlete recovery instrumentation, reinforcing a positioning that appeals to serious runners and triathletes who treat their wearables as performance management platforms. COROS has carved a distinct identity in the ultralight endurance space, leveraging the Pace 4, Apex 4, and NOMAD to deliver multi-sensor navigation, extended battery life, and rugged outdoor construction. In August 2025, COROS expanded this footprint with the NOMAD outdoor GPS watch, introducing dual-frequency navigation, detailed mapping, rugged construction, and an Adventure Journaling capability that broadens its utility beyond conventional running sessions. Suunto maintains a strong presence through multisport and running GPS devices, including the Vertical 2, Run, and 9 series, where dive-rated durability, precise heart rate capture, and performance data delivery under extreme conditions differentiate its engineering narrative. Polar approaches the category through advanced physiological monitoring and training optimization, exemplified by the Vantage M3, Street X, and broader Vantage lineup, which integrate heart rate and GPS running capabilities into structured performance feedback loops. Meanwhile, Amazfit represents an increasingly influential affordability-and-functionality axis, with T-Rex 3 Pro, T-Rex Ultra 2, and Active series offerings that balance GPS accuracy, battery endurance, and fitness tracking at accessible price points. In May 2026, iRunFar updated its best GPS running watches guide to reflect the latest 2026 lineup, validating pricing and availability while incorporating models such as the Amazfit T-Rex Ultra 2, signaling how independent verification and consumer media continue to shape purchase consideration.
The research does more than profile product portfolios; it evaluates go-to-market posture, brand equity durability, channel leverage, and innovation cadence. The report examines how premium players protect hardware margins while layering subscription-adjacent services, how mid-tier challengers leverage material efficiency and sensor commoditization to narrow capability gaps, and how value-oriented entrants use packaging, battery longevity, and GPS reliability to defy entry-level stigma. These strategic lenses enable clients to benchmark their own positioning, assess vulnerability to competitive encroachment, and prioritize partnership, acquisition, or product roadmap investments with greater precision.
Smartwatch Market
Structural Shifts: Supply Dynamics and Regulatory Undercurrents
No forward-looking market assessment is complete without addressing the material and policy environments that shape production economics and long-term resilience. In 2025, the U.S. Geological Survey recommended adding copper, silicon, silver, rhenium, and lead to the List of Critical Minerals, directly elevating supply disruption risk for semiconductors, sensors, and precision components embedded in running watches. This development is particularly consequential for manufacturers who depend on tightly integrated electronic assemblies, advanced navigation chipsets, and sensor-grade materials. The same agency’s 2025 methodology for the Critical Minerals List assesses probability-weighted net decreases in U.S. GDP from foreign trade disruptions, prioritizing the monitoring of semiconductor and electronics supply chains. For the running watches sector, this framework signals heightened attention to sourcing diversification, inventory buffering, component substitution feasibility, and geopolitical exposure in downstream electronics manufacturing. The study integrates these supply-side realities into a broader dynamics assessment, showing how raw material classification, trade flow sensitivity, and component lead times can alter cost structures, delay product introductions, and recalibrate competitive advantage for firms that lack flexible procurement architectures. Beyond materials, the analysis considers how ecosystem software, data privacy expectations, firmware update sustainability, and device longevity expectations are becoming structural differentiators. Companies that treat hardware as the entire product are increasingly exposed, while those designing integrated hardware-plus-software experiences with durable update pathways are building more defensible customer relationships and lower churn profiles.
What the Full Research Delivers: Operational Intelligence for 2026 Decision-Making
This report is engineered to function as a working strategic asset rather than a static summary. It combines quantitative modeling with qualitative competitive assessment to support planning cycles across R&D, sourcing, sales, and investment functions. The complete study provides a structured examination of market sizing and forward projections grounded in a consistent 2025 base year and 2032 forecast framework. It details the evolution of product architectures and application demand patterns, helping teams align platform roadmaps with actual usage migration rather than speculative trend narratives. The competitive review places primary emphasis on how leading players structure their value propositions, manage innovation cadence, and defend market share in a concentrated environment. The dynamics section translates critical mineral designations, semiconductor supply considerations, and regulatory monitoring frameworks into implications for procurement strategy, cost planning, and resilience design. The report also addresses how pricing architecture, channel composition, and brand positioning interact to shape profitability, and it maps the practical consequences of independent review cycles and retail validation for launch timing and promotional strategy. Throughout, the analysis is designed to support scenario planning: clients can use the frameworks to test capacity expansion assumptions, evaluate portfolio additions, stress-test supply dependencies, and refine messaging strategies for different consumer tiers. By focusing on the mechanisms that drive the 9.4 percent compound growth trajectory, the study equips teams to make decisions that are robust under multiple demand and cost conditions rather than dependent on a single baseline outcome.
Closing the Intelligence Gap
The Running Watches Market is entering a period in which competitive advantage will be determined less by product availability than by strategic precision. Firms that understand where growth is structurally concentrated, how product architectures are converging, and which supply and regulatory pressures will reshape cost economics will be better positioned to allocate capital, time product introductions, and defend margins. The macro arc from 7.43 billion USD in 2025 toward a 13.95 billion USD endpoint in 2032 is clear, but the strategic value lies in the operational insight beneath that headline: how concentration shapes pricing power, how sensor and navigation innovation changes demand, how material classifications alter sourcing strategy, and how competitive portfolios evolve under sustained scrutiny from both consumers and independent reviewers. PW Consulting’s complete analysis is built to convert these dynamics into executable strategy. Organizations ready to move from observation to decision will find the full dataset, segmentation logic, competitor deep dives, and scenario frameworks essential to shaping their 2026 programs and beyond.
For detailed analysis of this topic, please visit the official page: Running Watches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intravesical BCG Market Hits $195M in 2025, Projected 8.97% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating Supply Chain Complexity and Treatment Demand: Strategic Insights into the Intravesical BCG Market
As the global healthcare landscape continues to evolve, the management of non-muscle invasive bladder cancer remains a critical focal point for urologists, pharmaceutical manufacturers, and healthcare administrators. The Intravesical Bacillus Calmette-Guérin market has experienced steady expansion over the past five years, reflecting both the clinical indispensability of BCG therapy and the structural challenges inherent in biological manufacturing. Our latest market intelligence study provides a comprehensive examination of this evolving landscape, offering executives and strategy teams a rigorous foundation for capital allocation, supply chain planning, and competitive positioning through the 2026 to 2032 forecast horizon.
The therapeutic context for intravesical BCG is unambiguous. Major clinical guidelines continue to position BCG as the preferred adjuvant treatment for intermediate- and high-risk disease presentations, underscoring a durable demand profile that transcends short-term pricing fluctuations or regional reimbursement variations. At the same time, the biological nature of BCG production introduces constraints that have repeatedly tested supply resilience. Understanding how these clinical mandates intersect with manufacturing bottlenecks, regulatory pathways, and regional procurement patterns is precisely the kind of strategic clarity that our research is designed to deliver.
Historical Trajectory and Forecast Outlook
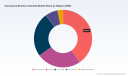
The market has followed a measured but consistent growth curve since the early 2020s, driven by steady adoption in established markets and gradual expansion of access in developing regions. Our historical reconstruction places total market revenue at approximately 150 million dollars in 2020, progressing to 158 million dollars in 2021, 168 million dollars in 2022, 178 million dollars in 2023, and 184 million dollars in 2024. The base year analysis for 2025 reflects continued momentum, with the market reaching 195 million dollars as procurement cycles stabilized and clinical demand maintained its upward trajectory.
Looking forward, our forecast modeling projects the market to exceed 214 million dollars in 2026, followed by progressive expansion toward 237 million dollars in 2027, 241 million dollars in 2028, 279 million dollars in 2029, 292 million dollars in 2030, 315 million dollars in 2031, and 342 million dollars by 2032. The compound annual growth rate across the forecast period is calculated at 8.97 percent, a figure that captures the combined effect of sustained clinical utilization, capacity investments by key manufacturers, and incremental market participation from newly authorized or expanded-access formulations. This trajectory is not merely a statistical projection; it is a strategic signal that underscores the importance of long-term planning for procurement teams, investors, and clinical network operators who must anticipate both volume growth and supply volatility.
Structural Dynamics Shaping Market Behavior
The Intravesical BCG ecosystem is defined by a small number of entrenched manufacturers, each operating within distinct regulatory environments and supply chain architectures. Because BCG is a live biological product, production is inherently sensitive to process validation, strain stability, facility compliance, and distribution logistics. These factors have historically limited the number of viable commercial suppliers and concentrated market participation among a handful of established entities. Our research maps these structural realities in detail, offering decision-makers a clear view of where supply-side constraints originate and how they influence procurement strategies across different clinical settings.
Shortages have been a recurring theme in the market narrative, particularly in regions where a single manufacturer has served as the primary domestic source. This concentration has prompted repeated discussions within clinical guideline bodies regarding dose modification protocols and alternative sourcing strategies when supply disruptions occur. At the same time, recent authorization and supply-agreement developments have begun to diversify the availability landscape, introducing expanded-access programs and cross-border supply arrangements that create new options for treating centers. Our report examines these developments not as isolated announcements, but as interconnected signals that reshape procurement risk, pricing expectations, and competitive dynamics over the forecast period.
The Competitive Landscape: Positioning Among Core Participants
A defining feature of this market is the strategic positioning of its leading commercial participants, each of whom brings a different combination of manufacturing capability, regulatory footprint, and supply-chain response to the table. Our analysis evaluates these participants with a focus on operational readiness, product presentation, and the ability to respond to demand pressure.
One of the most closely watched developments involves the sole U.S.-based manufacturer of a widely recognized intravesical formulation. This company has publicly outlined plans to construct a new production facility intended to significantly expand output capacity, with an operational timeline that positions the expansion to intersect with the later years of our forecast window. The strategic significance of this investment extends beyond volume; it reflects an effort to address persistent supply limitations that have influenced clinical scheduling, procurement planning, and payer discussions for years. Our research explores how this capacity expansion is likely to alter supply risk perceptions and what it implies for market share stability among competing sources.
Alongside this effort, other participants have pursued complementary routes to strengthen availability. One manufacturer and distributor involved in U.S. intravesical administration continues to play a central role in the commercial pathway for a well-established product, maintaining its presence as a key node in the domestic supply chain. In parallel, an Indian-based producer has advanced a lyophilized formulation with broad international authorization for non-muscle invasive bladder cancer treatment, supported by a multi-year shelf-life profile and a presentation designed for practical clinical use. This participant has also been linked to recent regulatory authorization activity that expanded access to a recombinant BCG approach under specific program conditions, signaling a more direct response to shortage-driven demand.
A Japanese manufacturer adds another dimension to the competitive picture through its intravesical offering built on a distinct strain with specific potency characteristics. This supplier's product has been associated with recent supply arrangements intended to broaden availability in key markets, including an exclusive development and supply framework for U.S. activity. These moves illustrate how strain differentiation, dosing conventions, and regional authorization strategies all feed into a competitive environment where supply assurance can be as strategically important as the product itself. Our report unpacks these positioning choices and evaluates how they interact with procurement realities across hospital and clinic settings.
Segmentation Logic and Revenue Concentration Patterns
Our segmentation framework is designed to help executives understand where revenue is generated, which product formats dominate commercial activity, and how procurement is distributed across clinical care environments. The study examines product-type dynamics across the principal vial presentations that define commercial supply, with particular attention to how volume concentration differs across dosage forms. The analysis also maps application-level demand patterns, distinguishing between the largest care setting that anchors bulk utilization and the secondary setting that contributes a smaller but strategically meaningful share of total demand.
In addition, the research evaluates regional revenue distribution to identify where commercial activity is most concentrated and where growth potential is emerging. Rather than presenting percentages in isolation, our analysis situates regional data within the broader context of procurement habits, guideline adoption, and supply accessibility, enabling readers to interpret geographic patterns in a way that directly informs market-entry discussions, partnership evaluation, and inventory planning. The report further addresses market concentration metrics to clarify how revenue is distributed among leading participants, providing a realistic picture of the degree to which the market remains consolidated and where competitive pressure may intensify.
Report Contents and Operational Utility for Decision-Makers
This study is structured to support practical decision-making rather than abstract market observation. Readers will find a detailed examination of the demand drivers that shape utilization, the supply-side factors that influence availability, and the regulatory and guideline environment that governs treatment selection. The report includes a comprehensive competitive profiling section that describes each major participant's operational base, product positioning, and strategic response to market constraints. It also provides a forward-looking synthesis of how capacity investments, authorization activity, and supply agreements may alter the balance of availability across the forecast period.
Beyond competitive mapping, the report delivers actionable analytical building blocks for pricing strategy, sourcing diversification, and network planning. Procurement teams can use the segmentation analysis to better understand where demand concentrates and how product formats are distributed across end-use settings. Executive teams can draw on the forecast structure to test scenario assumptions around capacity release, shortage mitigation, and regional expansion. Investors and business development professionals can use the concentration and competitive assessments to evaluate entry feasibility and partnership opportunities without relying on incomplete or anecdotal information.
The study also incorporates discussions of cost considerations and treatment-course economics where relevant to strategic planning, alongside the practical implications of strain potency differences, dosing conventions, and product presentation choices. These details matter because they influence both clinical workflow and procurement behavior, and our report places them in context so that strategic conclusions are grounded in operational reality rather than surface-level market descriptors.
Why This Research Matters for 2026 Strategy
The 2026 to 2032 window represents a period in which the Intravesical BCG market is likely to be shaped as much by supply-side restructuring as by underlying clinical demand. Capacity expansion commitments, authorization pathways, and cross-company supply arrangements are beginning to alter the availability landscape, yet the biological and regulatory complexity of BCG production means that uncertainty will not disappear overnight. In this environment, decision-makers need more than top-line growth figures; they need an integrated view of how product formats, care settings, regional dynamics, and competitive actions combine to create risk and opportunity.
Our report is designed to provide that integrated view. It connects market size progression and forecast expansion to the operational realities behind the numbers, helping organizations anticipate where supply resilience will improve, where dependence on limited sources may persist, and how different procurement strategies may perform under varying shortage and authorization scenarios. For executives planning budgets, sourcing frameworks, or competitive responses in 2026, this research offers the level of detail required to move from reactive positioning to informed strategy.
BCG Vaccine Market
Conclusion and Next Steps
The Intravesical BCG market is at a point where clinical importance, manufacturing complexity, and evolving supply arrangements converge to create both challenge and opportunity. Our study translates that convergence into a structured, forward-looking analysis that supports strategic planning across commercial, operational, and investment decisions. The full report provides the complete segmentation detail, competitive assessment, and forecast architecture needed to evaluate market potential with confidence. Readers interested in the full set of regional breakdowns, application-level revenue patterns, product-type splits, and concentration metrics are encouraged to access the complete study for the comprehensive intelligence required to guide 2026 decision-making.
Intravesical Bacillus Calmette Market
For detailed analysis of this topic, please visit the official page: Intravesical Bacillus Calmette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Auto Hand Dryer Market to Reach $372.52M by 2032, Growing at 8.2% CAGR
By PW Consulting, 2026-09-16
The Automatic Hand Dryers Market: Strategic Intelligence for 2026 and Beyond
Executive Summary: Why Timing Matters
The automatic hand dryer industry stands at a critical inflection point. As commercial facilities, healthcare networks, and hospitality operators recalibrate their capital expenditure priorities for 2026 and beyond, the choice of hygiene infrastructure has evolved from a routine procurement decision to a strategic lever with implications for sustainability targets, regulatory compliance, and occupant experience. Our latest comprehensive research on the Automatic Hand Dryers Market is designed specifically to equip executives, procurement leaders, and industry analysts with the granular intelligence required to navigate this shifting terrain.
The market registered an estimated valuation of USD 215.0 Million in the 2025 base year, reflecting sustained momentum from the post-pandemic acceleration in facility modernization. Looking forward, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 8.2% , culminating in a market valuation of approximately USD 372.52 Million by the end of the horizon. These figures are not merely retrospective acknowledgments of growth; they represent a structural recalibration of how commercial environments approach hygiene, energy consumption, and operational efficiency. For organizations making procurement bets in 2026, this report provides the evidentiary framework necessary to align tactical purchasing with long-term strategic positioning.
Market Trajectory: Mapping the Growth Arc from 2020 to 2032
Over the historical window from 2020 through 2025, the automatic hand dryer sector demonstrated resilience that outpaced many adjacent facility management categories. Revenue expanded from USD 163.15 Million in 2020 to the aforementioned 2025 baseline, navigating supply chain friction, shifting public awareness of surface-contact transmission, and evolving building code expectations. The progression from year to year reveals a market that has matured beyond its initial pandemic-driven surge into a phase of sustained, utility-driven adoption.
The forward-looking trajectory through 2032 indicates continued expansion, with year-by-year forecasts suggesting incremental gains that compound meaningfully over the forecast horizon. The 2026 opening estimate of approximately USD 225.93 Million sets a foundation for steady growth through subsequent years, reaching the terminal valuation previously noted. This growth arc is underpinned by several structural forces: the replacement cycle of legacy drying equipment, municipal and corporate sustainability mandates that favor high-efficiency electro-mechanical solutions over single-use paper alternatives, and heightened institutional focus on touchless interaction in high-traffic environments. Decision-makers evaluating capital plans for the 2026-2032 window will find our time-series analysis and scenario modeling particularly valuable for aligning budget cycles with anticipated demand shifts.
Segmentation Dynamics: Navigating Category and Application Divergence
Our research dissects the market across multiple segmentation axes that matter most to product planners and commercial sales teams. At the product-category level, the Jet Air segment commands a distinctly larger share of total revenue compared to Hot Air units and Others categories, reflecting the industry's pivot toward high-velocity, low-cycle-time drying experiences that reduce queue congestion in busy facilities. Hot air variants continue to serve specific retrofit and cost-sensitive applications, while specialized equipment segments maintain relevance in niche institutional contexts.
Application-wise, the Hospitality sector emerges as the most significant demand driver, a finding that aligns with the segment's dual imperatives of guest experience enhancement and operational cost containment. Healthcare facilities represent a strategically important, regulation-intensive application environment where hygiene certification, rapid drying performance, and infection-control protocols converge to shape procurement decisions. The Others application cohort—encompassing educational institutions, corporate offices, and municipal buildings—contributes meaningful volume and serves as a bellwether for broader commercial adoption trends.
Geography further stratifies demand patterns. North America and Asia Pacific collectively anchor the largest revenue pools, while Europe , Latin America , and the Middle East and Africa regions each present distinct regulatory, climate, and procurement dynamics. Our report does not simply partition the market into static regional silos; it contextualizes regional behavior within the frameworks of local building codes, labor cost structures, energy pricing, and institutional procurement cycles. Readers seeking regional-specific procurement insights will find the detailed territorial breakdowns essential for tailoring market entry and expansion strategies.
Regulatory and Operational Dynamics: Compliance as Competitive Moats
The commercial hand dryer landscape is governed by a dense matrix of standards and protocols that directly influence product design, testing, certification, and go-to-market strategy. In the United States, ADA Accessibility Standards require that all commercial automatic hand dryers comply with accessibility and safety requirements, ensuring that deployed units accommodate a broad spectrum of user needs without creating barriers. Simultaneously, the UL 499 Standard for Safety – Electric Heating Appliances governs the construction and operational parameters of heating-element-based devices, establishing baseline electrical and fire-safety expectations that manufacturers must satisfy.
Automatic Hand Dryers Market
International considerations add further complexity. The NSF International Protocol P335 for Hygienic Commercial Hand Dryers is increasingly referenced in safety and hygiene certification frameworks, reflecting the sector's heightened scrutiny around microbial exposure and aerosolization dynamics. In European markets, Directive 2011/65/EU (RoHS 2) restricts the use of specified hazardous substances in electrical and electronic equipment, including hand dryers, compelling manufacturers to adapt material selections, component sourcing, and manufacturing processes accordingly.
These regulatory threads are not peripheral compliance checkboxes. They shape bill of materials decisions, influence total cost of ownership calculations, and determine which products can realistically compete in regulated procurement tenders. Our report maps the regulatory environment with precision, identifying which standards carry the greatest weight in specific application and regional contexts so that product strategists can anticipate certification pathways and commercial barriers before committing R&D or manufacturing resources.
Competitive Landscape: Differentiated Portfolios and Convergent Priorities
The automatic hand dryer market exhibits moderate concentration, with the top three firms collectively representing approximately 24.6% of total market share and the top five firms accounting for roughly 26.2% . This competitive structure indicates a field in which several established players maintain defensible niches while broader adoption creates room for challengers with differentiated value propositions. The profiles of leading participants illustrate how product engineering, compliance positioning, and production capacity decisions collectively define competitive advantage.
Excel Dryer Inc. , headquartered in East Longmeadow, Massachusetts, has continued to invest aggressively in capacity. The company's July 2025 expansion of its manufacturing facility in Massachusetts was explicitly aimed at increasing production capacity for automatic hand dryers, a move that signals both demand confidence and the strategic importance of supply responsiveness. Excel's portfolio centers on the XLERATOR high-speed automatic sensor-activated jet hand dryer, distinguished by HEPA filtration integration, ADA compliance, and eco-variants such as the XLERATOReco . These features reflect a coherent strategy that pairs performance credentials with sustainability and accessibility positioning.
World Dryer Corporation , based in West Bend, Wisconsin, competes with the SMARTdri Plus series, an automatic high-speed hand dryer lineup emphasizing low energy use and optional HEPA filtration. The emphasis on energy efficiency resonates strongly with facility operators managing long-term operating costs and sustainability reporting requirements.
American Dryer, Inc. , operating from Bensenville, Illinois, offers touchless high-speed automatic hand dryers including the Extreme Air and a Global value series tailored for commercial and institutional applications. This dual-track approach addresses both premium performance segments and cost-conscious procurement environments, broadening the addressable market across institution types.
Danish Design A/S , located in Denmark, brings a distinct aesthetic and hygiene-driven identity through its automatic touchless LOKI and BJØRK series. The brand's Danish design heritage is paired with hygiene features that appeal to markets where appearance, ergonomics, and cleanliness narrative converge in procurement criteria.
American Specialties, Inc. , based in the United States, fields the TURBO ADA and Roval series automatic high-speed hand dryers offered in stainless steel and matte black finishes. The emphasis on ADA-compliant touchless designs and finish options positions the company for hospitality and commercial environments where design integration and accessibility both matter.
Beyond these core firms, broader industry activity underscores the directional priorities of the sector. In 2026, the electric Handdryer Initiative highlighted the industry's trajectory during its week at InterClean 2026 in Amsterdam , emphasizing growing demand for touchless and green high-speed hand drying solutions. The initiative's May 2026 activities for World Hand Hygiene Day further reinforced advocacy for high-speed HEPA-filtered automatic hand drying technology. Meanwhile, Dyson Ltd. 's August 2025 launch of a latest hand dryer model featuring advanced HEPA filtration technology illustrated how premium engineering outfits continue to push hygiene and performance benchmarks, exerting downstream pressure on the entire category. Collectively, these developments demonstrate that the competitive field rewards firms that simultaneously deliver touchless operability, energy efficiency, filtration credibility, and installation elegance.
Hair Dryer Market
What Our Research Delivers: A Practical Toolkit for 2026 Decisions
The Automatic Hand Dryers Market research report is structured to translate macro-level intelligence into actionable decision support. Readers will find a rigorous quantitative foundation paired with qualitative analysis that connects data to commercial reality. The report's architecture is designed around several pillars.
- Historical Reconstruction and Forward Modeling: A detailed time-series analysis covering 2020-2025 provides the empirical backbone for understanding how the market behaved through distinct cycles. The 2026-2032 forecast framework extends this foundation with scenario-based projections that account for demand elasticity, replacement cycles, and adoption pacing across application types.
- Segmentation Detail at Category, Application, and Regional Levels: Our segmentation analysis goes beyond aggregate splits to reveal how product categories perform across different end-use environments and geographies. This enables readers to assess where growth concentrates, which segments exhibit resilience during economic variability, and how regional procurement cultures shape product preferences.
- Competitive Intelligence on Major Players: The report profiles leading manufacturers, examines their product strategies, evaluates recent corporate and facility developments, and contextualizes competitive positioning within the moderation of overall market concentration. This section supports benchmarking, partnership evaluation, and competitive response planning.
- Regulatory Mapping and Compliance Roadmaps: A dedicated treatment of relevant standards—including ADA accessibility, UL 499, NSF Protocol P335, and EU RoHS 2—helps product teams, procurement officers, and legal/compliance stakeholders anticipate certification requirements and identify potential barriers to market entry or expansion.
- Demand Drivers, Restraints, and Industry Event Context: The report synthesizes macro drivers such as hygiene awareness, sustainability mandates, and touchless interaction trends alongside constraints including cost sensitivity, installation complexity, and regulatory fragmentation. Recent industry events and association activities from 2025 and 2026 are integrated to ground analysis in current market sentiment and directional signals.
- Executive Decision Frameworks: Beyond raw data, the report provides interpretive guidance on how to prioritize investments, time procurement cycles, evaluate supplier alternatives, and align product selection with corporate sustainability and hygiene objectives for the 2026-2032 horizon.
Conclusion: Turning Market Intelligence into Strategic Advantage
The automatic hand dryer market is no longer a commoditized fixture category. It has become a strategically significant segment where hygiene performance, energy efficiency, regulatory adherence, and design sensibility converge to influence procurement outcomes and long-term operational economics. The 8.2% CAGR projected over the 2026-2032 period, anchored by a market that has grown from 163.15 million USD in 2020 to an estimated 372.52 million USD by 2032, reflects an environment in which informed decision-making can materially affect competitive positioning and total cost of ownership.
For executives, procurement leaders, and product strategists preparing for 2026 and the subsequent years, the detailed intelligence within our full report is purpose-built to reduce uncertainty and sharpen execution. Regional breakdowns, granular segmentation figures, company-level strategic profiles, regulatory pathway analyses, and forward scenario modeling are available in the complete publication. We invite you to access the full report to obtain the precise data and interpretive frameworks required to make confident, evidence-based decisions for the automatic hand dryer market in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Automatic Hand Dryers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Legal Practice Management Software Market Hits $2.68B in 2025, 11.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for Legal Decision-Makers: Navigating the Practice Management Software Market in 2026
The legal technology landscape has reached an inflection point. What was once a fragmented market of niche tools has matured into a consolidated ecosystem where operational efficiency, AI integration, and regulatory compliance converge. For enterprise buyers, law firm managing partners, and institutional investors, understanding the trajectory of legal practice management software is no longer optional. It is a core component of operational strategy.
PW Consulting is pleased to introduce our latest market intelligence study, a comprehensive analysis designed to equip leadership teams with the actionable insights required to navigate the 2026 landscape and beyond. This report does not merely recount historical trends. It constructs a forward-looking framework that aligns technology procurement, competitive positioning, and capital allocation with the structural shifts reshaping legal service delivery.
Market Trajectory and the Case for Strategic Foresight
The legal practice management software sector has demonstrated consistent, above-average growth across the historical analysis window. Revenue expansion has outpaced many adjacent enterprise software categories, driven by a compounding set of operational pressures: rising labor costs, stringent client expectations around transparency, and the accelerating digitization of court and compliance workflows. The market has moved decisively from early-adopter experimentation to mainstream operational dependency.
This maturation is not accidental. It reflects a structural recalibration within legal operations. Firms of all sizes are confronting margin compression and talent scarcity, forcing a shift from manual, paper-heavy processes toward integrated platforms that centralize matter management, financial operations, and client engagement. Cloud-based architectures have become the default deployment model, supported by an increasingly robust security and compliance infrastructure that addresses the sector's unique trust accounting and data privacy requirements.
The forecast horizon captured in our analysis points to continued robust expansion through the end of the decade. However, aggregate growth rates only tell part of the story. The true strategic value of this research lies in its ability to segment that growth into actionable intelligence: where adoption is concentrating, which deployment models are winning, how revenue is shifting across user categories, and what competitive dynamics will determine market leadership over the next several years. These are the questions that separate reactive procurement from proactive strategy.
Inside the Analysis: What the Report Delivers
Our research methodology combines quantitative modeling with on-the-ground industry validation. The resulting publication is structured to serve multiple executive functions simultaneously: situational awareness, vendor evaluation, investment scenario planning, and operational roadmap development.
Readers will find detailed examinations across the dimensions that matter most to decision-makers:
- Market sizing and trajectory modeling spanning historical performance and a forward-looking forecast window, enabling scenario-based planning rather than single-point estimates.
- Deployment architecture analysis comparing cloud-native and on-premises environments, with emphasis on security postures, integration pathways, and total cost of ownership implications.
- Application-level segmentation distinguishing demand patterns across law firms and attorneys, court systems, and other institutional users, revealing where procurement momentum is strongest.
- Regional landscape mapping that contextualizes adoption maturity, regulatory environments, and purchasing dynamics across key geographic markets.
- Competitive benchmarking of leading platform providers, evaluating product roadmaps, AI integration depth, pricing architectures, and ecosystem partnerships.
- Operational dynamics assessment covering labor cost pressures, compliance frameworks, reimbursement cycle acceleration, and the evolving ethical boundaries around AI-driven case analysis and document review.
Each section is designed to produce a clear decision artifact. Rather than leaving readers with abstract market commentary, the report translates data into procurement criteria, vendor shortlisting guidance, and implementation sequencing recommendations.
The AI Inflection and Competitive Reconfiguration
No variable has reshaped this market more rapidly than artificial intelligence. Over the past year, AI usage among legal professionals has expanded meaningfully, with practice management platforms absorbing automation capabilities that were previously isolated in point solutions. Document generation, time capture, matter triage, and financial reconciliation are increasingly handled through embedded intelligence rather than manual workflow. This shift is altering vendor value propositions across the board.
The competitive landscape reflects this transformation. Market concentration remains moderate, with leading firms commanding a combined share that underscores both established presence and ongoing consolidation potential. The roster of influential players spans full-suite cloud platforms, specialized matter management systems, and AI-forward tools targeting specific practice verticals.
Analysis of the current vendor ecosystem reveals several distinct strategic postures. Cloud-native leaders such as Clio and MyCase continue to expand their functional breadth, embedding client intake, billing, trust accounting, and compliance tooling within unified workflows. Clio's strategic moves illustrate the scale-up dynamic: the acquisition of vLex in mid-2025 represents the largest legal tech M&A transaction in recent memory, merging AI-powered global legal research directly into practice management infrastructure. Shortly thereafter, the launch of a large-firm platform signaled a deliberate push into more complex case and process management environments.
Medical Practice Management Software Market
Other providers are executing differentiated plays. Rocket Matter and Filevine have emphasized reimagined platforms with stronger analytics and AI-powered case handling, while Smokeball and PracticePanther have doubled down on automated time capture, document automation, and trust accounting for firms seeking operational simplification. Centerbase's partnership to embed accounts payable automation directly into its midsize firm platform highlights a parallel trend: integration with back-office financial ecosystems as a competitive differentiator. Supio's specialization in personal injury and mass tort workflows demonstrates how vertical-specific AI can command premium positioning. Lexzur and Caseflow extend the field with AI-assisted matter management and client communication features, while LeanLaw's focus on QuickBooks-integrated revenue operations points to a growing appetite for financial tooling built around familiar accounting backbones.
These vendor movements matter because they redefine buyer expectations. A practice management decision in 2026 is simultaneously a decision about AI strategy, data residency, financial reconciliation speed, and vendor longevity. The report's competitive analysis maps these trade-offs explicitly, helping organizations match platform capabilities against their operating model rather than adopting a one-size-fits-all framing.
Industry Dynamics Driving Procurement and Adoption
Market growth is not simply a function of technology availability. It is being propelled by a set of interlocking operational and regulatory forces that raise the cost of inaction. Our research distills these dynamics into practical considerations for both buyers and vendors.
Cloud adoption has become the baseline expectation. Recent industry survey data indicates that a substantial majority of law firms now rely on cloud-based legal tools, with practice management and document management software posting the highest utilization rates. This shift is not cosmetic. It reflects reduced on-premises maintenance burdens, improved remote collaboration, and the ability to push updates and security patches without disrupting firm operations. For decision-makers, the question has moved from whether to adopt cloud architecture to how to select platforms that meet rigorous compliance and performance standards.
Security and regulatory compliance have accordingly become central procurement criteria. Cloud-based platforms increasingly emphasize SOC 2 alignment and data privacy standards to support trust accounting integrity and client data protection. These requirements are not uniform across jurisdictions, and the report examines how compliance posture varies by platform and what that means for multi-jurisdiction firms.
Financial workflow acceleration is another powerful driver. Automated billing, trust accounting, and integrated payment capabilities are shortening client payment cycles and reducing administrative overhead. For firms operating on tight margins, faster cash conversion is a direct operational benefit, not merely a feature checkbox. The analysis quantifies how these capabilities influence vendor selection and what performance indicators buyers should track post-implementation.
At the same time, AI integration introduces a new compliance layer. As automation expands into case analysis and document review, firms must navigate evolving professional ethics guidance on the use of AI in legal work. Regulatory bodies are actively updating expectations around supervision, accuracy, and client confidentiality. The report evaluates how leading platforms are addressing these requirements and what risk management frameworks should accompany AI adoption.
Legal Practice Management Software Market
Why This Research Matters for 2026 Decision-Making
The strategic stakes for 2026 are unusually high. Organizations that treat practice management software as a routine IT purchase risk underinvesting in capabilities that directly affect profitability, risk exposure, and client retention. Conversely, organizations that approach the market with structured intelligence can sequence implementations, negotiate from a position of clarity, and avoid vendor lock-in to platforms that lack the roadmap depth required for future growth.
This report is built for that decision environment. It provides the macro context needed to validate market timing, the segmentation detail needed to prioritize investment, and the competitive analysis needed to assess vendor durability. For law firm leadership, it supports operational transformation planning and resource allocation. For technology buyers and institutional stakeholders, it clarifies where durable demand is forming and which platform categories are likely to consolidate further.
Because the full value of this analysis depends on the underlying segmentation models, regional breakdowns, deployment comparisons, and company-level benchmarking, the complete dataset and executive findings are available through our comprehensive market study. The page-length overview presented here is intended as a strategic preview: a demonstration of the analytical rigor and decision-focus that define the full publication.
Next Steps for Strategic Alignment
Market leadership in legal technology is being redefined in real time. Firms that align their practice management strategy with the realities of AI adoption, compliance evolution, and financial workflow acceleration will be best positioned to convert operational software into durable competitive advantage. Those that delay structured evaluation risk entering a more consolidated market with fewer negotiating advantages and higher switching costs.
The complete market research extends well beyond this overview. It delivers the segmented data, vendor assessments, and forward-looking projections required to support confident 2026 decision-making across procurement, investment, and operational transformation initiatives. Readers seeking the full intelligence package, including detailed segmentation splits and competitive benchmarking, are encouraged to access the complete report at the source page, where the full dataset and executive insights are available for direct review.
For detailed analysis of this topic, please visit the official page: Legal Practice Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Ultrasound Probe Market Hits $215M in 2025, Projected 3.3% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Pulse: Strategic Intelligence for the 2026 Medical Ultrasound Probe Market
The medical ultrasound probe market stands at a critical inflection point as healthcare delivery models shift toward point-of-care diagnostics and advanced imaging integration. For executives and strategy teams planning capital allocation and product roadmaps through 2032, understanding the nuanced trajectory of this sector is not merely analytical—it is imperative. This article introduces PW Consulting's latest comprehensive market research, designed to equip decision-makers with the foresight required to navigate regulatory shifts, competitive realignments, and evolving clinical demands. The following insights distill the executive summary of our full report, highlighting the strategic value embedded within our analysis while preserving the granular data necessary for precise execution available exclusively in the complete document.
Macroeconomic Trajectory and Market Size Evolution
Our analysis covers a robust historical period from 2020 through 2025, extending a forecast horizon to 2032. This longitudinal view allows for the identification of structural trends rather than transient fluctuations. The market has demonstrated consistent growth over the past half-decade, with revenue figures reflecting a steady expansion in diagnostic imaging adoption globally. In 2020, the market valuation stood at approximately 163.15 Million USD. Year-over-year progression saw increases to 167.51 Million USD in 2021, 175.83 Million USD in 2022, and a notable acceleration to 183.64 Million USD in 2023. The recent past indicates a significant jump to 205.21 Million USD in 2024, culminating in an estimated base year valuation of 215.0 Million USD for 2025.
Looking forward, the forecast period projects the market to reach 222.9 Million USD in 2026. The trajectory suggests continued growth, with valuations anticipated to climb toward 236.95 Million USD by 2027. However, strategic planners must note specific variance points within the forecast window. While growth is the overarching theme, the data indicates a slight contraction to 235.1 Million USD in 2028 before resuming an upward trend toward 252.9 Million USD in 2029. Subsequent years show fluctuation, with dips to 247.5 Million USD in 2030, followed by recovery to 266.77 Million USD in 2031 and a projected stabilization near 268.83 Million USD by 2032. The Compound Annual Growth Rate (CAGR) calculated over this forecast period is 3.3 percent. This moderate yet steady growth rate underscores a mature market environment where competitive advantage is derived from segmentation precision and operational efficiency rather than pure volumetric expansion.
Structural Segmentation Overview
To truly leverage market opportunities, one must understand the underlying architecture of demand and supply. Our research dissects the market across three primary dimensions: Region, Type, and Application. Each dimension reveals distinct behavioral patterns and strategic entry points for stakeholders.
Geographically, the market exhibits significant dispersion. While North American markets have historically commanded strong positions, our data highlights the substantial weight of the Asia Pacific region, followed closely by North America and Europe. Latin America and the Middle East and Africa represent emerging vectors with unique adoption curves. The concentration of revenue across these regions suggests that supply chain resilience and localized regulatory compliance are becoming key differentiators.
In terms of product Type, the landscape is diversified. Convex probes remain a dominant segment, reflecting their broad utility in abdominal and obstetric imaging. Linear probes constitute a significant portion of the revenue mix, driven by vascular and musculoskeletal applications. Specialized categories such as Phased Array and Endocavitary probes serve niche but critical clinical needs, while Other types capture emerging technologies. The distribution across these types indicates that innovation is not solely focused on volume drivers but also on high-value specialized transducers.
Regarding Clinical Application, the demand is heavily influenced by standard diagnostic protocols. OB-GYN applications represent a substantial share, consistent with the global emphasis on maternal health and routine screening. Vascular and Nervous System applications follow as a major demand driver, supported by the rising prevalence of cardiovascular conditions. Renal, Digestive, and Musculoskeletal applications round out the core demand pillars, with Other applications encompassing emerging use cases in emergency medicine and primary care. Understanding the revenue contribution of each application helps manufacturers prioritize R&D and marketing resources effectively.
Competitive Landscape and Strategic Positioning
The market is characterized by a fragmented yet competitive environment. The top three companies hold a combined market concentration of 24.6 percent, while the top five extend this to 26.2 percent. This relatively low concentration ratio implies that no single entity dominates the entire value chain, leaving ample room for specialized players and regional champions to compete on technology, service, and cost.
Our report provides detailed profiles and strategic assessments of key industry participants. Global giants such as GE HealthCare, headquartered in Chicago, Illinois, continue to lead with proprietary diagnostic systems and transducer compatibility, notably within their Voluson Expert series. Koninklijke Philips N.V., based in Amsterdam, maintains a strong presence through its EPIQ and Affiniti series, offering broad diagnostic compatibility. Siemens Healthineers AG, operating from Erlangen, Germany, manufactures MyLab systems and associated probes that serve diverse clinical imaging needs.
Recent Regulatory Milestones and Industry Noise
The regulatory environment remains a pivotal factor in product deployment and market access. Recent months have seen significant activity regarding FDA 510(k) clearances, which directly impact the availability and cycle times for new probe technologies. In January 2025, GE HealthCare announced FDA clearance for enhanced Voluson Expert Series ultrasound systems, including lightweight probes, signaling a push toward ergonomics and portability. Further clearances followed in July 2025 for the Venue Go, Venue Fit, Venue Sprint, and Venue systems, and again in November 2025 for the Voluson Expert 18, 20, and 22 systems under specific K-numbers. Philips also secured FDA clearance in June 2025 for its EPIQ and Affiniti Series diagnostic systems.
Beyond approvals, the industry must also navigate recall dynamics. Recent database entries indicate Class III recalls for multiple Philips ultrasound transducers in early 2026. Such events highlight the importance of quality assurance and risk management in strategic planning. Additionally, service ecosystems are evolving; for instance, in January 2026, Probo Medical secured the inclusion of ultrasound probe repair services on the Federal Supply Schedule via Maclean Group LLC, indicating a growing demand for lifecycle management and repair solutions alongside new equipment sales.
Unlocking Decision-Ready Intelligence
While this overview establishes the strategic context, the full PW Consulting report delivers the depth required for actionable execution. The complete study moves beyond high-level trends to provide specific revenue splits, growth rates by segment, and detailed competitor benchmarking that are essential for tactical planning. By accessing the full intelligence, stakeholders can dissect exactly how regional shifts will impact their supply chains, which probe types offer the highest margin potential in specific clinical settings, and how the competitive moves of entities like FUJIFILM Sonosite, Canon Medical, Samsung Medison, Hitachi Healthcare, Esaote, Mindray, SIUI, and emerging players like Shenzhen Ruqi Technology will reshape the battlefield.
Worldwide Ultrasonic Probe Covers Market
The report integrates real-world data to map out the competitive intensity, identifying where consolidation might occur and where niche players can secure defensible positions. It also analyzes the implications of regulatory clearances on market entry barriers and the strategic value of service contracts in an era of increasing hardware complexity. With the market projected to nearly double from its 2020 levels by the end of the forecast period, the cost of inaction or misinformed strategy is significant.
Medical Ultrasound Probe Market
Call to Action for Strategic Leaders
As we move through 2026, the ability to anticipate market fluctuations—such as the variance projected between 2027 and 2030—will separate market leaders from followers. The data suggests that while the overall CAGR is 3.3 percent, specific segments and regions may outperform or underperform this average based on regulatory adoption and clinical guideline updates. PW Consulting's detailed analysis provides the granular visibility needed to capitalize on these discrepancies.
We invite industry executives, investors, and product strategists to explore the full findings of our Medical Ultrasound Probe Market report. The comprehensive document includes detailed segmentation tables, competitor SWOT analyses, and forward-looking scenarios that go beyond the summary provided here. To gain the competitive edge required for 2026 and beyond, access the complete intelligence package available on the PW Consulting website. Let us guide your strategy with data precision and industry expertise.
For detailed analysis of this topic, please visit the official page: Medical Ultrasound Probe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects 9.5% CAGR for High Speed Oven Market to Hit $7.88B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the High Speed Oven Market: Navigating the 2026–2032 Growth Cycle
The commercial foodservice sector is undergoing a profound operational transformation, driven by acute labor constraints, rising real estate costs, and an unprecedented demand for rapid ticket-to-order fulfillment. In this volatile environment, the high speed oven market has emerged as a critical enabler of kitchen efficiency, bridging the gap between traditional cooking methodologies and the aggressive throughput requirements of modern quick-service and fast-casual operations. As we analyze the trajectory of this sector through 2032, our latest market research provides a comprehensive strategic blueprint for manufacturers, investors, and foodservice operators aiming to capitalize on a projected industry expansion. This article outlines the macro-economic foundations of the sector, highlights the competitive dynamics shaping vendor strategies, and details the actionable intelligence embedded within our full report.
The Macro Trajectory: A High-Growth Window Across 2026–2032
Market data spanning the evaluation period paints a clear picture of sustained acceleration. Following a robust historical baseline, the industry has entered a steep growth phase, with the overall market value reaching $4,370.0 million in 2025 before projected to chart $4,686.06 million in 2026. Our forecast models indicate that this momentum will compound consistently, pushing revenue toward $7,880.0 million by 2032. This represents a compound annual growth rate of 9.5 percent, a figure that significantly outpaces broader commercial kitchen equipment benchmarks and underscores a structural shift in how operators are designing their culinary workflows.
The valuation trajectory does not merely reflect cyclical demand; it signals a permanent reorientation of commercial cooking infrastructure. As high-throughput concepts proliferate and legacy kitchen footprints contract, speed cooking appliances are transitioning from supplementary tools to central production assets. Organizations that align their capital expenditure strategies with this growth pattern stand to secure meaningful first-mover advantages in supply chain positioning, channel partnerships, and menu innovation capabilities.
Market Structure and Demand Drivers Shifting the Landscape
Segmentation Dynamics and End-Use Priorities
The current market architecture reveals a balanced but rapidly evolving distribution of demand across equipment configurations and deployment environments. Operators are increasingly evaluating built-in installation formats against standalone countertop solutions, with the strategic choice heavily dependent on modular kitchen design, ventilation constraints, and throughput targets. Simultaneously, end-use applications are bifurcating between high-volume restaurant environments and a diverse array of other commercial deployments, including corporate cafeterias, educational dining facilities, retail food halls, and airport concessions. This diversification is critical, as it insulates the market from overreliance on a single dining segment and broadens the addressable customer base for manufacturers and distributors.
Geographic Expansion and Infrastructure Maturation
Regional adoption patterns are stabilizing around established commercial foodservice hubs while demonstrating clear upward pressure in emerging markets. North American and European territories continue to anchor substantial share, anchored by mature restaurant supply chains, stringent health and safety compliance frameworks, and widespread adoption of ventless and impingement cooking technologies. Meanwhile, Asia Pacific and Latin American markets are exhibiting accelerating deployment rates as quick-service brands expand internationally and local operators prioritize operational efficiency to offset rising commodity and labor costs. Middle Eastern and African regions, though smaller in absolute valuation, are carving out niche growth corridors driven by hospitality infrastructure projects and tourism-centric foodservice concepts.
Regulatory Compliance and Operational Cost Pressures
The commercial deployment of high speed ovens is strictly governed by a multi-layered certification ecosystem. Equipment destined for U.S. and Canadian commercial kitchens must satisfy UL and NSF safety and sanitation standards, while ETL certification remains mandatory for market entry across North America. Ventless configurations introduce an additional compliance layer, requiring catalytic converter certification to meet stringent emissions thresholds. Furthermore, energy efficiency frameworks, including Energy STAR and related efficiency certifications, are increasingly influencing procurement decisions, particularly for models that integrate convection, microwave, and broil capabilities in a single footprint.
Worldwide Build-in High Speed Oven Market
Beyond regulatory overhead, labor economics are the most potent demand catalyst in the current cycle. High speed ovens routinely deliver cook times up to 80 percent faster than conventional equipment, directly compressing staffing requirements and reducing dependency on highly specialized culinary labor. In an environment where wage inflation and recruitment volatility remain unresolved, this labor efficiency premium is no longer a convenience feature—it is a financial imperative that dictates capital allocation and menu engineering strategies.
High Speed Oven Market
Competitive Arena: Strategic Moves and Product Evolution
Market concentration remains firmly consolidated, with the top three participants commanding a combined 62 percent share and the top five firms extending that footprint to 65 percent. This structure rewards scale, technical differentiation, and robust service networks, while simultaneously raising the barrier for new entrants attempting to disrupt established channel relationships.
Several active manufacturers are currently defining the competitive tempo through targeted product evolution and strategic positioning. Prática Klimaquip, operating out of Minas Gerais, Brazil, has solidified its footprint in commercial rapid-cook applications with stackable configurations such as the FIT XL and Rocket Express, specifically engineered for pizza, wing, and quick-service workflows. The Middleby Corporation, leveraging its TurboChef Technologies subsidiary based in Elgin, Illinois, continues to deploy impingement-based rapid-cook architecture optimized for high-volume foodservice throughput. Hatco Corporation, through its Ovention Ovens brand in Milwaukee, Wisconsin, maintains a strong emphasis on 100 percent ventless impingement systems that integrate seamlessly into constrained kitchen footprints without extensive exhaust infrastructure.
Merrychef Ltd., headquartered in Elkhart, Indiana, remains a pioneer in high-speed oven technology, with its eikon and conneX series reflecting a consistent focus on streamlined kitchen operations and connectivity-driven workflow management. Panasonic Corporation, from its Osaka base, extends its commercial reach through convection-microwave-broil hybrids such as the NE-SCV3 series, targeting restaurants and cafes that require multi-functionality within a single appliance footprint. UNOX S.p.A. contributes a distinct European engineering perspective from Italy, offering commercial speed ovens such as the SPEED.Pro line that merge convection, steam, and microwave capabilities for versatile culinary outputs. Sharp Corporation has also entered the acceleration curve with its Celerity high speed oven, showcasing advanced thermal engineering capable of reducing whole-chicken cook times to roughly one-third of conventional methods. Additionally, Buffalo Equipment has expanded its proprietary portfolio by unveiling two new high-speed models, reinforcing the trend of domestic and regional manufacturers investing heavily in rapid-cook technology differentiation.
2026–2027 Product Cycle: Real-Time Market Signals
The competitive landscape is being actively reshaped by a concentrated wave of product launches, catalog updates, and application-focused messaging during mid-2026. Ovention Ovens recently refreshed its product catalog with detailed guidance on integrating high-speed ovens into modular kitchen designs and optimizing team workflow allocation. TurboChef simultaneously promoted its Bullet Oven for campus dining environments and high-volume service settings, emphasizing throughput efficiency and space-conscious deployment. Merrychef announced an expansion of its conneX high-speed oven range, positioning the new line as a solution for consolidated kitchen operations and reduced equipment sprawl. Buffalo Equipment followed with the unveiling of two new models within its branded cooking range, signaling continued investment in rapid-cook capacity across retail and foodservice channels. These concurrent developments reflect a broader industry pivot toward operational modularity, deployment flexibility, and menu-agnostic performance.
Inside the Report: Operational Intelligence and Decision Frameworks
Our full market research publication extends well beyond macro-valuation summaries to deliver a tactical decision-support architecture. The report systematically deconstructs market sizing across historical baselines and forward-looking forecast periods, enabling precise revenue modeling and capacity planning. It examines structural segmentation splits that illuminate how built-in versus countertop configurations are performing across distinct commercial environments, while also mapping end-use distribution between restaurant-grade deployments and alternative foodservice applications. Geographic coverage is analyzed through a lens of market maturity, infrastructure readiness, and regional adoption velocity, providing a nuanced view of where demand is stabilizing and where it is accelerating.
The competitive intelligence section profiles active market participants, mapping headquarters locations, technological specializations, and recent developmental activity. Recent product launches, catalog revisions, and targeted promotional campaigns are cataloged to reveal how vendors are responding to shifting operator requirements. Beyond hardware and vendor mapping, the report incorporates regulatory and certification pathways, ensuring that compliance planning is integrated directly into procurement and deployment strategies. Labor cost mitigation scenarios are quantified against conventional cooking benchmarks, and energy efficiency considerations are evaluated alongside certification requirements to provide a complete total-cost-of-ownership perspective. This multidimensional framework is designed to support capital planning, channel strategy formulation, competitive positioning, and menu engineering initiatives with minimal reliance on secondary interpretation.
Strategic Imperatives for Stakeholders
For equipment manufacturers and technology developers, the 9.5 percent growth trajectory and concentrated market share structure underscore the necessity of differentiated engineering, robust ventless and hybrid-cooking portfolios, and proactive compliance alignment. For foodservice operators and franchise groups, the immediate priority lies in evaluating kitchen reconfiguration opportunities that leverage 80 percent faster cook times to compress labor dependency, improve ticket throughput, and expand menu flexibility within constrained footprints. For investors and financial analysts, the diversification across end-use environments and regional growth corridors provides a clear framework for assessing exposure, identifying channel expansion opportunities, and monitoring vendor consolidation patterns. The data demonstrates that high speed ovens are transitioning from tactical kitchen tools to strategic infrastructure assets; companies that embed this reality into their planning cycles will be better positioned to navigate the operational and financial demands of the coming half-decade.
Conclusion: Accessing the Complete Strategic Blueprint
The high speed oven market is entering a phase of sustained, structurally driven expansion marked by technological consolidation, regulatory rigor, and intensifying competitive maneuvering. The aggregate market trajectory, segment dispersion patterns, vendor activity cycles, and compliance frameworks documented in our full research publication provide a comprehensive foundation for informed capital allocation, product planning, and operational optimization. While the overview presented here captures the essential strategic contours, the complete report contains granular sizing breakdowns, detailed vendor profiling, segment-level deployment dynamics, regional adoption mappings, and actionable scenario models that are essential for precise decision-making. To access the full intelligence suite and integrate these findings directly into your 2026 planning cycle, please visit the official market research portal and download the complete publication.
For detailed analysis of this topic, please visit the official page: High Speed Oven Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


