



PW Consulting: Metal 3D Printing Hits $1.79B in 2025, Billion-Dollar Surge Forecast to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Decisive Year: Why the 2026 Metal Material Based 3D Printing Market Report Is Essential for Executive Decision-Making
The Momentum Is Real, But the Path Forward Demands Precision
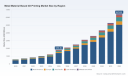
The global landscape for metal material based 3D printing has evolved from experimental prototyping to industrialized production at a pace that has caught many organizational leaders off guard. Over the past half-decade, the market has demonstrated a compounding trajectory that signals a structural shift rather than a temporary cycle. Independent industry tracking indicates that revenue expansion has consistently outpaced earlier projections, with the total market size climbing from approximately $600 million in 2020 to an estimated $1.79 billion in 2025. Looking toward the forecast window spanning 2026 through 2032, the sector is projected to sustain a compound annual growth rate of 20.0 percent, pushing the market toward a multi-billion-dollar valuation by the end of the decade.
Numbers of this magnitude attract attention, yet attention alone does not build competitive advantage. What separates organizations that capture value from those that merely watch it being created is the ability to translate macroeconomic momentum into operational clarity. Enterprise teams need to understand where capital is flowing, which material categories are commanding premium positioning, how regional procurement patterns are shifting, and which certification regimes will determine market access in the coming quarters. This is precisely the analytical gap that our latest market research addresses.
Metal 3D Printer Market
Why 2026 Represents a Binary Year for Strategic Planning
The forecast period opens in a year defined by inflection. Industrial metal additive manufacturing is moving rapidly toward full production rate operations, and the qualification requirements that accompany this transition are reshaping procurement timelines, supplier relationships, and investment priorities. Aerospace and defense organizations are increasingly demanding rigorous material validation, while medical and dental practitioners are navigating new regulatory expectations that directly affect production throughput and component traceability. The convergence of production scaling and standardization is not a theoretical concern; it is a live operational constraint that will determine which manufacturers can fulfill orders, which can maintain yield consistency, and which can secure long-term supply agreements.
At the same time, the supply chain for metal powders and master alloys is undergoing consolidation and vertical integration. Producers are expanding capacity, tightening quality control, and aligning feedstock availability with the specific requirements of laser powder bed fusion and directed energy deposition processes. Organizations that fail to map these supply-side shifts risk encountering bottlenecks precisely when their own production schedules are accelerating. The strategic question for 2026 is not whether metal additive manufacturing will continue to grow, but whether a given enterprise will be positioned upstream, midstream, or downstream of the value capture that this growth generates.
What This Market Research Delivers: Actionable Architecture, Not Static Tables
Our Metal Material Based 3D Printing Market study is built for decision-makers who need to convert industry signals into execution roadmaps. Rather than offering a retrospective summary of past shipments, the report is structured around the operational questions that procurement, engineering, finance, and corporate strategy teams face when allocating resources in a high-growth environment. The analysis spans the historical baseline from 2020 through 2025 and extends forward across the 2026 to 2032 forecast horizon, allowing readers to evaluate both the evidence of what has already occurred and the scenarios that will shape the next several years.
Metal Material Based 3D Printing Market
The report dissects the market through multiple lenses that matter to enterprise planning. Material categories are examined with attention to how different metal systems are being positioned across high-volume production and specialized applications. Application segments are assessed in the context of demand intensity, qualification demands, and the pace at which additive components are moving from prototype approval to serial production. Regional patterns are analyzed to illuminate where demand is concentrating, where supply chain infrastructure is maturing, and where localized production strategies may offer advantages in responsiveness or cost structure. Throughout the analysis, the study tracks how market concentration is evolving among leading participants, offering context for partnership strategy, procurement negotiation, and competitive positioning.
Equally important, the report integrates the regulatory and standards environment that increasingly governs market access. As process validation requirements tighten and certification frameworks such as ISO standards and Nadcap credentials become prerequisites for participation in high-stakes applications, organizations need a clear understanding of the compliance trajectory and its implications for production readiness. The research does not treat regulation as a sidebar; it embeds regulatory dynamics into the competitive analysis so that readers can anticipate where qualification lead times will extend, where supplier consolidation may affect material availability, and where early compliance investment can create durable barriers to entry for less-prepared rivals.
Competitive Intensity and the Emerging Order of the Market
The company landscape reflects both the maturity of established equipment and materials providers and the velocity of recent strategic moves. Participants with headquarters across Europe and North America are competing on multiple fronts: system reliability, build volume scalability, material breadth, software integration, and the ability to support customers through qualification cycles. Manufacturers of laser powder bed fusion platforms continue to expand their materials portfolios and system configurations, while electron beam melting specialists are reinforcing their presence in high-performance alloy segments. Alongside the equipment makers, powder and alloy suppliers are deepening their engagement with end users, often through technical collaboration that ties feedstock development to application-specific performance requirements.
Recent activity among key players underscores how rapidly the competitive environment is shifting. In late 2025, one major system manufacturer introduced an expanded set of metal additive materials optimized for laser powder bed fusion, broadening the material ecosystem available to production users. Around the same period, a separate equipment provider secured a notable order tied to naval applications, reinforcing how defense-driven requirements are pushing manufacturers to develop first-of-their-kind process capabilities in specialized alloys. By early 2026, additional strategic moves included facility investment aimed at improving regional production capacity and delivery speed, as well as the launch of next-generation data preparation software intended to streamline industrial metal additive workflows. These are not isolated announcements; they are indicators of a market in which equipment availability, material access, and software-driven process efficiency are becoming tightly intertwined competitive differentiators.
For enterprise strategists, the practical implication is clear. Sourcing decisions can no longer be evaluated solely on machine price or material cost per kilogram. They must account for the pace at which a supplier can support qualification, the robustness of its materials portfolio against evolving application requirements, the geographic proximity of its production and support infrastructure, and the degree to which its software environment reduces the friction between design intent and finished part. The companies that will prevail in 2026 and beyond are those that treat these dimensions as an integrated value proposition rather than a collection of separate features.
How the Findings Translate into 2026 Decisions
Market research becomes valuable only when it changes behavior. In the context of metal material based 3D printing, the strategic stakes in 2026 fall into several actionable categories:
- Capital allocation for production capability must be aligned with the segments where qualification momentum is strongest and where serial production is already transitioning from pilot scale to repeat manufacturing.
- Procurement strategies need to reflect the consolidation occurring in metal powder and master alloy supply chains, including the trade-offs between single-source dependency and the stability that comes from deeper supplier integration.
- Engineering and quality organizations should map the incoming standards and certification environment against current process validation capabilities, identifying gaps that could delay customer acceptance or restrict participation in high-value programs.
- Partnership and vendor selection should be informed by a realistic assessment of who can support scale-up without sacrificing material consistency, documentation rigor, and process repeatability.
- Geographic expansion or sourcing shifts should be evaluated in light of where demand is intensifying and where local supply chain responsiveness can reduce lead times or mitigate logistical risk.
Our report provides the structural clarity required to make these judgments with greater confidence. It offers the comparative context needed to distinguish transient market noise from durable demand shifts, and it presents the segmentation logic that allows an organization to identify where its own capabilities intersect with the most promising commercial pathways. Readers will gain a sharper sense of which applications are moving fastest toward production normalization, which material families are anchoring value in high-performance sectors, and how the broader competitive field is organizing itself around platform reliability, material qualification, and software-enabled throughput.
What Is Reserved for the Full Report
Depth matters, and disciplined intelligence requires that some of the most decision-relevant figures be delivered in their complete form rather than summarized in a preview. The full market research contains the detailed segmentation values, the precise regional and application-level revenue breakdowns, the material-category projections, and the company-level competitive assessments that executives need for board-level discussion, budget defense, and investment justification. Those specifics are not blunt instruments; they are calibrated to support scenario planning, sensitivity analysis, and cross-functional alignment. Releasing them in isolation would undercut the analytical context that makes them useful.
The complete study also includes the methodology, the historical reconstruction, the forecast assumptions, and the supporting evidence that connect raw market size figures to the operational dynamics shaping customer behavior. It explains how concentration patterns are evolving, how qualification and certification requirements are influencing adoption curves, and how equipment and materials suppliers are positioning themselves relative to one another as the industry moves from expansion to execution.
The Strategic Imperative for 2026
The trajectory of metal material based 3D printing is no longer a matter of speculation. The market has crossed the threshold from early adoption into a phase dominated by production scaling, standardization, and competitive differentiation based on process maturity. With a forecast compound annual growth rate of 20.0 percent over the 2026 to 2032 period and a market size anticipated to expand well beyond the $6 billion mark by 2032, the opportunity is substantial, but the window to align organization, supply chain, and compliance posture is narrowing.
Enterprise leaders who approach this environment with generic market narratives will find themselves making decisions in the dark. Those who ground their choices in rigorous segmentation, competitive intelligence, regulatory mapping, and scenario-aware forecasting will be better positioned to secure supply, win qualification-heavy contracts, and deploy capability where the returns are most decisive. Our Metal Material Based 3D Printing Market research is designed to make that alignment possible. The full report is the instrument for doing the work that 2026 demands, and it is available now for teams that are ready to convert momentum into strategy.
For detailed analysis of this topic, please visit the official page: Metal Material Based 3D Printing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Copper Strips Market Hits $126.6M in 2025; 5.24% CAGR Drives $180M Projection by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Copper Strips Market: Navigating Growth, Volatility, and Competitive Shifts in 2026
The global copper strips market stands at a critical inflection point. As industries accelerate electrification, expand automotive connectivity, and modernize electrical infrastructure, demand for high-performance rolled copper products has evolved from a cyclical commodity play into a strategically indispensable component of next-generation manufacturing. For executives, procurement leaders, and strategy teams, understanding where this market is headed—and why—requires more than headline metrics. It demands a structured, forward-looking view of valuation pathways, regional demand architectures, application drivers, and the competitive maneuvers reshaping supply chains.
Our latest Copper Strips Market research delivers precisely that perspective. Spanning historical analysis from 2020 through 2025 and extending with a detailed forecast horizon through 2032, the study is engineered to translate complex market signals into actionable decision frameworks. This overview highlights the strategic rationale behind the report, the operational intelligence it contains, and the market dynamics that will define competitive positioning throughout the remainder of the decade.
Why This Research Matters for 2026 Decision-Making
The copper strips sector is no longer governed by simple supply-demand equilibriums. Price volatility, regulatory interventions, midstream margin compression, and rapid product innovation are converging to redefine how manufacturers, distributors, and end-users plan capacity, negotiate contracts, and allocate capital. In this environment, strategic foresight is not optional—it is a competitive necessity.
Examining the market trajectory from a base year of 2025, the sector has demonstrated consistent expansion, with revenue scaling from approximately 102.45 million USD in 2020 to an estimated 126.6 million USD in 2025. Projections indicate continued momentum, with the market expected to reach 136.64 million USD in 2026 and advance toward 180.0 million USD by 2032. This growth trajectory is underpinned by a forecast CAGR of 5.24 percent, reflecting sustained industrial adoption and incremental push from high-growth applications.
For leadership teams, these figures are more than historical snapshots. They represent baseline scenarios that must be stress-tested against pricing shocks, regional demand reallocation, and technology-driven specification changes. The research is designed to help decision-makers answer critical questions: How should procurement strategies adapt to fluctuating input costs? Which end-use segments will drive volume versus value growth? Where do competitive threats and partnership opportunities emerge as capacity expands across key manufacturing hubs? By mapping these dimensions systematically, the report equips organizations with the analytical rigor needed to build resilient, forward-aligned strategies.
Market Architecture: Segmentation, Growth Drivers, and Structural Shifts
The market’s expansion is not uniform across regions or applications. Instead, it reflects a layered architecture where mature industrial economies, rapidly industrializing regions, and specialized high-performance verticals each contribute distinct demand profiles. Understanding these layers is essential for accurate forecasting, capacity planning, and go-to-market prioritization.
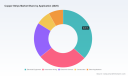
Demand concentration is particularly pronounced across core application categories. Electrical equipment and automotive wiring represent dominant consumption channels, while electronic devices, construction, and diversified industrial uses contribute additional layers of volume and specification complexity. At the end-use level, automotive and electrical segments anchor a substantial share of demand, with electronics reinforcing growth through miniaturization, thermal management, and connectivity requirements. The interplay between these segments shapes pricing dynamics, alloy selection, gauge diversification, and supply chain reliability expectations.
Regional demand patterns further illustrate the market’s evolving structure. Asia Pacific continues to command a leading share of consumption, driven by manufacturing intensity, infrastructure investment, and expanding electrical and automotive production ecosystems. North America and Europe maintain strong industrial baselines, supported by mature electrical grids, vehicle production networks, and ongoing modernization programs. Latin America and the Middle East and Africa contribute incremental but strategically relevant growth, often tied to specific industrial corridors, energy projects, and localized supply chain development.
This segmentation complexity matters because competitive positioning is rarely about total market size alone. It is about where value is captured, which specifications command premium margins, and how regional sourcing strategies interact with trade policy, logistics constraints, and customer qualification cycles. The report dissects these relationships in detail, enabling users to isolate the segments most aligned with their operational strengths and growth objectives.
Competitive Landscape: Leading Players and Strategic Maneuvers
The copper strips market is characterized by a moderately concentrated competitive structure, with a handful of established producers shaping pricing norms, technological benchmarks, and regional supply reliability. Market concentration metrics indicate that the top three firms account for approximately 35.2 percent of industry revenue, while the top five extend their combined share to roughly 52.1 percent. This distribution suggests a landscape where scale, technical capability, and vertical integration matter, yet competitive differentiation is still achievable through product specialization, service reliability, and strategic capacity deployment.
Among the leading participants, Aurubis AG stands out as a global non-ferrous metals producer and recycler whose copper strip offerings form part of a broader portfolio of rolled copper products. Its positioning reflects the increasing importance of recycled feedstock integration, material traceability, and supply continuity in a market sensitive to both cost and sustainability expectations.
KME Germany GmbH & Co. KG operates as a manufacturer of rolled copper and copper alloy semi-finished products, with strip solutions tailored for industrial applications. The company’s recent activity underscores a focus on processing depth and regional capacity reinforcement, aligning production capabilities with demand from demanding industrial customer bases.
Mitsubishi Materials Corporation brings specialized expertise in wrought copper products, including oxygen-free copper strips, multi-gauge strip configurations, and high-performance alloys designed for automotive and electronics applications. Its product strategy emphasizes material performance under thermal and mechanical stress, reflecting the broader industry shift toward higher-specification components in electrified and miniaturized systems.
Wieland-Werke AG serves as a specialist supplier of semi-finished copper and copper alloy rolled products, with dedicated strip, sheet, and plate offerings. Its market role highlights the value of application-focused engineering support, consistent quality assurance, and the ability to serve customers who require tightly controlled material properties across varied geometries.
Copper Strips Market
Worldwide Tin Plated Copper Strip Market
The competitive environment is further shaped by recent strategic moves that signal where industry leadership is being contested. In mid-2025, KME advanced its refining capabilities with the inauguration of a second refining furnace at its Osnabrück site, reinforcing processing capacity and operational flexibility in Europe. Later in the year, Mitsubishi Materials Corporation introduced a new high-strength, high-heat-resistance oxygen-free copper MOFC™-HR multi-gauge strip, designed to enable heat dissipation and contact area production using a single material platform—an innovation that illustrates how product differentiation is increasingly tied to functional performance rather than commodity volume alone. Heading into 2026, Wieland-Werke AG broke ground on a major expansion in Northwest Ohio, signaling continued investment in North American manufacturing presence and supply chain proximity.
These developments are not isolated events. They reflect an industry actively reshaping capacity, specification leadership, and regional footprint in response to demand relocation, customer qualification requirements, and margin pressures across the value chain. The report evaluates these moves within a broader competitive context, helping readers assess which strategies are likely to strengthen positioning and which may expose firms to risk if market conditions shift.
Macroeconomic and Regulatory Dynamics Shaping the Market
No market assessment is complete without addressing the external forces that influence cost structures, trade behavior, and investment timing. In the copper strips sector, recent price action and policy developments have introduced both opportunity and complexity.
Raw material dynamics have been particularly pronounced. Global copper prices reached record levels, briefly surpassing 14,500 USD per tonne in early 2026, supported by strong demand from electric vehicles, renewable energy deployment, and broader electrification trends. Quarter-over-quarter movements have been sharp, with prices rising to approximately 12,822 USD per metric tonne in the first quarter of 2026, following a notable climb from late-2025 levels. Such volatility directly affects input planning, inventory strategy, and contract structuring for downstream manufacturers.
Regulatory and trade measures have compounded these pressures. U.S. tariffs on semi-finished copper products—while exempting refined copper—have influenced pricing behavior across traded markets, contributing to a pronounced rise in benchmark contract values over the course of 2025 and into 2026. At the same time, smelter treatment and refining charges have reached historic lows even as headline copper prices climb, highlighting midstream margin compression and the challenges faced by processors navigating input cost inflation while operating under constrained treatment economics.
These dynamics create a dual challenge for market participants. On one hand, strong demand and elevated pricing can support revenue growth and justify capacity investment. On the other, margin pressure, trade uncertainty, and feedstock volatility can erode profitability if not managed through strategic sourcing, product mix optimization, and regional supply balancing. The research addresses these pressures directly, offering frameworks for interpreting price signals, evaluating procurement risk, and aligning capacity decisions with realistic market scenarios rather than short-term fluctuations.
What the Report Delivers: Practical Intelligence for Execution
Beyond macro analysis and competitive profiling, the study is built around operational usability. It provides a structured foundation for teams that need to translate market intelligence into planning assumptions, investment cases, and commercial strategies.
Key components of the report include:
- A comprehensive market size and forecast model that traces historical performance and projects future revenue pathways across the 2026 to 2032 horizon, enabling scenario planning under varying demand and pricing conditions.
- Segment-level evaluation across regions, applications, and end-use categories, allowing users to identify where demand intensity, specification requirements, and growth momentum differ.
- Competitive benchmarking and company-level analysis of leading producers, with attention to product portfolios, manufacturing focus, and recent strategic developments.
- Assessment of market concentration and structural dynamics that influence pricing power, supplier negotiation leverage, and barriers to entry.
- Contextual analysis of raw material trends, regulatory interventions, and midstream margin conditions, helping stakeholders interpret external volatility within a coherent strategic framework.
- Forward-looking discussion of the drivers likely to shape adoption, capacity deployment, and product innovation throughout the forecast period.
By combining quantitative structure with qualitative strategic interpretation, the report is designed to support a wide range of use cases: market entry evaluation, capacity justification, sourcing strategy refinement, competitive monitoring, and long-range planning. Each section is oriented toward reducing ambiguity and improving decision quality in an environment where assumptions must be tested against evidence.
Conclusion: Position Your Strategy Ahead of the Next Cycle
The copper strips market is being shaped by a rare combination of structural demand growth, material price volatility, regulatory disruption, and rapid product-level innovation. Organizations that rely on outdated assumptions or reactive procurement habits risk misjudging both opportunity and exposure. Those that invest in rigorous, forward-looking market intelligence can align sourcing, capacity, and commercial strategy with the segments and regions where value is most likely to consolidate.
This research is intended to serve as a strategic reference point for exactly that kind of planning. It provides the market sizing, segmentation logic, competitive context, and dynamic analysis needed to make informed decisions in 2026 and beyond. To access the complete dataset, detailed segmentation evaluations, full company profiles, and the complete forecast model, visit the source page and explore the full Copper Strips Market research. In a market moving as quickly as this one, the depth of your intelligence will directly shape the quality of your next strategic move.
For detailed analysis of this topic, please visit the official page: Copper Strips Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Concrete Fibers Market Set to Hit $344.8M by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
Navigating the Synthetic Concrete Fibers Market: Strategic Intelligence for 2026 and Beyond
The global construction landscape is undergoing a fundamental transformation, driven by demands for durability, sustainability, and cost-efficient reinforcement solutions. At the forefront of this shift is the Synthetic Concrete Fibers Market, a sector poised to redefine how infrastructure and buildings are reinforced against cracking and structural stress. As we move through 2026, enterprise decision-makers require more than just high-level growth figures; they need granular intelligence on competitive positioning, supply chain volatility, and application-specific adoption rates.
PW Consulting has released a comprehensive market research study designed to serve as a strategic compass for stakeholders navigating this evolving terrain. This article provides a preview of the key dynamics, competitive forces, and market trajectories shaping the industry, while highlighting the critical intelligence contained within the full report.
Market Trajectory and Strategic Context
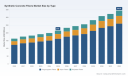
The Synthetic Concrete Fibers Market has demonstrated resilient growth over the past half-decade, reflecting a broader industry move away from traditional steel reinforcement toward advanced polymer-based solutions. According to our analysis, the global market revenue reached approximately USD 215.0 Million in 2025. This figure represents a significant expansion from the 2020 baseline, underscoring the accelerating adoption of synthetic fibers in concrete mixes.
Looking ahead, the growth trajectory remains robust. Our forecasts indicate that the market size will continue to expand through the end of the decade, surpassing the USD 300 Million mark by 2030 and reaching an estimated USD 344.8 Million by 2032. This projection is underpinned by a Compound Annual Growth Rate (CAGR) of 6.5 percent during the forecast period from 2026 to 2032.
For strategists, these numbers signify more than just volume; they represent a maturing market where differentiation becomes key. The consistent upward trend suggests that synthetic fibers are no longer a niche alternative but a mainstream standard in specific high-performance applications. However, capturing this growth requires understanding where the value lies across different product types, end-use sectors, and geographies.
Key Segments and Value Pools
The market is characterized by distinct segmentation across product types, applications, and regions. While the overall market expands, the distribution of revenue across these segments reveals where the immediate opportunities and challenges reside.
Product Type Dynamics
Polypropylene Fibers currently dominate the revenue landscape, accounting for the largest share of the market. This dominance is driven by the material's cost-effectiveness and widespread availability for general crack control and secondary reinforcement. However, the market is not monolithic. Nylon Fibers and Polyester Fibers maintain significant presence, catering to specialized applications where specific mechanical properties, such as higher impact resistance or specific tensile strengths, are required.
The strategic implication for manufacturers is clear: while polypropylene offers volume, innovation in nylon and polyester blends may offer higher margins in niche sectors. Understanding the price elasticity and performance trade-offs between these material types is critical for product portfolio strategy.
Application-Led Growth
In terms of end-use, Industrial Flooring stands out as the primary revenue contributor. The demanding nature of industrial environments, which require floors capable withstanding heavy loads, abrasion, and chemical exposure, makes synthetic fiber reinforcement indispensable. This segment is expected to continue driving volume as warehousing, logistics hubs, and heavy manufacturing facilities expand globally.
Conversely, Residential and Commercial Building applications represent a substantial but distinct opportunity. Here, the value proposition often centers on labor savings, reduced concrete shrinkage, and improved surface quality. Other Applications, including precast and specialized infrastructure, round out the demand profile. A deep dive into these segments reveals varying adoption barriers and procurement cycles that differ significantly from industrial use cases.
Regional Shifts
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America and Asia Pacific currently represent the largest regional markets, reflecting strong construction activity and infrastructure investment in these areas. Europe follows as a mature market with a strong emphasis on sustainable construction practices that favor synthetic reinforcement.
Synthetic Concrete Fibers Market
Emerging regions in Latin America and the Middle East and Africa are witnessing increasing uptake, driven by infrastructure development projects. However, the regulatory environments and supply chain maturity in these regions vary widely, necessitating localized strategies that our report details extensively.
Competitive Landscape and Strategic Consolidation
The market structure is moderately fragmented, though key players are increasingly leveraging scale and technological differentiation to secure market share. Our analysis indicates a competitive environment where concentration levels are evolving. The top three companies hold a combined market share of approximately 24.6 percent, while the top five control around 26.2 percent. This suggests that while large incumbents hold significant sway, there is ample room for specialized players and regional leaders to thrive.
Several key companies define the competitive boundaries of this market. Sika AG, headquartered in Baar, Switzerland, remains a formidable force with its SikaFiber® and FiberSave™ product lines. Their strategy focuses on replacing steel reinforcement in slabs, industrial flooring, and precast applications, leveraging a strong global distribution network. Sika's recent capacity expansion at its Tennessee plant in the United States, announced in June 2025, highlights the strategic priority given to industrial flooring and mining applications, as well as the push toward sustainable construction.
MAPEI S.p.A., based in Milan, Italy, competes strongly with its Mapefibre® line. Their offerings, including the ST 42 blend of polypropylene and polyethylene resins, target crack control and steel replacement, positioning them as a go-to for technical concrete solutions. Similarly, Euclid Chemical Company, operating out of Cleveland, Ohio, has carved a niche with its patented TUF-STRAND SF polypropylene/polyethylene macro synthetic fiber. Euclid's focus on replacing welded wire mesh and steel in floors and industrial applications was recently reinforced through a partnership with Terminal Ready Mix and Rudolph Libbe Group in May 2025, supplying fibers for a major auto manufacturing plant in Ohio.
FORTA Corporation, based in Huntingdon Valley, Pennsylvania, offers a dual strategy with FORTA-FERRO® macro fibers for impact resistance and steel replacement, alongside micro and monofilament fibers for plastic shrinkage crack control. GCP Applied Technologies Inc., from Cambridge, Massachusetts, continues to innovate with its STRUX® 90/40 and BT50 synthetic macrofibers. Their update in September 2024, launching version 2.0 of the STRUX mobile app with enhanced cost analysis tools, demonstrates a focus on digital integration and user support to drive adoption.
The landscape also includes agile players such as BarChip Inc. in Houston, Texas, which provides CE-certified high-performance fibers for global infrastructure projects. Fabpro Polymers, a division of Great Lakes Polymer Technologies, specializes in high-performance macro and micro types for construction. Polyfibers® operates with a global manufacturer presence, offering full lines with technical support. Mighty Shield Sdn Bhd in Malaysia contributes with Dunamis™ fibers for shotcrete and pavement applications. Adfil in Spain targets floors, precast, and tunneling, while Belgian Fibers in Belgium rounds out the list with macro and micro reinforcement solutions.
The strategic takeaway for competitors and new entrants is that success relies on a combination of product performance, technical support, and regional presence. Partnerships with ready-mix suppliers and contractors, as seen in recent developments, are becoming standard tactics for market penetration.
Supply Chain Volatility and Raw Material Dynamics
A critical layer of complexity in the Synthetic Concrete Fibers Market is the volatility of raw material costs, particularly polypropylene. As the primary feedstock for the dominant fiber type, polypropylene price fluctuations directly impact margin structures and pricing strategies.
Recent industry data highlights significant volatility. As of April 2026, polypropylene prices rose by approximately 34 percent year-to-date, reaching regional benchmarks of USD 1.43/kg in Northeast Asia, USD 1.52/kg in North America, and USD 2.53/kg in Europe. By May 2026, prices in Northeast Asia stood at 1.43 USD/kg, up 16.3 percent from the prior period, supported by stable supply from propylene monomer feedstock. In North America, prices reached US$1.48/kg in May 2026, up 6.5 percent from the previous period, while European prices stood at US$2.46/kg in April 2026, up 9.3 percent year-to-date.
More recent data from June 2026 shows a slight easing, with Polypropylene benchmark prices falling to 8696 CNY/T, down 0.54 percent day-over-day and 2.39 percent over the past month. However, this remained 24.53 percent higher than one year prior. This persistent elevation in raw material costs underscores the importance of supply chain resilience. Companies must navigate these cost pressures through strategic sourcing, hedging, or value engineering to maintain competitiveness.
The disparity in regional pricing also presents arbitrage opportunities and challenges. Manufacturers operating across multiple regions must account for these cost differentials when planning production allocation and pricing strategies. The full report provides a detailed analysis of how these raw material dynamics intersect with regional demand and competitive pricing.
Content Overview: What the Research Delivers
To support data-driven decision-making in 2026, the PW Consulting Synthetic Concrete Fibers Market report offers a granular examination of the industry. The research is structured to provide actionable intelligence across multiple dimensions, enabling stakeholders to formulate robust strategies.
The report encompasses a comprehensive analysis of market size and growth projections, segmented by type, application, and region. It goes beyond aggregate numbers to explore the drivers, restraints, and opportunities within each segment. Readers will find detailed profiles of key companies, including their product offerings, strategic initiatives, and recent developments. The competitive landscape analysis includes market concentration metrics and an assessment of the strategies employed by leading players to gain advantage.
Furthermore, the study delves into the supply chain dynamics, examining raw material trends, production capacities, and distribution channels. The integration of recent industry events, such as capacity expansions, partnerships, and product launches, provides a real-time view of market momentum. This context is essential for anticipating shifts in supply availability and competitive intensity.
The research also addresses the macroeconomic and regulatory factors influencing the market. Construction trends, sustainability mandates, and infrastructure investment plans are analyzed to forecast how they will shape demand over the forecast period. By connecting these external factors to market mechanics, the report helps stakeholders align their strategies with broader industry currents.
Concrete Fiber Market
Strategic Imperatives for 2026
As the market matures, several strategic imperatives emerge for companies operating in the Synthetic Concrete Fibers Market. First, product differentiation is becoming increasingly important. While cost remains a factor, the ability to demonstrate superior performance in specific applications, such as industrial flooring or high-stress infrastructure, can command premium positioning.
Second, supply chain agility is paramount. Given the volatility in polypropylene prices and regional cost disparities, companies must build resilient supply networks. This may involve diversifying sourcing, investing in local production capabilities, or developing long-term contracts that mitigate price risk. The capacity expansion by Sika in the US serves as a prime example of proactive supply chain management to meet regional demand.
Third, strategic partnerships and ecosystem integration are key growth levers. Collaborations with ready-mix producers, contractors, and engineering firms can accelerate adoption and lock in demand. The partnership between Euclid Chemical and major construction groups for an auto plant highlights the value of aligning with large-scale projects. Additionally, digital tools, like GCP's updated mobile app, enhance customer engagement and provide value-added services that support adoption.
Fourth, geographic expansion requires careful localization. While North America and Asia Pacific offer substantial volume, emerging regions present growth opportunities that require tailored approaches. Understanding local regulatory standards, construction practices, and price sensitivities is essential for successful market entry or expansion.
Conclusion
The Synthetic Concrete Fibers Market stands at a pivotal juncture in 2026. With a projected CAGR of 6.5 percent and a market value expected to reach USD 344.8 Million by 2032, the sector offers significant opportunities for growth. However, realizing this potential requires navigating a complex landscape of competitive dynamics, raw material volatility, and diverse application needs.
PW Consulting's comprehensive market research provides the depth and precision needed to make informed strategic decisions. From detailed segmentation analysis to competitive profiling and supply chain insights, the report equips stakeholders with the intelligence required to capitalize on market trends and mitigate risks.
To access the full scope of data, forecasts, and strategic recommendations, we invite you to explore the complete market research report. The detailed findings contained within will empower your organization to navigate the synthetic concrete fibers market with confidence and precision.
For detailed analysis of this topic, please visit the official page: Synthetic Concrete Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sandals Market Hits $36.29B in 2025, Projects 4.52% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Insights into the Global Sandals Market: Navigating Growth Trajectories Through 2032
Executive Overview
The global footwear industry has consistently demonstrated resilience, yet few categories exhibit the versatile demand patterns and seasonal adaptability of the sandals segment. As organizations plan for the 2026 fiscal cycle and beyond, understanding the underlying structural forces shaping this market is no longer optional—it is a strategic imperative. Our latest comprehensive market intelligence study on the Sandals Market delivers a rigorous, forward-looking blueprint designed to support executive decision-making, portfolio optimization, and competitive positioning. By synthesizing historical performance metrics with multi-year projections, this report equips stakeholders with the contextual clarity needed to anticipate demand shifts, allocate capital efficiently, and respond proactively to evolving consumer preferences.
Macro Trajectory and Long-Term Market Dynamics
Over the past half-decade, the sandals market has navigated a complex landscape of supply chain recalibrations, shifting seasonal purchasing behaviors, and sustained retail expansion. Historical baseline data from 2020 through 2025 reveals a market that has steadily consolidated its position, with revenue trajectories reflecting both recovery phases and structural growth. The 2025 valuation provides a critical inflection point, anchoring our baseline for the forecast window extending through 2032. The projected compound annual growth rate of 4.52 percent across this eight-year horizon underscores a market that is neither stagnating nor overheating, but rather maturing with predictable, compounding momentum.
What makes this trajectory strategically significant is not simply the headline growth figure, but the consistency of the underlying demand architecture. While short-term fluctuations in raw material costs, regional logistics bottlenecks, and discretionary spending cycles have introduced periodic volatility, the long-term expansion curve remains anchored by foundational consumption drivers. The forecast pathway outlines a stepwise progression of revenue milestones, each representing a phase of market adaptation, product category evolution, and channel optimization. Executives who internalize this sequential growth narrative can align product roadmaps, inventory strategies, and regional market entry timelines with greater precision.
Sandals Market
Structural Demand Drivers and Consumer Behavior Shifts
The sustained expansion of the sandals category is fundamentally rooted in the convergence of lifestyle normalization, climate-adaptive purchasing, and functional footwear demand. Consumers have increasingly treated sandals not merely as seasonal accessories, but as year-round staples across casual, light-duty, and specialized environments. Recent industry tracking highlights a notable acceleration in both dollar and unit performance during early 2026, with certain silhouettes driving disproportionate share gains. Footwear segments characterized by open-back designs and streamlined closures have emerged as primary growth catalysts, reflecting a broader consumer preference for lightweight comfort, rapid transition wear, and versatile styling.
Beyond core categories, adjacent silhouettes such as mules, clogs, and lightweight slip-ons have contributed positively to category performance, signaling that demand elasticity extends across multiple design architectures. This diversification implies that brands and retailers cannot rely on a single product archetype to capture market share. Instead, success increasingly depends on portfolio breadth, fit innovation, and the ability to align aesthetic trends with functional utility. The market is also showing clear gender and age-related consumption patterns, with adult segments commanding the largest revenue contribution while children’s segments reflect targeted, occasion-driven purchasing. Understanding these consumption gradients allows companies to tailor marketing messaging, merchandising strategies, and assortment planning more effectively.
Footwear Market
Geographic and Segment-Level Intelligence
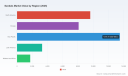
Market performance does not distribute uniformly across regions or product types, and our research framework isolates the structural factors that explain these divergences. Regional demand profiles reflect distinct climatic conditions, retail maturity levels, pricing sensitivities, and cultural adoption cycles. Certain markets have emerged as high-volume anchors due to sustained consumer purchasing power and established distribution networks, while others present higher growth potential as retail infrastructure expands and middle-income consumption broadens. The report maps these regional dynamics in detail, providing decision-makers with comparative context for supply chain positioning, localized assortment design, and market penetration sequencing.
Product-type segmentation further reveals where value creation is concentrated. Open footwear architectures continue to dominate volume and revenue discussions, but the relative weight of each subcategory shifts based on seasonal demand, work-environment applications, and leisure usage patterns. Flip-flops, slides, and slippers each serve different functional and emotional use cases, and their performance variance offers a window into how consumers balance comfort, durability, and style. The study breaks down these category-level behaviors without reducing them to simplistic rankings, instead emphasizing the strategic implications for product development, inventory allocation, and promotional cadence.
Competitive Landscape and Strategic Positioning
The competitive environment in this market reflects a blend of specialized manufacturers, regional footwear producers, and multinational players with diversified portfolios. Market concentration metrics indicate a moderately fragmented landscape, where no single entity dominates the overall category. This fragmentation creates both opportunity and risk: it allows agile entrants to capture niche demand and differentiate through design or functionality, while also requiring established players to defend share through brand equity, distribution strength, and operational efficiency.
Within the specialized safety and industrial footwear segment, companies such as WorkWay Safety and Hillson Safety Shoes illustrate how functional sandals and protective footwear are carving out distinct demand pathways. These organizations emphasize safety-oriented designs, including steel-toe variants and work-appropriate sandals tailored for automotive and workshop environments. Their presence highlights a broader strategic truth: performance-driven subcategories can command loyalty and pricing resilience when they solve specific occupational or environmental discomfort problems. For broader consumer brands, the lesson is clear—functional differentiation, material innovation, and context-appropriate design can serve as durable competitive advantages even in a category often perceived as purely aesthetic.
Beyond direct competitors, the market is shaped by the actions of data providers, retail analysts, and consumer behavior trackers whose periodic reporting influences purchasing sentiment and inventory planning. Recent market commentary has reinforced the narrative of early-cycle strength in key silhouettes, helping organizations validate near-term assortment decisions and promotional investments. Access to disciplined, continuously updated intelligence allows firms to distinguish between temporary noise and structural trend reinforcement, a distinction that directly affects margin protection and markdown risk.
Research Scope and Operational Utility
Our Sandals Market research report is structured to function as an operational tool rather than a passive reference document. It integrates historical baselines, forward-looking projections, and contextual analysis into a unified decision-support framework. The study examines market sizing across multiple time horizons, traces performance evolution from 2020 through the baseline year, and extends projected revenue pathways through the end of the forecast window. This temporal coverage enables users to benchmark current performance against prior cycles and assess whether recent momentum aligns with longer-term expectations.
The report also provides segmentation analysis across geography, product type, and consumer demographics, allowing stakeholders to identify where growth concentrates and where differentiation opportunities remain under-explored. Competitive profiling, market concentration indicators, and category-level performance context are presented to help organizations understand positioning relative to peers and potential entrants. In addition, the research incorporates recent industry developments, consumption observations, and retail tracking signals to connect quantitative projections with on-the-ground market behavior. For executives, this means the report can support scenario planning, product launch timing, regional expansion prioritization, and channel strategy refinement without requiring extensive internal data synthesis.
Implications for 2026 Decision-Making
As organizations finalize 2026 strategies, the strategic value of this research lies in its ability to translate broad market momentum into actionable business direction. The forecasted growth trajectory suggests that demand will continue to expand at a measured, sustainable pace, but the real competitive advantage will come from how companies interpret the composition of that growth. Firms that understand which silhouettes, regional markets, and consumer segments are driving performance can allocate resources more efficiently, reduce exposure to overstock risk, and prioritize innovation where it will generate the strongest return.
The research also supports more disciplined approaches to pricing, distribution, and product lifecycle management. In a market where certain subcategories outperform while others plateau, aggregate growth figures can mask important underlying variation. By examining structural drivers and category-level behavior in detail, decision-makers can avoid overgeneralizing market strength and instead build strategies that reflect actual consumption patterns. This level of precision becomes especially important in 2026, as companies balance capacity planning, inventory optimization, and competitive response in an environment still influenced by shifting retail dynamics and consumer spending sensitivity.
Conclusion: Turning Market Intelligence into Competitive Advantage
The Sandals Market is not undergoing a speculative surge; it is evolving through a steady, evidence-backed expansion that rewards informed strategic positioning. Historical performance, forward projections, and current consumption signals all point to a category with durable demand foundations and meaningful room for differentiation. The insights contained in this report are designed to help leaders move beyond surface-level trend awareness and toward concrete, timing-aware decisions that align with long-term market architecture. For organizations seeking a clearer view of where growth is concentrated and how competitive dynamics are evolving, this study offers the analytical depth required to act with confidence. The full market intelligence, including detailed segmentation breakdowns, regional comparisons, and extended forecast tables, is available through our complete report package, providing the comprehensive foundation needed to shape 2026 strategy and beyond.
For detailed analysis of this topic, please visit the official page: Sandals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Office Storage Market Hits USD 3.15 Billion in 2025, Projected 7.9% CAGR to 2032
By PW Consulting, 2026-09-16
Unlocking Strategic Value in the Office Storage & Organization Market: A 2026 Executive Briefing
The modern workplace is undergoing a structural transformation. As hybrid work models solidify and organizations rethink physical footprint efficiency, the Office Storage & Organization Market has emerged as a critical infrastructure layer for operational productivity, compliance, and spatial optimization. For executive leadership, facility managers, and procurement strategists, the question is no longer whether to invest in smarter storage ecosystems, but how to align those investments with long-term growth trajectories, cost containment mandates, and evolving workplace safety mandates.
Our latest market research publication delivers a comprehensive, data-grounded assessment of this sector, mapping historical performance, forward-looking demand signals, competitive positioning, and the macroeconomic forces reshaping procurement decisions. This briefing outlines the strategic architecture of the study and explains why it serves as an essential decision-support tool for 2026 planning cycles.
Macro Trajectory: Scaling Demand in a Shifting Workspace Economy
Over the past half-decade, the office storage and organization sector has demonstrated consistent expansion, reflecting broader trends in workplace rationalization, inventory visibility, and the formalization of remote and hybrid work environments. Historical tracking from 2020 through 2025 shows a steady climb in market revenue, with the sector moving from approximately 2.18 billion USD to 3.15 billion USD by the base year. This upward arc underscores a sustained organizational appetite for structured storage solutions that support document management, equipment housing, and spatial decluttering across corporate and decentralized work settings.
Looking ahead, the forecast horizon through 2032 projects continued momentum, with the market anticipated to reach 5.34 billion USD by the close of the period. The implied compound annual growth rate of 7.9 percent signals a sector that is not merely recovering from post-pandemic workspace adjustments, but actively re-architecting how organizations store, access, and manage physical assets. This growth trajectory carries meaningful implications for capital allocation, supplier relationship management, and facility planning. Decision-makers who internalize the pace and shape of this expansion can better time procurement cycles, negotiate volume commitments, and align storage investments with broader workplace modernization roadmaps.
Office Furniture Market
Structural Shifts Driving Buyer Behavior and Product Preference
The sector’s evolution is being shaped by several intersecting forces that alter both demand composition and supplier strategy. First, the proliferation of remote and hybrid work arrangements has expanded the addressable footprint for home office storage and organization products. As professionals convert residential spaces into functional work environments, demand for scalable, aesthetically cohesive, and ergonomically mindful storage units has grown. This shift is not simply a residential trend; it reverberates through corporate procurement as employers extend stipends, equipment packages, and standardized organization kits to distributed workforces.
Second, workplace safety and regulatory expectations are tightening the specification criteria for storage infrastructure. Occupational safety regulations increasingly require storage units to meet defined load-bearing thresholds and fire-resistance standards. These requirements elevate the importance of compliance-ready designs, pushing buyers toward suppliers that can document material certifications, structural testing, and adherence to regional building and fire codes. In practice, this means procurement teams must evaluate not only storage capacity and modularity, but also the evidentiary trail that supports regulatory conformity.
Third, cost dynamics are introducing complexity into margin planning and pricing strategy. Raw material volatility affecting steel, wood composites, and engineered plastics has constrained manufacturers’ ability to absorb cost fluctuations without adjusting product pricing or reprioritizing feature sets. Simultaneously, the wood office-furniture producer price index reached elevated levels in mid-2025, creating cost headwinds that ripple through the broader storage and organization supply chain. For buyers, this environment rewards strategic sourcing, multi-supplier diversification, and specification flexibility that preserves functional requirements while mitigating exposure to input-cost spikes.
Finally, financing mechanisms are shaping deployment timing, particularly for small and mid-sized enterprises. In the United States, Small Business Administration 504 loans provide long-term financing pathways for office storage infrastructure investments. This availability can smooth capital expenditure planning, enable phased rollouts, and help organizations align storage upgrades with broader facility improvement programs. Understanding the interplay between financing options and procurement cadence is increasingly relevant for market participants evaluating total cost of ownership rather than upfront price alone.
What the Report Delivers: Operational Intelligence for Procurement and Strategy Teams
This research is structured to move beyond headline figures and provide actionable intelligence that supports real-world decision-making. The study combines quantitative modeling with qualitative assessment, giving readers a multidimensional view of market behavior, supplier capabilities, and demand-side priorities. Key components of the publication include:
- A detailed historical reconstruction of market performance across the 2020–2025 period, establishing a reliable baseline for evaluating growth consistency, demand elasticity, and segment maturation.
- A forward-looking forecast framework extending through 2032, designed to help organizations stress-test procurement assumptions, plan capacity alignment, and anticipate inflection points in adoption.
- An examination of product-type dynamics, contrasting conventional office storage cabinets with mobile shelving systems, including the operational trade-offs that influence selection in different workspace configurations.
- An application-level analysis that disaggregates demand across corporate headquarters, remote home offices, and other deployment contexts, highlighting how use-case requirements shape specification, throughput expectations, and purchase frequency.
- A regional perspective that maps demand distribution and contextual factors across major geographic markets, supporting multinational planning and localization strategies.
- A competitive landscape assessment that profiles leading participants, evaluates strategic positioning, and tracks recent product and catalog developments that signal where the market is heading.
- An integrated review of market concentration indicators, providing context on supplier consolidation, pricing power, and the degree of fragmentation or consolidation that characterizes the sector.
The report is intended for use by strategic procurement leaders, workplace operations executives, financial planners, and market-entry teams who require a structured, evidence-based foundation for evaluating storage and organization investments. Rather than treating the sector as a commoditized furniture category, the study frames it as a functional infrastructure market where compliance, space efficiency, durability, and total cost of ownership carry decisive weight.
Competitive Landscape: Positioning, Innovation, and Recent Market Signals
The competitive environment in office storage and organization reflects a blend of established manufacturers, specialized systems providers, and broad-access retail players. Each category brings a distinct value proposition to buyers, and understanding these differences is essential for evaluating supplier fit, negotiating terms, and building resilient supply chains.
Companies such as Office Furniture EZ operate through a hybrid distribution model that combines physical showroom access with online catalog availability, offering modular furniture, cabinets, and accessories that appeal to buyers seeking visible product interaction and convenient catalog browsing. SHUTER emphasizes manufacturing capability with a focus on modern office storage cabinets, tool storage, and organizational systems built around innovation and durability, positioning itself for customers who prioritize engineered reliability and product evolution. Livinbox enters the space with a design-oriented approach, crafting stylish home and office storage products, plastic containers, organizers, and modular solutions that resonate with buyers balancing aesthetics and practicality. HNI Corporation contributes high-density storage systems and office organization solutions integrated with broader workplace furniture offerings, making it relevant for organizations pursuing space optimization within a unified furniture strategy. Spacesaver Corporation specializes in high-density mobile storage and organization systems, targeting environments where maximizing accessible storage within limited footprints is a core operational requirement.
Additional participants broaden the market’s reach and purchasing pathways. Montel Inc. provides storage and organization solutions tailored to office environments, while The Container Store extends retail and home office storage options that support productivity-focused organization for distributed professionals. Ikea remains a prominent global retailer of affordable, modular office storage and organization products, offering a value-focused entry point for cost-sensitive buyers and standardized deployment scenarios.
Recent company activities reinforce the sector’s dynamic character. In 2026, Office Furniture EZ released its product catalog featuring office storage and organization solutions, while SHUTER issued a 2026 catalog highlighting modern office storage cabinets and organizational systems. Livinbox meanwhile showcased new product lineups at major trade events, signaling continued product refresh activity and an emphasis on visible innovation in storage design and modularity. These developments illustrate how competitors are using catalog expansion and product showcases to capture attention, differentiate capabilities, and align offerings with evolving buyer expectations.
Market concentration data provides additional context for competitive assessment. With a CR3 of 25.0 percent and a CR5 of 30.0 percent, the sector exhibits a moderate degree of consolidation without full concentration at the top. This structure suggests that while leading players hold meaningful share, there remains ample room for specialized suppliers, regional performers, and design- or price-focused entrants to compete on specification, service, and niche application fit. For procurement leaders, this landscape supports a dual strategy: leveraging scale and consistency from established suppliers while preserving flexibility through secondary sources that can address specialized requirements or cost constraints.
Office Storage & Organization Market
Why This Research Matters for 2026 Decision-Making
The strategic value of this study lies in its ability to connect market structure with operational consequence. In 2026, organizations are making decisions under multiple pressures: the need to optimize real estate and workspace utilization, the imperative to maintain compliance with evolving safety standards, the challenge of managing input-cost volatility, and the expectation to support distributed workforces with consistent, reliable storage solutions. A superficial view of the market can lead to under-specification, reactive purchasing, or over-reliance on single-supplier relationships. A structured, evidence-based view enables more disciplined planning.
For procurement and operations leaders, the report provides a basis for comparing product types against actual usage scenarios, weighting durability and compliance alongside capacity and aesthetics, and evaluating supplier portfolios against recent innovation signals. For financial and strategy teams, the forecast framework supports scenario modeling around demand growth, investment timing, and the potential impact of financing instruments on deployment schedules. For market-entry and business development teams, the segmentation and competitive analysis clarifies where differentiation is achievable and which buyer priorities are most likely to shape purchasing decisions over the forecast period.
Equally important, the study helps organizations avoid misreading the market as purely price-driven. While cost remains a central factor, the sector’s trajectory is increasingly defined by functional performance, regulatory readiness, modular flexibility, and the ability to support both centralized and distributed workplace models. Buyers who evaluate storage and organization investments through this broader lens are better positioned to secure long-term value rather than short-term savings that may compromise durability, compliance, or adaptability.
Conclusion: Moving from Awareness to Actionable Intelligence
The Office Storage & Organization Market is expanding at a measured but meaningful pace, shaped by workspace redesign, regulatory compliance, material-cost dynamics, and the continuing normalization of hybrid work. The sector’s projected growth through 2032 reflects an environment in which storage infrastructure is no longer a peripheral procurement category, but a core enabler of productivity, safety, and spatial efficiency.
This research publication is designed to give executives the depth they need to act with confidence. It integrates historical context, forward-looking modeling, competitive profiling, and industry dynamics into a single decision-support framework. To access the full segmentation detail, regional breakdowns, application-level evaluations, and complete competitive intelligence, we invite stakeholders to review the complete report through our official research portal. The full dataset and proprietary analysis are available there for teams ready to translate market insight into structured 2026 and beyond procurement strategies.
For detailed analysis of this topic, please visit the official page: Office Storage & Organization Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Waste Paper Recycling Market to Reach $74.3B by 2032, 5% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Waste Paper Recycling Market: Navigating Growth from 2026 to 2032
The global waste paper recycling industry stands at a critical inflection point. As environmental regulations tighten and corporate sustainability mandates become non-negotiable, the sector is transitioning from a linear waste management model to a circular economy cornerstone. For strategic decision-makers, understanding the trajectory of this market is no longer optional—it is a prerequisite for capital allocation, supply chain resilience, and competitive positioning. This analysis draws upon comprehensive market research to outline the opportunities and risks defining the period from 2026 through 2032.
Market Trajectory: From Recovery to Sustained Expansion
The macroeconomic backdrop for waste paper recycling is characterized by robust historical growth and a confident forecast horizon. Tracing the valuation from the base year 2025 through the forecast period ending in 2032 reveals a sector that has successfully weathered economic volatility to establish a strong upward trend. In 2020, the market valuation stood at approximately 41,500 million USD. Over the subsequent five years, the industry demonstrated resilience, climbing to 48,982.3 million USD by 2024 despite supply chain disruptions and fluctuating raw material costs.
The momentum accelerated leading into the current baseline, with the market size reaching 53,000 million USD in 2025. This growth trajectory is projected to continue, with the valuation expected to breach 56,491.54 million USD in 2026. Looking further ahead, the compound annual growth rate (CAGR) is estimated at 5.0 percent throughout the forecast period. By 2032, the market is anticipated to reach 74,300 million USD. This steady expansion underscores a structural shift in how industries view recovered fiber—not merely as waste, but as a valuable commodity integral to manufacturing supply chains.
Key Growth Drivers and Industry Dynamics
Several converging forces are fueling this expansion. First, the global push toward reducing carbon footprints is driving demand for recycled content in packaging and tissue products. Second, regulatory frameworks in key economic zones are increasingly mandating minimum recycled content thresholds, effectively creating a price floor for recovered paper. Third, technological advancements in sorting and pulping efficiency are lowering the operational costs of recycling facilities, improving margins for processors.
Recent industry data highlights the sensitivity of this market to supply and demand fundamentals. For instance, in March 2026, recovered paper prices for Old Corrugated Containers (OCC) increased due to stronger demand for recycled fiber coupled with tightening supply. Such fluctuations indicate a mature market where inventory management and long-term supply contracts are becoming critical strategic levers. Companies that secure reliable feedstock sources will hold a distinct advantage as competition for high-grade waste paper intensifies.
Segmentation Insights: Where Value is Concentrated
Understanding where value resides within the waste paper recycling ecosystem is essential for targeted investment. The market is segmented by type, application, and region, each presenting unique risk-reward profiles. While specific granular data is reserved for the full report, the broader distribution patterns reveal where strategic focus should be applied.
Material Types and Processing Requirements
The market encompasses various grades of waste paper, each requiring distinct processing technologies. Corrugated cardboard remains a dominant stream due to its prevalence in logistics and e-commerce packaging. High-grade paper and old newspapers or magazines also constitute significant portions of the feedstock mix. Mixed paper presents a more complex challenge due to contamination risks but offers volume potential. The choice of processing equipment—whether shredding, pulping, or baling—depends heavily on the specific material stream a company intends to target. Investing in the wrong technology for a specific paper grade can erode margins quickly.
Application End-Uses
The downstream demand is diversified across several key industries. Packaging represents the largest consumption channel, driven by the retail and e-commerce sectors' relentless demand for sustainable boxes and containers. Construction utilizes recycled fiber for insulation and other materials, while printing and writing applications maintain a steady, albeit slower-growing, demand. The tissue and hygiene sector is another critical consumer of high-quality recycled pulp. Understanding the yield rates and quality specifications required by each application is vital for recyclers aiming to maximize revenue per ton of input material.
Regional Nuances
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific, in particular, has shown significant activity due to industrialization and urbanization trends. However, regional regulations regarding waste imports and exports create varying operational landscapes. A strategy that works in North America may not be directly transferable to Latin America or Europe without adjusting for local compliance costs and infrastructure maturity.
Competitive Landscape: Technology Leaders and Strategic Roles
The competitive environment is fragmented but features distinct players who dominate specific niches of the technology stack. The market concentration metrics indicate a moderate level of consolidation, with the top three companies holding a notable share and the top five increasing that presence. This suggests that while there is room for specialized players, scale and technological superiority are becoming increasingly important.
Equipment Manufacturers and Technology Providers
Several key companies define the current equipment landscape, offering solutions that range from primary shredding to complete turnkey recycling lines. WEIMA , based in Germany, focuses on single-shaft shredders such as the WLK 15 and WLK 18 Jumbo models. These are designed for efficient processing of paper, cardboard, and OCC into flakes or pulp, offering customizable configurations for recycling lines. Their technology is critical for initial size reduction and preparation.
In the realm of complete processing facilities, Parason Engineering from India provides turnkey recycled-fiber lines. Their offerings include pulpers, cleaners, screens, and deinking systems for OCC and mixed waste. These lines produce board, liner, newsprint, and tissue at capacities ranging from 8 to 1030 TPD. This breadth allows them to serve both small-scale localized operations and large industrial mills.
For material handling and volume reduction, American Baler Company and Maren Engineering Corporation in the USA are prominent. American Baler specializes in horizontal and two-ram balers engineered for OCC, paper, and cardboard bales, reducing volume and labor in recycling and distribution centers. Maren Engineering complements this with horizontal auto-tie, two-ram, and closed-door balers specifically for OCC and cardboard recycling to flatten material for storage and transport. Efficient baling is crucial for logistics economics, directly impacting the cost of moving recycled fiber to mills.
On the shredding and pre-processing side, BHS-Sonthofen in Germany provides shredders and pre/post-shredding equipment for paper, cardboard, and OCC in recycling applications. Meanwhile, SOYU in China focuses on OCC dry pulping and recycling lines that convert waste paper into recycled pulp with energy-efficient dry processing. This energy efficiency angle is becoming a key differentiator as energy costs rise. Rexon Hydraulics , also based in India, offers automatic horizontal paper balers and recycling machines for cardboard and OCC, catering to the automation needs of modern facilities.
Recent Market Movements
Market activity remains dynamic. In June 2026, ReBAT confirmed its status as an exhibitor at the World of Recycling Expo 2026 in India, showcasing material recycling machinery including waste paper solutions. Such events highlight the ongoing innovation cycle and the importance of industry networking for identifying emerging technologies and partnership opportunities. Participation in major expos often signals a company's commitment to expanding its footprint in high-growth regions.
Waste Paper Reuse Market
Strategic Imperatives for 2026 Decision Makers
For executives and investors looking to navigate this landscape in 2026, several strategic imperatives emerge from the data.
Waste Paper Recycling Market
- Supply Chain Security: With tightening supply noted in recent months, securing long-term contracts with waste generators or establishing owned collection networks is vital. Volatility in OCC prices can impact profitability significantly.
- Technology Alignment: Investing in the right machinery is crucial. Whether it is energy-efficient dry pulping, high-capacity shredding, or automated baling, the technology must match the target material stream and end-use quality requirements.
- Regional Compliance: Navigating the regulatory divergence between regions like Europe, North America, and Asia Pacific requires localized expertise. Compliance costs can vary widely and impact the economic feasibility of cross-border trade in recycled materials.
- Capacity Planning: With the market projected to grow steadily towards 2032, capacity expansion plans must be timed correctly. Overbuilding too early risks underutilization, while delaying risks missing the demand surge driven by sustainability mandates.
Conclusion: The Value of Comprehensive Market Intelligence
The waste paper recycling market offers substantial opportunities for growth, but realizing them requires more than just general industry awareness. It demands a granular understanding of segmentation splits, competitive positioning, regulatory pressures, and technological capabilities. The macroeconomic numbers tell a story of growth, but the operational details tell the story of profitability.
This overview serves as a high-level indicator of the trends shaping the industry. However, the complex interplay between material grades, regional regulations, and specific equipment specifications requires deeper analysis. For organizations aiming to make informed capital deployment decisions or strategic partnerships in this sector, access to detailed segmentation data, company profiles, and risk assessments is indispensable.
To fully leverage the 5.0 percent CAGR opportunity and navigate the competitive landscape defined by key players like WEIMA, Parason, and others, stakeholders need the complete intelligence picture. The full market research study provides the necessary depth on segmentation values, historical trends, and forecast nuances to build a robust strategy for the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Waste Paper Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ring Laser Gyroscope Market to Hit $10.9B by 2032, 9.2% CAGR
By PW Consulting, 2026-09-16
Navigating Precision: The Strategic Imperative of the Ring Laser Gyroscope Market in 2026
Introduction: The Precision Economy
In the landscape of modern navigation, stability is not merely a preference; it is a fundamental requirement for operational success. The Ring Laser Gyroscope, or RLG, stands as a cornerstone technology within this sector, enabling inertial navigation systems to maintain accuracy without reliance on external signals. As global industries increasingly depend on autonomous platforms, advanced aerospace systems, and secure naval operations, the demand for high-fidelity rotational sensing has escalated. This shift represents more than a technical evolution; it signals a substantial economic opportunity that demands rigorous analysis and strategic foresight.
For enterprise leaders operating in aerospace, defense, automotive, and marine sectors, understanding the trajectory of the RLG market is critical. The period extending from 2026 through 2032 promises to be a transformative era defined by technological maturation, supply chain realignment, and heightened competition. Our latest market research publication is designed to cut through the noise, offering a comprehensive view of where value is being created and how competitive dynamics are shifting. This article serves as a strategic primer, outlining the macro-economic currents and competitive forces that will define the landscape, while highlighting the depth of intelligence available in the full report.
Market Trajectory and Economic Scale
The financial magnitude of the Ring Laser Gyroscope sector underscores its importance as a strategic investment area. Historical data from 2020 through 2025 reveals a consistent upward trend, reflecting the gradual integration of RLG technology into more complex and demanding applications. The market valuation has demonstrated resilience and growth, culminating in a significant baseline as we enter the forecast period. Looking ahead, the revenue projections indicate a robust expansion trajectory that extends well into the next decade.
According to our analysis, the global market revenue is poised to grow from a established base in the mid-five billion USD range in 2026 to nearly eleven billion USD by 3032. This growth is not linear but reflects compounding demand drivers across multiple high-value industries. The Compound Annual Growth Rate during this forecast window is estimated at 9.2 percent, signaling a healthy velocity that outpaces many traditional industrial sectors. This rate suggests that capital allocated toward RLG-related technologies or capabilities has the potential for substantial return, provided the investment is targeted correctly within the value chain.
Laser Rangefinder Market
However, aggregate numbers only tell part of the story. The real strategic value lies in understanding the composition of this growth. The revenue stream is not uniform; it is distributed across varying technological configurations and end-use sectors, each with its own risk profile and growth potential. Decision-makers need to know which segments are driving the headline figures and which are lagging, without necessarily revealing the specific numerical breakdowns that could be used by competitors. Our full report dissects these variances, allowing clients to benchmark their position against the broader market rhythm without exposing sensitive comparative data publicly.
Competitive Landscape and Key Players
The structure of the RLG market is characterized by a moderate level of concentration, where a handful of specialized entities hold significant influence over supply chains and technological standards. With a CR3 concentration ratio hovering around 45 percent and a CR5 near 55 percent, the market remains accessible yet competitive. This structure implies that while large players set the tempo, there is room for specialized innovators and component suppliers to capture value through niche excellence. Understanding the identity and capability of these key players is essential for partnership strategy, procurement decisions, and competitive positioning.
Several companies have emerged as pivotal actors in this ecosystem, each contributing distinct value propositions. G&H Products, based in California, exemplifies the artisanal yet high-precision approach to manufacturing. They design and manufacture RLG frames and optical components by hand, supplying complete RLG component packages. Their operations are deeply entrenched in quality assurance, with facilities certified to ISO9001 and AS9100D standards. Furthermore, their compliance with ITAR legislation and registration with the US government underscores their role in the sensitive defense supply chain. By supplying entire component packages including Zerodur frames and precision mirrors, they occupy a critical upstream position that influences the final performance of the gyroscope.
On the optical component side, Excelitas Technologies Corp., headquartered in Pittsburgh, provides the foundational elements that make high-performance RLGs possible. Their precision mirrors and optics are optimized for RLG applications, achieving micro-roughness below 0.5 Angstrom and low scattering. These technical specifications are not merely marketing claims; they represent the physical limits required for maintaining laser cavity finesse, reported at levels up to 200,000. For system integrators seeking to minimize signal noise and maximize stability, the choice of optical supplier is a critical technical decision that impacts the entire navigation suite's reliability.
Completing the triad of innovation is Micro Magic, also based in the United States. They focus on developing and producing complete RLG-based inertial navigation systems, or INS. Their portfolio includes high-precision models tailored for defense and aerospace platforms. This vertical integration from component to system allows them to address end-user requirements directly. In late 2025, Micro Magic announced the launch of new solid-state RLG models, specifically the G-R90, G-R70, and G-R50. These launches target high-precision INS needs for defense and unmanned platforms, indicating a strategic pivot toward versatile, scalable solutions that can accommodate smaller unmanned aerial vehicles as well as larger defense assets. Tracking such product launches is vital for anticipating shifts in capability availability and pricing pressure.
Industry Dynamics and Supply Chain Considerations
The operational environment for RLG market participants is shaped by a complex interplay of regulatory, technological, and supply chain factors. For manufacturers operating in the United States, particularly those serving defense clients, regulatory compliance is not optional. The requirement to comply with ITAR legislation means that export controls and government registration are integral to business continuity. Companies like G&H Products maintain this status explicitly, which serves as both a barrier to entry for non-compliant competitors and a signal of reliability for government contractors. Understanding the regulatory landscape is necessary for assessing market accessibility and potential geopolitical risks that could disrupt supply.
Supply chain resilience is another critical dynamic. The production of an RLG requires specialized materials and precise manufacturing capabilities that are not easily commoditized. The use of materials like Zerodur for frames, supplied by key component vendors, highlights the dependency on specific material sciences. Any disruption in the supply of these high-grade materials can ripple through the production timeline. Our research delves into the sourcing strategies of major players, examining how they mitigate risk through vertical integration or long-term supplier partnerships. For procurement leaders, identifying single points of failure in the supply chain is a prerequisite for building robust inventory strategies.
Ring Laser Gyroscope (RLG) Market
Technological differentiation remains the primary battleground. While the basic physics of the ring laser gyroscope is established, incremental improvements in cavity performance, thermal stability, and size-weight-power profiles continue to drive market segmentation. The push toward solid-state models, as seen in recent developments, suggests a trend toward reduced maintenance and higher reliability, which is particularly valuable for unmanned systems that may lack onboard maintenance crews. Companies that can offer superior micro-roughness in optics or tighter tolerances in mechanical assembly gain a competitive edge that is difficult to replicate quickly. These technological moats are analyzed in depth to help clients understand where true differentiation lies versus where marketing hype may obscure reality.
Strategic Value for Enterprise Decision-Makers
Access to granular market intelligence provides a distinct advantage in formulation of corporate strategy. For investors, the projected revenue path offers a framework for valuation models, helping to determine whether current market sentiment aligns with fundamental growth drivers. For manufacturers, the segmentation data helps identify whitespace opportunities where competition is less intense but demand is growing. For defense contractors, understanding the supply chain positions of component providers like G&H Products or Excelitas ensures that sourcing strategies are aligned with long-term program requirements.
The full report goes beyond the macro trends summarized here. It provides detailed profiling of the ecosystem, mapping out the capabilities of key players against specific application needs. It examines the regulatory environment not just as a constraint but as a strategic filter that defines who can participate in high-value government contracts. The supply chain analysis extends to identifying potential bottlenecks and opportunities for vertical integration. Furthermore, the application analysis breaks down demand drivers across aerospace, marine, automotive, and other sectors, providing context on which industries are leading adoption and why.
Timing is also a critical component of strategic planning. With the forecast period extending to 2032, organizations need to plan capital expenditures and R&D investments today that will pay off in the latter half of the decade. Knowing when market maturity might lead to price compression allows companies to adjust their margin expectations and shift focus to service-based revenue or system integration. Conversely, identifying emerging segments early allows for first-mover advantages in securing supply contracts or intellectual property positions. The report is designed to support these timeline-dependent decisions with data that is both forward-looking and grounded in historical performance.
Conclusion: The Path Forward
The Ring Laser Gyroscope market stands at a pivotal intersection of technological capability and economic opportunity. The growth trajectory suggests that demand will continue to outpace supply in certain high-precision segments, creating leverage for established players while offering challenges for newcomers. The competitive landscape is defined by specialized firms that combine deep technical expertise with regulatory compliance, creating high barriers to entry that protect incumbents. For enterprise leaders, the ability to navigate this landscape depends on having access to accurate, detailed, and actionable intelligence.
This article has provided a high-level overview of the market dynamics, key participants, and structural factors influencing the sector. However, the true power of this research lies in the detailed data and specific strategic recommendations available in the full publication. To truly understand the nuances of the segmentation splits, the regional dynamics, and the specific financial projections required for robust planning, direct access to the comprehensive dataset is necessary. We invite stakeholders to explore the full report to equip their organizations with the insights needed to thrive in this evolving precision economy. Making informed decisions now will determine competitive positioning for the remainder of the decade and beyond.
For detailed analysis of this topic, please visit the official page: Ring Laser Gyroscope (RLG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Door Handle Sensor Market Hits $2.12B in 2025, Poised for 6.15% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Automotive Door Handle Sensors Market: Navigating the 2026–2032 Landscape
The automotive industry is undergoing a profound transformation in how vehicles are accessed, secured, and interacted with. At the heart of this evolution lies a seemingly minor component that carries outsized strategic importance: the door handle sensor. What was once a purely mechanical element has become a critical interface for keyless entry, gesture recognition, and hands-free operation, particularly in electric vehicle platforms where flush and hidden handle designs are increasingly preferred. To support executives, product strategists, and investment analysts in making informed decisions throughout 2026, we have assembled a comprehensive market study on the Automotive Door Handle Sensors Market. This article offers a focused preview of the research, highlights its strategic value, and outlines the operational intelligence contained within the full report.
Why 2026 Marks a Defining Moment for Door Handle Sensor Strategy
The base year of 2025 established a market valuation of approximately 2.12 billion USD, and the trajectory through the forecast window points to steady, compounding expansion. By 2032, the market is projected to reach roughly 3.22 billion USD, reflecting a compound annual growth rate of 6.15 percent over the 2026–2032 period. These figures are not merely backward-looking statistics; they signal a structural shift in vehicle architecture, consumer expectations, and regulatory scrutiny. Automotive door handles are no longer passive hardware. They are becoming integrated sensing nodes that must satisfy demands for reliability, aesthetics, user convenience, and, increasingly, safety compliance.
For decision-makers in 2026, the strategic question is no longer whether door handle sensors will become standard, but how quickly portfolios can adapt to varying sensor technologies, regional regulatory timelines, and OEM customization requirements. The market study is designed to give leaders a clear line of sight into these dynamics, enabling resource allocation that is aligned with long-term revenue opportunities rather than reactive to short-term fluctuations.
What the Research Delivers: Actionable Intelligence Beyond Headline Numbers
The study is built for practical application. It maps the market across sensor types, end-use applications, and geographic regions, while also examining concentration levels among leading suppliers. Rather than presenting static tables, the report translates data into strategic context, helping teams assess where growth is most durable, which applications are gaining traction, and how regional demand profiles differ in pace and character.
Below is a structured preview of the report’s core analytical sections:
- Market sizing and growth trajectory: A multi-year view from historical baseline years through the full forecast period, supporting planning for capacity, investment, and product roadmap decisions.
- Technology segmentation analysis: An evaluation of capacitive, infrared, ultrasonic, and other sensing approaches, with attention to integration complexity, false-trigger resistance, power consumption, and suitability for compact door handle designs.
- Application-driven demand mapping: A breakdown of how keyless entry systems, power door systems, and gesture control systems are shaping sensor requirements across different vehicle segments and OEM priorities.
- Regional demand patterns: A comparative look at how North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa contribute to overall market expansion, with implications for localization, supply planning, and market-entry timing.
- Competitive landscape and concentration: An assessment of market share distribution among leading participants, highlighting the degree of consolidation and the strategic room available for differentiation.
- Regulatory and safety dynamics: A review of policy developments that are reshaping engineering requirements, particularly around hidden or flush door handle designs in electrified platforms.
- Recent industry developments: A timeline-based synthesis of product launches, standards approvals, and investigative activity that are influencing near-term procurement and engineering decisions.
Each section is designed to be referenced independently or read as part of an integrated strategy narrative. The objective is to give automotive suppliers, tier-1 component developers, OEM strategy teams, and investors a reliable basis for scenario planning, risk assessment, and prioritization.
Sensor Technology Choices and the Real-World Trade-Offs They Create
Sensor selection in door handle applications is not a purely technical decision; it is a commercial one. The report examines how different sensing modalities align with distinct vehicle requirements and user experience goals. Capacitive sensing continues to attract strong interest for its ability to support sleek, flush-mounted designs and low-profile integration, especially when combined with gesture recognition and improved resistance to false triggers. Infrared-based solutions offer attractive proximity detection characteristics and can be well suited to specific detection ranges and environmental conditions. Ultrasonic approaches provide an additional pathway for hands-free activation, with relevance to both premium and mass-market vehicle programs. A broader category of alternative sensor designs also exists, often tailored to specialized use cases or OEM-specific integrations.
What matters strategically is that no single technology is universally optimal. The right choice depends on vehicle platform, power budget, aesthetic targets, cost constraints, and the intended user interaction model. The study helps decision-makers compare these trade-offs in a structured way, so that product planning teams can anticipate where demand will concentrate and how supplier capabilities will need to evolve.
Applications Are Reshaping Demand, Not Just Component Specs
Door handle sensors are being deployed across multiple functional domains, and each application creates a different demand profile. Keyless entry systems remain a major driver, reflecting the broader industry movement toward seamless access and digital key ecosystems. Power door systems introduce additional requirements for reliable detection, actuation coordination, and failure-mode resilience. Gesture control systems represent a more advanced interaction layer, particularly relevant where interior and exterior interfaces are being redesigned to support touchless operation and intuitive user experiences.
Automotive Door Handle Sensors Market
These application categories do not grow in isolation. Their adoption patterns are influenced by vehicle segment strategy, regional consumer preferences, electrification roadmaps, and the pace at which OEMs are willing to standardize new interaction models. The report analyzes how these forces interact, enabling readers to gauge which application areas are likely to generate the most consistent demand and which may remain more niche or region-specific over the forecast window.
Competitive Dynamics and the Shape of Market Leadership
The industry is shaped by a group of established players with distinct technical strengths and integration philosophies. NXP Semiconductors brings automotive NFC door handle reference designs and solutions optimized for compact integration. Melexis contributes Hall effect and low-power sensor solutions, including door handle wake-up switches and e-door handle applications. Continental AG has developed capacitive door handle sensor modules with features such as gesture recognition and enhanced false-trigger resistance. Valeo SA supplies ultrasonic-based flush handle sensor systems for hands-free activation across luxury and mass-market vehicles. Infineon Technologies supports door handle detection and control through microcontrollers and sensor ICs for proximity and position sensing. NMB Technologies Corporation manufactures vehicle door handle systems with integrated sensor solutions for OEM customization, including sensing and lighting. ADAC Companies provides vehicle access systems with integrated sensing technologies, capacitive sensors, and microswitches in exterior door handles and trim.
Taken together, these participants illustrate a competitive environment where differentiation is increasingly tied to integration quality, reliability, and the ability to meet OEM-specific design requirements. The report further examines market concentration indicators to provide a clearer picture of how consolidated the field is and where new entrants or niche solutions may still find room to compete.
Regulation, Safety, and the New Compliance Imperative
Regulatory developments are becoming a decisive factor in product planning. In January 2026, China’s Ministry of Industry and Information Technology approved the mandatory national standard GB 48001-2026, Safety Technical Requirements for Automotive Door Handles. The standard addresses safety concerns associated with hidden or flush door handle designs, particularly in electrified vehicle architectures. New vehicle type approvals must comply fully from January 1, 2027, with a transition period extending to January 1, 2029 for previously approved vehicles. This regulatory move reflects a broader scrutiny of electronic door release reliability and signals that safety performance will be a major engineering and procurement consideration in the near term.
At the same time, investigative coverage in the United States has drawn attention to potential defects in electronic door releases in certain Tesla models, with reports of occupants trapped and fatalities linked to crashes where doors would not open. While each case involves specific technical and legal contexts, the cumulative effect is clear: consumer safety, fail-safe design, and verifiable reliability are moving to the foreground of automotive access-system discussions. These dynamics create both risk and opportunity. Suppliers that can demonstrate robust safety performance, transparent validation, and compliance readiness may gain a meaningful advantage in OEM evaluations.
Recent Developments That Are Already Shaping Procurement and Roadmaps
The report incorporates recent events that are actively influencing market direction. In January 2026, both regulatory approval activity and high-profile safety investigations reinforced the importance of dependable door handle sensing and release mechanisms. Then, in February 2026, Continental AG introduced a new capacitive door handle sensor module featuring integrated gesture recognition and improved false-trigger resistance for premium EV platforms. This launch highlights the accelerating focus on user experience, false-trigger mitigation, and electrification-aligned design. Such developments are not isolated news items; they are indicators of how product roadmaps, qualification processes, and buying criteria are shifting in real time.
Automotive Door Handles Market
How to Use This Research for 2026 Decision-Making
The strategic value of the full study lies in its ability to convert market signals into executable insight. The report is intended to support several concrete decisions, including:
- Portfolio prioritization: Determining which sensor technologies and application segments deserve the greatest engineering and commercial focus in the coming years.
- Regional planning: Aligning supply, localization, and market-entry strategies with region-specific demand patterns and regulatory timelines.
- Competitive benchmarking: Understanding where leading suppliers are concentrating their capabilities and where differentiation opportunities remain.
- Risk management: Anticipating safety-related compliance requirements and integrating them into product validation and procurement strategies.
- Investment and partnership decisions: Identifying where long-term market growth is most credible and which capability gaps may create collaboration or acquisition opportunities.
Completing the Picture: Accessing the Full Market Intelligence
This article provides a structured overview of the themes, growth path, and competitive context that define the Automotive Door Handle Sensors Market. However, the full report contains the detailed sizing framework, segmentation comparisons, regional breakdowns, competitive profiles, and operational guidance needed to turn these themes into precise strategic actions. For teams planning product launches, capacity decisions, supplier negotiations, or market-entry assessments in 2026, the complete dataset and analytical commentary offer the depth required to reduce uncertainty and support confident choices.
To access the full market research and obtain the complete segmentation detail, regional analysis, and company-level intelligence, visit the official report page. The complete study is designed to serve as a working reference for strategic planning throughout the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Automotive Door Handle Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


