



PW Consulting: Golf Tourism Market Hits $187.04M in 2025, Projected to Surge at 9.1% CAGR by 2032
By PW Consulting, 2026-09-16
The Strategic Imperative of Golf Tourism in 2026: Navigating a High-Growth Landscape
The global golf tourism industry stands at a critical inflection point. As we move beyond the post-pandemic recovery phase, the sector has transformed from a niche leisure segment into a robust economic driver with complex interdependencies across hospitality, travel services, and regional development. For executives, investors, and strategic planners, understanding the trajectory of this market is no longer optional—it is a prerequisite for capital allocation, partnership formation, and competitive positioning.
Our latest comprehensive market research on the Golf Tourism Market is designed to serve as a decision-making compass for 2026 and beyond. This article provides a preview of the analytical depth and strategic frameworks contained within the full report, highlighting the macro trends, competitive shifts, and structural dynamics that will define the industry over the next seven years.
Market Trajectory: From Recovery to Sustained Expansion
The historical data from 2020 through 2025 reveals a story of resilience and accelerating momentum. Following the disruptions of 2020, the industry demonstrated a rapid rebound, with revenue climbing steadily each subsequent year. By the base year of 2025, the global market had established a firm foundation, setting the stage for a pronounced growth phase.
Looking ahead, the forecast period from 2026 to 2032 projects a compelling expansion curve. The market is expected to deliver a compound annual growth rate of 9.1 percent, propelling total revenue from approximately 206.92 million USD in 2026 to an estimated 342.53 million USD by 2032. This trajectory signals more than just linear growth; it indicates a structural broadening of the golf tourism ecosystem, driven by new infrastructure investments, resort package innovations, and a recalibration of traveler preferences toward experiential leisure.
For corporate strategists, these figures are not merely background statistics. They represent a shifting window of opportunity. The speed of expansion suggests that market entry timing, capacity planning, and partnership agreements forged in 2026 will have disproportionate impacts on share capture by the end of the decade. Early movers who align their service portfolios with the projected demand curves will secure advantages that late entrants will struggle to replicate.
Golf Tourism Market
Key Structural Themes Shaping the Forecast
The growth narrative is underpinned by several interconnected dynamics that our research dissects in detail:
- Resort Package Expansion: The bundling of golf experiences with accommodation, dining, and leisure activities has become a primary revenue accelerator. Operators who integrate seamless stay-and-play models are capturing higher per-capita spend and longer booking windows.
- Infrastructure Investment: New course developments, modernization of existing facilities, and enhanced transport linkages are lowering barriers to access in emerging destinations, effectively enlarging the addressable market.
- Cultural and Sustainable Travel: Golf tourism is increasingly recognized as a vehicle for cultural exchange and sustainable practices. Travelers are seeking destinations that offer not only championship play but also local immersion, environmental stewardship, and community engagement.
- Operator-Dependent Booking Channels: A significant portion of golf tourism bookings continues to flow through specialized tour operators, highlighting the enduring importance of B2B distribution networks and curated travel packages.
- Government Incentives: Policy interventions, including tax breaks and targeted infrastructure support, are actively bolstering operator confidence and encouraging destination-level investment in golf tourism infrastructure.
Competitive Landscape: Diversification and Strategic Positioning
The golf tourism market is characterized by a moderately fragmented competitive structure, with a handful of leading players commanding notable but not overwhelming market shares. The top three companies collectively hold a combined market concentration of 24.5 percent, while the top five account for 28.7 percent. This concentration level suggests that while established brands retain influence, there is substantial room for regional specialists, boutique operators, and hospitality giants to differentiate through service quality, destination expertise, and digital integration.
Specialized Golf Travel Operators
A distinct tier of companies has built its identity around curated golf travel experiences. These firms compete on destination breadth, bespoke itineraries, and tournament access.
- PerryGolf operates out of Wilmington, North Carolina, and distinguishes itself through year-round golf and travel experiences spanning more than forty countries across six continents. Its value proposition blends world-class golf with iconic sightseeing and boutique accommodation, appealing to travelers who view golf as part of a broader cultural itinerary.
- Golfbreaks , headquartered in Windsor, Berkshire, focuses on customized golf breaks, holidays, and tournaments paired with 5-star resorts and online tee-time booking functionality. Its model emphasizes convenience, luxury accommodation, and the ability to organize competitive or social tournament formats.
- Your Golf Travel leverages a digital-first approach from London, offering golf holidays and breaks to over 3500 destinations across 24 countries. Its competitive edge rests on guaranteed best prices, app-based rewards, and a broad destination catalog that caters to both casual and dedicated golfers.
- Carr Golf , based in Dublin, positions itself in the premium segment with bespoke luxury golf trips tailored for Ireland, Scotland, and the world's finest golf destinations and tournaments. Its offering targets high-net-worth travelers and groups seeking personalized, high-touch service.
Hospitality and Resort Giants
Major hotel and resort groups have integrated golf into their broader leisure and business portfolios, using championship courses and tee-time access as differentiators within their brand ecosystems.
- Hilton Worldwide Holdings Inc. incorporates golf resorts and hotels with Stay and Play packages, championship courses, and tee-time access at iconic locations. Its scale and loyalty program infrastructure enable cross-selling and repeat visitation across global properties.
- Marriott International Inc. features golf resorts with championship courses, vacation packages, and amenities such as professional lessons and clubhouse dining. Its strategy emphasizes the full guest journey, from booking to on-course experience to post-round hospitality.
- Club Med SAS offers integrated golf and resort packages at all-inclusive destinations, combining on-site courses with a broader suite of leisure activities. This model appeals to families and groups seeking a self-contained vacation experience.
- Accor S.A. provides luxury resorts with direct access to prestigious golf courses under its ALL - Accor Live Limitless collection, positioning golf access as a premium perk within a larger lifestyle and hospitality brand.
- TUI Group delivers golf holidays and packages that pair hotels and villas near top courses in destinations such as Turkey, Spain, and the Algarve. Its strength lies in destination expertise, volume capabilities, and integrated travel logistics.
These competitive archetypes illustrate a market where specialization and scale coexist. Specialized operators compete on authenticity, itinerary depth, and destination knowledge, while hospitality giants leverage brand 신뢰, loyalty ecosystems, and property networks. The full report maps these competitive positions against regional demand patterns, price sensitivities, and service-level expectations to identify where strategic convergence and disruption are most likely to occur.
Industry Events and Recent Developments as Strategic Signals
Recent events in 2026 provide tangible indicators of where attention, capital, and partnerships are flowing within the golf tourism sector.
In May 2026, the European Golf Tourism Convention in Málaga City broke IAGTO records, drawing unprecedented attendance and registrations. This surge signals strong industry appetite for networking, partnership formation, and knowledge exchange in the European market. The convention's scale suggests that stakeholders are actively preparing for continued growth and are seeking structured platforms to align on standards, distribution, and destination marketing.
Earlier in the year, in March 2026, IAGTO announced that the Asia Golf Tourism Convention will head to Kuala Lumpur in 2027 as a record-setting event. This development underscores the rising strategic importance of Asia Pacific as a destination hub and a source market for golf travel. The decision to host a record-scale convention in Kuala Lumpur reflects confidence in the region's infrastructure readiness, demand growth, and potential for cross-border golf tourism collaborations.
On the operational side, January 2026 saw Hyatt announce the reopening of Secrets Playa Mujeres Golf & Spa Resort following renovation. This move highlights the ongoing investment in property refreshes and experience upgrades, reinforcing the notion that golf-adjacent hospitality assets are being positioned for premium segments that value both course quality and resort amenities.
Together, these developments paint a picture of an industry that is actively reinvesting in its physical and relational infrastructure. For decision-makers, they serve as leading indicators of where competitive intensity will rise, where new partnership opportunities may emerge, and which geographic markets are attracting disproportionate industry focus.
Strategic Considerations for 2026 Decision-Makers
The intersection of macro growth, competitive diversification, and event-driven momentum creates a complex environment for strategic planning. Our research translates these dynamics into actionable frameworks across several dimensions:
Market Entry and Expansion Timing
With the forecast indicating sustained double-digit momentum through 2032, the question for many organizations is not whether to engage with golf tourism, but how and where to deploy resources. Timing matters. Destinations and operators that secure distribution agreements, course partnerships, or resort integrations in 2026 can lock in favorable positioning before demand outpaces supply in high-growth corridors. Conversely, delayed moves risk entering markets where pricing power has shifted and customer acquisition costs have risen.
Segmentation Strategy and Value Capture
The revenue base is distributed across leisure, business, and tournament golf tourism, as well as across domestic and international tourist flows. While we do not disclose granular split percentages here, the full report provides a detailed breakdown of how these segments interact with pricing elasticity, booking lead times, and service expectations. For operators, the strategic challenge lies in aligning product offerings with the right segment mix. Leisure-focused resorts may prioritize package bundling and family-friendly amenities, while business and tournament segments may demand premium scheduling flexibility, meeting facilities, and high-touch concierge services. Understanding which segments drive margin versus volume is essential for portfolio design.
Regional Dynamics and Destination Positioning
Golf tourism demand is not evenly distributed. Certain regions benefit from established course networks, favorable climate conditions, and mature travel infrastructure, while others are accelerating due to targeted investments and policy support. Government initiatives, such as tax incentives and infrastructure programs, are actively shaping the competitive attractiveness of specific destinations. The full report evaluates how these regional factors influence inbound travel patterns, operator location decisions, and the relative bargaining power of destination marketing organizations versus private operators.
Competitive Positioning and Partnership Architecture
Given the moderate market concentration, partnerships and alliances are becoming increasingly important. Specialized tour operators can add value for hospitality groups seeking to fill tee times and rooms during off-peak periods, while hotel chains can leverage their loyalty bases to drive volume to golf destinations. The report analyzes how leading companies are structuring their offerings, where digital booking and app-based rewards are creating differentiation, and which partnership models are most effective in converting interest into booked revenue.
Risk Awareness and Resilience Planning
Growth brings complexity. Operators must navigate seasonality, weather dependency, geopolitical shifts affecting travel flows, and evolving consumer preferences around sustainability and authenticity. The report incorporates scenario-based considerations to help organizations stress-test their strategies against demand variability, input cost fluctuations, and changes in regulatory or tax environments. Building resilience into pricing models, distribution channels, and destination diversification is a recurring theme for firms aiming to sustain performance through cyclical fluctuations.
Why the Full Report Matters for 2026 Strategy
market intelligence is only as valuable as its relevance to concrete decisions. This Golf Tourism Market research goes beyond high-level sizing to deliver the operational detail that strategy teams need when evaluating investments, partnerships, and service expansions.
The full publication includes deep dives into segmentation structures, regional demand drivers, competitive benchmarking, and forward-looking scenario analysis. It maps how resort package growth, infrastructure investments, and operator distribution models are reshaping the revenue landscape. It also provides context on how consumer habits—such as the preference for culturally immersive travel, sustainable practices, and operator-mediated bookings—are influencing product design and marketing strategies.
Worldwide Culinary Tourism Market
For executives tasked with setting 2026 priorities, the report offers a structured way to assess where to commit resources, which customer segments warrant dedicated offerings, and how to position against both specialized golf travel firms and large hospitality brands. It is designed to reduce uncertainty in capital allocation, guide partnership targeting, and inform product development roadmaps.
Conclusion: Acting with Precision in a Growing Market
The golf tourism sector in 2026 presents a rare combination of strong macro momentum, diverse competitive playbooks, and clear signals from industry events and infrastructure investments. The projected growth path, anchored by a 9.1 percent CAGR through 2032, indicates that the market will continue to expand in both scale and sophistication. Yet growth alone does not guarantee success. The organizations that thrive will be those that combine data-informed market understanding with disciplined execution, thoughtful segmentation, and strategic partnerships.
This introduction has outlined the strategic contours of the landscape. The complete market research fills in the analytical details that turn high-level trends into actionable plans. For decision-makers ready to move from awareness to execution, the full report provides the depth required to act with precision. We invite you to access the complete publication to explore the segmentations, competitive profiles, regional insights, and strategic recommendations that will inform your 2026 golf tourism strategy.
For detailed analysis of this topic, please visit the official page: Golf Tourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fused Magnesia Sales Hit $1.89B in 2025, Projected to Grow at 5.6% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Decade Ahead: Why the 2026 Fused Magnesia Outlook Demands Immediate Executive Attention
The global fused magnesia market is entering a phase of structural redefinition. As industries grapple with tightening supply chains, evolving regulatory frameworks, and shifting demand vectors, the need for precise, forward-looking intelligence has never been more critical. Our newly released 2026 Fused Magnesia Market Research Report delivers exactly that: a comprehensive, data-grounded, and strategically actionable analysis designed to equip corporate leaders, procurement directors, and market strategists with the clarity required to navigate the forecast period from 2026 through 2032.
This executive preview outlines the foundational insights embedded in our study, demonstrates how historical trajectories and forward-looking indicators converge to shape near-term decision-making, and reveals the analytical architecture that will guide your organization through an increasingly complex market landscape. We deliberately reserve granular segmentation forecasts and proprietary modeling outputs for the full report, because strategic success depends not only on knowing where the market is heading, but on understanding the underlying mechanics that will determine competitive advantage.
The Macro Trajectory: Historical Resilience Meets Forecasted Expansion
Over the past half-decade, the global fused magnesia sector has demonstrated remarkable resilience, outpacing several downstream commodity benchmarks while absorbing geopolitical friction, energy price volatility, and downstream capacity realignments. Historical data from 2020 through 2025 captures a market that steadily rebuilt momentum after initial pandemic-era disruptions, translating structural demand from core industrial applications into consistent revenue growth. By the close of the base year, the market reached an estimated valuation of approximately 1.885 billion USD, reflecting a compound trajectory that underscores the material's entrenched role across heavy industry, advanced ceramics, and specialized refractory systems.
Looking forward, our analysis projects that this expansion will continue its upward cadence, with the market advancing toward a valuation of roughly 2.730 billion USD by the terminal year of our forecast window. Driving this progression is a forecasted compound annual growth rate of 5.6 percent, a figure that encapsulates both baseline industrial demand and the incremental pull from capacity optimization initiatives, high-performance material substitution, and regional supply chain restructuring. The growth curve is neither linear nor uniform. It is shaped by the interplay of raw material consolidation, trade policy recalibration, and the steady migration toward higher-purity specifications in applications that demand superior thermal stability and chemical inertness.
For decision-makers, the implication is clear: the market is large enough to attract sustained capital allocation, yet dynamic enough to reward organizations that anticipate structural inflection points rather than react to them after they materialize.
Structural Drivers and Market Concentration Dynamics
The fused magnesia ecosystem is characterized by a concentrated yet increasingly competitive landscape. Our assessment indicates that the top three participants command approximately 52 percent of total market share, while the top five collectively represent around 68 percent. This concentration level signals an industry where scale, integrated supply chains, and technical differentiation remain decisive competitive moats. Yet it also suggests that mid-tier producers, regional specialists, and vertically aligned operators are actively carving out defensible positions through application-specific grading, logistics optimization, and strategic partnerships with downstream users.
Several macroeconomic and industrial forces are reinforcing demand durability. The steel and iron sector continues to anchor a substantial portion of consumption, driven by sustained production requirements, refractory lining upgrades, and the broader push toward extended campaign life in high-temperature processing environments. At the same time, emerging applications across advanced ceramics and glass manufacturing are reshaping specification requirements, with end-users increasingly prioritizing consistency, purity thresholds, and customized particle profiles over commoditized bulk supply. Construction-related utilization, though comparatively smaller in absolute terms, continues to provide baseline demand stability as infrastructure programs and building material formulations evolve in response to performance and regulatory considerations.
The market is therefore not merely expanding; it is bifurcating. High-purity segments are attracting premium valuation dynamics and long-term supply commitments, while medium-purity grades remain essential for cost-sensitive bulk applications. Understanding how these layers interact, where substitution risks emerge, and how pricing architecture responds to energy and feedstock variability is central to any credible strategic forecast. Our report isolates those dynamics and maps them against actionable procurement and capacity-planning scenarios.
Policy, Trade, and Supply-Side Realignment: A Landscape in Motion
No contemporary market assessment can be complete without grappling with the regulatory and trade environment shaping input costs, market access, and competitive positioning. Recent developments underscore that fused magnesia is no longer a purely commercial commodity; it is also a product of policy intervention, trade defense measures, and localized consolidation mandates.
One of the most consequential supply-side trends involves the ongoing consolidation of magnesite mining operations in key producing regions. Between 2020 and 2024, the number of active magnesite-mining enterprises in Liaoning declined from 114 to 63, with further consolidation anticipated to bring the total to approximately 56 operators by the end of 2025. This trajectory reflects a deliberate move toward operational scale, environmental compliance, and output coordination. In parallel, provincial guidance in China has emphasized sector-wide output consolidation, signaling that future supply will be increasingly determined by a smaller number of coordinated producers with enhanced control over feedstock availability and pricing.
Trade policy is equally transformative. The U.S. Department of Commerce initiated an antidumping investigation on imported dead burnt magnesite, while the U.S. International Trade Commission voted unanimously to continue the existing antidumping duty order on fused magnesia originating from China. Meanwhile, the Magnesite Association of India filed a petition alleging dumping of dead burnt magnesite from the People's Republic of China, highlighting how trade remedies are becoming a recurring feature of the global refractory raw material landscape. These actions are not isolated; they form a pattern that will influence sourcing strategies, regional cost structures, and the geography of competitive advantage.
Organizations that treat trade measures as peripheral risk factors will likely encounter costly supply disruptions or margin erosion. Those that integrate policy trajectories into procurement diversification, inventory architecture, and regional capacity planning will be better positioned to absorb shocks and capture relative pricing power.
Competitive Architecture: Who Shapes the Market and How
The competitive environment surrounding fused magnesia is defined by a blend of globally integrated incumbents, regionally anchored specialists, and application-focused producers. Our report examines the strategic postures, operational footprints, and positioning strategies of key market participants, including:
Fused Magnesia Market
- RHI Magnesita , headquartered in Vienna, Austria, which operates as a global leader in high-grade refractory products. With fused magnesia production and system-level solutions spanning more than 35 sites, the company serves steel, cement, glass, and non-ferrous metals industries. Its scale and integrated product portfolio make it a benchmark for downstream alignment and technical service differentiation.
- Grecian Magnesite S.A. , based in Athens, Greece, which specializes in magnesite products and grades including fused magnesia for refractories, electrical applications, and industrial uses. Its positioning reflects a focus on specialty-grade consistency and export-oriented distribution networks.
- Kumas Manyezit Sanayi A.Ş. , operating from Kütahya, Turkey, which manufactures refractory materials including fused magnesia and magnesite for industrial applications. Its regional manufacturing footprint provides supply agility and proximity advantages for European and nearby downstream markets.
- Baymag Inc. , headquartered in Calgary, Alberta, Canada, which acts as an integrated producer of magnesium oxide, including fused magnesia derived from its Canadian magnesite deposit. This vertical integration from deposit to processed output supports supply reliability and specification control for refractory and industrial uses.
- Premier Magnesia, LLC , located in Gabbs, Nevada, United States, which is recognized as a global leader in magnesia-based products with natural magnesia supply and processing capabilities for industrial applications. Its North American footprint and feedstock access provide strategic relevance in the context of trade flows and domestic sourcing initiatives.
- Nedmag B.V. , based in the Netherlands, which produces high-purity magnesium oxide products including dead-burned and fused magnesia for refractories and specialty uses. Its emphasis on purity and specialty-grade output aligns with high-value application requirements.
- Martin Marietta Magnesia Specialties , operating in the United States, which supplies high-purity magnesium oxide products including specialty grades for refractory and industrial applications. Its portfolio reflects a focus on performance-grade differentiation and downstream technical support.
- Niche Fused Magnesia Ltd , based in Hull, United Kingdom, which supplies fused magnesia for industrial and refractory applications. As a more specialized participant, its role illustrates how targeted market niches can sustain viable competitive positions without relying solely on scale.
Beyond company profiles, our analysis evaluates the strategic logic underpinning each player's positioning: where integration confers resilience, where geographic proximity drives logistics advantage, and where technical service capabilities create switching costs for end-users. The report also examines how these participants are likely to respond to consolidation pressures, trade remedy developments, and evolving purity requirements. In a market where the top five players already account for a substantial share of revenue, competitive differentiation increasingly depends on supply security, application engineering, and the ability to align product specifications with downstream process optimization.
What the Full Report Delivers: Operational Intelligence, Not Just Forecasts
Market data alone does not generate competitive advantage. The value of a research study lies in how effectively it translates complex signals into executable strategy. Our 2026 Fused Magnesia Market Report is built around that principle. It goes beyond headline growth figures to provide a structured toolkit for decision-makers across procurement, production planning, investment evaluation, and market entry analysis.
The report is organized to support multiple strategic use cases. It maps the historical performance of the market from 2020 through the 2025 base year, establishing a credible baseline against which forecast assumptions are tested. It then extends the analysis through 2032, incorporating segment-level demand patterns, purity-grade evolution, application-driven specification shifts, and regional supply chain considerations. Importantly, it connects these elements to operational implications rather than leaving them as abstract projections.
Readers will find detailed coverage of:
- The structural composition of demand across major application categories, including the relative weight of steel and iron processing, ceramics and glass manufacturing, and construction-related utilization, along with the qualitative drivers that determine how these shares evolve over time.
- How purity segmentation shapes pricing behavior, customer loyalty, and capacity allocation, with attention to the diverging requirements of high-purity and medium-purity value chains.
- Regional demand architecture and the strategic significance of geographic concentration, logistics corridors, and cross-border trade flows, analyzed in a way that helps organizations evaluate sourcing options without relying on static rankings.
- The competitive posture of leading producers and the operational levers that differentiate them, including integration depth, specialty-grade capabilities, and downstream application support.
- Regulatory and trade developments that alter cost structures and market access, with scenario-based considerations for procurement and supply continuity planning.
- Material consolidation trends and their implications for raw material availability, pricing volatility, and long-term contract strategy.
- Forward-looking indicators that signal where demand intensity is likely to intensify, where substitution pressures may emerge, and where investment or capacity decisions carry the highest strategic payoff.
By aligning quantitative trajectory analysis with qualitative industry mechanics, the report is designed to be referenced repeatedly throughout planning cycles. It supports budgeting precision, supplier evaluation, risk mitigation, and competitive positioning without requiring readers to reconstruct the underlying logic from disparate sources.
White Fused Alumina Market
Why This Research Matters for 2026 Decision-Making
The 2026 to 2032 window is not simply a continuation of past trends. It is a period in which the fused magnesia market will be shaped by simultaneous forces: sustained industrial demand, increasing emphasis on material performance, policy-driven consolidation, and trade measures that redraw sourcing maps. Organizations that treat these forces as background noise will likely find themselves reacting late, paying premium prices, or committing to supply arrangements that no longer match market realities.
Conversely, firms that ground their strategies in a rigorous, scenario-aware analysis will be better equipped to negotiate long-term contracts from a position of understanding, diversify sourcing without sacrificing reliability, and identify where purity upgrades or application-specific support can command favorable commercial terms. The strategic question is no longer whether the market will grow; it is how each organization will position itself to capture value as growth unfolds unevenly across segments, regions, and competitive tiers.
Our full report provides the depth, structure, and actionable framing required to answer that question with confidence. It is intended for leaders who need a single, coherent reference point that integrates market sizing, competitive assessment, regulatory context, and forward-looking demand logic into one analytical platform.
Access the Complete Intelligence
This preview has outlined the strategic rationale, high-level market trajectory, competitive architecture, and policy environment that form the foundation of our analysis. It has also made clear that the market's future is not defined by a single metric, but by the interaction of purity requirements, application dynamics, consolidation patterns, and trade policy. To move from directional understanding to decision-ready intelligence, however, organizations need the full scope of segmentation logic, scenario detail, and competitive evaluation that only the complete study can provide.
We invite executives, strategy teams, and procurement leaders to access the full 2026 Fused Magnesia Market Report for comprehensive data, detailed forecasting architecture, and the operational insights required to translate market momentum into competitive advantage. In a sector where timing, specification alignment, and supply resilience determine outcomes, the right intelligence is not an accessory to strategy. It is the foundation of it.
For detailed analysis of this topic, please visit the official page: Fused Magnesia Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Specialty Carbon Black Market to Reach $400M by 2032, Driven by 6.5% CAGR
By PW Consulting, 2026-09-16
Specialty Carbon Black Market Strategic Outlook 2026: Navigating Growth, Volatility, and Competitive Shifts
The specialty carbon black sector is entering a defining phase. As industrial formulations grow more complex and sustainability mandates tighten across major economies, decision-makers require more than backward-looking summaries. They need a forward-looking, data-grounded view of where value is shifting, which applications will absorb incremental capacity, and how leading producers are repositioning their portfolios against feedstock volatility and regulatory pressure. Our latest Specialty Carbon Black Market study is built precisely for that moment. Covering the historical window from 2020 through 2025 and extending forecasts to 2032, the analysis gives procurement leaders, strategy teams, and investors a structured lens on a market projected to reach a 2026 valuation of 270.77 million USD, up from 255.0 million USD in 2025, and to expand steadily toward 400.0 million USD by 2032. This translates to a forecast-period CAGR of 6.5 percent, a pace that signals durable demand but also rewards players who can read the fine print behind the headline numbers.
The report is designed as a decision-support instrument rather than a static market snapshot. It maps how historical inflection points between 2020 and 2025 set the stage for the current cycle, then translates those patterns into actionable scenarios for 2026 and beyond. Readers will find a disciplined breakdown of market architecture by region, type, and application, alongside a focused competitive profile of the organizations shaping pricing, capacity, and product differentiation. Equally important, the study embeds the operational realities that now govern margin outcomes: feedstock cost dynamics, compliance expenditures, and the strategic moves producers are already making to protect or expand their positions.
Why This Study Matters for 2026 Decision-Making
2026 is not a typical baseline year. Companies are operating in an environment where raw material volatility, environmental compliance, and regional capacity shifts are interacting at the same time. The specialty carbon black market reflects that convergence. Over the historical period, the sector moved from 180.0 million USD in 2020 to 255.0 million USD in 2025, a trajectory that underscores consistent expansion but also hides the uneven pace of growth across end-use sectors and geographies. The forward view shows continued uplift, with the market expected to reach 287.83 million USD in 2027, 311.24 million USD in 2028, and 335.4 million USD in 2029 before crossing toward 376.68 million USD in 2031 and 400.0 million USD in 2032.
For executives, the strategic question is not whether the market is growing, but where the growth is structurally concentrated and how to position for it. The study helps answer that by separating signal from noise. It shows how overall momentum is being shaped by a handful of high-value application areas and by regional demand centers that differ in both scale and maturity. It also highlights the competitive reality that market share is not evenly distributed: the top three players account for approximately 55.0 percent of the market, while the top five reach about 68.0 percent. That concentration has real implications for pricing power, contract negotiation, and supply security, especially when leading producers adjust their commercial terms or introduce surcharge mechanisms.
This is exactly why the report is framed around operational relevance. Rather than presenting isolated figures, it connects market size and growth to the decisions that matter in 2026: how to plan for feedstock uncertainty, which product families deserve closer evaluation, how regional demand centers compare in absolute scale, and where competitive intensity is likely to rise as new capacity and import-substitution dynamics take hold.
Market Architecture at a Glance
A clear view of market structure is essential for prioritizing resource allocation and risk management. The study organizes the landscape across three core dimensions, giving readers a structured way to interpret demand, supply, and segmentation without obscuring the differences that drive strategic advantage.
Regional Scale and Demand Patterns
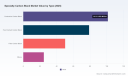
The regional view places absolute market scale in context. Asia Pacific stands as the largest regional market at 96.05 million USD, followed by North America at 66.87 million USD, Europe at 46.51 million USD, Latin America at 30.43 million USD, and the Middle East and Africa at 15.14 million USD. These figures make the geographic hierarchy explicit while leaving room for the report's deeper discussion of growth rates, demand drivers, and local supply conditions. In practice, that means procurement and expansion planning can be anchored in relative market size while still accounting for the distinct regulatory, manufacturing, and logistics realities that differ from one region to another.
Product Families and Value Positioning
On the type side, conductive carbon black leads at 101.31 million USD, with food contact carbon black at 78.81 million USD, fiber carbon black at 50.18 million USD, and other specialty grades at 24.7 million USD. This structure matters because each family serves different performance requirements and end-market expectations. Conductive grades, for example, are tied to functionality in electronics, battery-related formulations, and advanced polymer applications, while food-contact and fiber-oriented grades carry their own regulatory and processing considerations. The report uses these categories to show where value is being created today and where product development is likely to open additional room for premium positioning.
Application Demand and Portfolio Implications
By application, the market is anchored by plastics at 95.27 million USD, printing inks at 69.51 million USD, paints and coatings at 60.04 million USD, and batteries at 30.18 million USD. These segments collectively illustrate how specialty carbon black has moved beyond traditional bulk uses into formulation-intensive areas where dispersion, conductivity, UV protection, pigmentation, and consistency are critical. The study examines each application cluster not as a simple revenue line, but as a set of performance requirements, substitution risks, and specification sensitivities that influence purchasing behavior and supplier selection. For teams evaluating expansion, reformulation, or dual-sourcing strategies, that application-level clarity is often the difference between a generic market thesis and an executable plan.
Competitive Landscape: Leaders, Moves, and Meaning
The competitive environment is defined by established global players, regional specialists, and emerging producers pursuing higher-value grades and import substitution. The report profiles the organizations that are most influential in shaping pricing, product breadth, and capacity strategy, with a focus on how their offerings map to the specialty carbon black segments that matter most to buyers.
Global Incumbents and Portfolio Breadth
Orion S.A., headquartered in Spring, Texas, is positioned as a global leader in specialty carbon black grades for paints, coatings, inks, toners, plastics, adhesives, polymers, batteries, and tires. With 15 production facilities and a stated emphasis on sustainable and circular solutions, Orion illustrates how scale can be paired with a sustainability narrative that increasingly matters to downstream customers. Cabot Corporation, based in Boston, Massachusetts, is described as the world's largest producer of specialty carbons, with its BLACK PEARLS, EMPEROR, REGAL, and MONARCH lines supporting UV protection, pigmentation, and conductivity across plastics, coatings, toners, and printing inks. Birla Carbon, headquartered in Mumbai, India, is presented as a leading manufacturer of sustainable carbon black additives, with Raven, Conductex, and Ultra brands targeting high-performance applications in paints, coatings, inks, plastics, adhesives, and tires.
Specialty Carbon Black Market
These profiles are not simply corporate summaries. They are used in the study to show how product naming, grade breadth, and application coverage influence customer choice in specification-driven markets. When buyers compare suppliers, they are often evaluating more than price; they are weighing consistency, technical support, regulatory readiness, and the ability to support reformulation or sustainability goals.
Regional Players and Emerging Capacity Strategies
The competitive picture also includes regionally anchored producers and newer entrants that are altering the market's center of gravity. Tokai Carbon Co., Ltd., based in Tokyo, produces ASTM blacks and specialty carbon blacks for tire, rubber goods, plastics, coatings, and inks, with recent Southeast Asia capacity expansion reinforcing its regional presence. PCBL Chemical Ltd., headquartered in Kochi, India, manufactures seven specialty carbon black grades and has moved to enhance capacity for high-margin grades in rubber and industrial applications. In China, Anhui Black Cat Material Science Co., Ltd. is noted as a leading supplier of specialty carbon black that is realizing import substitution in medium and high-value grades for the paint industry, while Shandong Huibaichuan New Materials Co., Ltd., based in Jinan, Shandong Province, produces pigment and conductive carbon black for coatings, inks, plastics, master batches, sealants, and other applications.
Together, these companies highlight a broader trend: competition is intensifying not only through capacity additions, but through grade specialization, regional proximity, and the pursuit of higher-value niches. The study translates these developments into a practical competitive map, helping readers understand where incumbency is strongest, where import substitution is advancing, and where new capacity may alter supply conditions over the forecast period.
Industry Dynamics Shaping Margin and Strategy in 2026
The market does not move in a vacuum. Several concurrent forces are reshaping cost structures, compliance burdens, and commercial behavior, and the report integrates them into a single operational lens rather than treating them as separate side notes.
Feedstock Pressure and Price Environment
Crude oil price volatility in 2026 has intensified feedstock pressure for specialty carbon black production, with coal tar and oil-based inputs rising sharply due to disruptions in the Strait of Hormuz and higher energy costs. This matters because feedstock economics sit at the center of margin stability, inventory planning, and pricing negotiation. The study examines how this pressure is propagating through production costs and how leading producers are responding, including through commercial mechanisms that transfer part of the volatility into contract terms.
Regulatory Tightening and Compliance Costs
On the regulatory front, stringent environmental regulations in the EU and US have imposed stricter air emission standards and workplace exposure rules on carbon black production, raising compliance costs for specialty grades. At the same time, stricter carbon taxes and emissions trading schemes in key markets are constraining traditional carbon black production methods that release particulate matter, NOx, and sulfur compounds. These forces do more than add cost; they influence which production routes remain competitive, how suppliers justify premium grades, and where sustainable or circular solutions gain commercial traction.
Recent Commercial and Strategic Moves
Recent developments make these dynamics concrete. In March 2026, Orion S.A. announced that it will raise prices and introduce a variable surcharge for specialty carbon black products, a move that directly reflects the feedstock and cost environment while signaling how incumbents are protecting margins. In April 2026, Birla Carbon showcased advanced sustainable carbon black solutions at Chinaplas 2026 for high-performance applications in plastics, electronics, cables, and fibers, underlining the growing linkage between sustainability and performance claims in demanding end markets. In May 2026, Orion S.A. launched circular carbon black production in China, and also announced plans to showcase award-winning bio-circular carbon black plus high-jet grades for automotive coatings at the 2026 American Coatings Show. These events are not isolated news items; they illustrate how product innovation, circular production, and targeted application messaging are being used to navigate a more complex operating environment.
What the Report Delivers: A Practical Toolkit for Strategy Teams
The study is organized to support real decision cycles, not just high-level observation. It blends market sizing, segmentation, competitive profiling, and industry dynamics into a single framework that can be used for sourcing strategy, product planning, investment screening, and risk assessment.
Carbon Black Market
- Historical trajectory and forecast structure covering 2020 through 2032, anchored in consistent market sizing and a 6.5 percent forecast-period CAGR
- Clear segmentation views by region, type, and application, with absolute scale provided to support prioritization and comparison
- Competitive profiles that connect product offerings, production footprints, and strategic positioning to the segments most relevant to specialty carbon black buyers
- Integration of feedstock volatility, regulatory pressure, and recent corporate moves into a working view of margin and supply risk
- Focused analysis of concentration dynamics, with top-three and top-five share context that informs supplier dependence and negotiation strategy
- Practical orientation toward 2026 decision-making, including how to interpret price actions, capacity shifts, and sustainability-driven product launches
In short, the report is built to help teams move from awareness to action. It gives readers a defensible basis for evaluating where demand is strongest, which grades and applications warrant closer attention, how competitors are shaping the commercial environment, and what operational pressures are likely to influence cost and availability in the near term.
How to Use This Intelligence
For procurement and supply chain leaders, the study offers a structured way to assess supplier options, anticipate pricing pressure, and understand where concentration and recent price actions may affect contract strategy. For product and formulation teams, it provides context on how application requirements and regulatory trends are influencing grade selection and substitution risk. For corporate strategy and investment functions, it frames the market in terms of structural growth, competitive positioning, and the regions and product families that are likely to define the next phase of expansion.
The full study goes further than the overview presented here. It contains the deeper segmentation detail, company-level analysis, and scenario-based interpretation needed to turn market visibility into concrete decisions. For teams that need the complete picture—region-by-region scale, application-level demand context, type-level value positioning, and the competitive moves that are actively reshaping the market—the source report is the appropriate next step.
The specialty carbon black market is expanding, but the value of that growth will depend on how well organizations can read its structure, anticipate its pressures, and respond to the moves of a concentrated and increasingly adaptive competitive set. This report is designed to give decision-makers exactly that vantage point for 2026 and the years that follow.
For detailed analysis of this topic, please visit the official page: Specialty Carbon Black Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Conductive Polymers Market to Hit $344.8M by 2032 at 6.98% CAGR from 2026
By PW Consulting, 2026-09-16
Industrial Metamorphosis: Navigating the Next Wave of the Conductive Polymers Market
Executive Overview: The Strategic Imperative for 2026
The conductive polymers landscape is undergoing a quiet yet profound industrial metamorphosis. Far from being a niche chemical segment, this market now sits at the intersection of advanced electronics, sustainable manufacturing, and next-generation functional materials. Our latest Conductive Polymers Market research synthesizes seven years of historical tracking alongside a seven-year forward outlook, delivering a decision-grade intelligence framework engineered specifically for corporate strategy, procurement, and R&D leadership navigating 2026 and beyond.
Market valuation has tracked a consistent upward trajectory, advancing from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025. Our baseline projections extend this arc through 2032, positioning the market at 228.07 million USD in 2026 and climbing toward 344.8 million USD by the close of the forecast window. This translates to a compound annual growth rate of 6.98 percent across the 2026–2032 horizon. These figures are not abstract projections; they reflect structural supply chain realignments, accelerating electrification roadmaps, and the tightening integration of functional polymers into mainstream industrial architectures. Understanding where growth concentrates, which material classes command margin resilience, and how competitive dynamics are reshaping procurement leverage requires the granular dissection only our full report delivers.
Conductive Polymers Market
From Baseline to Breakthrough: Decoding the Growth Trajectory
Historical performance reveals an industry moving through phases of stabilization and acceleration. Between 2020 and 2025, the market navigated raw material volatility, regulatory recalibration, and shifting end-use demand, yet consistently expanded its revenue base. The transition from 192.63 million USD in 2023 to 205.66 million USD in 2024, followed by the 215.0 million USD mark in 2025, signals a market that has moved past cyclical recovery and into sustained expansion. Looking forward, our forecast model maps incremental but compounding gains: 238.57 million USD in 2027, 272.15 million USD in 2028, and a sharper inflection toward 273.18 million USD in 2029, ultimately accelerating to 310.23 million USD by 2030 before settling at 331.66 million USD in 2031 and 344.8 million USD in 2032.
This trajectory is not linear by accident. It reflects the cumulative effect of manufacturing automation, material performance improvements, and the broadening application footprint across industrial, electronic, and energy-adjacent sectors. The 6.98 percent CAGR serves as a strategic anchor, but the real value for decision-makers lies in understanding the velocity of adoption across material types, the regional distribution of capacity and demand, and the competitive maneuvers that will determine margin capture. Our complete analysis isolates these drivers, mapping inflection points that generic market summaries consistently overlook.
Competitive Architecture: Who Shapes the Field and How
Market Concentration and the Real Meaning of Fragmentation
The competitive structure of the conductive polymers sector presents a nuanced picture. A CR3 concentration of 25.3 percent and a CR5 concentration of 30.5 percent indicate a market that is moderately consolidated at the upper tier while remaining highly distributed across specialty producers, regional formulators, and application-focused innovators. This fragmentation is not a weakness; it is a structural feature that rewards strategic patience and penalizes undifferentiated pricing approaches. Market leaders compete less on volume alone and more on formulation precision, regulatory compliance readiness, and application-specific performance certification.
Incumbent Profiles and Strategic Positioning
- Premix Group (Finland) operates as a specialty chemicals company delivering conductive polymer compounds and concentrates engineered for ESD protection, EMI shielding, and static control across medical, automotive, electronics, defense, and packaging end markets. Their footprint illustrates how material specialization and application-side integration reinforce pricing power.
- Heraeus Epurio (Germany) remains a pioneer and manufacturer of Clevios PEDOT:PSS conductive polymers, addressing electronics, displays, smart textiles, and thin-film applications. Their technology positioning underscores the ongoing relevance of high-purity, application-tuned conductive systems in advanced manufacturing.
- Eeonyx Corporation (United States) specializes in industrial-scale conductive polymer coatings for nonwoven and woven fabrics as well as staple fibers, positioning itself at the intersection of textile engineering and functional e-textile requirements.
- Agfa-Gevaert Group (Belgium) develops and supplies ORGACON and Orgacon PEDOT-based conductive polymer materials and inks for optical films, printed electronics, and flexible electronics, reflecting the growing convergence of imaging heritage and printed-circuit functionality.
- SABIC (Saudi Arabia) contributes as a global producer of advanced conductive polymer materials, including polycarbonate blends and compounds tailored for electronics and industrial applications, highlighting how large-scale polymer platforms integrate conductive functionalities into broader material portfolios.
- Heraeus Holding (Germany) encompasses Heraeus Epurio and maintains a group-level focus on advanced conductive polymer solutions for electronics, displays, and smart textiles, signaling how parent-company scale and cross-segment coordination shape long-term capability building.
These profiles represent only the visible layer of a more complex ecosystem. Our report dissects supplier capability matrices, regional manufacturing footprints, application-specific qualification pathways, and the strategic rationale behind recent capacity and technology moves. The following recent developments illustrate the pace and direction of competitive evolution.
Recent Competitive Moves Redefining Strategic Options
- June 2025: Premix Group officially inaugurated a new US manufacturing facility producing conductive polymer compounds for medical, automotive, defense, electronics, and packaging applications. The plant integrates AI-driven automation and real-time conductivity monitoring, signaling a decisive shift toward localized production, process transparency, and quality assurance at scale.
- September 2025: Premix Group transformed its conductive polymer manufacturing operations using an AI/ML platform known as PERTTI 3.0, deploying over 20,000 historical recipes for property prediction and automated process optimization. This move demonstrates how formulation heritage and machine learning are converging to compress development cycles and reduce variability.
- September 2025: BASF SE debuted its latest high-performance conductive polymer additive grades at the K 2025 industrial exhibition, reinforcing the ongoing stream of incremental performance upgrades that reshape downstream compatibility and processing windows.
- February 2026: Heraeus Group scaled up its advanced conductive polymer footprint in China by expanding its production facility within the Shanghai Chemical Industry Park, incorporating AI-driven analytics. This expansion reflects both regional demand maturation and the strategic use of data-rich manufacturing to defend margin in high-growth geographies.
Each event carries strategic implications for procurement timing, supplier diversification, and technology roadmap alignment. The full report translates these developments into actionable scenarios, linking corporate moves to market-wide risk and opportunity mapping.
Structural Forces Shaping the 2026–2032 Horizon
Material Economics, Regulatory Architecture, and the Cost of Compliance
Conductive polymer economics do not operate in isolation. High-purity EDOT monomer used in PEDOT:PSS conductive polymers costs hundreds of euros per kilogram, creating persistent sensitivity in formulation cost structures and reinforcing the strategic value of high-yield processing and material recovery. At the same time, volatile aniline and specialty monomer prices exert medium-term pressure with acute effects concentrated in Asia Pacific manufacturing, where input cost transmission can reshape regional competitiveness and delivery economics. These dynamics mean that procurement strategy must be paired with supply chain resilience planning and formulation flexibility.
Worldwide Structural Conductive Polymer Market
Regulatory frameworks are equally consequential. Under REACH regulation, all chemicals including fillers and additives in conductive polymers must be registered to protect human and environmental health. This requirement elevates compliance from a back-office function to a competitive precondition, particularly for manufacturers targeting European and export-sensitive markets. The EU Ecodesign Directive and ESPR further require registration and restrictions on chemicals in electronics and appliances using conductive polymers, tightening the link between material selection, product certification, and market access. The interaction between regulatory timelines, formulation adjustments, and application qualification cycles creates a planning environment where foresight directly translates into commercial advantage.
Application Breadth and the Diversification Imperative
The conductive polymers value chain now stretches across a wide array of functional use cases, from anti-static packaging and coating to capacitors, actuators and sensors, batteries, solar cells, electroluminescence, and printed circuit boards. This breadth is both an opportunity and a strategic stress test. End-use diversification can cushion volatility in any single segment, but it also demands material grades, processing protocols, and qualification frameworks tailored to distinctly different performance criteria. Generalized product offerings increasingly lose relevance against application-tuned solutions that balance conductivity, mechanical properties, environmental stability, and processing compatibility. Our complete report unpacks how these application pathways diverge in growth behavior, margin structures, and competitive intensity, enabling readers to prioritize investments where the highest risk-adjusted returns emerge.
What Our Full Analysis Delivers
This article is an introduction to a deeper intelligence package. The complete Conductive Polymers Market research expands every theme introduced here into a structured, decision-ready format built for executive review, scenario planning, and cross-functional alignment. Inside the full study, leadership teams will find:
- A regionally disaggregated market view that maps demand distribution, manufacturing geography, and growth velocity across major economic zones, enabling localization strategy and supply chain prioritization without relying on aggregate assumptions.
- A material-type dissection that evaluates performance characteristics, cost drivers, and application fit across major conductive polymer classes, helping R&D and procurement teams align formulation strategy with end-use requirements and processing realities.
- An application-level analysis that tracks adoption intensity, qualification barriers, and revenue contribution patterns across functional sectors, supporting portfolio decisions in electronics, energy, automotive, medical, and industrial markets.
- A competitive landscape framework that assesses market positioning, capability differentiation, recent corporate moves, and regional expansion logic, giving strategy teams a clearer view of supplier leverage, partnership opportunities, and displacement risks.
- Integrated regulatory and raw material insights that connect compliance pathways, monomer cost behavior, and regional manufacturing sensitivities to practical planning horizons, allowing leaders to model cost scenarios and supply continuity strategies with greater confidence.
- Forward-looking scenario structures that translate historical trends and 2026–2032 projections into decision trees for capacity planning, supplier selection, and technology investment, rather than leaving the organization with a single-point forecast.
We deliberately avoid publishing the full segmentation percentages and precise regional or application-level revenue breakdowns here. Those figures are central to the report’s competitive value and are reserved for readers who need the complete dataset to support investment committee reviews, procurement negotiations, and strategic planning cycles. The excerpts and directional signals above demonstrate analytical rigor, but the full intelligence—complete with cross-segment comparisons, regional dynamics, and detailed supplier assessments—is available through the complete report.
Strategic Takeaway for 2026 Decision-Makers
The conductive polymers market is no longer defined solely by material science breakthroughs; it is being shaped by the compounding effects of manufacturing digitization, regulatory tightening, monomer cost volatility, and the expanding demand for functional materials in electronics and industrial systems. Organizations that treat this landscape as a static commodity category will misread both risk and opportunity. Those that approach it as a dynamic, application-linked ecosystem can extract meaningful advantage through supplier alignment, formulation strategy, regional capacity planning, and compliance readiness.
Our 2026–2032 outlook, built on a 6.98 percent CAGR trajectory and reinforced by recent corporate expansions, AI-integrated manufacturing, and high-performance product introductions, provides the scaffold for that strategic shift. The market is moving toward 228.07 million USD in 2026 and continues climbing through the end of the forecast window, but value capture will depend on timing, specificity, and operational execution rather than headline growth alone. For leaders who need to convert market directionality into concrete planning decisions, the complete Conductive Polymers Market research offers the depth, structure, and actionable clarity required to move from awareness to advantage.
For detailed analysis of this topic, please visit the official page: Conductive Polymers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Imperatives in the Edge Protection System Market: A 2026 Outlook
Executive Summary: The Case for Precision Intelligence
As the global construction sector enters a phase of recalibrated growth, the Edge Protection System Market stands at the intersection of regulatory tightening, material cost volatility, and evolving site safety expectations. For corporate strategists, procurement leaders, and risk management executives, navigating this landscape requires more than generalized trends. It demands a structured, forward-looking view of how market size trajectories, segment performance, and competitive positioning will unfold through the end of the decade.
Our latest Edge Protection System Market research has been designed specifically for 2026 decision-making. It converts historical performance data, forecast modeling, and competitive intelligence into an actionable framework that supports capital allocation, supplier negotiation, product development prioritization, and geographic expansion strategies. This article serves as a strategic preview of the report's scope, analytical depth, and practical utility, while preserving the full dataset and granular breakdowns for clients who require it.
From Retrospective Tracking to Forward-Looking Strategy
Over the historical window of 2020 through 2025, the market demonstrated steady expansion supported by sustained demand for temporary work-at-height safety solutions across commercial, infrastructure, and industrial projects. Revenue moved from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025, reflecting a pattern of resilient demand even as contractors navigated supply chain disruptions, labor constraints, and shifting project pipelines.
Looking ahead to the forecast period of 2026 through 2032, the market is projected to continue its upward arc, reaching an estimated 344.8 million USD by 2032. This trajectory implies a compound annual growth rate of 6.98 percent, a pace that signals more than cyclical recovery. It points to structural demand drivers tied to stricter site safety enforcement, increased adoption of modular and integrated protection solutions, and growing contractor emphasis on reducing on-site incident exposure.
For strategists, the significance of this growth path lies not only in its direction but in its composition. Growth is unlikely to be distributed evenly across product categories, end-use verticals, or geographies. Some segments will benefit from regulatory momentum and specification-driven purchasing. Others will face margin pressure from raw material cost volatility and intensifying competition. Understanding where value is created, where pricing power is eroding, and where adoption is accelerating is precisely the kind of intelligence that separates reactive planning from proactive positioning.
Edge Protection System Market
Why 2026 Decisions Require Segment-Level Clarity
The market's evolution through 2026 and beyond will be shaped by a combination of technical, regulatory, and commercial forces. Several dynamics deserve close attention as companies frame their near-term strategy:
- Regulatory and standards evolution is reshaping specification behavior. Updated product specification and test methods for temporary edge protection systems are elevating expectations around energy absorption, arrest functions, and performance verification. These changes are not abstract compliance issues; they influence which systems can be specified on demanding projects, how manufacturers differentiate their offerings, and how quickly new designs can gain market acceptance.
- Material cost pressure continues to affect installed economics. High steel and timber costs remain a relevant factor in the total installed cost of edge protection systems across global markets. For contractors and distributors, this affects bid pricing, supplier selection, and the attractiveness of alternative system designs. For manufacturers, it reinforces the importance of engineered efficiency, reusable components, and total-cost-of-ownership messaging.
- Safety adoption is increasingly linked to project procurement logic. In several major construction markets, temporary edge protection is no longer treated as an optional add-on but as a baseline expectation embedded in contractor qualifications, site planning, and insurance considerations. This shift expands addressable demand but also raises the competitive bar for product reliability, deployment speed, and integration with formwork or scaffolding workflows.
- Competitive intensity is rising among established and specialist players. The market remains relatively fragmented at the top, with a concentrated group of leading firms holding meaningful but not dominant share. That structure creates room for differentiation through product innovation, regional service capability, and partnership-driven distribution, while also making margin defense more dependent on value proposition than on scale alone.
Each of these forces affects a different part of the value chain. A company evaluating its 2026 roadmap needs to know not just that demand is growing, but which solution types are gaining share, which application areas are driving specification changes, and which regions present the strongest risk-adjusted opportunities. The full report addresses those questions with structured segmentation analysis that avoids broad generalizations and instead maps where growth is concentrated and why.
Wall Protection Market
What the Research Delivers: An Operational Toolkit
This study is built to support concrete strategic actions rather than high-level observation. Its architecture is intended to help teams translate market intelligence into procurement planning, product portfolio decisions, sales targeting, and competitive benchmarking. The report includes:
- A long-horizon market size and forecast framework that traces historical performance into the 2026 to 2032 period, giving executives a consistent baseline for scenario planning and investment prioritization.
- Segment-level analysis across type, application, and region that reveals how demand patterns differ by solution category, project environment, and geographic context. This allows readers to assess which segments are most exposed to regulatory tailwinds, material cost sensitivity, or competitive crowding.
- Competitive landscape profiling of leading participants across multiple headquarters markets, with attention to product focus, system integration strategies, and the kinds of applications each company is positioned to serve.
- Recent industry developments and standards-related updates that matter for procurement timing, product conformance, and specification risk, including emerging documentation and testing expectations affecting edge protection systems.
- Market concentration context that helps frame the balance between fragmented opportunity and consolidated influence, supporting realistic assessments of bargaining power, substitution risk, and market entry difficulty.
Importantly, the report is structured to support comparison and prioritization. Rather than presenting a single narrative line, it gives decision-makers a way to test assumptions against market evidence: Which solution categories are expanding most reliably? Which end-use environments are absorbing the highest value of protection work? Where do leading suppliers appear strongest, and where are gaps still present? These are the questions that determine whether a company's 2026 plan is robust under different demand and cost scenarios.
Competitive Landscape: Differentiation in a Fragmented Market
The edge protection sector includes a diverse set of manufacturers and suppliers spanning concrete, steel, timber, and modular construction applications. The marketplace is not defined by a single dominant architecture; instead, it features several companies competing on system design, integration with formwork and scaffolding, speed of deployment, and compliance with evolving safety expectations.
Leading participants illustrate the breadth of strategic approaches in the market. Some organizations emphasize rapid-deployment edge protection systems engineered for concrete, timber frame, and steel frame applications, often aligning product design with repeatability and site efficiency. Others integrate edge protection into broader formwork and scaffolding platforms, positioning safety as part of a unified workflow rather than a standalone purchase. A further group focuses on modular or mesh-based barrier solutions, perimeter safety screens, or roof-edge applications designed for specific project conditions.
Geographic diversity is also significant. Suppliers headquartered in the United States, Germany, Austria, France, Spain, the United Kingdom, Norway, Sweden, India, and China each bring different distribution strengths, regional specification relationships, and product specialization. In practice, this means the competitive picture varies by market: in some regions, integrated system providers may hold an advantage through incumbent project relationships; in others, specialist manufacturers may compete effectively through compliance leadership, lightweight design, or adaptability to local construction methods.
Strategic relevance comes from understanding how these players are likely to respond to the next phase of market development. Companies that can combine conformance with updated testing expectations, cost-effective material engineering, and flexible deployment models are better positioned to capture specification share. At the same time, the presence of multiple capable suppliers means that buyers have increasing leverage to compare total cost, lead time, and integration fit rather than accept a narrow set of options.
Recent activity underscores how quickly the compliance and product refresh cycle is moving. Updated standards documentation and revised product catalogs have already begun to reshape how suppliers present system classes and performance characteristics. For buyers, this creates both a conformance checklist and a competitive signal: manufacturers that move promptly to align documentation, testing, and system configuration with current specifications may gain an advantage in tenders and design reviews, while slower responders risk being excluded from increasingly specification-driven projects.
Using This Intelligence for 2026 Strategy Design
The strategic value of the full report lies in its ability to connect market structure to operational choices. Depending on a company's role in the value chain, the research can support several distinct decision paths:
- For manufacturers and product developers, segment trends and regulatory developments can inform portfolio focus, engineering priorities, and the relative merit of investing in modular, integrated, or application-specific designs.
- For distributors and procurement leaders, market size paths and competitive profiles can guide supplier diversification, inventory planning, and negotiation strategy in an environment where material costs and specification requirements both matter.
- For contractors and project organizations, the report can help clarify where safety system selection influences bid competitiveness, site risk posture, and compliance readiness, especially as standards-related expectations become more explicit.
- For investors and market entrants, concentration metrics, regional differences, and the mix of established and specialist competitors provide a realistic basis for assessing where differentiation is possible and where barriers are higher.
In each case, the goal is the same: reduce uncertainty enough to make better resource decisions without overgeneralizing from aggregate totals. The macro forecast provides the direction of travel. The segmentation, competitive, and standards context explains the mechanism beneath that direction. Together, they create a more reliable foundation for planning than headline growth figures alone.
Accessing the Full Strategic View
This preview has outlined the market's direction, the forces shaping its 2026 evolution, and the competitive logic that will influence decision-making through the forecast period. It has also described the operational scope of the research and the kinds of questions it is built to answer. What it has not done is release the full segmentation data, regional breakdowns, application splits, or company-level comparisons that make the analysis directly usable for internal planning.
Those details are reserved for the complete Edge Protection System Market report. They are structured to support detailed scenario work, supplier evaluation, and segment prioritization without requiring teams to reconstruct the underlying logic from broad market summaries. For executives and analysts who need to move from directional confidence to specific action, the full report provides the evidence base required to justify investment choices, procurement strategy, and competitive positioning in the year ahead.
In a market defined by changing specifications, material cost pressure, and rising expectations for site safety performance, the most valuable intelligence is not simply that growth is occurring, but where, why, and with what competitive implications. The complete research is designed to answer those questions in a format that supports disciplined 2026 decision-making across the construction safety value chain.
For detailed analysis of this topic, please visit the official page: Edge Protection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: APU Market Hits $200M in 2025, Projected 5.2% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Aircraft Auxiliary Power Unit Market: Navigating Growth and Innovation Through 2032
The global aviation landscape is undergoing a profound transformation. As airlines balance operational efficiency with rigorous environmental mandates, the Aircraft Auxiliary Power Unit (APU) has emerged as a critical component in the aerospace value chain. Far more than a simple engine starter, the modern APU serves as a versatile energy hub, providing bleed air, electrical power, and engine starting capabilities essential for ground operations and emergency backup in flight. For strategic decision-makers, understanding the trajectory of this market is no longer optional; it is a prerequisite for capitalizing on upcoming shifts in manufacturing, aftermarket services, and technological integration.
PW Consulting's latest comprehensive analysis, Aircraft Auxiliary Power Unit (APU) Market , offers a detailed roadmap of this sector from a base year of 2025 through a forecast period extending to 2032. This report is designed not merely as a statistical digest but as an actionable intelligence tool. It synthesizes historical performance data with forward-looking projections to help stakeholders navigate an environment defined by consolidation, regulatory pressure, and rapid technological evolution. The following overview highlights the strategic value embedded within this research, illustrating why it is essential reading for executives in aerospace manufacturing, aviation services, and investment firms.
Market Trajectory and Quantitative Context
Understanding the scale and momentum of the APU market provides the foundation for any strategic planning exercise. Over the historical period spanning 2020 to 2025, the industry demonstrated resilience and steady expansion despite global supply chain disruptions and fluctuating flight volumes. The market valuation in 2020 stood at 150.0 million USD, reflecting the initial impact of reduced travel demand. However, recovery drove valuations upward, reaching 158.35 million USD in 2021 and climbing to 172.38 million USD in 2022. By 2023, the market had surpassed the 180 million USD threshold, recording 184.45 million USD, before settling at 186.62 million USD in 2024 as manufacturers optimized production schedules.
The base year of 2025 marks a significant inflection point, with the market reaching 200.0 million USD. This milestone underscores the renewed confidence in aviation infrastructure and the increasing reliance on reliable auxiliary power systems for both new aircraft deliveries and fleet sustainment. Looking ahead, the forecast period from 2026 to 2032 projects sustained growth. The year 2026 is anticipated to open at 206.33 million USD, followed by progressive increments leading to 219.7 million USD in 2027 and 224.92 million USD in 2028. As the decade progresses, the valuation is expected to approach 234.8 million USD by 2029 and cross the 255.1 million USD mark by 2030. The final years of the forecast horizon show the market stabilizing near its peak potential, with projections of 268.5 million USD in 2031 and 270.0 million USD in 2032.
This growth trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 5.2 percent over the forecast period. While this rate indicates steady expansion, it also masks the underlying complexities of regional performance, technological shifts, and competitive dynamics that drive the aggregate number. Stakeholders must look beyond the headline figures to understand where value is being created and how to position their portfolios accordingly.
Segmentation Dynamics and Structural Shifts
The APU market is not a monolith. It is segmented by type, application, and geography, each presenting distinct opportunities and challenges. Our analysis delves into the nuanced performance of these segments without merely presenting isolated percentages. Instead, we examine the structural forces reshaping demand.
In terms of technology, the market is currently anchored by traditional gas turbine solutions, which continue to dominate due to their proven reliability and high power-to-weight ratios in established airframe configurations. However, the research highlights a gradual but decisive shift toward alternative propulsion technologies. Electric and fuel cell-based APU concepts are gaining traction, driven by the industry's decarbonization goals and the specific needs of newer aircraft designs. The interplay between legacy gas turbine offerings and emerging electric architectures is a key theme explored in depth, providing insights into where R&D investments should be directed to future-proof product lines.
Application-wise, commercial aviation remains the primary driver of volume, reflecting the sheer scale of the global passenger fleet. Military aviation represents a specialized but high-value segment, often characterized by stringent performance requirements and long-term support contracts. Business and general aviation contribute additional layers of demand, often serving as early adopters of new technologies or niche configurations. Understanding the relative weight and growth characteristics of these applications is vital for companies deciding whether to focus on high-volume commercial platforms or high-margin specialized military and business jet solutions.
Geographically, the market exhibits a diversified footprint. North America, Europe, and Asia Pacific represent the bulk of revenue generation, reflecting the concentration of aircraft manufacturers, major operators, and maintenance hubs in these regions. Latin America and the Middle East and Africa also contribute to the global total, often linked to specific fleet modernization programs or growing regional connectivity. The report provides a granular view of how regional procurement cycles, fleet age profiles, and local regulatory environments influence revenue streams, enabling clients to tailor their market entry or expansion strategies with precision.
Competitive Landscape and Strategic Consolidation
The APU market is characterized by a high degree of concentration. Market data indicates that the top three competitors hold a combined share of approximately 55.0 percent, while the top five players command around 70.0 percent. This oligopolistic structure suggests that barriers to entry are significant, particularly in the civil sector where certification hurdles are substantial. In fact, industry data confirms that only four companies worldwide are currently authorized to develop and certify civil APUs, creating a tightly controlled environment for new market entrants.
Several key players define the current competitive arena. Pratt & Whitney, headquartered in East Hartford, Connecticut, maintains a robust portfolio including the APS5000 all-electric series, APS3200, PW980, and APS2100. Their strategic movements are closely watched, particularly their recent cooperation agreement signed in September 2025 with PBS Group to develop next-generation APUs with the highest power density and reduced form factors for both civil and military aviation. This collaboration signals a clear intent to lead in efficiency and compactness. Furthermore, the March 2026 supply agreement between VSE Aviation and Pratt & Whitney Canada for over 2,500 aftermarket parts covering APS1000, APS2000, and APS2100 units highlights the enduring value of the aftermarket ecosystem and the importance of long-term distribution partnerships.
Honeywell International Inc., based in Charlotte, North Carolina, remains a formidable competitor with its GTCP series, including the GTCP331 and HGT1700, as well as the 36-150 and Micro Power Unit lines. Honeywell's selection of the 36-150 APU by Bell Textron for the Future Long-Range Assault Aircraft (FLRAA) program in June 2025 demonstrates the company's ability to secure critical platforms in the defense sector, reinforcing its position as a provider of mission-critical power solutions.
Safran Power Units, located in Bordeaux, France, continues to leverage its SPU series for both civil and military aircraft. The company's expansion of its partnership with Lufthansa Technik in October 2025 for APU generator maintenance and overhaul on Airbus A320 aircraft illustrates the growing emphasis on integrated maintenance solutions and lifecycle support. This trend toward closer collaboration between OEMs and MRO providers is a recurring theme that affects margin structures and customer lock-in strategies across the industry.
Other notable entities include PBS Aerospace in Prague, known for its APU systems from Velká Bíteš; Kinetics Ltd. in Israel, focusing on auxiliary power units for military applications; AEGIS Power Systems, Inc. in the United States, specializing in aircraft power supplies and related APU components; and AMETEK Airtechnology in the United Kingdom, which is pushing boundaries with hydrogen-powered APU thermal management and electric power units. The presence of these diverse players underscores the breadth of innovation occurring across different technologies and end-use sectors.
Aircraft Auxiliary Power Unit (APU) Market
Industry Dynamics and Regulatory Catalysts
Market growth does not occur in a vacuum. It is shaped by a complex web of regulatory requirements, material cost fluctuations, and airframe design changes. One of the most significant regulatory pressures currently affecting the industry is the phase-out of Halon in airplane applications per ICAO deadlines. This transition forces manufacturers and operators to seek alternative fire suppression and cooling solutions within APU systems, driving design modifications and potentially altering component costs. The FAA Q1 2026 Transport Airplane Issues List highlights this issue alongside special conditions introduced by Airbus and Boeing for automatic speed protection systems that reduce airplane structural loads. These airframe-level changes can indirectly influence APU requirements, particularly regarding mounting, vibration tolerance, and integration with flight control systems.
On the material and manufacturing front, the adoption of additive manufacturing for hot-section components is yielding tangible benefits. Sector analysis from 2025 indicates that this technology has reduced APU part lead times by 15 to 25 percent and lowered inventory requirements. For operators, this translates to improved fleet availability and reduced downtime. For manufacturers, it offers a pathway to optimize supply chains and respond more rapidly to aftermarket demand. However, the integration of additive manufacturing also raises questions about certification standards, quality control, and long-term durability, all of which are examined in the report.
Auxiliary Power Units (APU) Market
The concentration of certification authority in the hands of a few entities adds another layer of strategic consideration. Companies must navigate a rigorous approval process to bring new civil APUs to market. This reality favors established players with deep regulatory expertise and long-standing relationships with certification bodies, while also creating opportunities for partnerships that can share the burden of compliance. The report explores how these dynamics influence competitive positioning and the pace of innovation.
Operational and Financial Implications for Decision-Makers
For executives and investors, the APU market presents a mix of steady revenue streams and pockets of high growth potential. The aftermarket segment, in particular, offers recurring revenue opportunities tied to the extensive operational life of aircraft fleets. With thousands of units in service and ongoing support agreements, the lifecycle value of an APU extends far beyond the initial sale. Companies that can secure exclusive distribution rights or forge strong MRO partnerships, as seen in recent developments, are well-positioned to capture a disproportionate share of this value.
Conversely, the transition toward electric and hydrogen-based technologies introduces uncertainty and opportunity in equal measure. Early movers in these areas may gain competitive advantages, but they also face higher R&D costs and the risk of shifting standards. The report assesses the maturity of these technologies, the likely adoption timelines, and the potential impact on incumbent gas turbine markets. This analysis helps clients evaluate whether to invest in incremental improvements to existing platforms or to pursue disruptive innovations that could reshape the market landscape.
Cost management is another critical area. Material costs, supply chain resilience, and manufacturing efficiency all play a role in determining profitability. The insights on additive manufacturing and inventory optimization provide actionable levers for reducing operational expenses. Additionally, understanding regional variations in demand and regulatory requirements enables more accurate capacity planning and resource allocation.
What the Full Report Delivers
The Aircraft Auxiliary Power Unit (APU) Market research publication is structured to provide a holistic view of the industry. Beyond the high-level market sizing and trajectory discussed here, the full report contains detailed segmentation analysis, competitive benchmarking, and scenario-based forecasting. Readers will find comprehensive profiles of key companies, including their strategic positioning, product portfolios, and recent developments. The report also examines the interplay between airframe manufacturers, airlines, defense contractors, and regulatory bodies, offering a 360-degree perspective on the forces shaping the market.
Specific deliverables include an in-depth examination of type-based segmentation, covering gas turbine, electric, and fuel cell technologies, with analysis of their respective growth drivers and constraints. Application-based analysis breaks down demand across commercial, military, business, and general aviation, highlighting the unique requirements and revenue characteristics of each segment. Regional analysis provides a nuanced view of market performance across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, factoring in local fleet dynamics and procurement trends.
Furthermore, the report includes a thorough assessment of market concentration, analyzing the market share held by leading players and the implications for competition and pricing. It also explores the impact of recent developments, such as cooperation agreements, supply contracts, and technology selections, to illustrate how strategic moves are reshaping the competitive landscape. Regulatory and technical factors are woven throughout the analysis, ensuring that readers have a complete understanding of the external environment in which they operate.
Conclusion: Actionable Intelligence for a Complex Market
The Aircraft Auxiliary Power Unit market stands at a crossroads. Steady demand from commercial and military fleets provides a solid foundation for growth, while environmental regulations and technological advancements are pushing the industry toward new paradigms. Success in this environment requires more than a surface-level understanding of market size and CAGR. It demands a deep appreciation of segmentation dynamics, competitive pressures, regulatory constraints, and the evolving nature of value capture across the product lifecycle.
PW Consulting's comprehensive market research equips stakeholders with the knowledge needed to make informed decisions. Whether the goal is to identify new market entry opportunities, optimize existing product lines, forge strategic partnerships, or assess investment potential, the report delivers the granular insights necessary to navigate complexity and seize opportunity. The data presented in this preview serves as a reminder of the scale and momentum of the sector, but the full intelligence contained in the report is essential for translating that momentum into actionable strategy.
For organizations committed to staying ahead in the aerospace sector, this research represents a vital resource. It bridges the gap between broad market trends and specific operational decisions, providing the clarity needed to thrive in a competitive and rapidly changing industry. We invite readers to explore the complete analysis to unlock the full strategic potential of the APU market outlook through 2032.
For detailed analysis of this topic, please visit the official page: Aircraft Auxiliary Power Unit (APU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Application Security Software Market to Reach $614.7M by 2032, 10.4% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Application Security Software Market: A 2032 Outlook for Enterprise Leaders
As organizations accelerate their digital transformation journeys, the perimeter of corporate defense has shifted decisively from network edges to the application layer itself. The proliferation of cloud-native architectures, microservices, and API-driven ecosystems has expanded the attack surface, making application security no longer a mere compliance checkbox but a core business enabler. For C-suite executives and security architects navigating the complexities of 2026 and beyond, understanding the trajectory of the Application Security Software Market is essential for allocating capital, mitigating risk, and maintaining competitive resilience.
Our latest comprehensive market research offers a rigorous examination of this evolving landscape, synthesizing historical performance data with forward-looking projections to equip decision-makers with the intelligence required for strategic planning. This article serves as an executive overview of the key themes, growth drivers, and competitive dynamics captured in the full report. While we highlight the macro-level trajectories and structural shifts reshaping the industry, the granular segmentation data, detailed vendor benchmarking, and actionable investment frameworks are reserved for the complete study. We invite you to explore the full report to unlock the precise metrics and segmented intelligence necessary for your organization's specific context.
The Macro Trajectory: Sustained Growth in a High-Stakes Environment
The Application Security Software Market has demonstrated remarkable resilience and expansion over the past half-decade, reflecting the non-negotiable nature of software protection in modern enterprise operations. Historical data from 2020 through 2025 reveals a consistent upward trend, with the market growing from approximately 248.5 million USD to 311.0 million USD. This progression underscores a fundamental shift in how organizations prioritize security investments, moving beyond reactive measures toward proactive, integrated application defense strategies.
Looking ahead, the forecast period from 2026 to 2032 indicates that this momentum will not only continue but accelerate. The market is projected to reach 333.15 million USD in 2026, representing a meaningful step up from the previous year, and is expected to climb steadily to 614.7 million USD by 2032. This trajectory reflects a compound annual growth rate of 10.4 percent, signaling sustained demand driven by escalating threat sophistication, regulatory mandates, and the widespread adoption of cloud-native application architectures. For enterprise leaders, this growth rate translates into an expanding ecosystem of solutions, increased vendor competition, and evolving best practices that must be carefully monitored to avoid technological obsolescence and ensure optimal security posture.
The sheer scale of data generation further amplifies the urgency of these investments. As noted by the Security Industry Association in November 2025, the world is expected to generate 181 zettabytes of data in 2025, marking a 23 percent year-over-year increase. This exponential data growth directly correlates with increased application complexity and surface area, reinforcing the need for robust, scalable application security tools that can keep pace with information volume without compromising performance or user experience.
Regulatory Pressures and the New Compliance Imperative
The regulatory landscape has become a primary catalyst for application security adoption, reshaping how organizations approach software development and deployment. European digital sovereignty requirements are intensifying, driven by Regulation (EU) 2025/37, as highlighted by ENISA in June 2025. This shift reflects a broader geopolitical and economic push toward self-reliance in digital infrastructure, compelling organizations operating within or alongside European markets to align their security strategies with localized standards and data governance frameworks.
Equally significant is the introduction of the Cyber Resilience Act, which imposes direct digital product cybersecurity obligations on software suppliers. This legislation moves beyond traditional enterprise procurement requirements, placing responsibility squarely on the shoulders of developers and vendors to ensure that applications meet stringent security benchmarks before reaching the market. For enterprises that develop or procure software, this regulatory evolution necessitates a fundamental rethinking of application security lifecycles, from initial design through continuous runtime protection.
These regulatory dynamics are not isolated to Europe. Global regulatory convergence is creating a complex compliance environment where organizations must navigate overlapping mandates across jurisdictions. The full report delves into how these regulatory forces influence procurement decisions, technology selection criteria, and the long-term cost structure of application security programs, providing a nuanced view that goes beyond surface-level compliance checklists.
Technology Segmentation and the Evolution of AppSec Tooling
The application security software landscape is characterized by a diverse array of tooling categories, each addressing distinct phases of the software development lifecycle and operational environments. The market encompasses static code analysis tools, which examine source code for vulnerabilities before execution; dynamic code analysis tools, which test running applications for runtime weaknesses; and software composition analysis tools, which assess third-party and open-source components for known vulnerabilities and licensing risks. This tripartite structure reflects the comprehensive approach required to secure modern applications, where threats can emerge at any point from code commit to production deployment.
As organizations mature their security programs, the integration of these tooling categories into cohesive platforms is becoming increasingly prevalent. The demand for unified visibility, automated remediation, and continuous monitoring is driving consolidation trends, with vendors expanding their portfolios to offer end-to-end application protection. The report provides a detailed mapping of how these technology categories are evolving, including adoption patterns, integration challenges, and the emerging capabilities that are setting new industry benchmarks. Decision-makers will find value in understanding how these segments interact and which combinations yield the most effective security outcomes for different organizational profiles.
Competitive Dynamics: A Consolidated Landscape with Differentiated Leaders
The application security market is marked by a high degree of concentration, with a small number of dominant players capturing a significant share of overall revenue. Analysis indicates a CR3 of 62.3 percent and a CR5 of 78.1 percent, reflecting an environment where established vendors leverage extensive product portfolios, global sales channels, and deep customer relationships to maintain market leadership. This concentration has implications for procurement strategy, pricing dynamics, and the pace of innovation, as competitive pressure drives both consolidation and differentiation.
Application Security Software Market
Several key companies exemplify the strategic positioning and technological focus that define the current competitive landscape. Palo Alto Networks, headquartered in Santa Clara, California, has centered its application security strategy on the Prisma platform, which includes a dedicated Application Security module. This offering provides cloud-native posture management, runtime protection, and API security, reflecting a holistic approach that aligns with the shift toward cloud-first architectures. Fortinet, based in Sunnyvale, California, emphasizes its FortiWeb and FortiApplication Security Fabric solutions, delivering web application protection, WAF capabilities, and API security across hybrid environments. This breadth of coverage appeals to organizations seeking unified protection across on-premises and cloud deployments.
Imperva, headquartered in San Mateo, California, has built a strong reputation through its Application Security and Data Security portfolio, with a particular focus on Web Application and API Protection (WAAP), WAF, and DDoS mitigation. The company's market recognition is underscored by independent evaluations, including KuppingerCole's 2025 WAAP Report, which named Imperva an overall leader, and the Forrester Wave 2025 for Web Application Firewall Solutions, which recognized Imperva as a security leader. These accolades highlight the company's sustained investment in both technology and market validation.
Cisco Systems, based in San Jose, California, leverages its extensive networking heritage to deliver Cisco Secure Firewall and application security solutions that support zero-trust application delivery and threat protection. This network-integrated approach resonates with organizations seeking to align security controls with underlying infrastructure. Check Point Software Technologies, headquartered in Tel Aviv, Israel, focuses on Harmony SASE and application security solutions, emphasizing API protection and WAF capabilities within a broader secure access service edge framework. F5 Networks, based in Seattle, Washington, concentrates on BIG-IP and Application Security solutions designed for API, web, and application delivery protection in multicloud environments, addressing the complexities of modern traffic management and security enforcement.
Worldwide Application Security Solution Market
The full report provides an in-depth competitive analysis, including vendor profiles, strategic positioning, product capabilities, and market share dynamics. It offers a granular view of how these companies are responding to market demands, innovating their portfolios, and competing for enterprise contracts. This level of detail is essential for organizations evaluating vendor partnerships, assessing technology roadmaps, and making informed procurement decisions.
Enterprise Adoption Patterns and the SME Challenge
Adoption of application security software varies significantly across organizational sizes, reflecting differences in budget, risk tolerance, technical expertise, and regulatory exposure. Large enterprises represent the dominant segment, driven by expansive application portfolios, stringent compliance requirements, and the resources to implement sophisticated security programs. SMEs, while growing in adoption, face distinct challenges related to cost constraints, talent shortages, and the need for streamlined, easy-to-deploy solutions that deliver immediate value without requiring extensive security operations overhead.
The report examines how these adoption patterns are evolving, highlighting the factors that influence purchasing decisions across different organizational profiles. It explores the role of managed services, cloud-based delivery models, and integrated security platforms in lowering barriers to entry for smaller organizations, while also analyzing how enterprises are scaling their application security programs to match the complexity of their digital ecosystems. Understanding these dynamics is critical for tailoring security strategies to organizational realities and ensuring that investments yield measurable risk reduction.
Operational Considerations: Infrastructure, Costs, and Strategic Alignment
Beyond technology selection, successful application security programs require careful consideration of operational factors, including infrastructure costs, integration complexity, and alignment with broader business objectives. The exponential growth in data generation puts pressure on security infrastructure, requiring solutions that can scale efficiently without incurring disproportionate cost increases. Organizations must balance the need for comprehensive protection with the realities of budget constraints, ensuring that security investments are optimized for both coverage and efficiency.
Strategic alignment is equally important. Application security must be integrated into the fabric of software development, DevOps practices, and cloud operations, rather than treated as a separate, siloed function. This requires cross-functional collaboration, clear governance frameworks, and metrics that tie security outcomes to business risk reduction. The full report provides actionable frameworks for aligning application security investments with organizational priorities, including guidance on capability mapping, vendor evaluation, and program maturation.
What the Full Report Delivers: A Roadmap for Informed Decision-Making
Our comprehensive Application Security Software Market research is designed to serve as a strategic reference for executives, security leaders, and technology procurement professionals. The study delivers a multi-dimensional view of the market, combining historical analysis, forward-looking projections, segmentation insights, and competitive intelligence into a cohesive narrative that supports informed decision-making. Key components include detailed market sizing and growth forecasts, segmentation analysis across regions, technology types, and application profiles, competitive landscape mapping with vendor profiles and strategic positioning, regulatory and industry context analysis, and actionable recommendations for investment and program development.
While this article has provided an executive-level overview of the market's trajectory, the underlying structural drivers, and the competitive players shaping the industry, the full report contains the depth and precision required to translate strategic awareness into operational action. It offers the granular data points, comparative analyses, and nuanced interpretations that enable organizations to benchmark their current posture, identify gaps, and prioritize investments with confidence.
For leaders seeking to navigate the complexities of application security in 2026 and beyond, the full study provides the intelligence foundation necessary to make decisions that are both strategically sound and execution-ready. We encourage you to access the complete report to explore the detailed findings, segmented breakdowns, and vendor-specific insights that will directly inform your organization's security roadmap.
The application security landscape is evolving rapidly, driven by technological innovation, regulatory change, and the relentless creativity of threat actors. Organizations that invest in understanding this landscape and align their security strategies accordingly will be best positioned to protect their digital assets, comply with emerging mandates, and sustain growth in an increasingly interconnected world. Our research is intended to be a trusted partner in that journey, offering clarity, depth, and actionable insight at every step.
For detailed analysis of this topic, please visit the official page: Application Security Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SerDes Market Hits $900M in 2025, 13.7% CAGR to $2.2B by 2032
By PW Consulting, 2026-09-16
Navigating the SerDes Market: Strategic Intelligence for 2026 and Beyond
In the rapidly evolving landscape of high-speed data transmission, the Serial Deserializer (SerDes) market stands as a critical infrastructure backbone for modern digital ecosystems. As enterprises across healthcare, automotive, and industrial sectors demand higher bandwidth and lower latency, the strategic implications of SerDes architecture have never been more pronounced. At PW Consulting, we recognize that understanding the macro-economic trajectory of this sector is not merely an academic exercise but a vital component of capital allocation and technology roadmapping for 2026 and beyond.
This article serves as an executive preview to our latest comprehensive market research release. Our objective is to outline the strategic value this intelligence offers to decision-makers who must anticipate shifts in supply chain dynamics, competitive positioning, and technological adoption rates. The data covered herein spans a robust historical period from 2020 through the base year of 2025, with a detailed forecast extension through 2032. This longitudinal view allows stakeholders to model risk and opportunity with a granularity that short-term forecasts simply cannot provide.
Macro-Economic Trajectory and Growth Indicators
The foundational metric for any strategic investment decision is a clear understanding of market scale and velocity. Based on rigorous analysis of historical performance and forward-looking indicators, the SerDes market has demonstrated a resilient growth pattern over the past half-decade. From approximately 500.0 USD Million in 2020, the market size expanded steadily to reach 900.0 USD Million by 2025. This trajectory underscores the increasing reliance on high-speed serial links as a fundamental component of modern electronic design.
Looking forward into the forecast period extending to 2032, the momentum is projected to accelerate. The market is expected to breach the 1 billion USD Million mark during 2026, reaching 1005.28 USD Million. This growth is not linear; it reflects compounding technological demands and the proliferation of connectivity-enabled devices. By the end of the forecast window in 2032, the overall market size is anticipated to reach 2200.0 USD Million.
This expansion is underpinned by a strong Compound Annual Growth Rate (CAGR). For the period covering 2026 through 2032, the analysis indicates a CAGR of 13.7 percent. This rate of growth suggests that the SerDes market is outpacing many broader semiconductor segments, driven by specific high-demand verticals. For strategists, this percentage is a key indicator of where R&D budgets should be prioritized to capture emerging value pools. It signals a market that is not only expanding but doing so at a pace that warrants aggressive attention from both chipset manufacturers and system integrators.
It is crucial for leadership teams to note that this currency-denominated revenue is tracked in USD across all units of Million. Consistency in reporting standards ensures that cross-border investments and partnerships are evaluated on a comparable basis. The data provided in our full report eliminates ambiguity, allowing CFOs and strategic planners to model revenue projections without the friction of currency conversion assumptions or unit discrepancies.
Operational Intelligence Within the Report
A market report is only as valuable as the actionable intelligence it contains. Our research goes beyond surface-level sizing to provide deep operational insights that directly impact engineering and supply chain strategy. We understand that in the semiconductor industry, the difference between success and obsolescence often lies in the details of supply chain volatility and regulatory compliance.
SerDes Market
One significant area of focus in our analysis is the impact of raw material costs on production economics. Recent industry data indicates that aluminum-based raw materials used for PCB substrates in SerDes components have incurred significant cost increases. This volatility stems from global supply chain disruptions that have persisted through 2025. For procurement officers and production managers, understanding the magnitude of this cost pressure is essential for margin protection. Our report contextualizes these material constraints within the broader manufacturing cost structure, helping organizations factor supply chain risk into their vendor selection processes.
Furthermore, the human element of semiconductor fabrication cannot be overlooked. Our analysis highlights that skilled semiconductor fabrication labor in Asia accounts for approximately 25 percent of SerDes manufacturing costs. This labor dynamic influences where companies choose to manufacture and source components. As geopolitical tensions and labor availability shift, understanding this cost composition helps firms optimize their manufacturing footprint. The report provides the necessary context to evaluate whether near-shoring or maintaining Asian-based fabrication offers better long-term value propositions given the cost structures involved.
HSMT SerDes Chip Market
Infrastructure requirements are another critical pillar of our research. Advanced data center infrastructure, particularly within healthcare facilities, requires low-latency SerDes links for real-time imaging systems. This specific technical requirement drives demand patterns that differ from standard commercial data centers. Our report dissects these infrastructure needs, allowing technology leaders to tailor their connectivity solutions to the rigorous latency and reliability standards demanded by critical sectors like healthcare imaging.
Competitive Dynamics and Market Concentration
The SerDes market is characterized by a high degree of concentration among leading players, creating a complex competitive environment where partnerships and licensing agreements are as valuable as proprietary hardware. Our analysis details a market structure where the top three entities hold a CR3 of 72.0 percent, and the top five extend this concentration to a CR5 of 78.0 percent. This level of concentration indicates significant barriers to entry and suggests that established players possess considerable leverage over pricing and technology standards.
Prominent organizations shaping this landscape include Texas Instruments, headquartered in Dallas, Texas, USA. They offer high-speed SerDes solutions such as the DS90UB954, targeting industrial, automotive, and healthcare data transmission applications. Their presence underscores the importance of versatile solutions that can span multiple verticals. Similarly, Broadcom Inc., based in San Jose, California, USA, provides products like the BCM87412 for networking and data centers, extending into healthcare systems. Their strategy highlights the intersection of networking infrastructure and specialized medical applications.
Intel Corporation, located in Santa Clara, California, USA, supplies the Intel Agilex I-Tile SerDes for high-performance data transmission in healthcare and industrial sectors. Their focus on high-performance transmission aligns with the growing demand for compute-heavy workflows. Marvell Technology, also in Santa Clara, delivers PAM4 400G SerDes solutions that support cloud, 5G, and healthcare connectivity needs. This specific technical implementation indicates a market moving toward higher density and speed protocols to handle increased data loads.
On the intellectual property front, Synopsys Inc. from Mountain View, California, licenses DesignWare 112G SerDes IP for custom semiconductor designs, including those for healthcare and medical devices. Cadence Design Systems, based in San Jose, provides SerDes PHY IP for SoC development in similar sectors. These IP licensing models represent a distinct revenue stream and competitive dynamic compared to physical component manufacturing. Lattice Semiconductor, headquartered in Hillsboro, Oregon, USA, offers an Avant platform with leading 25 Gb/s SERDES for mid-range FPGA applications, including healthcare. This demonstrates that even within FPGA markets, specialized SerDes capabilities are a key differentiator.
International players also exert significant influence. NXP Semiconductors, based in Eindhoven, Netherlands, manufactures components for automotive and healthcare data interfaces. Analog Devices, in Wilmington, Massachusetts, USA, provides high-speed solutions supporting healthcare and 5G applications. ON Semiconductor, from Scottsdale, Arizona, USA, supplies products for industrial, automotive, and medical device connectivity. Finally, STMicroelectronics, located in Geneva, Switzerland, offers solutions for automotive and healthcare sensor fusion systems. The geographic diversity of these headquarters reflects the global nature of the supply chain, even amidst concentration risks.
Regulatory Frameworks and Sector-Specific Drivers
Technology deployment does not occur in a vacuum; it is heavily influenced by regulatory environments and reimbursement structures. Our report integrates these external forces to provide a holistic view of market viability. For instance, ISO 13485 certification for SerDes components in medical devices is required for all healthcare applications. This regulatory hurdle creates a barrier to entry that favors established players with robust quality management systems. It also dictates the timeline for new product introduction in the medical sector, requiring strategists to plan for compliance lead times.
Simultaneously, reimbursement models play a crucial role in demand generation. Medicare and private payers reimburse for healthcare devices incorporating high-speed SerDes connectivity. This financial incentive effectively subsidizes the adoption of higher-cost, higher-performance connectivity solutions in the medical field. For companies targeting the healthcare vertical, understanding the alignment between reimbursement policies and hardware specifications is a key driver of commercial success. Our research highlights how these financial flows support the wider adoption of advanced SerDes architectures in life-critical systems.
These dynamics vary significantly by application focus. While the full report breaks down value by application, it is evident that sectors like Data Centers and Automotive represent substantial value pools, driving the need for robust interfaces. The interplay between regulatory compliance, reimbursement availability, and technical performance creates a complex matrix that engineers and business developers must navigate. Our analysis provides the necessary context to understand which combinations of regulation and reimbursement create the most favorable conditions for market entry or expansion.
Strategic Implications for 2026 Decision-Making
As we move into 2026, the strategic implications of these findings are profound for enterprise leadership. The projected growth to 1005.28 USD Million in 2026 and beyond suggests that SerDes technology will remain a priority investment area. Companies that delay integration or fail to secure reliable supply chains may find themselves at a competitive disadvantage as bandwidth requirements escalate.
For procurement and supply chain executives, the cost volatility associated with raw materials and labor costs necessitates a diversified sourcing strategy. Relying on a single region or supplier type exposes the organization to risks highlighted by the aluminum substrate cost increases and the significant labor cost component in Asian fabrication. Diversification and strategic inventory management become imperative to mitigate these variables.
For technology strategists and R&D leaders, the competitive landscape defined by high market concentration suggests that partnerships may be more fruitful than outright competition for new entrants. Leveraging IP cores from leaders like Synopsys or Cadence, or collaborating with established component manufacturers like TI or Broadcom, may offer faster time-to-market than attempting to develop proprietary high-speed links from scratch. The CR3 and CR5 metrics serve as a reality check on the feasibility of independent development in this saturated space.
Furthermore, the regulatory aspect regarding ISO 13485 certification cannot be an afterthought. Product roadmaps must incorporate compliance testing early in the design phase. The correlation between reimbursement policies and hardware capabilities also suggests that value propositions should be built around the performance benefits that justify higher costs and qualify for reimbursement. Marketing and sales strategies should reflect this alignment to maximize adoption rates in healthcare and other regulated sectors.
Conclusion and Access to Full Intelligence
The SerDes market is entering a phase of accelerated expansion defined by high growth rates, concentrated competition, and rigorous regulatory demands. The data points from 2020 through the 2032 forecast provide a clear narrative of a sector vital to the future of high-speed connectivity. However, the macro-level view only scratches the surface of the complexities involved in successful market participation.
To fully leverage these insights for your organization's specific context, access to the complete dataset, segmentation details, and proprietary analysis is required. Our full report offers granular breakdowns that allow for precise modeling and risk assessment tailored to your operational needs. We invite you to visit our source webpage to download the complete study. There, you will find the detailed segmentation splits and specific regional and application data that inform the broader trends discussed here, enabling you to make fully informed strategic decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: SerDes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


